
Study Guides
AQA A-Level Accounting: The Double Entry Model (7127)
Source documents, books of prime entry, ledger accounts and the recording of adjustments – the full content of Topic 3 for AQA A-Level Accounting (7127).
- Subject
- Accounting
- Level
- A LEVELS
- Topic
- The double entry model
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to AQA A Level Accounting (7127), 2017-onwards. Official specification .
Syllabus page (what it covers and how it is assessed): AQA A Level Accounting.
Syllabus topics and points this page is mapped to
7127
- 3 The double entry model (topic-level mapping)
"Topic-level mapping" means this page belongs to that topic; it does not claim to cover every point in it.
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Accounting (7127).
This guide covers Topic 3 The double entry model, the third of 18 named subject-content sections in AQA A-level Accounting (7127), first teaching September 2017. This is the qualification’s technical core: every later topic, from limited company accounts to standard costing, assumes fluent double-entry technique. These notes complement the site’s guide to The Role of the Accountant in Business.
Where this fits in 7127
Topic 1 explained what accountants do; Topic 2 covered the different types of business organisation. Topic 3 is where the qualification becomes technical: it introduces the actual recording system that Topics 6-7 (preparing financial statements) and every costing topic later in the specification depend on.
Syllabus coverage
AQA A-LEVEL ACCOUNTING (7127) – TOPIC 3 THE DOUBLE ENTRY MODEL
- The double entry system: recording transactions from source documents in books of prime entry and ledger accounts; transferring accounts to income statements, balancing accounts, and preparing statements of financial position
- Source documents: purchase invoices, sales invoices, credit notes, cheque counterfoils, till rolls, cash receipts, paying-in slip counterfoils, bank statements (standing orders, direct debits, credit transfers, dishonoured cheques, debit card transactions, direct transfers)
- Books of prime entry: purchases journal, sales journal, sales returns journal, purchases returns journal, general journal, three-column cash book
- Ledger accounts subdivided into: receivables ledger, payables ledger, general ledger accounts
- Transactions including trade and cash discounts, disposal of non-current assets, irrecoverable debts, and contra entries between customer and supplier accounts
- The distinction between revenue expenditure/income and capital expenditure/income
- Recording adjustments in ledger accounts and financial statements: accruals, prepayments, income due, income received in advance, provisions for doubtful debts, depreciation charges, disposal of non-current assets, opening and closing inventory
- Preparing income statements and statements of financial position from trial balances, for service and trading businesses only (manufacturing accounts are not examined)
- Statements of financial position with subheadings: non-current assets, current assets, capital (equity), non-current liabilities, current liabilities
- Entries for expense prepayments and accruals, irrecoverable debts (including recovery), and depreciation (straight line and reducing balance methods)
How to approach it
The examiners’ own structure is a chain: source document, to book of prime entry, to ledger account, to trial balance, to financial statement. Learn that chain as a single sequence rather than as separate topics, because a question can start anywhere along it – given a source document, post the entry; given a trial balance, prepare the statements. The two depreciation methods (straight line, reducing balance) are frequently tested against each other in the same question, so practise both from the same asset figures to see directly how the annual charge and closing net book value diverge.
Official syllabus
AQA A-level Accounting (7127) specification, first teaching September 2017 – aqa.org.uk.
The recording chain, source to statement
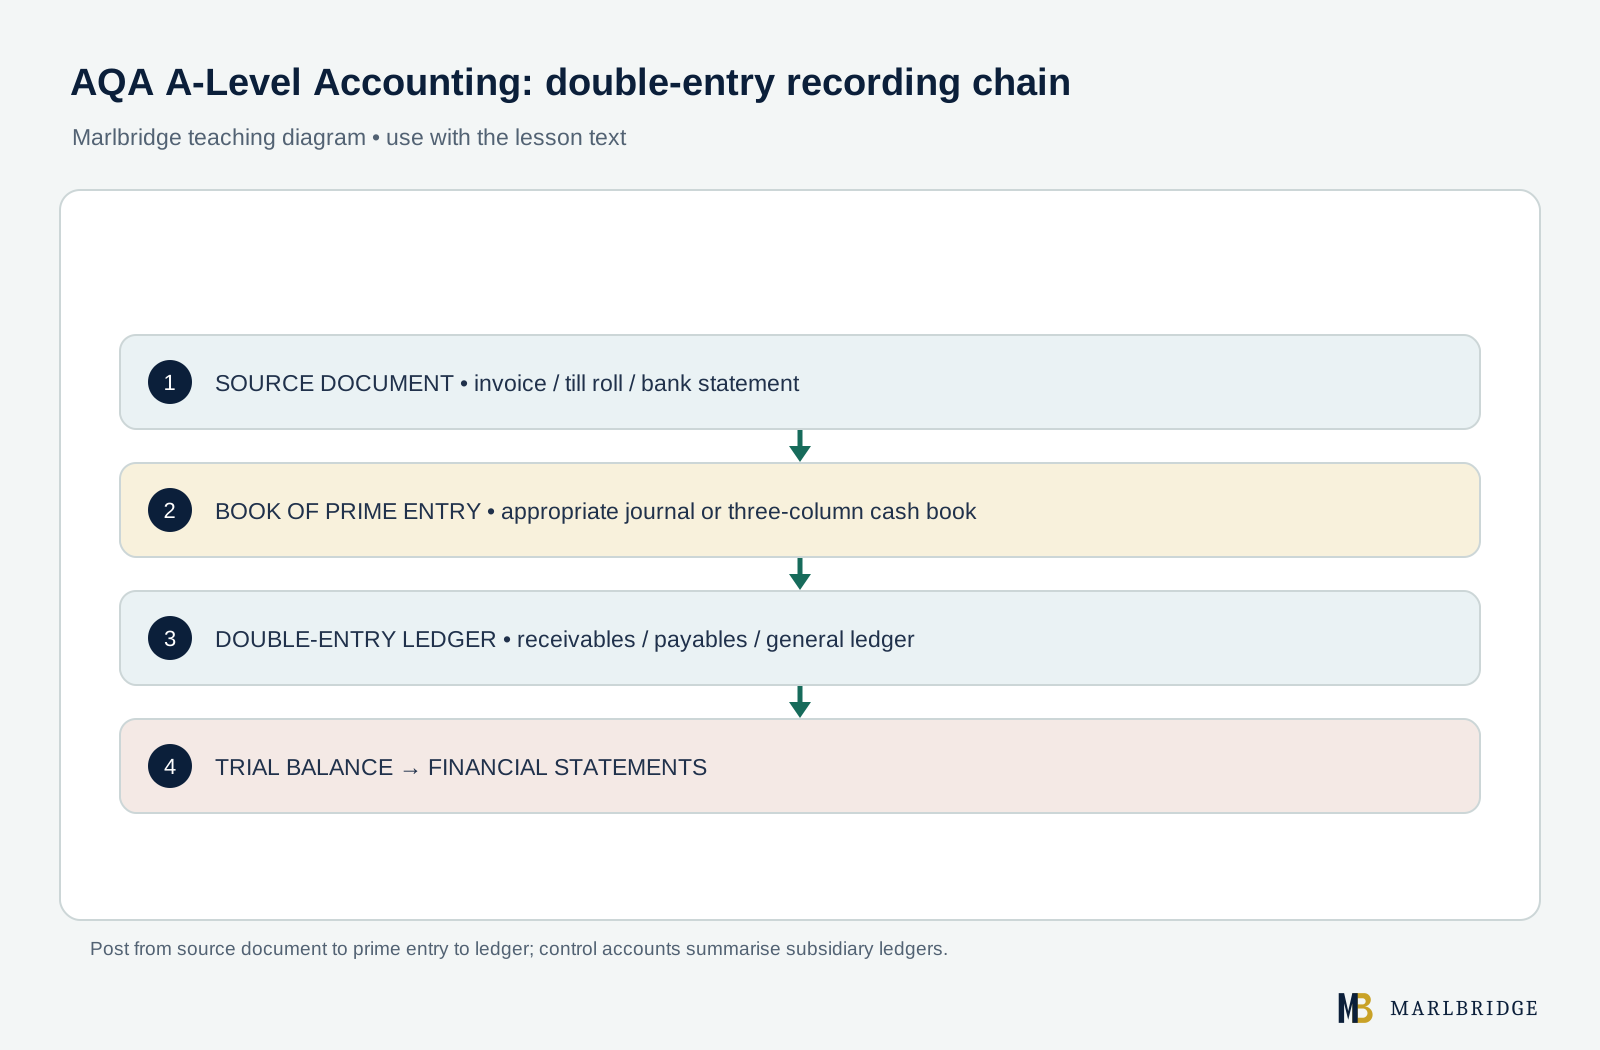
Every transaction starts with a source document (an invoice, a till roll, a bank statement entry). It is first entered into a book of prime entry – the appropriate journal or the three-column cash book – and only from there posted into the double-entry ledger accounts. Ledger accounts are commonly subdivided into a receivables ledger (individual customer balances), a payables ledger (individual supplier balances), and the general ledger (everything else, including the control accounts that summarise the receivables and payables ledgers).
Capital vs revenue
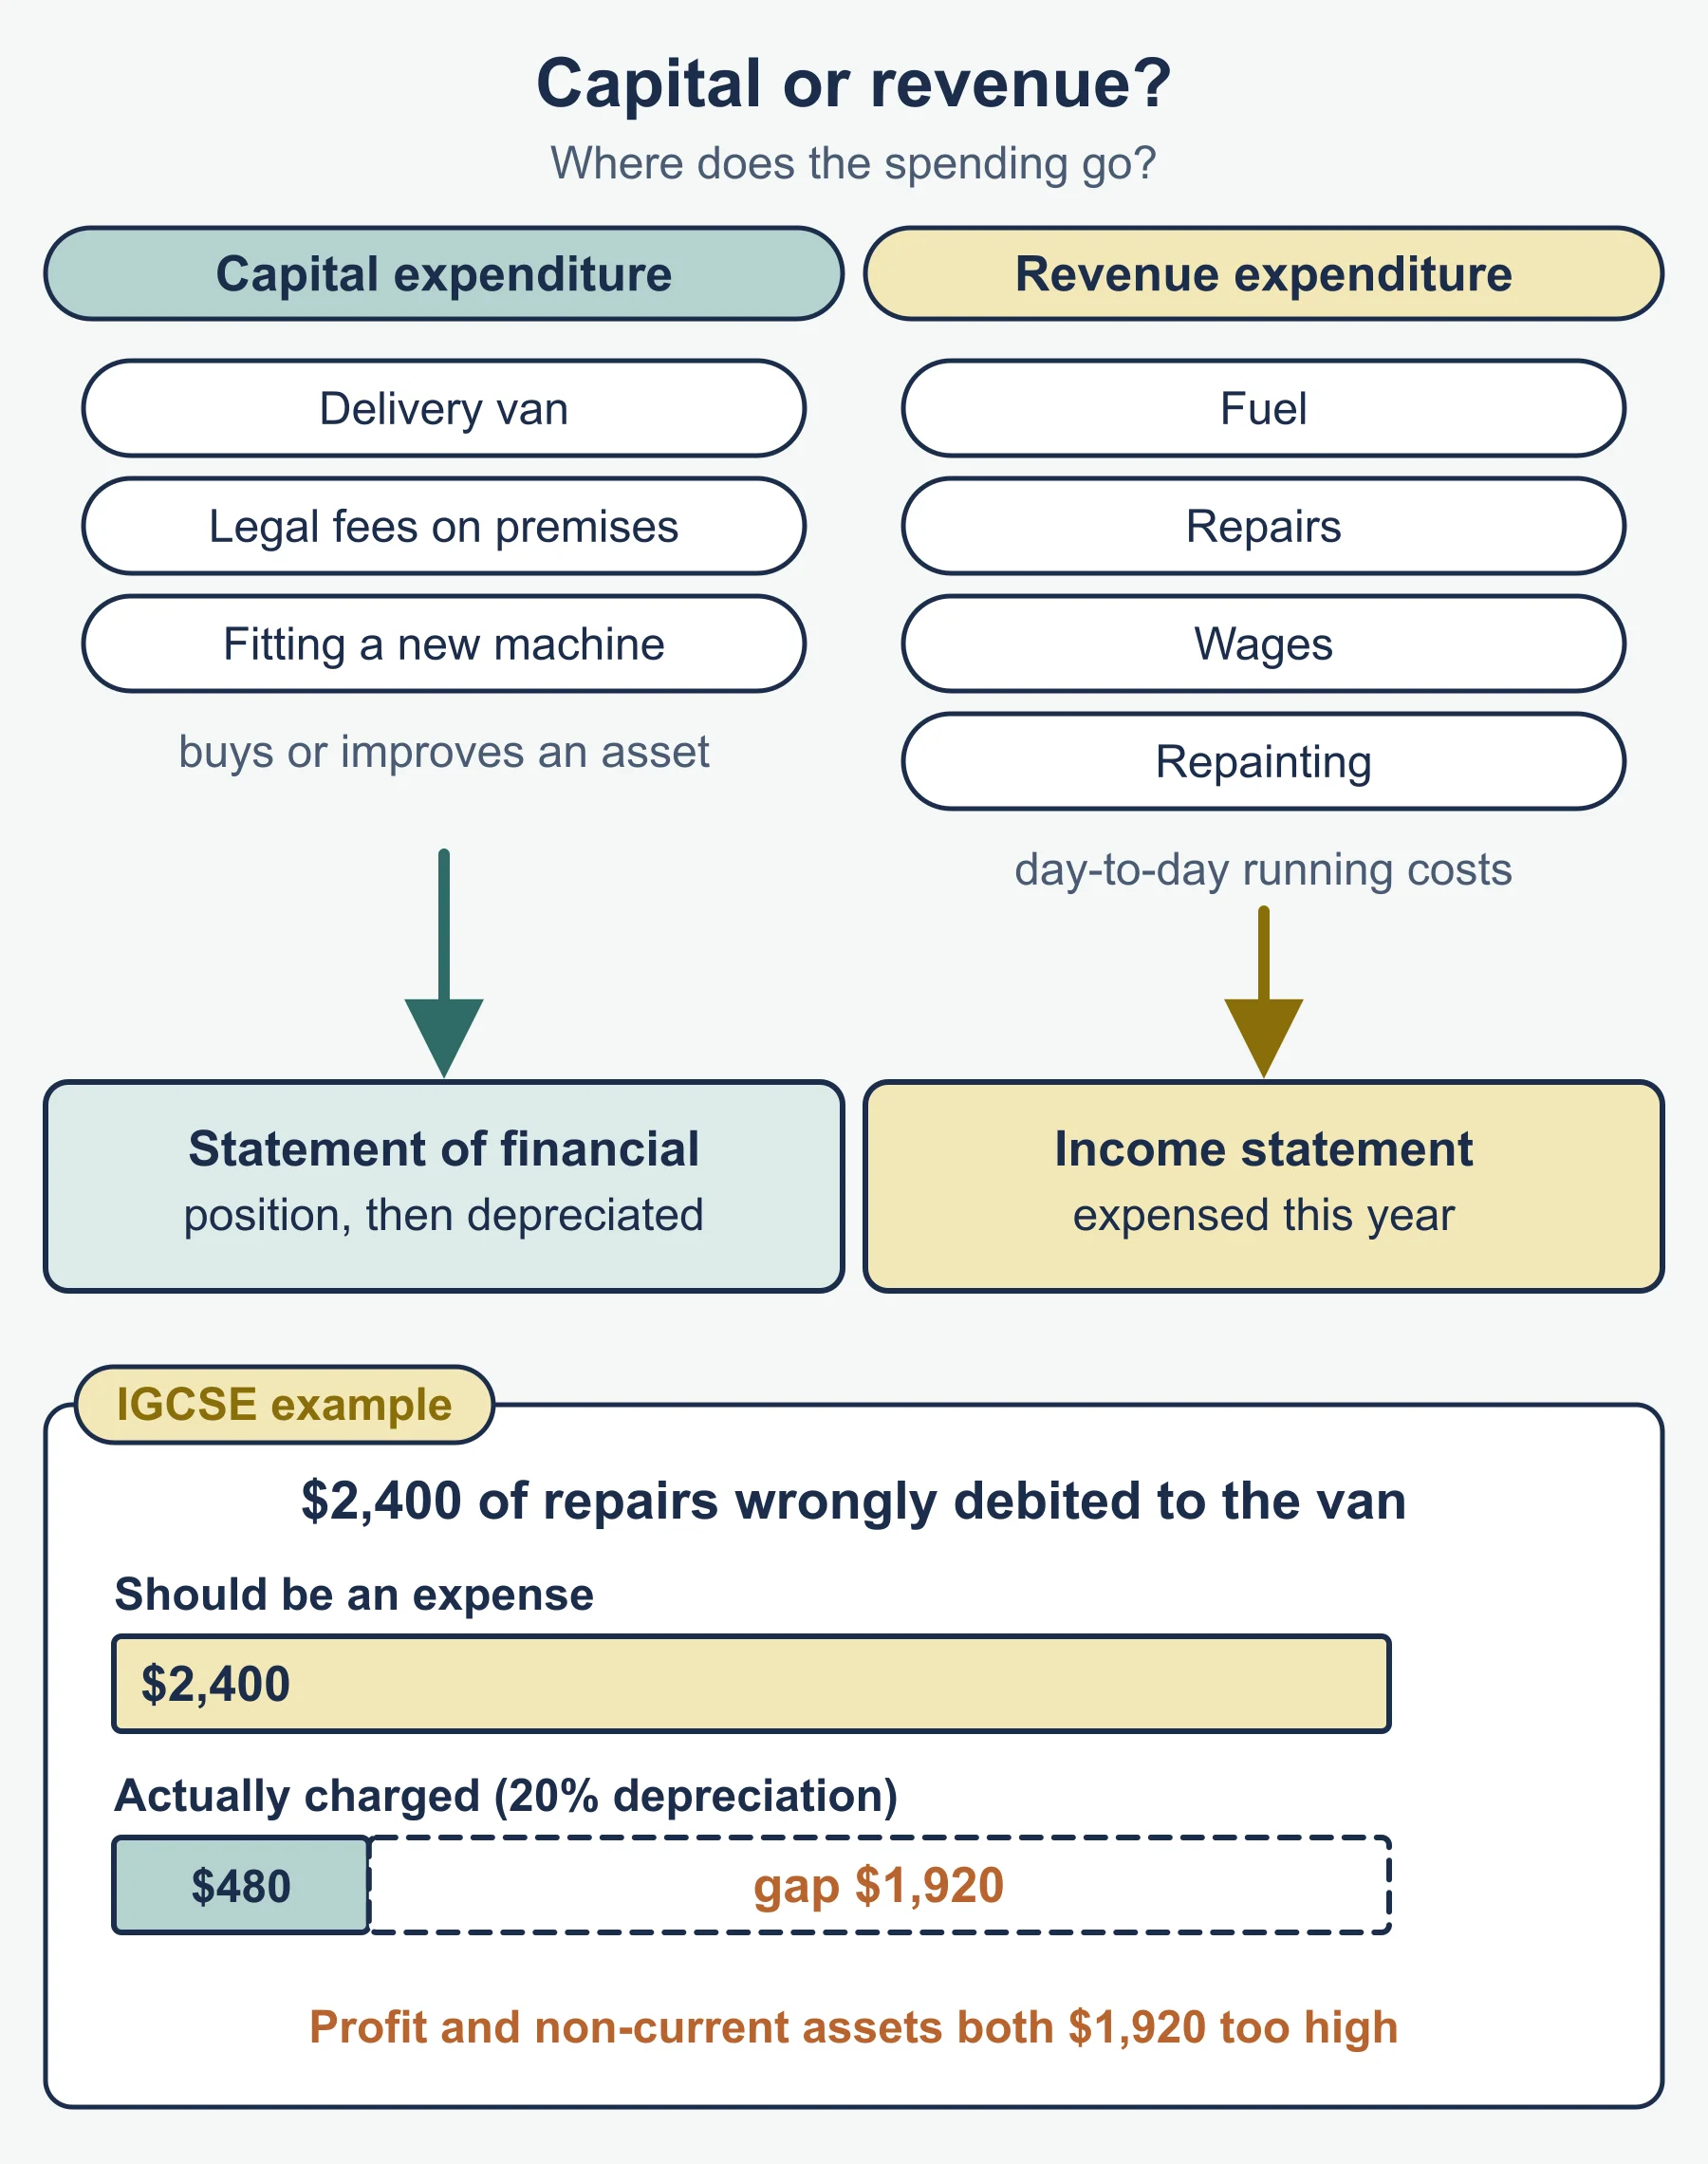
Capital expenditure buys or improves a non-current asset (a new delivery van, an extension to premises); revenue expenditure keeps the business running day to day (fuel, repairs, wages). Misclassifying one as the other distorts both the income statement and the statement of financial position, since capital items belong on the statement of financial position and are depreciated, while revenue items are expensed immediately.
The adjustments that turn a trial balance into financial statements
A trial balance is not yet a set of financial statements – adjustments must be applied first:
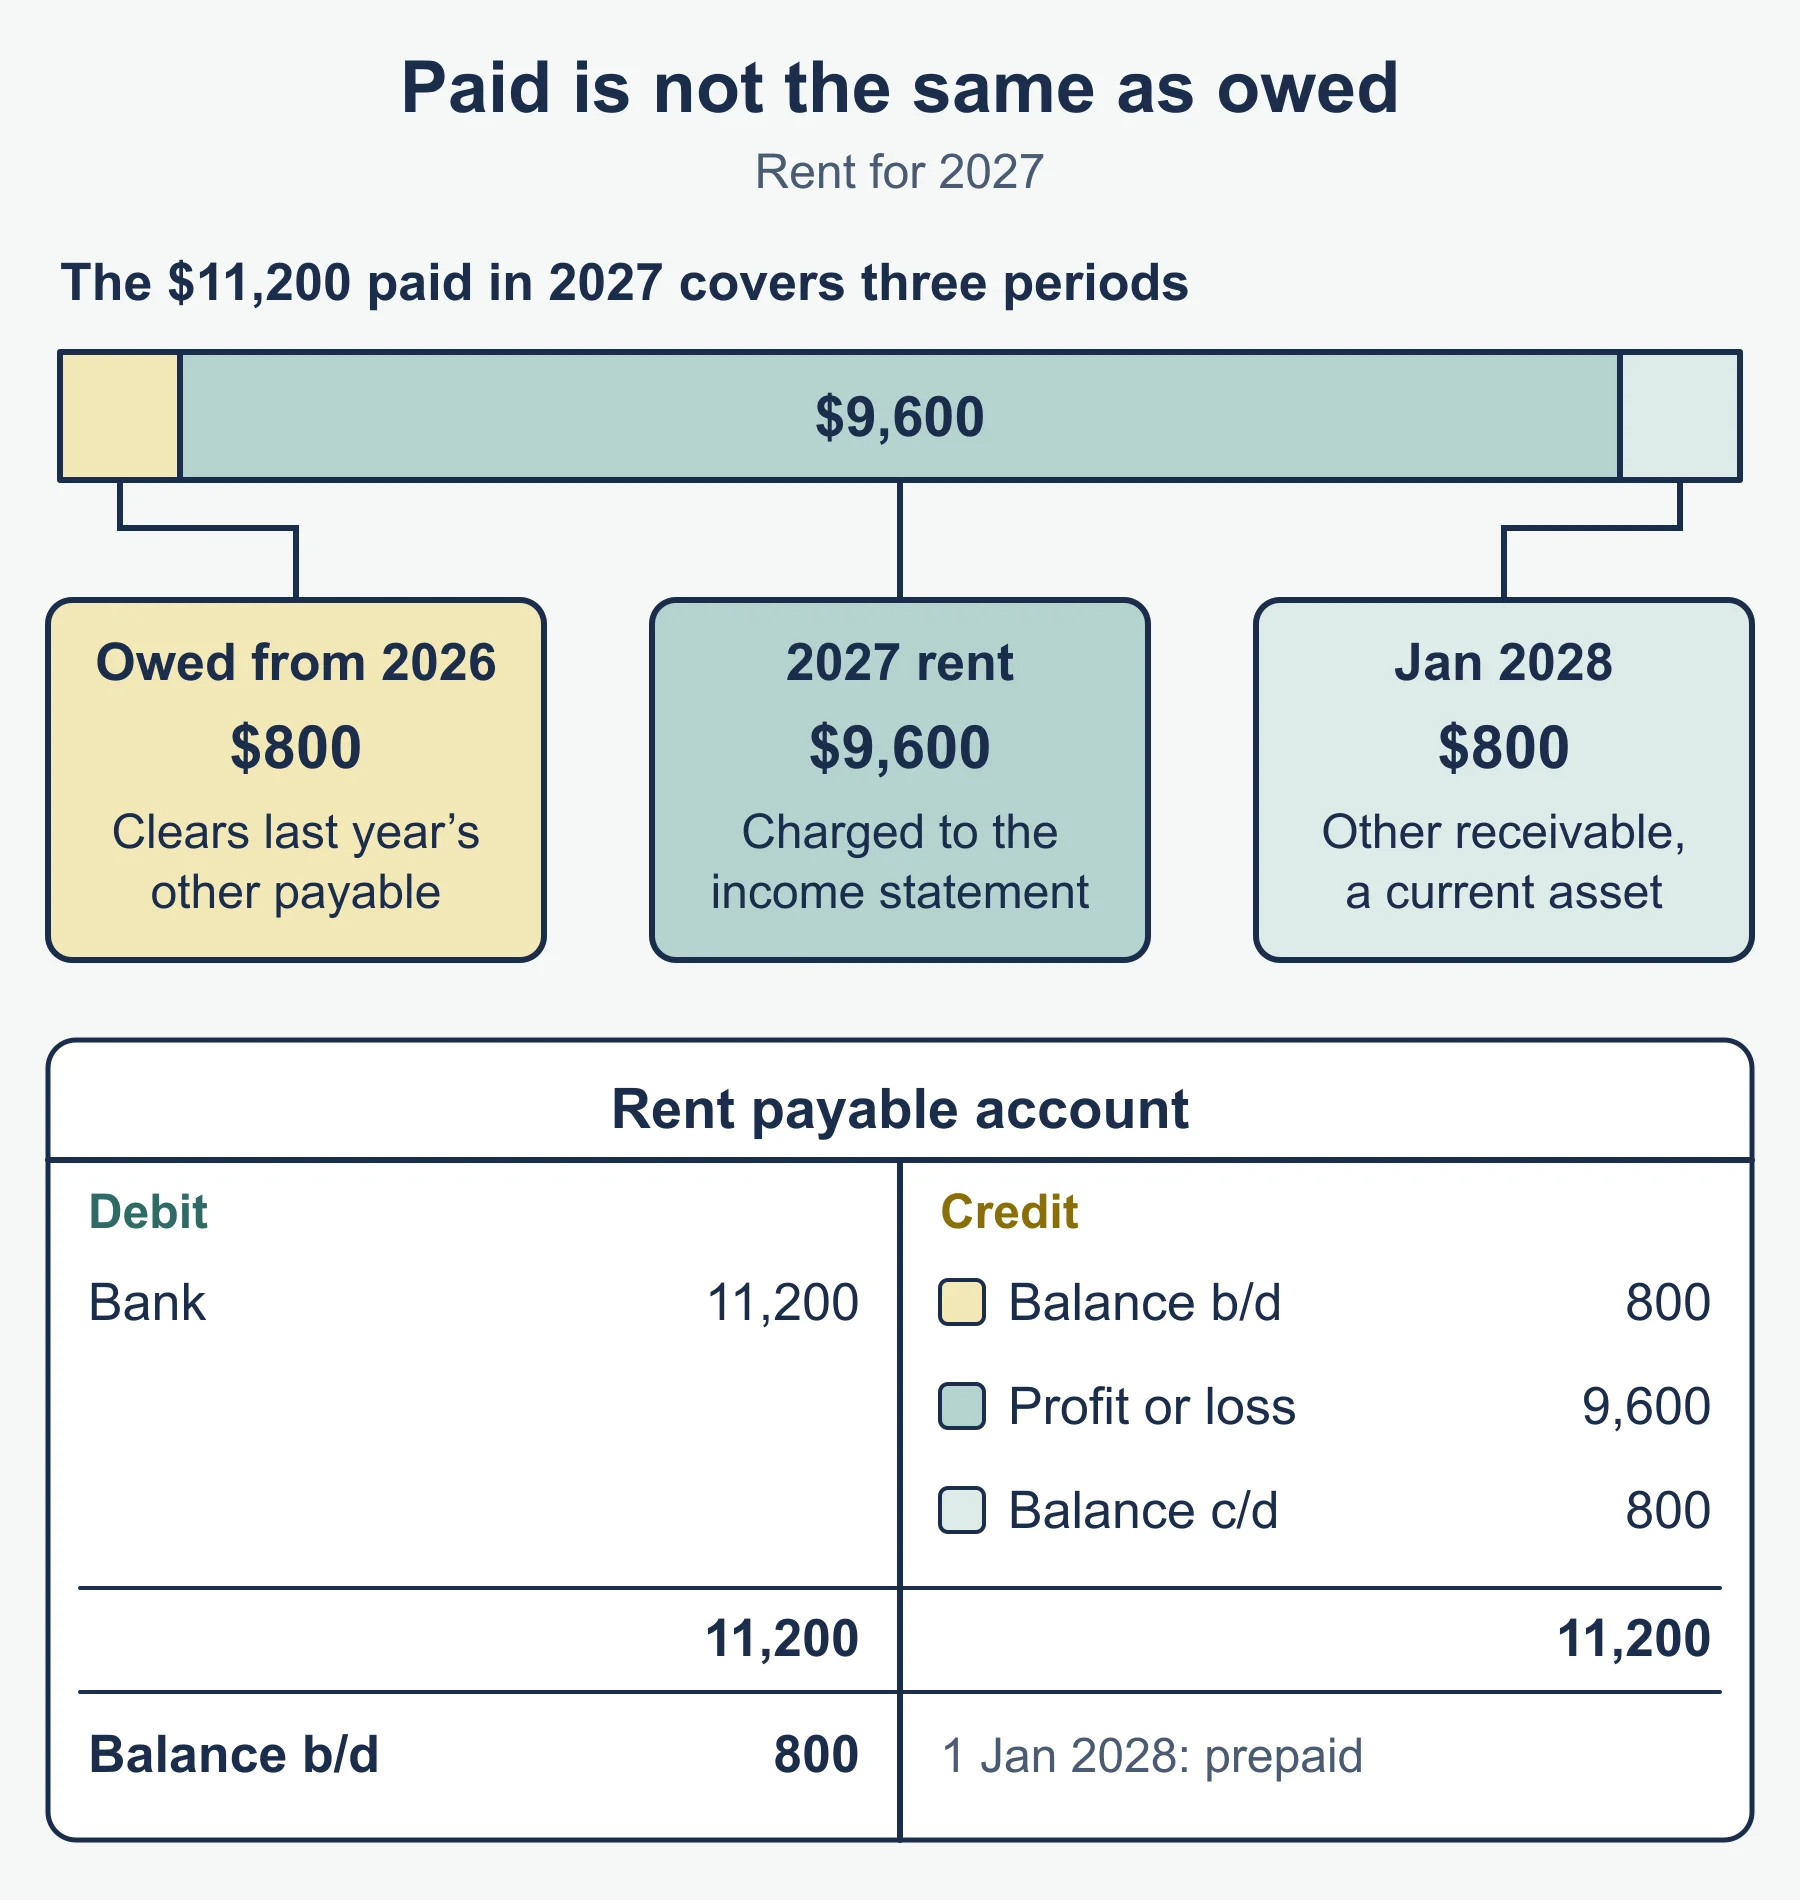
- Accruals and prepayments – expenses incurred but unpaid (accruals) or paid in advance (prepayments) must be matched to the correct accounting period.
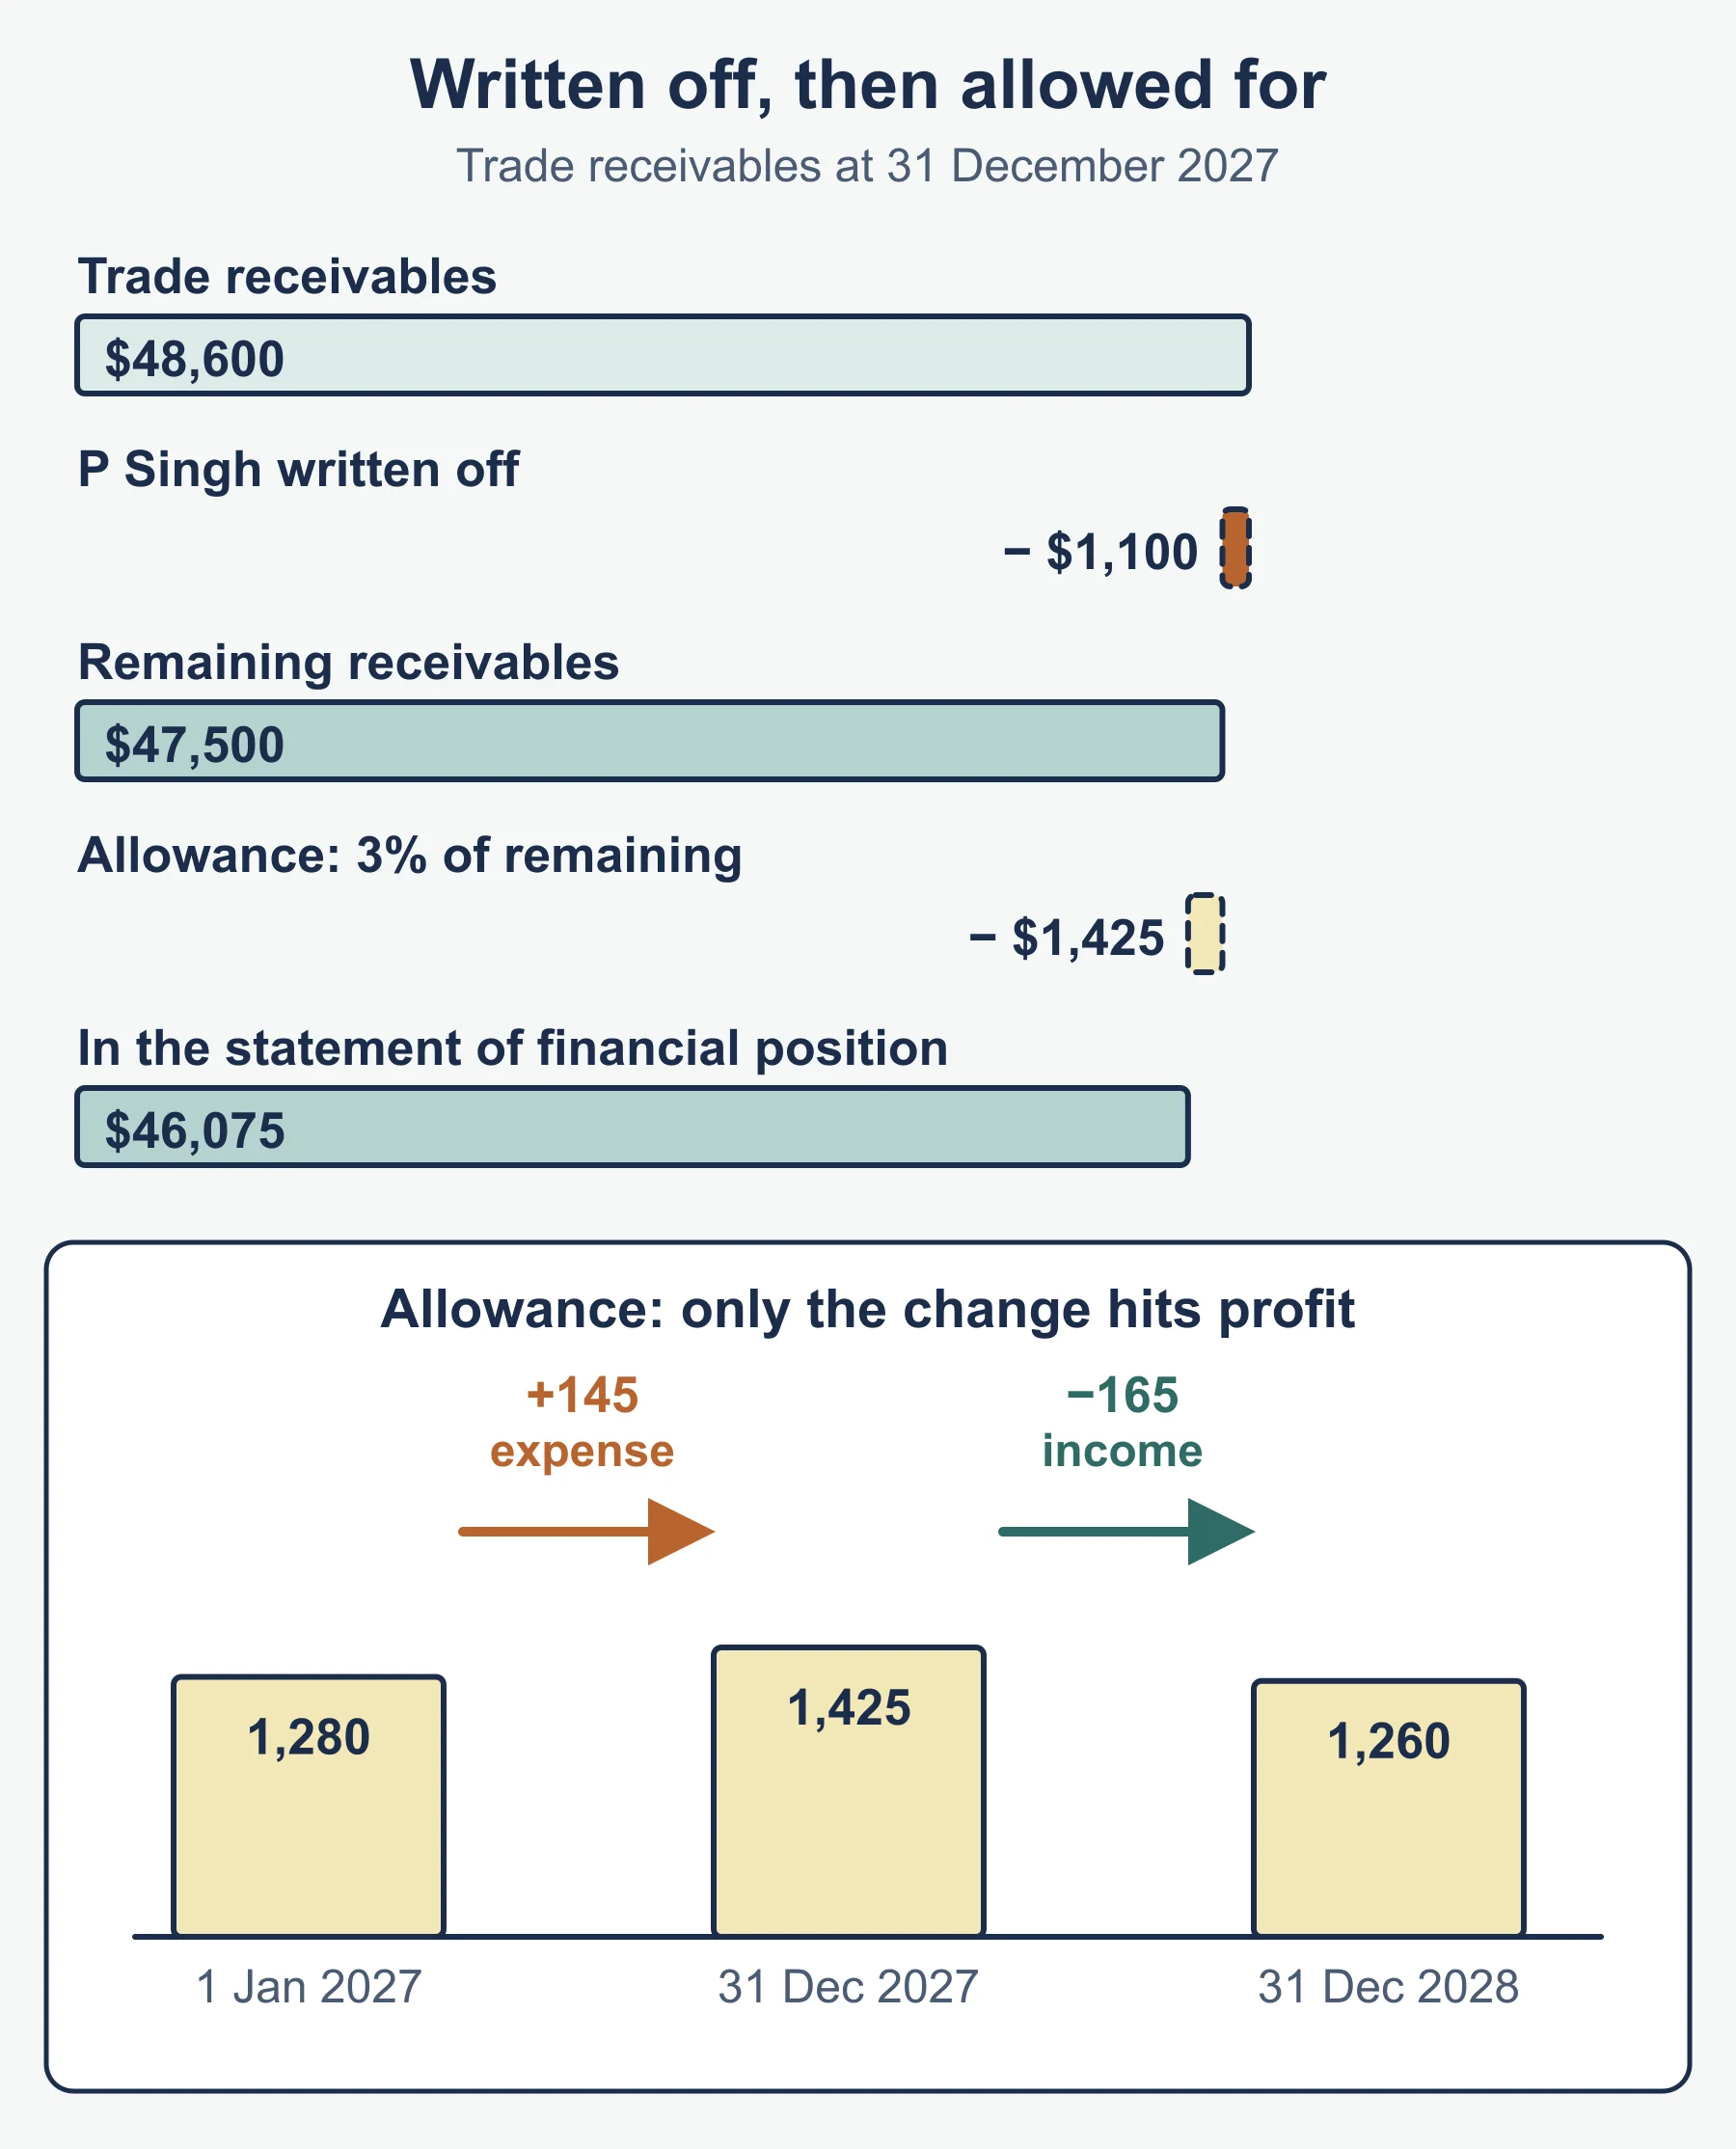
- Irrecoverable debts – written off as an expense; a later recovery is recorded as income, not reversed against the original write-off.
- Depreciation – straight line spreads cost evenly across useful life; reducing balance applies a fixed percentage to the asset’s carrying value each year, so the charge falls over time.
- Opening and closing inventory – adjusts cost of sales in the income statement and appears as a current asset on the statement of financial position.
Worked example: straight line vs reducing balance depreciation
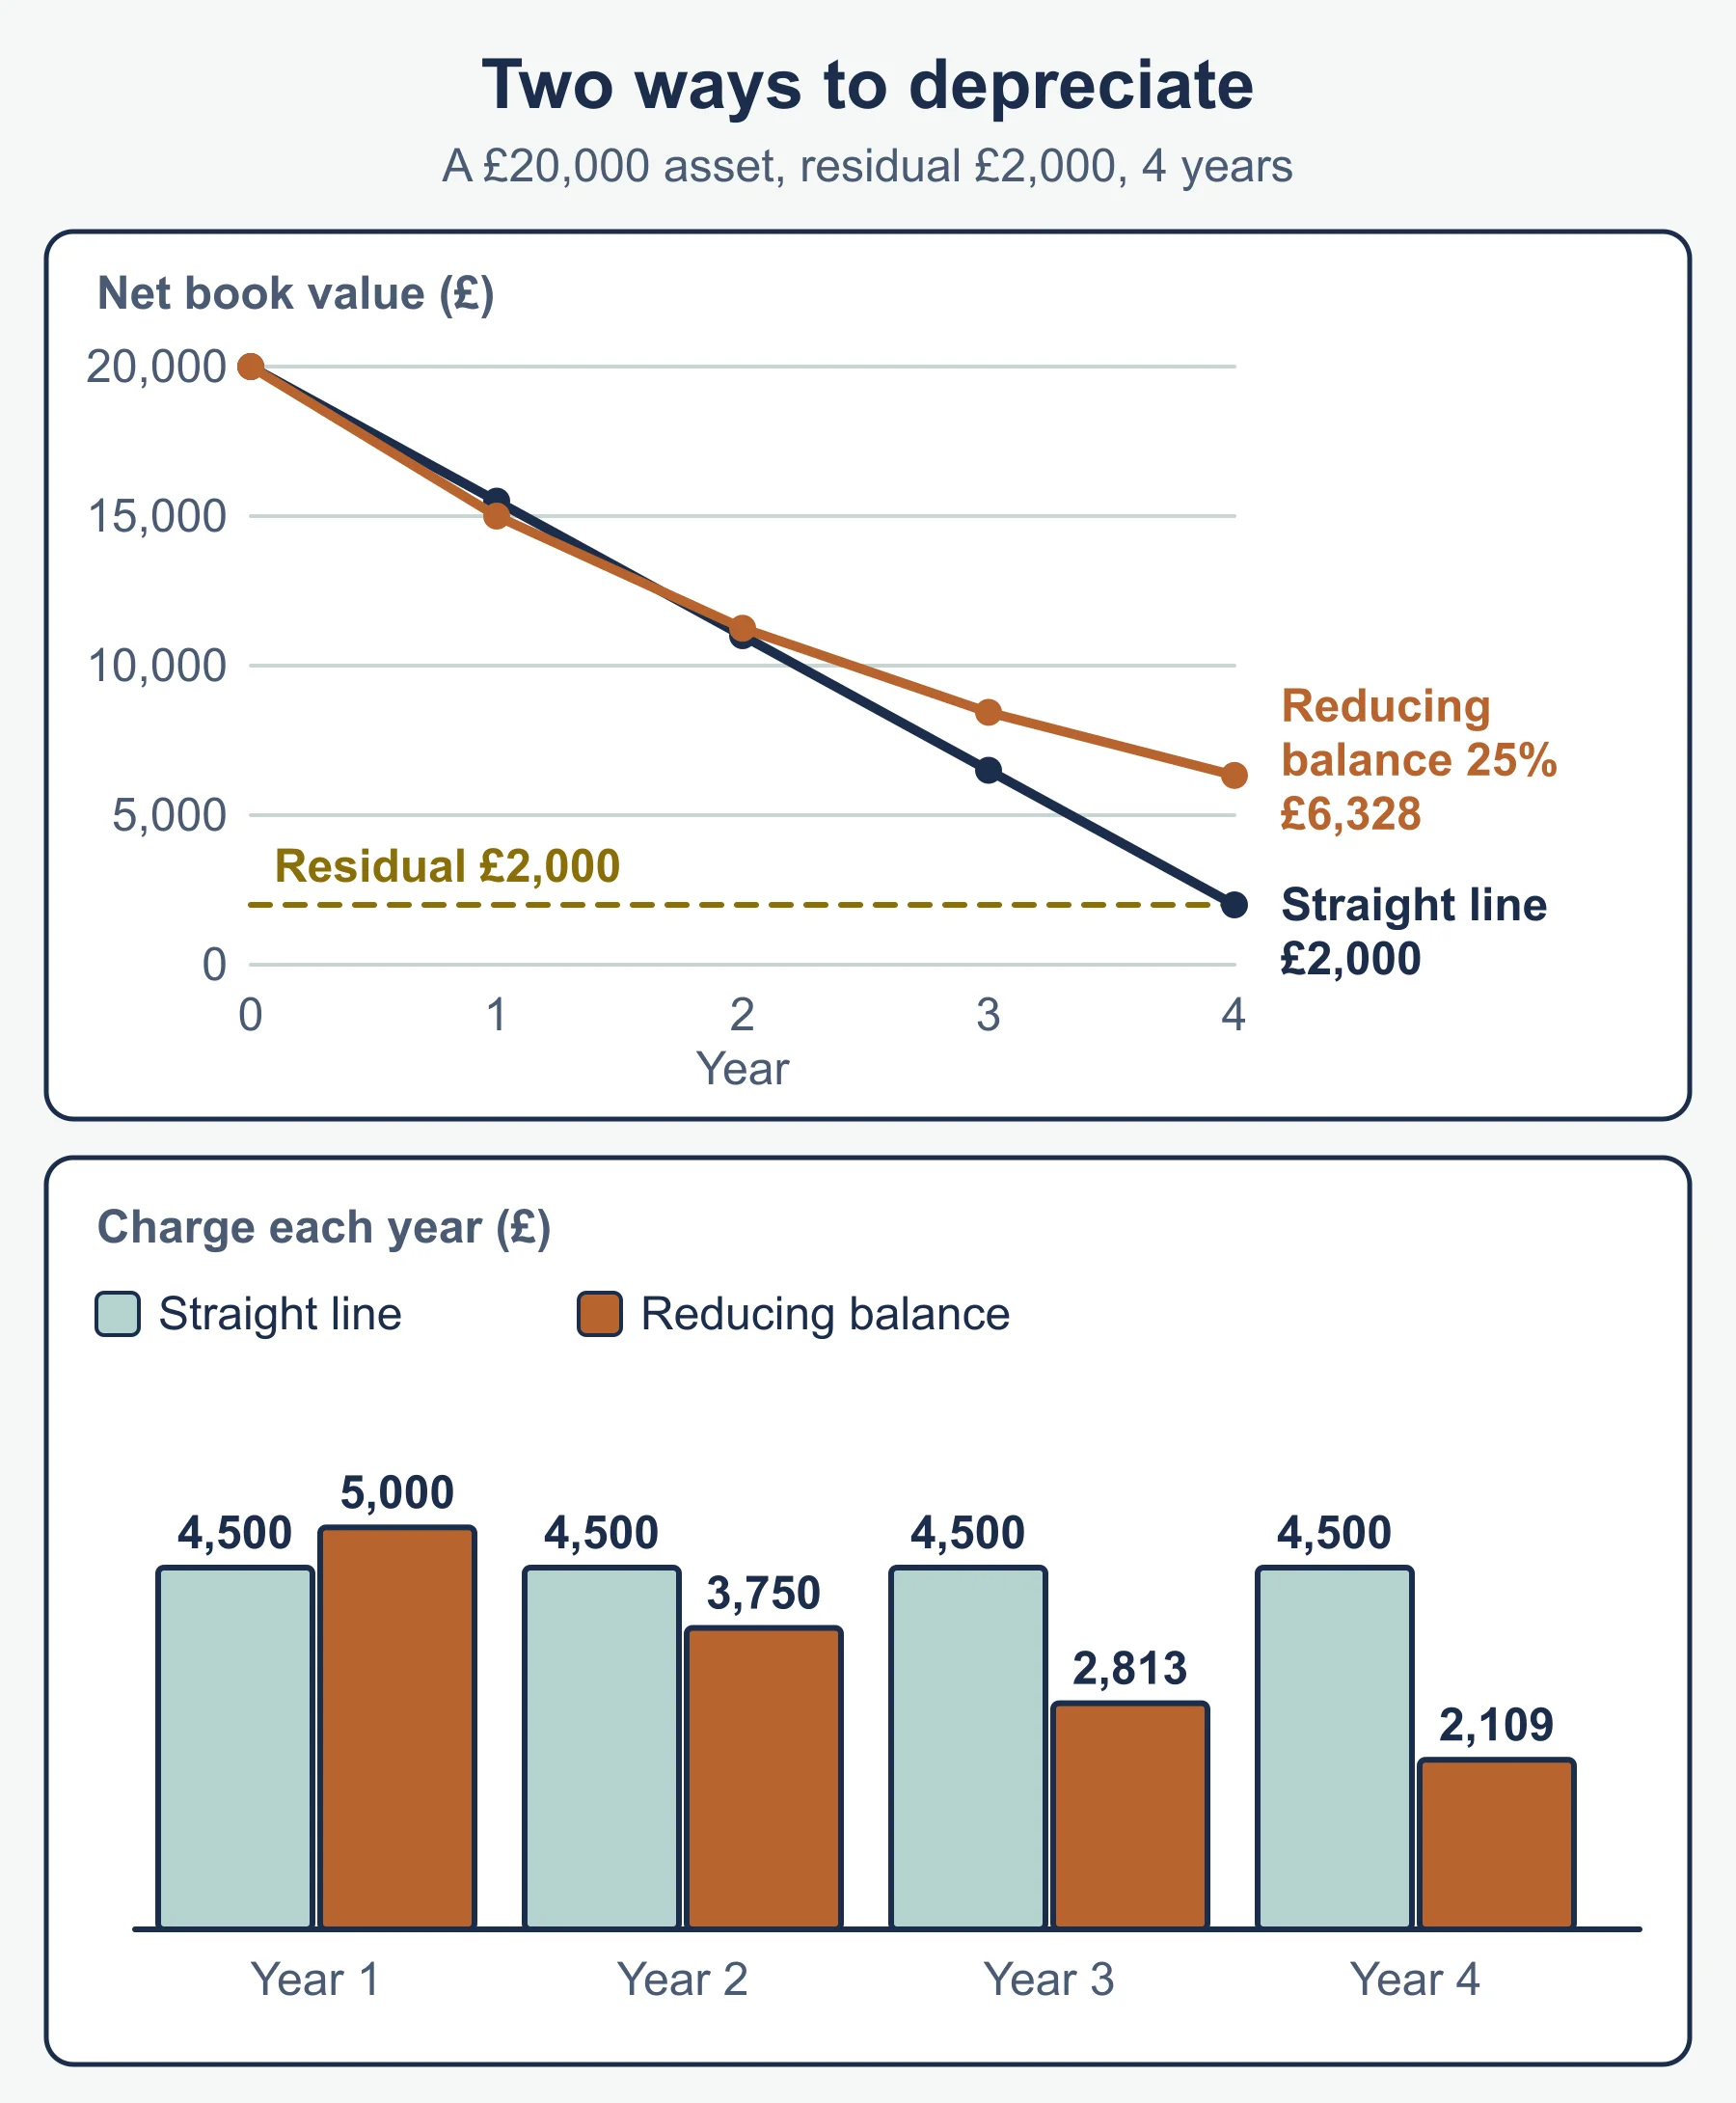
A non-current asset costs £20,000, with an estimated residual value of £2,000 and a 4-year useful life.
Straight line:
Annual charge = (20 000 - 2 000) / 4 = £4 500 per year, every year.

Reducing balance (25% per year, for comparison):
Year 1: 20 000 x 25% = £5 000  -> carrying value 15 000
Year 2: 15 000 x 25% = £3 750  -> carrying value 11 250
Year 3: 11 250 x 25% = £2 813  -> carrying value  8 438 (approx)
Year 4:  8 438 x 25% = £2 109  -> carrying value  6 328 (approx)

Straight line carrying values: 15 500, 11 000, 6 500, 2 000.
Straight line produces a constant annual charge; reducing balance applies its rate to a falling carrying value, so it front-loads the expense. Whether its carrying value is higher or lower than straight line’s in a given year depends on the rate chosen, not on the method. At 25%, the year 1 charge (£5 000) is higher than straight line’s (£4 500) but every later charge is lower, so the carrying value is below straight line’s after year 1 and above it from year 2, ending year 4 at about £6 328 – well above the £2 000 residual value. A rate of about 43.8% would bring the carrying value down to £2 000 after four years (charges of about £8 753, £4 922, £2 768 and £1 557), with a higher charge than straight line in years 1 and 2 and a lower one in years 3 and 4. The two methods charge the same total over the asset’s life only when the reducing-balance rate is set to reach the same residual value.
Common mistakes
Posting directly from a source document to the ledger without going through the correct book of prime entry. Confusing capital and revenue expenditure. Treating a prepayment as a liability instead of a current asset. Reversing an irrecoverable debt write-off instead of recording the recovery as income. Applying reducing balance depreciation to original cost every year instead of to the reducing carrying value. Forgetting closing inventory adjusts cost of sales as well as appearing on the statement of financial position.
Quick revision checklist
- Trace a transaction through the full chain: source document, book of prime entry, ledger account, trial balance, financial statement.
- Correctly classify capital versus revenue expenditure and income.
- Apply accrual and prepayment adjustments to both the income statement and statement of financial position.
- Calculate depreciation by both straight line and reducing balance, and explain why they diverge.
- Record irrecoverable debts and their recovery correctly, without reversing the original write-off.
Frequently asked questions
What are the books of prime entry in AQA A-Level Accounting 7127? The specification names the purchases journal, sales journal, sales returns journal, purchases returns journal, general journal and three-column cash book. Transactions are entered here from source documents before being posted to the ledger accounts.
What is the recording chain in double entry accounting? A transaction moves from a source document, to a book of prime entry, to a ledger account, to the trial balance, and finally to the financial statements. Exam questions can start anywhere along this chain.
How is the recovery of an irrecoverable debt recorded? The recovery is recorded as income; the original write-off is not reversed.
Are manufacturing accounts examined in AQA 7127? No. Income statements and statements of financial position are prepared from trial balances for service and trading businesses only; manufacturing accounts are not examined.
Is a prepayment an asset or a liability? A prepayment is an expense paid in advance, so it is shown as a current asset. Treating it as a liability is a common mistake.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
AQA A-Level Accounting: The double entry model (7127) – Practice Questions
Original practice questions with worked answers on the double entry model for AQA A-Level Accounting: journals, ledgers, adjustments and statements.
Accounting · AQA · A Level
Try questions -
Revision notes
AQA A-Level Accounting: The double entry model (7127) – Revision Notes
Condensed recall notes for the double entry model in AQA A-Level Accounting: documents, journals, ledgers, adjustments and statements, with a self-test.
Accounting · AQA · A Level
Revise topic -
Exam preparation
AQA A-Level Accounting: Paper-by-Paper Exam Preparation
How the two identical AQA A-Level Accounting 7127 papers, with 30, 40 and 50 mark sections and different content, should shape revision, timing and workings.
Accounting · AQA · A Level
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting A LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
AQA Accounting teachers at Marlbridge

