
Study Guides
AQA GCSE Business: Business Operations (8132)
Production methods, procurement and stock management, quality, and customer service – the full content of Topic 3.3 for AQA GCSE Business (8132).
- Subject
- Business
- Level
- GCSE
- Topic
- Business operations
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to AQA GCSE Business (8132), First teaching September 2017. Official specification .
Syllabus page (what it covers and how it is assessed): AQA GCSE Business.
Syllabus points this page covers
8132
- 3.3.1 Production processes
- 3.3.2 The role of procurement
- 3.3.3 The concept of quality
- 3.3.4 Good customer services
Found an error? Report a correction.
Need help with this topic? Request a free trial class for GCSE Business (8132).
This guide covers 3.3 Business operations, the third of six subject-content topics in AQA GCSE Business (8132), first teaching September 2017. It is examined on Paper 1 (Influences of operations and HRM on business activity). These notes complement the site’s guides to Business in the Real World and Technology and Ethical/Environmental Considerations.
Where this fits in 8132
Business operations, human resources, marketing and finance are interdependent – a single business objective typically splits into functional plans across all four areas, with clear links between them. This topic covers what business operations actually involve: their role in producing goods and providing services, and how operational decisions influence the wider business.
Syllabus coverage
AQA GCSE BUSINESS (8132) – 3.3 BUSINESS OPERATIONS
- 3.3.1 Production processes: methods of production (job and flow), and when each is appropriate; efficiency in production through lean production techniques and just in time (JIT)
- 3.3.2 The role of procurement: managing stock via just in time (JIT) versus just in case (JIC), and evaluating JIT’s reduced-cost benefits against the cost of more frequent deliveries and lost purchasing economies of scale, balanced against the benefit of buffer stock versus its holding cost (stock control charts are not required); factors affecting choice of supplier (price, quality, reliability); the effects of procurement and logistics on efficiency and unit costs; the value of effective supply chain management (working with suppliers, best price and value, cutting waste)
- 3.3.3 The concept of quality: consequences of quality issues, including how businesses identify and measure quality problems; methods of maintaining consistent quality through Total Quality Management (TQM); the costs and benefits of maintaining quality (additional sales, reputation, higher price, inspection costs, staff training, product recalls, service provision), including quality issues that can arise from outsourcing and franchising as a business grows
- 3.3.4 Good customer service: methods of good service (product knowledge, customer engagement, post-sales services such as user training, help lines, servicing); benefits of good customer service (satisfaction, loyalty, increased spend, profitability); dangers of poor customer service (dissatisfaction, poor word-of-mouth reputation, reduced revenue); how advances in ICT (websites, e-commerce, social media) have changed customer service
How to approach it
This topic rewards being able to evaluate a trade-off, not just describe a technique – JIT reduces holding costs but increases delivery frequency and risk; TQM improves quality but adds inspection and training costs; good customer service costs money to deliver but builds loyalty and repeat spend. Practise stating both sides of each trade-off and reaching a judgement for a specific business context, since “evaluate” and “to what extent” questions are common at this topic’s highest mark tariffs.
Official syllabus
AQA GCSE Business (8132) specification, first teaching September 2017 – aqa.org.uk.
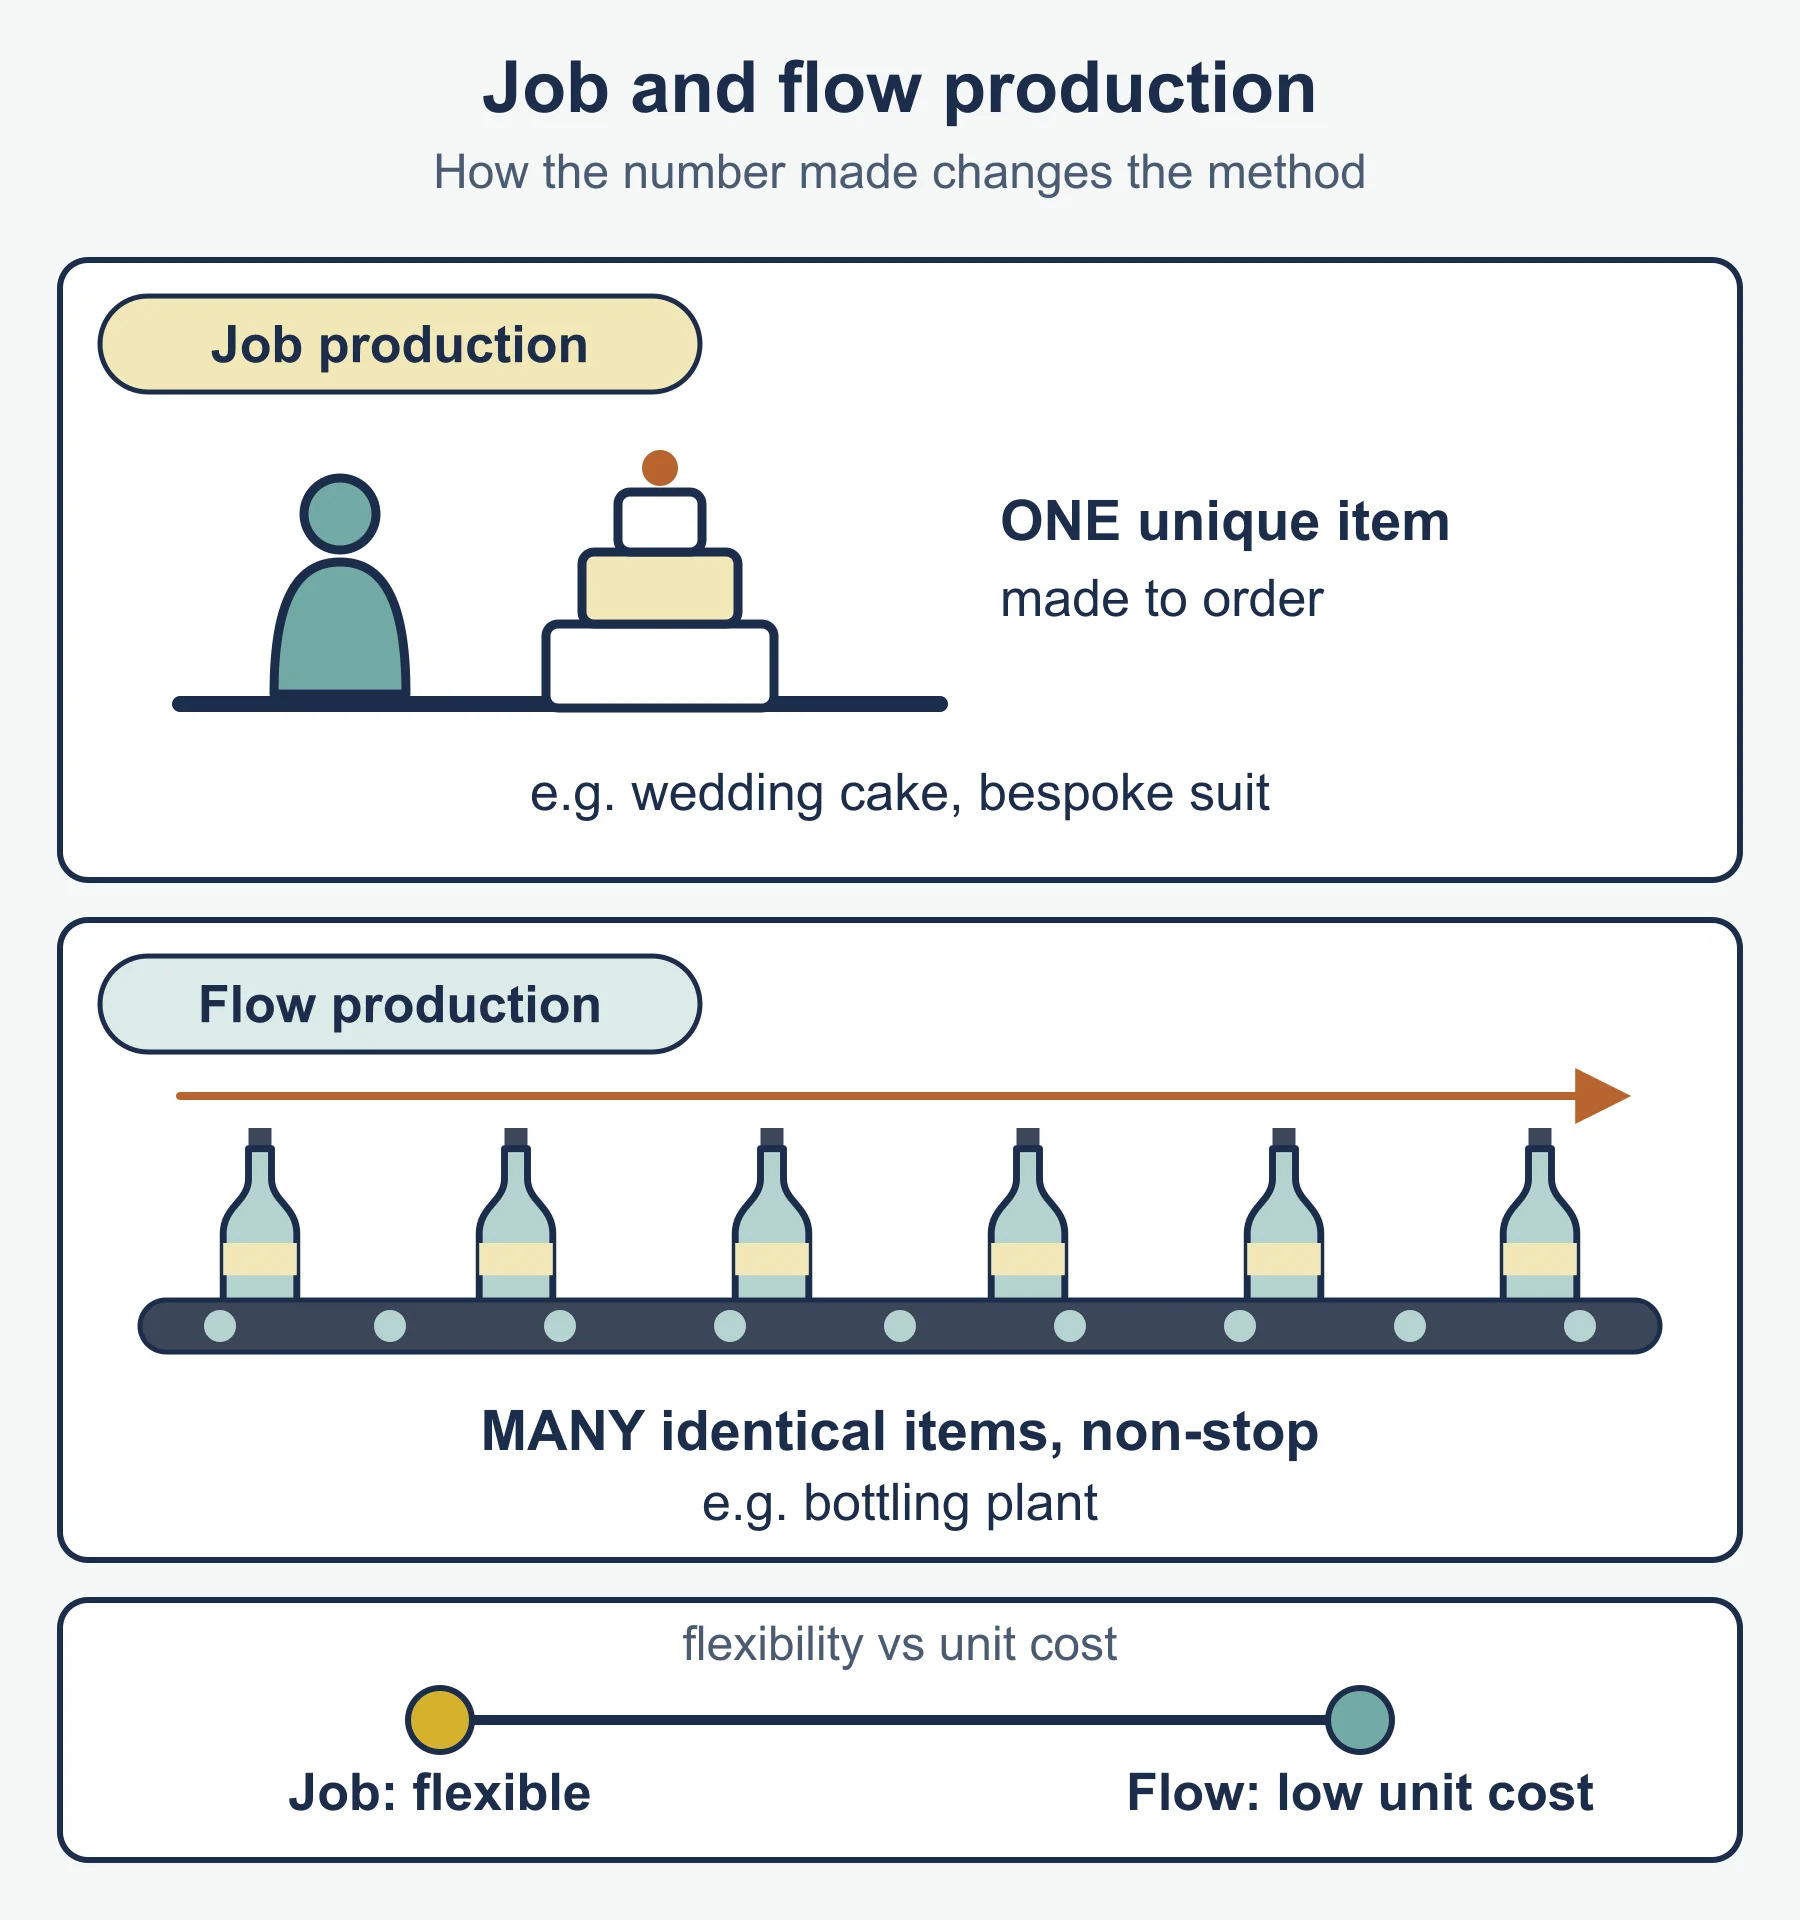
Job vs flow production
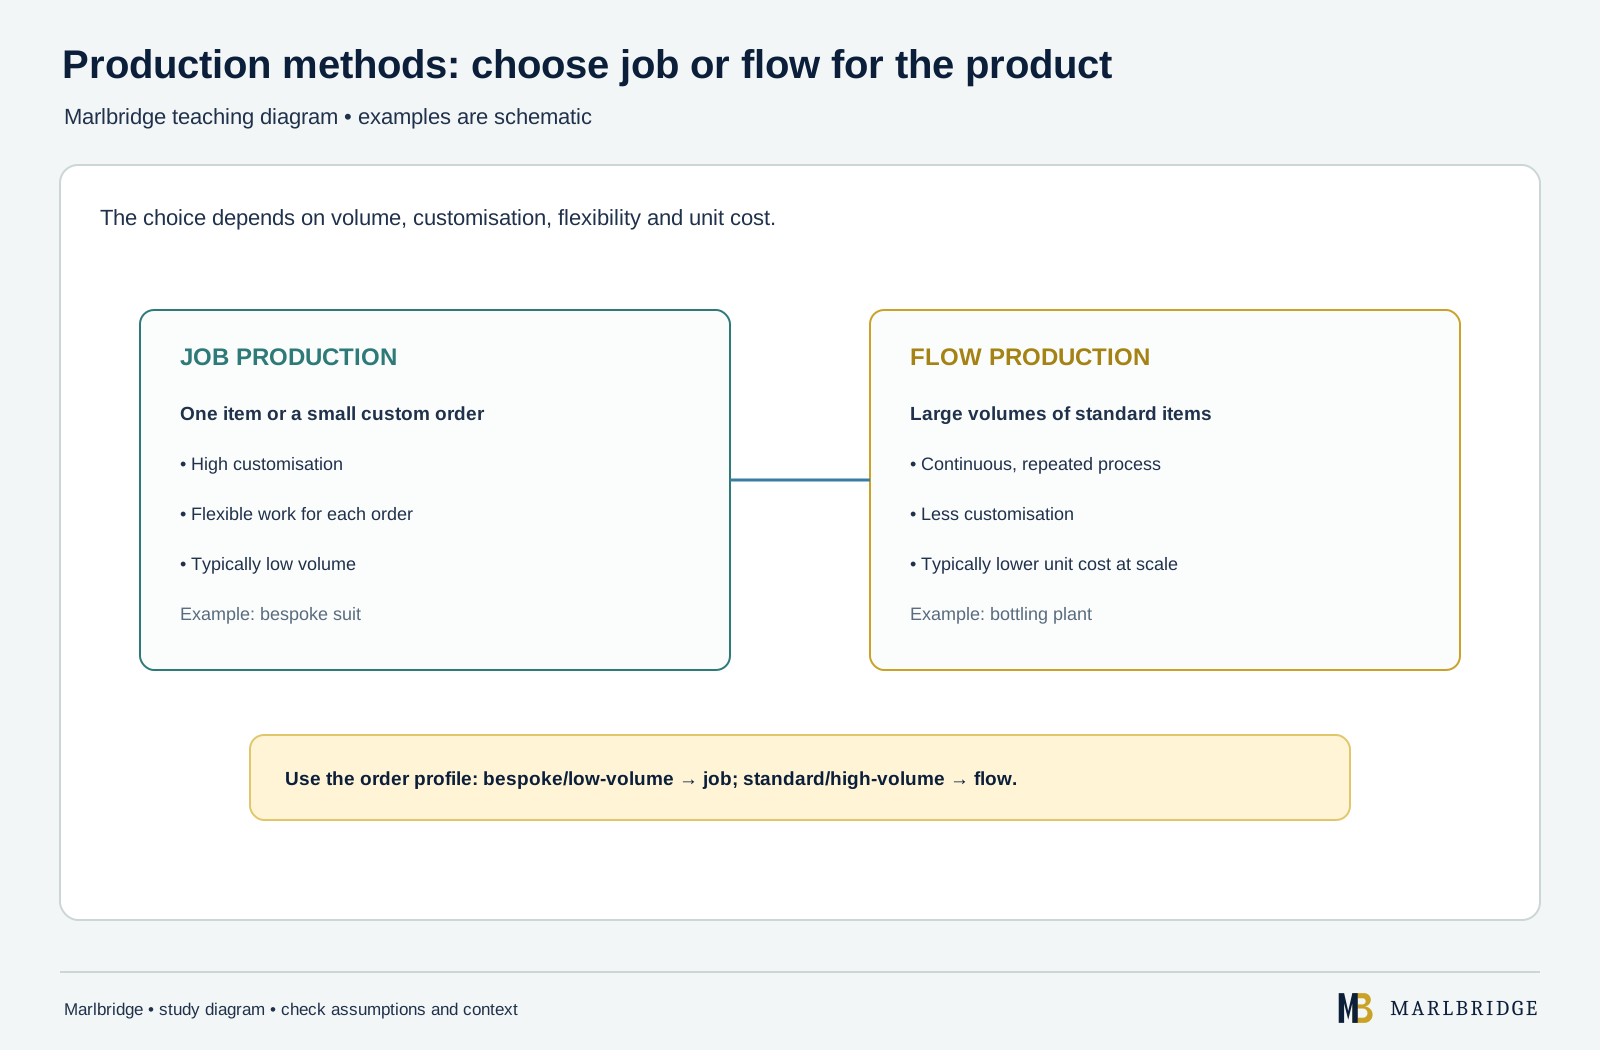
Job production makes single, often unique items to order (a wedding cake, a bespoke suit), suiting low-volume, high-customisation output. Flow production makes large volumes of identical, standardised items continuously (a bottling plant), suiting high-volume, low-customisation output. The choice depends on the product, the market, and the trade-off between flexibility and unit cost.
JIT vs JIC stock management
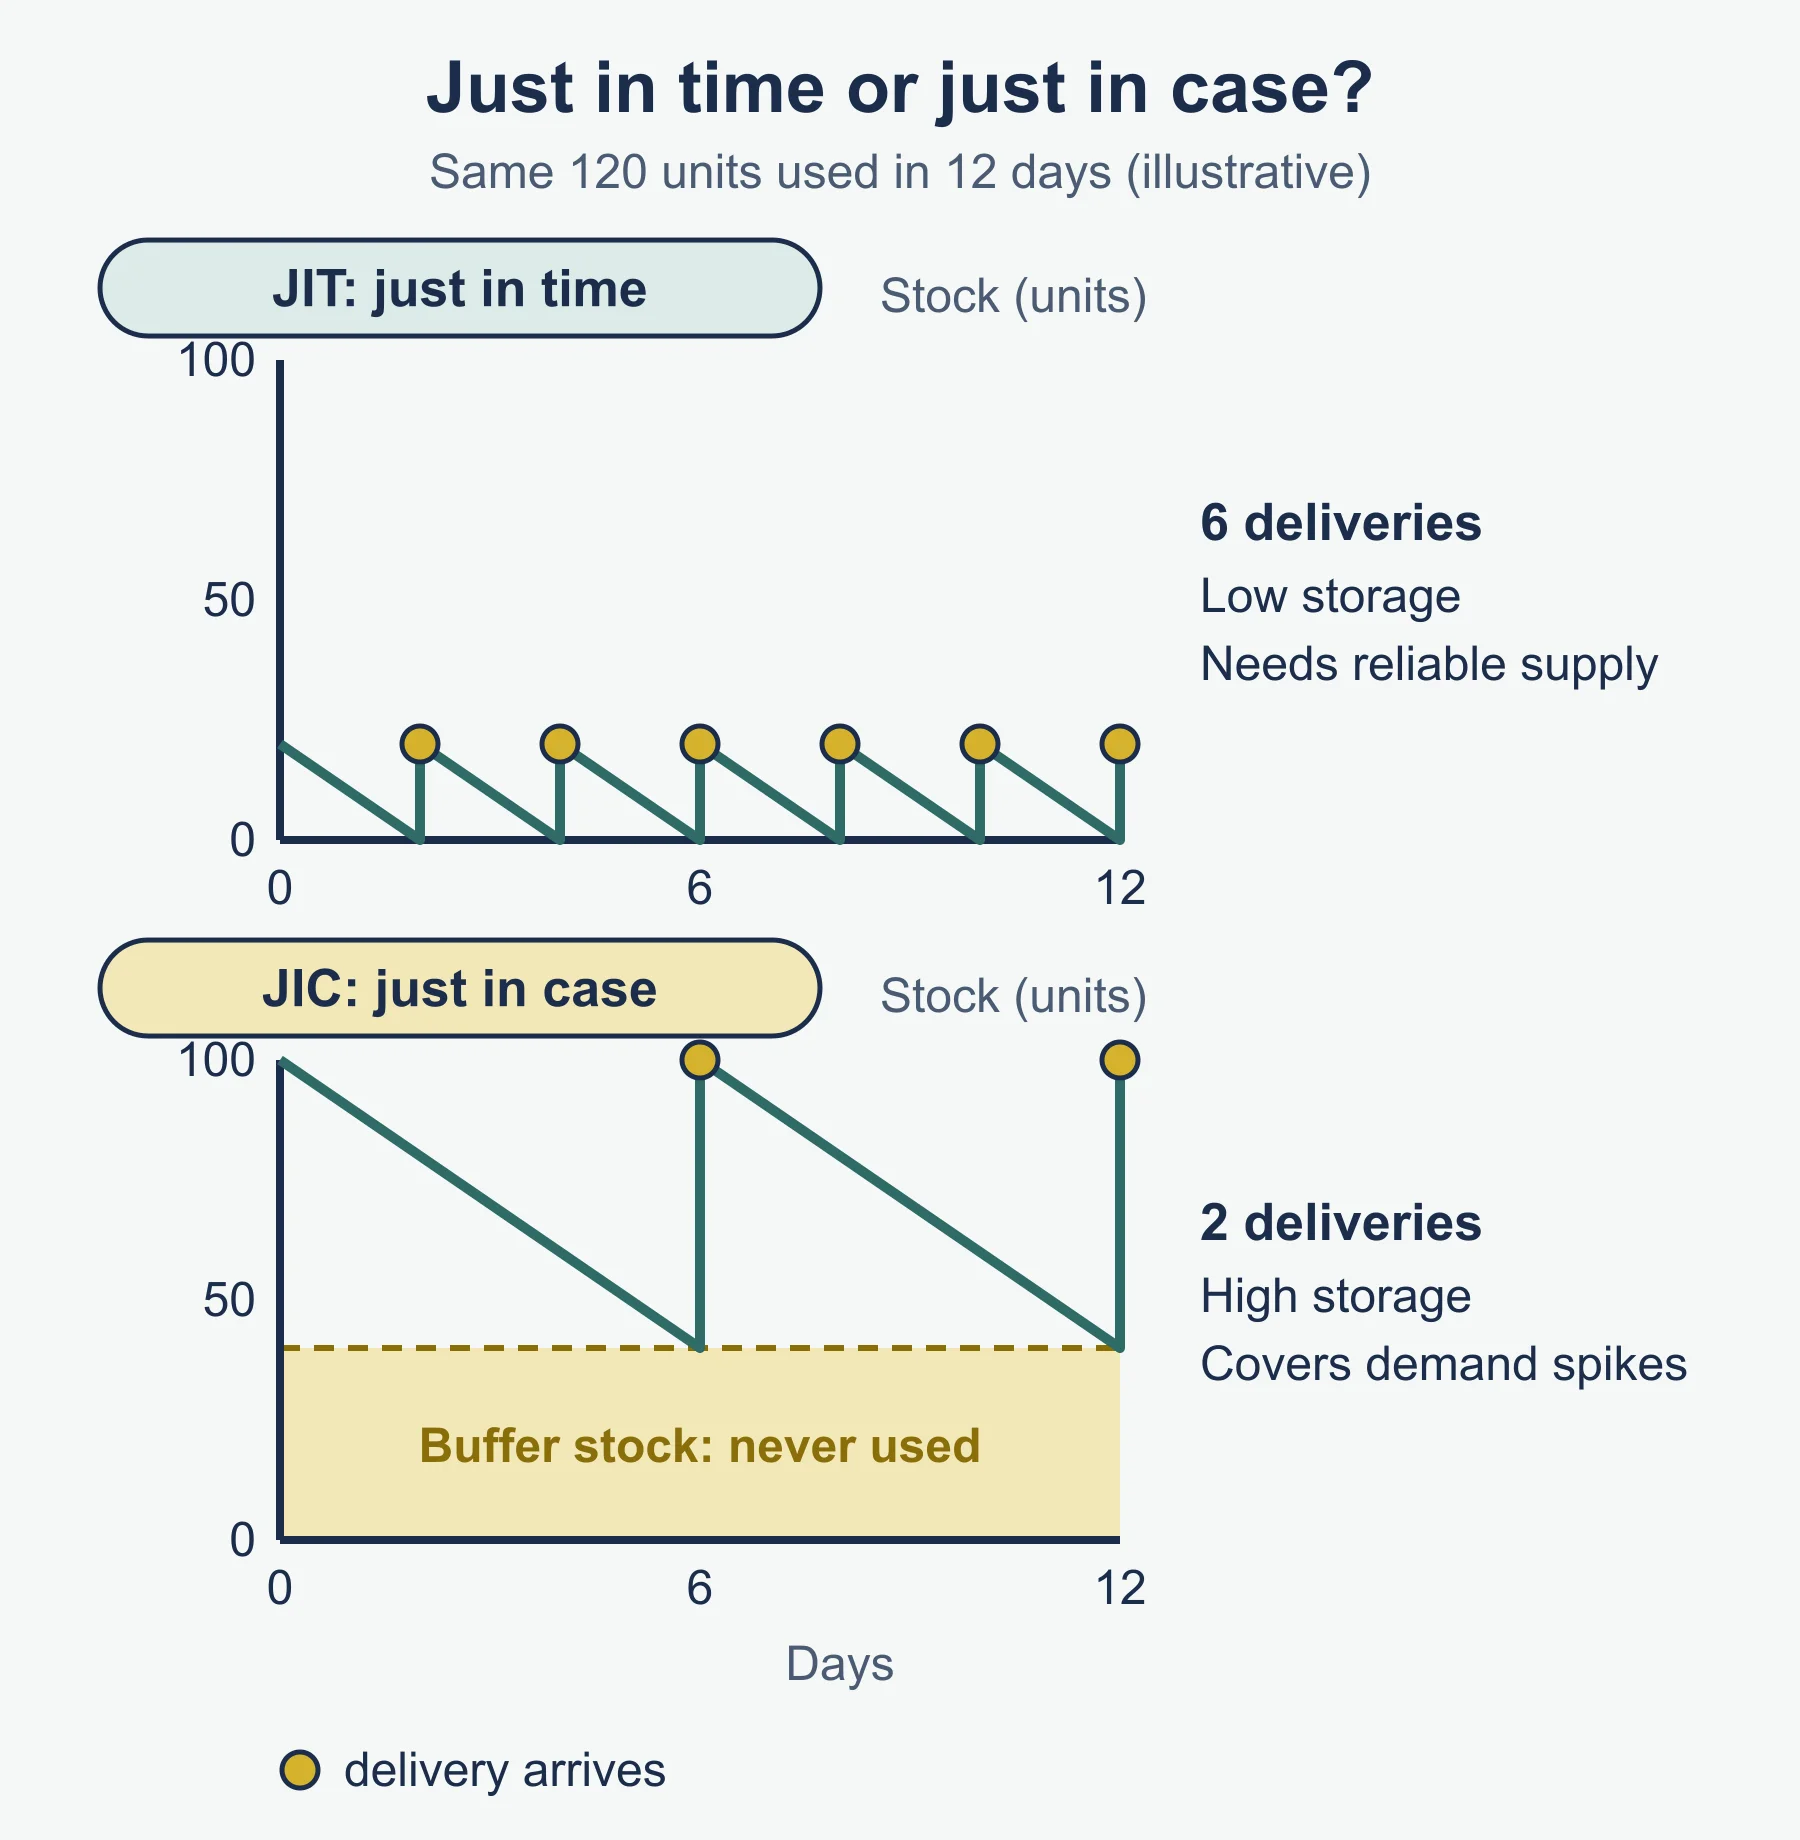
Just in time (JIT) holds minimal stock, ordering only what is needed just before it is used – this cuts storage costs but increases dependence on reliable, frequent deliveries and removes the cushion against sudden demand spikes. Just in case (JIC) holds buffer stock to meet unexpected demand or supply disruption, at the cost of storage and the risk of unsold or obsolete stock. Neither is universally better – the right choice depends on how predictable demand is and how reliable suppliers are.
Worked example: evaluating a quality investment decision
The routine below is an original model written for this resource, not a reproduction of any official past paper or mark scheme.
Scenario: A growing business is considering introducing TQM.

Step 1 - state the immediate cost:
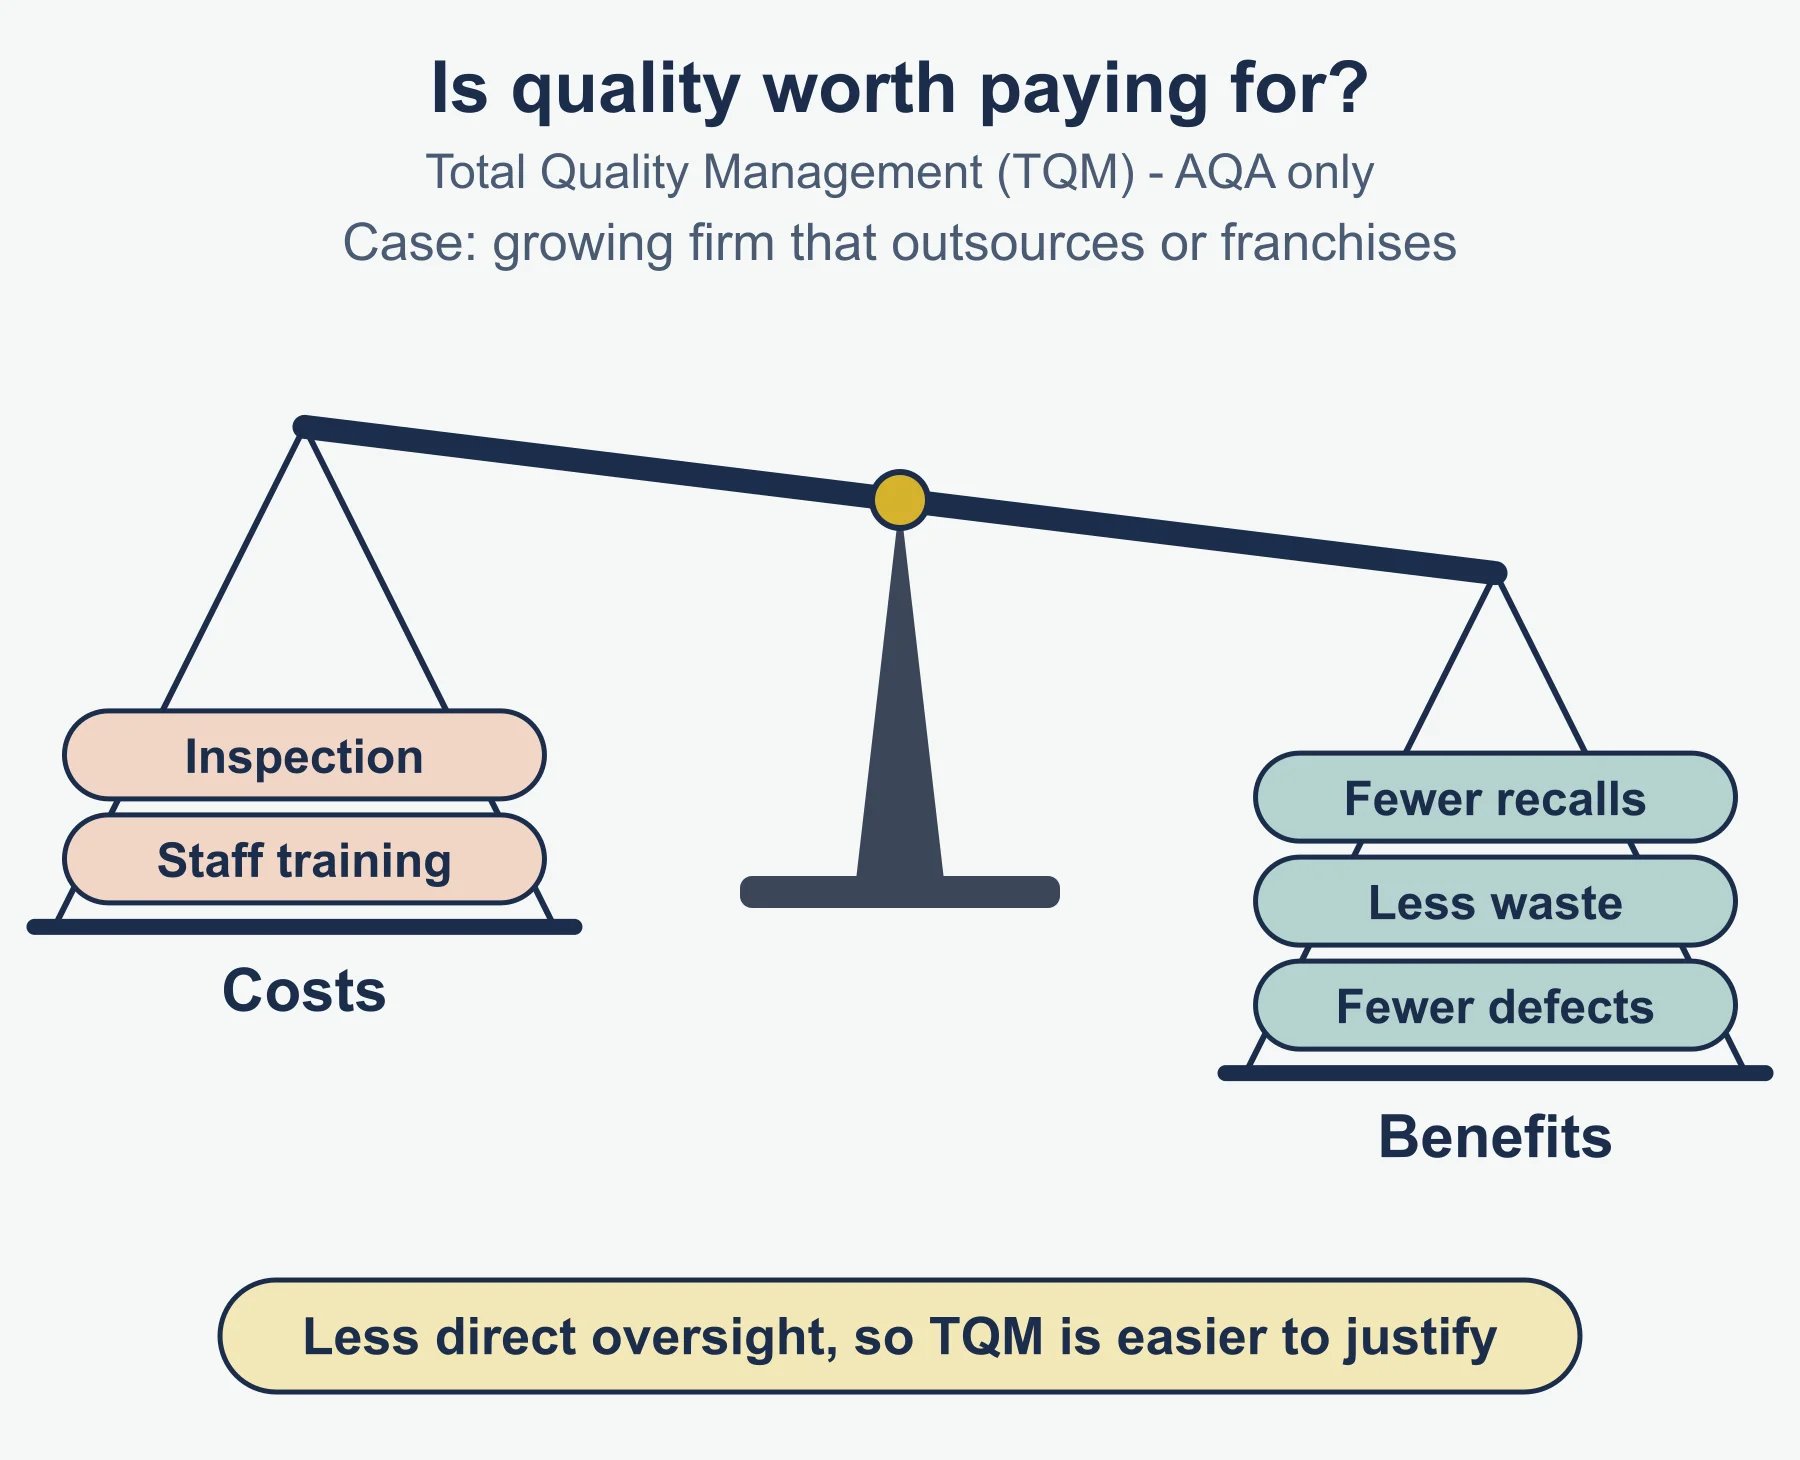
Staff training and inspection costs rise.

Step 2 - state the immediate benefit:
Fewer defects, less waste, fewer costly product recalls.

Step 3 - link to the business's specific growth context:
A growing business franchising or outsourcing production faces
greater quality-control risk, since it has less direct oversight
of every unit produced.

Step 4 - reach a judgement:
For a business scaling through outsourcing/franchising
specifically, TQM's upfront cost is more easily justified than
for a small, tightly controlled operation where quality is
already easy to monitor directly.
Step 4 shows the evaluative move examiners reward: not “TQM is good” or “TQM is expensive” alone, but a judgement that depends on the business’s specific situation.
Common mistakes
Describing JIT and JIC as though one is simply correct in all situations, rather than each suiting different circumstances. Confusing production methods (job, flow) with stock management methods (JIT, JIC) – they are separate decisions. Listing quality costs and benefits without linking them to a specific business scenario. Describing customer service only in terms of politeness, missing the syllabus’s specific methods (product knowledge, engagement, post-sales service) and ICT developments.
Quick revision checklist
- Distinguish job and flow production, and state when each is appropriate.
- Evaluate JIT against JIC stock management for a given business scenario.
- Explain the factors affecting choice of supplier and the value of supply chain management.
- Evaluate the costs and benefits of maintaining quality through TQM, including risks from outsourcing and franchising.
- Explain how good customer service benefits a business, and how poor service and ICT developments both affect it.
Frequently asked questions
Which paper is Business operations examined on in AQA GCSE Business (8132)? Topic 3.3 Business operations is examined on Paper 1, Influences of operations and HRM on business activity.
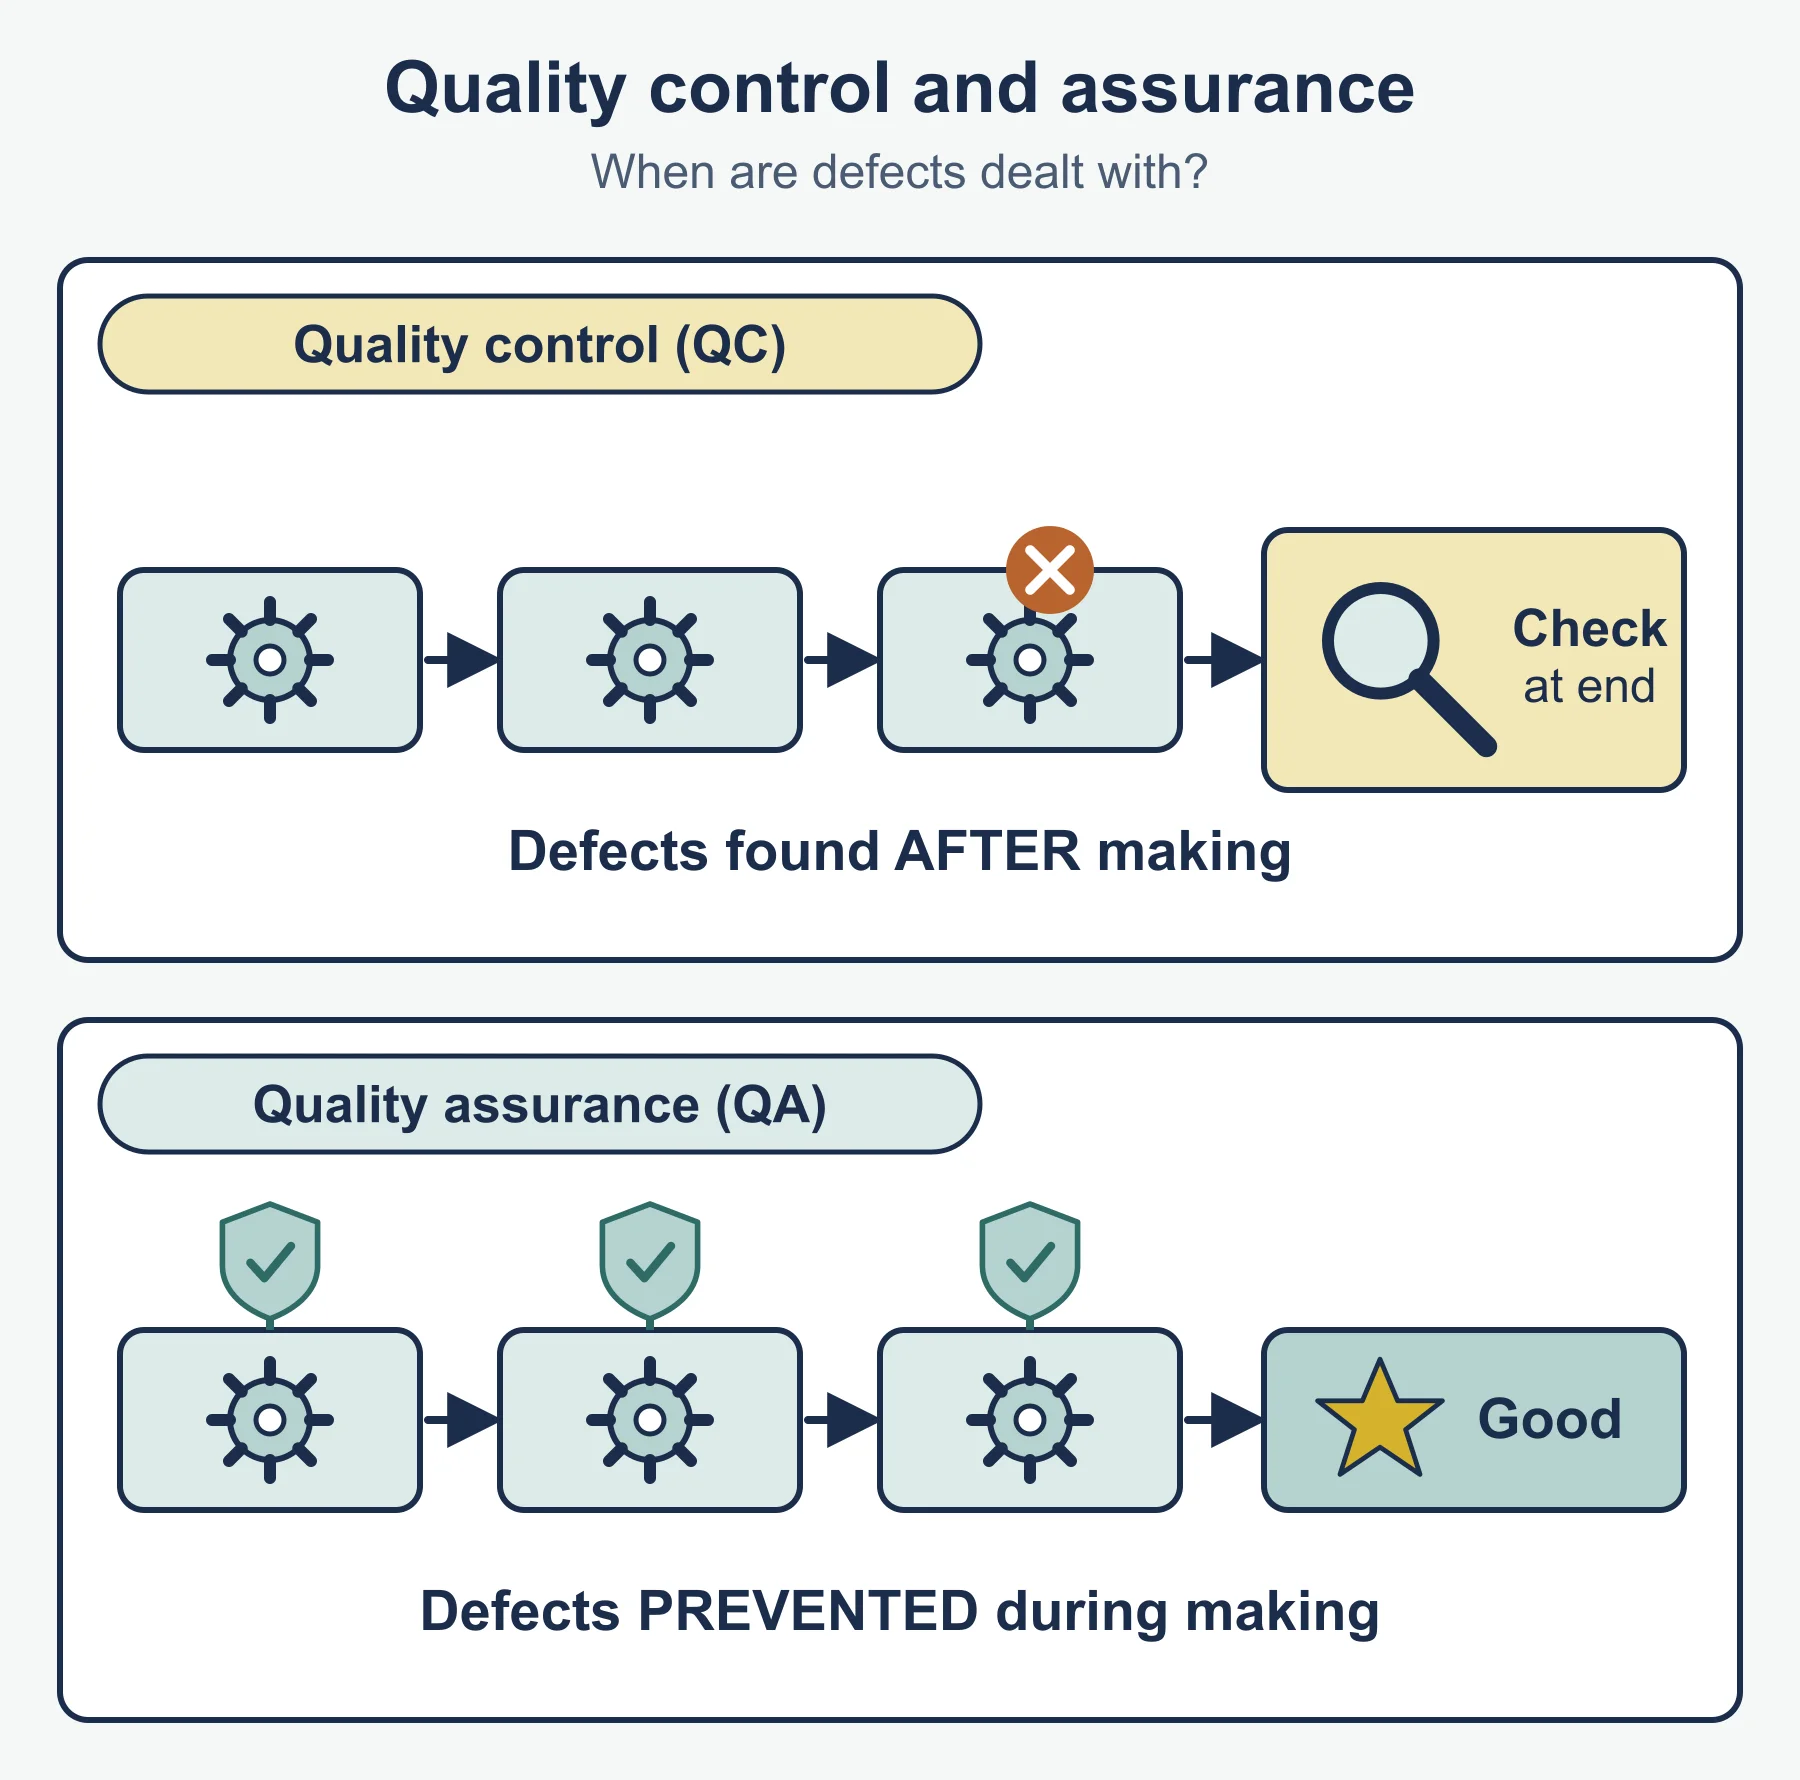
What is total quality management (TQM)? TQM makes quality the responsibility of every employee in every department, aiming to get things right first time. It reduces defects and recalls but adds training and inspection costs.
Why can franchising and outsourcing cause quality problems? As a business grows through franchising or outsourcing, it has less direct oversight of every unit produced or service given, so standards may vary between outlets or suppliers.
What are the benefits of good customer service? The specification lists greater customer satisfaction, customer loyalty, increased spend and profitability. Poor service risks dissatisfied customers, a poor word-of-mouth reputation and reduced revenue.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
AQA GCSE Business: Business operations (8132) – Practice Questions
Original short-answer, calculation and case-study questions with worked answers on production, procurement, quality and service for AQA GCSE Business.
Business · AQA · GCSE
Try questions -
Revision notes
AQA GCSE Business: Business operations (8132) – Revision Notes
Condensed revision notes on production, procurement, quality and customer service for AQA GCSE Business, with worked reminders and a self-test.
Business · AQA · GCSE
Revise topic -
Study guides
AQA GCSE Business: Competitive environment (8132)
Study guide to AQA GCSE Business 8132 section 3.2.6: markets and competition, little or no competition, uncertainty and risk, and how entrepreneurs reduce risk.
Business · AQA · GCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business GCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
AQA Business teachers at Marlbridge
