
Revision Notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- Analysis and interpretation
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus topics and points this page is mapped to
0452
- 6 Analysis and interpretation (topic-level mapping)
7707
- 6 Analysis and interpretation (topic-level mapping)
"Topic-level mapping" means this page belongs to that topic; it does not claim to cover every point in it.
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. For this topic, the 2026 syllabus lists eight ratios without inventory turnover in days (mark-up appears only in its ratio appendix), names ROCE’s numerator “net profit before interest”, lists interested parties as owners, managers, trade payables, banks, investors, club members and others such as governments and tax authorities, and gives the limitations of accounting statements as historic cost, difficulties of definition and non-financial aspects. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
Condensed for the final weeks. For the full explanation and a complete two-year worked example, use the Analysis and Interpretation study guide. The figures come from the statements in Topic 5’s Preparation of Financial Statements.
The core question this topic answers
What do the financial statements say about the business, and who needs to know? Calculate the ratio, compare it (with last year or another business), then explain the change and what to do about it.
6.1 Calculation and understanding of accounting ratios
The p.21 formulas. Note: “Candidates must use the formulas given in the Accounting ratios included at the end of this section. These are the only formulas accepted in candidate responses.”
| Ratio | Formula |
|---|---|
| Gross profit margin (%) | Gross profit ÷ Revenue × 100 |
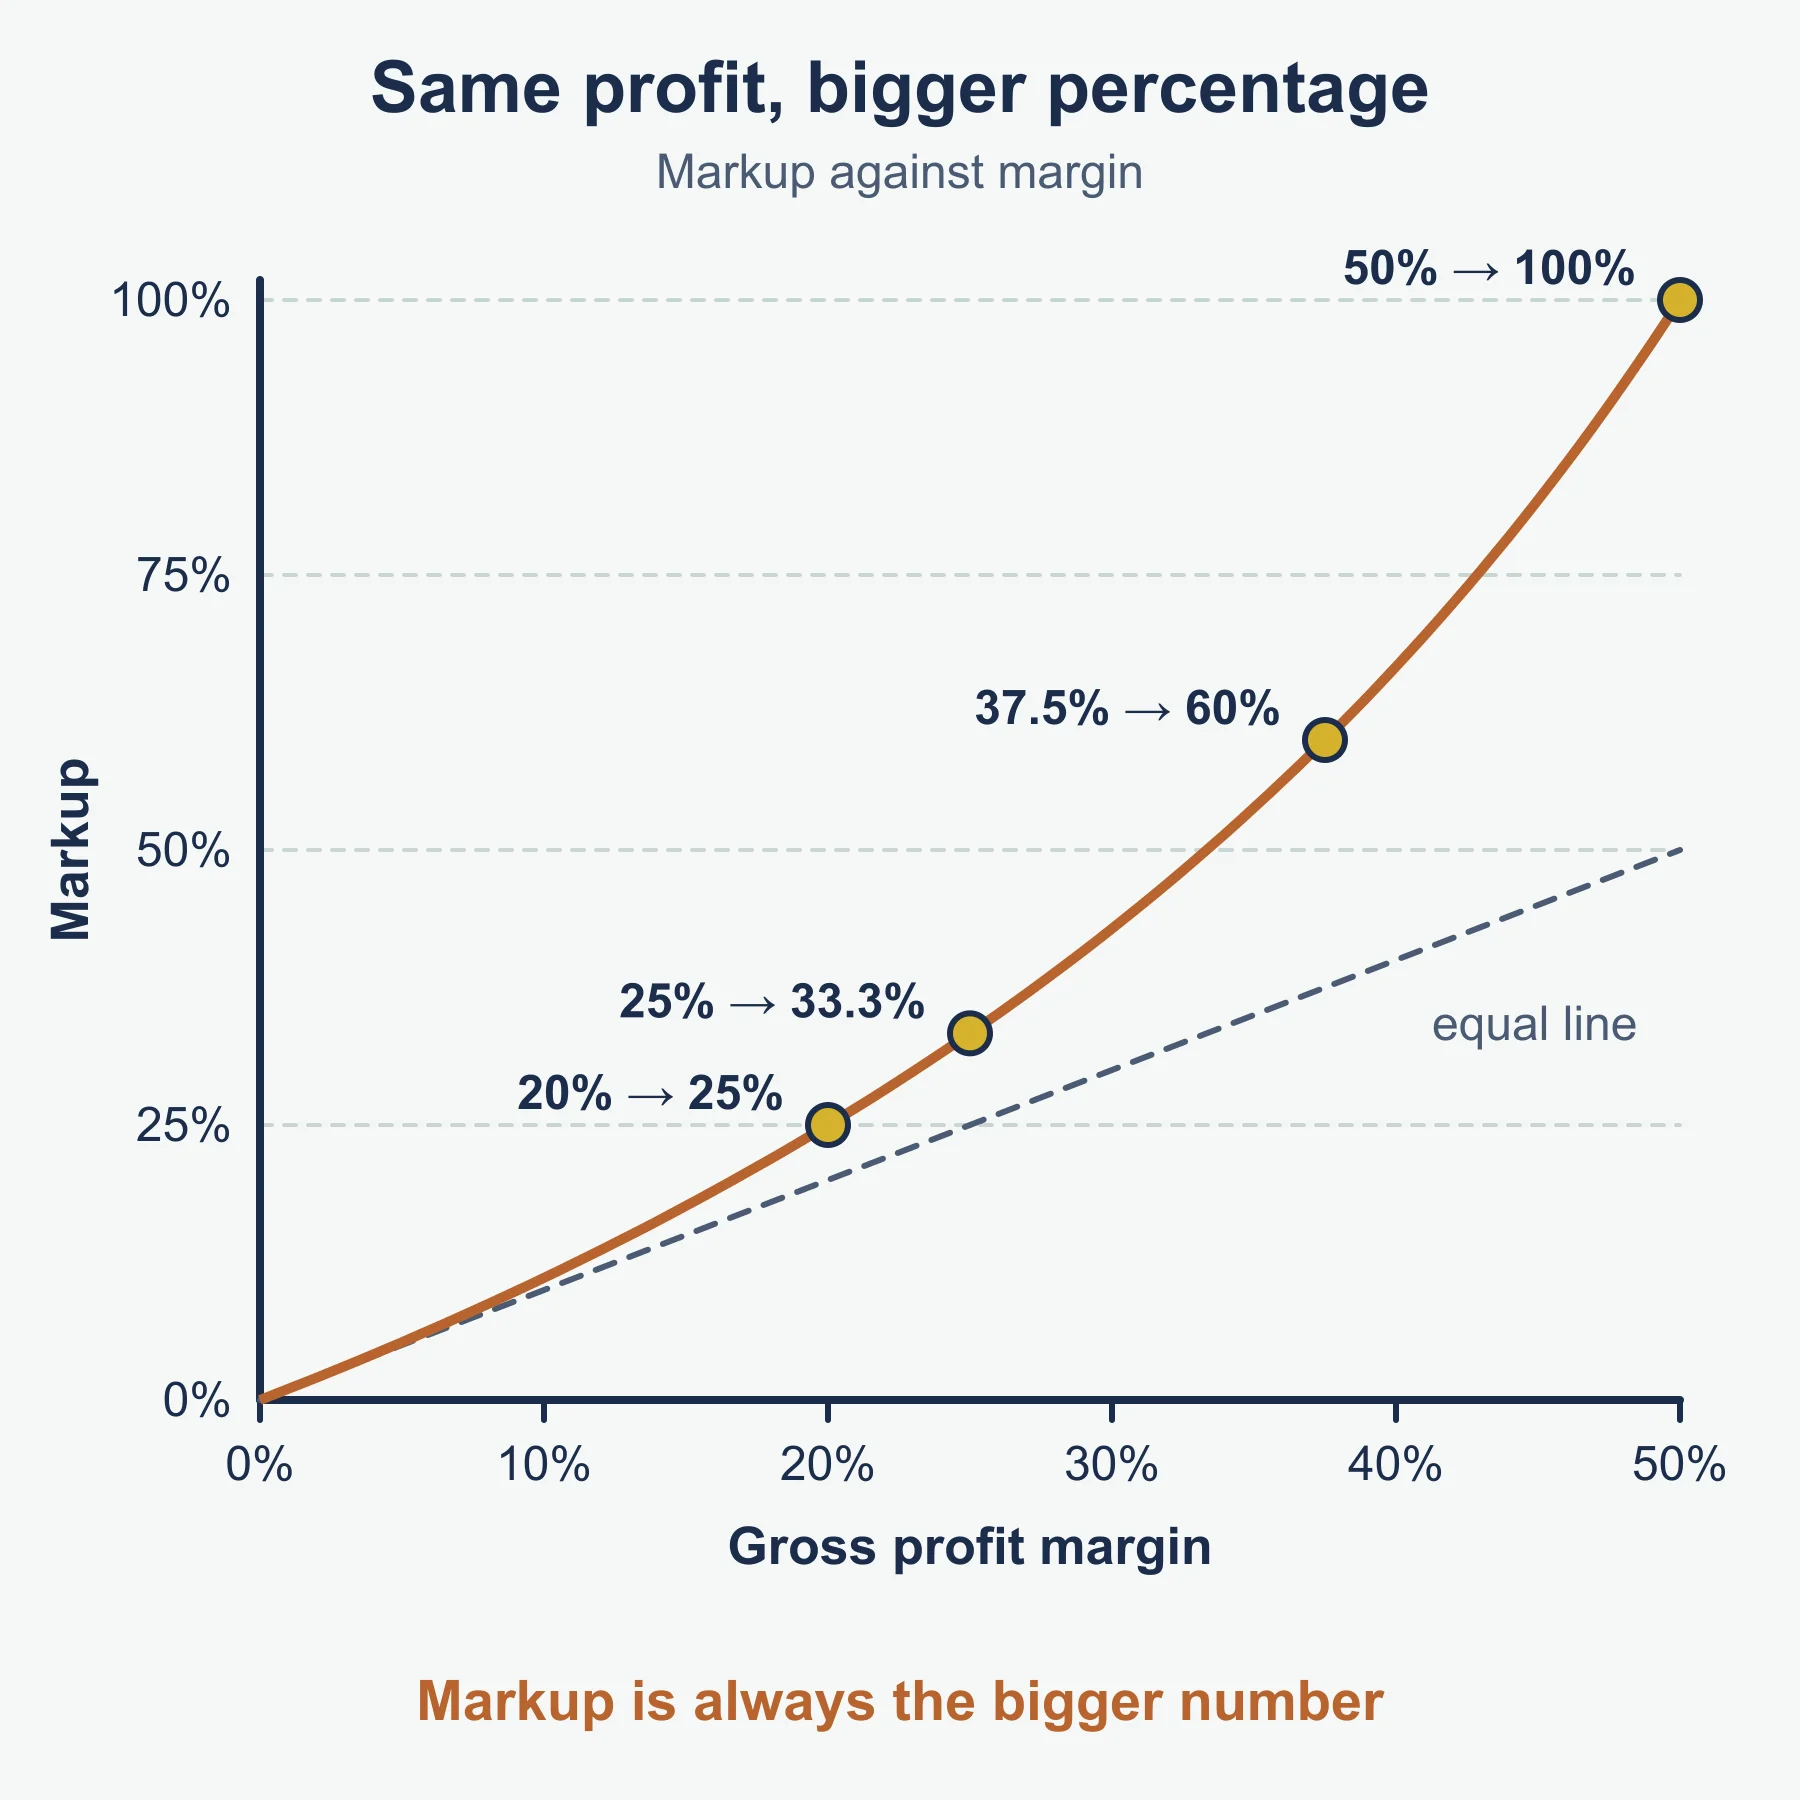
| Mark-up (%) | Gross profit ÷ Cost of sales × 100 |
| Profit margin (%) | Profit for the year ÷ Revenue × 100 |
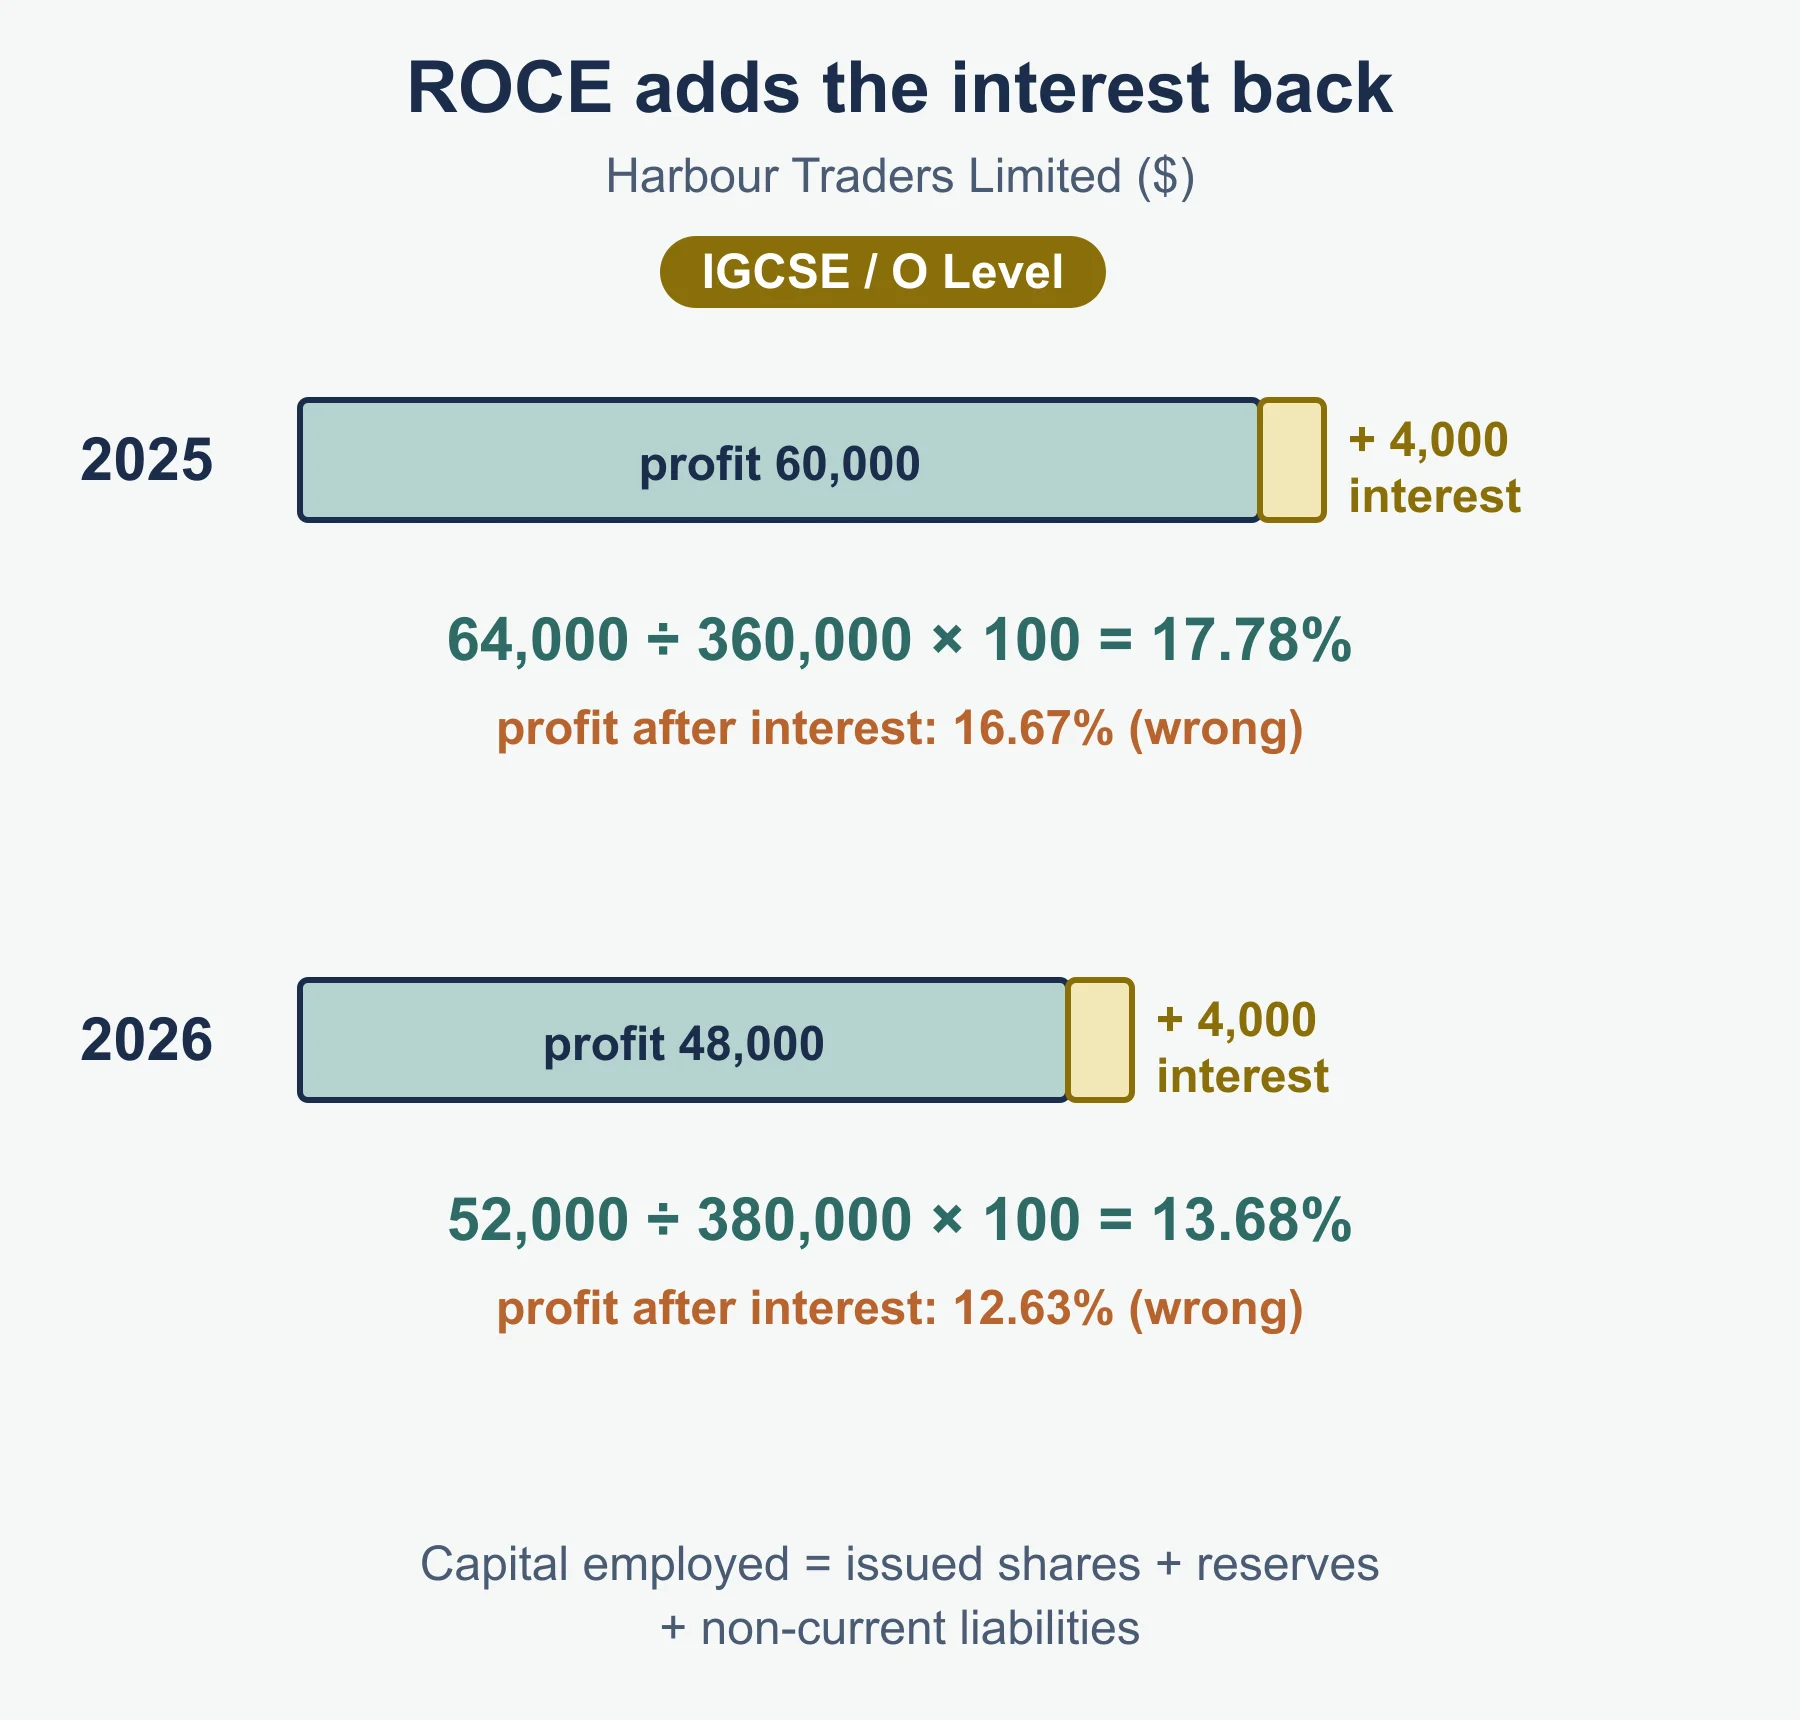
| Return on capital employed (ROCE) (%) | Profit for the year before interest ÷ Capital employed × 100 |
| — capital employed | issued shares + reserves + non-current liabilities |
| Current (working capital) ratio | Current assets : Current liabilities (answer presented as a ratio) |
| Acid test (liquid) ratio | (Current assets – inventory) : Current liabilities (answer presented as a ratio) |
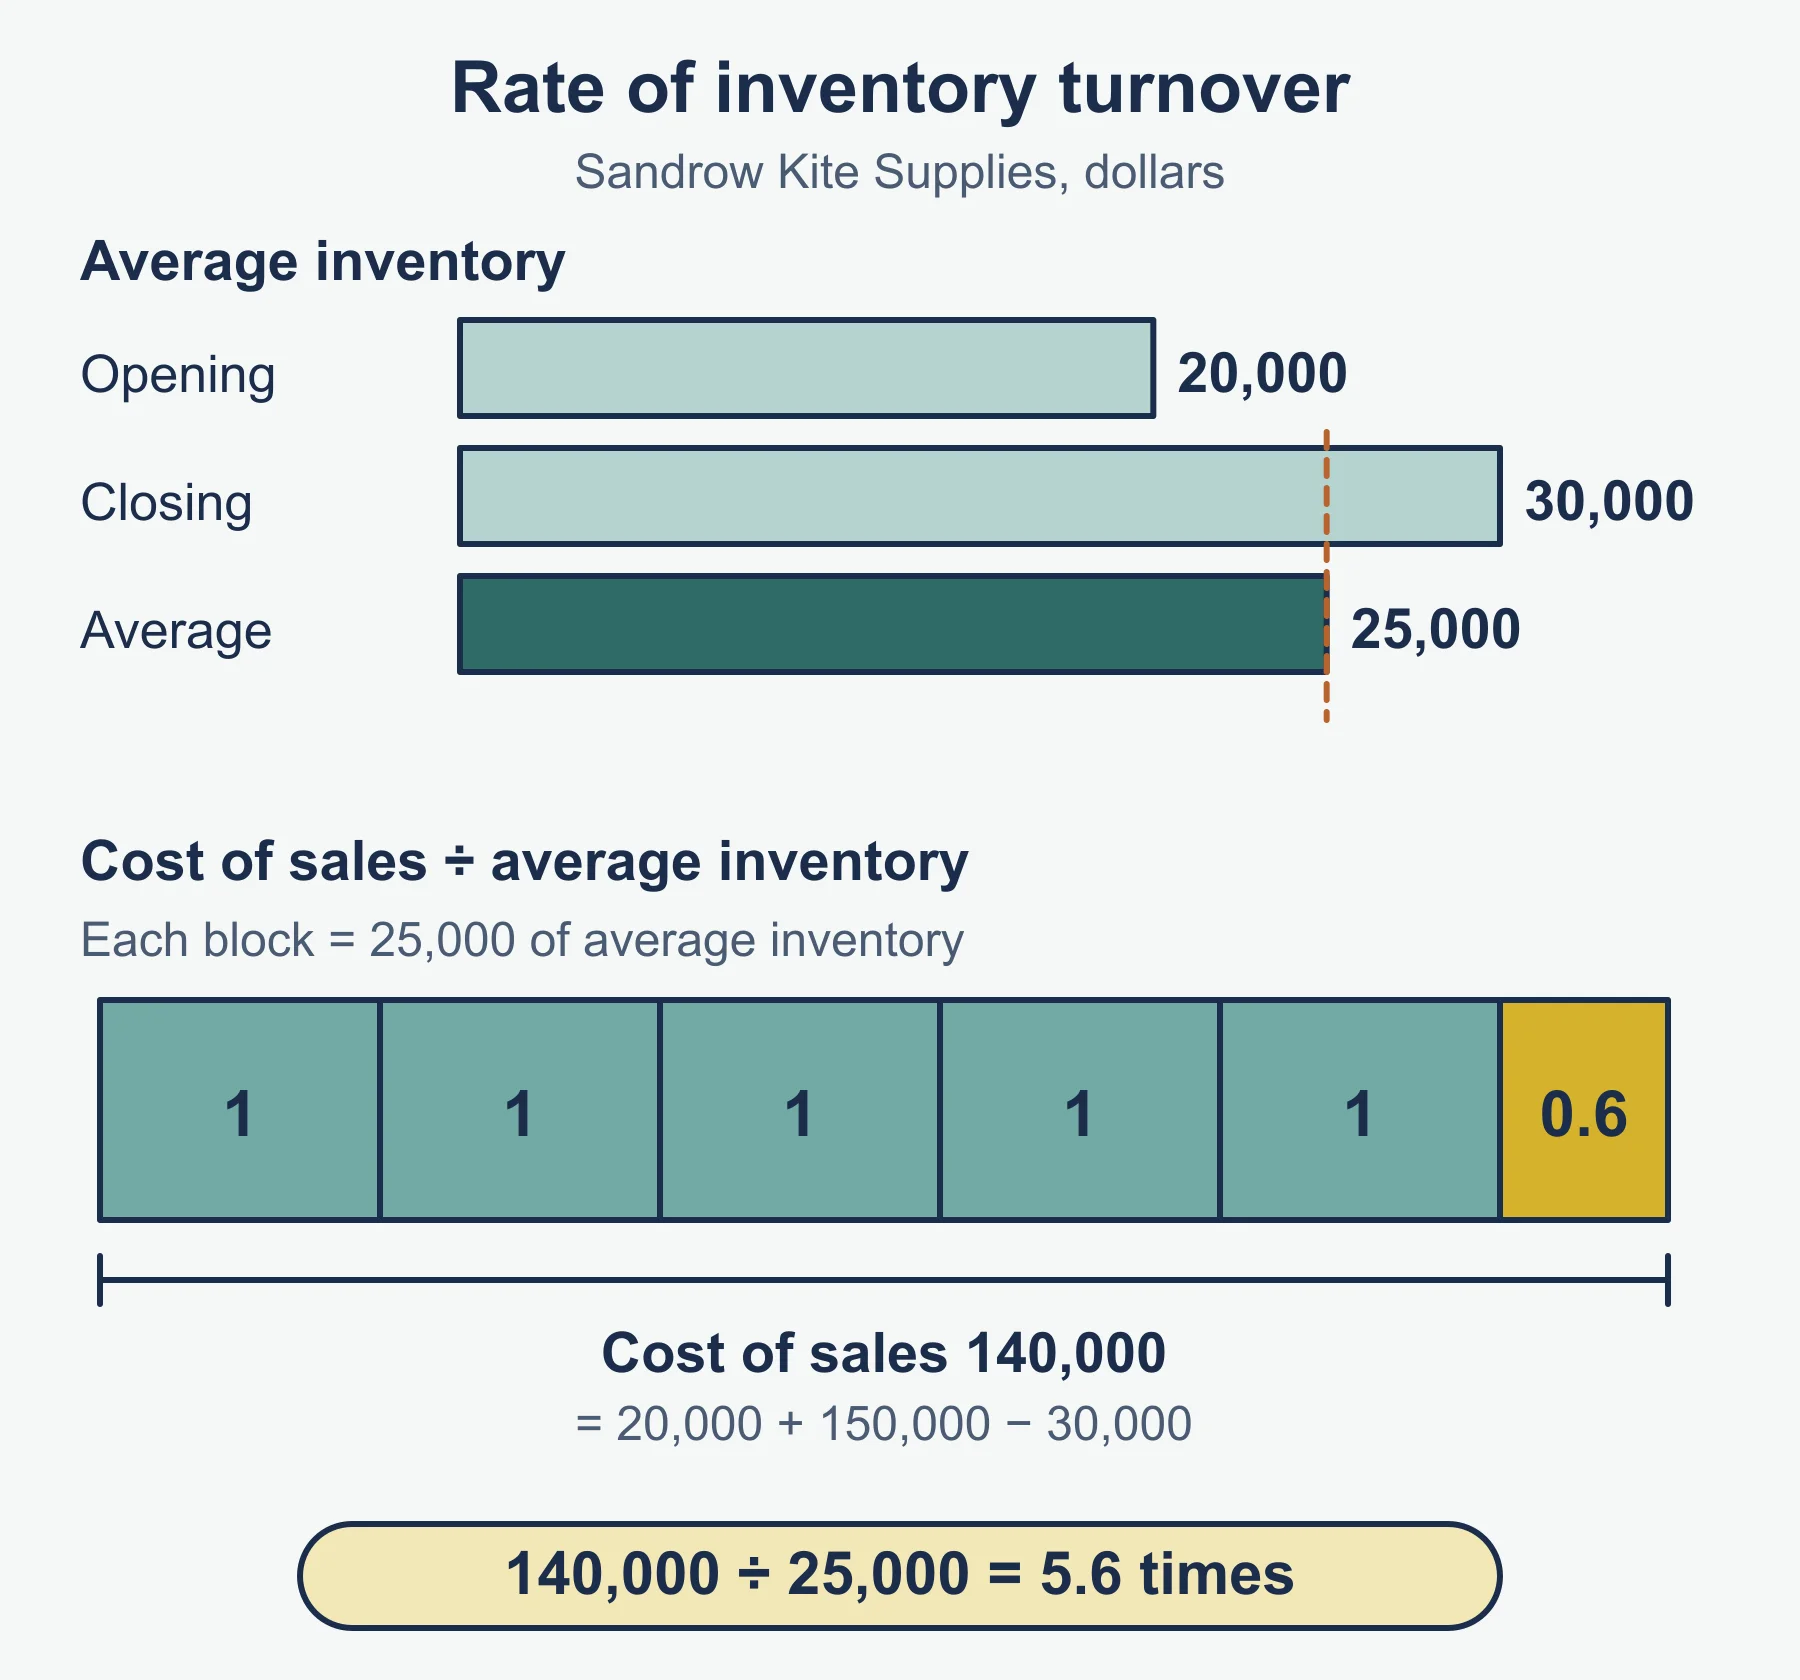
| Rate of inventory turnover (times) | Cost of sales ÷ Average inventory |
| Inventory turnover (days) | Average inventory ÷ Cost of sales × 365 days |
| Trade receivables turnover (days) | Trade receivables ÷ Credit sales × 365 days |
| Trade payables turnover (days) | Trade payables ÷ Credit purchases × 365 days |
Average inventory = (opening inventory + closing inventory) ÷ 2.
6.2 Interpretation of accounting ratios
| Ratio | What it shows | A rise usually means |
|---|---|---|
| Gross profit margin | Gross profit earned on each $100 of revenue | Better pricing or cheaper purchases |
| Mark-up | Gross profit added to each $100 of cost of sales | Same story as the margin, measured on cost |
| Profit margin | Profit left from each $100 of revenue after all expenses | Better control of expenses (or better gross profit) |
| ROCE | Return before interest on each $100 of capital employed | Capital used more profitably |
| Current ratio | Current assets available for each $1 of current liabilities | Better able to pay short-term debts (but too high may mean idle resources) |
| Acid test | The same, without relying on selling inventory | Better immediate liquidity |
| Rate of inventory turnover | How many times inventory is sold and replaced in a year | Inventory sold faster |
| Inventory turnover (days) | Average days inventory is held | Inventory sold more slowly |
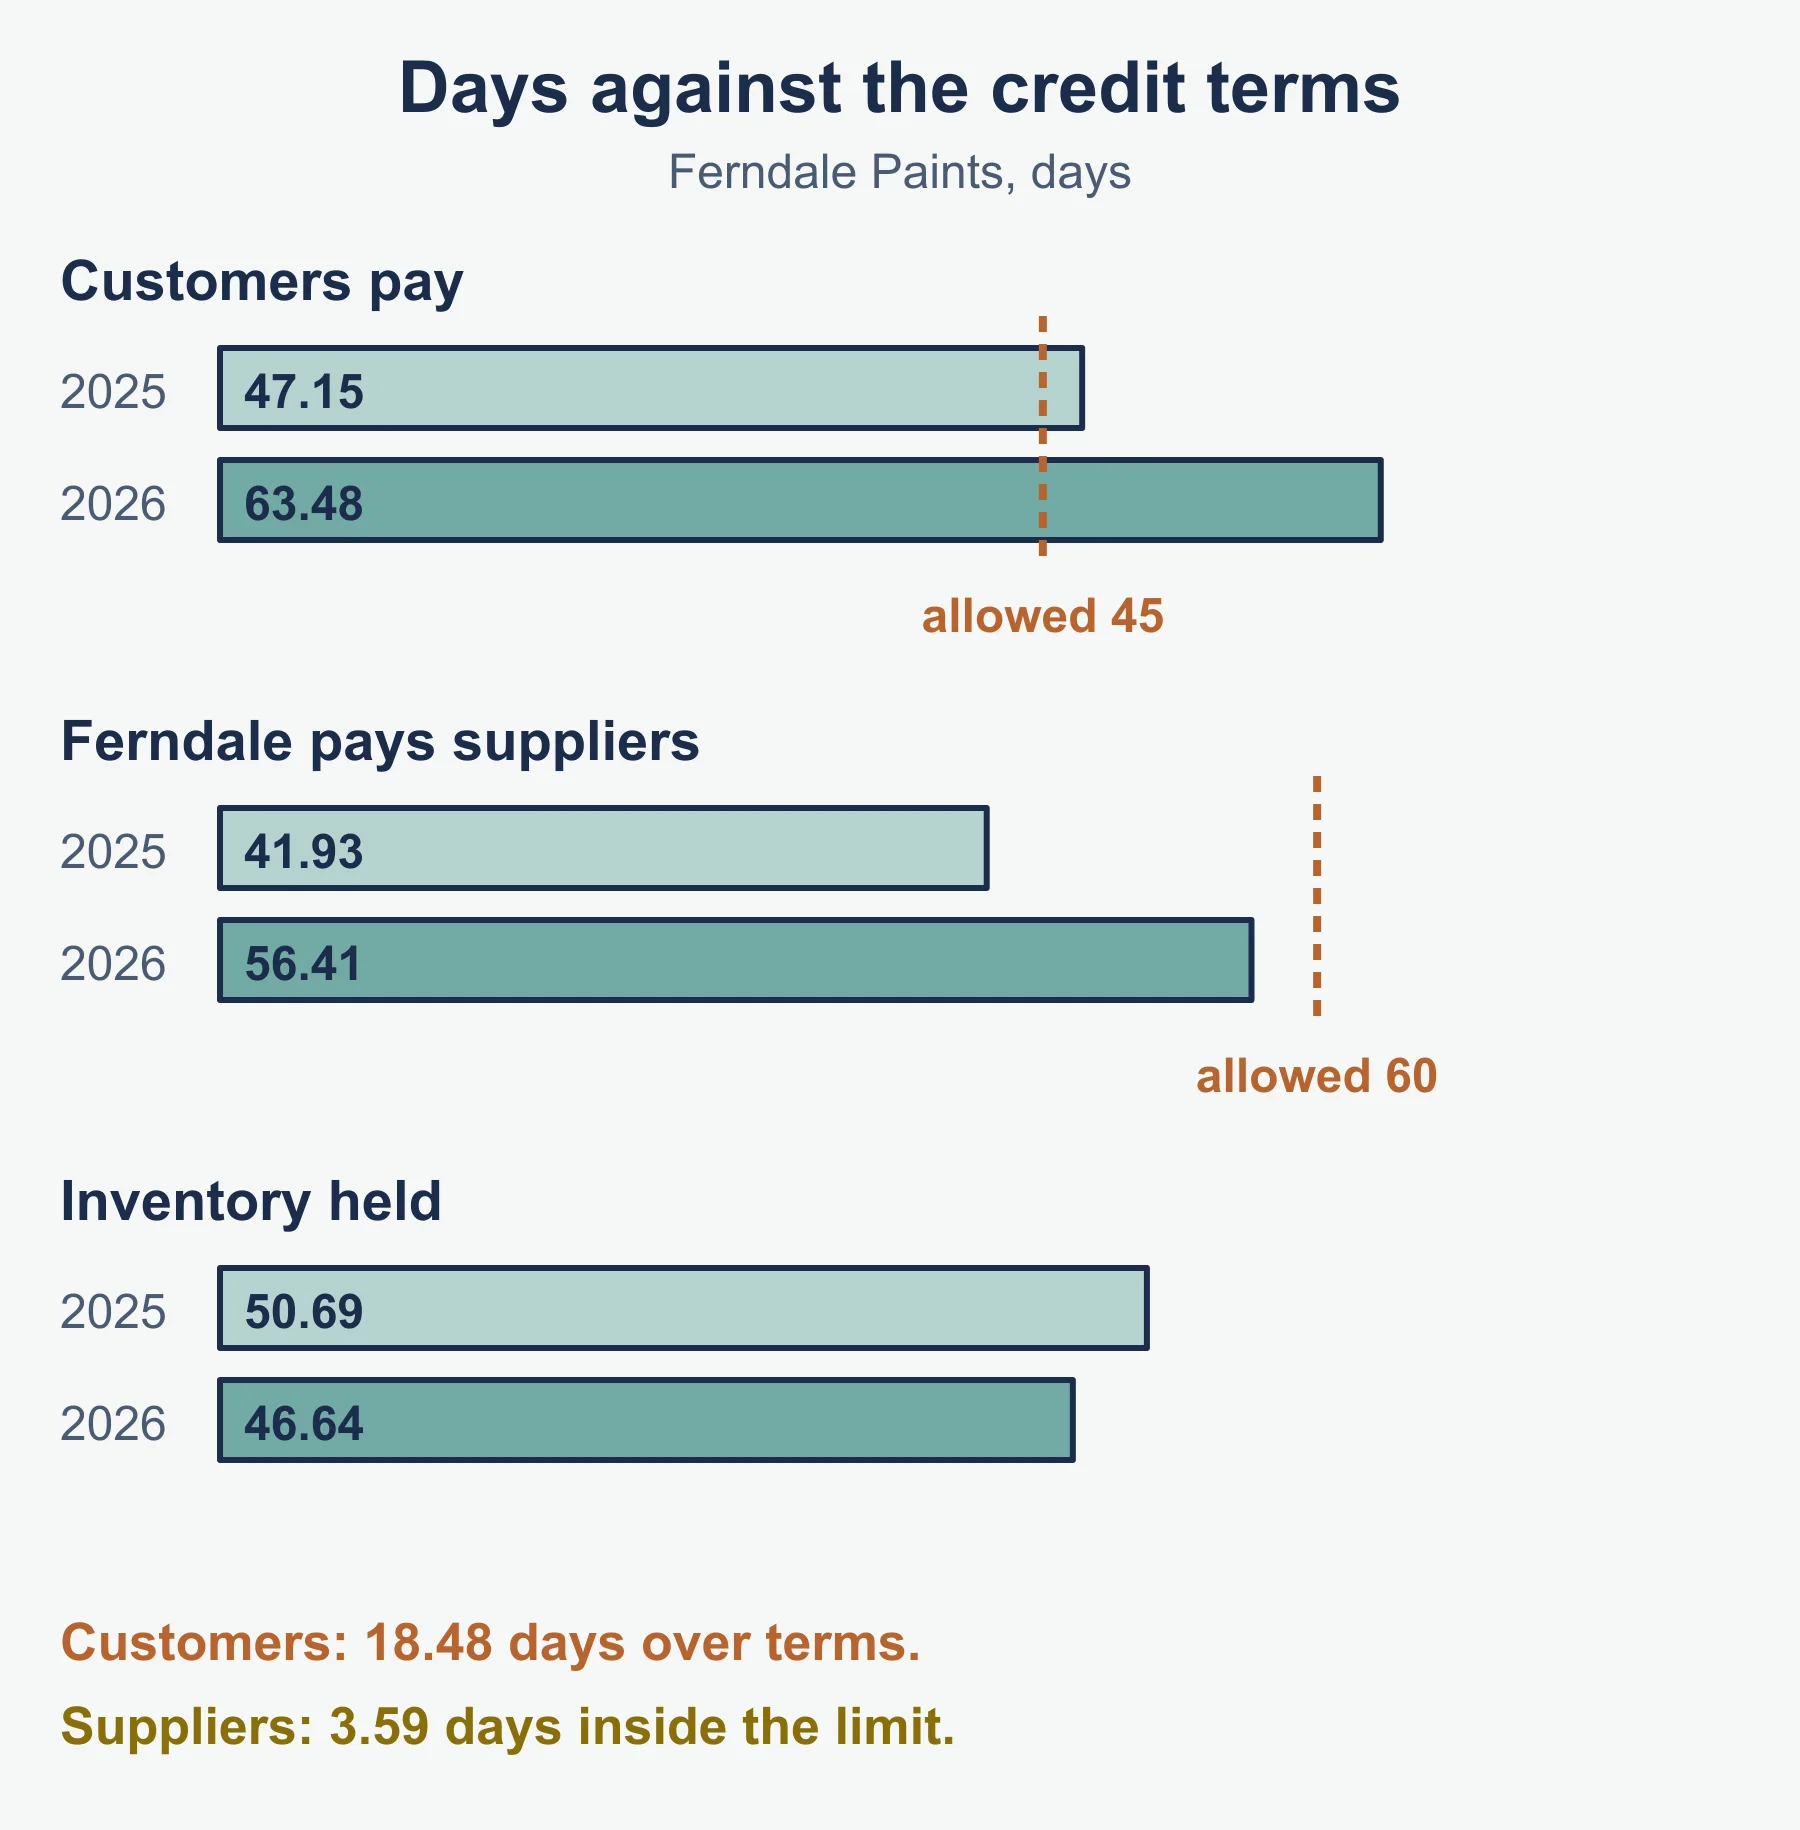
| Trade receivables turnover (days) | Average days customers take to pay | Customers paying more slowly — compare with credit allowed |
| Trade payables turnover (days) | Average days taken to pay suppliers | Paying more slowly — keeps cash, but risks supplier goodwill |
Profitability indicators: the gross profit margin and the profit margin. A steady gross profit margin with a falling profit margin points to expenses; a falling gross profit margin points to prices, purchase costs or inventory.
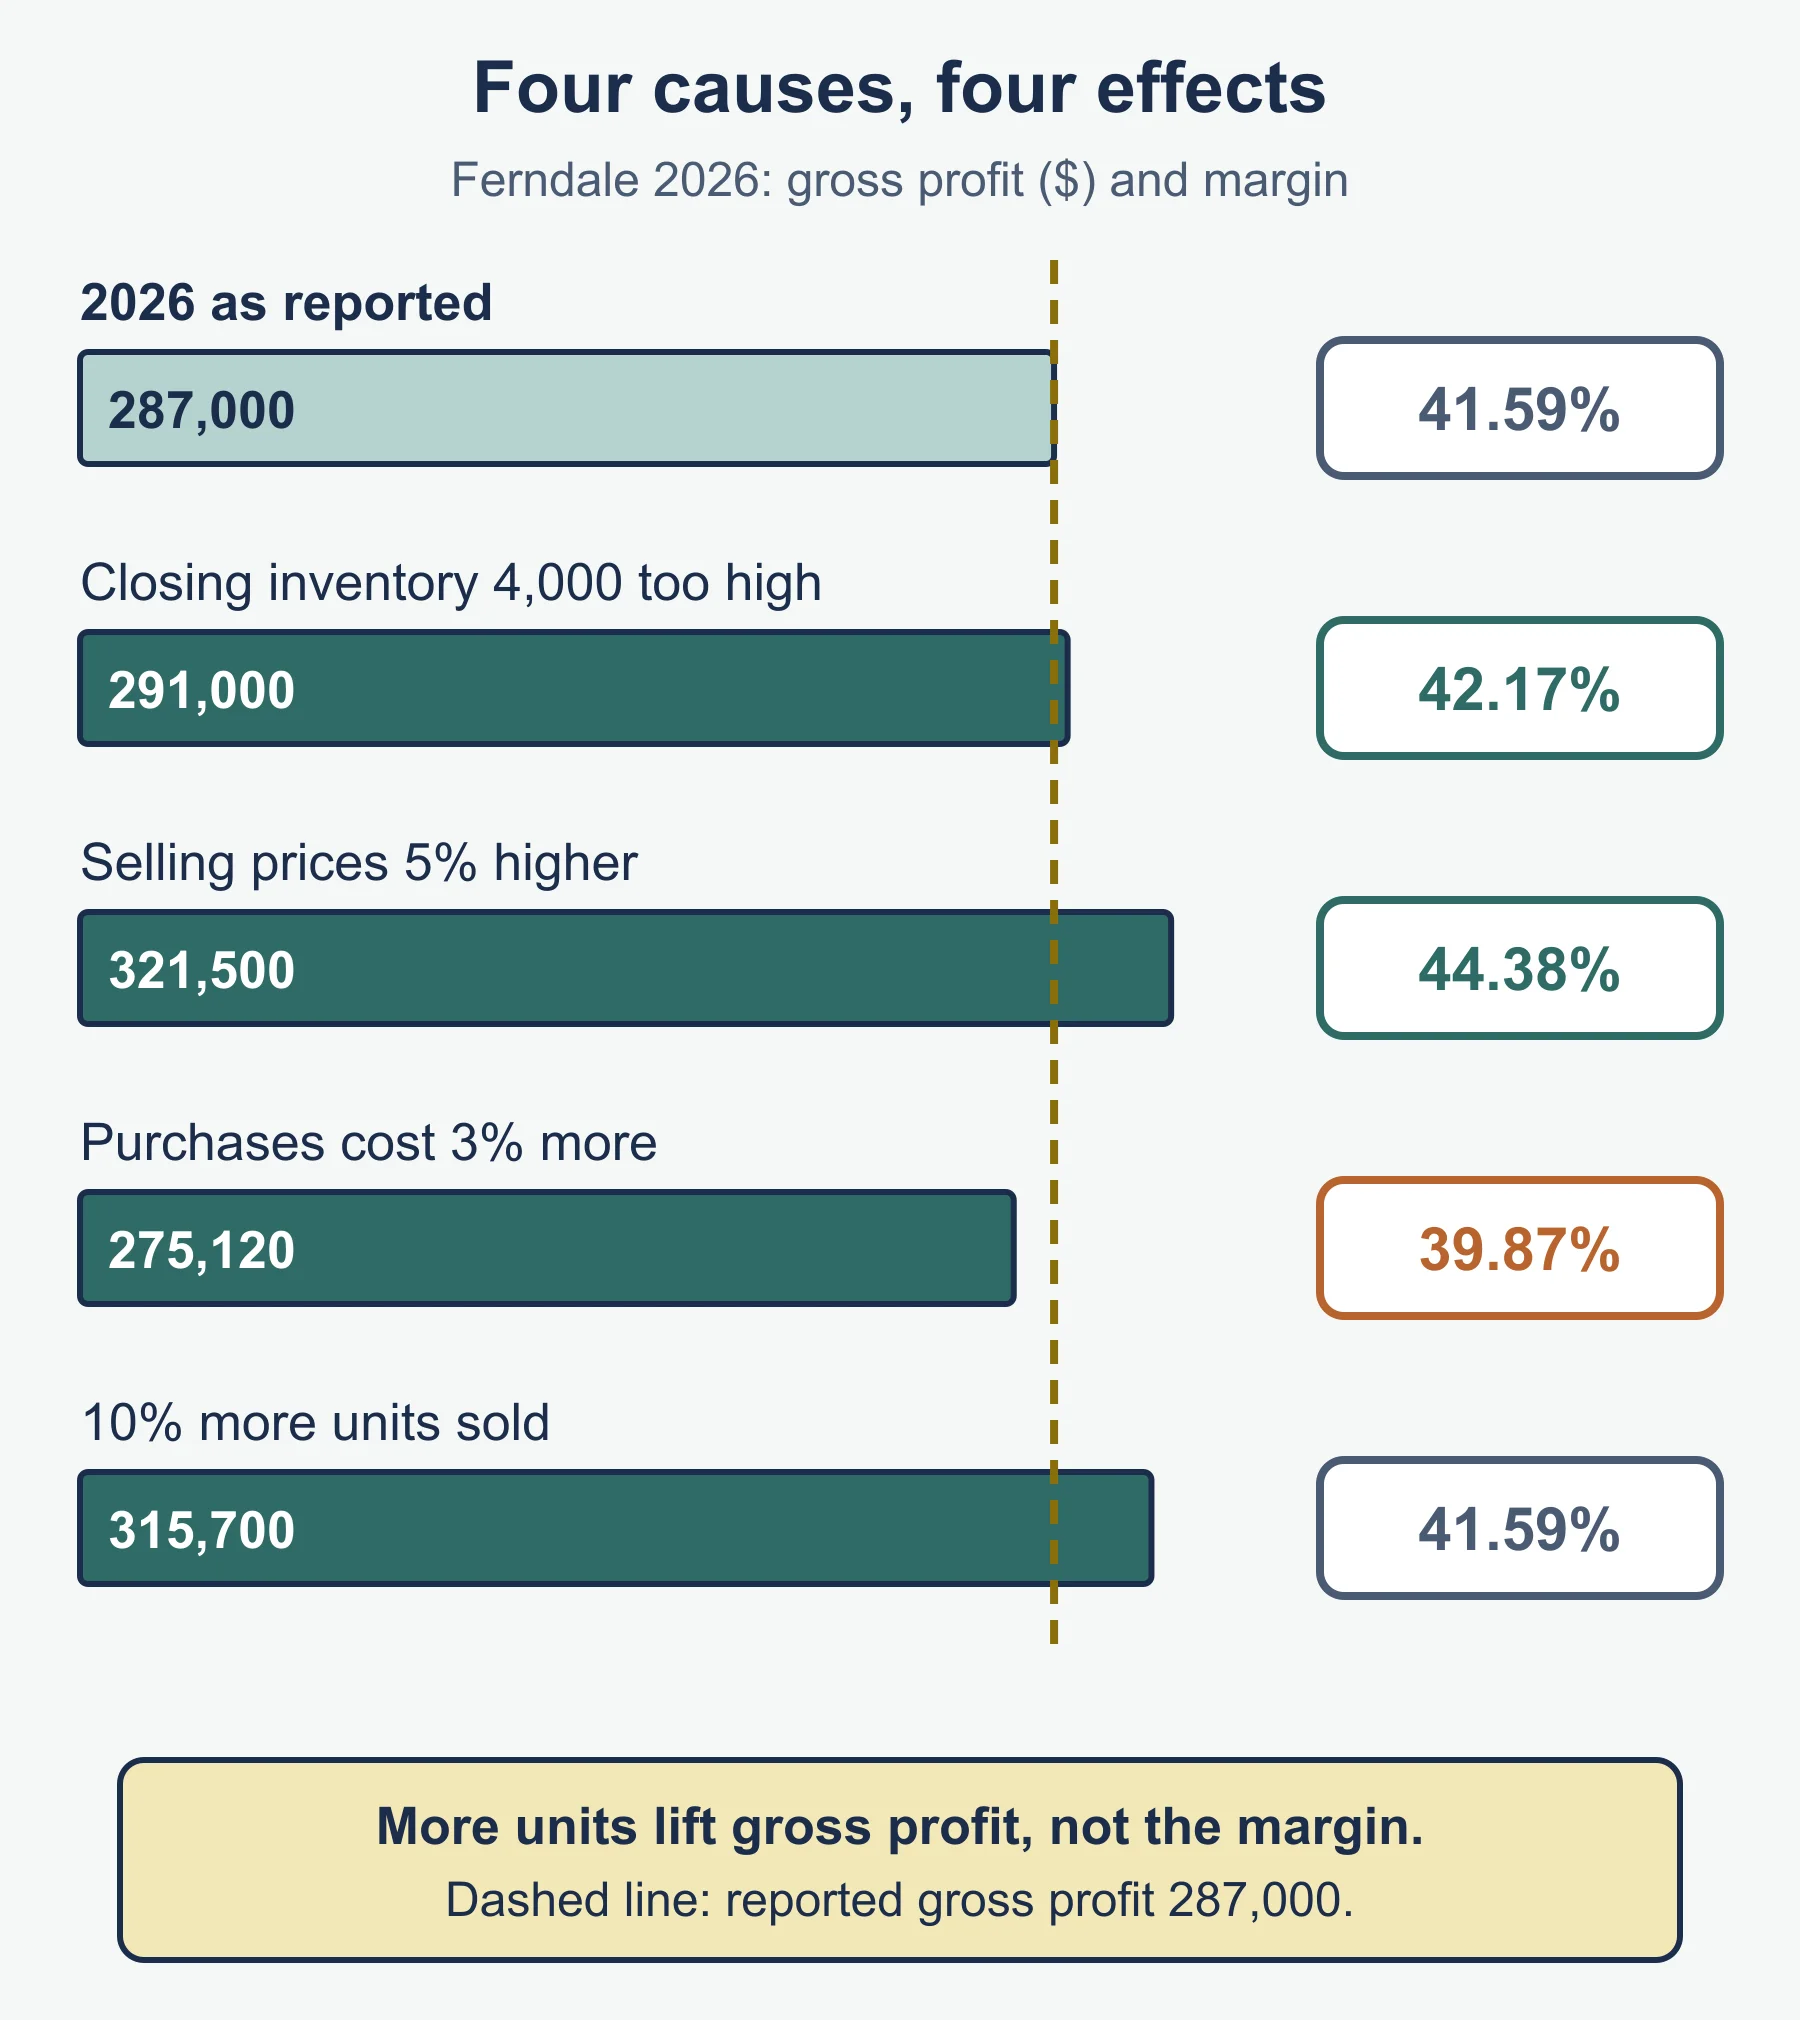
Gross profit is affected by: the valuation of inventory (overvalued closing inventory overstates gross profit — see Topic 4’s Accounting Procedures); sales quantity (more units at the same prices raises gross profit, not the margin); changes in selling prices; changes in purchasing prices.
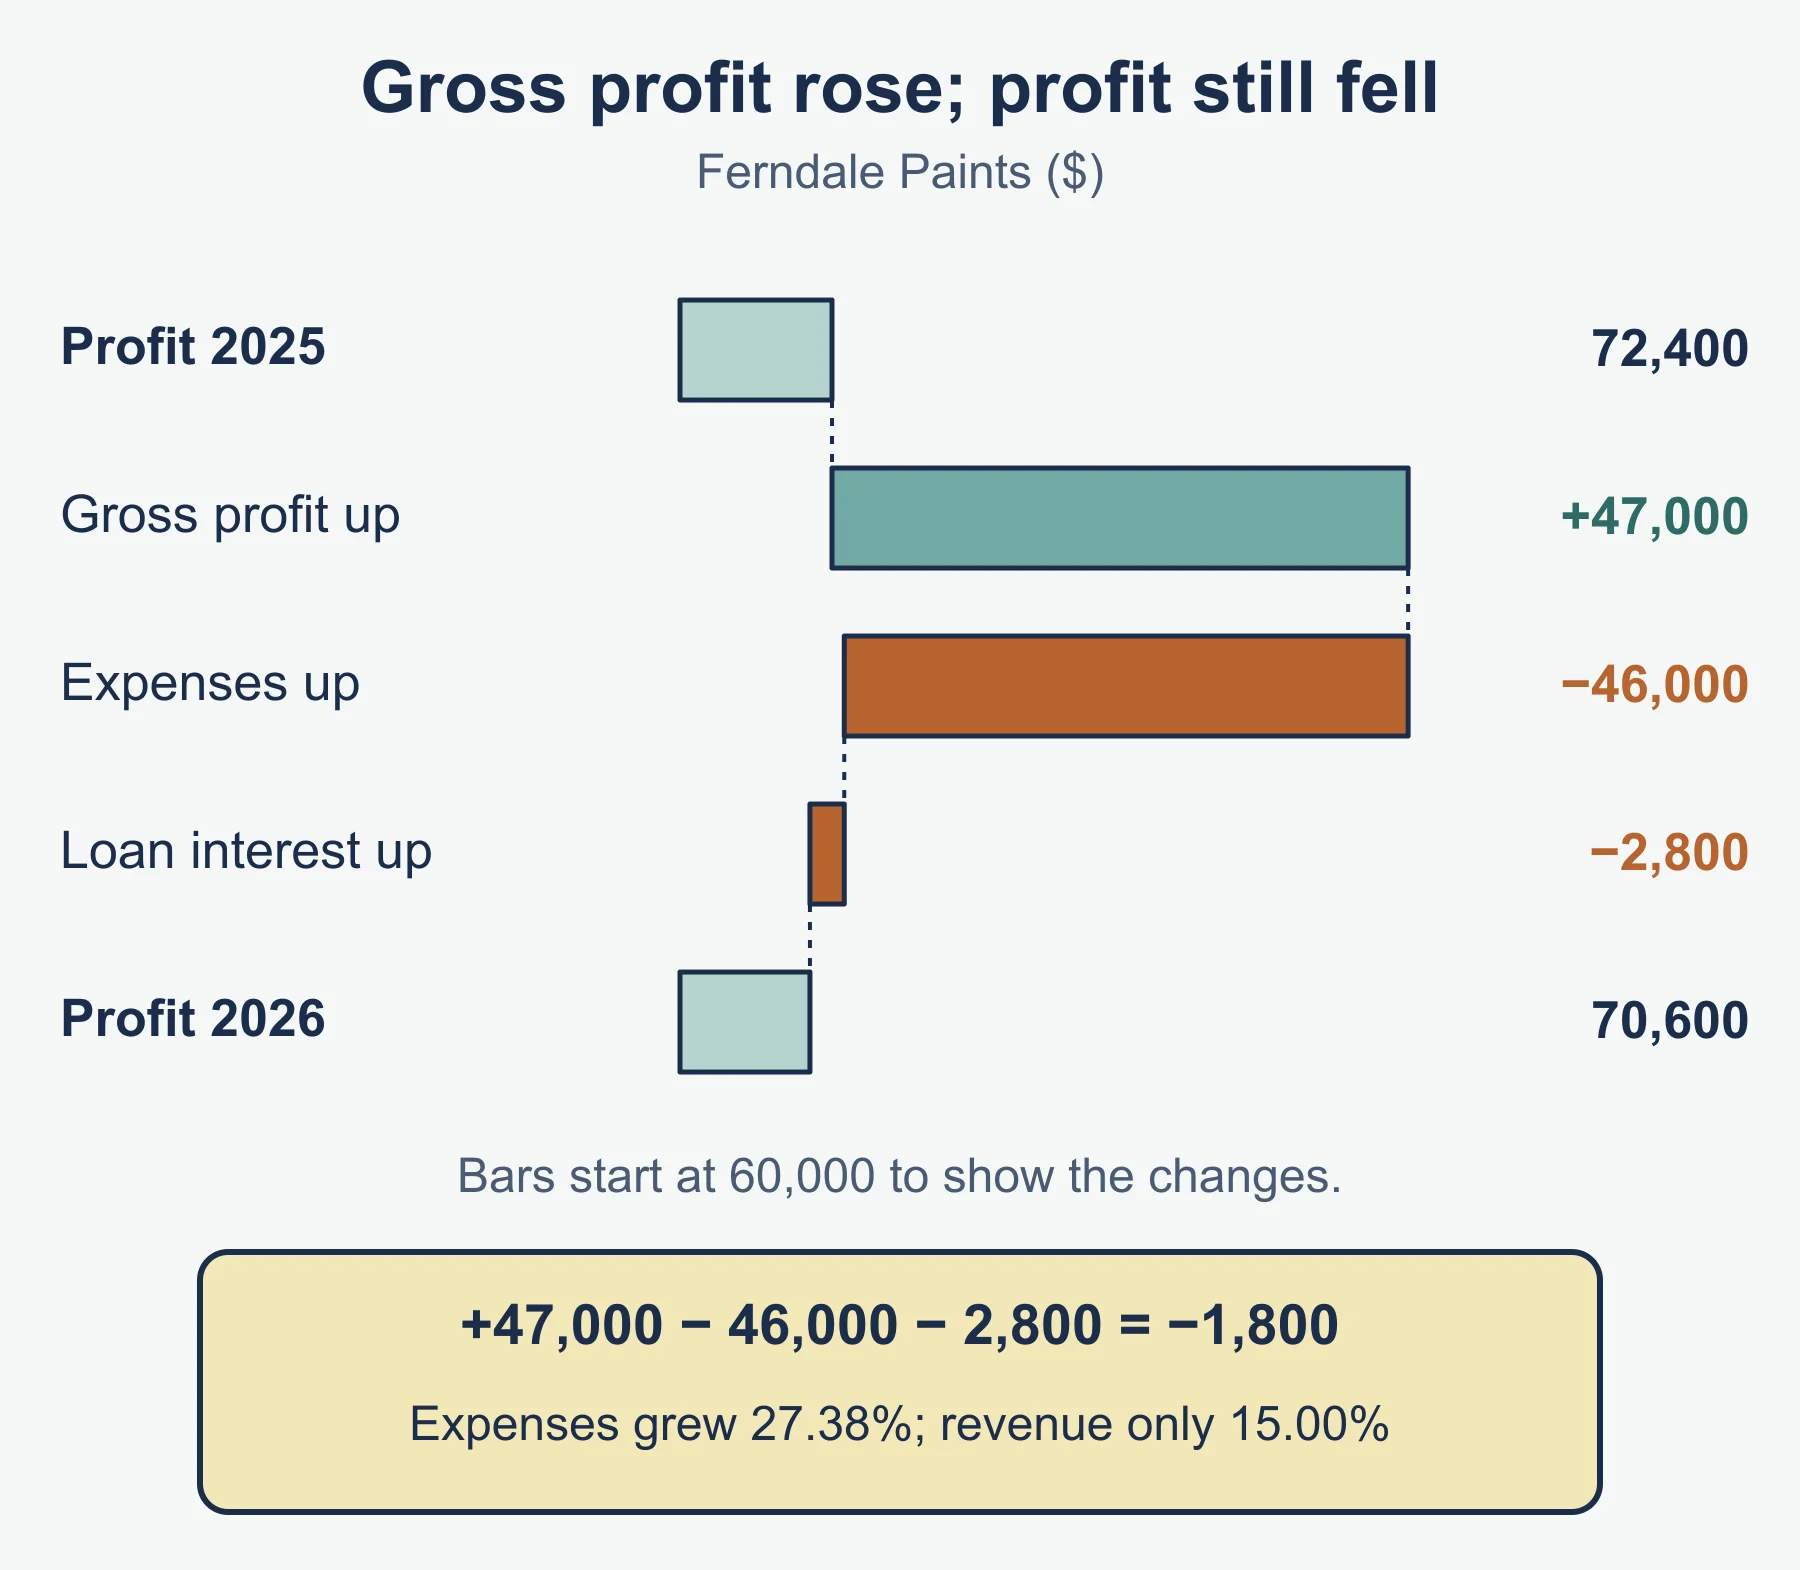
Profit for the year is affected by: changes in gross profit, other income (such as rent received) and expenses.
Comparison statements: set out two years side by side with the change, then comment on each significant change with a reason.
Recommendations:
- Profitability — raise selling prices where customers will accept it; find cheaper suppliers or trade discounts; cut unnecessary expenses; increase sales quantity.
- Liquidity — collect trade receivables faster (chase overdue accounts, offer cash discount); raise long-term finance rather than rely on an overdraft; sell unused non-current assets.
- Working capital — hold less inventory; use the full credit period suppliers allow; limit drawings or dividends.
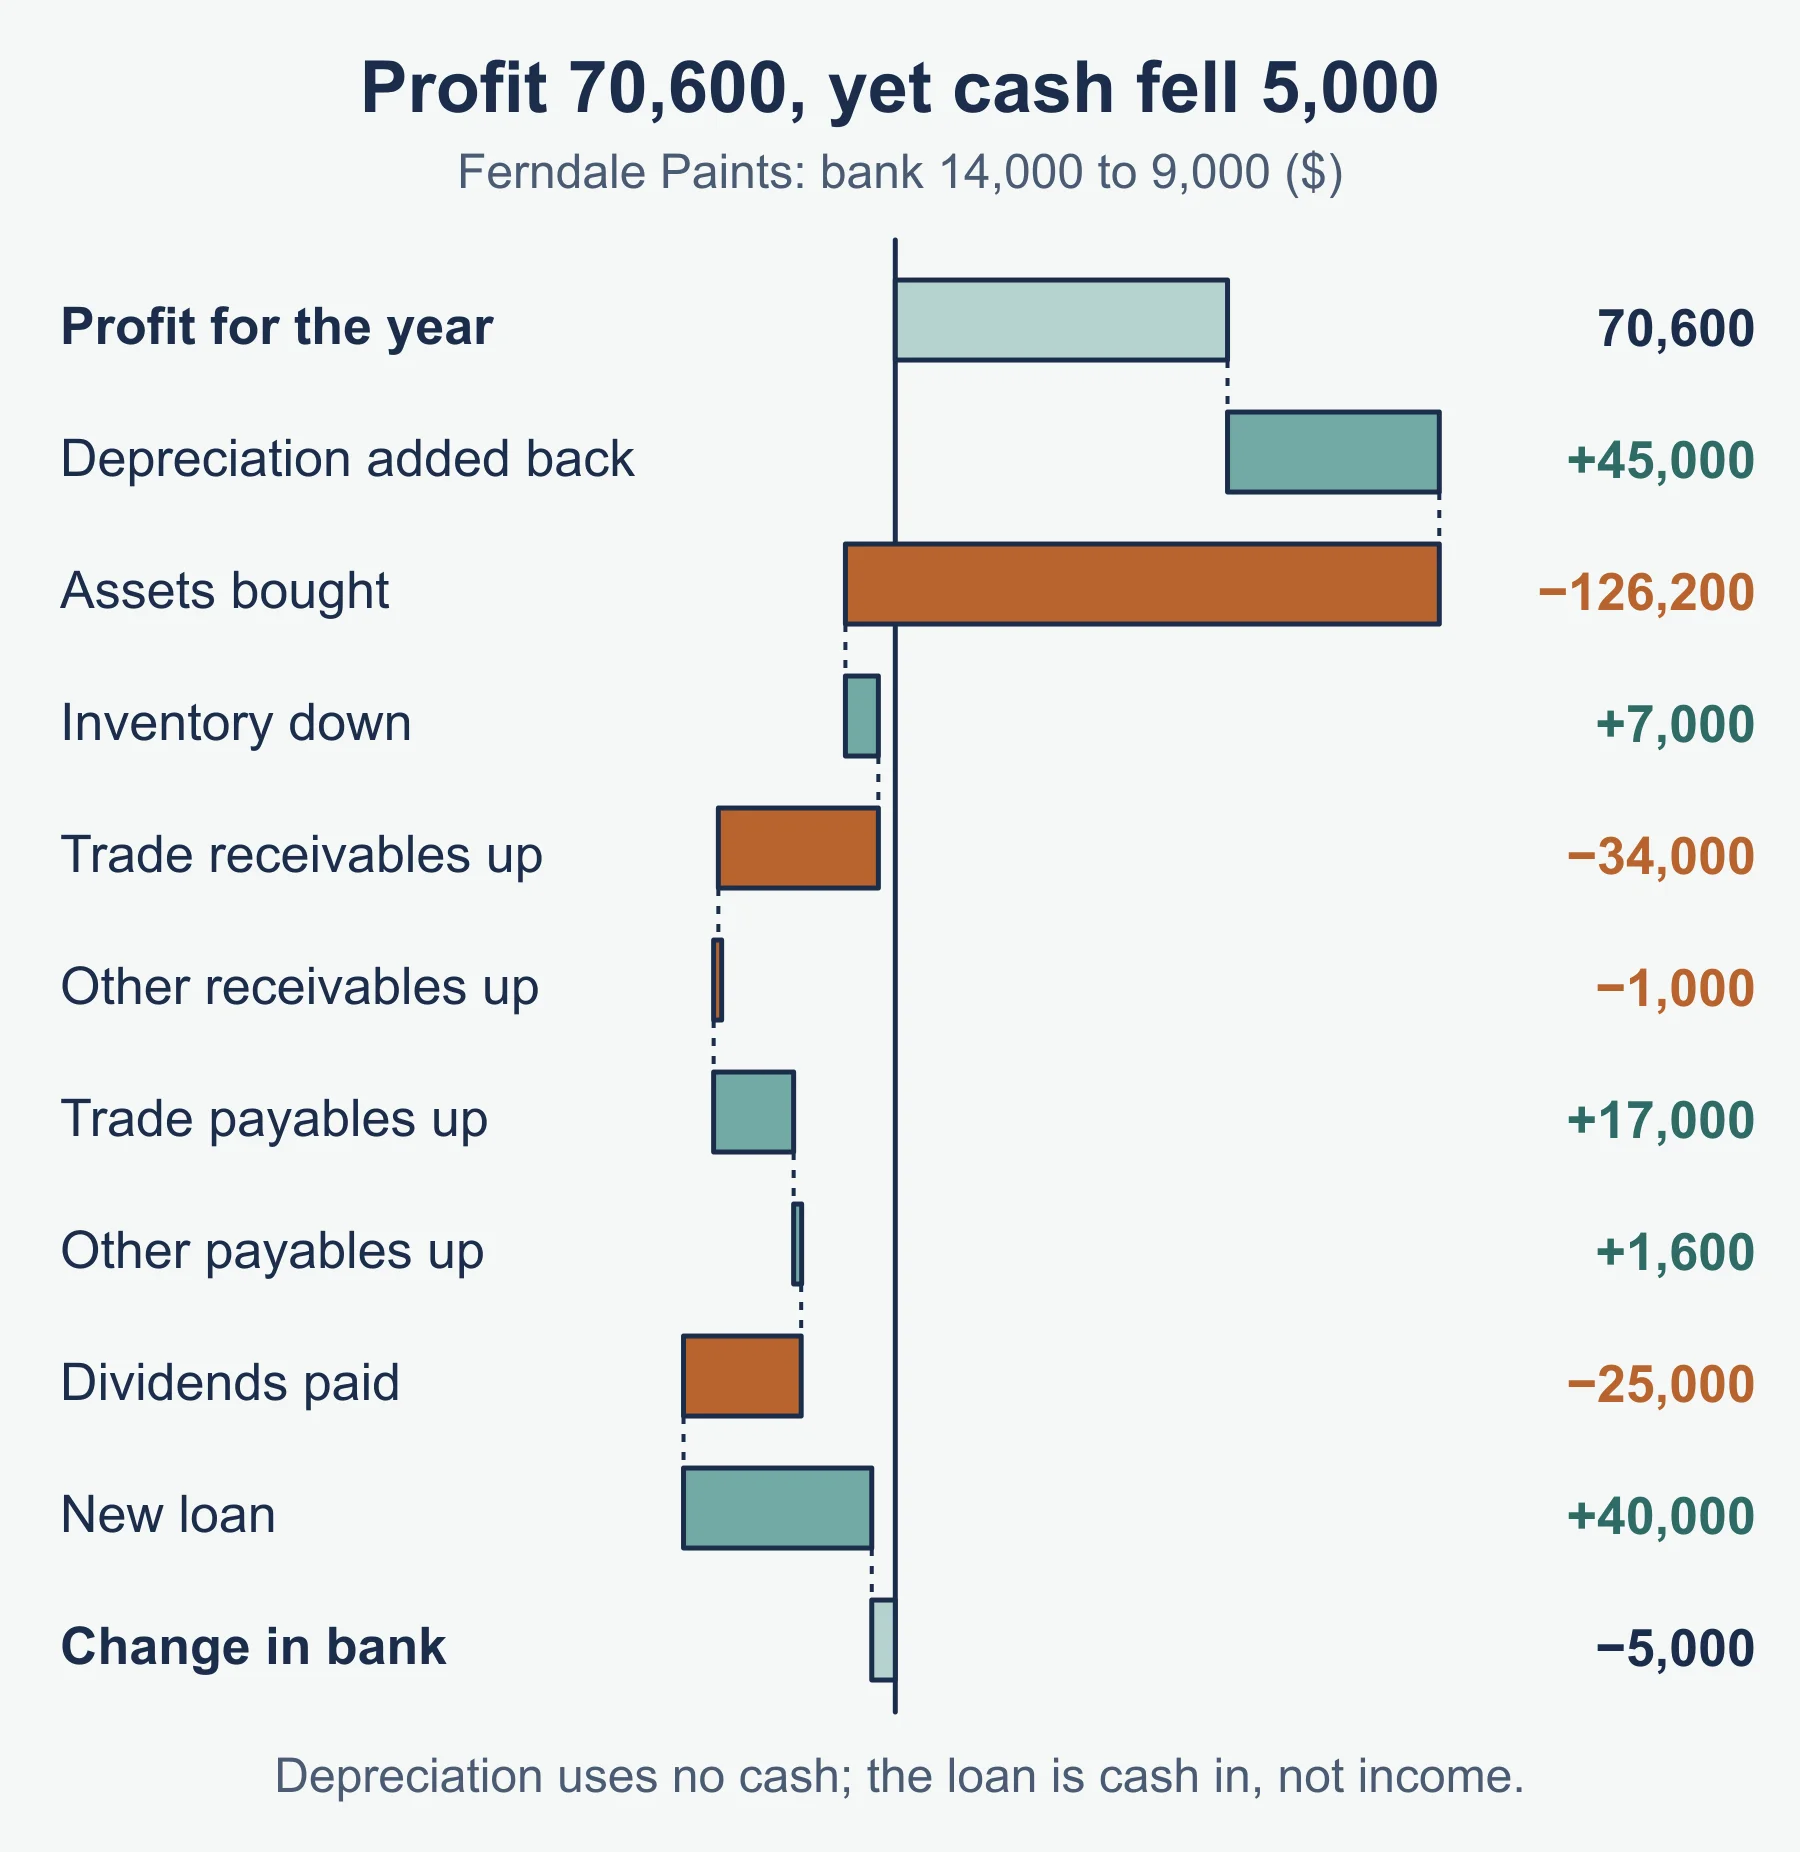
Why cash and profit differ: depreciation (expense, no cash); buying non-current assets (cash, not an expense); changes in inventory, trade receivables and trade payables; accrued and prepaid expenses and income; irrecoverable debts and allowance changes; capital introduced, loans received and repaid, shares issued; drawings and dividends (cash out, not expenses in the statement of profit or loss).
6.3 Inter-business comparison
Factors that may affect two businesses’ ratios: type of goods or service; size and buying power; pricing policy; location; cash or credit sales; how each is financed; owned or rented premises and age of assets; accounting policies.
Problems of inter-business comparison: detailed statements may not be available; different accounting policies; different year-end dates; businesses not truly alike; historic figures and untypical years; non-financial aspects ignored.
6.4 Interested parties
| Party | Main decision |
|---|---|
| Owners | Is the return worth it? Keep, expand or close? |
| Managers | Planning and control — prices, costs, inventory |
| Employees | Job security and pay |
| Banks | Lend or extend an overdraft? Can it repay with interest? |
| Investors and lenders | Invest or lend? Return and risk |
| Suppliers | Give credit, and how much? |
| Customers | Will the business keep supplying? |
| Governments / tax authorities | Tax due, grants, statistics |
| Club members | How subscriptions are used; surplus or deficit |
| Other interested parties, e.g. public and environmental bodies | Effect on the community and environment |
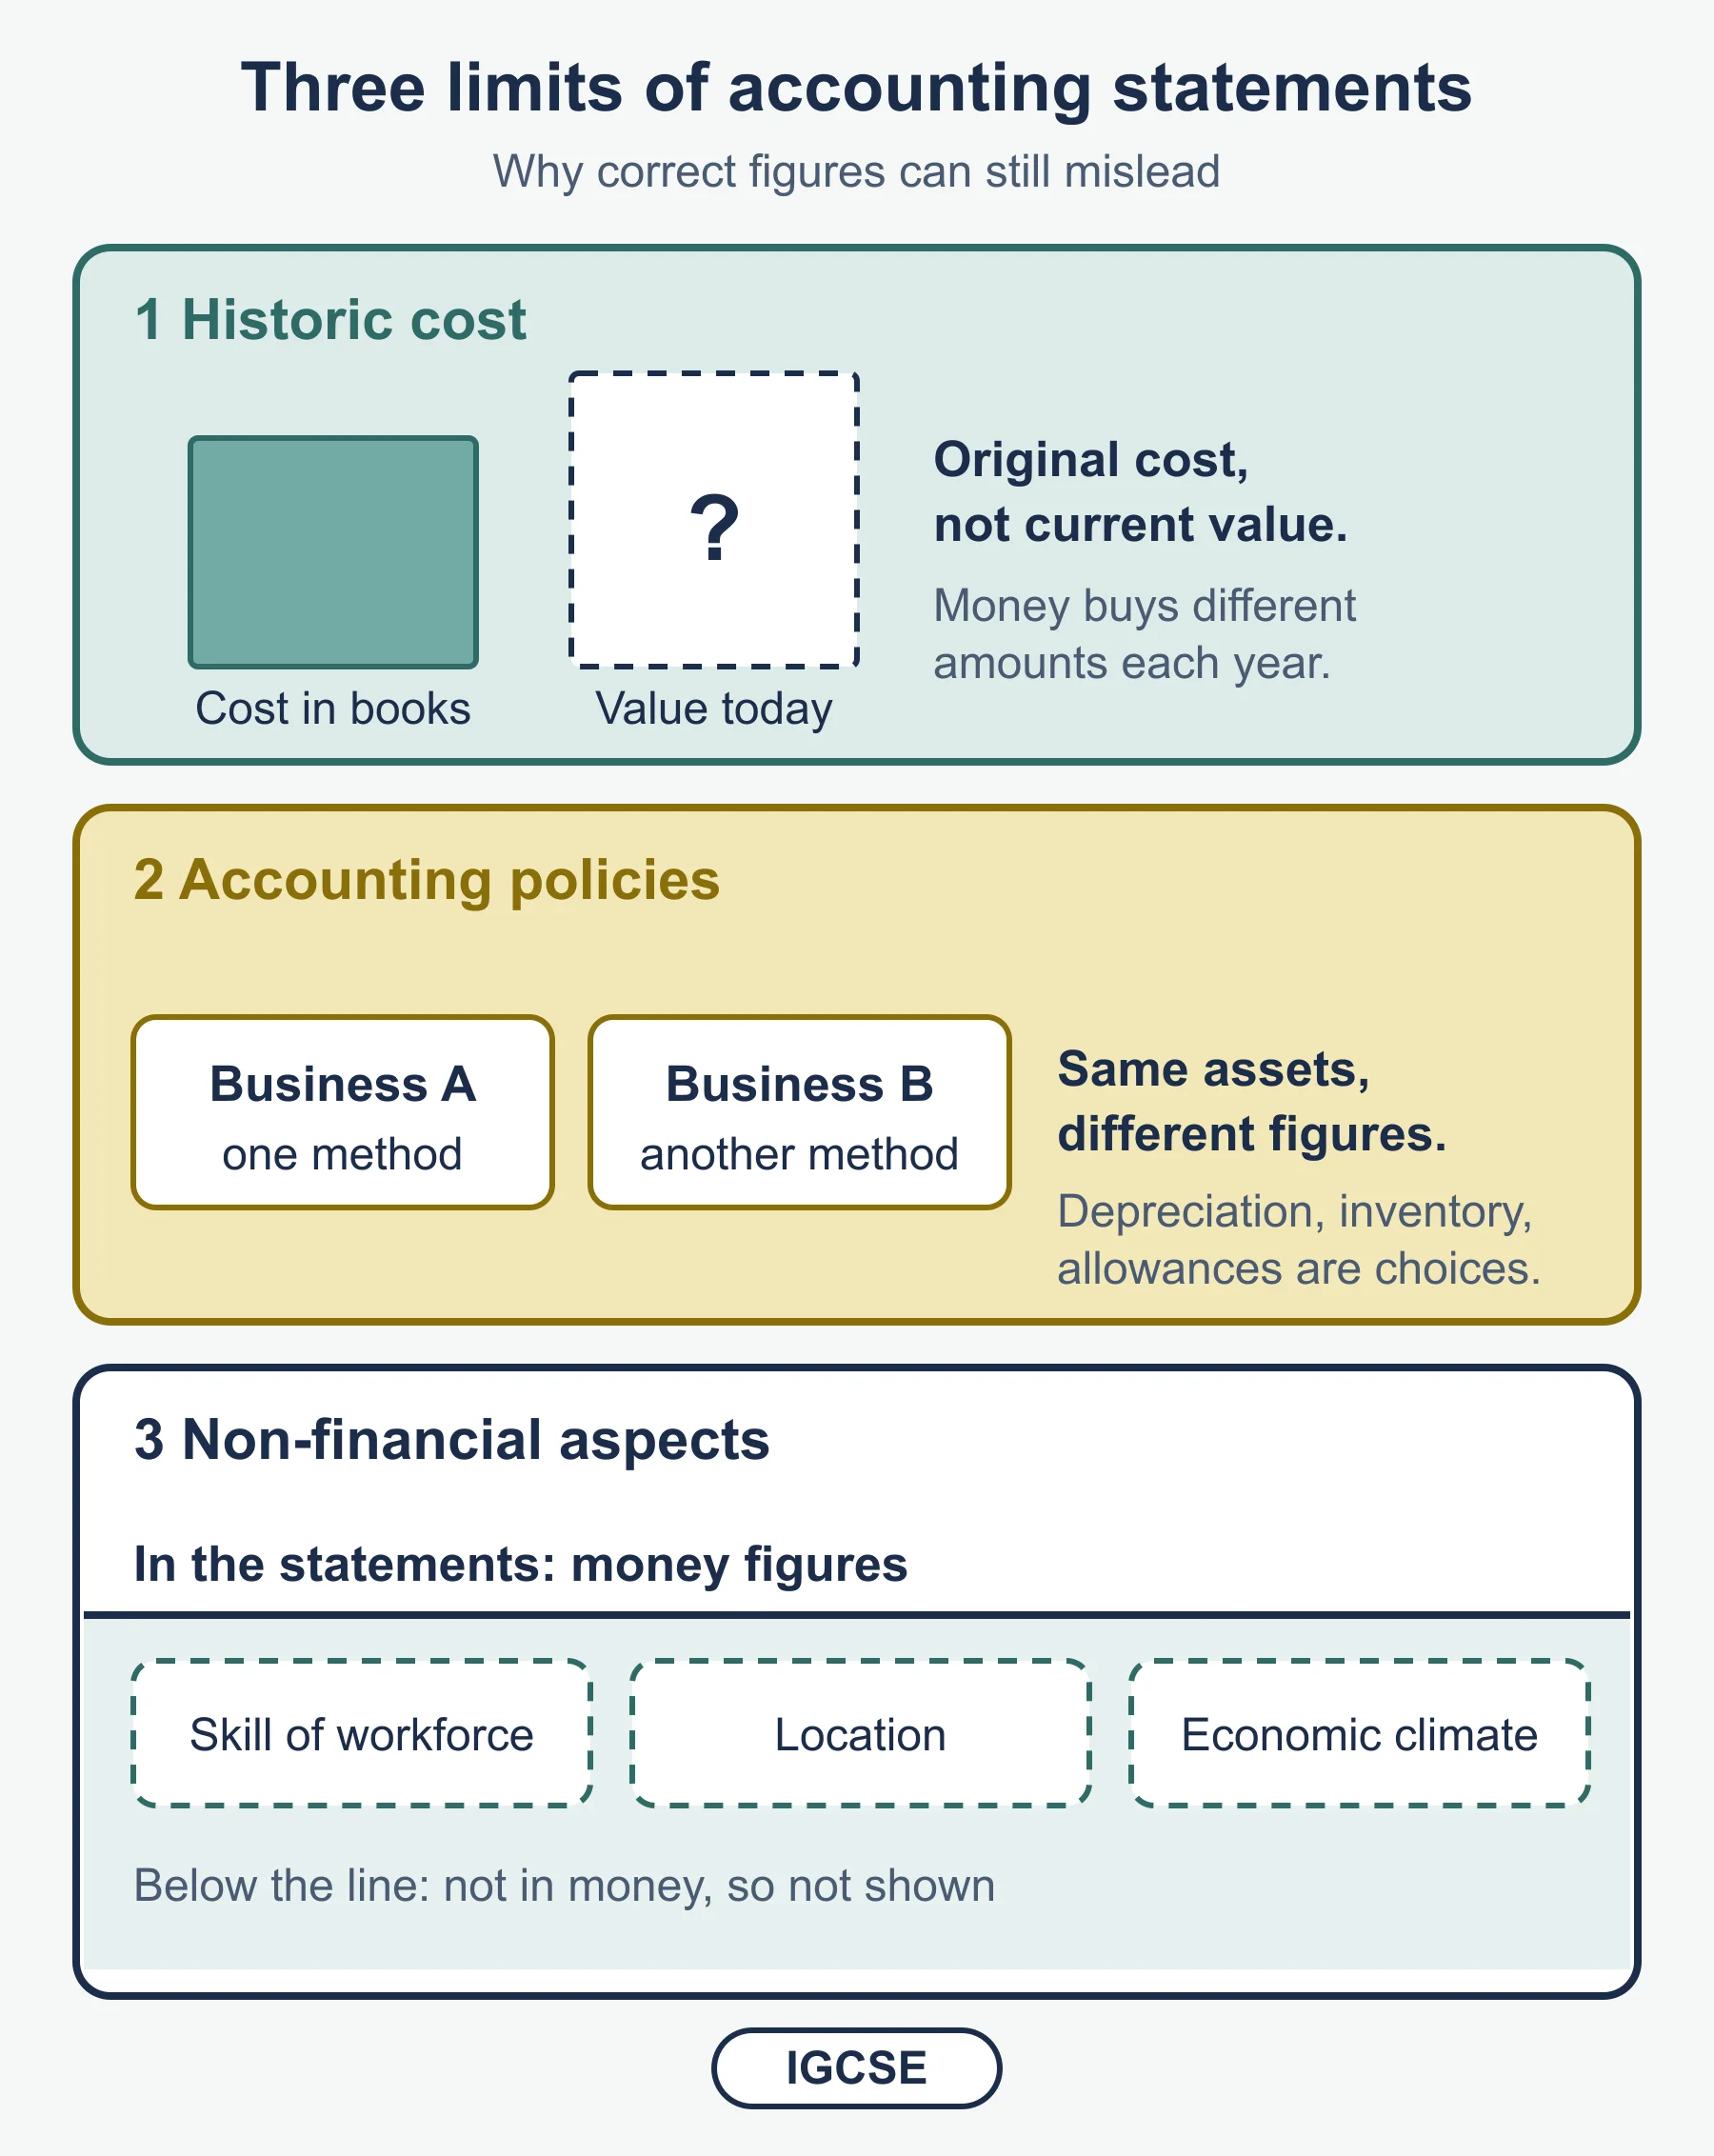
6.5 Limitations of accounting statements
- Historic cost — assets at original cost, not current value; figures from different years are not in comparable money.
- Application of accounting policies — depreciation methods, inventory valuation and allowances are choices and estimates, so figures vary between businesses and after a change of policy.
- Non-financial aspects — e.g. skill of the workforce, location of the business, economic climate: not measured in money, so not shown.
Worked example: two years at a glance
Harbour Traders Limited (full statements in the study guide). Profit for the year $60,000 (2025) and $48,000 (2026); debenture interest $4,000 each year; capital employed $360,000 and $380,000.
Ratio                               2025          2026
Gross profit margin               40.00%        35.42%
Mark-up                           66.67%        54.84%
Profit margin                     15.00%        10.00%
ROCE                              17.78%        13.68%   (64,000 / 360,000; 52,000 / 380,000)
Current ratio                   2.50 : 1      1.86 : 1
Acid test                       1.50 : 1      1.00 : 1
Rate of inventory turnover    6.86 times    6.20 times
Inventory turnover            53.23 days    58.87 days
Trade receivables turnover    47.91 days    60.83 days   (credit allowed: 30 days)
Trade payables turnover       54.75 days    50.69 days   (credit received: 60 days)
Reading it: revenue rose but lower selling prices and higher purchase prices cut the gross profit margin; expenses rose $22,000 against a $10,000 rise in gross profit, so the profit margin and ROCE fell. Liquidity weakened because customers pay more slowly, inventory is held longer and suppliers are paid sooner — the business now has a $20,000 overdraft despite a $48,000 profit.
Exam traps
- Writing the current ratio or acid test as a percentage — present it as a ratio, e.g. 1.86 : 1.
- Using profit after interest in ROCE, or leaving non-current liabilities out of capital employed.
- Using closing inventory, not average inventory, for inventory turnover.
- Using total revenue for trade receivables turnover when credit sales are given.
- Swapping gross profit margin (÷ revenue) and mark-up (÷ cost of sales).
- Stating a change without explaining it, or giving a recommendation that does not match the weak ratio.
- Assuming profit means more cash.
- Reading “higher days” as good: more inventory or receivables days usually means slower, not better.
Self-test
- State the formula for ROCE and what capital employed consists of.
- Revenue is $90,000 and cost of sales is $63,000. Calculate the gross profit margin and the mark-up.
- Why does the acid test leave out inventory?
- Give two reasons why profit for the year can fall when gross profit rises.
- Closing inventory is overvalued by $2,000. What is the effect on gross profit and profit for the year?
- Name two factors, other than management performance, that may make two businesses’ ratios differ.
- How might a supplier use a business’s accounting information?
- Give the three causes of the limitations of accounting statements named in the syllabus.
Answers: 1. Profit for the year before interest ÷ capital employed × 100; capital employed = issued shares + reserves + non-current liabilities. 2. Gross profit $27,000; gross profit margin $27,000 ÷ $90,000 × 100 = 30.00%; mark-up $27,000 ÷ $63,000 × 100 = 42.86%. 3. Inventory is the current asset least easily turned into cash, so the acid test shows whether current liabilities can be paid without relying on selling it. 4. Any two: expenses rose by more than gross profit; other income fell; a new expense such as interest on a new loan appeared. 5. Both are overstated by $2,000, because cost of sales is understated by $2,000. 6. Any two: type of business; size; location; pricing policy; how each is financed; accounting policies; different year-end dates. 7. To decide whether to supply on credit and how much credit to allow, by checking liquidity and how quickly the business pays its trade payables. 8. Historic cost; the application of accounting policies; non-financial aspects (e.g. skill of the workforce, location of the business, economic climate).
Frequently asked questions
What are the ten accounting ratios in Cambridge IGCSE Accounting 0452? The ten ratios are gross profit margin, mark-up, profit margin, return on capital employed, the current ratio, the acid test ratio, rate of inventory turnover (times), inventory turnover (days), trade receivables turnover (days) and trade payables turnover (days).
Why can profit and cash be different? Depreciation is an expense with no cash payment, buying non-current assets uses cash but is not an expense, and changes in inventory, receivables and payables move cash without changing profit. Loans, capital introduced, drawings and dividends also affect cash but not profit.
What does a fall in profit margin with a steady gross profit margin mean? If the gross profit margin is steady but the profit margin falls, expenses have risen relative to revenue. A falling gross profit margin points instead to selling prices, purchase costs or inventory valuation.
What are the problems of inter-business comparison? Detailed statements may not be available, the businesses may use different accounting policies or year-end dates, they may not be truly alike, the figures are historic and may include an untypical year, and ratios ignore non-financial aspects.
Do more inventory days or trade receivables days mean better performance? Usually not. Higher inventory or trade receivables days normally mean goods are selling more slowly or customers are paying more slowly, which ties up cash in working capital.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
IGCSE Accounting: Calculating and interpreting accounting ratios (Cambridge 0452)
Study guide to calculating and interpreting the ten accounting ratios with a two-year worked example, for Cambridge IGCSE Accounting 0452, 6.1-6.2.
Accounting · Cambridge · IGCSE, O Level
Read guide -
Practice questions
IGCSE Accounting: Calculating and interpreting accounting ratios (Cambridge 0452) – Practice Questions
Original practice questions with worked answers on calculating and interpreting accounting ratios, for Cambridge IGCSE Accounting 0452 sections 6.1-6.2.
Accounting · Cambridge · IGCSE, O Level
Try questions -
Revision notes
IGCSE Accounting: Calculating and interpreting accounting ratios (Cambridge 0452) – Revision Notes
Condensed revision notes on the ten accounting ratios, interpreting them and profit versus cash, for Cambridge IGCSE Accounting 0452 sections 6.1-6.2.
Accounting · Cambridge · IGCSE, O Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

