
Revision Notes
IGCSE Accounting: Accounting Concepts and Modern Practice — Revision Notes
Condensed notes on the ten accounting concepts, five ethical principles, digital records and four storage types for Cambridge IGCSE Accounting 0452 Topic 7.
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- Accounting concepts and modern practice
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus topics and points this page is mapped to
0452
- 7 Accounting concepts and modern practice (topic-level mapping)
7707
- 7 Accounting concepts and modern practice (topic-level mapping)
"Topic-level mapping" means this page belongs to that topic; it does not claim to cover every point in it.
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. For this topic, the 2026 syllabus calls the same ten items accounting principles, and its 7.2 is Accounting policies (the influence of international accounting standards and the objectives of comparability, relevance, reliability and understandability), which the 2027-2029 syllabus removes. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
Condensed for the final weeks. For the full explanation, use the Accounting Concepts and Modern Practice study guide. Most applications link back to Topic 4 (Accounting Procedures) and Topic 5 (Preparation of Financial Statements).
The core question this topic answers
Why are the records kept the way they are, by whom, and how? 7.1 gives the reasons behind the entries, 7.2 the standards of the people making them, and 7.3 the tools used to keep and store them. 7.2 and 7.3 are new in the 2027-2029 syllabus.
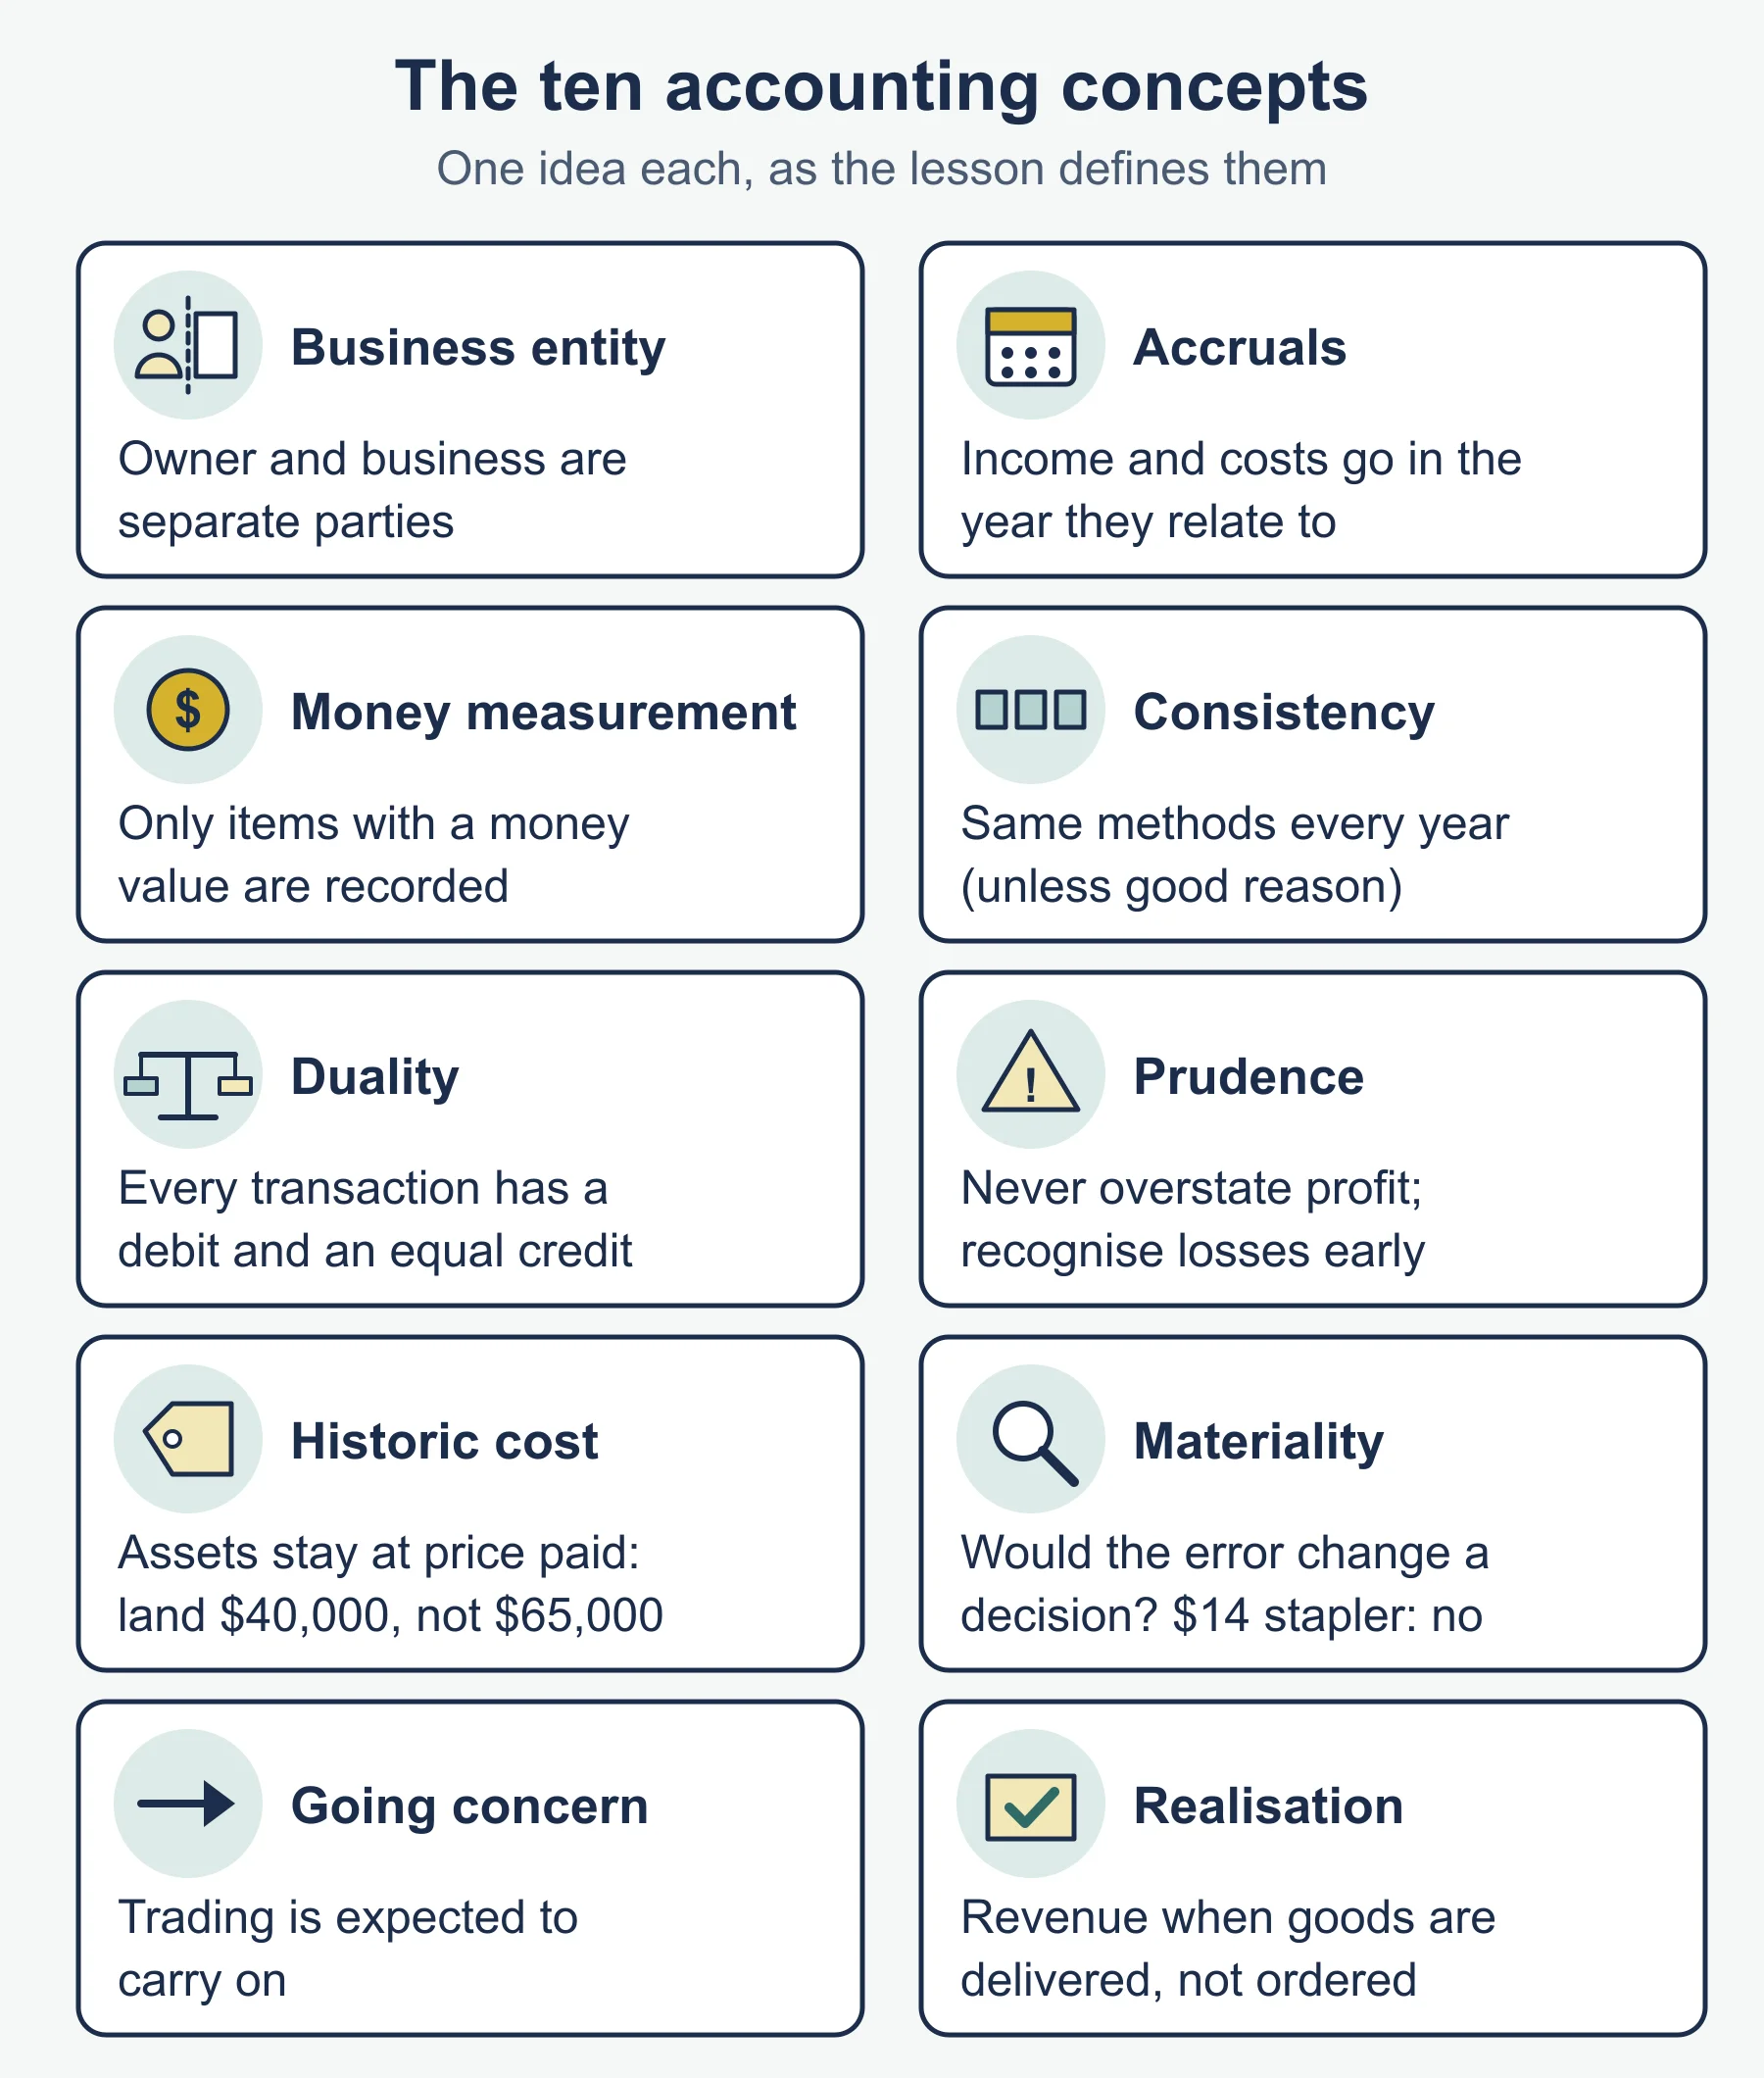
7.1 Accounting concepts — meaning plus application
| Concept | Meaning in one line | Application to learn |
|---|---|---|
| Business entity | Business is separate from its owner | Owner’s goods taken and private expenses paid = drawings |
| Consistency | Same method used period after period | Keep the same depreciation method; don’t switch to change profit |
| Duality | Every transaction has two equal aspects | Debit and credit of equal value; accounting equation |
| Going concern | Business will continue for the foreseeable future | Non-current assets at cost less depreciation, not forced-sale value |
| Historic cost | Assets recorded at original cost | Rise in market value of land not recorded |
| Matching / accruals | Revenue and costs in the period they relate to | Accruals (other payables), prepayments (other receivables), depreciation |
| Materiality | Small items need not be treated precisely | Cheap long-lasting item (e.g. $25 waste bin) charged as an expense |
| Money measurement | Only items measurable in money are recorded | Staff skill and morale not recorded |
| Prudence | Do not overstate profit or assets; recognise expected losses | Allowance for irrecoverable debts; inventory at lower of cost and NRV |
| Realisation | Revenue when goods/services pass and the customer accepts liability to pay | Order taken now, goods delivered next year = next year’s revenue |
Answer pattern: name the concept → what it means → what it requires in this business’s records → the effect on profit or assets.
7.2 Ethical considerations
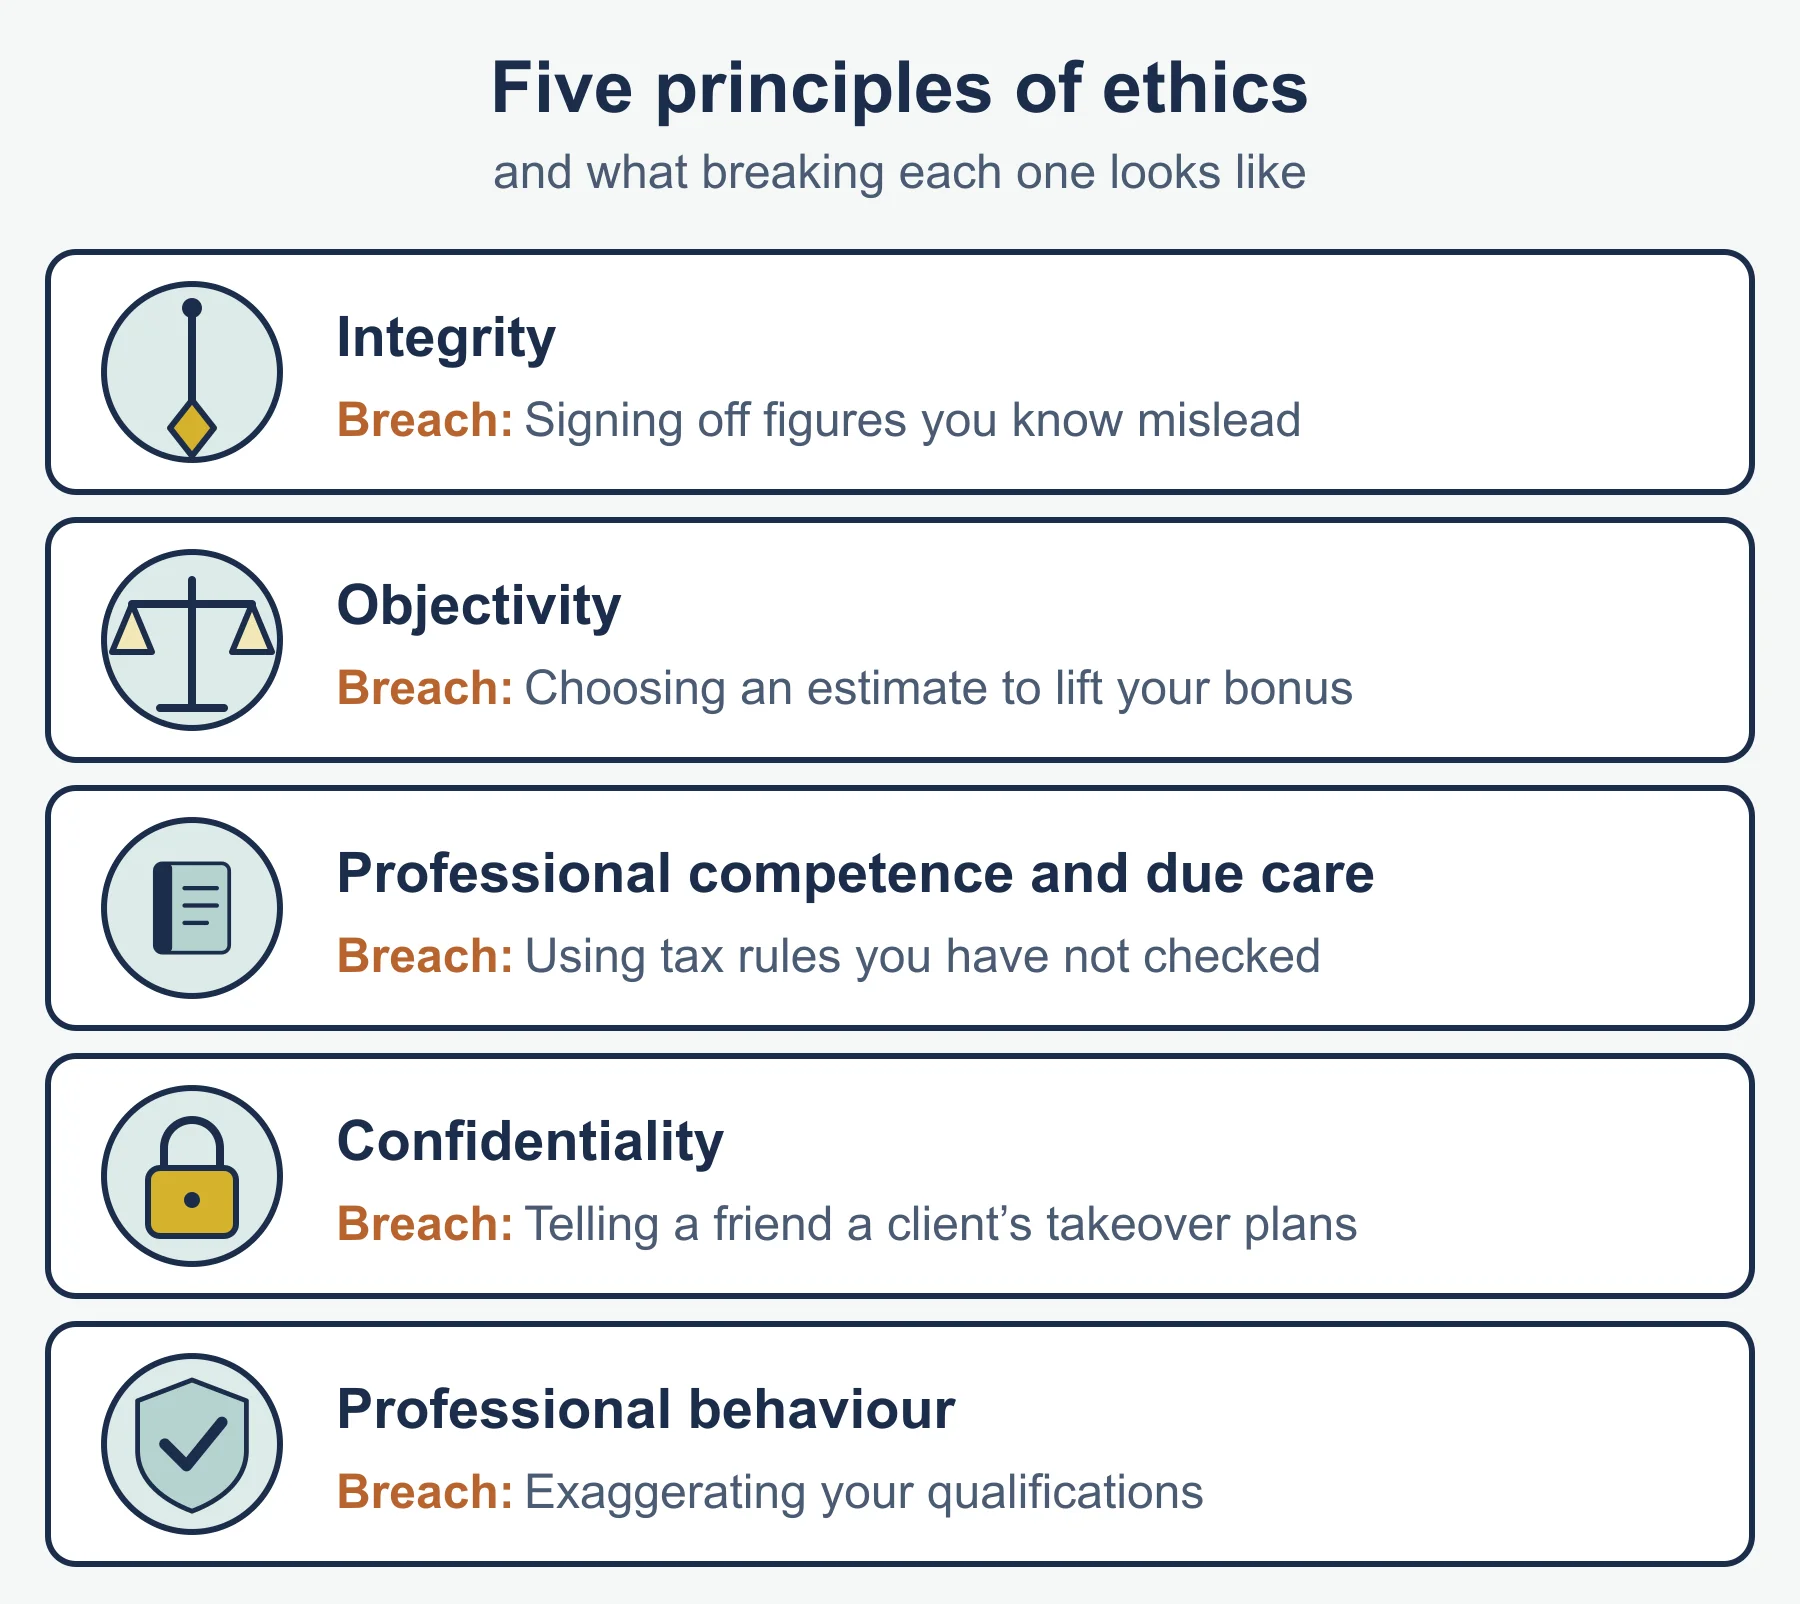
Need for a framework: others rely on accounting information they cannot check; accountants face pressure (higher profit for a loan, lower for tax) and see confidential data. A framework sets the standard in advance.
| Principle | Meaning | Example |
|---|---|---|
| Integrity | Straightforward and honest | Not recording fictitious sales or hiding liabilities |
| Objectivity | No bias, conflict of interest or undue influence | Owner’s pressure must not change the allowance for irrecoverable debts |
| Professional competence and due care | Keep knowledge up to date; work carefully | Check depreciation and accruals before issuing statements |
| Confidentiality | Don’t disclose or misuse work information without authority or a duty to | Don’t discuss a customer’s debts or staff wages outside work |
| Professional behaviour | Comply with laws and regulations; don’t discredit the profession | Don’t help an owner evade tax |
Significance: owners, investors, banks and lenders, suppliers, employees and governments / tax authorities (6.4, Analysis and Interpretation) decide using the figures. Unethical figures lead to bad loans, unpaid suppliers, lost jobs, lost tax revenue and lost trust in financial information.
7.3 Technology and sustainability
- Digital applications can hold all or part of the records: automatic double entry, totals, control accounts and trial balance; faster and fewer arithmetic errors, but cost, training, system dependence and input errors carried through.
- Store safely: complete, accurate, available, protected from loss and unauthorised access.
- Store sustainably: less paper and printing, no needless duplicate copies, responsible disposal of old devices after securely removing data, storage that stays usable as long as records are needed.
- Risks of not doing so: data lost (fire, flood, theft, failure, deletion); hacking or fraud; confidential data exposed; penalties; cost of rebuilding records; reputational damage; waste.
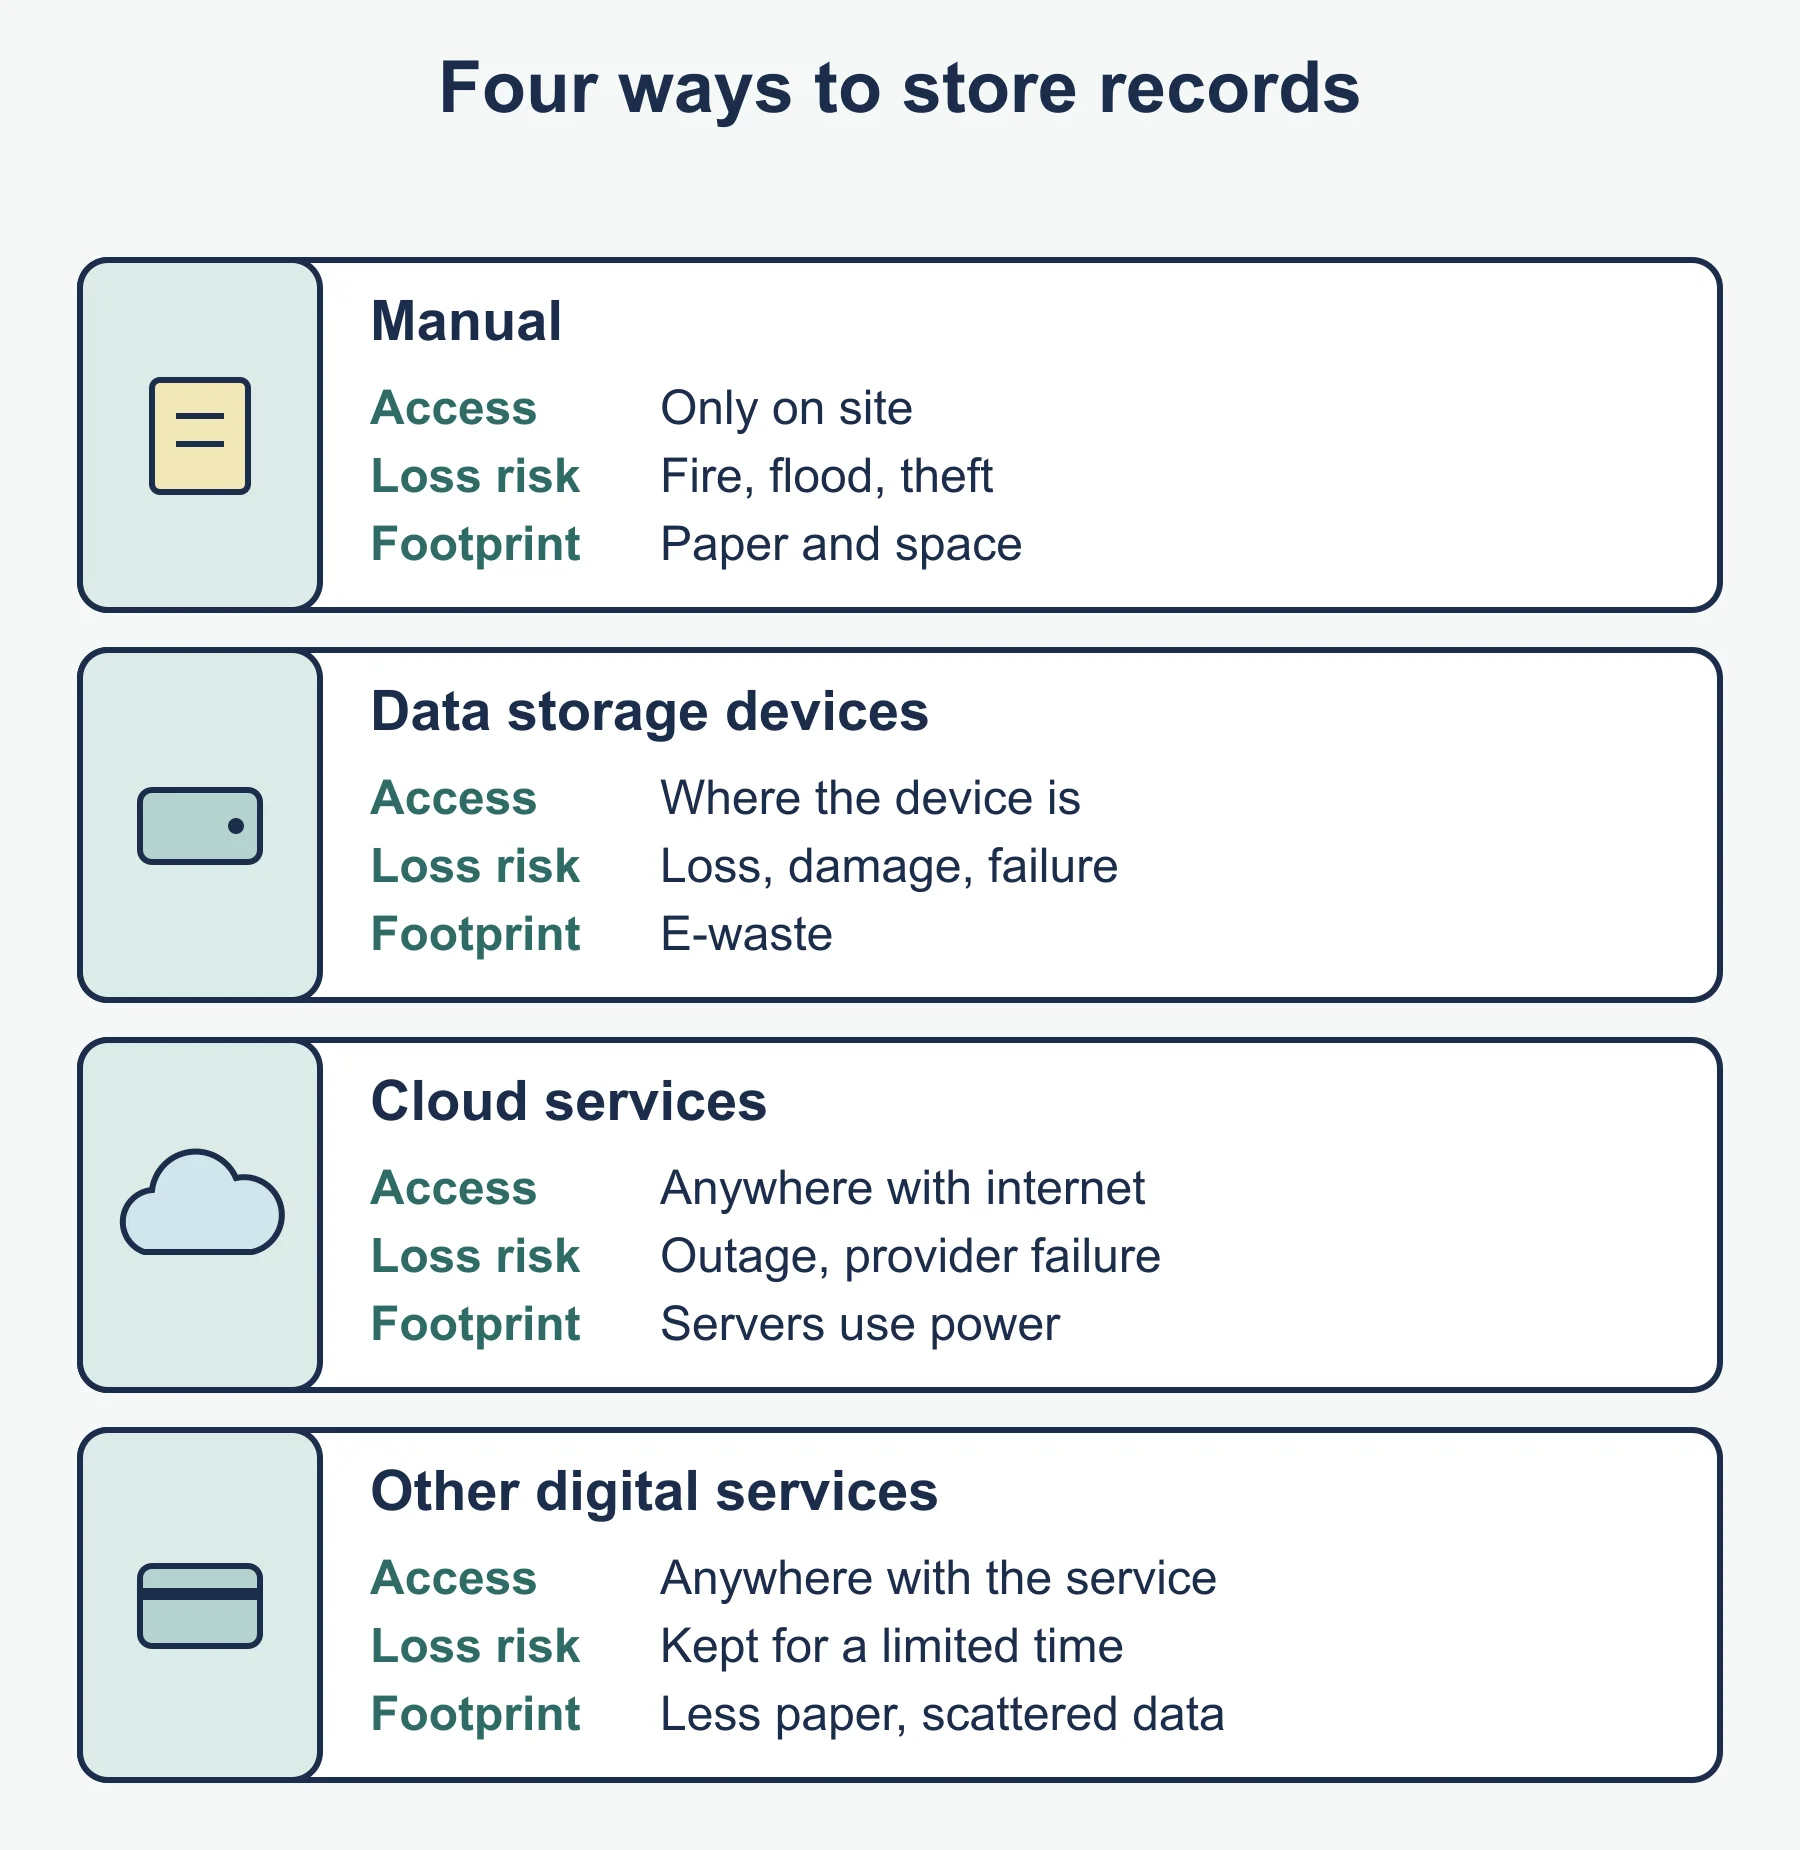
| Storage | Advantages | Disadvantages |
|---|---|---|
| Manual | Cheap; no power/internet; cannot be hacked | Bulky; fire, flood, theft; slow to search; hard to back up; paper |
| Data storage devices | Large capacity; fast; no internet; physical control | Lost or stolen; can fail; back-ups needed elsewhere; outdated; e-waste |
| Cloud services | Access anywhere; provider back-ups; safe from local fire/theft | Needs internet; ongoing cost; depends on provider; third party holds data |
| Other digital services | Records created automatically; less paper; searchable | Scattered; depends on each service; may be kept for a limited time only |
Note (7.3): “Candidates do not need to have knowledge of or access to specific accounting software packages or programs.”
Worked example: concept, correction, figure
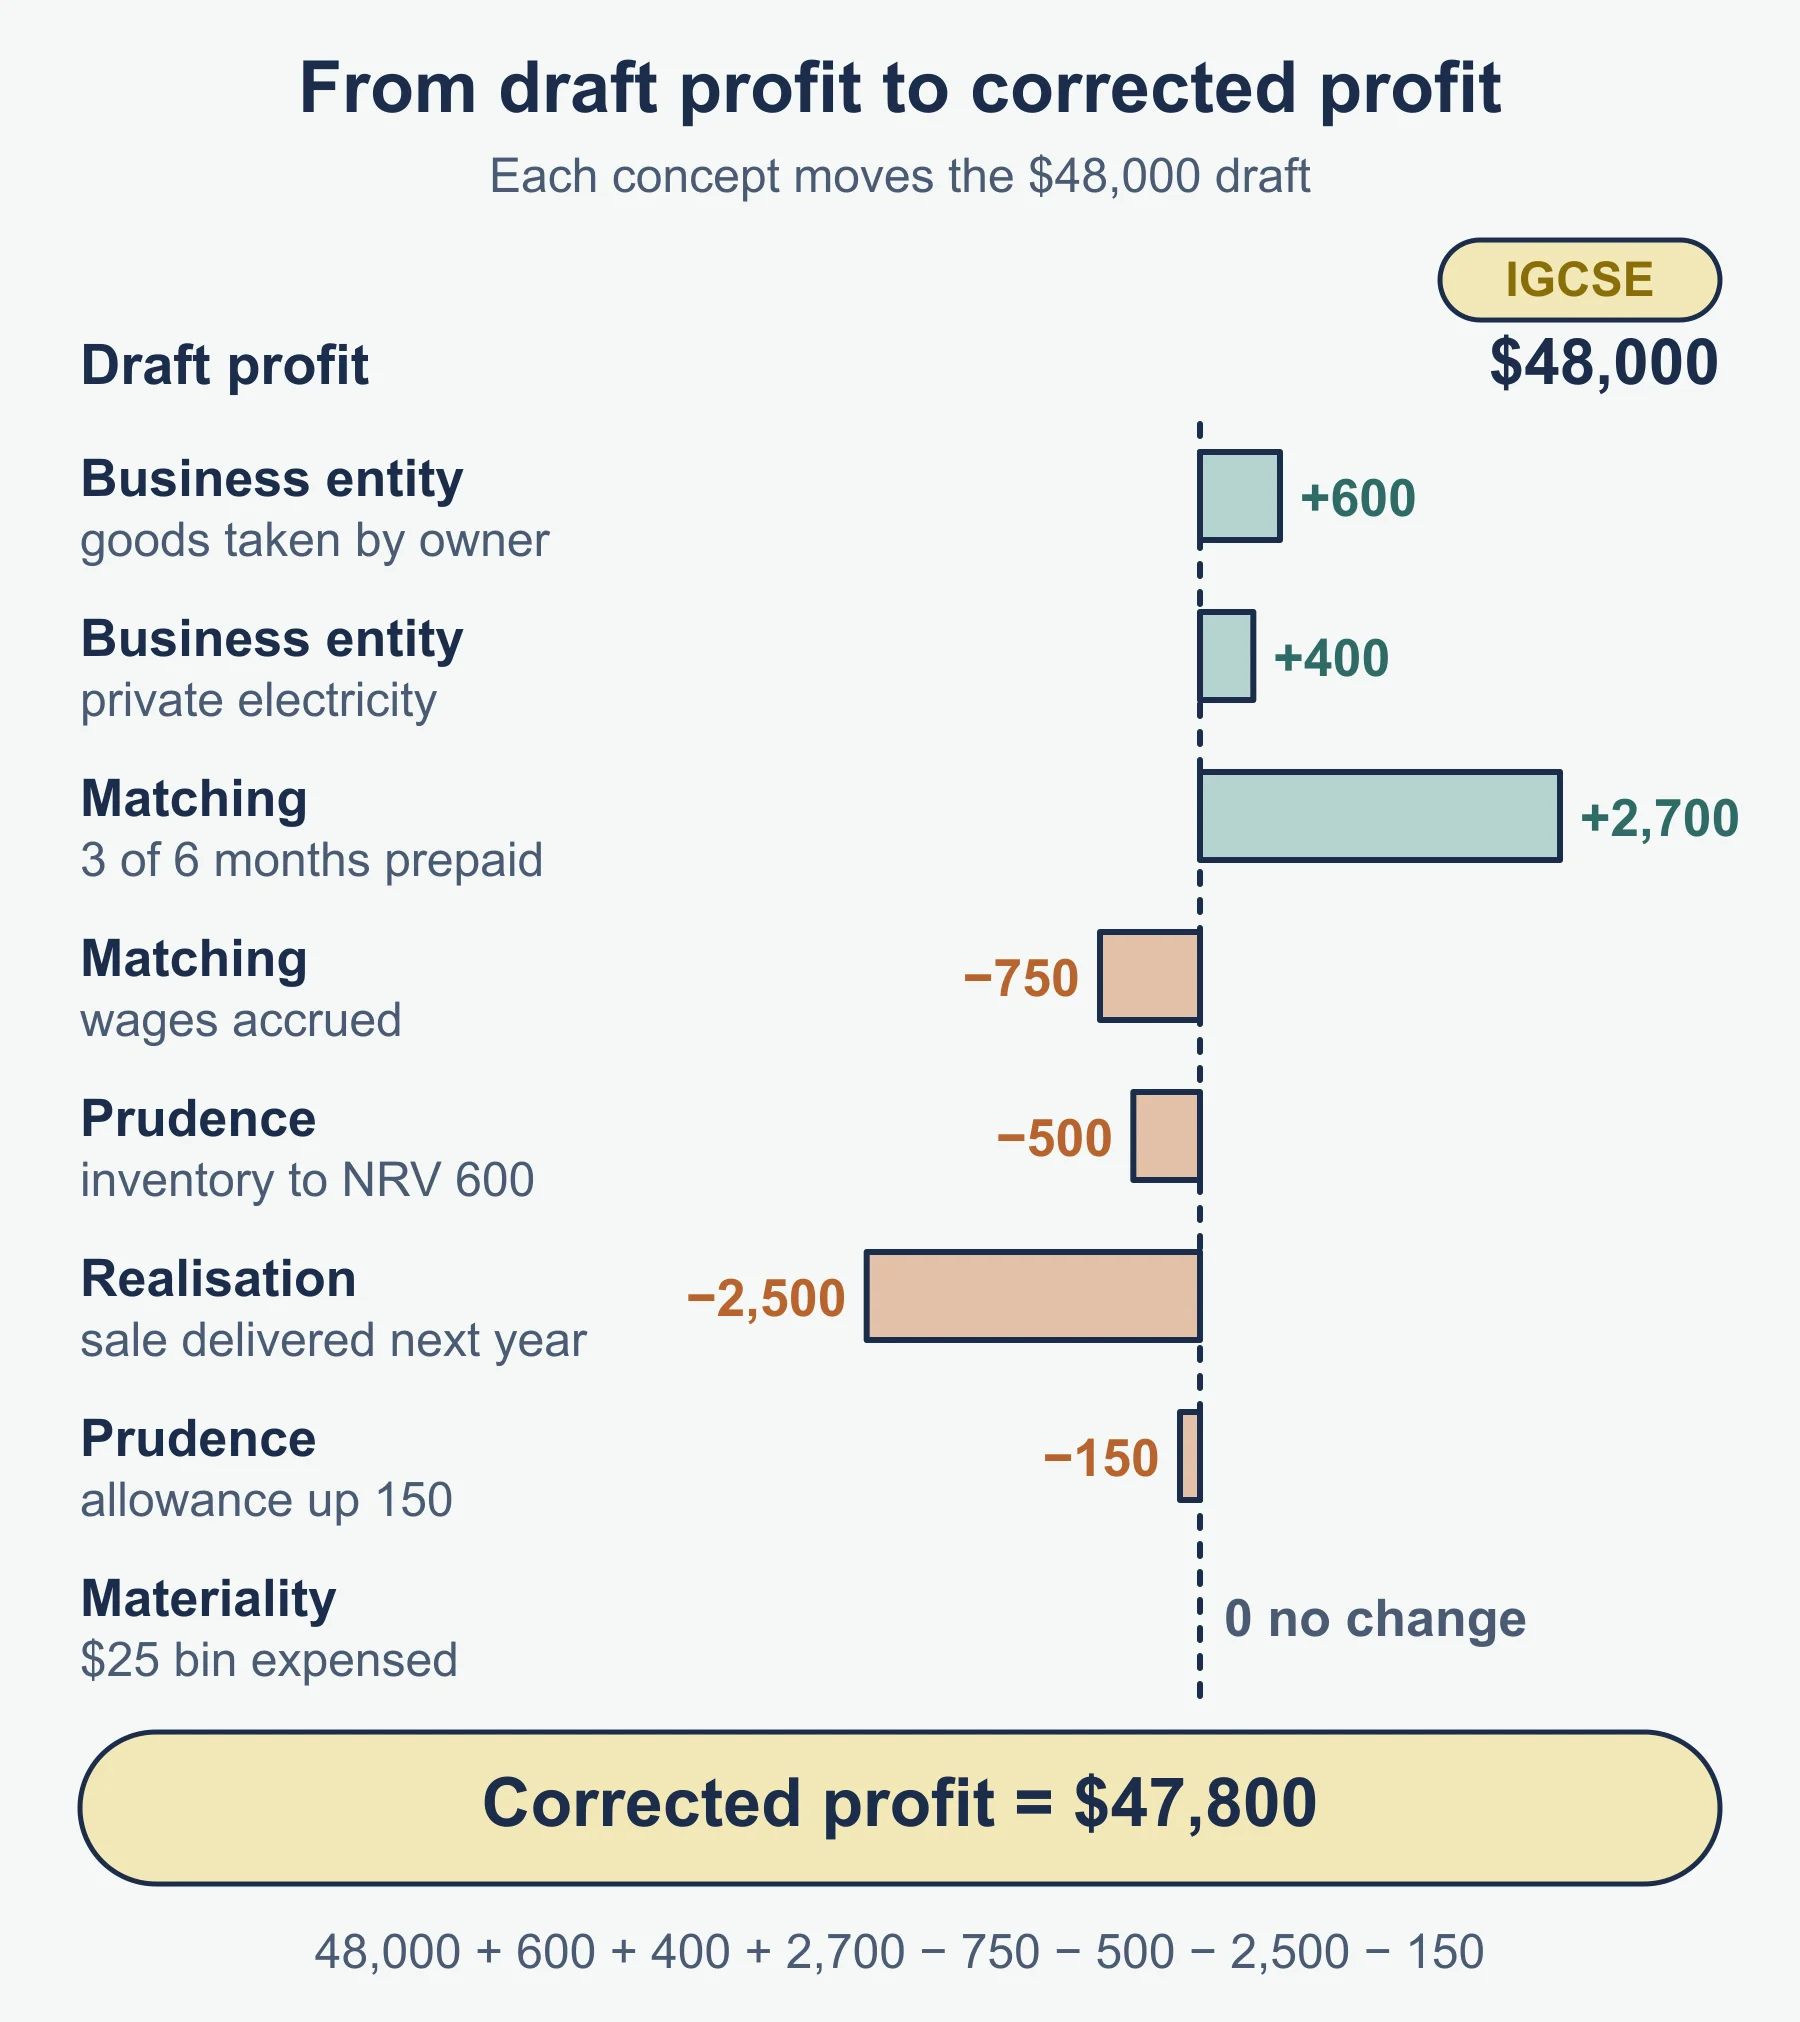
Draft profit for the year $48,000. Adjust:
Draft profit for the year                                48,000
Goods taken by owner, no entry (business entity)           +600
Owner's private electricity in expenses (entity)           +400
Rent 5,400 for 6 months from 1 Oct; 3 months prepaid
  5,400 x 3/6 = 2,700 (matching)                         +2,700
Wages accrued (matching/accruals)                          -750
Inventory item cost 1,100; NRV 700 - 100 = 600
  write down 1,100 - 600 = 500 (prudence)                  -500
Sale recorded, goods delivered next year (realisation)   -2,500
Allowance 12,000 x 5% = 600; b/f 450
  increase 600 - 450 = 150 (prudence)                      -150
$25 waste bin expensed (materiality)                          0
Corrected profit for the year                            47,800
48,000 + 600 + 400 + 2,700 − 750 − 500 − 2,500 − 150 = 47,800.
Exam traps
- Defining a concept without applying it to the figures given.
- Mixing up matching (which period) and realisation (when revenue is earned at all).
- Saying prudence means understating profit — it means not overstating it.
- Treating materiality as permission to ignore errors.
- Confusing integrity (honesty) with objectivity (freedom from bias and pressure).
- Discussing storage with advantages only, or naming software products.
- Answering with the 2026 syllabus’s 7.2 Accounting policies content (see the edition note), which is not part of 7.1–7.3 for 2027-2029.
Self-test
- Which concept explains why an owner’s private expenses paid by the business are recorded as drawings?
- Name two applications of the prudence concept.
- Why does the going concern concept mean non-current assets are shown at cost less depreciation?
- A $15 stapler is charged as an expense rather than depreciated. Which concept allows this?
- Name the five fundamental principles of the ethical framework in 7.2.
- Give one example of how objectivity applies in accounting.
- List the four types of storage system named in 7.3.
- Give one advantage and one disadvantage of cloud services.
Answers: 1. Business entity. 2. Any two of: an allowance for irrecoverable debts; writing off irrecoverable debts; valuing inventory at the lower of cost and net realisable value. 3. The business is expected to keep using the assets, so their cost is spread over their useful lives rather than valued at what they would fetch if sold now. 4. Materiality. 5. Integrity; objectivity; professional competence and due care; confidentiality; professional behaviour. 6. For example, not reducing the allowance for irrecoverable debts because the owner wants a higher profit, or not deciding a relative’s debt. 7. Manual, data storage devices, cloud services, other digital services. 8. Advantage: accessible from anywhere by authorised users, or provider back-ups, or safe from fire or theft at the premises. Disadvantage: needs a reliable internet connection, or ongoing cost, or dependence on the provider.
Frequently asked questions
What does the duality concept mean? Duality means every transaction has two aspects of equal value, both recorded by a debit and a credit of the same amount. It is the basis of double entry, the trial balance and the accounting equation.
What does the realisation concept mean? Revenue is recognised when goods or services are passed to the customer and the customer accepts liability to pay, not when an order is received or cash is paid. A credit sale is recorded when the goods are supplied.
Can a business keep only part of its records digitally? Yes. A business can keep all its records digitally or only part of them, for example a digital sales ledger and cash book with a handwritten petty cash book. The 0452 syllabus does not require knowledge of any particular software package.
Is 7.2 Accounting policies in the 2027-2029 Cambridge IGCSE Accounting syllabus? No. For 2027 to 2029, section 7.2 is Ethical considerations; Accounting policies belongs to the 2026 syllabus. Answering with the older 7.2 content does not match the current sections 7.1 to 7.3.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Revision notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
Accounting · Cambridge · IGCSE, O Level
Revise topic -
Study guides
IGCSE Accounting: Accounting concepts, ethics, technology and sustainability (Cambridge 0452)
Example-led study guide to the ten accounting concepts, five ethical principles, digital records and data storage for Cambridge IGCSE Accounting 0452.
Accounting · Cambridge · IGCSE, O Level
Read guide -
Practice questions
IGCSE Accounting: Accounting concepts, ethics, technology and sustainability (Cambridge 0452) – Practice Questions
Original practice questions with worked answers on accounting concepts, ethical principles, digital records and storage for Cambridge IGCSE Accounting.
Accounting · Cambridge · IGCSE, O Level
Try questions
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

