
Revision Notes
IGCSE Accounting: Preparation of Financial Statements — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 5: sole traders, partnerships, companies, manufacturing accounts, clubs and incomplete records.
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- Preparation of financial statements
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus topics and points this page is mapped to
0452
- 5 Preparation of financial statements (topic-level mapping)
7707
- 5 Preparation of financial statements (topic-level mapping)
"Topic-level mapping" means this page belongs to that topic; it does not claim to cover every point in it.
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. For this topic, the 2026 syllabus covers only trading and service businesses in 5.1 and limits drawings adjustments to goods taken by the owner for own use; for limited companies it excludes cumulative and non-cumulative preference shares, rights issues, share premium and capital redemption reserve but requires the difference between redeemable and non-redeemable preference shares (the 2027-2029 syllabus lists none of these); and for incomplete records it does not ask why businesses keep them or what their advantages are. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
Condensed for the final weeks. For the full explanation and fully balanced worked examples, use the Preparation of Financial Statements study guide. The ledger entries behind the adjustments are in the Accounting Procedures study guide, and the ratios built from these statements are in Analysis and Interpretation.
The core question this topic answers
What profit did the organisation make, and what is its financial position at the year end? Six sub-topics, one pair of statements — a statement of profit or loss (or income and expenditure account) and a statement of financial position — prepared for different organisations and from different starting information. Master the sole trader version and the rest are variations.
5.1 Sole traders
Types: trading (cost of sales and gross profit), service (fees less expenses, no gross profit), manufacturing (adds a manufacturing account) or a combination (service income added after gross profit).
| Advantages | Disadvantages |
|---|---|
| Keeps all profit; full control; quick decisions | Unlimited liability |
| Easy and cheap to set up; privacy | Limited capital; bears all losses; heavy workload; lack of continuity |
Why the statements matter: the statement of profit or loss measures profit or loss for a period; the statement of financial position records assets, liabilities and capital on a specified date.
SOFP headings: non-current assets (tangible); intangible assets (no physical form, e.g. goodwill); current assets; current liabilities; non-current liabilities; capital (opening + capital introduced + profit – drawings).
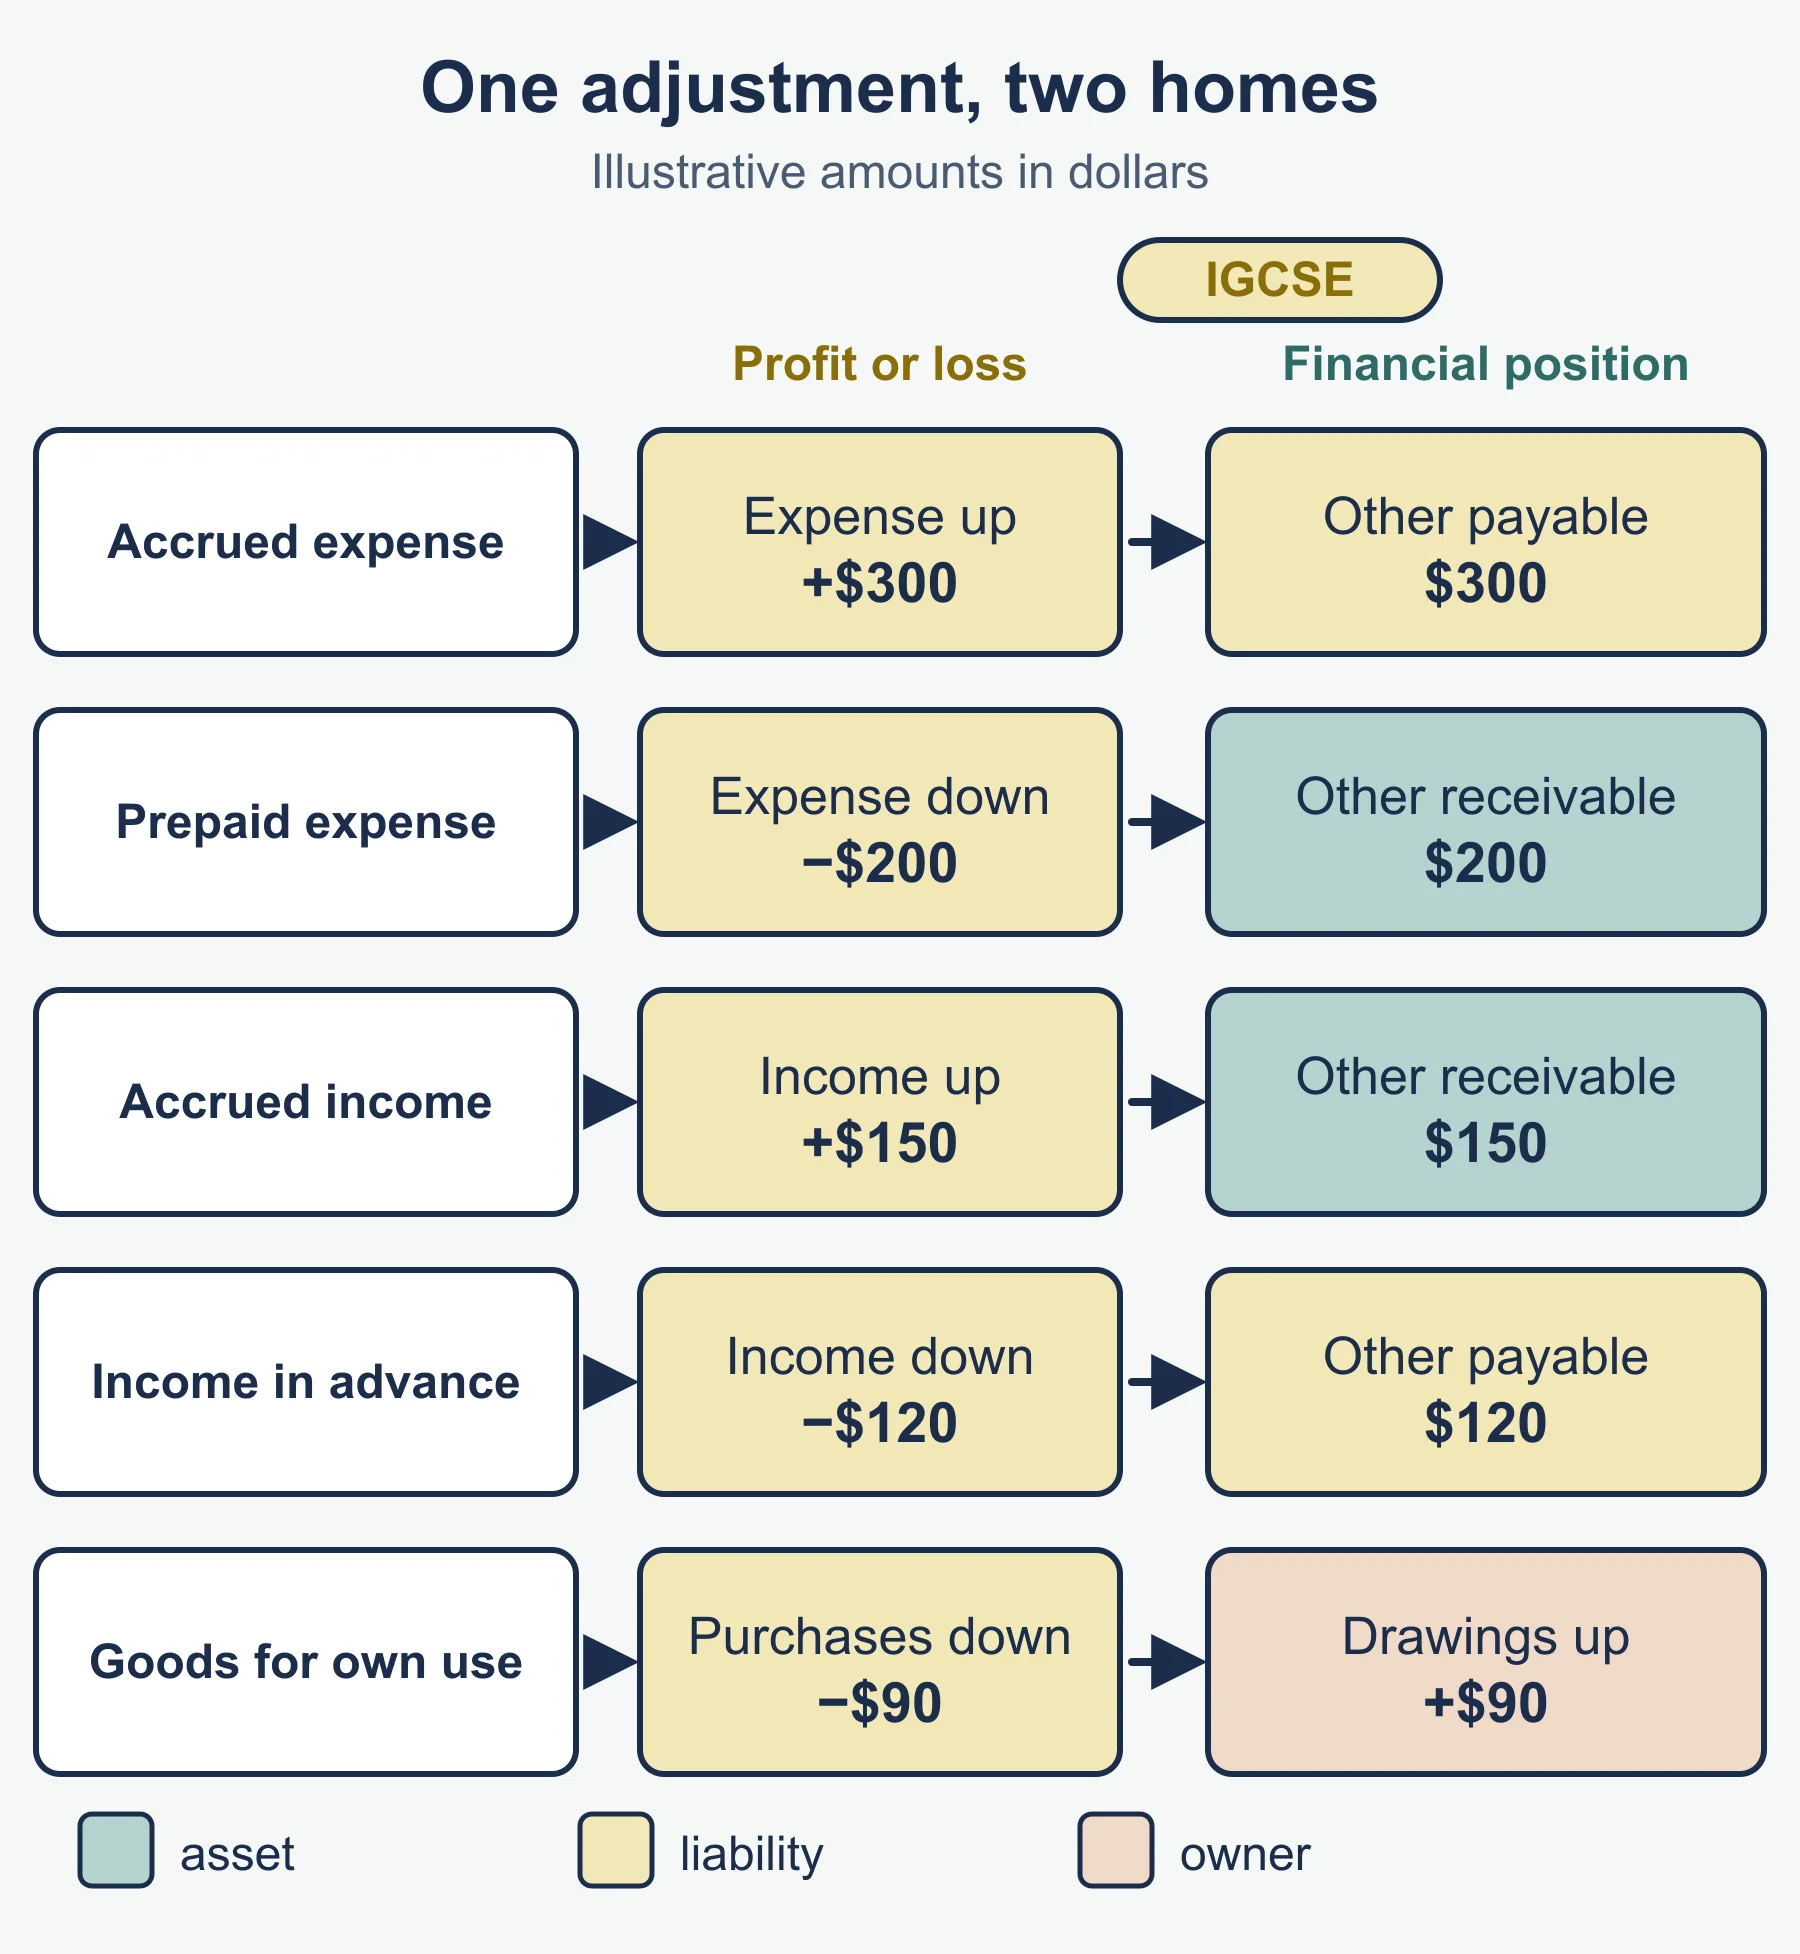
Every adjustment has two homes:
| Adjustment | SoPL | SOFP |
|---|---|---|
| Depreciation (straight line / reducing balance) | This year’s charge as expense | Cost less accumulated depreciation |
| Depreciation (revaluation: start value + additions – end value) | Fall in value as expense | End-of-year valuation |
| Accrued expense | + expense | Other payables |
| Prepaid expense | – expense | Other receivables |
| Accrued income | + income | Other receivables |
| Income received in advance | – income | Other payables |
| Irrecoverable debt | Expense | – trade receivables |
| Allowance for irrecoverable debts | Only the increase (expense) or decrease (income) | Full allowance deducted from trade receivables |
| Goods taken for own use (cost) | – purchases | + drawings |
| Other assets taken by owner | — | – that asset; + drawings |
| Owner’s private expense paid by business | – expense | + drawings |
Effect of a change in a balance: trace it through both statements. Closing inventory up $400 → gross profit, profit, current assets and capital all up $400. Recording goods for own use → profit up, drawings up by the same amount, closing capital unchanged.
5.2 Partnerships
Can be trading, service, manufacturing or a combination. Advantages: more capital, shared skills, workload and losses. Disadvantages: unlimited liability, shared profits, disagreements, each partner bound by the others’ decisions.
Partnership agreement (avoids disputes): capital contributed, profit-sharing ratio, interest on capital, interest on drawings, partners’ salaries, interest on partners’ loans, limits on drawings.
| Item | Where it goes |
|---|---|
| Interest on a partner’s loan | Expense in the statement of profit or loss (not an appropriation) |
| Interest on drawings | Added in the appropriation account; debit current account |
| Interest on capital | Deducted in the appropriation account; credit current account |
| Partners’ salaries | Deducted in the appropriation account; credit current account |
| Balance of profit or loss | Shared in the profit-sharing ratio |
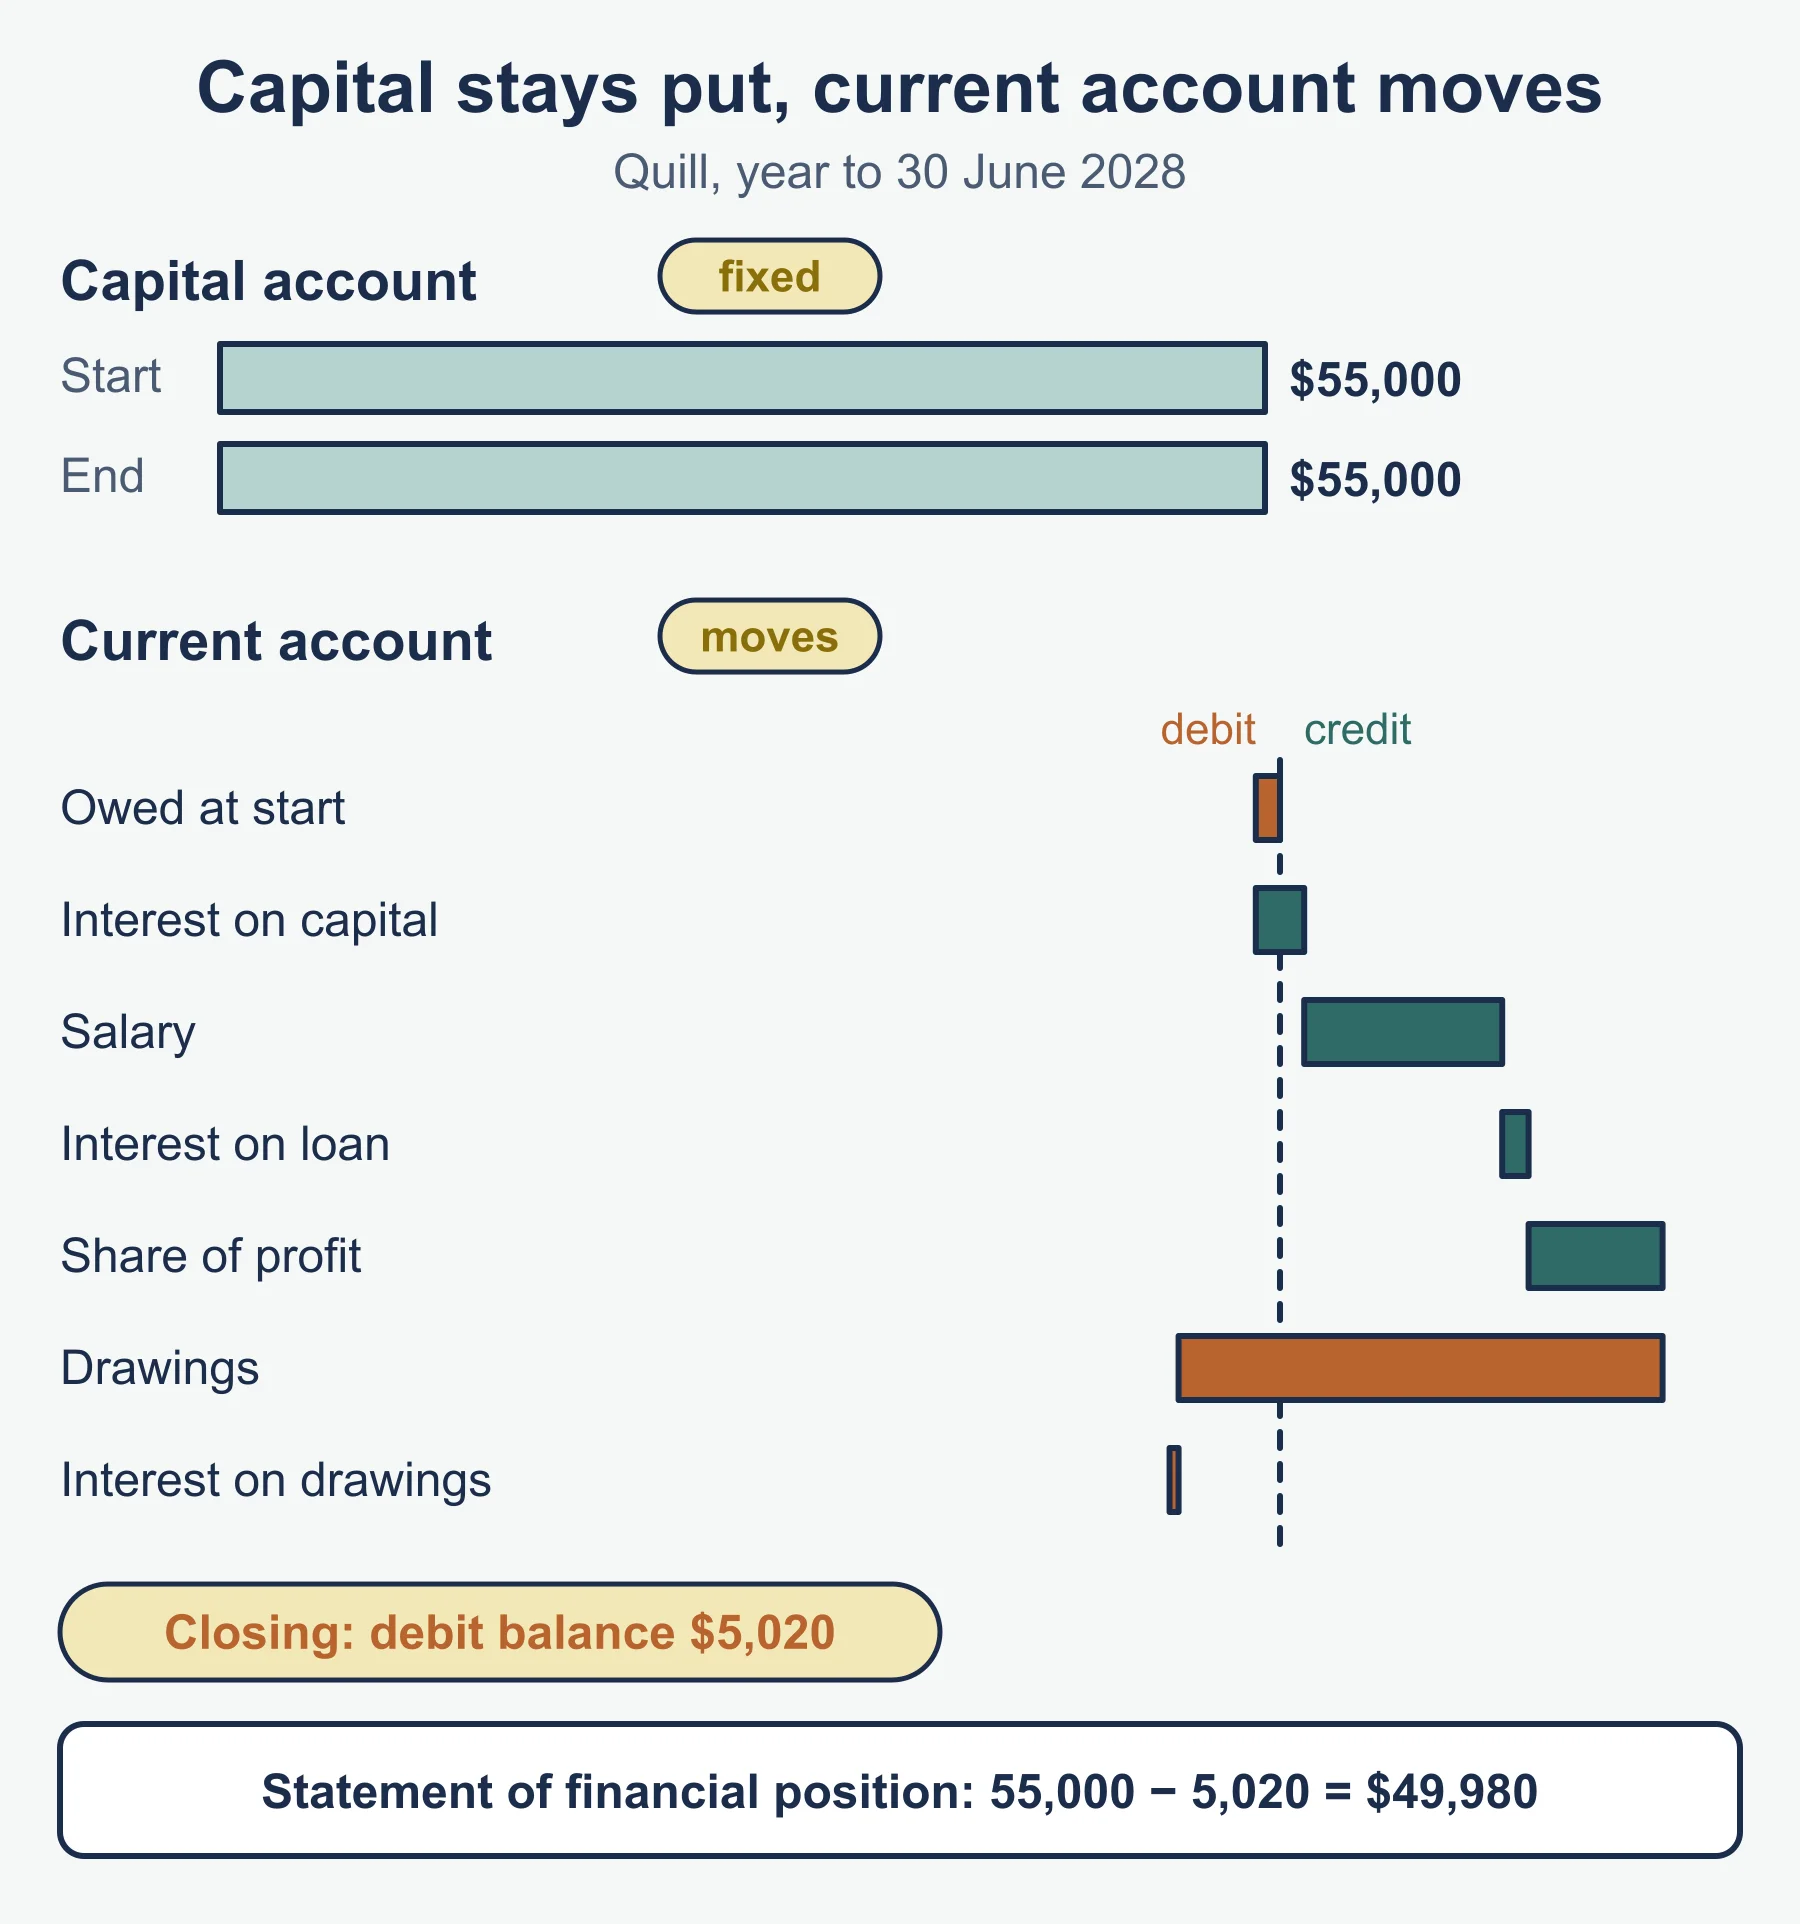
Capital account: long-term investment, usually fixed. Current account: changes yearly — credited with interest on capital, salary, share of profit; debited with drawings, interest on drawings, share of loss; can have a debit balance (shown in brackets in the SOFP).
Not required (syllabus Note): dissolution, changes to the profit-sharing ratio, limited liability partnerships, and financial statements on the admission/departure of a partner.
5.3 Limited companies
Can be trading, service, manufacturing or a combination.
- Limited liability: shareholders can lose only what they paid, or agreed to pay, for their shares.
- Equity: share capital + reserves = total assets – total liabilities.
- Capital structure: preference share capital (fixed-rate dividend, paid first), ordinary share capital, general reserve, retained earnings.
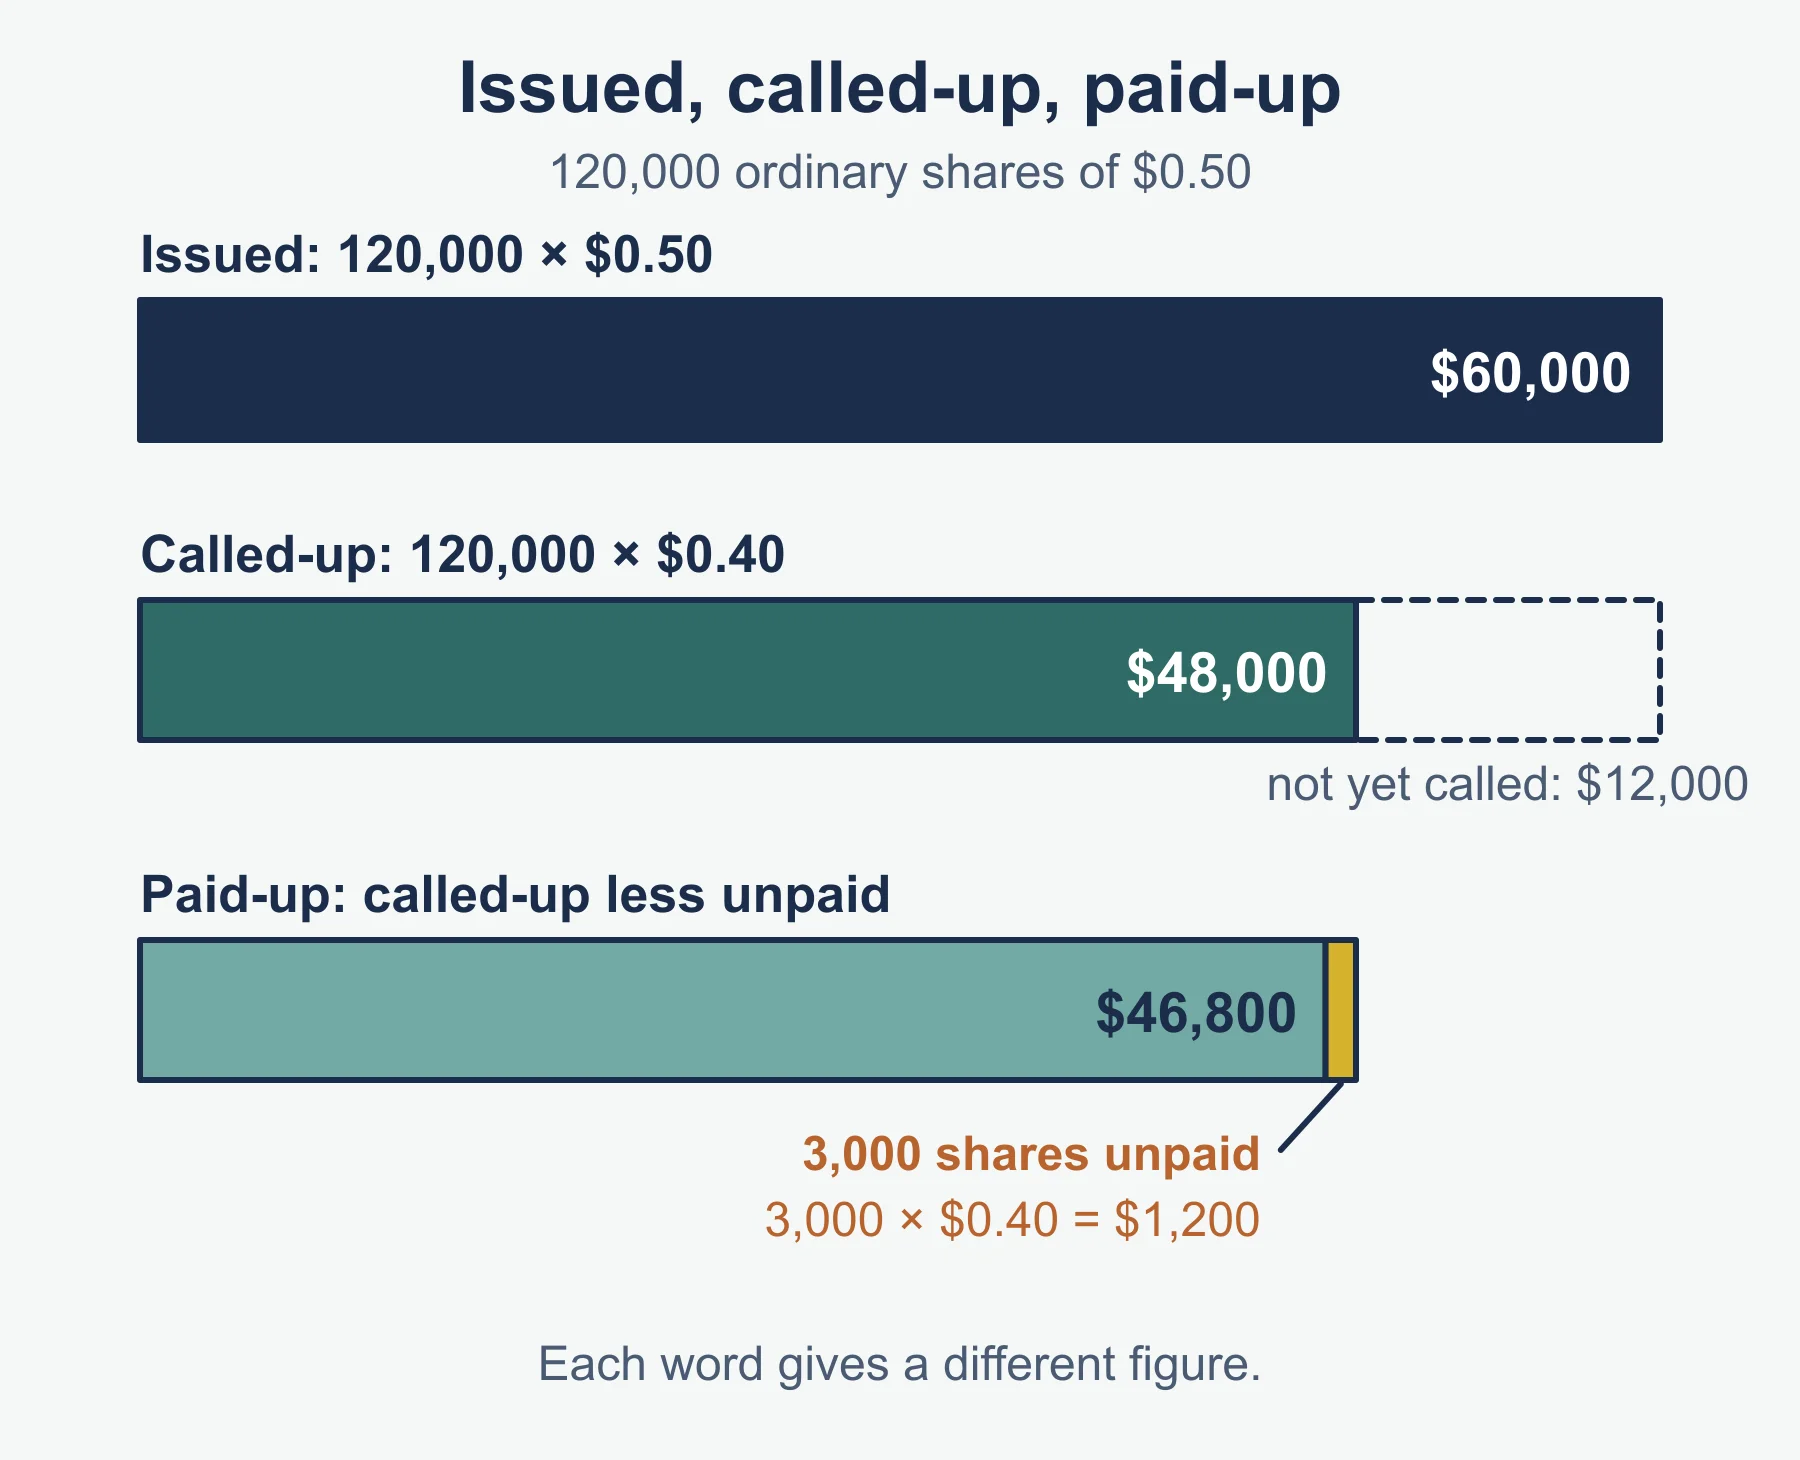
- Issued (shares issued) → called-up (amount asked for so far) → paid-up (amount actually received).
| Advantages | Disadvantages |
|---|---|
| Limited liability; can raise large capital; continuity | More legal requirements and costs; profits shared as dividends |
| Easier to borrow | Information may have to be made public; owners may not run the company |
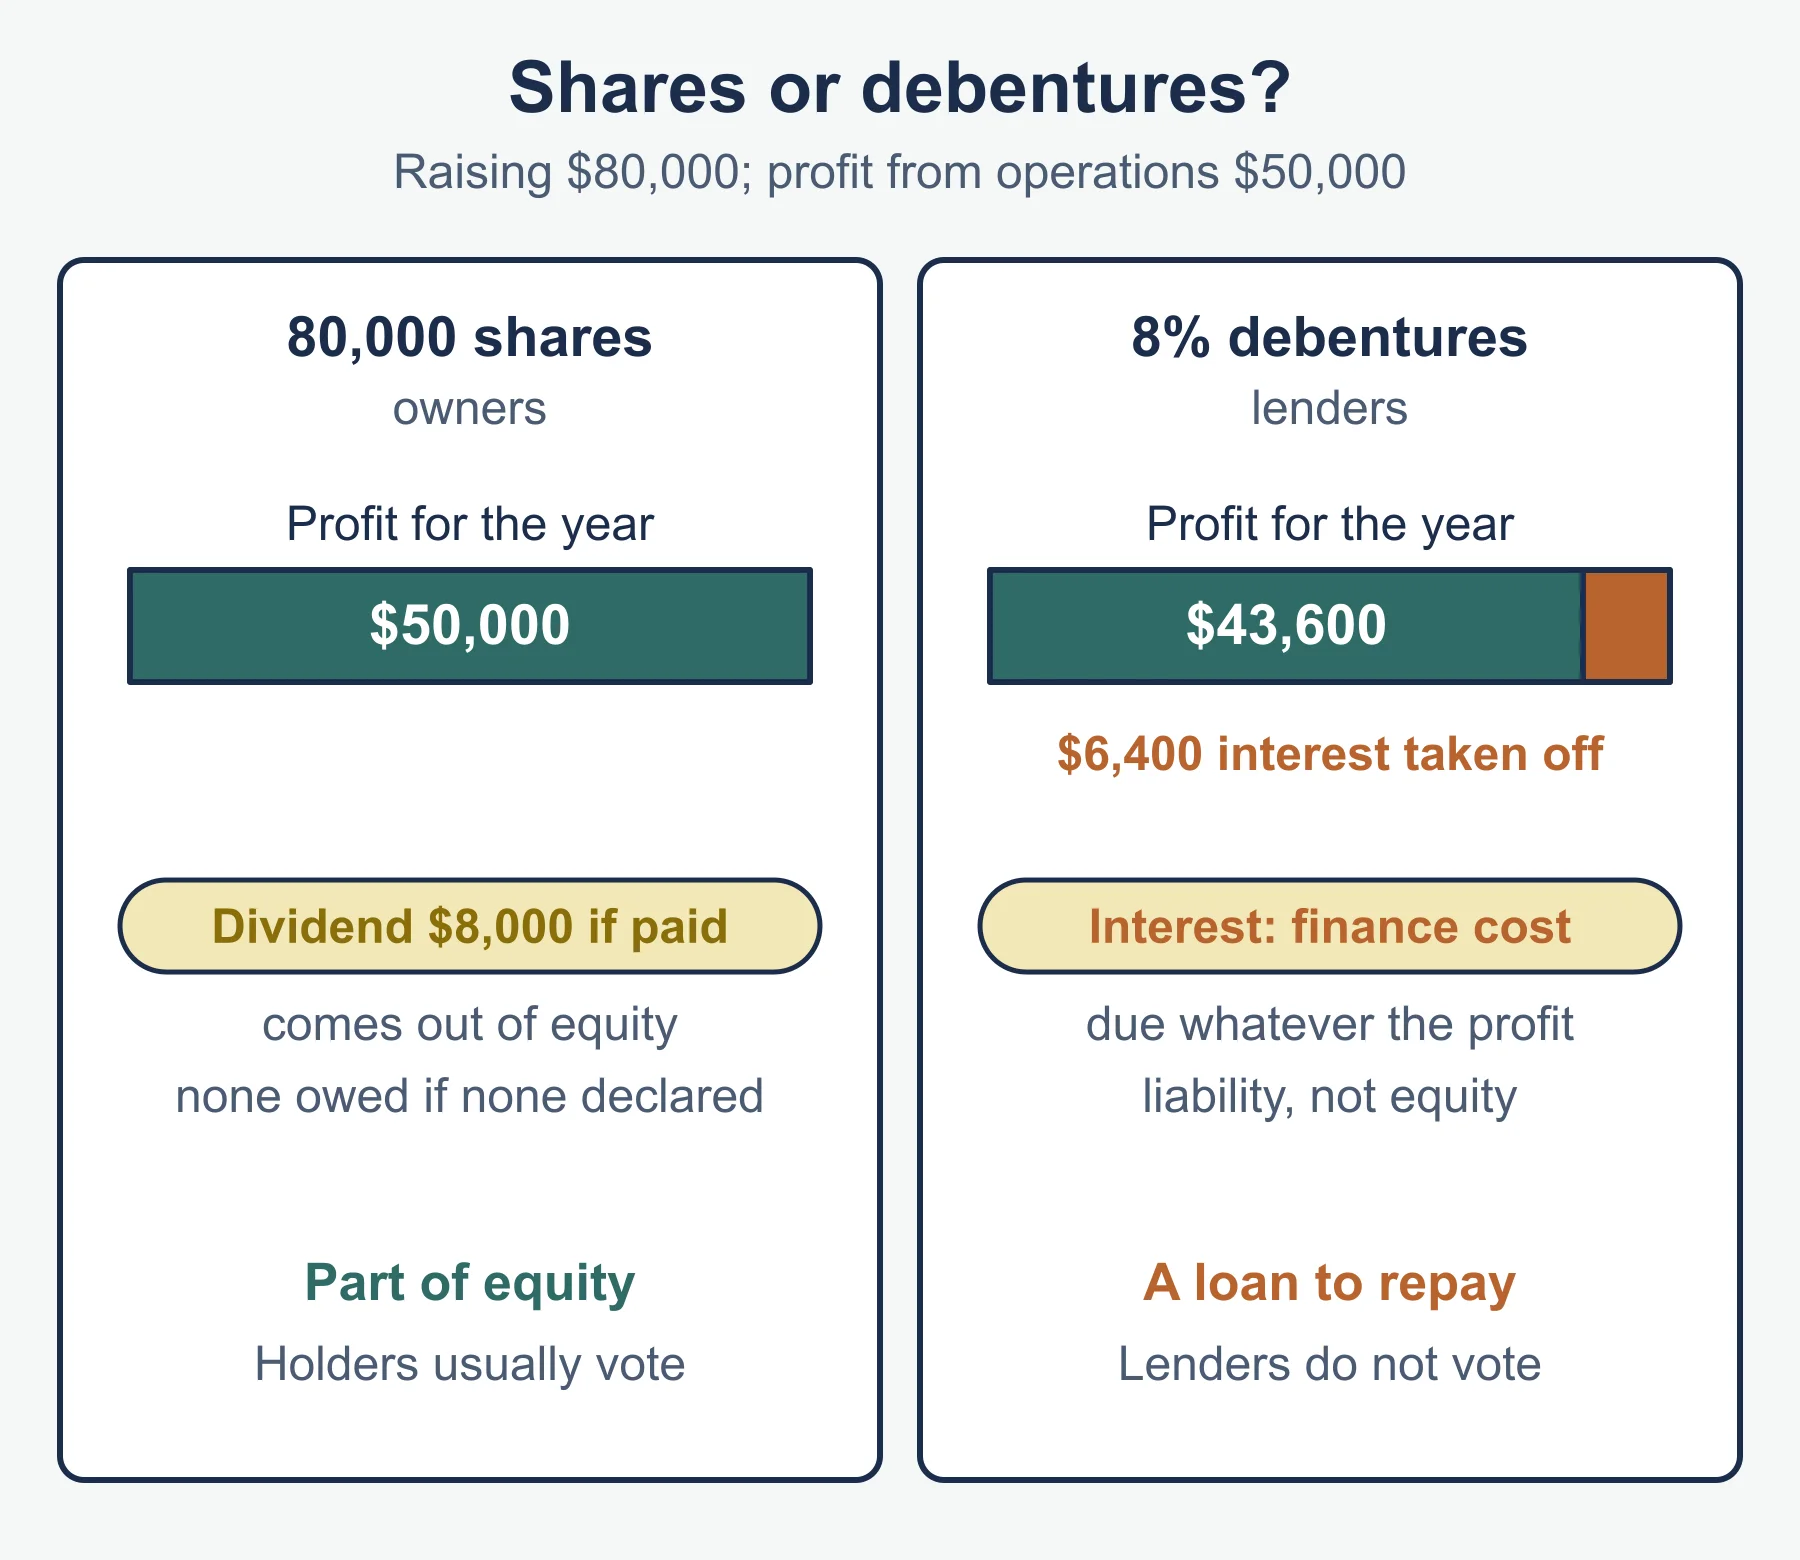
| Ordinary shares | Debentures |
|---|---|
| Owners | Lenders |
| Variable dividends, need not be paid | Fixed interest, must be paid |
| Dividends in the statement of changes in equity | Interest is a finance cost in the SoPL |
| Equity | Non-current liability |
| Usually voting rights | No votes; repaid on an agreed date |
Statements: SoPL to profit from operations, less debenture interest = profit for the year (no dividends). Statement of changes in equity: opening balances + shares issued + profit for the year ± transfer to general reserve – dividends paid = closing balances. SOFP shows equity from the SOCE closing line; debentures under non-current liabilities.
5.4 Manufacturing accounts
| Term | Meaning |
|---|---|
| Direct costs | Traced to the product: direct material, direct labour |
| Prime cost | Direct material + direct labour |
| Indirect costs (factory overheads) | Factory costs not traced to units: indirect wages, factory rent, power, depreciation of machinery |
| Work in progress | Partly finished goods: + opening, – closing |
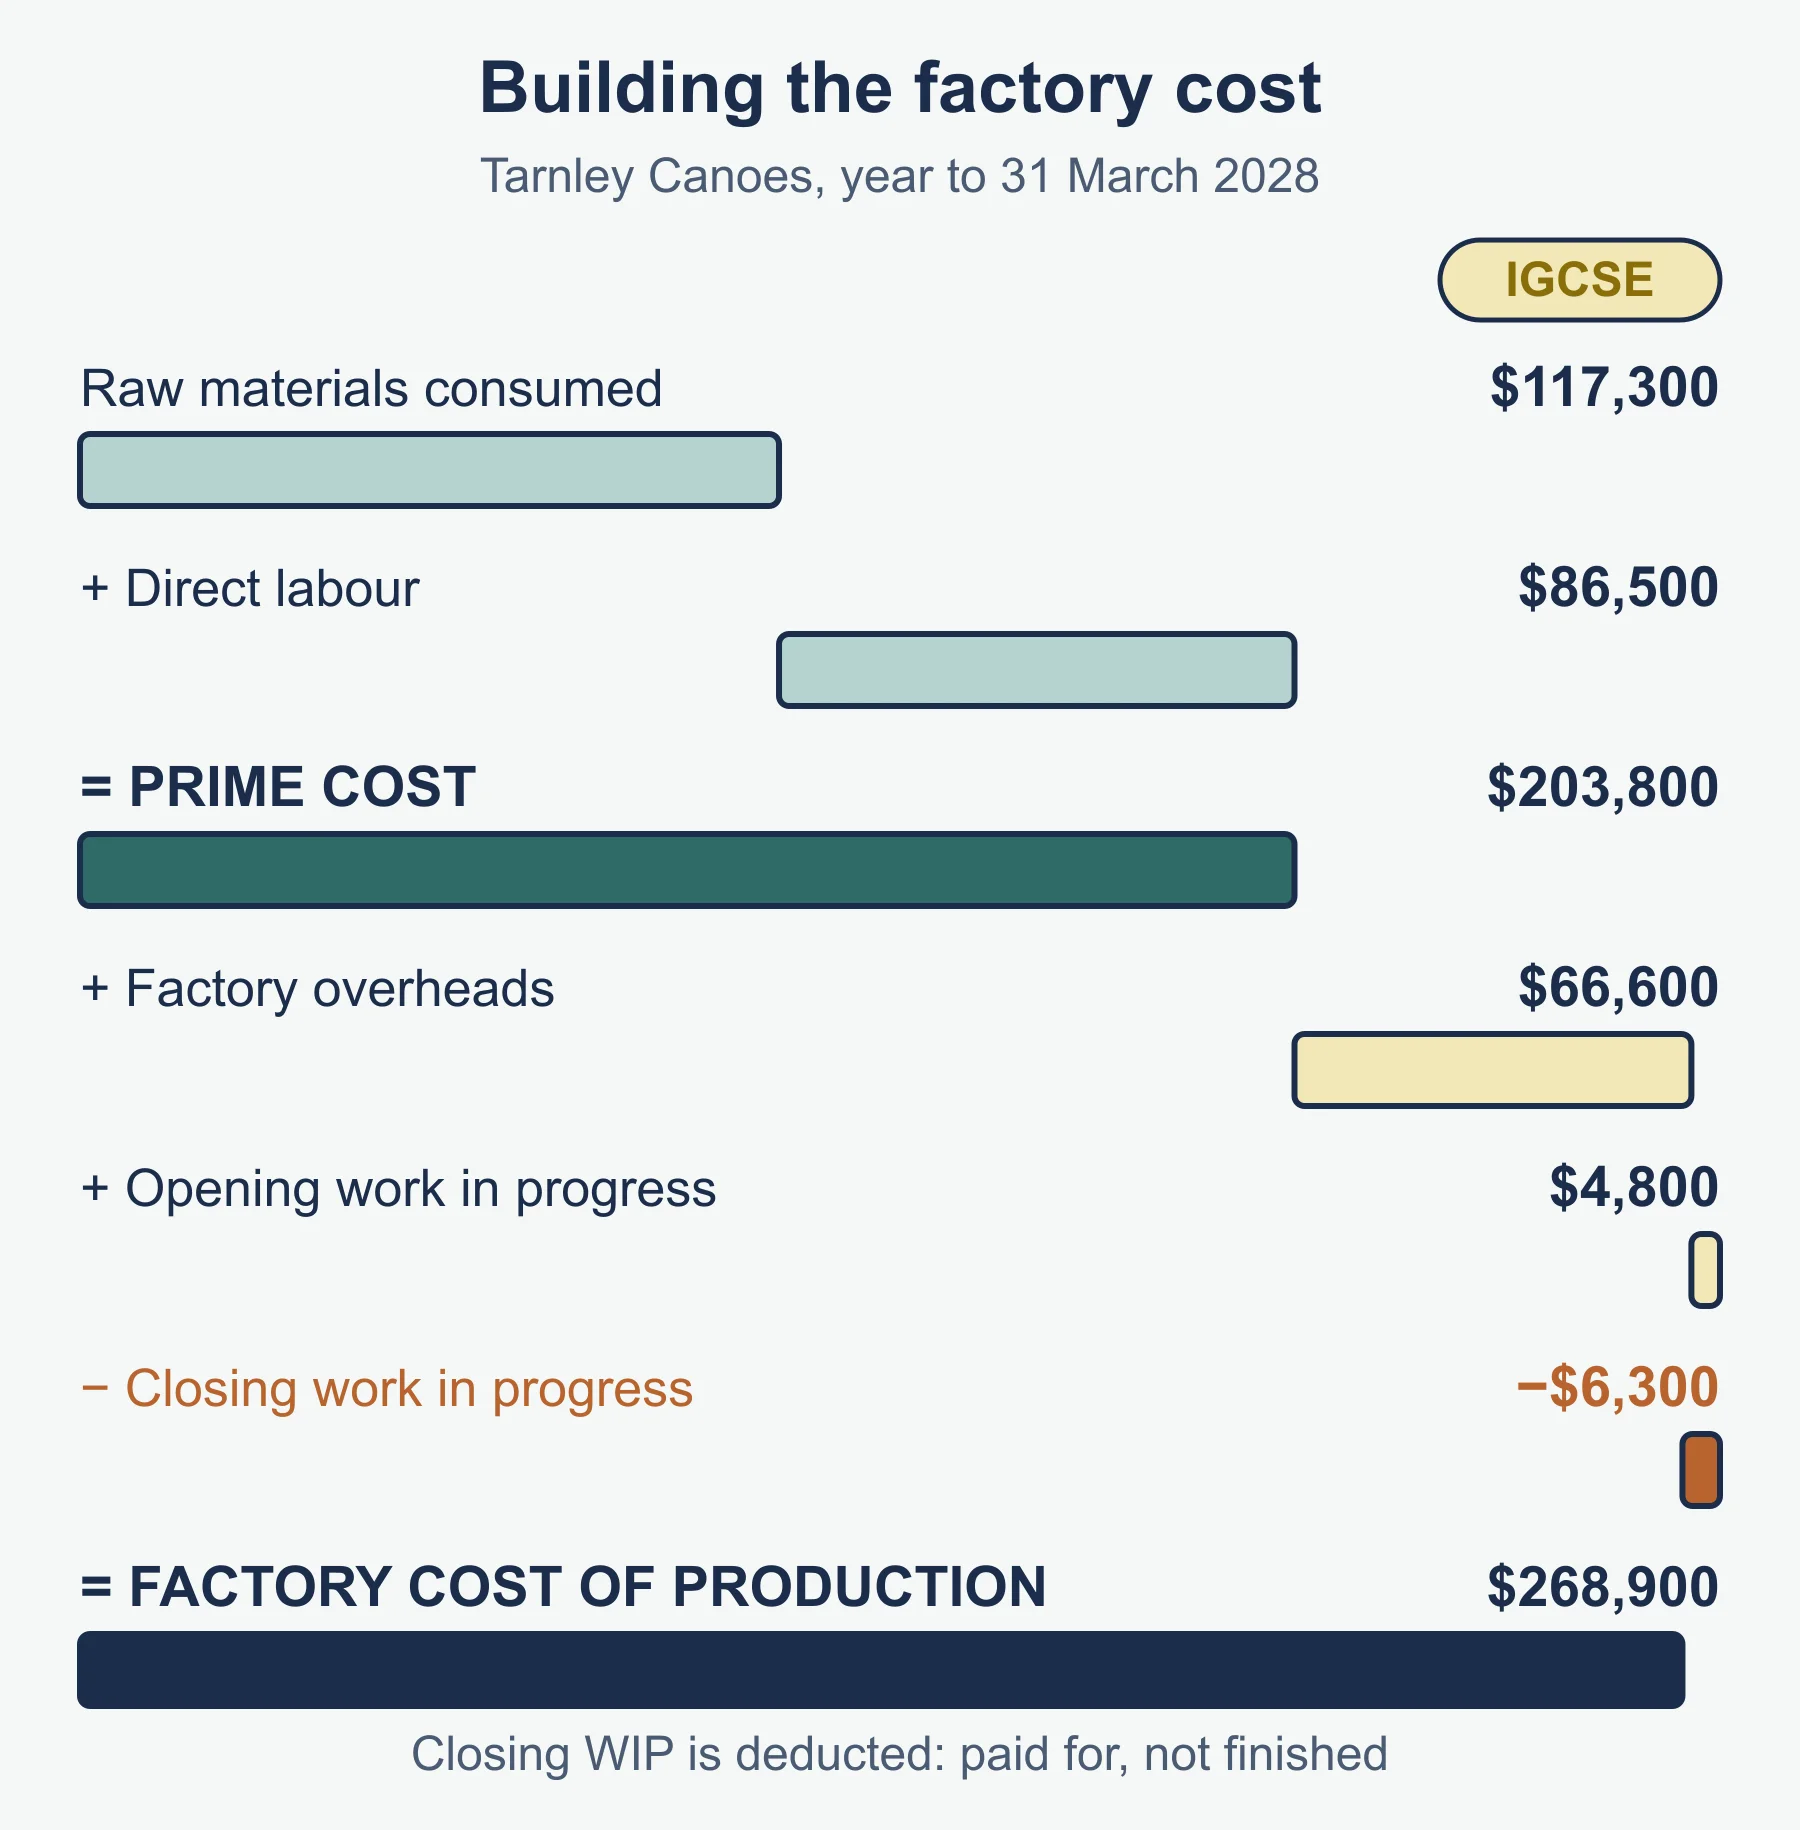
| Factory cost of production | Prime cost + factory overheads + opening WIP – closing WIP |
Factory cost of production goes into cost of sales in the SoPL. The SOFP shows three inventories: raw materials, work in progress, finished goods.
5.5 Clubs and societies
| Receipts and payments account | Income and expenditure account |
|---|---|
| Summary of the cash book; cash/bank balances | Like a SoPL; surplus or deficit |
| Includes capital items | Revenue items only |
| No adjustments | Adjusted for accruals, prepayments, depreciation |
- Revenue-generating activities (e.g. refreshments): separate account; only the profit or loss goes to the I&E account.
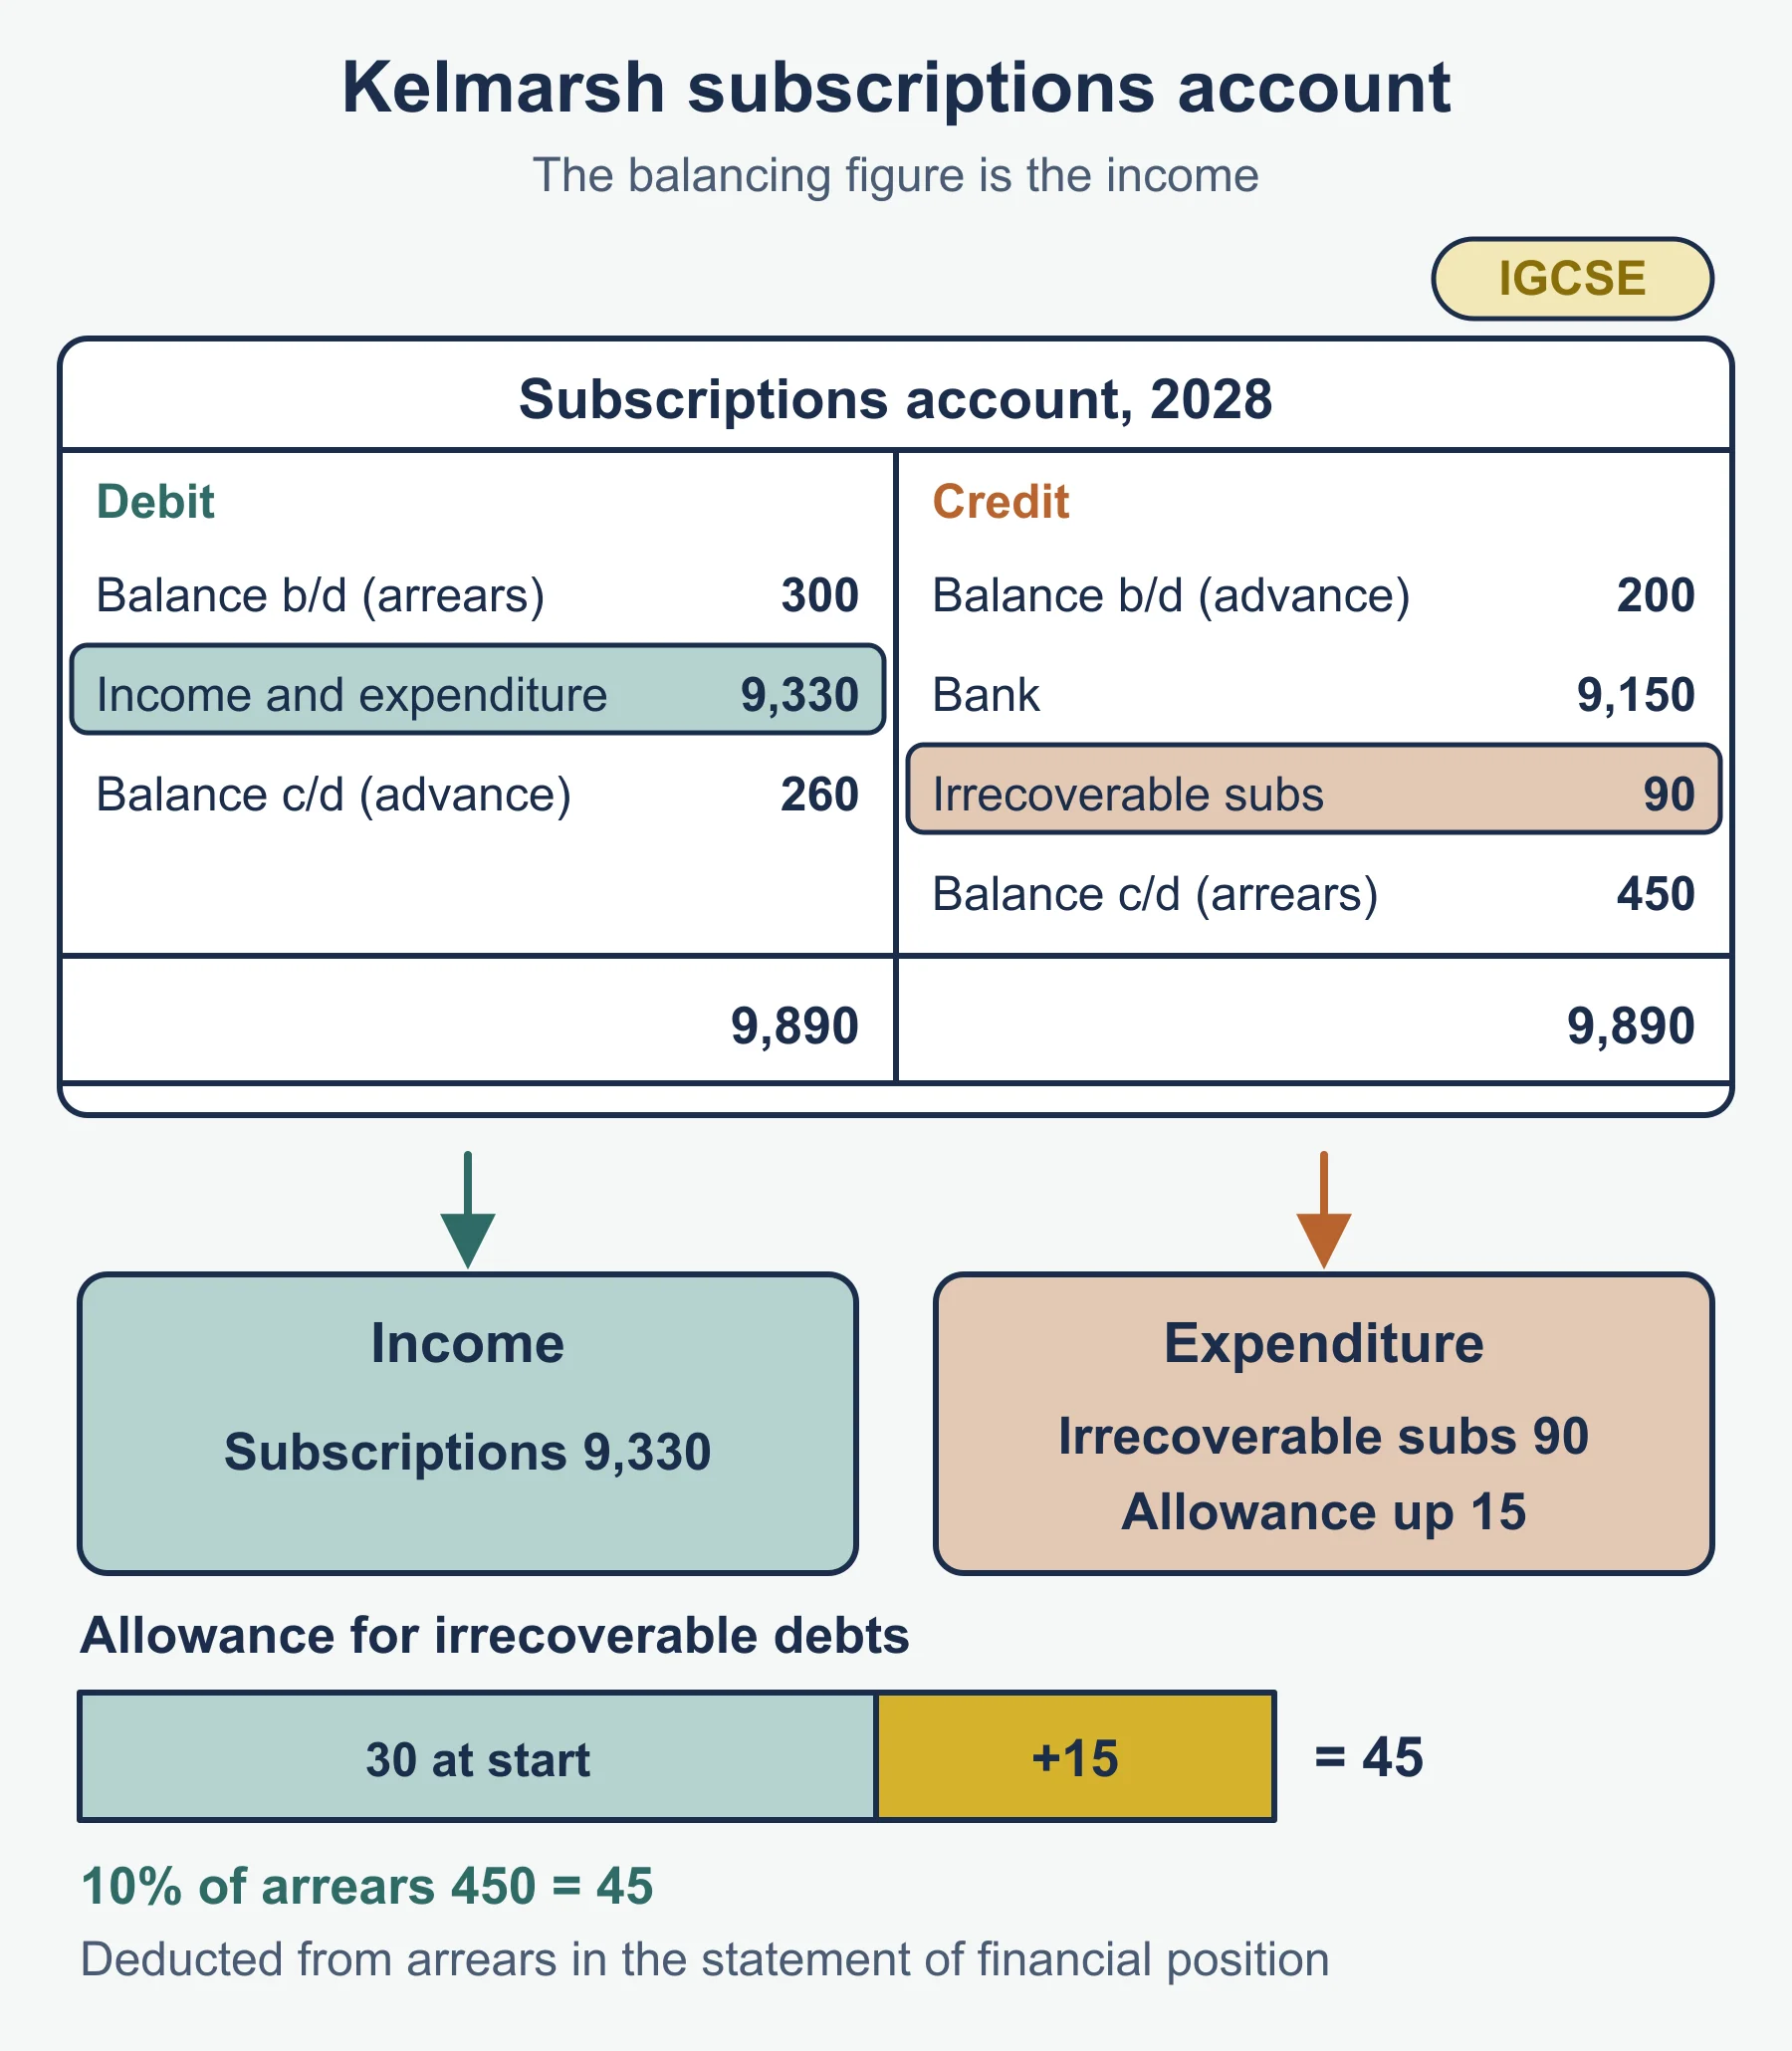
- Subscriptions: in arrears = other receivable; in advance = other payable. I&E figure = received + closing arrears + opening advance – opening arrears – closing advance.
- Accumulated fund = assets – liabilities (the club’s capital); closing = opening + surplus (– deficit).
5.6 Incomplete records
Why: lack of knowledge, time or money for full double entry; small businesses may keep only bank records. Advantages: cheaper, simpler, quicker. Disadvantages: no trial balance check, fraud and errors harder to detect, profit hard to find, poor control of receivables and payables, lenders and tax authorities may not accept the figures.
- Statement of affairs: assets – liabilities = capital, at a date.
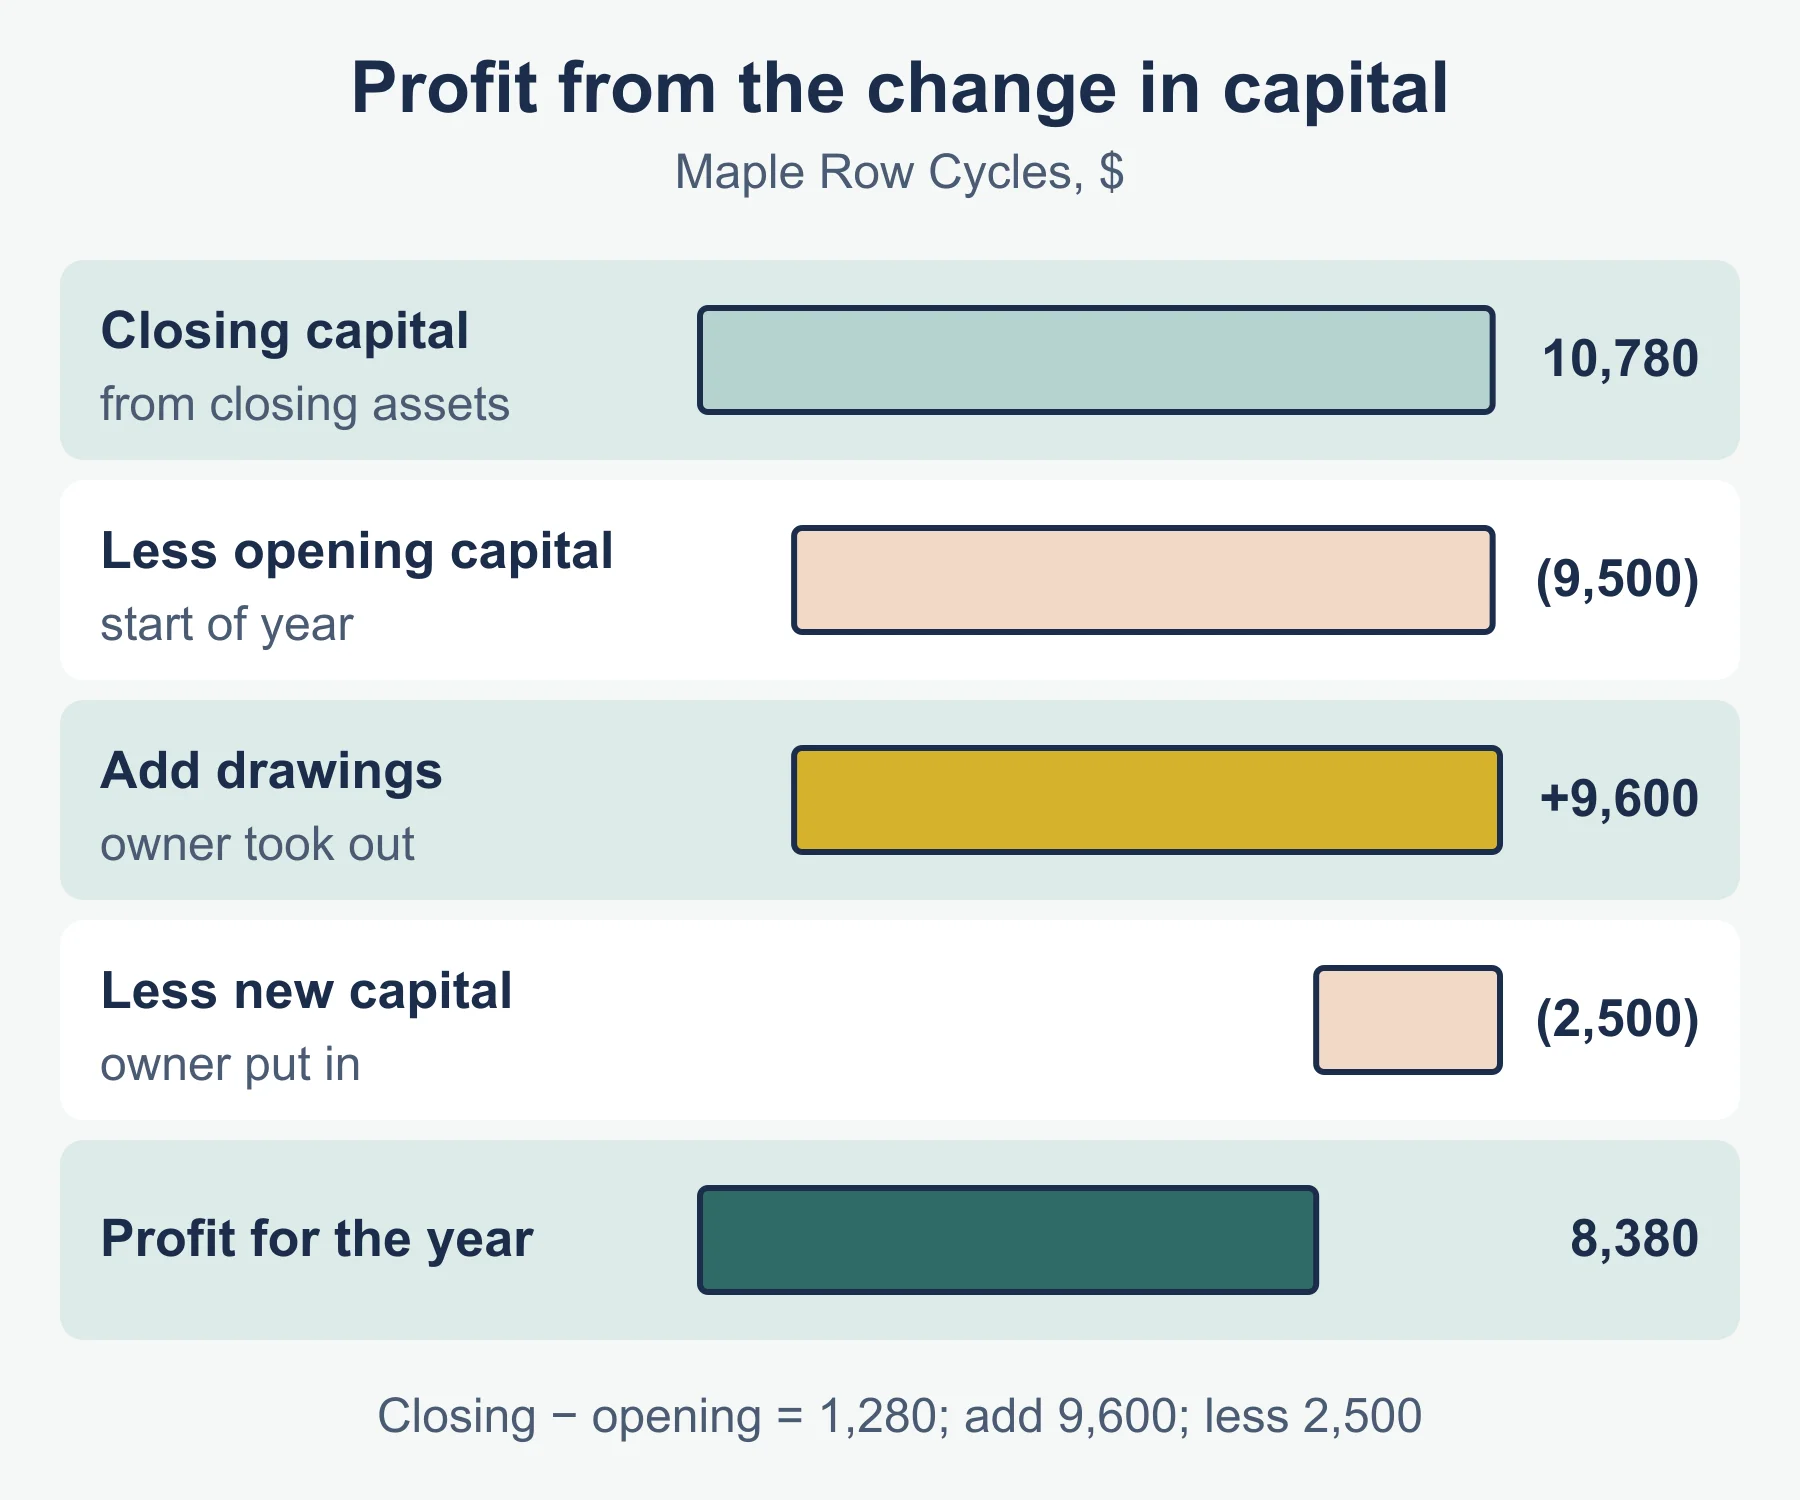
- Profit = closing capital – opening capital + drawings – capital introduced.
- Credit sales = receipts from customers + closing trade receivables – opening trade receivables.
- Credit purchases = payments to suppliers + closing trade payables – opening trade payables.
- Mark-up (%) = Gross profit / Cost of sales × 100; Gross profit margin (%) = Gross profit / Revenue × 100; Rate of inventory turnover (times) = Cost of sales / Average inventory. These are the syllabus formulas, the only ones accepted in candidate responses.
Syllabus Note: incomplete records questions are only on sole traders, not on service or manufacturing businesses.
Worked example: partnership appropriation account
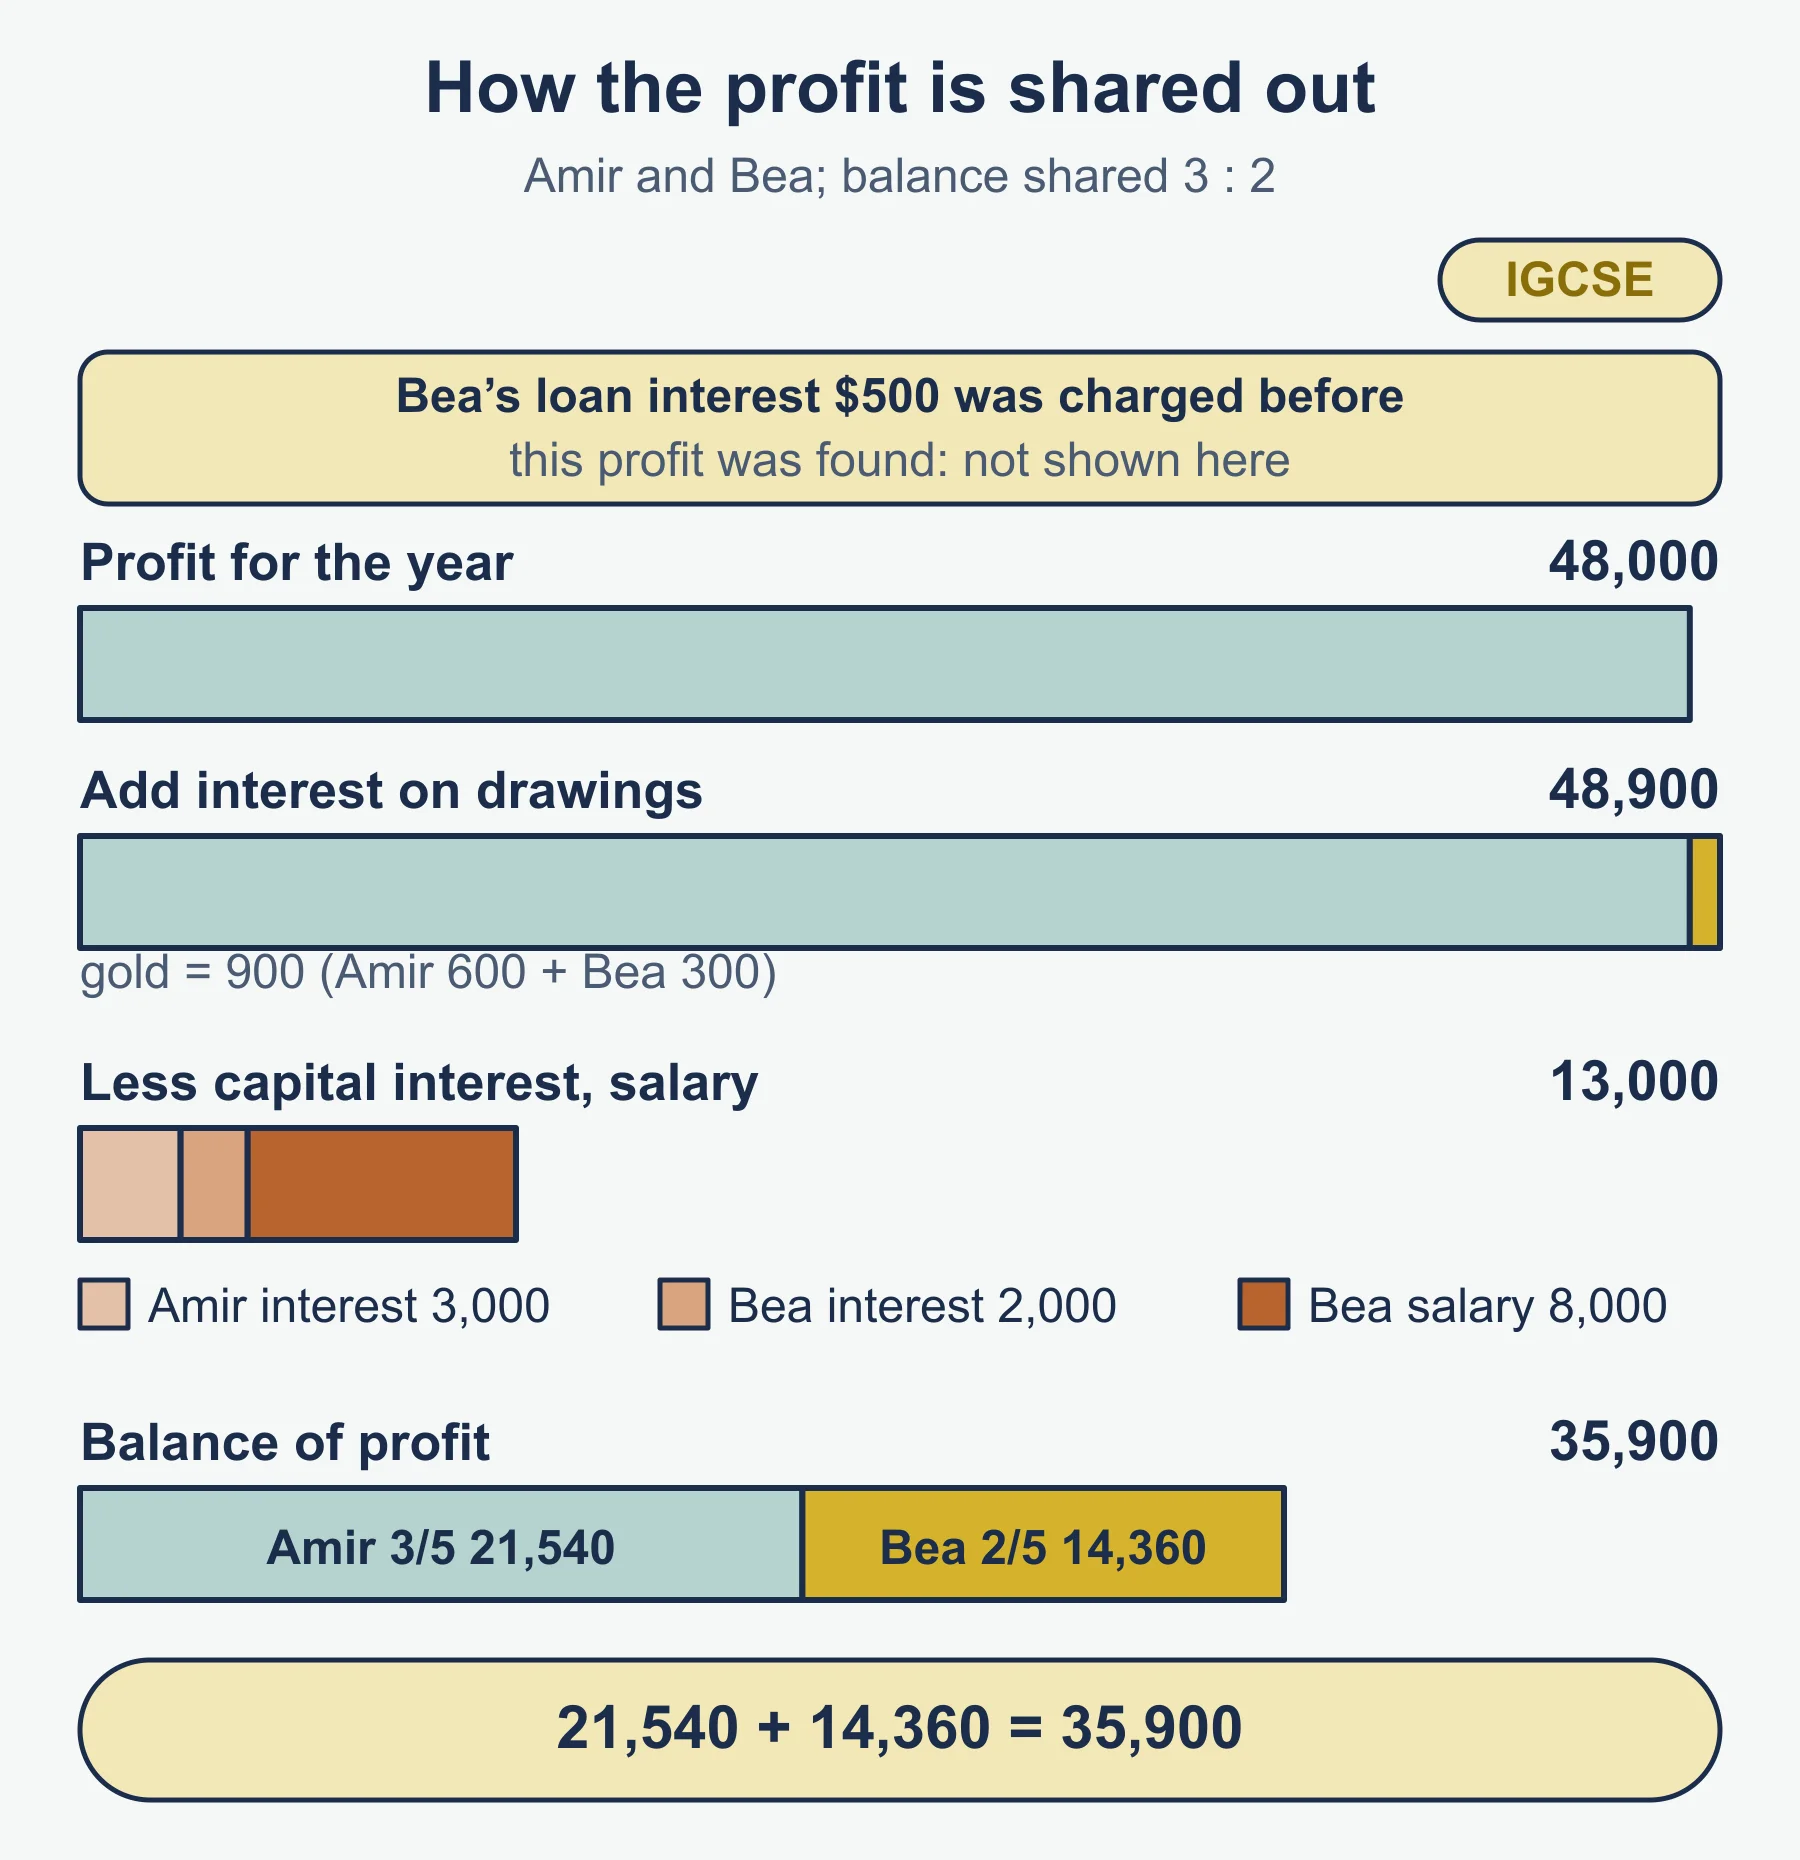
Profit for the year $48,000 (after $500 interest on Bea’s loan). Interest on capital 5%: Amir $60,000, Bea $40,000. Bea’s salary $8,000. Interest on drawings: Amir $600, Bea $300. Balance shared 3 : 2.
Profit for the year                         48,000
Add Interest on drawings (600 + 300)           900
                                            48,900
Less Interest on capital: Amir 3,000
                          Bea  2,000
     Salary:              Bea  8,000        13,000
Balance of profit                           35,900
Shared: Amir 3/5 = 21,540;  Bea 2/5 = 14,360   (total 35,900)
The $500 loan interest was charged in the statement of profit or loss before the $48,000 was found — it is not in the appropriation account.
Exam traps
- Adjusting only one statement, so the SOFP does not balance.
- Charging the whole allowance for irrecoverable debts instead of only the change.
- Reducing balance on cost instead of on carrying value.
- Interest on a partner’s loan in the appropriation account; interest on drawings deducted instead of added.
- Dividends in a company’s SoPL; debentures shown as equity.
- Subscriptions in arrears and in advance the wrong way round.
- Capital items such as equipment in an income and expenditure account.
- Forgetting drawings and capital introduced in profit from changes in capital.
- Mixing up mark-up (on cost of sales) and margin (on revenue).
Self-test
- Where do prepaid expenses and income received in advance appear in the statement of financial position?
- A business increases its allowance for irrecoverable debts from $300 to $340. What is charged in the statement of profit or loss?
- Loose tools were valued at $1,500 at the start of the year, $400 were bought, and they were valued at $1,300 at the end. Calculate the depreciation.
- Why is interest on a partner’s loan not shown in the appropriation account?
- Give two differences between ordinary shares and debentures.
- Prime cost is $77,000, factory overheads $31,100, opening work in progress $5,000 and closing work in progress $6,100. Calculate factory cost of production.
- Subscriptions received in the year were $6,300; arrears were $240 at the start and $180 at the end; subscriptions in advance were $160 at the start and $300 at the end. Calculate subscription income for the income and expenditure account.
- Opening capital is $15,600, closing capital $17,000, drawings $9,000 and capital introduced $2,000. Calculate the profit for the year.
Answers: 1. Prepaid expenses are other receivables (current assets); income received in advance is other payables (current liabilities). 2. Only the increase, $40, as an expense. 3. $1,500 + $400 – $1,300 = $600. 4. The loan is a liability of the business, so its interest is an expense charged in the statement of profit or loss before profit for the year is found; the appropriation account only shares out that profit. 5. Any two: shareholders are owners, debenture holders are lenders; dividends vary and need not be paid, debenture interest is fixed and must be paid; shares are equity, debentures are a non-current liability; dividends go in the statement of changes in equity, debenture interest is a finance cost in the statement of profit or loss. 6. $77,000 + $31,100 + $5,000 – $6,100 = $107,000. 7. $6,300 + $180 + $160 – $240 – $300 = $6,100. 8. $17,000 – $15,600 + $9,000 – $2,000 = $8,400.
Frequently asked questions
How is subscription income calculated for a club? Subscription income equals subscriptions received plus closing arrears plus opening subscriptions in advance, minus opening arrears and minus closing subscriptions in advance. Arrears are an other receivable and advance payments an other payable.
How do you calculate profit from changes in capital? Profit equals closing capital minus opening capital, plus drawings, minus capital introduced. Capital at each date comes from a statement of affairs: assets minus liabilities.
Which businesses are tested in 0452 incomplete records questions? The syllabus note says incomplete records questions are only on sole traders, not on service or manufacturing businesses.
What are the advantages and disadvantages of incomplete records? Incomplete records are cheaper, simpler and quicker to keep. However, there is no trial balance check, errors and fraud are harder to detect, profit is hard to find, and lenders and tax authorities may not accept the figures.
What inventories does a manufacturer show in the statement of financial position? A manufacturer shows three inventories: raw materials, work in progress and finished goods. Factory cost of production goes into cost of sales in the statement of profit or loss.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Revision notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
Accounting · Cambridge · IGCSE, O Level
Revise topic -
Study guides
IGCSE Accounting: Incomplete records (Cambridge 0452)
Study guide to incomplete records for Cambridge IGCSE Accounting 0452: statements of affairs, missing figures, mark-up, margin and full statements.
Accounting · Cambridge · IGCSE, O Level
Read guide -
Practice questions
IGCSE Accounting: Incomplete records (Cambridge 0452) – Practice Questions
Original practice questions with worked answers on incomplete records for Cambridge IGCSE Accounting 0452: statements of affairs and missing figures.
Accounting · Cambridge · IGCSE, O Level
Try questions
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

