
Study Guides
Pearson Edexcel IGCSE Economics: Business Competition, the Labour Market and Government Intervention (4EC1)
Monopoly, oligopoly, the labour market, trade unions and government intervention: sub-topics 1.2.4 to 1.2.6 of Edexcel International GCSE Economics 4EC1.
- Subject
- Economics
- Level
- IGCSE
- Topic
- Business economics
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to Pearson Edexcel IGCSE Economics (4EC1), Issue 3, February 2026. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Economics.
Syllabus points this page covers
4EC1
- 1.2.4 Business competition
- 1.2.5 The labour market
- 1.2.6 Government intervention
Found an error? Report a correction.
Need help with this topic? Request a free trial class for IGCSE Economics (4EC1).
This guide covers sub-topics 1.2.4–1.2.6, the second half of Topic 2 Business Economics, Pearson Edexcel International GCSE Economics (4EC1), Issue 3, February 2026. The Production and Business Costs guide covers the first three sub-topics (1.2.1–1.2.3); this guide completes Topic 2 by moving from how firms produce to how firms compete, how the labour market they operate in works, and how government responds to the problems markets create.
Where this fits in 4EC1
1.2.1–1.2.3 established the factors of production, productivity and the cost structure of a firm, including how average costs change with scale. 1.2.4–1.2.6 build directly on that: business competition (1.2.4) asks what happens when firms of different sizes compete for the same market, the labour market (1.2.5) treats labour itself as a good bought and sold at a price (the wage), and government intervention (1.2.6) closes Topic 2 by looking at how policy responds to the externalities and labour market outcomes the topic has just described. Topic 2.1 (Government and the Economy) later revisits government policy at the macroeconomic level; 1.2.6 is deliberately narrower, covering only intervention in individual markets and the labour market.
Syllabus coverage
PEARSON EDEXCEL INTERNATIONAL GCSE ECONOMICS (4EC1) — 1.2.4–1.2.6
- 1.2.4 Business competition — the advantages and disadvantages of competition to firms, consumers and the economy; the advantages and disadvantages of large firms and small firms; factors that allow a firm to grow (access to finance, economies of scale, spreading risk, taking over competitors) and reasons some firms stay small (limited market size, a niche market, financing constraints, the owner’s own goals); the definition and features of monopoly (a single dominant firm, a unique product, price-maker status, high barriers to entry) and its advantages and disadvantages for efficiency, choice, quality, innovation, price and scale; the definition and features of oligopoly (a few dominant firms, differentiated products, high barriers to entry, the possibility of collusion, interdependent pricing) and its advantages and disadvantages, including the effect of cartel pricing and price wars
- 1.2.5 The labour market — factors affecting the demand for labour (labour is a derived demand, the availability of substitutes such as capital, and worker productivity) and factors affecting the supply of labour (population size, net migration, the age structure of the population, retirement and school-leaving ages, female participation rates, skills and qualifications, and geographical mobility); the importance of the quantity and quality of labour to a business; how education and training build human capital; using a labour market diagram to show how shifts in labour demand or supply change the equilibrium wage and the level of employment; the role of trade unions in negotiating working conditions and wages
- 1.2.6 Government intervention — policies used to deal with negative and positive externalities (taxation, subsidies, fines, regulation and pollution permits) and the advantages and disadvantages of each; policies to regulate competition, including promoting competition, limiting the power of a monopoly, protecting consumers, and controlling mergers and takeovers; intervention in the labour market through a minimum wage, and the advantages, disadvantages and diagrammatic effect of setting a minimum wage above the market equilibrium
How to approach it
1.2.4’s monopoly-versus-oligopoly material is easiest to hold in memory as two structured comparisons rather than two separate lists: for each market structure, work through the same five headings (efficiency, choice, quality, innovation, price) in the same order. Examiners often ask you to evaluate whether a monopoly is “always bad for consumers” – the strongest answers use higher prices and reduced choice as the case against, and economies of scale or funded innovation (for example in pharmaceuticals) as the case for, before reaching a reasoned judgement.
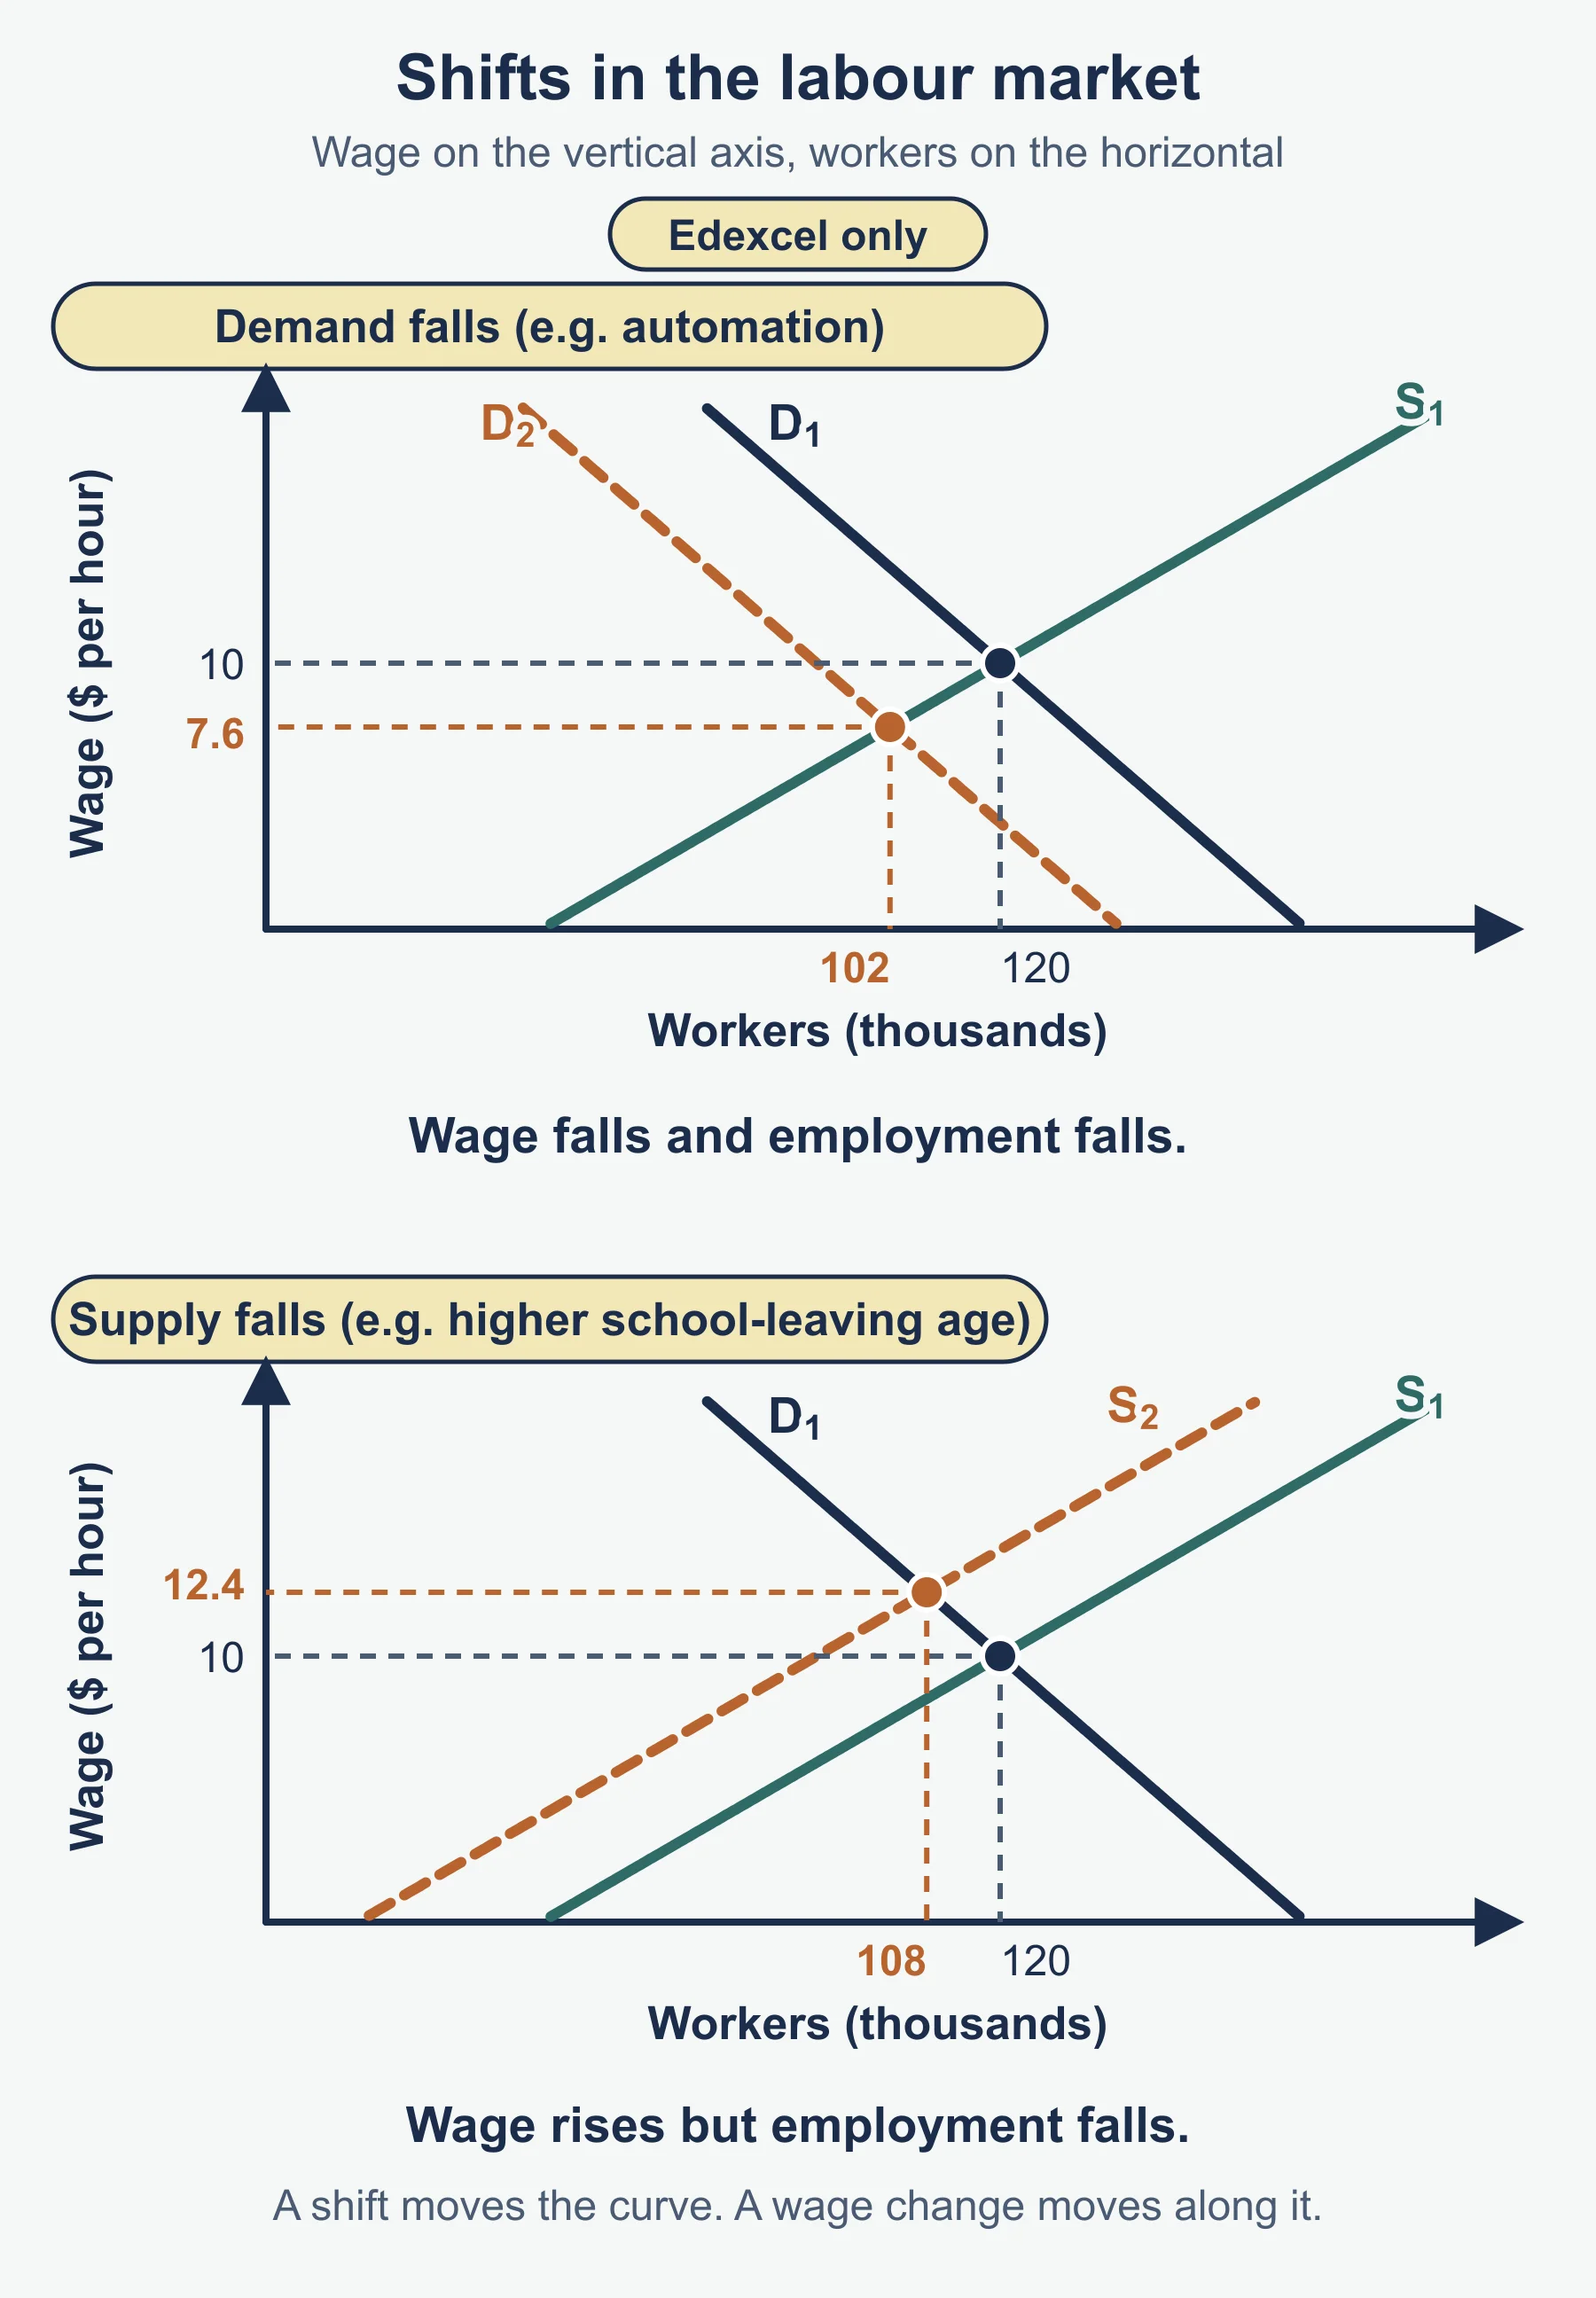
For 1.2.5, treat the labour market exactly like the product markets in 1.1: the same demand-and-supply diagram tools apply, only the “price” is now the wage and the “quantity” is the number of workers employed. Practising labour-market diagrams where a rise in the school-leaving age shifts the supply curve, or automation shifts the demand curve, transfers the Topic 1 skills you already have into a new context rather than requiring an entirely new diagram type.
1.2.6 rewards precision about which policy targets which problem: taxes, subsidies, fines, regulation and pollution permits address externalities; competition policy and merger controls address monopoly power; the minimum wage addresses labour market outcomes specifically. A common mark loss is using “government intervention” as one undifferentiated policy rather than naming which specific tool solves which specific market failure.
Worked example: minimum wage above equilibrium
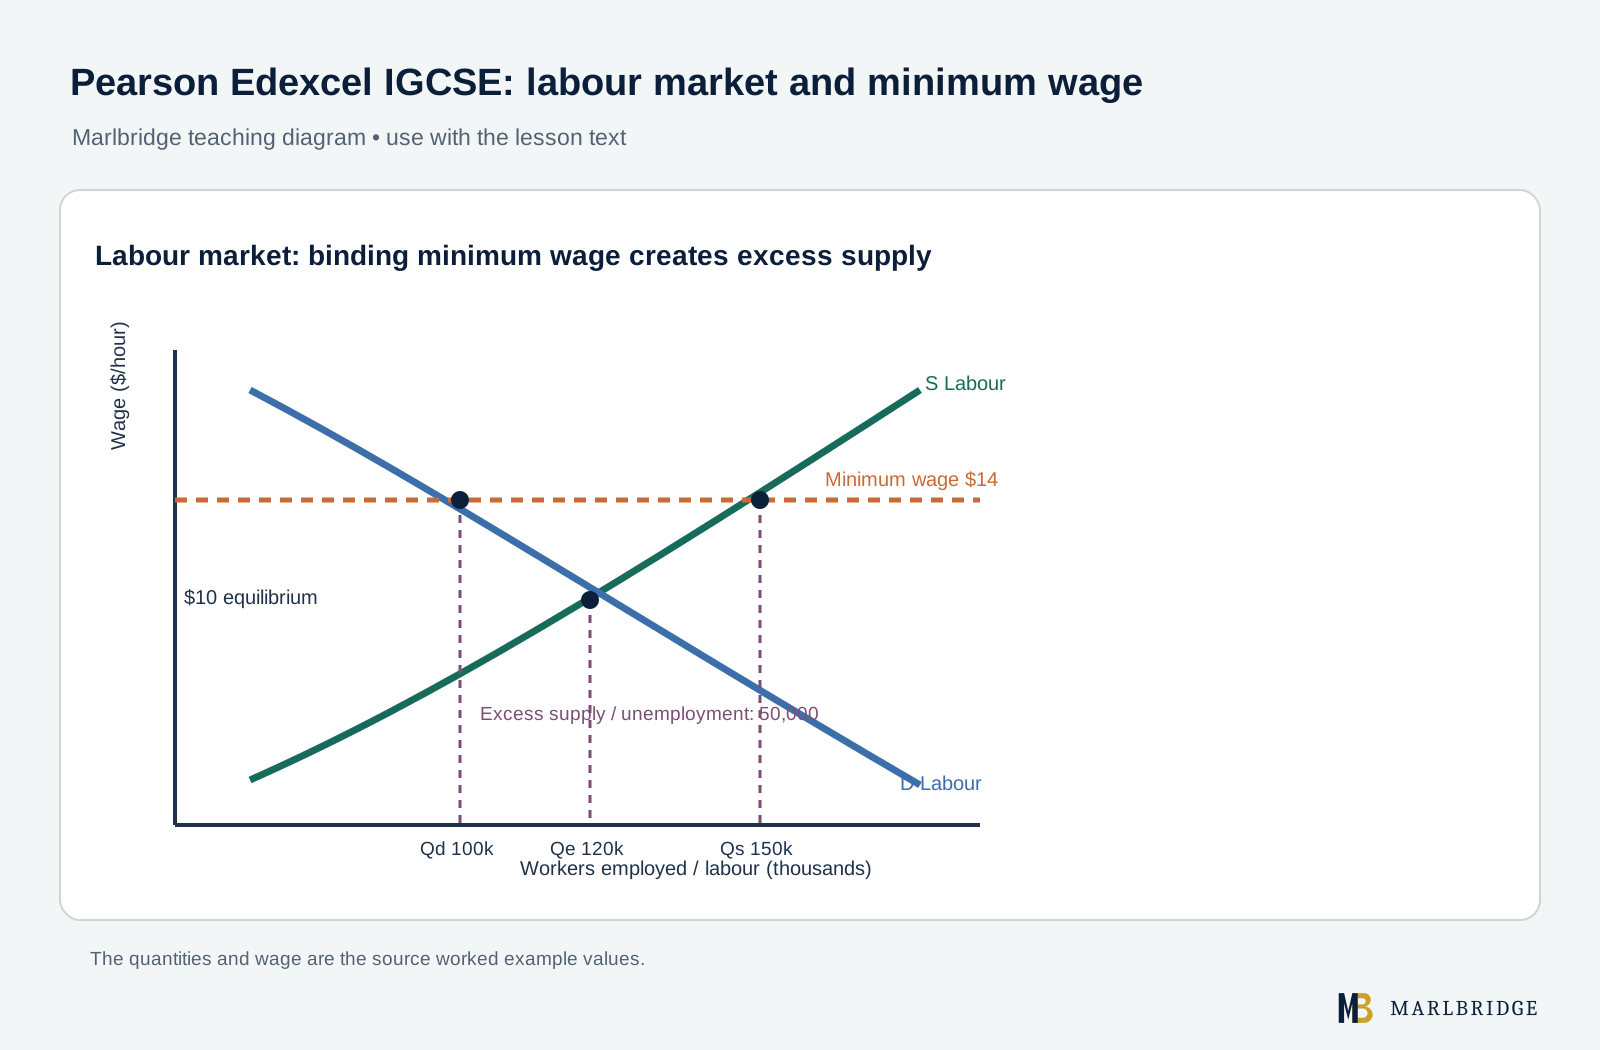
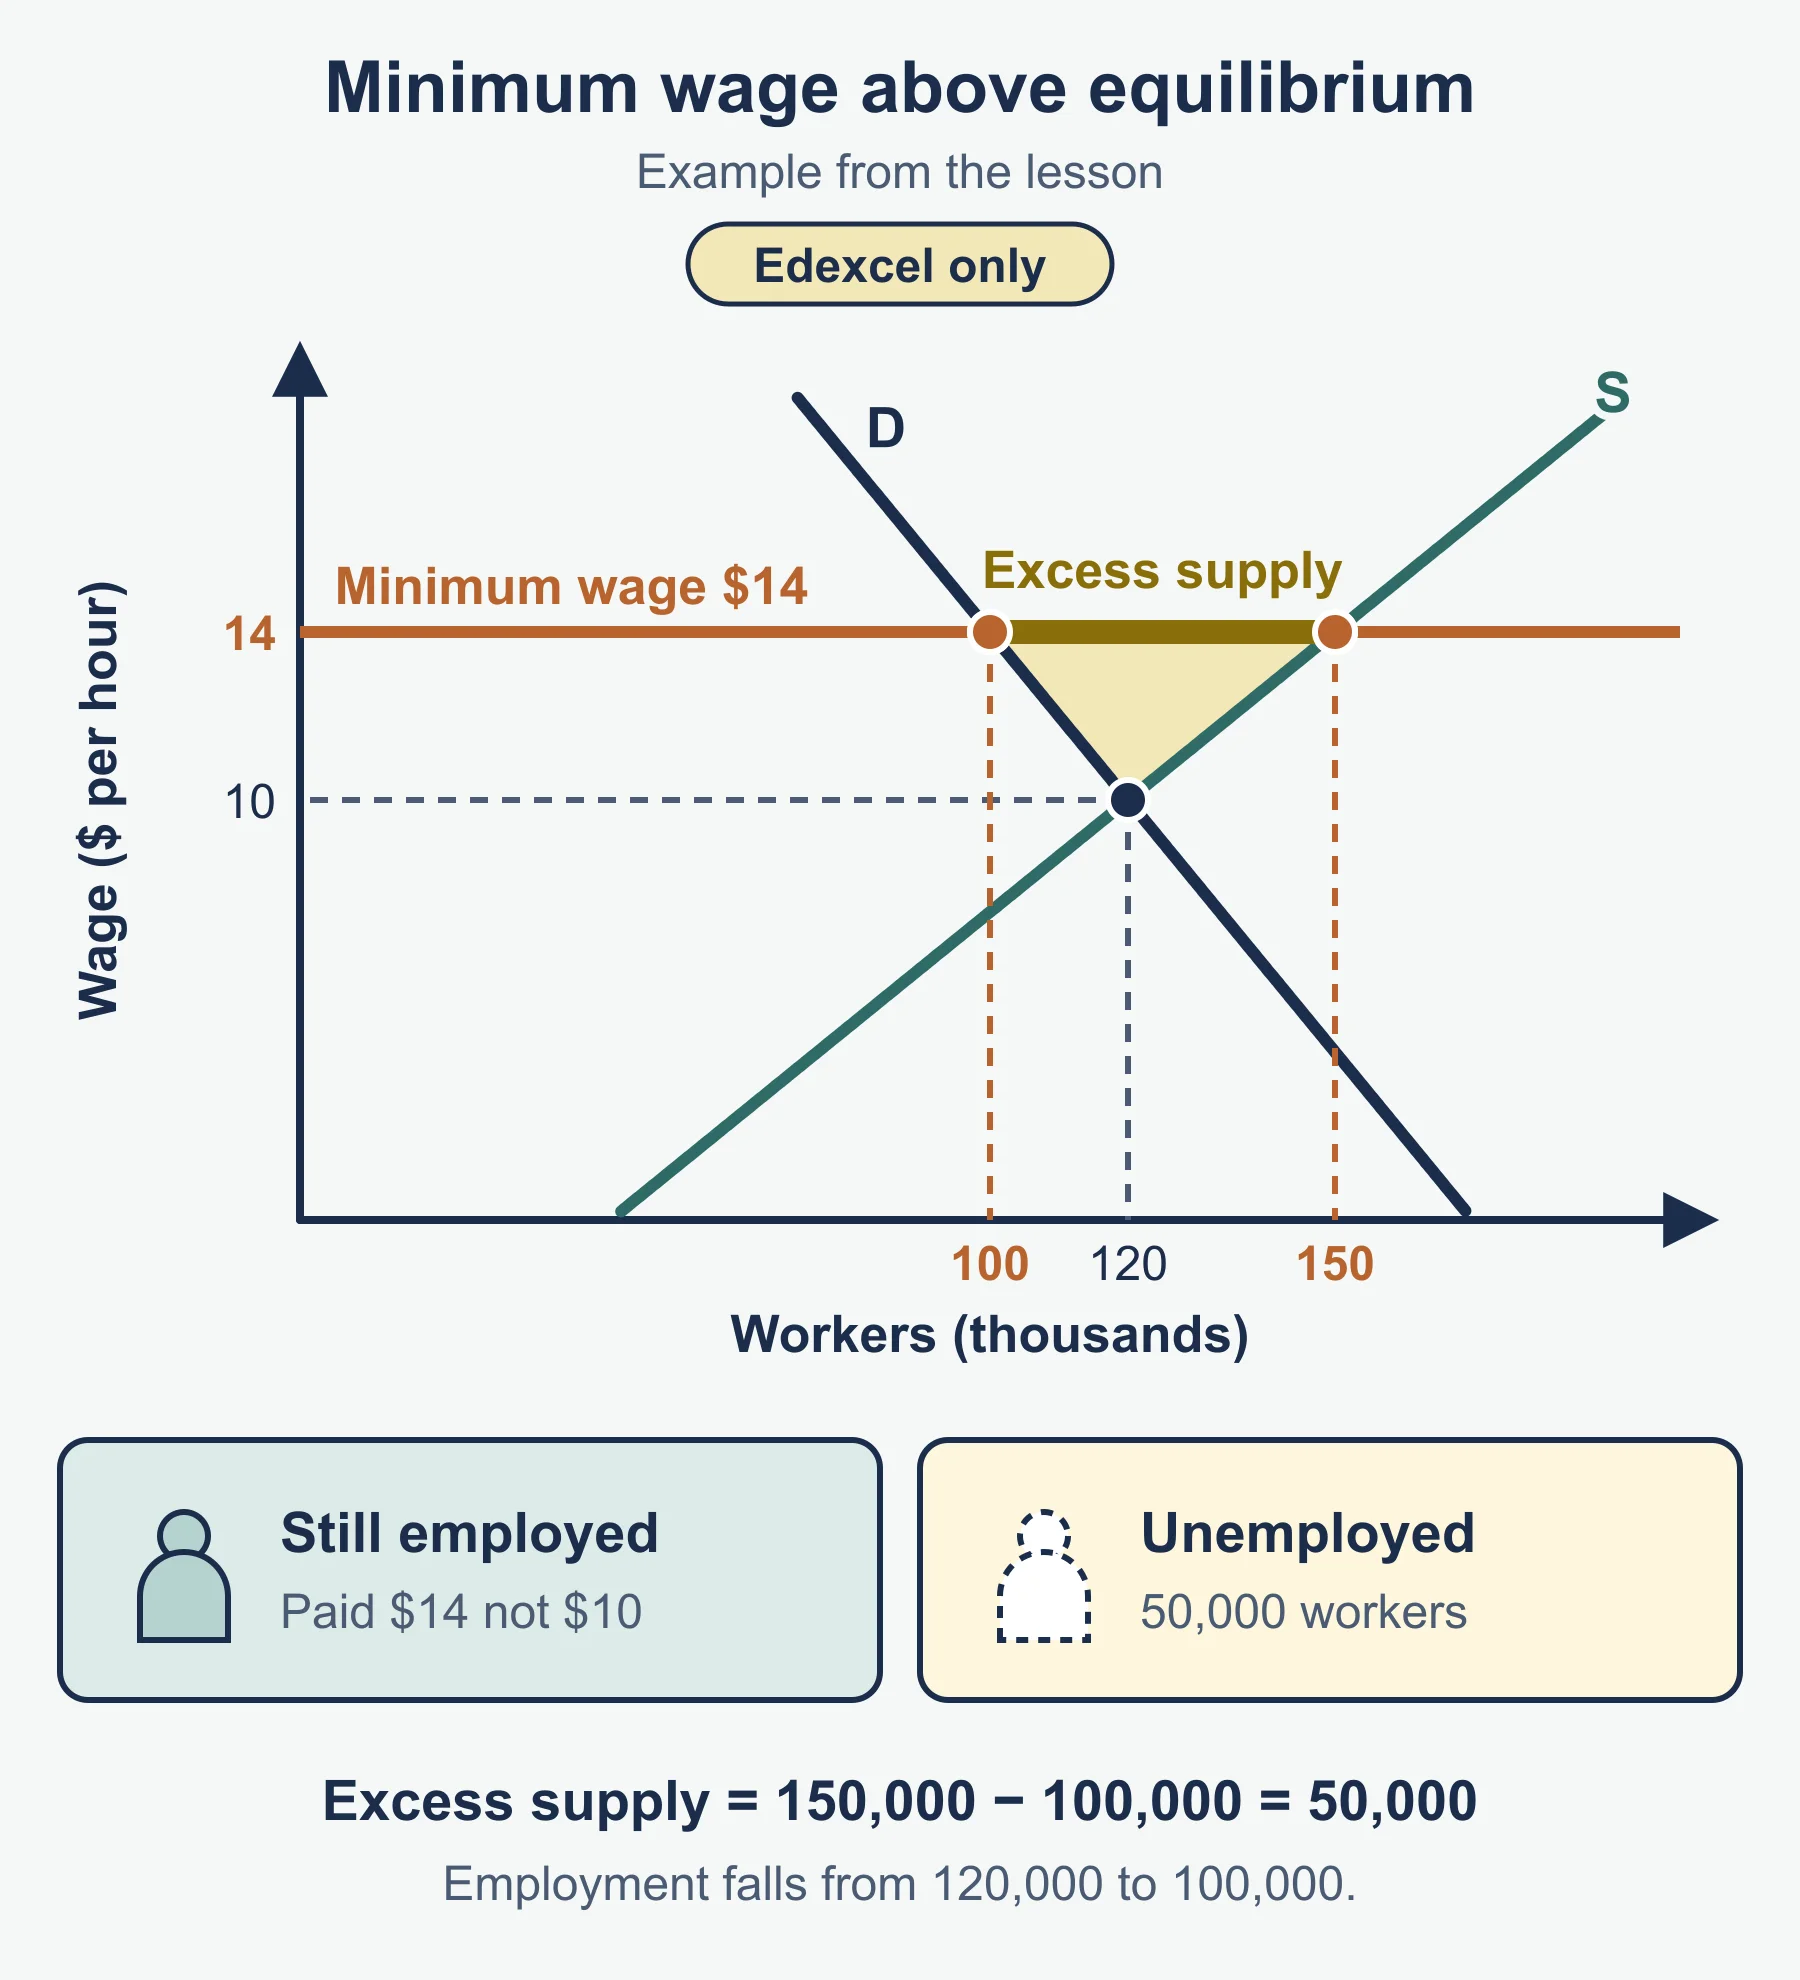
A labour market has an equilibrium wage of $10 per hour, at which 120,000 workers are employed. The government sets a minimum wage of $14 per hour.
At $14/hour: quantity of labour supplied  = 150,000 workers
             quantity of labour demanded  = 100,000 workers
             excess supply of labour      = 150,000 - 100,000
                                           = 50,000 workers (unemployment)
The 50,000 excess supply is the diagram’s standard result: a minimum wage set above equilibrium raises pay for those who keep their jobs but creates unemployment among workers who would have been hired at the lower, market-clearing wage. Being able to state both the winners (those still employed, now on higher pay) and the losers (those now unemployed) is what separates a full-mark evaluation from a one-sided description.
Common mistakes
Describing oligopoly and monopoly as if either is simply “one big firm” – oligopoly specifically requires a small number of dominant, mutually aware firms, not a single one. Treating all government intervention as interchangeable, rather than matching taxation/subsidies/regulation to externalities and the minimum wage to the labour market specifically. Forgetting that a rise in the minimum wage does not raise everyone’s pay equally – it only affects workers whose market wage was already below the new minimum. Confusing a shift in the labour supply curve (caused by, for example, migration or the school-leaving age) with a movement along it (caused by a change in the wage itself).
Quick revision checklist
- Compare monopoly and oligopoly using the same five headings each time: efficiency, choice, quality, innovation, price.
- Practise labour-market diagrams for both a demand shift (for example, automation) and a supply shift (for example, migration).
- Match each government policy tool to the specific problem it is meant to solve: externalities, monopoly power, or the labour market.
- Be able to state both a winner and a loser when evaluating a minimum wage set above the equilibrium wage.
Frequently asked questions
What are the features of a monopoly in Edexcel IGCSE Economics? In the Pearson Edexcel International GCSE Economics (4EC1) specification, a monopoly has a single dominant firm, a unique product, price-maker status and high barriers to entry.
What is the difference between a monopoly and an oligopoly? A monopoly is a single dominant firm. An oligopoly has a few dominant firms that are aware of each other, with differentiated products, high barriers to entry, interdependent pricing and the possibility of collusion.
Is a monopoly always bad for consumers? Not always. The case against is higher prices and reduced choice; the case for is economies of scale and funded innovation, for example in pharmaceuticals. A strong answer weighs both before reaching a judgement.
What happens when a minimum wage is set above equilibrium? Quantity of labour supplied rises above quantity demanded, so there is an excess supply of labour, or unemployment. Workers who keep their jobs earn more, while others lose out.
Why do some firms stay small? The specification gives a limited market size, serving a niche market, financing constraints and the owner’s own goals as reasons some firms stay small.
Official syllabus
Pearson Edexcel International GCSE Economics (4EC1) specification, Issue 3 — qualifications.pearson.com.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
Pearson Edexcel IGCSE Economics: Production and Business Costs (4EC1)
Factors of production, productivity, division of labour, costs, revenue and economies of scale, sub-topics 1.2.1 to 1.2.3 of Edexcel IGCSE Economics 4EC1.
Economics · Pearson Edexcel · IGCSE
Read guide -
Practice questions
Pearson Edexcel IGCSE Economics: Business Economics — Practice Questions (4EC1)
Practice questions with worked answers on factors of production, productivity, division of labour, costs and scale economies for Edexcel IGCSE Economics 4EC1.
Economics · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Pearson Edexcel IGCSE Economics: Production and Business Costs — Revision Notes
Revision notes on factors of production, productivity, division of labour, costs, revenue and economies of scale for Edexcel International GCSE Economics 4EC1.
Economics · Pearson Edexcel · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Economics IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Economics classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Economics teachers at Marlbridge

