
Revision Notes
IGCSE Accounting: Accounting Procedures — Revision Notes
Quick-recall Cambridge IGCSE Accounting 0452 Topic 4 notes: capital and revenue items, depreciation, disposals, accruals, irrecoverable debts and inventory.
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- Accounting procedures
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus topics and points this page is mapped to
0452
- 4 Accounting procedures (topic-level mapping)
7707
- 4 Accounting procedures (topic-level mapping)
"Topic-level mapping" means this page belongs to that topic; it does not claim to cover every point in it.
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. For this topic, the 2026 syllabus says “recovery of debts written off” where the 2027-2029 syllabus says “irrecoverable debts recovered”, asks for simple inventory valuation statements, and does not separately list choosing a depreciation method for each type of non-current asset, journal entries for purchasing a non-current asset, or calculating the profit or loss on disposal. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
Condensed for the final weeks. For the full explanation and worked ledger accounts, use the Accounting Procedures study guide.
The core question this topic answers
Five procedures, one underlying purpose: does each figure belong to this year, and does it belong in the statement of profit or loss or the statement of financial position? Each adjustment moves an amount between the two statements, and every one of them is applied again in Topic 5’s Preparation of Financial Statements.
4.1 Capital and revenue expenditure and receipts
| Capital | Revenue | |
|---|---|---|
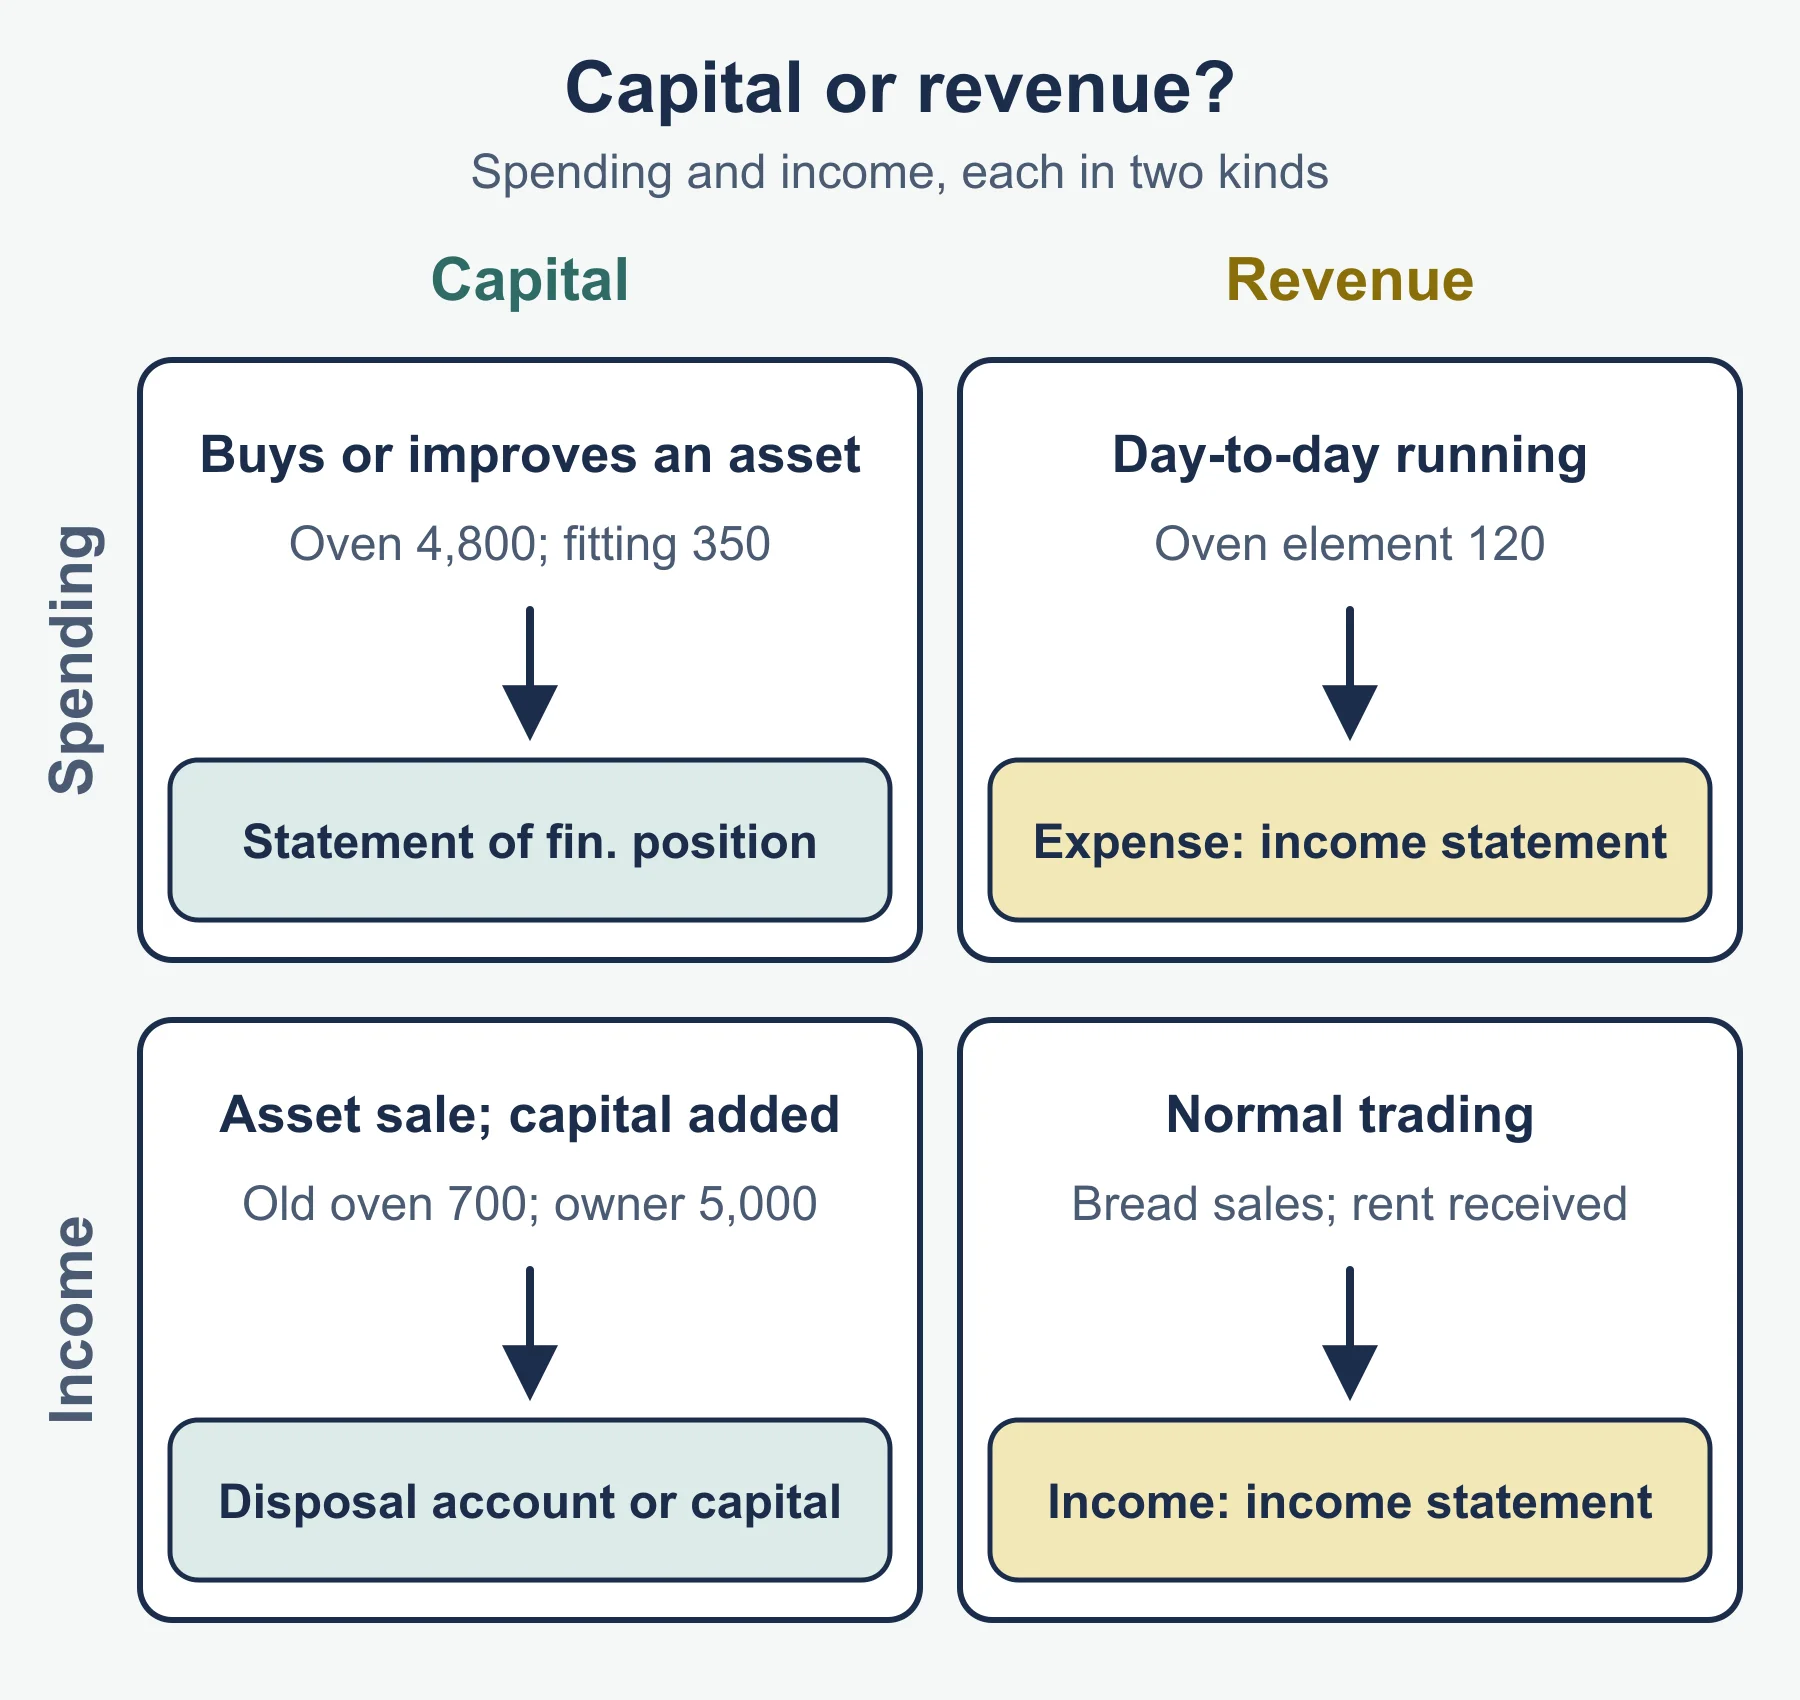
| Expenditure | Buying or improving non-current assets, including delivery, installation and other costs of getting them ready for use | Running costs: repairs, maintenance, fuel, wages, insurance, rent |
| Where it goes | Non-current asset account → statement of financial position (then depreciated) | Expense → statement of profit or loss |
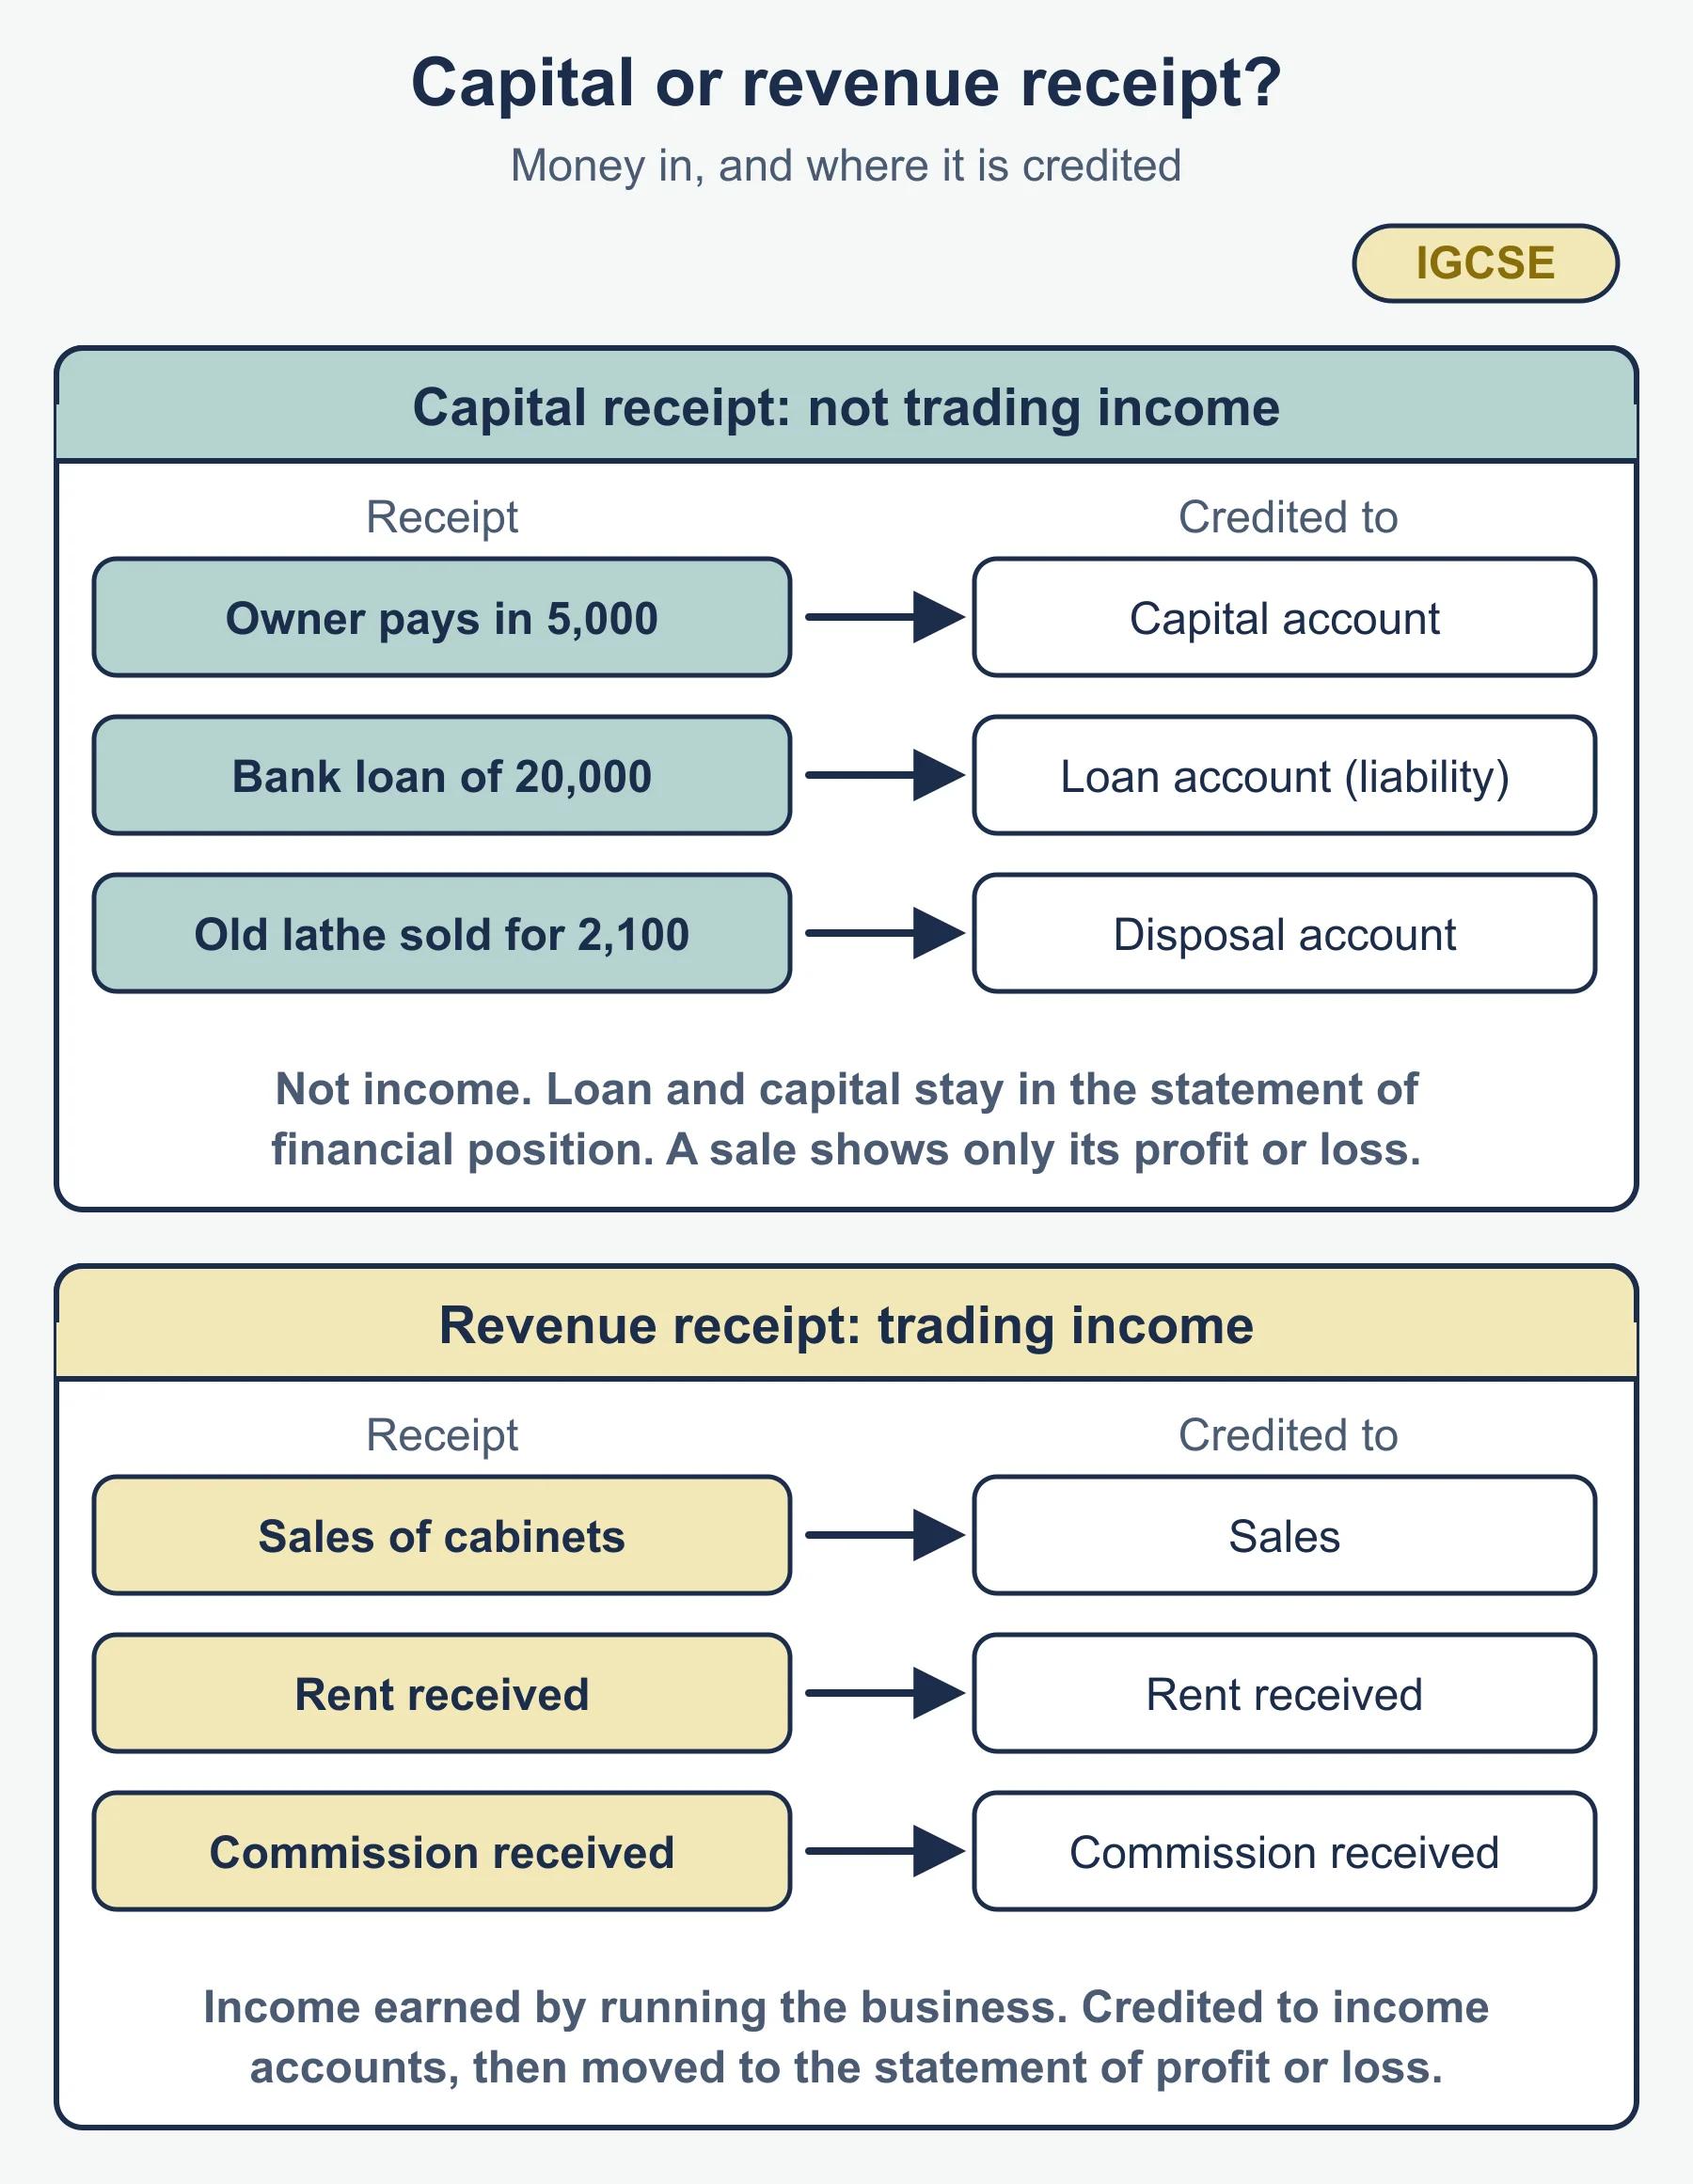
| Receipts | Proceeds from selling a non-current asset; capital introduced by the owner; loans received | Sales, rent received, commission received, interest received |
| Where it goes | Not income — only any profit or loss on disposal reaches the statement of profit or loss | Income → statement of profit or loss |
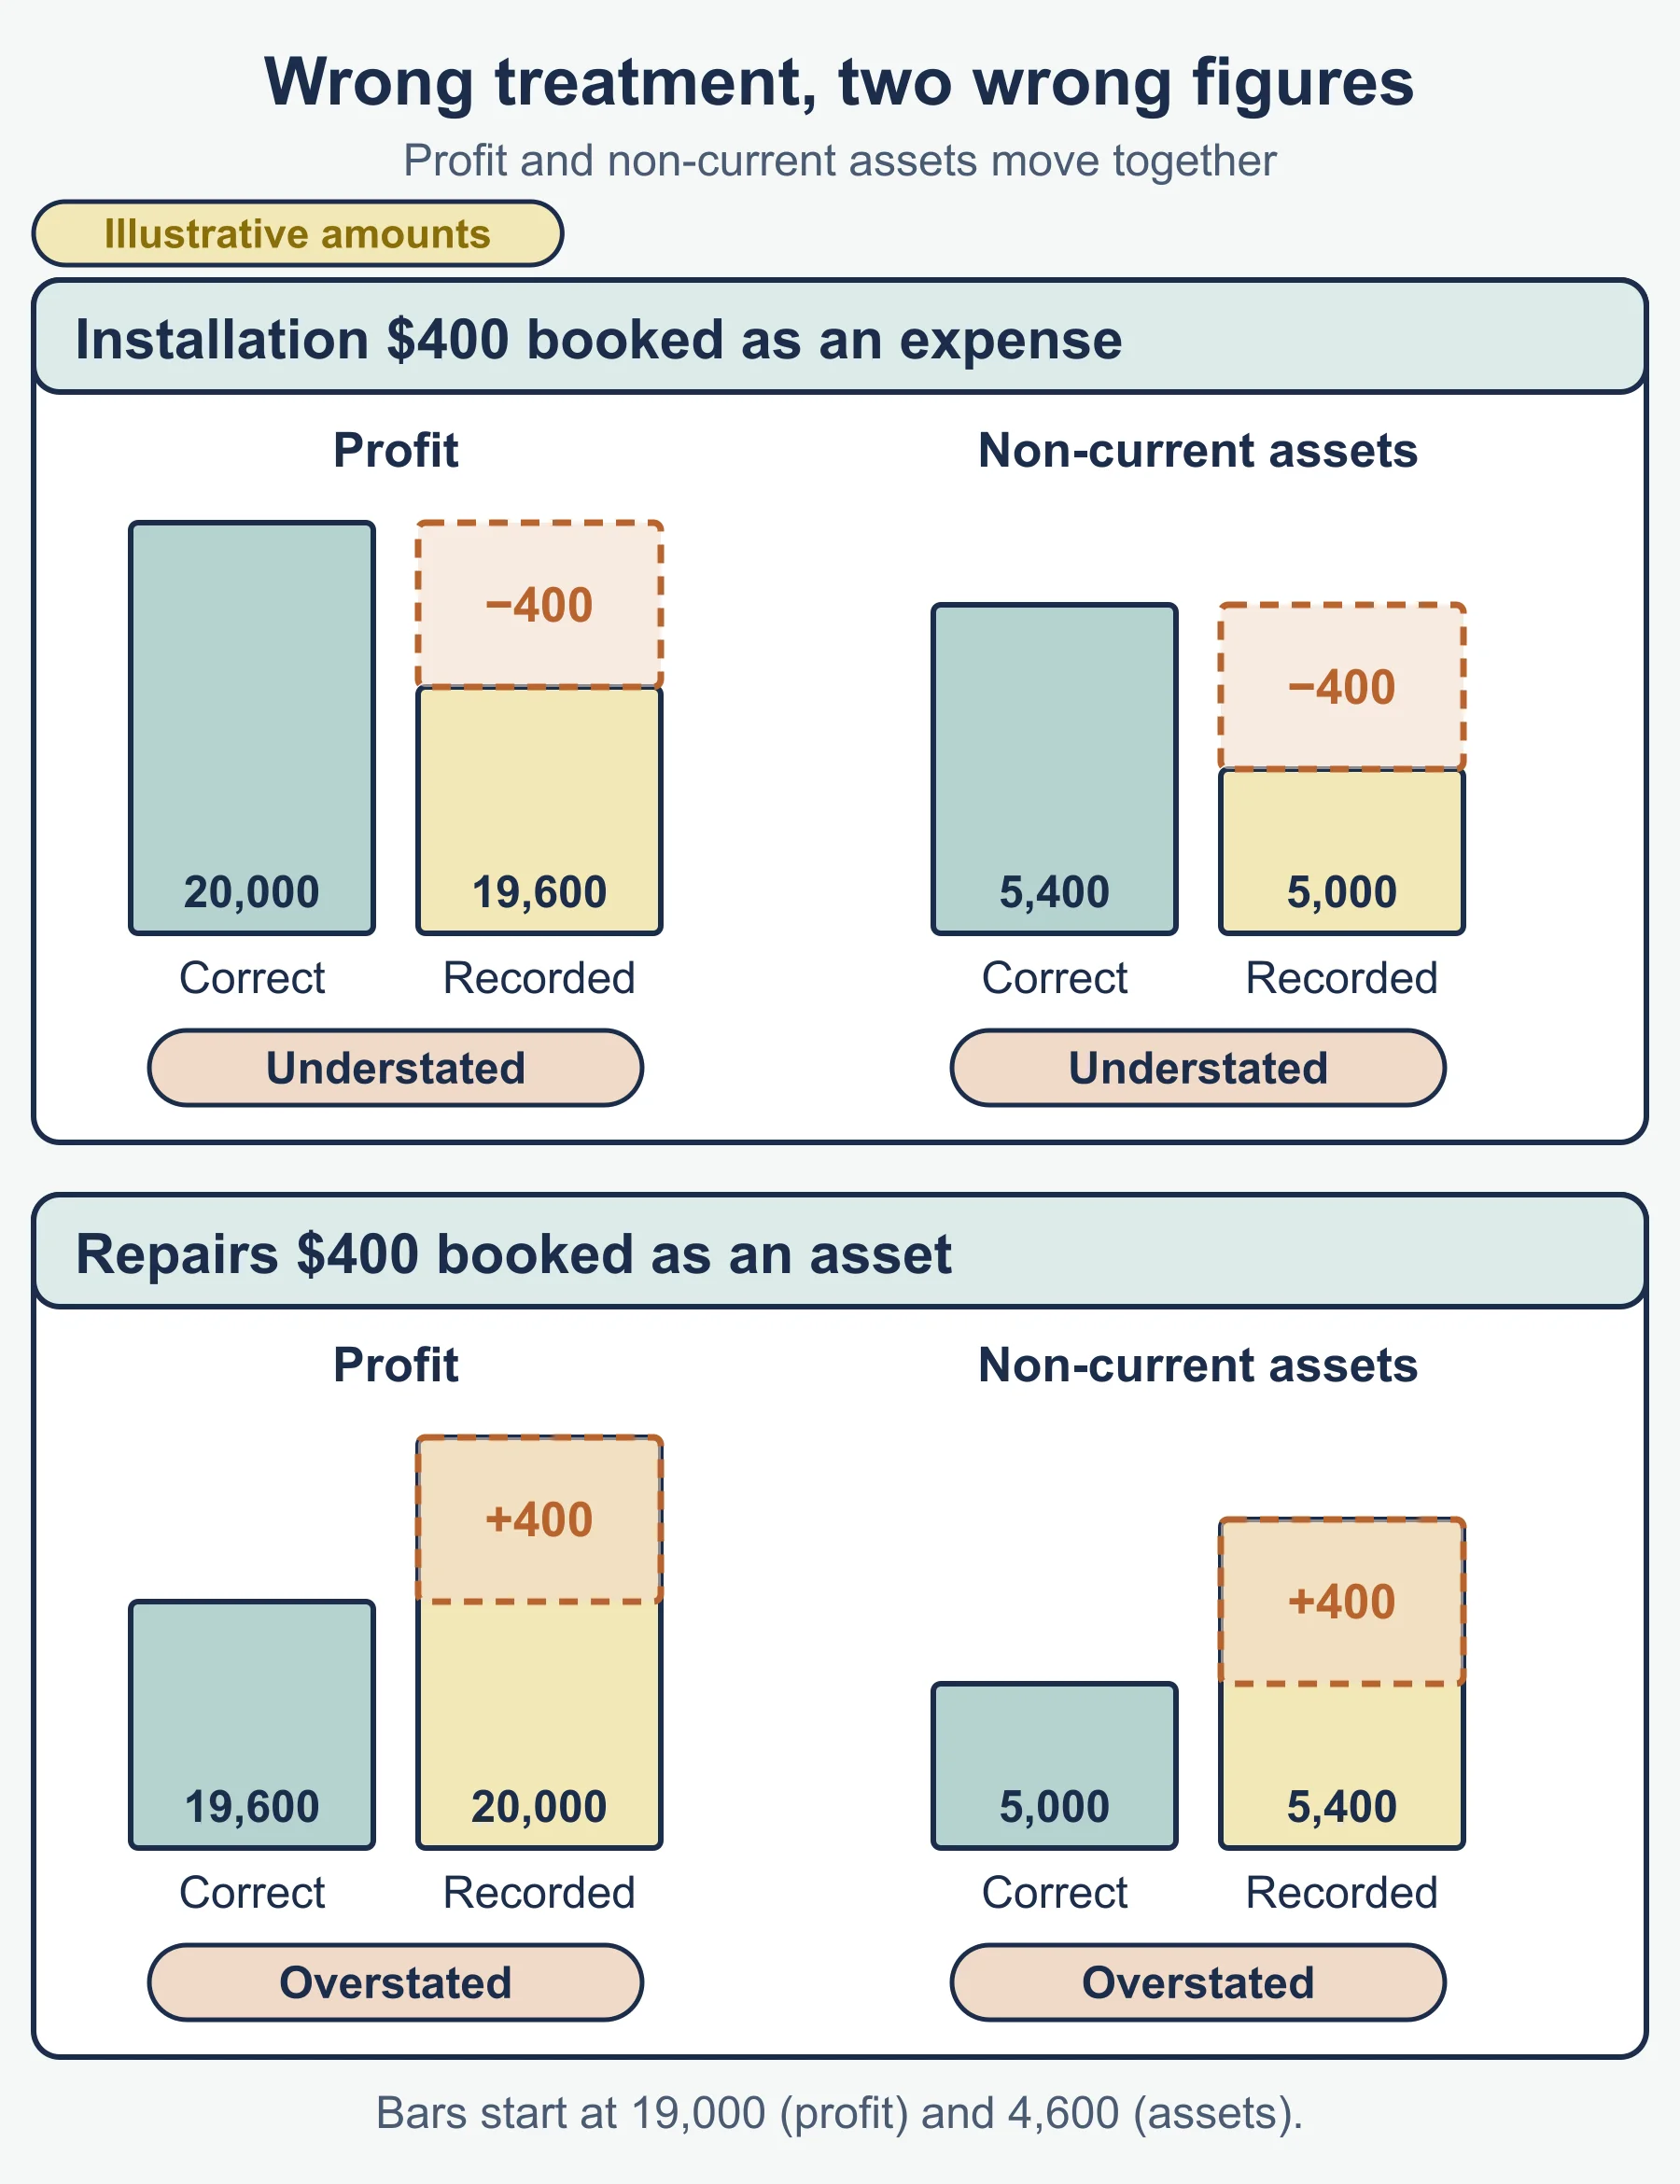
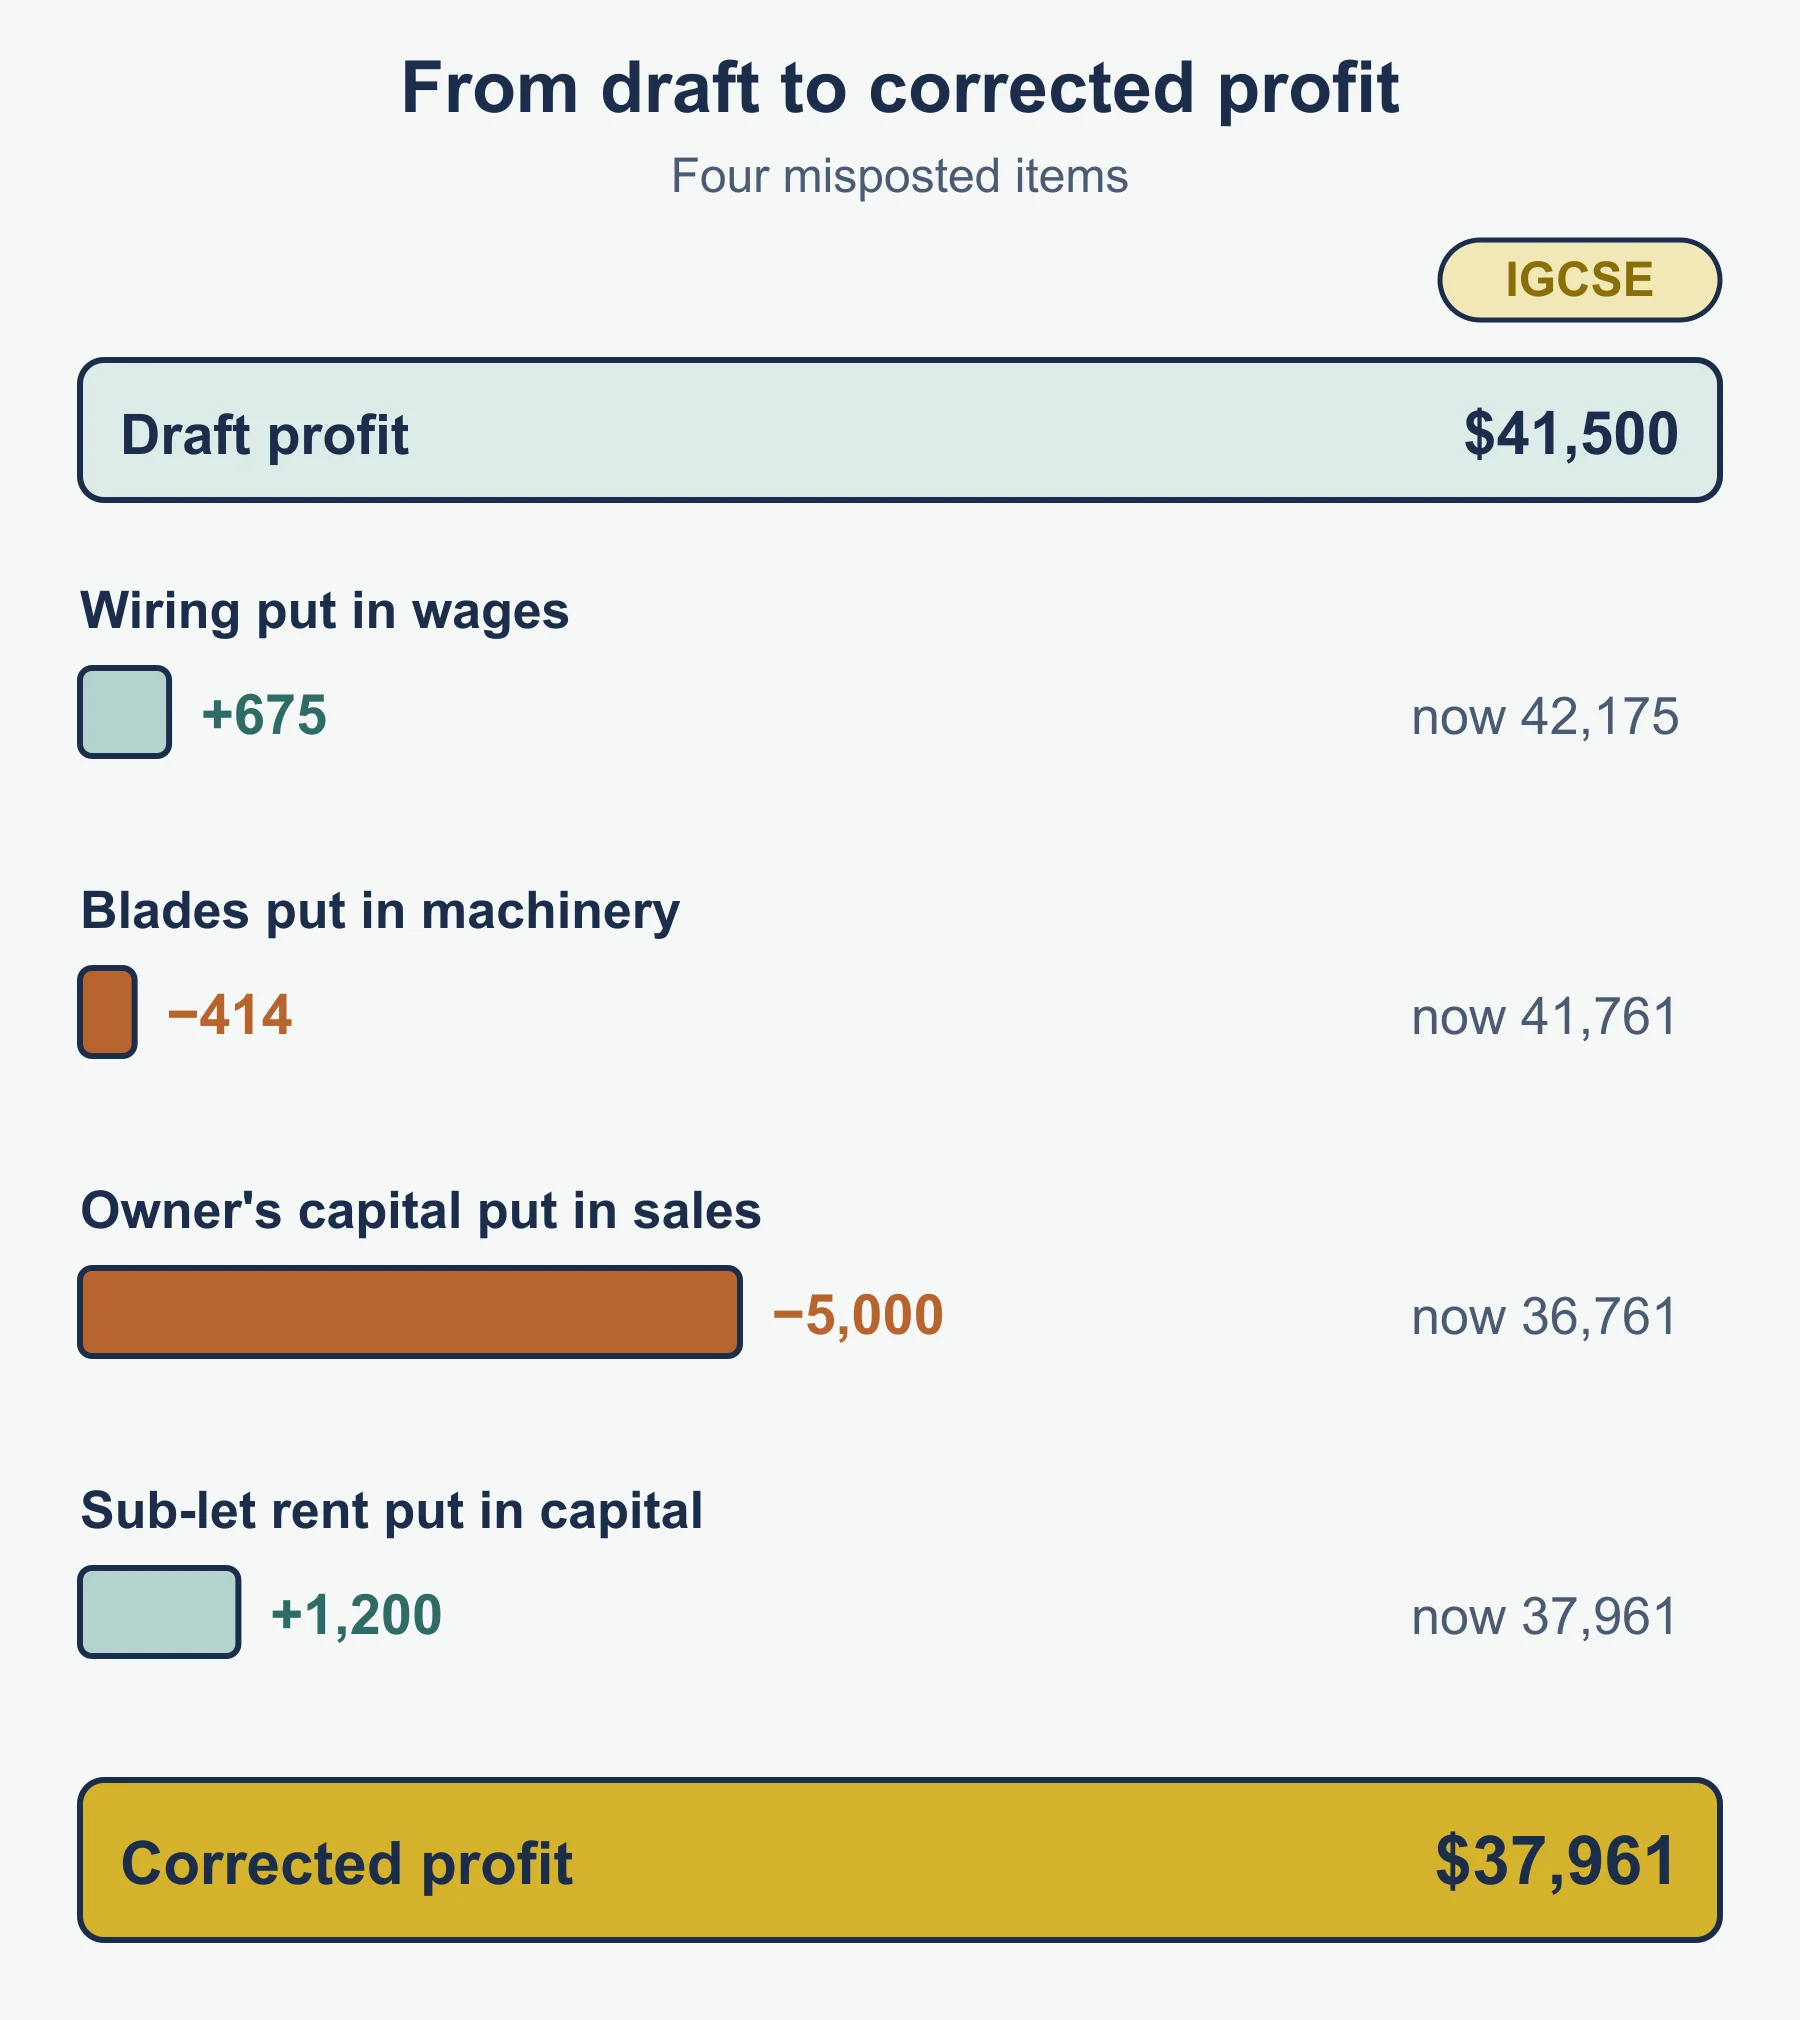
Wrong treatment — the effect:
| Mistake | Profit | Asset valuation |
|---|---|---|
| Revenue expenditure treated as capital | Overstated | Non-current assets overstated |
| Capital expenditure treated as revenue | Understated | Non-current assets understated |
| Proceeds of a non-current asset credited to sales (asset not removed) | Overstated by the net book value | Non-current assets overstated by the net book value |
| Revenue receipt credited to capital or a liability | Understated | — |
If the wrongly capitalised amount has been depreciated, the overstatement is the amount less the depreciation charged on it. Posting an item to the wrong type of account like this is an error of principle, corrected by journal entry in Topic 3’s Verification of Accounting Records.
4.2 Accounting for depreciation and disposal of non-current assets
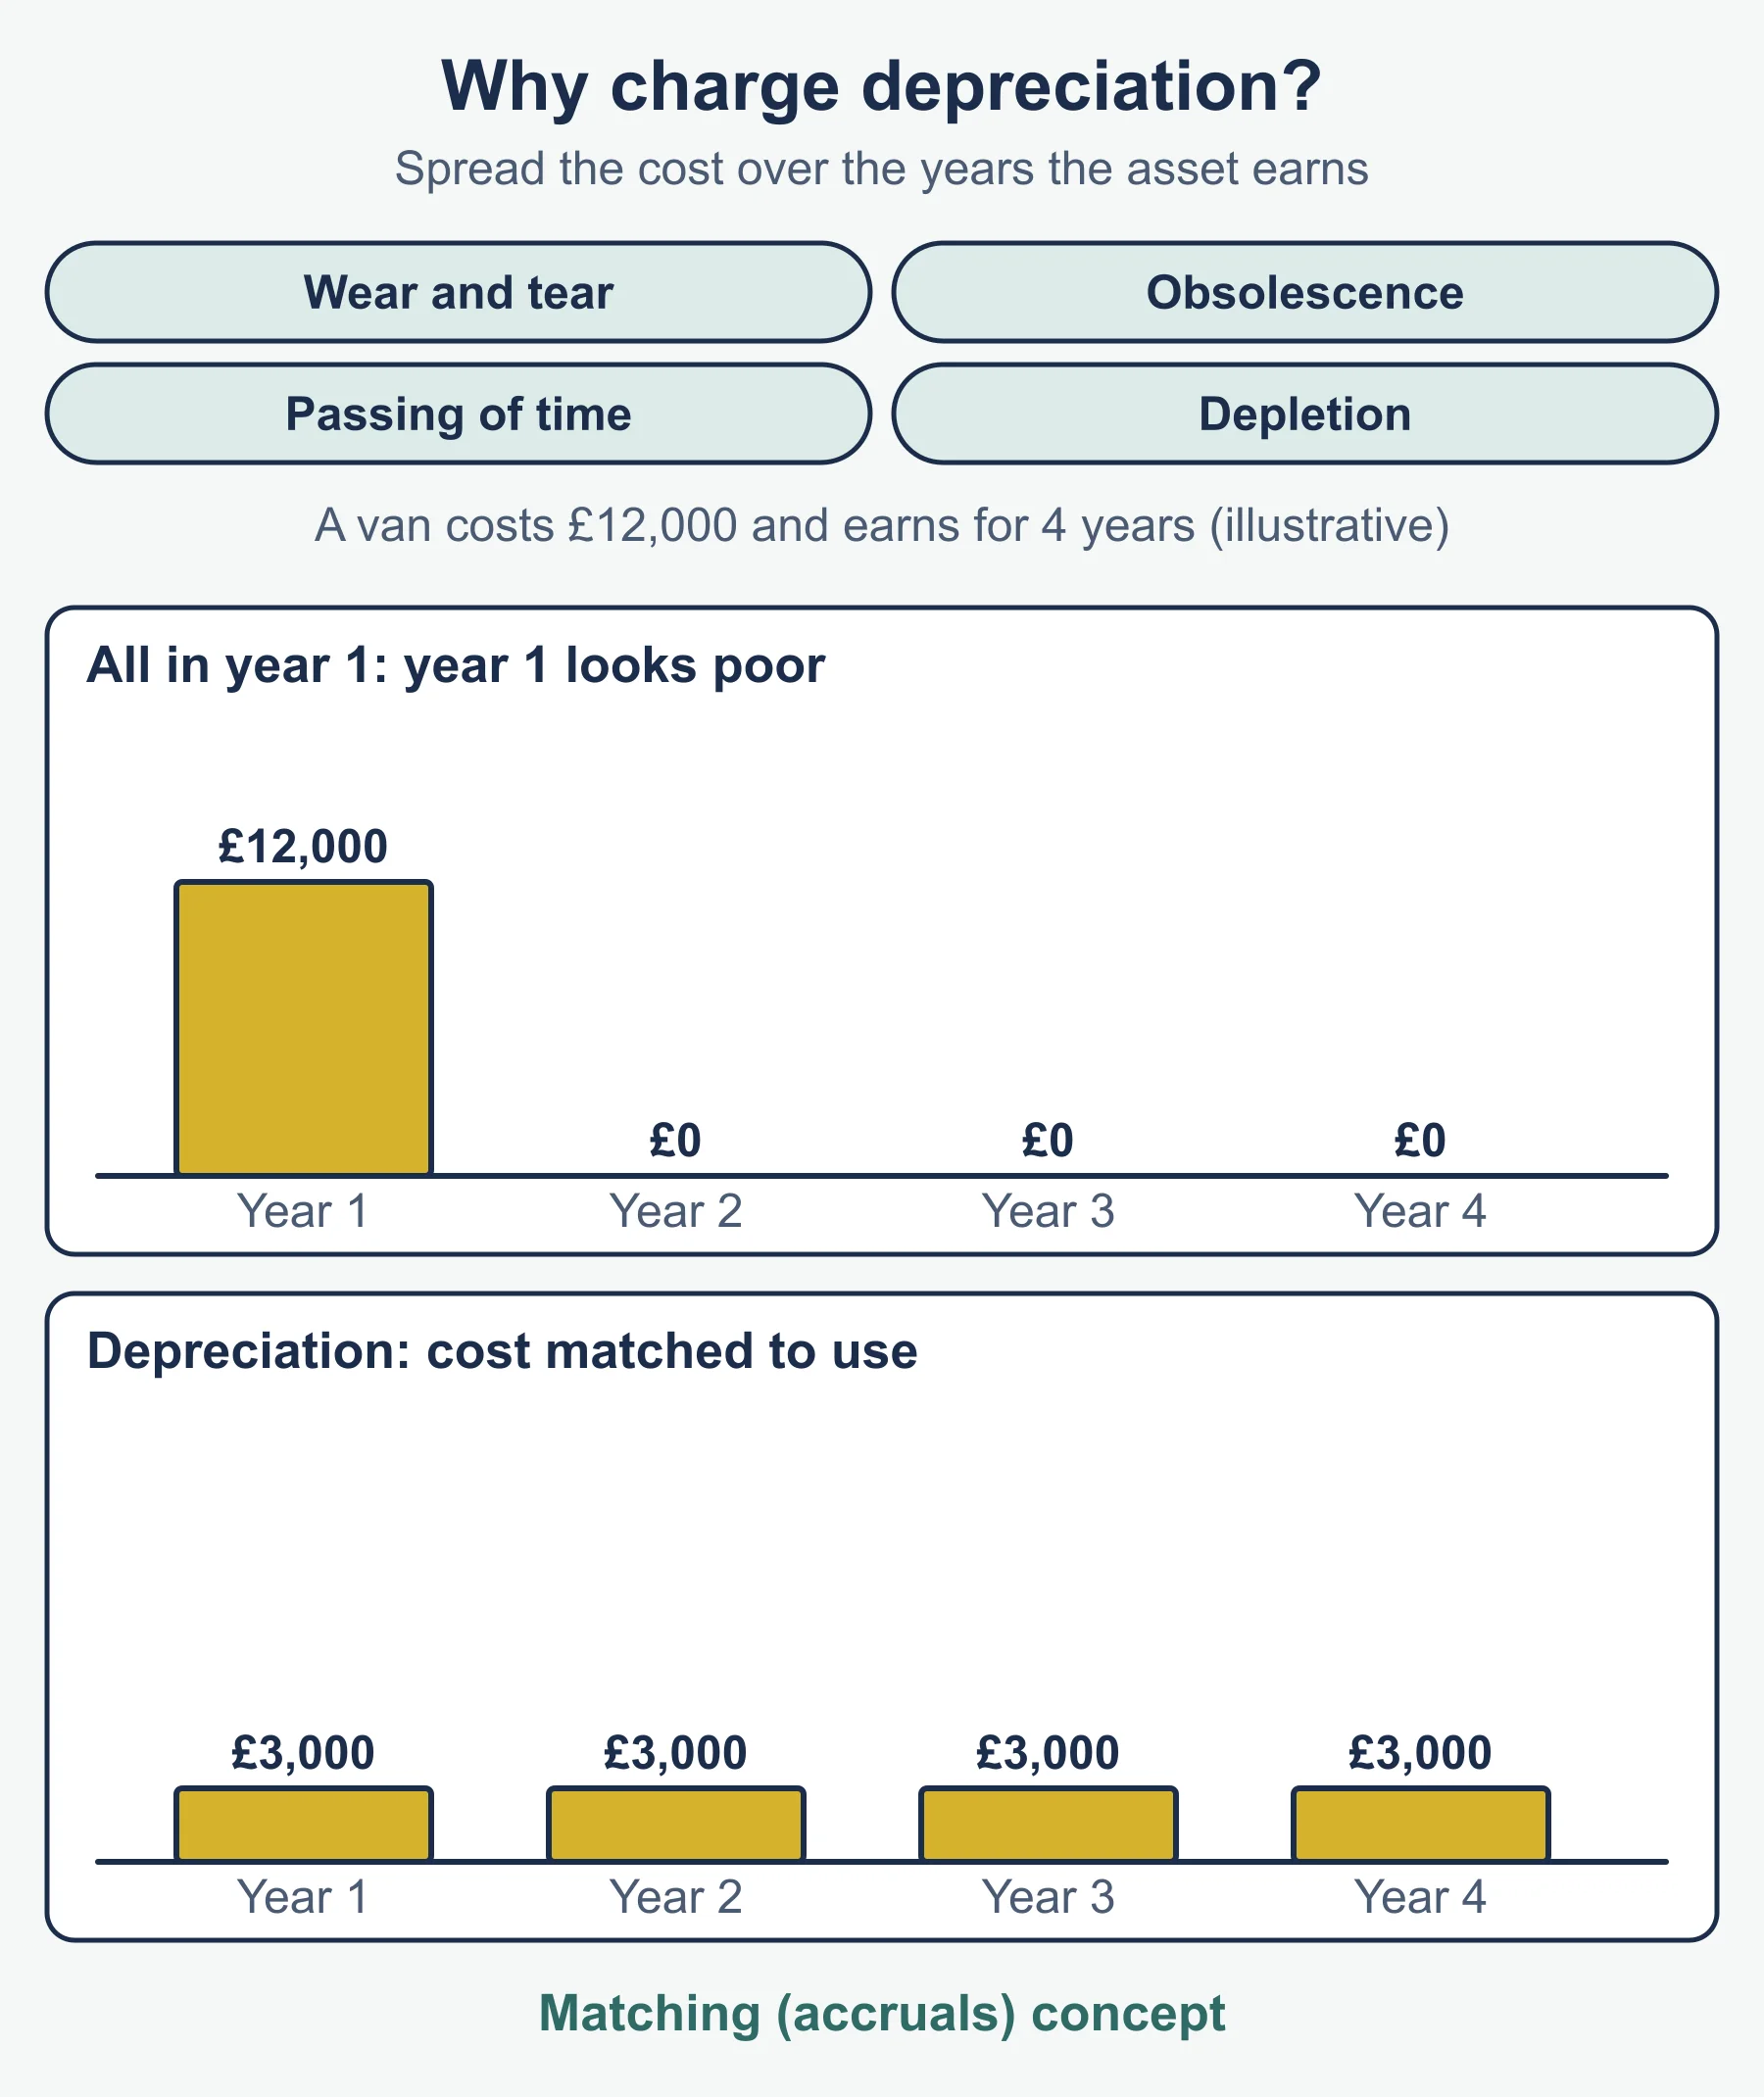
Depreciation = the part of a non-current asset’s cost used up in the period (wear and tear, time, becoming out of date). Why: matches the cost against the revenue the asset helps to earn; stops profit and asset values being overstated. No cash is paid.
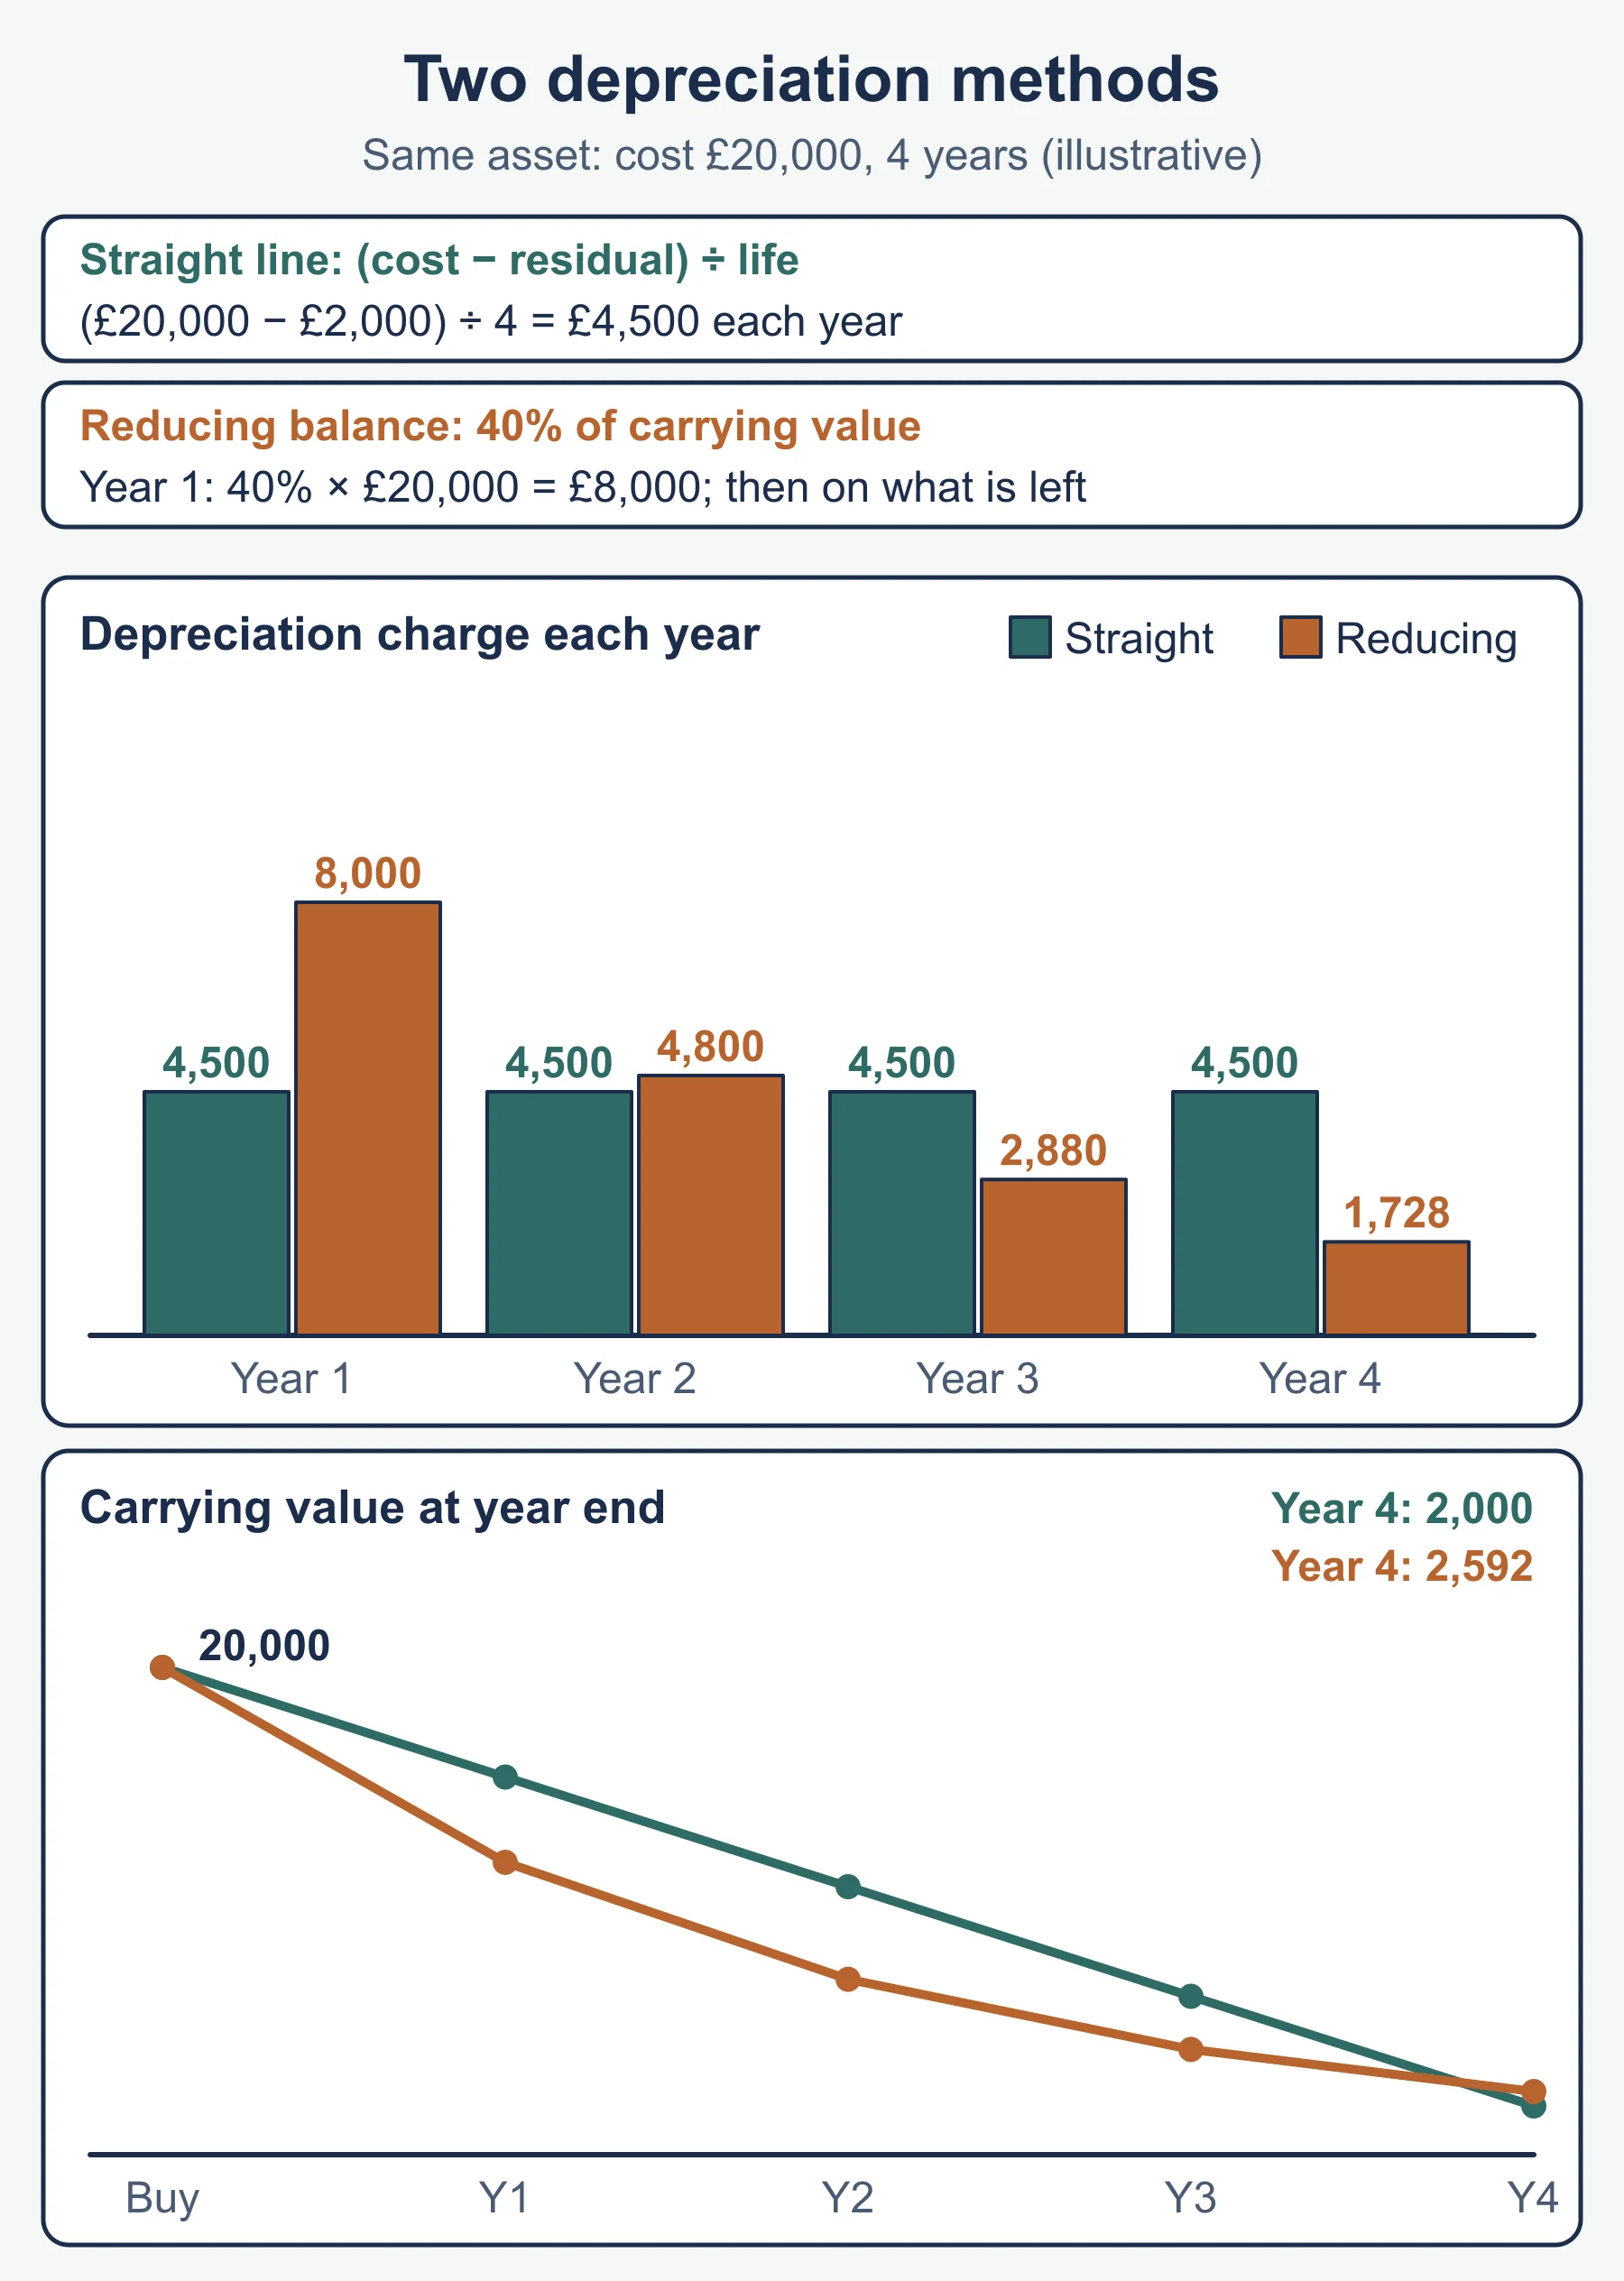
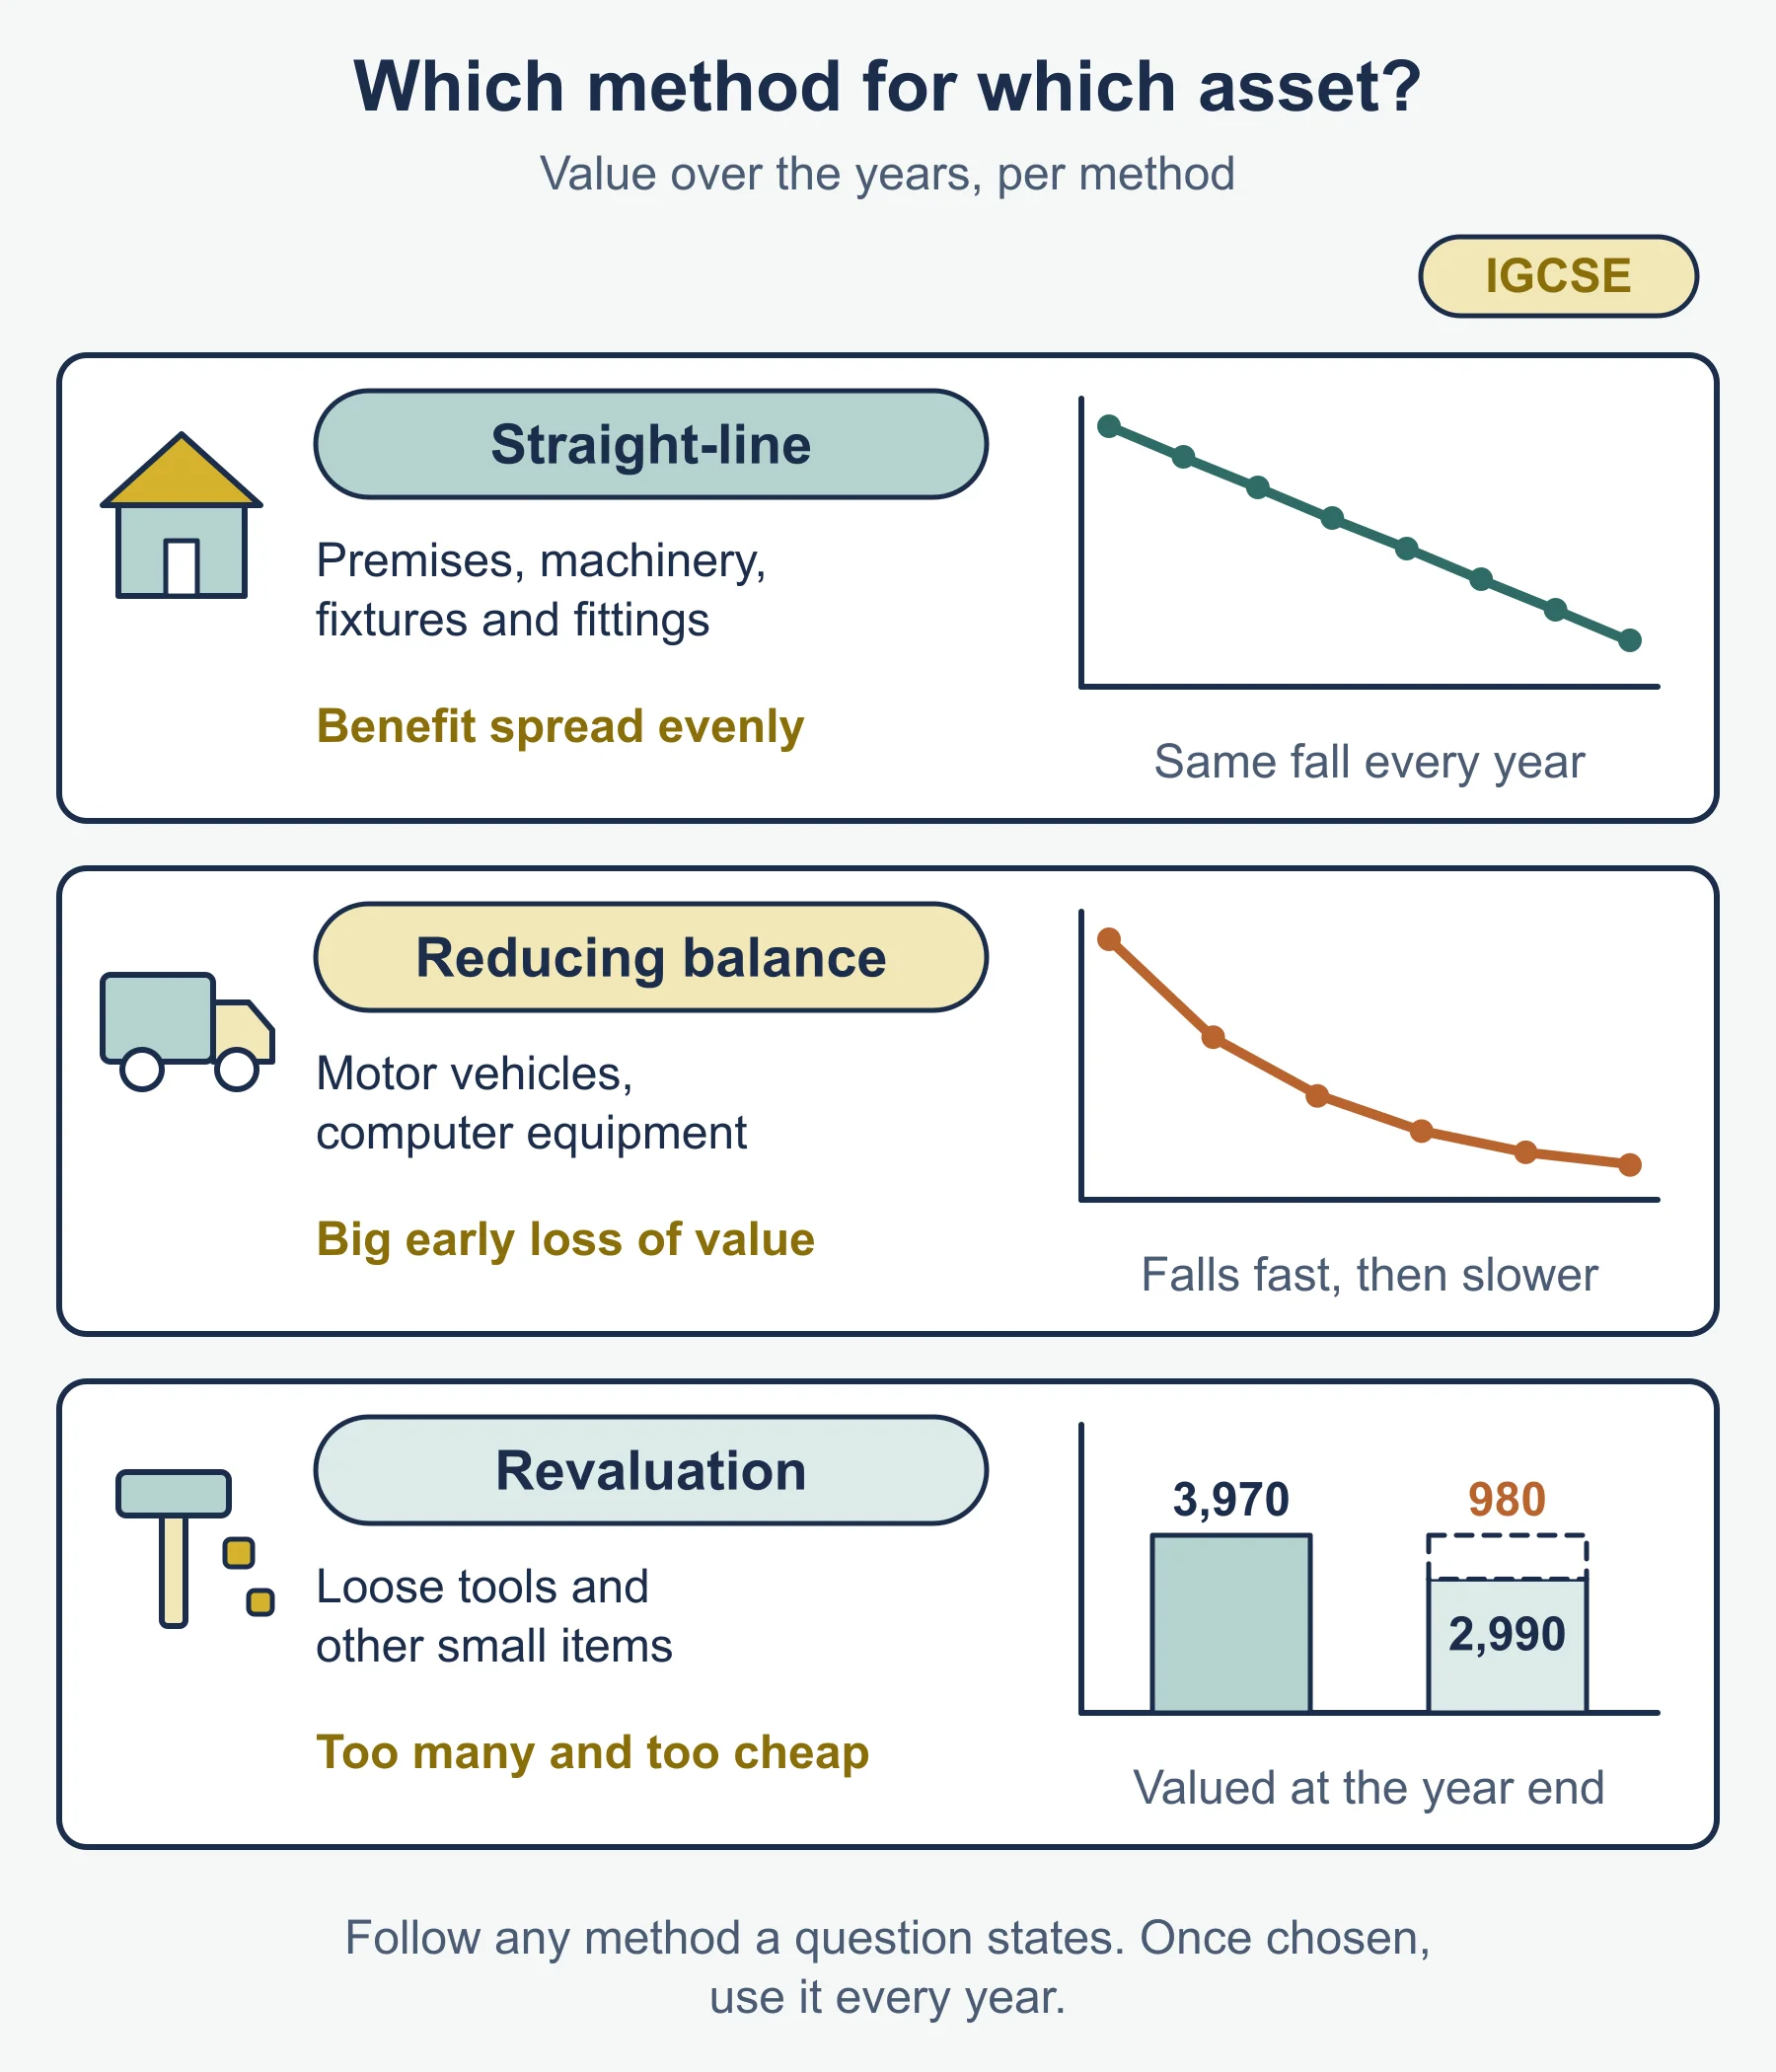
| Method | Calculation | Suits |
|---|---|---|
| Straight-line | (Cost − residual value) ÷ useful life | Assets giving even benefit each year, e.g. machinery used evenly, fixtures and fittings |
| Reducing balance | Fixed % × net book value at the start of the year | Assets losing most value early, e.g. motor vehicles, computer equipment |
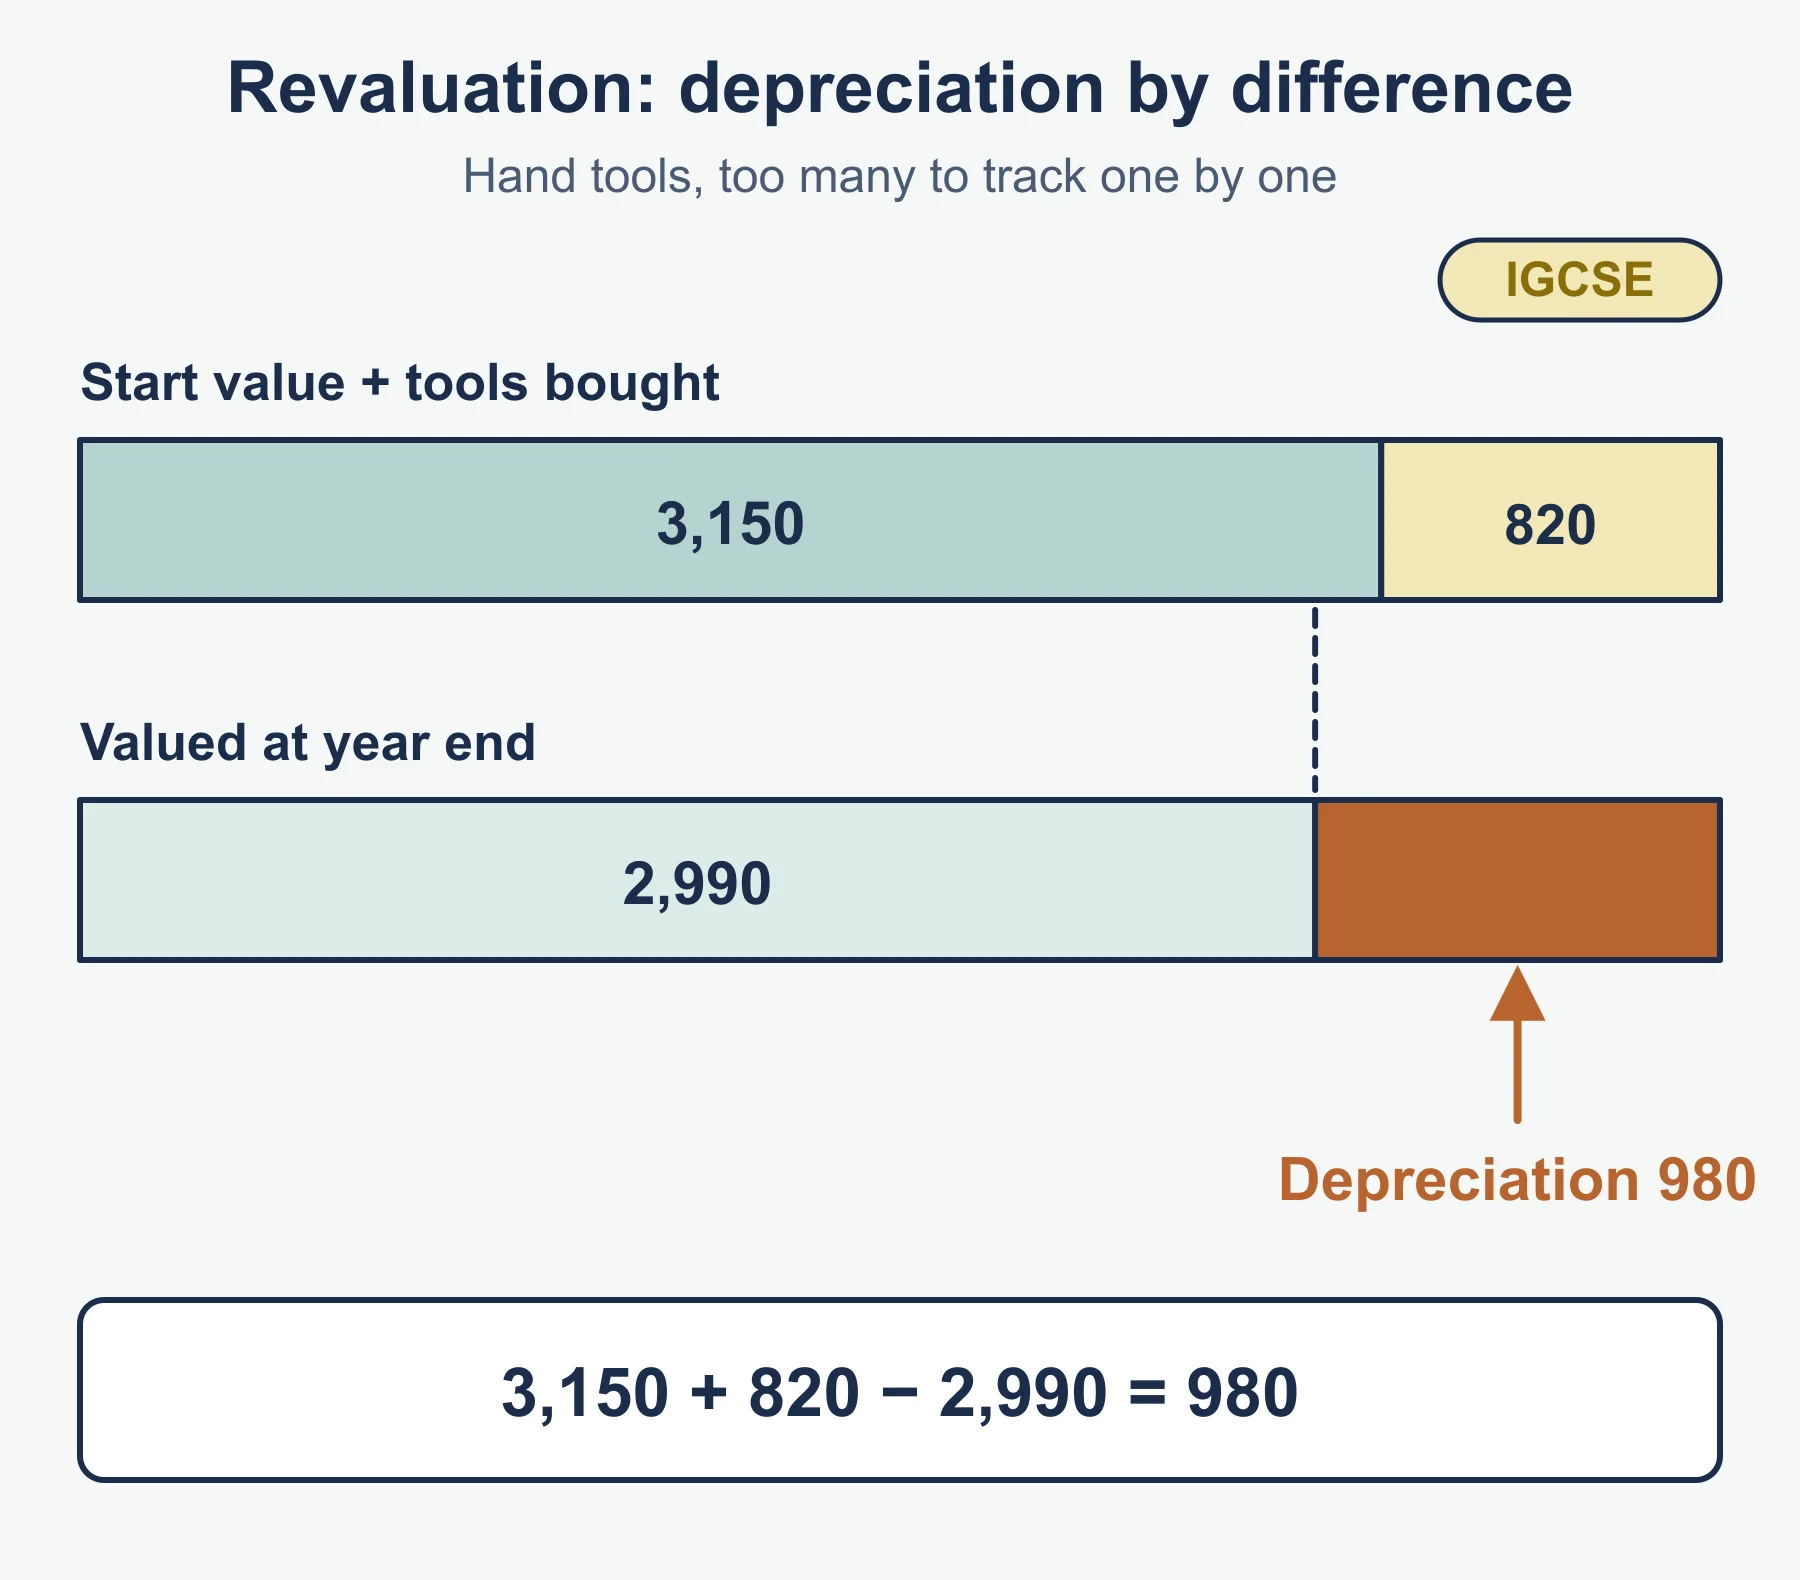
| Revaluation | Opening valuation + purchases − closing valuation | Loose tools and similar small, low-cost items |
Double entries:
- Depreciation: Dr statement of profit or loss, Cr provision for depreciation.
- Purchase: Dr non-current asset, Cr bank (or the supplier, an other payable, if on credit).
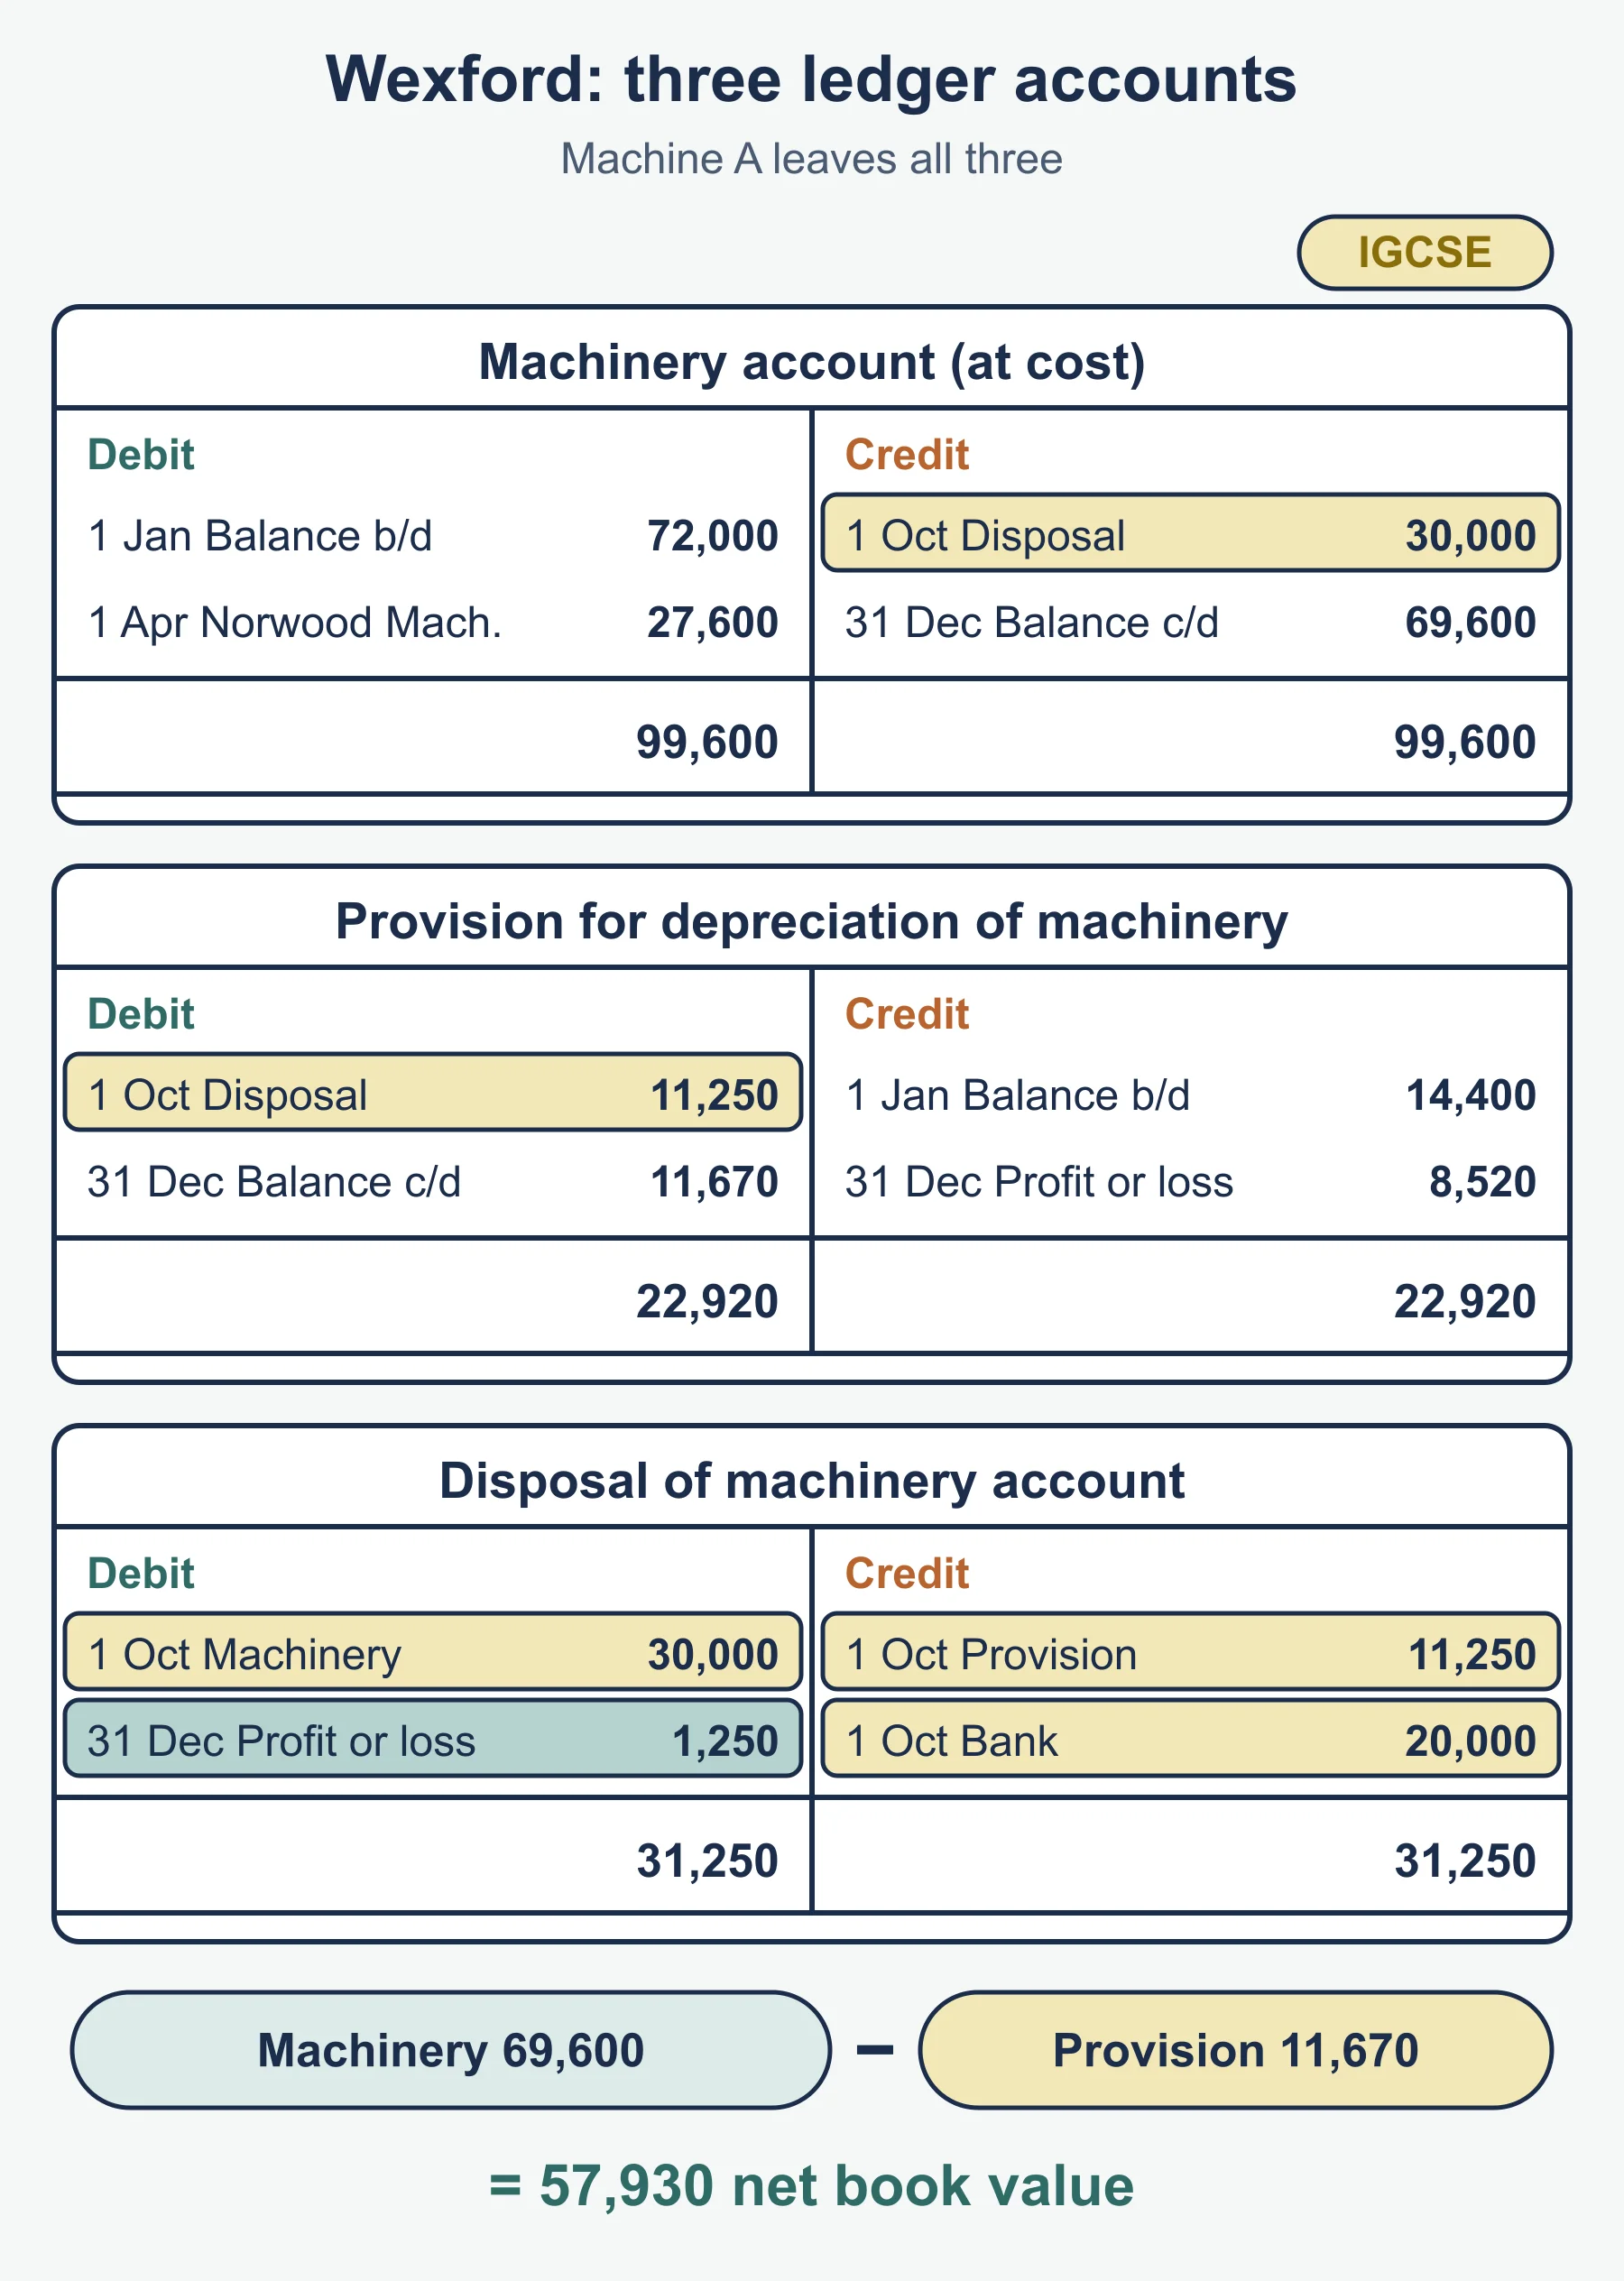
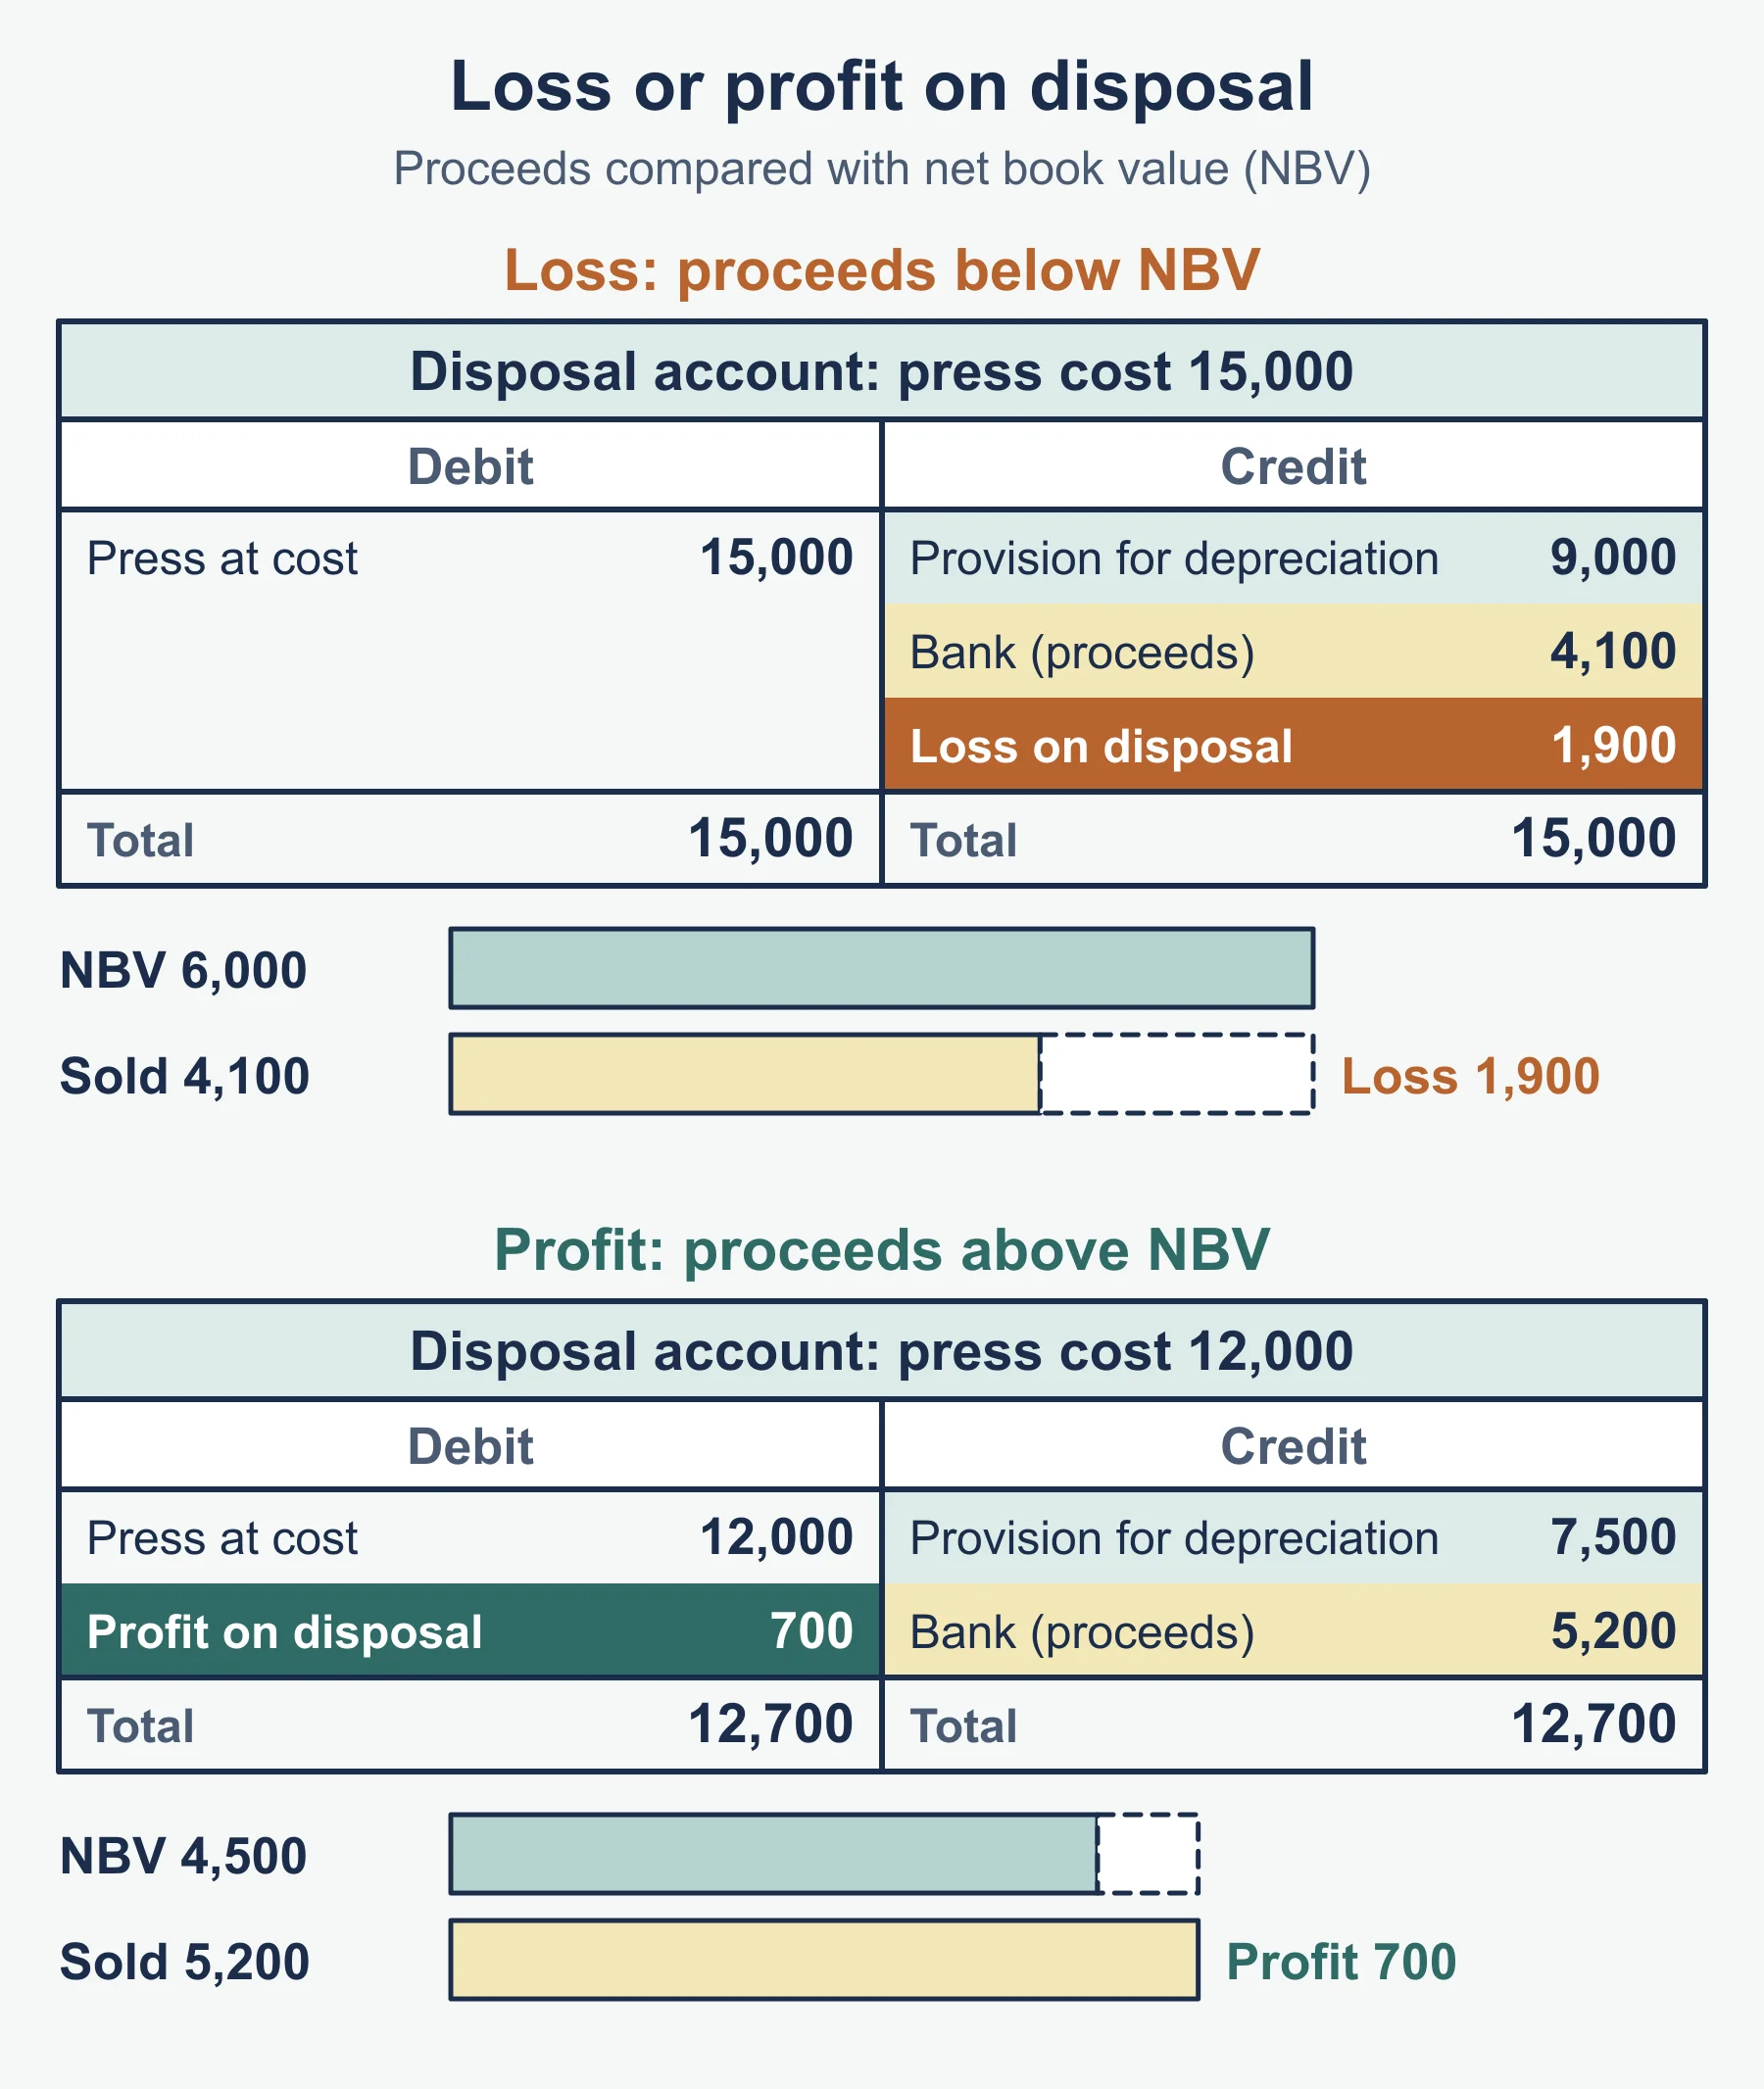
- Sale: Dr disposal, Cr non-current asset (cost); Dr provision for depreciation, Cr disposal (accumulated depreciation on that asset); Dr bank, Cr disposal (proceeds).
- Balance on disposal: profit → Dr disposal, Cr statement of profit or loss (other income); loss → Dr statement of profit or loss, Cr disposal (expense).
Profit or loss on disposal = proceeds − net book value at the date of disposal. Net book value = cost − accumulated depreciation.
4.3 Other payables and other receivables
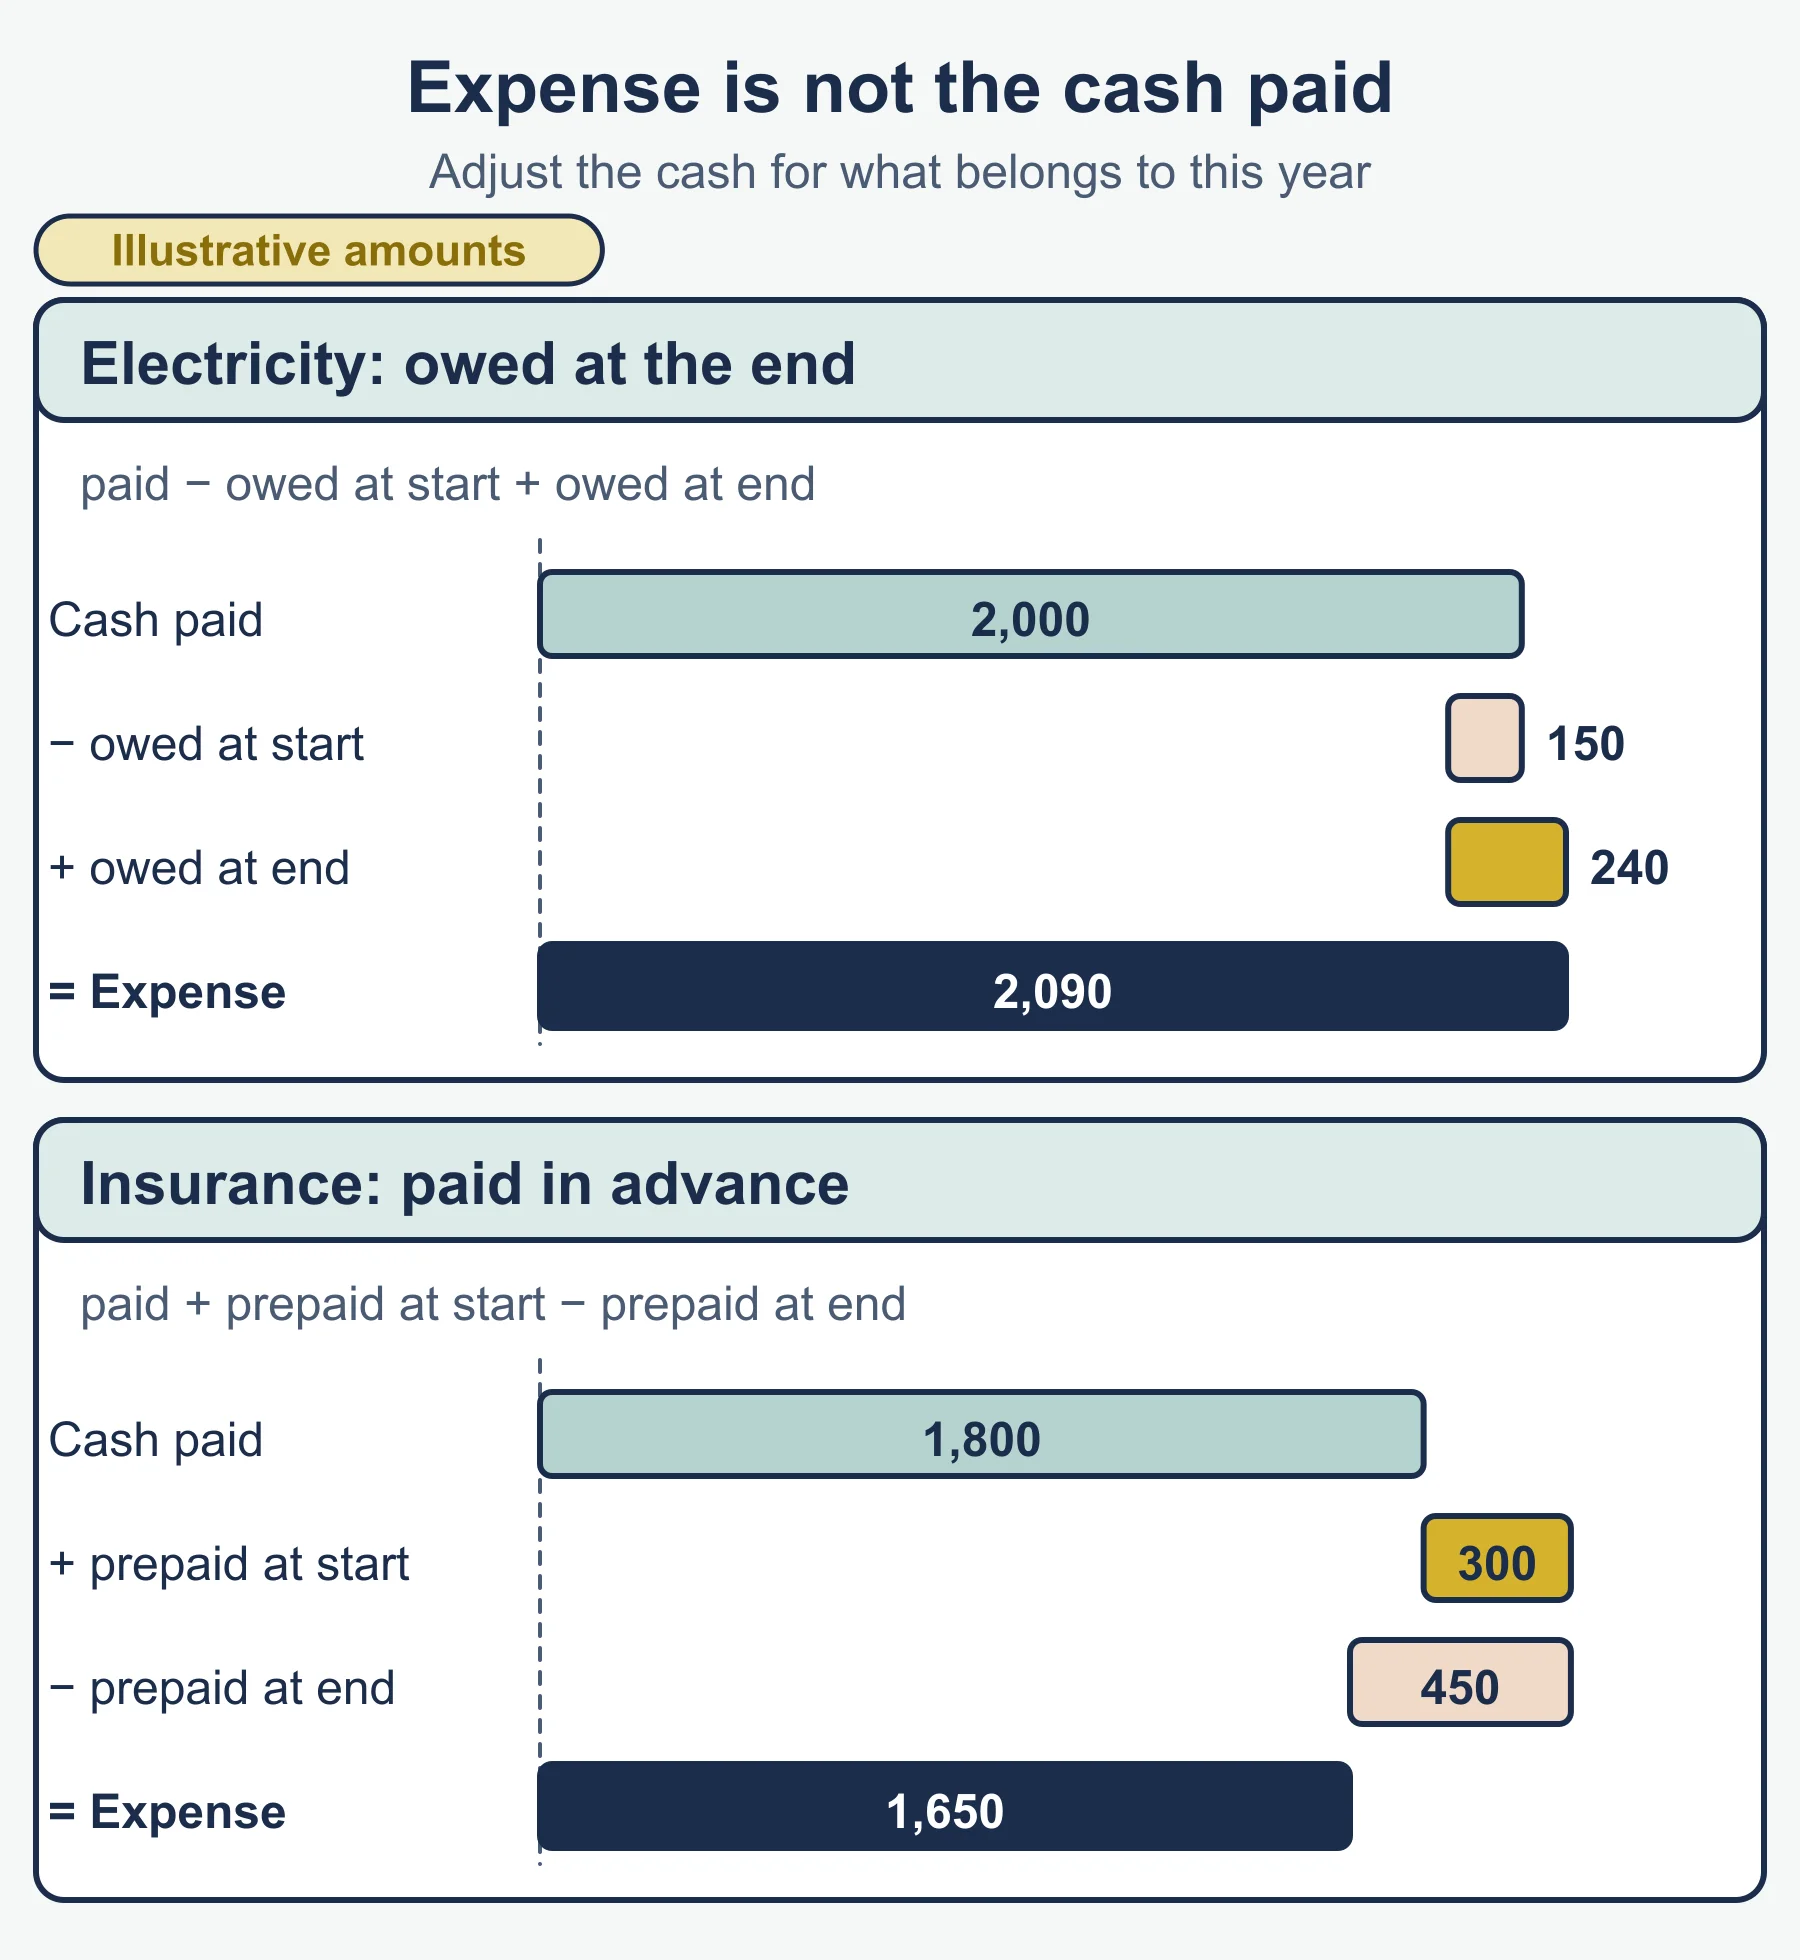
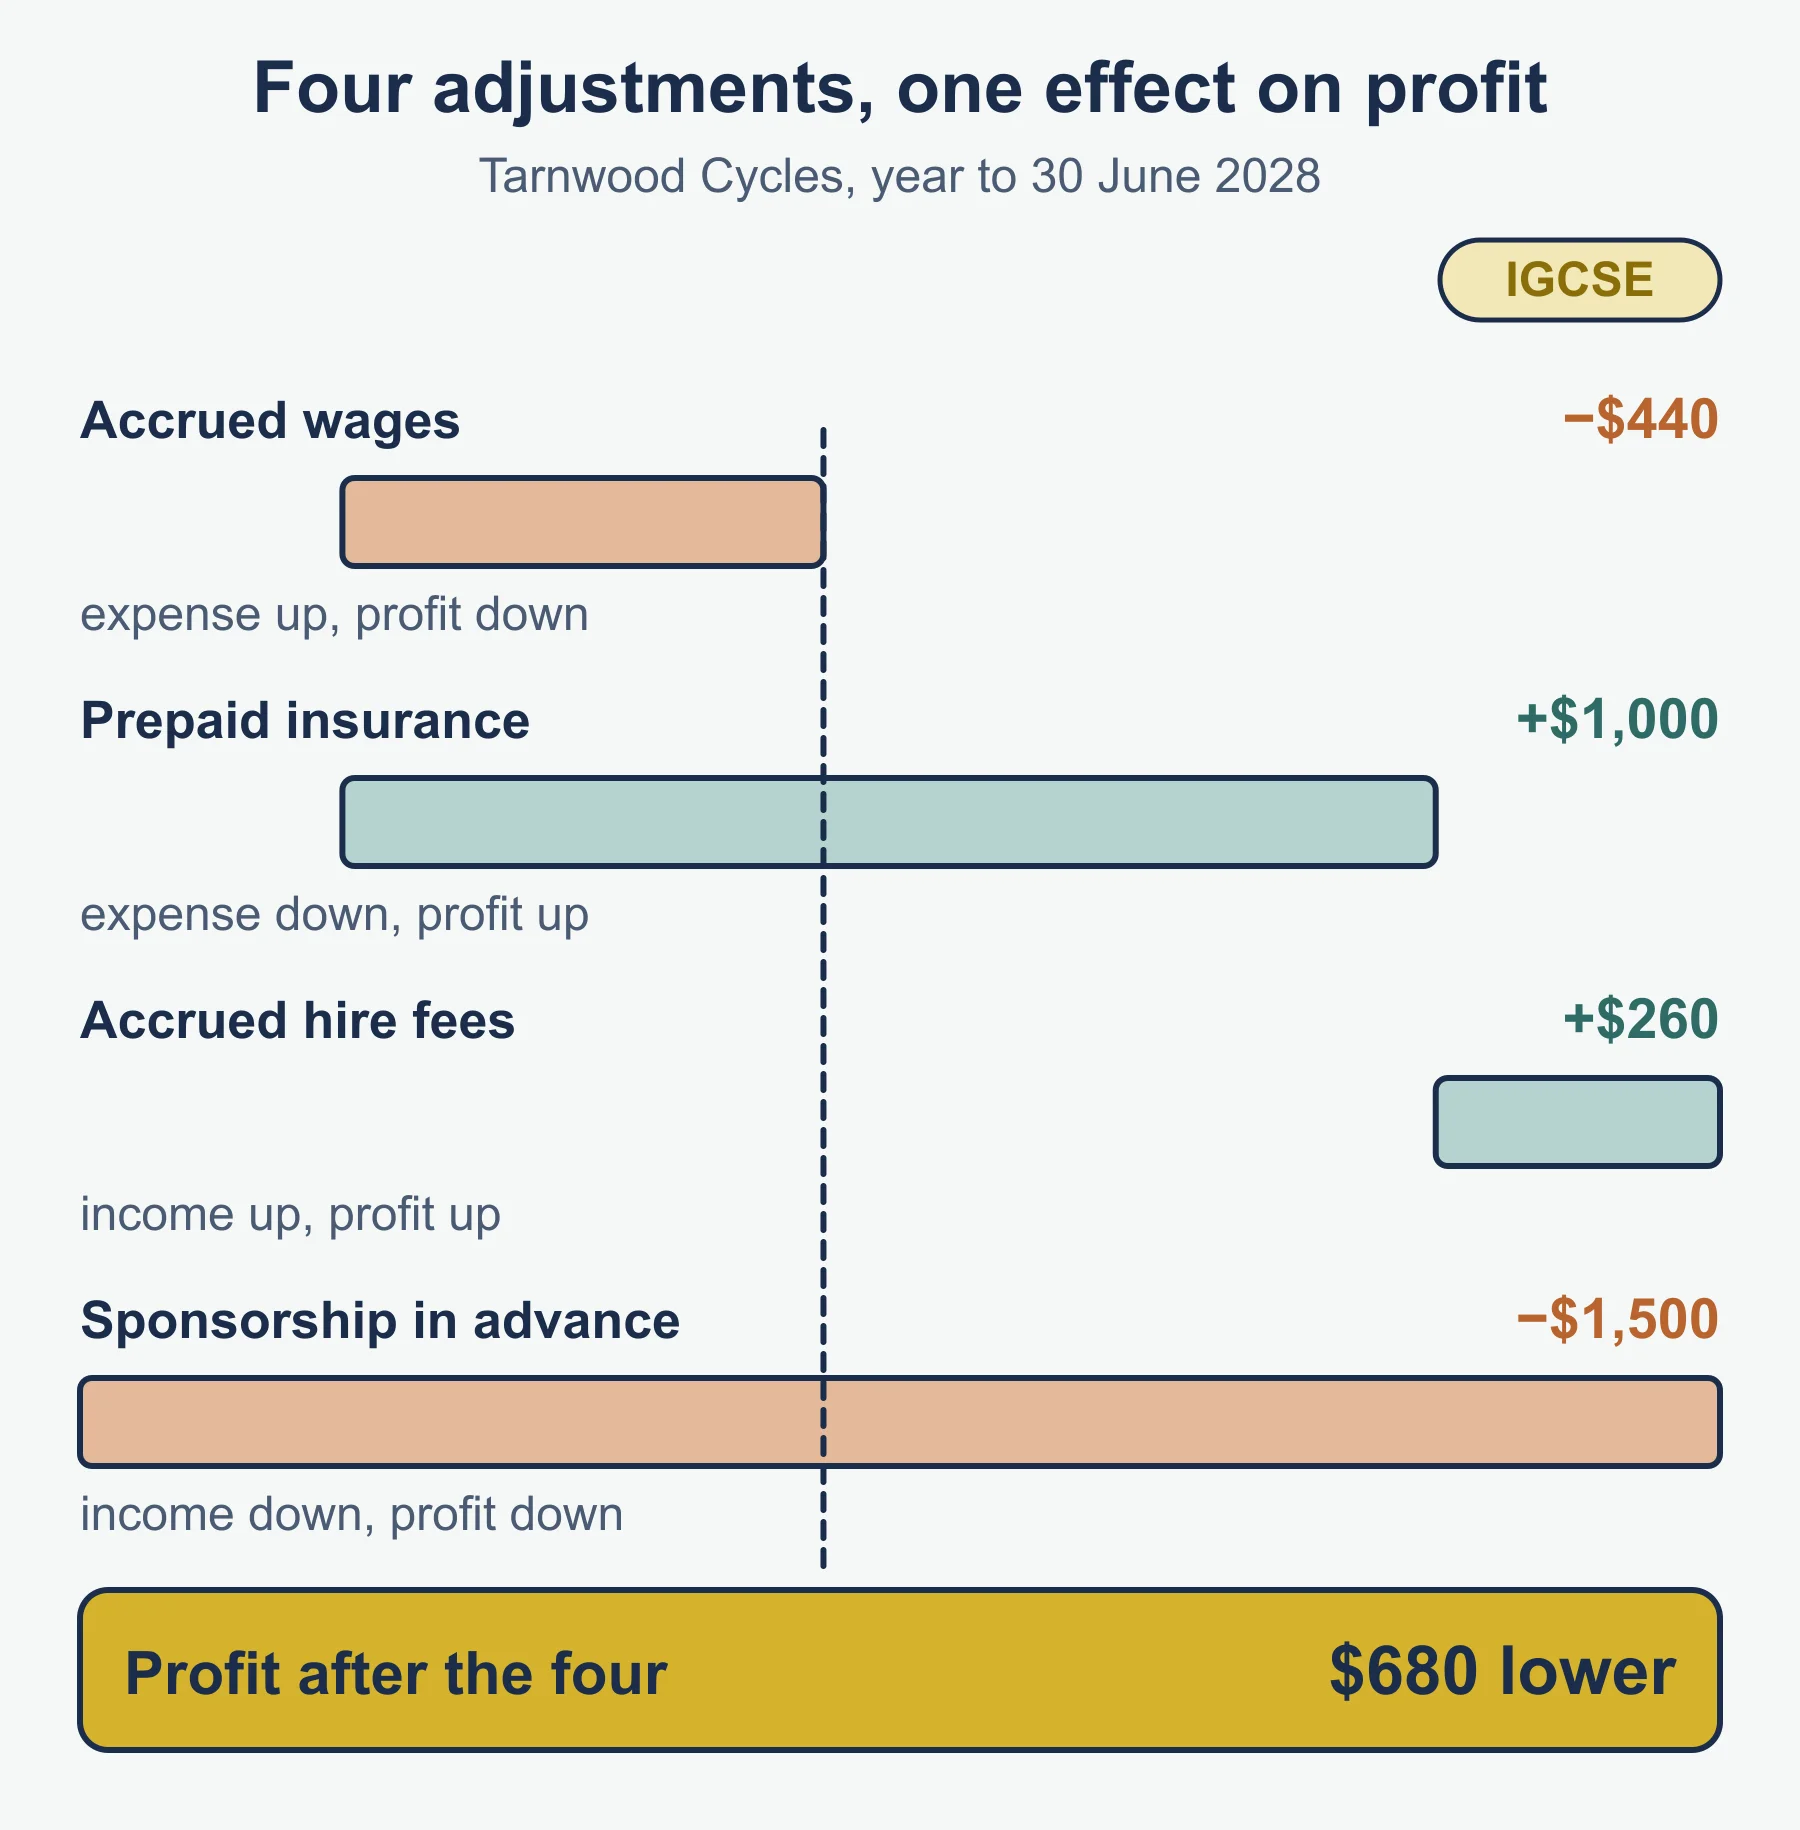
Matching / accruals: record the expenses and incomes that belong to the period, not the cash paid or received in it.
| Item | Year-end journal | Balance b/d | Statement of financial position |
|---|---|---|---|
| Accrued expense | Dr expense, Cr other payables | Credit | Other payables (current liability) |
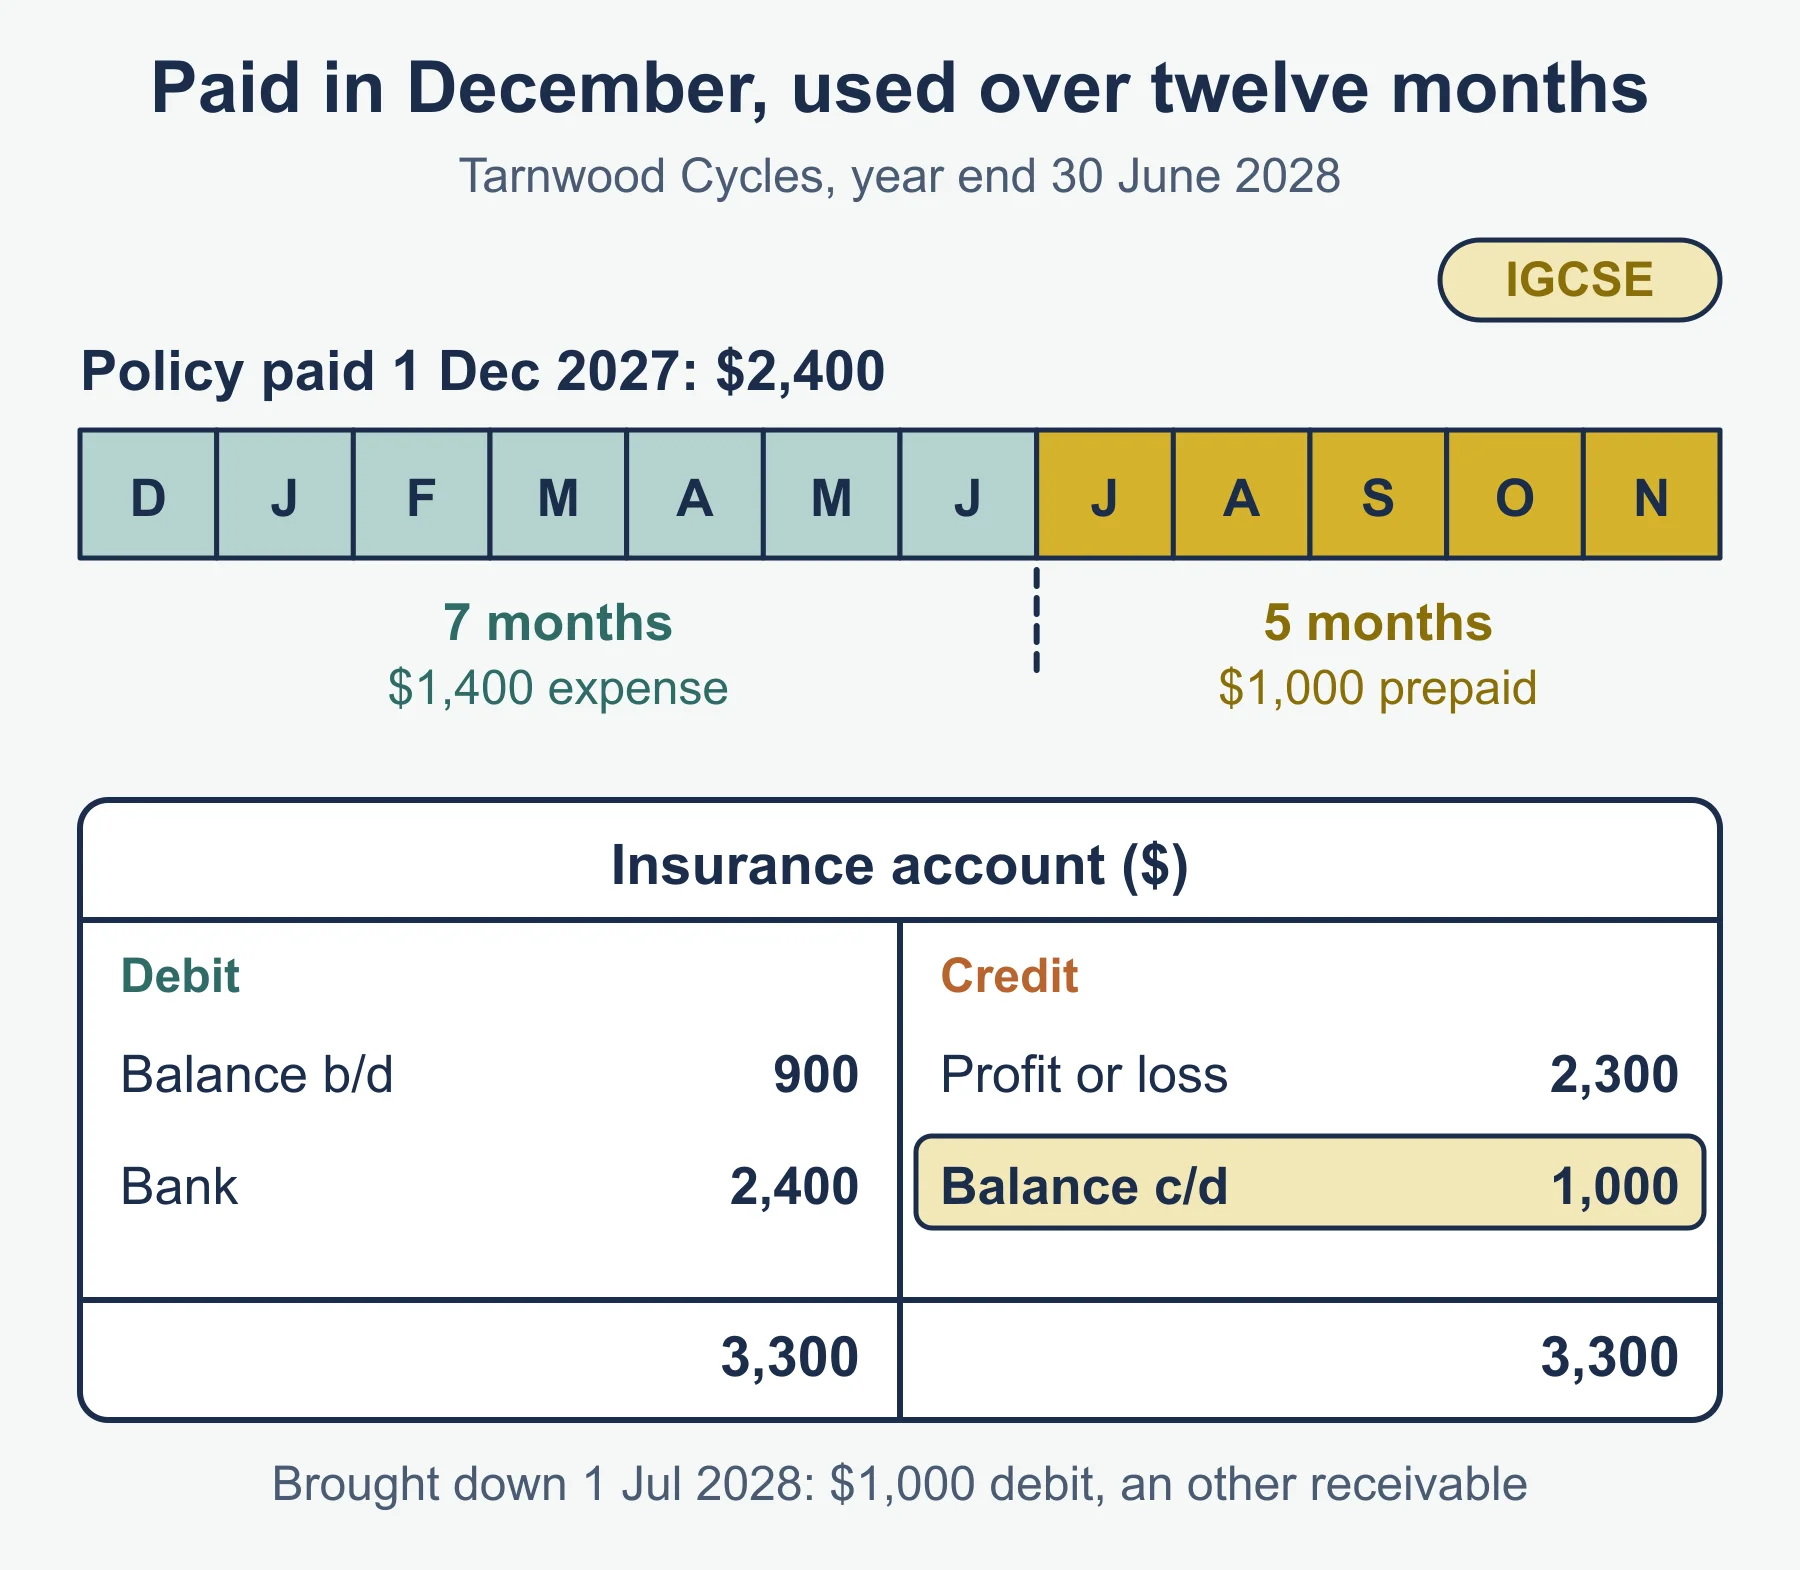
| Prepaid expense | Dr other receivables, Cr expense | Debit | Other receivables (current asset) |
| Accrued income | Dr other receivables, Cr income | Debit | Other receivables (current asset) |
| Income received in advance | Dr income, Cr other payables | Credit | Other payables (current liability) |
Expense for the year = paid − opening accrual + closing accrual (+ opening prepayment − closing prepayment). In the ledger, the transfer to the statement of profit or loss is the balancing figure once the opening balance, the cash and the closing balance c/d are in.
4.4 Irrecoverable debts and allowance for irrecoverable debts
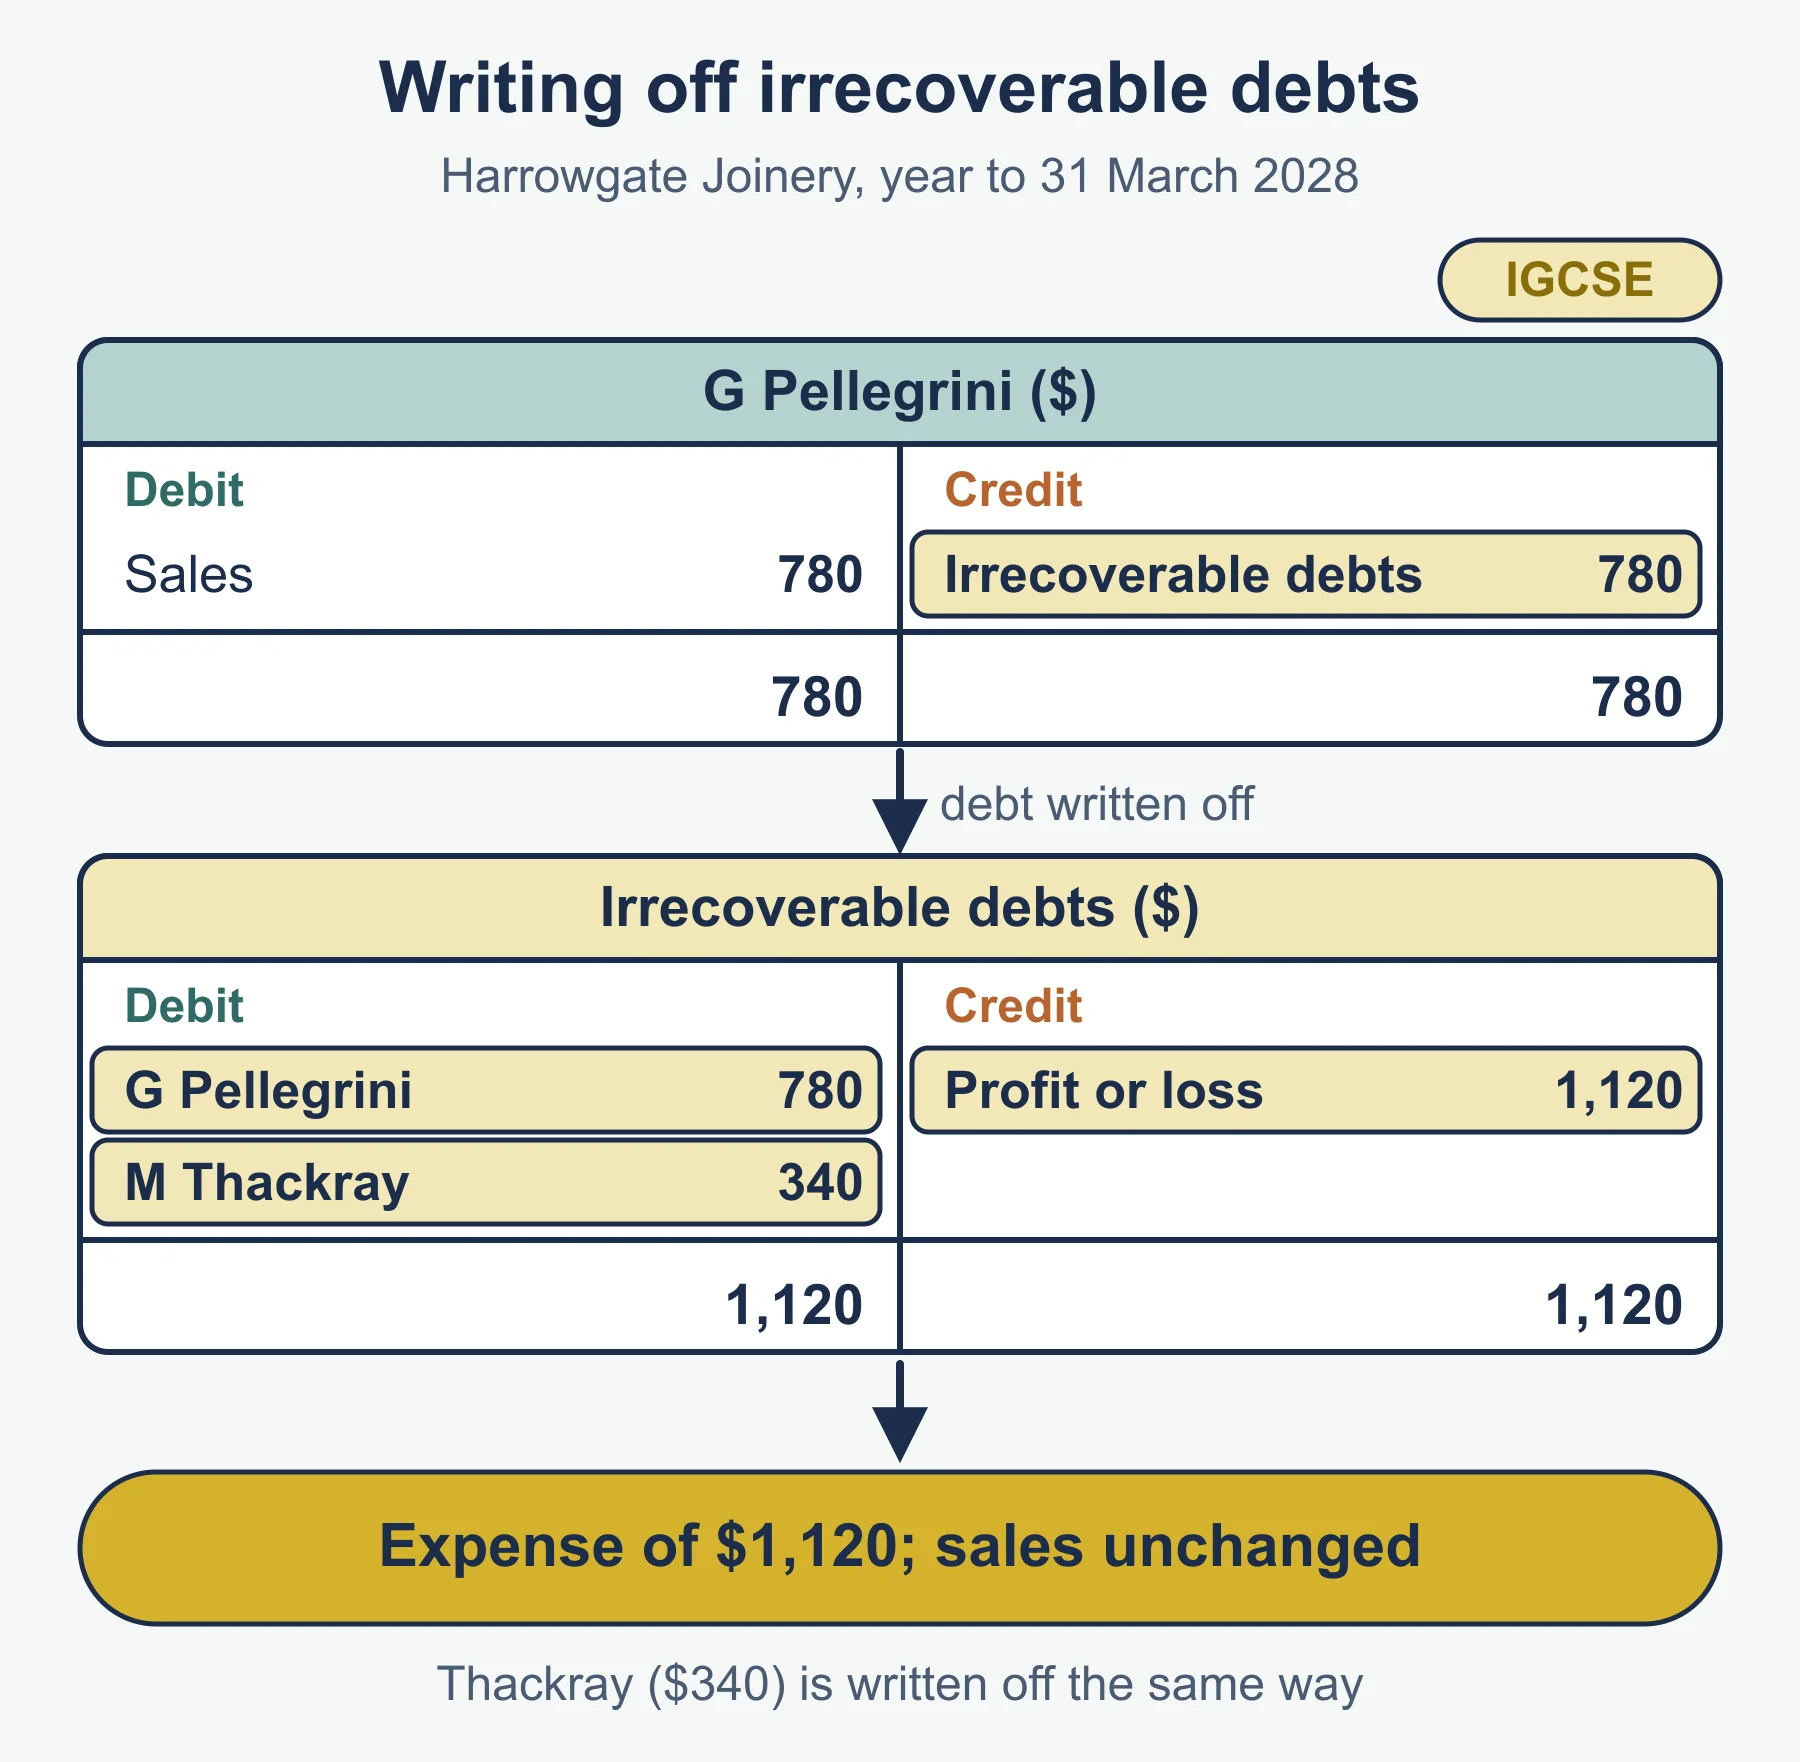
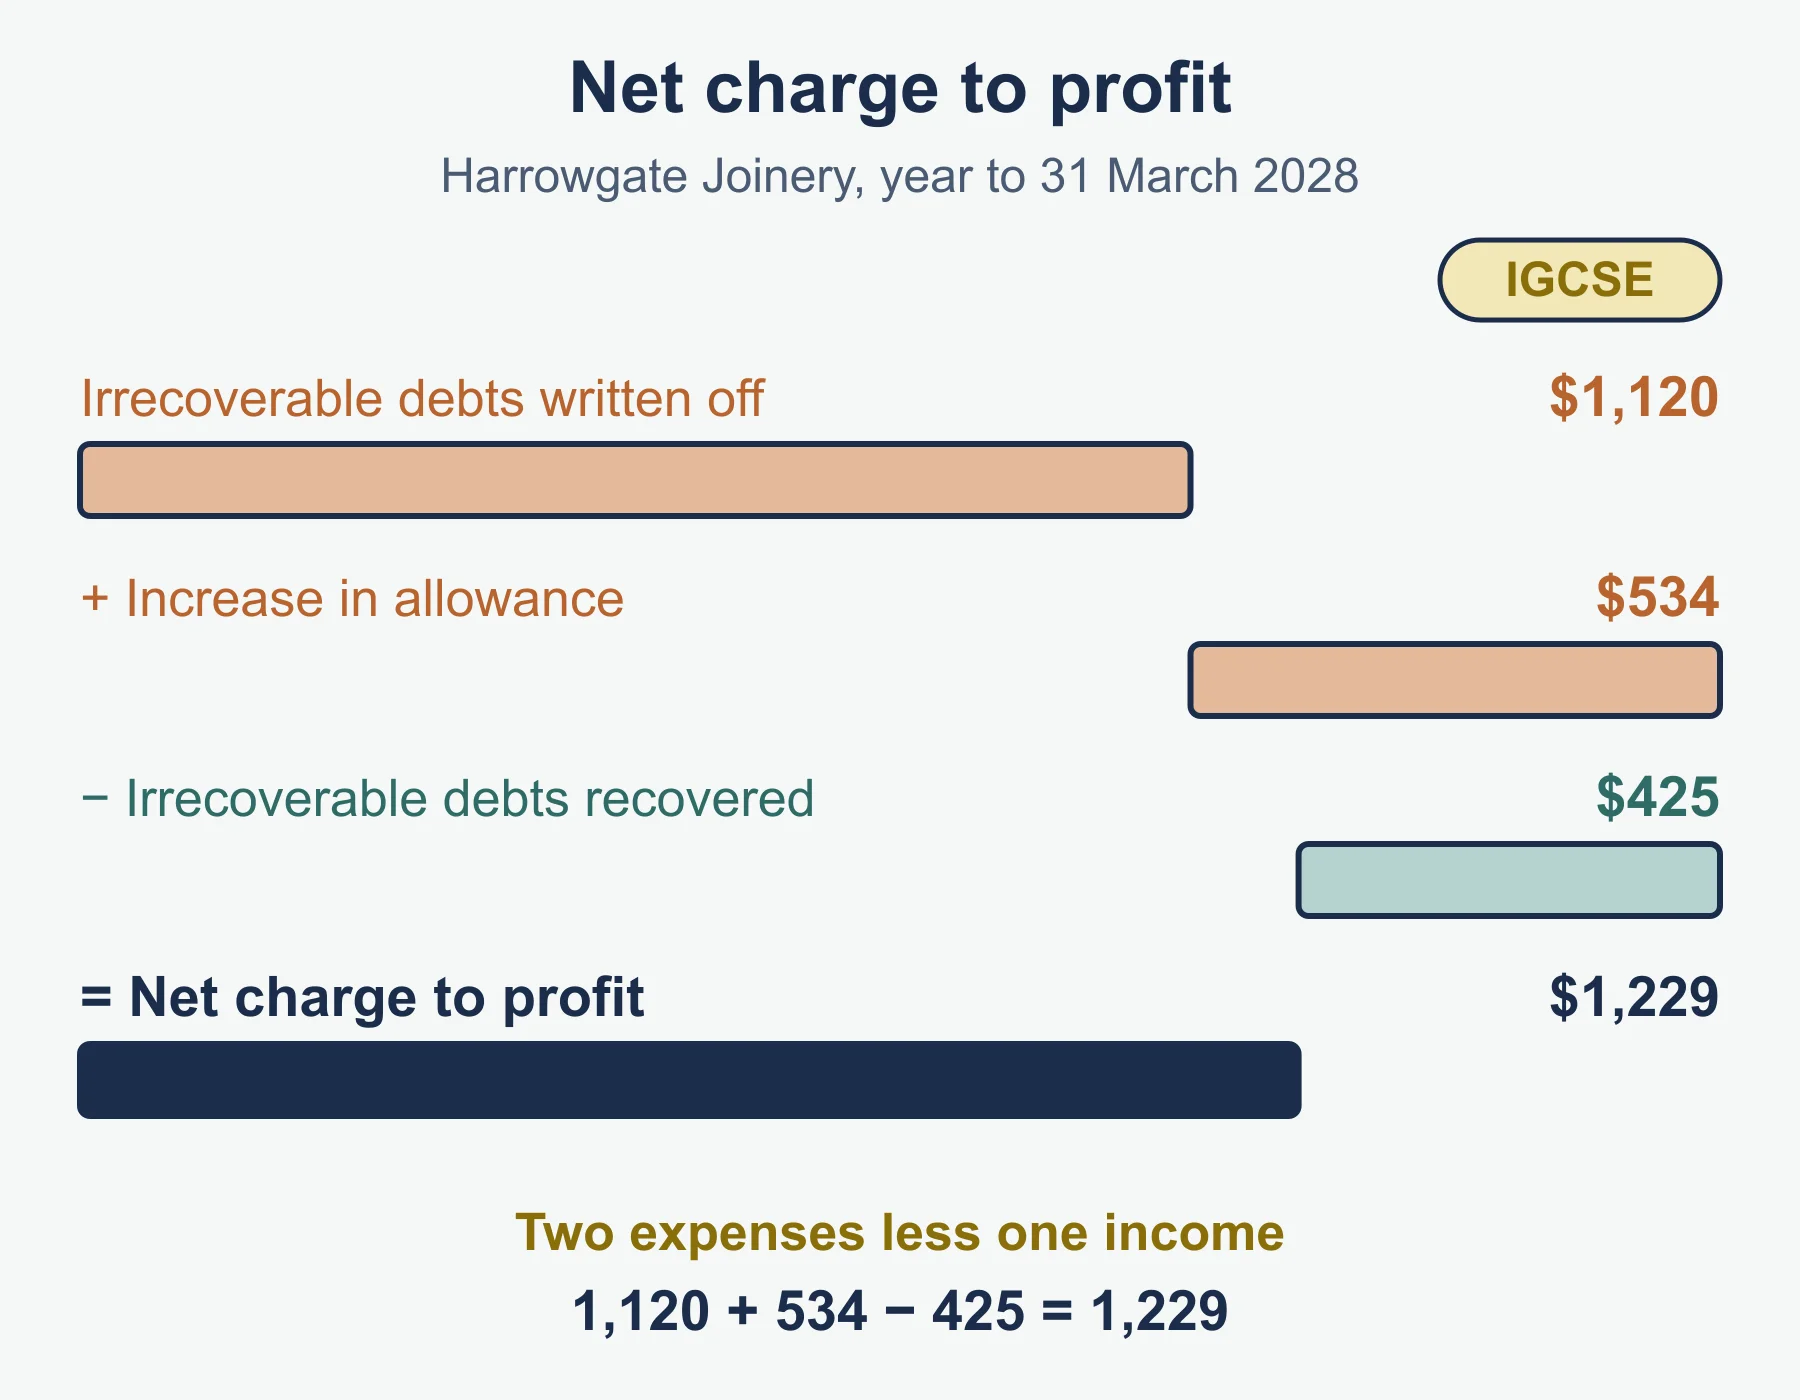
- Irrecoverable debt: Dr irrecoverable debts, Cr customer. Year end: Dr statement of profit or loss, Cr irrecoverable debts (expense).
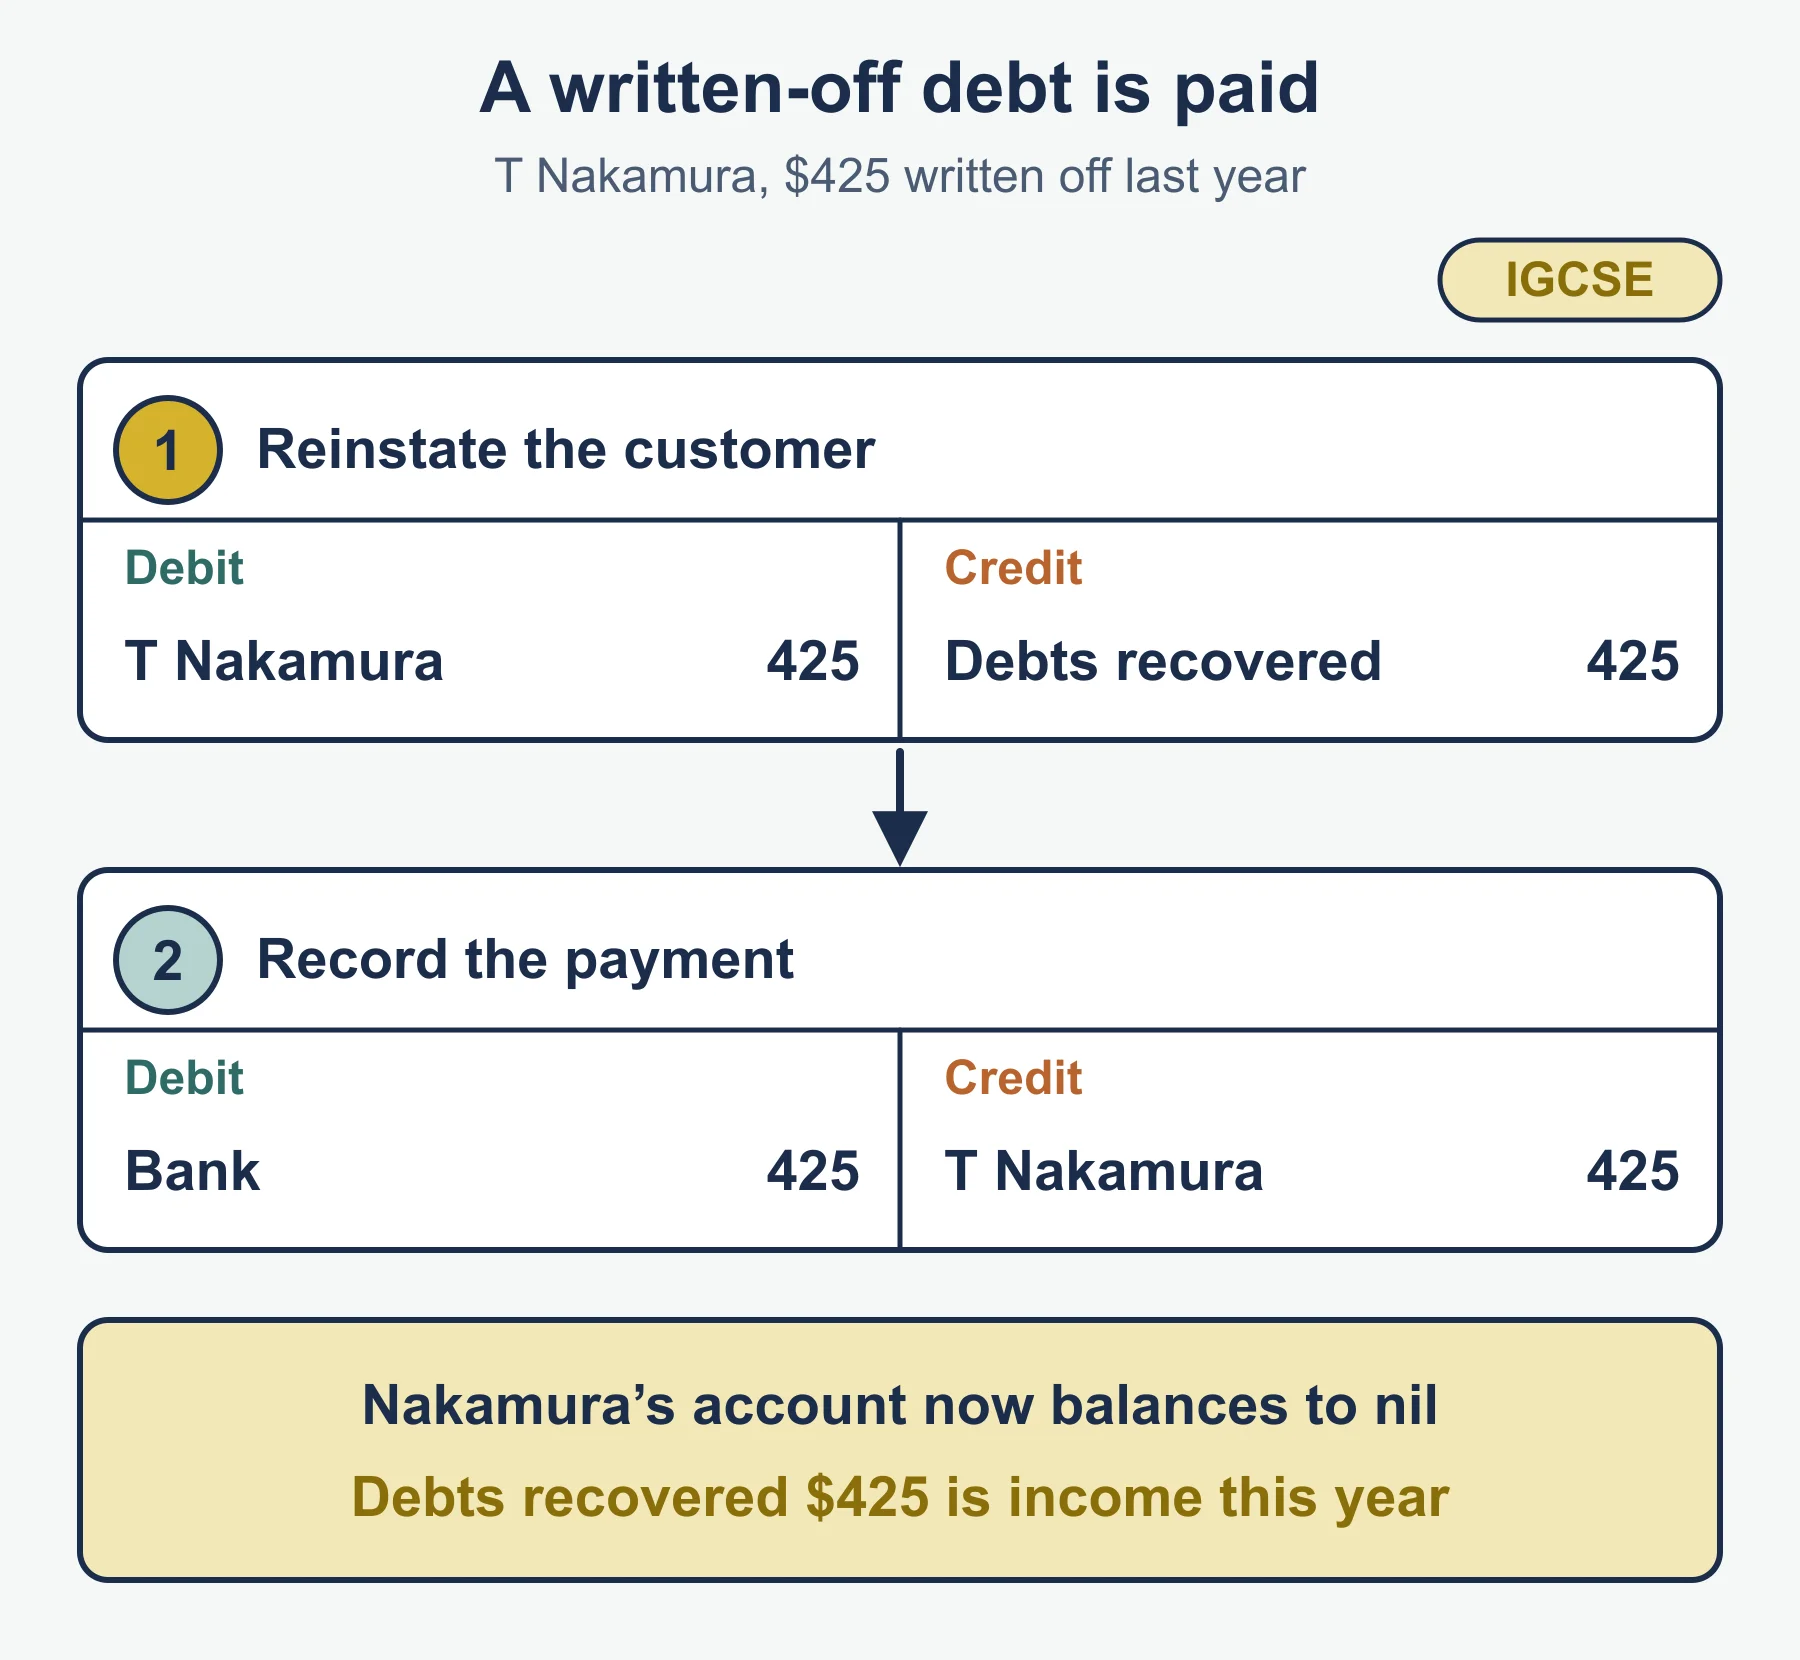
- Irrecoverable debt recovered: reinstate — Dr customer, Cr irrecoverable debts recovered; then receipt — Dr bank, Cr customer. Year end: the recovery is income in the statement of profit or loss.
- Allowance for irrecoverable debts: an estimate of trade receivables
that may not be collected, kept for prudence and matching.
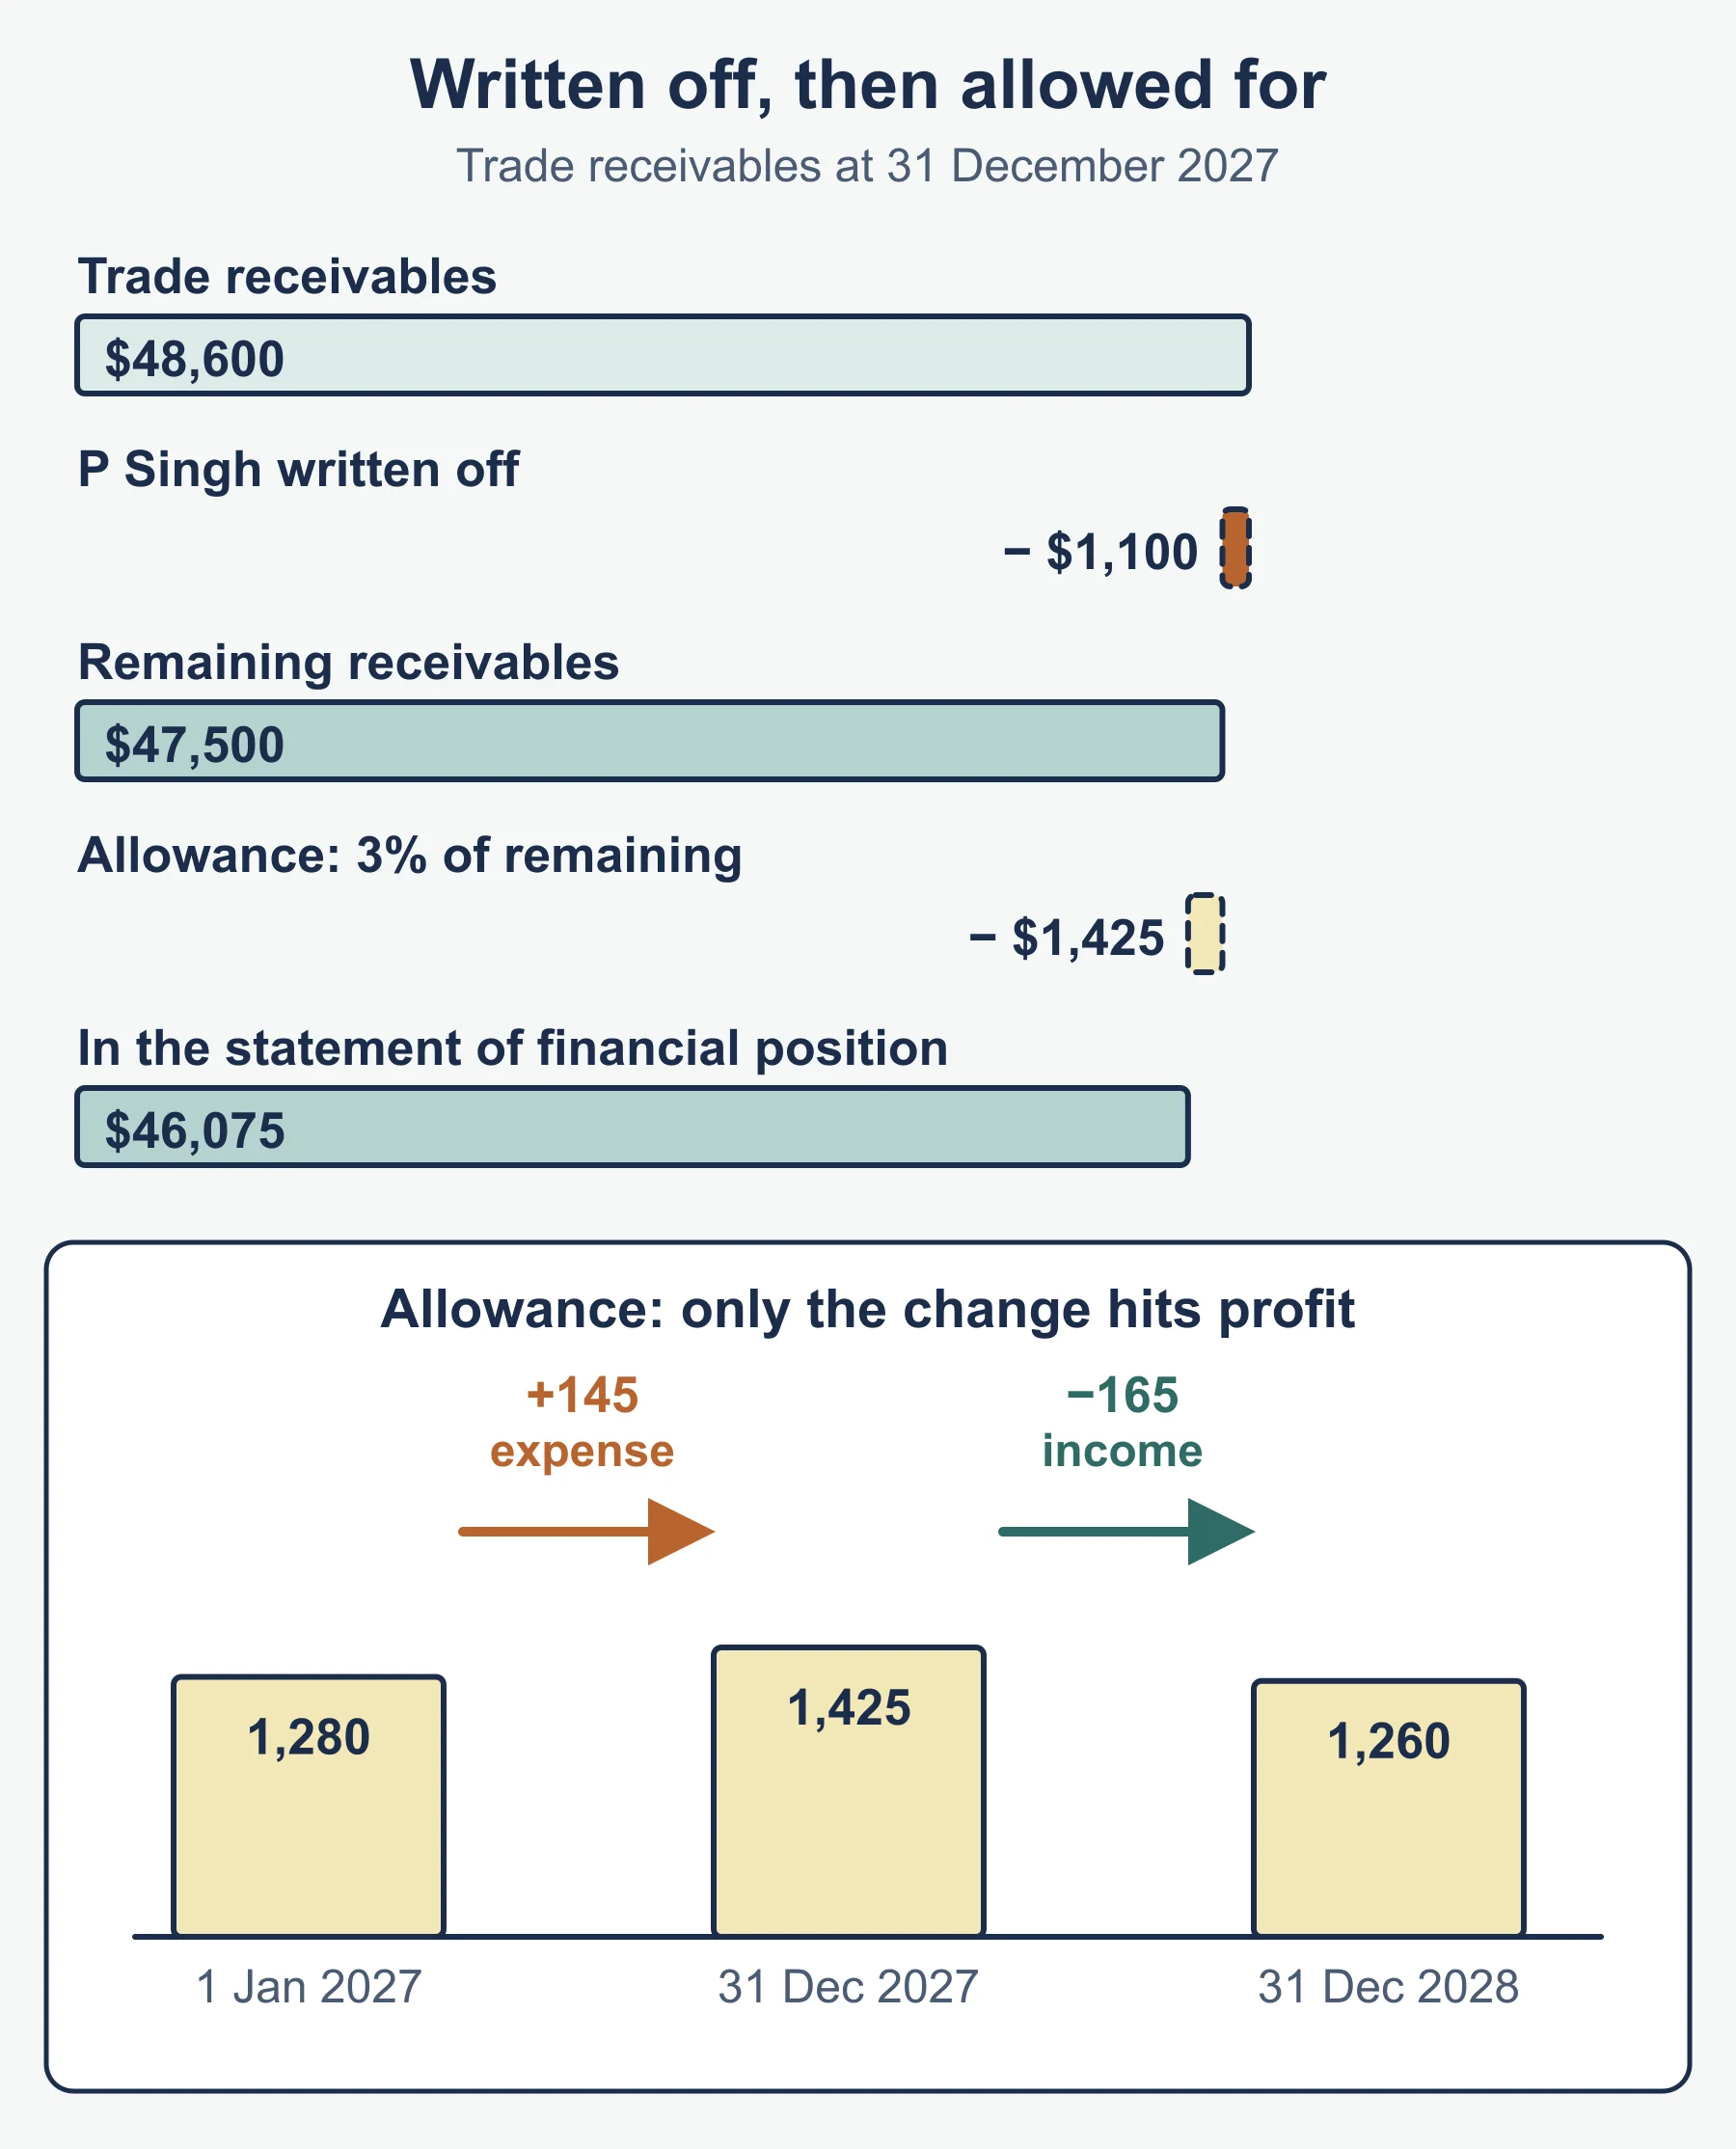
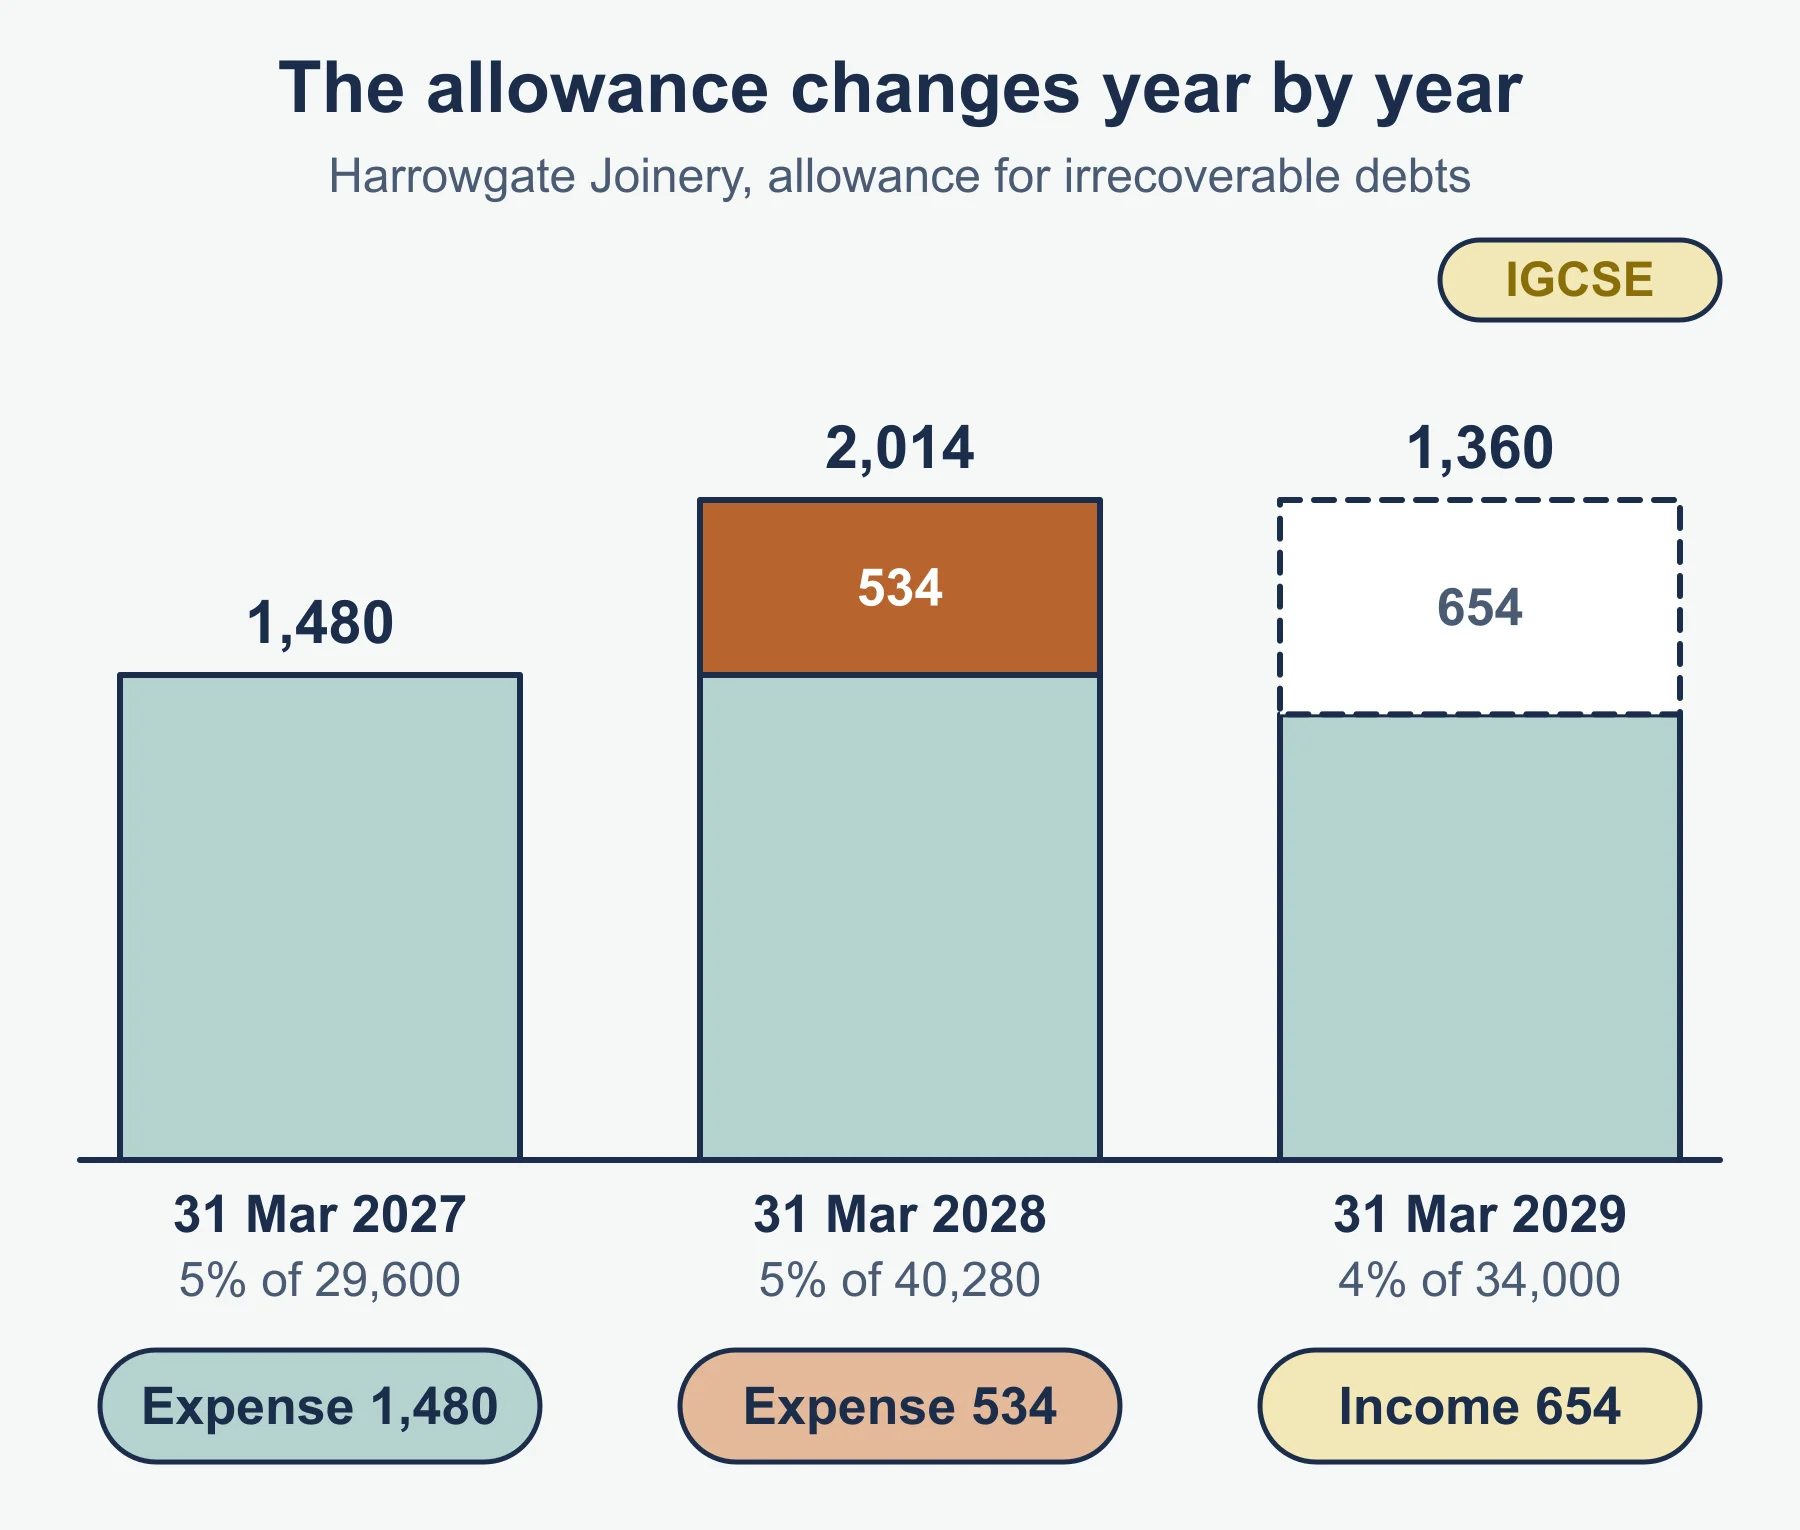
- Create or increase: Dr statement of profit or loss, Cr allowance (only the new amount or the increase is an expense).
- Decrease: Dr allowance, Cr statement of profit or loss (income).
- Statement of financial position: trade receivables less the full allowance.
- Write off irrecoverable debts before calculating a percentage allowance on the remaining trade receivables.
4.5 Valuation of inventory
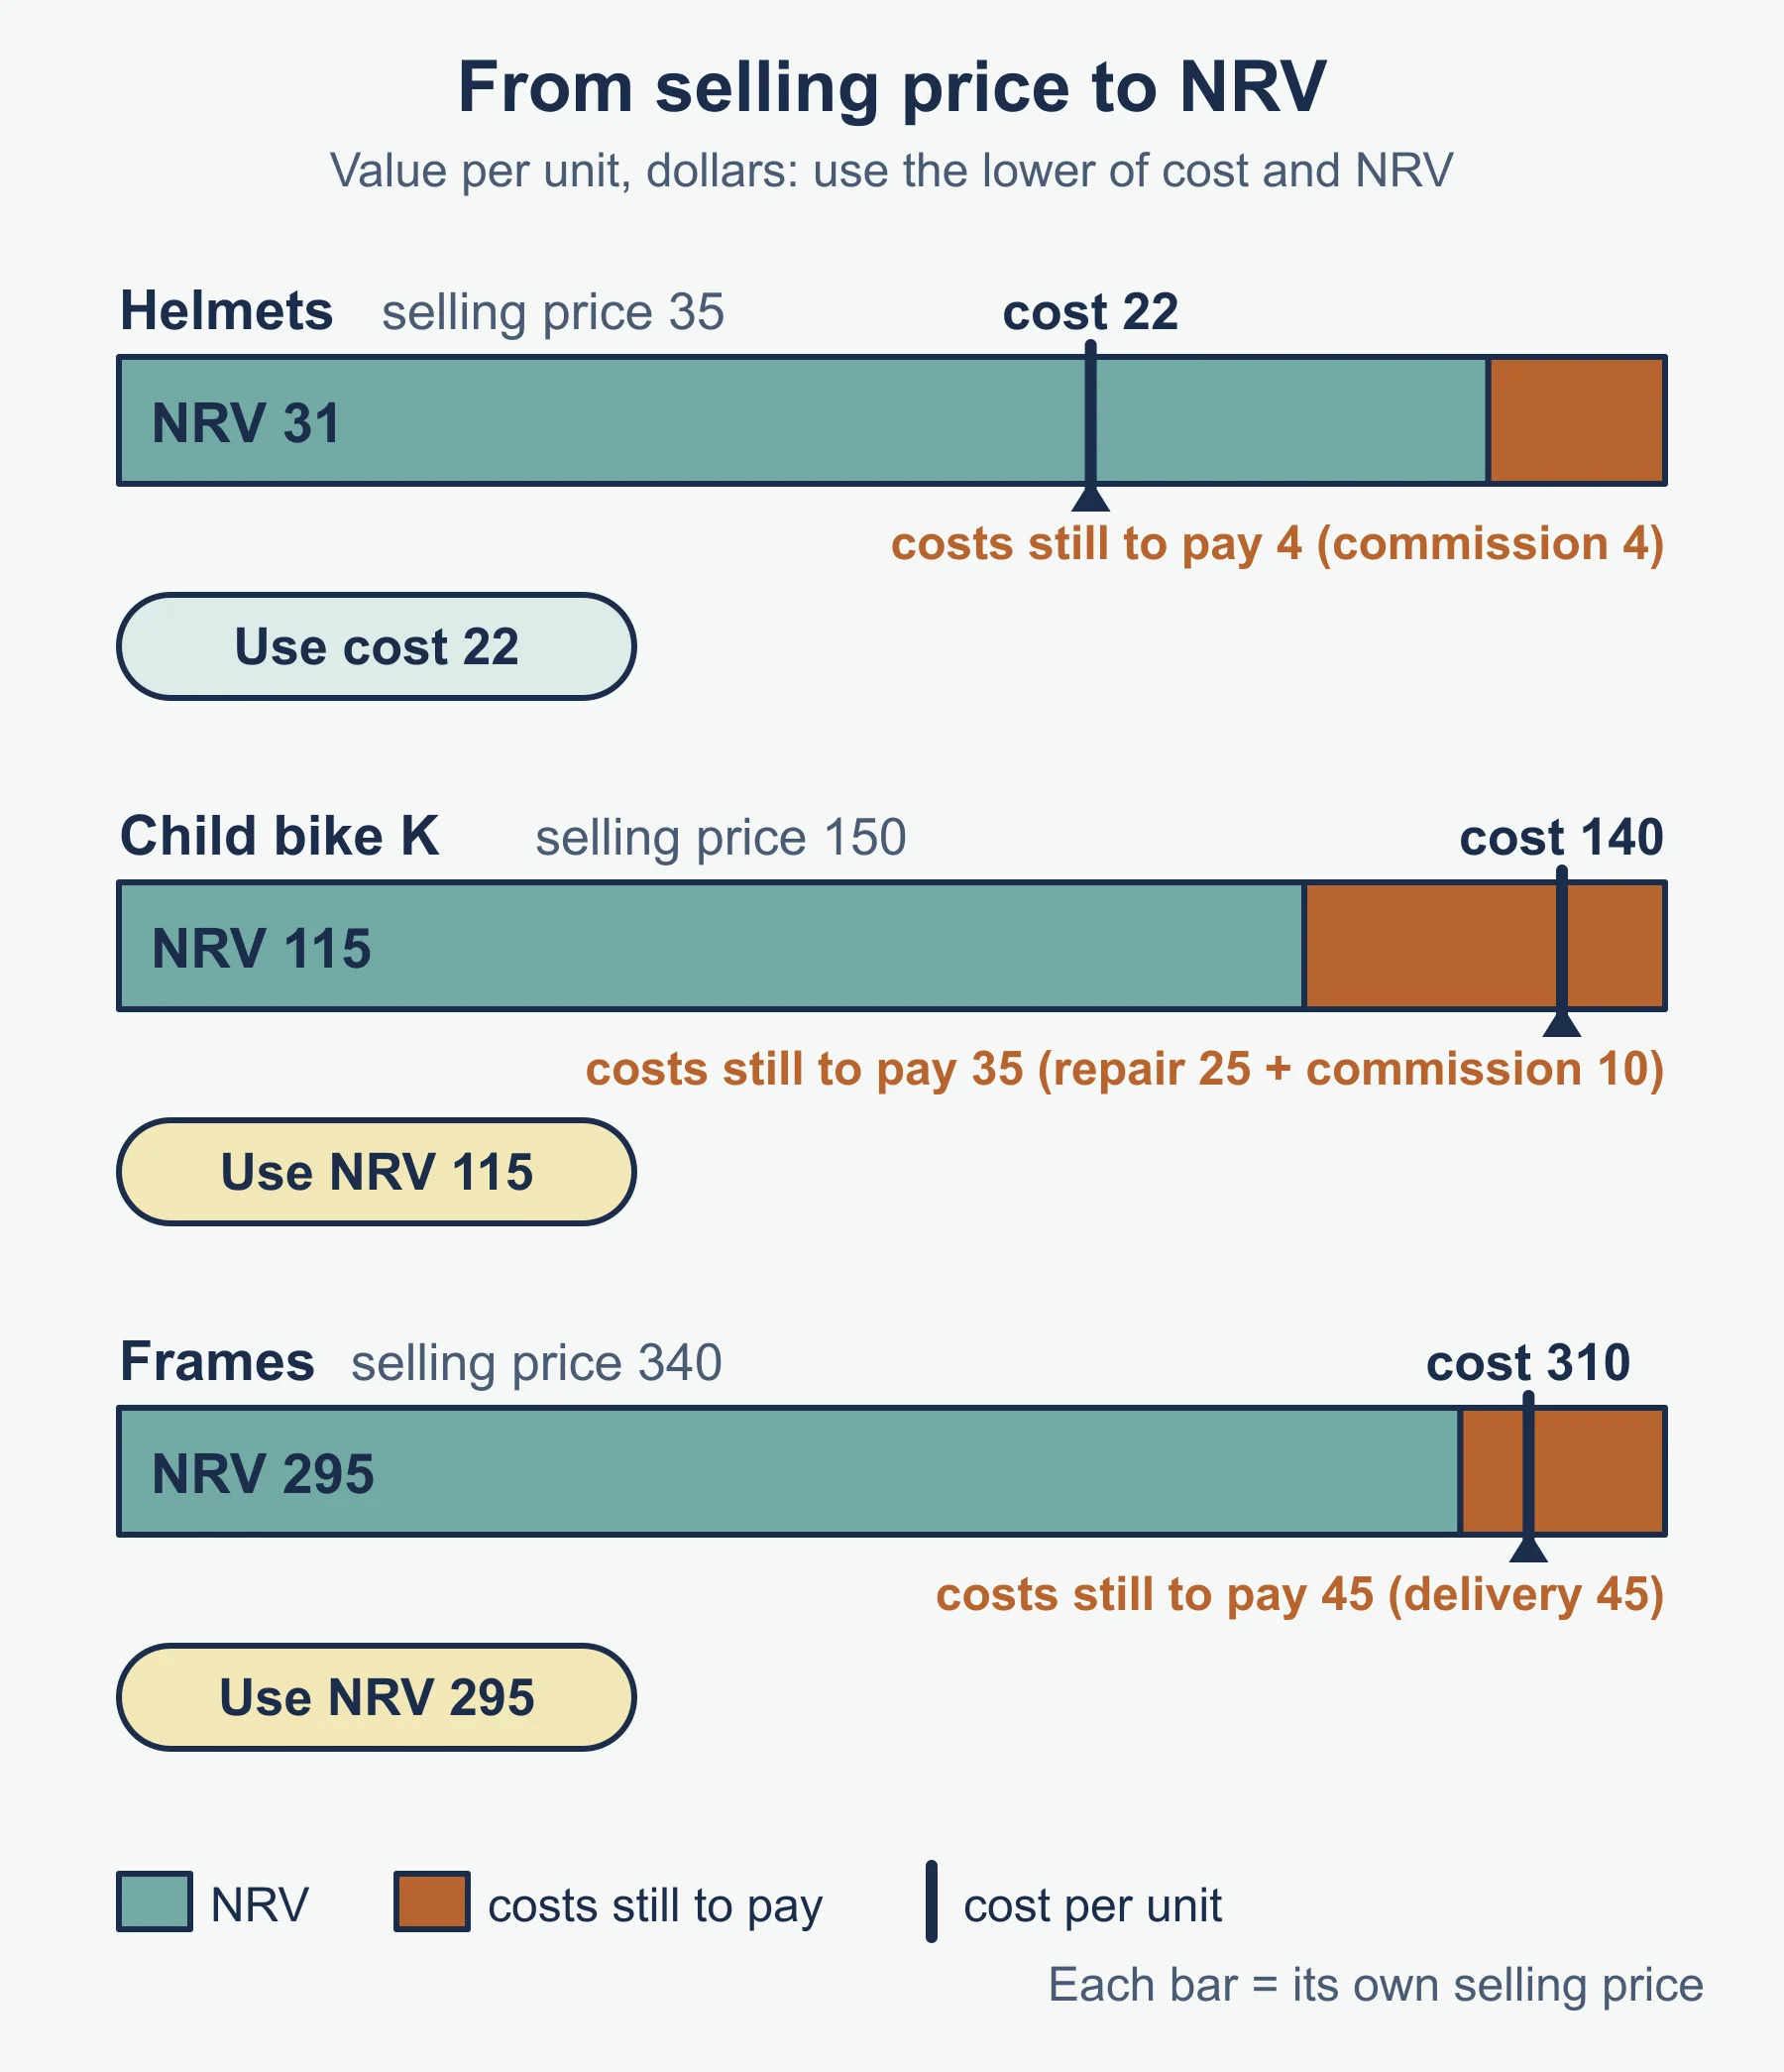
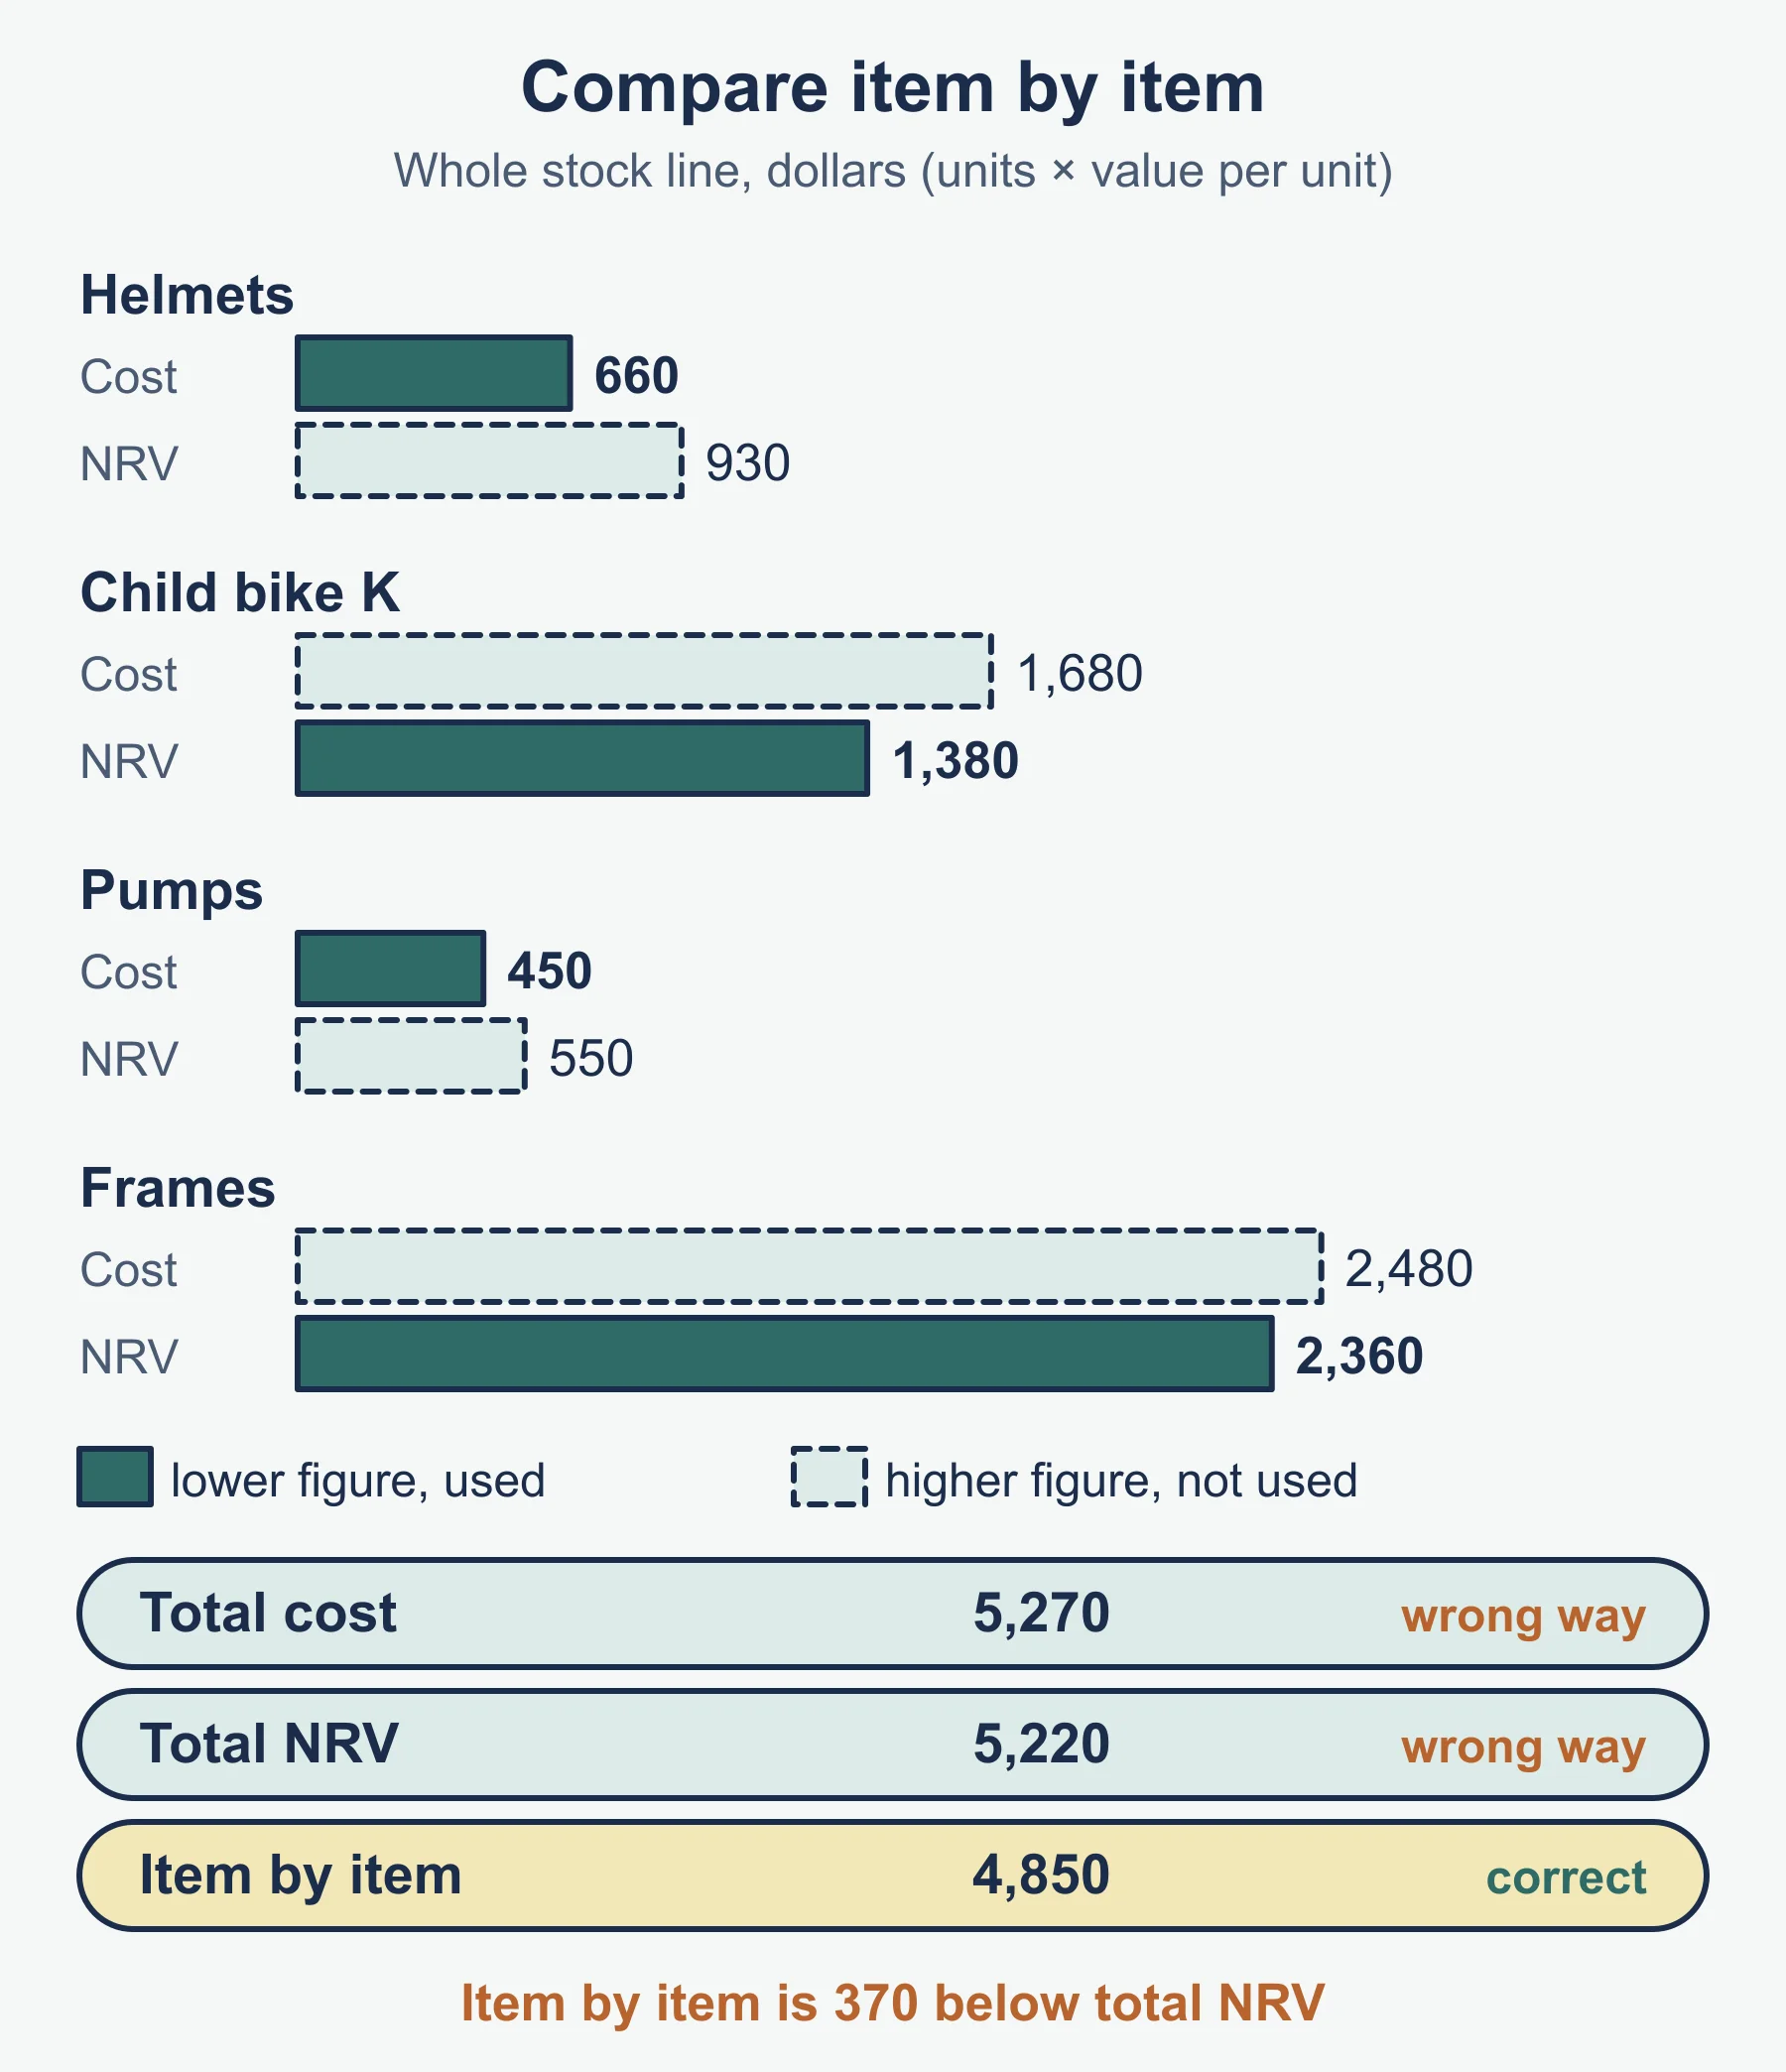
- Lower of cost and net realisable value, item by item.
- Net realisable value = expected selling price − costs still to be paid to complete and sell the goods.
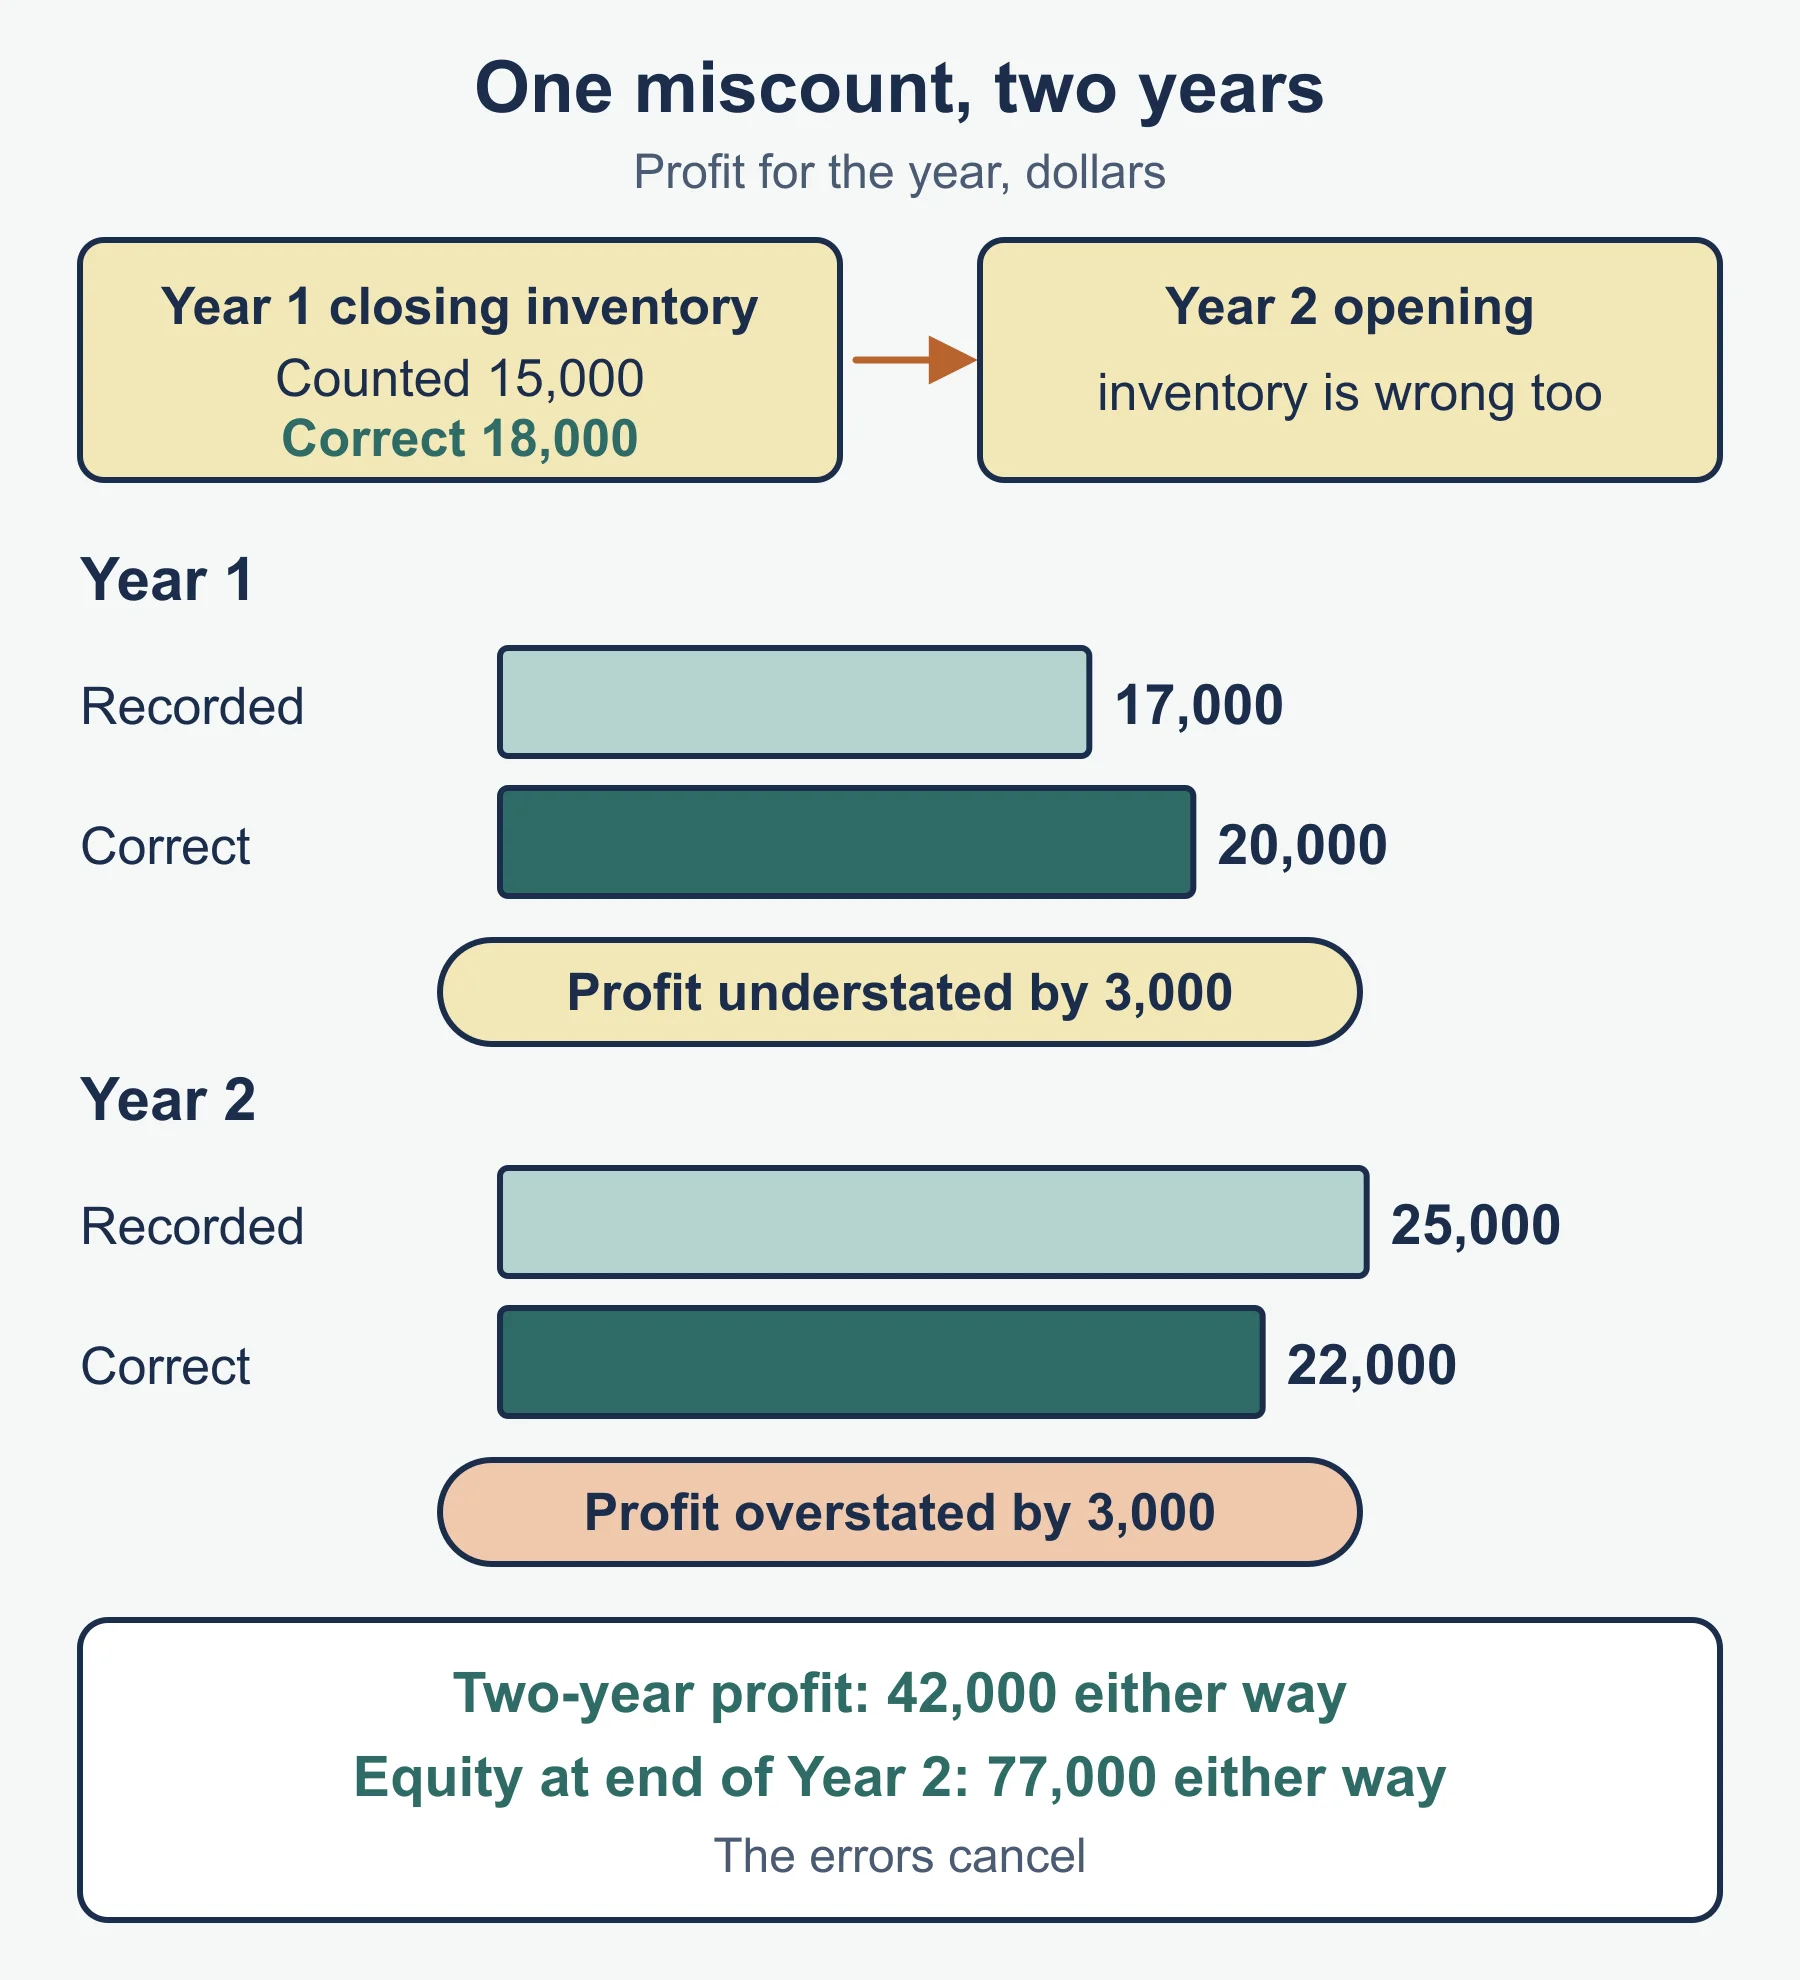
| Closing inventory | Gross profit | Profit for the year | Equity | Current assets |
|---|---|---|---|---|
| Overstated | Overstated | Overstated | Overstated | Overstated |
| Understated | Understated | Understated | Understated | Understated |
Next year: the wrong figure becomes opening inventory, so the next year’s gross profit and profit for the year move by the same amount in the opposite direction.
Worked example: loss on disposal
A machine bought for $15,000 is depreciated at 20% per year on cost. It is sold for $5,200 after three full years’ depreciation.
Accumulated depreciation   3 × 20% × $15,000   =  $9,000
Net book value             $15,000 − $9,000    =  $6,000
Loss on disposal           $6,000 − $5,200     =    $800

Disposal account
  Debit side:   Machinery (cost)                      15,000
  Credit side:  Provision for depreciation             9,000
                Bank (proceeds)                        5,200
                Statement of profit or loss (loss)       800
                                                      ------
                Credit side total                     15,000
Exam traps
- Treating repairs as capital expenditure, or delivery and installation costs of a new asset as revenue expenditure.
- Applying the reducing balance percentage to cost every year.
- Comparing disposal proceeds with cost instead of net book value.
- Crediting depreciation to the asset account instead of the provision for depreciation account.
- Bringing an accrued expense down as a debit or a prepayment down as a credit.
- Charging the whole allowance for irrecoverable debts each year instead of only the change.
- Calculating the allowance before writing off the year’s irrecoverable debts.
- Comparing total cost with total net realisable value instead of item by item.
- Forgetting the knock-on effect of a closing inventory error on the next year’s profit.
Self-test
- Classify as capital or revenue: (a) installation of a new machine; (b) proceeds from selling an old vehicle; (c) commission received.
- Loose tools are valued at $900 at the start of the year, $420 of tools are bought, and they are valued at $780 at the end. Calculate depreciation.
- A vehicle costs $20,000 and is depreciated at 20% reducing balance. Calculate the depreciation for the second year.
- State the journal entry for a loss on disposal of a non-current asset.
- Electricity of $2,600 was paid in the year. $180 was owing at the start and $250 at the end. Calculate the charge to the statement of profit or loss.
- Trade receivables are $18,000 and the allowance is to be 5%. The opening allowance is $1,000. State the effect on the statement of profit or loss.
- Closing inventory is understated by $600. State the effect on profit for the year, and on next year’s gross profit.
- 200 units cost $14 each and have a net realisable value of $11 each. Calculate their inventory value.
Answers: 1. (a) capital expenditure; (b) capital receipt; (c) revenue receipt. 2. $900 + $420 − $780 = $540. 3. First year $4,000, net book value $16,000; second year 20% × $16,000 = $3,200. 4. Dr statement of profit or loss, Cr disposal of non-current asset. 5. $2,600 − $180 + $250 = $2,670. 6. Required allowance 5% × $18,000 = $900, a decrease of $100, which is income in the statement of profit or loss. 7. Profit for the year is understated by $600; next year’s gross profit is overstated by $600 because opening inventory is understated. 8. 200 × $11 = $2,200 (net realisable value is lower than cost).
Frequently asked questions
How do you calculate the profit or loss on disposal of a non-current asset? Profit or loss on disposal equals the sale proceeds minus the net book value at the date of disposal. Net book value is cost minus accumulated depreciation.
What is the double entry for depreciation in Cambridge IGCSE Accounting 0452? Debit the statement of profit or loss and credit the provision for depreciation account. The provision builds up as accumulated depreciation, which is deducted from cost in the statement of financial position.
How is inventory valued in Cambridge IGCSE Accounting? Inventory is valued at the lower of cost and net realisable value, item by item. Net realisable value is the expected selling price minus the costs still to be paid to complete and sell the goods.
What happens next year if closing inventory is valued wrongly? The wrong figure becomes the next year’s opening inventory, so next year’s gross profit and profit for the year move by the same amount in the opposite direction.
What is the effect of treating revenue expenditure as capital expenditure? Profit is overstated and non-current assets are overstated. If the wrongly capitalised amount has been depreciated, the overstatement is the amount less the depreciation charged on it.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Revision notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
Accounting · Cambridge · IGCSE, O Level
Revise topic -
Study guides
IGCSE Accounting: Valuation of inventory (Cambridge 0452)
Study guide to Cambridge IGCSE Accounting 0452 section 4.5: lower of cost and net realisable value, count adjustments and inventory errors.
Accounting · Cambridge · IGCSE, O Level
Read guide -
Practice questions
IGCSE Accounting: Valuation of inventory (Cambridge 0452) – Practice Questions
Original practice questions with worked answers on Cambridge IGCSE Accounting 0452 section 4.5: lower of cost and NRV, count dates and inventory errors.
Accounting · Cambridge · IGCSE, O Level
Try questions
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

