
Revision Notes
AQA GCSE Economics: Money and the financial sector (8136) – Revision Notes
Condensed AQA GCSE Economics revision notes for 3.2.5.1 and 3.2.5.2: functions and definition of money, the Bank of England, banks and building societies.
- Subject
- Economics
- Level
- GCSE
- Topic
- The functions and definition of money; the Bank of England, banks and building societies
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to AQA GCSE Economics (8136), For first teaching from September 2017. Official specification .
Syllabus page (what it covers and how it is assessed): AQA GCSE Economics.
Syllabus points this page covers
8136
- 3.2.5.1 The role of money
- 3.2.5.2 The role and importance of the financial sector for the economy
Found an error? Report a correction.
Need help with this topic? Request a free trial class for GCSE Economics (8136).
These notes condense sections 3.2.5.1 The role of money and 3.2.5.2 The role and importance of the financial sector for the economy of the AQA GCSE Economics (8136) specification for first teaching from September 2017. The specification has no tiers. Saving, borrowing and interest calculations are in the interest rates revision notes, and how the Bank of England uses Bank Rate in the fiscal and monetary policy revision notes. Course links: AQA GCSE Economics hub, checklist and free diagnostics. Worked-example figures are invented unless a real UK fact is stated.
Part A: The role of money (3.2.5.1)
What money is
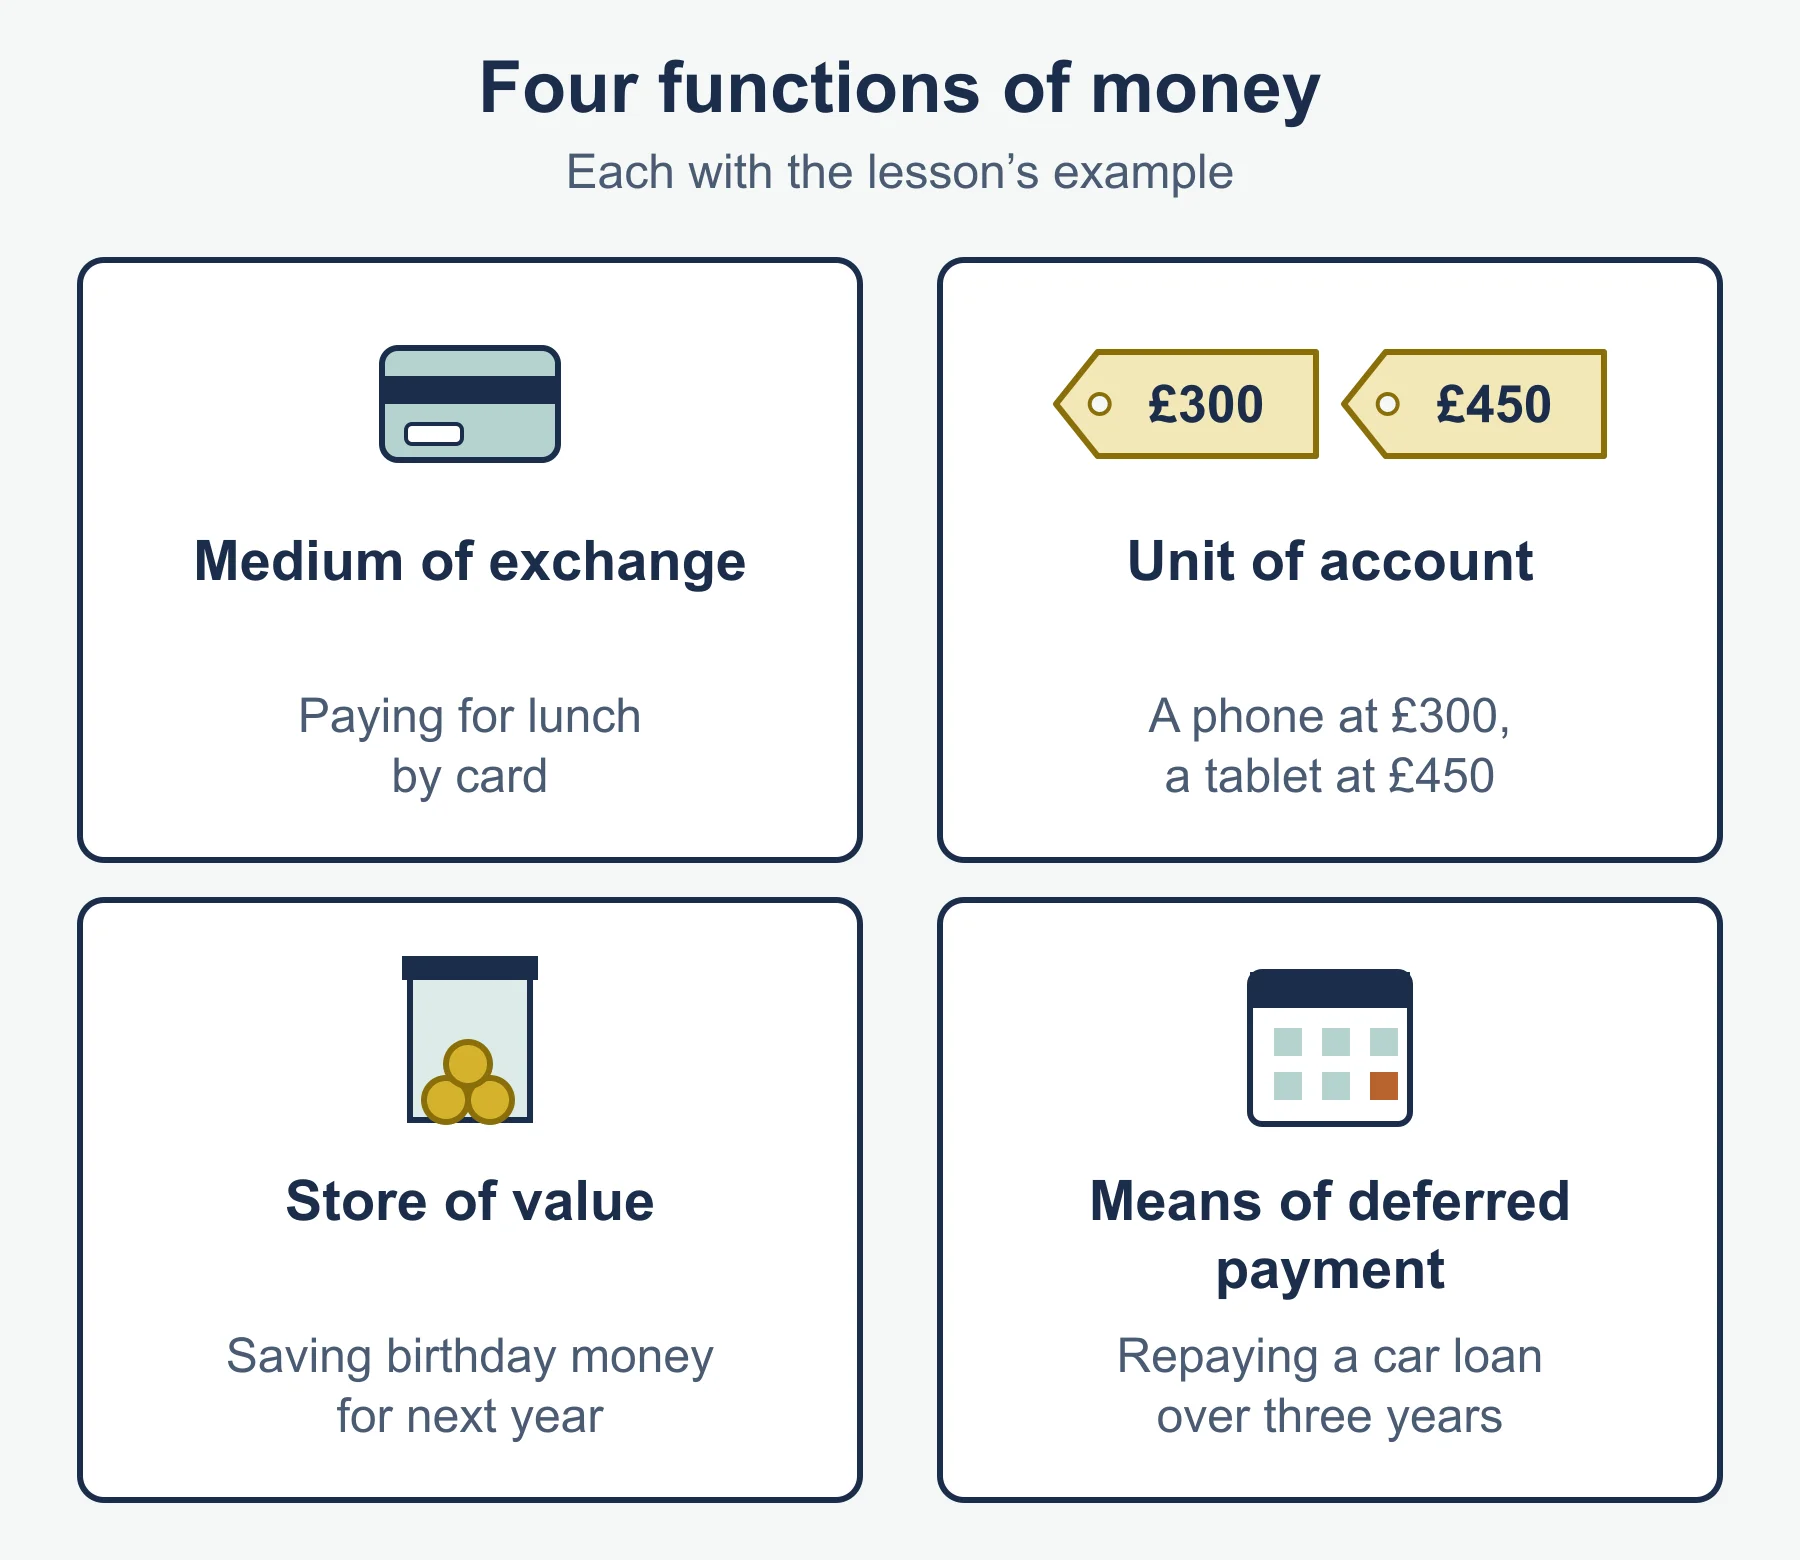
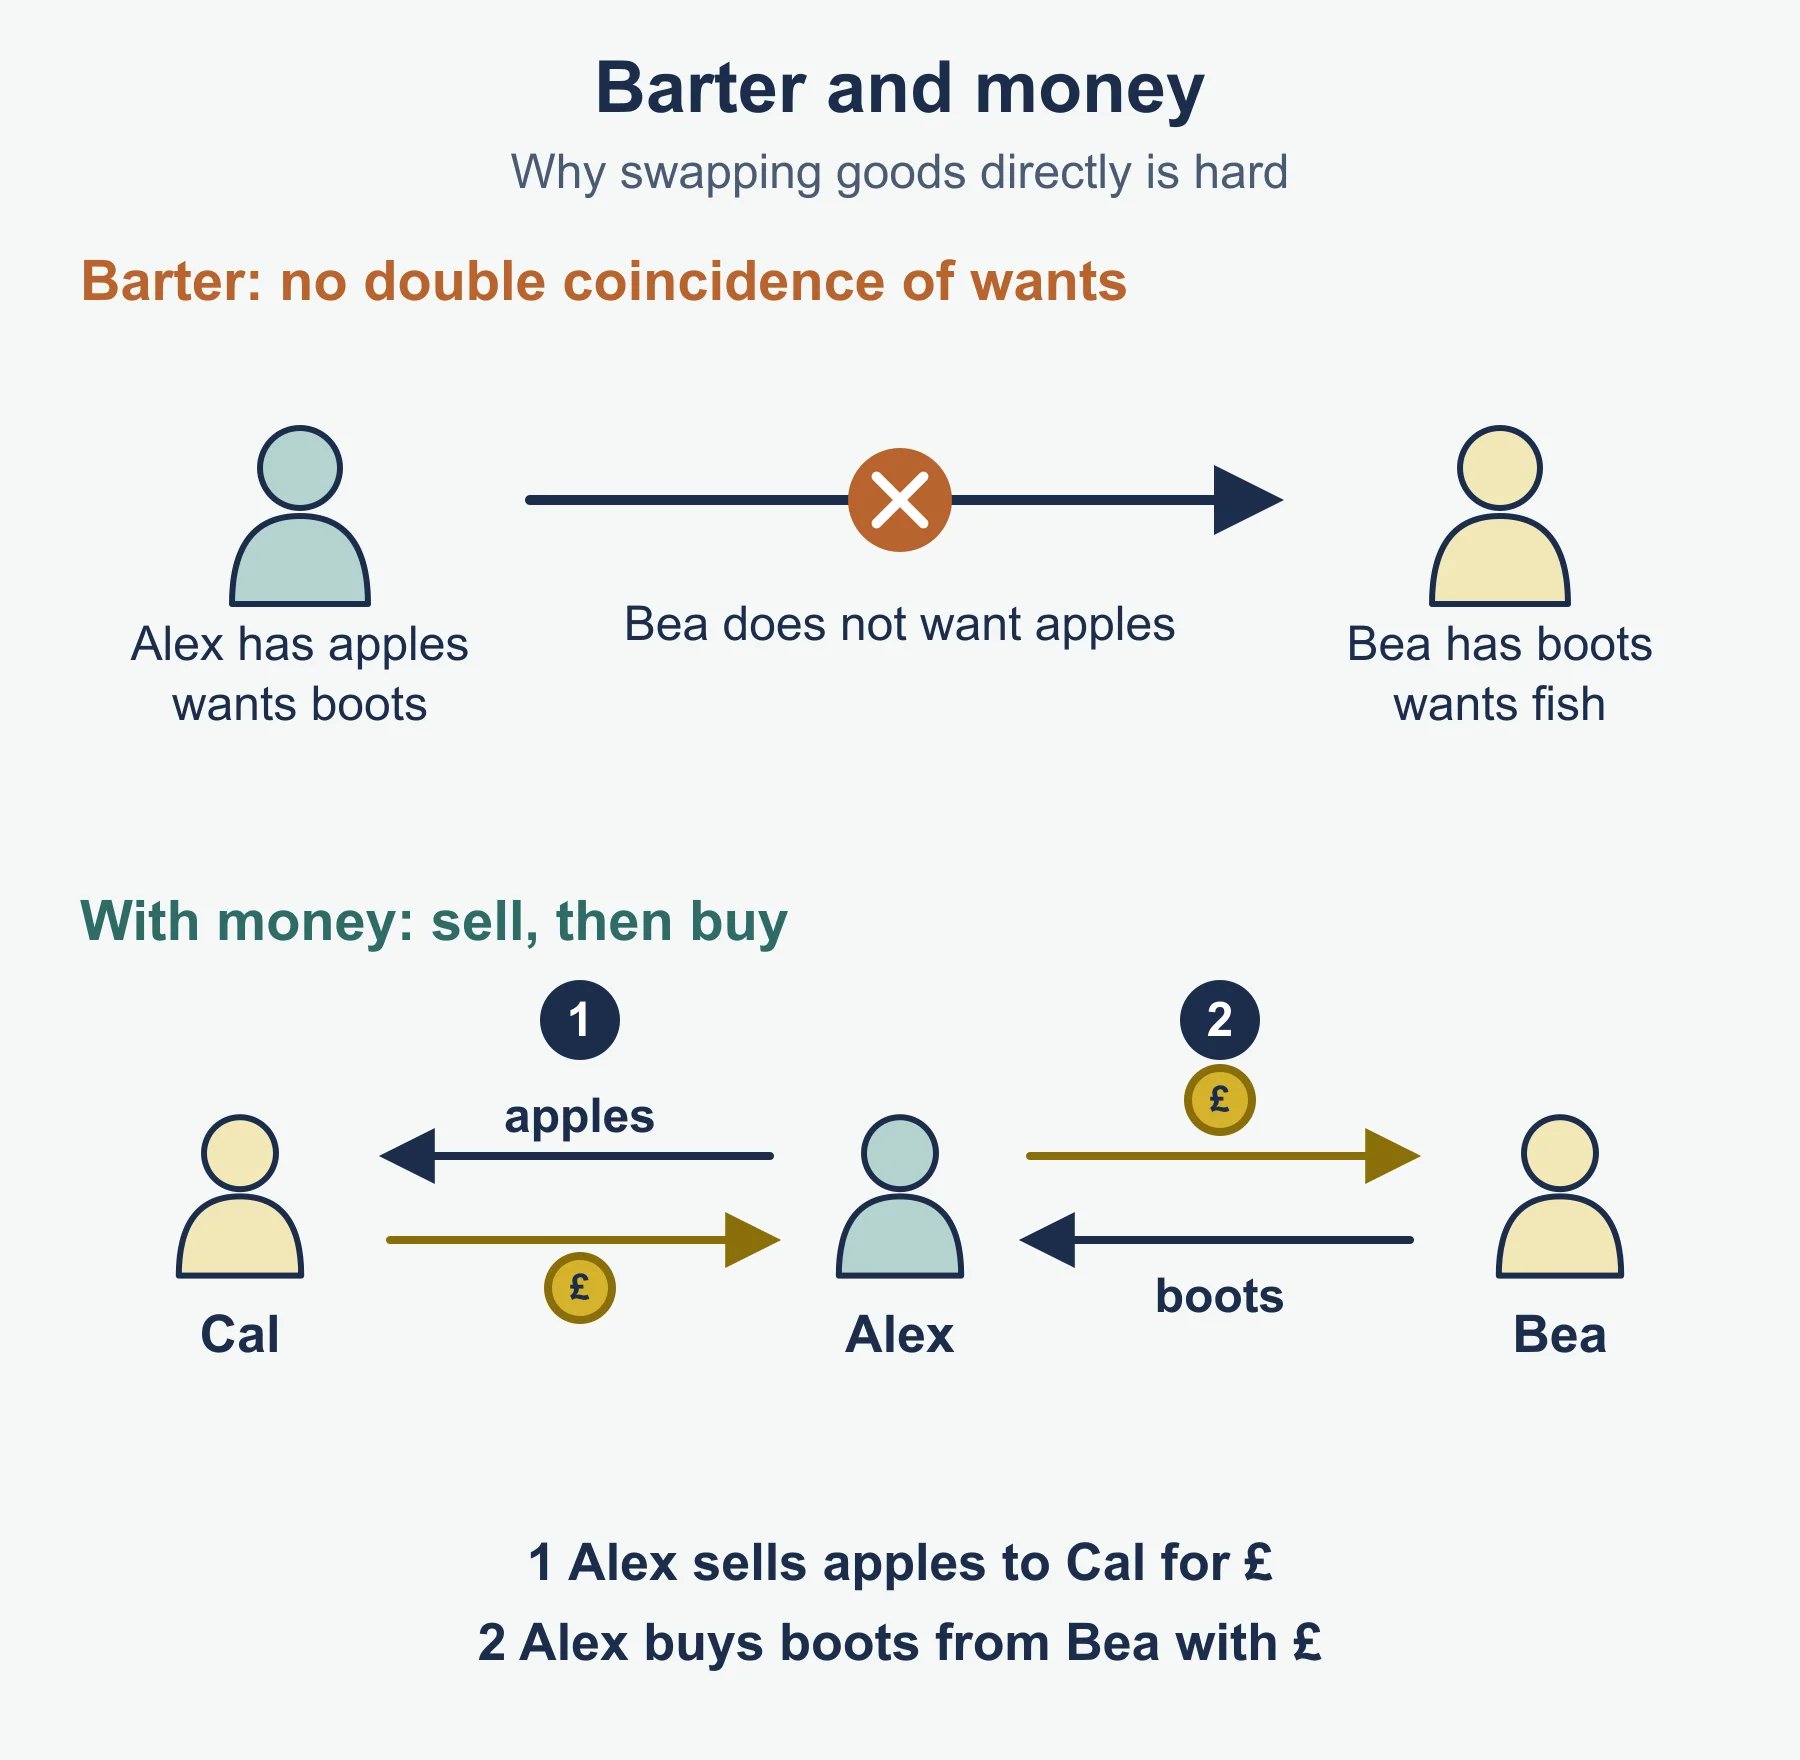
Money is anything that is generally accepted as payment for goods and services and for settling debts. Without money, people would have to barter: swap goods directly. Barter needs a double coincidence of wants (each person must want what the other offers), and it is hard to compare values or to save. Money removes these problems, which makes specialisation and trade much easier.
The four functions of money
| Function | Meaning | Example |
|---|---|---|
| Medium of exchange | Accepted in payment, so goods do not need to be swapped directly | Paying £3 for a sandwich |
| Unit of account | A common measure of value, so prices can be compared and accounts kept | A £600 phone is worth 200 sandwiches |
| Store of value | It can be kept and spent later | Saving part of your wages for a holiday next year |
| Means of deferred payment | Debts can be agreed now and repaid later in money | Repaying a car loan in monthly instalments |
Memory aid: “My Uncle Stores Dollars”: Medium, Unit, Store, Deferred.
Good money is acceptable, durable, portable, divisible, hard to forge and limited in supply.
Money is more than notes and coins
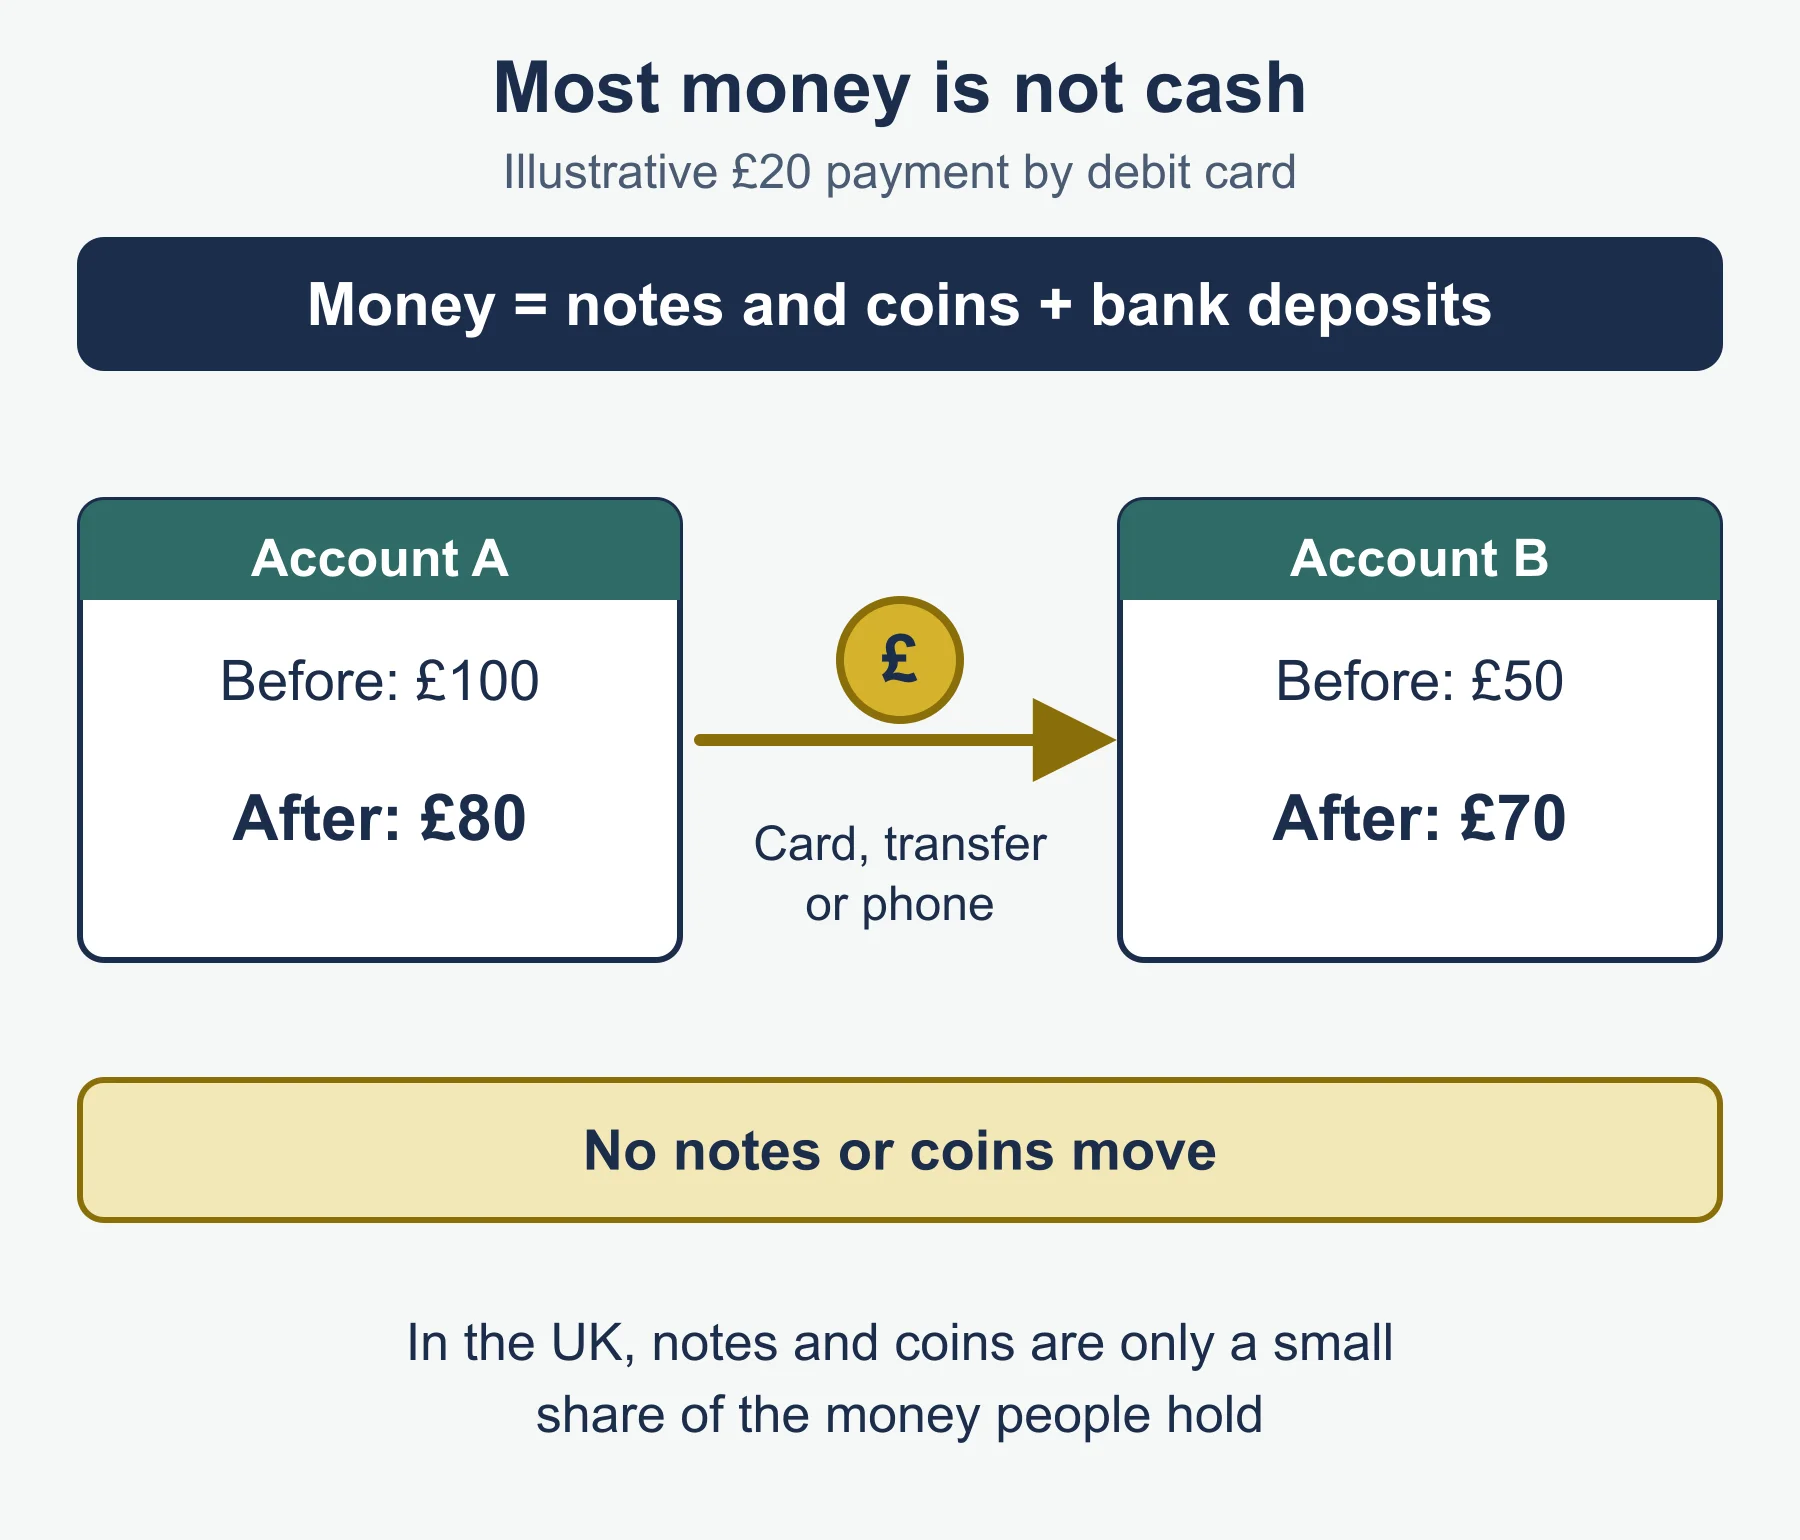
- Most money in the UK is held as bank and building society deposits, spent by debit card, contactless payment, phone or bank transfer.
- Notes and coins are only a few per cent of the total money in the UK economy.
- Most new money is created when banks make loans: the loan is paid into the borrower’s account as a new deposit.
- So a definition of money must include deposits, not just cash in circulation.
Link to inflation
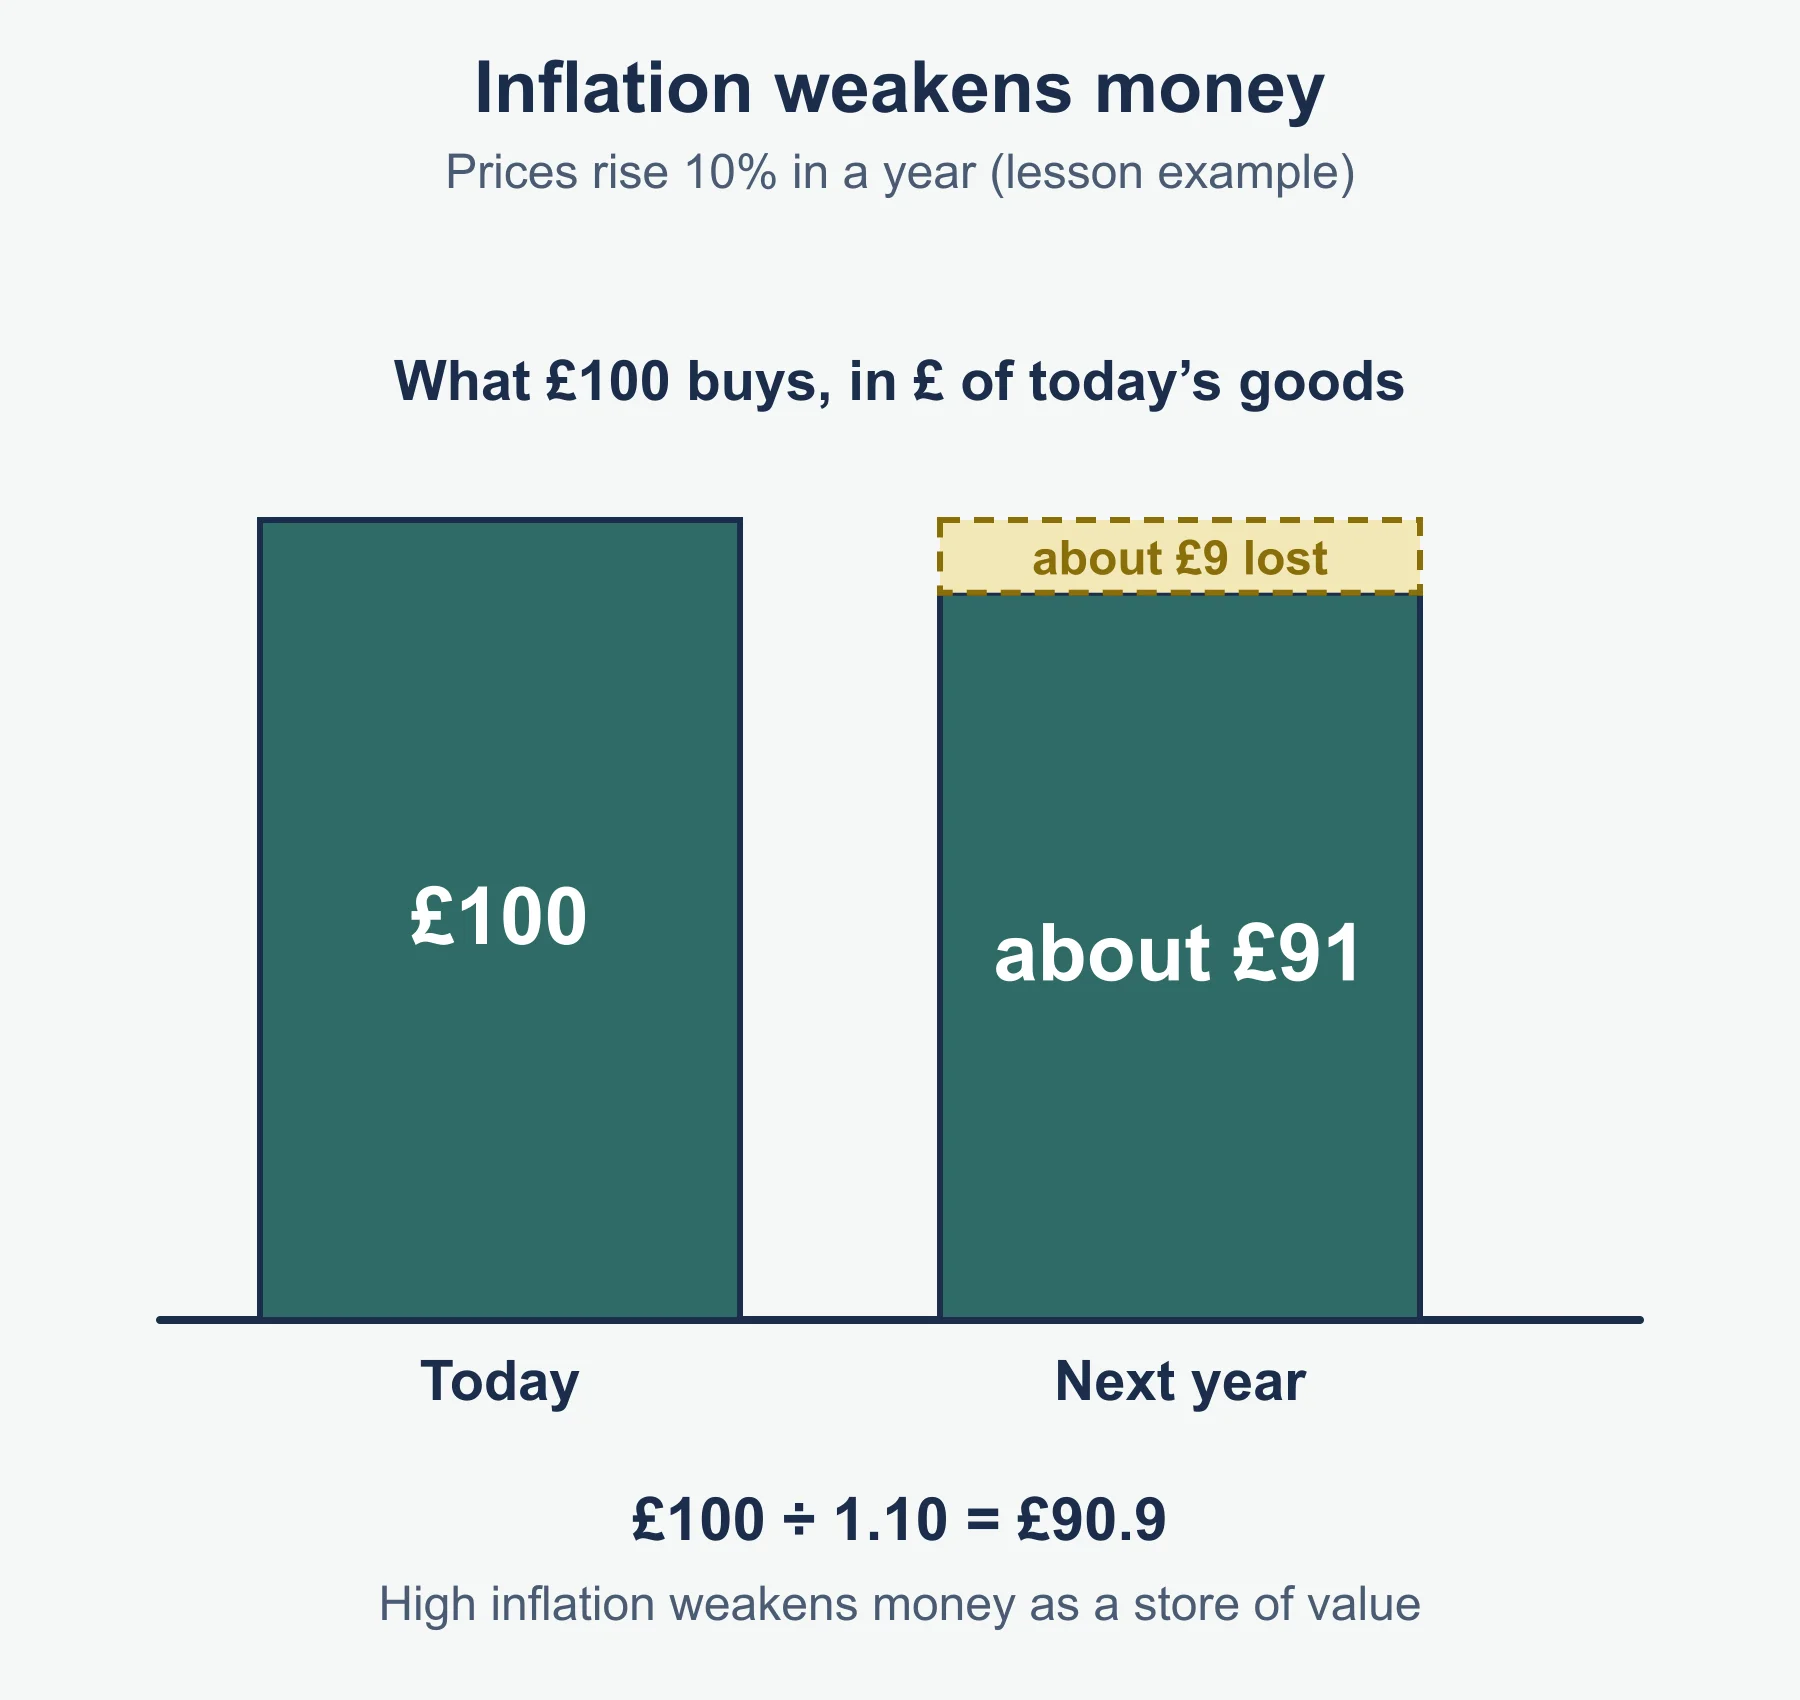
Money only works well as a store of value if prices are stable. If inflation is 4%, £100 kept for a year buys only what 100 ÷ 1.04 = £96.15 bought at the start. High inflation also weakens money as a unit of account, because prices keep changing.
Part B: The financial sector (3.2.5.2)
Main agents in the financial sector
| Agent | What it does |
|---|---|
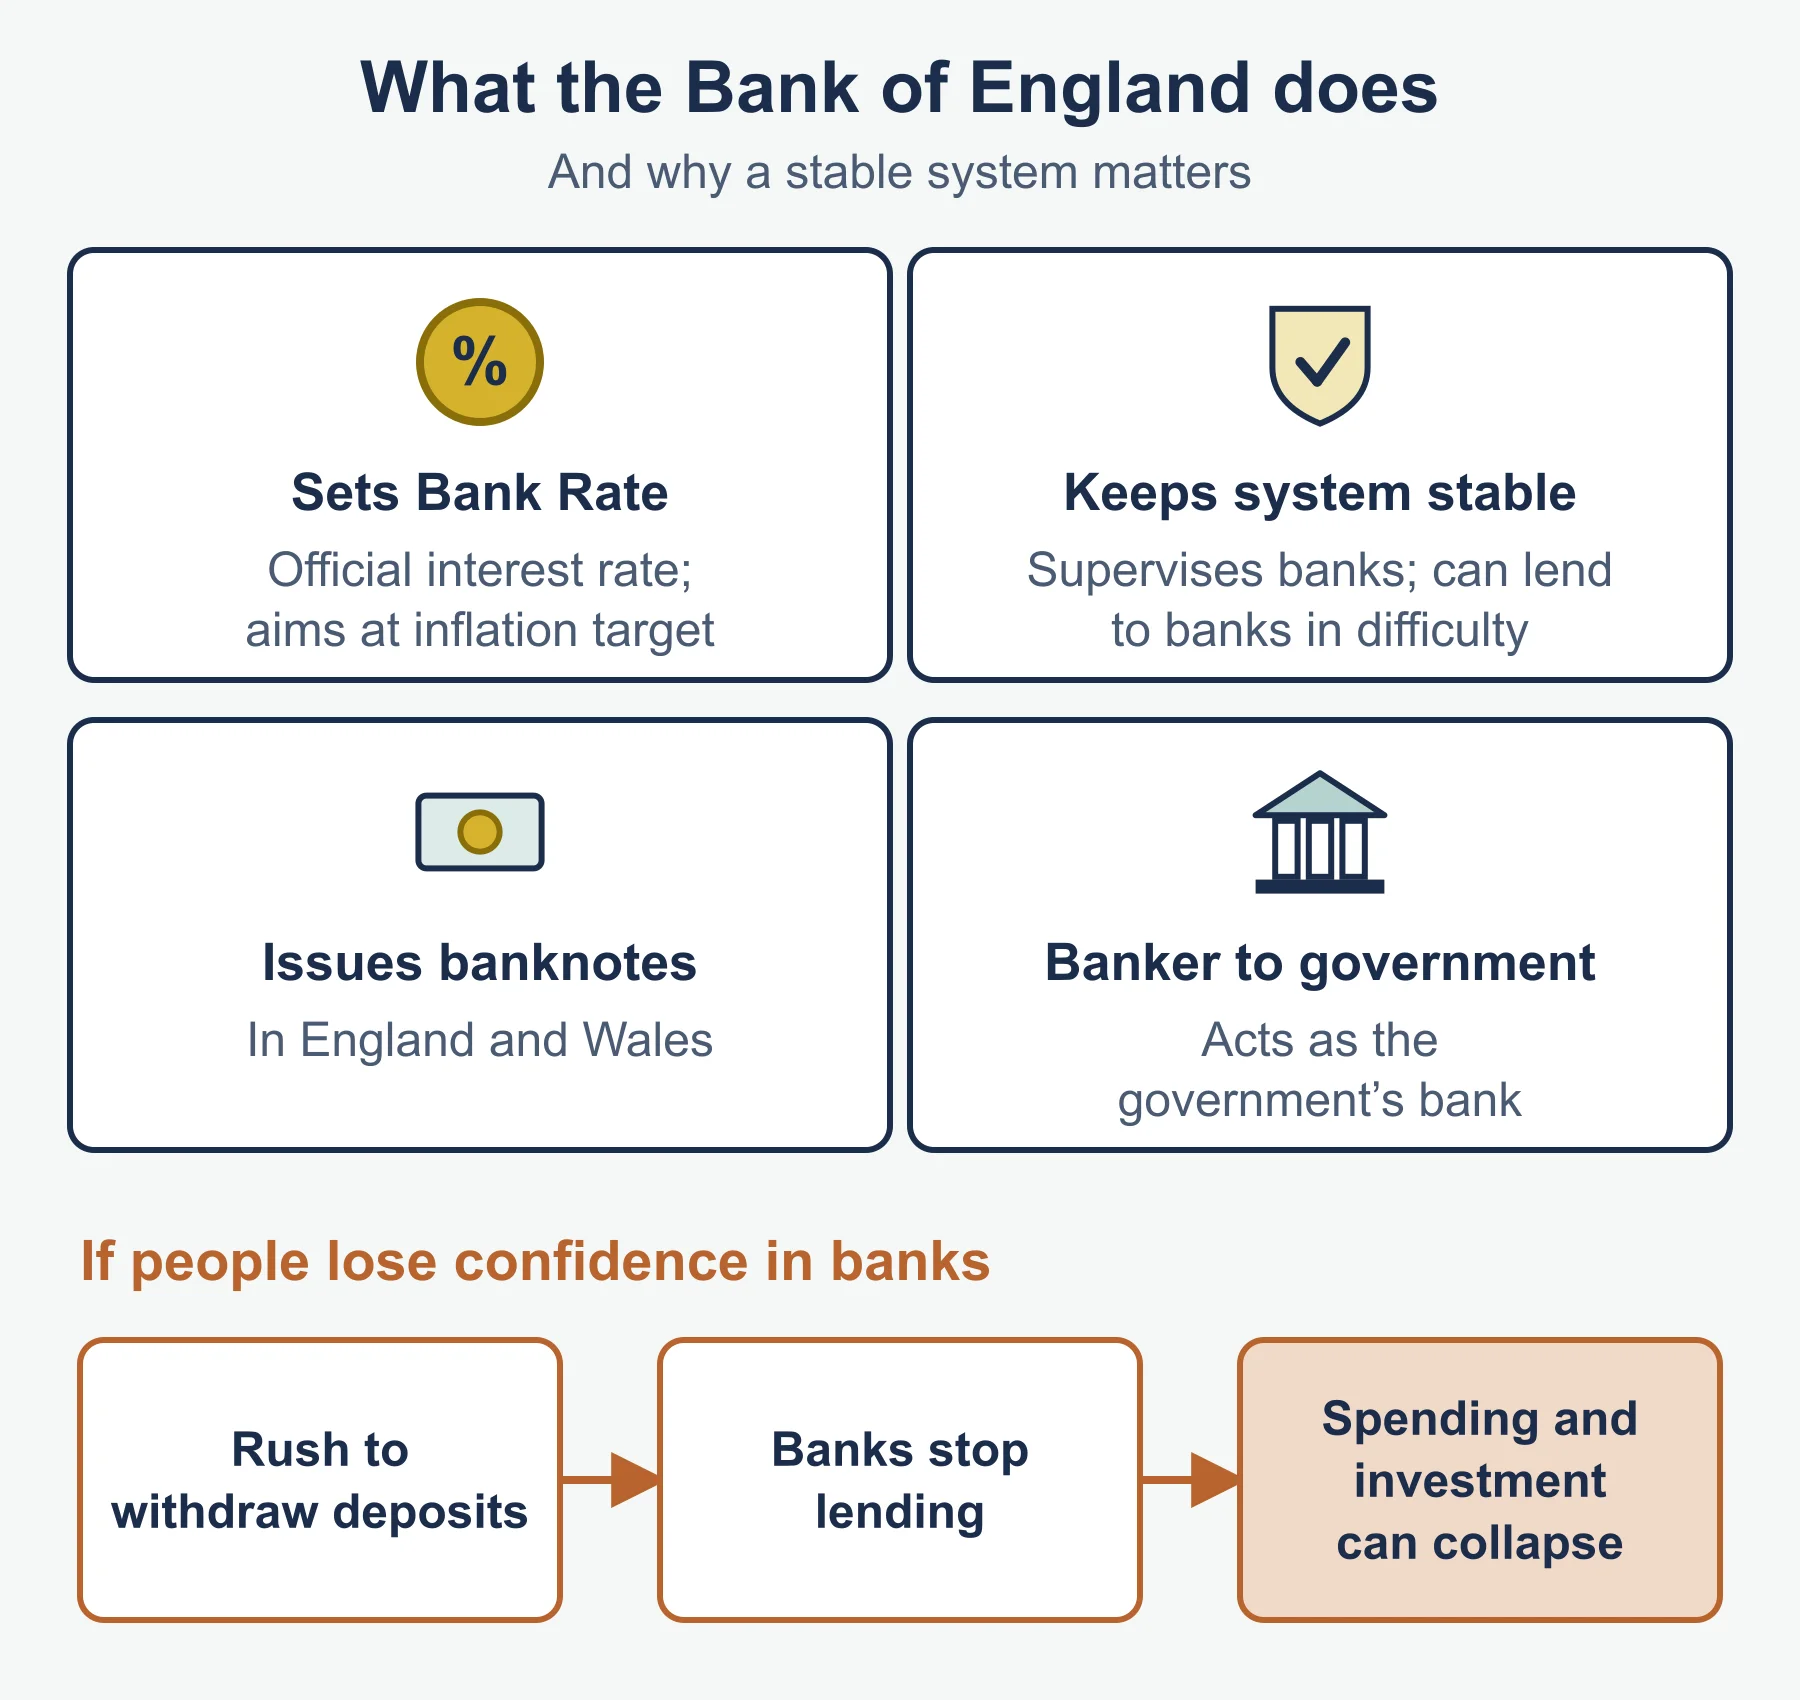
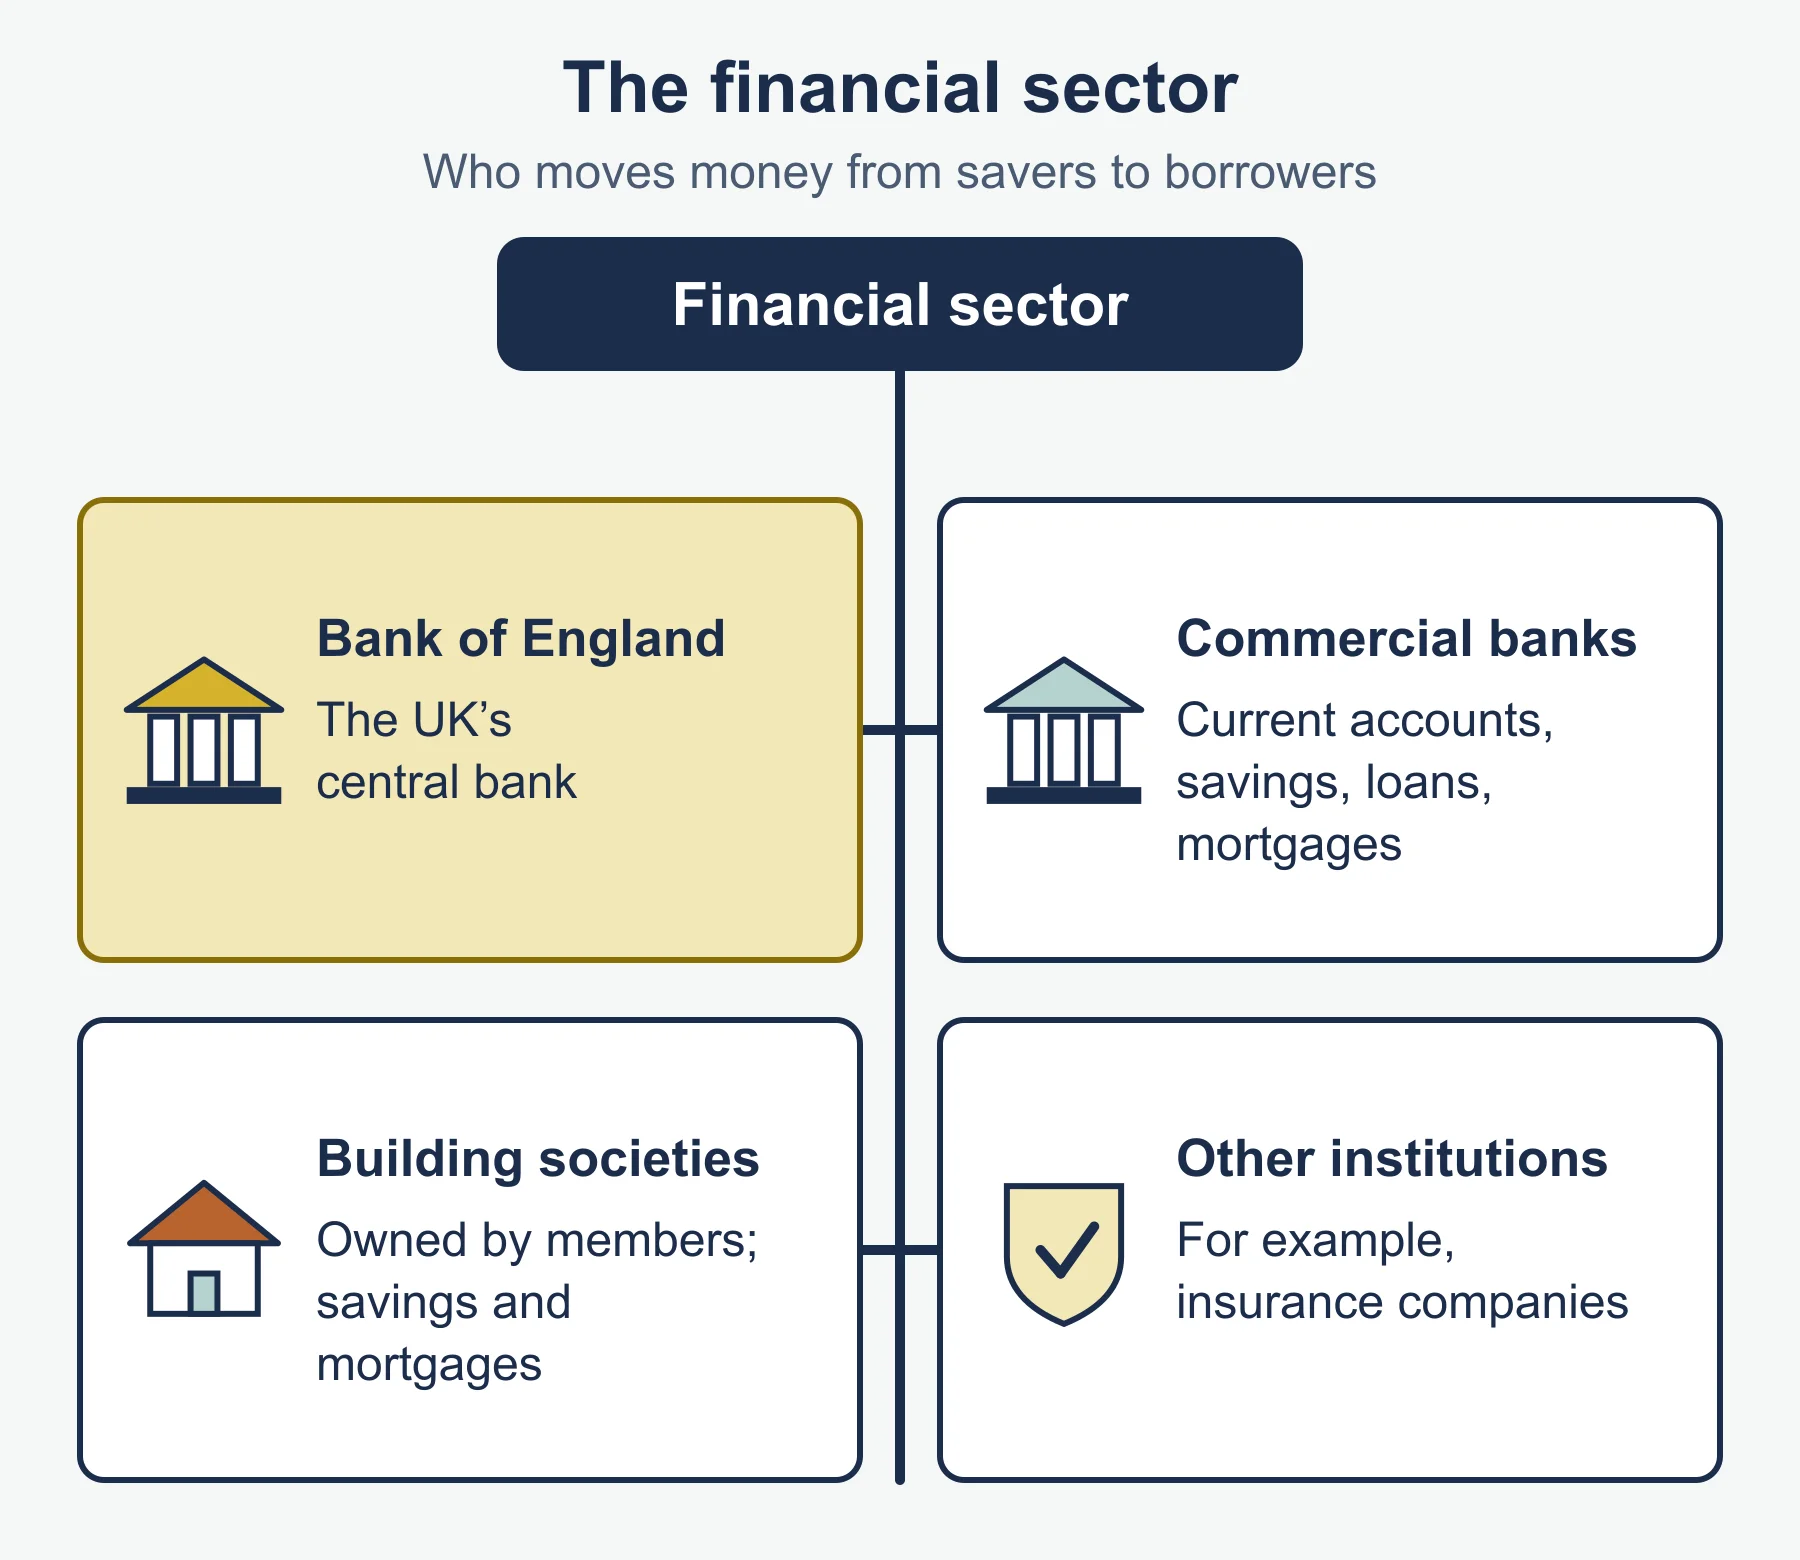
| Bank of England | The UK’s central bank: sets Bank Rate, keeps the financial system stable, issues banknotes in England and Wales, and is banker to the government and to other banks |
| Commercial (high street) banks | Owned by shareholders; take deposits, make loans, provide payment services |
| Building societies | Owned by their members (savers and borrowers) as mutuals; mainly savings accounts and mortgages. Nationwide is the largest |
| Other institutions | Insurance companies (manage risk), pension funds (invest savings for retirement), investment banks and the stock market (help firms raise finance by selling shares) |
The role of the Bank of England
- Influencing interest rates. The Monetary Policy Committee sets Bank Rate, which affects the rates high street banks charge borrowers and pay savers. Its aim is to keep CPI inflation at the government’s 2% target.
- Ensuring the stability of the financial system. It oversees and regulates banks (making them hold enough capital so they can survive losses), checks for risks across the whole system, and acts as lender of last resort, lending to banks in a crisis to stop a collapse spreading. In September 2007 it gave emergency support to the bank Northern Rock after savers rushed to withdraw their money.
The role of high street banks
- A service for savers: they keep money safe, pay interest and provide current accounts and cards. Deposits up to a limit are protected by a government-backed scheme (the Financial Services Compensation Scheme) if a bank fails.
- A service for borrowers: loans, overdrafts, mortgages and credit cards, so households can buy now and pay later.
- Funding investment: banks lend savers’ deposits to firms, which can then buy machinery, build premises and grow. This links saving to investment and raises future output.
- Payments: they run the systems that move money between people and firms.
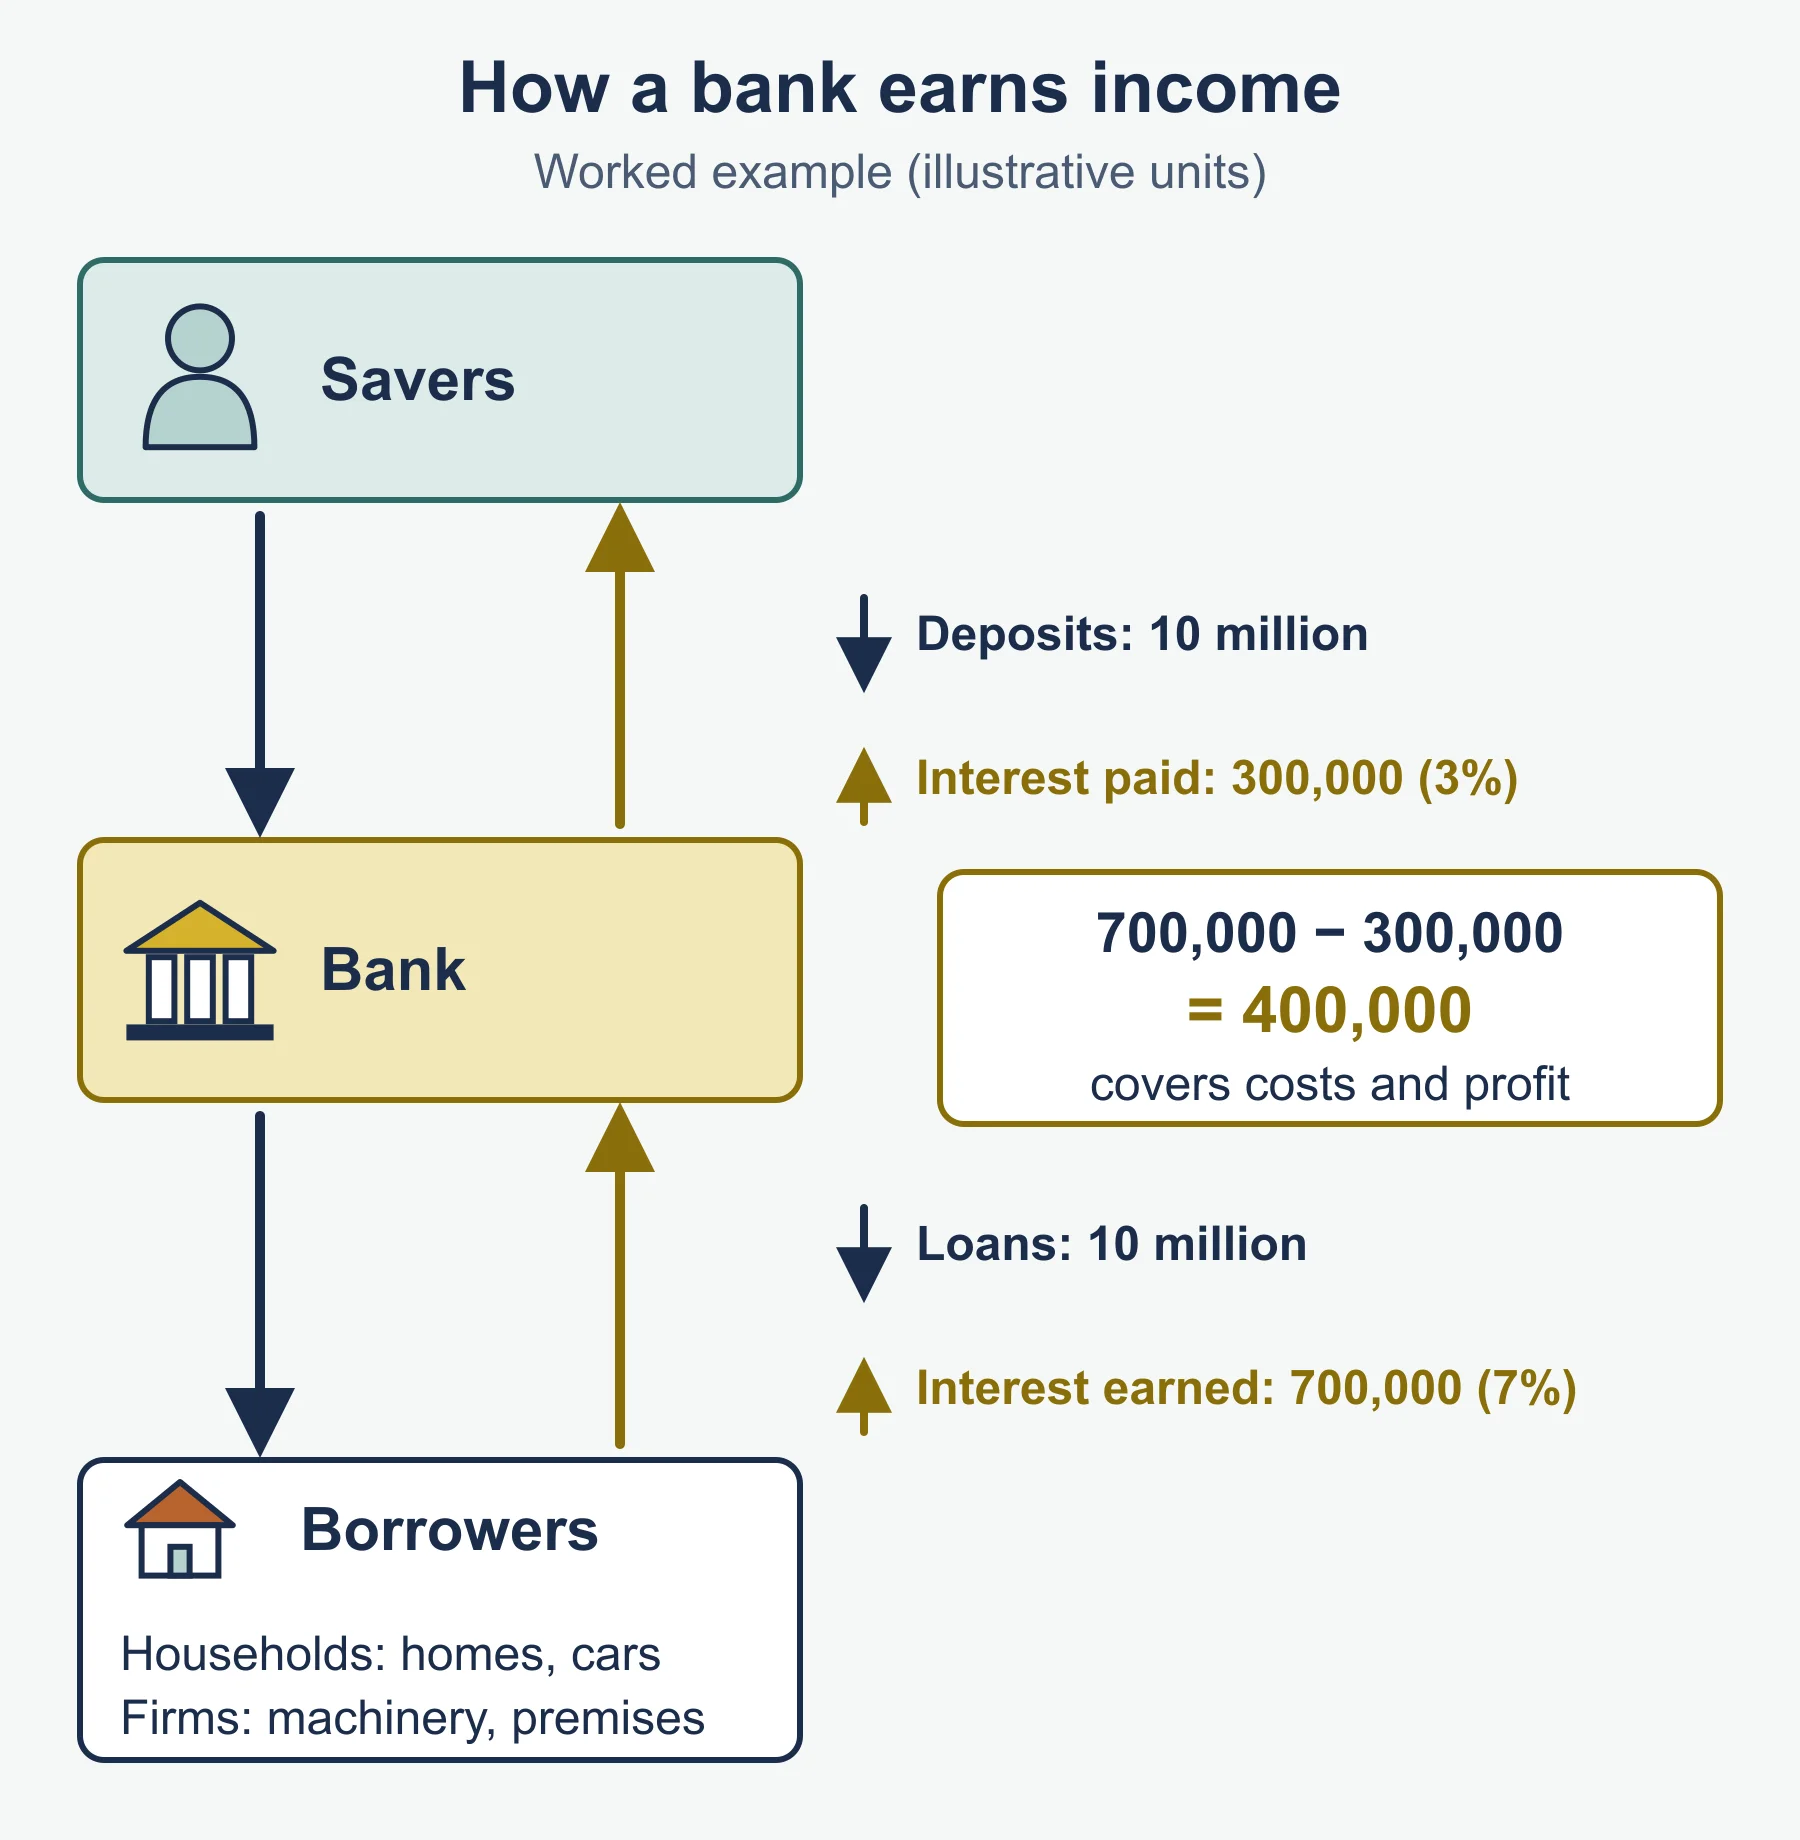
Banks make profit from the gap between the interest rate they charge borrowers and the rate they pay savers.
Importance to consumers, producers and the government
| Group | Why the financial sector matters |
|---|---|
| Consumers | A safe place to save, a return on savings, loans for homes and cars, easy payments, insurance |
| Producers | Loans and overdrafts for investment and day-to-day costs; ways to raise money by selling shares |
| Government | Borrows by selling bonds; collects tax from a large, high-earning industry; the sector employs many people and earns export income for the UK |
| The economy | Channels savings into investment; a banking crisis (as in 2007–08) can cause a deep recession |
Calculations
1. A bank’s interest margin. A bank pays savers 2% and charges borrowers 6% on £1 million lent. Interest received = 0.06 × 1,000,000 = £60,000. Interest paid = 0.02 × 1,000,000 = £20,000. Margin = £40,000 before costs.
2. Simple interest on savings. £2,500 saved at 3% for a year earns 0.03 × 2,500 = £75.
3. Compound interest. £2,500 at 3% for two years: Year 1 ends at £2,575; Year 2 adds 0.03 × 2,575 = £77.25, giving £2,652.25.
Exam traps
- Money is defined by what it does (its functions), not by being made of paper or metal.
- “Store of value” and “means of deferred payment” are different: one is saving, the other is debt repaid later.
- The Bank of England is not a high street bank: ordinary people do not hold accounts there.
- A building society is owned by its members, not by shareholders.
- Do not say the Bank of England “sets mortgage rates”. It sets Bank Rate, which influences them.
Quick self-test
- Name the four functions of money.
- What is a double coincidence of wants?
- Which function of money is used when you take out a loan to be repaid over three years?
- Why is money more than the notes and coins in circulation?
- How does high inflation weaken money as a store of value?
- Give the two main roles of the Bank of England named in the specification.
- What does “lender of last resort” mean?
- Give one way high street banks help savers and one way they help borrowers.
- How do banks help to fund investment?
- How is a building society different from a bank?
Answers
- Medium of exchange, unit of account, store of value and means of deferred payment.
- The need, in barter, for each trader to want what the other is offering.
- Means of deferred payment.
- Most money is held as bank and building society deposits, spent by card or transfer.
- Each pound buys less over time, so saved money loses purchasing power.
- Influencing interest rates (through Bank Rate) and ensuring the stability of the financial system.
- The Bank of England will lend to banks in difficulty when no one else will, to prevent a wider crisis.
- Savers: safe keeping and interest. Borrowers: loans, mortgages and overdrafts.
- They lend the deposits of savers to firms, which use the money to buy capital.
- A building society is a mutual owned by its members; a bank is owned by shareholders.
Where marks are usually lost
- Listing the functions of money without an example or explanation.
- Writing that money is “just cash”.
- Mixing up the Bank of England with high street banks.
- Describing a bank’s role without saying why it matters to the economy (investment, growth, stability).
Frequently asked questions
What are the four functions of money? Medium of exchange, unit of account, store of value and means of deferred payment. A memory aid is My Uncle Stores Dollars.
What are the two main roles of the Bank of England in AQA GCSE Economics? Influencing interest rates, through Bank Rate set by the Monetary Policy Committee, and ensuring the stability of the financial system.
How is a building society different from a bank? A building society is a mutual owned by its members, the savers and borrowers. A commercial bank is owned by shareholders.
How do banks make a profit? From the gap between the interest rate they charge borrowers and the rate they pay savers.
Is money just notes and coins? No. Most money in the UK is held as bank and building society deposits spent by card or transfer; notes and coins are only a few per cent of the total.
Official syllabus
AQA GCSE Economics (8136) specification, for first teaching from September 2017 (Version 1.0), published by AQA: sections 3.2.5.1 The role of money and 3.2.5.2 The role and importance of the financial sector for the economy.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
AQA GCSE Economics: Money and the financial sector (8136)
Study guide to AQA GCSE Economics 8136 3.2.5.1 and 3.2.5.2: the four functions of money, what counts as money, the Bank of England and high street banks.
Economics · AQA · GCSE
Read guide -
Practice questions
AQA GCSE Economics: Money and the financial sector (8136) – Practice Questions
Eleven original practice questions with worked answers for AQA GCSE Economics 8136 3.2.5.1 and 3.2.5.2: functions of money, banks and the Bank of England.
Economics · AQA · GCSE
Try questions -
Study guides
AQA GCSE Economics: The Economic Objectives of the Government (8136)
AQA GCSE Economics (8136) section 3.2.2 guide: stable prices, growth, full employment and the balance of payments, and why pursuing one can harm another.
Economics · AQA · GCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Economics GCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Economics classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
AQA Economics teachers at Marlbridge
