
Study Guides
A Level Accounting: Costs, cost behaviour and traditional costing methods (Cambridge 9706)
A study guide to cost classification, inventory valuation, absorption and marginal costing and break-even analysis for Cambridge AS & A Level Accounting.
- Subject
- Accounting
- Level
- AS LEVEL
- Topic
- Cost and management accounting
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Zain Ud Din Ahmed (what this means)
Aligned to Cambridge A Level Accounting (9706), 2026-2028. Official specification .
Syllabus page (what it covers and how it is assessed): Cambridge A Level Accounting.
Syllabus points this page covers
9706 (AS Level)
- 2.1 Costs and cost behaviour
- 2.2 Traditional costing methods
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Accounting (9706).
This guide covers sections 2.1 Costs and cost behaviour and 2.2 Traditional costing methods of the Cambridge International AS & A Level Accounting 9706 syllabus for examination in 2026, 2027 and 2028. Both sections are AS Level content. The syllabus says Paper 1 has eight questions on cost and management accounting, Question 4 of Paper 2 focuses on it (30 marks), and Paper 4 assumes this AS content. All businesses and figures below are invented and all amounts are in dollars.
Use it with the revision notes and the practice questions. See also the course hub, the checklist, the free diagnostics and the exam preparation guide.
What is covered
| Syllabus point | Where |
|---|---|
| 2.1.1 Costs, materials and labour, inventory, JIT | 1 to 3 |
| 2.2.1 Unit, job and batch costing | 4, 5 |
| 2.2.2 Absorption costing | 5 |
| 2.2.3 and 2.2.4 Marginal costing, decisions, CVP | 6, 7 |
1. Classifying costs, materials and labour
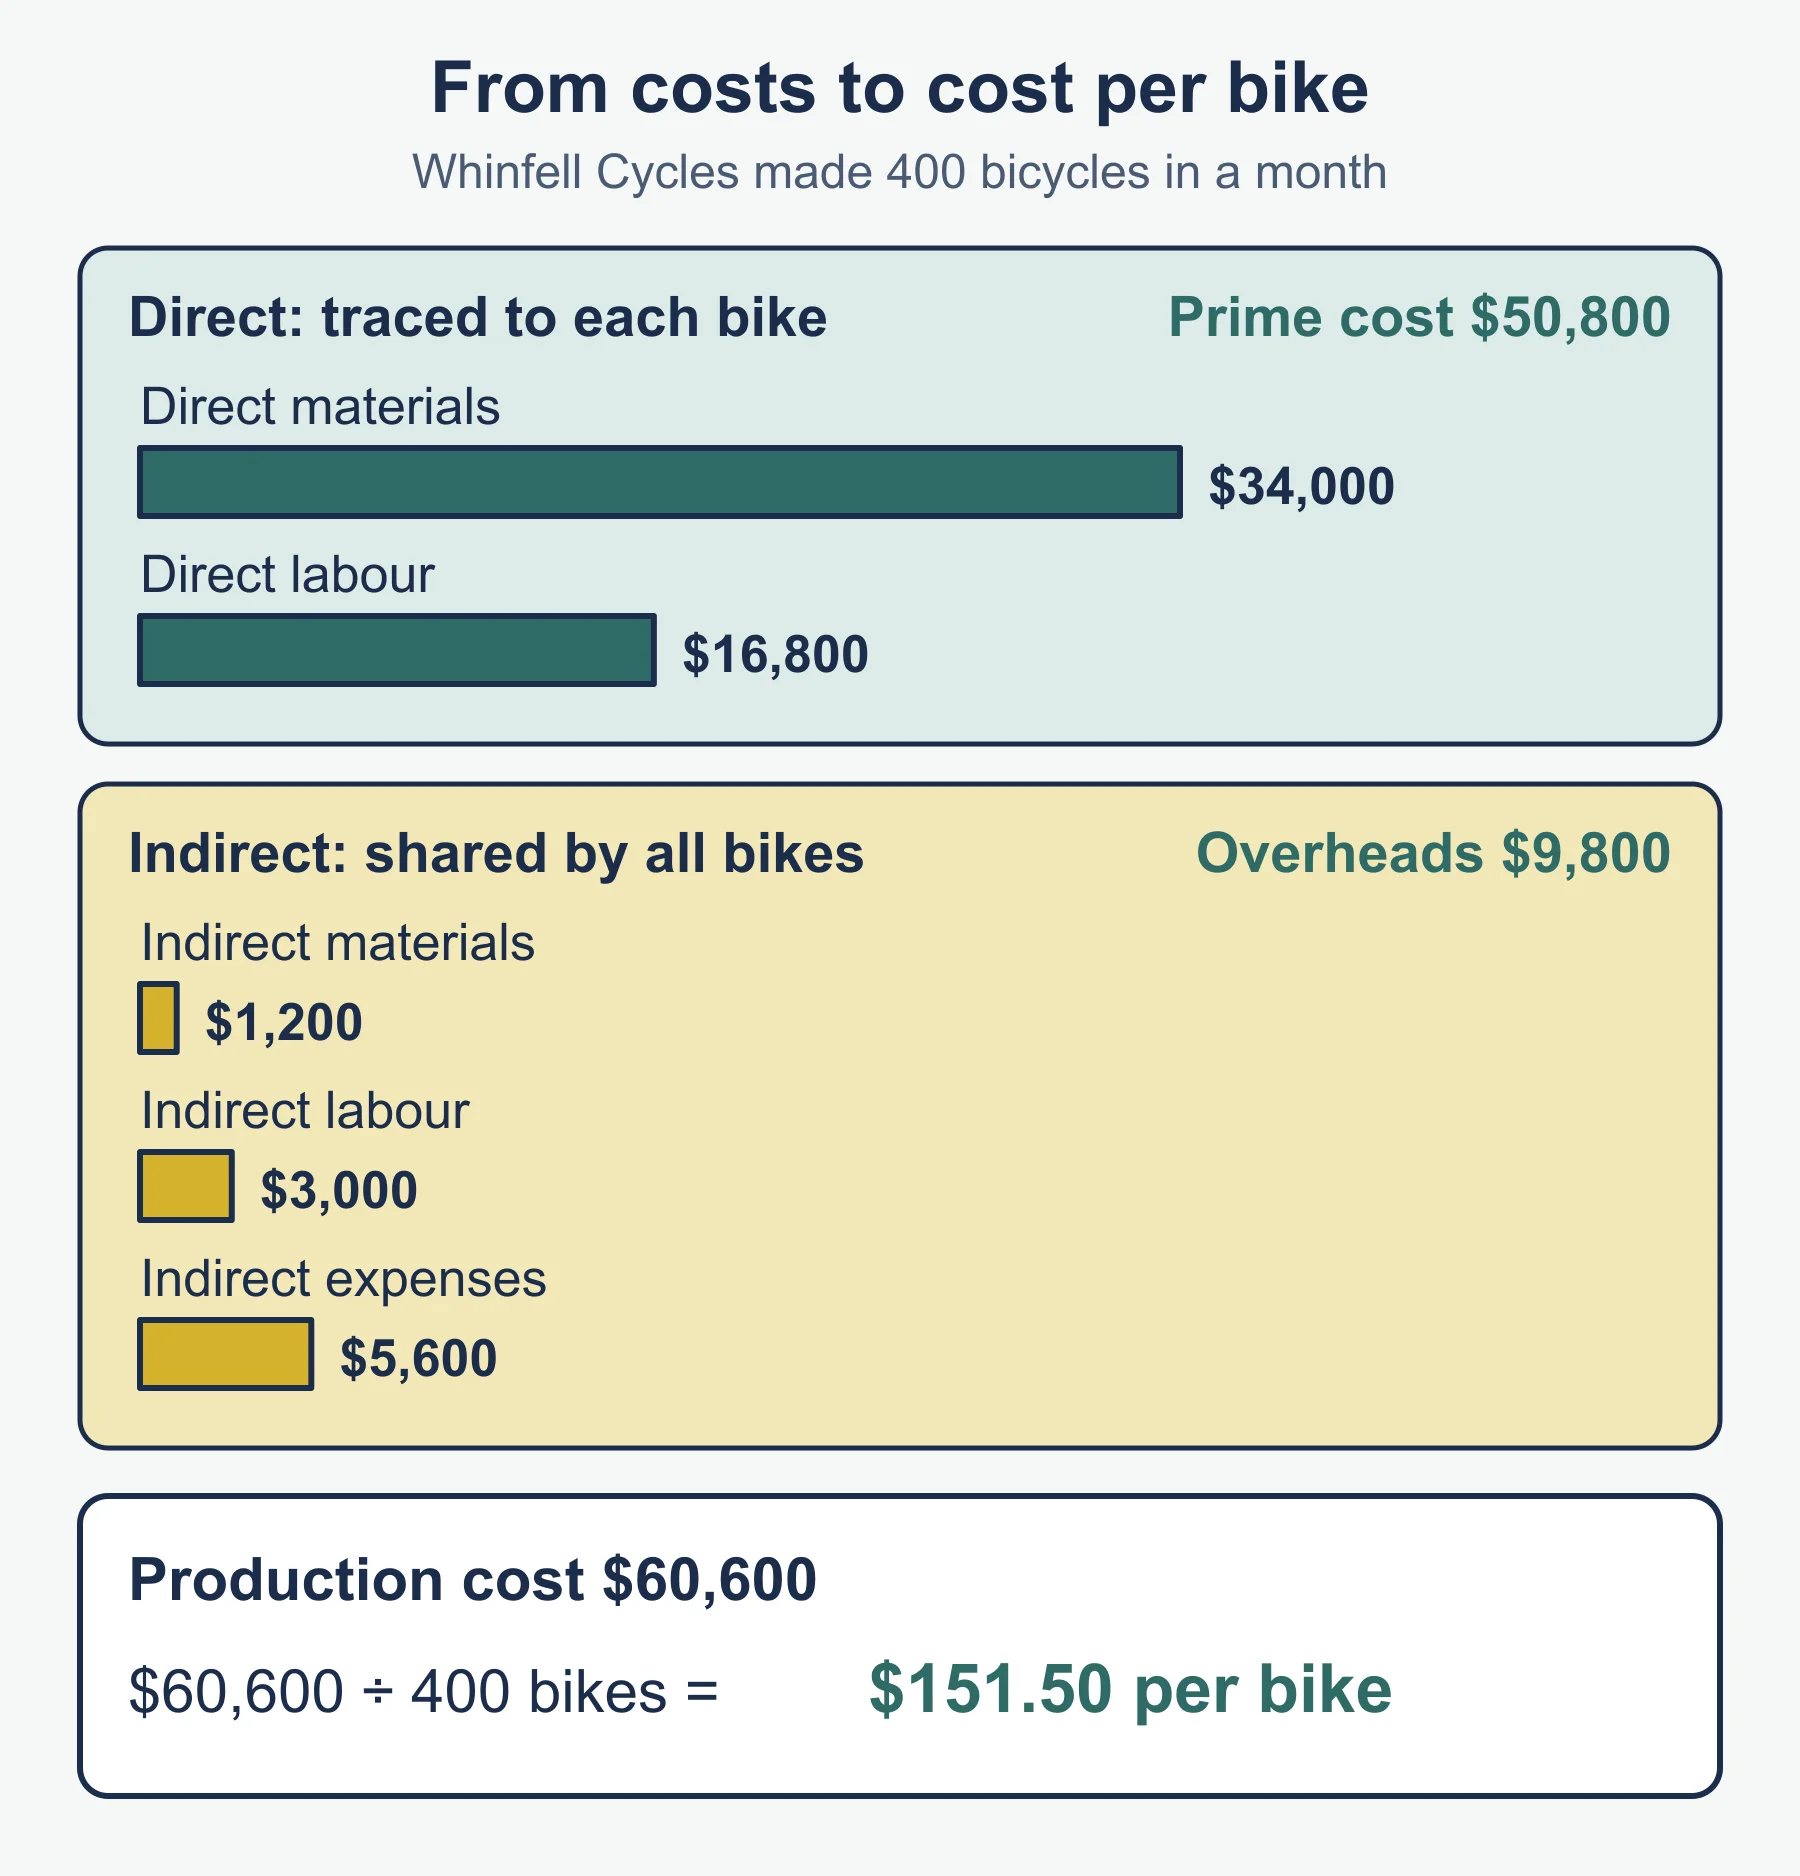
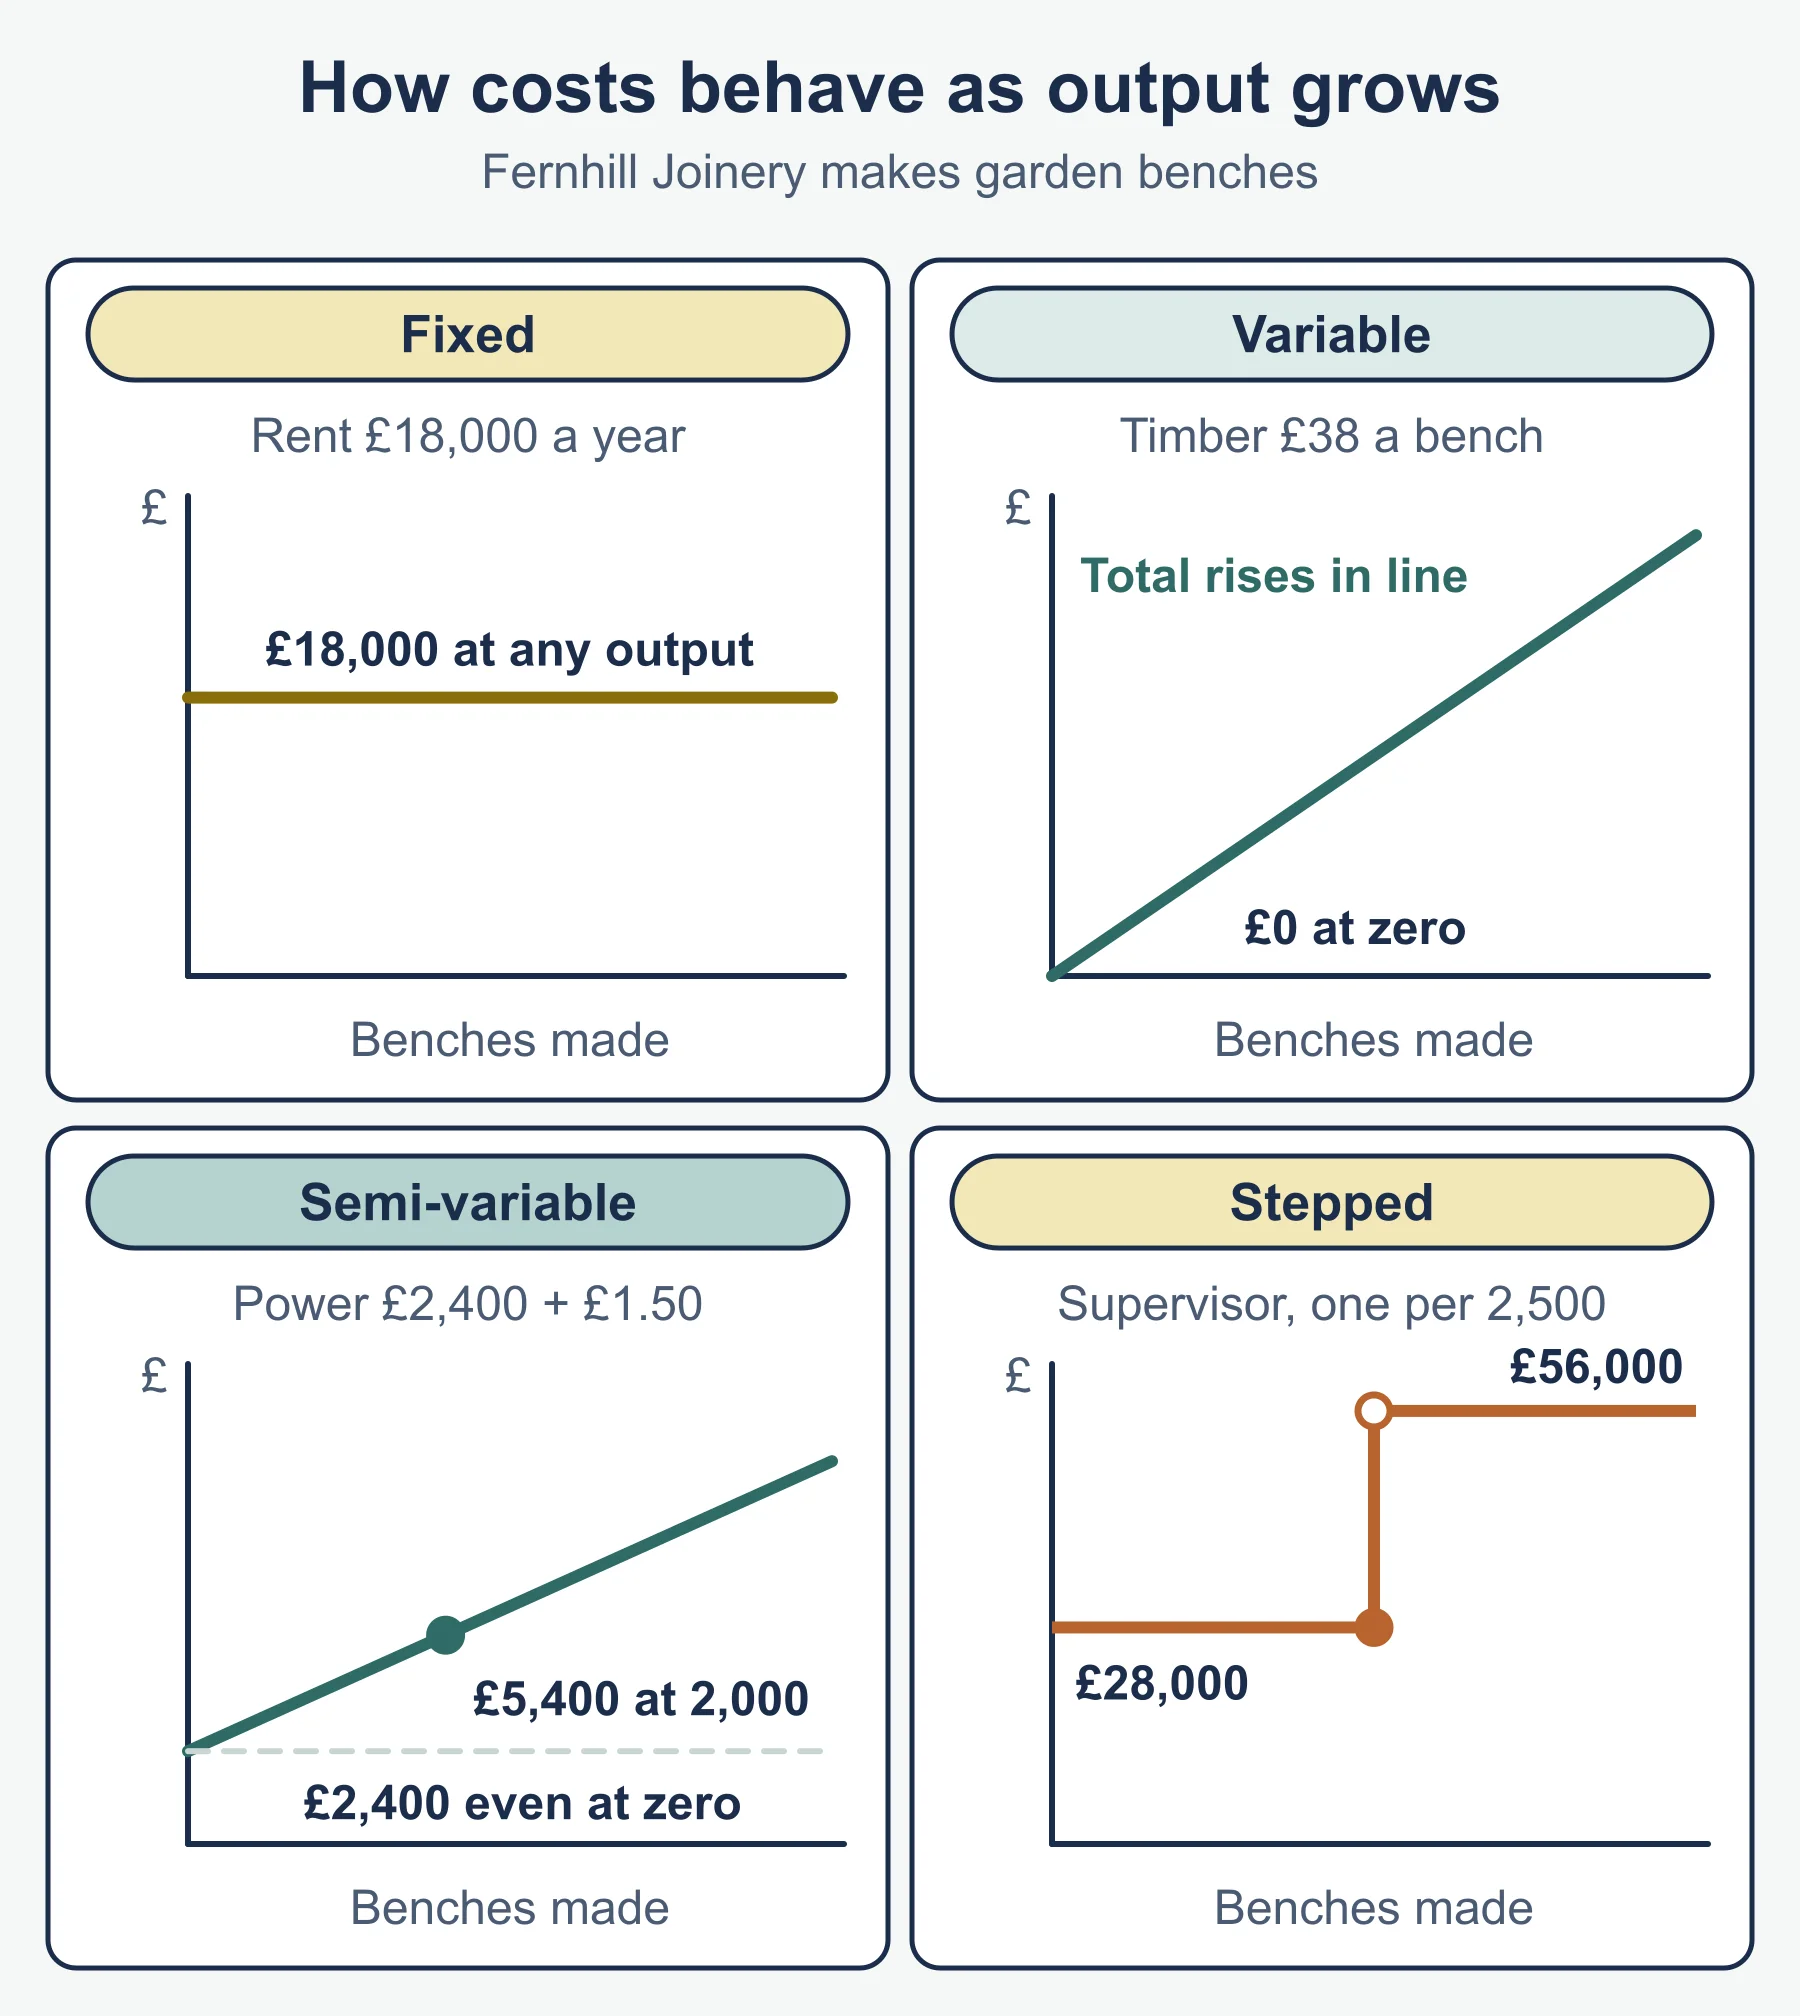
Costs are classified by traceability and behaviour. A direct cost can be traced to a cost unit: direct materials, direct labour and direct expenses. Together they make the prime cost. An indirect cost (overhead) cannot be traced economically to one unit. On behaviour, a fixed cost stays the same as output changes (within a range), a variable cost changes in proportion to output, a semi-variable cost has a fixed and a variable part, and a stepped cost is fixed until output passes a threshold, then jumps.
Whinfell Cycles made 400 bicycles in a month.
| Cost | Class | Amount |
|---|---|---|
| Frames and wheels, 85 per bike | Direct material, variable | 34,000 |
| Assemblers, 3 hours at 14 per bike | Direct labour, variable | 16,800 |
| Prime cost | 50,800 | |
| Lubricants and cleaning materials | Indirect material | 1,200 |
| Workshop supervisor | Indirect labour, fixed | 3,000 |
| Workshop rent, insurance | Indirect expense, fixed | 5,600 |
| Production overheads | 9,800 | |
| Production cost (60,600 / 400 = 151.50 per bike) | 60,600 |
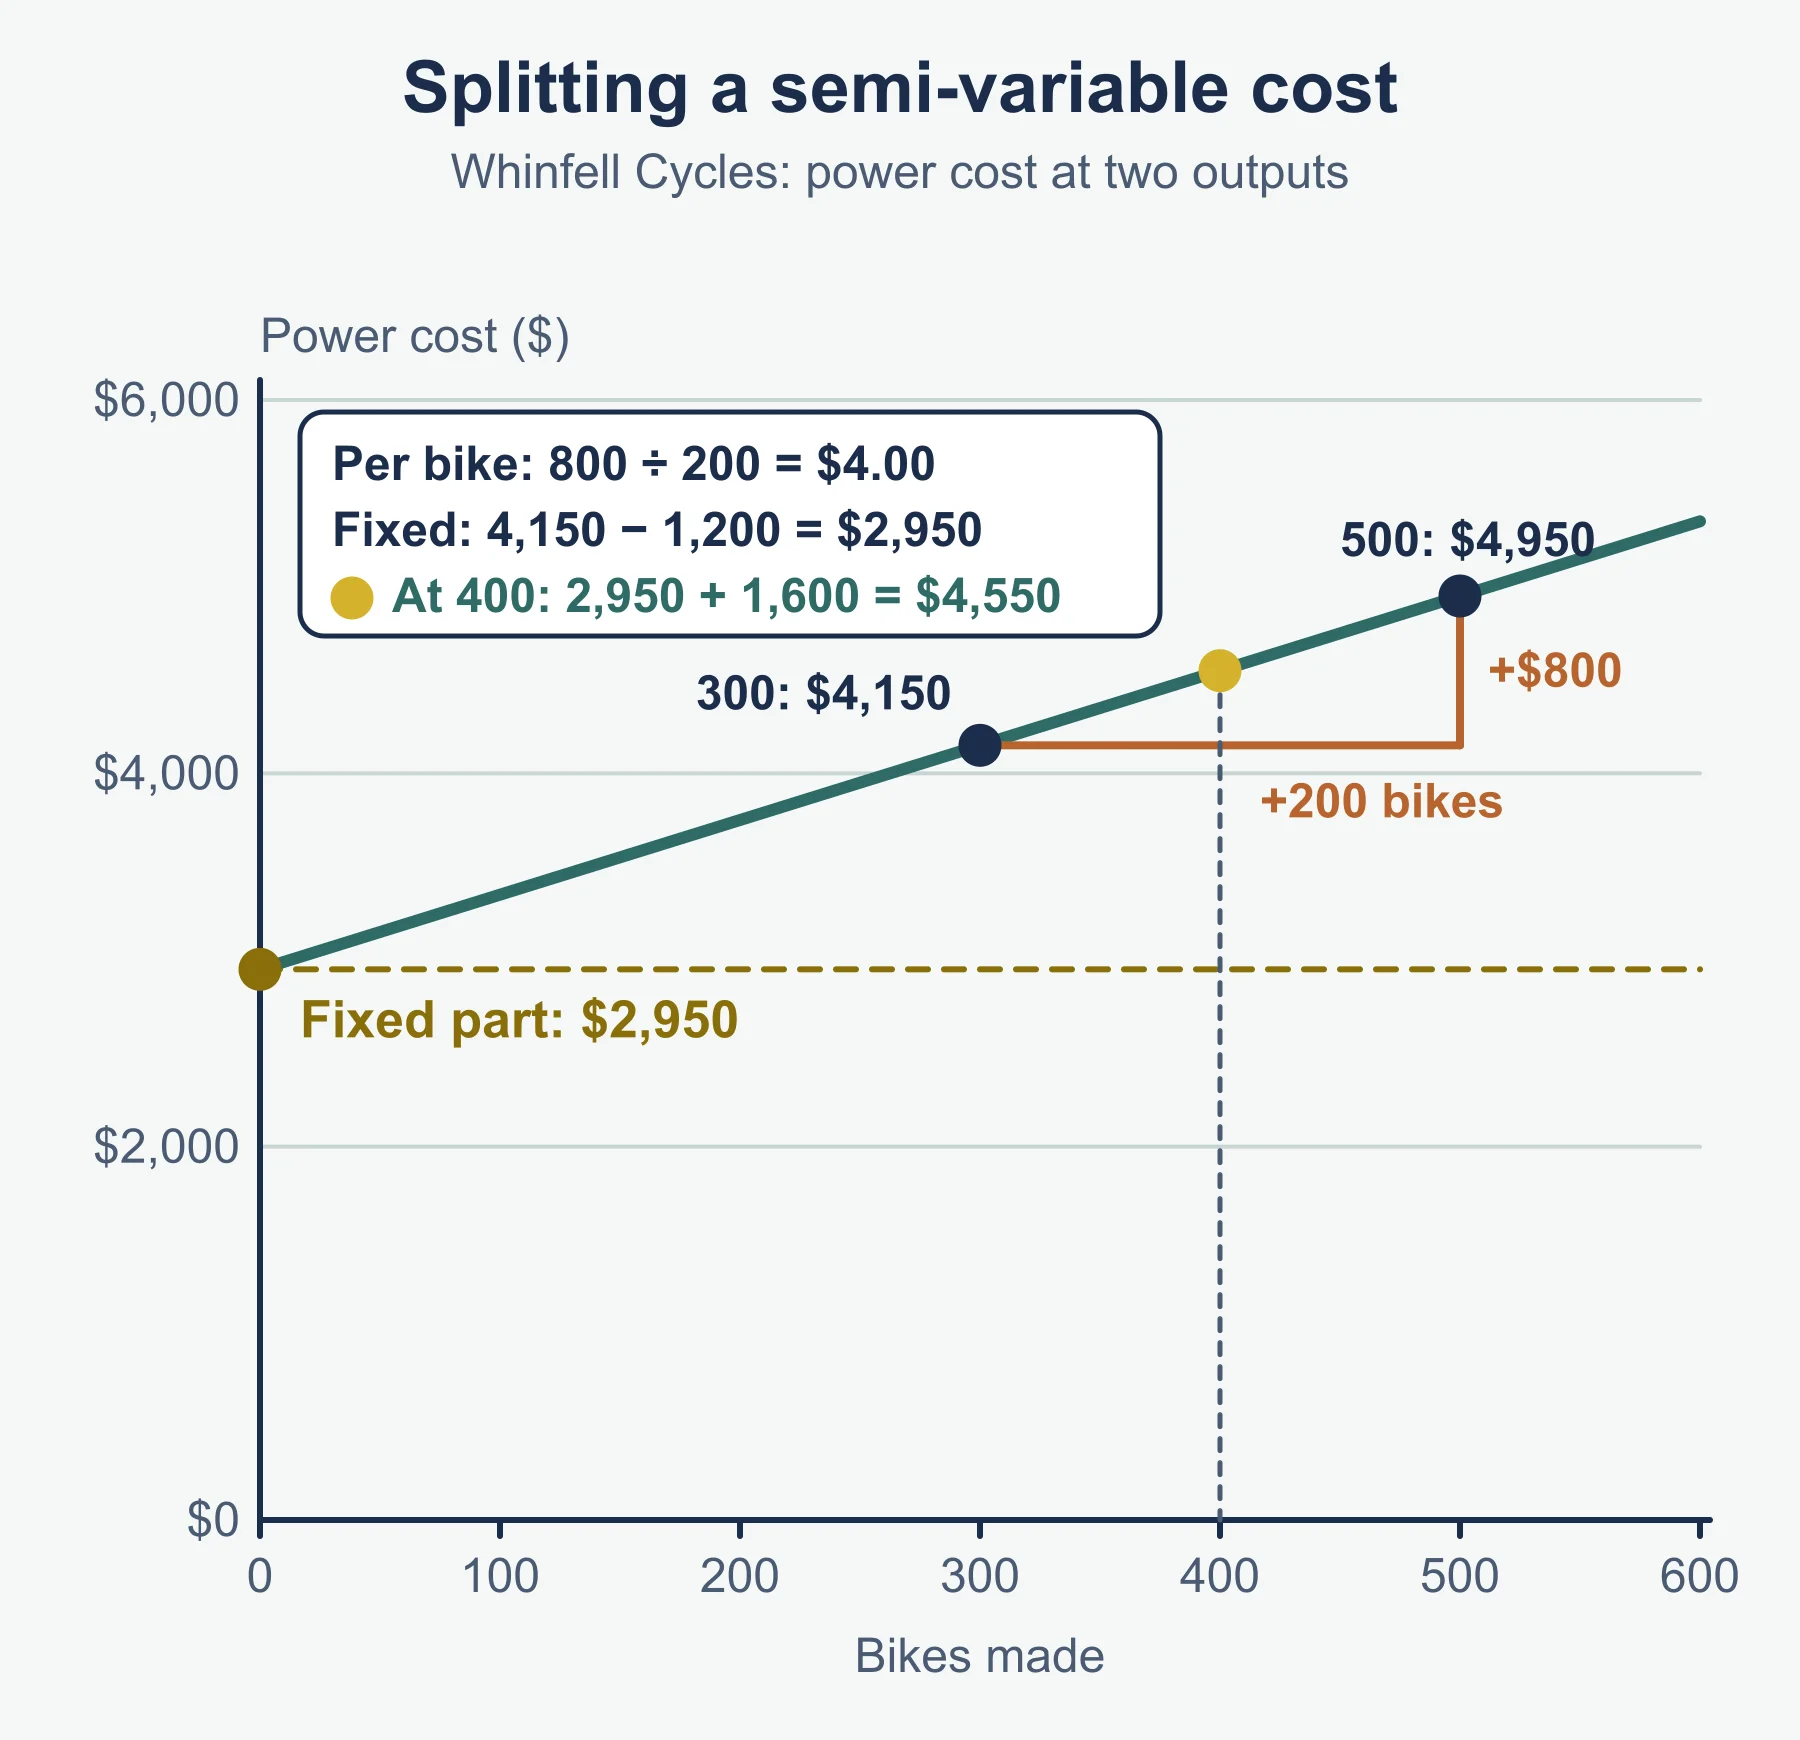
Semi-variable. Power cost 4,150 at 300 bikes and 4,950 at 500. Variable cost per bike = (4,950 − 4,150) / (500 − 300) = 4.00. Fixed part = 4,150 − 300 × 4.00 = 2,950. At 400 bikes: 2,950 + 1,600 = 4,550.
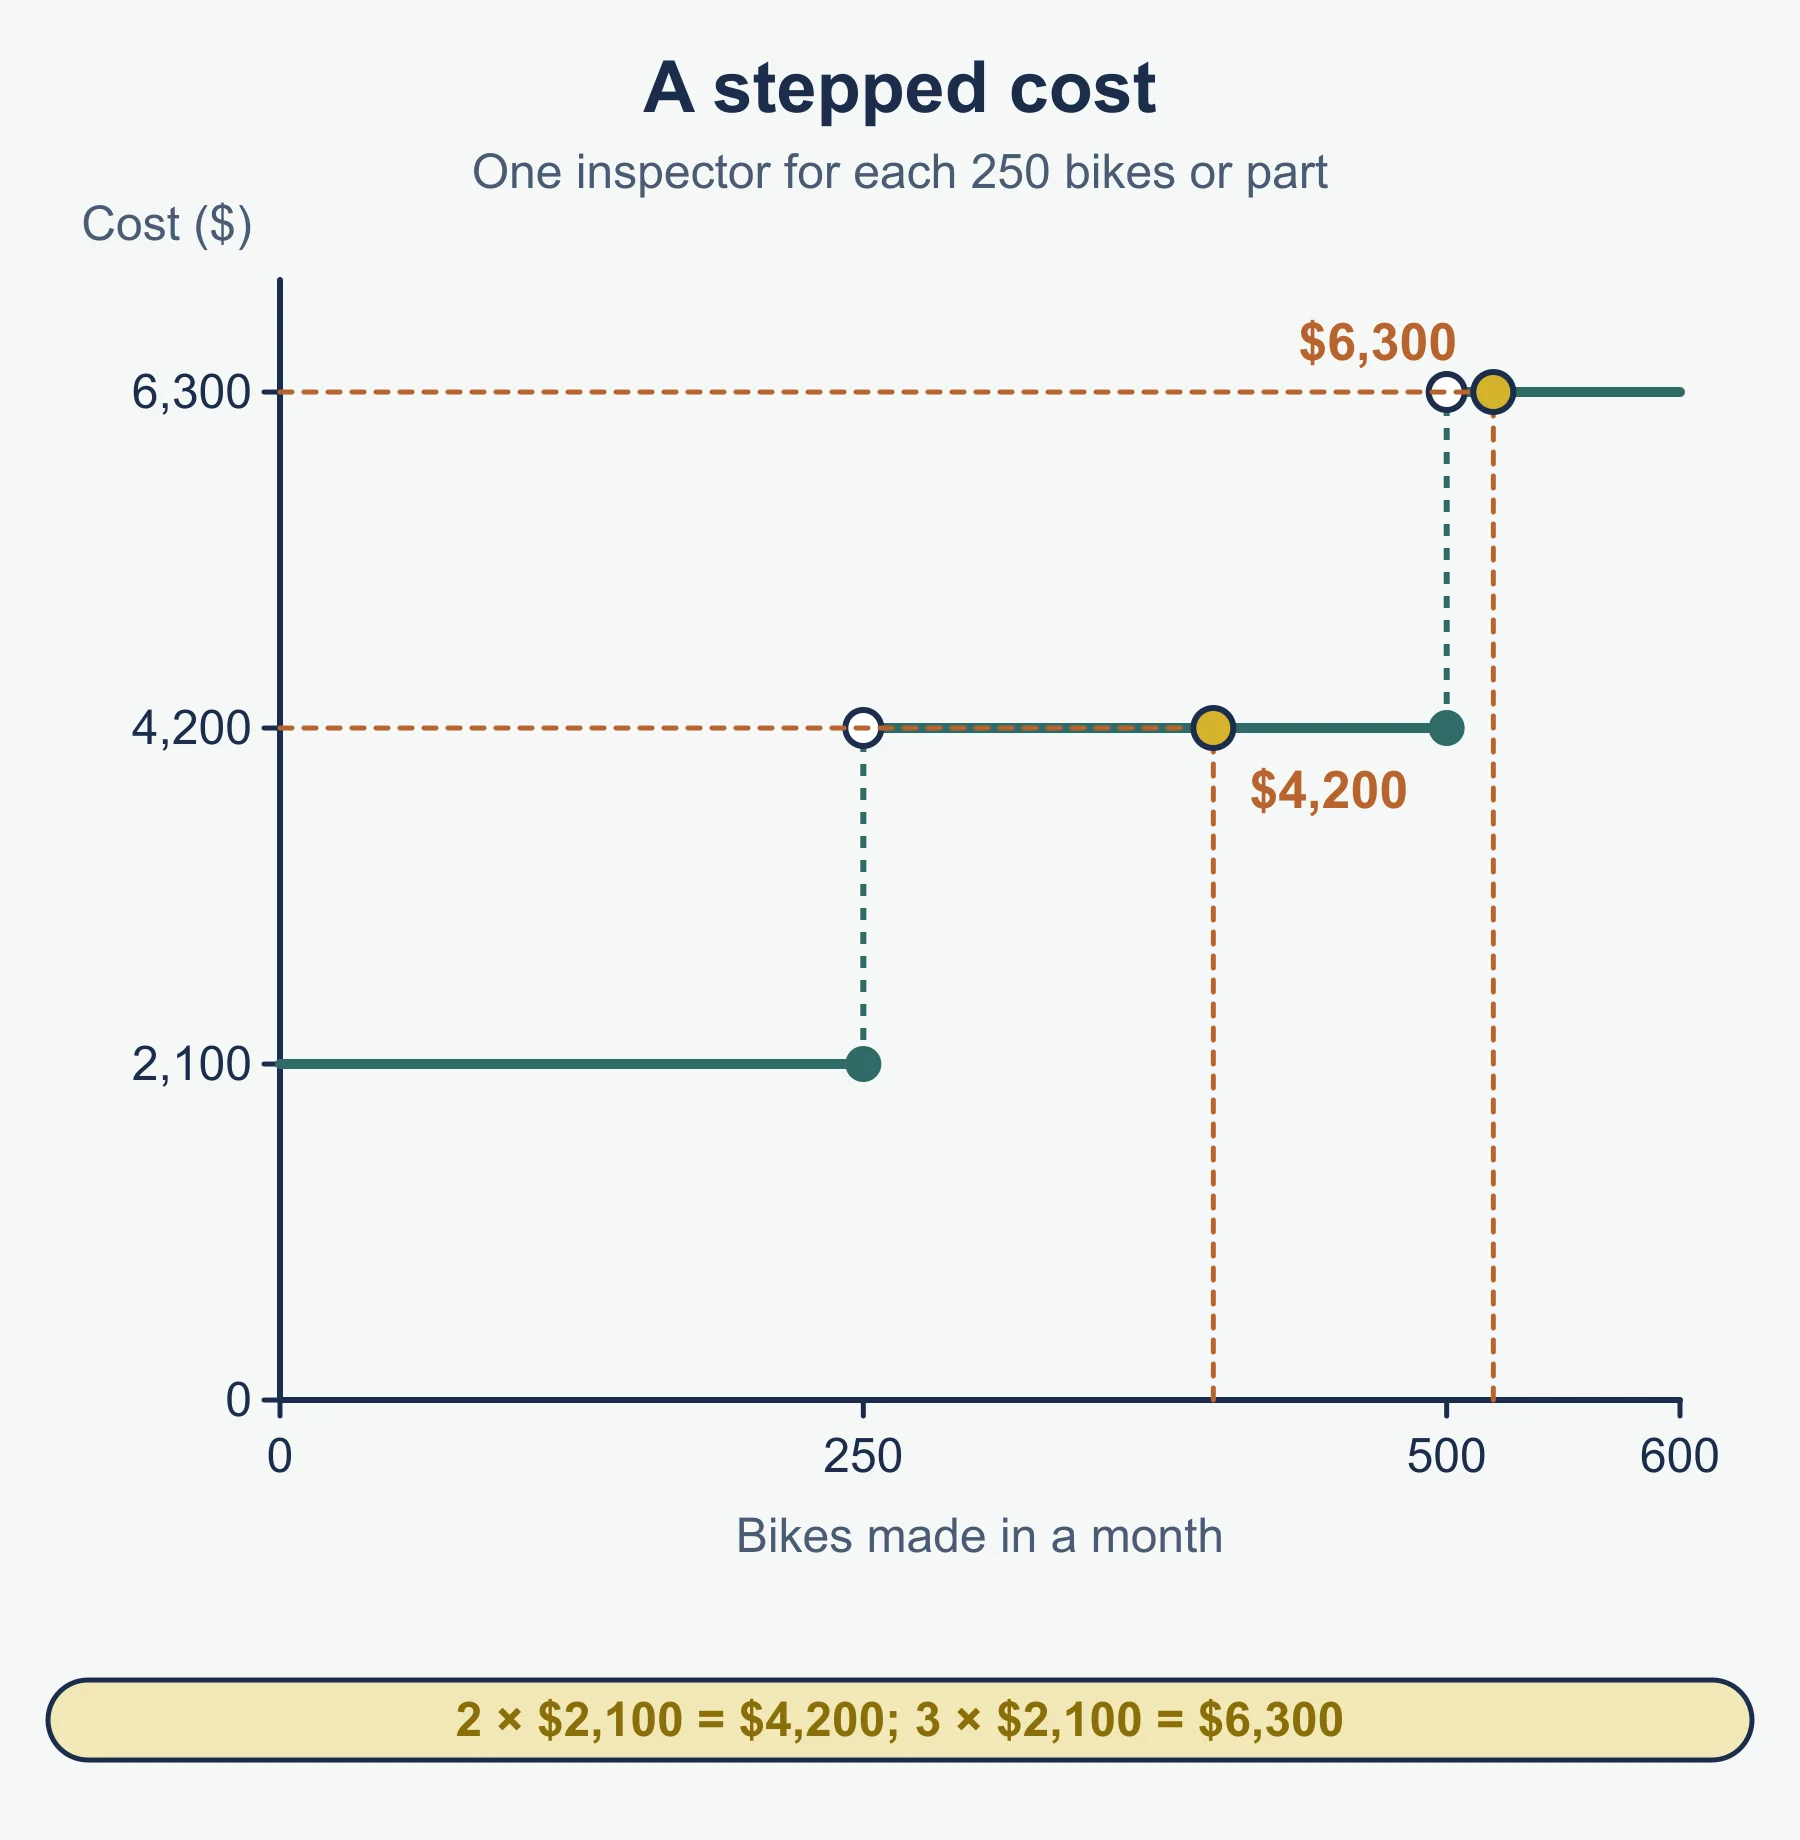
Stepped. One inspector (2,100 a month) is needed per 250 bikes or part of 250: 400 bikes cost 2 × 2,100 = 4,200; 520 bikes cost 3 × 2,100 = 6,300.
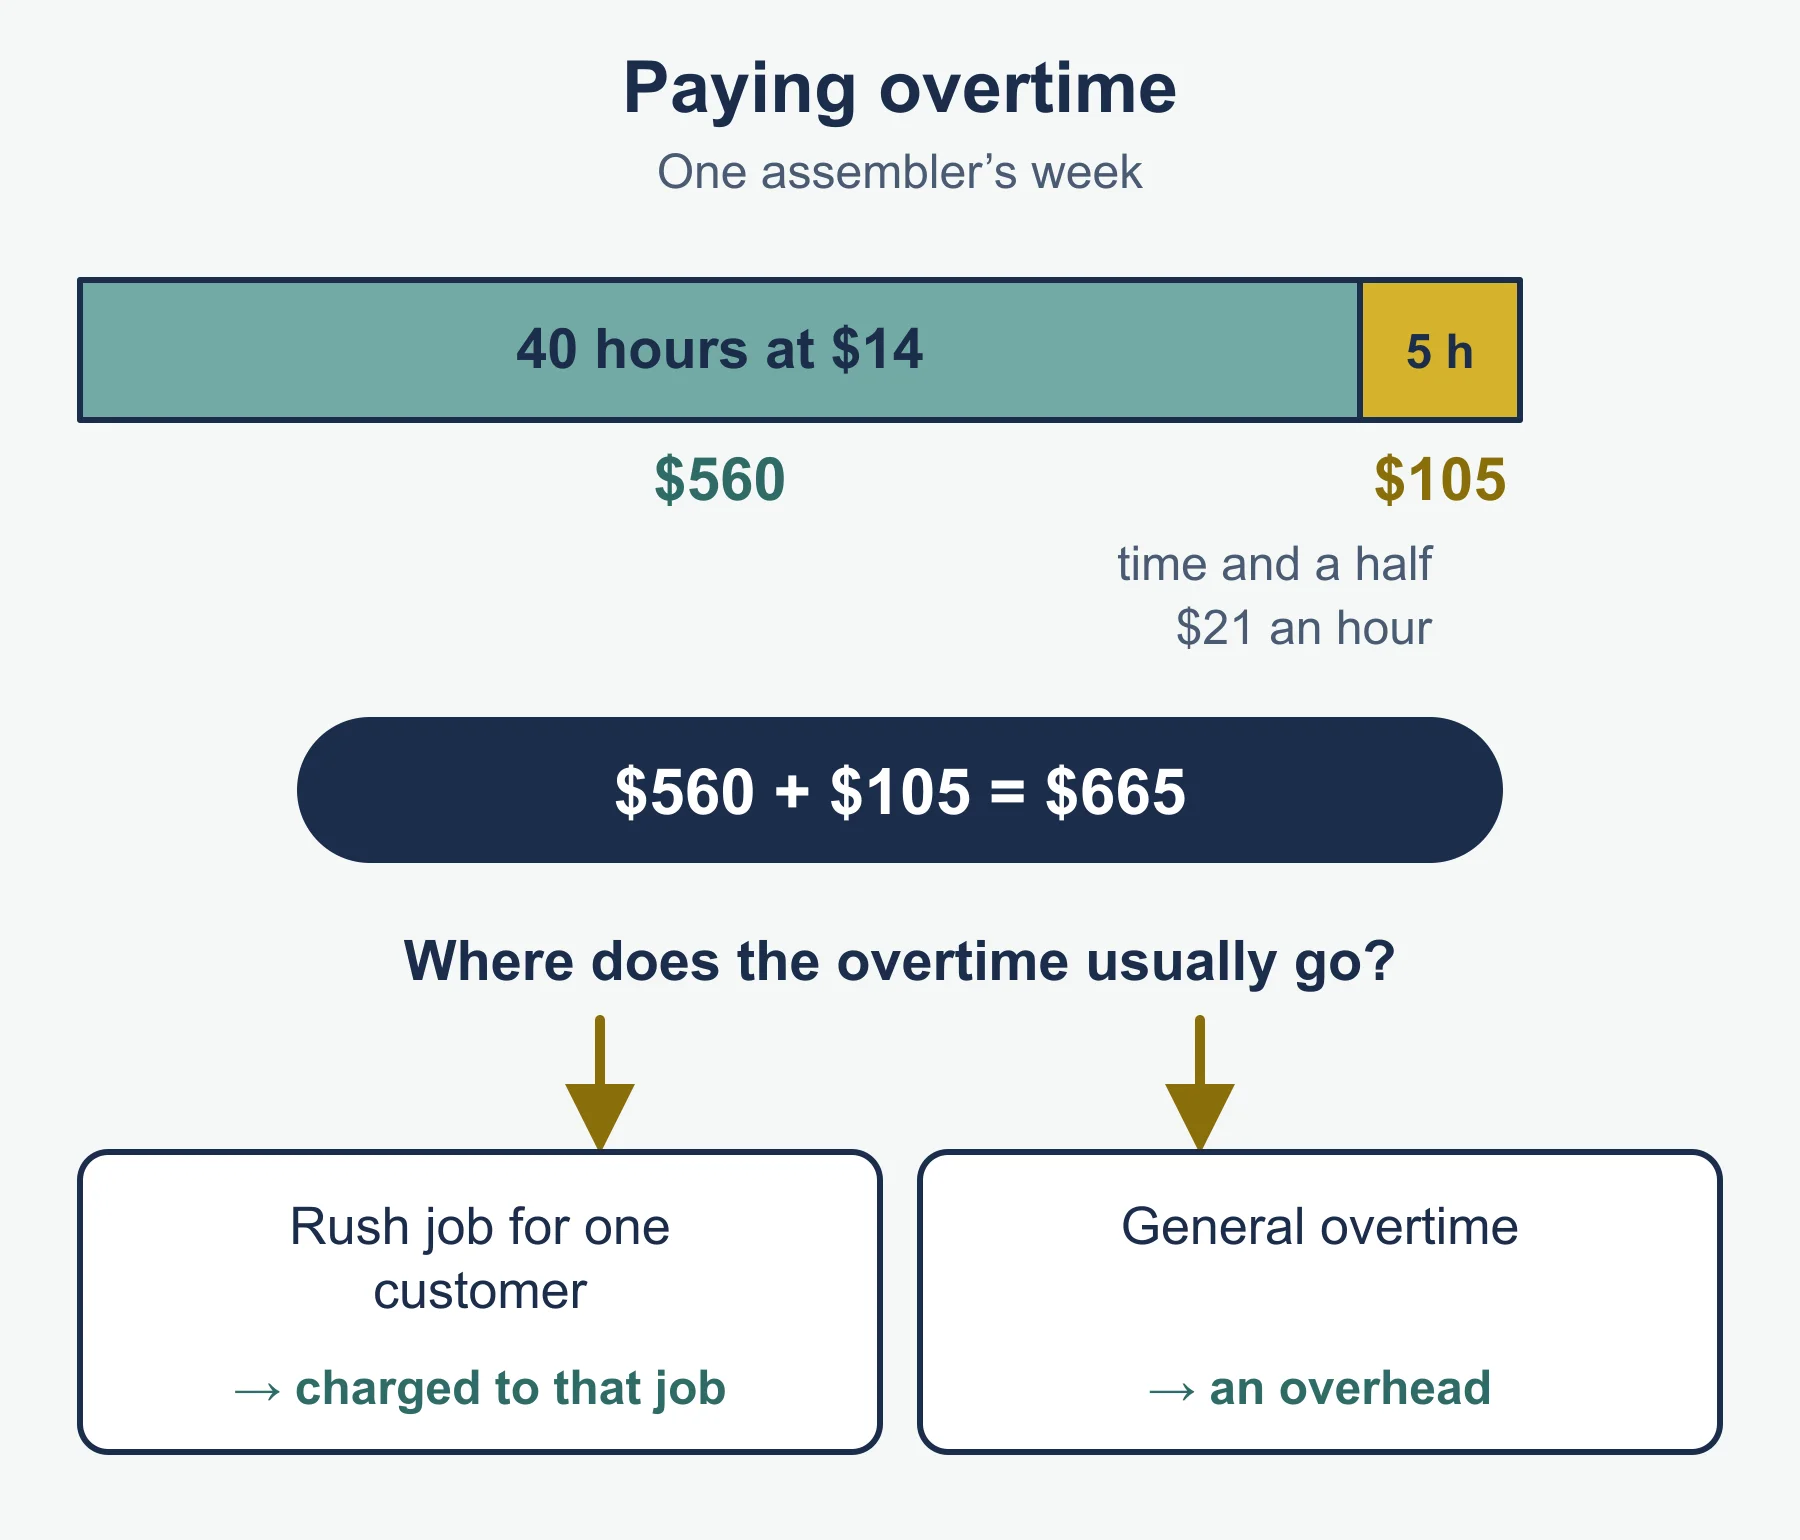
Accounting for labour. Gross wages are split into direct labour (time spent on units or jobs) and indirect labour (supervision, cleaning). An assembler works 40 hours at 14 and 5 overtime hours at time-and-a-half (21): 560 + 105 = 665. Overtime caused by one customer’s rush job is usually charged to that job; general overtime is an overhead.
Accounting for materials. Issues from inventory are charged to a unit or job if direct, or to overheads if indirect, at a value set by the inventory method.
2. Valuing inventory: FIFO and AVCO
FIFO assumes the oldest items are issued first, so closing inventory is the newest purchases. AVCO uses a weighted average cost. Under the periodic method, inventory is counted at the end of the period and valued once. Under the perpetual method, a record is updated after every receipt and issue.
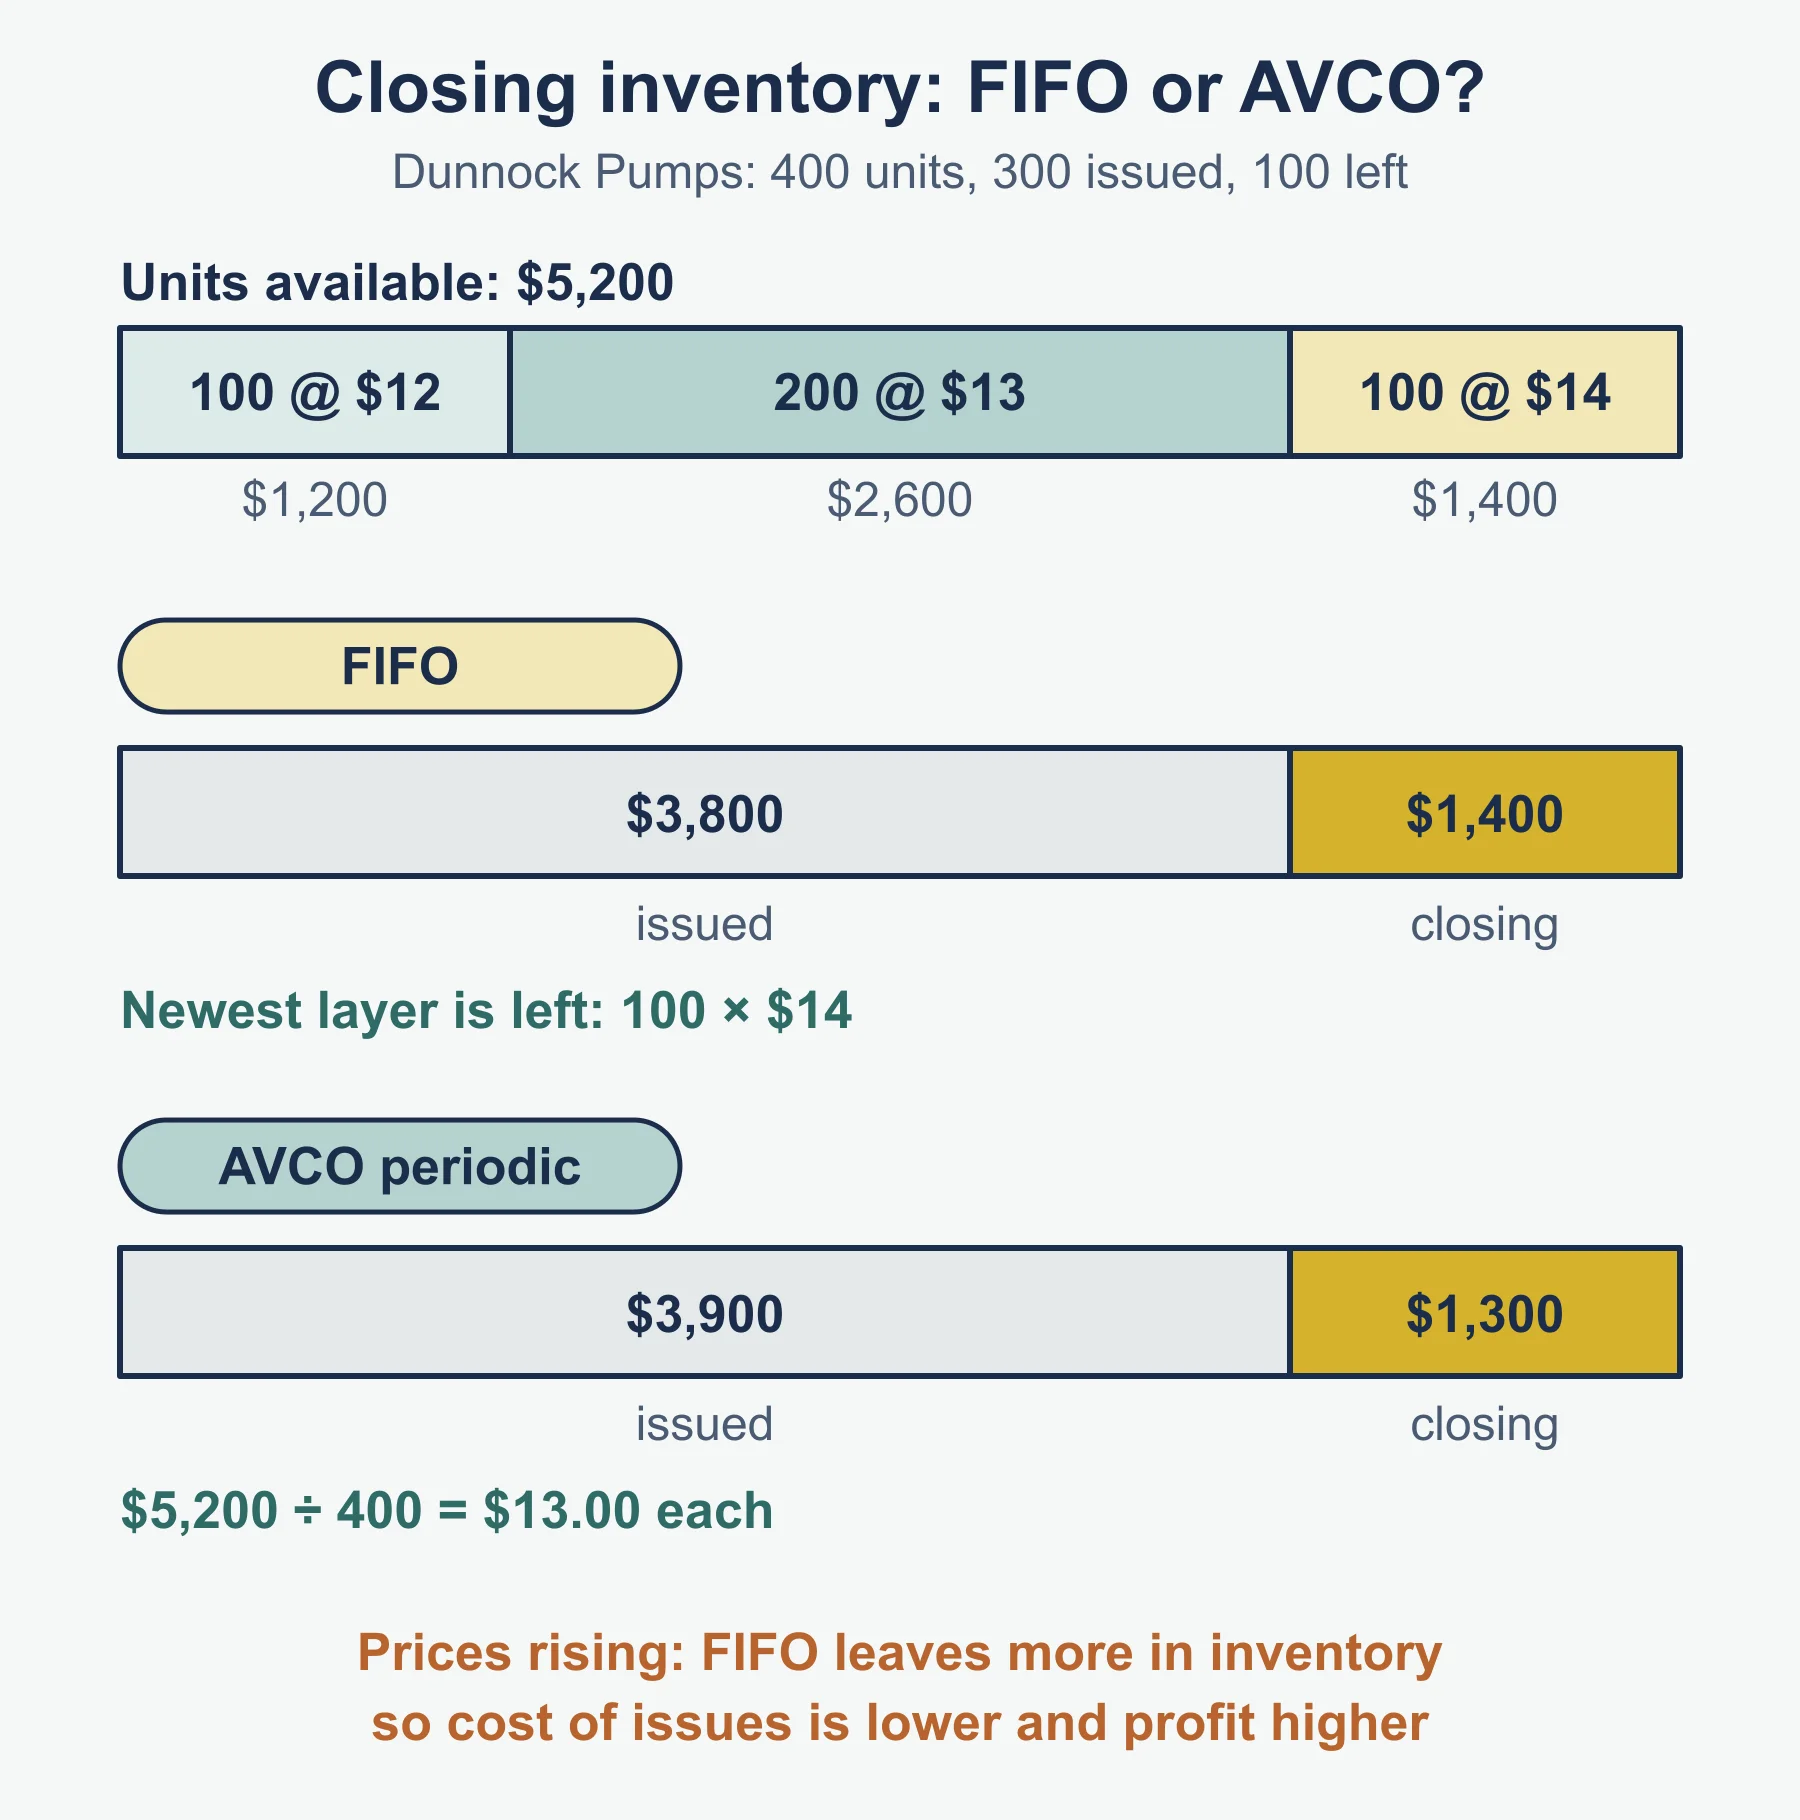
Dunnock Pumps: opening 100 units at 12; buys 200 at 13 (5 March); issues 150 (12 March); buys 100 at 14 (18 March); issues 150 (25 March). Closing inventory is 100 units.
- Periodic FIFO. Closing 100 × 14 = 1,400.
- Periodic AVCO. Total cost 1,200 + 2,600 + 1,400 = 5,200 for 400 units, an average of 13.00. Closing is 1,300.
- Perpetual FIFO. The first issue takes 100 at 12 and 50 at 13 (1,850); the second takes 150 at 13 (1,950). Closing is 100 at 14 = 1,400, as in periodic FIFO.
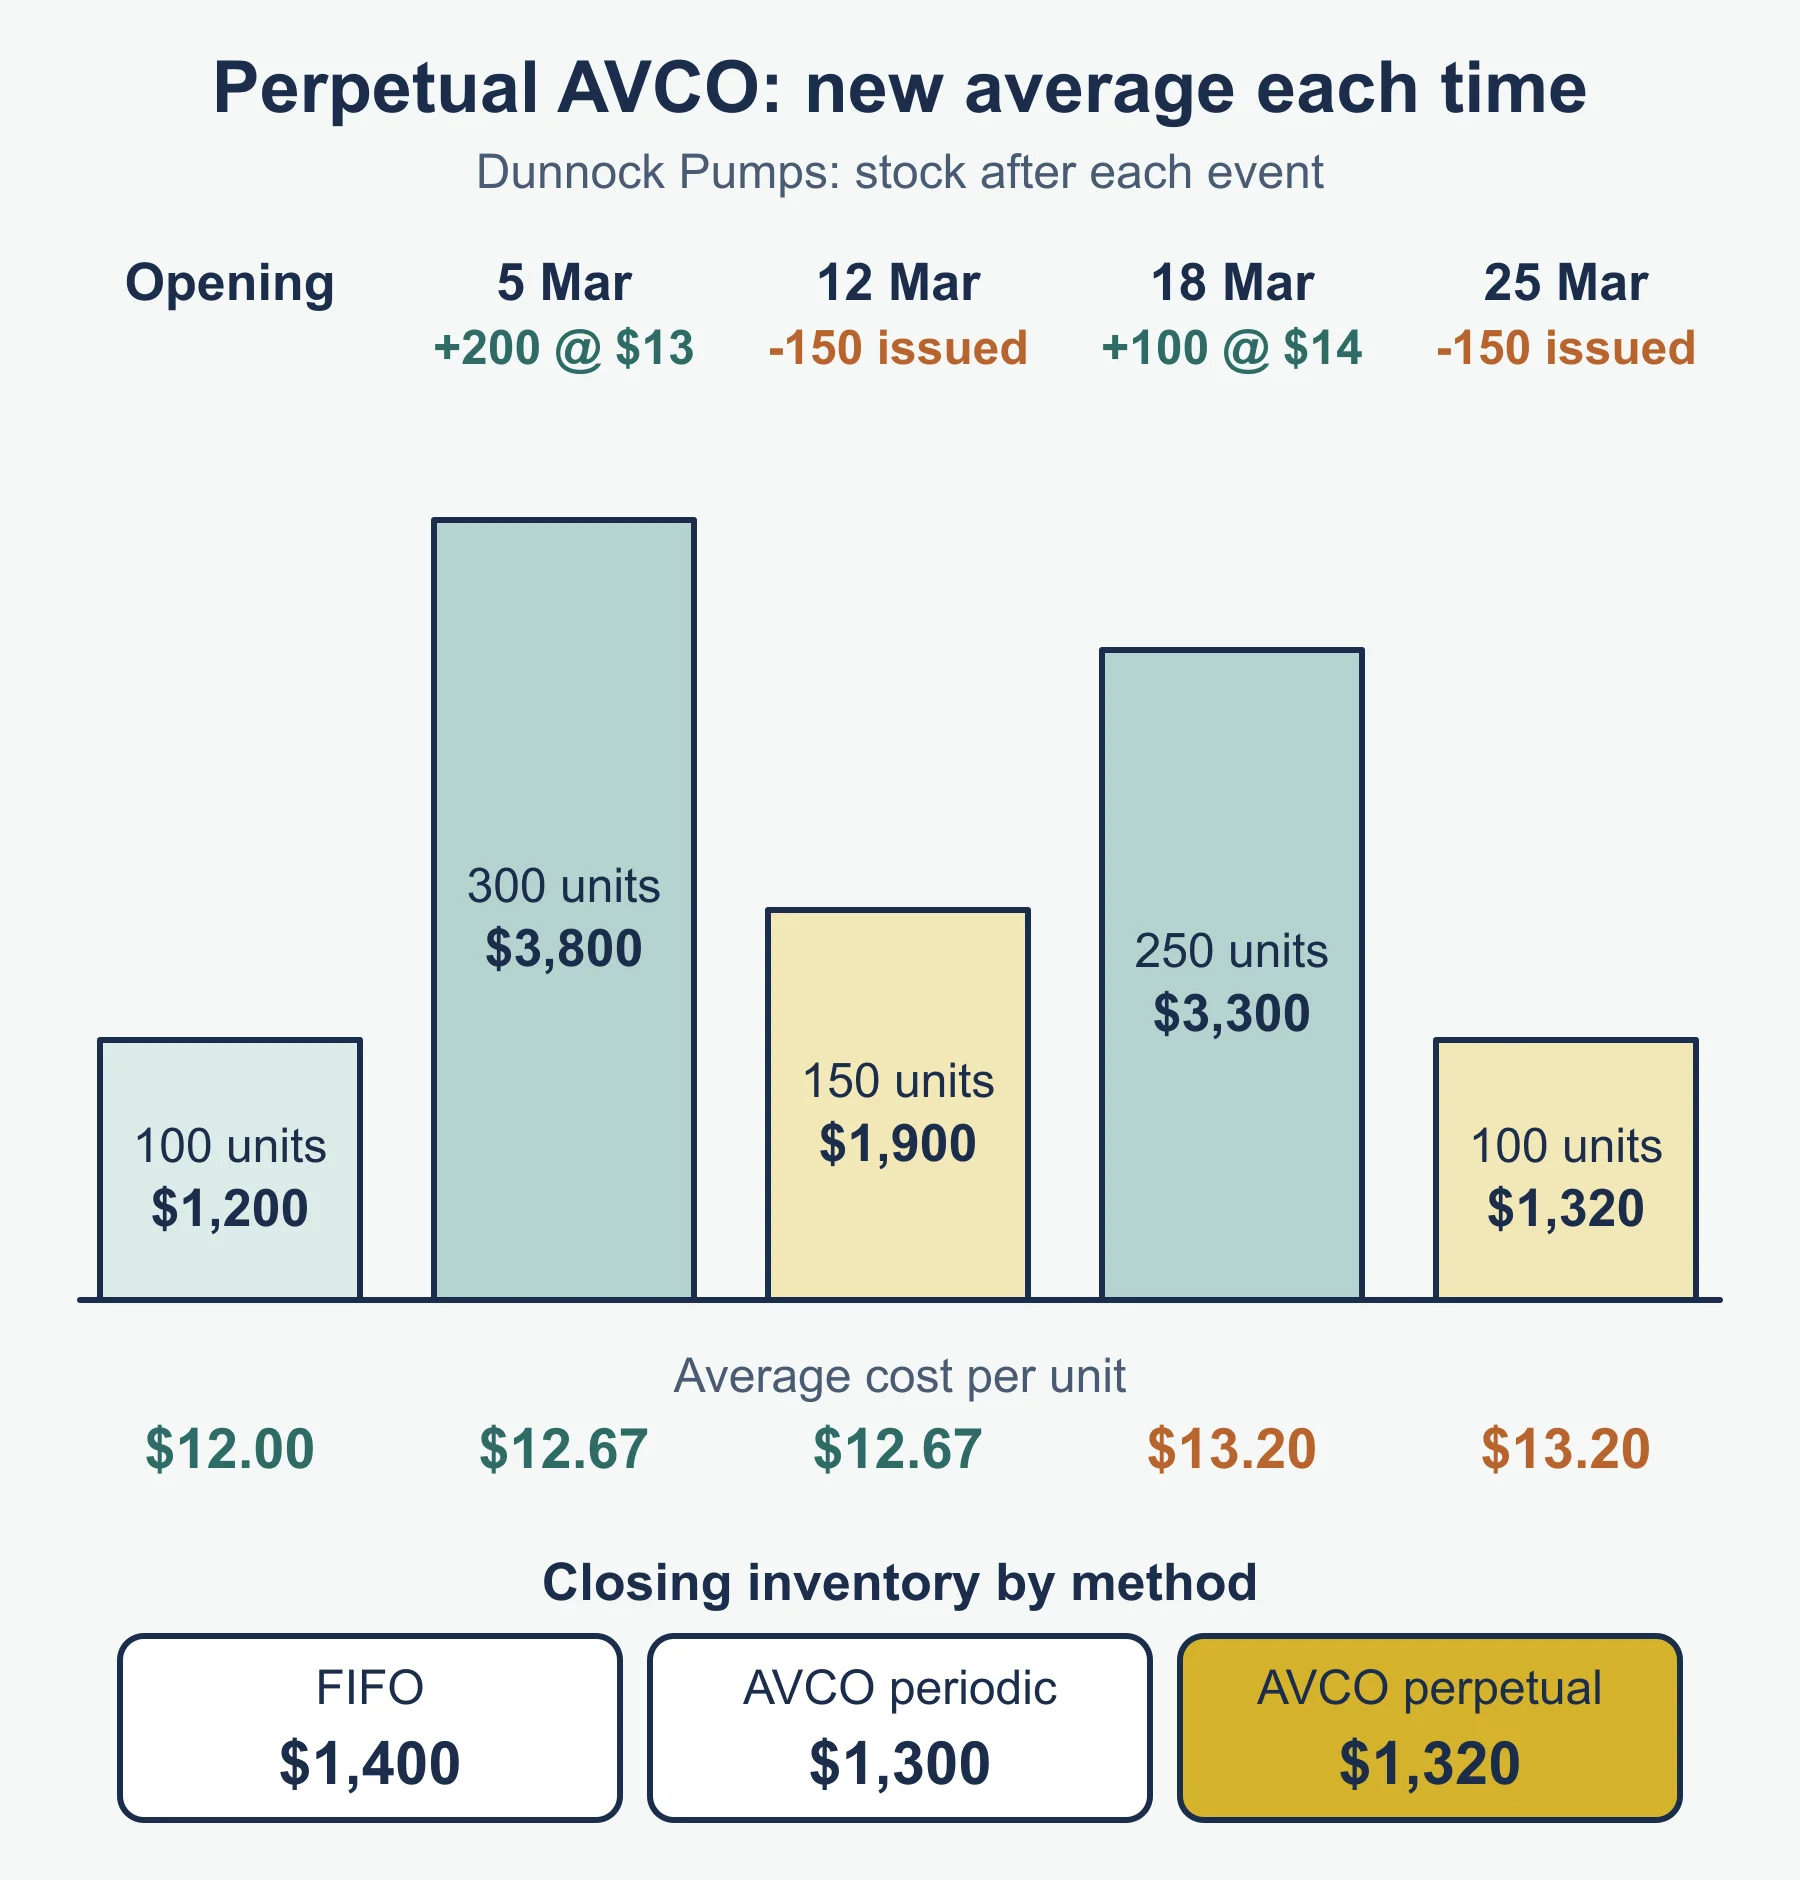
- Perpetual AVCO. After 5 March: 300 units worth 3,800, average 12.67; the issue costs 1,900, leaving 150 worth 1,900. After 18 March: 250 units worth 3,300, average 13.20; the issue costs 1,980, leaving 100 worth 1,320.
| Method | Closing inventory | Cost of issues |
|---|---|---|
| FIFO (periodic and perpetual) | 1,400 | 3,800 |
| AVCO periodic | 1,300 | 3,900 |
| AVCO perpetual | 1,320 | 3,880 |
Cost of issues = 5,200 minus closing inventory. With rising prices FIFO gives the highest profit.
3. Just in time (JIT)
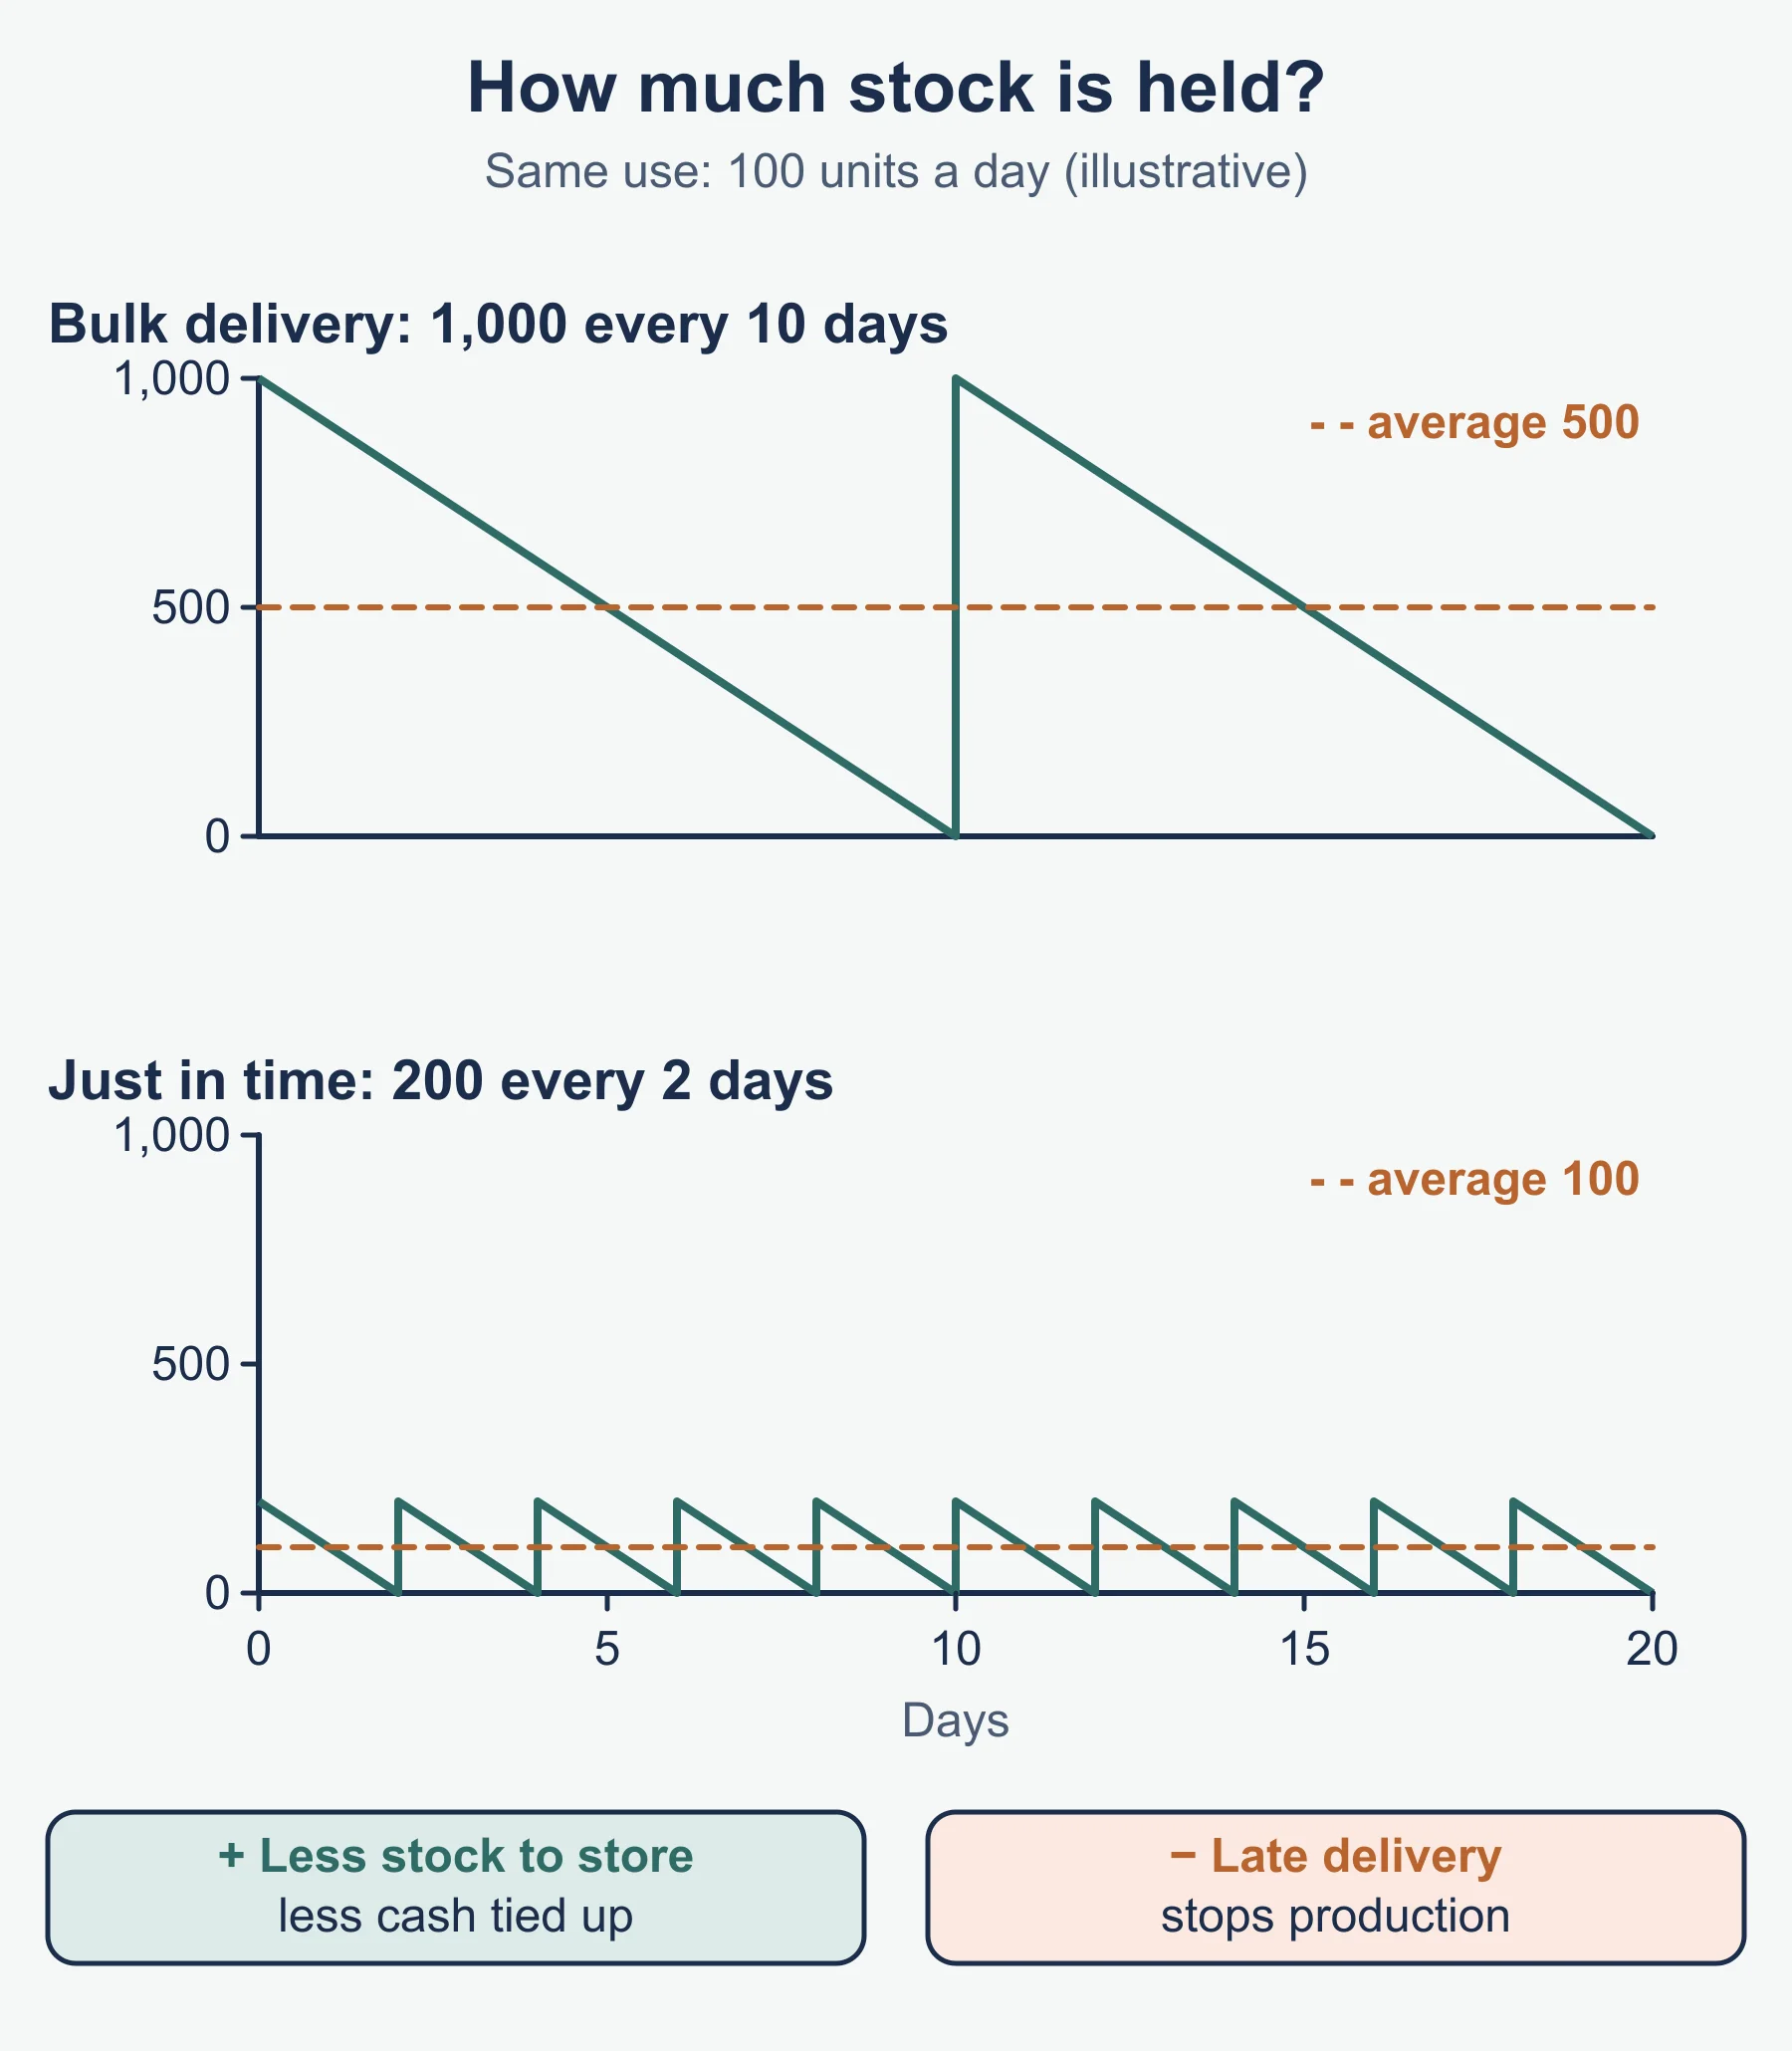
JIT management of inventory means materials arrive close to when production needs them, in small frequent deliveries, so little inventory is held. It relies on reliable suppliers and accurate planning. Benefits: lower storage costs, less cash tied up, less damage or obsolescence. Risks: a late delivery stops production, bulk discounts are lost, and ordering and delivery costs rise. It needs reliable suppliers and predictable demand.
4. Costing applications: unit, job and batch
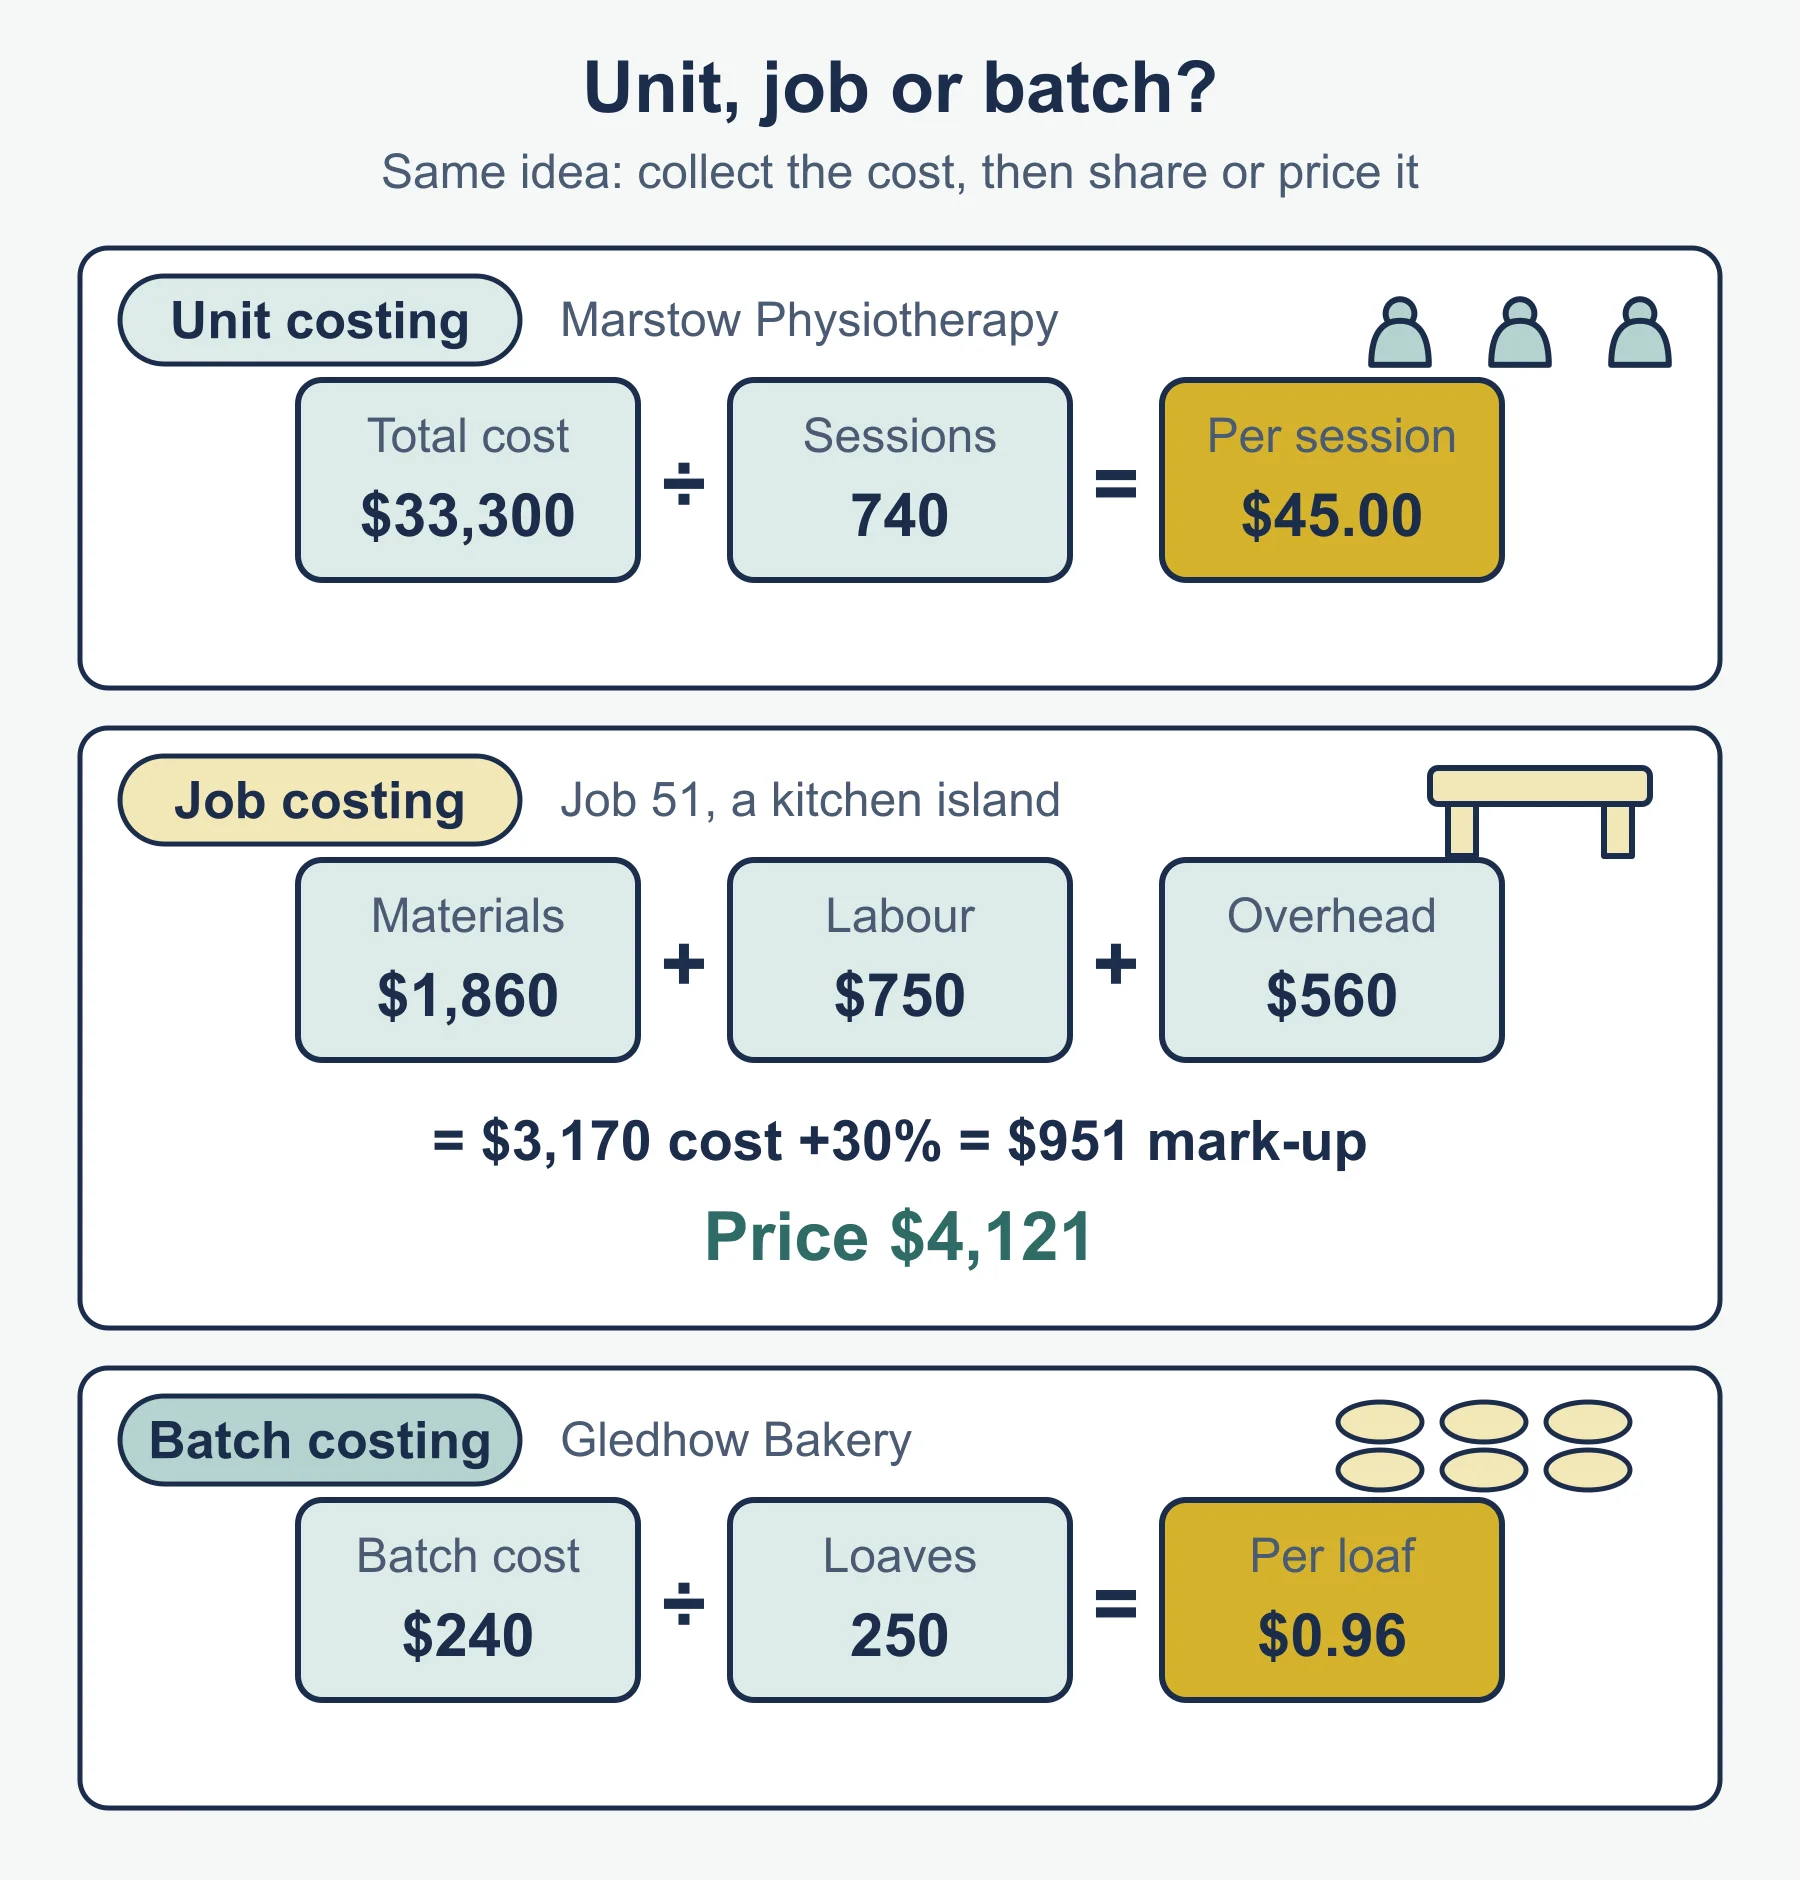
- Unit costing suits identical output or a repeated service. Cost per unit = total cost / units.
- Job costing suits work done to a customer’s specification. Costs are collected for each job and a price is set from the total.
- Batch costing suits groups of identical items made together. Cost per item = batch cost / items in the batch.
Each applies in manufacturing and services. Marstow Physiotherapy gave 740 sessions at a cost of 27,000 salaries, 4,500 rent and utilities and 1,800 consumables: 33,300 / 740 = 45.00 per session (unit costing, service). Gledhow Bakery baked 250 loaves: ingredients 150, labour 4 hours at 15 = 60, overhead 4 hours at 7.50 = 30. Batch cost 240; cost per loaf 0.96. Job costing is worked in Section 5.
5. Absorption costing
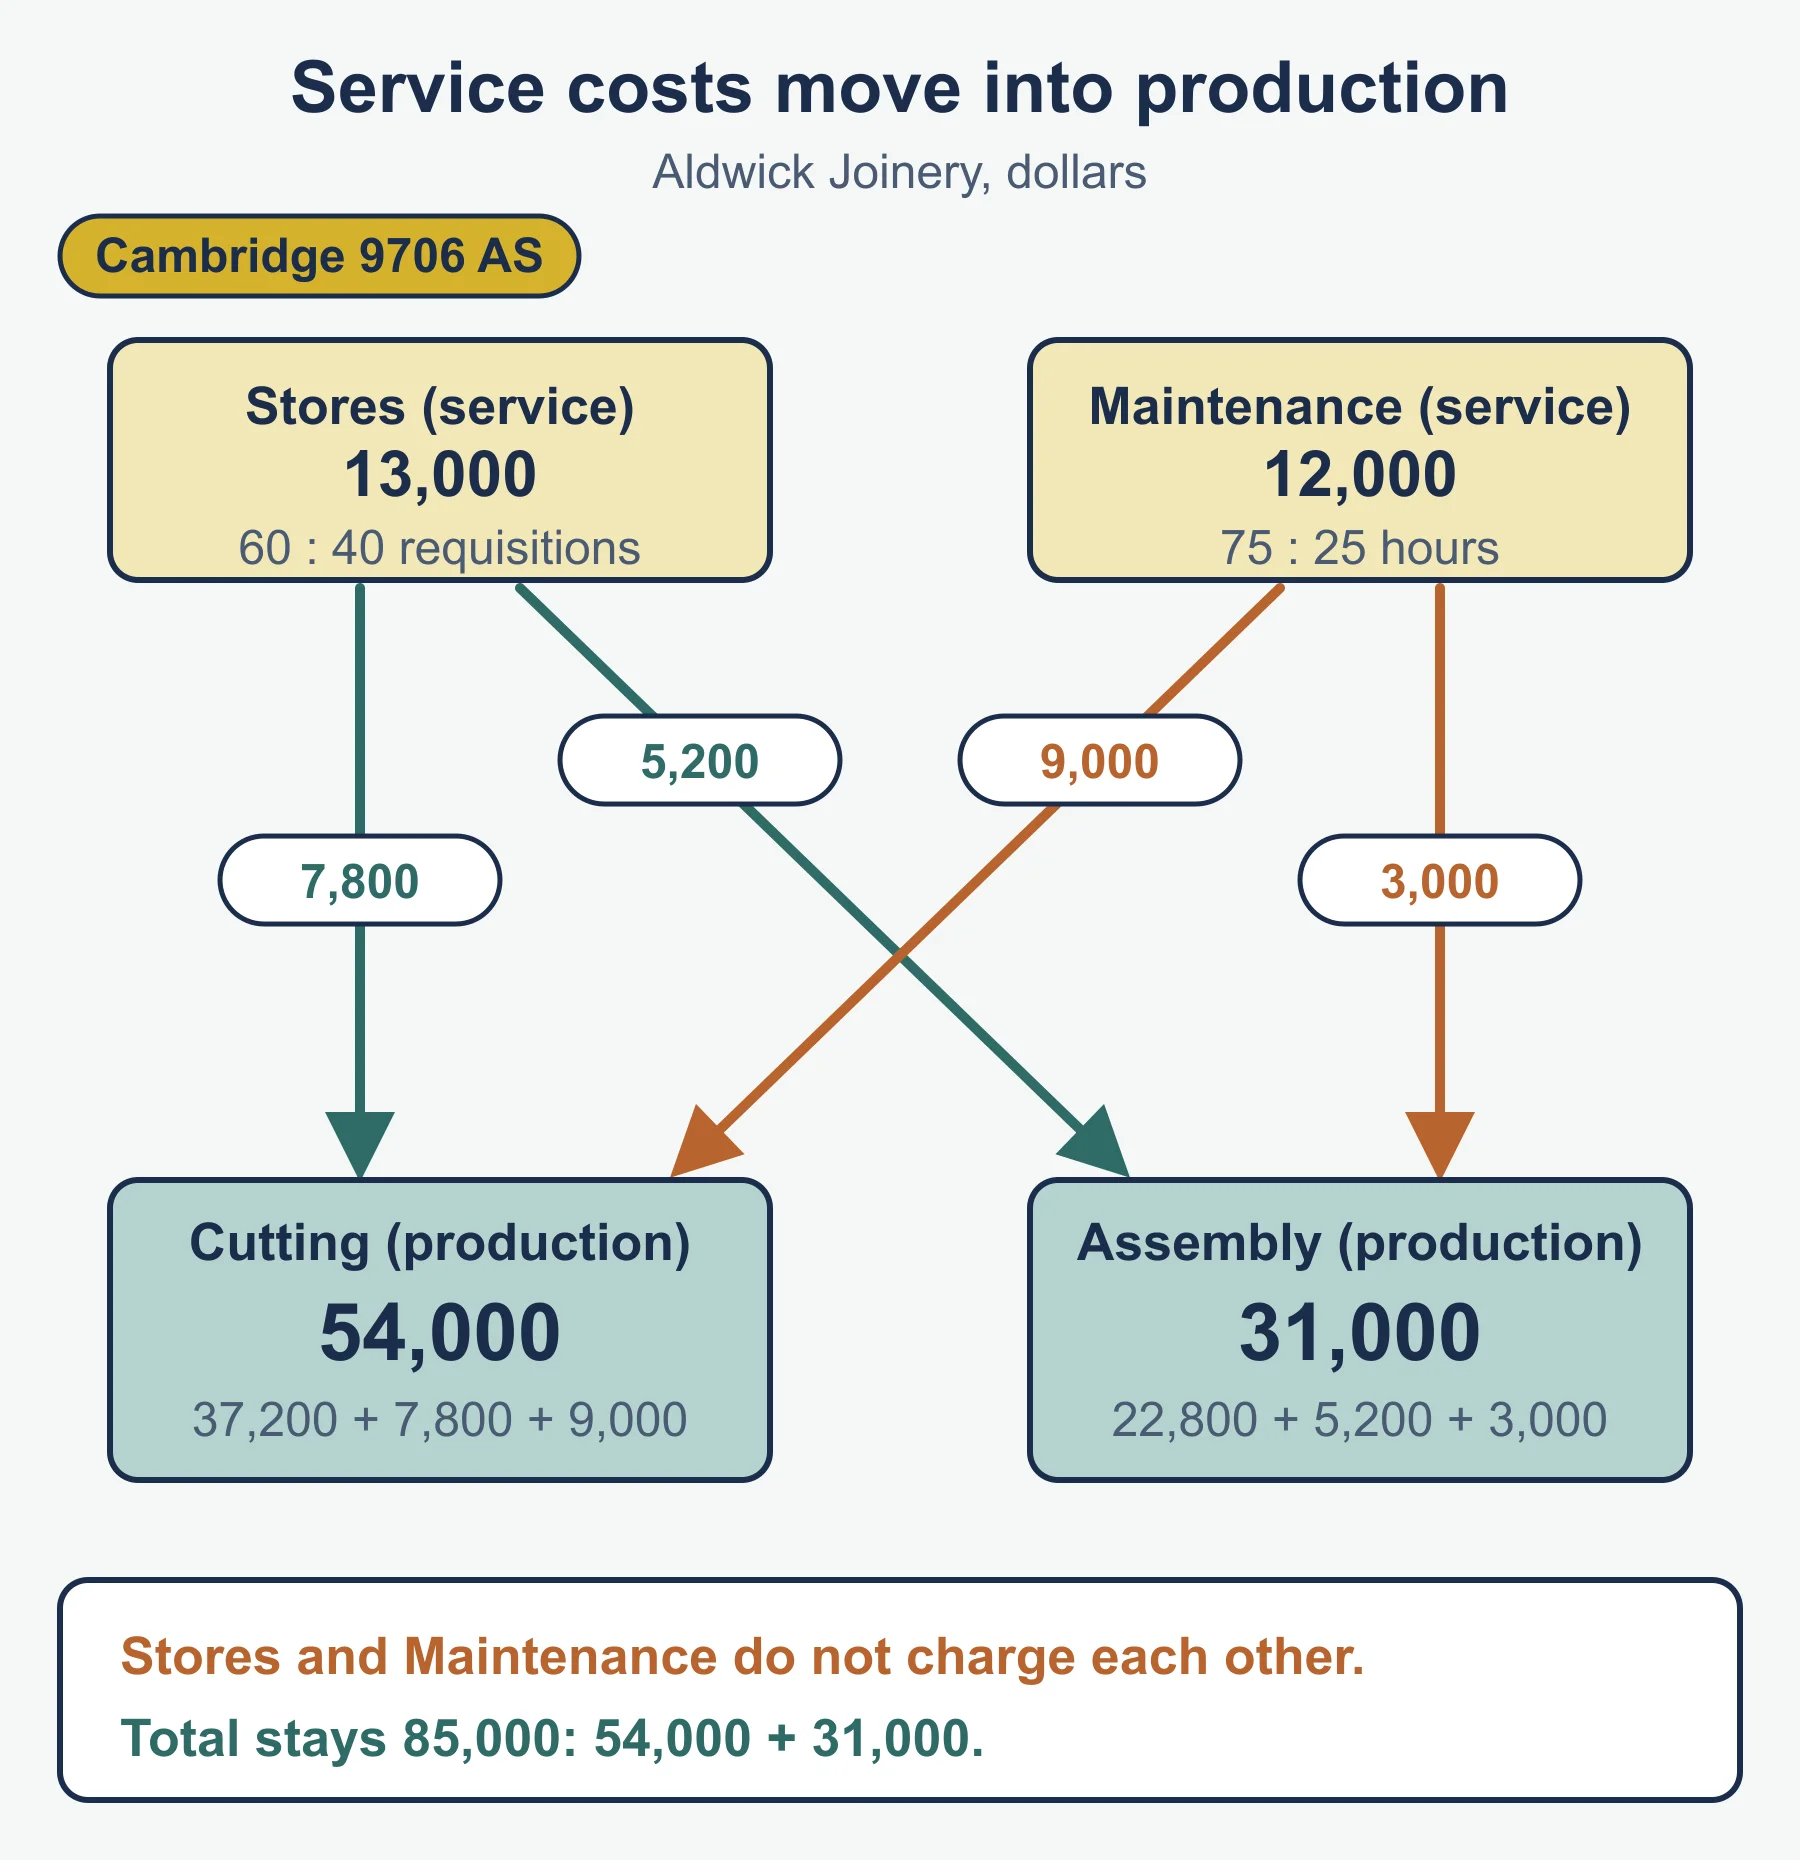
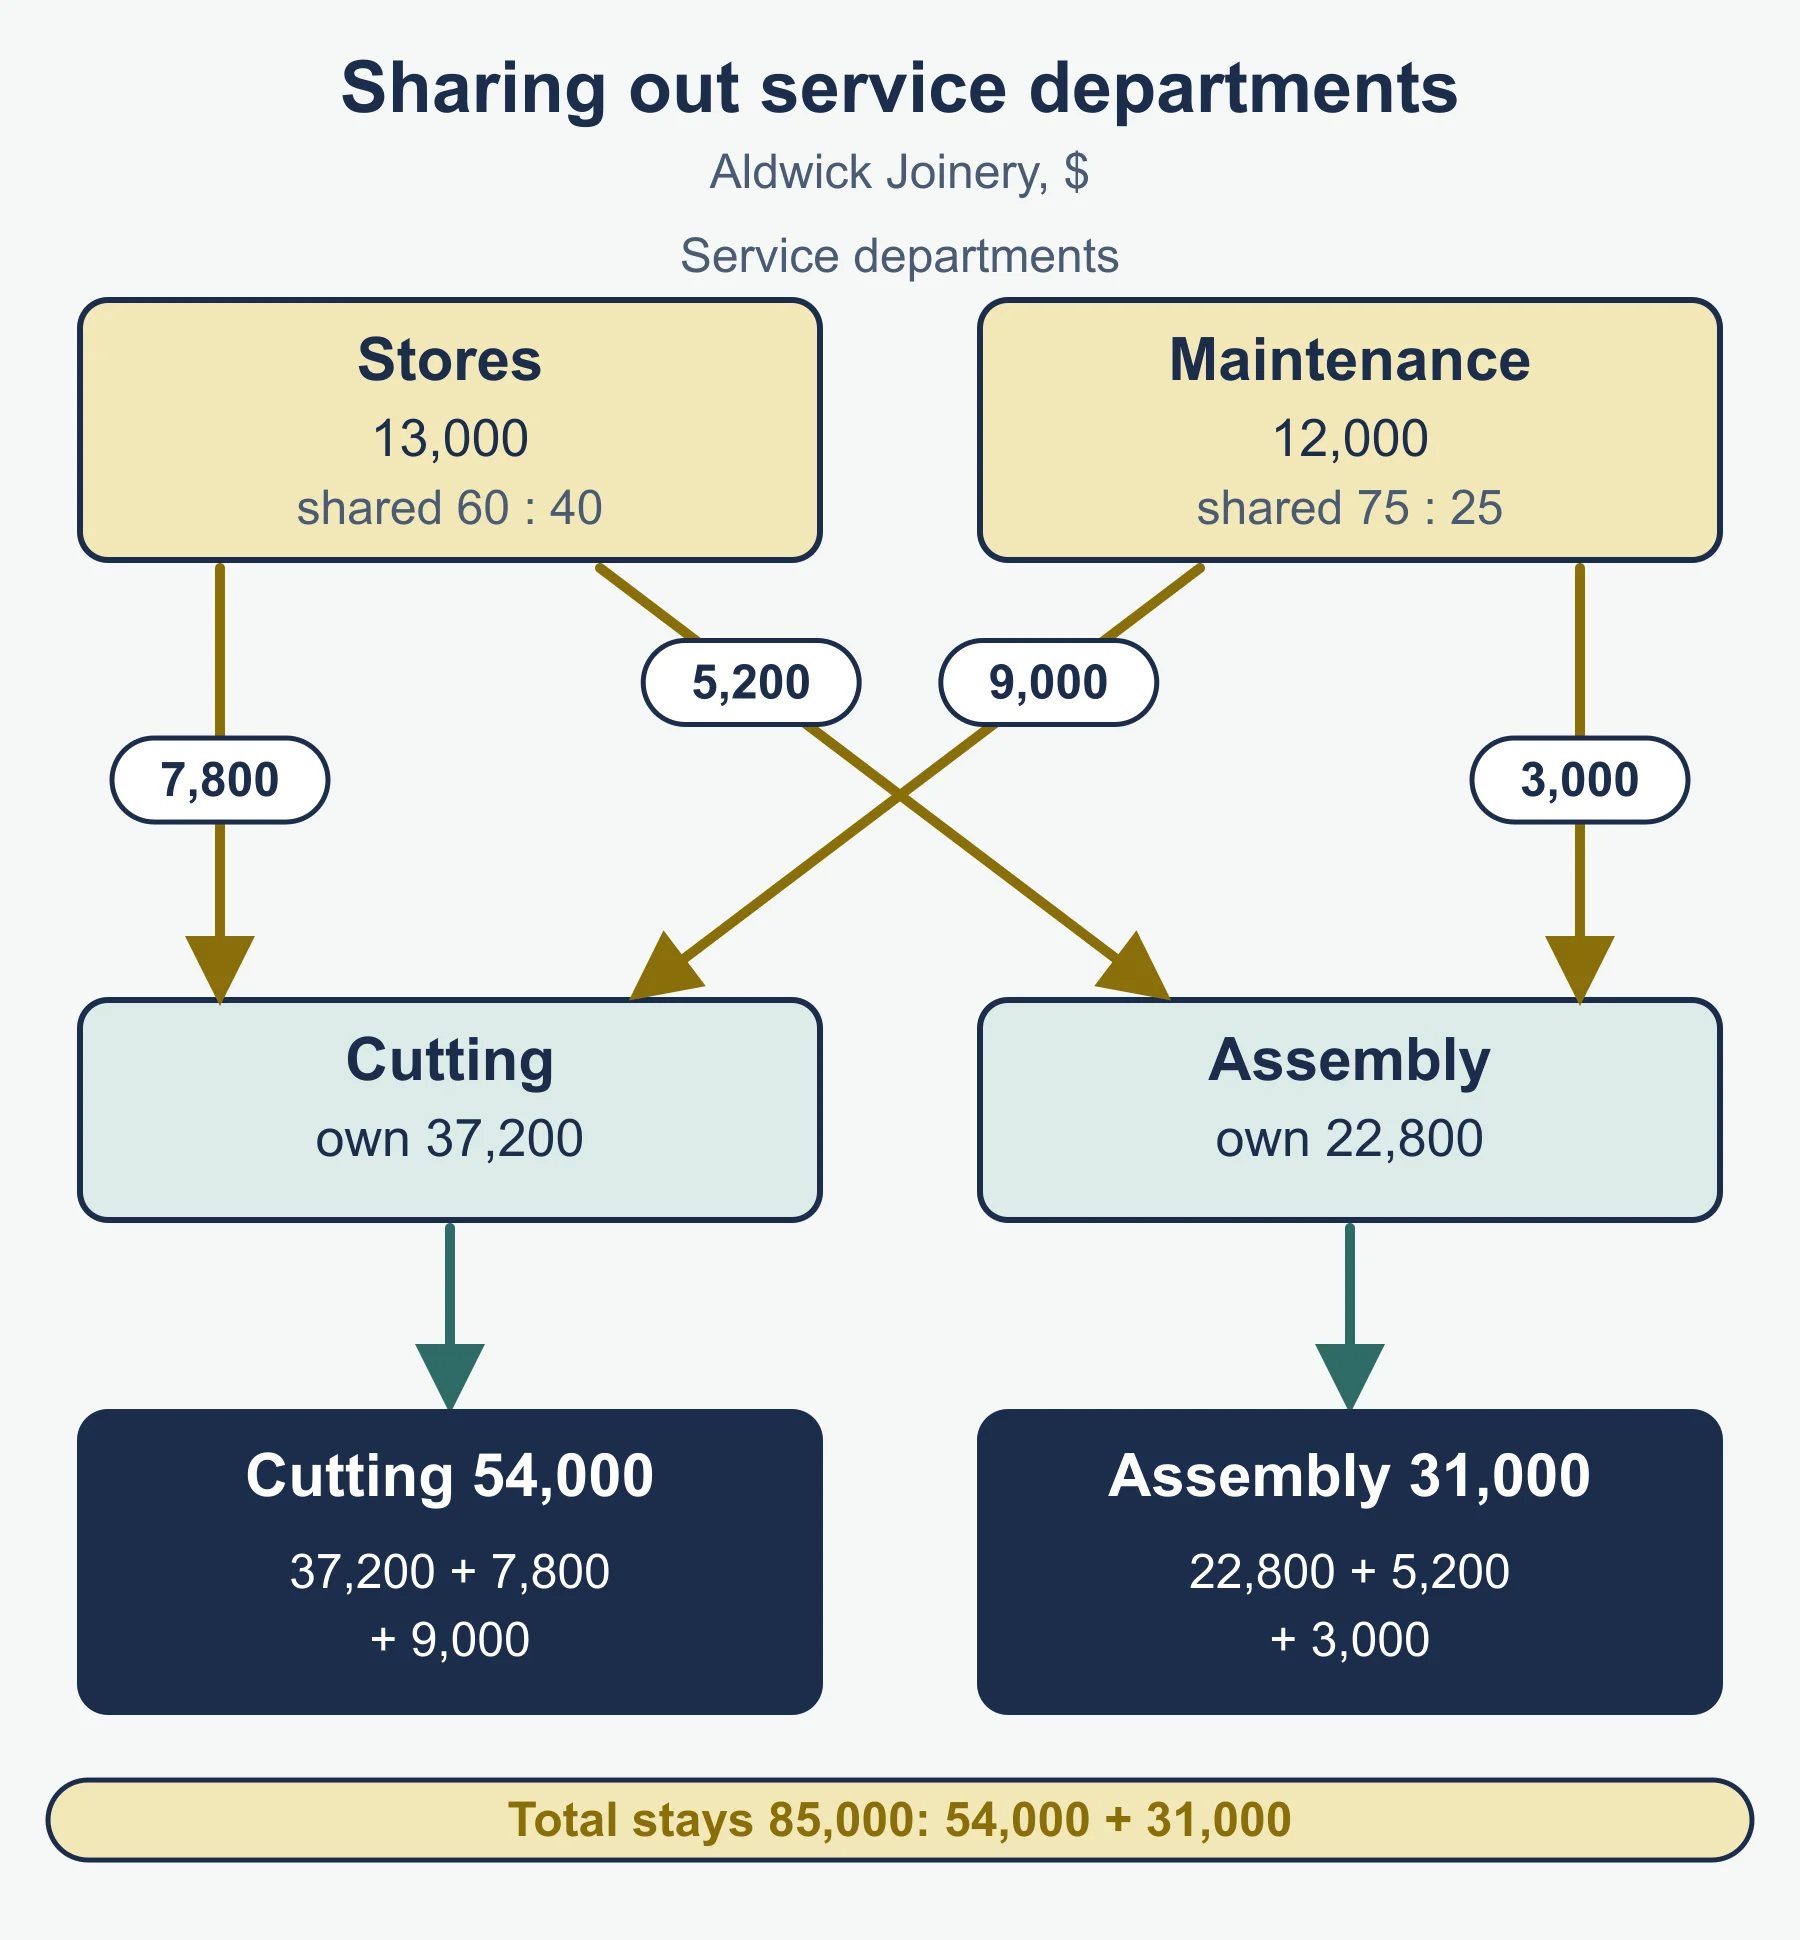
A cost centre is a department, process or location for which costs are collected. A cost unit is the unit of product or service to which costs are charged. Overheads are allocated when they belong wholly to one centre and apportioned when shared on a fair basis (floor area for rent, machine value for insurance). Service department costs are then reapportioned to production departments.
Aldwick Joinery has production departments Cutting and Assembly and service departments Stores and Maintenance.
| Overhead | Basis | Total | Cutting | Assembly | Stores | Maintenance |
|---|---|---|---|---|---|---|
| Rent | Floor area | 36,000 | 18,000 | 9,000 | 6,000 | 3,000 |
| Insurance | Machine value | 8,000 | 4,800 | 2,400 | 400 | 400 |
| Indirect labour | Allocated | 41,000 | 14,400 | 11,400 | 6,600 | 8,600 |
| Subtotal | 85,000 | 37,200 | 22,800 | 13,000 | 12,000 | |
| Stores (60:40 requisitions) | 7,800 | 5,200 | (13,000) | |||
| Maintenance (75:25 hours) | 9,000 | 3,000 | (12,000) | |||
| Total | 85,000 | 54,000 | 31,000 |
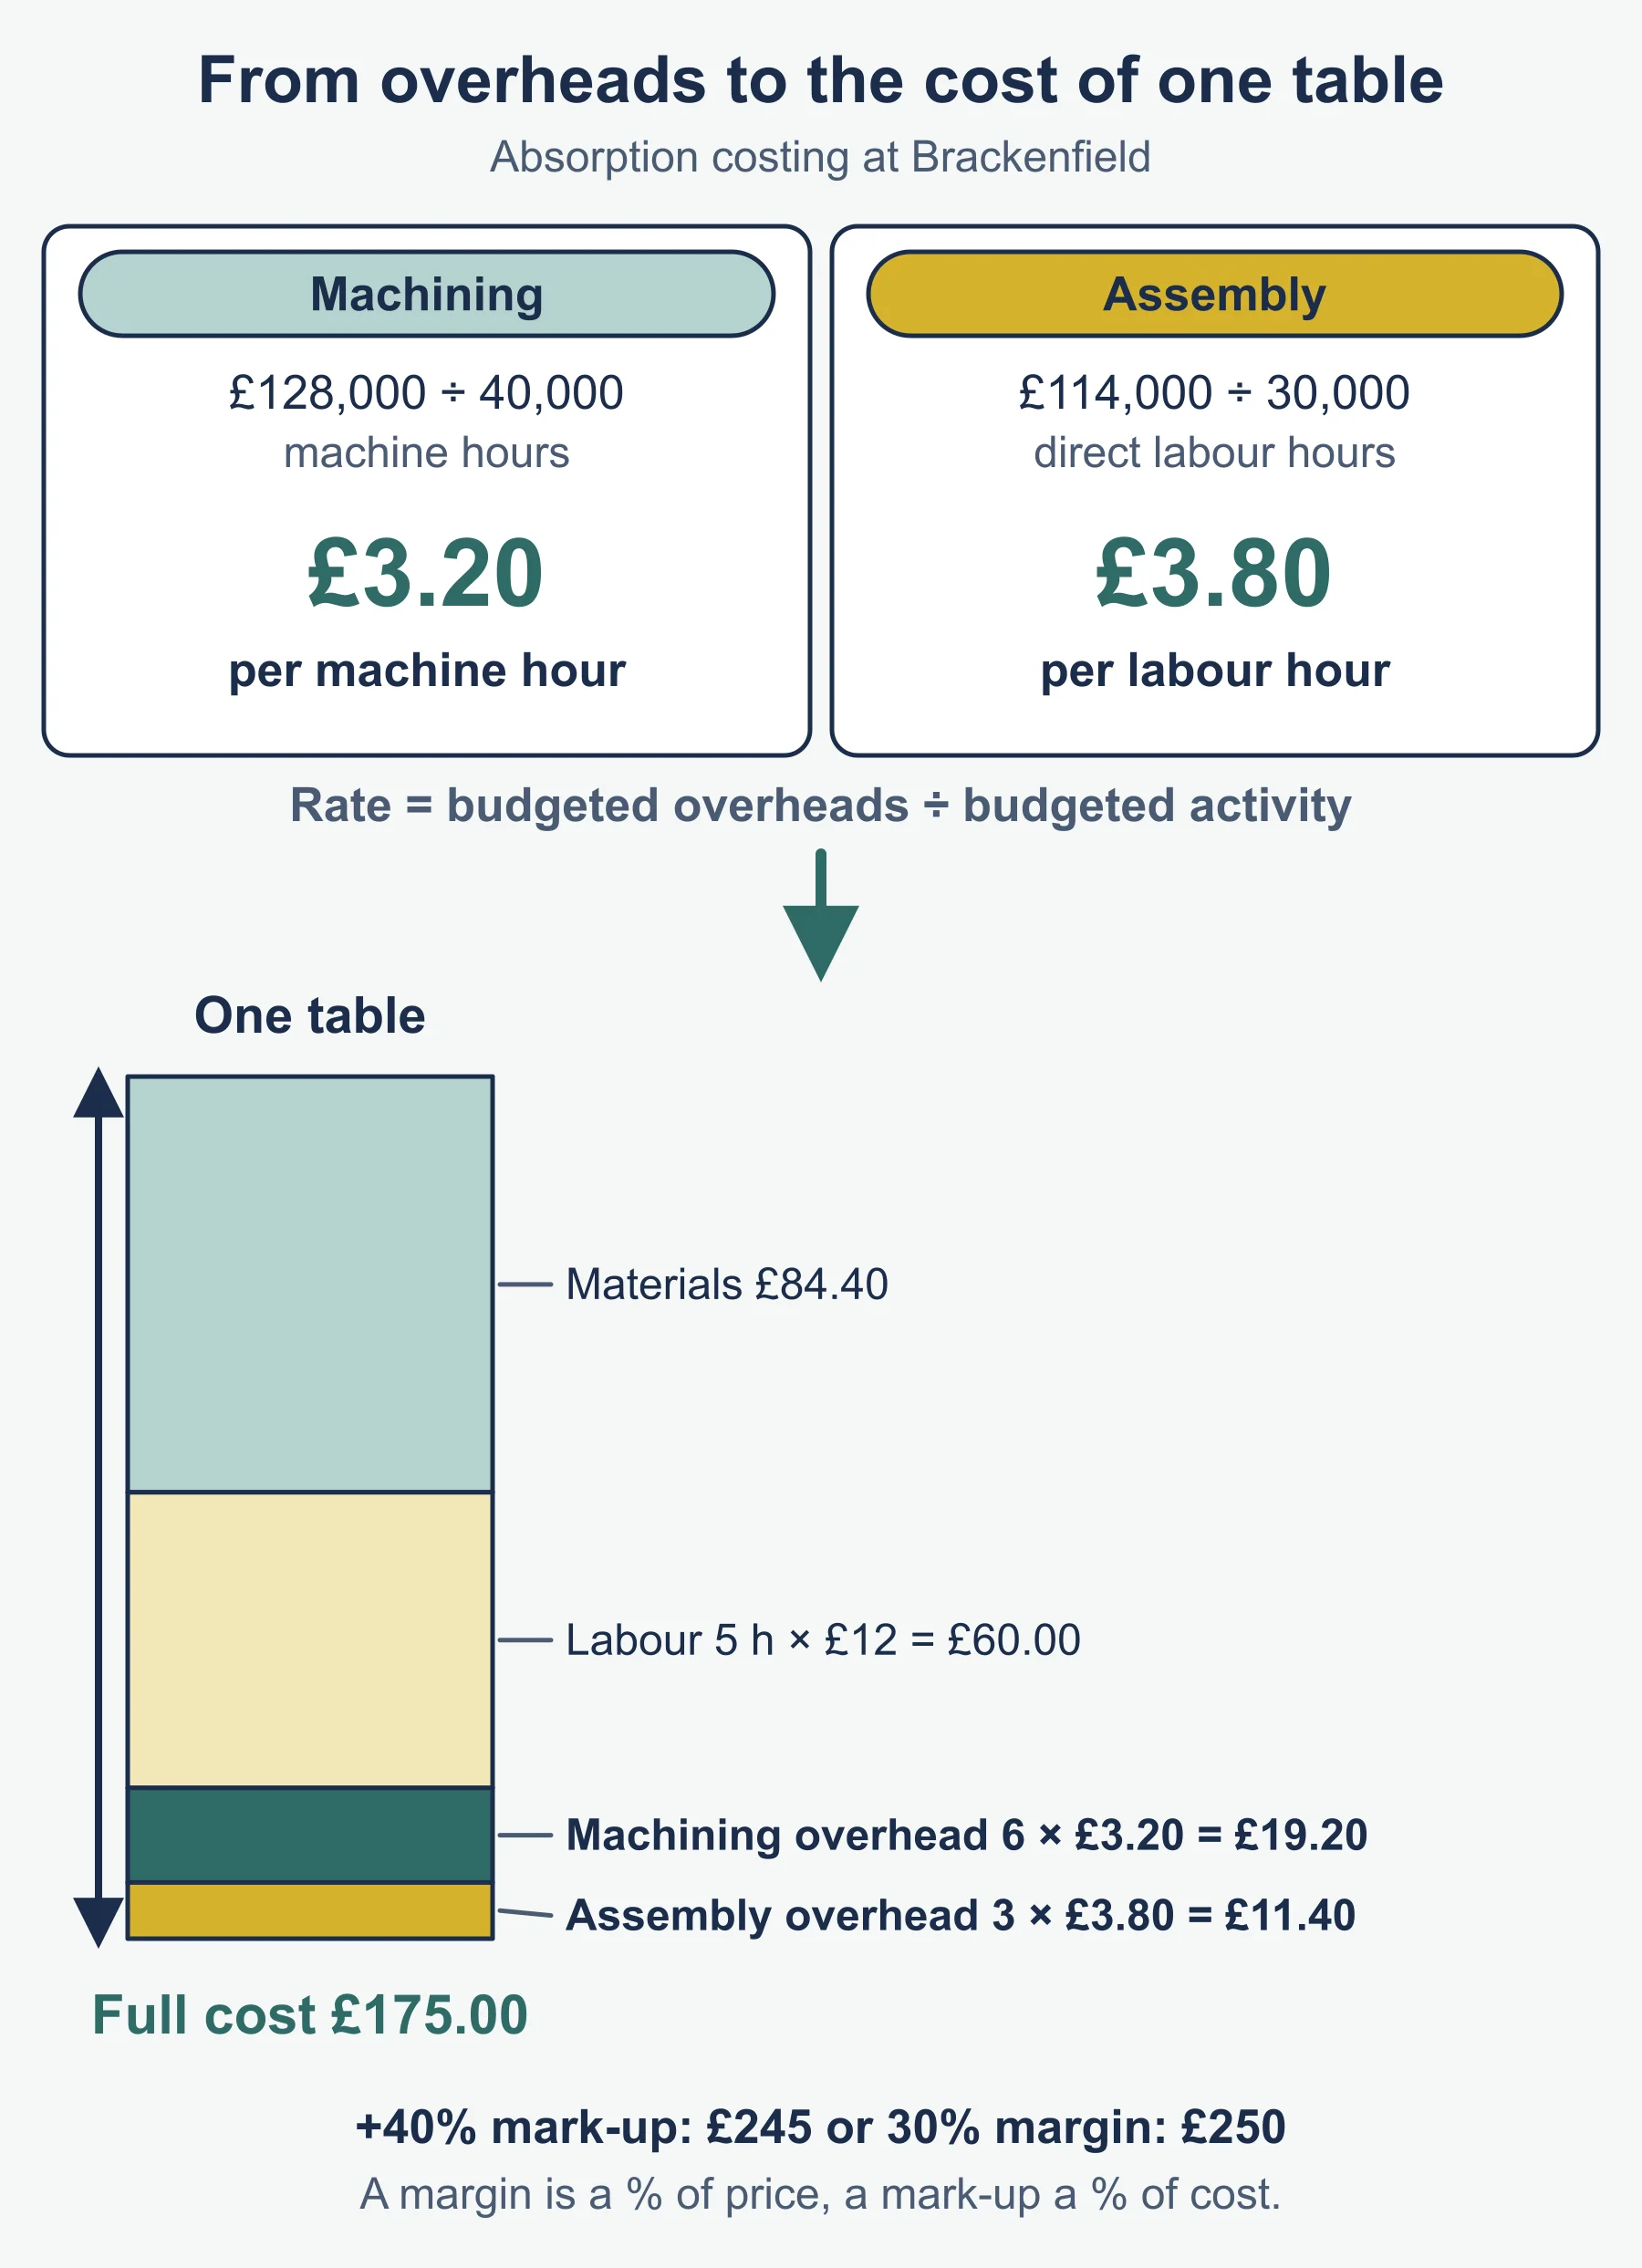
An overhead absorption rate (OAR) is budgeted overhead divided by budgeted activity, on the basis that reflects why the overhead is incurred. Cutting uses machine hours (budget 4,500): 54,000 / 4,500 = 12.00. Assembly uses direct labour hours (budget 6,200): 31,000 / 6,200 = 5.00.
Job 51 (a kitchen island): materials 1,860; labour 10 hours in Cutting and 40 in Assembly at 15 = 750; overhead 30 machine hours × 12 = 360 plus 40 labour hours × 5 = 200. Total cost 3,170. A 30% mark-up (951) gives a price of 4,121.
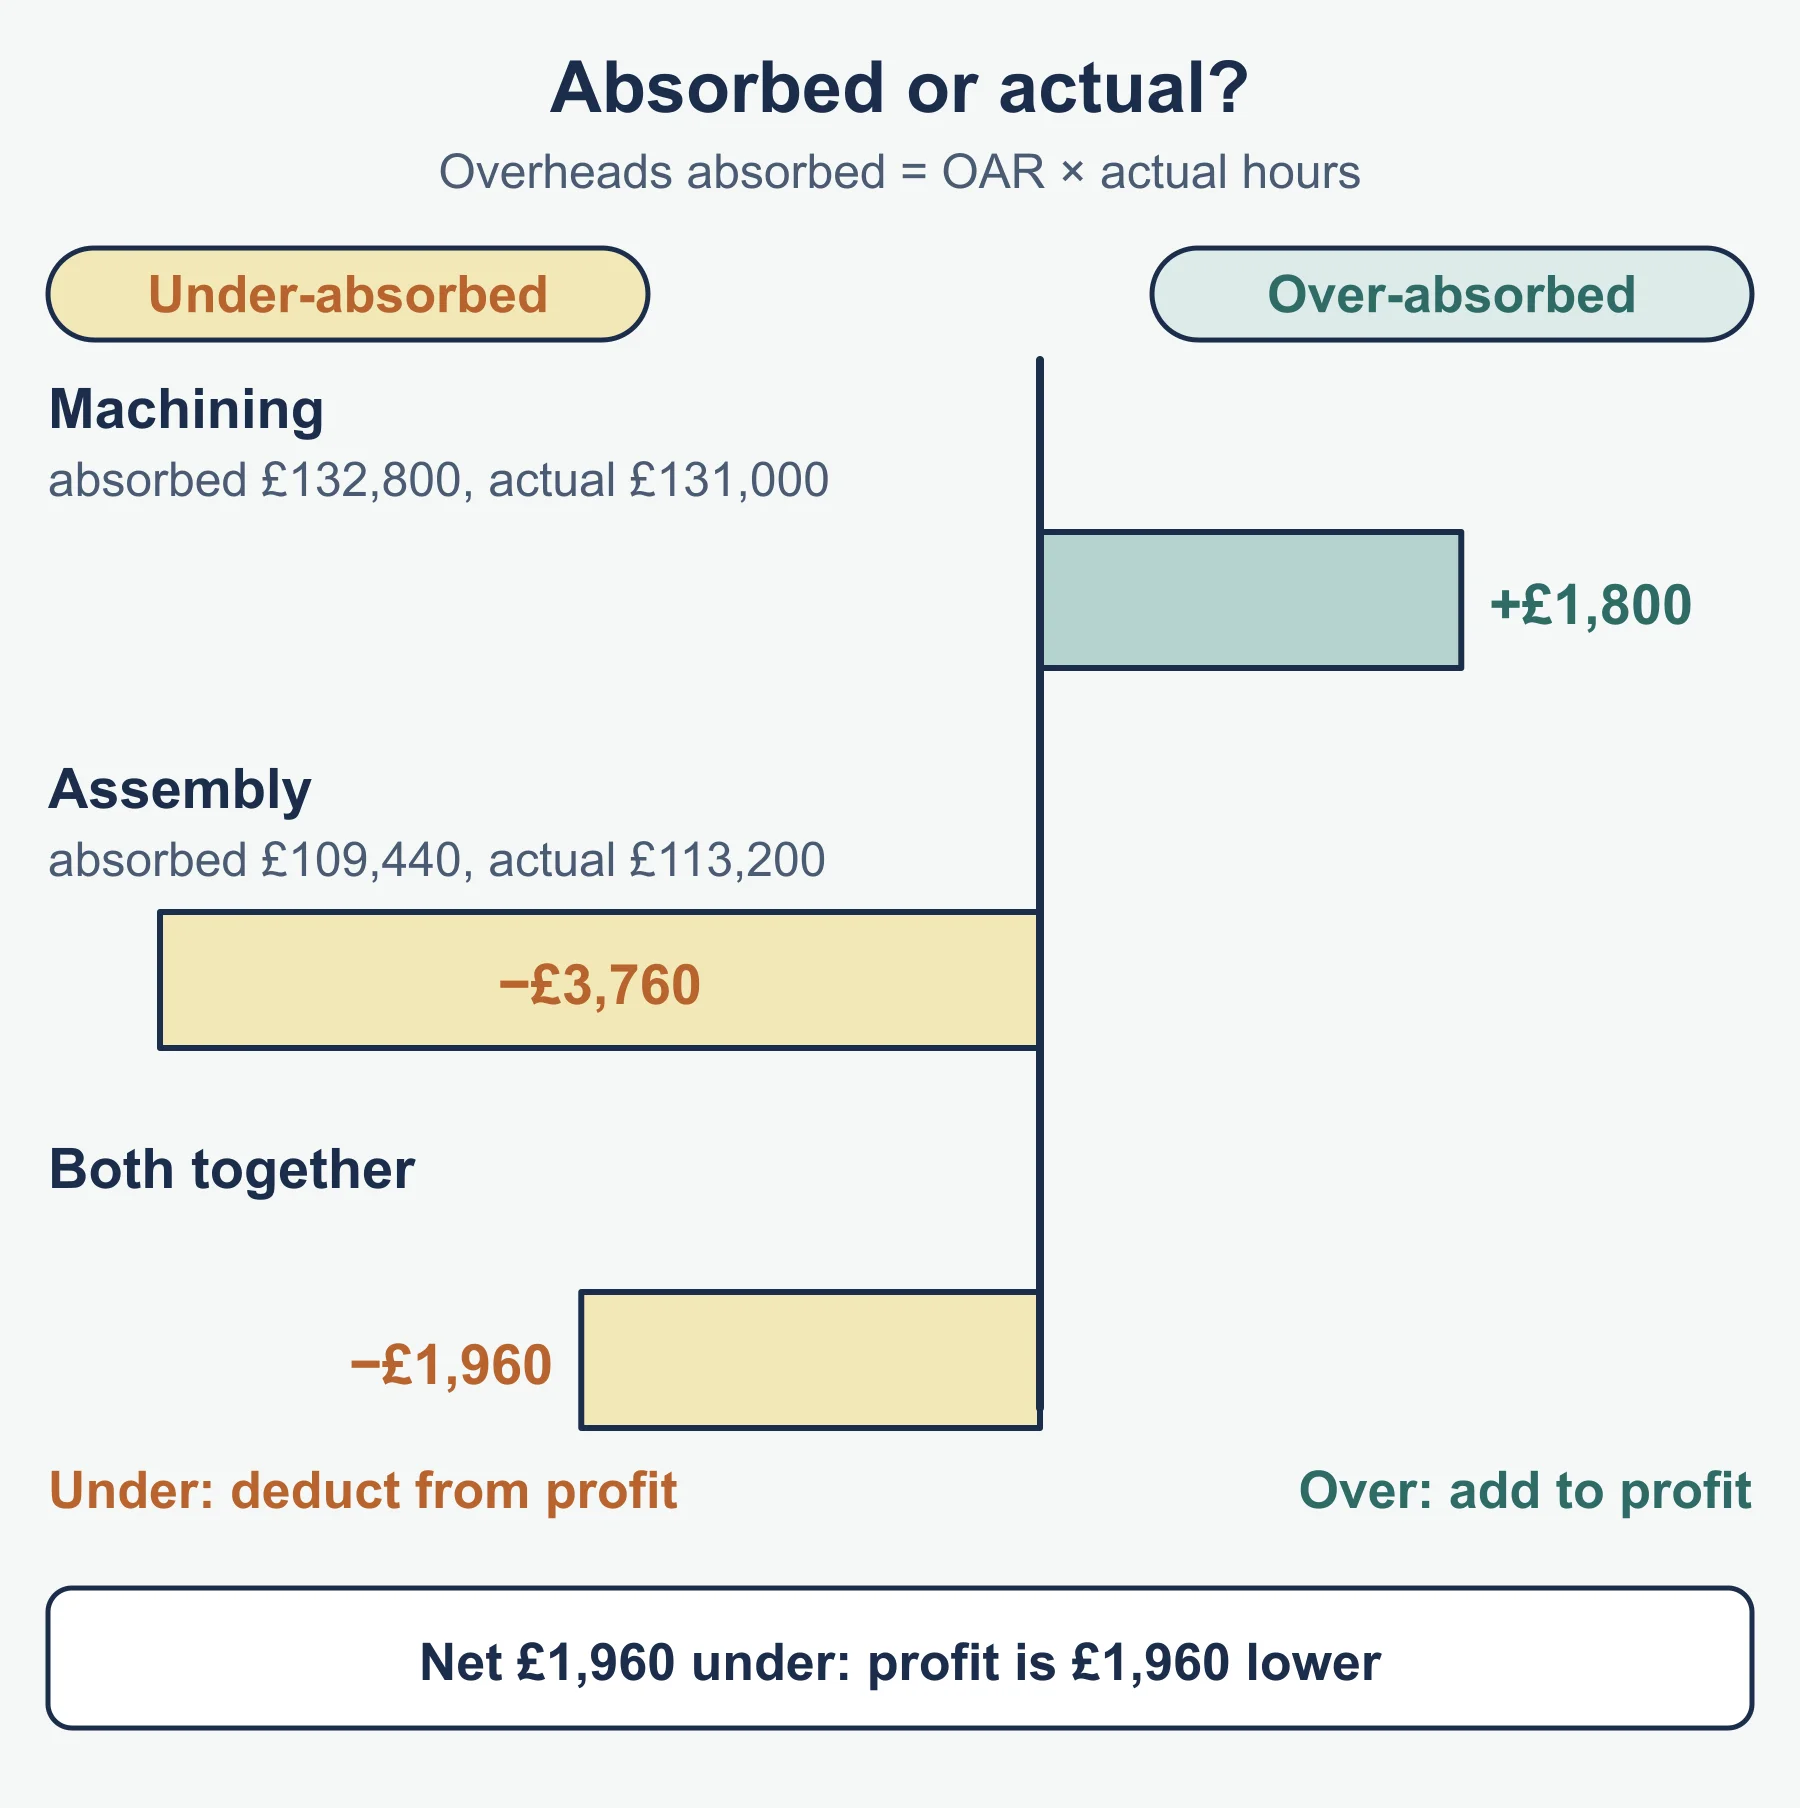
Under and over absorption. Cutting used 4,700 machine hours and spent 55,300 (budget 54,000). Overhead absorbed = 4,700 × 12 = 56,400, which exceeds actual by 1,100, so overhead is over-absorbed. If absorbed were lower than actual it would be under-absorbed. Causes: activity differs from budget (here +200 hours × 12 = 2,400 extra absorbed) and spending differs from budget (here 1,300 extra); net 2,400 − 1,300 = 1,100. The difference is adjusted in the statement of profit or loss: over-absorption raises profit, under-absorption lowers it.
Uses of absorption costing: a full cost per unit for pricing, inventory valued at full production cost, overheads spread across products. Limitations: apportionment bases are subjective; fixed overheads behave as if variable per unit; profit moves with inventory levels. Decision support: full cost helps set a long-run price but can mislead when only some costs change.
Non-financial factors matter in every costing decision: quality, customer relationships, employee morale, supplier reliability, reputation, environmental impact and capacity. A choice that looks best on the numbers can fail on these.
6. Marginal costing and break-even analysis
Contribution = selling price − variable cost per unit. Fixed costs are a period cost, charged in full to the period, and inventory is valued at variable cost only.
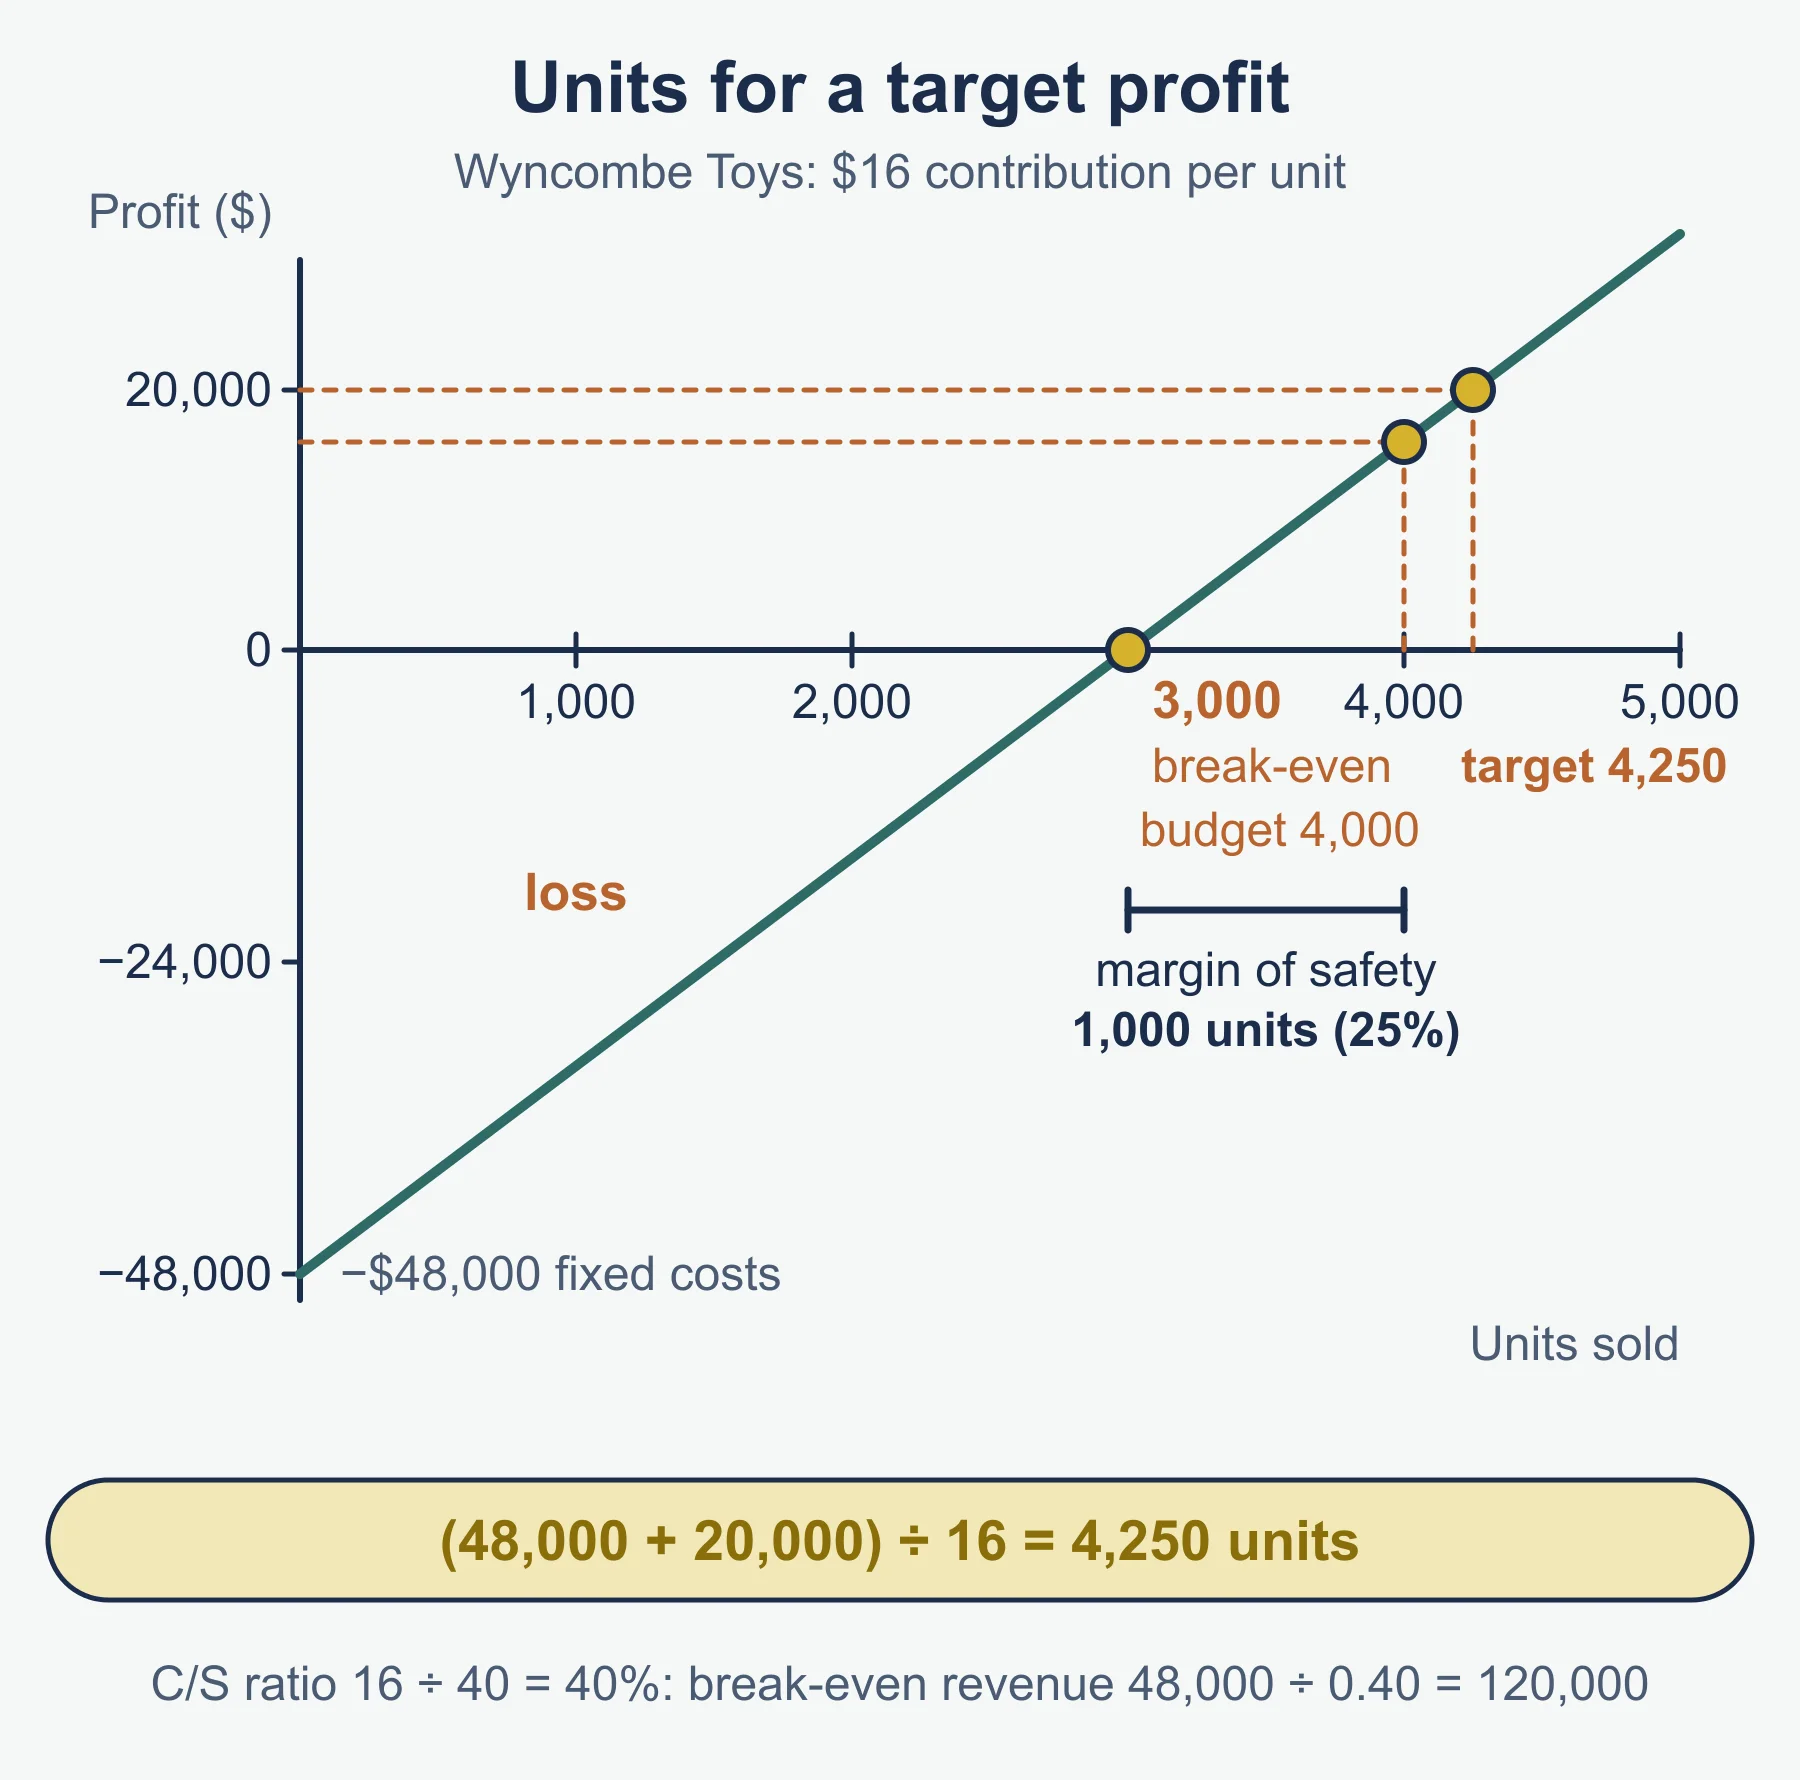
Wyncombe Toys sells a product at 40 (variable cost 24) with fixed costs of 48,000. Contribution is 16.
- Break-even point = 48,000 / 16 = 3,000 units (revenue 120,000).
- Contribution to sales (C/S) ratio = 16 / 40 = 40%; break-even revenue = 48,000 / 0.40 = 120,000.
- Target profit 20,000: units = (48,000 + 20,000) / 16 = 4,250.
- Budgeted sales 4,000 units: margin of safety = 4,000 − 3,000 = 1,000 units (25% of budget, or 40,000 of revenue).
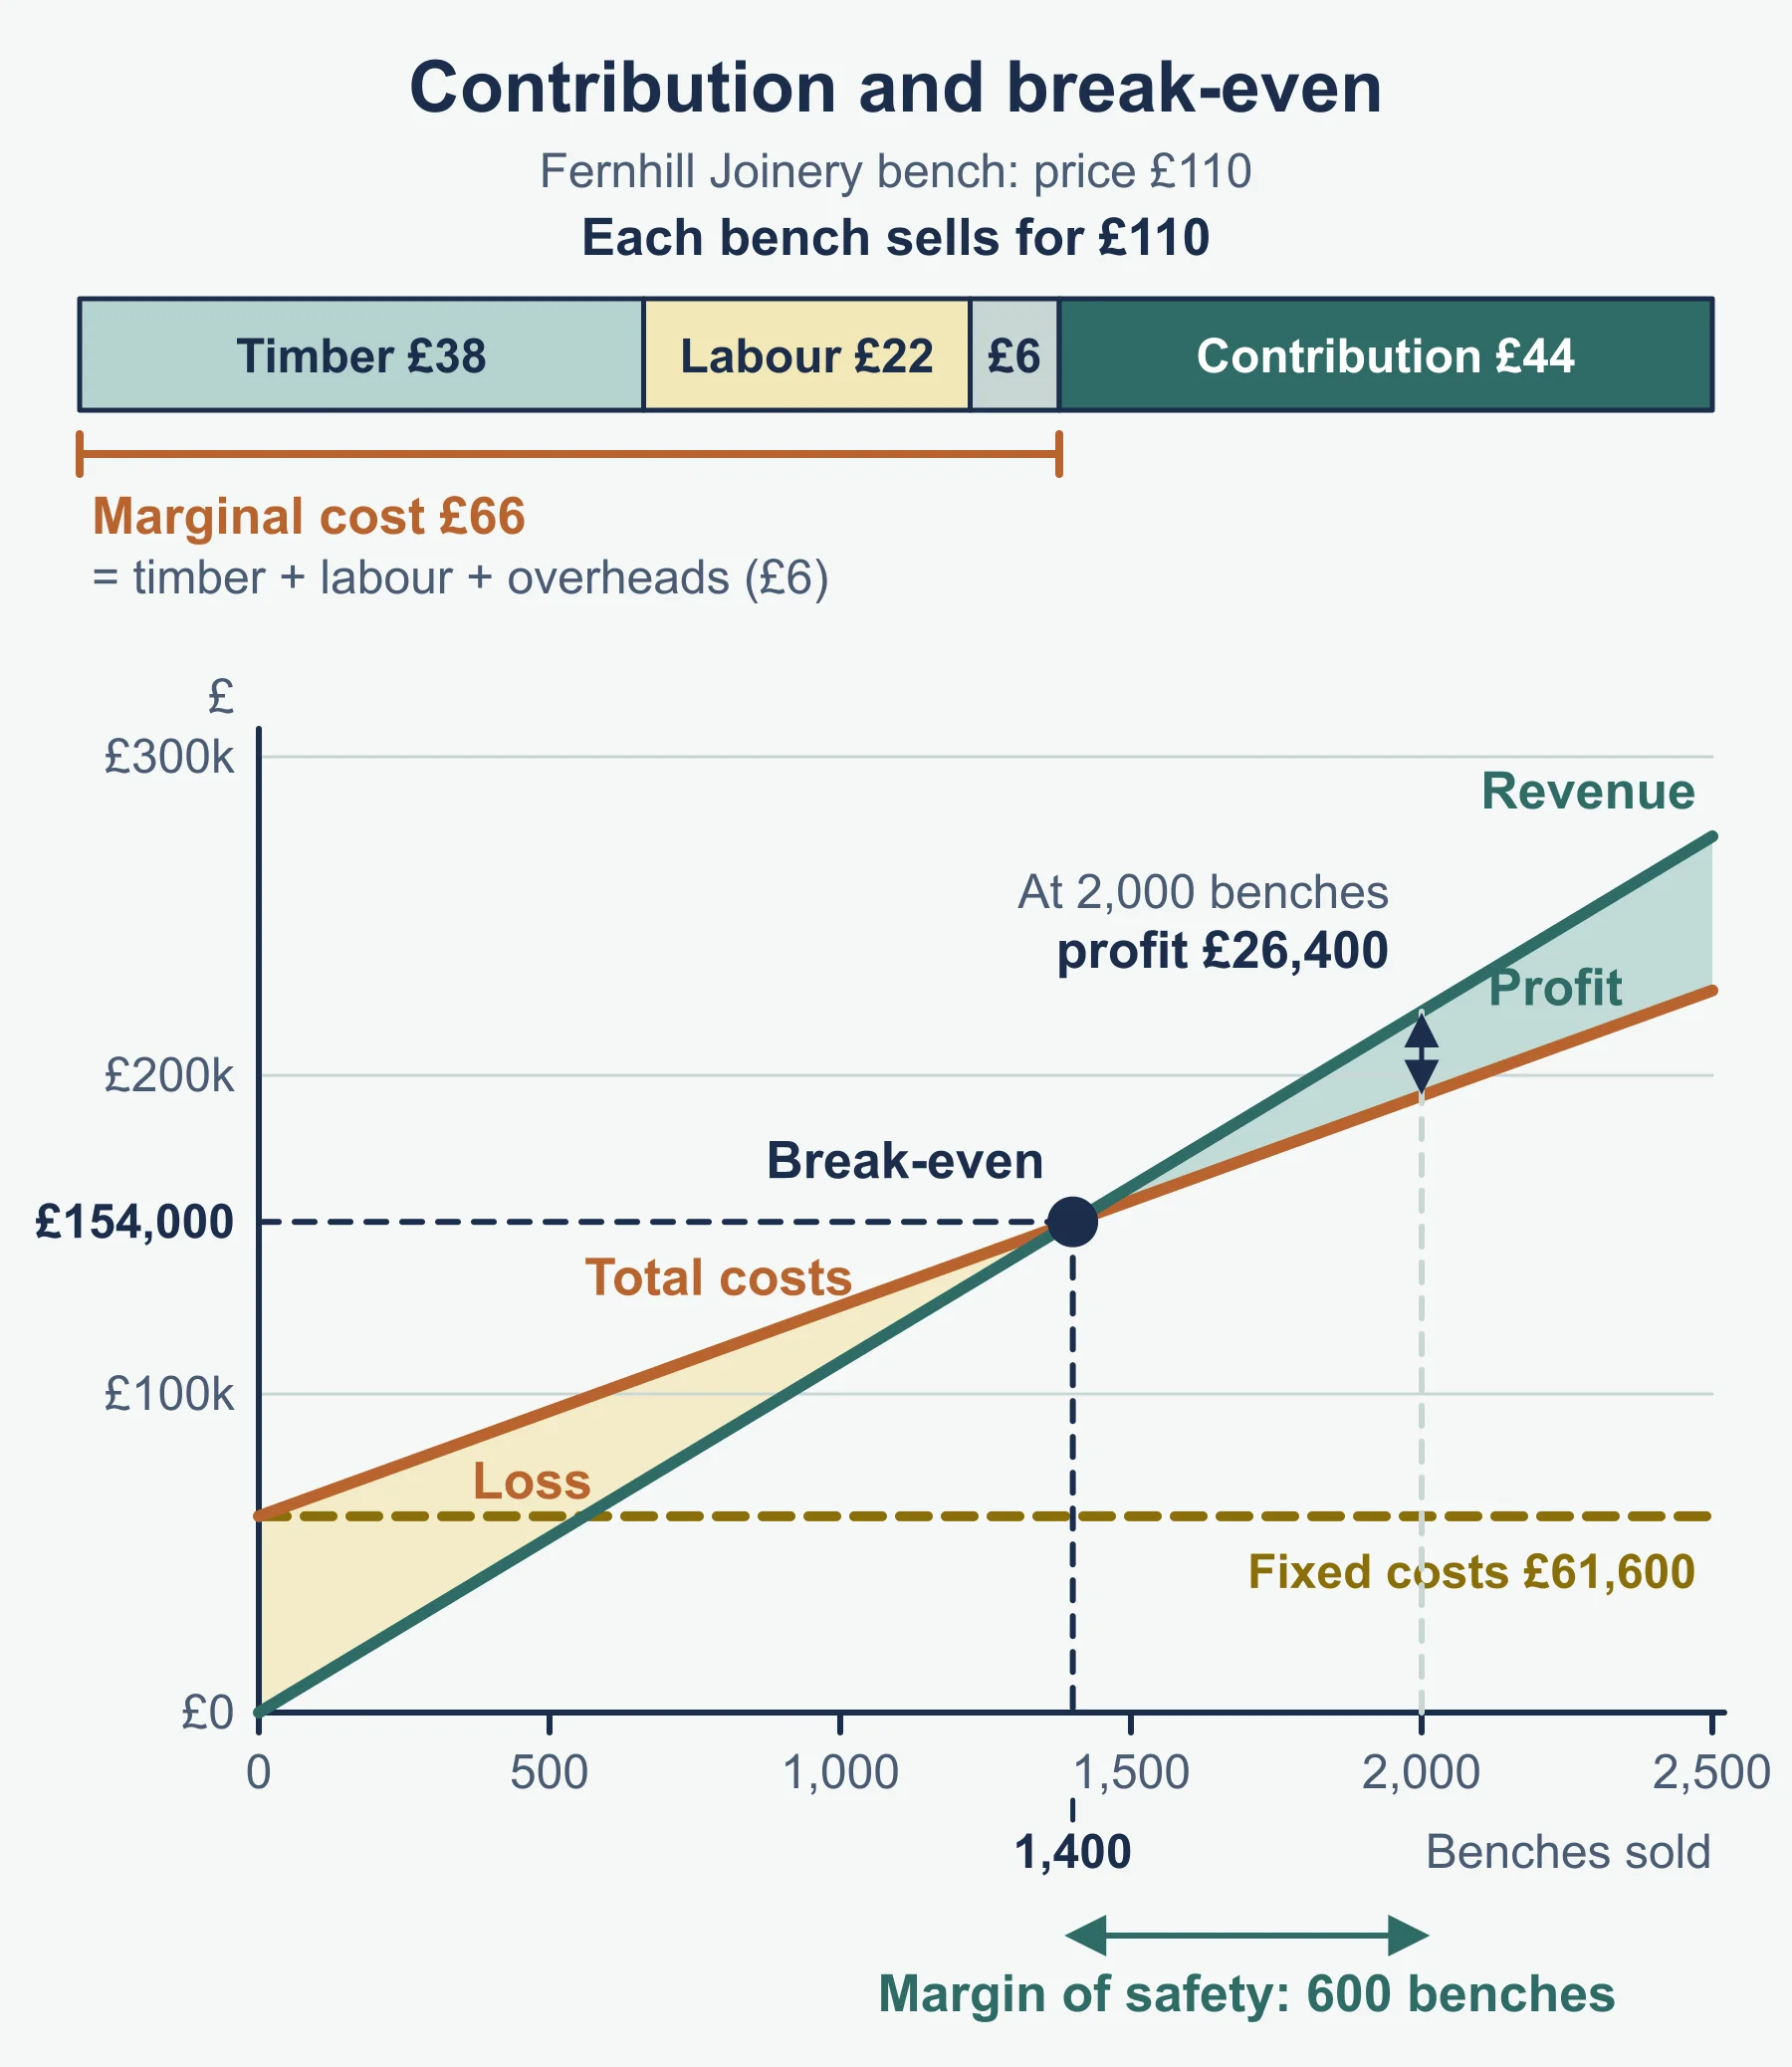
Reading a break-even chart (the syllabus says you will not be asked to prepare one). The revenue line starts at the origin; the total cost line starts at the fixed cost on the vertical axis. They cross at break-even. Left of it is a loss, right of it a profit. The margin of safety is the horizontal distance from break-even to budgeted output.
Limitations of break-even analysis: it assumes constant price and variable cost per unit, fixed costs that stay fixed, a single product or constant sales mix, and production equal to sales.
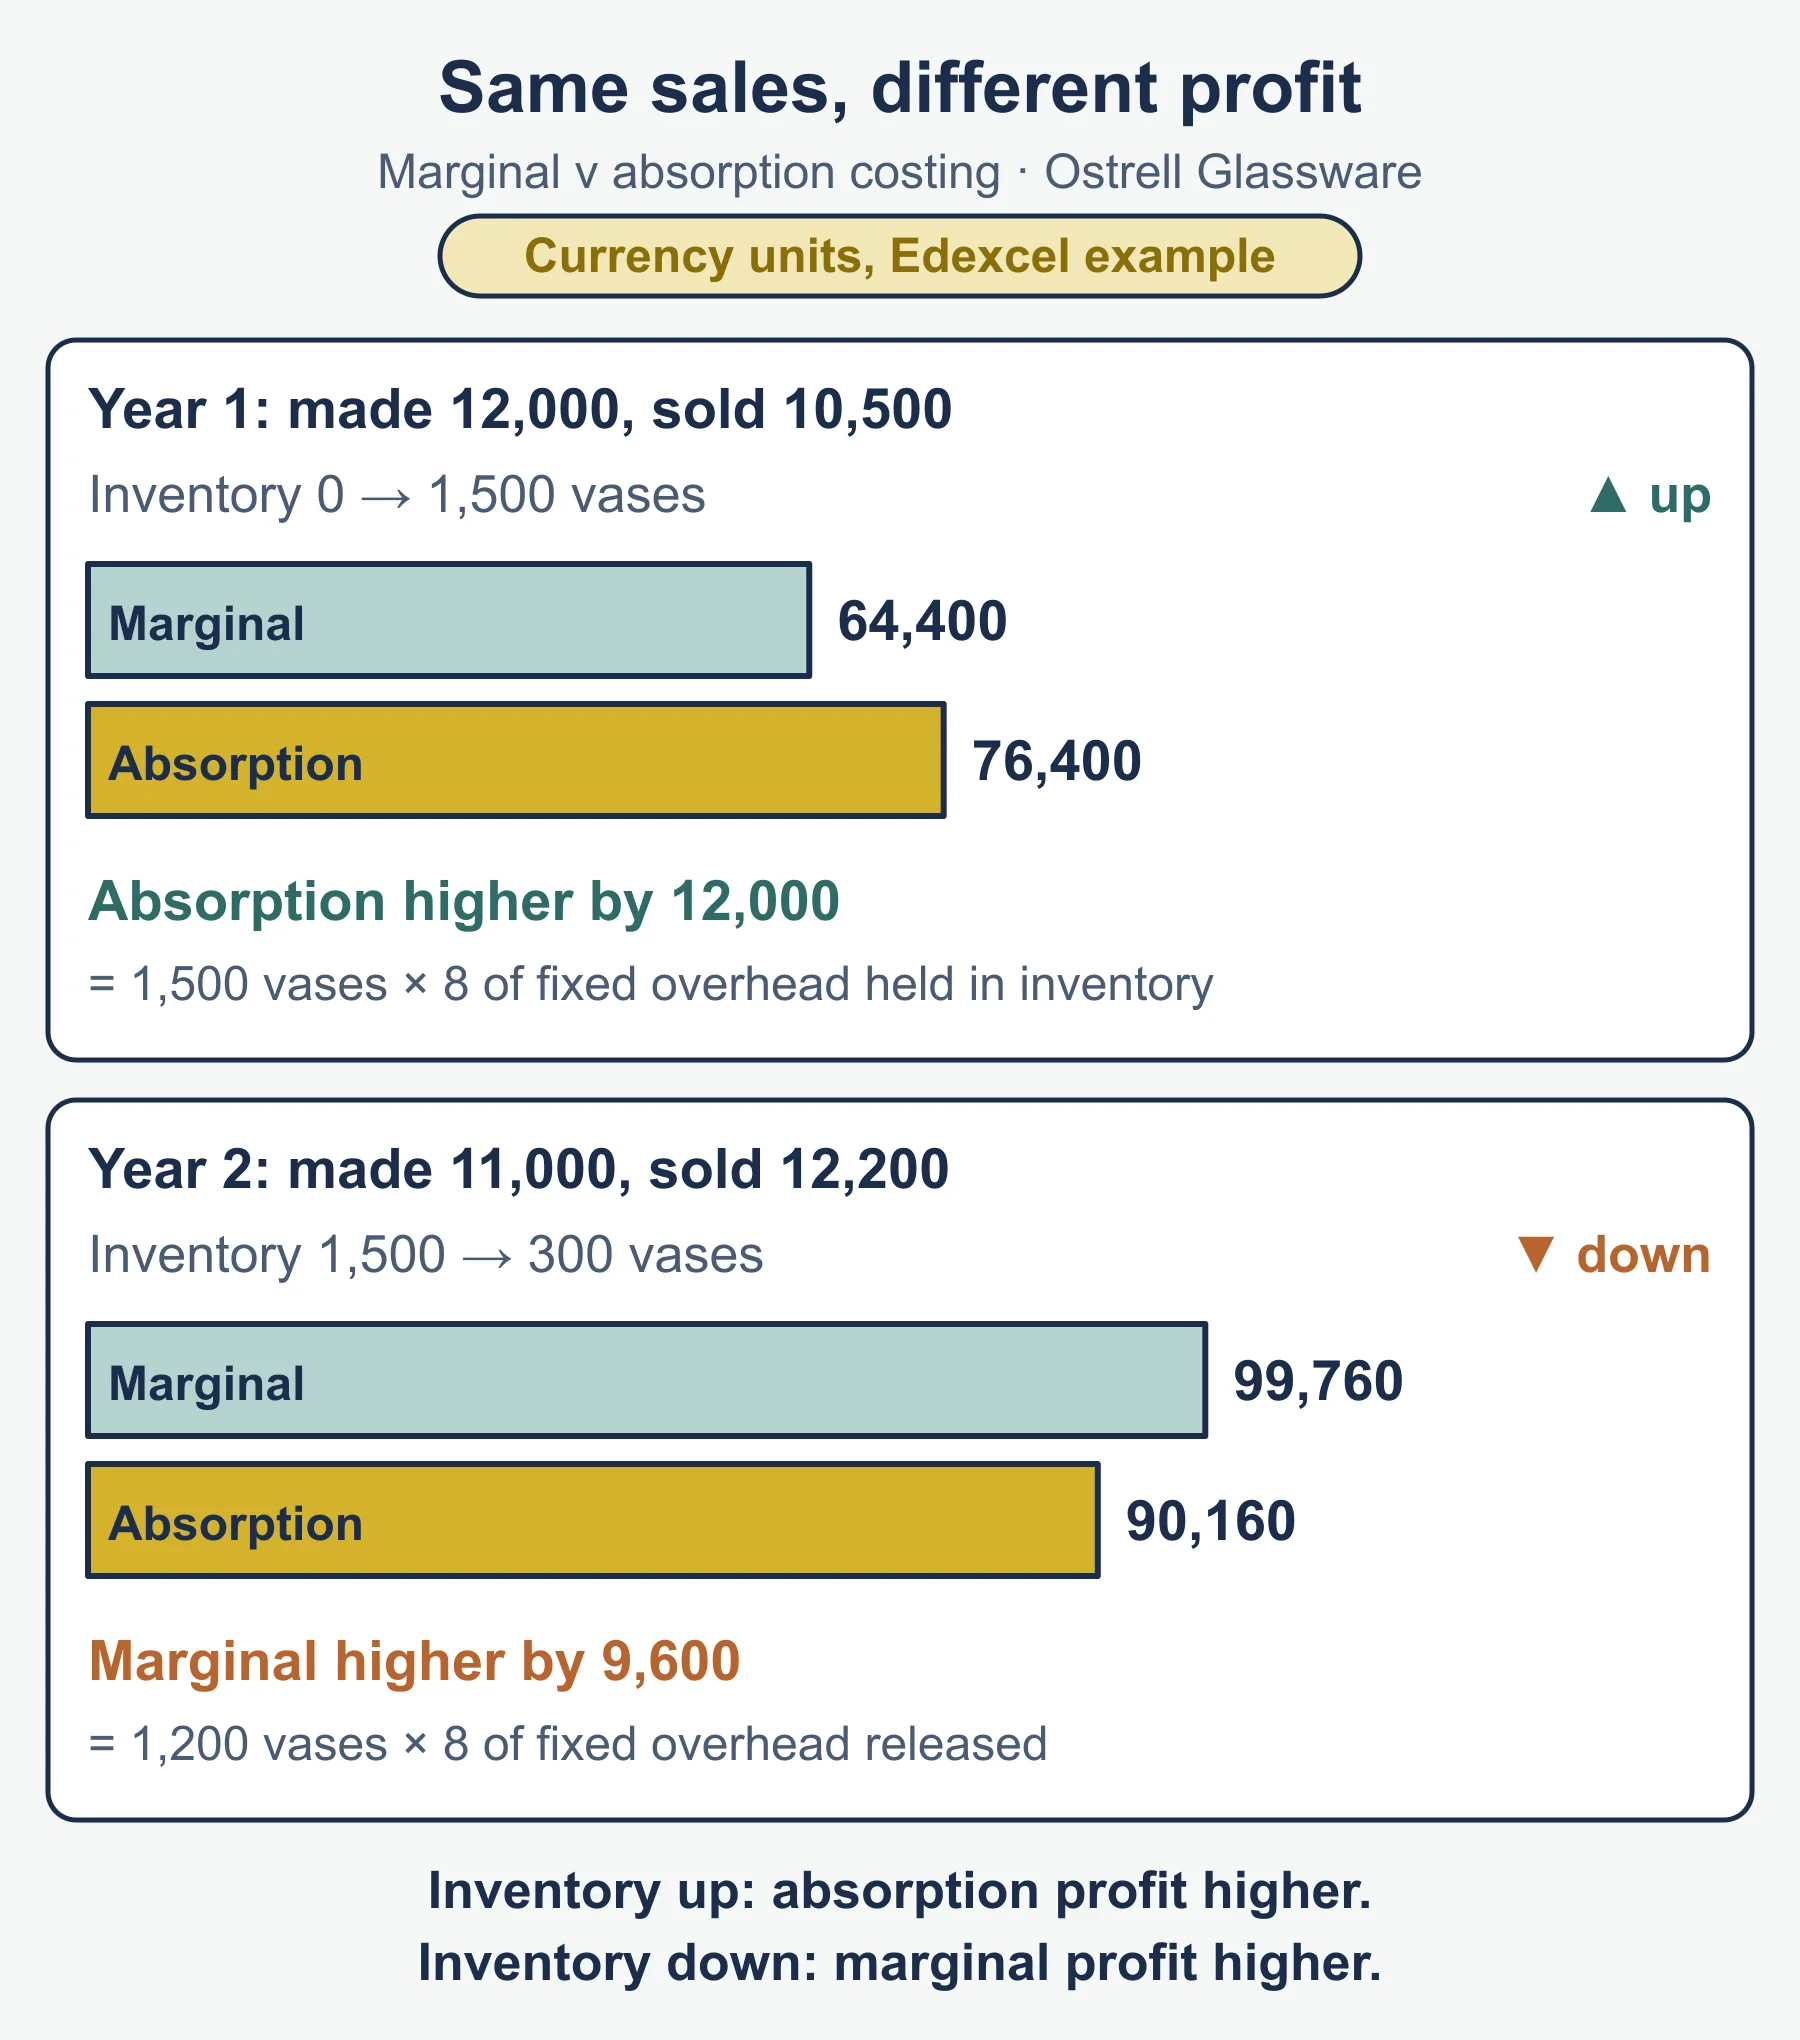
Absorption versus marginal profit. Pellwood Candles sells at 25 with variable cost 11. Fixed production overhead of 36,000 is absorbed at 6 per unit on normal output of 6,000; non-production overhead is 20,000. It makes 6,000 units in both months and sells 5,000 then 7,000.
| Month 1 | Absorption | Marginal |
|---|---|---|
| Sales | 125,000 | 125,000 |
| Cost of sales | (85,000) at 17 | (55,000) at 11 |
| Fixed costs charged | (20,000) | (56,000) |
| Profit | 20,000 | 14,000 |
Month 2 gives 36,000 (absorption) and 42,000 (marginal). The difference is the change in inventory units × fixed overhead per unit. Reconciliation: marginal profit, plus fixed overhead carried in closing inventory, less fixed overhead brought in with opening inventory, equals absorption profit. Month 1: 14,000 + 6,000 (1,000 units × 6) = 20,000. Month 2: 42,000 − 6,000 = 36,000.
Uses of marginal costing: it shows contribution by product, supports short-run decisions and keeps profit free of inventory effects. Limitations: prices may fail to cover fixed costs, costs must be split into fixed and variable, and inventory is not at full cost.
7. Decisions and cost-volume-profit (CVP) analysis
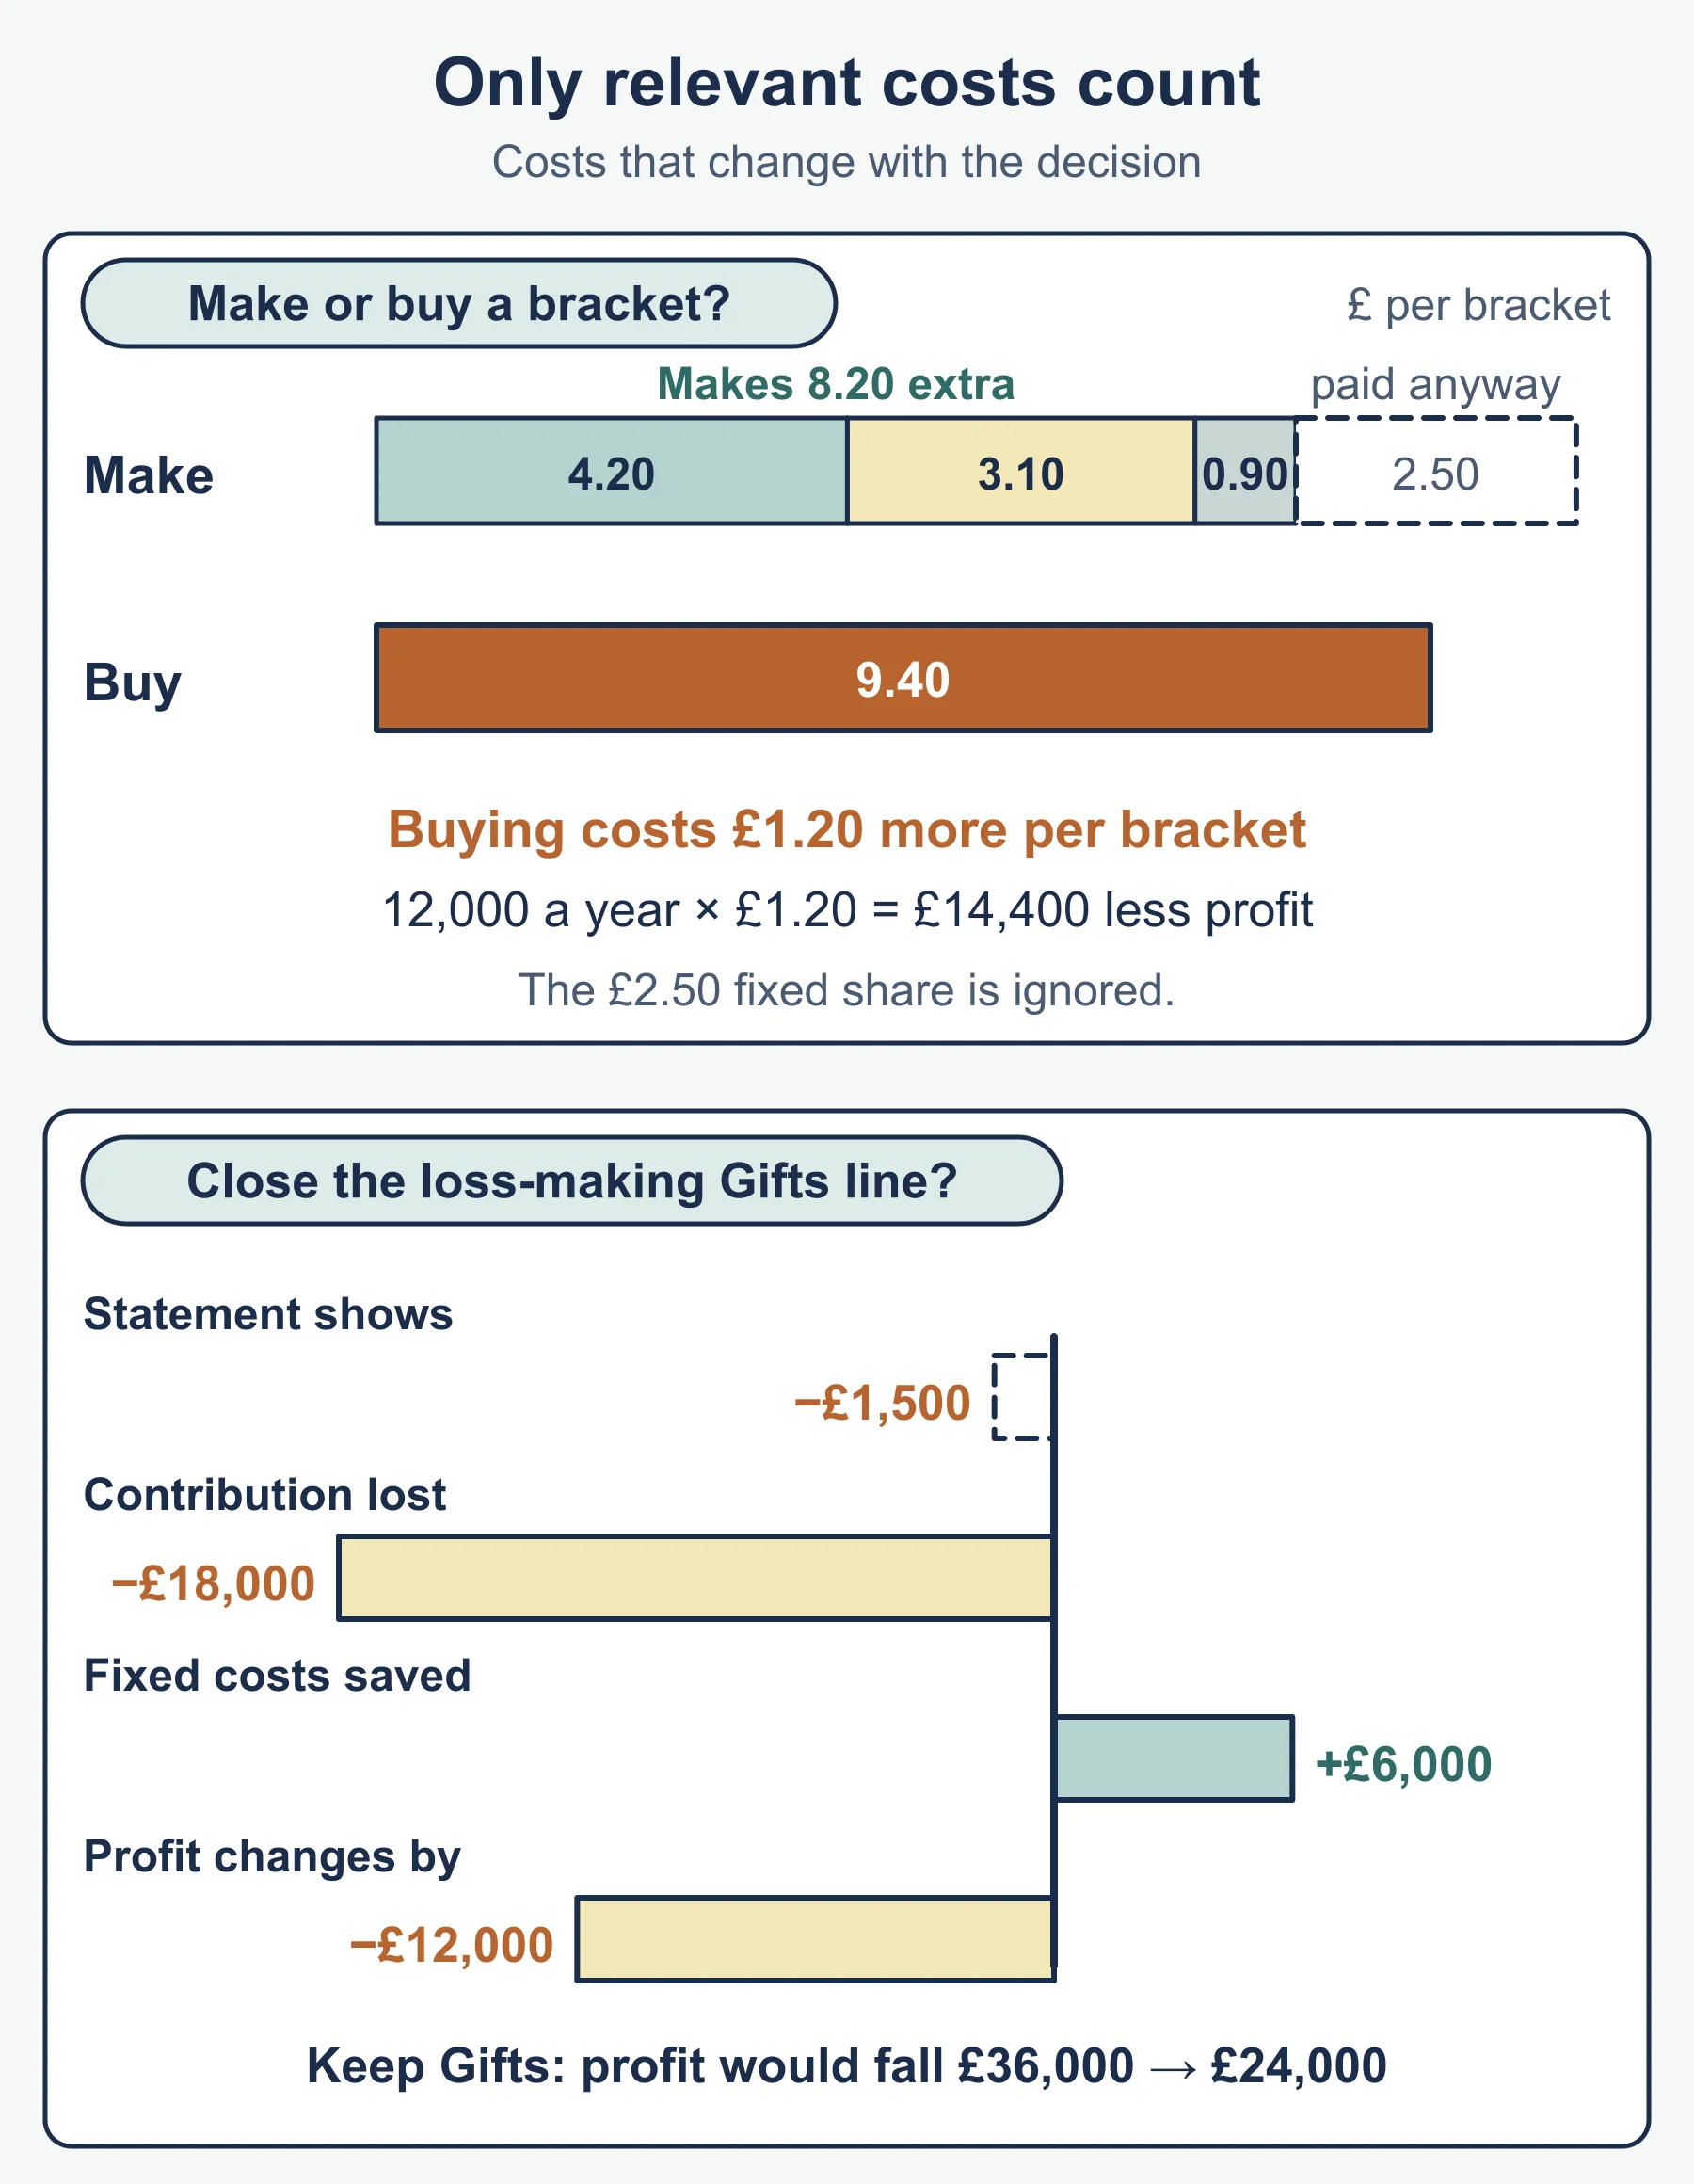
Use relevant costs: only future costs that change with the decision.
| Decision | Rule |
|---|---|
| Make or buy | Compare variable plus avoidable fixed cost of making with the purchase price |
| Special order | Accept if price exceeds variable cost and capacity is spare |
| Closure of a business unit | Compare its contribution with its avoidable fixed costs |
| Limiting factor | Rank by contribution per unit of the scarce resource |
| Target profit | Units = (fixed costs + target) / contribution per unit |
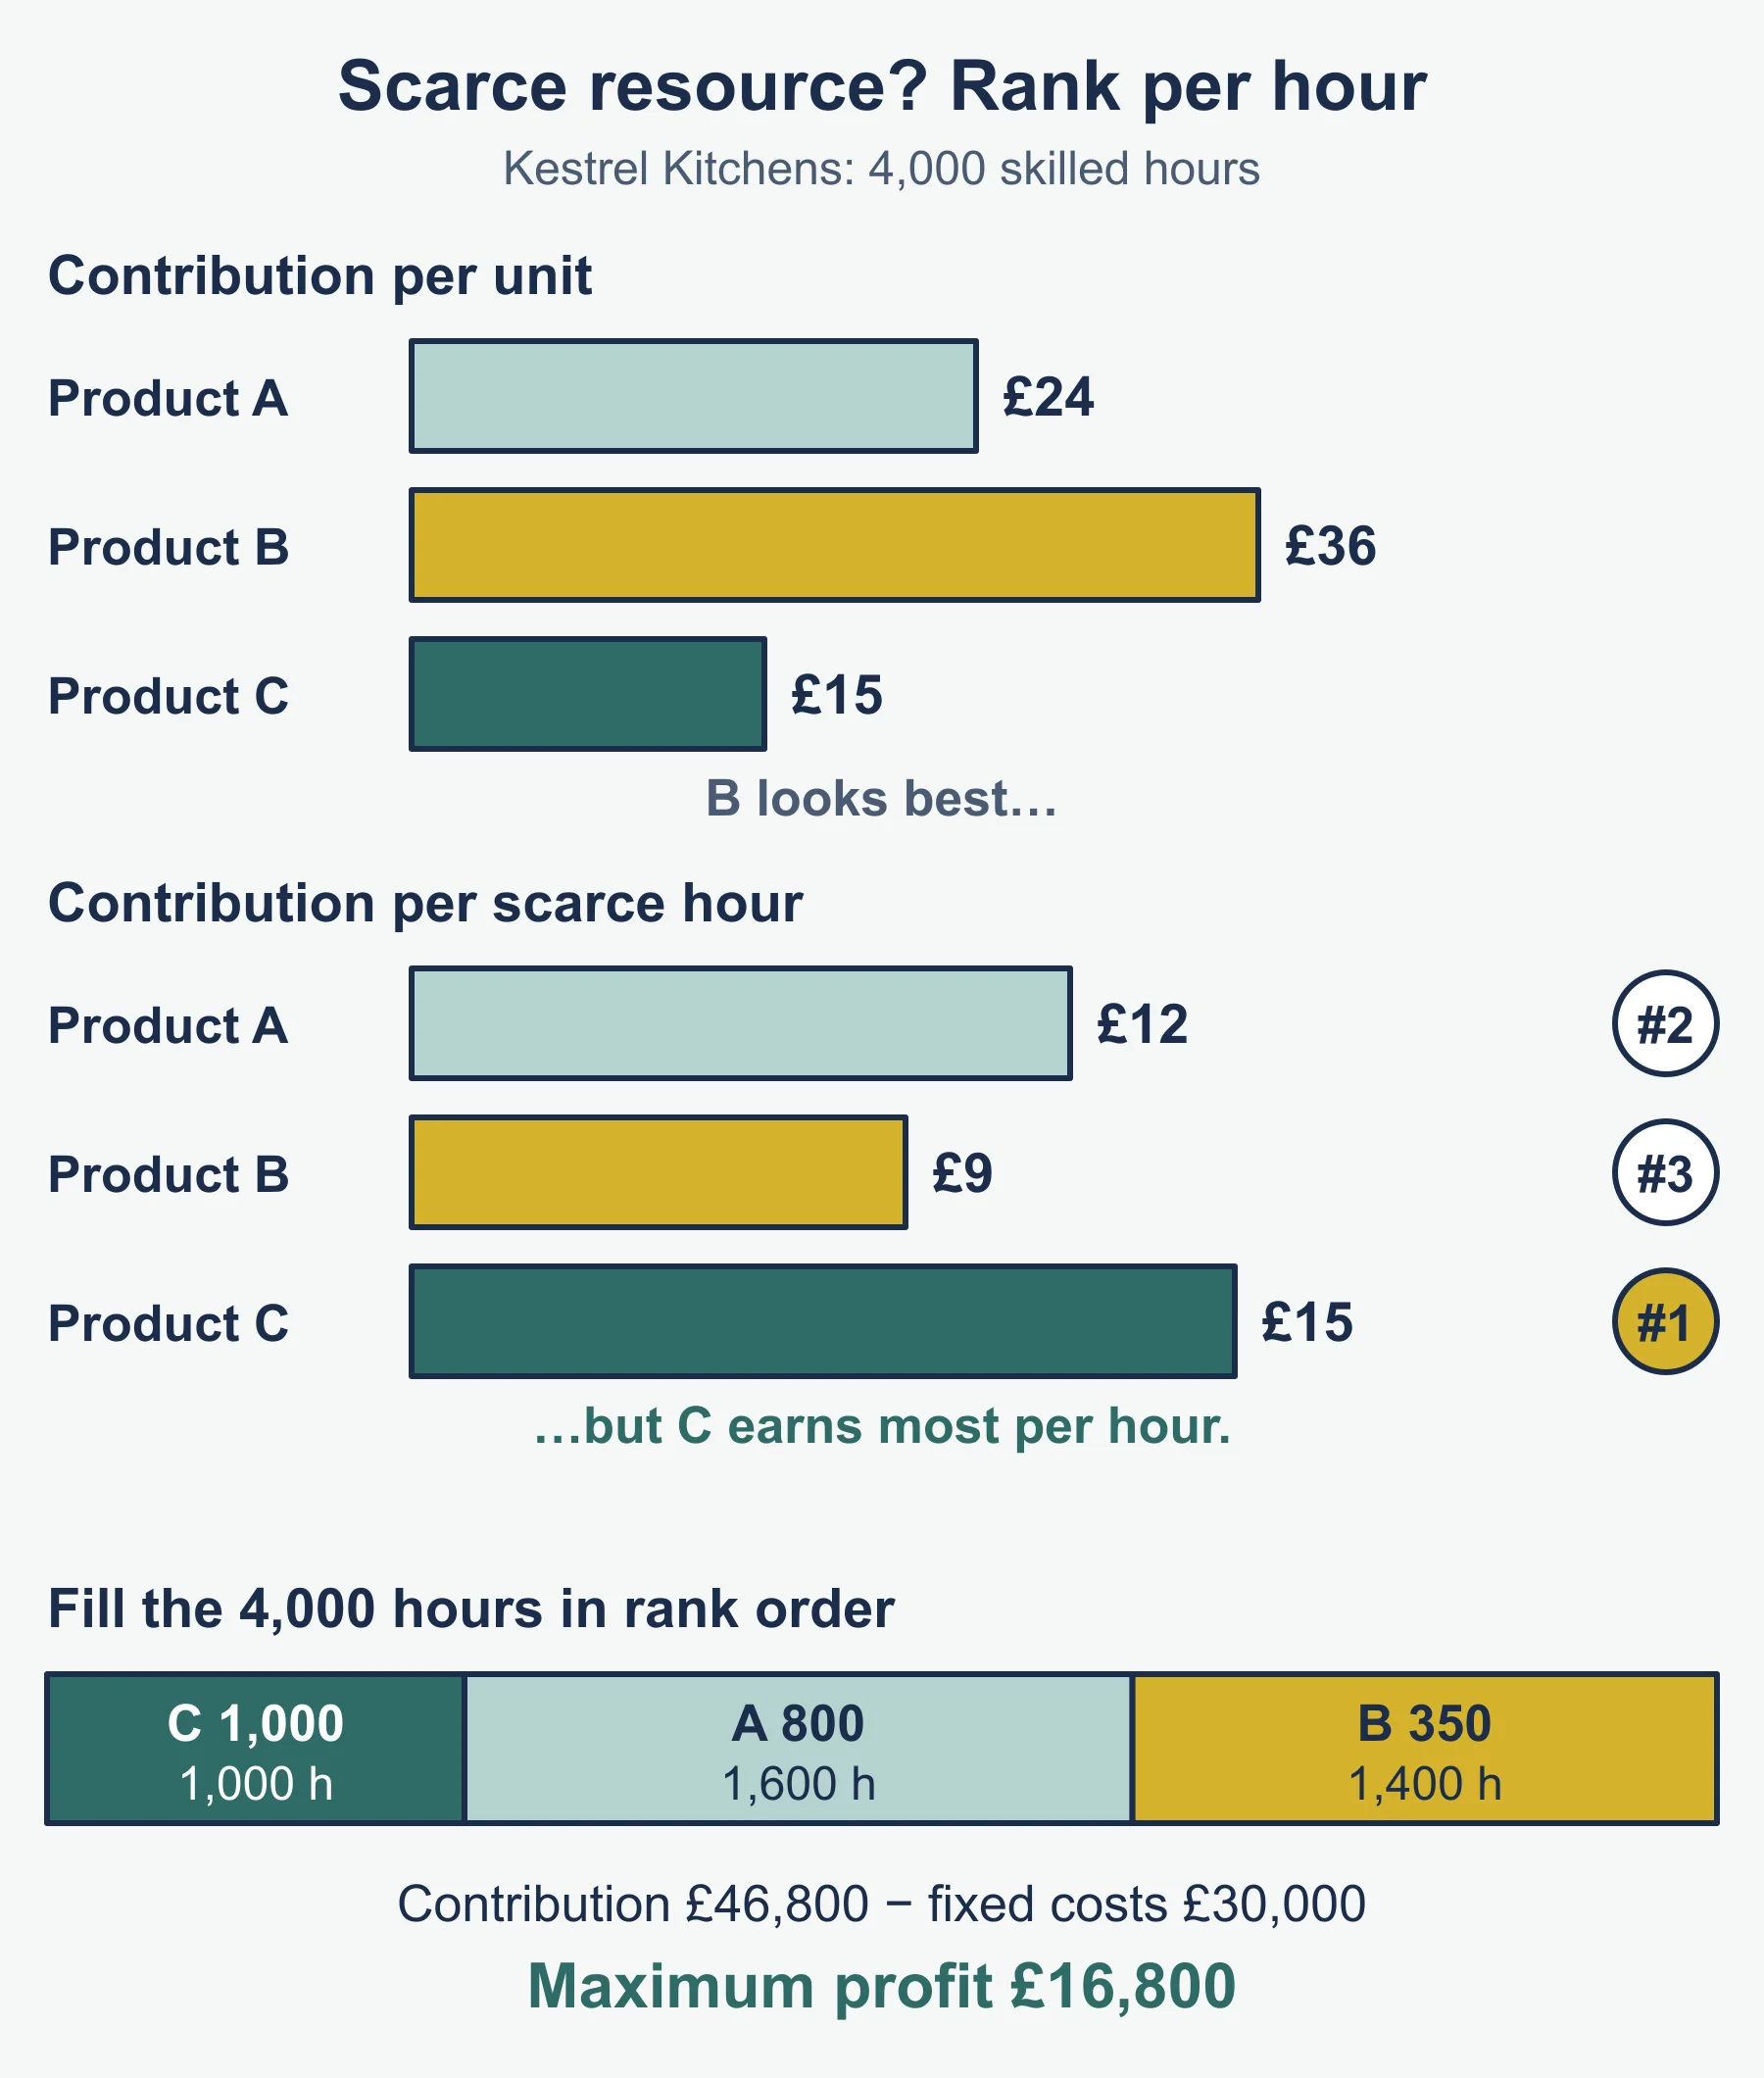
Cragmoor Garden Tools: product X contributes 18 and uses 2 machine hours; Y contributes 20 and uses 4 hours. Only 6,000 hours exist; demand is 2,000 X and 1,500 Y. Contribution per hour: X 9, Y 5. Make 2,000 X (4,000 hours), then 2,000 / 4 = 500 Y. Contribution = 36,000 + 10,000 = 46,000.
CVP analysis studies how costs, volume and profit move together. Advantages: it is quick, shows the effect of price or volume changes and supports target profit planning. Limitations: the assumptions in Section 6 rarely hold exactly, and it ignores non-financial factors. Finish decisions with a recommendation supported by reasons for and against.
Common errors
- Not recalculating the average after each receipt in perpetual AVCO.
- Dividing fixed costs by selling price, not contribution per unit.
- Ranking by contribution per unit, not per unit of the scarce resource.
Frequently asked questions
What is the difference between FIFO and AVCO? FIFO assumes the oldest items are issued first, so closing inventory is valued at the newest purchase prices. AVCO values issues and closing inventory at a weighted average cost, which in the perpetual method is recalculated after each receipt. With rising prices, FIFO gives the highest profit.
Do I have to draw a break-even chart for Cambridge 9706? No. The syllabus says you will not be asked to prepare a break-even chart, but you should be able to read and interpret one.
How do you calculate the margin of safety? Margin of safety = budgeted sales − break-even sales. It can be given in units, revenue or as a percentage of budgeted sales.
Why do absorption and marginal costing give different profits? Absorption costing carries some fixed production overhead in closing inventory, while marginal costing charges it all in the period. The difference equals the change in inventory units × fixed overhead per unit.
What is just in time inventory management? Under just in time (JIT), materials arrive close to when production needs them, in small, frequent deliveries, so little inventory is held.
Official syllabus
Cambridge International, AS & A Level Accounting 9706 syllabus for 2026, 2027 and 2028, sections 2.1 and 2.2.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
A Level Accounting: Accounting for Non-Current Assets (Cambridge 9706)
Capital versus revenue spending, why assets depreciate depreciation methods, cost and revaluation models and disposals, for Cambridge 9706 Accounting topic 1.3.
Accounting · Cambridge · AS Level
Read guide -
Practice questions
A Level Accounting: Costs, cost behaviour and traditional costing (Cambridge 9706) – Practice Questions
Eleven original questions with worked answers on cost behaviour, inventory, absorption and marginal costing and decisions for Cambridge 9706 AS Accounting.
Accounting · Cambridge · AS Level
Try questions -
Revision notes
A Level Accounting: Costs, cost behaviour and traditional costing methods (Cambridge 9706) – Revision Notes
Condensed revision notes on cost behaviour, FIFO and AVCO, absorption and marginal costing, break-even and decisions for Cambridge 9706 AS Accounting.
Accounting · Cambridge · AS Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting AS LEVEL?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

