
Revision Notes
A Level Business: Investment appraisal and Finance and accounting strategy (Cambridge 9609) – Revision Notes
Condensed revision notes on payback, ARR, NPV, appraisal decisions and ratio-based finance strategy for Cambridge A Level Business 9609.
- Subject
- Business
- Level
- A LEVEL
- Topic
- Finance and accounting
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to Cambridge A Level Business (9609), For examination in 2026, 2027 and 2028. Official specification .
Syllabus page (what it covers and how it is assessed): Cambridge A Level Business.
Syllabus points this page covers
9609 (A Level)
- 10.3 Investment appraisal
- 10.4 Finance and accounting strategy
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Business (9609).
These notes condense sections 10.3 Investment appraisal and 10.4 Finance and accounting strategy of the Cambridge International AS & A Level Business 9609 syllabus for examination in 2026, 2027 and 2028. Both sections are A Level content. For full explanations and worked cases, read the study guide, then test yourself with the practice set. Course links: the Cambridge A Level Business hub, the checklist, the free diagnostics and Finance and Accounting (A Level) practice. Businesses and figures are invented.
10.3 Investment appraisal
Why appraise (10.3.1)
- Capital projects are large, long-lived and hard to reverse.
- Projects compete for limited funds, so they must be compared.
- Appraisal tests a project against objectives and shows which forecasts matter most.
- It makes risk visible; it does not remove it.
Methods and formulas (10.3.2 and 10.3.3)
| Method | How to find it | Reads as |
|---|---|---|
| Payback | Cumulative net cash inflow until the cost is repaid, then fraction of the final year | Years and months; shorter is better |
| ARR | (average profit / average investment) × 100 (syllabus form) | Percentage; compare with a target rate |
| NPV | Sum of (net cash flow × discount factor) minus initial cost | Pounds; positive means worthwhile on this measure |
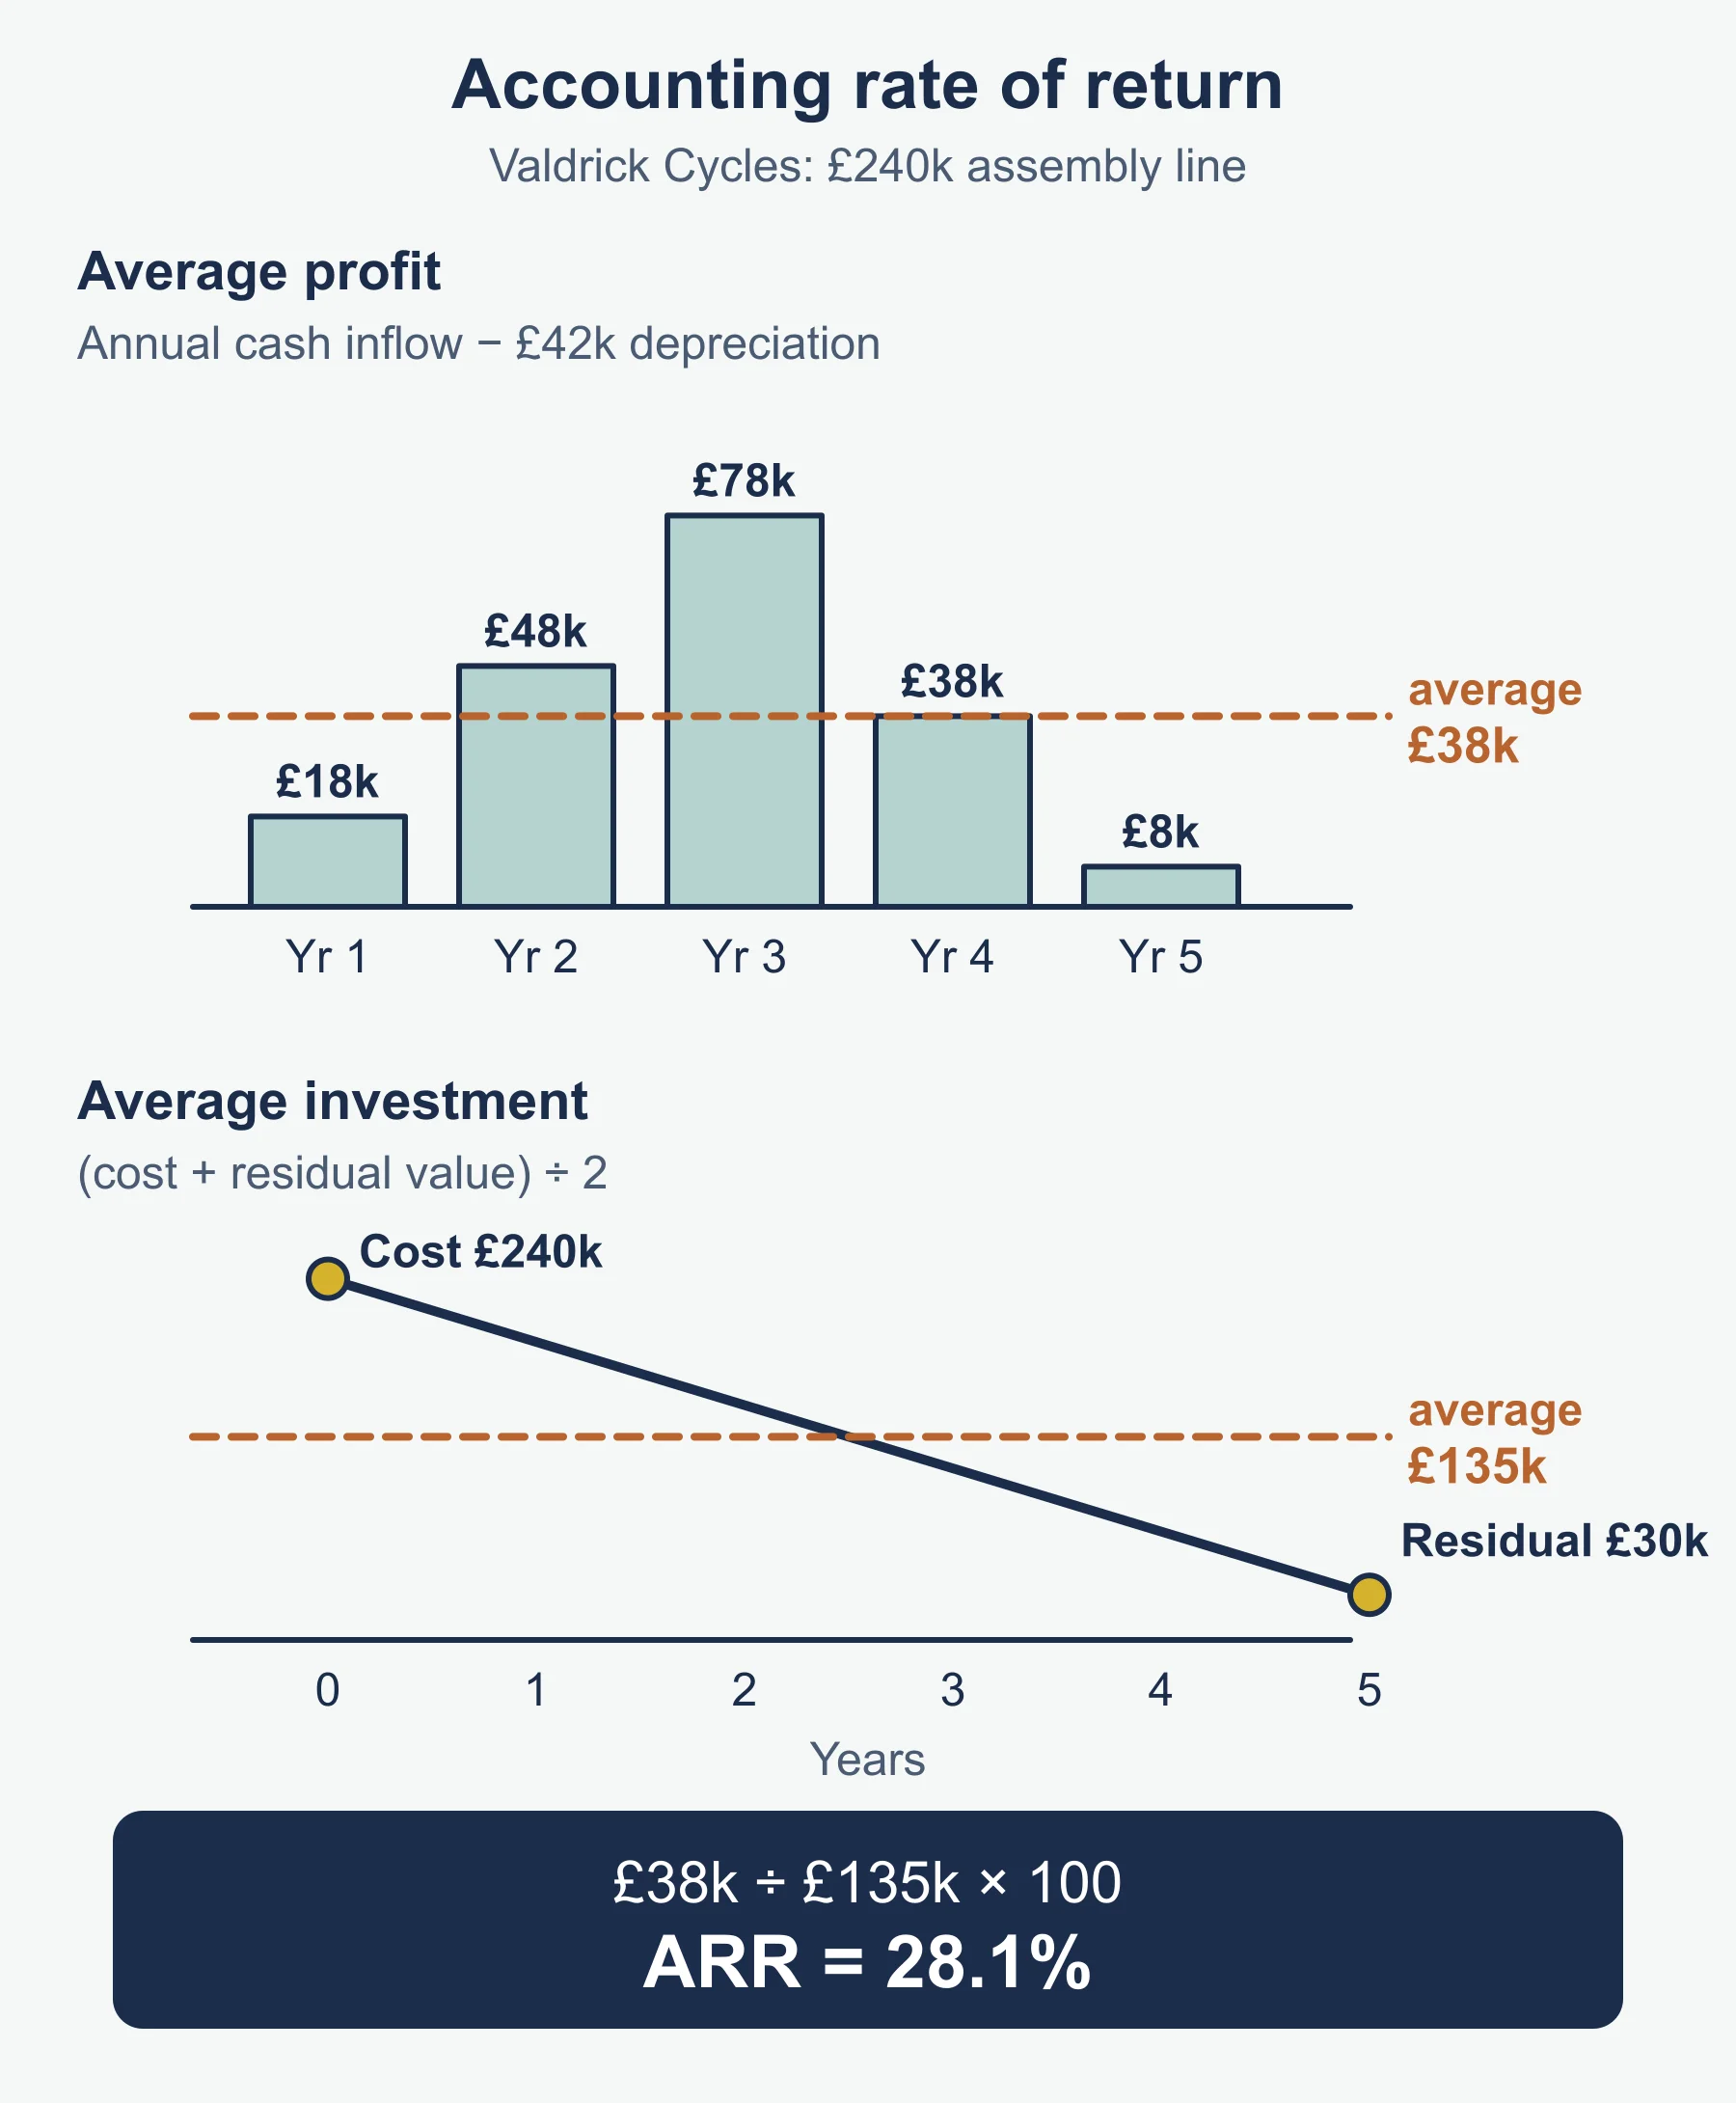
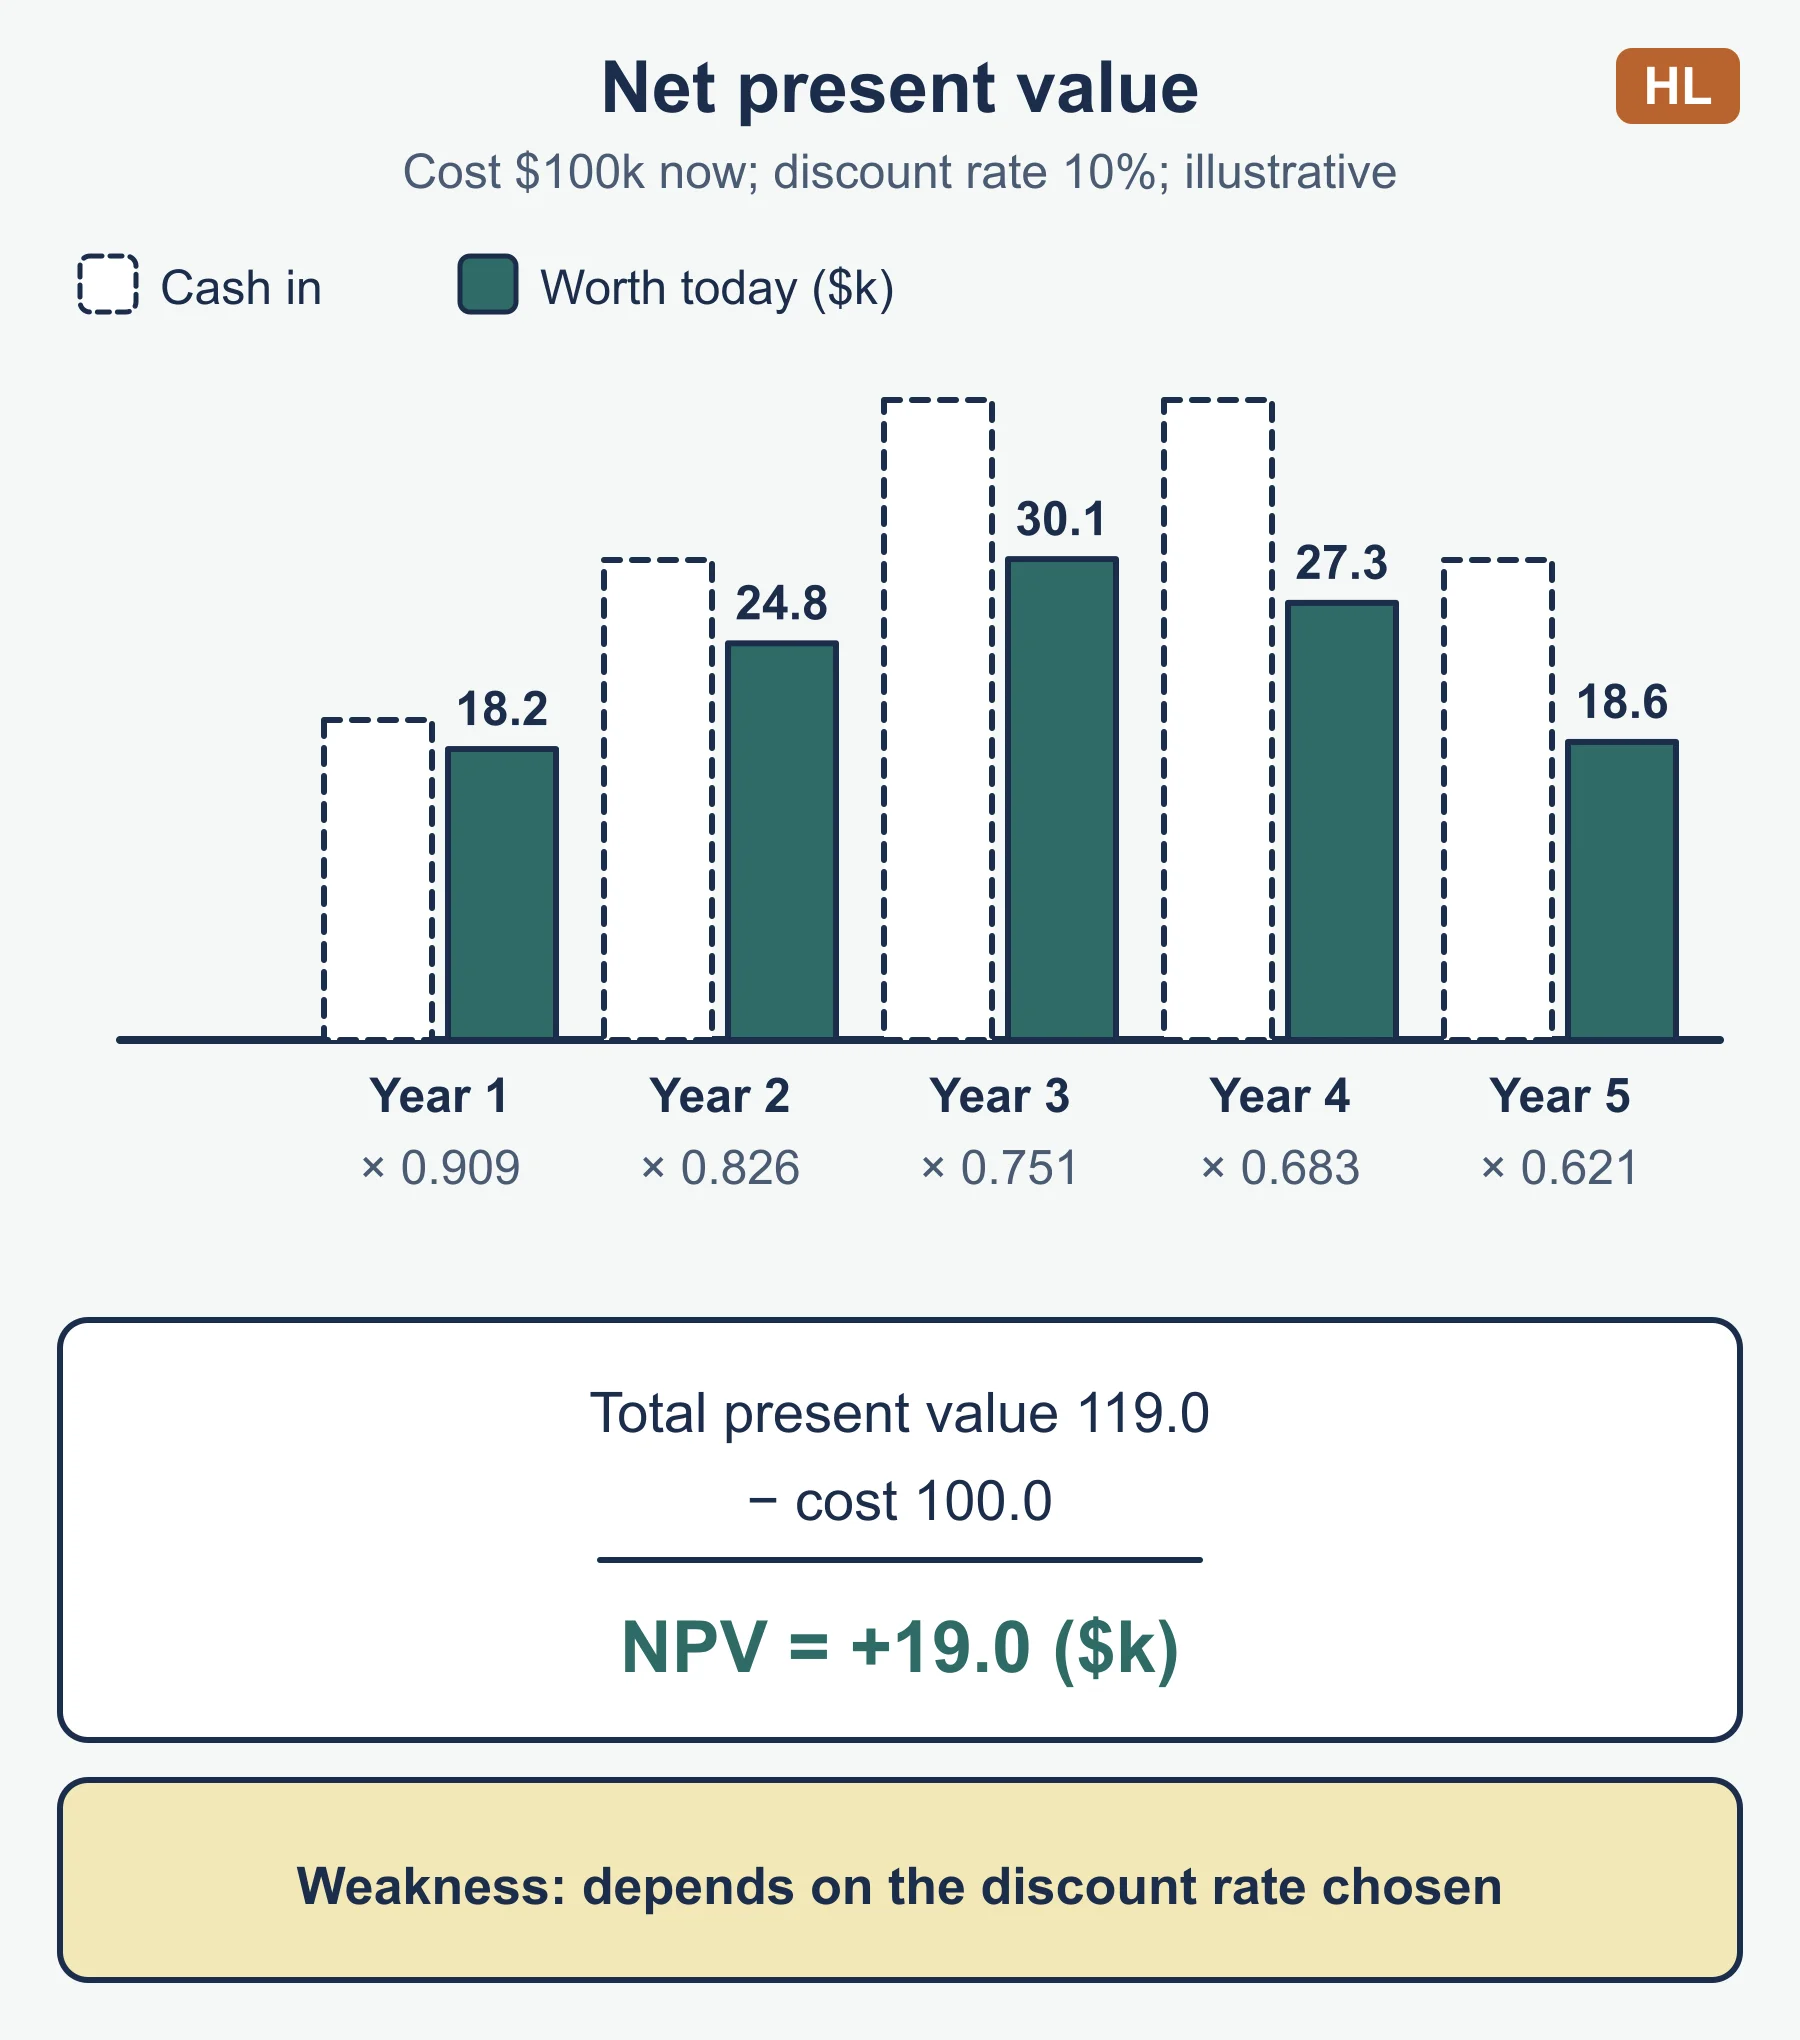
Average profit = (total net cash inflows − total depreciation) / years. Total depreciation = cost − residual value. Average investment is usually (cost + residual value) / 2. This is the standard form, so state it. Discount factor = 1 / (1 + r)^n is the standard form, and you use the factors a question gives you. The initial cost is paid now and is not discounted.
Method in steps
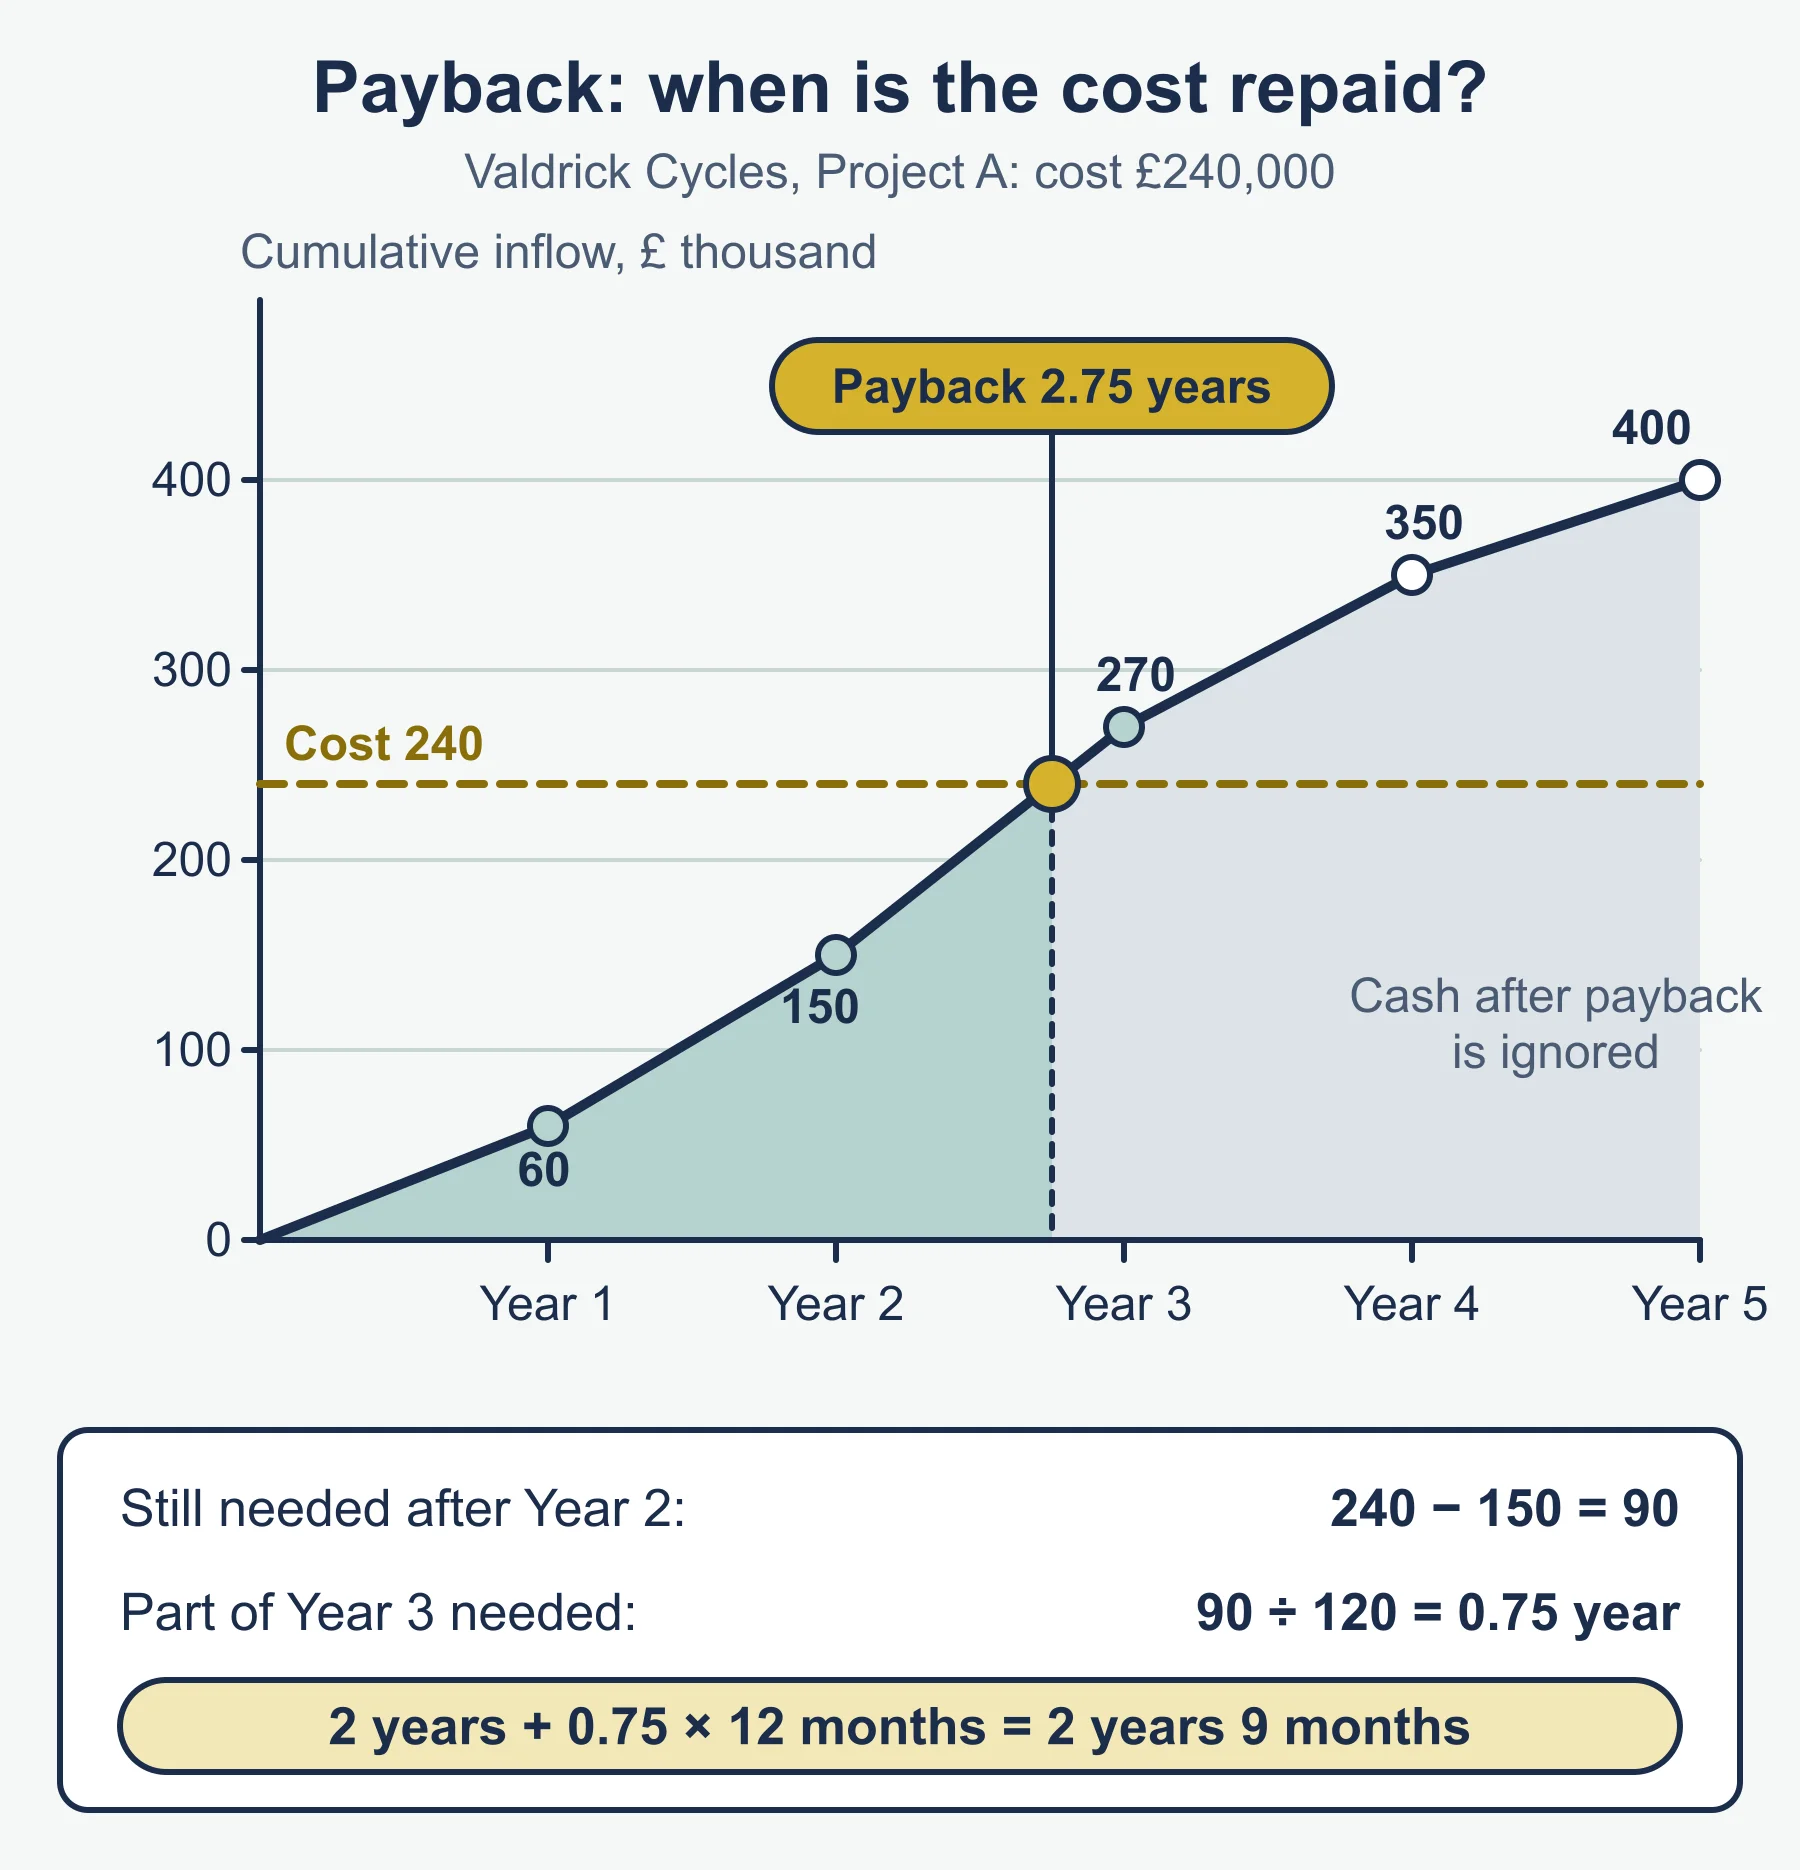
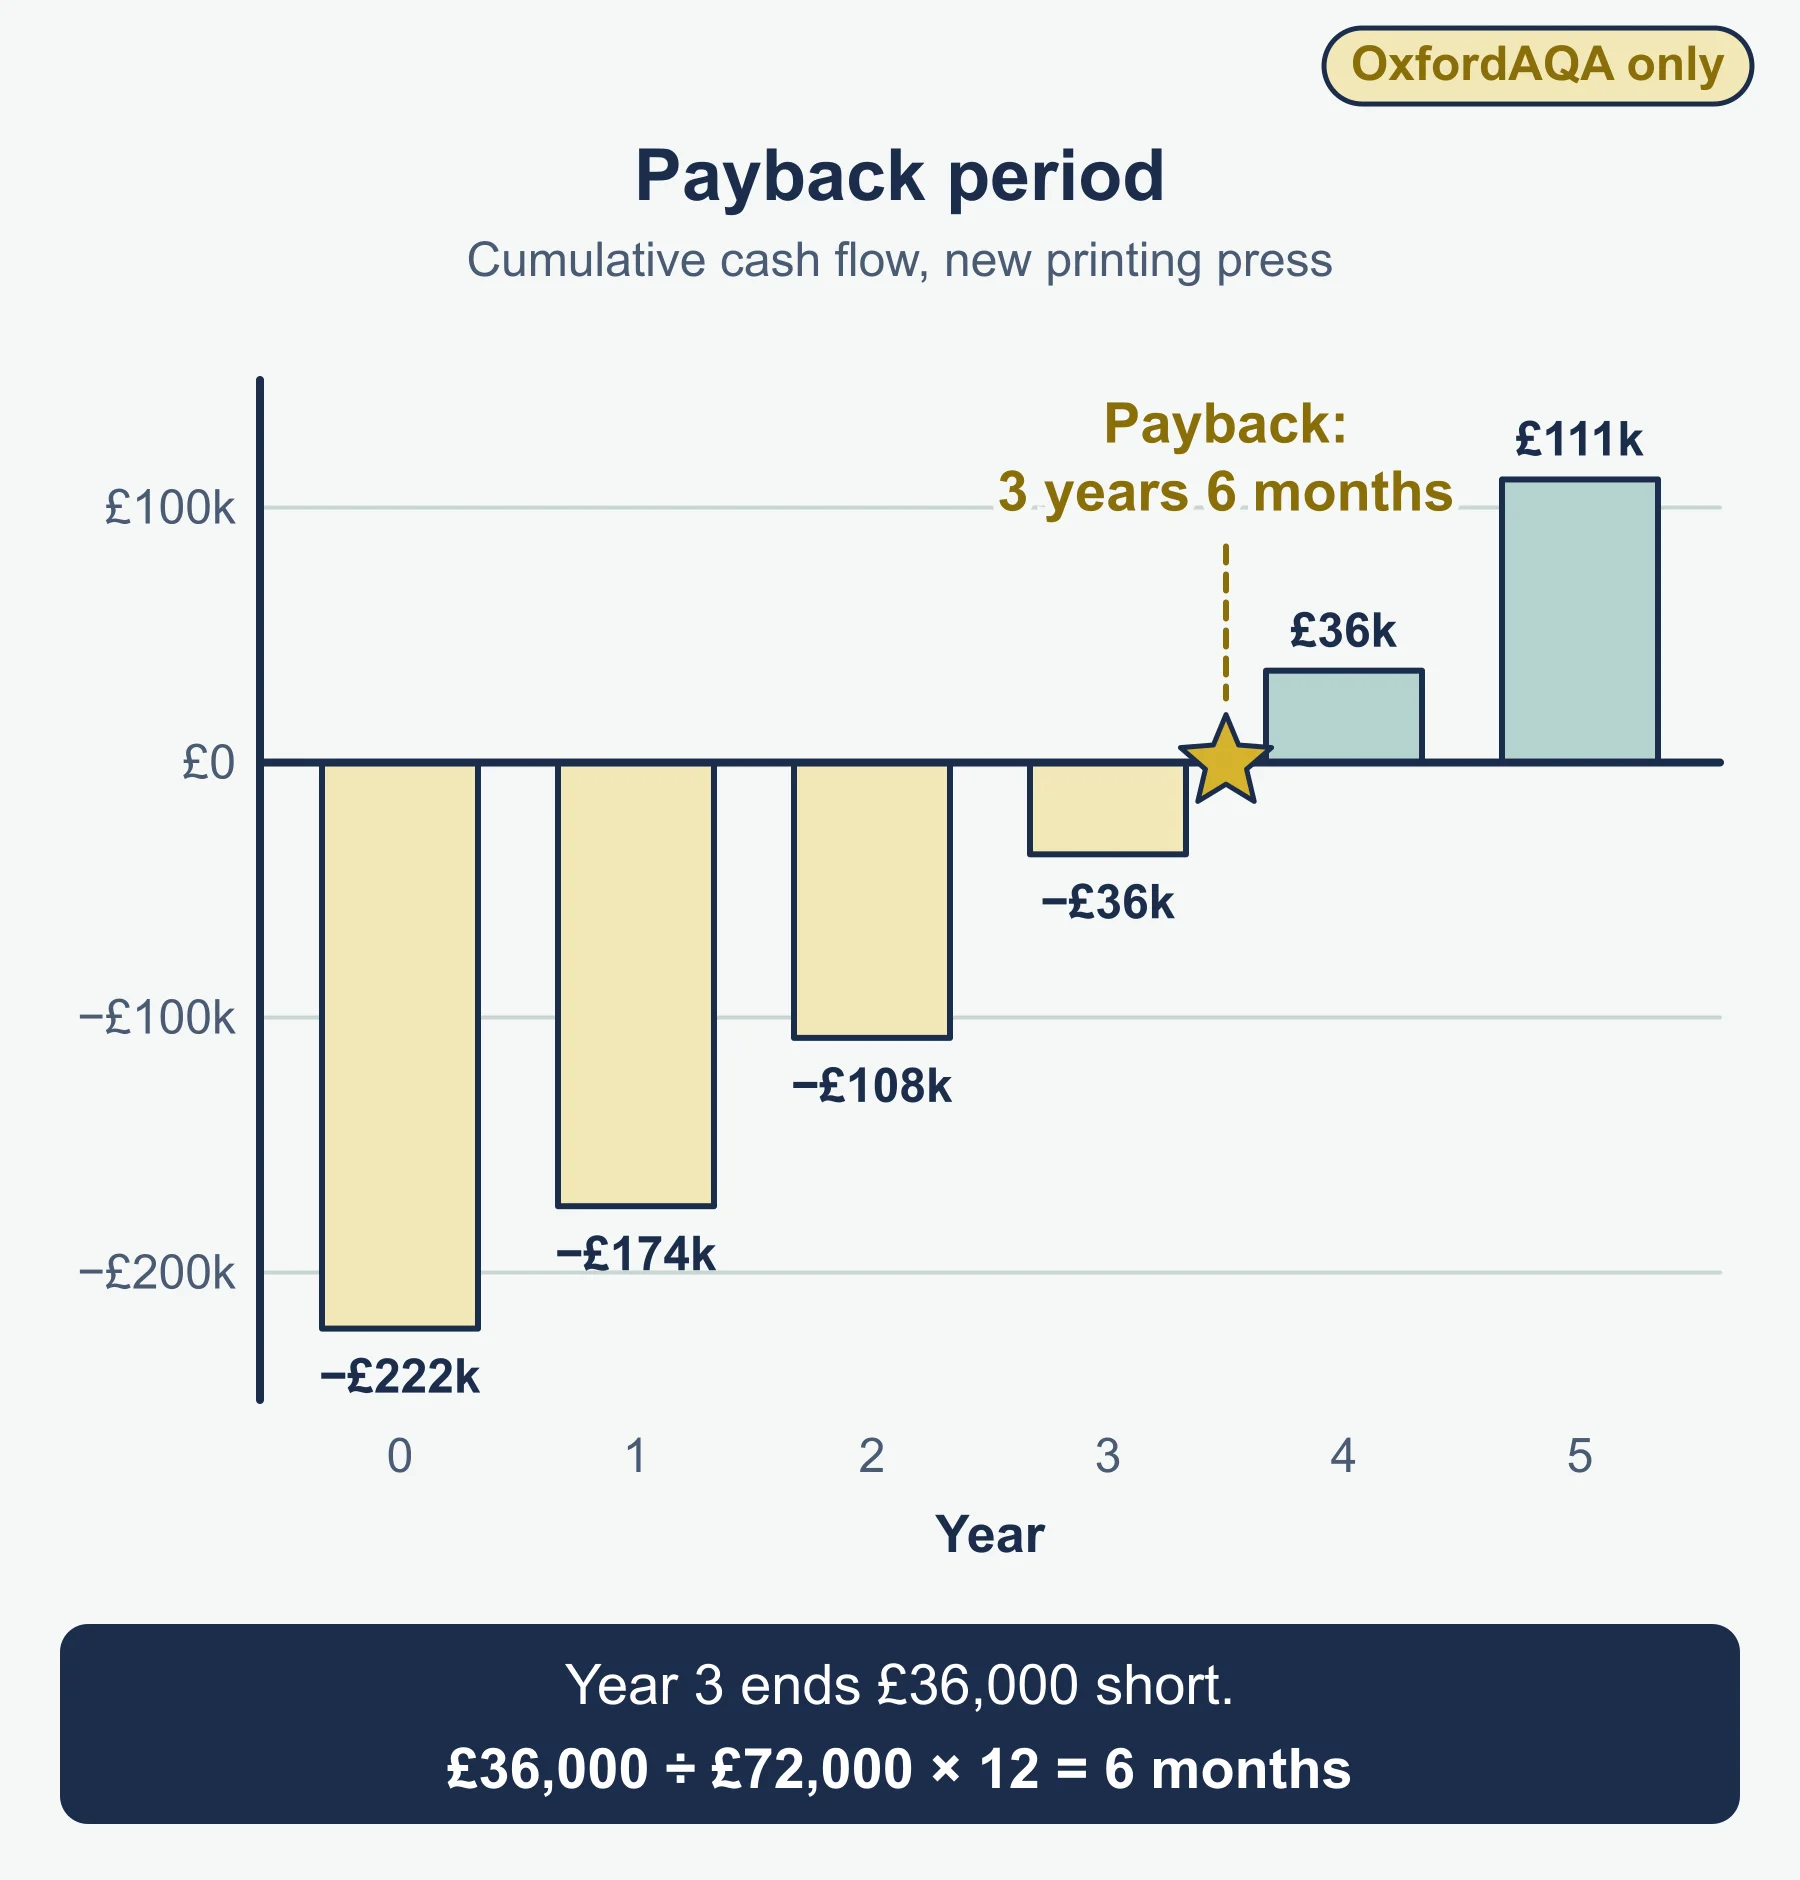
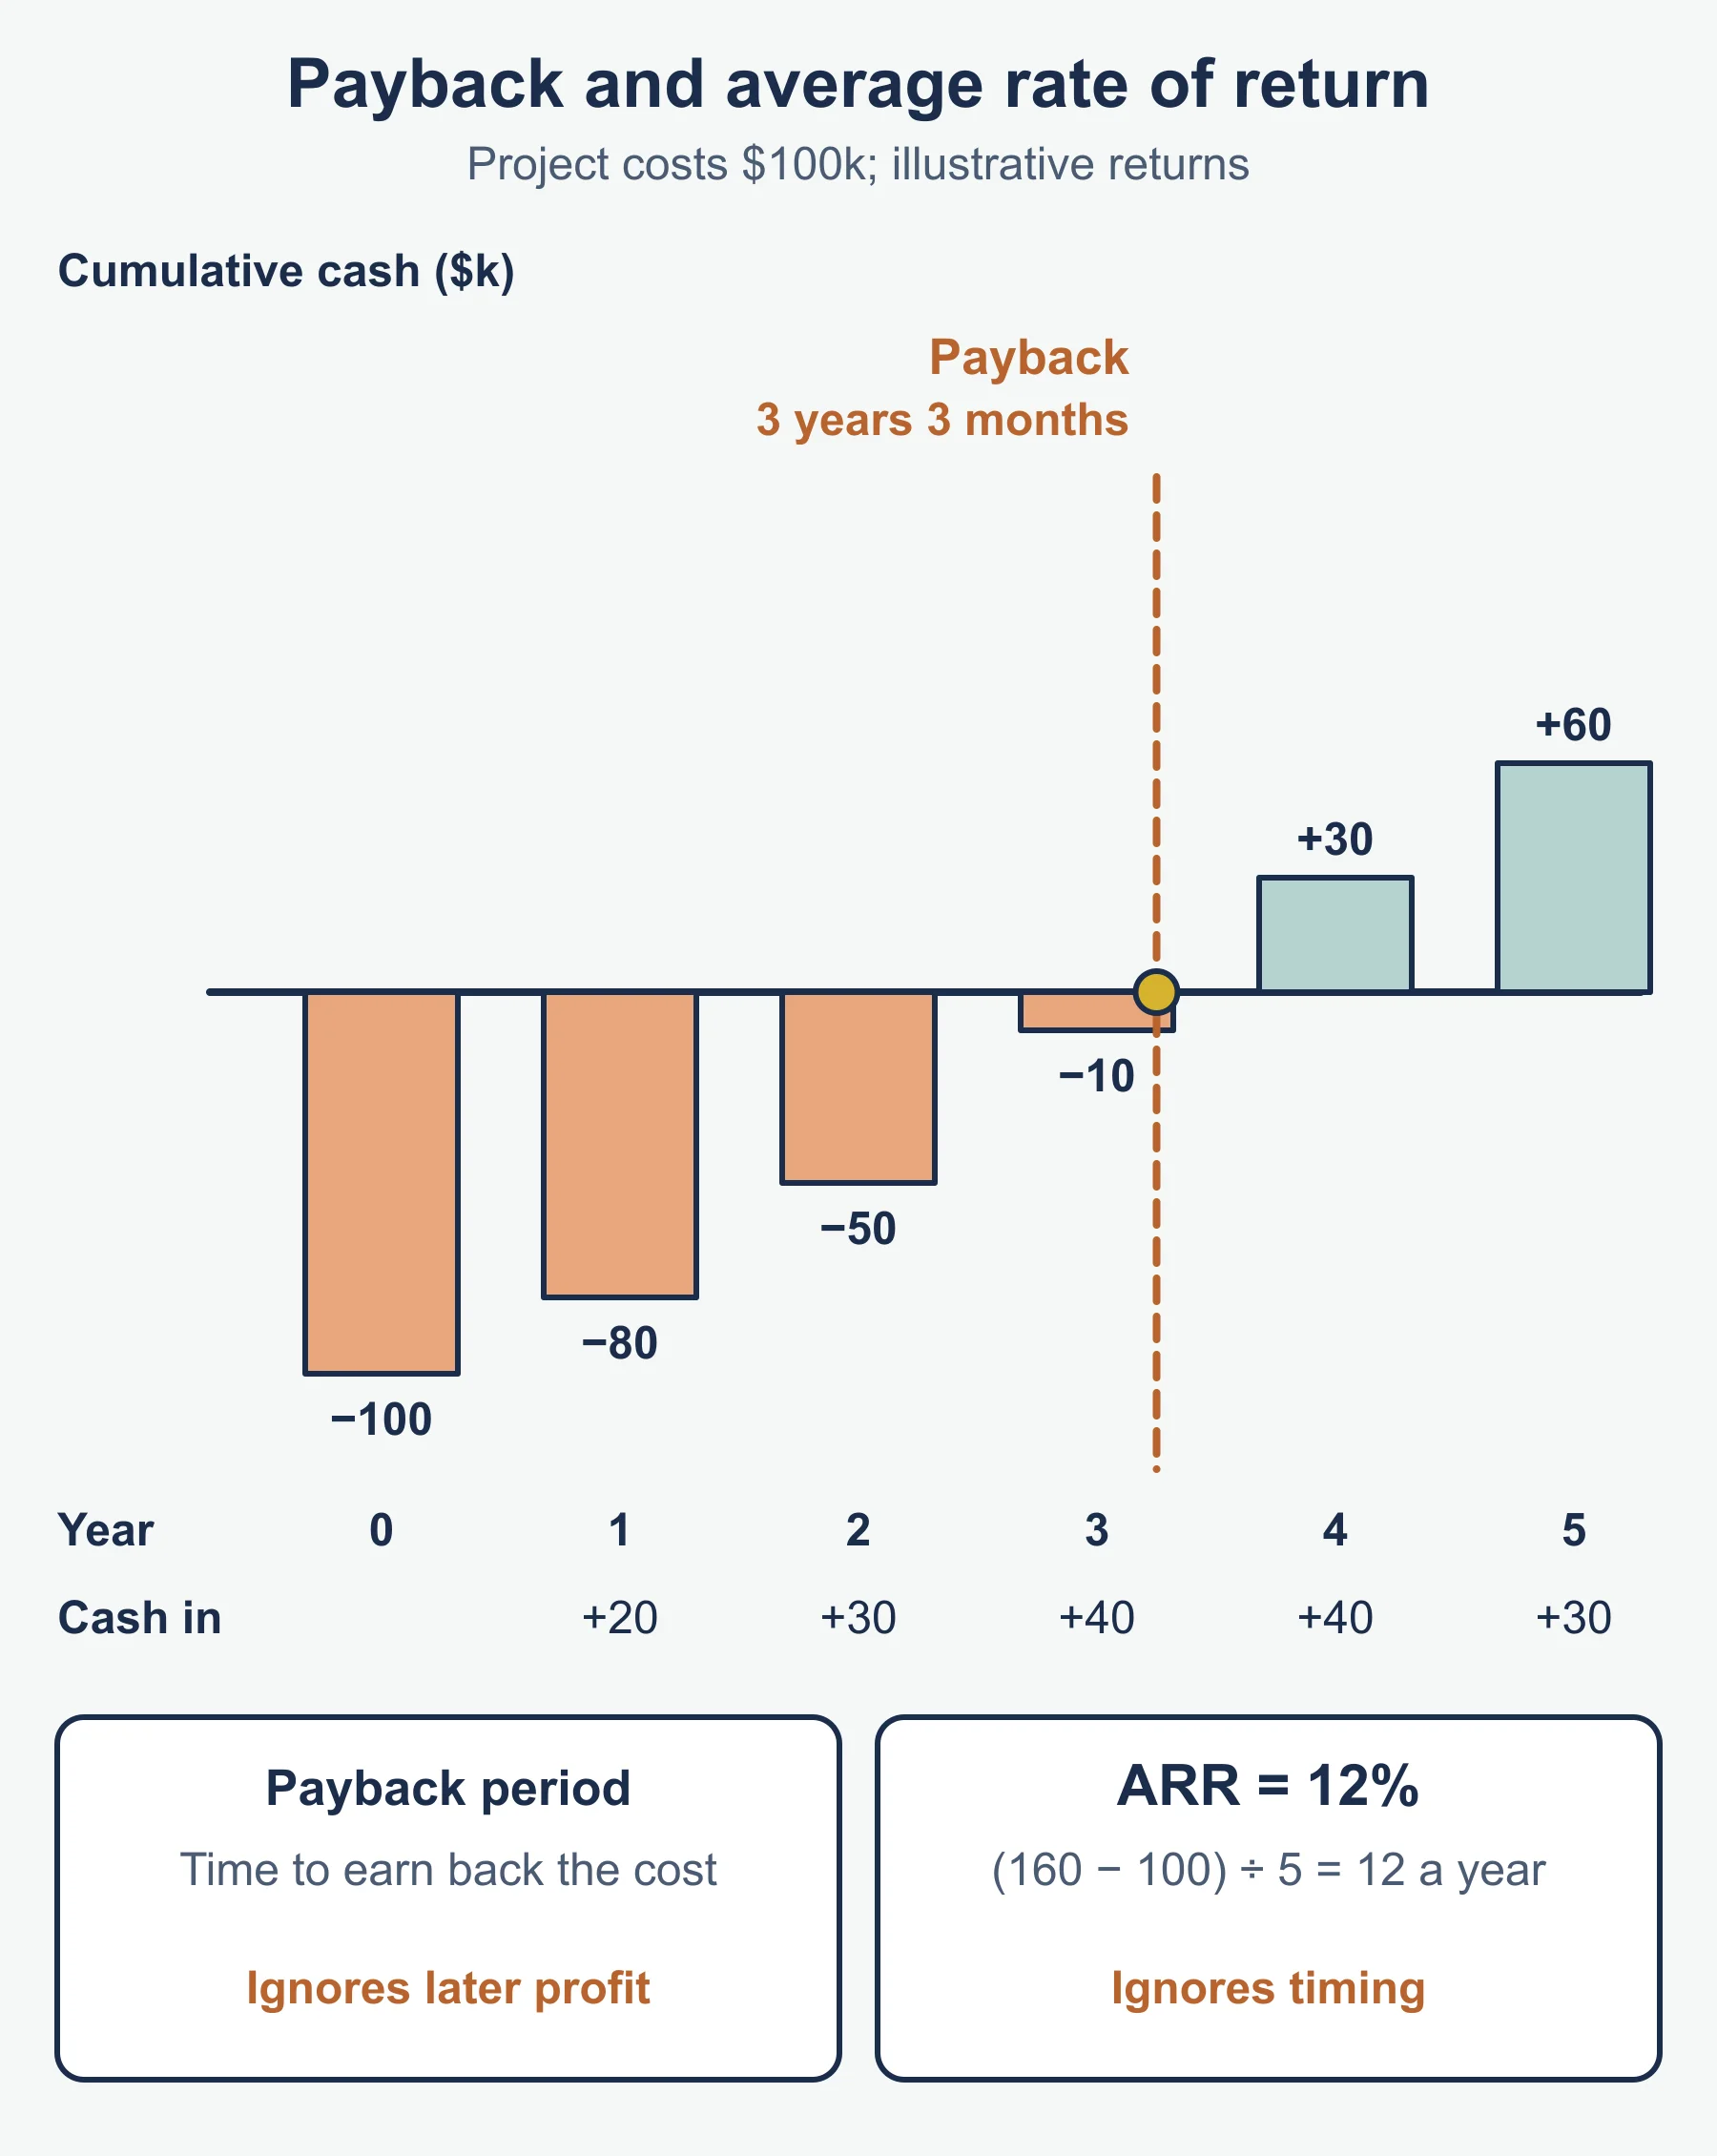
- Payback: write the cumulative total for each year. Find the year it passes the cost. Fraction = amount still needed / that year’s inflow. Convert to months.
- ARR: total inflows, minus depreciation, divided by years, over average investment, times 100.
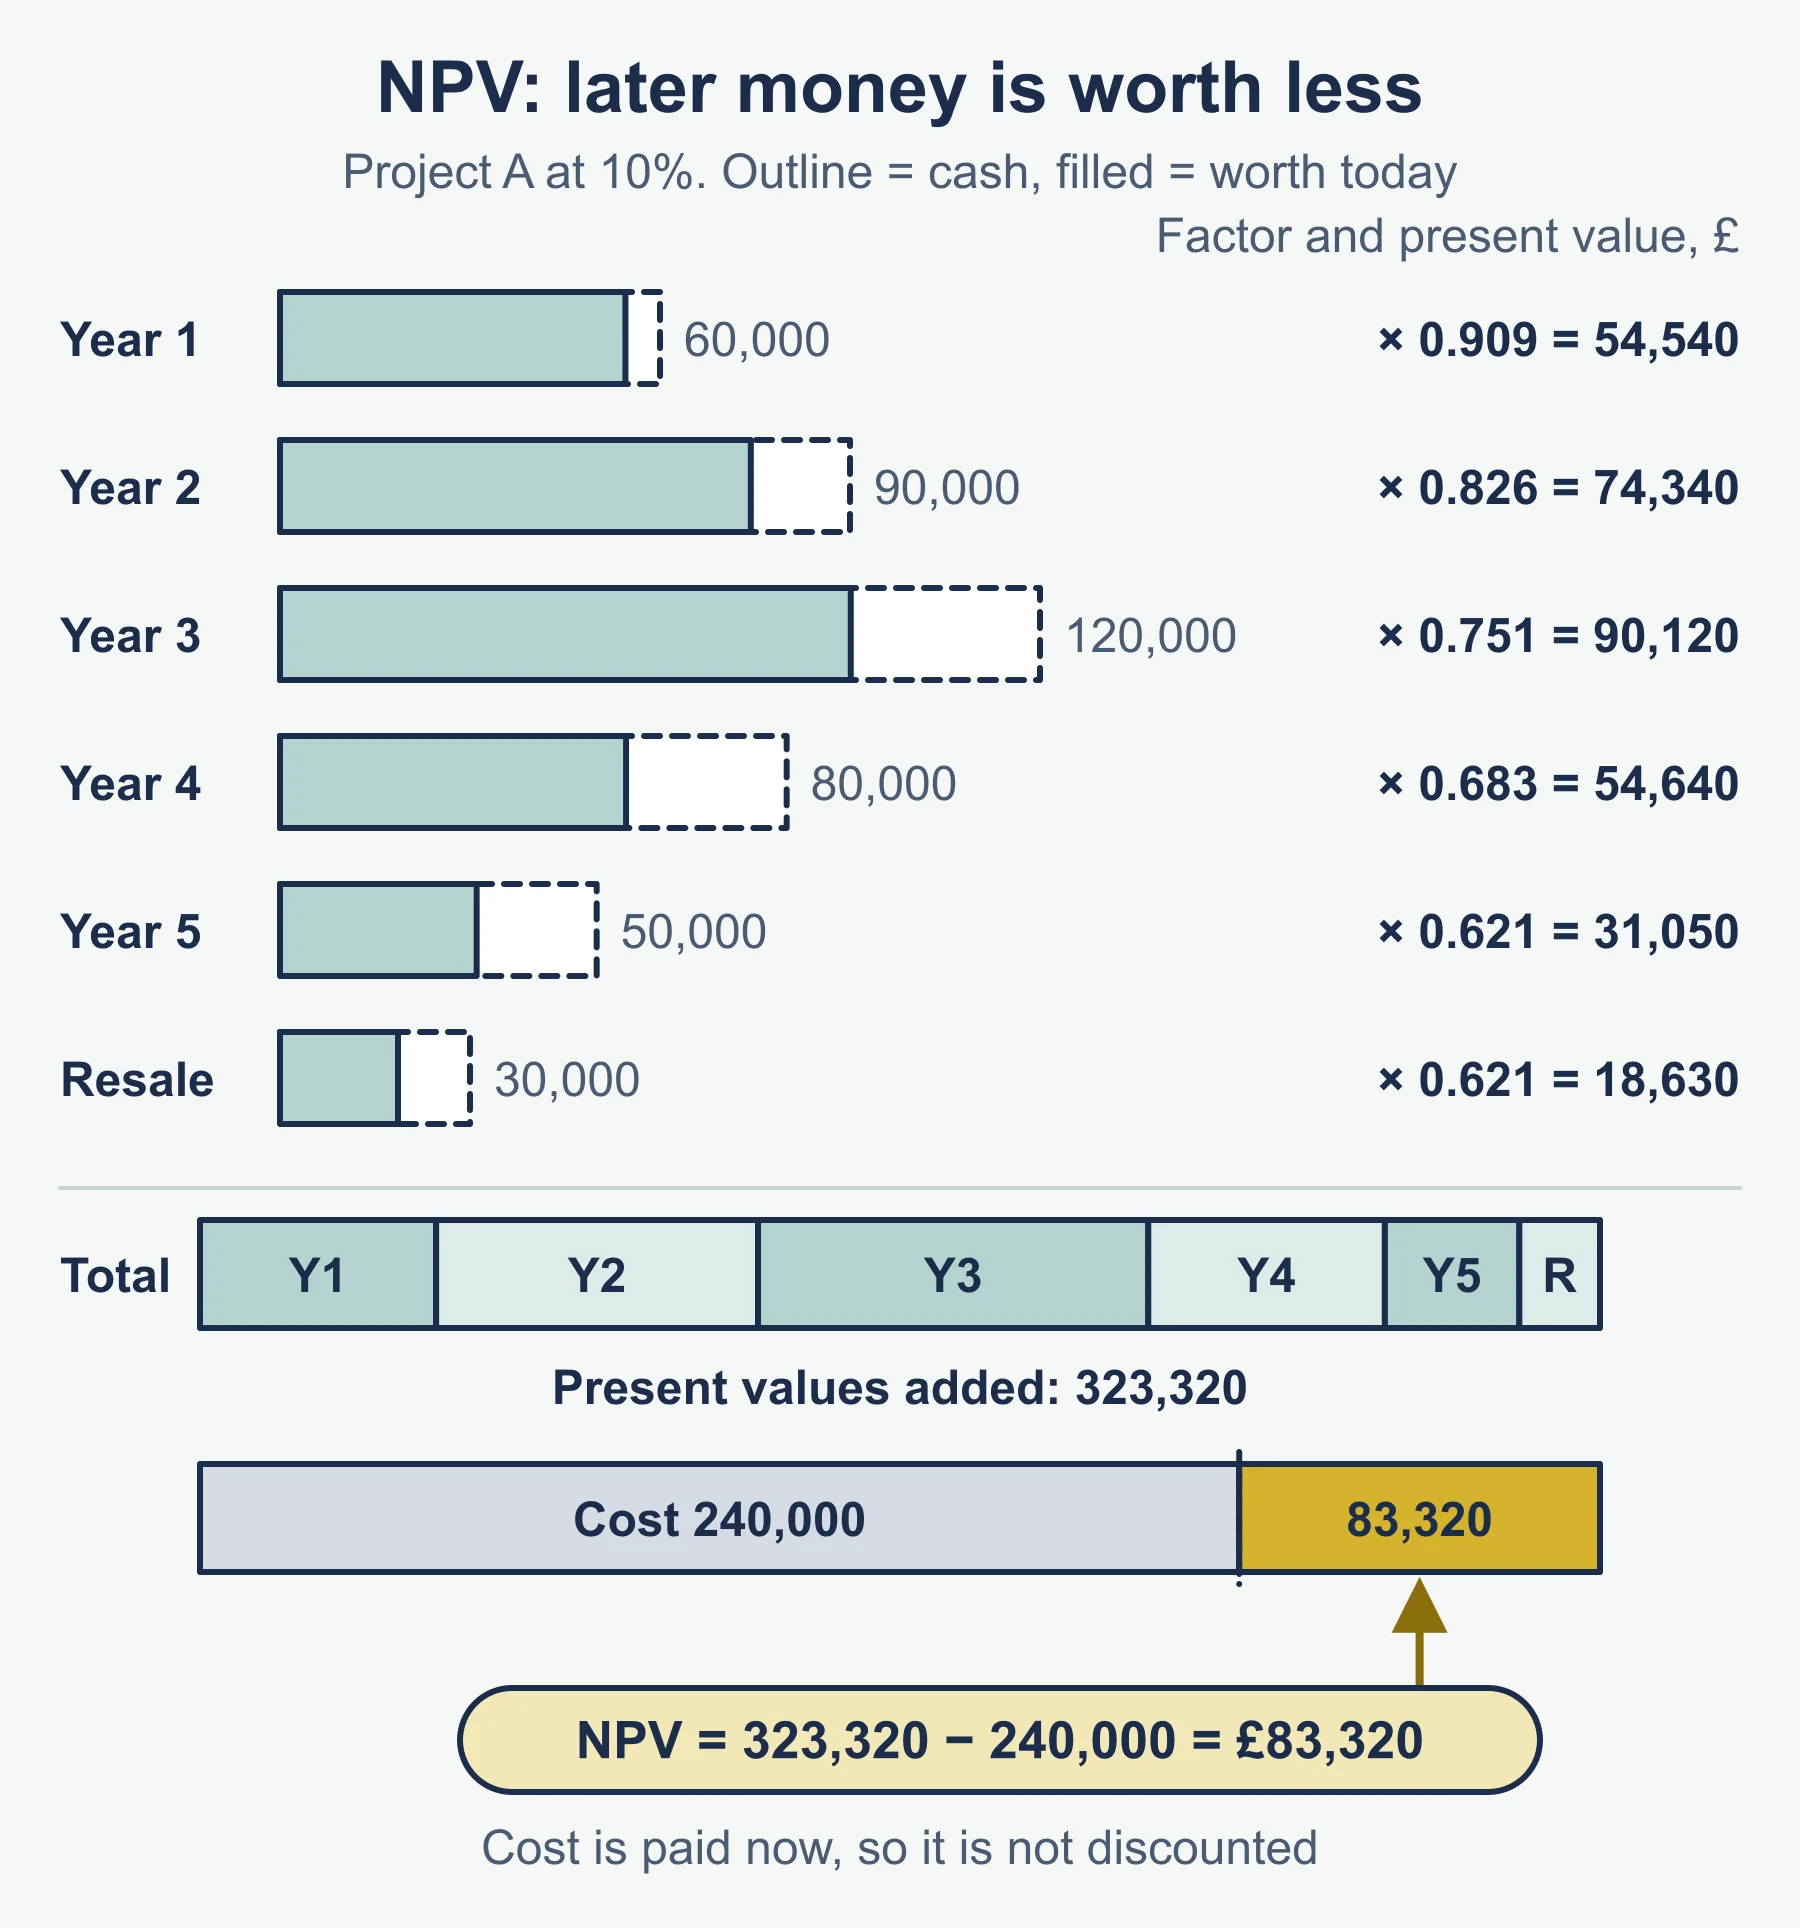
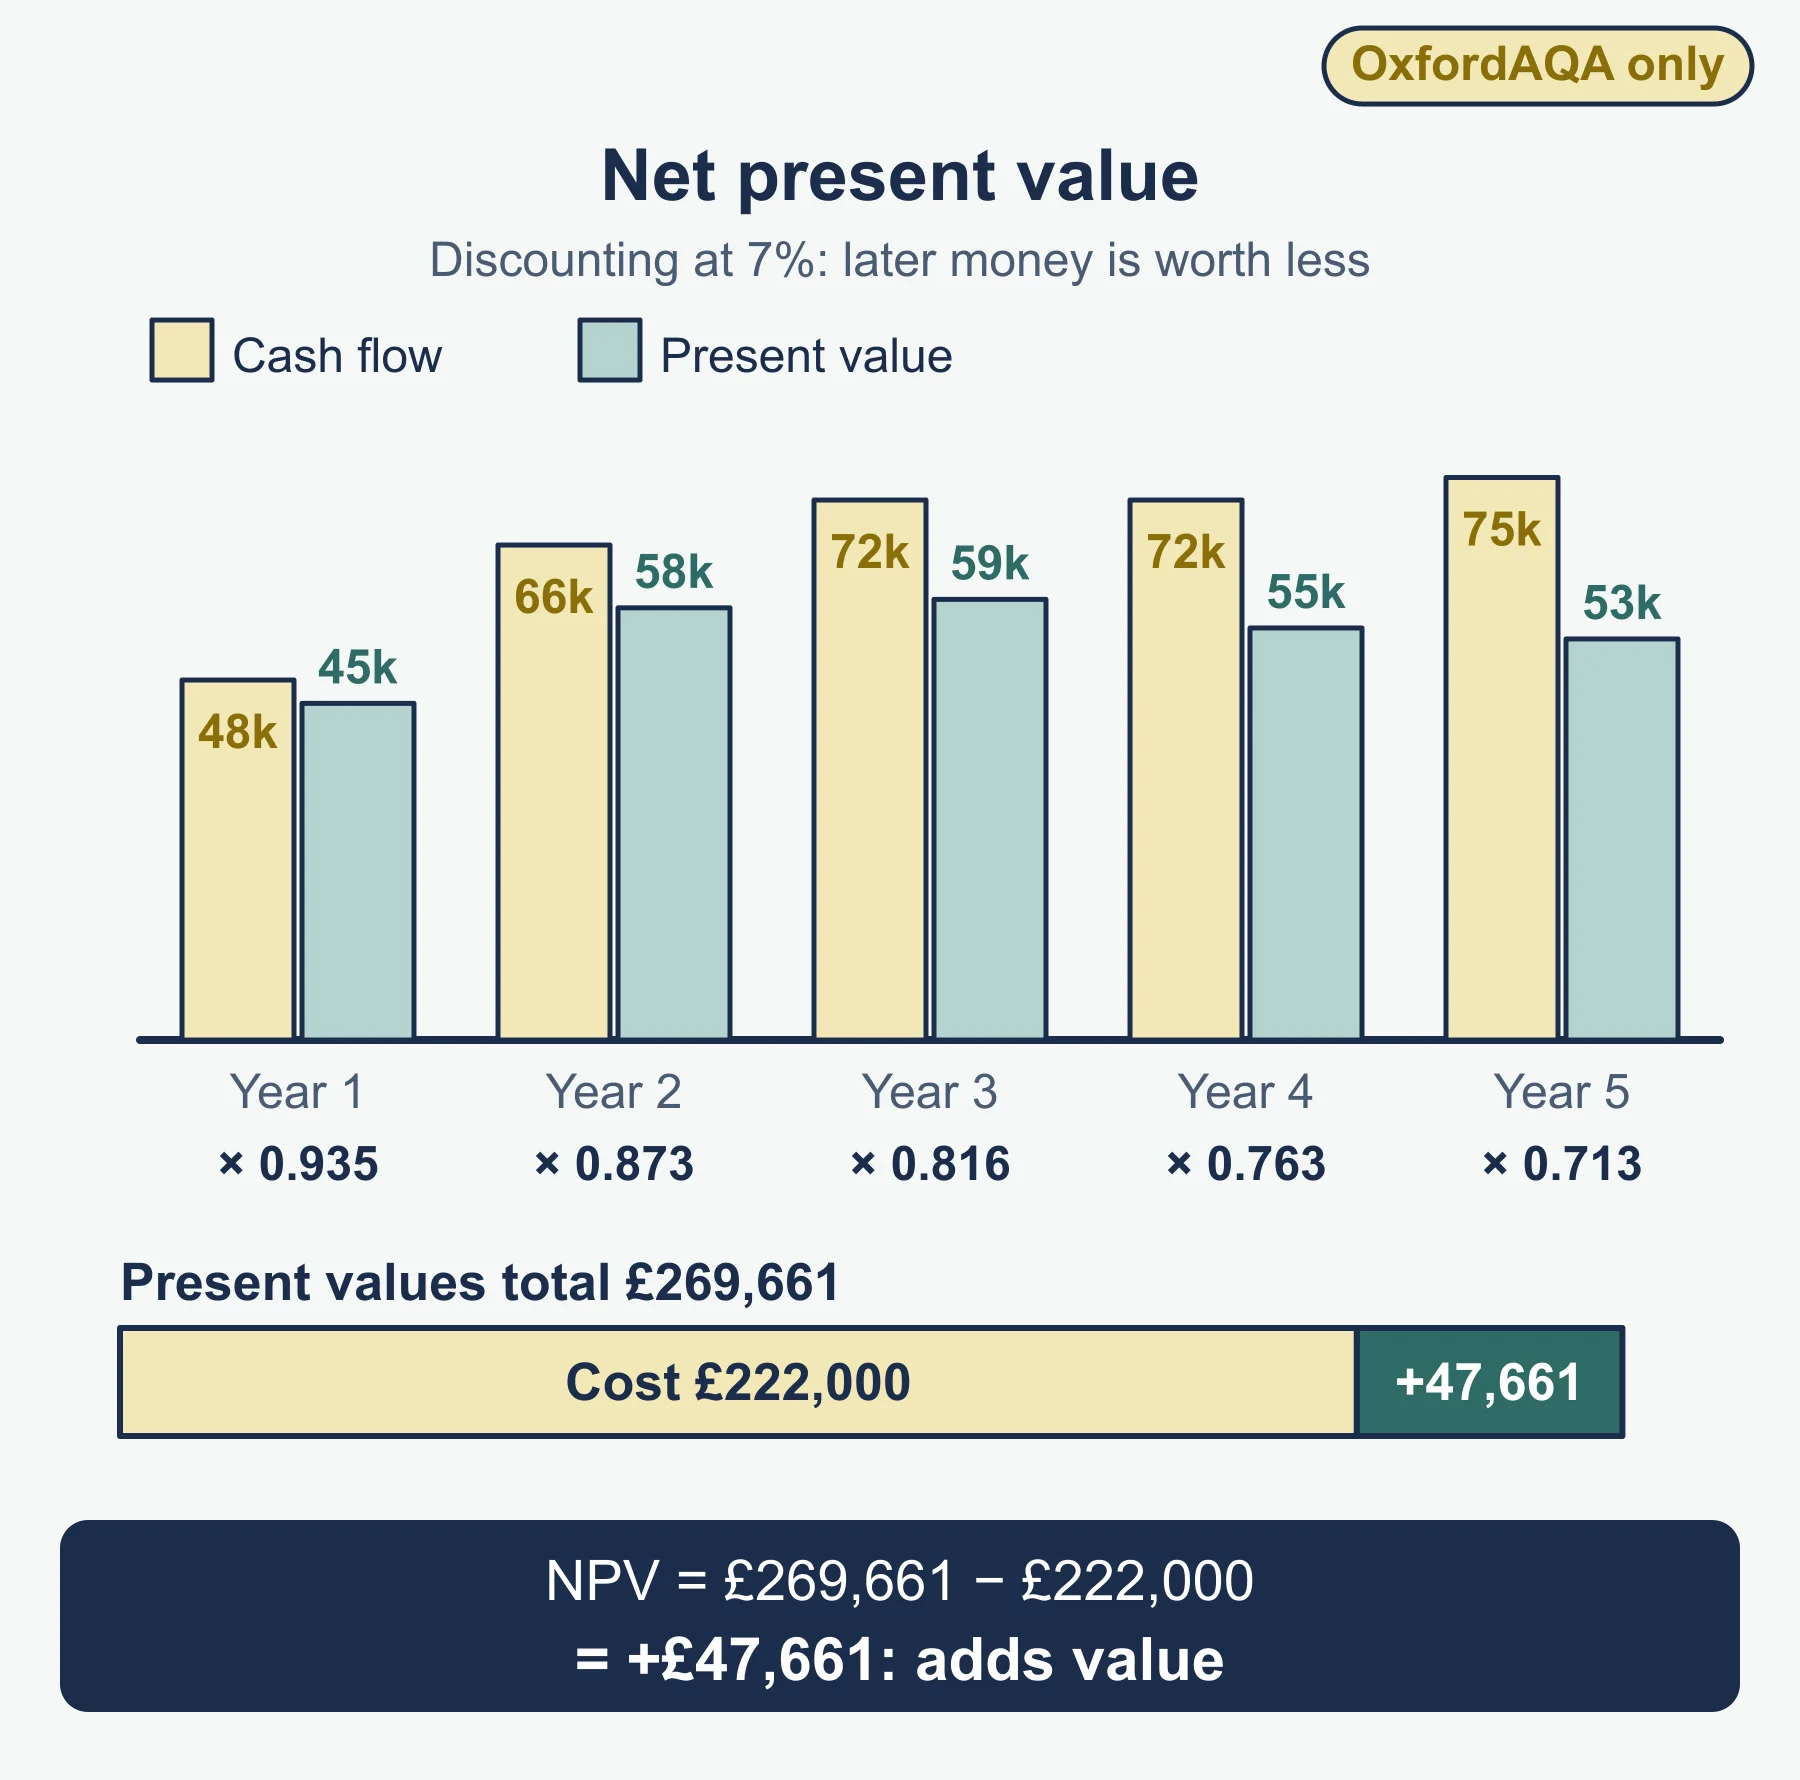
- NPV: multiply each year by its factor, add the results (including any residual value at the end), then subtract the cost.
Worked reminder: Sunderwick Foods
A packing line costs £70,000. Inflows are £20,000, £30,000, £30,000 and £20,000 in Years 1 to 4, and the residual value is £10,000.
- Payback: after Year 2 the total is £50,000. £20,000 is still needed, out of £30,000 in Year 3, which is two thirds of a year. Payback is 2 years 8 months.
- ARR: total profit = 100,000 − 60,000 = £40,000, so the average is £10,000. Average investment = (70,000 + 10,000) / 2 = £40,000. ARR = 25%.
- NPV at 8% (factors 0.926, 0.857, 0.794, 0.735): present values £18,520, £25,710, £23,820 and £14,700, plus residual 10,000 × 0.735 = £7,350. Total £90,100 less £70,000 gives £20,100.
Decisions and limitations (10.3.4)
| Method | Strength | Limitation |
|---|---|---|
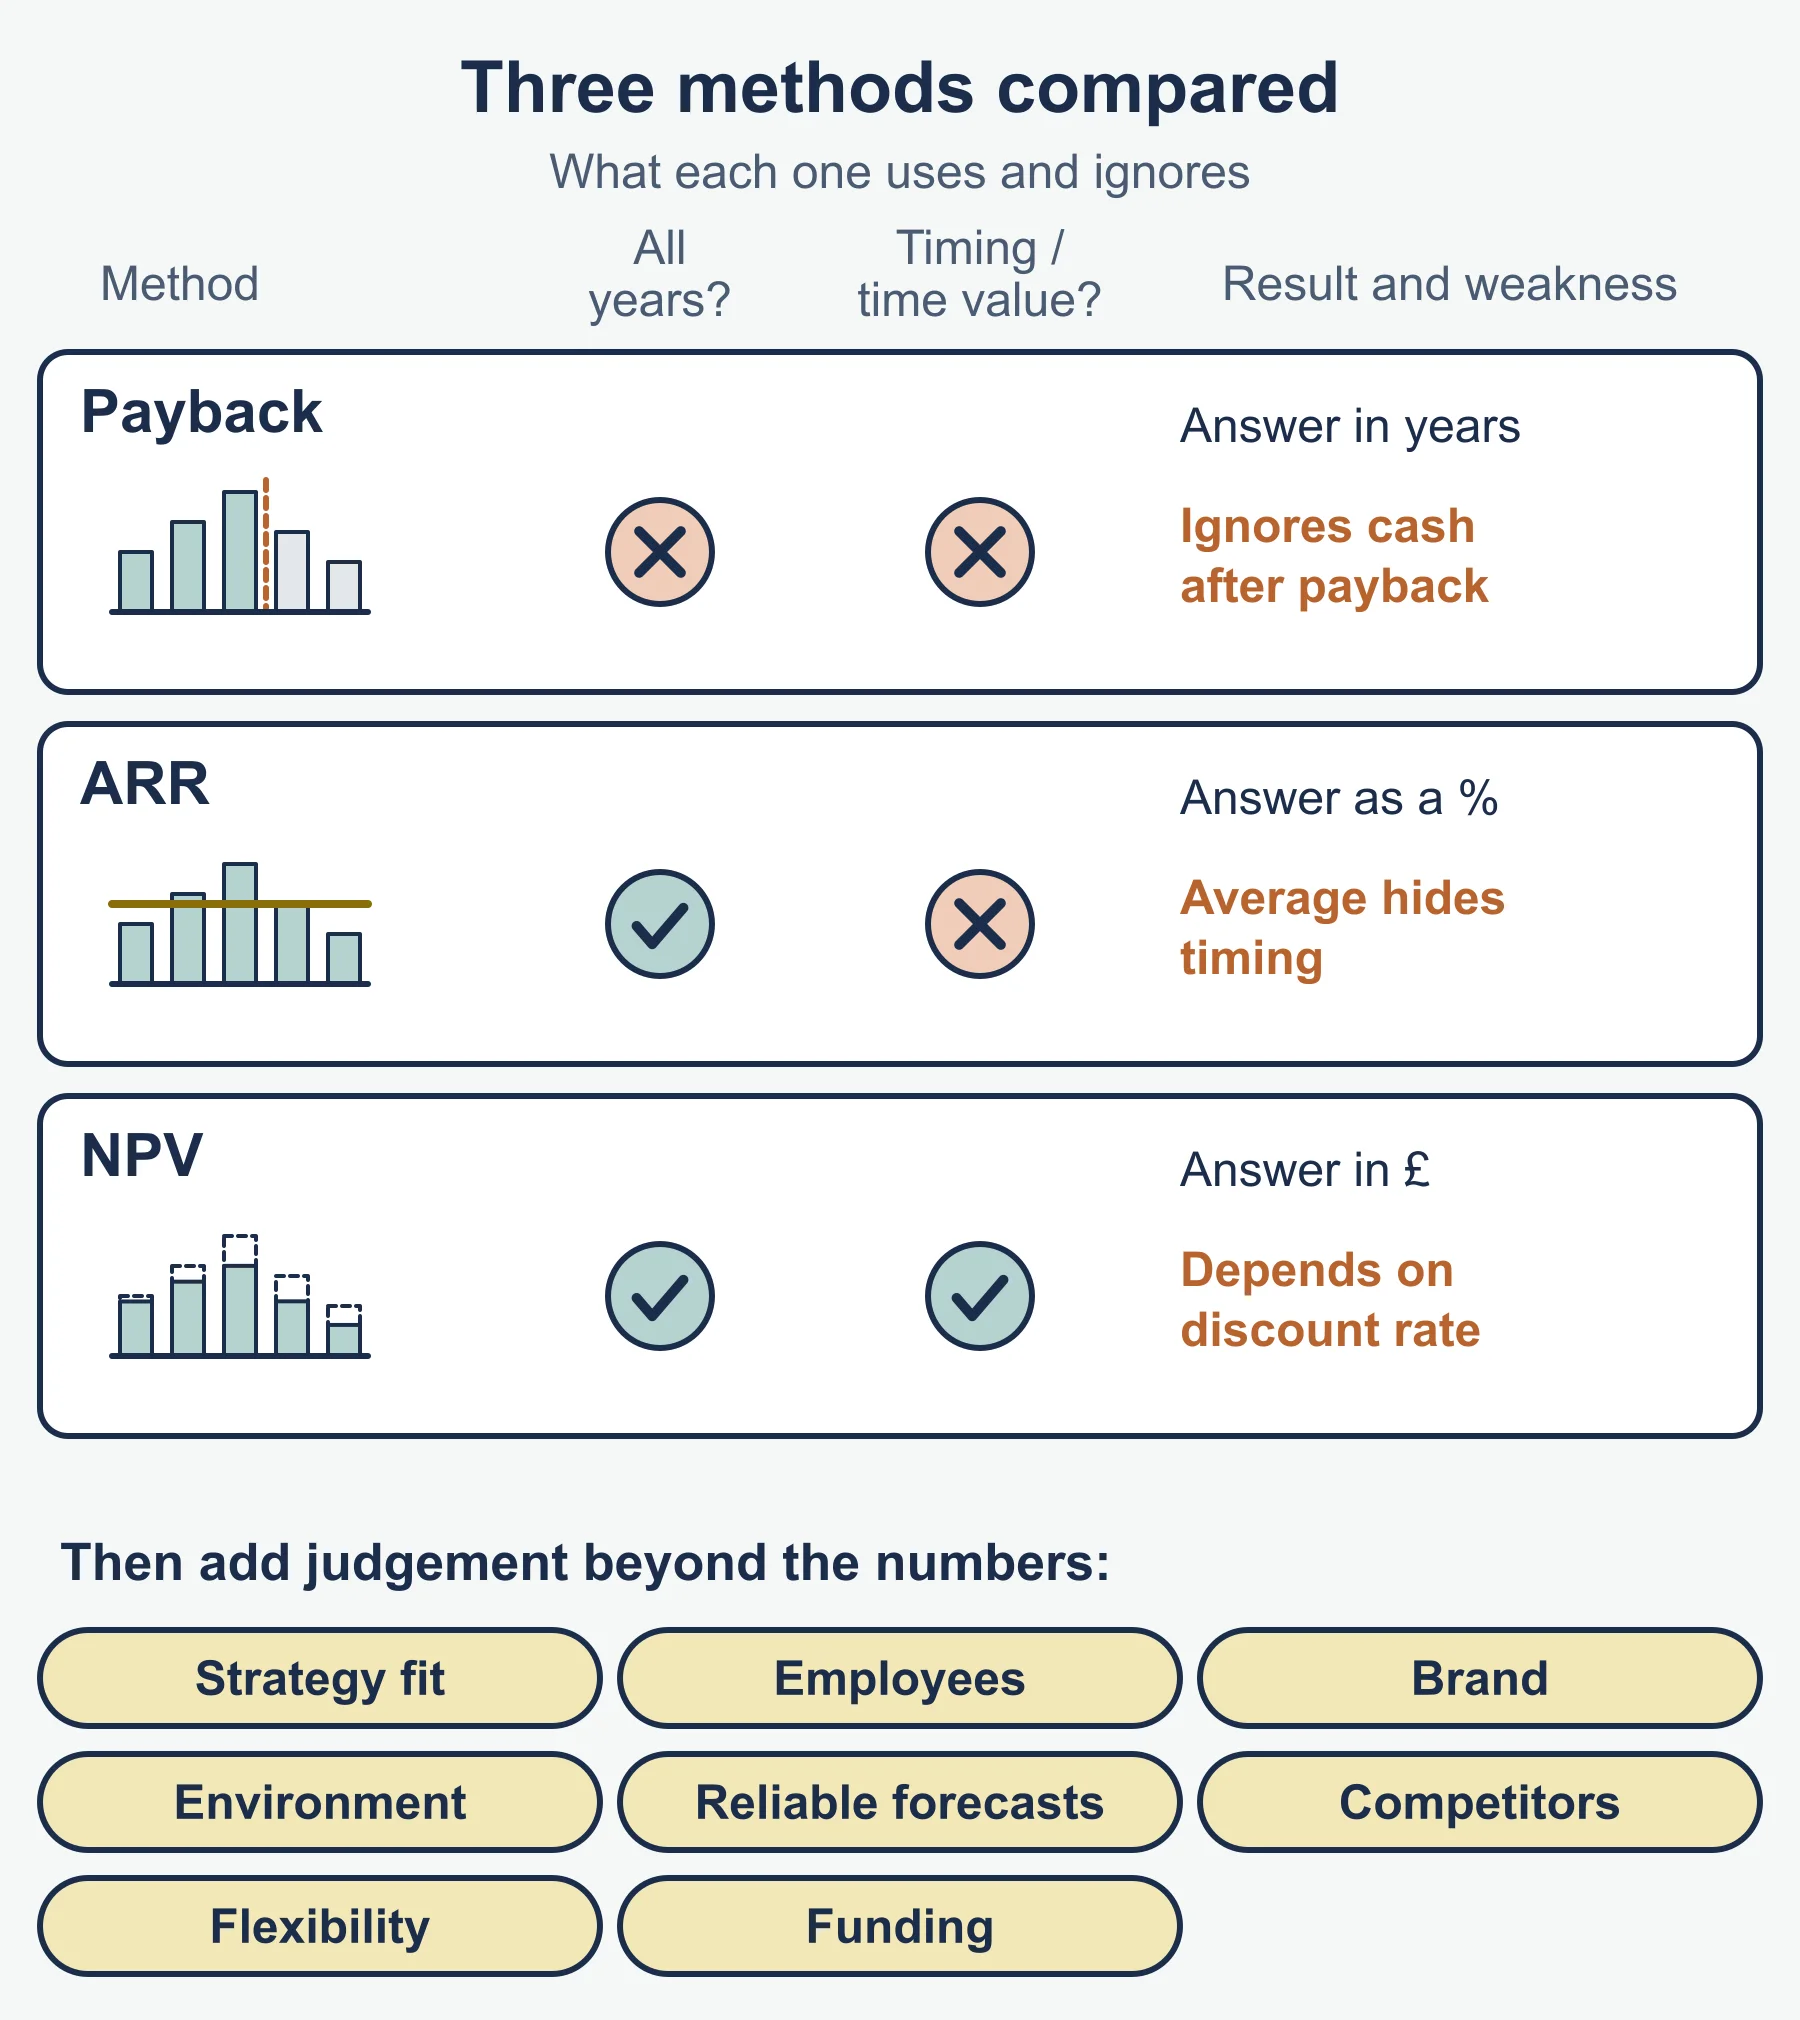
| Payback | Simple; shows how soon cash returns | Ignores later cash and the time value of money |
| ARR | Uses all years; percentage | Average hides timing; depends on how profit and investment are defined |
| NPV | Allows for time value; value in pounds | Result depends on the discount rate; harder to calculate |
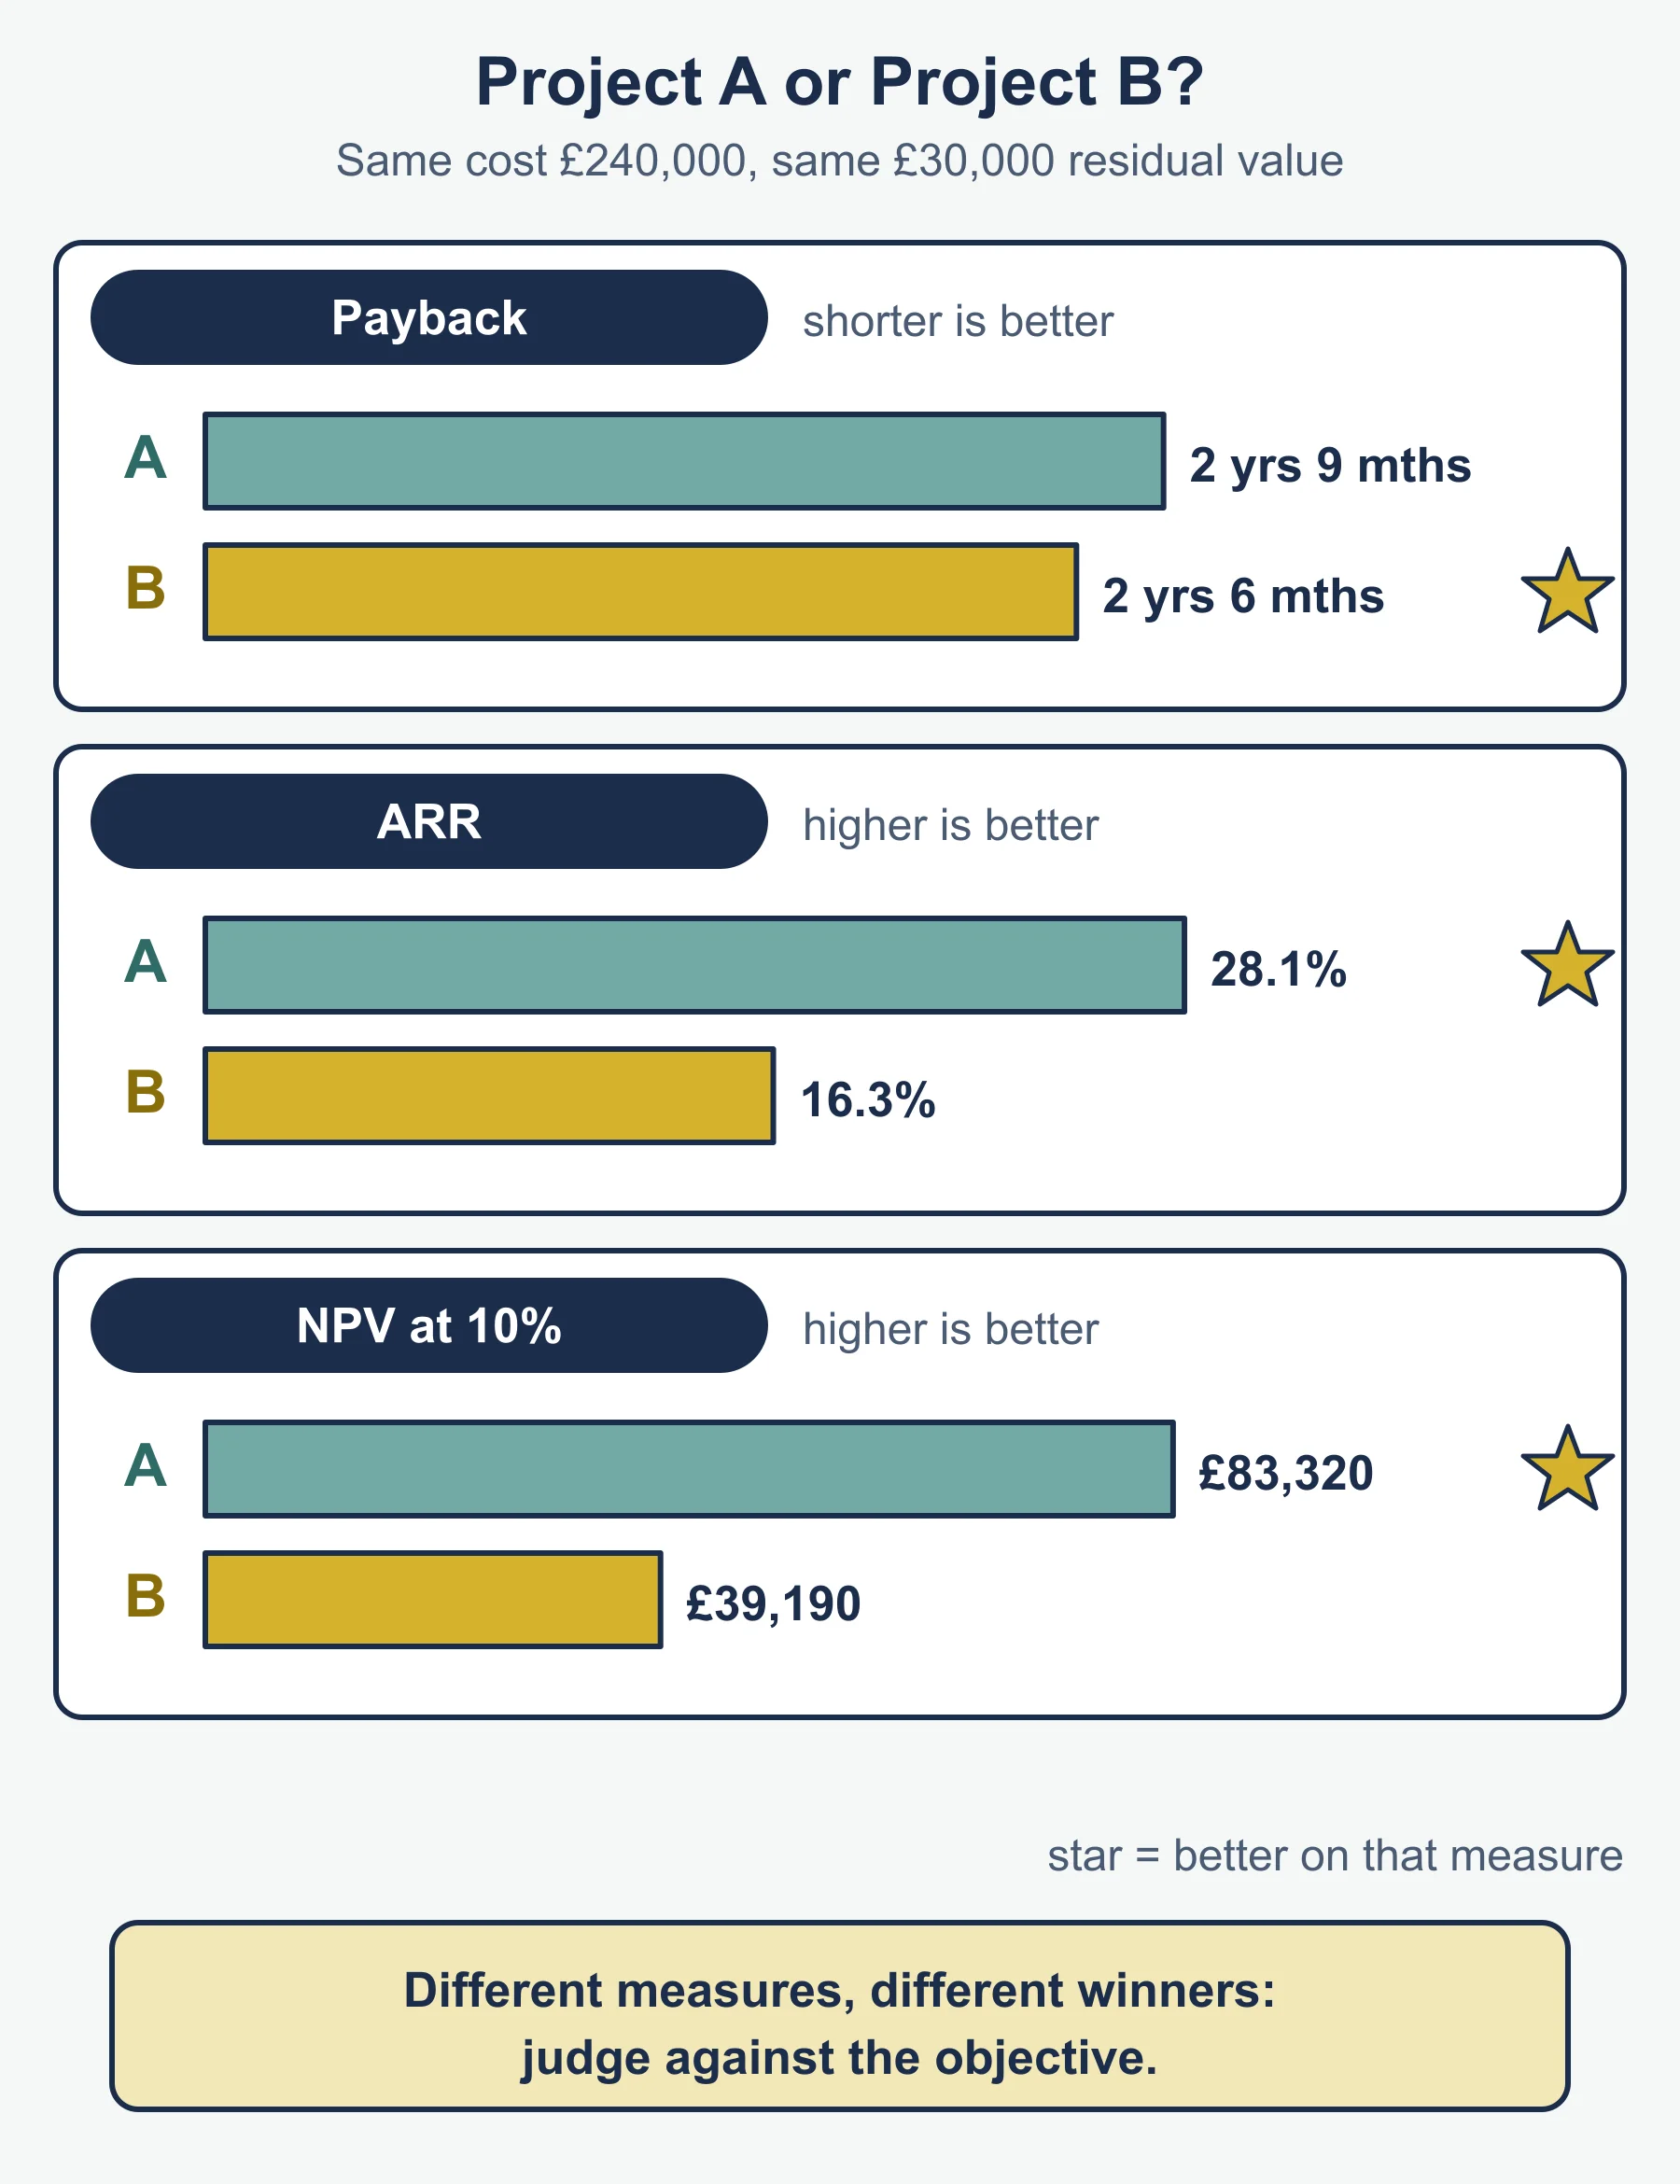
- Quantitative results: compare with criterion rates, maximum payback and a positive NPV. Methods can rank projects differently.
- Qualitative factors: strategic fit, employees, brand and reputation, environmental impact, reliability of forecasts, competitors’ reactions, flexibility, method of funding.
- Every method relies on forecasts. A balanced recommendation uses more than one method plus judgement.
10.4 Finance and accounting strategy
Accounting data and the annual report (10.4.1)
- Statement of financial position: what the business owns and owes, which shows funding capacity and financial strength.
- Statement of profit or loss: revenue, costs and profit, which shows what earns well.
- Used to set targets, choose growth or consolidation, choose funding and check progress.
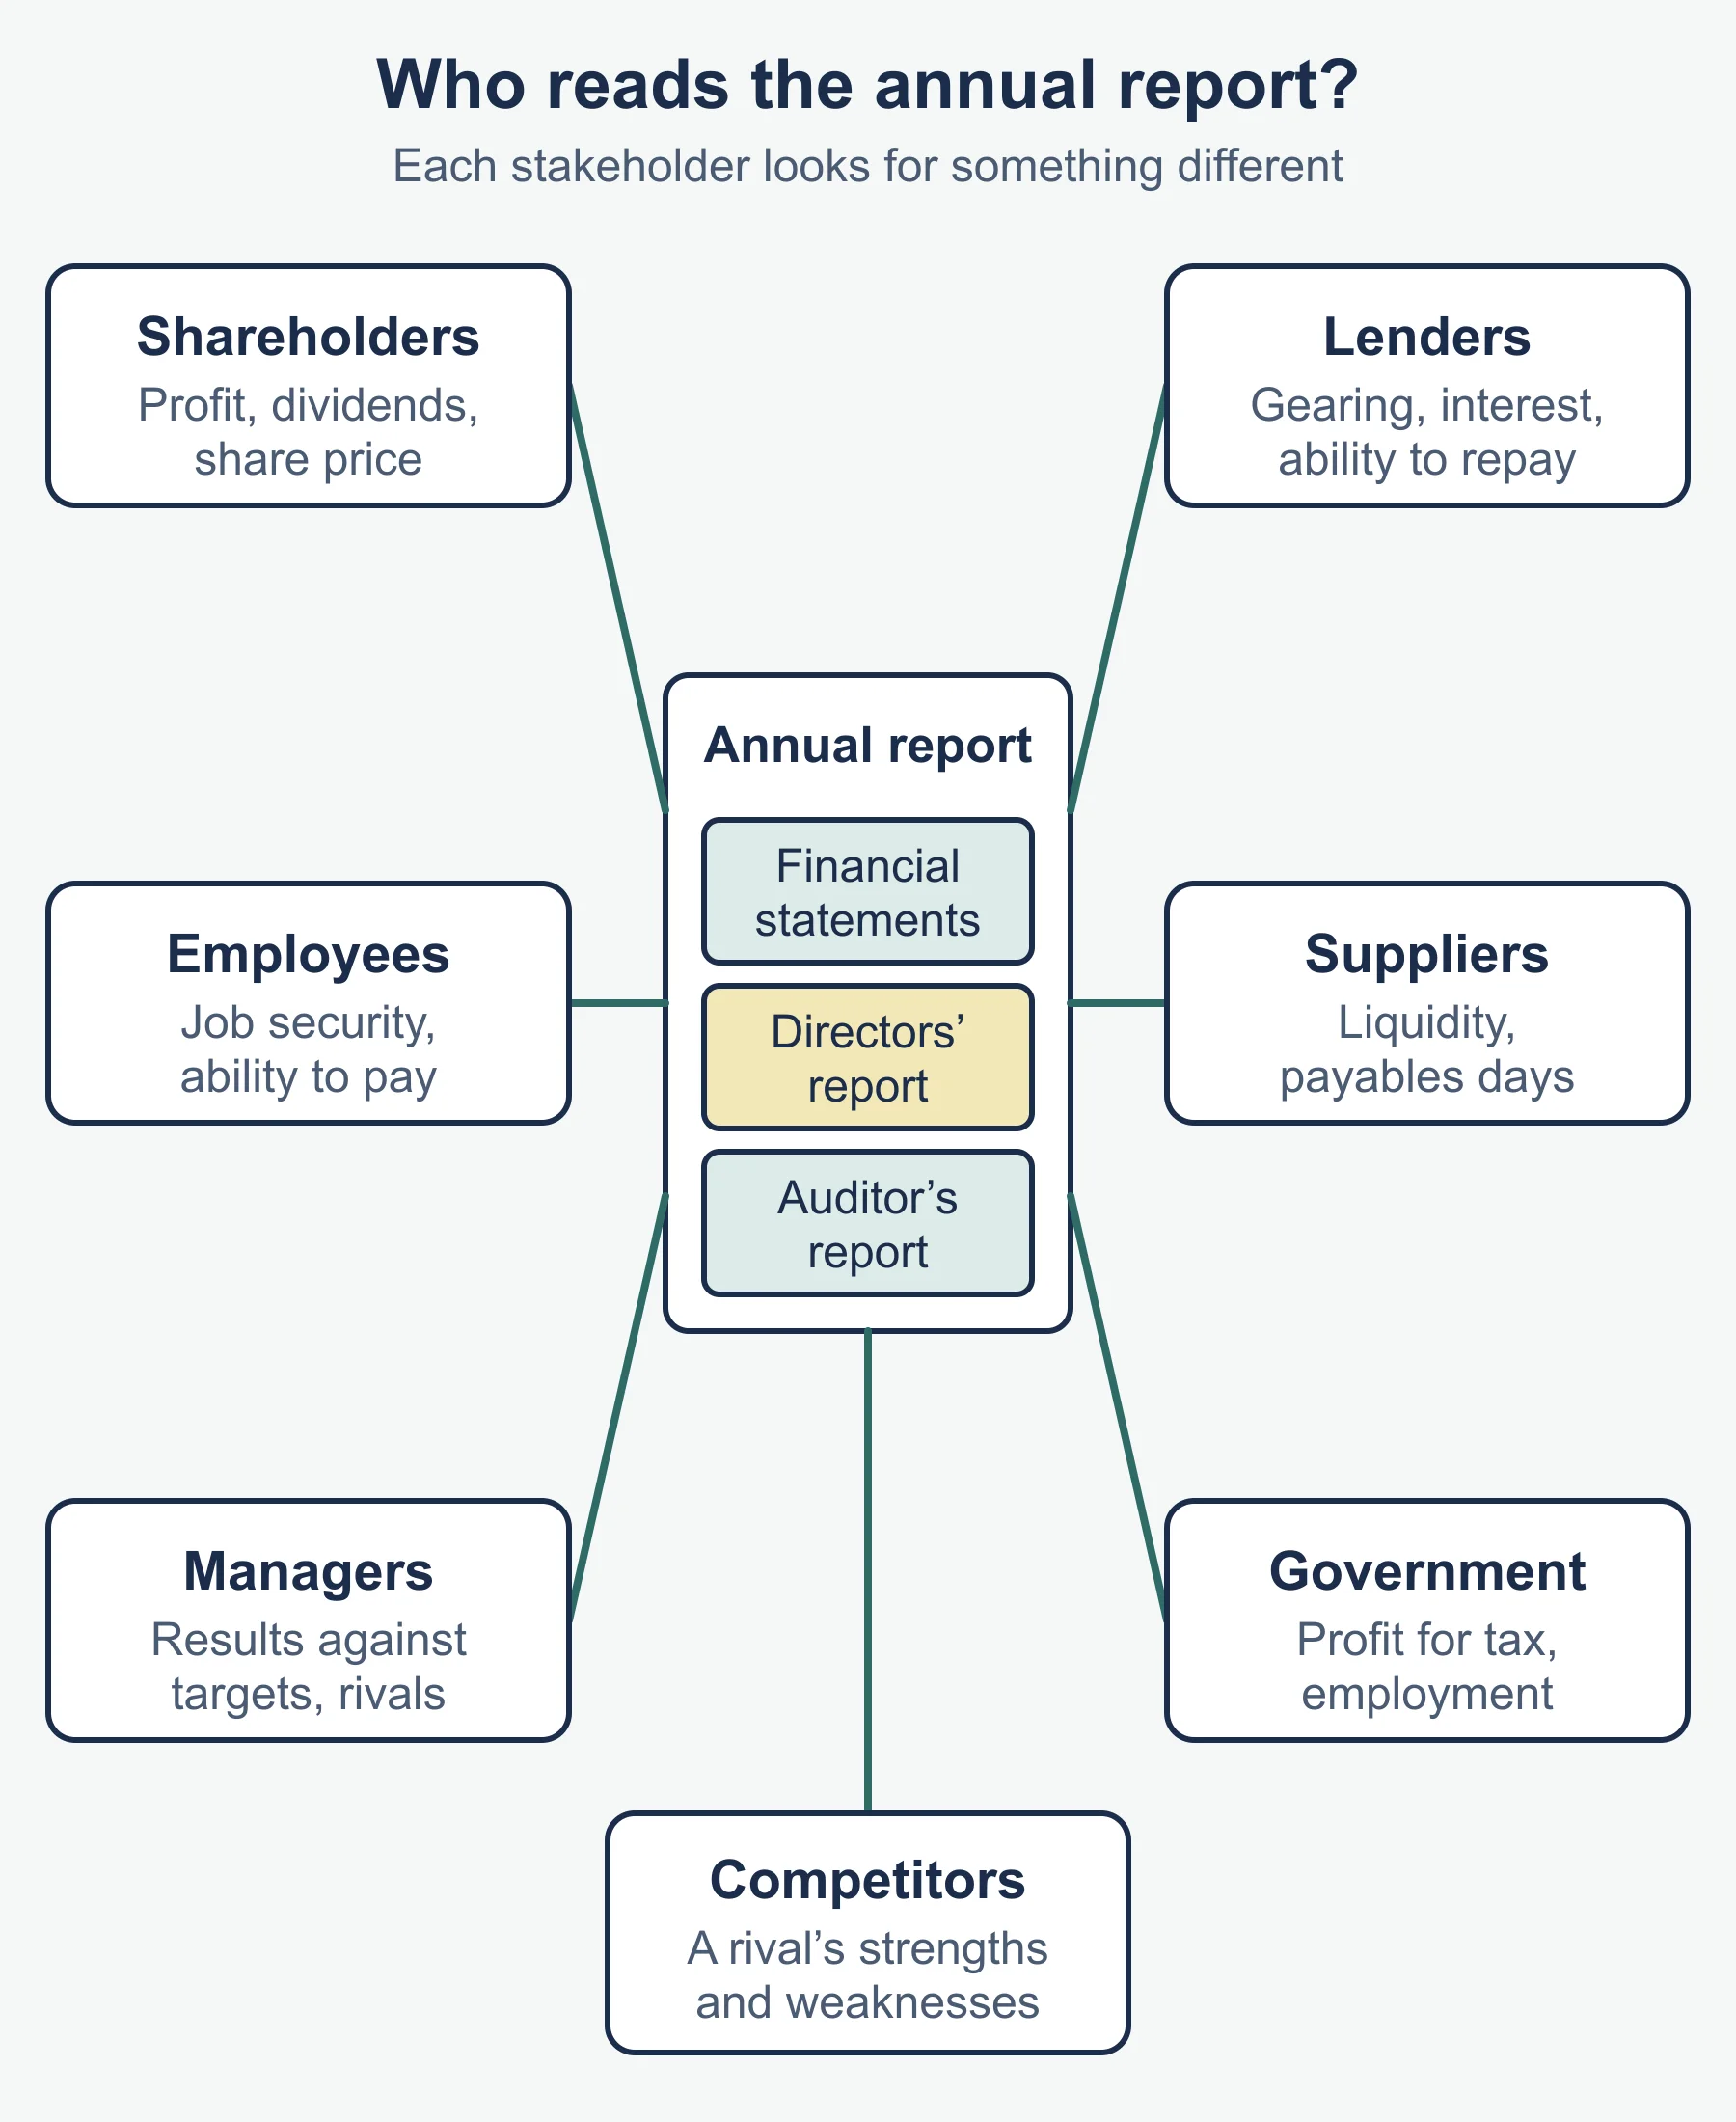
- Annual report (general description): financial statements and notes, a directors’ or chair’s report, an auditor’s report.
- Usefulness varies: shareholders want profit and dividends; lenders want gearing and ability to pay interest; suppliers want liquidity; employees want security; managers want performance against targets.
Ratio formulas (syllabus forms)
| Ratio | Formula |
|---|---|
| Current ratio | current assets / current liabilities |
| Acid test | (current assets − inventory) / current liabilities |
| Gross profit margin | gross profit / revenue × 100 |
| Operating profit margin | profit from operations / revenue × 100 |
| ROCE | profit from operations / capital employed × 100 |
| Gearing | non-current liabilities / capital employed × 100 |
| Dividend yield | dividend per share / market price per share × 100 |
| Dividend cover | profit for the year / annual dividend |
| Price/earnings | market price per share / earnings per share |
Capital employed = issued shares + reserves + non-current liabilities. Receivables and payables days use × 365 days, and inventory turnover uses cost of sales / average inventory.
How strategy changes ratios (10.4.2)
| Decision or event | Likely ratio effect |
|---|---|
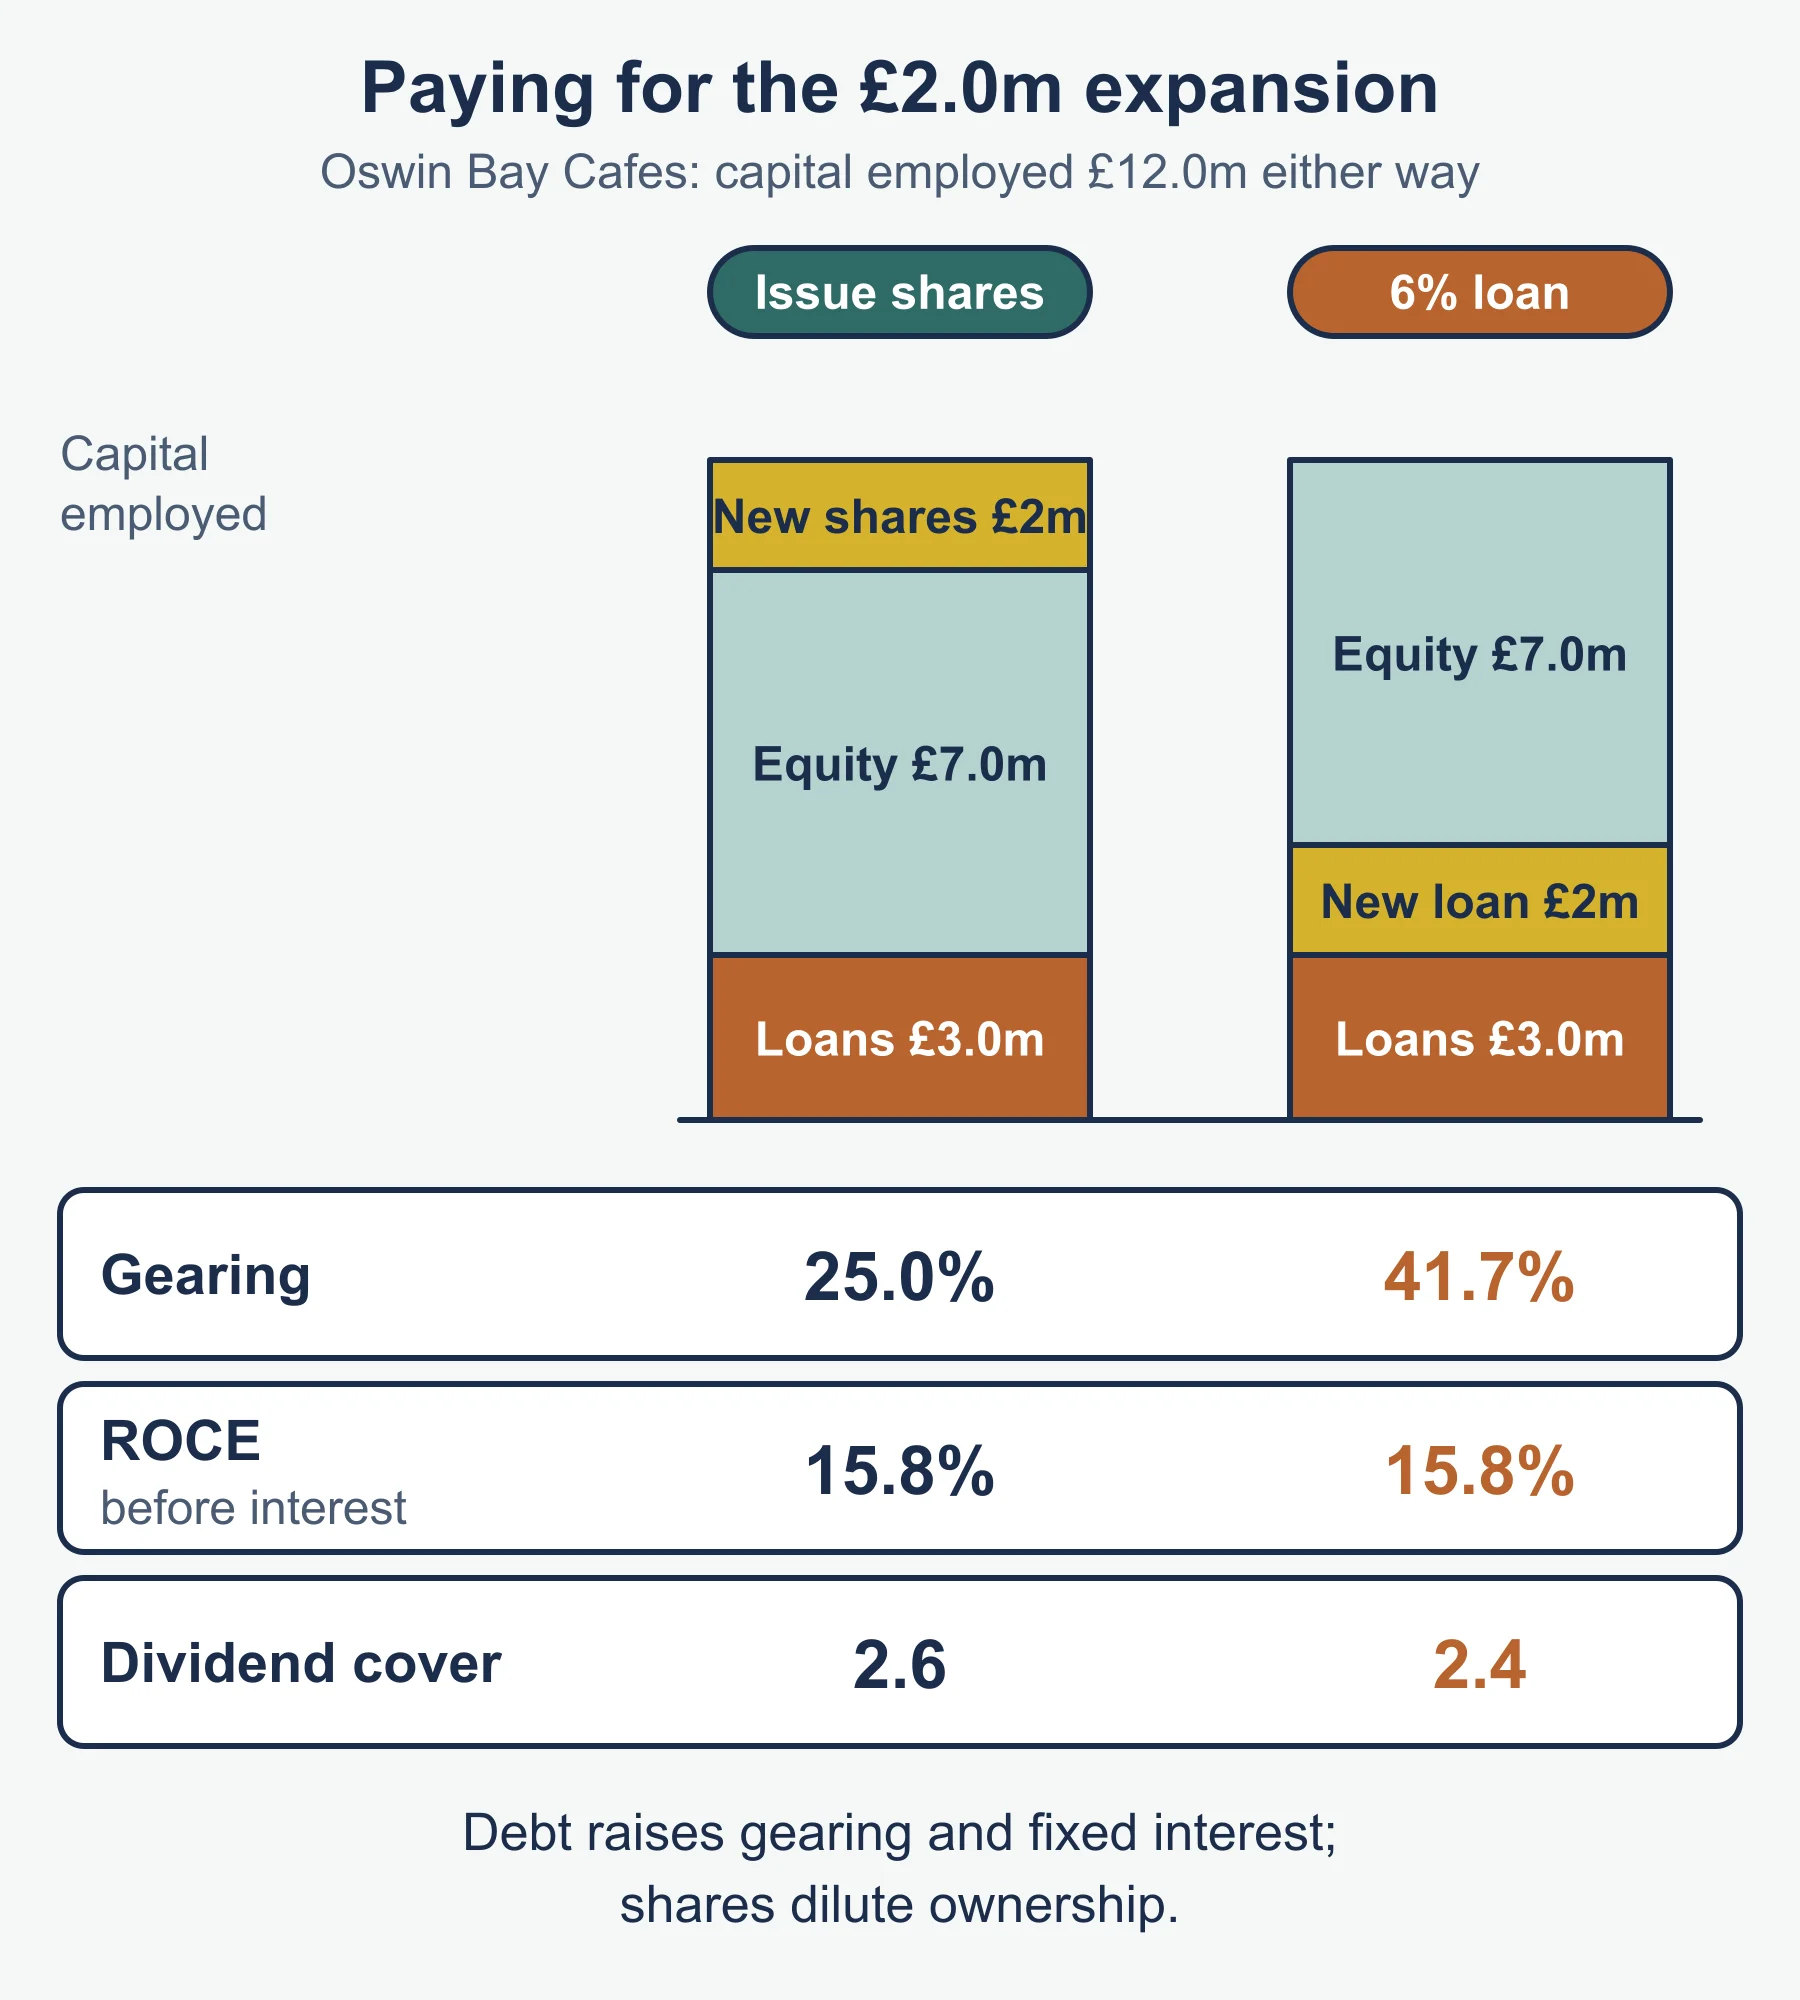
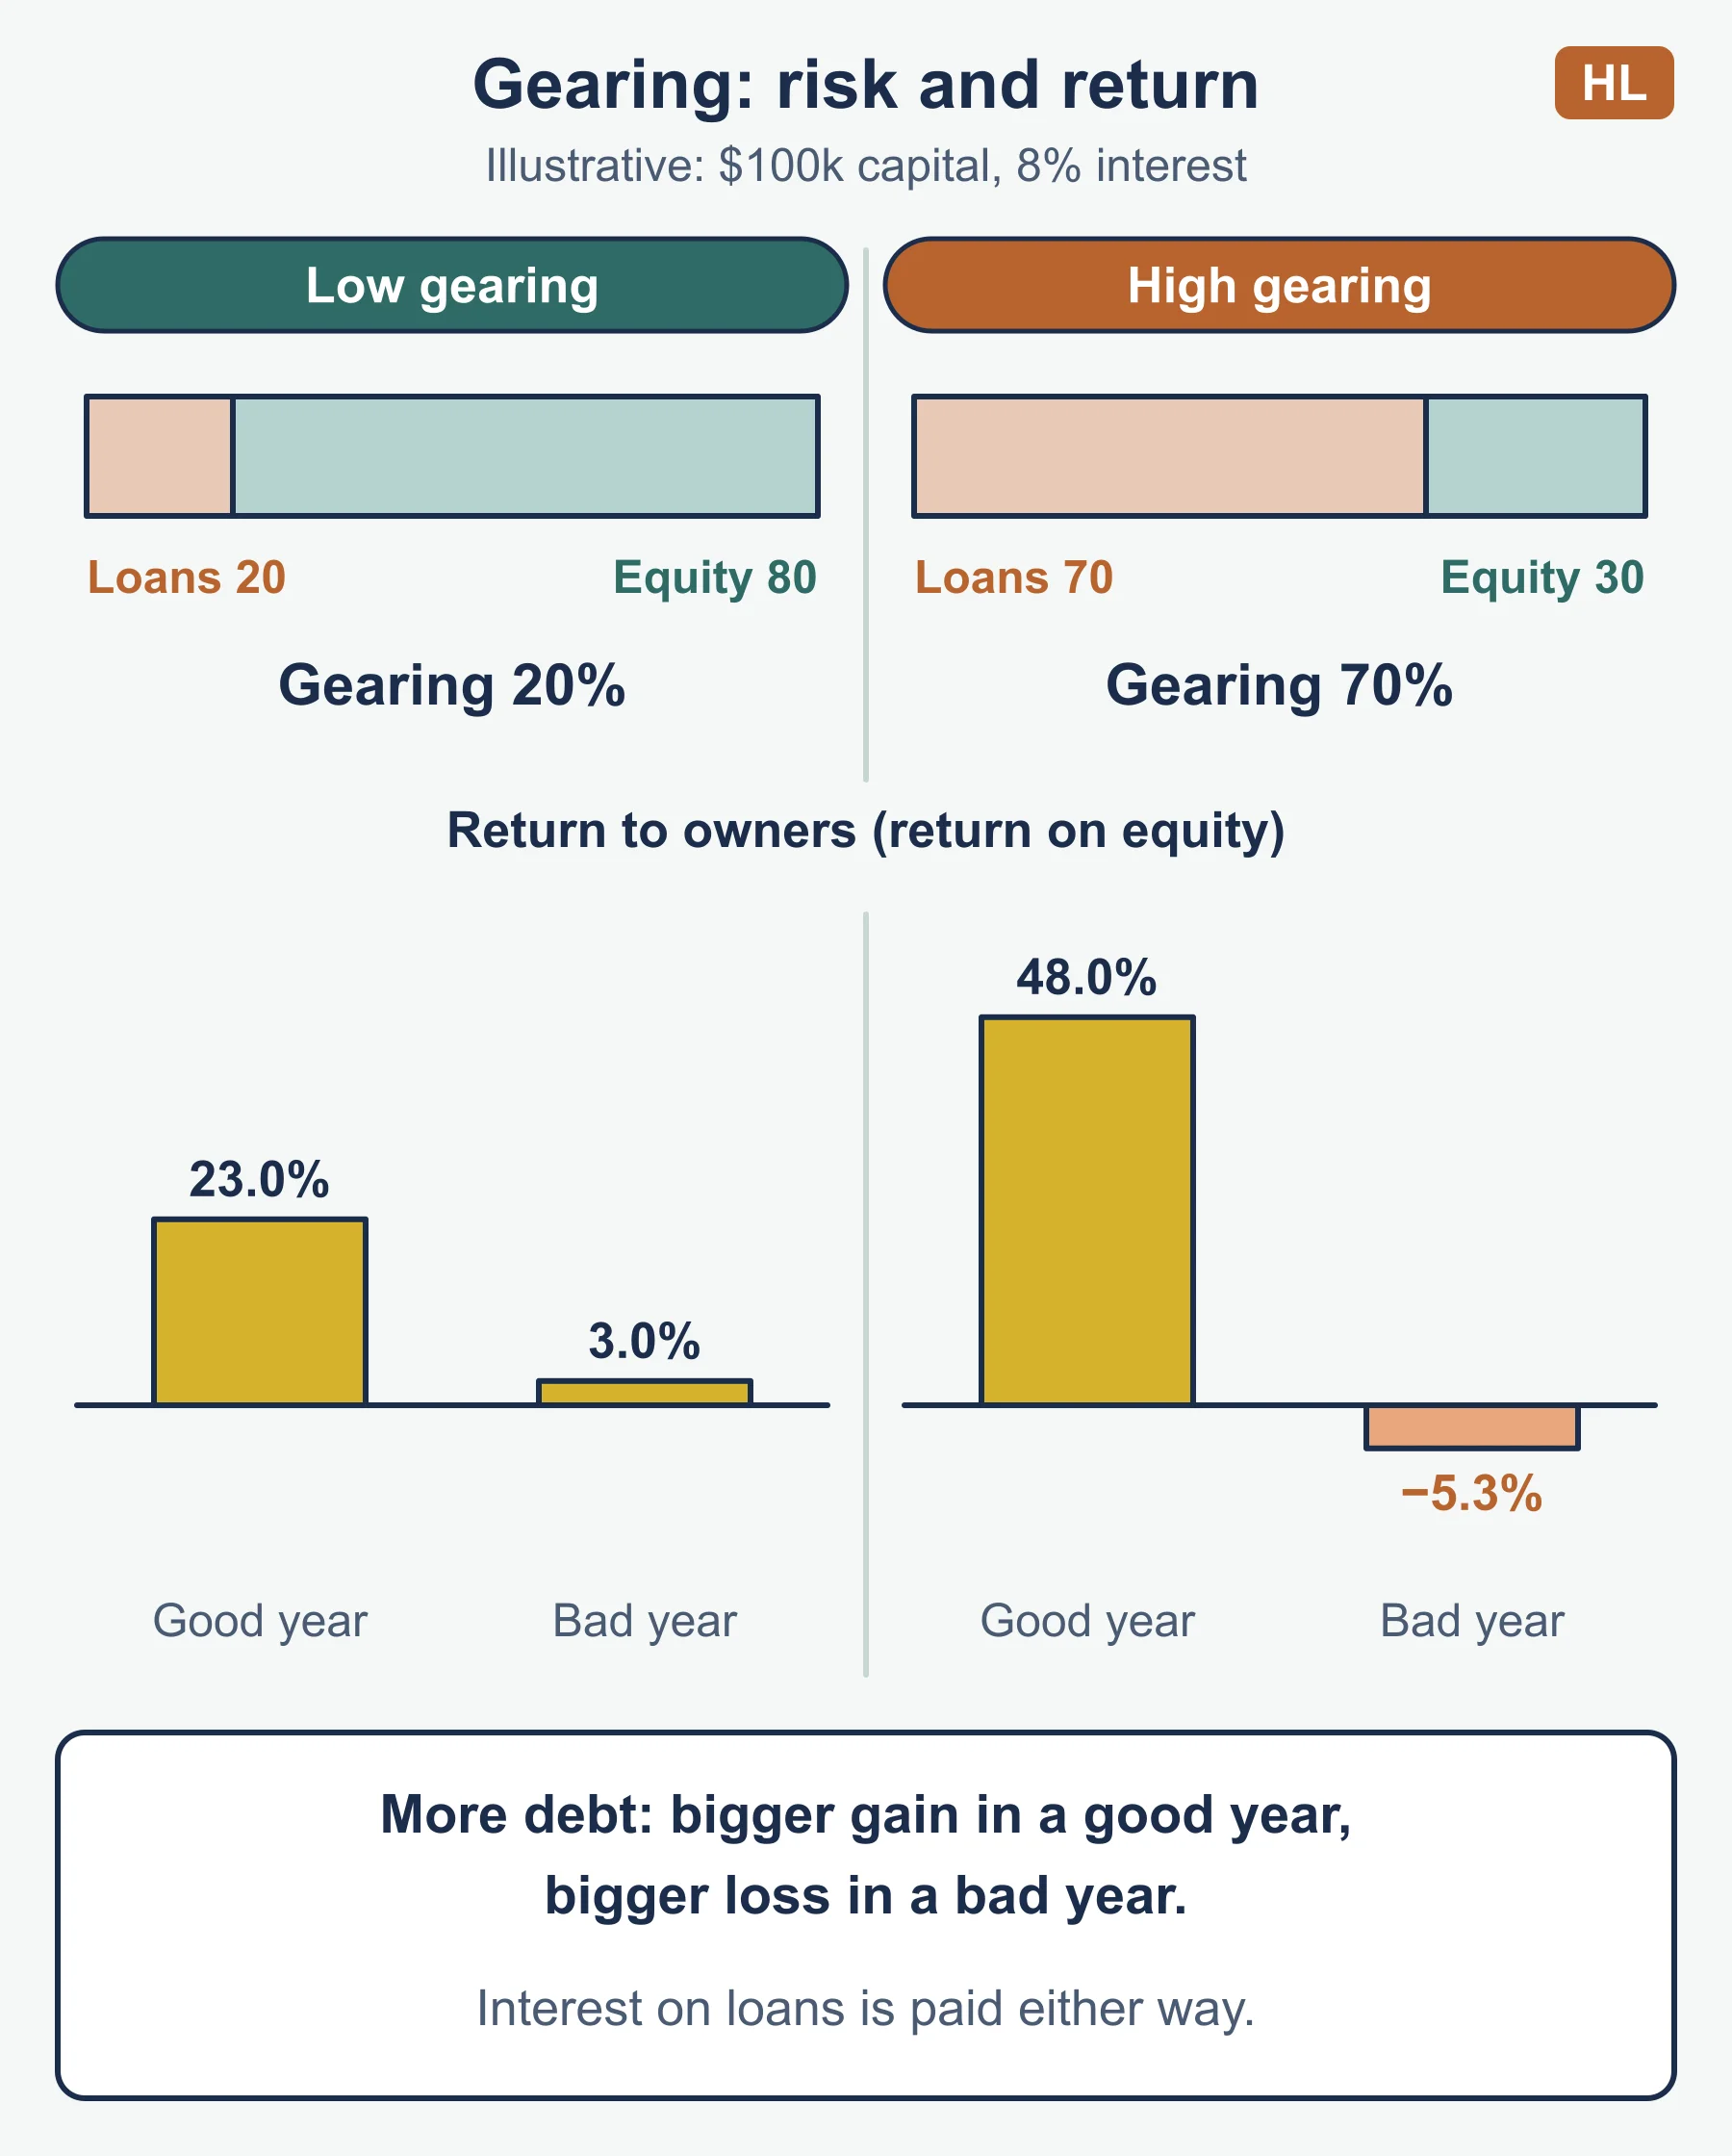
| Raise funds with debt | Gearing up; interest up; profit for the year and dividend cover down |
| Raise funds with new shares | Gearing down; ownership diluted; ROCE may fall if returns lag |
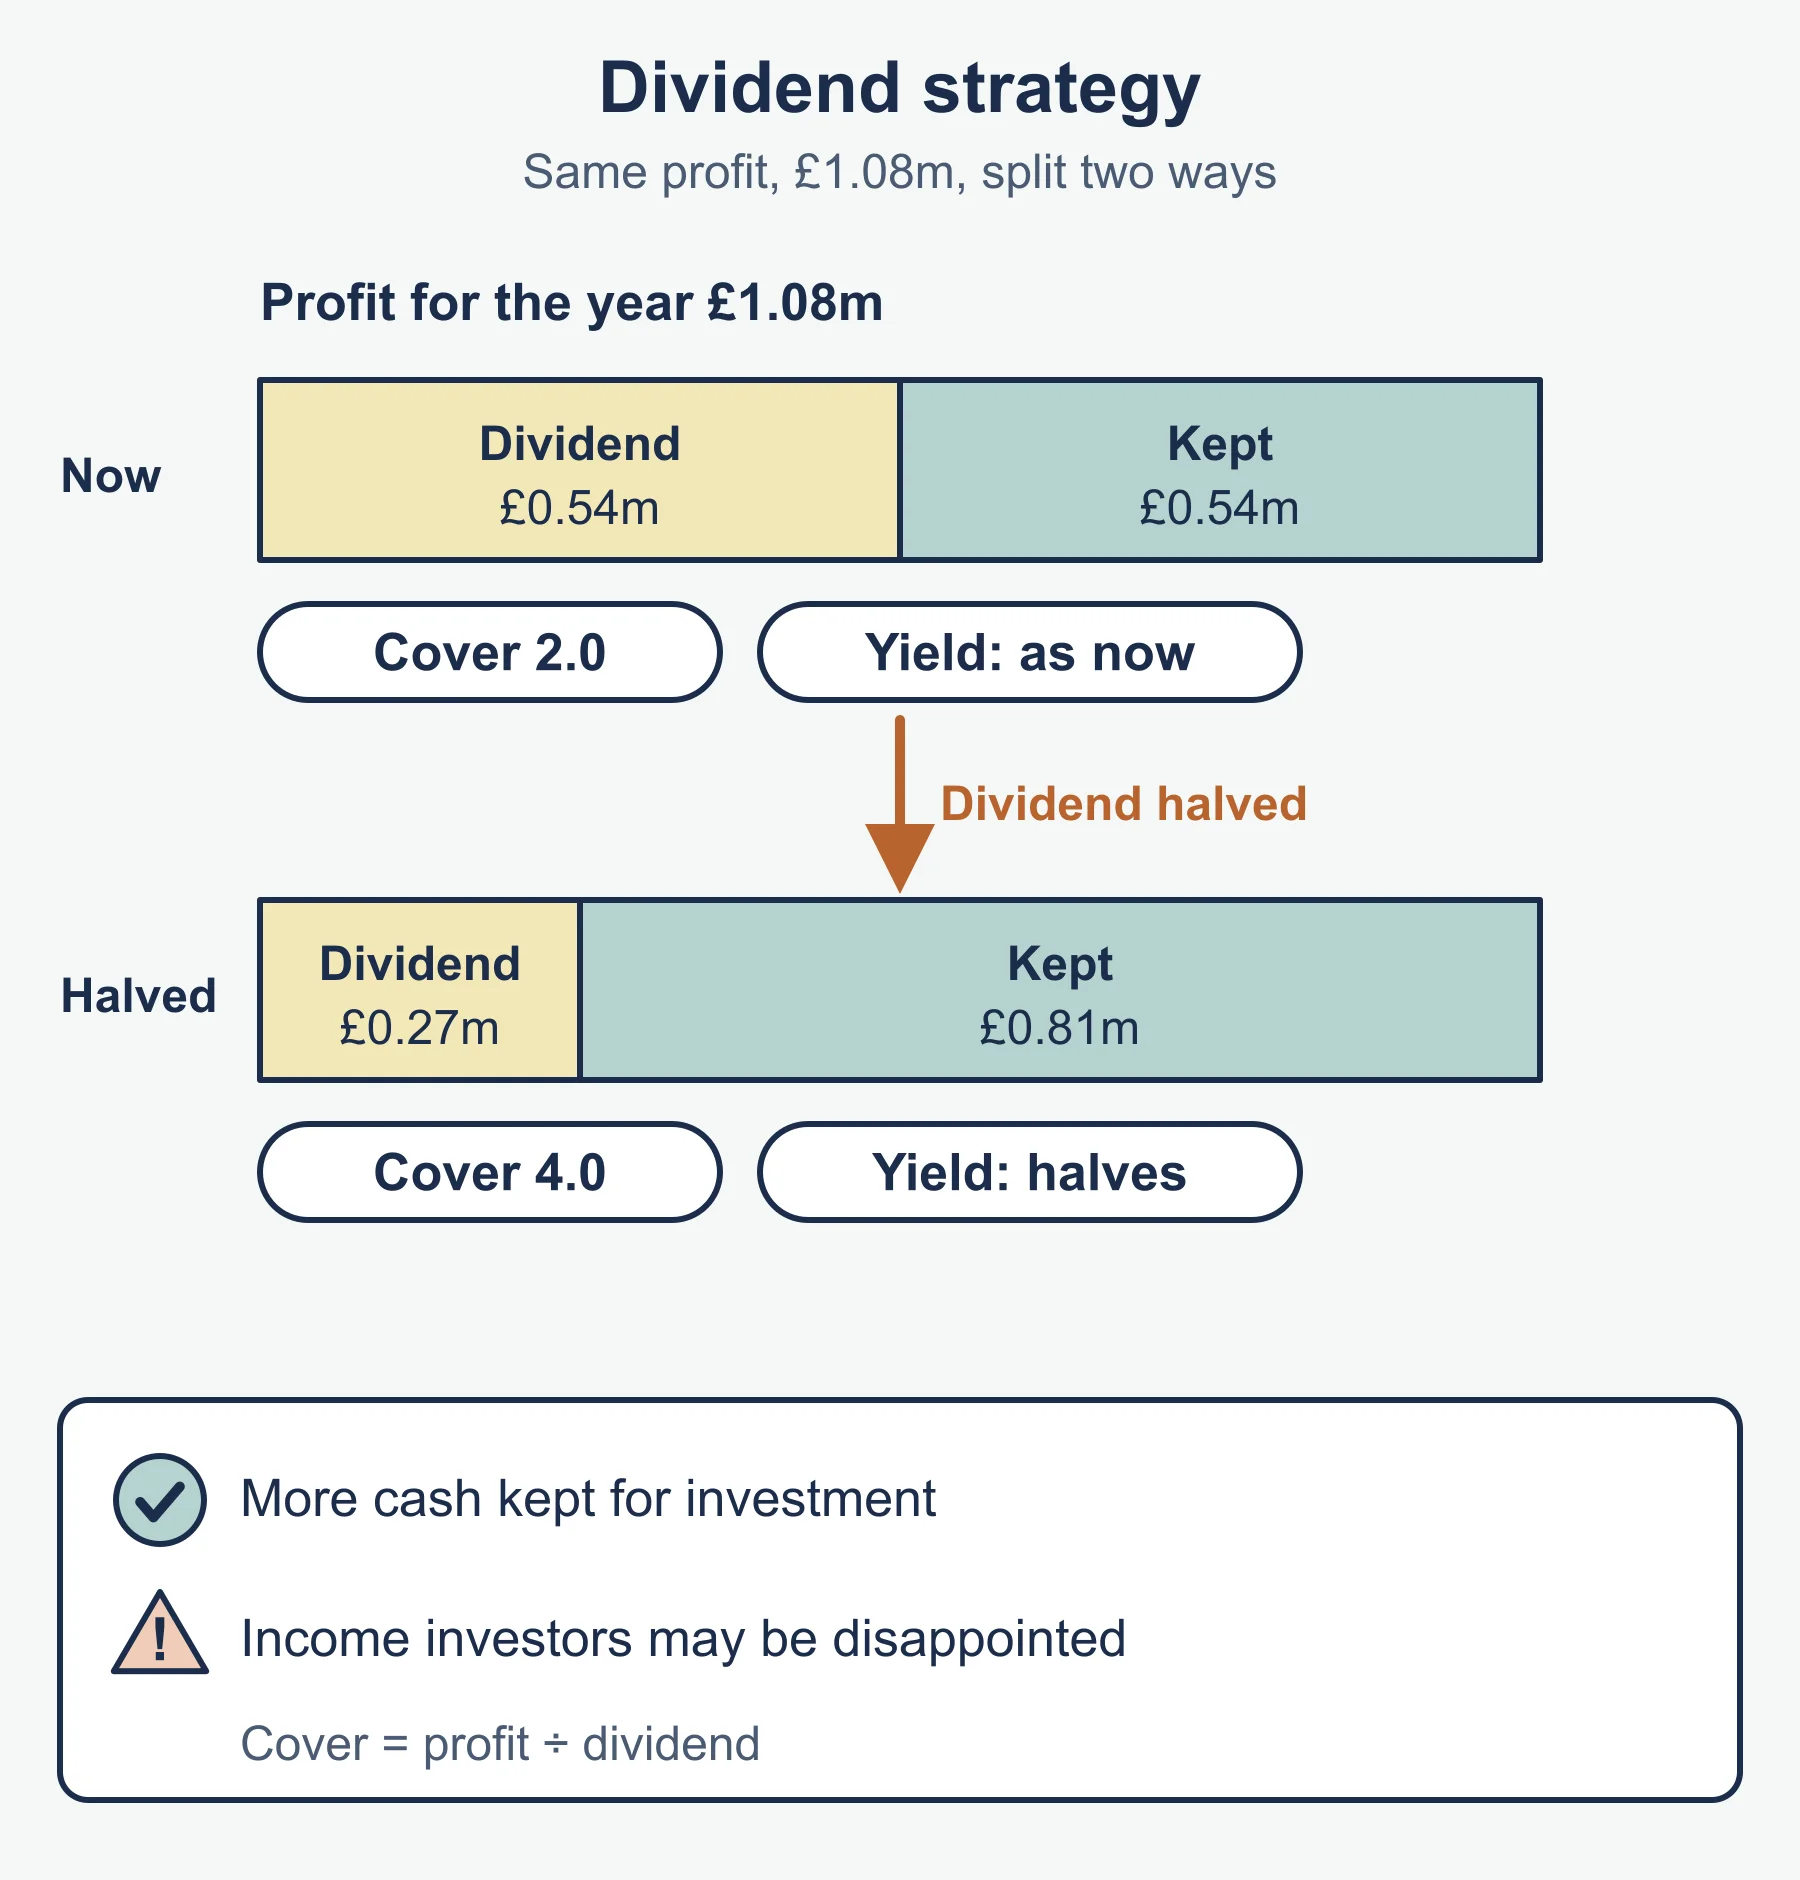
| Cut the dividend | Dividend cover up; dividend yield down; reserves rise |
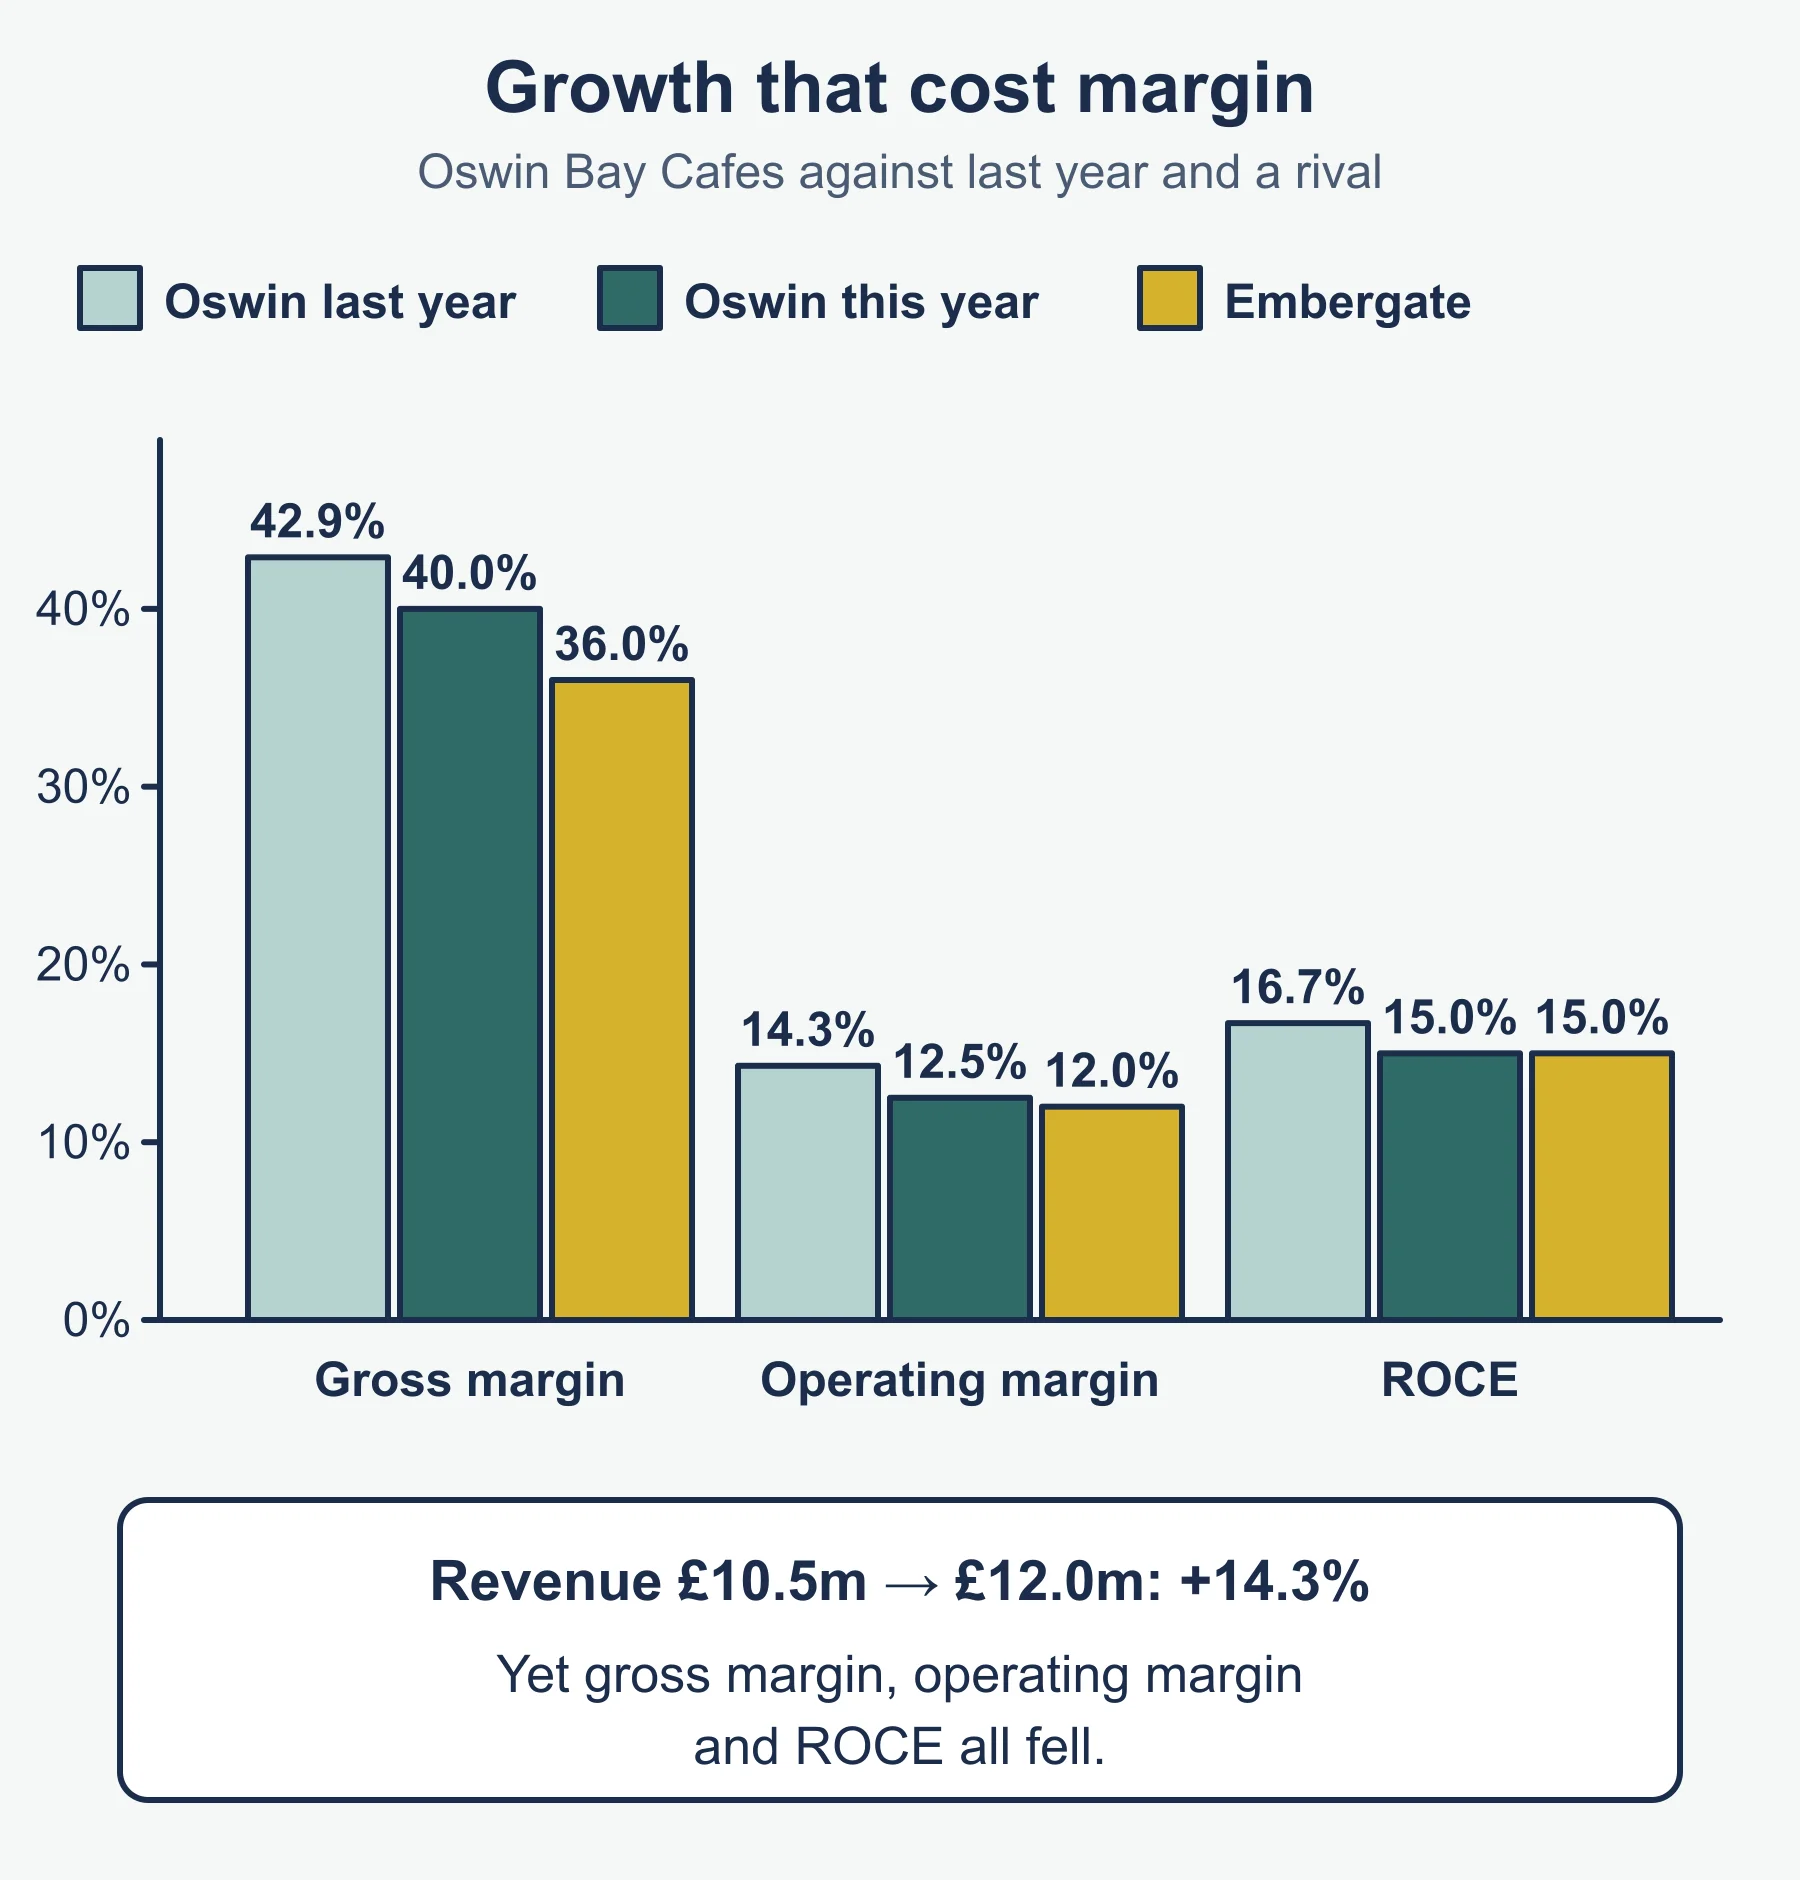
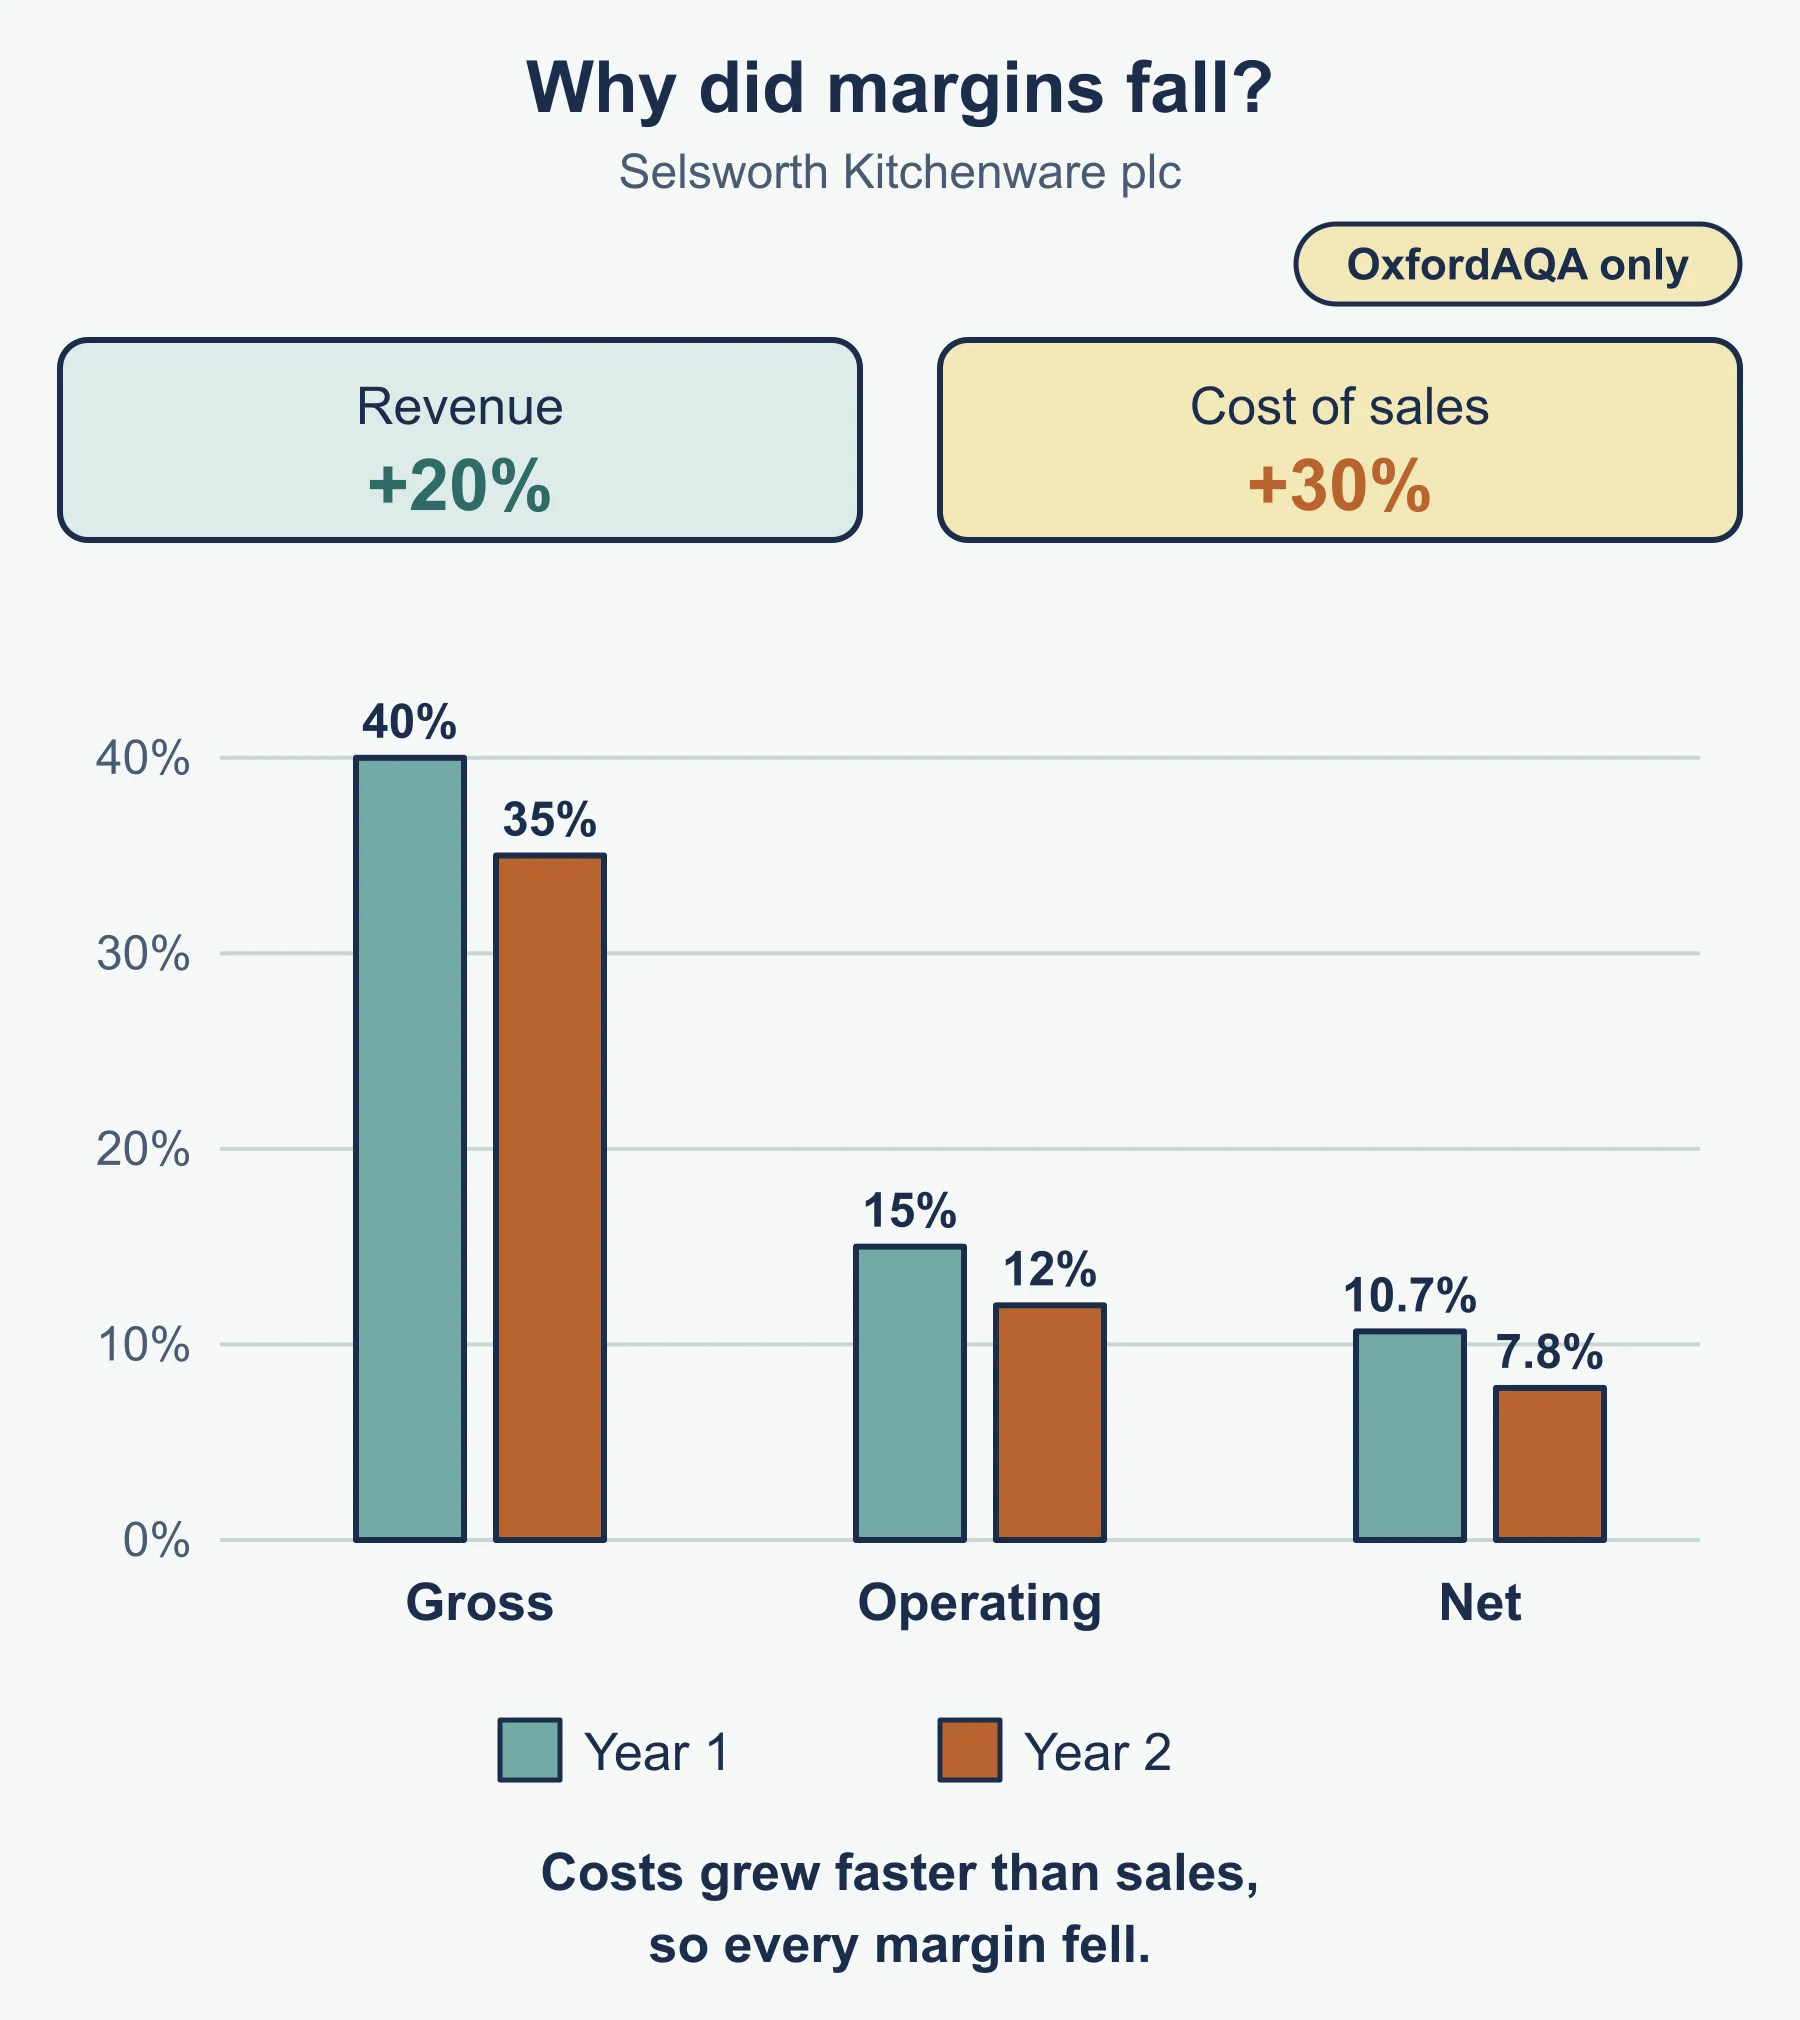
| Rapid growth | Inventory and receivables rise; liquidity and margins can fall at first |
| Cost cutting | Margins up |
| Price cuts | Margins down; inventory turnover may rise |
| Large capital spending | Capital employed up; ROCE down until returns arrive |
Compare ratios over time (trend) and with competitors. Ask why a ratio moved, then link it to a strategy.
Worked reminder: funding choice. Hobbsford (figures in the self-test below) borrows a further £1.0m for new tills, so non-current liabilities rise to £2.8m and capital employed to £7.0m. Gearing rises from 30% to 2.8 / 7.0 × 100 = 40%. If the project adds nothing to profit from operations in the first year, ROCE falls from 15% to 0.9 / 7.0 × 100 = 12.9%, and extra interest lowers profit for the year and so dividend cover. A comment must say whether the extra risk is justified by the expected return.
Limitations of accounts and ratios
Historical data, different accounting policies, window dressing, inflation, seasonality, differences between sectors and business models, no non-financial information, and a single ratio can mislead.
Must-know distinctions
- Payback measures speed; ARR measures average profitability; NPV measures value after the time value of money.
- ROCE uses profit from operations, so interest from the funding choice does not change it, but gearing and dividend cover do change.
- Dividend yield uses the market price. Dividend cover uses profit for the year.
- Liquidity (current and acid test) is short term. Gearing is long term.
Quick self-test
Hobbsford Stores has issued shares of £2.0m, reserves of £2.2m and non-current liabilities of £1.8m. Profit from operations is £0.9m, profit for the year is £0.72m and the annual dividend is £0.36m. Dividend per share is 9p, earnings per share 18p and the share price 150p. Current assets are £420,000, inventory £180,000 and current liabilities £300,000.
- Give two reasons a business appraises investments.
- Why is the initial cost not discounted in an NPV calculation?
- Calculate Hobbsford’s capital employed and gearing.
- Calculate Hobbsford’s ROCE.
- Calculate Hobbsford’s dividend cover.
- Calculate Hobbsford’s dividend yield and price/earnings ratio (1 d.p.).
- Calculate the acid test ratio.
- If Hobbsford halves its dividend, what happens to dividend cover and dividend yield?
- A project has a positive NPV but a long payback. Give one reason a manager might still reject it.
- Give two limitations of using ratios from published accounts.
Answers
- Any two: large and hard-to-reverse spending; competing projects; testing against objectives; showing forecast risk.
- It is paid now (Year 0), so its present value is its face value.
- Capital employed = 2.0 + 2.2 + 1.8 = £6.0m; gearing = 1.8 / 6.0 × 100 = 30%.
- 0.9 / 6.0 × 100 = 15%.
- 0.72 / 0.36 = 2.0.
- Yield = 9 / 150 × 100 = 6.0%; P/E = 150 / 18 = 8.3.
- (420,000 − 180,000) / 300,000 = 0.8.
- Cover doubles to 4.0 and yield halves to 3.0%.
- Examples: it needs cash back soon; the forecasts are uncertain; it conflicts with other objectives.
- Any two: historical; different accounting policies; window dressing; ignores non-financial factors; not comparable across sectors.
Where marks are usually lost
- Discounting the initial cost, or leaving the residual value out of NPV.
- Leaving payback as 2.75 when the question wants it in years and months.
- Using initial cost as average investment without saying so.
- Giving a calculation with no comment on what the number means for the decision.
- Calling a ratio “good” without a comparison, a trend or a criterion.
- Forgetting that ROCE excludes interest while profit for the year does not.
- Listing qualitative factors that do not link to the case.
- Stopping at the first method when the question asks you to evaluate or compare.
Frequently asked questions
What is the difference between payback, ARR and NPV? Payback measures how quickly a project’s cash inflows repay its cost, ARR measures average profitability as a percentage of average investment, and NPV measures the value of the project after allowing for the time value of money.
Why is the initial cost not discounted in NPV? The initial cost is paid now, in Year 0, so its present value is the same as its face value. Only future cash flows are multiplied by discount factors.
Why does ROCE stay the same whether a project is funded by debt or shares? ROCE uses profit from operations, which is before interest, so the funding choice does not change it. Gearing, profit for the year and dividend cover do change.
What happens to dividend cover and dividend yield if a company cuts its dividend? Dividend cover rises, because the same profit covers a smaller dividend. Dividend yield falls, because shareholders receive less per share at the same market price.
Official syllabus
Cambridge International AS & A Level Business 9609 syllabus for examination in 2026, 2027 and 2028, published by Cambridge University Press & Assessment, sections 10.3 and 10.4.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
A Level Business: Finance and Accounting (A Level) — Practice Questions (Cambridge 9609)
Worked practice questions on ARR, payback, net present value, efficiency ratios and investor ratios for Cambridge International AS & A Level Business 9609.
Business · Cambridge · A Level
Try questions -
Study guides
A Level Business: Business finance and Sources of finance (Cambridge 9609)
Study guide to 5.1 Business finance and 5.2 Sources of finance in Cambridge AS & A Level Business 9609: cash, working capital and choosing finance.
Business · Cambridge · AS Level
Read guide -
Practice questions
A Level Business: Business finance and Sources of finance (Cambridge 9609) – Practice Questions
Original practice questions with worked answers on 5.1 Business finance and 5.2 Sources of finance for Cambridge AS & A Level Business 9609.
Business · Cambridge · AS Level
Try questions
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business A LEVEL?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Business teachers at Marlbridge

