
Revision Notes
Edexcel International A Level Accounting: The trial balance and correction of errors (YAC11) – Revision Notes
Condensed Edexcel IAL Accounting revision notes on the trial balance, error types, correcting journals, suspense account and revised profit.
- Subject
- Accounting
- Level
- AS LEVEL
- Topic
- Control procedures
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Pearson Edexcel A Level Accounting (YAC11), 2015-onwards. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel A Level Accounting.
Syllabus points this page covers
YAC11 (AS Level)
- 1.2.1-1.2.2 Trial balance
- 1.2.5-1.2.9 Correction of errors
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Accounting (YAC11).
Condensed notes for outcomes 1.2.1, 1.2.2 and 1.2.5 to 1.2.9 of Unit 1 in the Pearson Edexcel International Advanced Subsidiary/Advanced Level in Accounting (XAC11/YAC11) specification, Issue 2 (September 2018). All International AS content. Full explanations are in the study guide; test yourself with the practice questions. Amounts are in dollars.
Links: Edexcel A-Level Accounting hub, printable checklist, free diagnostics, and the earlier control accounts guide for building control accounts (1.2.3 and 1.2.4).
Key definitions
| Term | Meaning |
|---|---|
| Trial balance | List of all ledger balances at one date in a debit and a credit column |
| Suspense account | Temporary account holding a trial balance difference until the errors are found |
| Compensating errors | Two or more errors whose effects cancel in the totals |
| Journal (correcting) | Debit, credit, amount and narrative that corrects an earlier posting |
| Statement of revised profit | Original profit adjusted for each correction that affects income or expenses |
1.2.1 Method: preparing a trial balance
- Balance every ledger account.
- Put each brought-down balance in the column of its side.
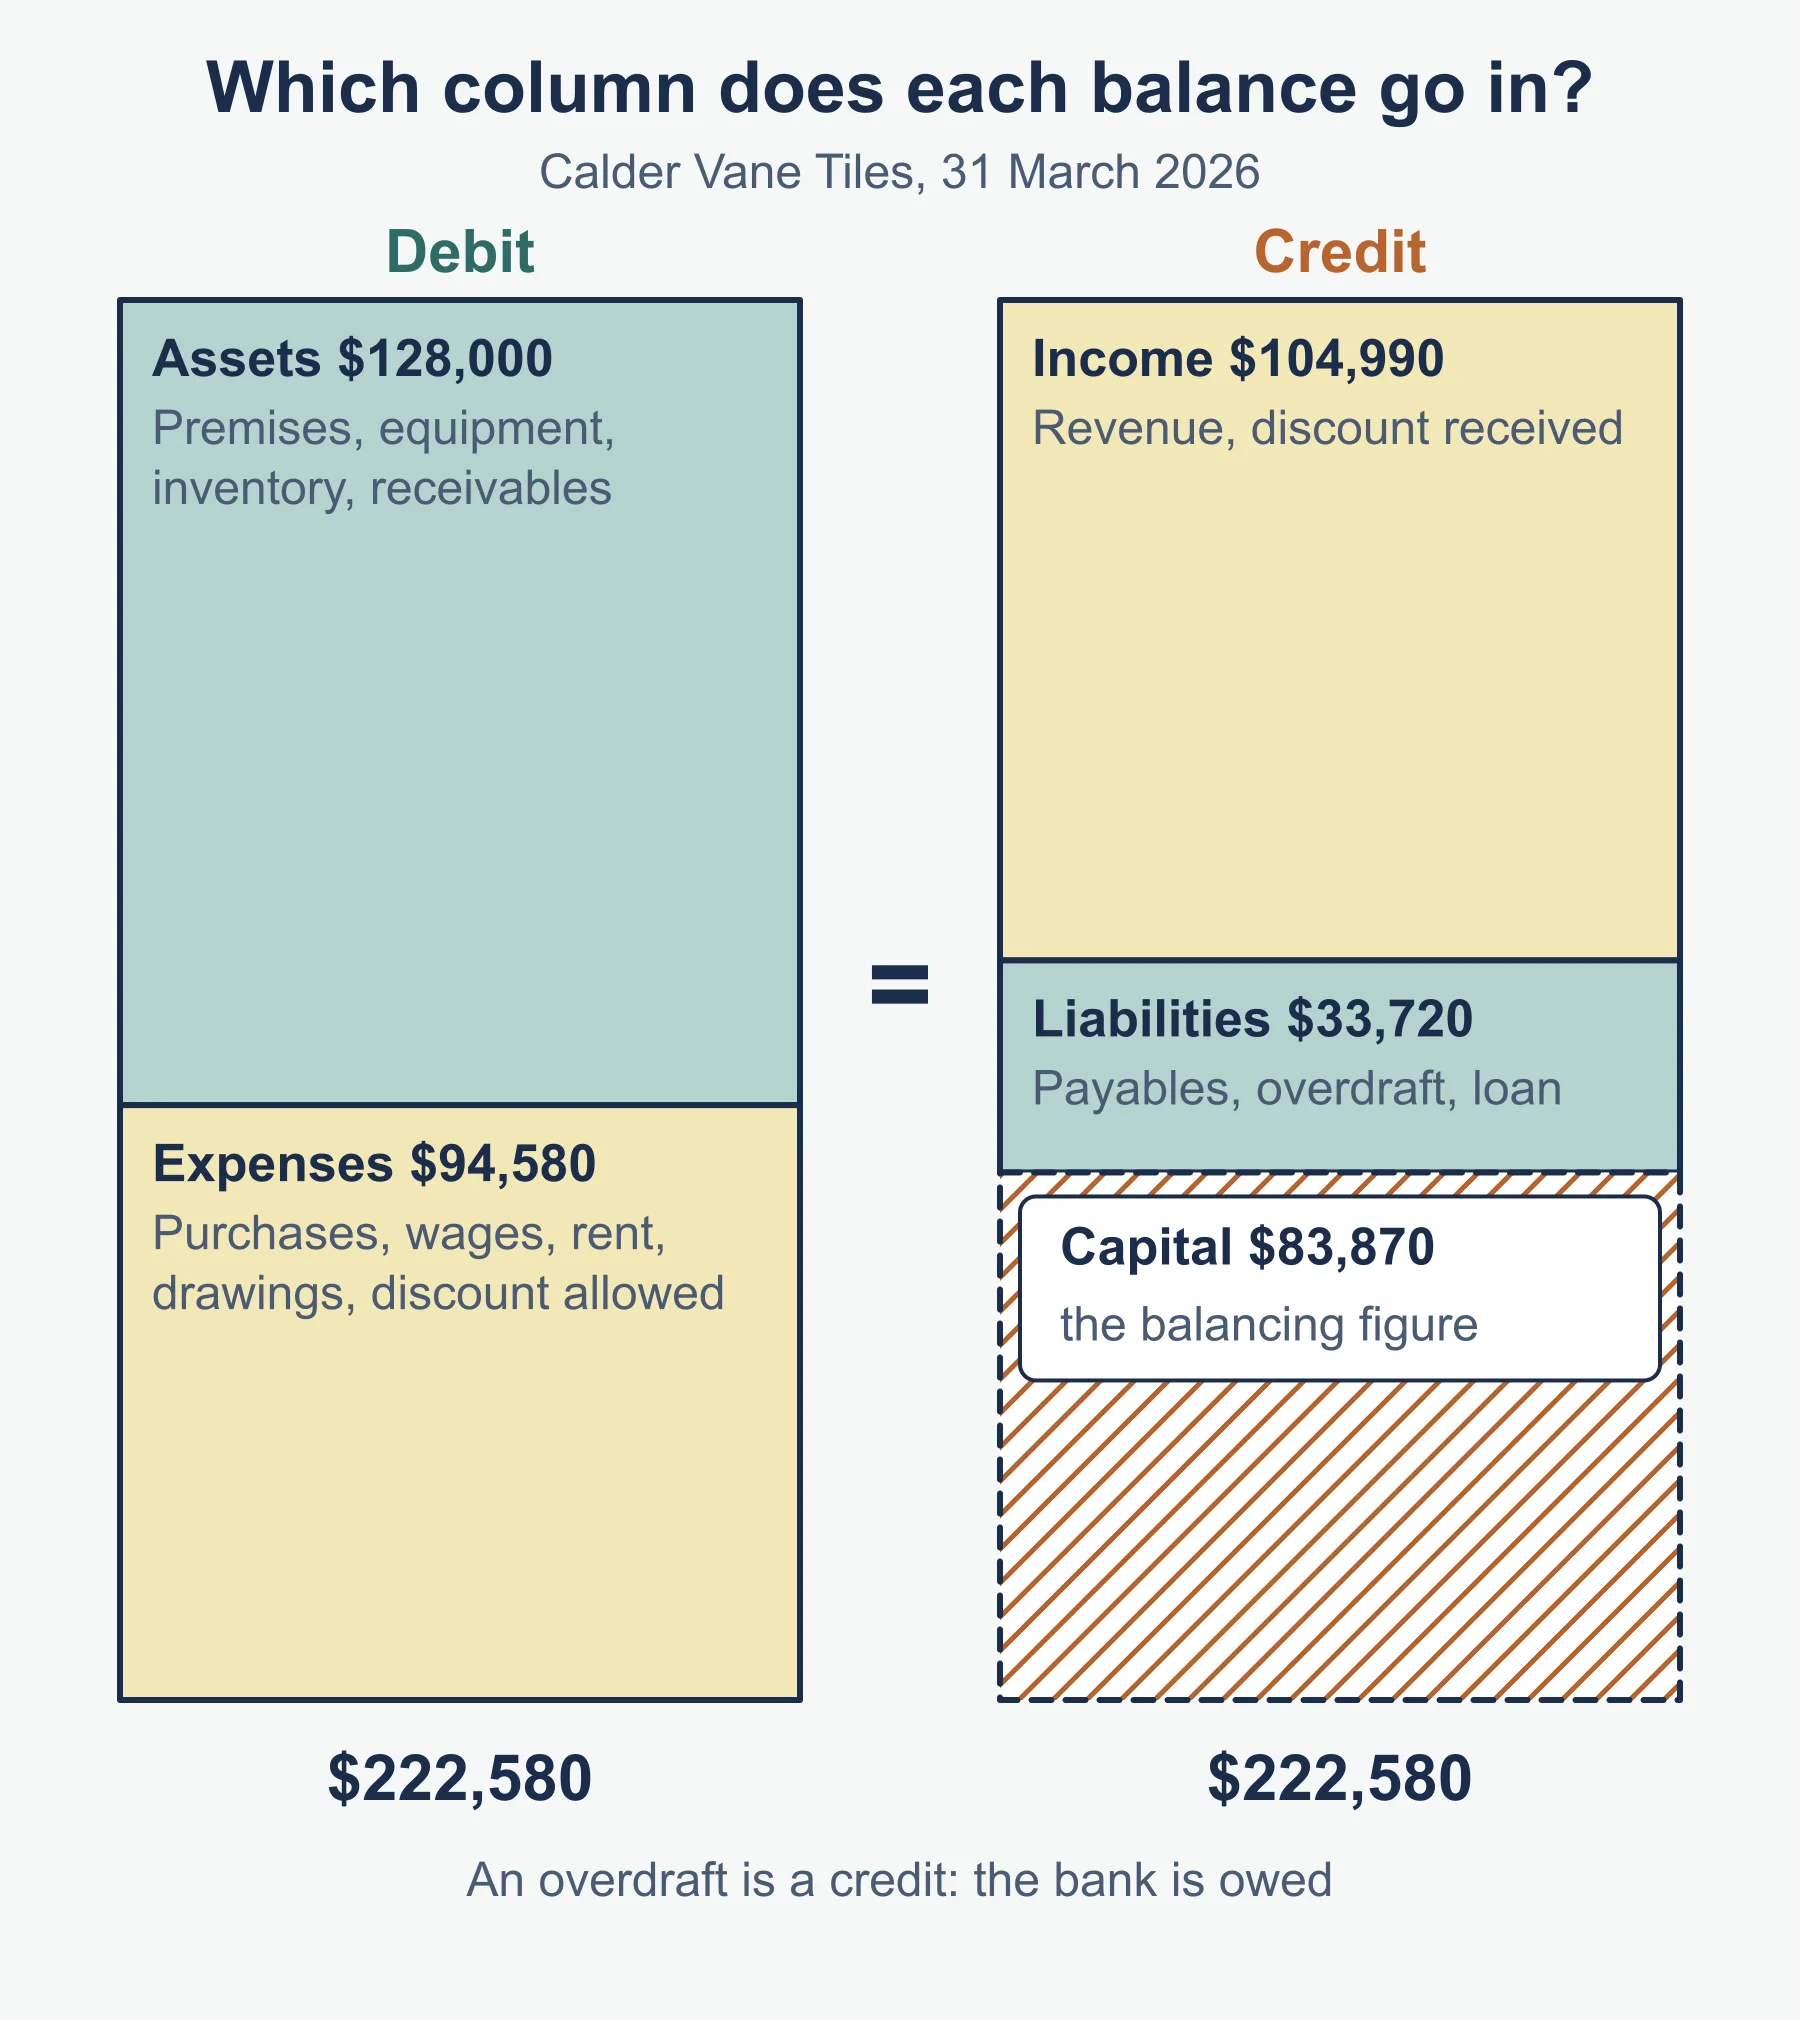
- Debit column: assets, expenses, purchases, drawings, discount allowed.
- Credit column: liabilities (including a bank overdraft), capital, revenue, discount received.
- Add both columns; the totals should agree.
Reminder: Oldacre Cycles’ trade payables account has credits of 18,900 and debits of 14,250. The balance is 4,650, shown on the debit side as carried down and brought down on the credit side. It goes in the credit column.
1.2.2 Limitations
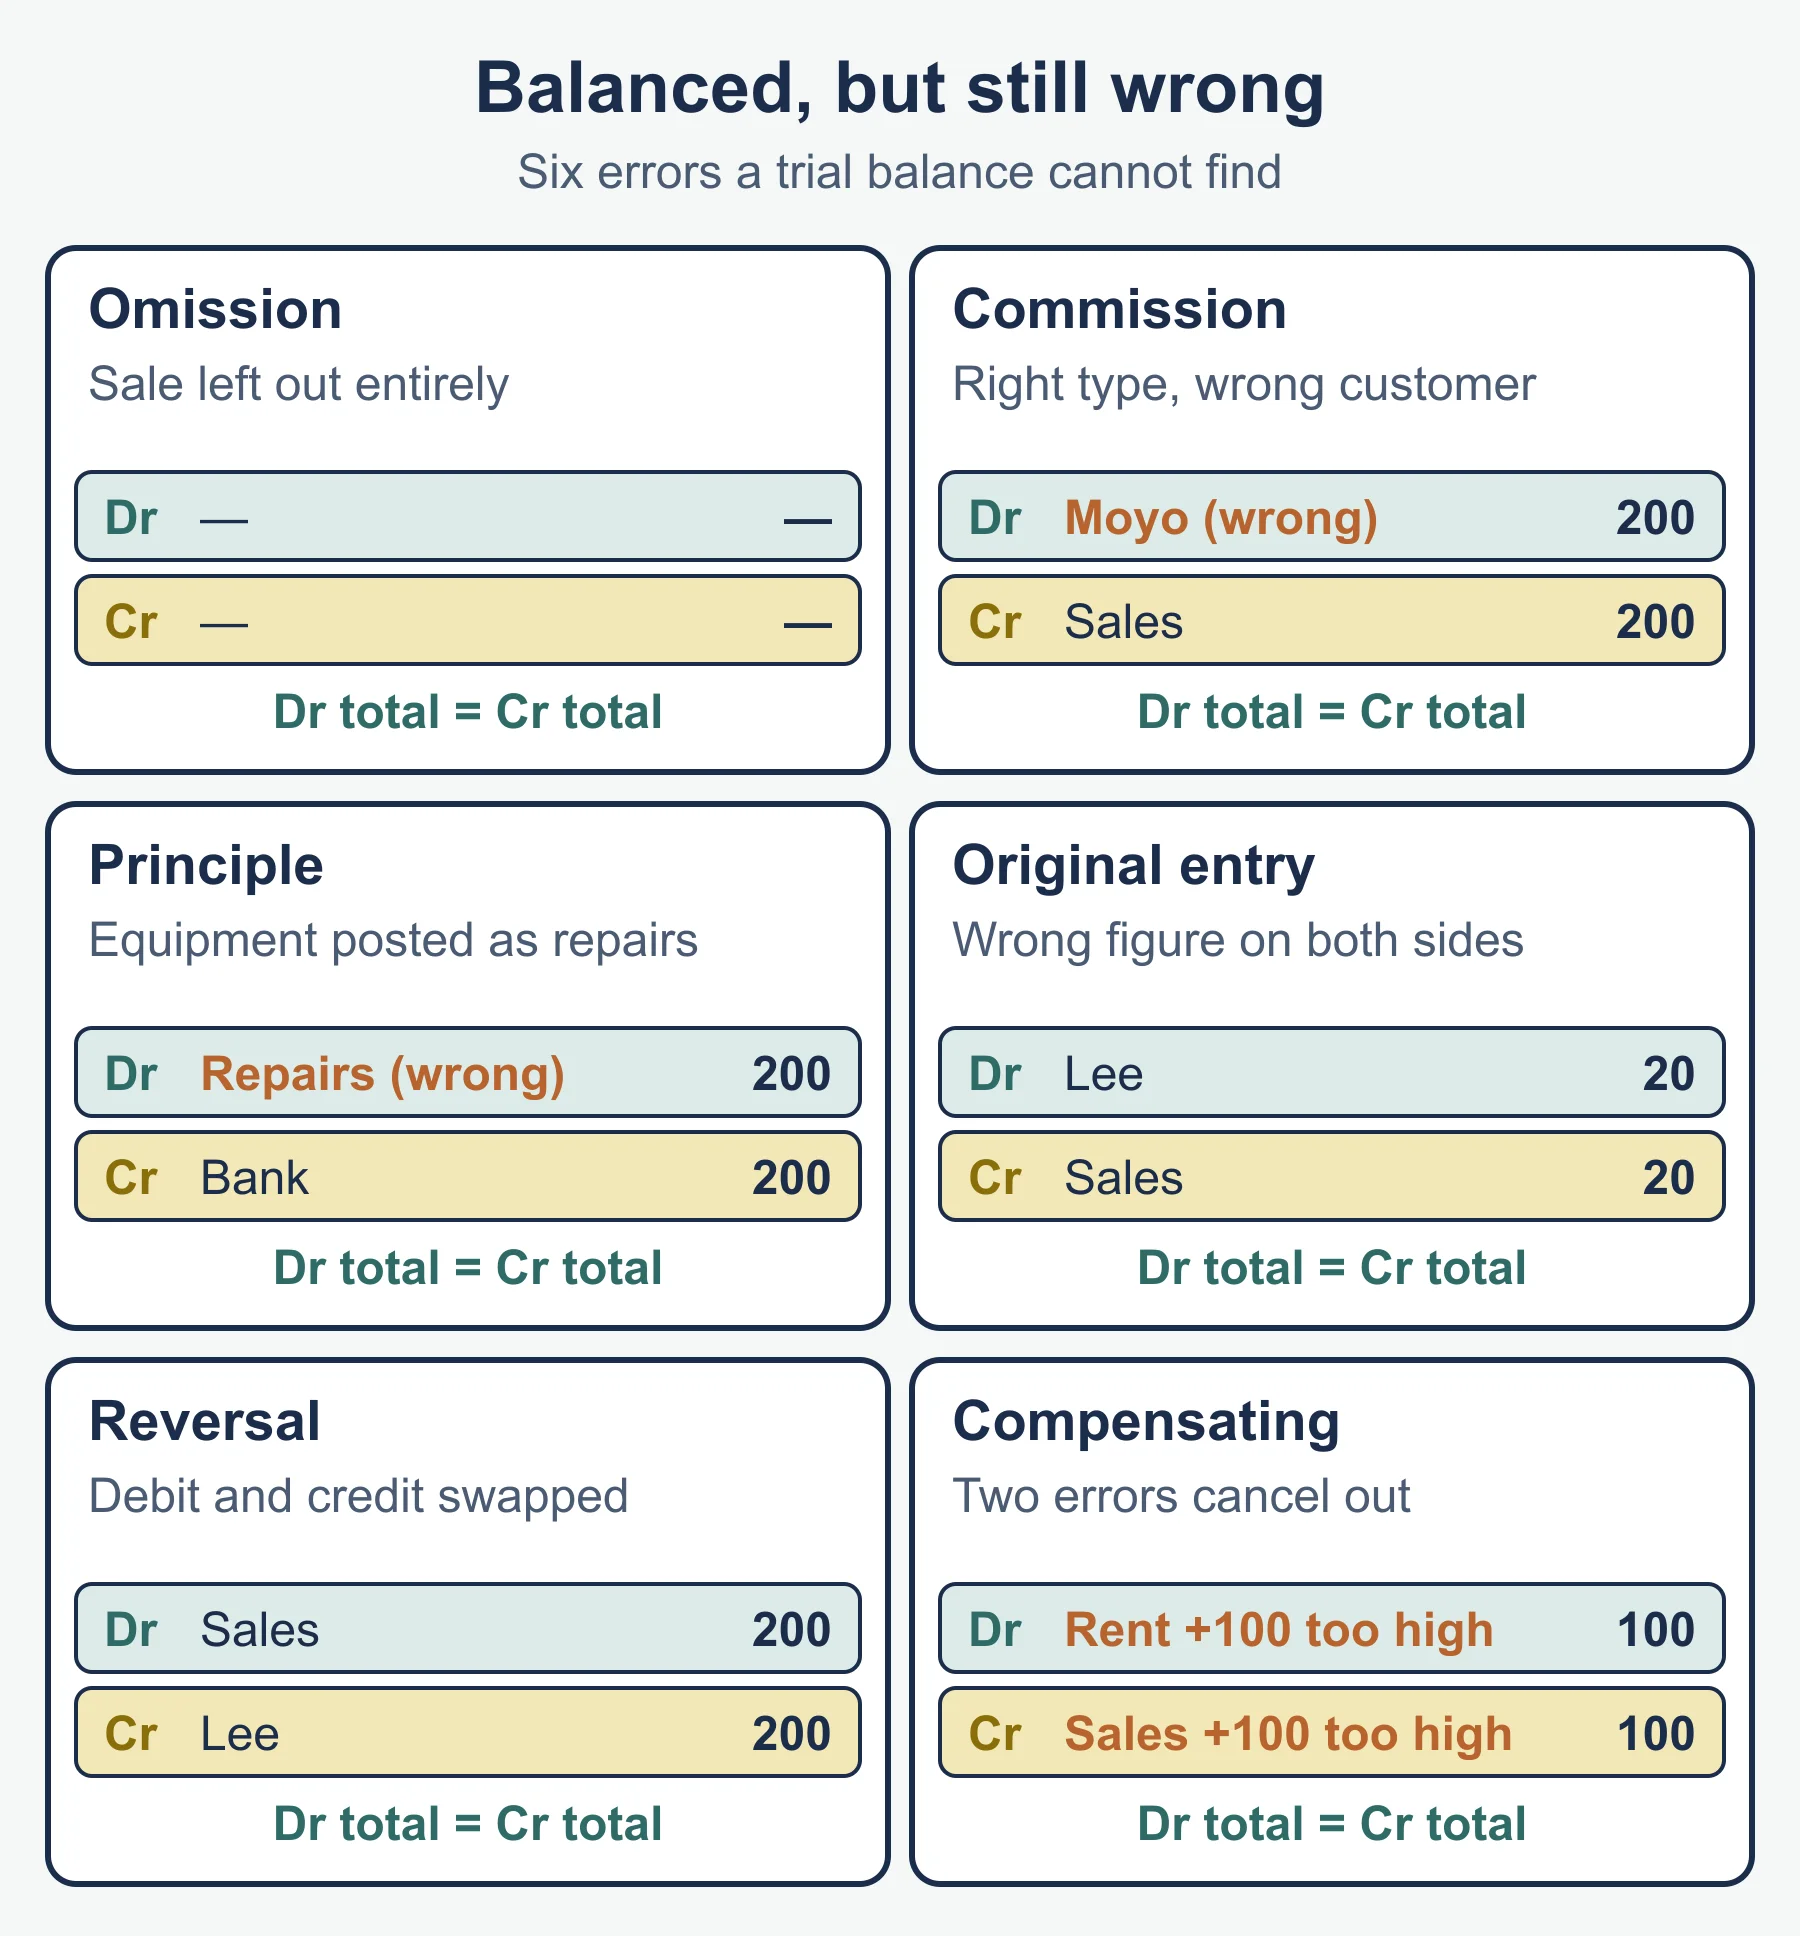
An agreeing trial balance does not prove the books are right. It misses:
- omission of a whole transaction
- posting to the wrong account of the right type
- posting to the wrong type of account
- the same wrong figure on both sides
- debit and credit swapped
- errors that cancel (compensating)
It also does not give profit or the financial position.
1.2.5 Which errors affect the trial balance
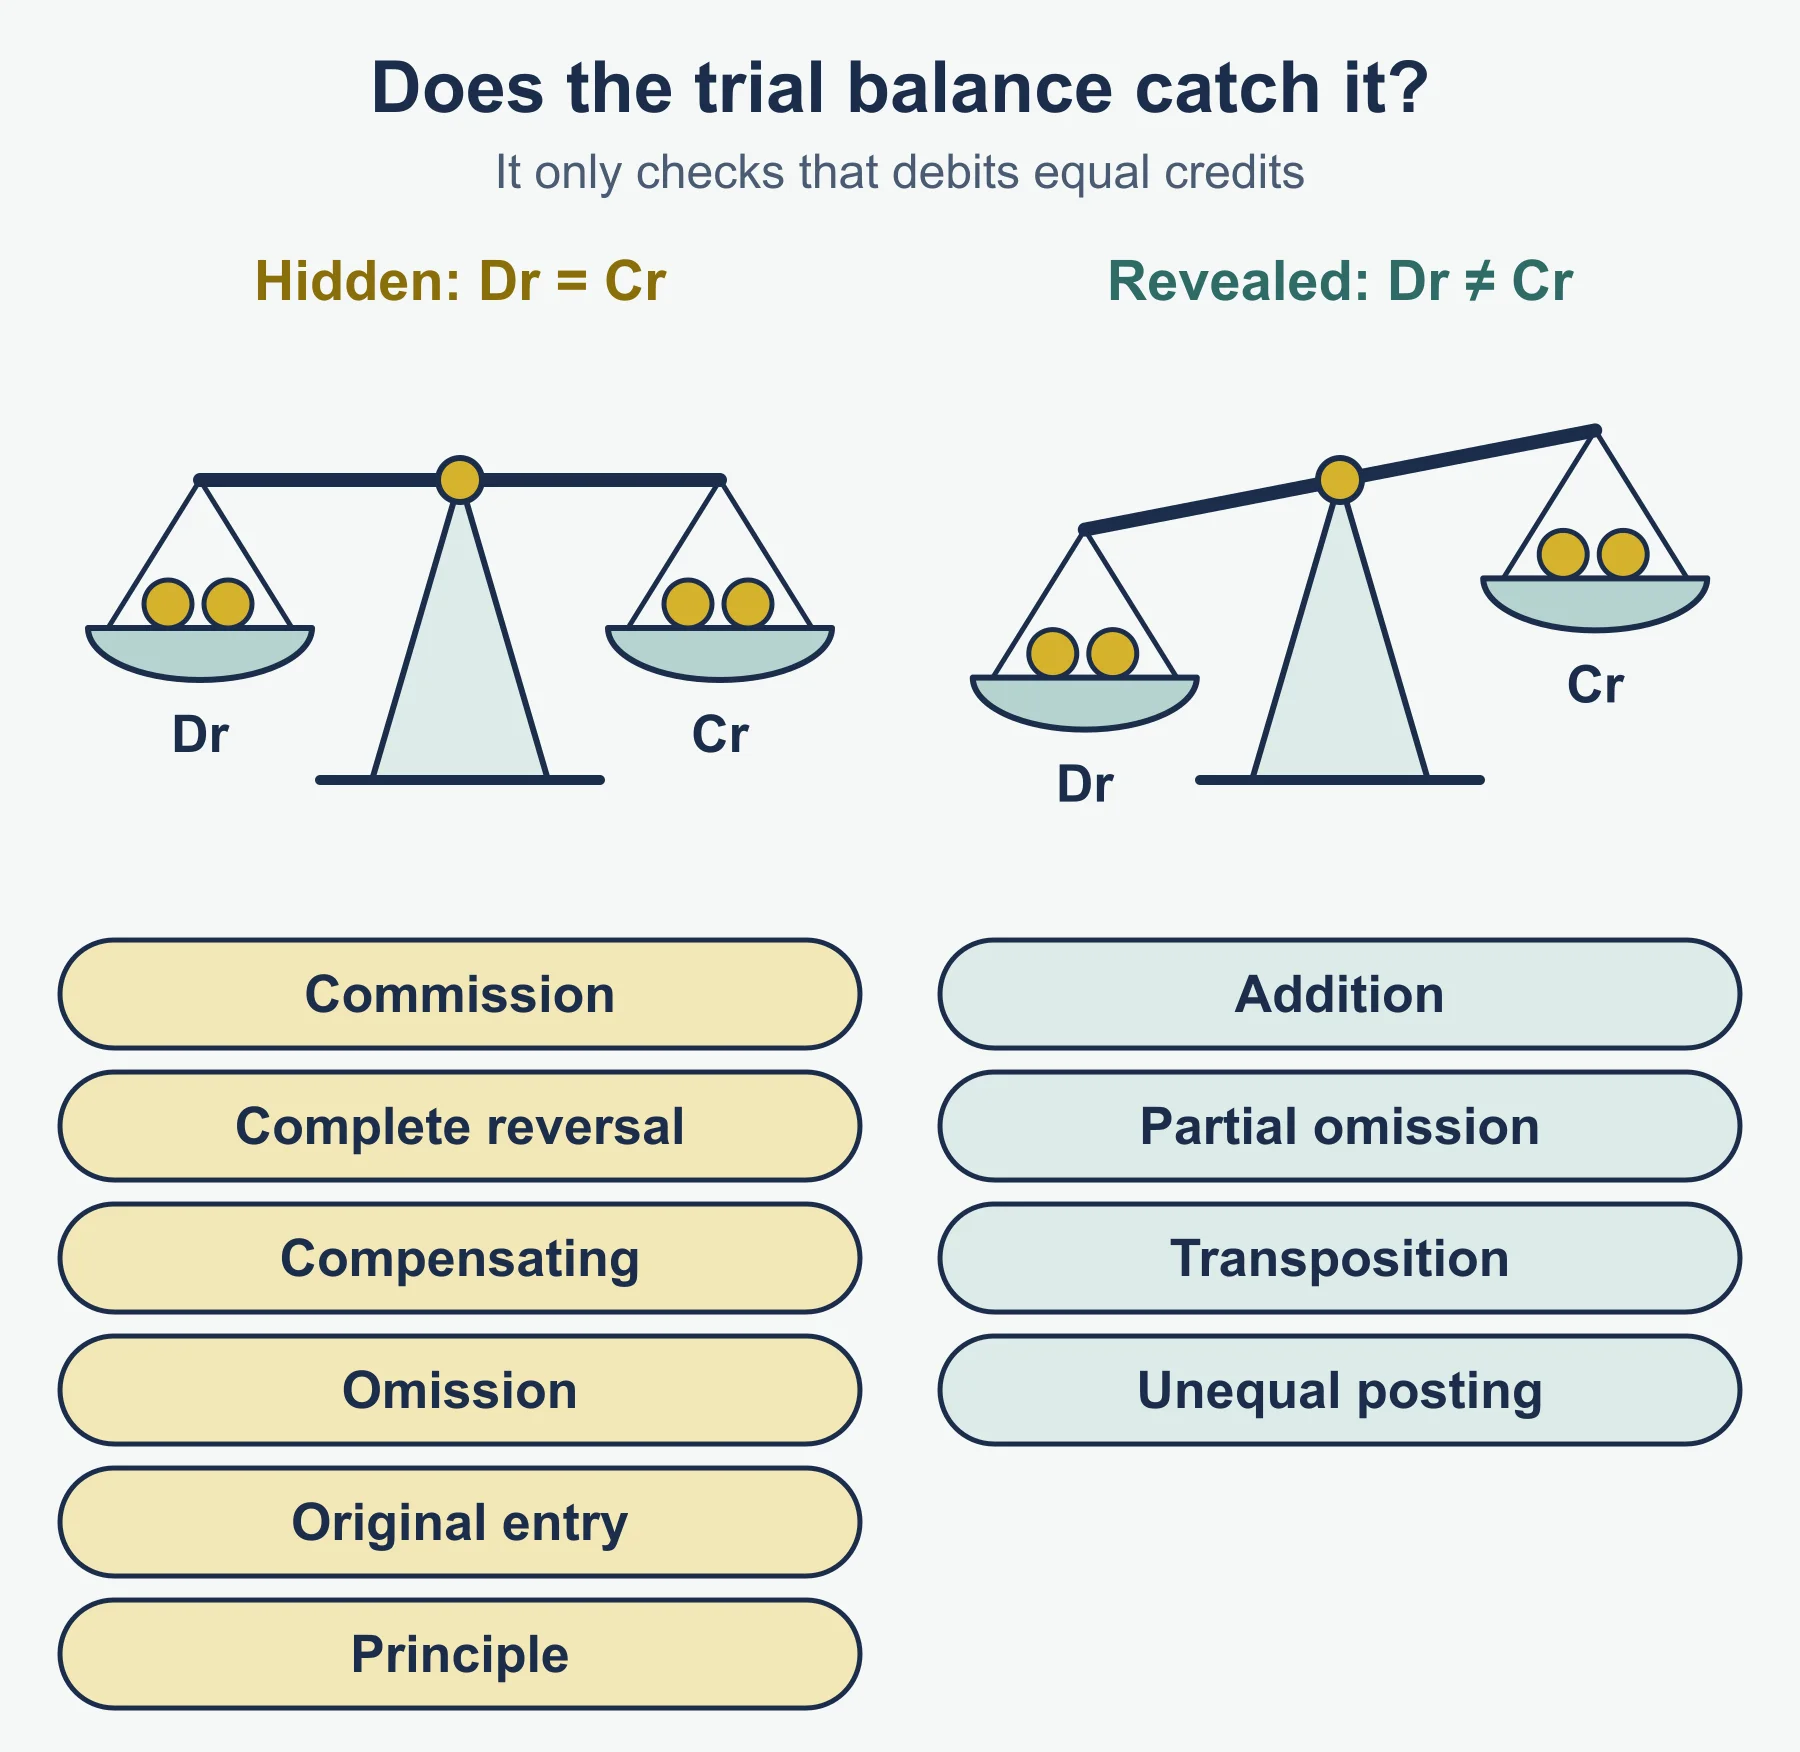
| Trial balance still agrees | Trial balance disagrees |
|---|---|
| Omission | One-sided entry |
| Commission | Different amounts on each side |
| Principle | Transposition on one side |
| Original entry | Casting (addition) error |
| Complete reversal | Balance left out or in the wrong column |
| Compensating |
Memory aid: if both sides of the entry went somewhere for the same amount, the totals agree. The specification does not name the types, so describe each error in words as well as naming it.
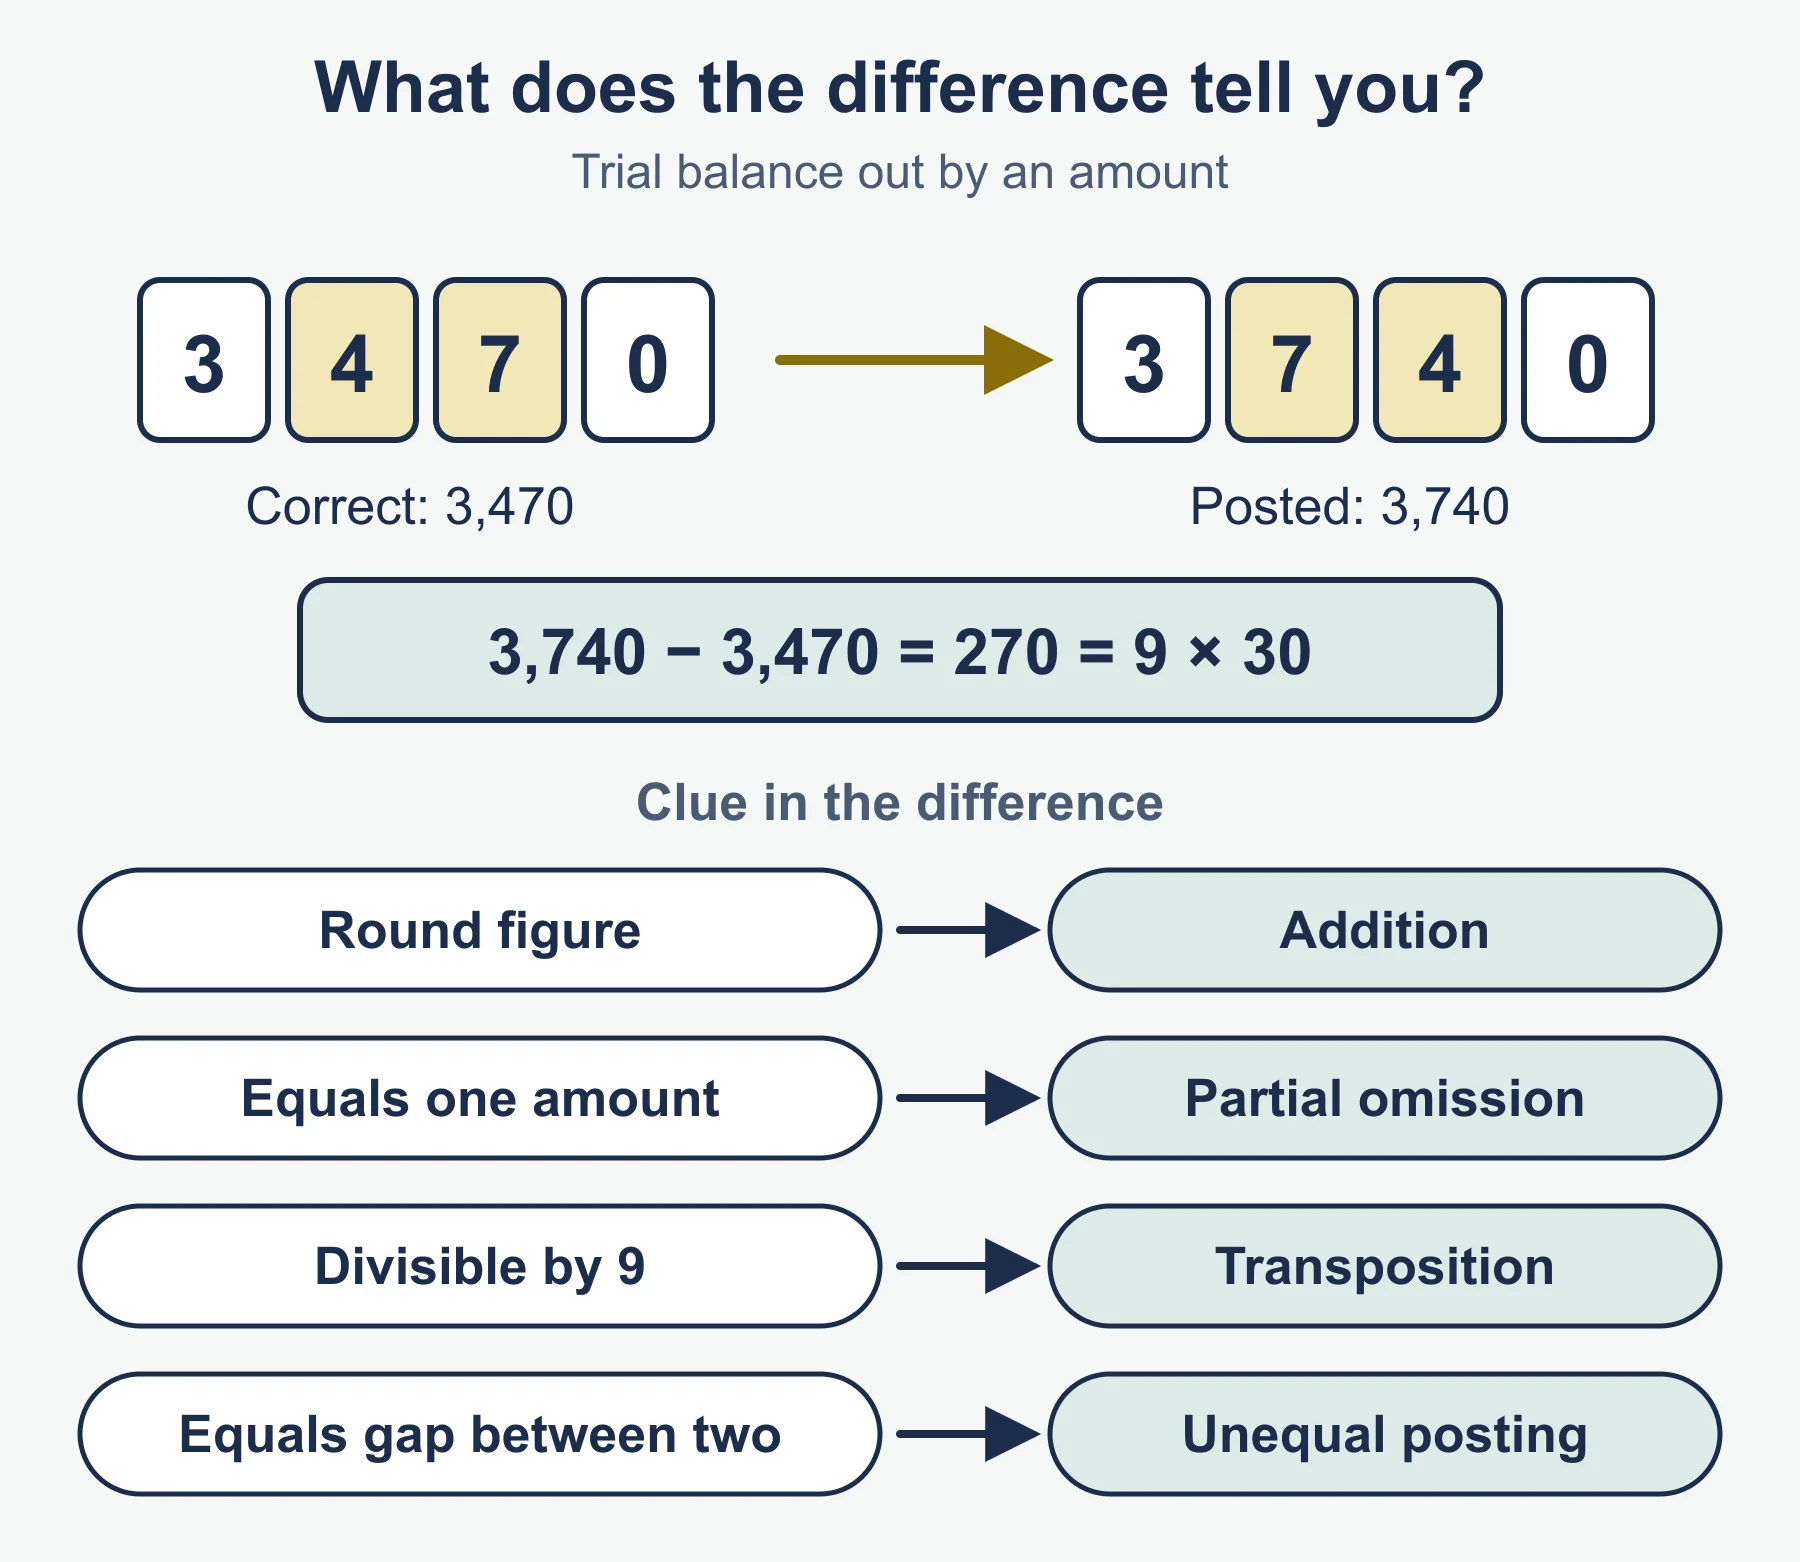
Difference clues. Divisible by 9 suggests transposition (387 is 9 × 43, so a single transposition could explain it, though it does not prove it). Equal to half the difference suggests a balance in the wrong column. Equal to a posting suggests a one-sided entry.
Wrong column reminder. A discount received of 310 is correct in the ledger but is listed in the debit column of the trial balance. Debits then exceed credits by 620, twice 310. No correcting journal is needed because the ledger is right: move the figure to the credit column.
1.2.6 Method: correcting journal
- Write down what was posted.
- Write down what should have been posted.
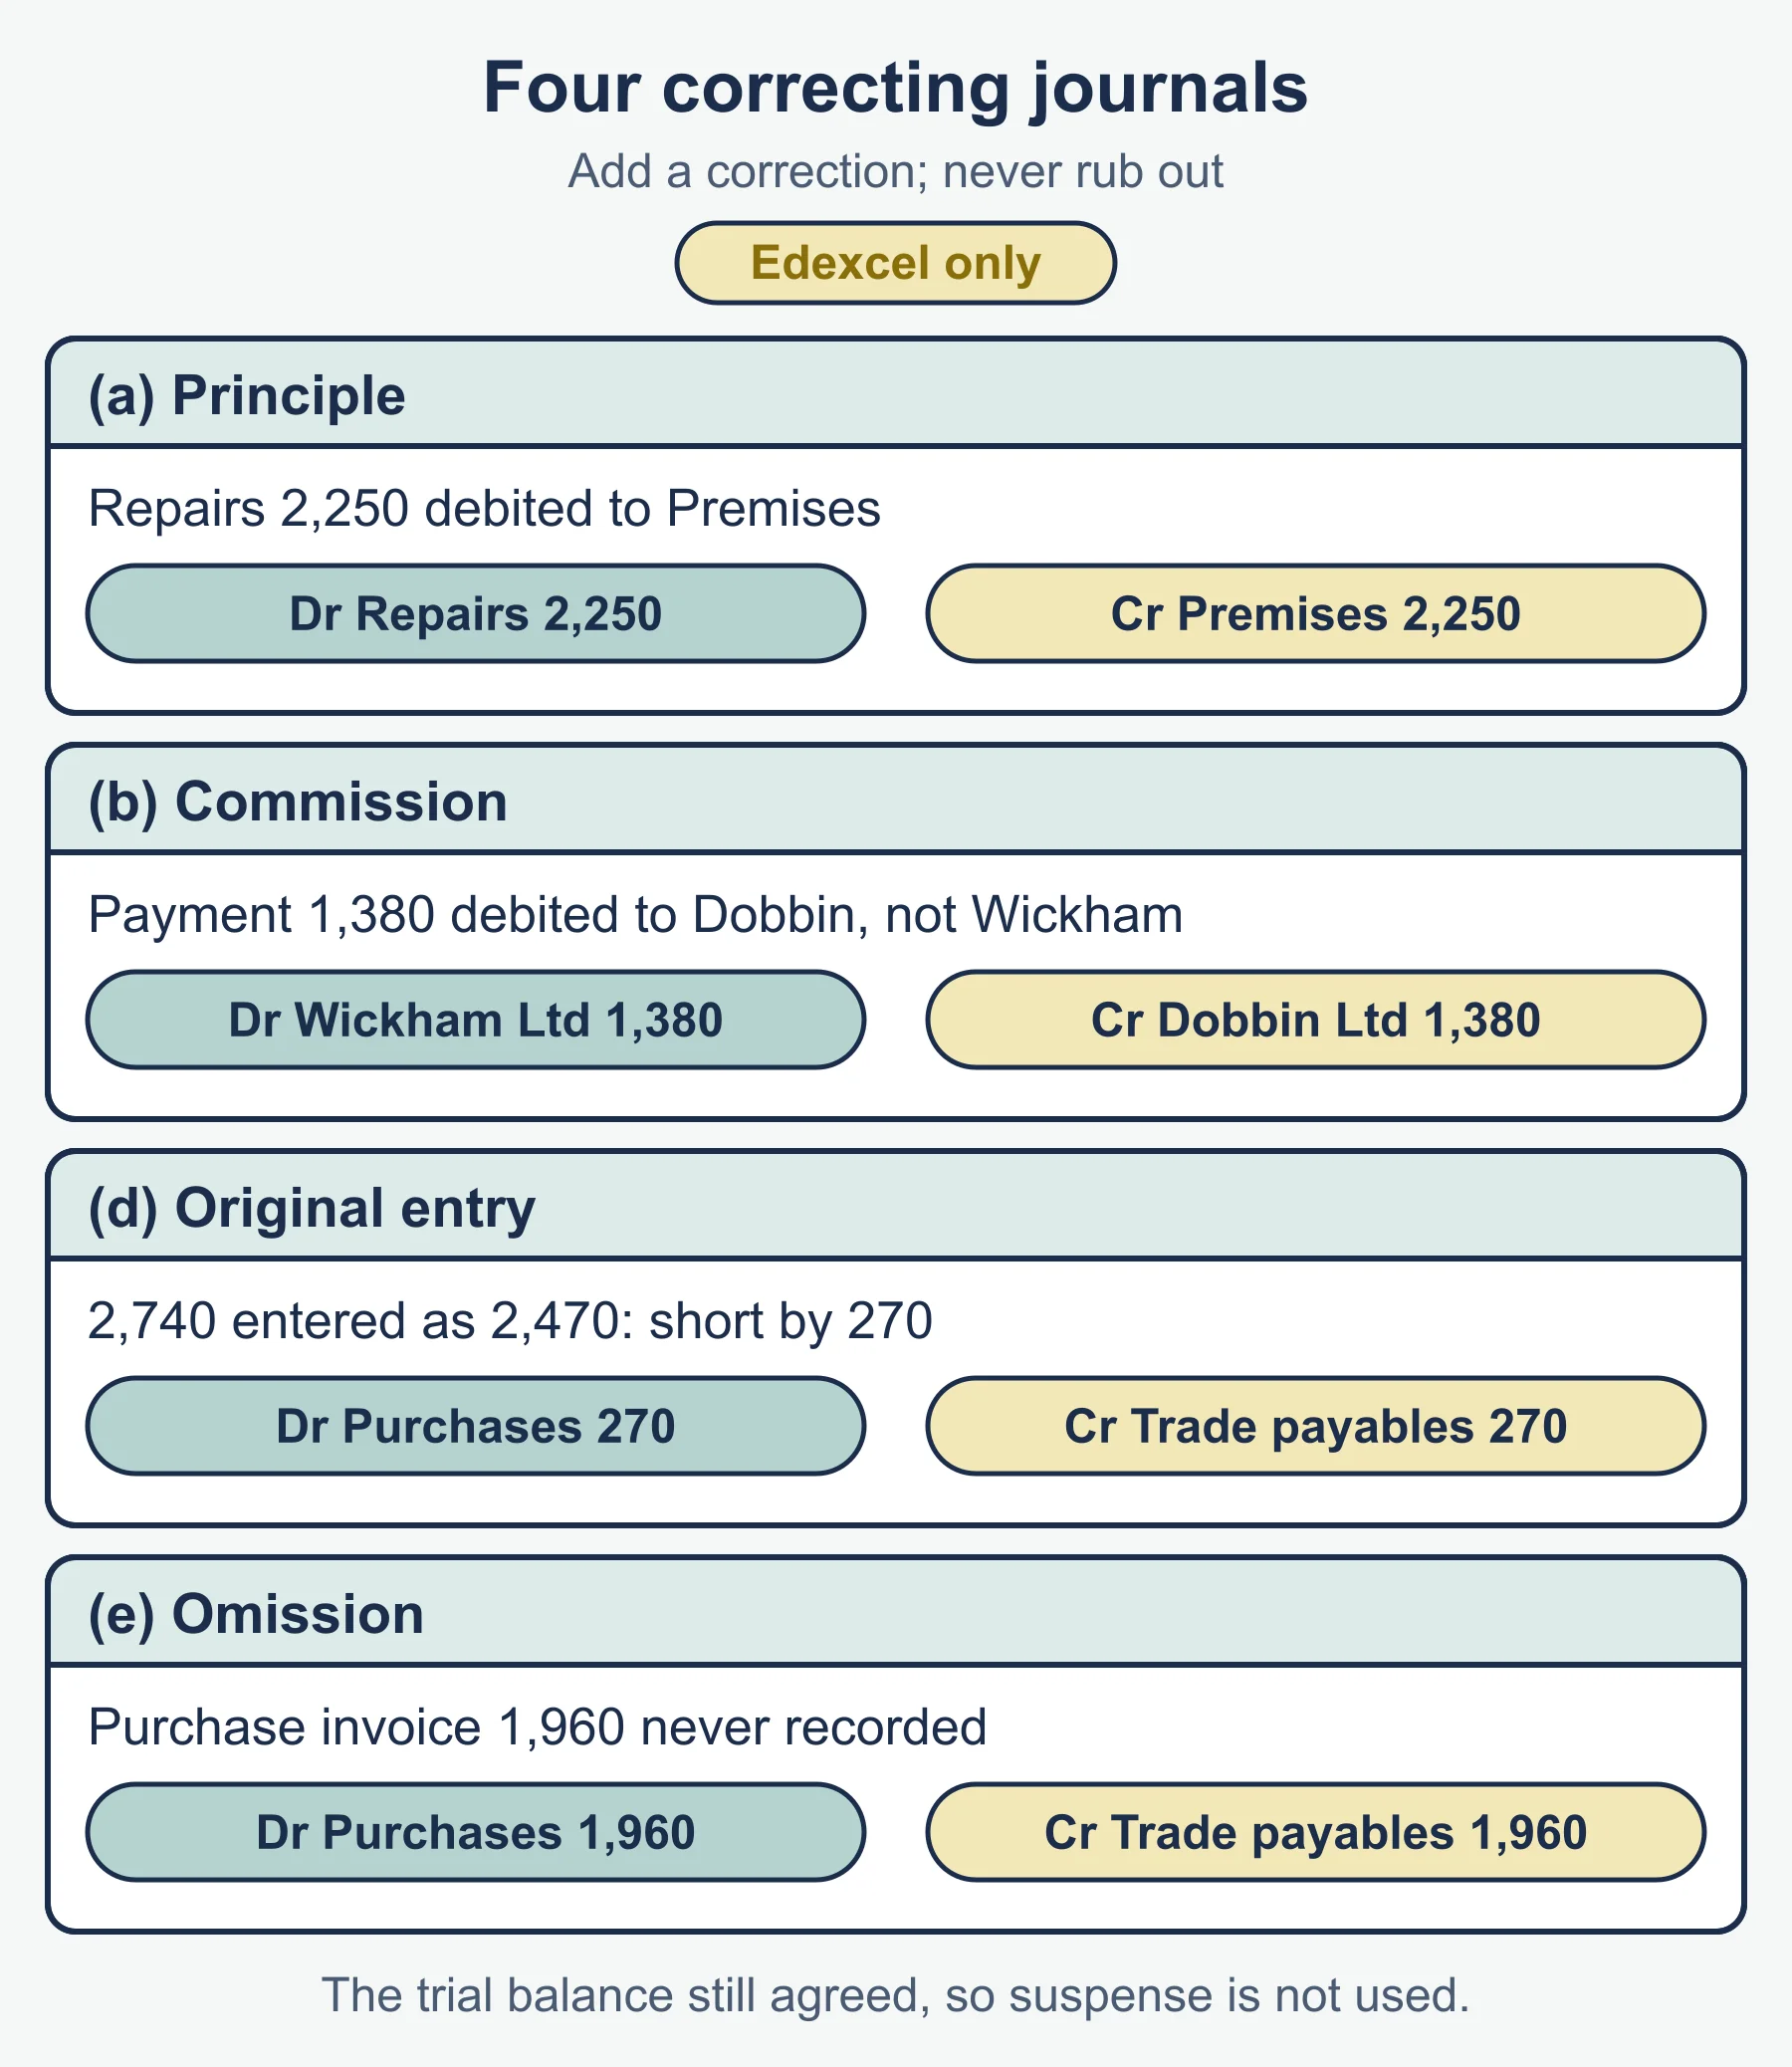
- Debit the account that should have been debited and credit the one that should have been credited, so that the wrong posting is cancelled and the right one made.
- Add a narrative.
| Error | Correction pattern |
|---|---|
| Omission | Post the whole entry |
| Commission | Debit the right account and credit the wrong one (or the reverse) |
| Principle | Move the amount from the wrong class of account to the right class |
| Original entry | Post only the difference |
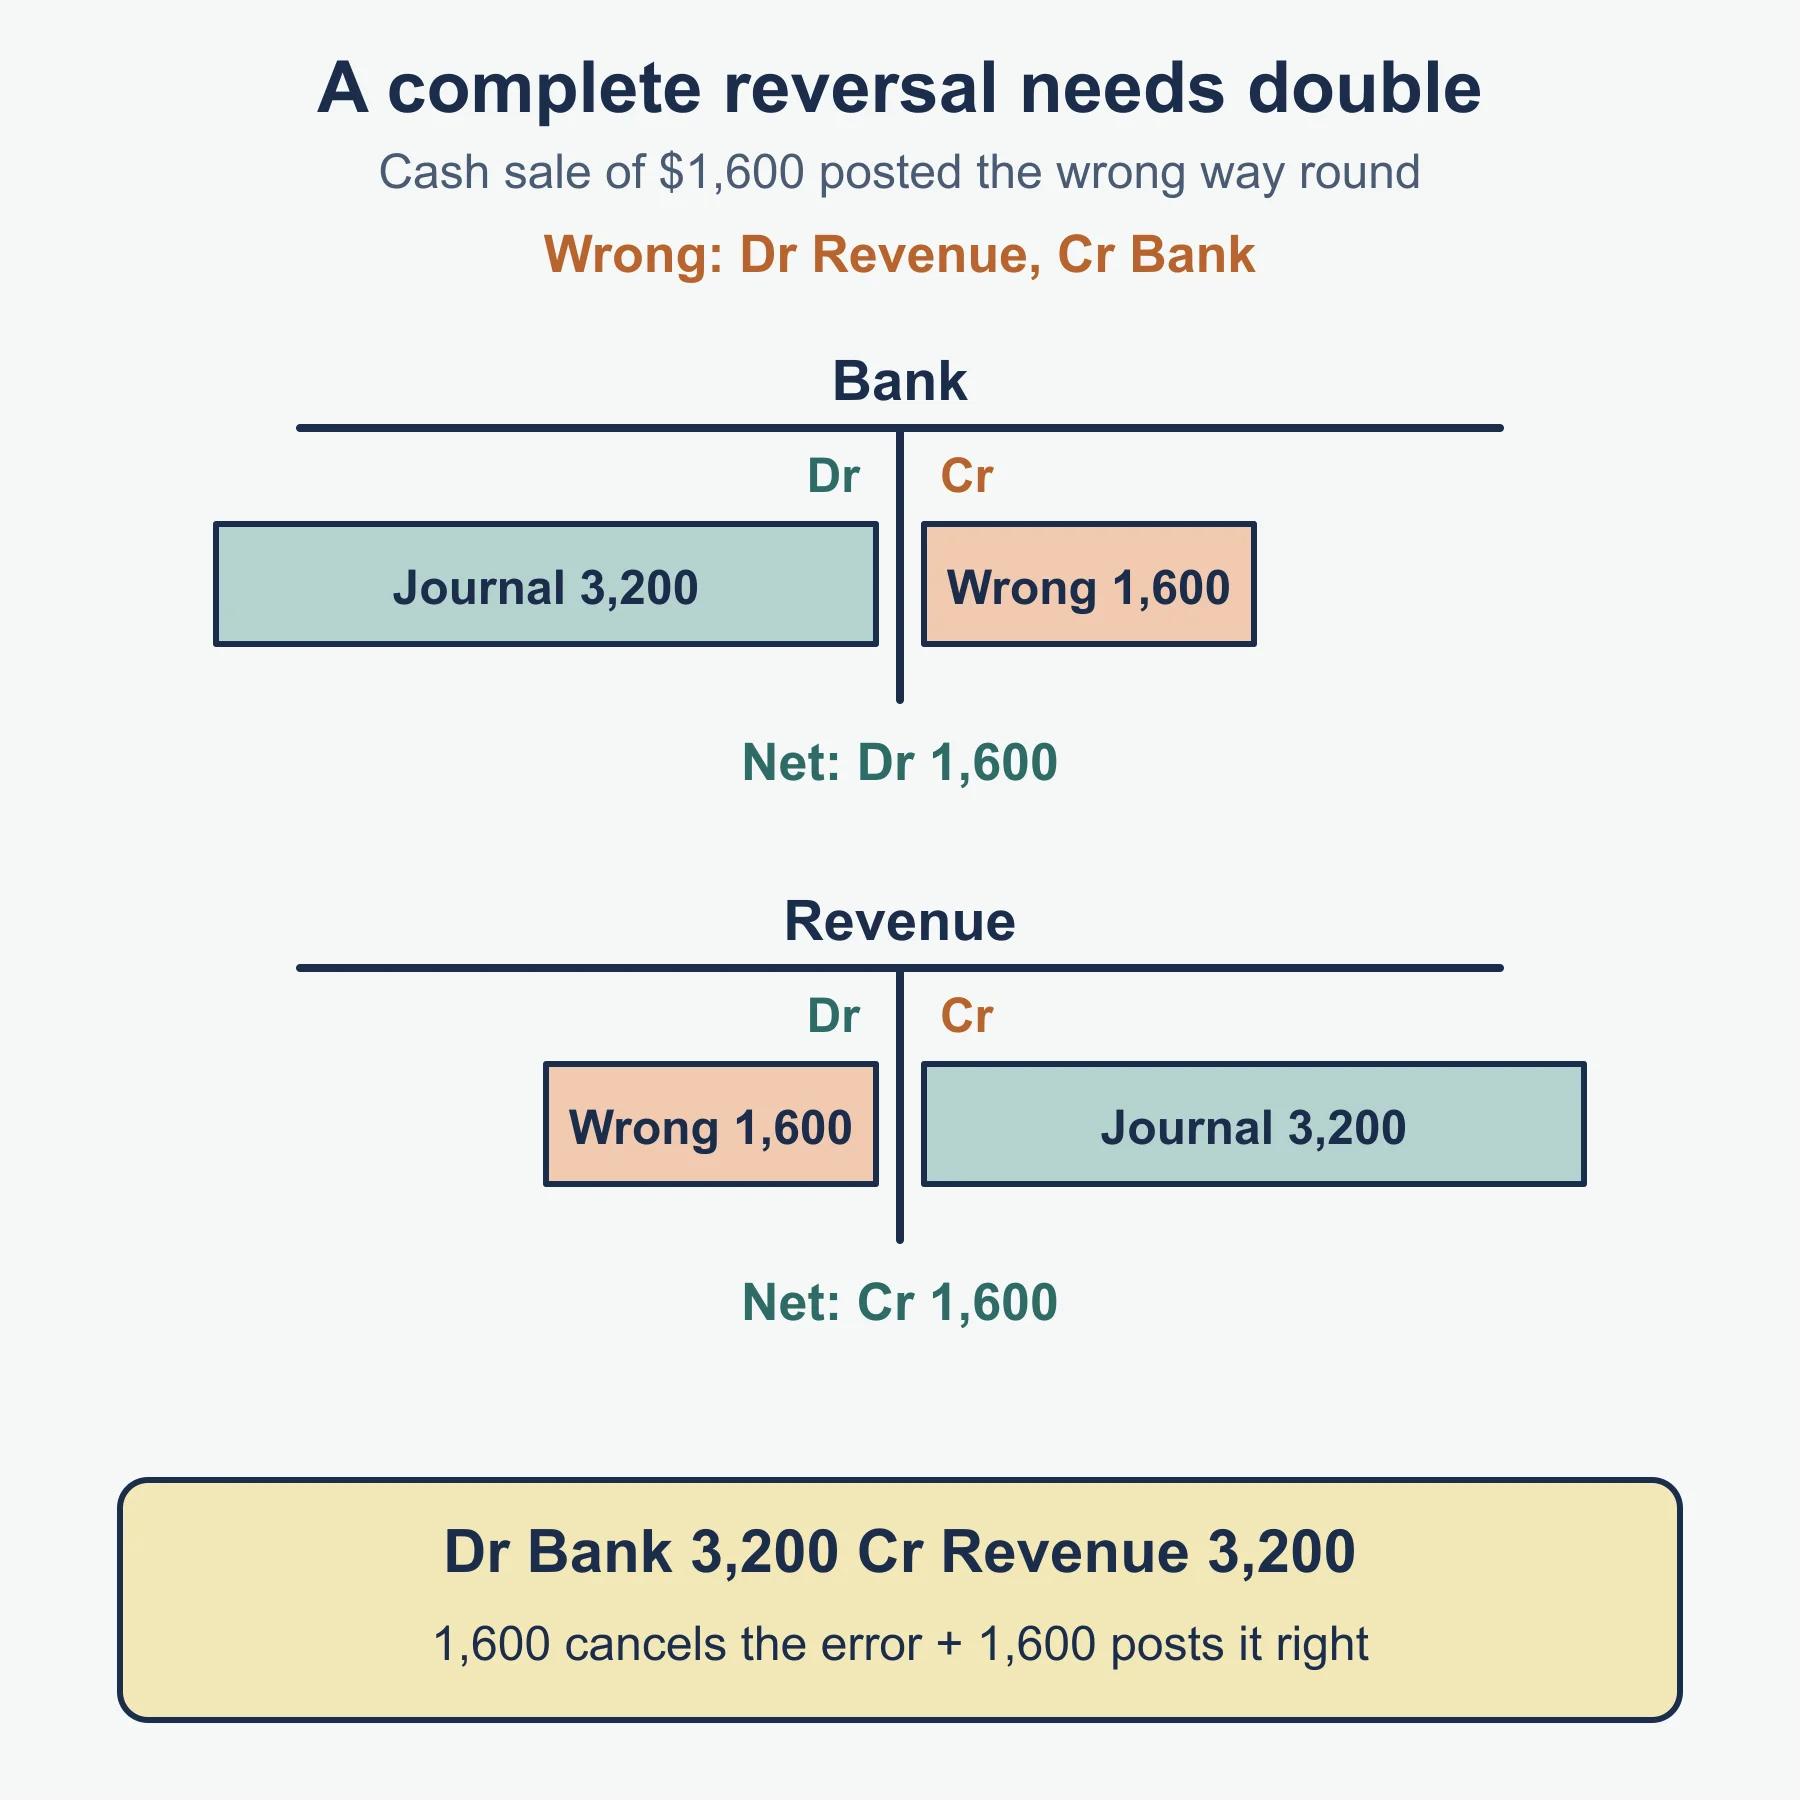
| Complete reversal | Post twice the amount the right way round |
Reminder: a payment of rent of 850 was debited to Bank and credited to Rent (reversed). Correction: Dr Rent 1,700, Cr Bank 1,700.
1.2.7 Suspense account rules
| Trial balance position | Suspense account |
|---|---|
| Debits exceed credits | Credit balance |
| Credits exceed debits | Debit balance |
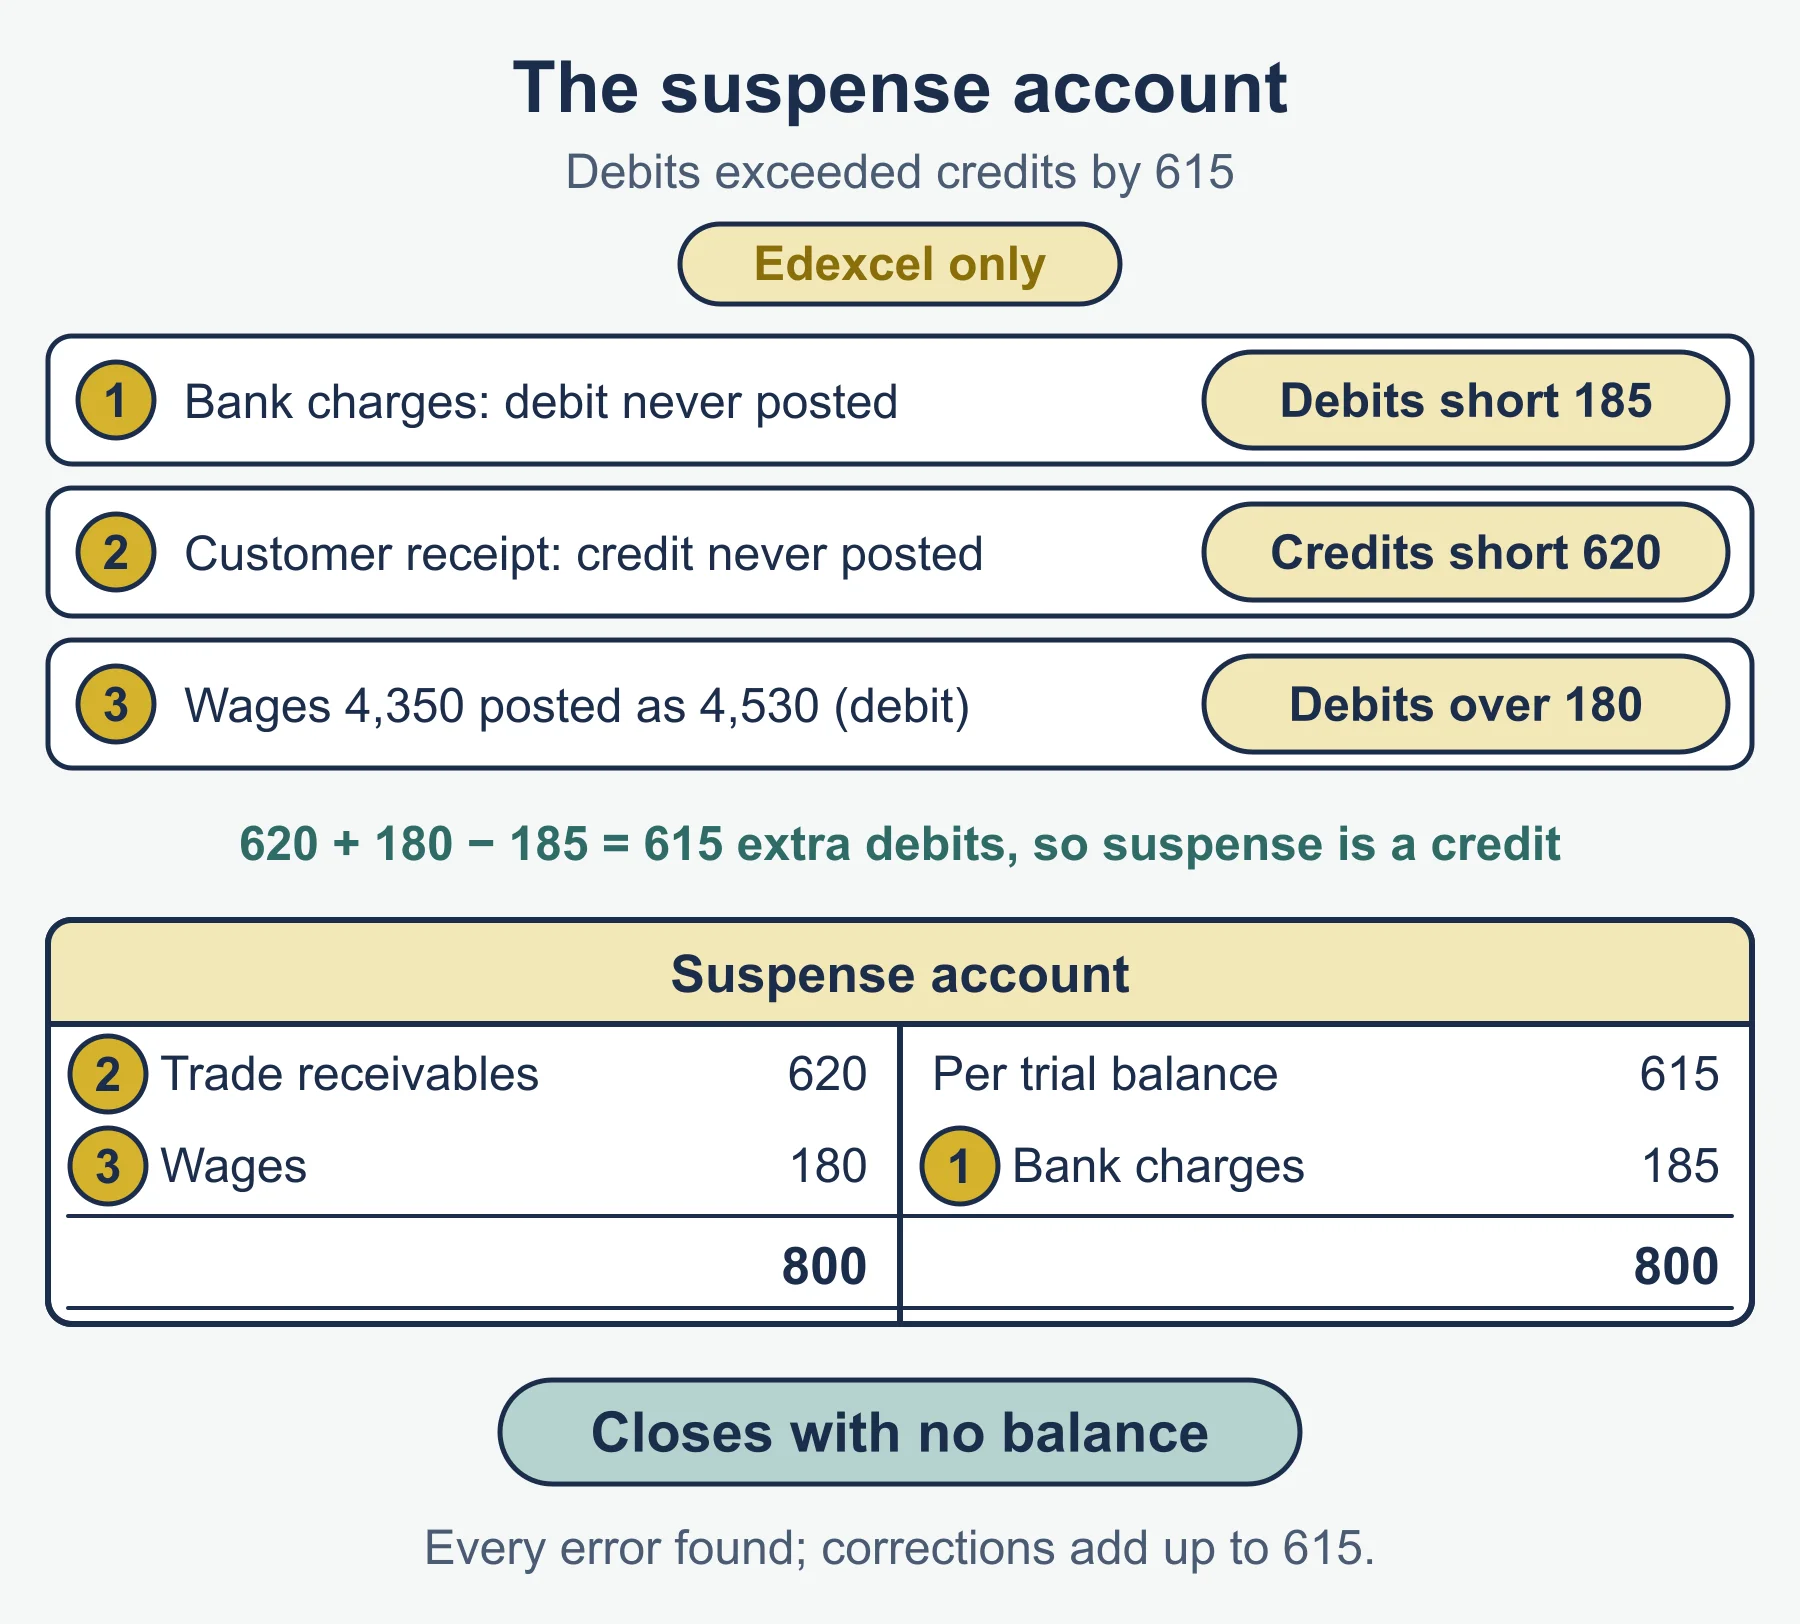
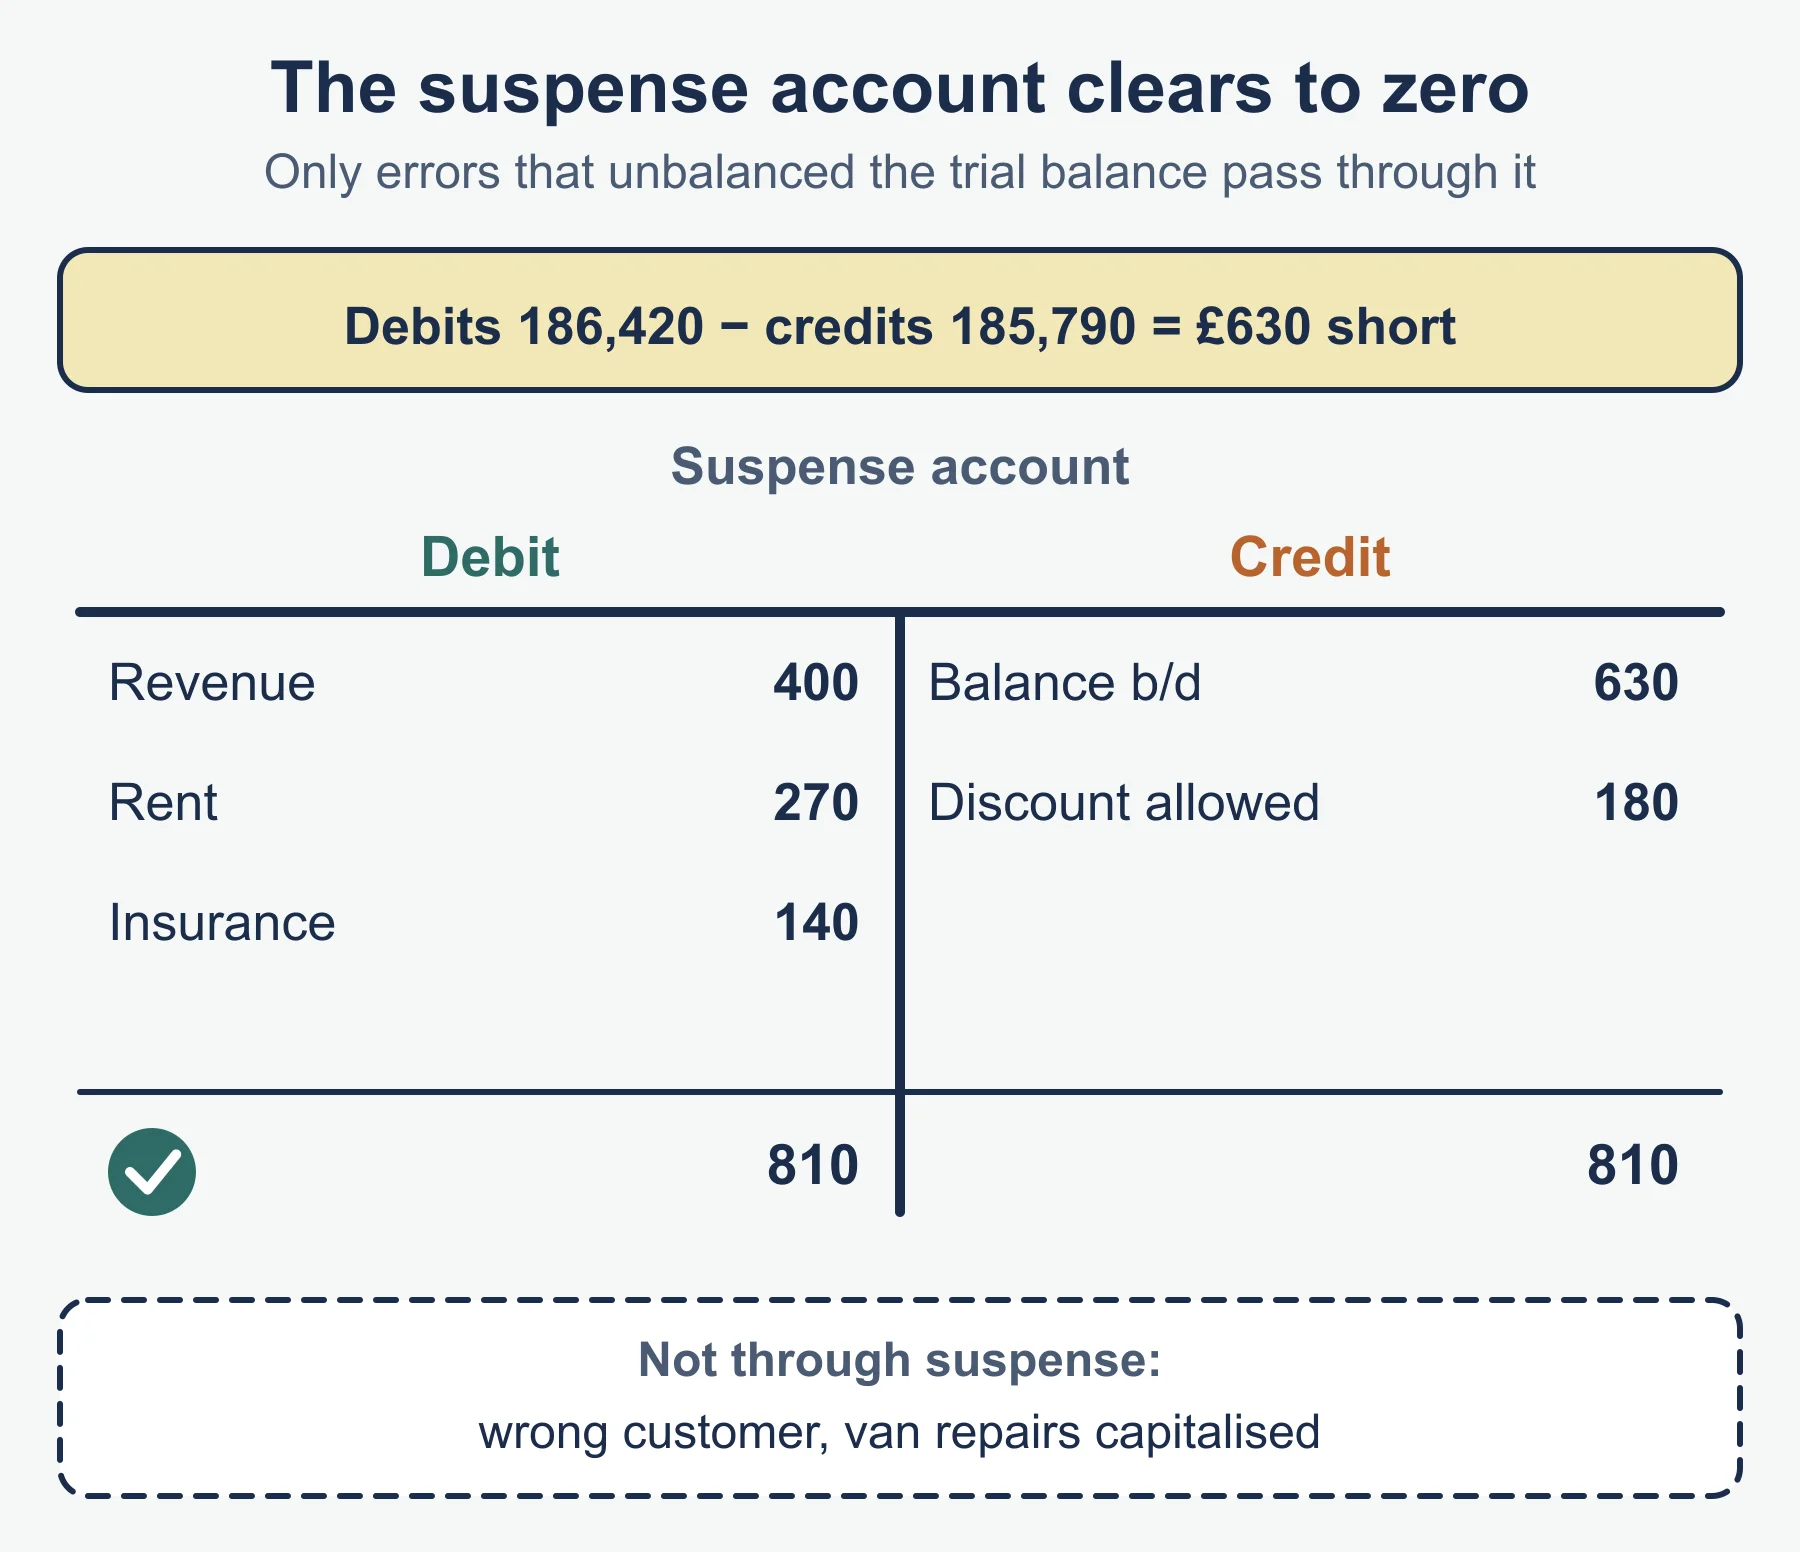
Only errors that make the totals disagree pass through suspense. The suspense account must close to nil when every error is corrected.
Reminder. Oldacre Cycles’ credits exceed debits by 1,260, so suspense is a debit of 1,260. Later: (i) rent of 1,500 was credited to bank, but the debit to rent was omitted; (ii) a return of 240 to a supplier was debited to the supplier but not credited to purchases returns.
| Suspense account | |||
|---|---|---|---|
| Balance per trial balance | 1,260 | Rent | 1,500 |
| Purchases returns | 240 | ||
| 1,500 | 1,500 |
1.2.8 Statement of revised profit
| Correction | Effect on profit |
|---|---|
| Expense understated | Decrease |
| Expense overstated | Increase |
| Income understated | Increase |
| Income overstated | Decrease |
| Errors between statement of financial position accounts only | None |
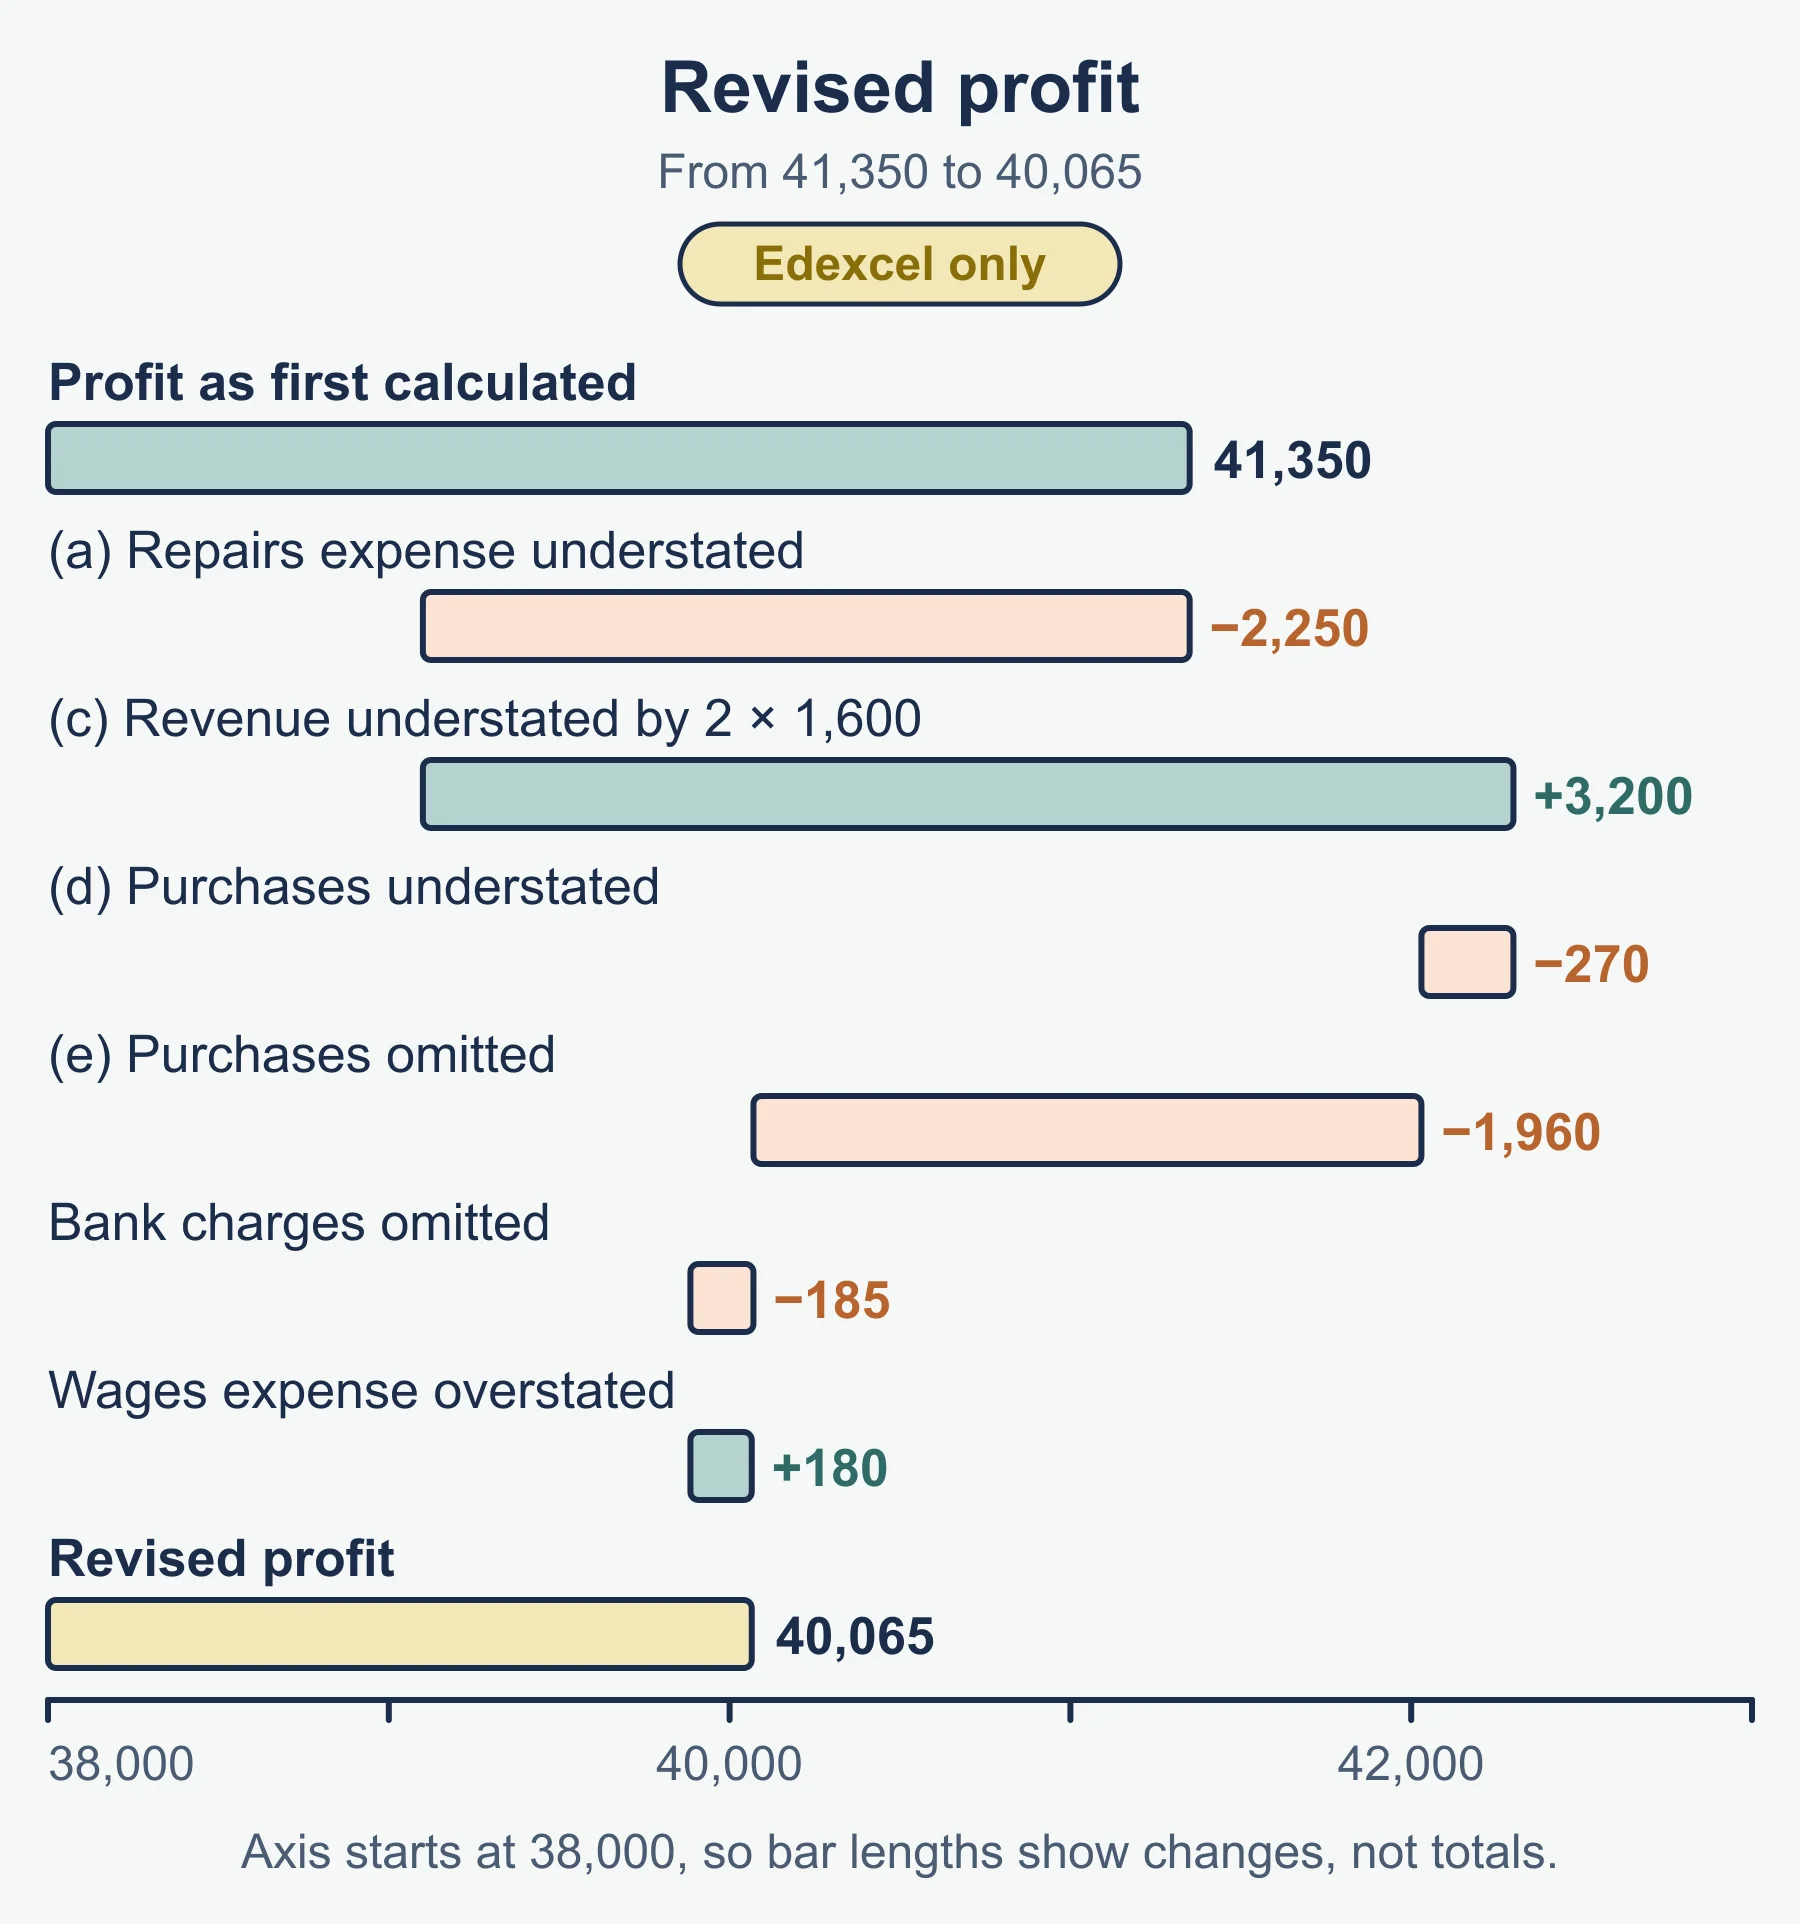
Layout: profit as first calculated, then each adjustment with a plus or minus, then revised profit. Reminder: Oldacre Cycles’ profit was 26,480. Rent of 1,500 was understated (−1,500) and purchases returns of 240 were omitted (+240). Revised profit is 26,480 − 1,500 + 240 = 25,220.
1.2.9 Control accounts: what to correct where
| Error | Control account | List of balances |
|---|---|---|
| Day book total over-added or under-added | Correct | No change |
| Total posted to the wrong side | Correct | No change |
| Irrecoverable debt or contra in the individual account only | Correct | No change |
| Individual account not posted, or posted wrongly | No change | Correct |
| Balance mis-copied or mis-added in the list | No change | Correct |
| Credit balance listed as debit | No change | Correct by twice the balance |
| Invoice posted to the wrong customer | No change | No change in total |
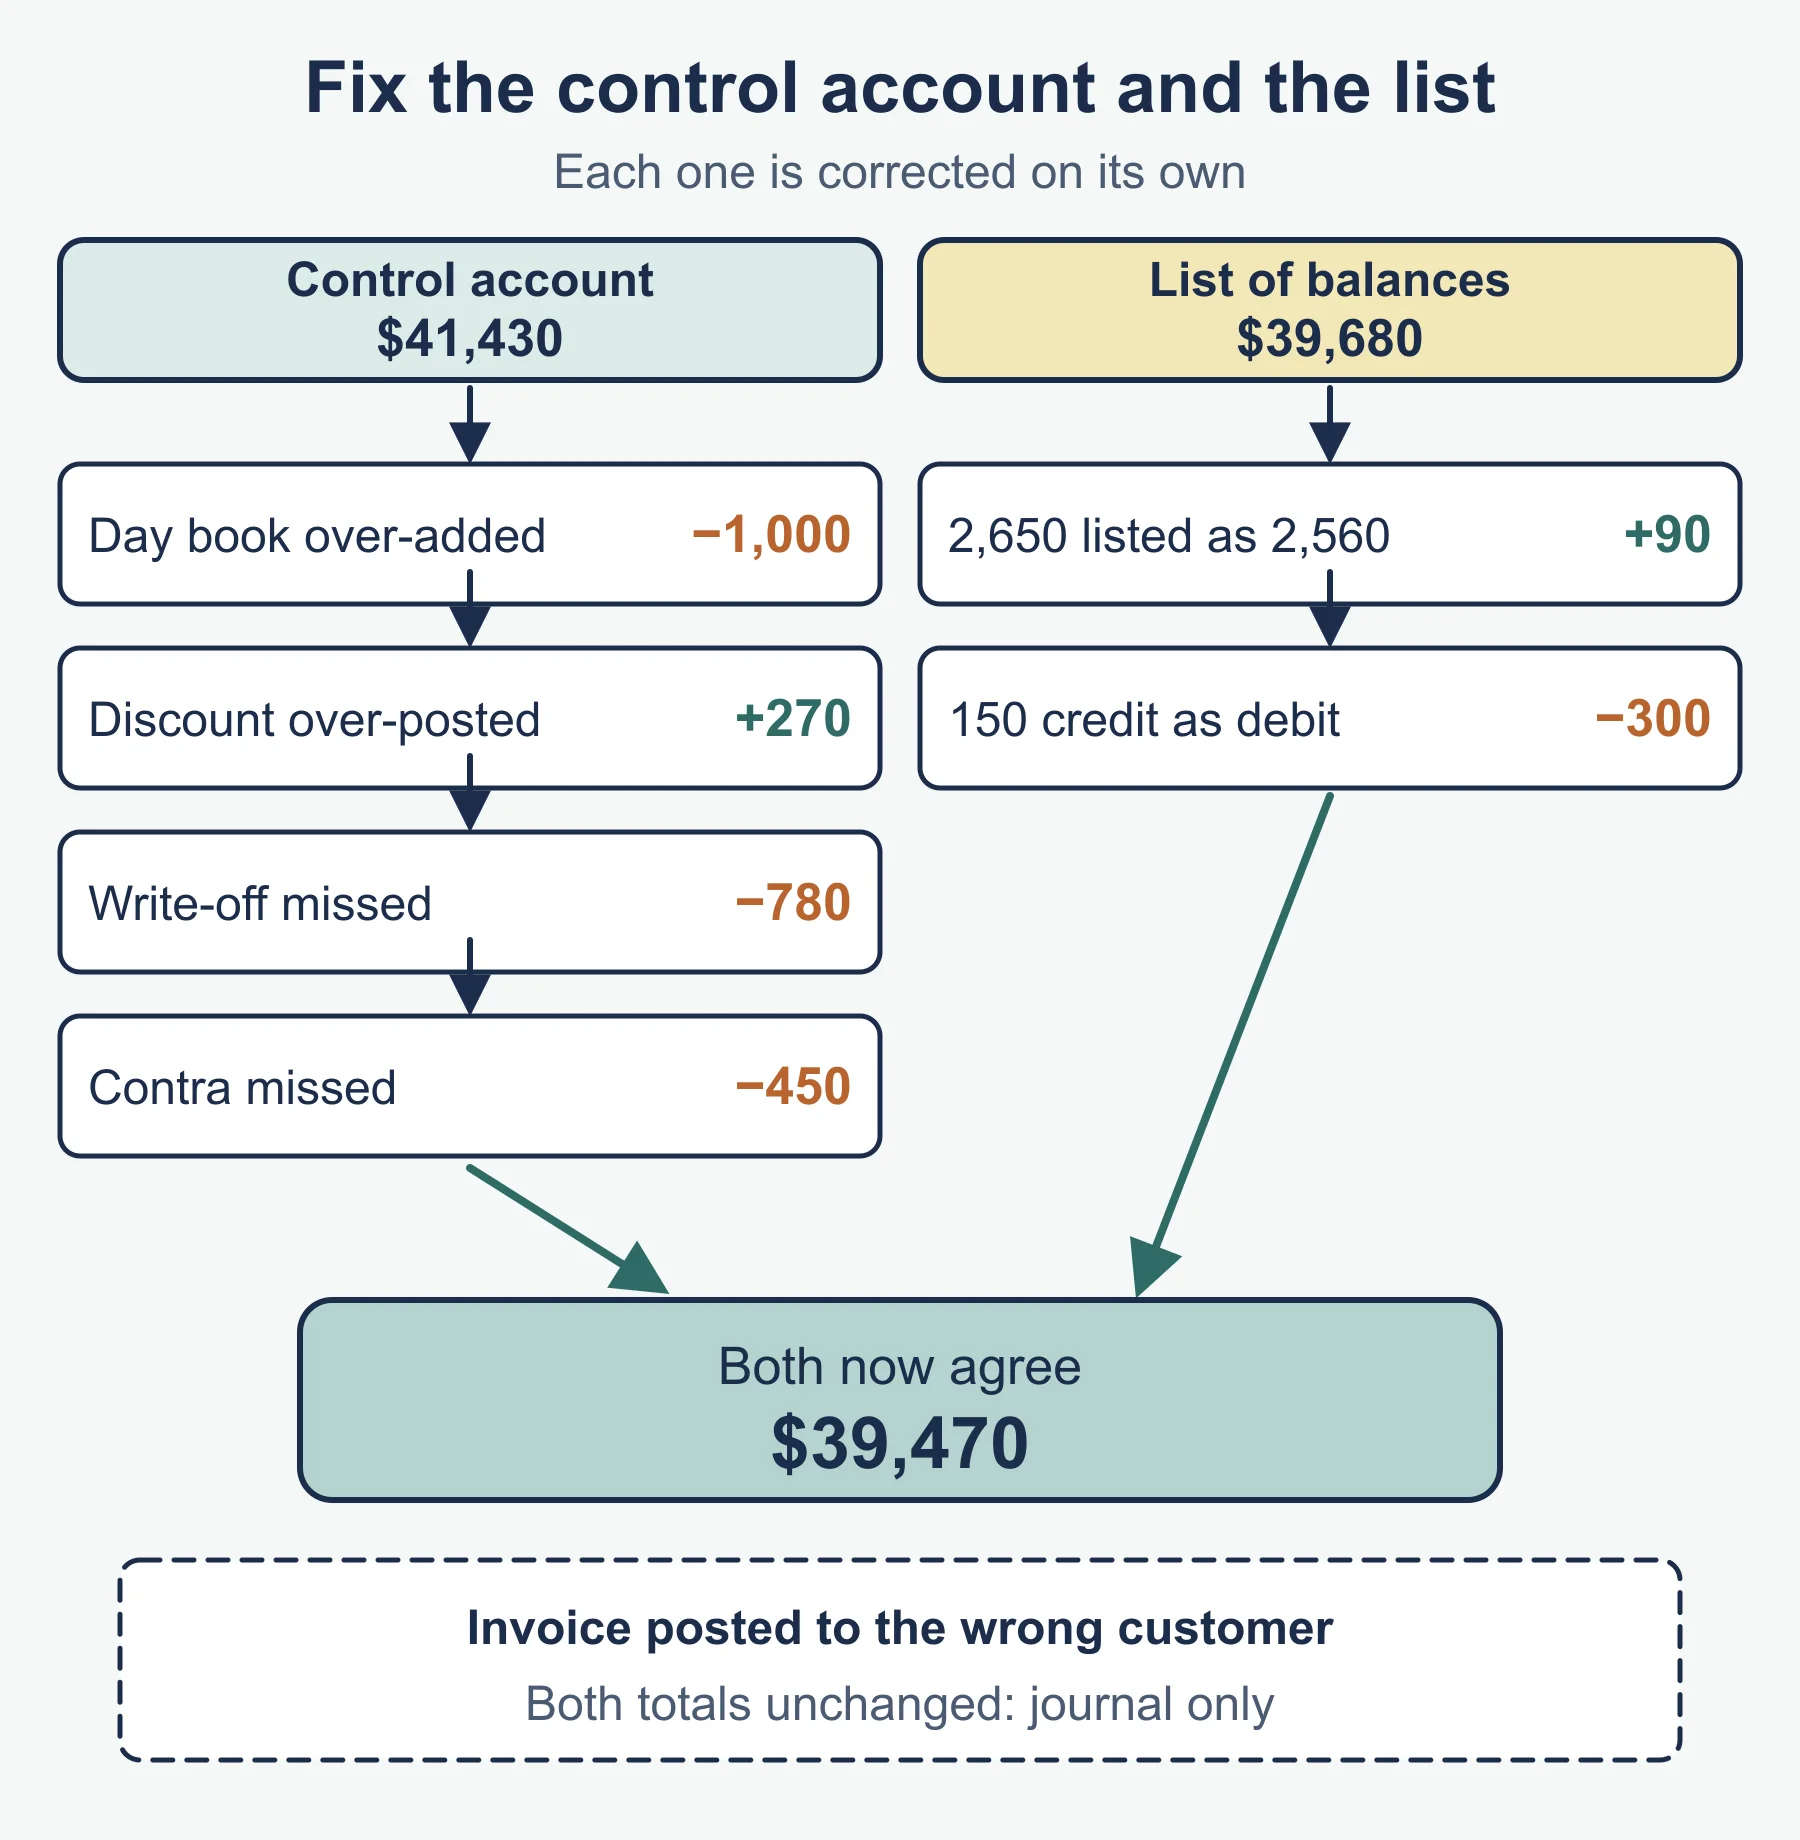
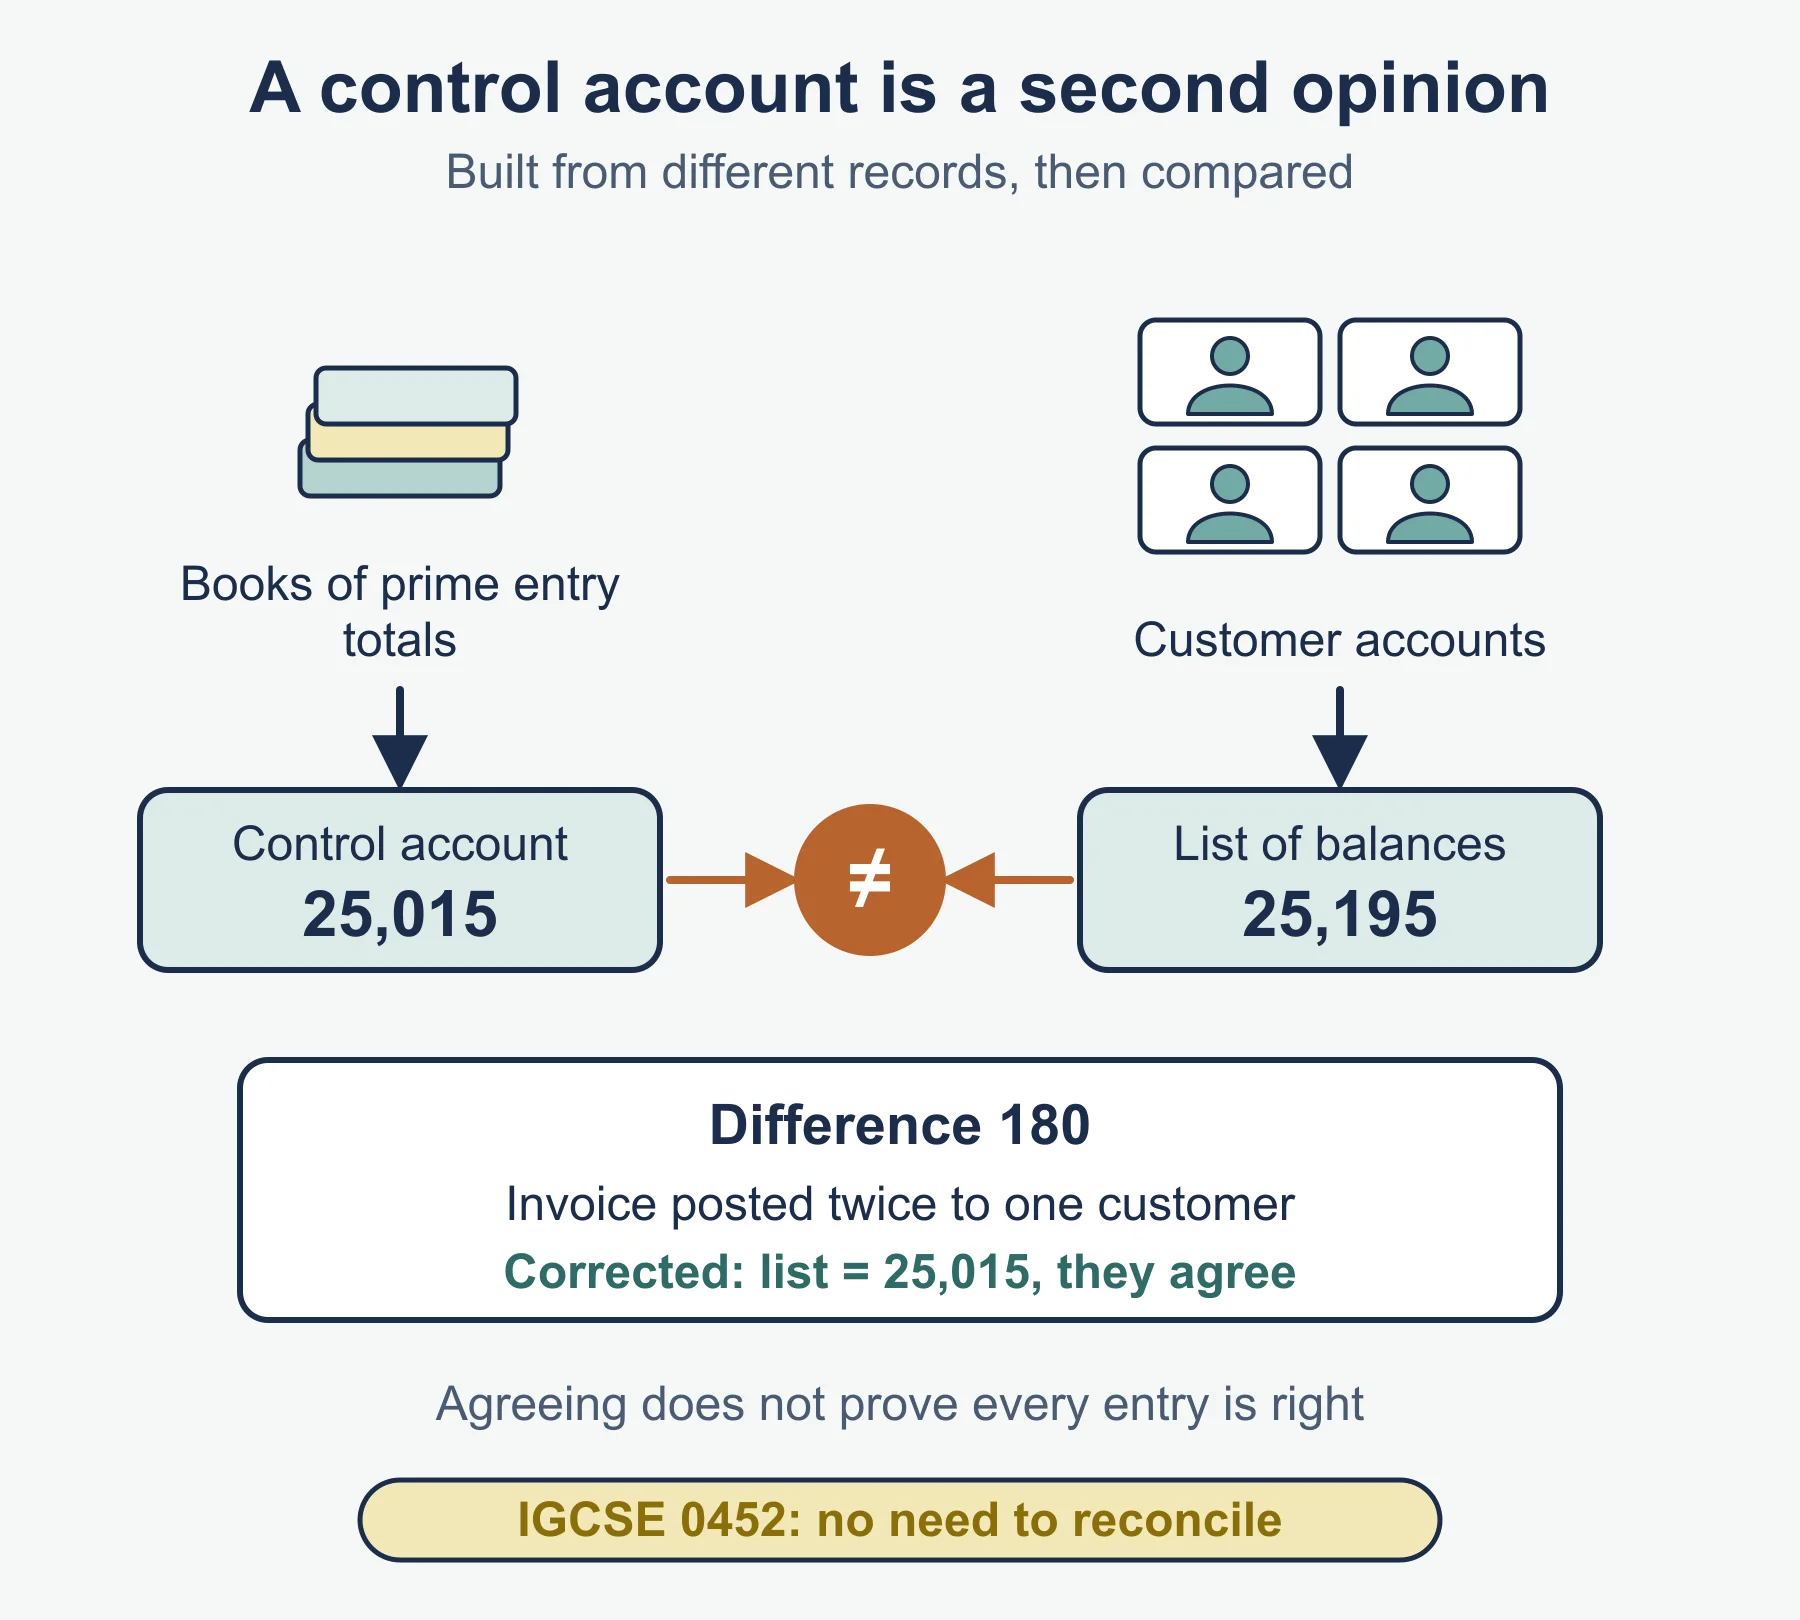
Correct each side separately, then check both agree.
Reminder. Oldacre Cycles’ receivables control account shows 22,500 and its list totals 22,980. The sales day book was under-added by 400 (debit 400) and a contra of 150 was entered in the individual accounts only (credit 150), so the control account becomes 22,500 + 400 − 150 = 22,750. In the list, a credit balance of 115 was shown as a debit, so subtract 230: 22,980 − 230 = 22,750. Both agree.
Exam routine for an error question
- Say whether each error leaves the trial balance agreeing or not.
- Write a journal for every error, with narrative and the doubled amount for a reversal.
- Put only the disagreeing errors through suspense, and show it closing to nil.
- Take each journal to the profit statement, stating increase or decrease.
- Re-read the question for what is asked: a journal, a suspense account, revised profit or a corrected control account.
Quick self-test
- Debits exceed credits. On which side is the suspense account?
- A trial balance differs by 387. Could one transposition explain this?
- A payment of 850 for rent was posted as a debit to Bank and a credit to Rent. What is the amount of the correcting journal?
- Name two errors that an agreeing trial balance can hide.
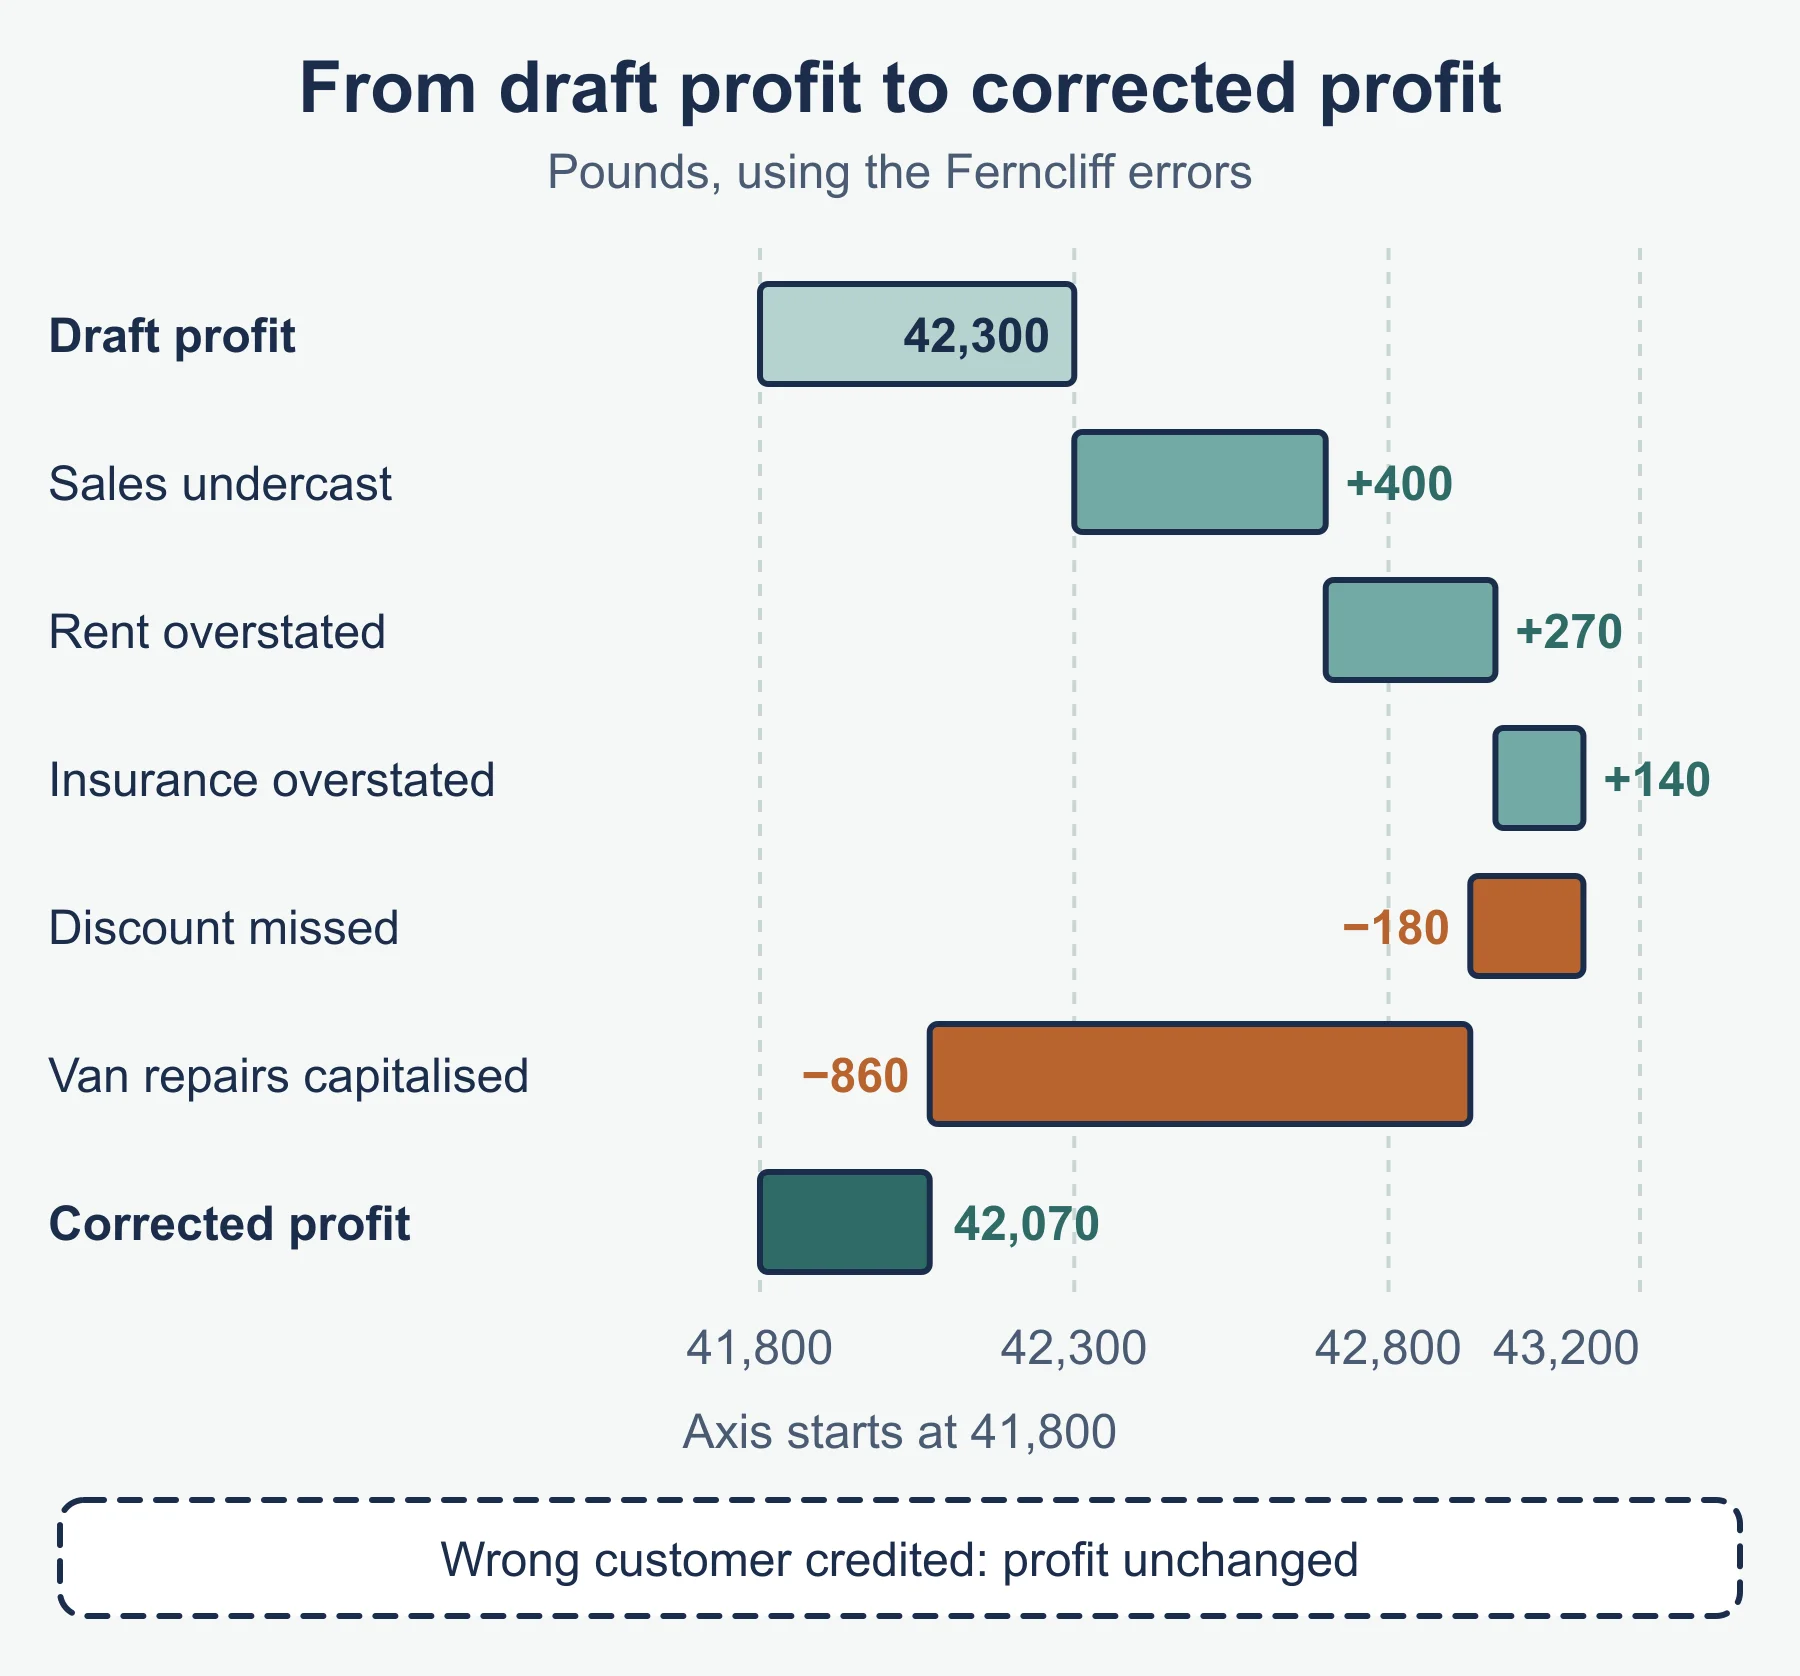
- Profit was 18,600. Purchases of 420 were understated, revenue of 700 was overstated and wages of 150 were overstated. What is revised profit?
- Debits total 90,420 and credits 90,870. Give the suspense entry.
- A computer costing 1,900 was debited to purchases. Does the trial balance disagree? Write the correction.
- A sales day book was over-added by 300. Which total is corrected?
- A customer’s credit balance of 80 was listed as a debit. By how much is the list wrong?
- Why does a suspense account have nil balance at the end?
Answers
- Credit side, as a credit balance.
- Yes, 387 is 9 × 43, so it could, but it is only a clue.
- 1,700 (twice 850): Dr Rent, Cr Bank.
- Any two of: omission, commission, principle, original entry, complete reversal, compensating errors.
- 18,600 − 420 − 700 + 150 = 17,630.
- Credits exceed debits by 450, so Dr Suspense 450 in the trial balance.
- No, both sides were posted (principle). Dr Computer equipment 1,900, Cr Purchases 1,900.
- The control account, by crediting 300; the list is unchanged.
- The list is overstated by 160, twice 80.
- Because the corrections add up to the original difference, which shows all errors are found.
Where marks are usually lost
- Putting suspense on the wrong side of the account.
- Posting only the original amount for a complete reversal.
- Using suspense for errors that leave the trial balance agreeing.
- Adjusting profit in the wrong direction.
- Changing profit for an error between two statement of financial position accounts.
- Writing the error type but no journal, or a journal with no narrative.
- Forgetting that a credit balance listed as a debit is out by twice the balance.
- Correcting the control account for an error that is only in the list.
Frequently asked questions
What clues help find a trial balance difference? A difference divisible by 9 suggests a transposition, though it does not prove it. A difference equal to a posting suggests a one-sided entry, and one equal to twice a balance suggests that balance was listed in the wrong column.
What are the limitations of a trial balance? An agreeing trial balance cannot reveal errors that put equal amounts on both sides or errors that cancel each other. It also does not show profit or the financial position, so financial statements are still needed.
What must a correcting journal entry include? It states the account debited, the account credited, the amount and a narrative. Work out what was posted, what should have been posted and the difference, then add a correction rather than rubbing out the original.
What is the exam routine for a correction of errors question? Say whether each error affects the trial balance, write a journal for every error, put only the disagreeing errors through suspense, then take each journal to the profit statement stating increase or decrease. Finally, check what the question actually asks for.
Official syllabus
Pearson Edexcel International Advanced Subsidiary/Advanced Level in Accounting (XAC11/YAC11) specification, Issue 2, September 2018, first teaching September 2015 (Pearson Education Limited). Unit 1, topic 1.2: outcomes 1.2.1, 1.2.2 and 1.2.5 to 1.2.9.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
Edexcel International A Level Accounting: Control Accounts and Correction of Errors (YAC11)
Control accounts as a check on receivable and payable ledgers, plus error correction, journals and the suspense account, for Edexcel IAL Accounting (YAC11).
Accounting · Pearson Edexcel · AS Level
Read guide -
Practice questions
Edexcel International A Level Accounting: Control Accounts and Correction of Errors — Practice Questions
Original practice questions with worked answers on control accounts, error types, journals, suspense accounts and revised profit for Edexcel IAL YAC11.
Accounting · Pearson Edexcel · AS Level
Try questions -
Revision notes
Edexcel International A Level Accounting: Control Accounts and Correction of Errors — Revision Notes
Revision notes on control accounts, error correction, suspense accounts and statements of revised profit for Edexcel IAL Accounting (YAC11), 1.2.3 to 1.2.9.
Accounting · Pearson Edexcel · AS Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting AS LEVEL?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Accounting teachers at Marlbridge

