
Study Guides
Edexcel IGCSE Business: Sources of business finance and cash flow forecasting (4BS1)
Study guide to sources of business finance, why cash matters, and building and reading a cash-flow forecast for Edexcel IGCSE Business (4BS1).
- Subject
- Business
- Level
- IGCSE
- Topic
- Business finance
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Asif Iqbal (what this means)
Aligned to Pearson Edexcel IGCSE Business (4BS1), Issue 2, February 2026. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Business.
Syllabus points this page covers
4BS1
- 3 Business finance (whole topic)
- 3.1 Business finance - sources
- 3.2 Cash flow forecasting
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Business online. Request a free trial class.
This guide follows the Pearson Edexcel International GCSE in Business (4BS1) specification, Issue 2, February 2026. It covers Topic 3, sections 3.1 “Business finance - sources” and 3.2 “Cash flow forecasting”, every numbered point under each. The specification says both papers draw on the whole of the subject content, so finance can appear in either.
Course links: the 4BS1 Business hub, the printable checklist and the free diagnostics. Companion pages: the revision notes and the practice questions.
What the specification asks for
| Point | You must be able to | Where in this guide |
|---|---|---|
| 3.1.1 | Explain the need for finance: short-term needs, long-term needs, to start up or expand | Section 1 |
| 3.1.2 | Describe internal sources: personal savings, retained profit, selling assets | Section 2 |
| 3.1.3 | Describe external sources: overdraft and trade payables; loan capital, share capital including stock market flotation (public limited companies); venture capital; crowdfunding | Section 3 |
| 3.2.1 | Explain why cash matters: to pay suppliers, overheads and employees; to prevent business failure (insolvency); the difference between cash and profit | Sections 4 and 5 |
| 3.2.2 | Calculate and interpret cash-flow forecasts: cash inflows, cash outflows, net cash flow, opening and closing balances | Sections 6 and 7 |
1. The need for finance (3.1.1)
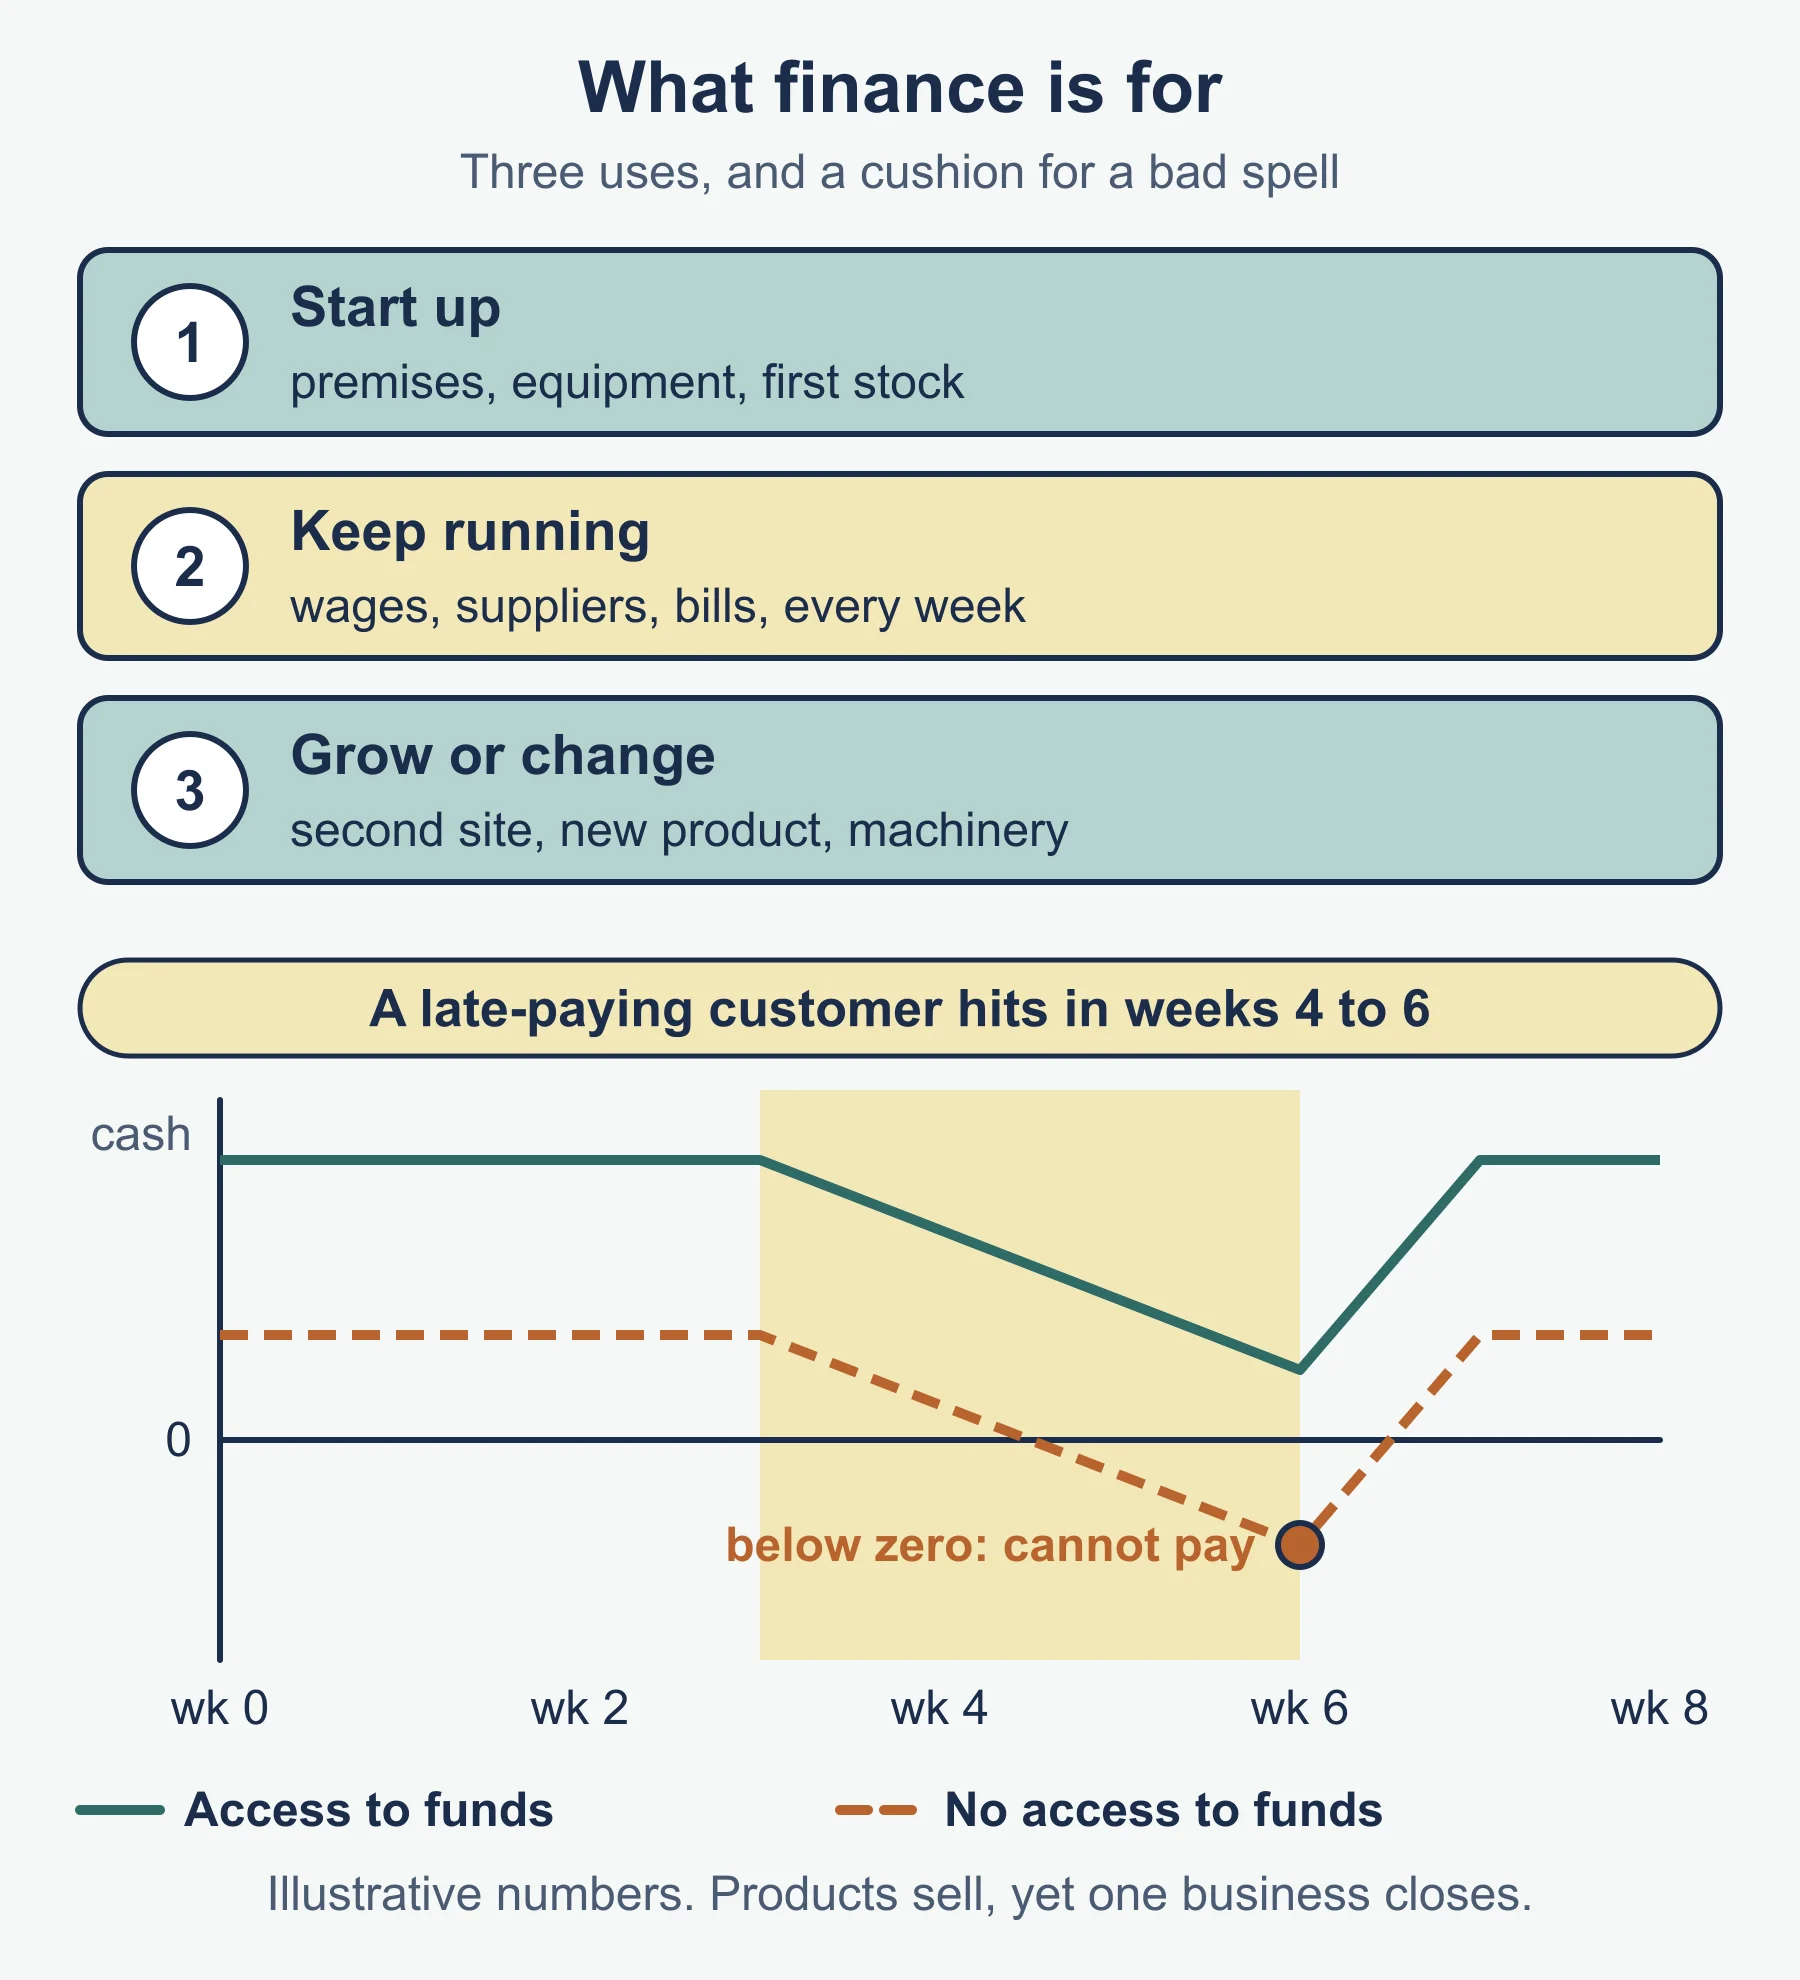
Every business needs money to operate. The specification lists three reasons: short-term needs, long-term needs, and finance to start up or expand. The explanations below are standard business knowledge.
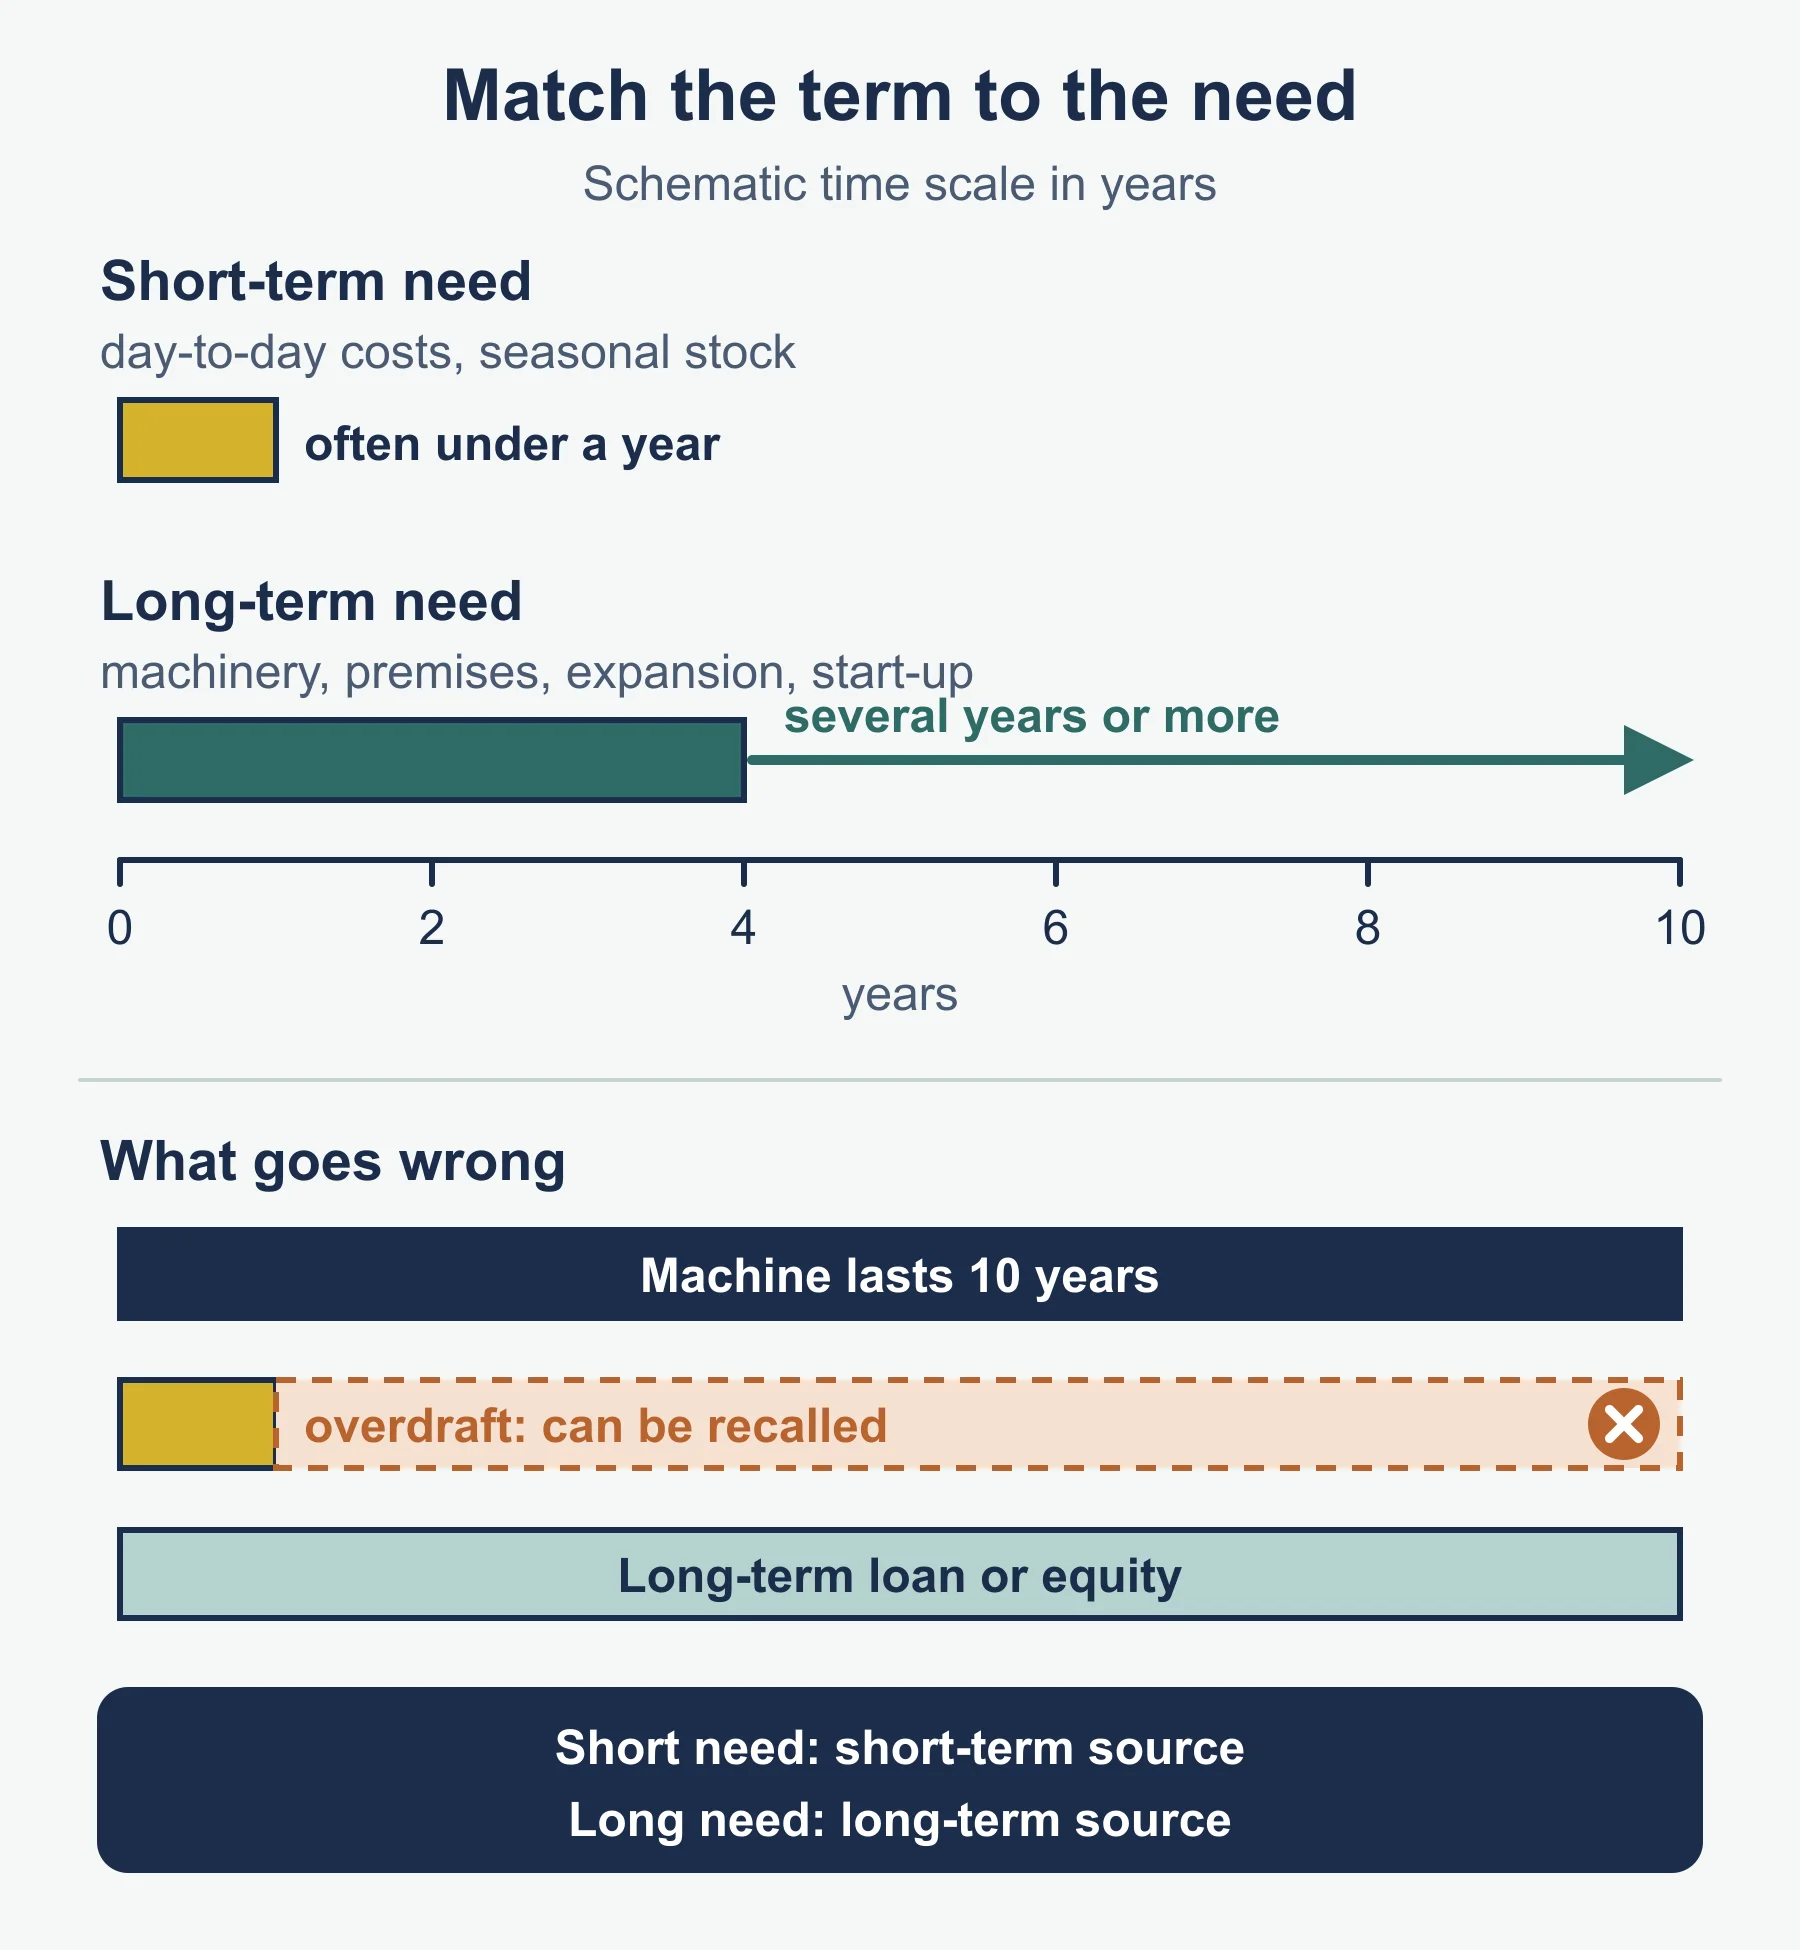
Short-term needs are bills that come up in the normal running of the business and are paid back or covered within a short period: buying inventory, paying wages and utility bills, covering a gap before customers pay.
Long-term needs are for spending that lasts for years and is not recovered quickly: a new building, heavy machinery, a fleet of vehicles. The money is usually tied up for a long time, so the finance should last as long as the asset does.
Finance is also needed to start up (premises, equipment, first stock, before any sales arrive) or to expand (a second branch, a new product range, a bigger factory).
When you choose a source, choose finance that lasts as long as the need it pays for. An overdraft the bank can recall is a risky way to pay for a machine that lasts ten years.
2. Internal sources of finance (3.1.2)
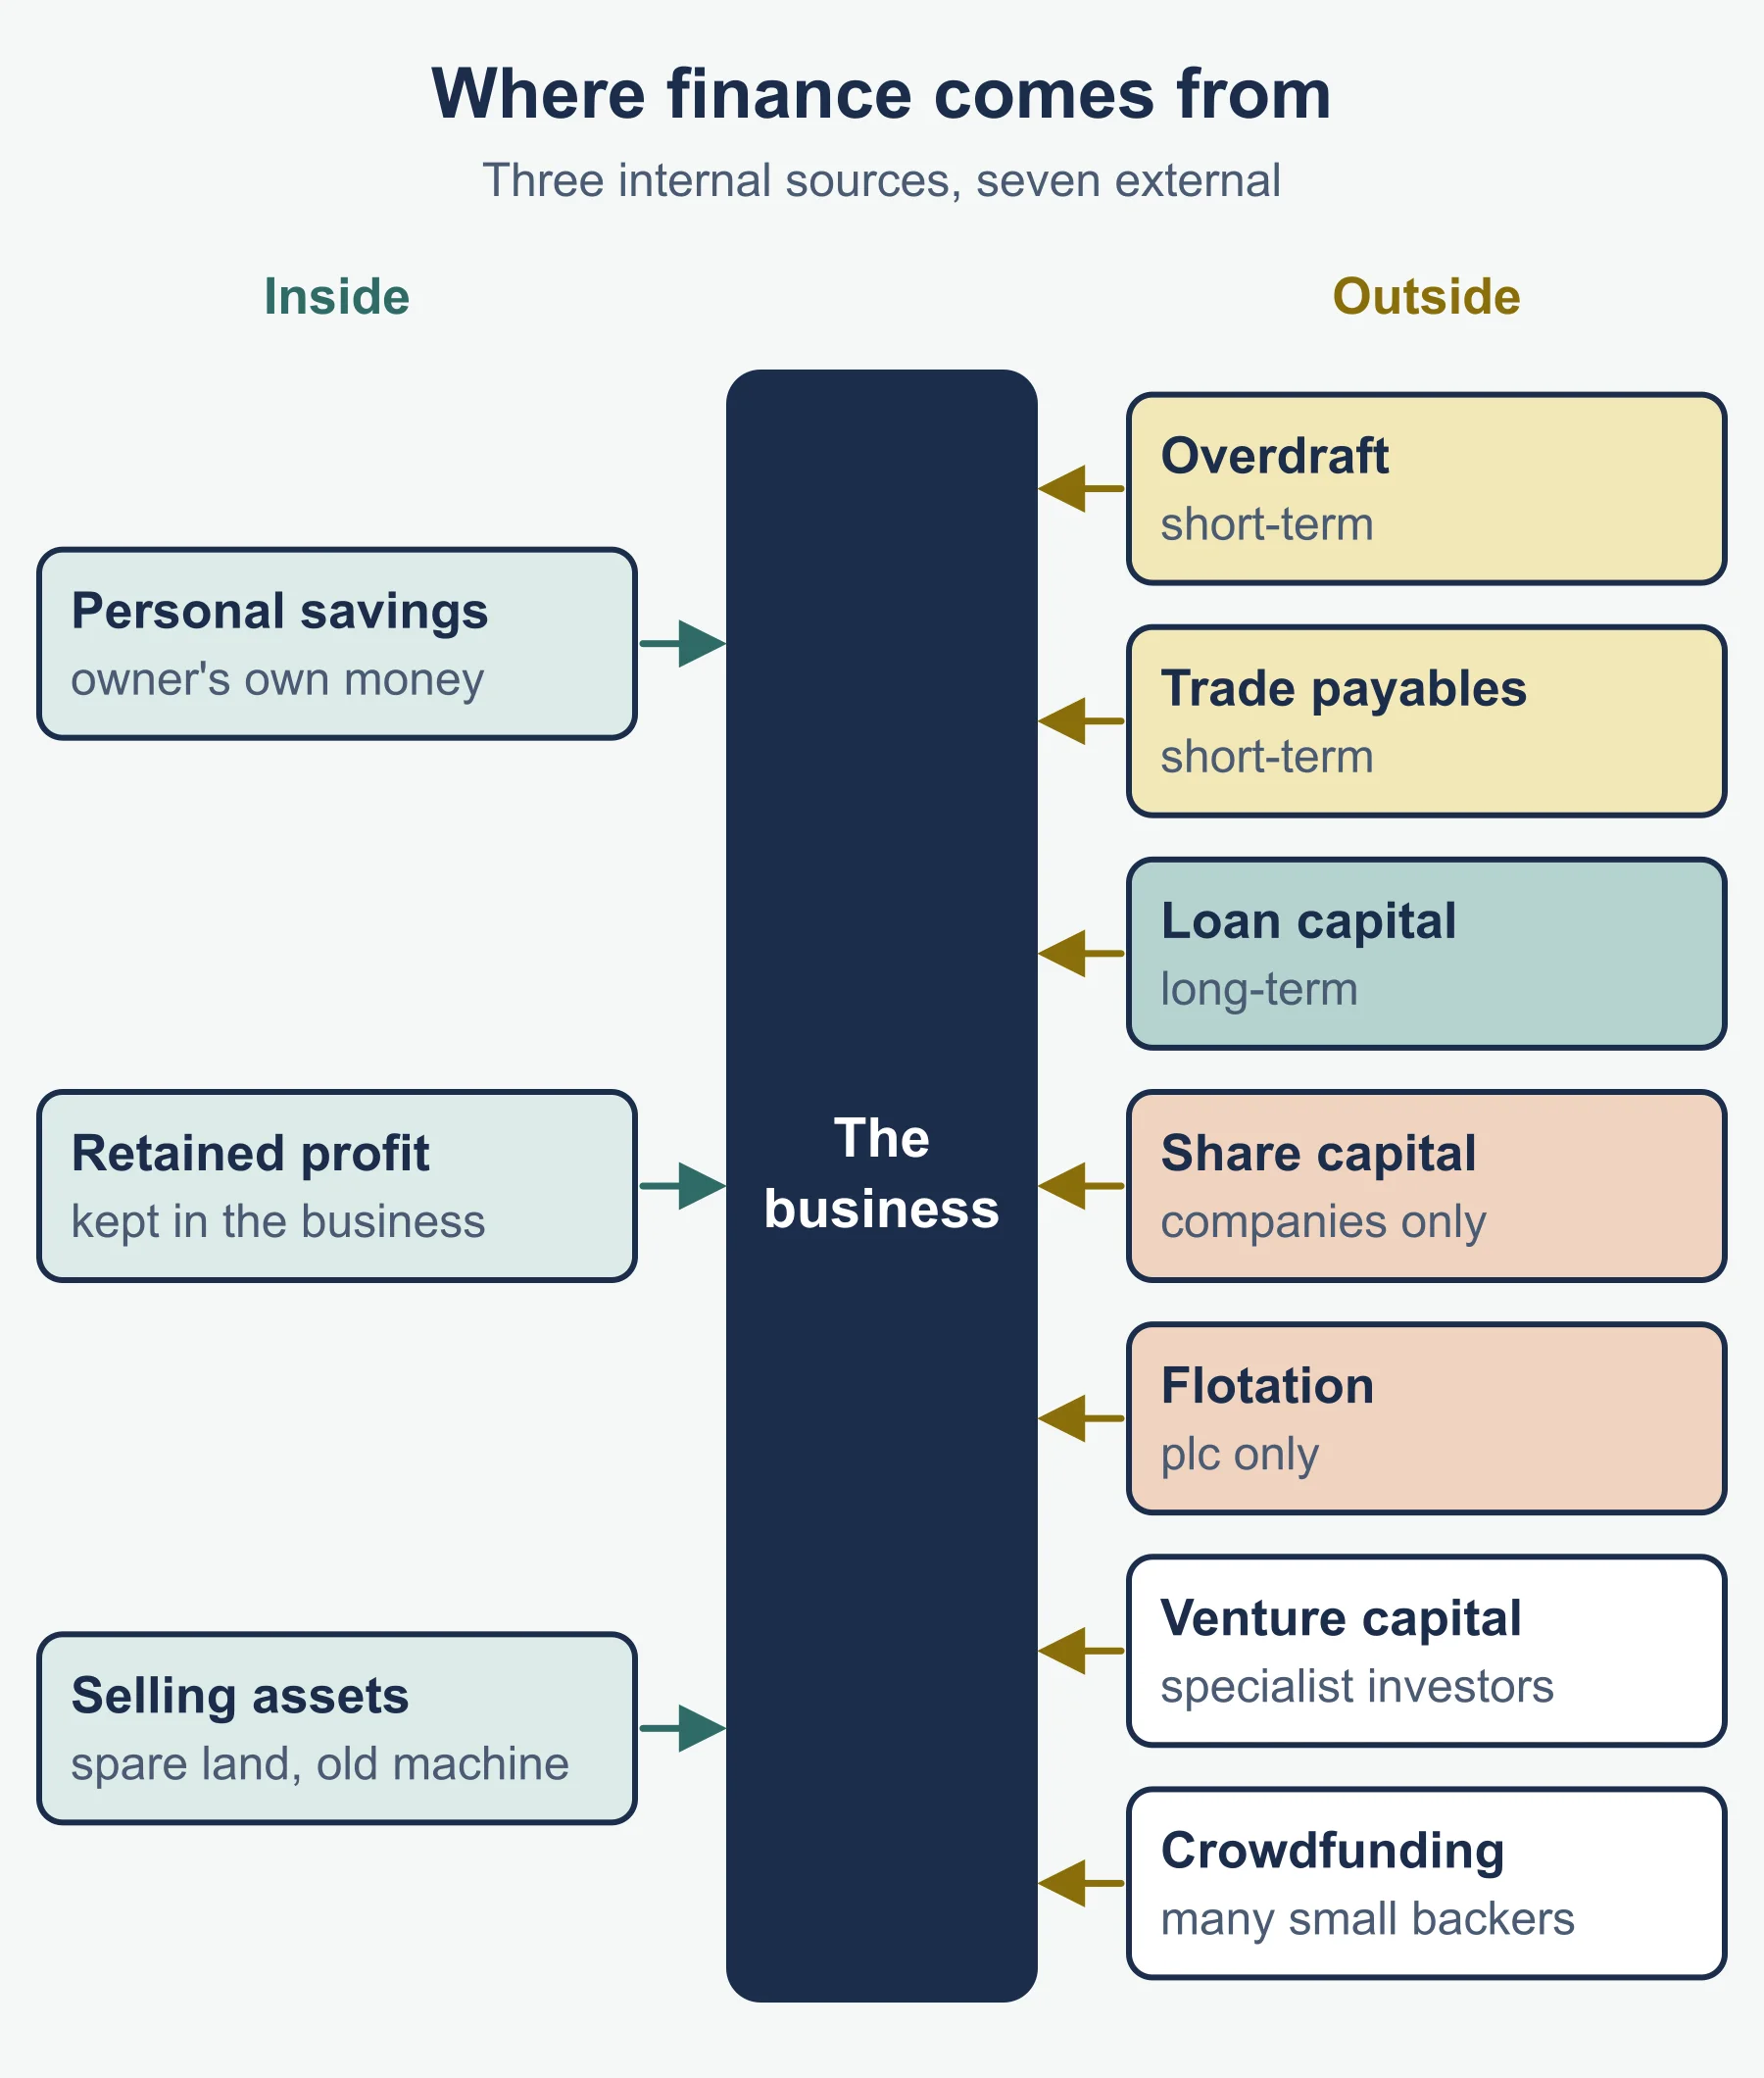
Internal finance comes from inside the business or from its owner.
- Personal savings. The owner puts in their own money. There is no interest to pay and no outsider gets a say, but the amount is limited, and the owner risks losing their own money if the business fails. Common at start-up.
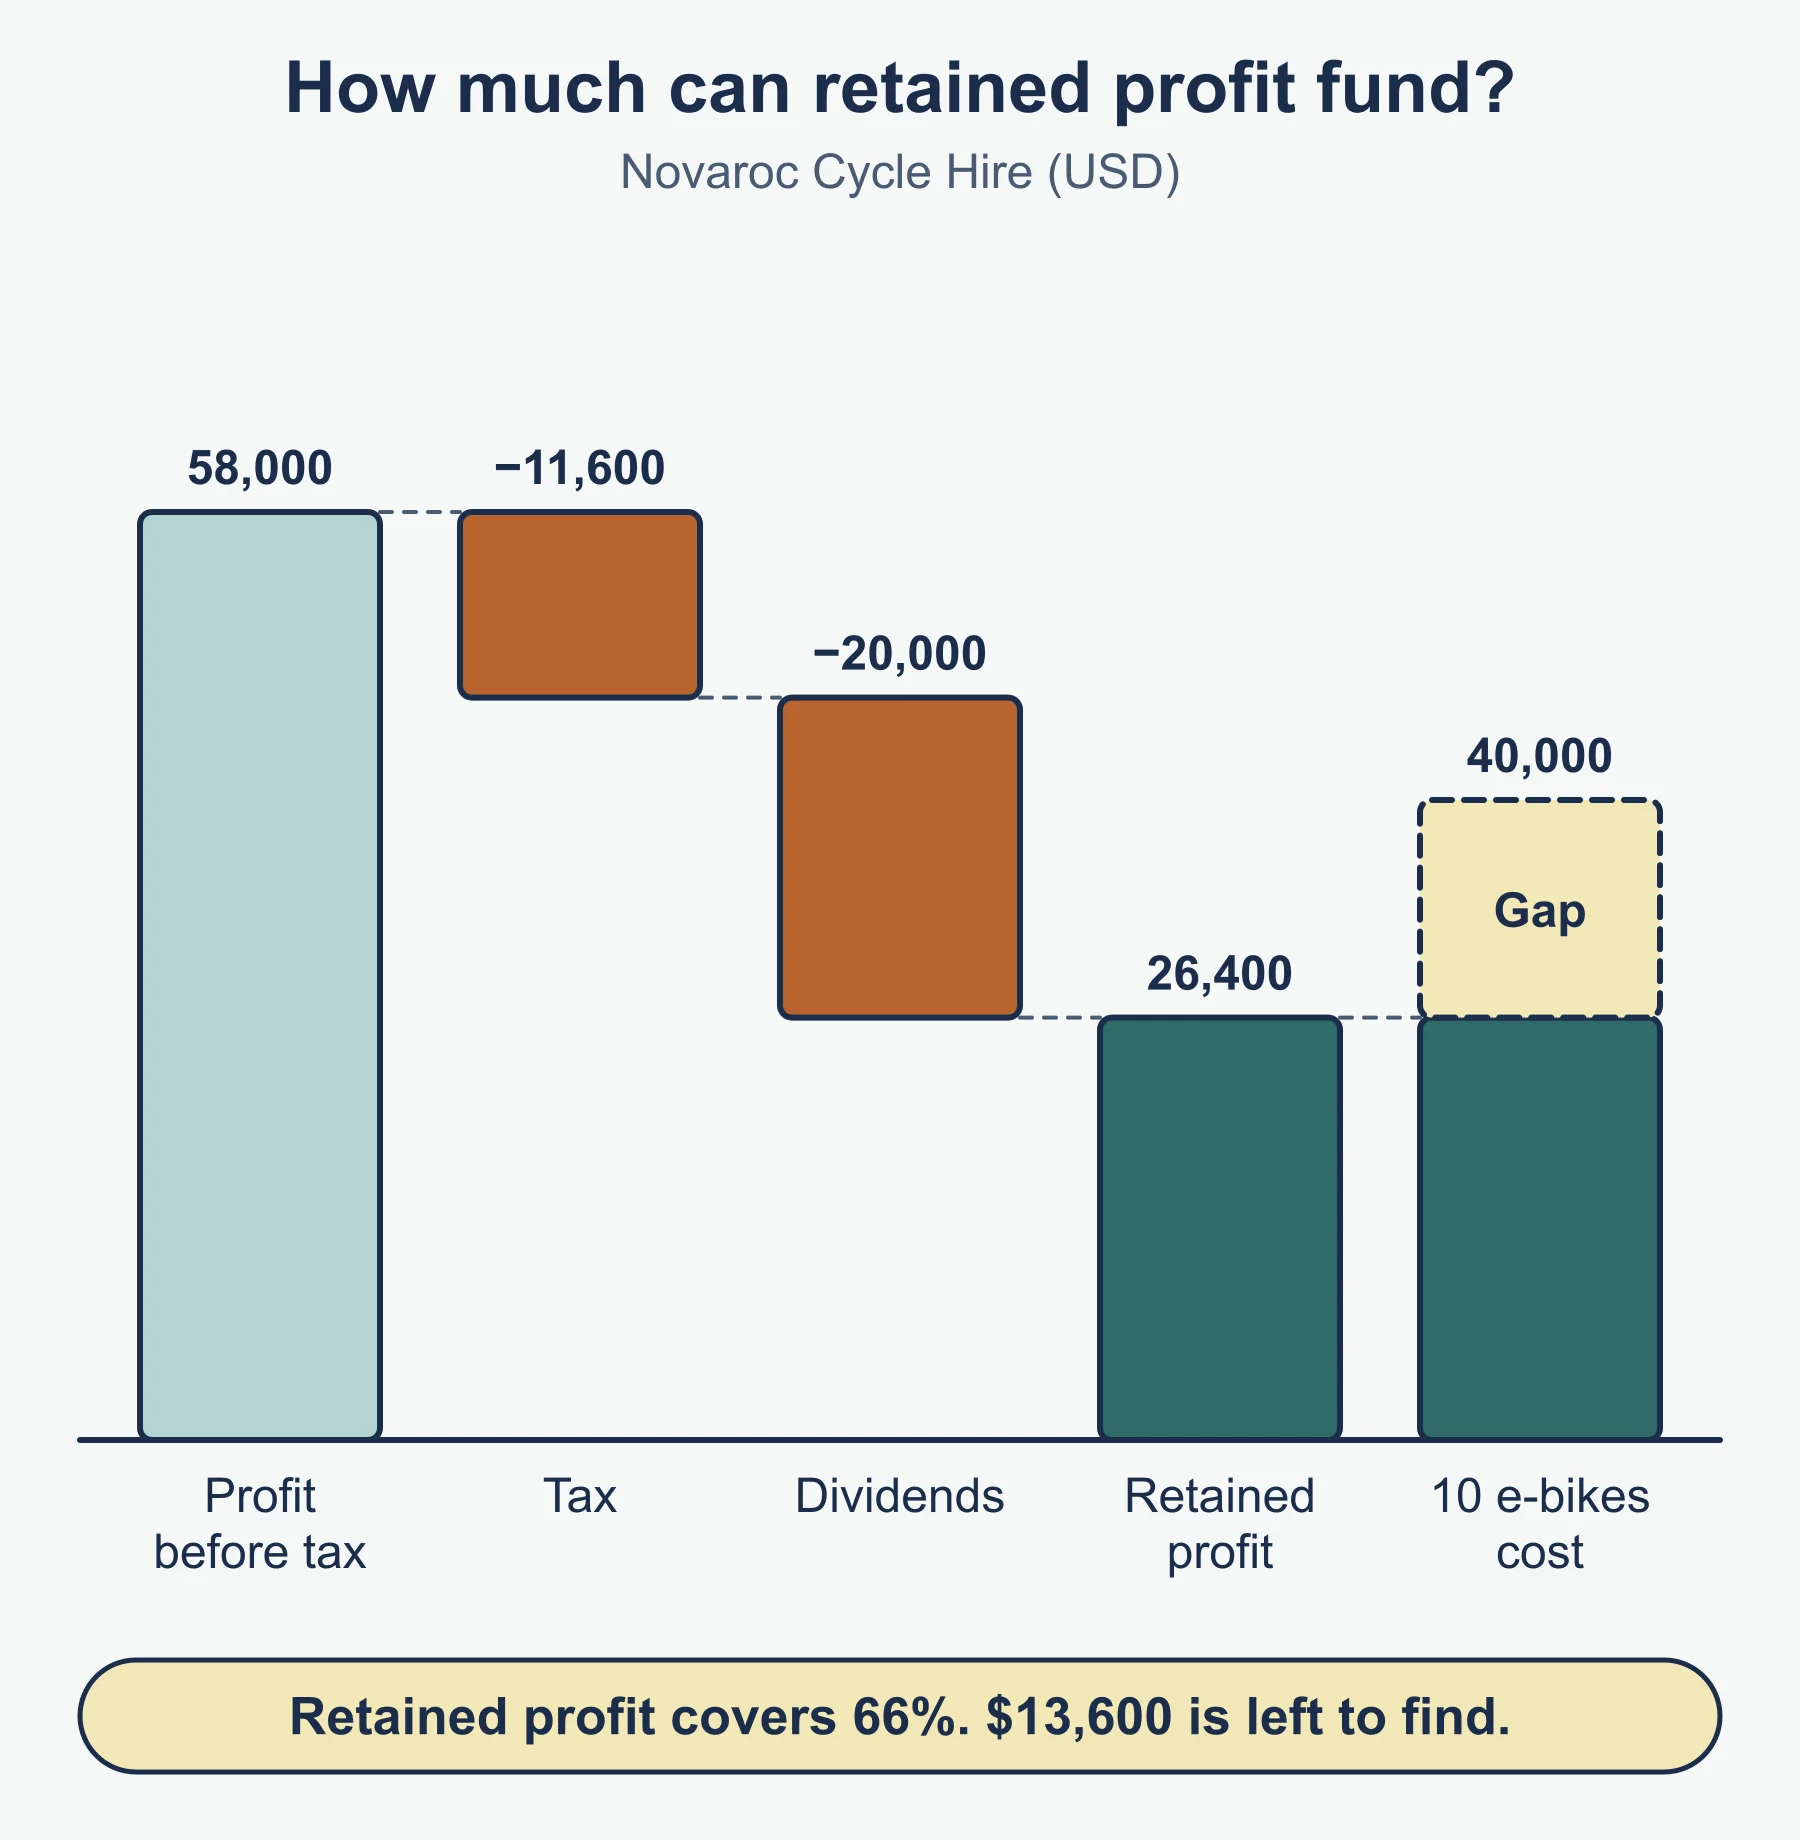
- Retained profit. Profit kept inside the business for reinvestment, once tax and any owners’ withdrawals or dividends have been taken out. It costs nothing to borrow, but a new business has no past profit to retain, and keeping profit in means owners or shareholders receive less now.
- Selling assets. The business sells something it owns, such as spare land or a machine it no longer uses, to raise cash. It can be quick and has no interest. The business loses the asset, which may harm output, and the price may disappoint.
3. External sources of finance (3.1.3)
External finance comes from people or organisations outside the business. The specification only names the sources. The descriptions, advantages and drawbacks below (overdraft, venture capital, crowdfunding, flotation costs and the rest) are standard business knowledge, not specification text.
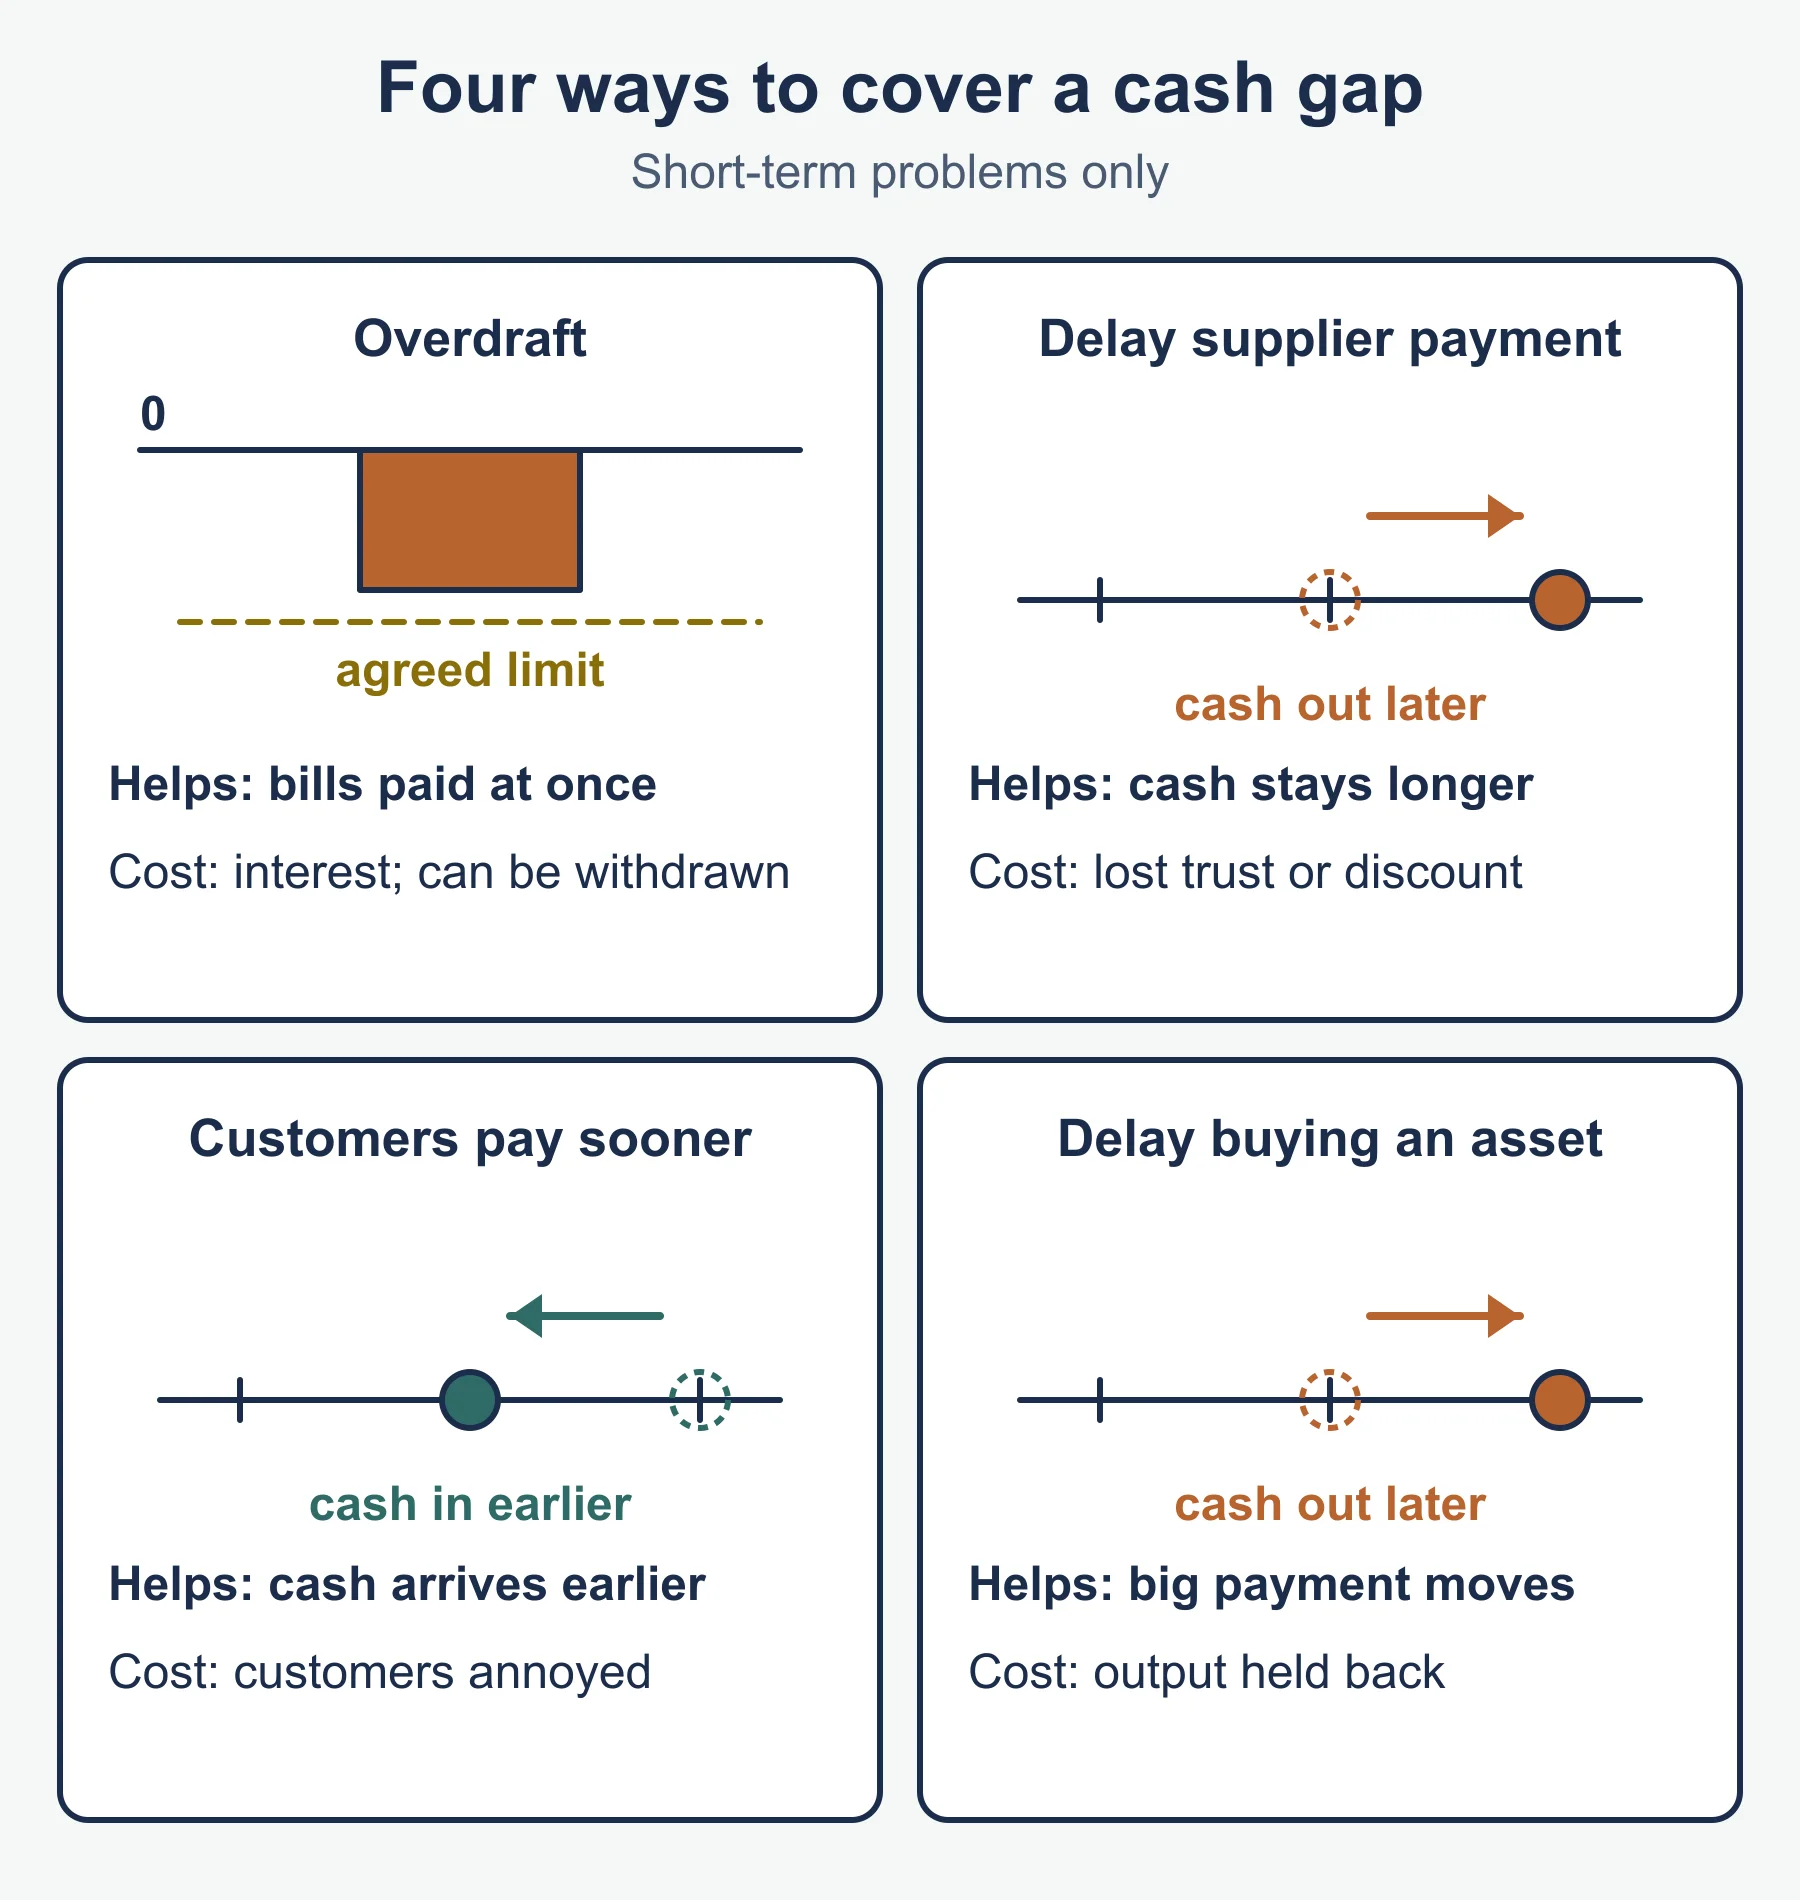
Overdraft. The bank lets the business take out more than it has in its account, up to an agreed limit. It is quick to set up and flexible, and the business pays interest on just the sum it borrows. It is aimed at short-term needs, the interest rate can be high, and the bank may demand repayment quickly. It is poorly suited to long-term needs.
Trade payables. Suppliers deliver goods now and the business pays later, for example in 30 days. This is a free, short-term source of finance, because the business holds on to its cash for longer. The risk is that a supplier may refuse future credit or lose goodwill, and a prompt-payment discount is missed.
Loan capital. Money borrowed from a bank or other lender and repaid over an agreed period with interest. It suits long-term needs and the lender does not take ownership. The business must make repayments even in a bad month, the interest adds to costs, and lenders may ask for security (an asset they can claim if the loan is not repaid).
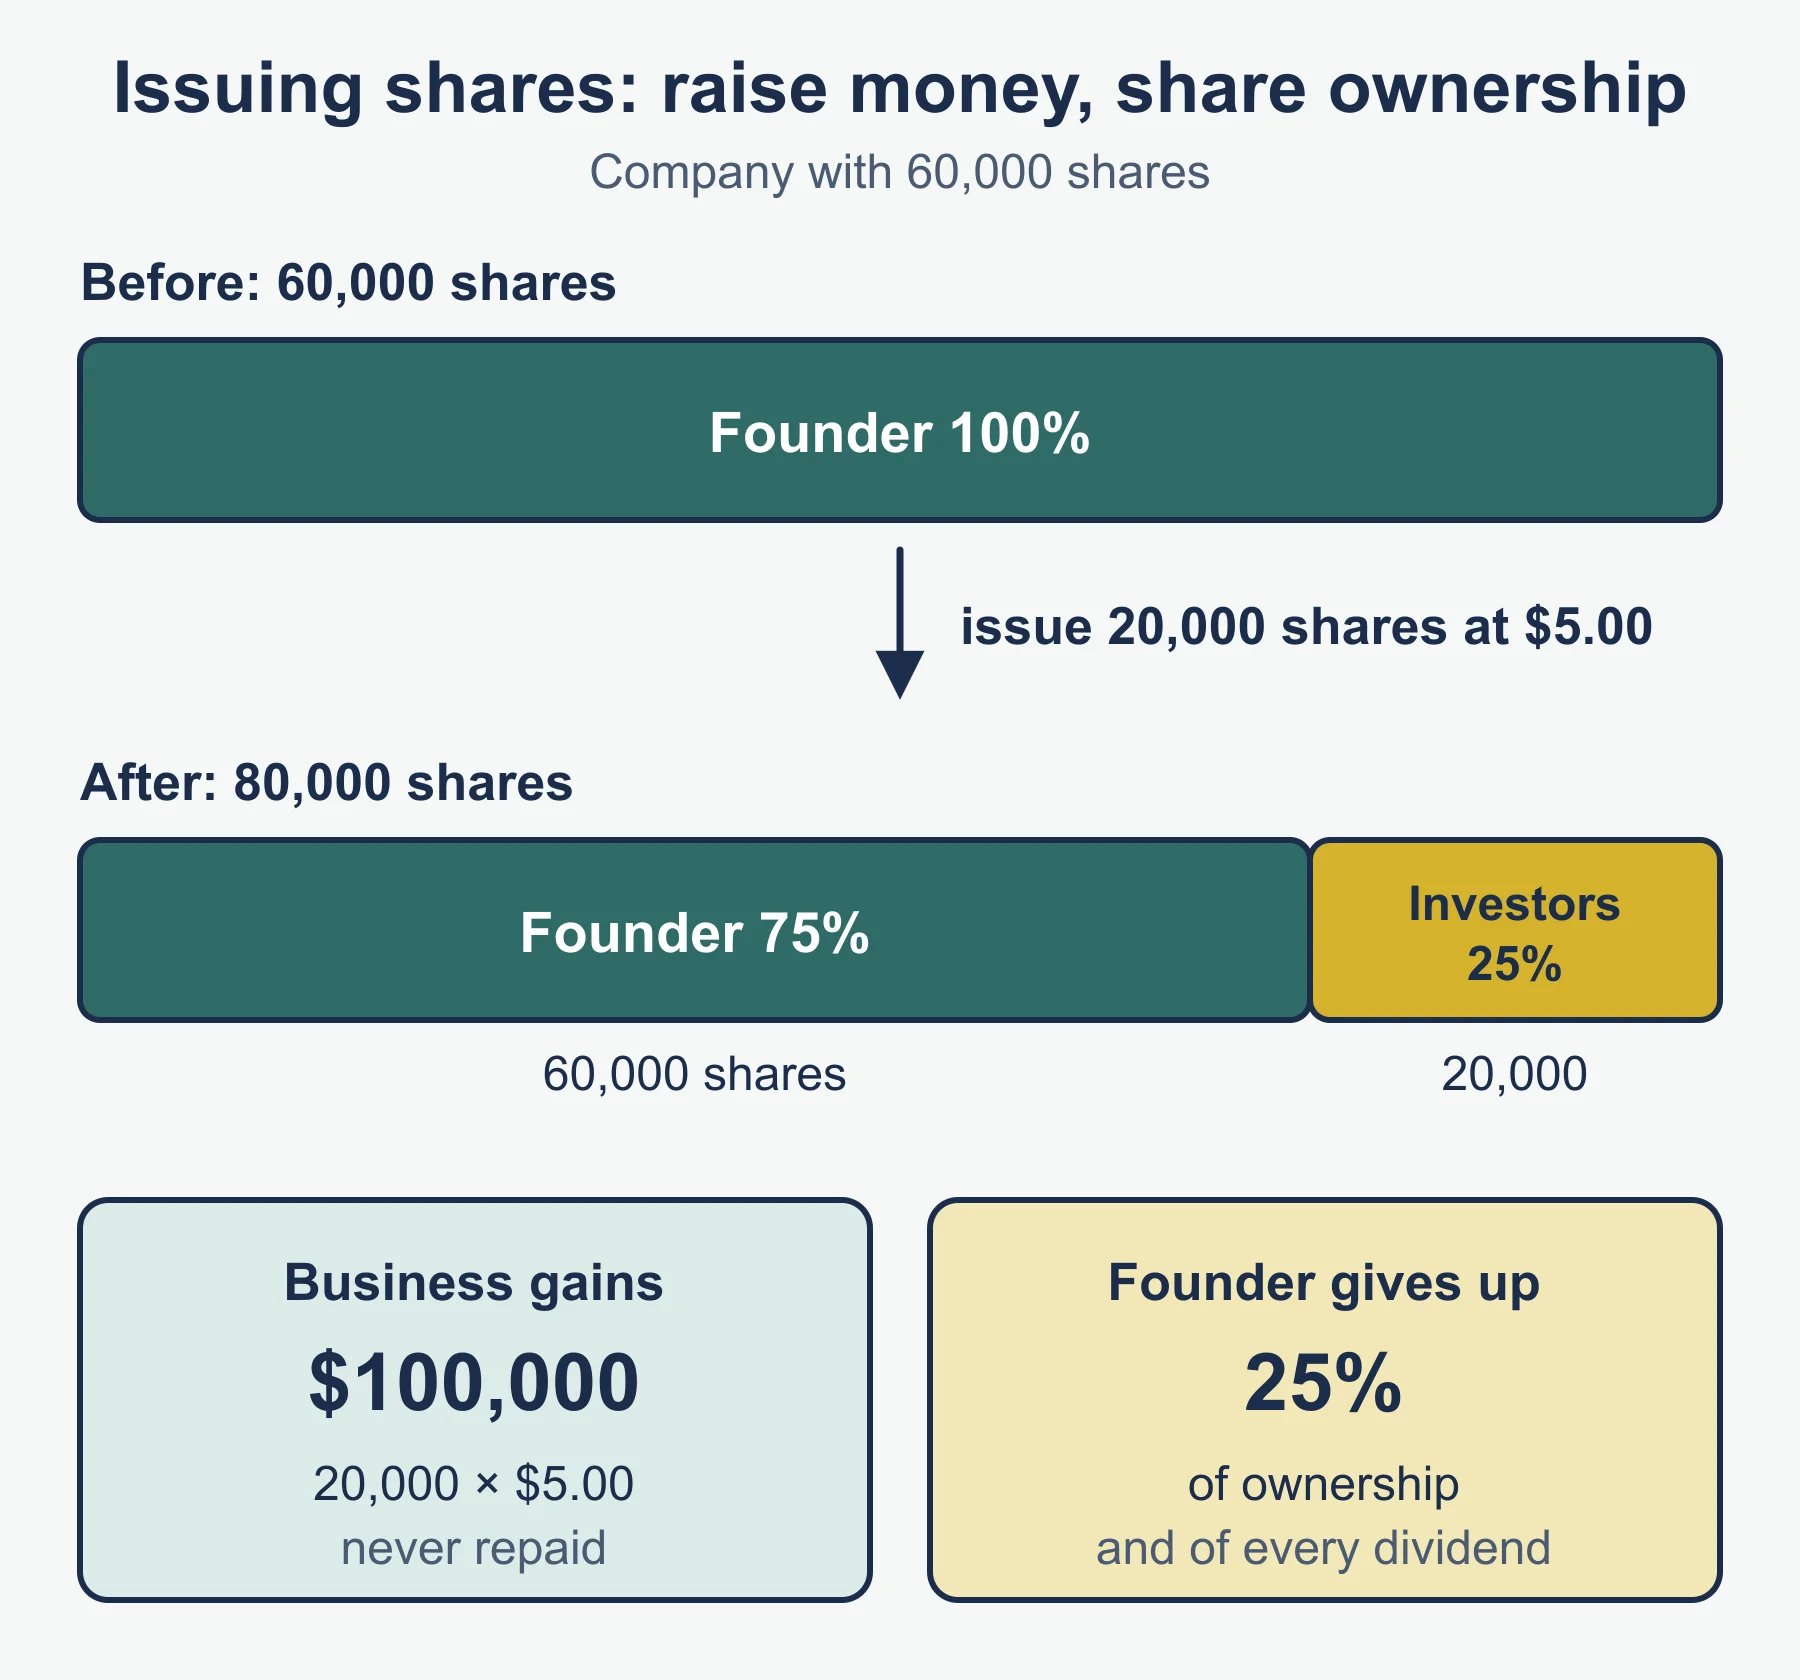
Share capital. Money raised by a company selling shares. Shareholders become part-owners and are paid a share of profit as dividends. There is no repayment date and no interest. The drawbacks are that ownership and control are shared and the dividends reduce the profit that is left to the owners. Only companies can issue shares, which is why a sole trader or partnership cannot use this source.
Stock market flotation (public limited companies). A plc (public limited company) may sell its shares to the general public through a stock market. This can raise very large sums, so it suits big expansion. The costs and the amount of legal and reporting work are high, ownership is spread more widely, and shareholders can sell their shares to others, so a takeover becomes possible.
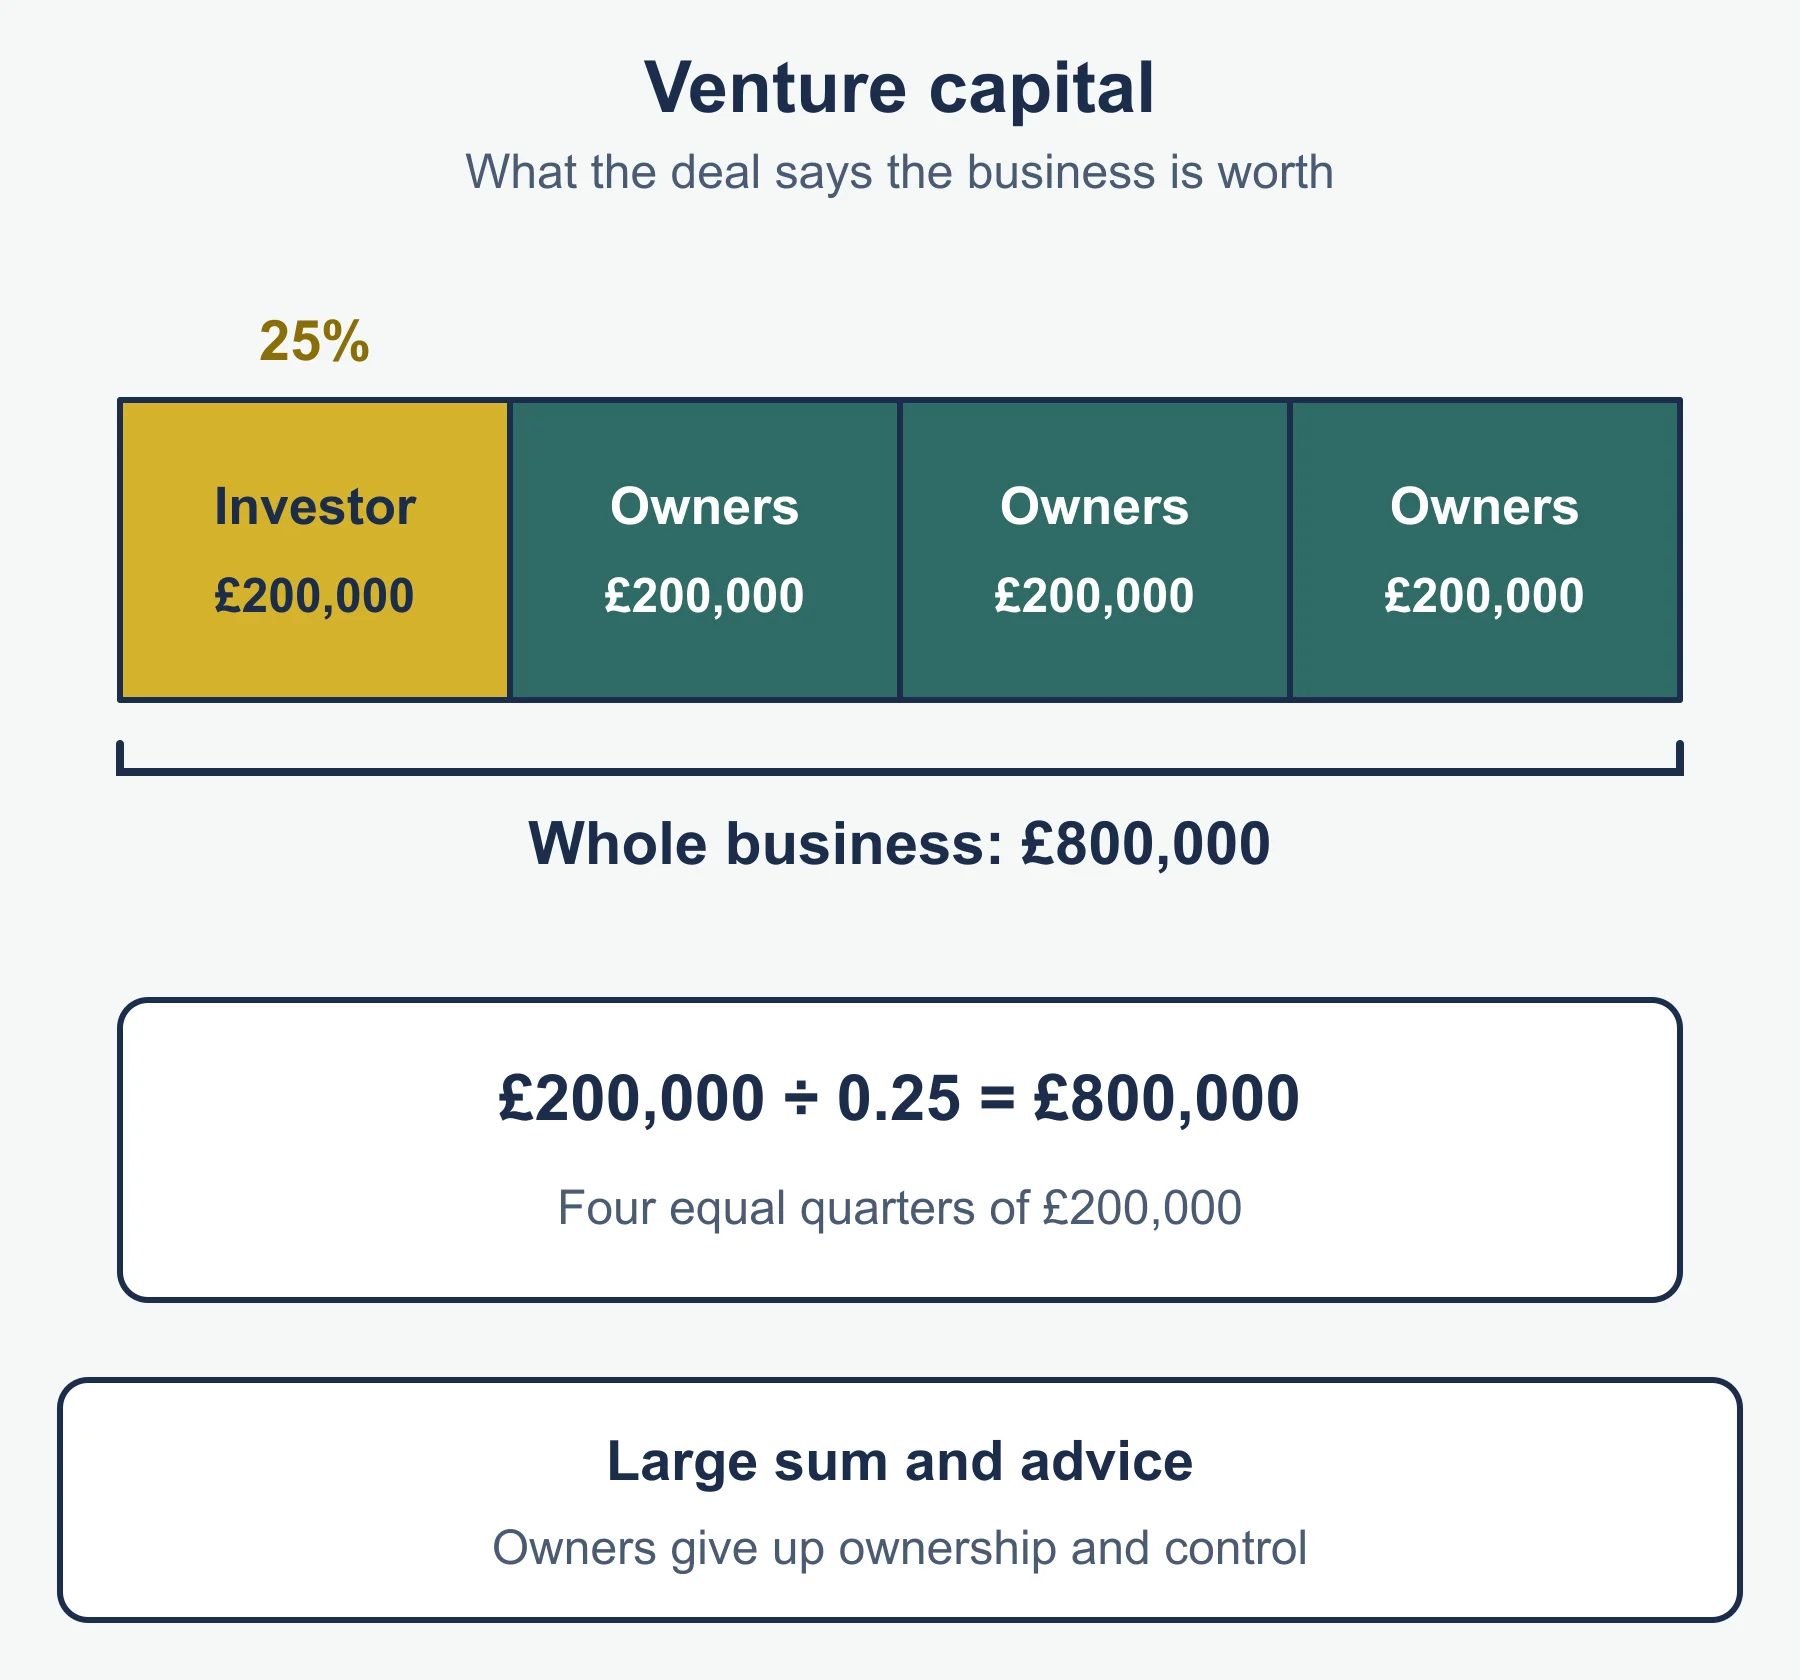
Venture capital. Investment by specialist investors, often into young businesses with growth potential, usually in return for a share of the ownership. It can supply large sums when banks think the risk is too high, and the investors often bring advice and contacts. The owner gives up part of the business and some control, and investors expect a good return.
Crowdfunding. Many people each give a modest sum, normally via a website, to back an idea. Depending on the scheme, backers may receive a product, a share in the business or nothing but thanks. It tests demand and does not need a bank. Running a campaign takes effort, and a project that misses its target may get nothing.
Worked example: choosing a source
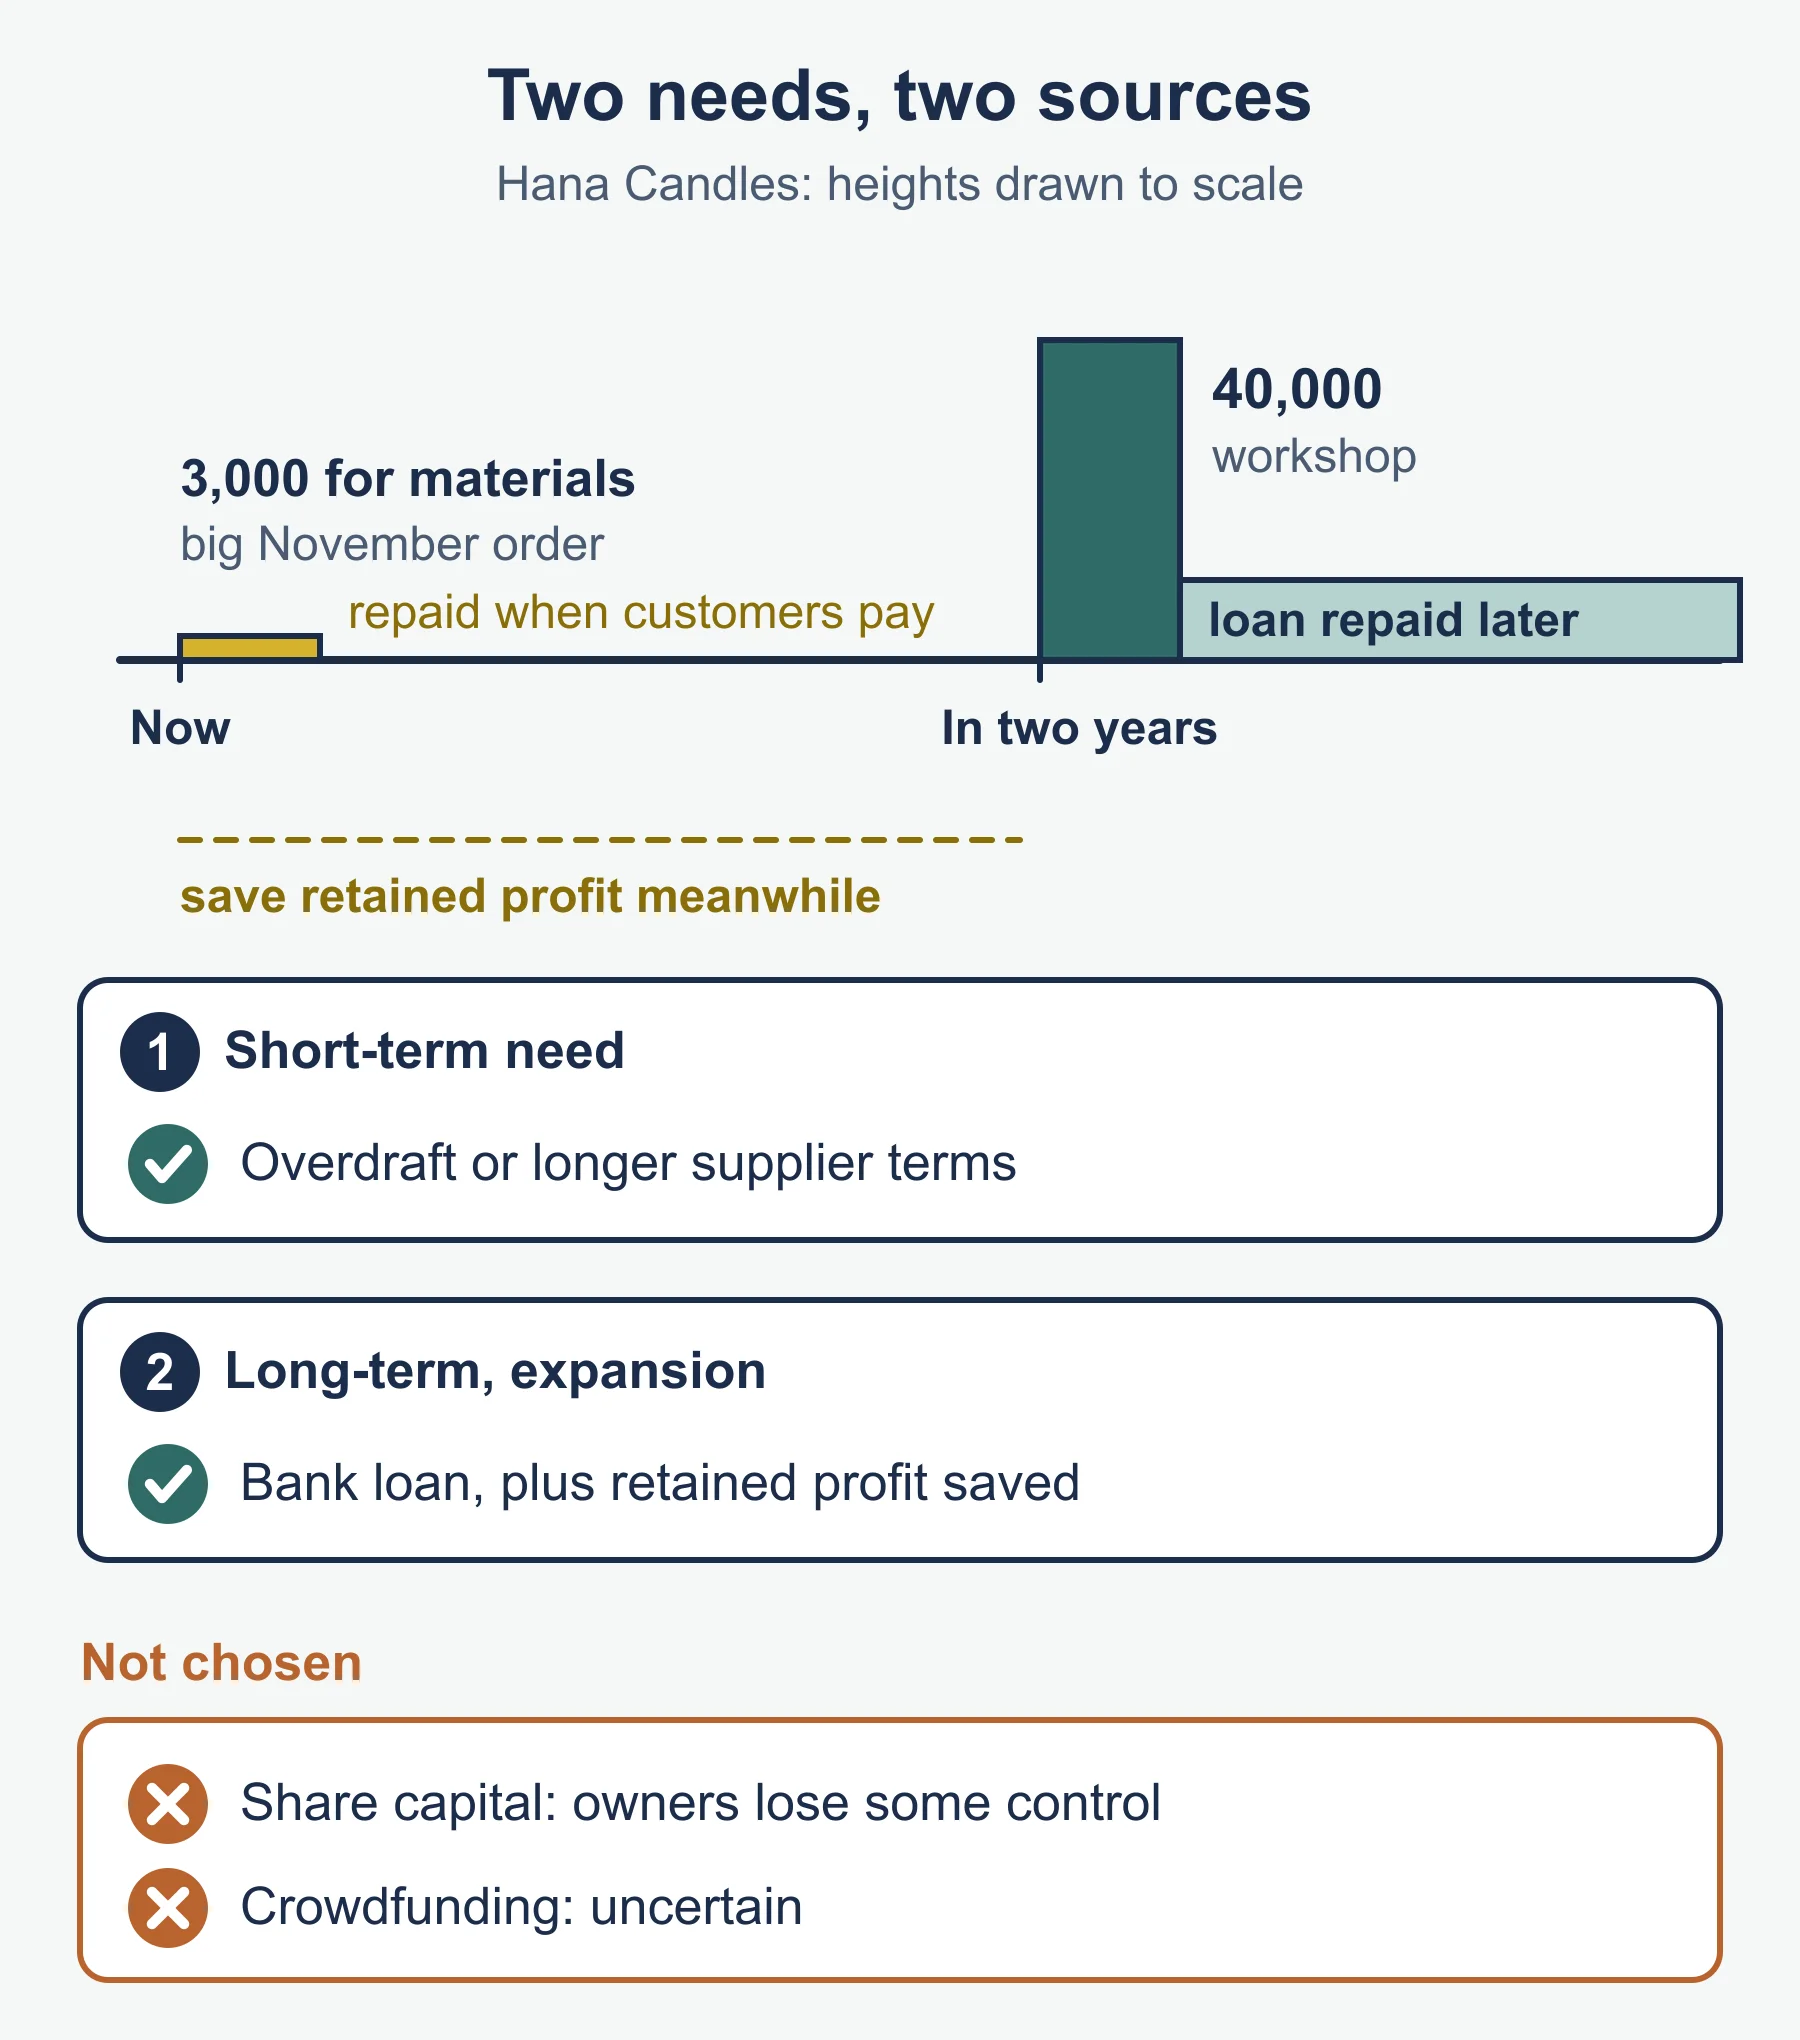
Hana Candles is a two-person business. It needs 3,000 to cover materials for a big November order, then wants 40,000 to open a workshop in two years’ time.
For the first need, a short-term one, an overdraft or longer payment terms with suppliers fit: the money is needed briefly and repaid when customers pay. For the second, a long-term and expansion need, a bank loan repaid over several years fits better, possibly alongside retained profit saved up beforehand. Share capital would dilute the owners’ control, and crowdfunding is uncertain.
4. Why cash matters (3.2.1)
Cash means the money the business actually has, in the till and the bank. It is used:
- to pay suppliers for goods and materials,
- to pay overheads such as rent, electricity and insurance,
- to pay employees their wages.
If a business cannot pay these when they fall due, suppliers stop supplying, staff leave and the business may be forced to close. A business that is unable to meet its debts on time is insolvent. The specification names preventing business failure (insolvency) as a reason cash matters: a business can fail through running out of cash even when it is selling well.
5. Cash and profit are different (3.2.1)
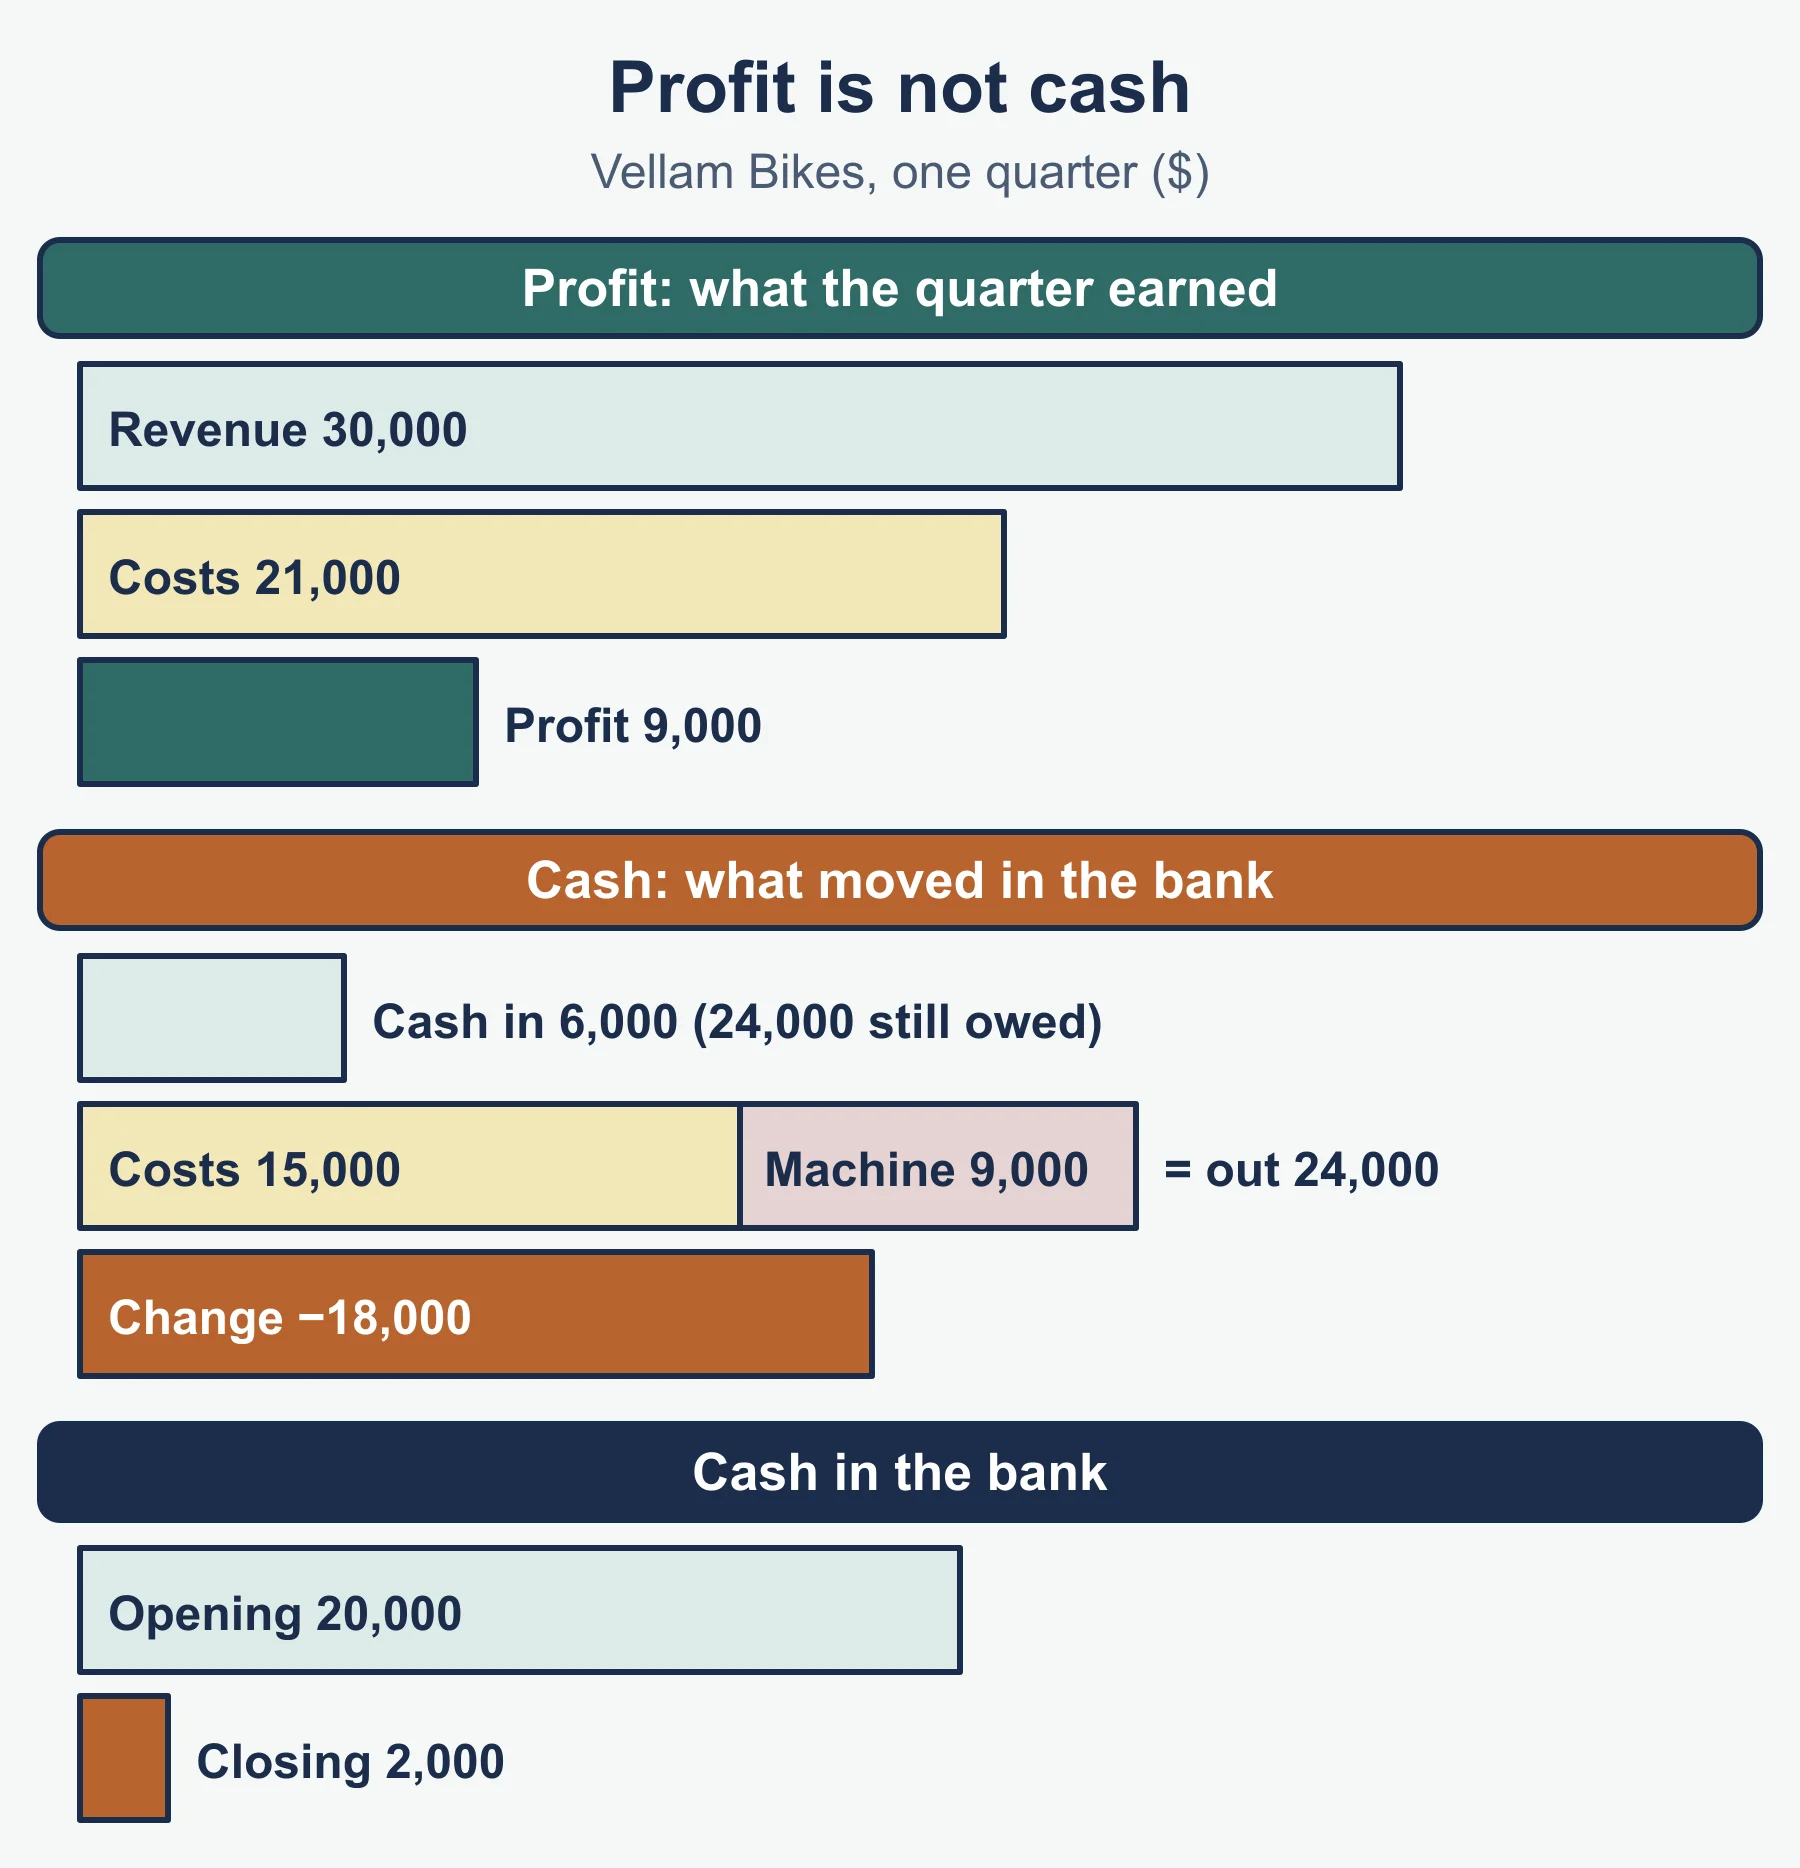
Profit is the difference between sales revenue and costs over a period. Cash is what has actually been received and paid. The two differ because of timing and because some payments are not costs of that period.
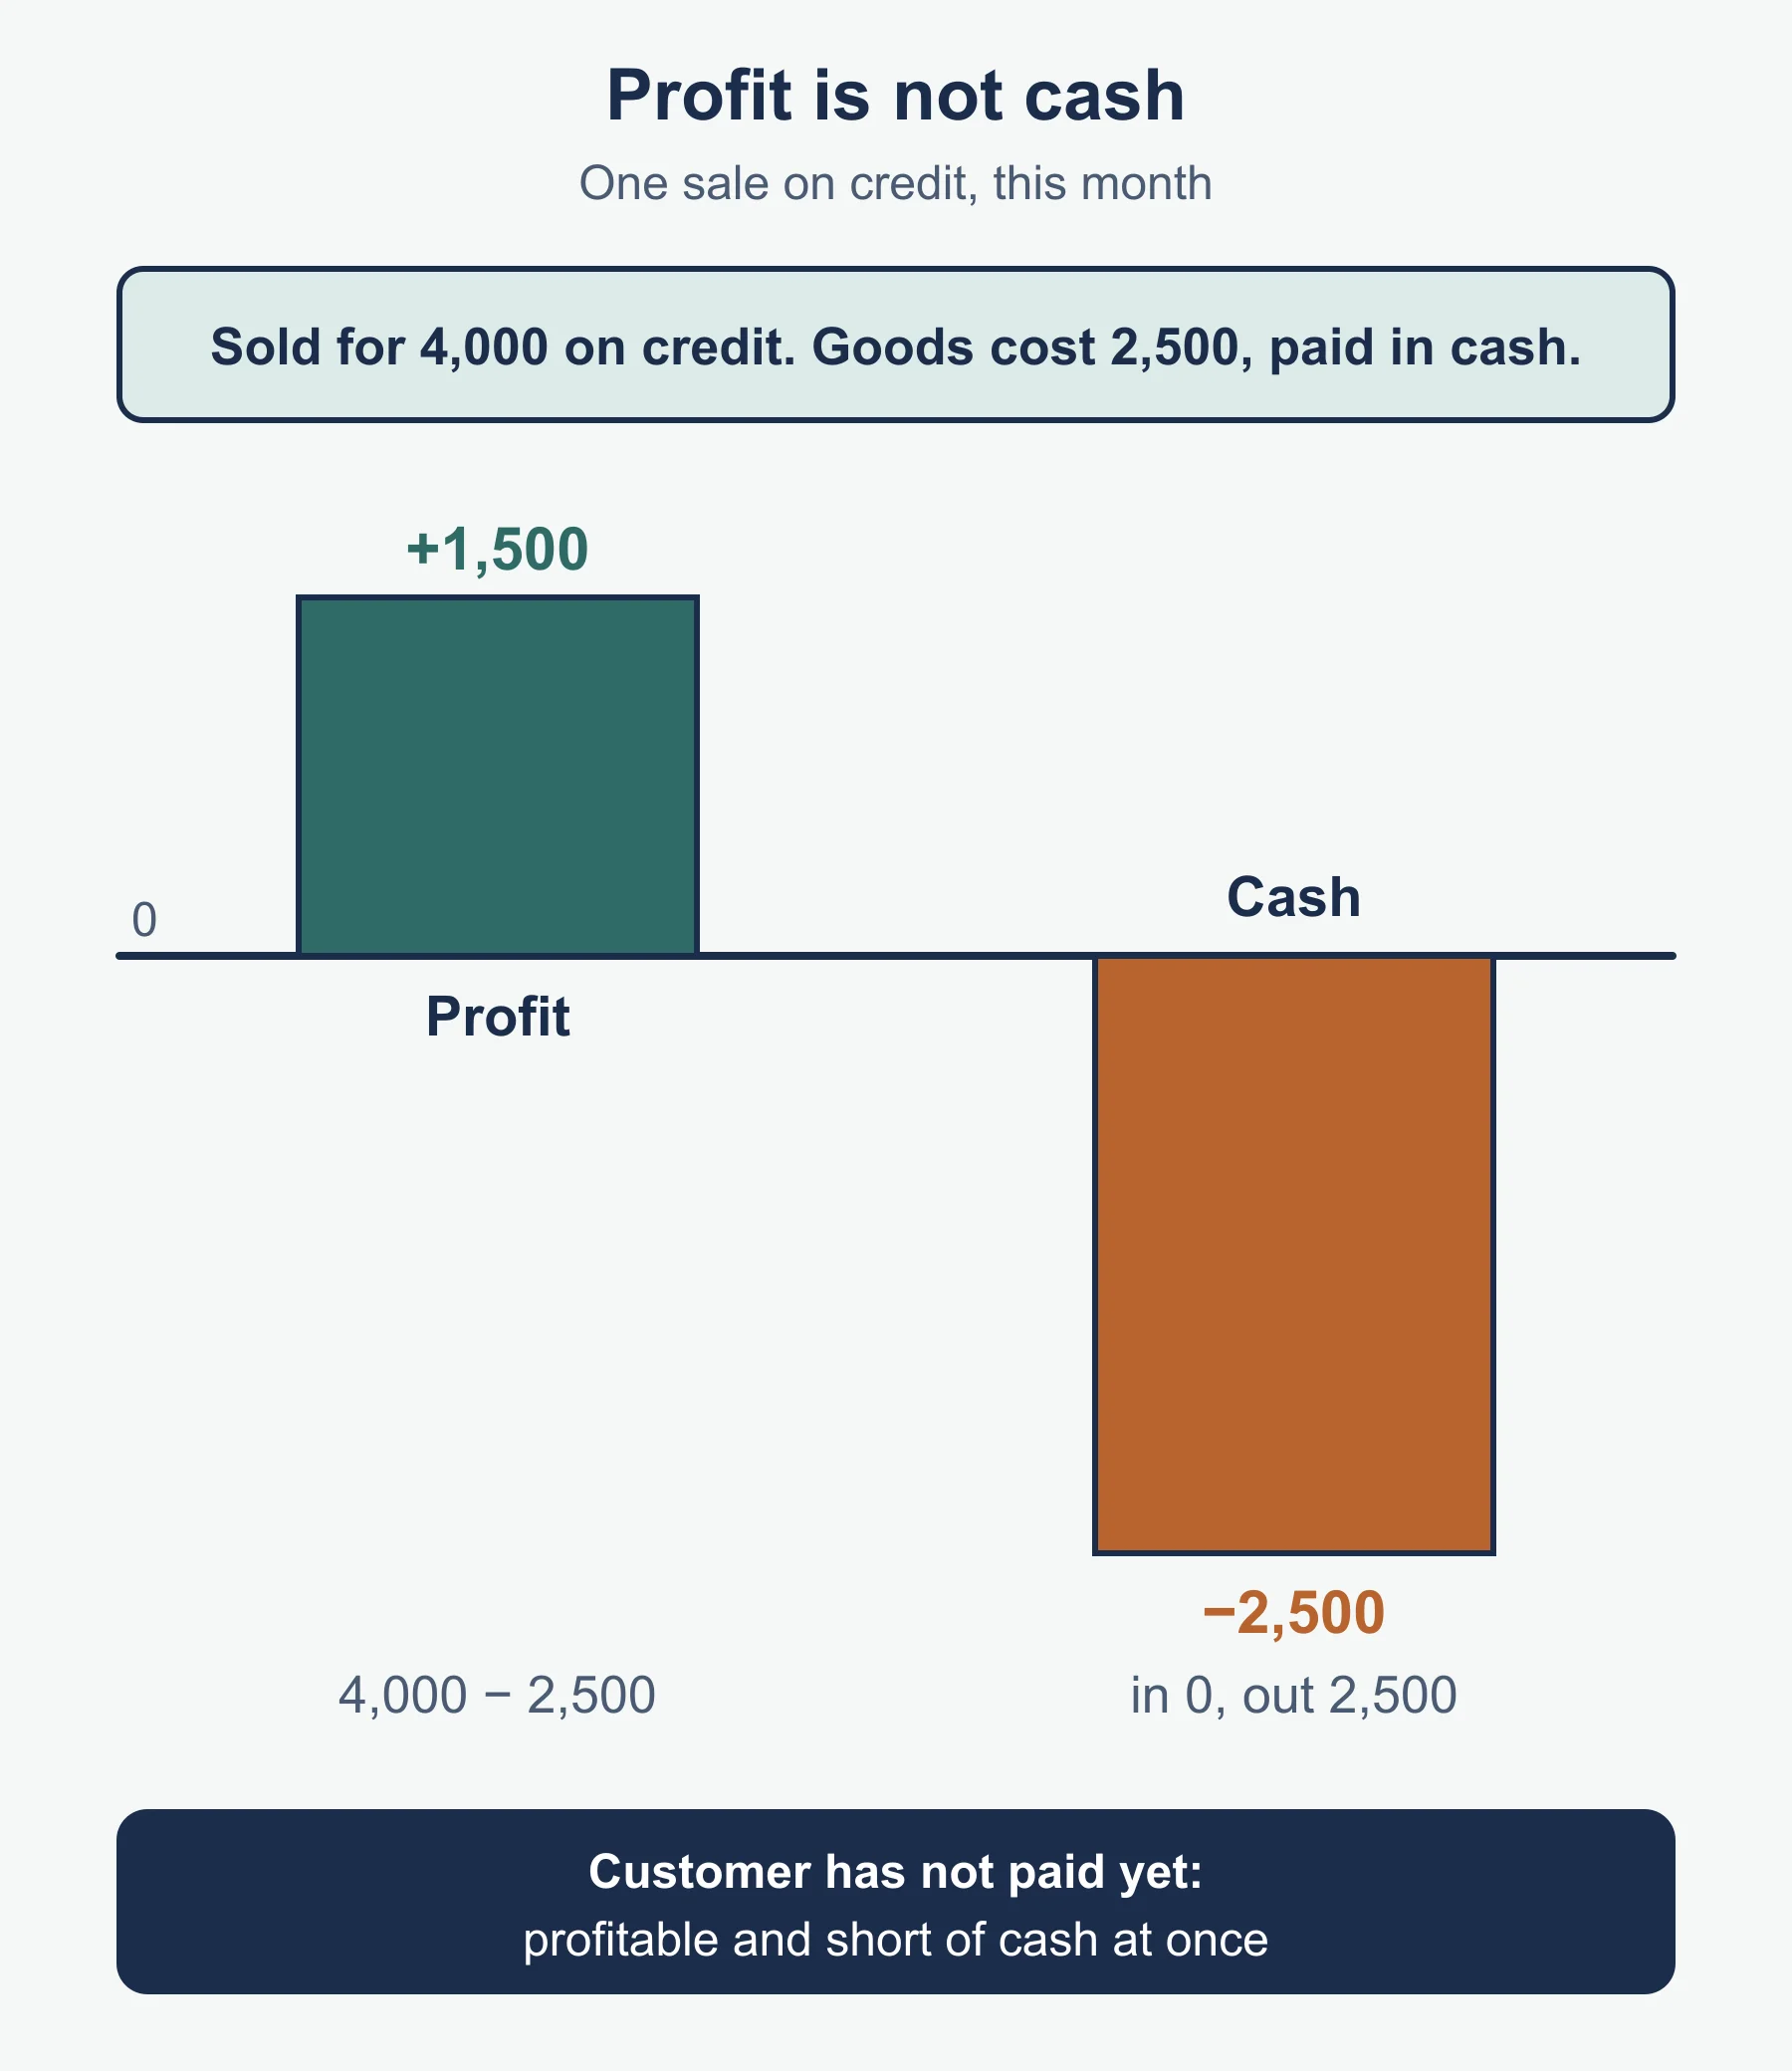
Worked contrast. A workshop sells goods for 4,000 on credit this month, and the goods cost 2,500, paid in cash this month. Profit on the sale is 4,000 - 2,500 = 1,500. But the customer has not paid yet, so the cash movement this month is -2,500. The business is “profitable” and short of cash at once.
Other causes of the gap: a machine bought for 6,000 reduces cash by 6,000 at once, while its cost to profit is spread over its life; a loan received increases cash but is not profit; late-paying customers and unsold bulk inventory tie up cash.
A business can therefore make a profit and run out of cash, or make a loss and still have a healthy bank balance for a while, for example after selling an asset.
6. Building a cash-flow forecast (3.2.2)
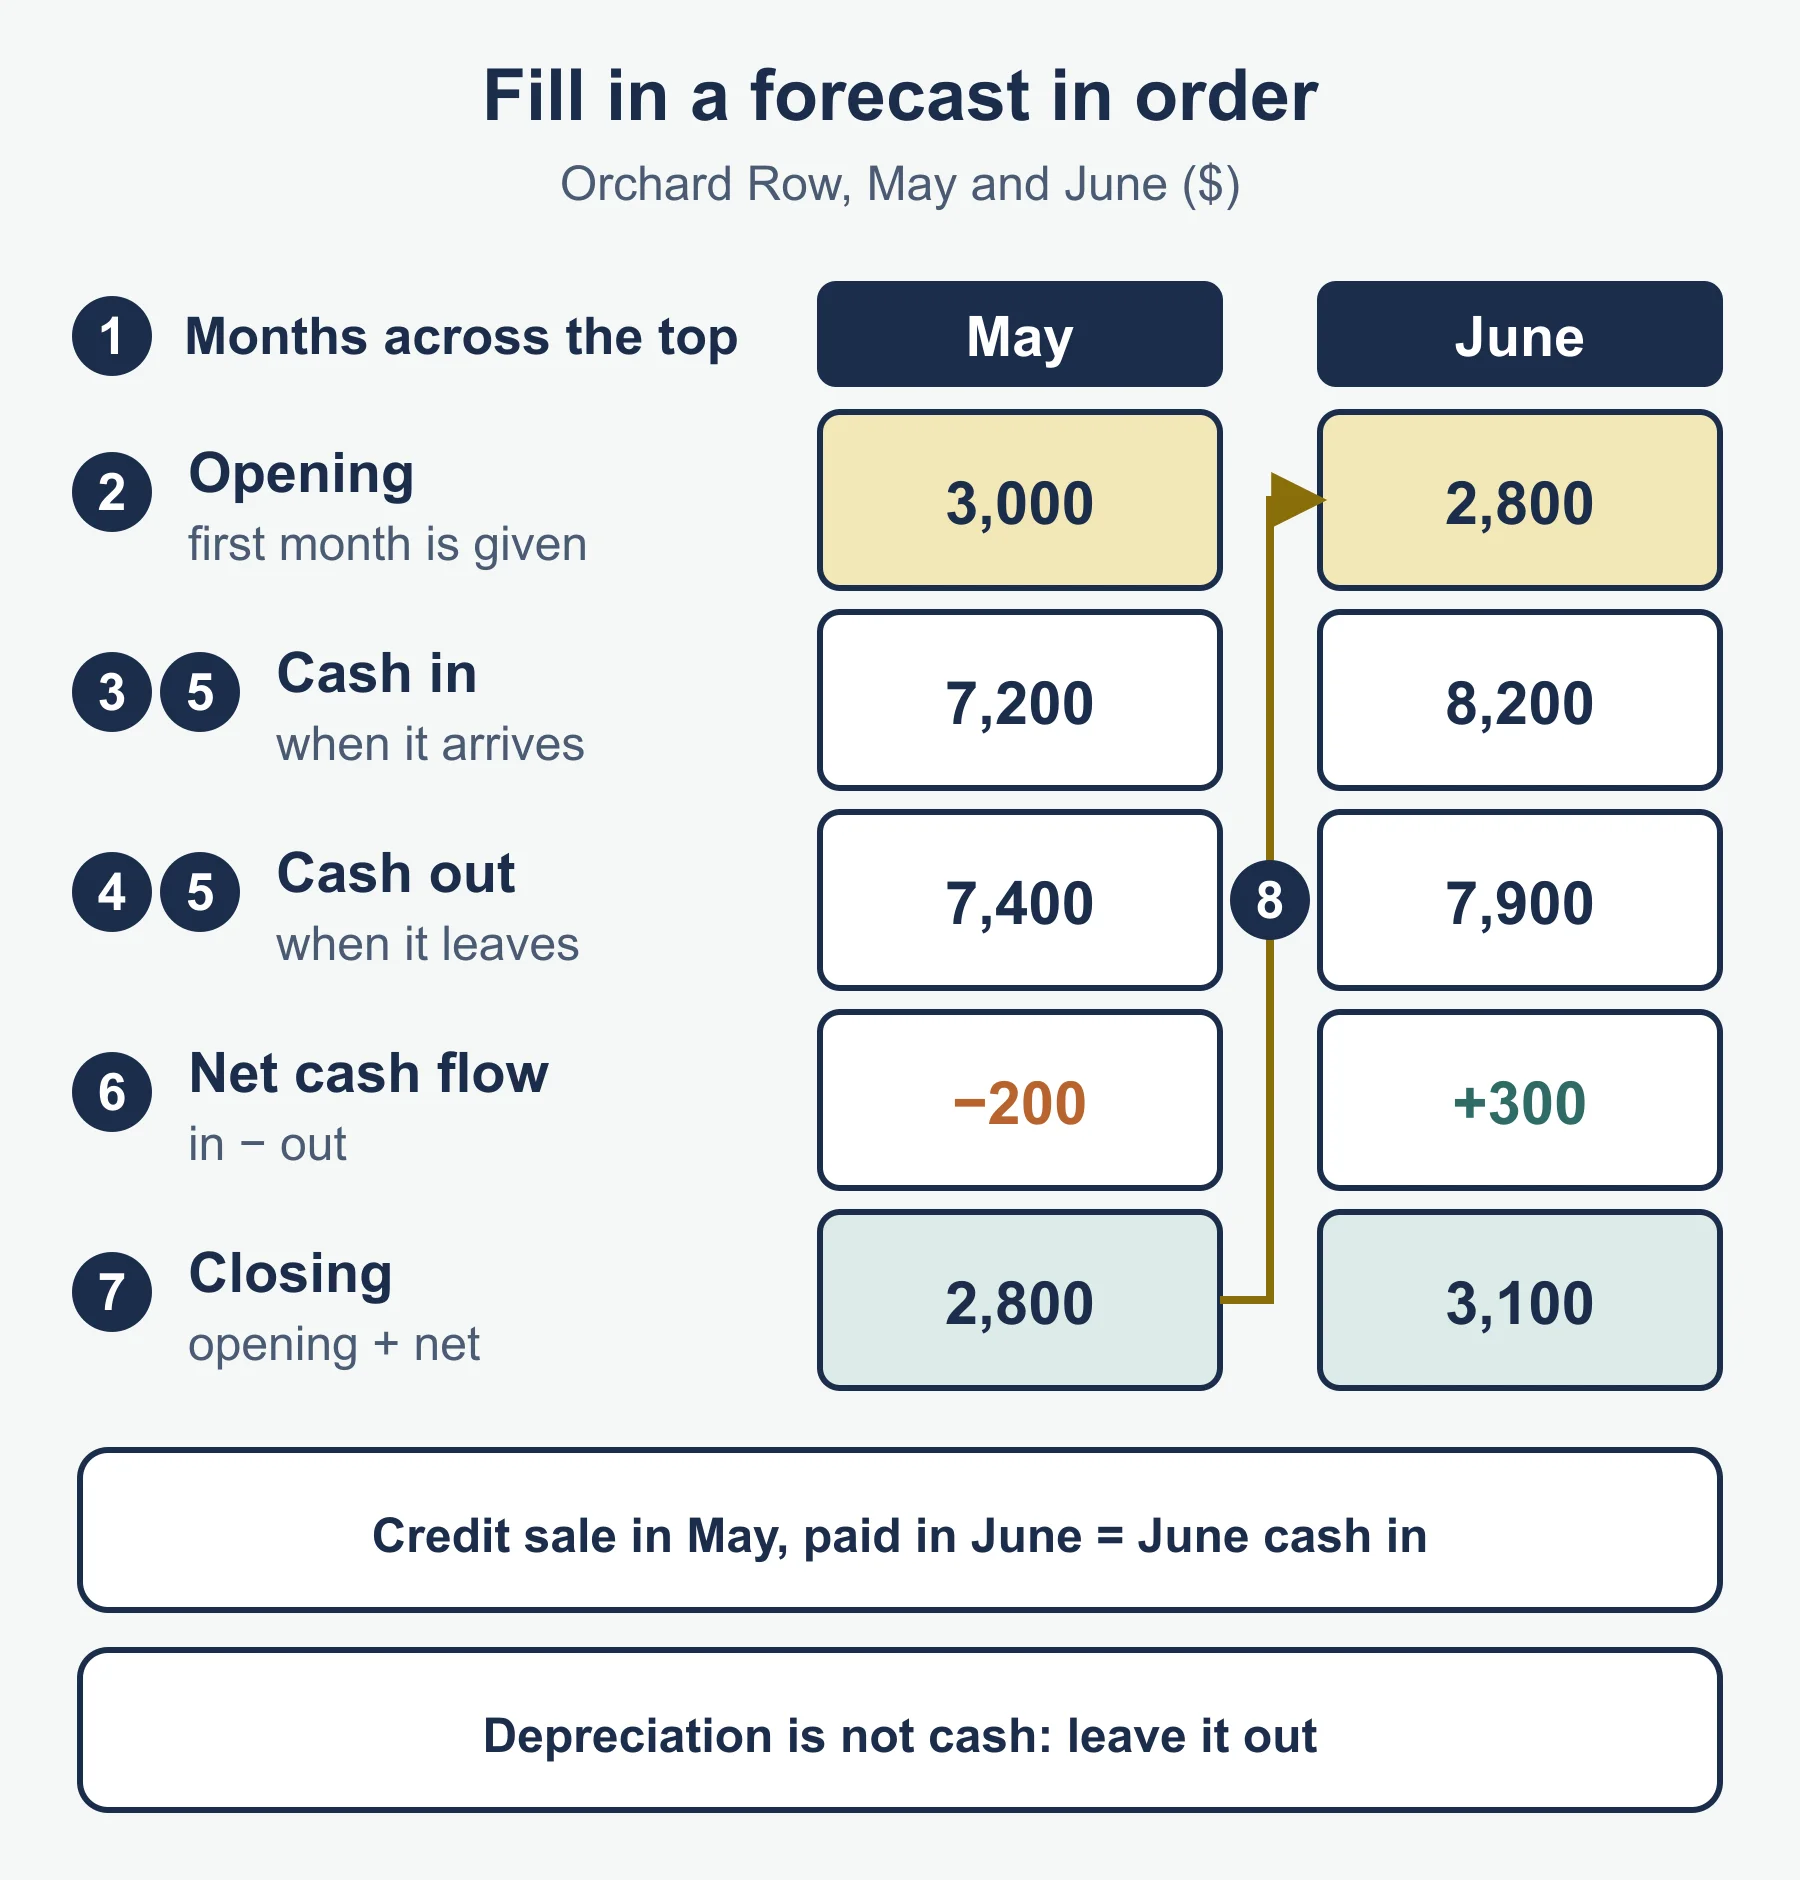
A cash-flow forecast is a prediction, usually month by month, of the money expected to come in and go out. Its parts, as the specification lists them:
- Cash inflows: money coming in, for example cash sales, customer payments, a loan or capital put in by the owner.
- Cash outflows: money paid out, such as materials, wages, rent, equipment purchases and loan repayments.
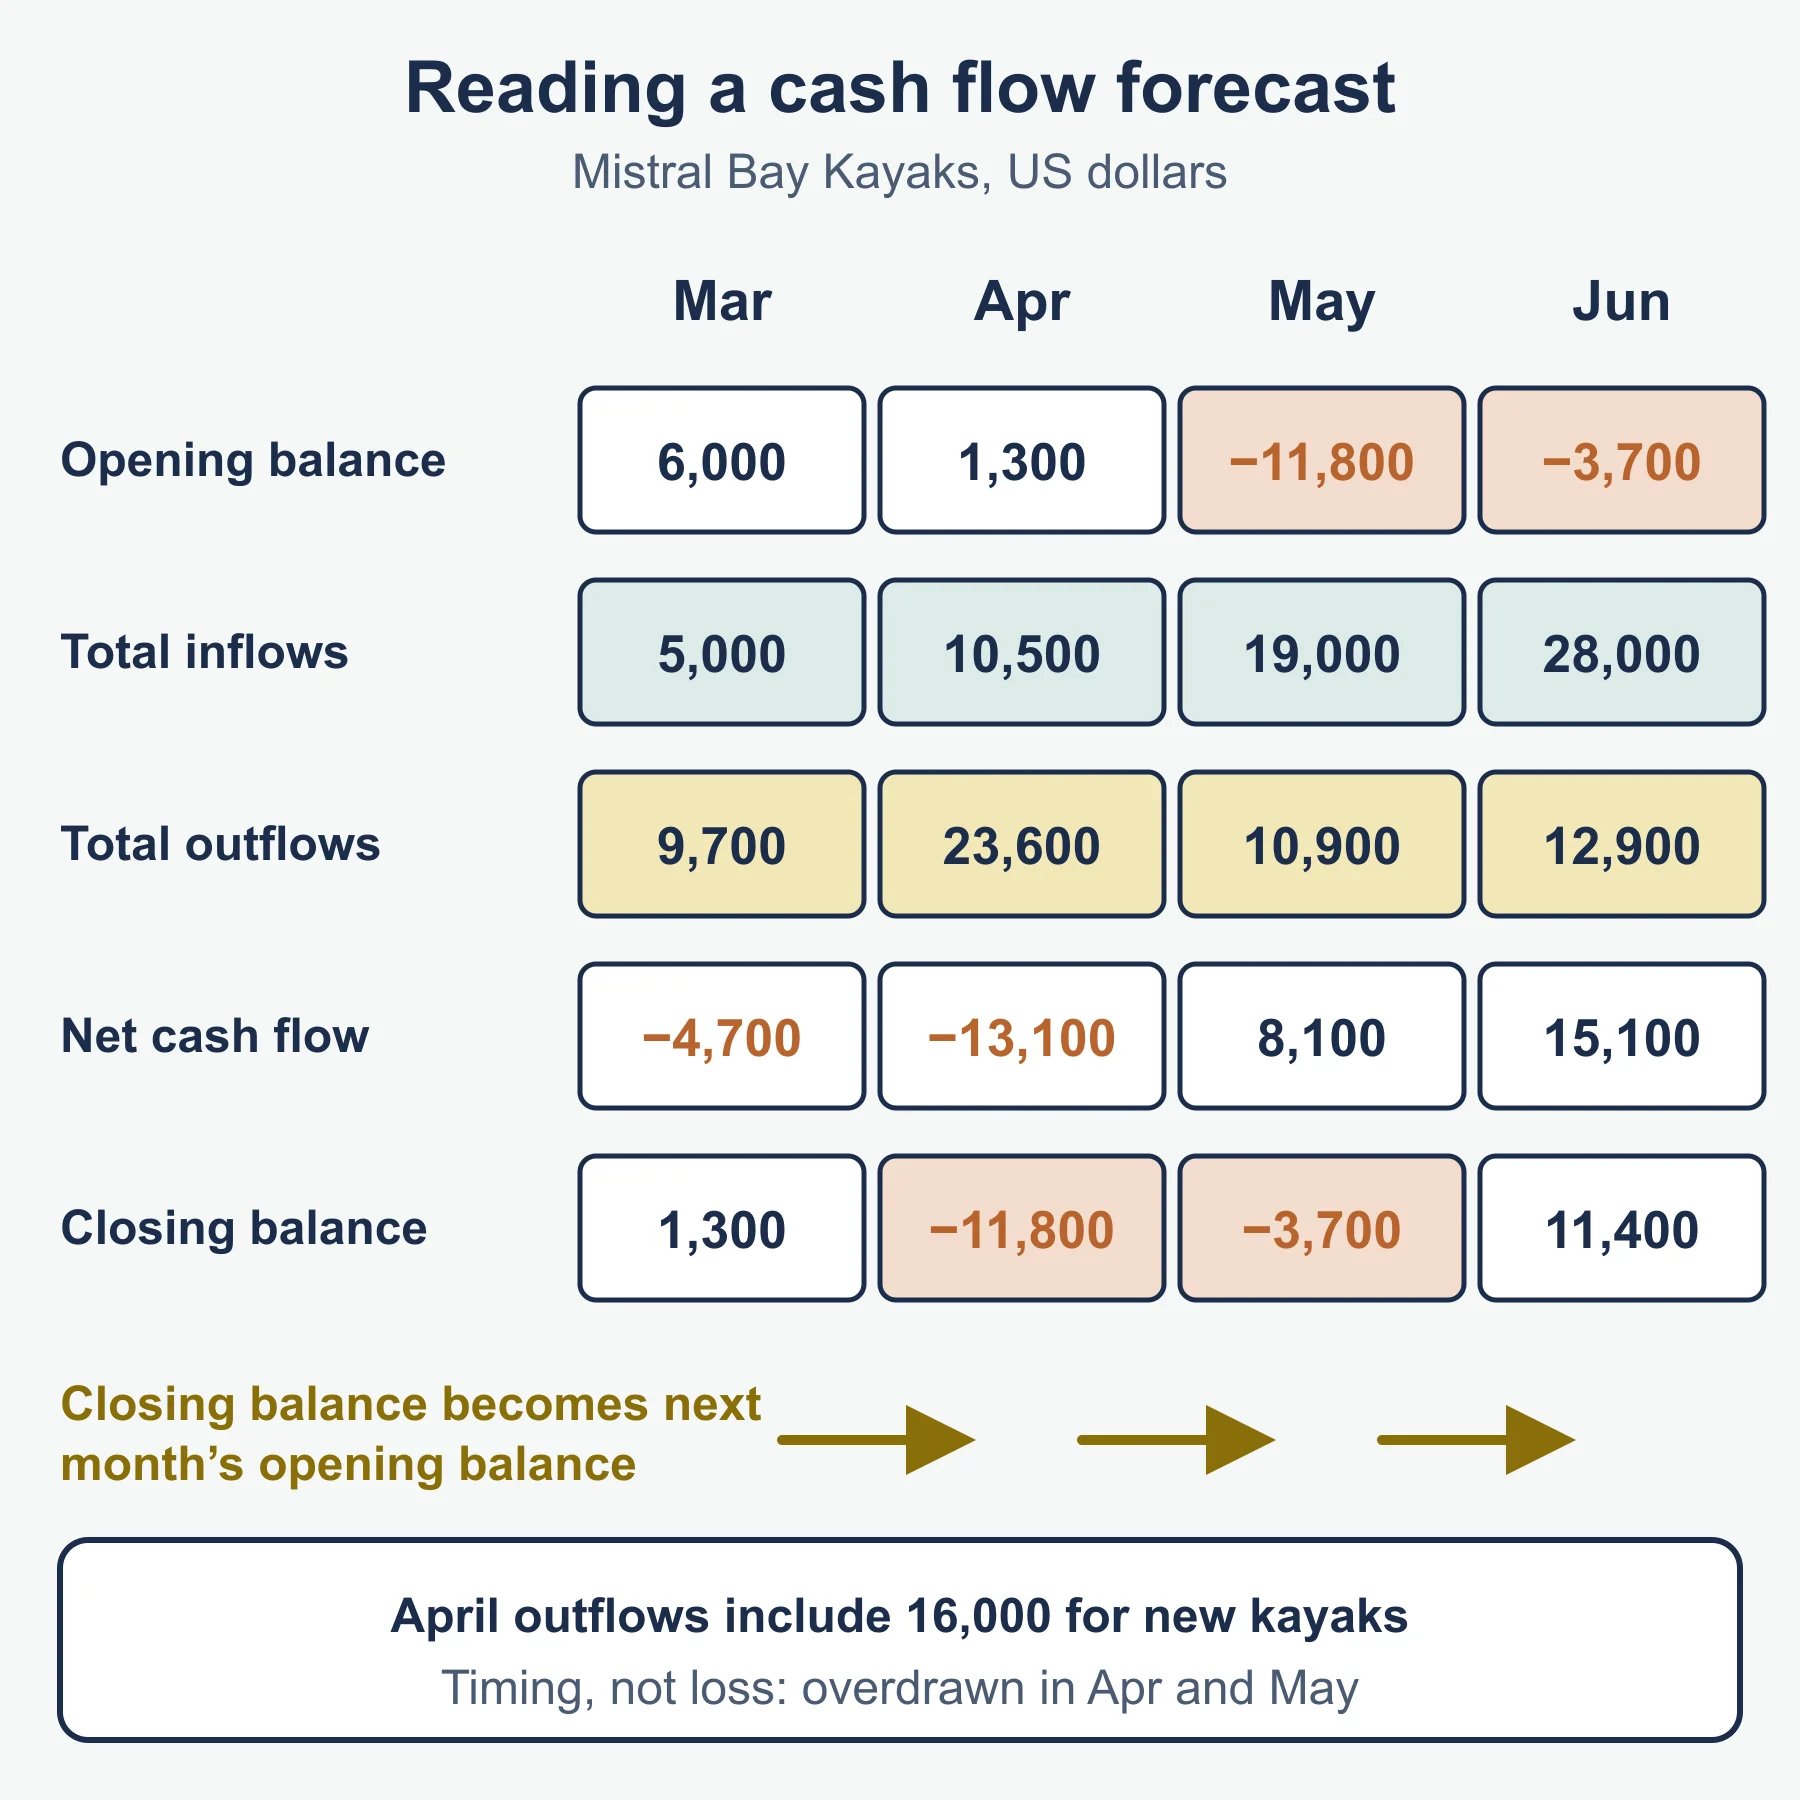
- Net cash flow = total cash inflows - total cash outflows for the month.
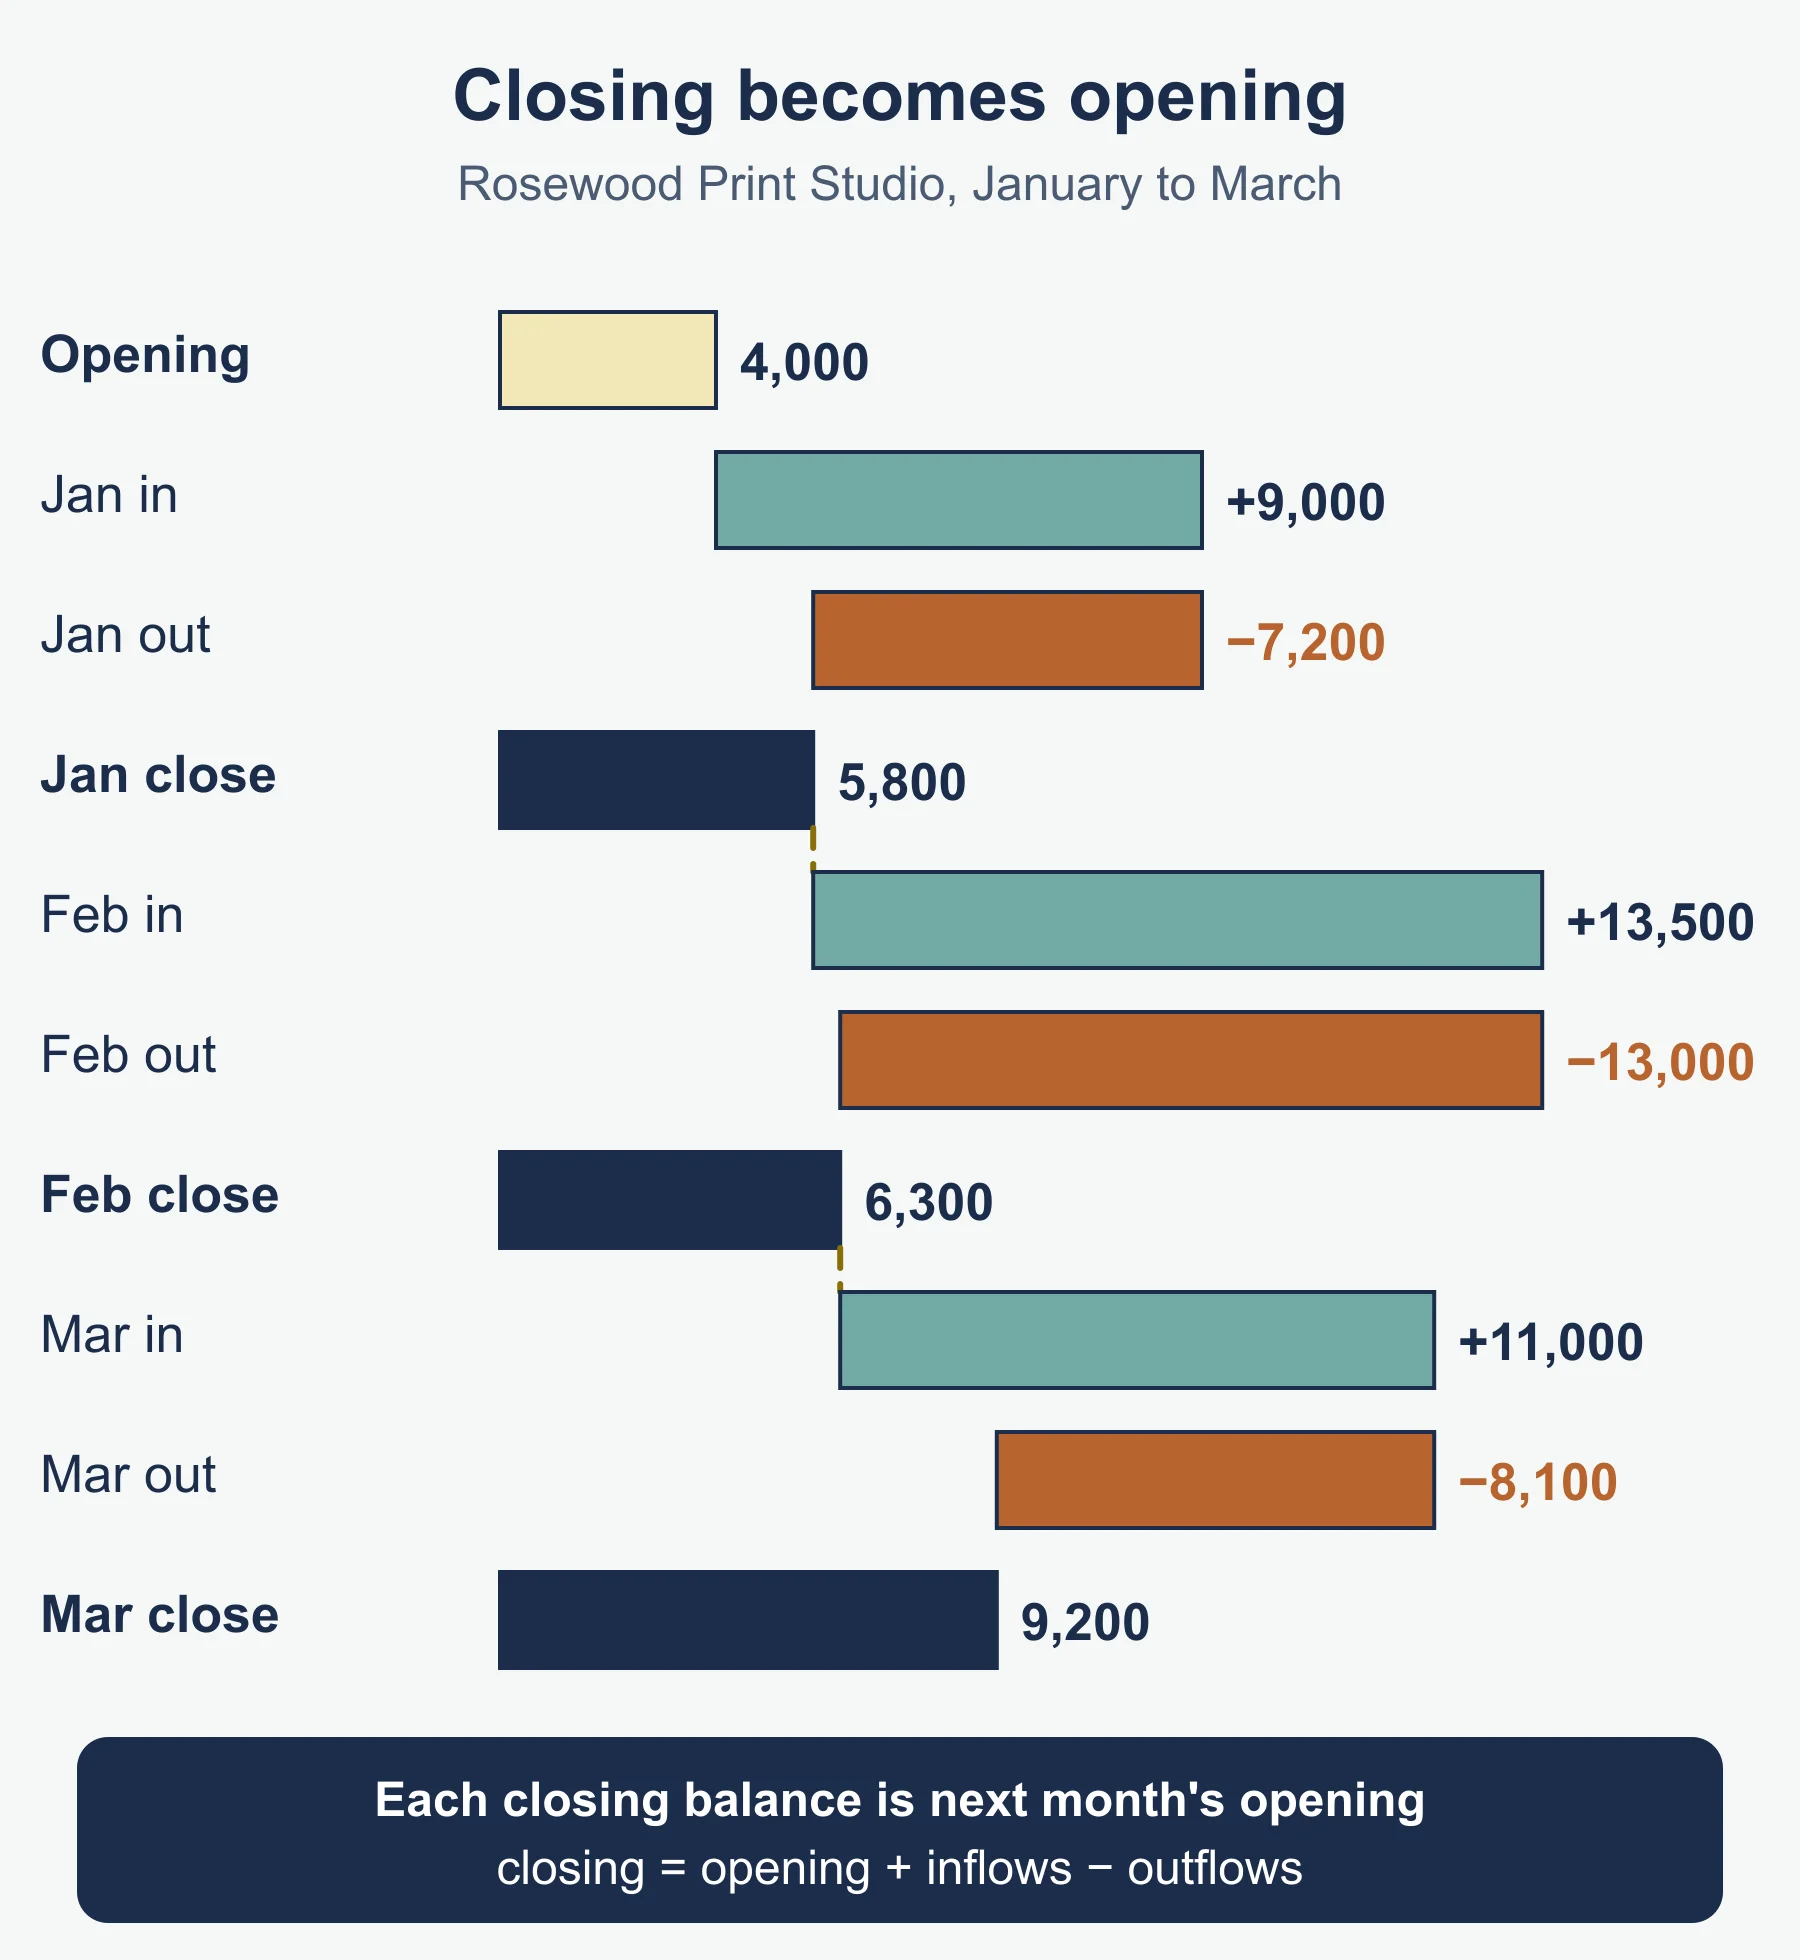
- Opening balance: the cash at the start of the month. It equals the previous month’s closing balance.
- Closing balance = opening balance + net cash flow.
Net cash flow is the change in a month. The closing balance is the total cash held at the end.
Worked example: Rosewood Print Studio
Rosewood begins January with 4,000. Its forecast for three months is below (all cash).
| January | February | March | |
|---|---|---|---|
| Cash sales | 9,000 | 8,500 | 11,000 |
| Loan received | 0 | 5,000 | 0 |
| Total inflows | 9,000 | 13,500 | 11,000 |
| Materials | 3,200 | 3,000 | 3,900 |
| Wages | 2,800 | 2,800 | 3,000 |
| Rent | 1,200 | 1,200 | 1,200 |
| Equipment | 0 | 6,000 | 0 |
| Total outflows | 7,200 | 13,000 | 8,100 |
| Net cash flow | 1,800 | 500 | 2,900 |
| Opening balance | 4,000 | 5,800 | 6,300 |
| Closing balance | 5,800 | 6,300 | 9,200 |
January: outflows 3,200 + 2,800 + 1,200 = 7,200; net = 9,000 - 7,200 = 1,800; closing = 4,000 + 1,800 = 5,800, which becomes February’s opening balance.
7. Interpreting a forecast (3.2.2)
Interpretation means using the figures to say something about the business.
- Look at the closing balances. All positive here, so Rosewood is not forecast to run short of cash. A negative closing balance means the business expects to run out of cash and must act.
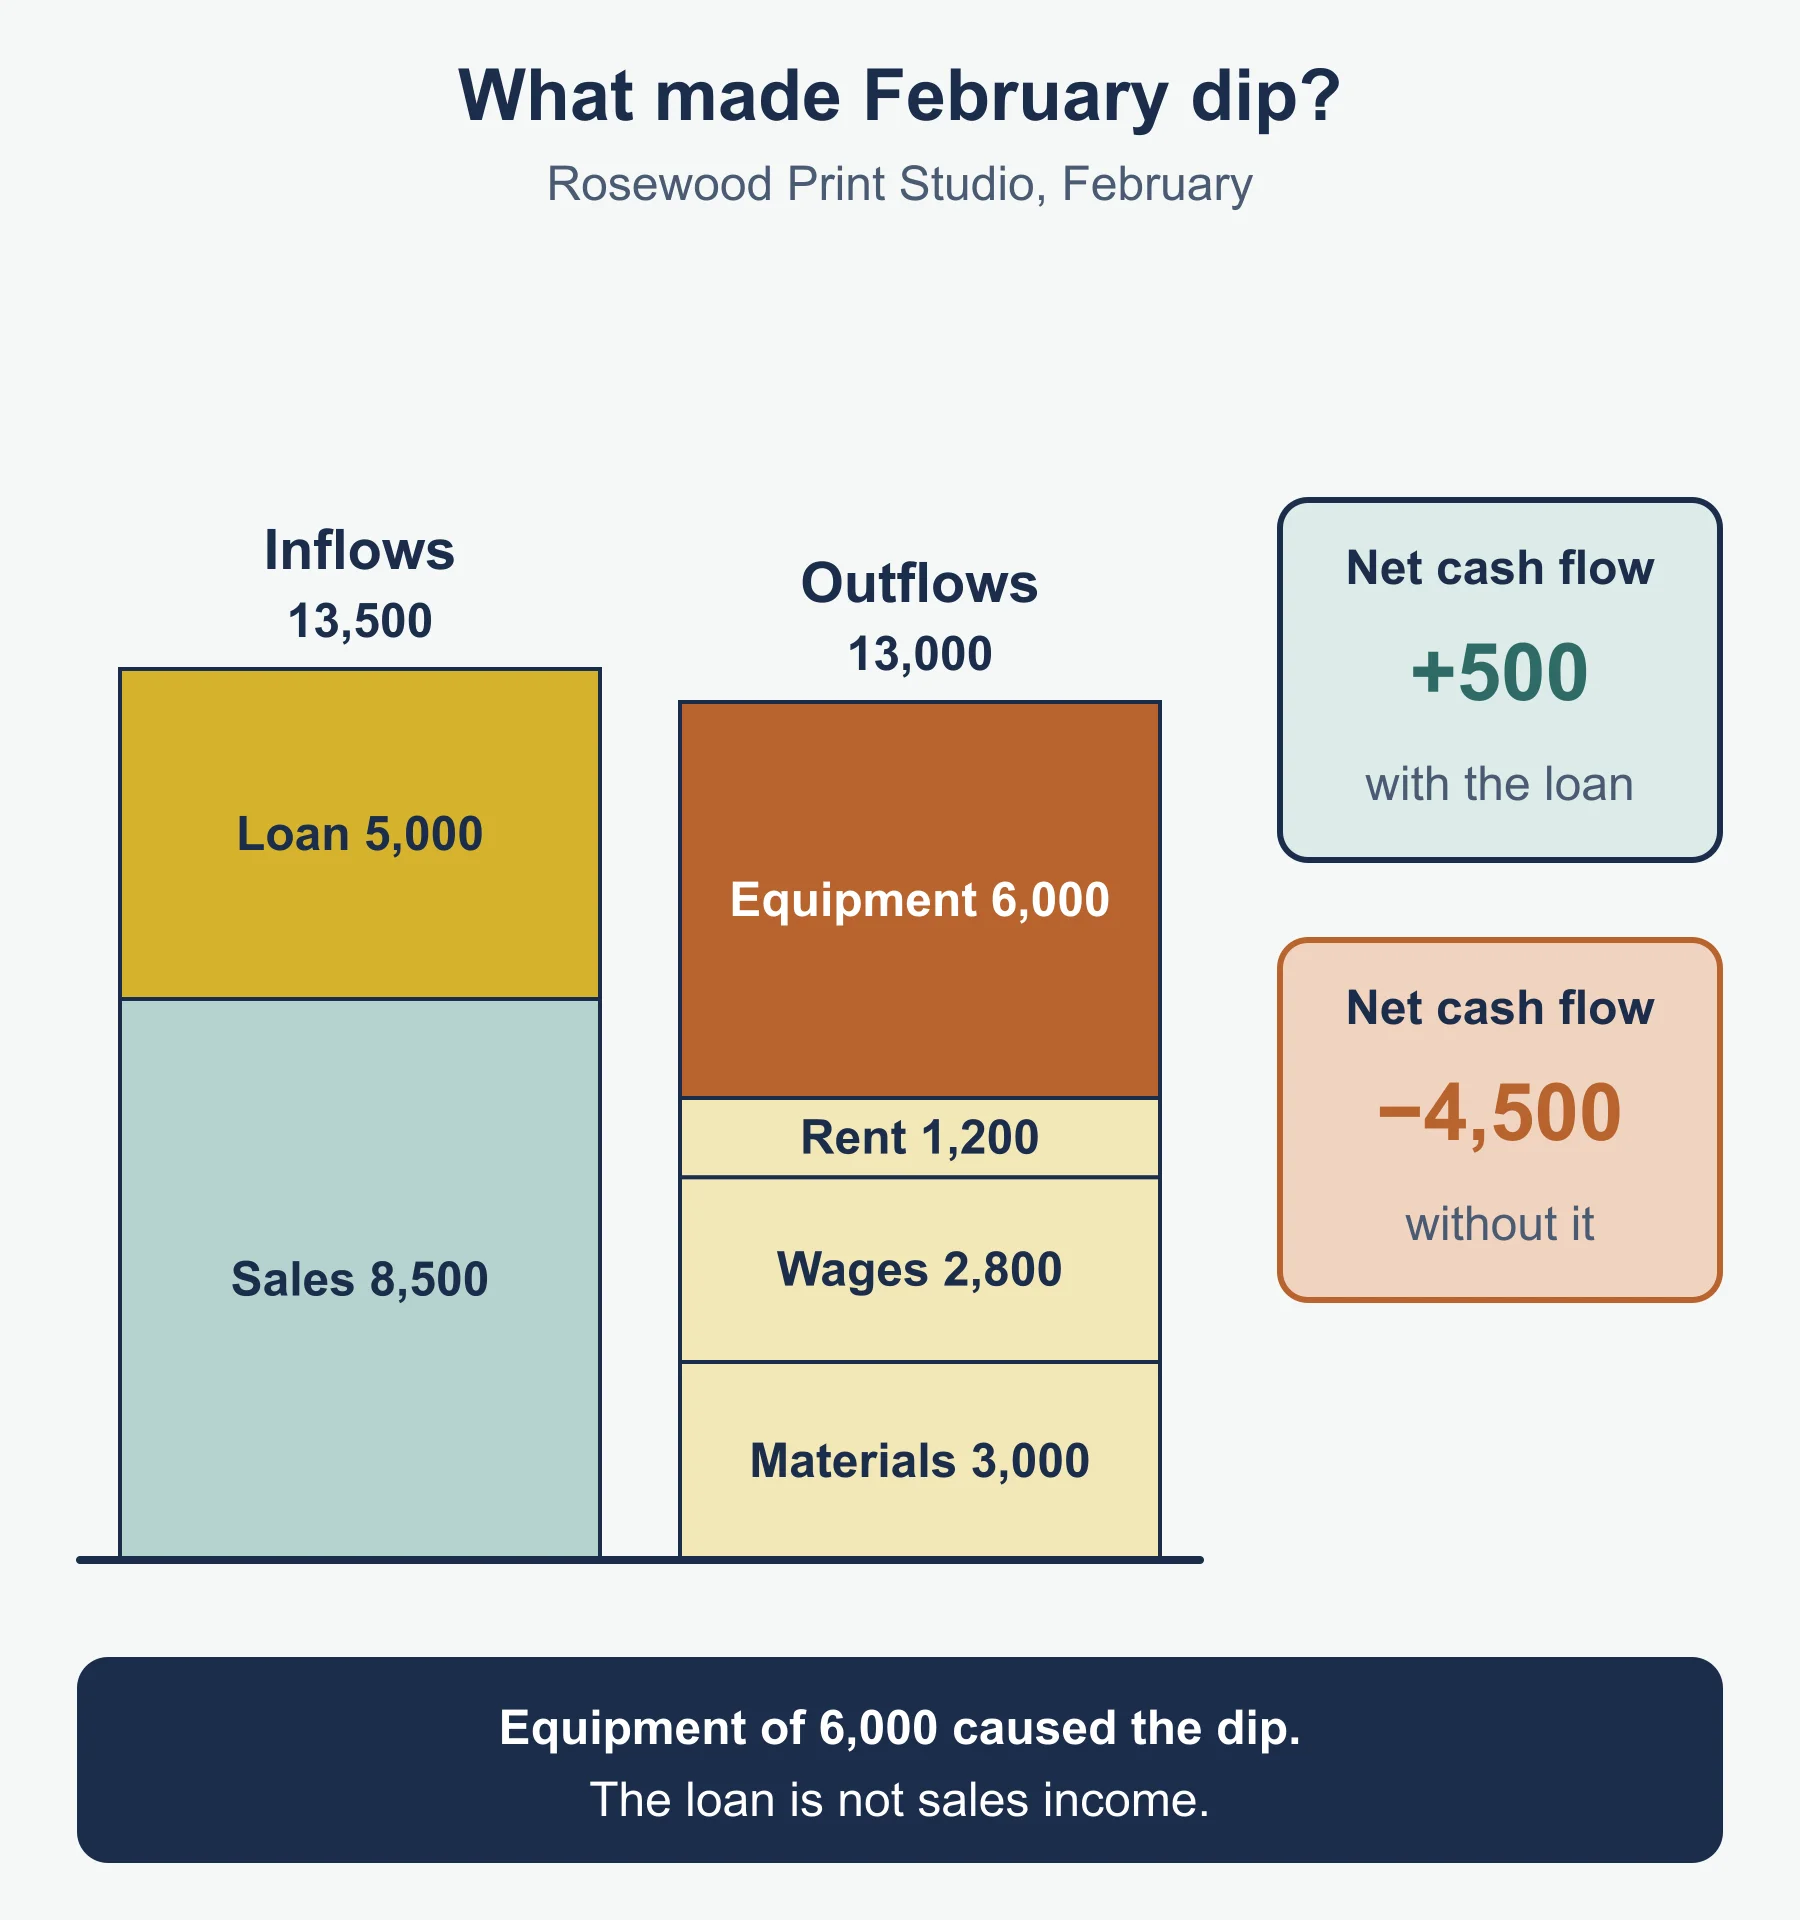
- Look at the trend in net cash flow. Rosewood’s February net flow (500) is low only because of the equipment; without the 5,000 loan it would be -4,500. Say what causes a dip.
- Spot timing problems. A large outflow early and a large inflow late is a warning sign.
- Suggest actions. For a forecast shortfall: arrange an overdraft, ask suppliers for longer payment terms, delay a purchase, encourage customers to pay sooner, or sell a spare asset. For surplus cash: repay a loan or invest in expansion.
- Remember it is a forecast. Sales may fall short or costs may rise, so actual cash can differ. It helps planning, but it is only as reliable as its assumptions.
Common errors
- Answering with profit when the question is about cash, or the reverse.
- Treating a loan received as profit.
- Adding the opening balance into the total inflows.
- Starting a month with a figure other than the previous month’s closing balance.
- Calling an overdraft a long-term source, or share capital a loan that must be repaid.
Next steps
Condense this with the revision notes, then test yourself on the practice questions. Return to the 4BS1 Business hub, tick off progress on the checklist, or find weak spots with the free diagnostics.
Frequently asked questions
Why does cash matter to a business? Cash is needed to pay suppliers, overheads and employees. A business that cannot meet its debts on time is insolvent and may be forced to close.
Why are cash and profit different? Profit is sales revenue minus costs over a period, while cash is what has actually been received and paid. Credit sales, equipment purchases and loans all make the two figures differ.
What is venture capital? Venture capital is investment by specialist investors, often into young businesses with growth potential, usually in return for a share of the ownership.
How can a business deal with a forecast cash shortfall? It can arrange an overdraft, ask suppliers for longer payment terms, delay a purchase, encourage customers to pay sooner or sell a spare asset.
Official syllabus
Pearson Edexcel International GCSE in Business (4BS1), Specification, Issue 2, February 2026, published by Pearson Education Limited. Topic 3: Business finance, sections 3.1 “Business finance - sources” (3.1.1 to 3.1.3) and 3.2 “Cash flow forecasting” (3.2.1 to 3.2.2).
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
Edexcel IGCSE Business: Sources of business finance and cash flow forecasting (4BS1) – Practice Questions
Original practice questions with worked answers on sources of finance, cash versus profit and cash-flow forecasts for Edexcel IGCSE Business.
Business · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Business: Sources of business finance and cash flow forecasting (4BS1) – Revision Notes
Condensed revision notes on sources of finance, cash versus profit and cash-flow forecasts for Edexcel IGCSE Business, with a quick self-test.
Business · Pearson Edexcel · IGCSE
Revise topic -
Study guides
Edexcel IGCSE Business: Costs and break-even analysis (4BS1)
Study guide to costs, profit and break-even charts for Pearson Edexcel International GCSE Business 4BS1, with worked examples and common errors.
Business · Pearson Edexcel · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Business teachers at Marlbridge

