
Study Guides
IGCSE Accounting: The purpose of accounting and the accounting equation (Cambridge 0452)
Worked guide to book-keeping versus accounting, measuring profit and loss, and using assets = liabilities + owner's equity, for Cambridge IGCSE 0452.
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- The fundamentals of accounting
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus points this page covers
0452
- 1.1 The purpose of accounting
- 1.2 The accounting equation
7707
- 1.1 The purpose of accounting
- 1.2 The accounting equation
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
This guide is aligned to the Cambridge IGCSE Accounting 0452 syllabus for exams in 2027, 2028 and 2029 (version 1). It covers syllabus sections 1.1 The purpose of accounting and 1.2 The accounting equation, which together make up Topic 1, The fundamentals of accounting. Every candidate takes the same two papers, so there is no tiering to worry about.
It works through new examples. For a shorter overview of the same topic, see the earlier Topic 1 study guide and fundamentals revision notes. For condensed recall use the revision notes for this unit, and test yourself with the practice questions and the free diagnostics. The course hub is at Cambridge IGCSE Accounting and the printable checklist lists every syllabus point.
What the syllabus asks for
| Section | You need to understand |
|---|---|
| 1.1 | The difference between book-keeping and accounting |
| 1.1 | The purposes of measuring business profit and loss |
| 1.1 | The role of accounting in providing information for monitoring progress and decision-making |
| 1.2 | Assets, liabilities and owner’s equity |
| 1.2 | The accounting equation |
| 1.2 | How to apply the accounting equation |
Paper 1 is multiple choice and Paper 2 is a structured written paper. Both are based on all the subject content, so these ideas can appear at any point in either paper, and later topics assume you can use them without thinking.
1.1 Book-keeping and accounting
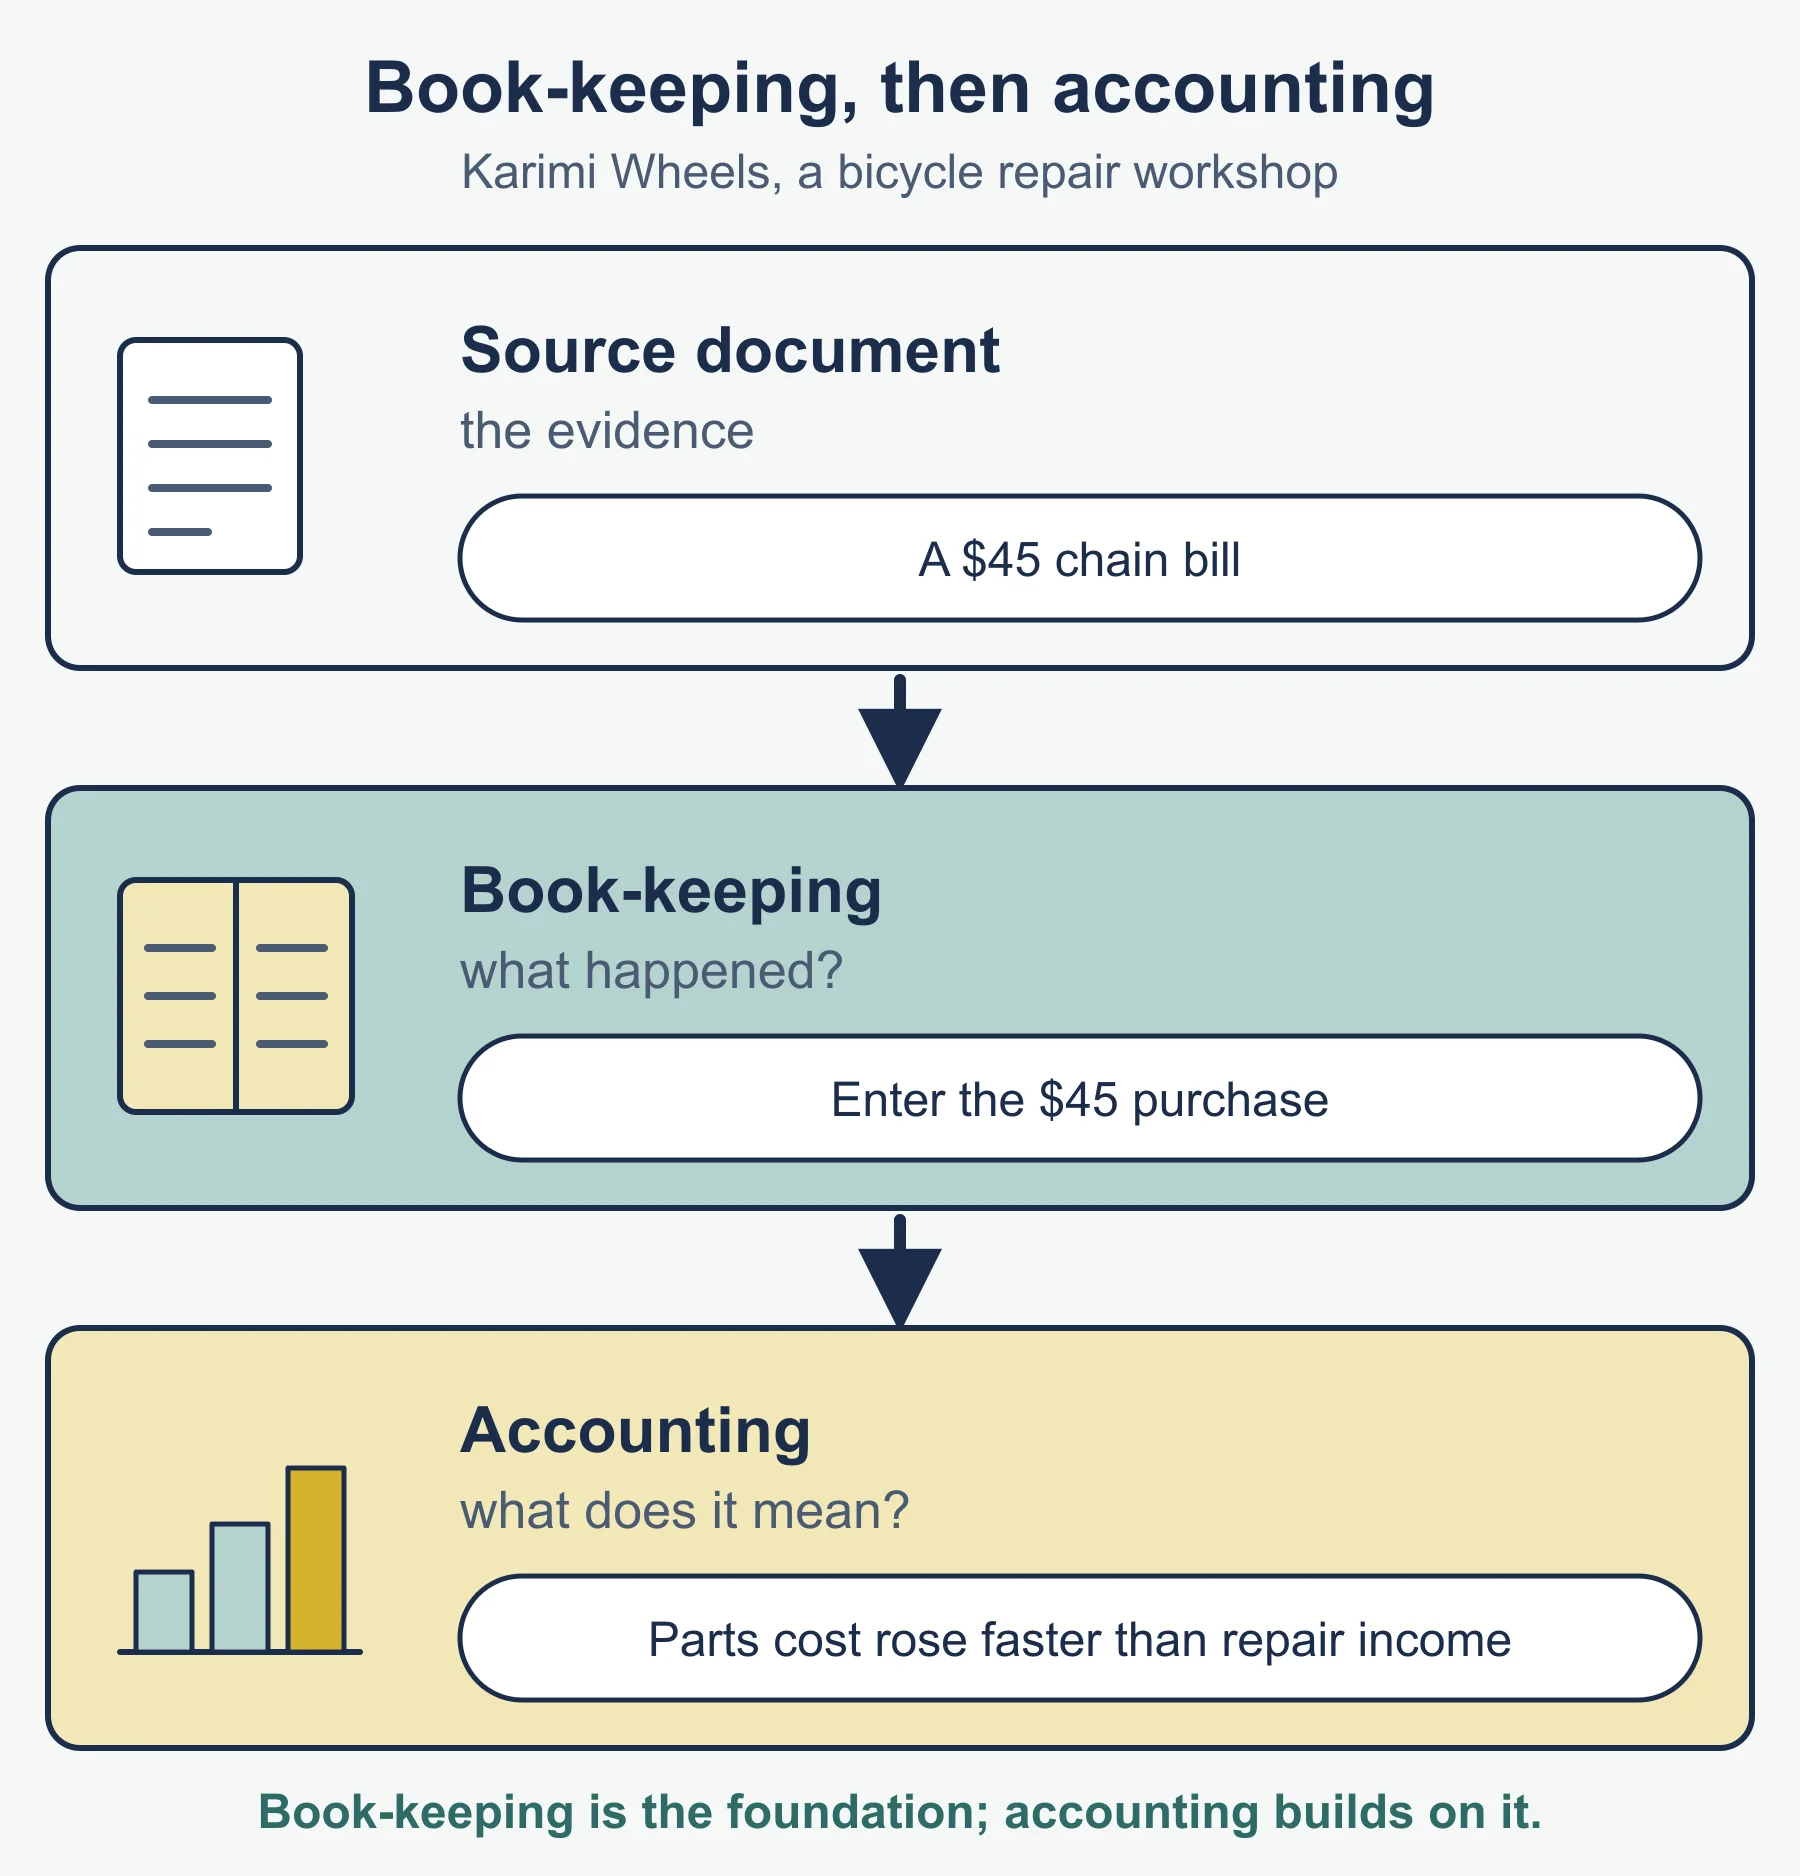
Book-keeping is the recording side. Hamid Karimi runs Karimi Wheels, a bicycle repair workshop. Each time he buys spare parts, issues a bill to a customer or pays a supplier, the transaction is entered in the business records from a source document. This work is routine and follows fixed rules. It answers the question “what happened?”.
Accounting starts where the recording stops. The recorded transactions are classified and summarised, financial statements such as the statement of profit or loss are prepared, and the results are analysed and communicated. It answers the question “what does this mean, and what should we do?”.
| Book-keeping | Accounting | |
|---|---|---|
| Main task | Recording transactions in the books | Summarising, presenting and interpreting the records |
| Output | Up-to-date ledger accounts | Financial statements, ratios, comments and advice |
| Skill level | Following set procedures | Judgement, analysis and communication |
| Example at Karimi Wheels | Entering a $45 chain purchase from a supplier | Telling Hamid that parts costs rose faster than repair income this quarter |
Book-keeping is the foundation. If it is careless, every statement built on it is unreliable. But entering figures does not tell the owner whether the business is doing well, so both are needed.
1.1 Why profit and loss is measured
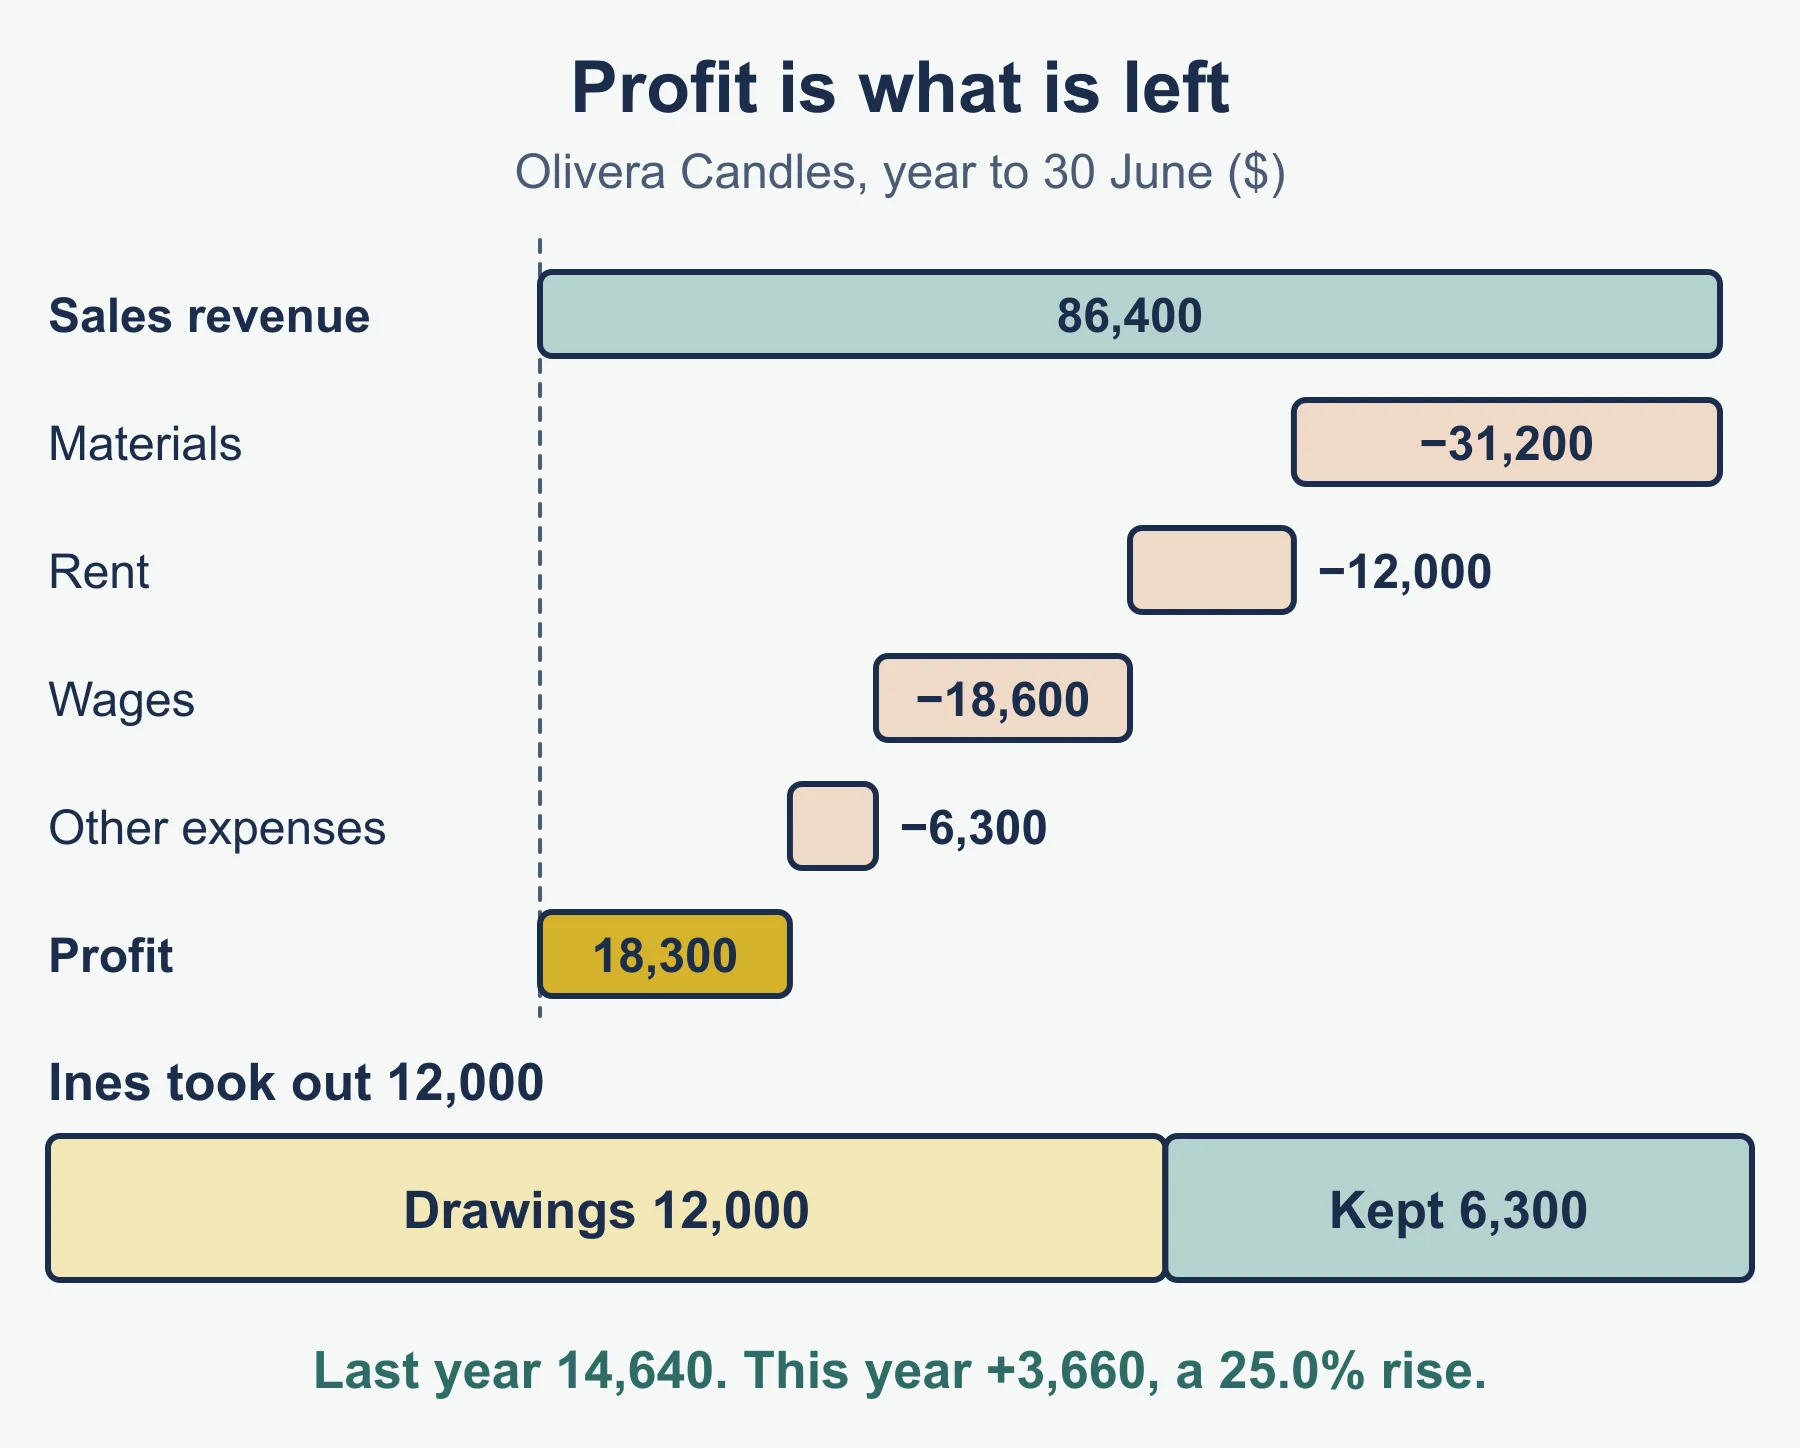
Profit is the amount by which income earned in a period exceeds the expenses of earning it. If expenses are greater, the business has made a loss. The measurement is made for a stated period, usually a year, and is shown in the statement of profit or loss.
Olivera Candles is owned by Ines Olivera. Her figures for the year to 30 June, in dollars:
| Item | Amount |
|---|---|
| Sales revenue | 86,400 |
| Materials | 31,200 |
| Rent | 12,000 |
| Wages | 18,600 |
| Other expenses | 6,300 |
| Total expenses | 68,100 |
| Profit for the year | 18,300 |
Profit is 86,400 − 68,100 = 18,300. The year before, profit was 14,640. The increase is 3,660, which is 3,660 ÷ 14,640 = 25.0% more. Measuring this gives several things:
- A verdict on performance. The owner sees whether the effort and money put in produced a return, and by how much.
- A guide to withdrawals. Ines took 12,000 for personal use, leaving 6,300 of profit in the business. If she had taken 20,000, she would have drawn out more than the business earned.
- A comparison over time. A 25.0% rise in profit tells her more than the profit figure alone.
- Evidence for outsiders. A lender deciding whether to give a loan, or a tax authority working out tax, wants a profit figure produced by recognised methods.
- A basis for decisions. Whether to raise prices, cut a cost or expand depends on what the profit figure shows.
A loss is equally informative. It warns the owner before cash runs out that something must change.
1.1 Monitoring progress and supporting decisions
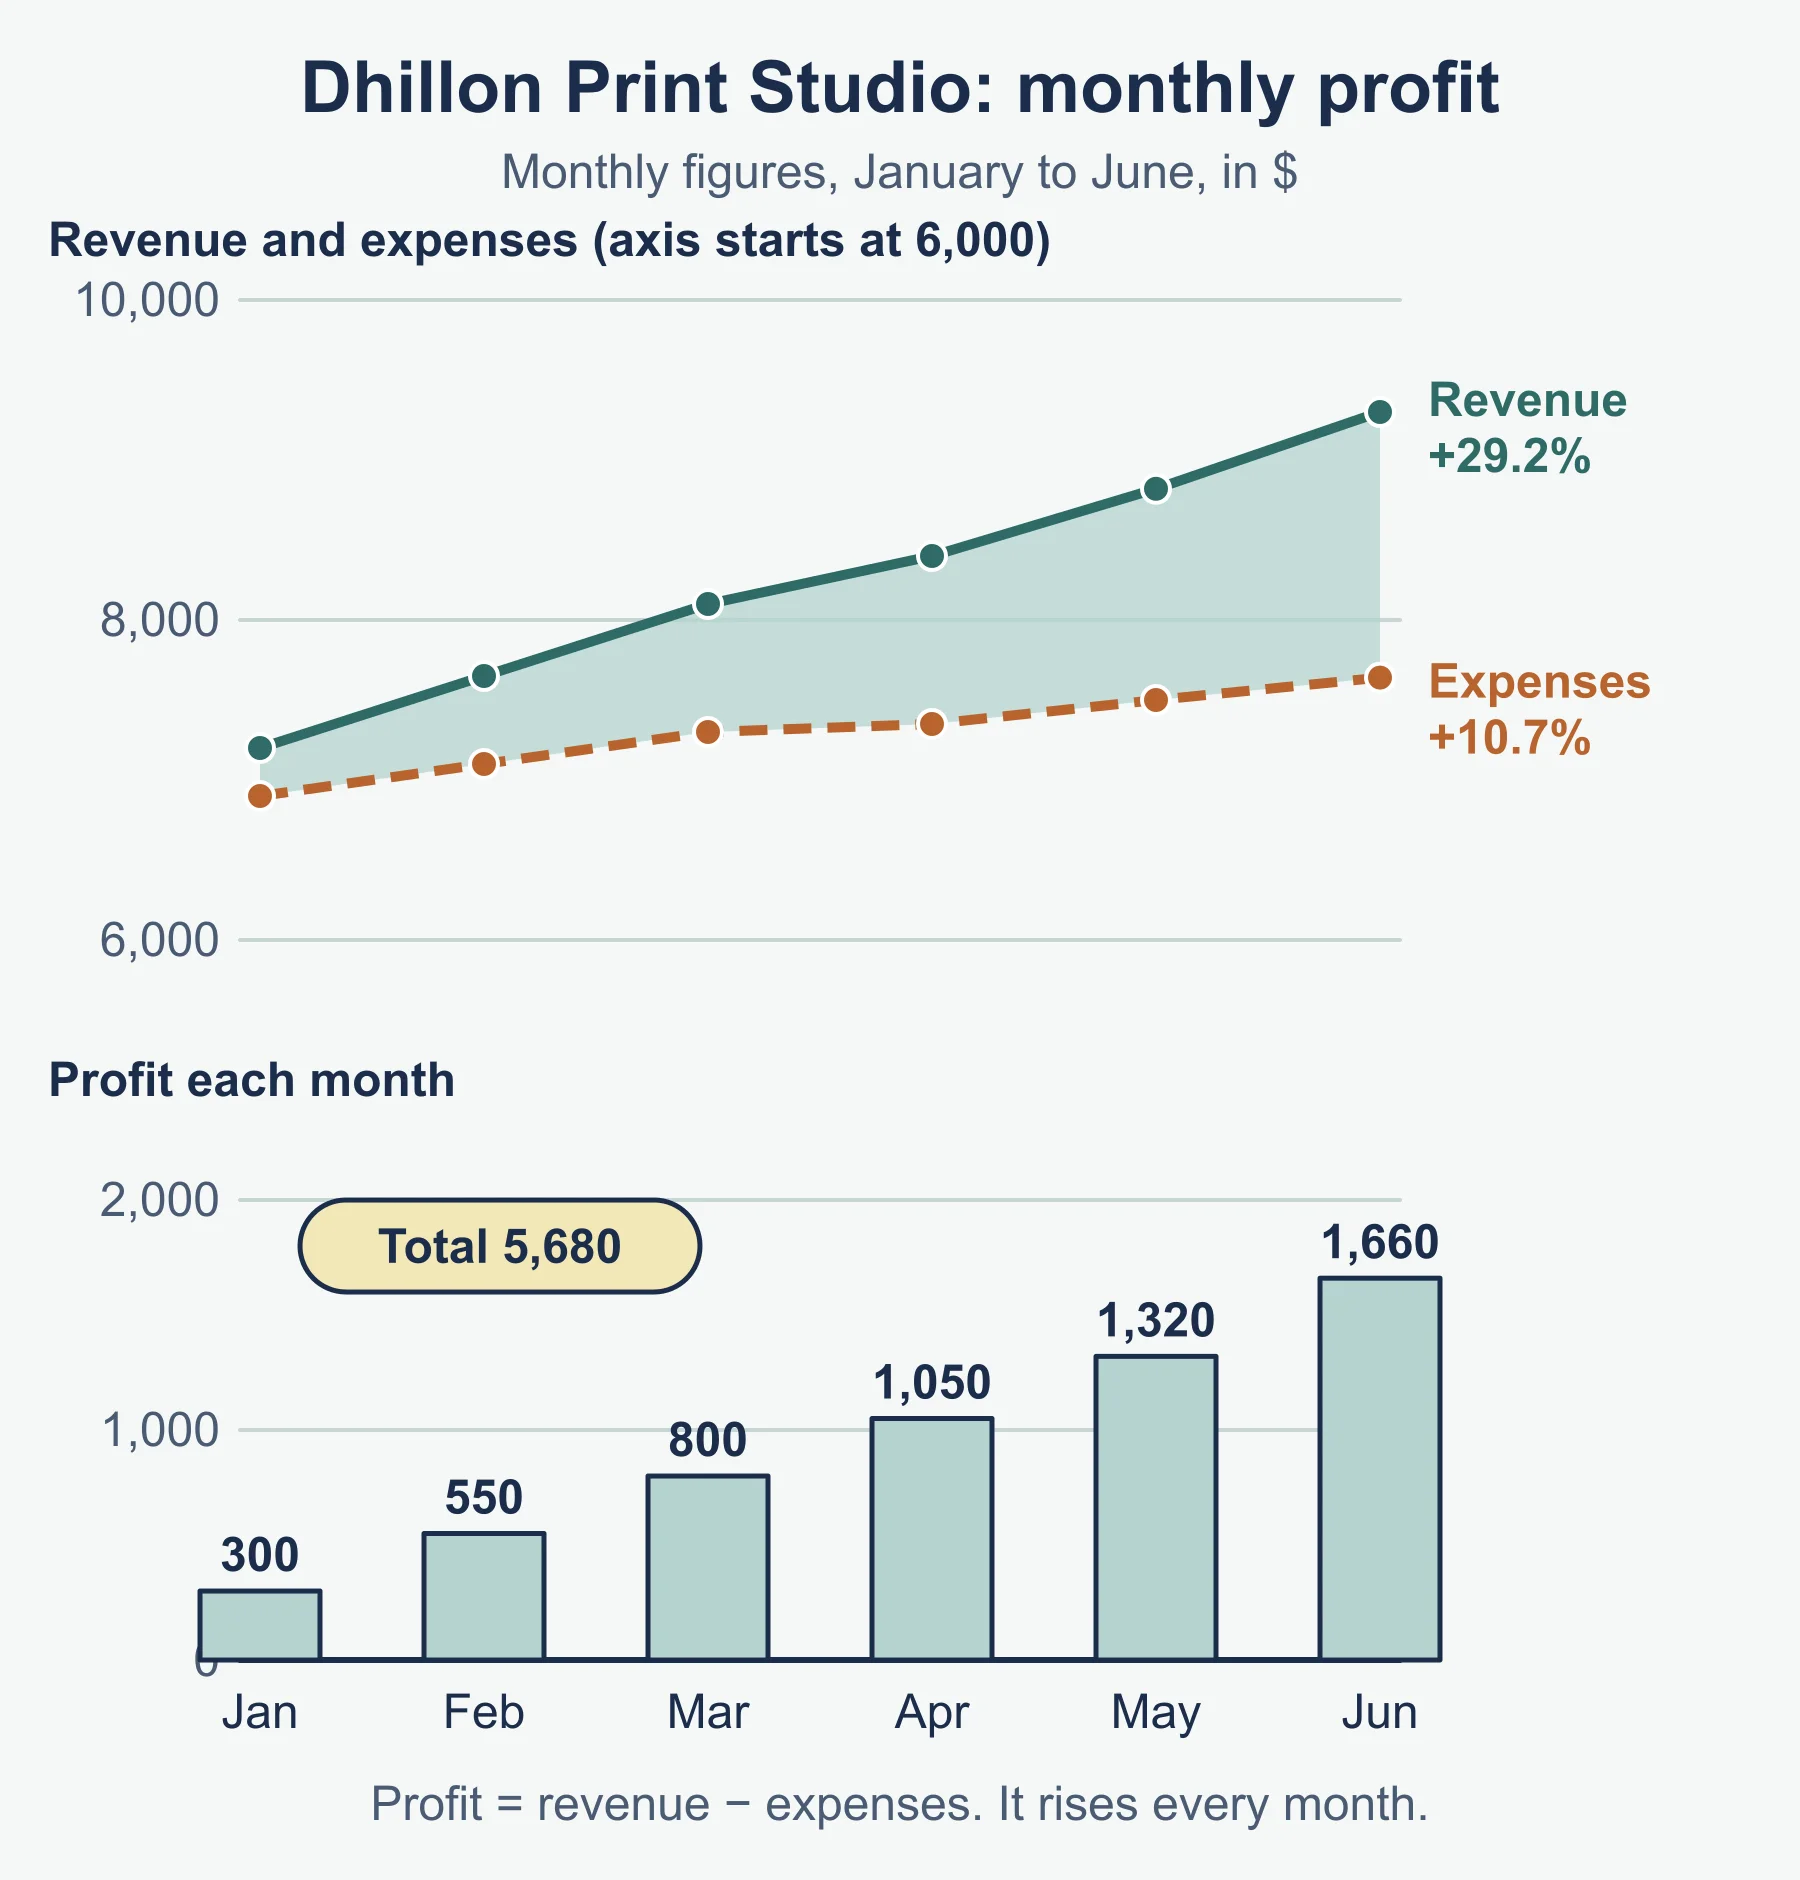
Accounting information is useful because it is compared with something: an earlier period, a plan, or another business. Gurpreet Dhillon owns Dhillon Print Studio. Her monthly figures for the first half of the year, in dollars:
| Month | Revenue | Expenses | Profit |
|---|---|---|---|
| January | 7,200 | 6,900 | 300 |
| February | 7,650 | 7,100 | 550 |
| March | 8,100 | 7,300 | 800 |
| April | 8,400 | 7,350 | 1,050 |
| May | 8,820 | 7,500 | 1,320 |
| June | 9,300 | 7,640 | 1,660 |
| Total | 49,470 | 43,790 | 5,680 |
Revenue grew by 29.2% from January to June (9,300 ÷ 7,200 = 1.292) while expenses grew by only 10.7% (7,640 ÷ 6,900 = 1.107). That is how she monitors progress: the business is becoming more profitable each month.
The same figures support decisions. A steady rise in profit might justify hiring a part-time assistant. If profit had fallen while revenue rose, she would look at which expense was climbing before agreeing to take on more work. Accounting information does not make the decision; it gives the owner facts to base it on. Other decisions of the same kind include whether to buy more equipment, how much credit to allow customers, and whether to ask the bank for a loan.
1.2 Assets, liabilities and owner’s equity
These are the three building blocks of the accounting equation.
| Term | Meaning | Examples |
|---|---|---|
| Asset | A resource owned by the business that has value | Premises, equipment, vehicles, inventory, trade receivables, bank balance, cash |
| Liability | An amount the business owes to someone outside it | Trade payables, bank loan, bank overdraft |
| Owner’s equity | The owner’s claim on the business: what is left of the assets after the liabilities are paid | Capital paid in, plus profits kept in the business, less drawings |
Note the direction of each credit item. Trade receivables are customers who owe the business money, so they are an asset. Trade payables are suppliers the business owes, so they are a liability. A bank overdraft is borrowing, so it is a liability even though it appears next to the bank.
Owner’s equity changes in four ways:
- It increases when the owner pays in more capital.
- It increases when the business makes a profit.
- It decreases when the business makes a loss.
- It decreases when the owner takes drawings, meaning money or goods taken out for personal use.
You will also see the word capital used for the owner’s equity, particularly the amount the owner first paid in.
1.2 The accounting equation
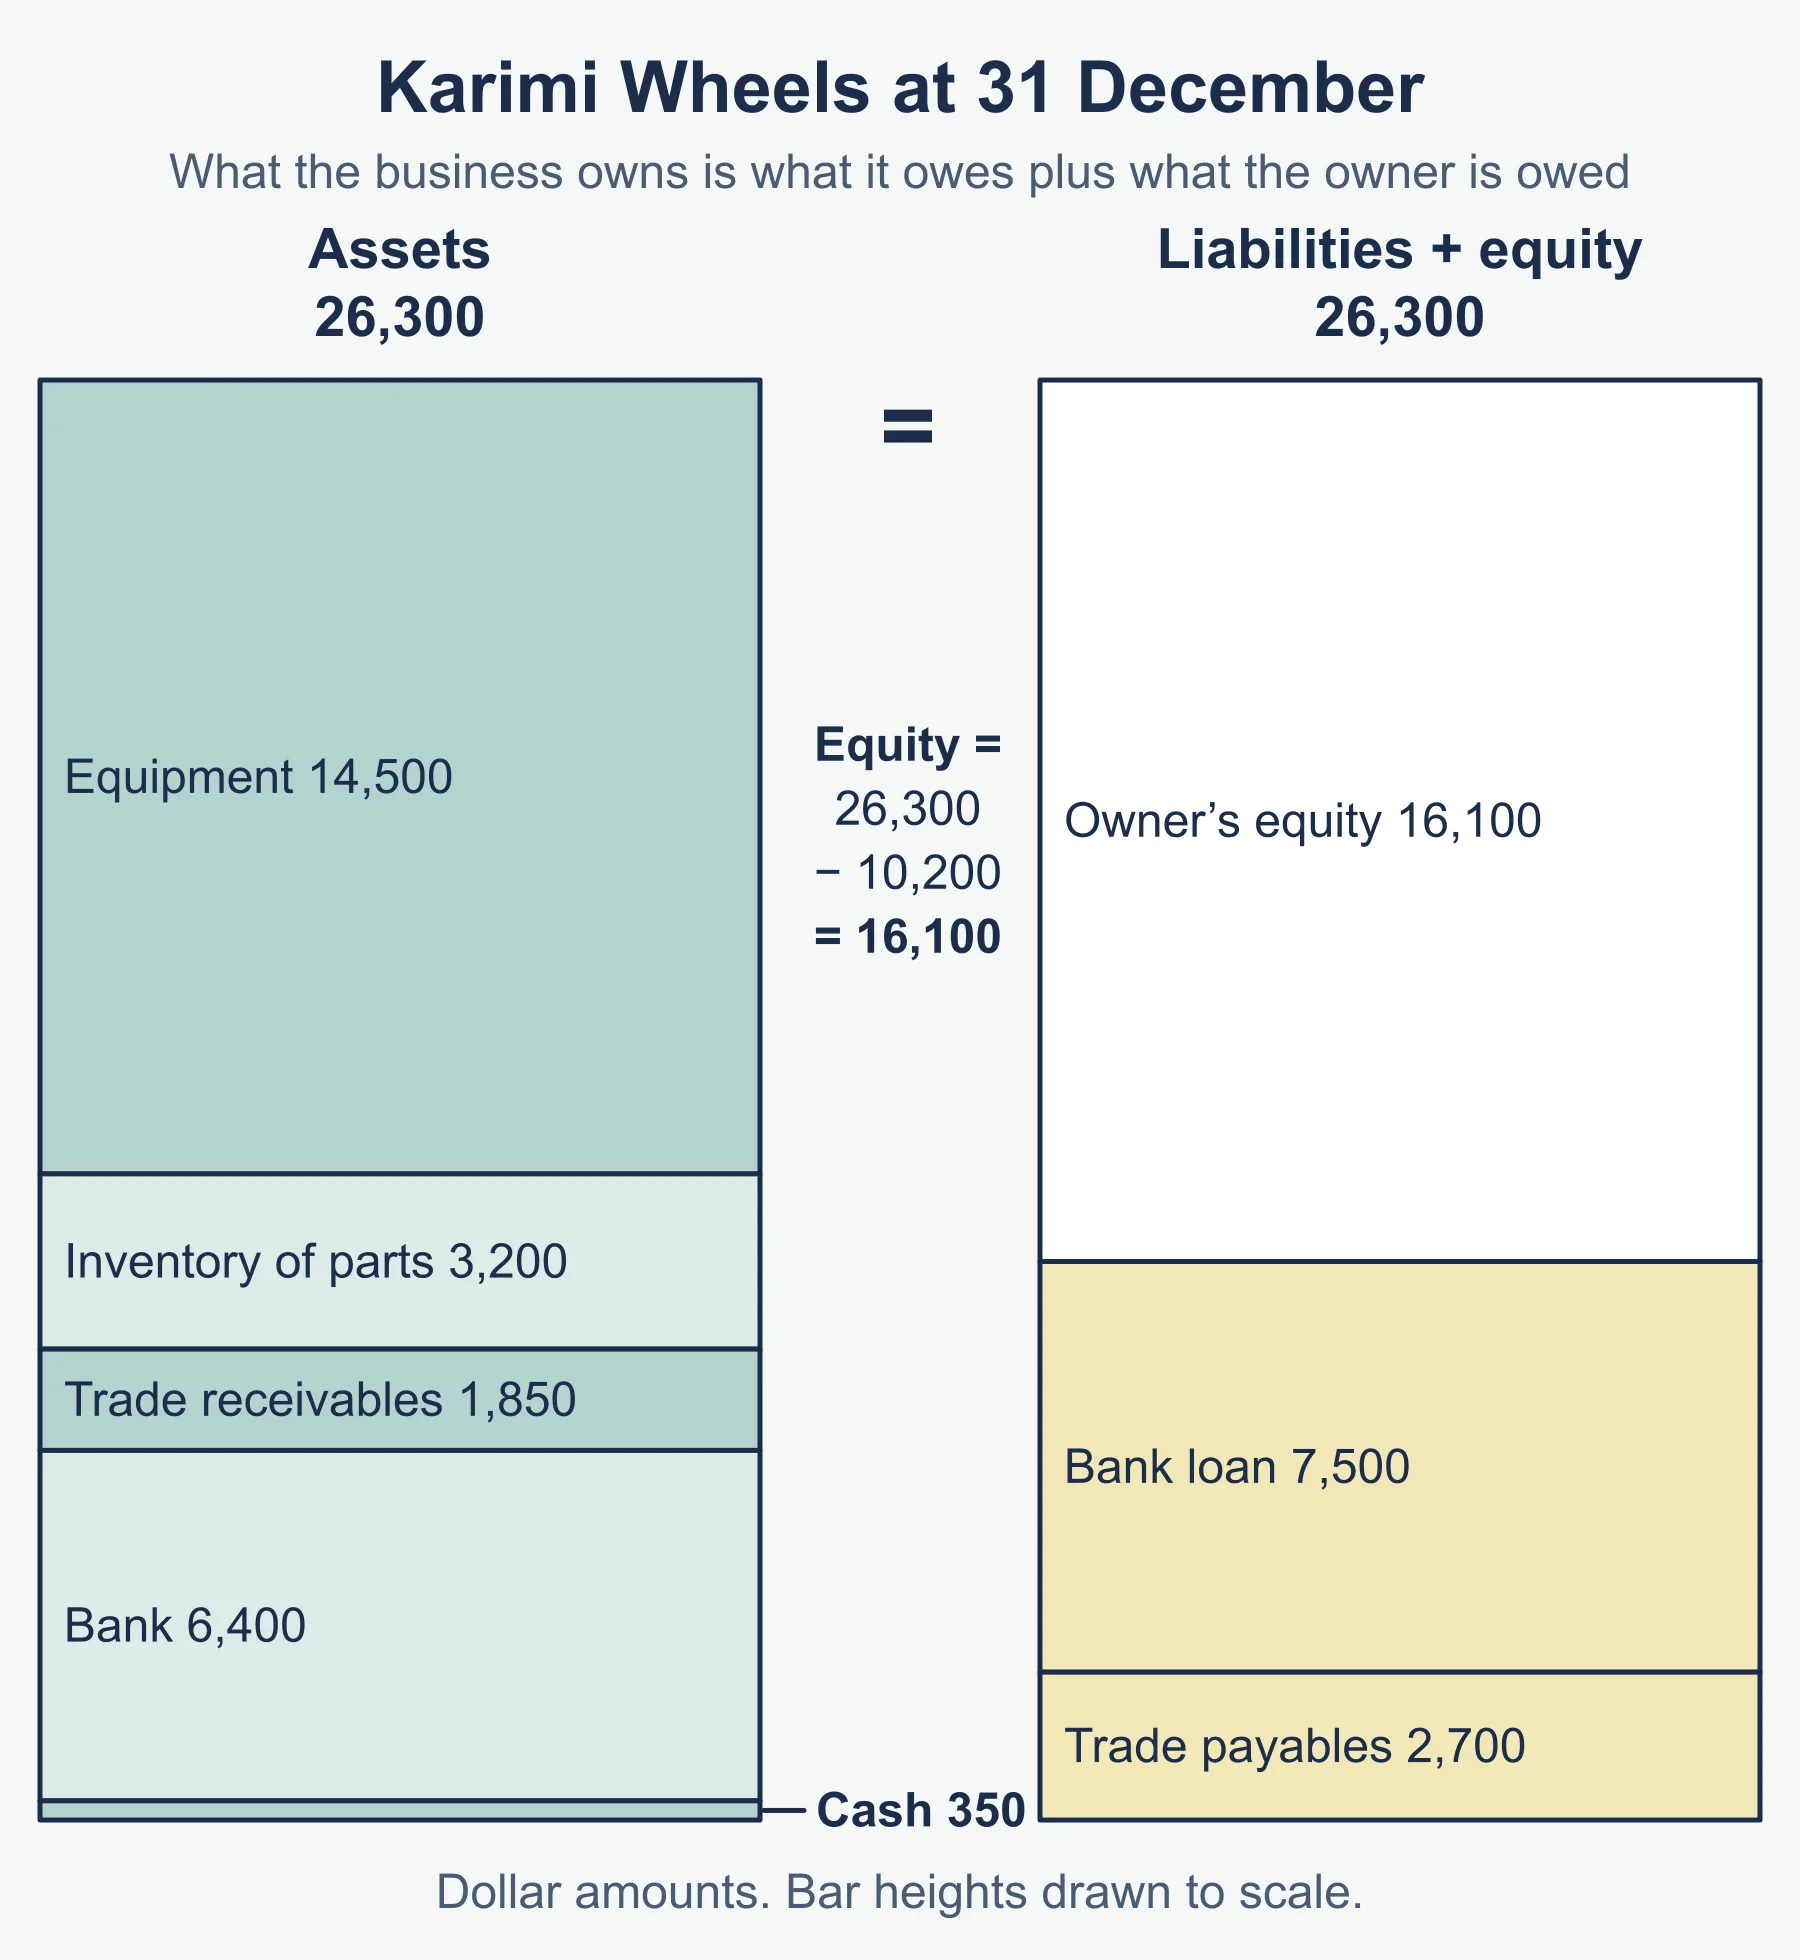
Everything the business owns is financed either by outsiders (liabilities) or by the owner (owner’s equity). So:
Assets = Liabilities + Owner’s equity
Rearranged: Owner’s equity = Assets − Liabilities, and Liabilities = Assets − Owner’s equity.
Here is Karimi Wheels at 31 December (dollar amounts):
Assets                    dollars       Liabilities         dollars
Equipment                  14,500       Trade payables        2,700
Inventory of parts          3,200       Bank loan             7,500
Trade receivables           1,850       Total liabilities    10,200
Bank                        6,400
Cash                          350       Owner's equity       16,100
Total assets               26,300       Liabilities + equity 26,300
Total assets are 26,300 and total liabilities 10,200, so owner’s equity is 26,300 − 10,200 = 16,100. The two sides agree because the equity figure is what is left over.
1.2 Applying the equation
Finding a missing figure
Write the equation, put in what you know, and solve for the gap.
- Assets 64,500 and liabilities 21,300: owner’s equity = 64,500 − 21,300 = 43,200.
- Liabilities 18,000 and owner’s equity 52,500: assets = 18,000 + 52,500 = 70,500.
- Assets 39,800 and owner’s equity 27,350: liabilities = 39,800 − 27,350 = 12,450.
Following transactions
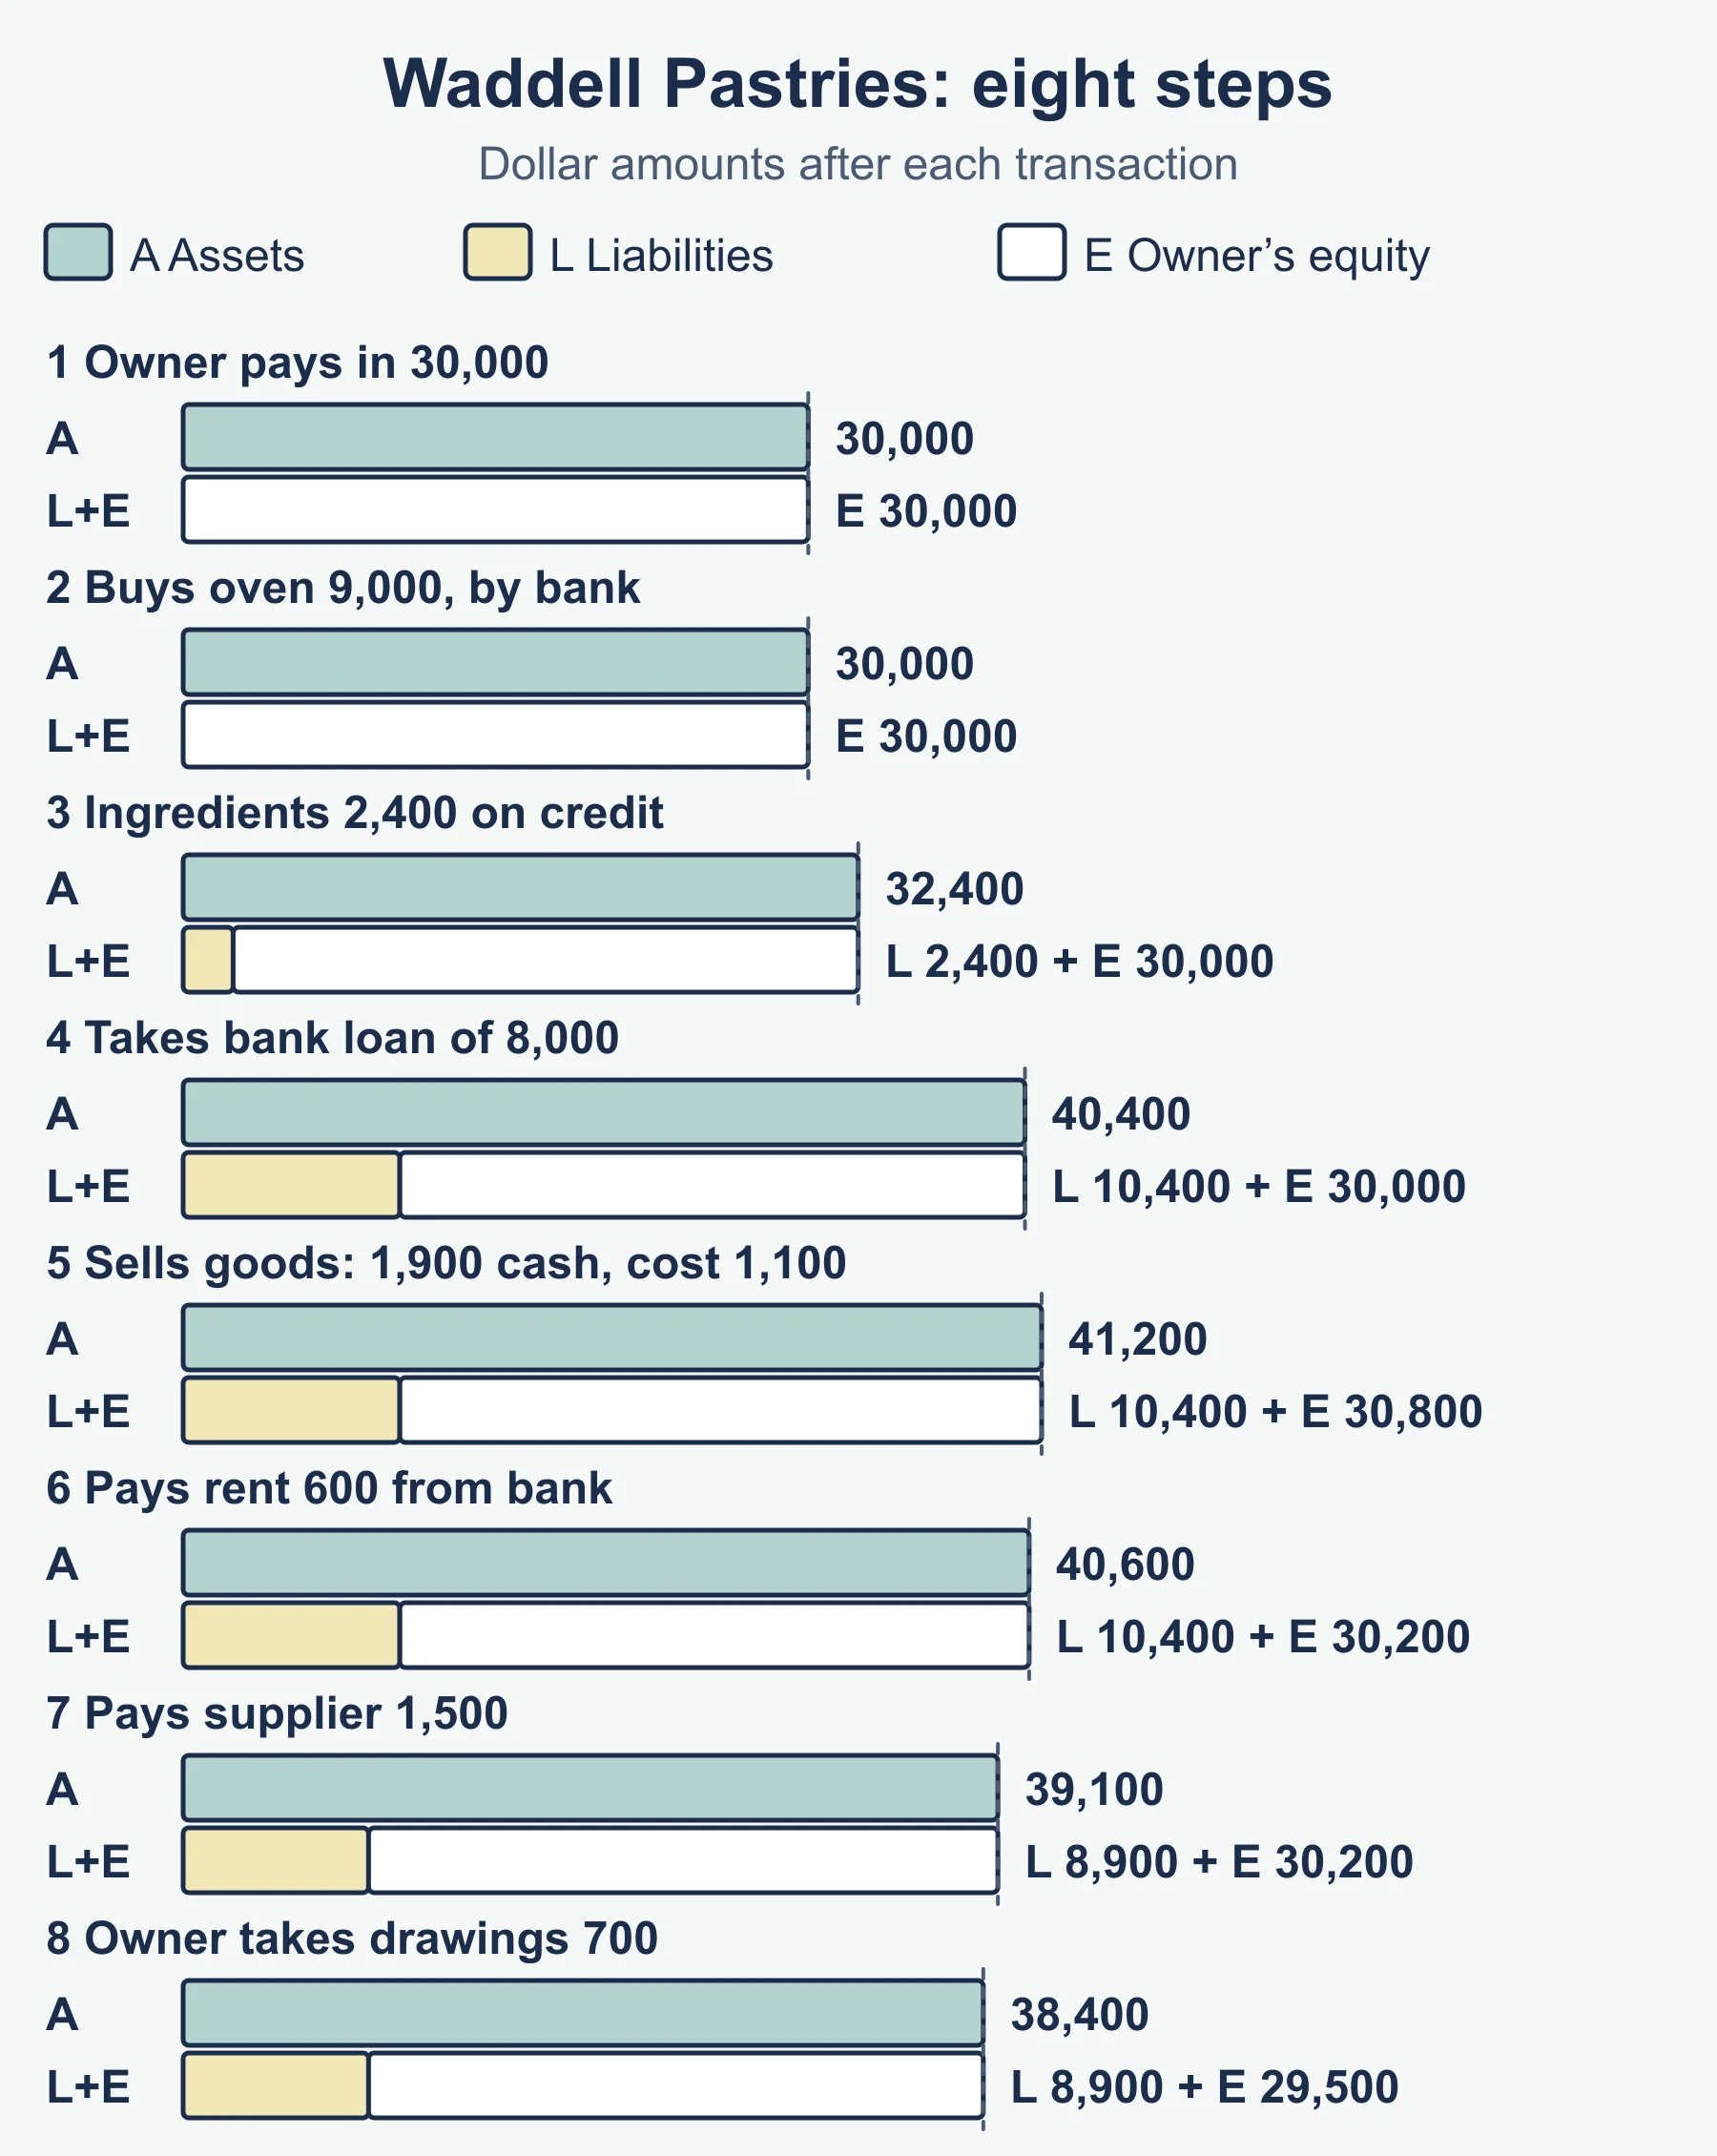
Every transaction changes at least two items, and the equation still balances afterwards. Moira Waddell starts Waddell Pastries (dollar amounts):
| Transaction | Assets | Liabilities | Owner’s equity |
|---|---|---|---|
| 1. Moira pays 30,000 into a business bank account | 30,000 | 0 | 30,000 |
| 2. Buys an oven for 9,000 by bank transfer | 30,000 | 0 | 30,000 |
| 3. Buys ingredients for 2,400 on credit | 32,400 | 2,400 | 30,000 |
| 4. Takes a bank loan of 8,000 | 40,400 | 10,400 | 30,000 |
| 5. Sells goods that cost 1,100 for 1,900 cash | 41,200 | 10,400 | 30,800 |
| 6. Pays rent of 600 from the bank | 40,600 | 10,400 | 30,200 |
| 7. Pays the supplier 1,500 | 39,100 | 8,900 | 30,200 |
| 8. Moira takes 700 cash as drawings | 38,400 | 8,900 | 29,500 |
Transaction 2 swaps one asset for another, so the total does not move. Transaction 3 raises assets and liabilities together. Transaction 5 raises assets by 800 because the goods sold earned 800 more than they cost: that 800 is profit, so owner’s equity rises. Transaction 6 is an expense, which reduces profit and therefore owner’s equity. In transaction 8, drawings reduce owner’s equity but are not an expense. After each line, check that assets equal liabilities plus owner’s equity; the last line gives 38,400 = 8,900 + 29,500.
Working out profit from two positions
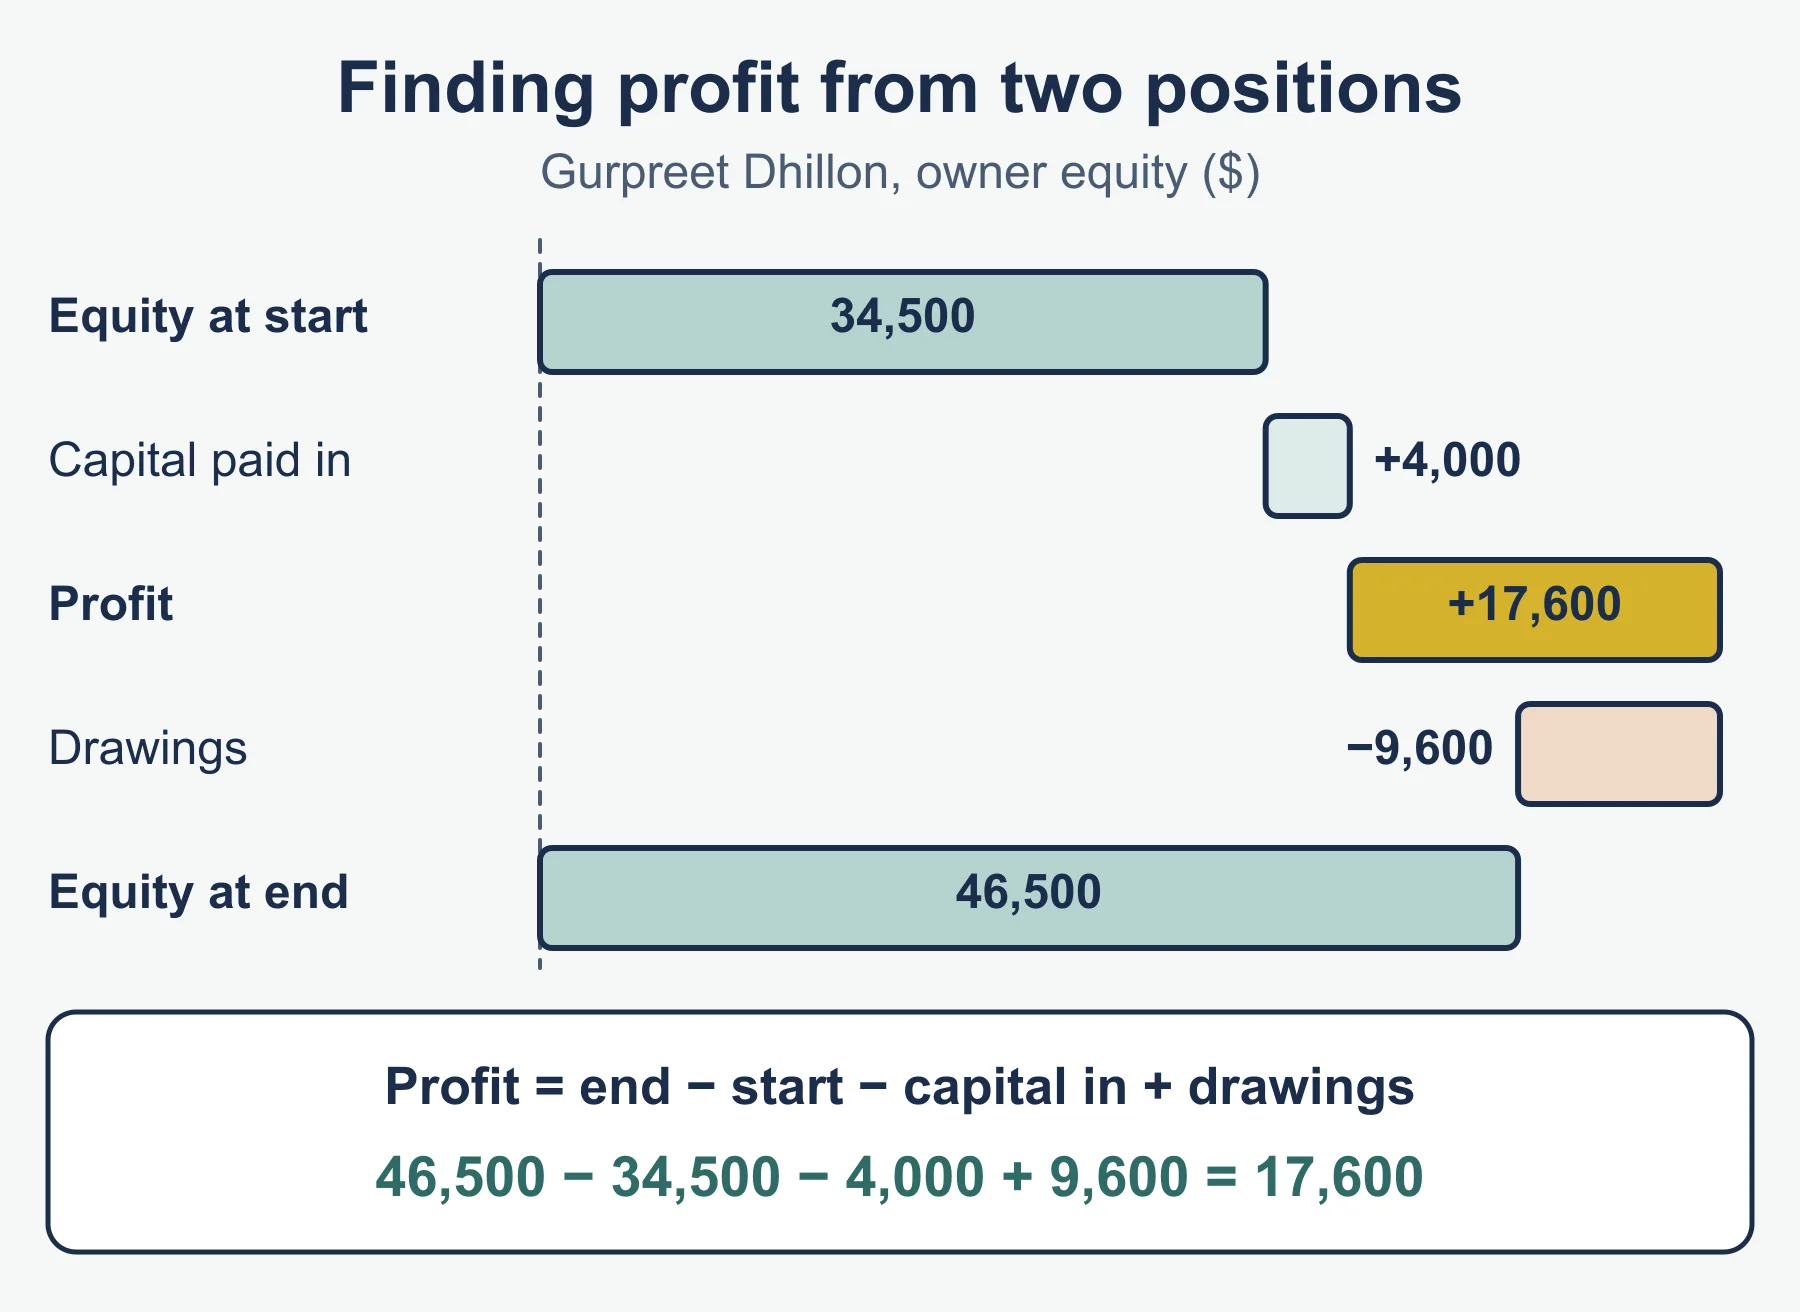
Gurpreet’s position at the start and end of the year, in dollars:
| Start | End | |
|---|---|---|
| Assets | 52,000 | 61,800 |
| Liabilities | 17,500 | 15,300 |
| Owner’s equity | 34,500 | 46,500 |
Owner’s equity rose by 12,000. During the year she paid in 4,000 of extra capital and took 9,600 in drawings. Profit = closing equity − opening equity − capital introduced + drawings = 46,500 − 34,500 − 4,000 + 9,600 = 17,600.
Common errors
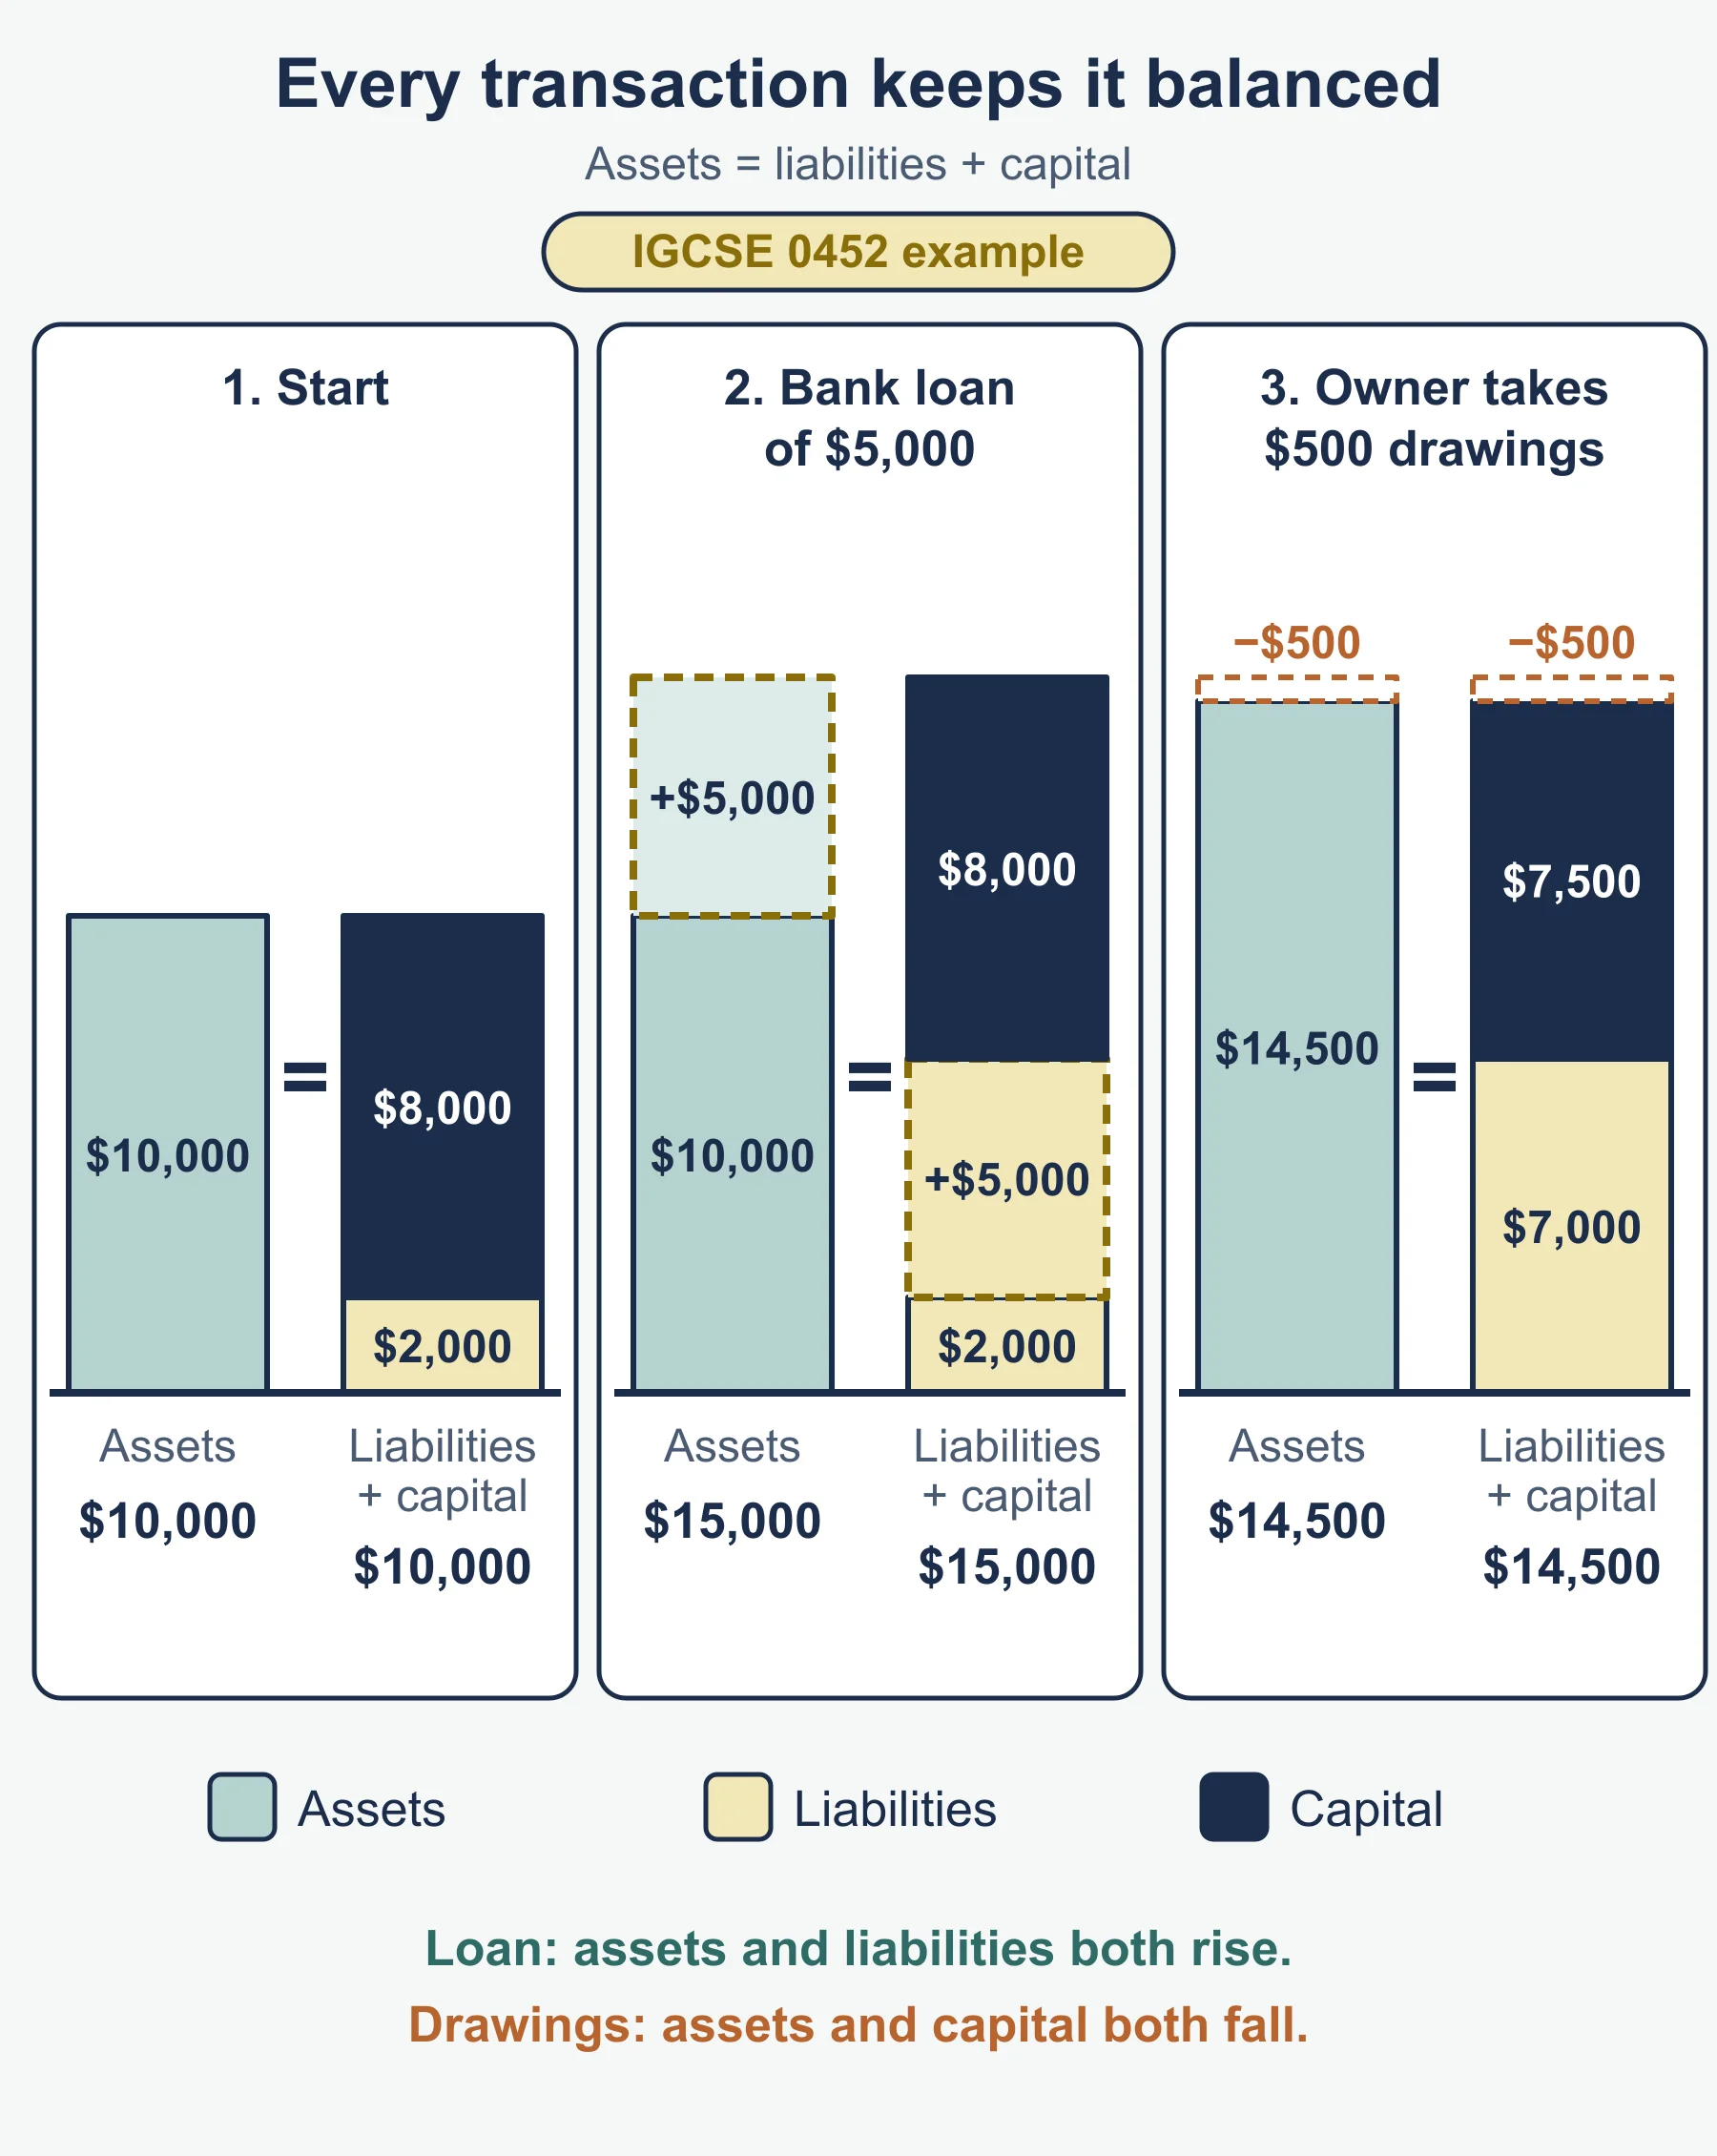
- Treating drawings as an expense. Drawings reduce owner’s equity directly and are not deducted when finding profit.
- Calling profit “the cash we have”. Profit is a measure of performance; the bank balance can differ from it.
- Listing a bank overdraft as an asset.
- Swapping trade receivables and trade payables.
- Saying that borrowing increases owner’s equity. A loan raises assets and liabilities by the same amount.
- Writing book-keeping and accounting as if they mean the same thing, or defining accounting as “writing in the books”.
- Stopping after one half of a transaction. Ask what the second change is.
Frequently asked questions
What is profit in Cambridge IGCSE Accounting 0452? Profit is the amount by which income earned in a period exceeds the expenses of earning it. If expenses are greater than income, the business has made a loss.
Are trade receivables an asset or a liability? Trade receivables are an asset, because they are customers who owe the business money. Trade payables are a liability, because they are suppliers the business owes.
Are drawings an expense? No. Drawings reduce owner’s equity directly and are not deducted when finding profit, so treating them as an expense is a common error.
Can a transaction change total assets without changing owner’s equity? Yes. Buying an asset on credit raises assets and liabilities together, and swapping one asset for another leaves total assets unchanged. Only capital introduced, profit, loss and drawings change owner’s equity.
Why is accounting information compared with other figures? Accounting information is useful because it is compared with something: an earlier period, a plan or another business. The comparison lets an owner monitor progress and supports decisions such as whether to hire staff.
Official syllabus
Cambridge IGCSE Accounting 0452 syllabus for exams in 2027, 2028 and 2029 (version 1), published by Cambridge University Press & Assessment (Cambridge International Education). Sections 1.1 and 1.2.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Revision notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
Accounting · Cambridge · IGCSE, O Level
Revise topic -
Practice questions
IGCSE Accounting: The purpose of accounting and the accounting equation (Cambridge 0452) – Practice Questions
Ten original questions with worked answers on book-keeping, profit and loss and the accounting equation for Cambridge IGCSE Accounting 0452.
Accounting · Cambridge · IGCSE, O Level
Try questions -
Revision notes
IGCSE Accounting: The purpose of accounting and the accounting equation (Cambridge 0452) – Revision Notes
Condensed notes on book-keeping versus accounting, profit and loss and the accounting equation for Cambridge IGCSE Accounting 0452, with a self-test.
Accounting · Cambridge · IGCSE, O Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

