
Revision Notes
OxfordAQA IGCSE Accounting: Bank reconciliation statements (9215) – Revision Notes
Condensed recall notes, method steps and a self-test on cash book updating and bank reconciliation statements for OxfordAQA IGCSE Accounting.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Verification of accounting records
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to OxfordAQA IGCSE Accounting (9215), First teaching 2024, first examined 2026. Official specification .
Syllabus page (what it covers and how it is assessed): OxfordAQA IGCSE Accounting.
Syllabus points this page covers
9215
- Prepare and understand the use and purpose of bank reconciliation statements
Found an error? Report a correction.
Need help with this topic? Request a free trial class for IGCSE Accounting (9215).
These notes condense the bank reconciliation statements study guide for the OxfordAQA International GCSE Accounting (9215) specification, version 1.2, section 3.2. Use the guide for explanations and the practice questions once you can recall everything below. All amounts are in dollars. For the other verification techniques see the Verification of Accounting Records revision notes. Find the course on the hub, tick it off on the checklist and check your starting level with the free diagnostics.
Key terms
| Term | Meaning |
|---|---|
| Bank statement | The bank’s record of the account, sent to the business; outside evidence for checking the cash book |
| Cash book (bank column) | The business’s own record of the same account |
| Bank reconciliation statement | A working that explains the difference between the two balances |
| Unpresented cheque | A cheque the business has paid out and recorded, but the bank has not yet deducted |
| Outstanding banking | A banking entered in the cash book that the bank has still to credit |
| Bank error | A mistake in the bank’s record, corrected on the reconciliation only |
| Direct debit | Payment collected by the payee under your authority; amount can vary |
| Standing order | Fixed payment made by the bank on set dates on your instruction |
| Credit transfer | A payment made straight into your account by another person |
Why the two records differ
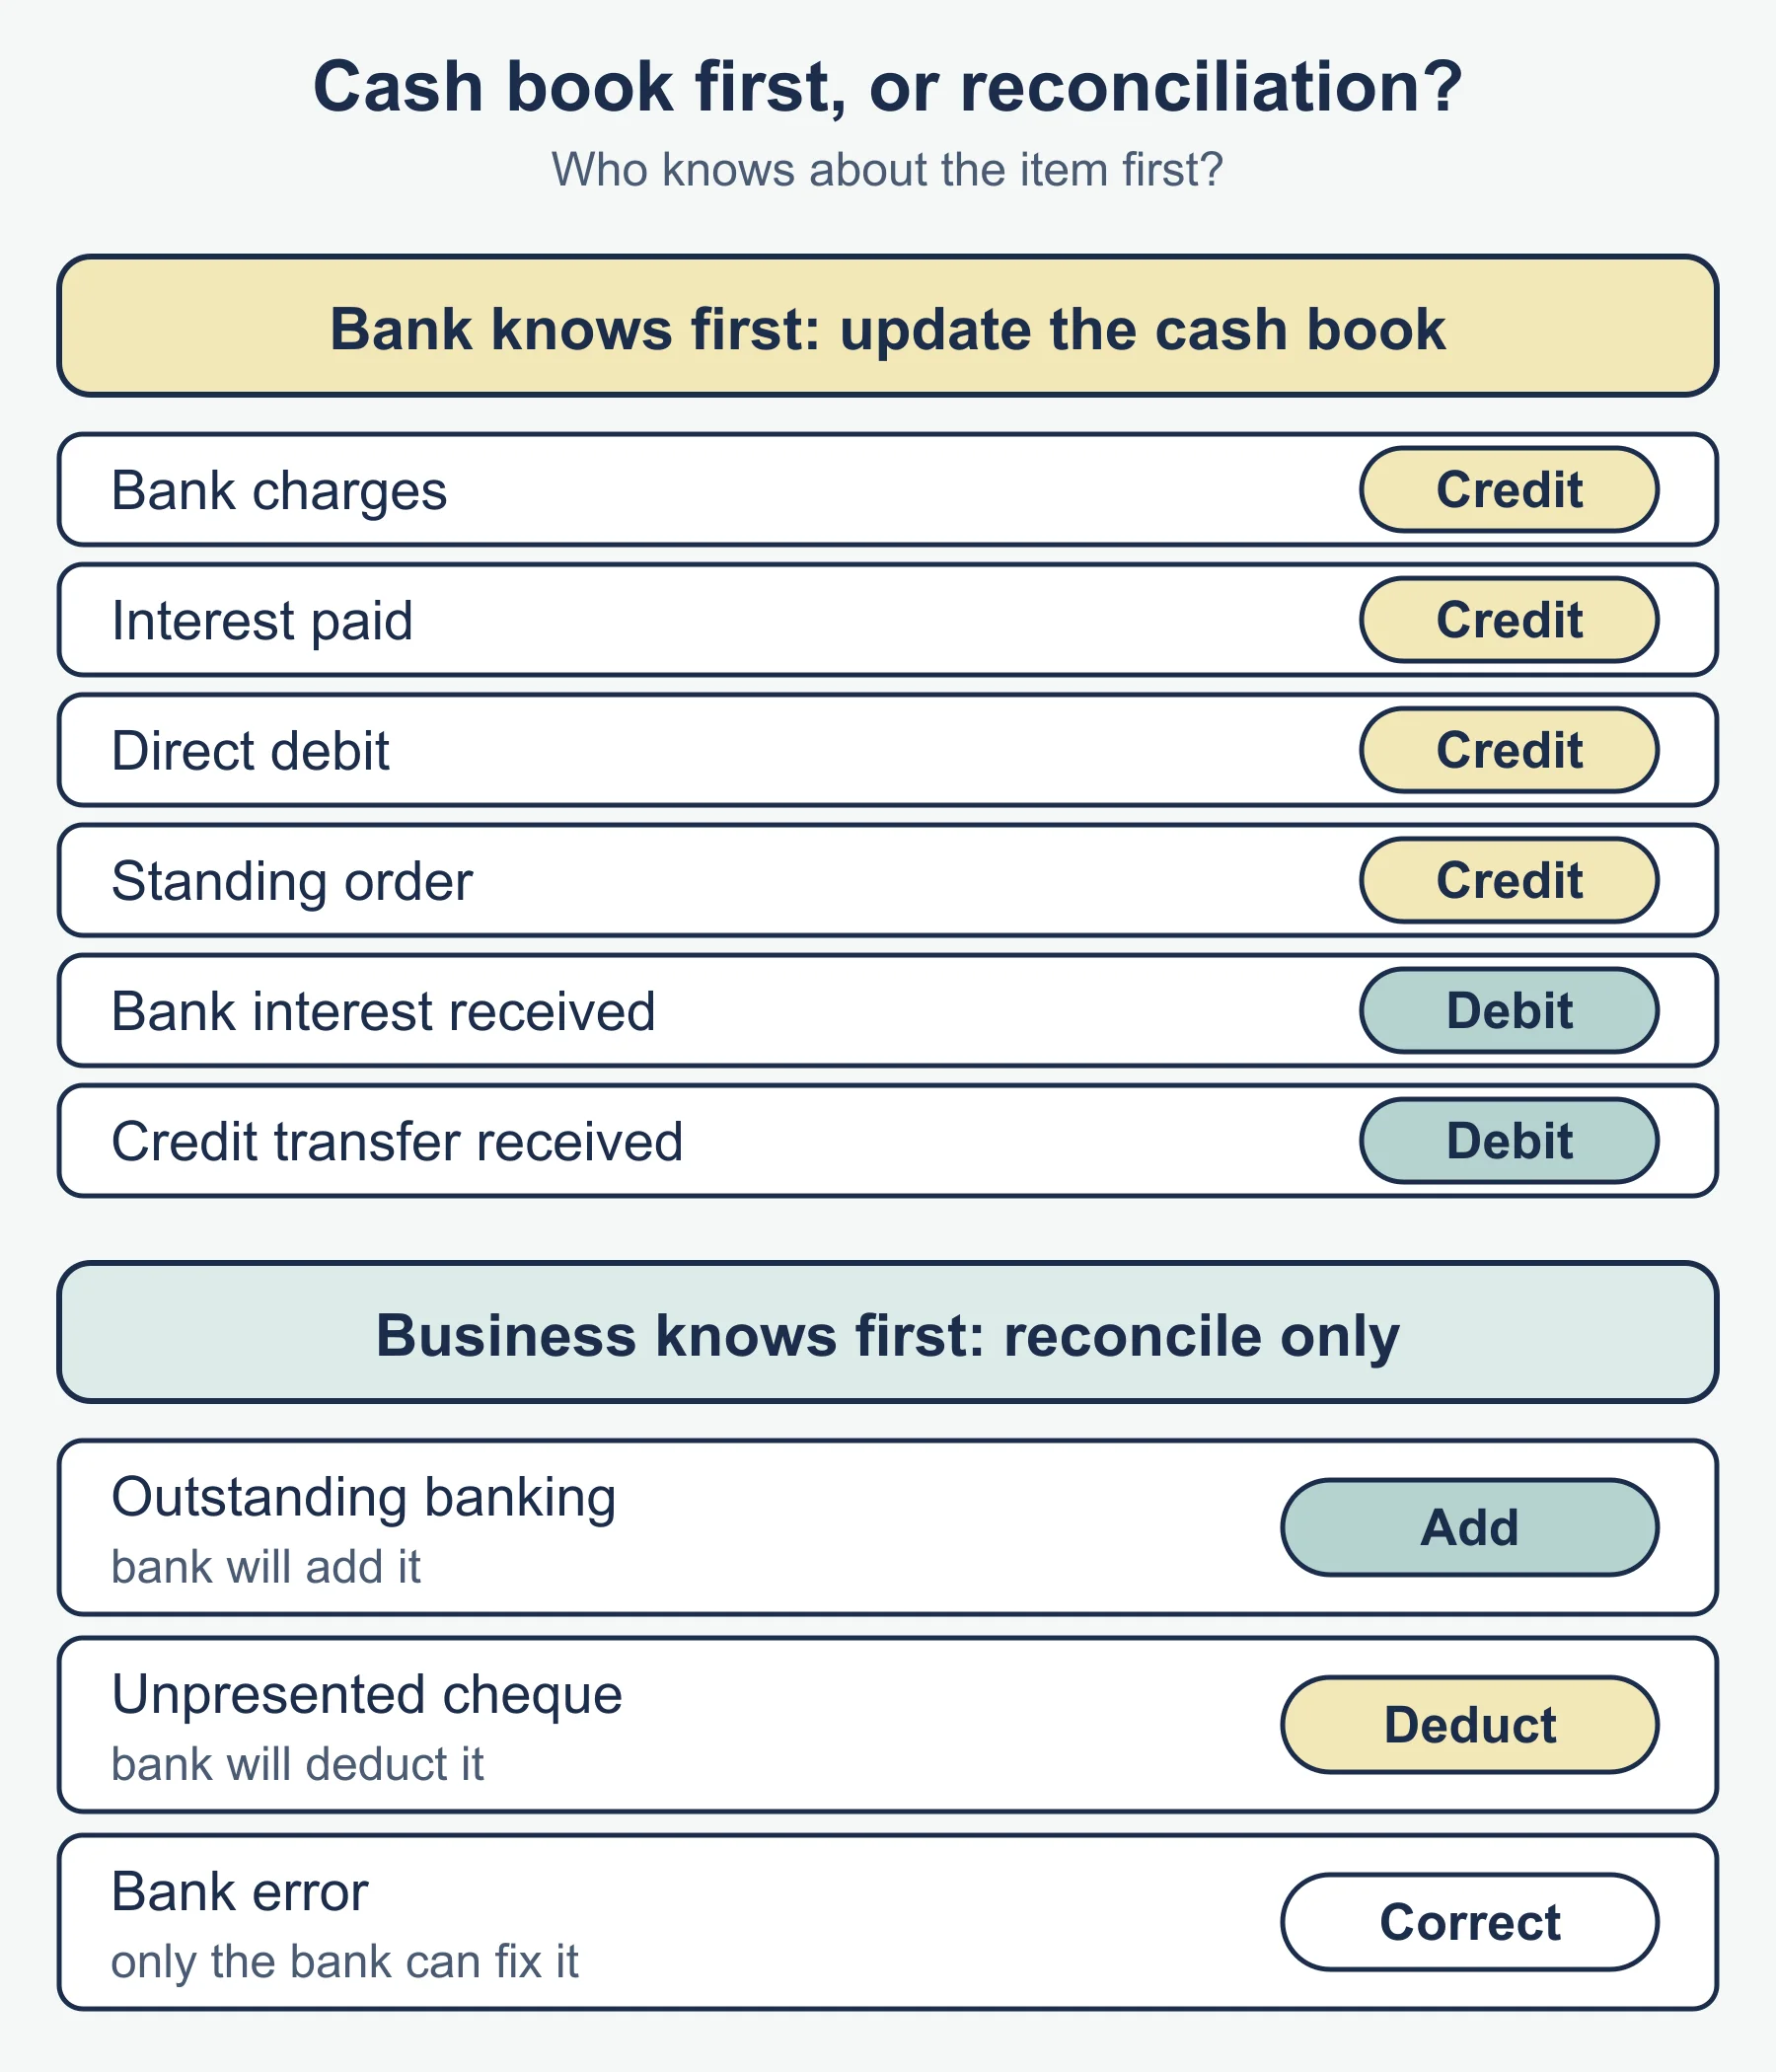
- The bank has an item the cash book lacks: charges, interest, direct debit, standing order, credit transfer.
- The cash book has an item the bank lacks: unpresented cheque, outstanding banking.
- A mistake: a cash book error (you fix it in the cash book) or a bank error (you fix it on the reconciliation).
Cash book updating table
| Item | Side of cash book |
|---|---|
| Bank charges | Credit |
| Interest paid | Credit |
| Bank interest received | Debit |
| Direct debit | Credit |
| Standing order | Credit |
| Credit transfer received | Debit |
| Receipt omitted or understated | Debit the difference |
| Payment omitted or understated | Credit the difference |
| Receipt overstated | Credit the difference |
| Payment overstated | Debit the difference |
Method in steps
- List every difference and classify it: cash book entry, timing item, or bank error.
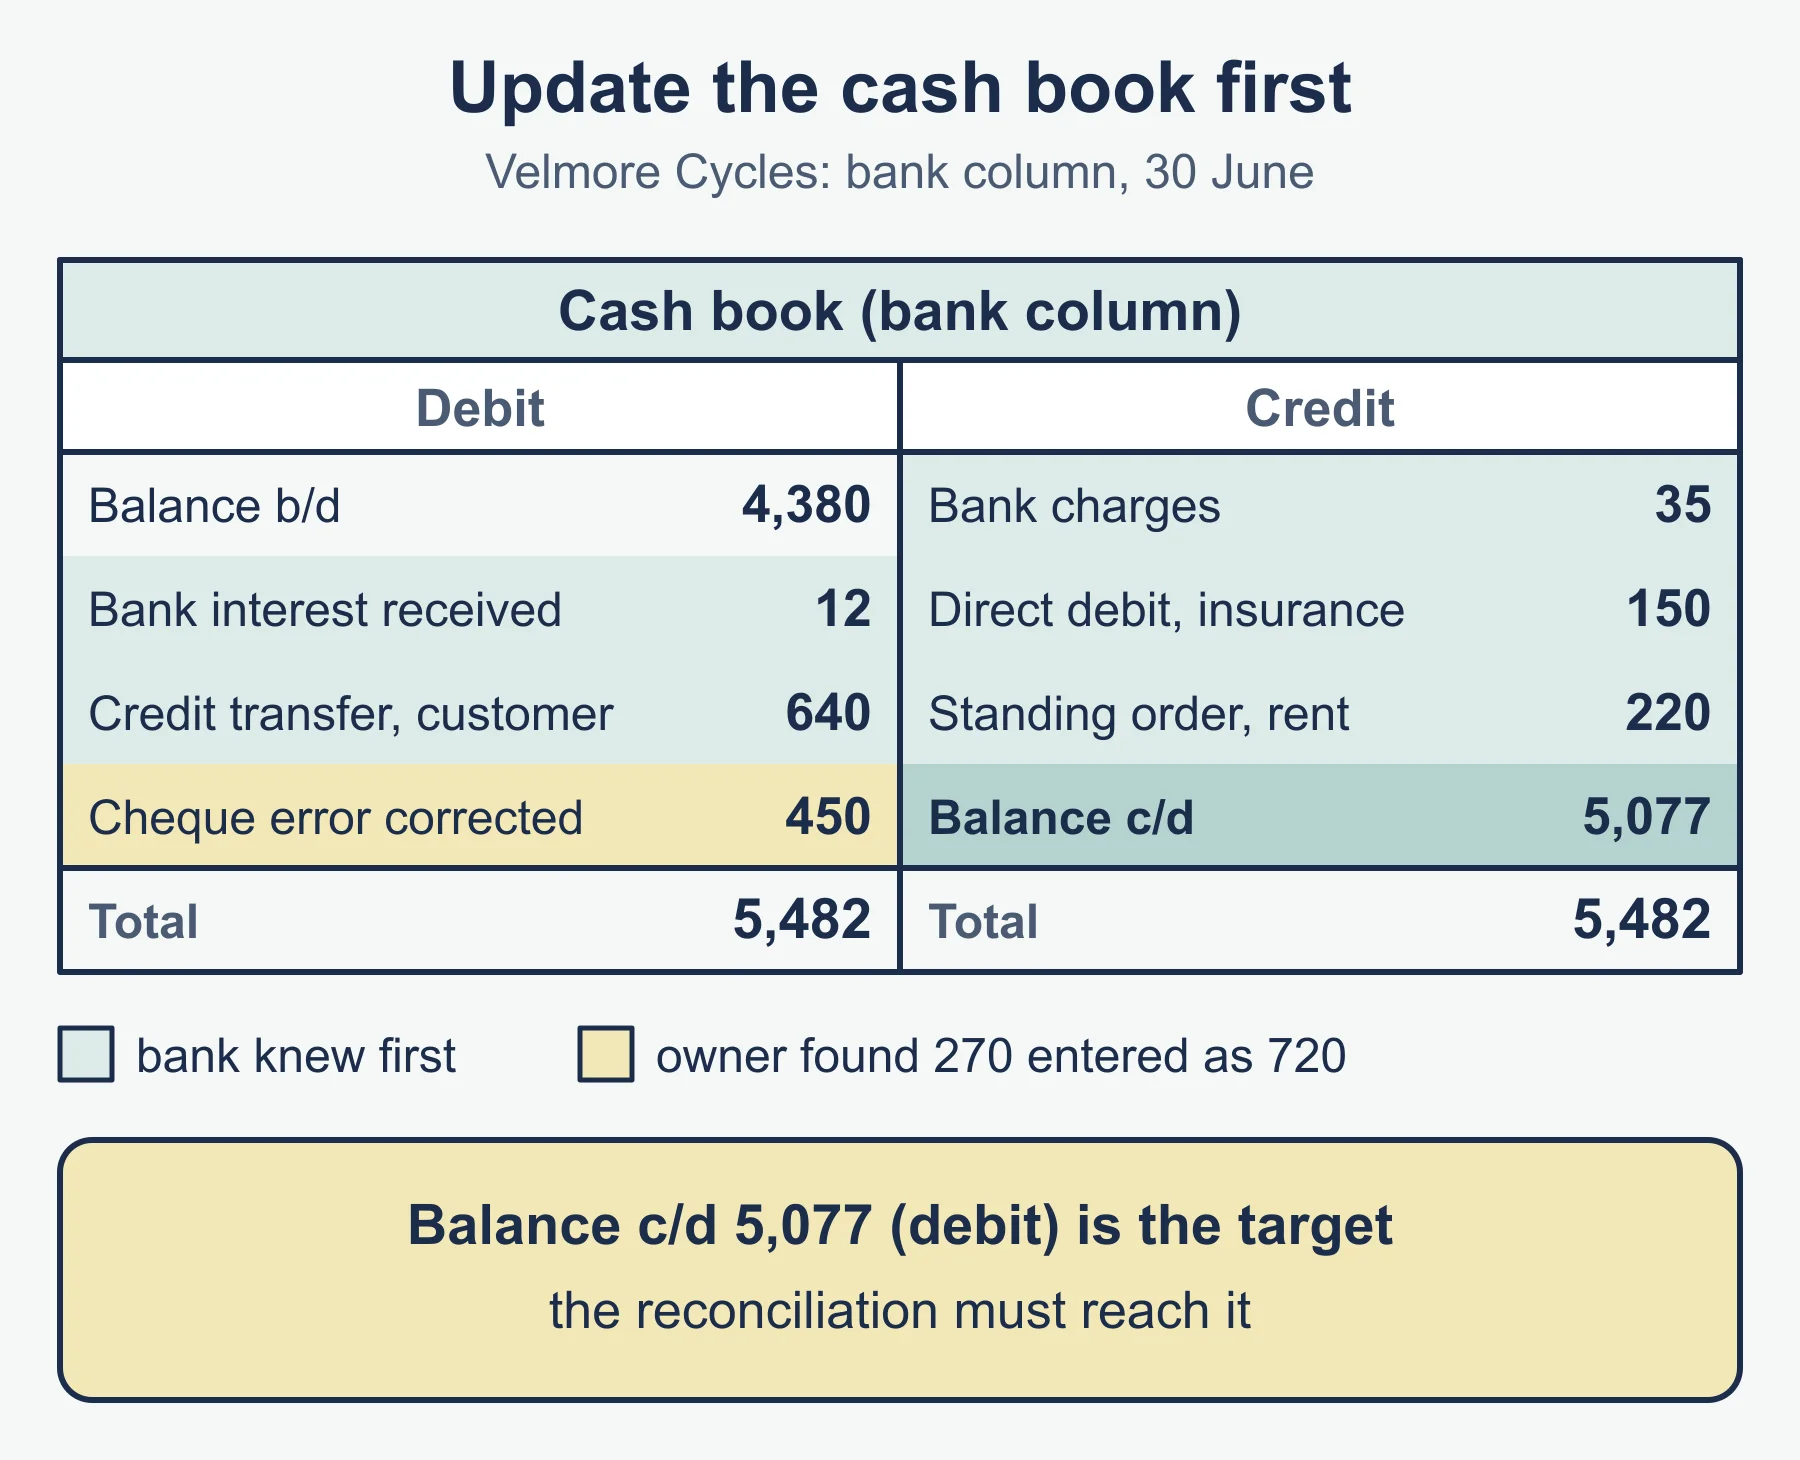
- Update the cash book, entering each cash book item, and find the new balance.
- Write the bank statement balance as the first line of the reconciliation.
- Add outstanding bankings.
- Deduct unpresented cheques.
- Adjust for bank errors: add if the bank took out too much or failed to credit something; deduct if the bank credited something it should not have.
- Compare the result with the updated cash book balance. If it differs, an item has been missed or put on the wrong side.
Reconciliation layout
Bank reconciliation statement at (date)
Balance per bank statement                  xxx
Add:  outstanding bankings                  xxx
Add or less: bank errors                    xxx
Less: unpresented cheques                  (xxx)
Balance per updated cash book               xxx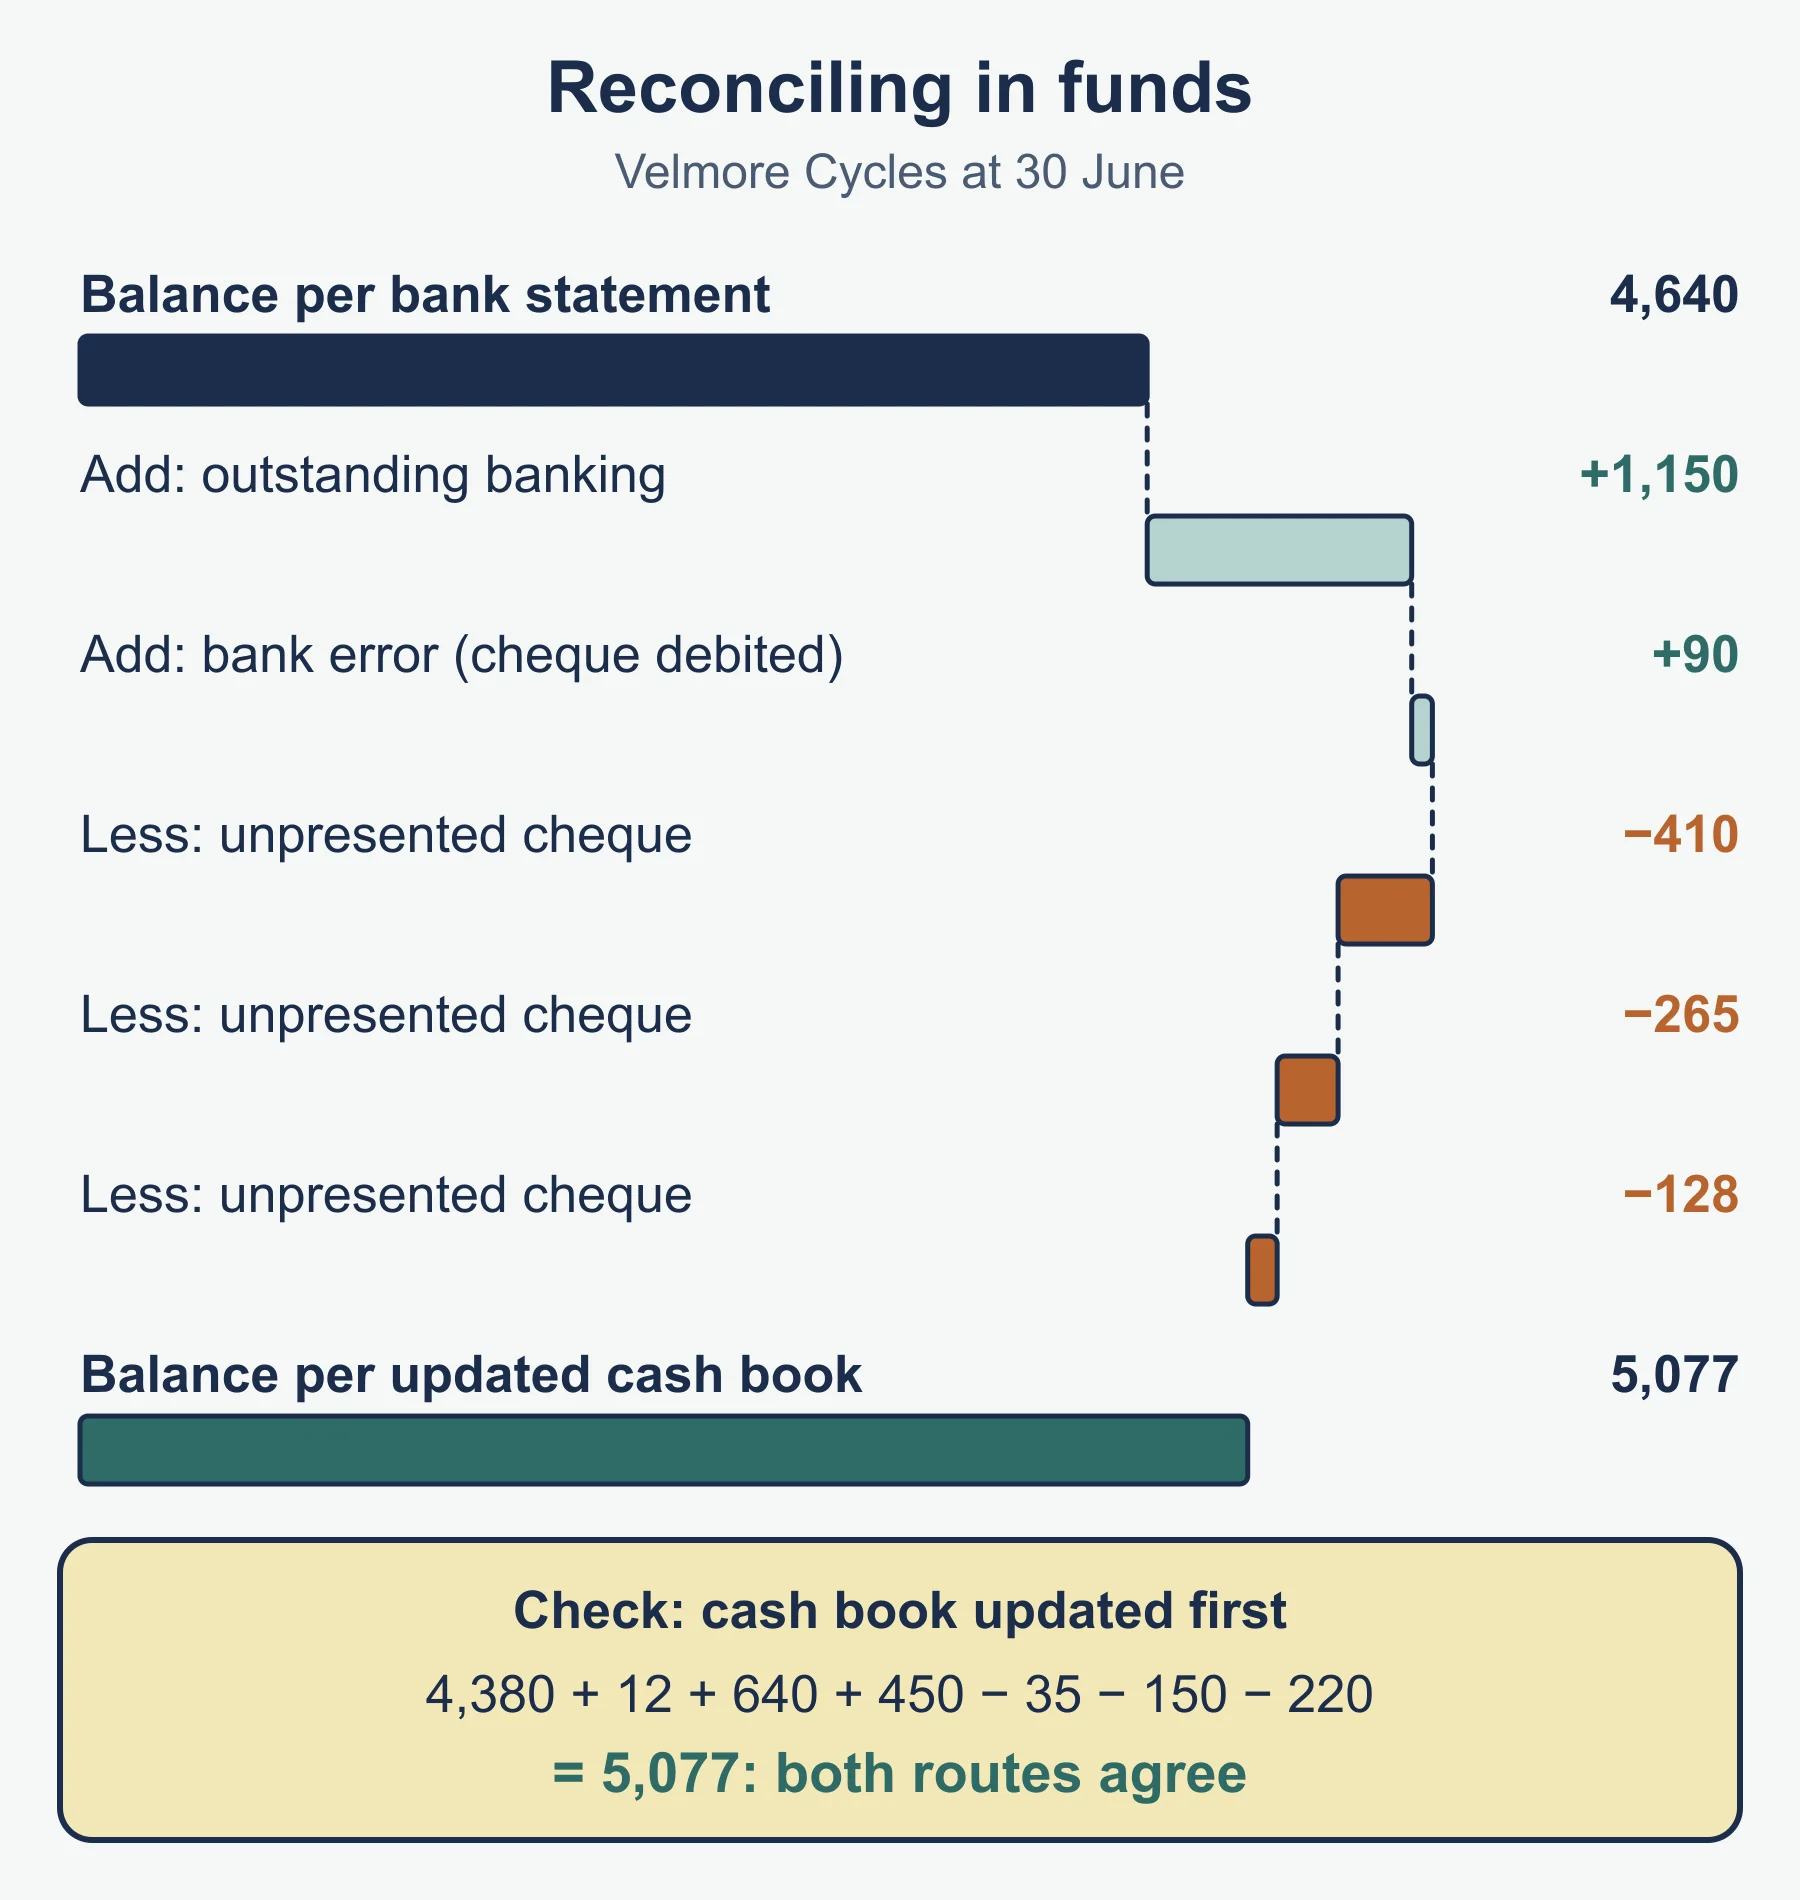
Small worked reminder
Thorncroft Tools has a cash book debit balance of 2,500. The bank statement shows charges of 60, interest received of 25 and a direct debit of 180, none yet in the cash book.
Updated cash book: 2,500 - 60 + 25 - 180 = 2,285 (debit)If the bank statement balance is 2,610 (credit) and the only other differences are one unpresented cheque of 325, the check is: 2,610 less 325 equals 2,285. The reconciliation agrees.
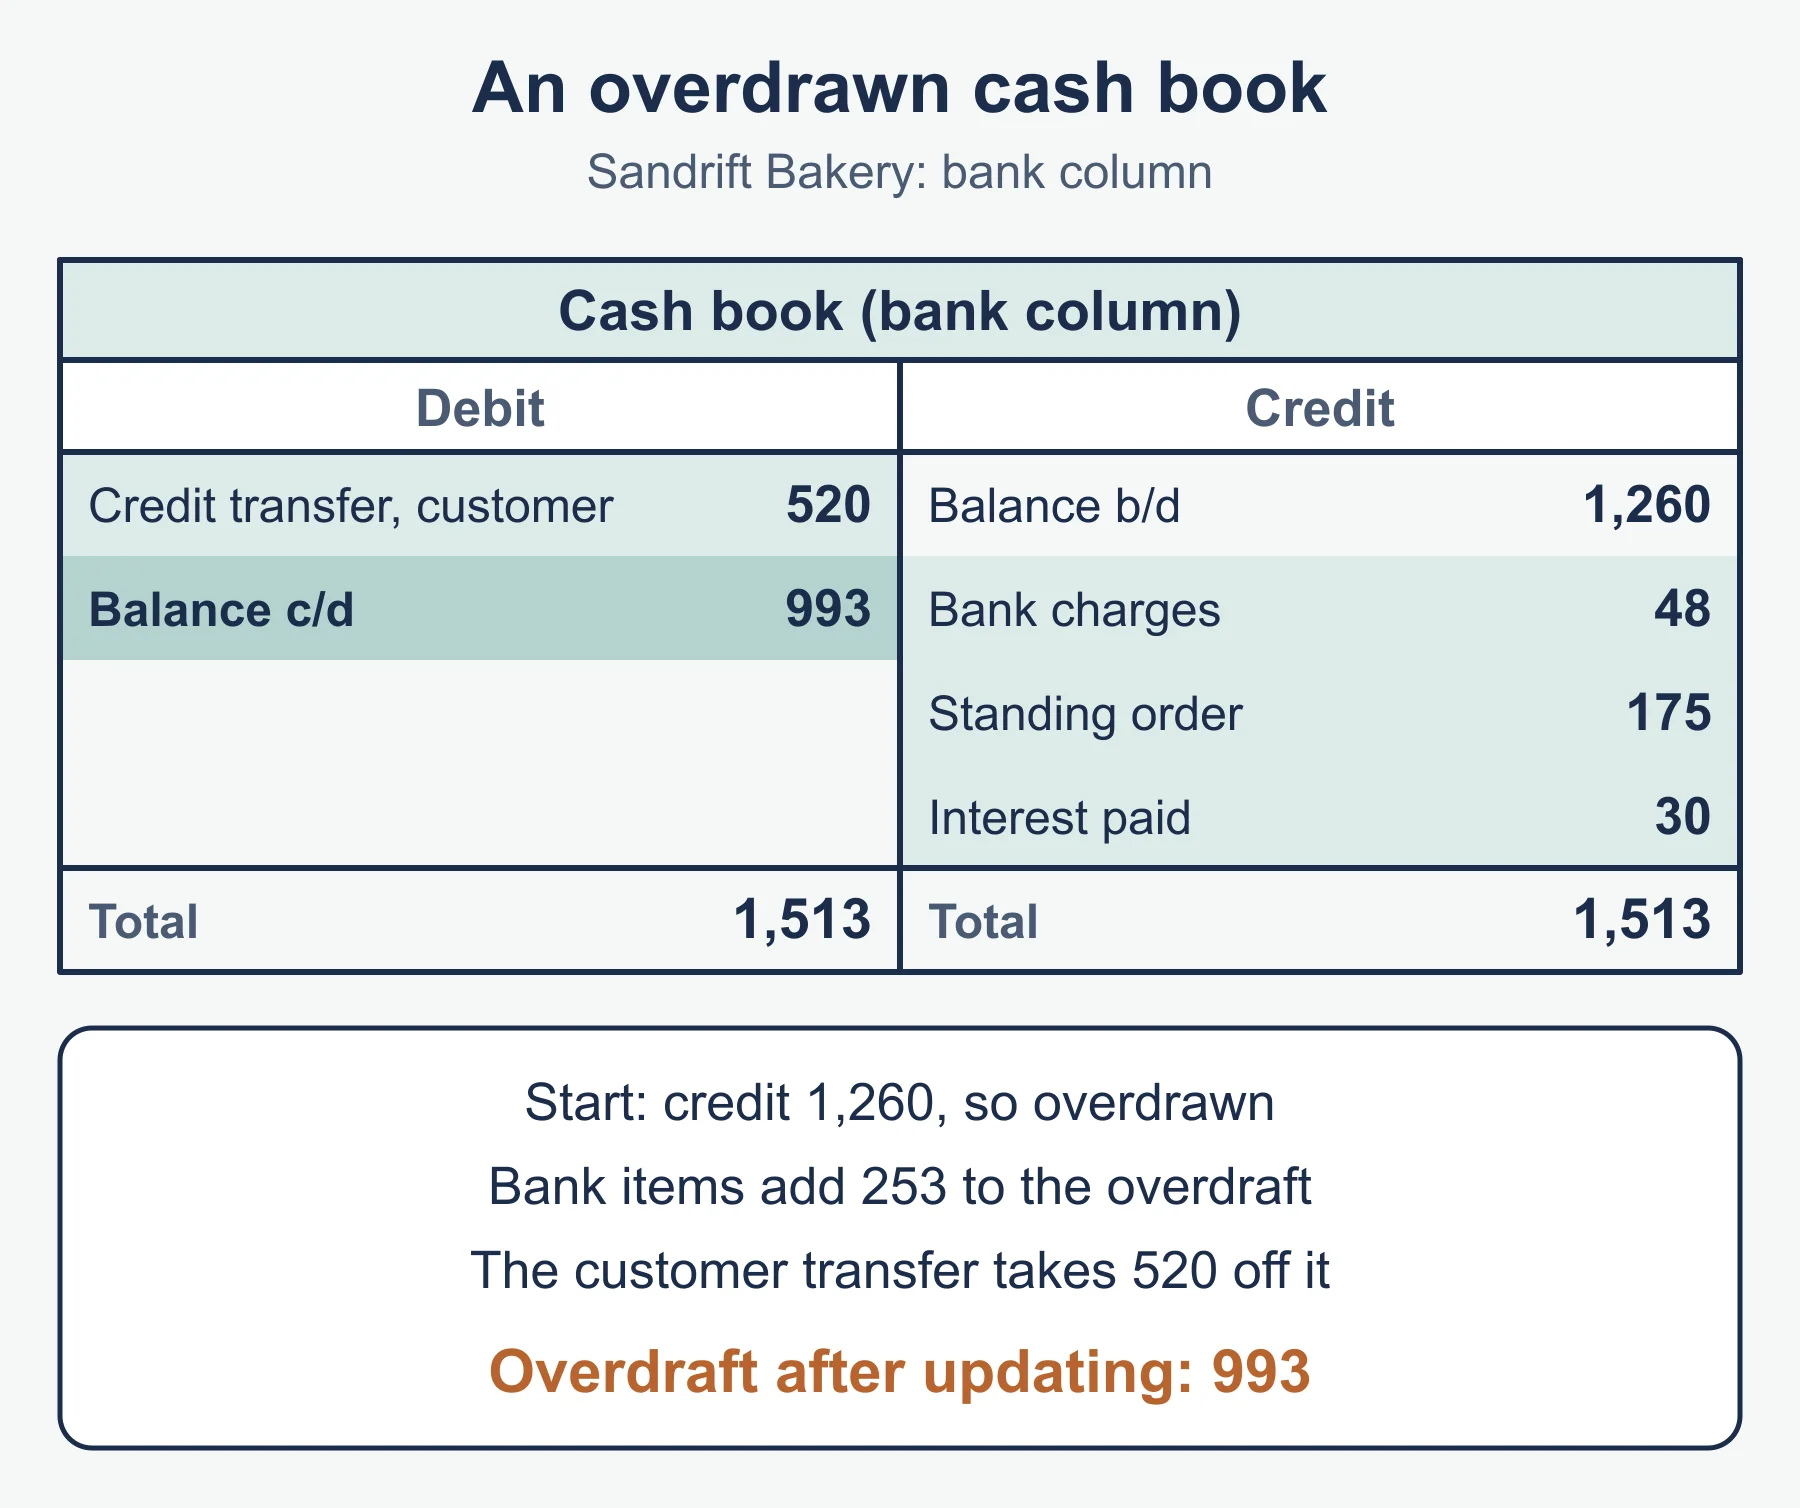
Overdraft reminder
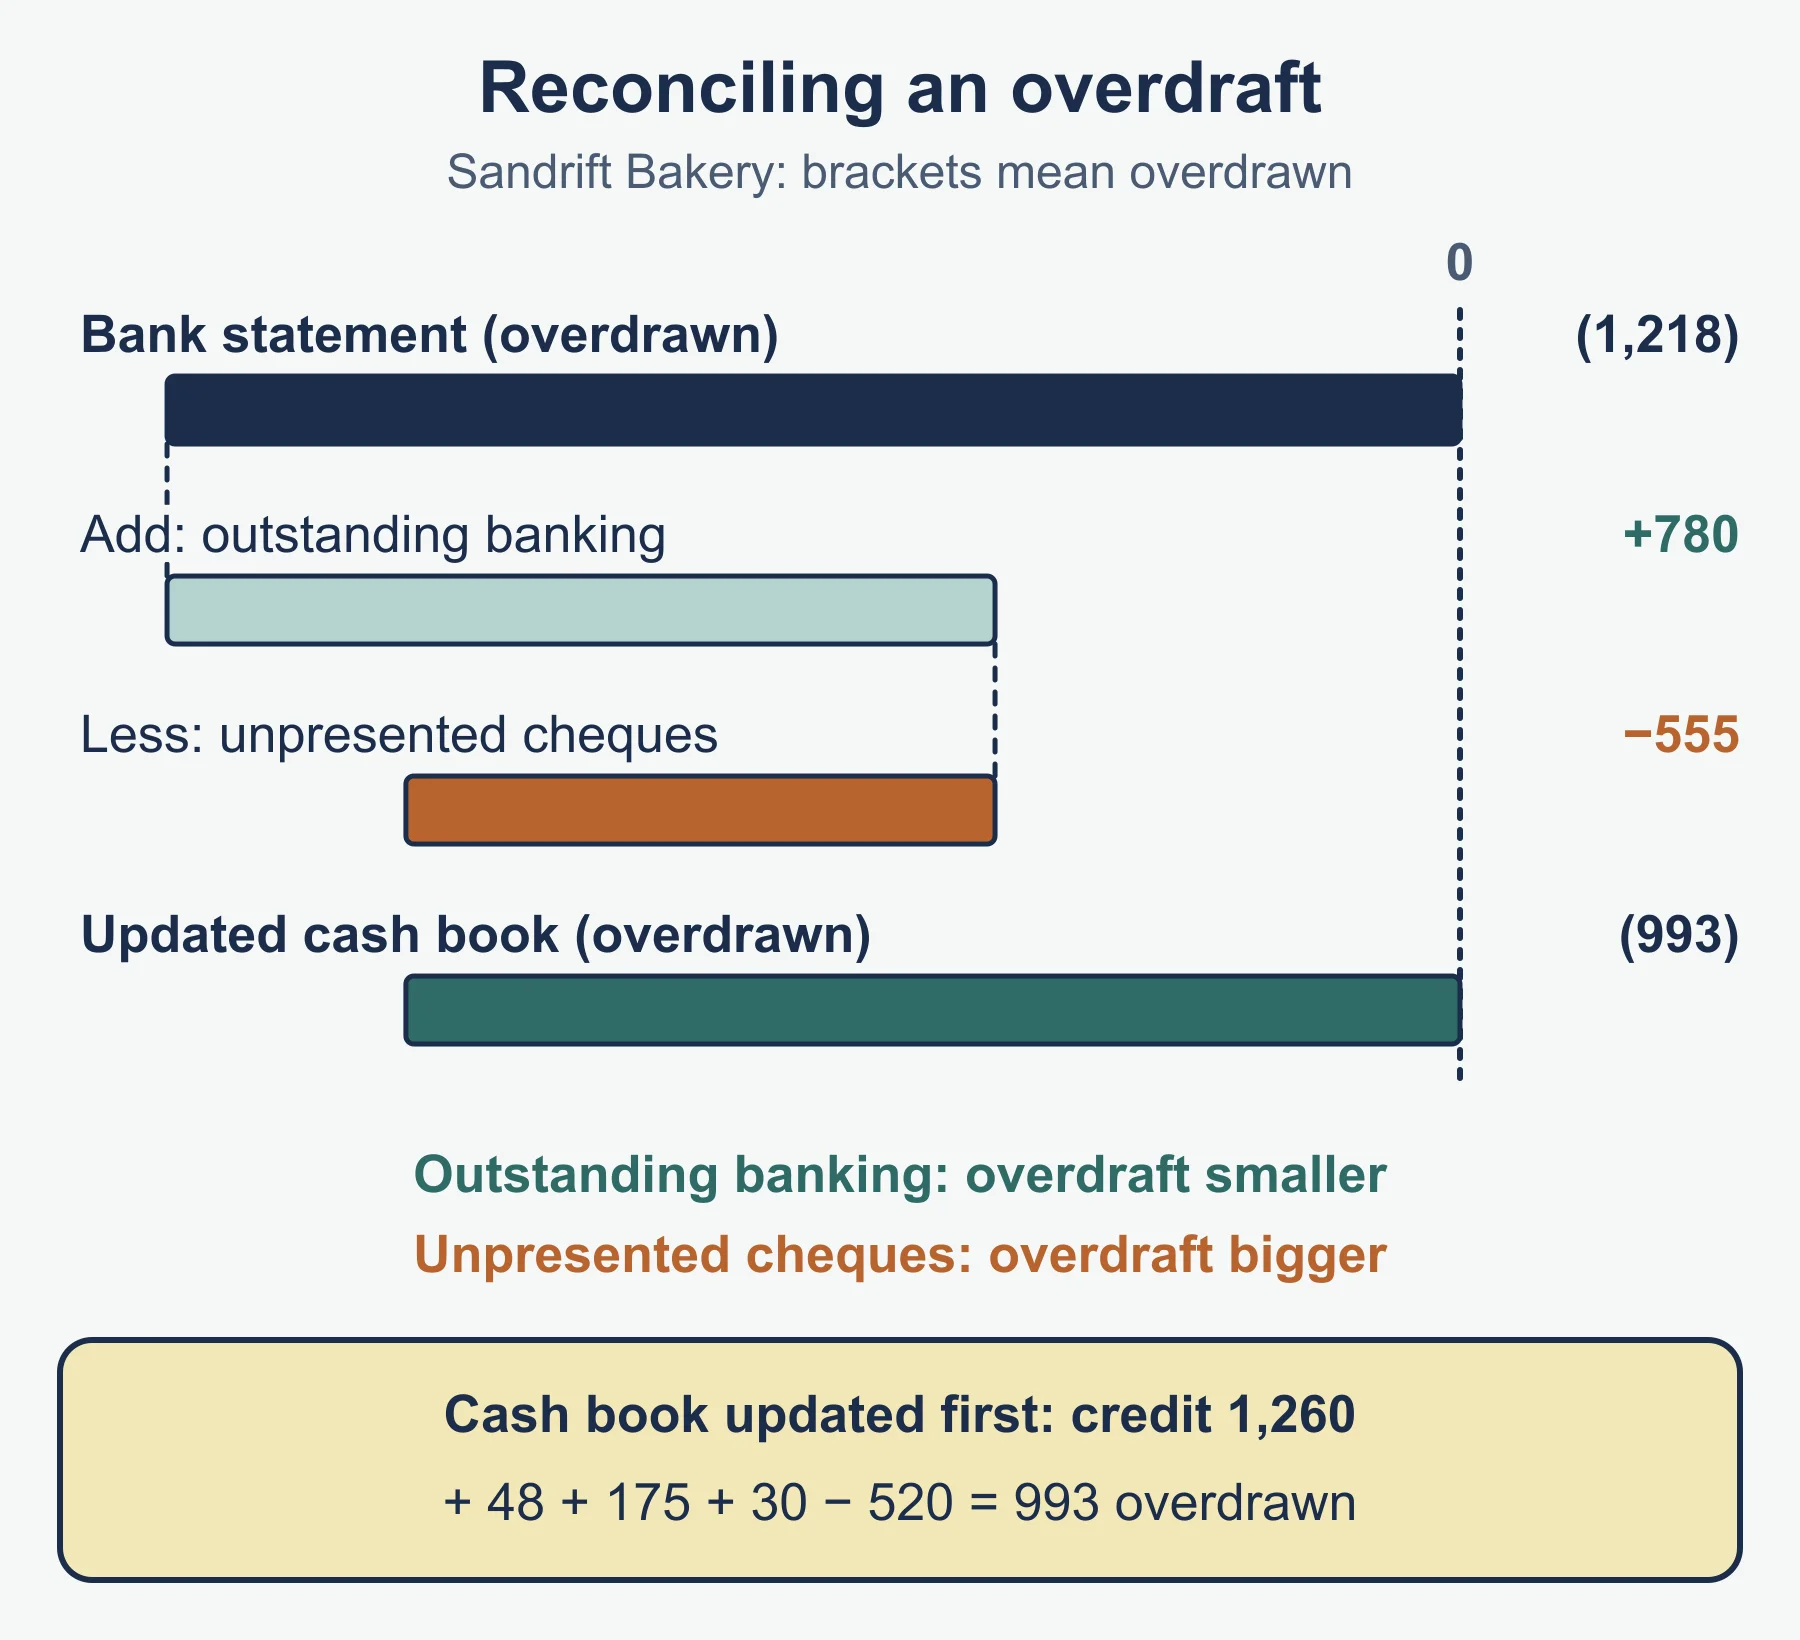
Thorncroft Tools in a different month has a cash book credit balance of 920 (overdrawn). Bank charges of 30 and a standing order of 110 are missing, so the updated balance is an overdraft of 1,060. It has an unpresented cheque of 240 and an outstanding banking of 500. The bank statement overdraft must therefore be 1,320.
Balance per bank statement (overdrawn)    (1,320)
Add: outstanding banking                     500
                                            (820)
Less: unpresented cheque                    (240)
Balance per updated cash book (overdrawn) (1,060)
Treat an overdraft as a negative figure and use the same add and deduct rules. Adding an outstanding banking makes the overdraft smaller.
Command words in this topic
| Command word | What the answer needs |
|---|---|
| State | A short fact, such as one reason for a difference |
| Calculate | The figure, with the working shown so that a slip does not lose everything |
| Prepare | A full statement with heading, date, labelled lines and a final balance |
| Explain | A reason joined to the fact with because or so |
| Identify | Pick the item or error out of the information given |
Where each item goes at a glance
| Item in the question | Cash book entry needed? | On the reconciliation? |
|---|---|---|
| Bank charges | Yes | No |
| Direct debit not yet recorded | Yes | No |
| Unpresented cheque | No | Yes, deduct |
| Outstanding banking | No | Yes, add |
| Bank error | No | Yes, add or deduct |
| Cash book error | Yes | No |
Check the table after you have classified your items. An item should never appear in both places.
Must-know distinctions
| Compare | Key point |
|---|---|
| Unpresented cheque vs outstanding banking | The first is a payment, deducted from the bank statement balance; the second is a receipt, added |
| Cash book error vs bank error | Cash book errors are corrected in the cash book; bank errors on the reconciliation |
| Direct debit vs standing order | Direct debit is initiated by the payee and can vary; standing order is fixed by you |
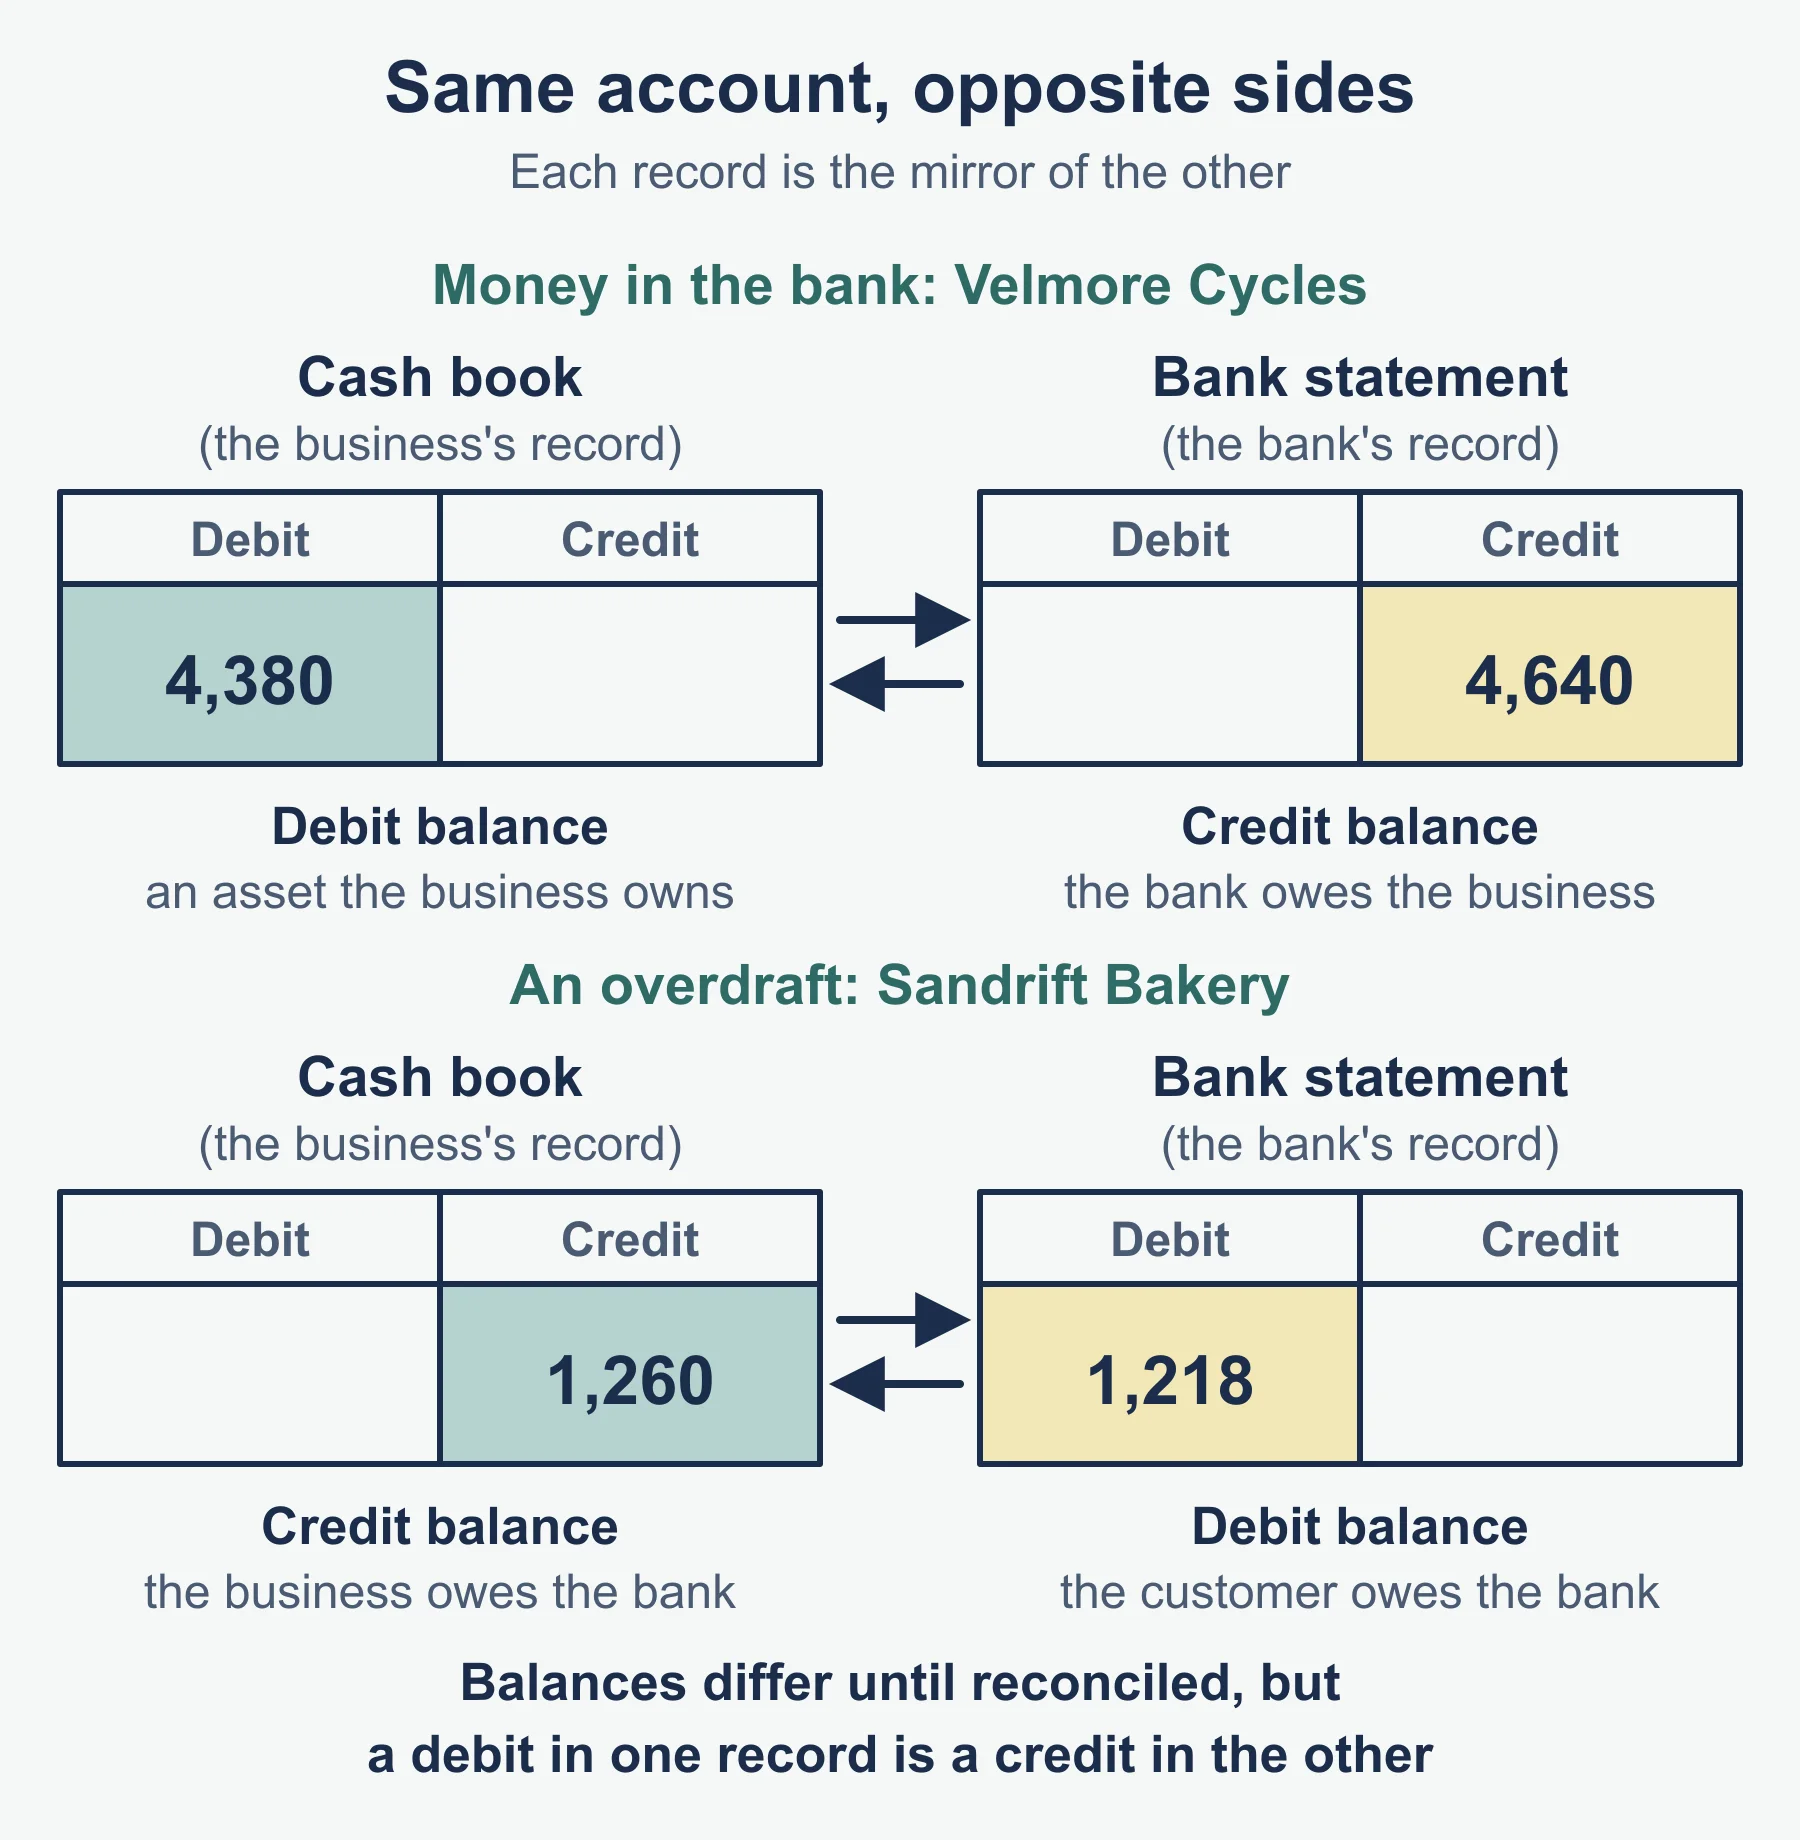
| Cash book debit balance vs bank statement balance | A favourable balance is debit in the cash book and credit on the bank statement |
| Updating the cash book vs reconciling | The first adjusts your own record; the second explains the gap to the bank record |
Limits of the statement
A reconciliation checks the bank account only. It will not show an error that appears in both the cash book and the bank statement, and it does not prove that the rest of the ledger is correct. Prepare it regularly, so that old unpresented cheques and unrecorded items are noticed early.
Use and purpose, in short
- Confirms the cash at bank figure used in the statement of financial position.
- Finds errors in the cash book and in the bank’s record.
- Reveals items not yet recorded, such as charges and standing orders.
- Helps spot fraud, such as unauthorised payments.
- Shows which bankings and cheques are still to clear.
Quick self-test
- State one reason why a bank statement may show a lower balance than the cash book.
- Which side of the cash book takes a credit transfer received?
- A cash book has a debit balance of 1,800. Bank charges of 42 and a standing order of 130 are missing. What is the updated balance?
- A bank statement shows a credit balance of 1,900. There are unpresented cheques of 300 and an outstanding banking of 450. What is the balance per updated cash book?
- A bank statement shows an overdraft of 640 and unpresented cheques of 200. There are no other differences. What is the cash book balance?
- Is a bank error corrected in the cash book? Explain briefly.
- A cash book has a credit balance of 410 (overdrawn). A credit transfer of 500 from a customer is not yet recorded. What is the updated balance and is it debit or credit?
- A payment of 85 was recorded in the cash book as 58. Is the correction a debit or credit, and for what amount?
- Give one use of preparing a bank reconciliation statement.
- Why is an unpresented cheque deducted from the bank statement balance?
Answers
- Any of: an unpresented cheque, or bank charges or a direct debit the cash book has not recorded.
- The debit side.
- 1,800 - 42 - 130 = 1,628 (debit).
- 1,900 - 300 + 450 = 2,050.
- The statement balance is minus 640; minus 640 minus 200 gives minus 840, an overdraft of 840 (credit balance in the cash book).
- No. The error is in the bank’s record, so the cash book is right; it is corrected on the reconciliation and the business tells the bank.
- -410 + 500 = 90, a debit balance (the account is now in funds).
- Credit, 27 (85 - 58), because the payment was understated and the balance overstated.
- Any of: confirm the cash at bank figure, find errors, reveal unrecorded items, detect fraud.
- The business has already recorded the payment but the bank has not yet taken it out, so the bank balance is too high until the cheque is presented.
Where marks are usually lost
- Starting the reconciliation from the old cash book balance instead of the bank statement balance, or ending on the wrong balance.
- Adding unpresented cheques and deducting outstanding bankings.
- Posting a bank error to the cash book.
- Putting direct debits and standing orders on the debit side.
- Showing no label for overdrawn balances, so the examiner cannot tell which sign you intended.
- Leaving out brackets or dates in the heading.
- Using a rounded or incomplete list of items, so that the reconciliation does not agree and no check is shown.
- Answering “explain” questions with a list of names and no reason.
Frequently asked questions
What is the difference between an unpresented cheque and an outstanding banking? An unpresented cheque is a payment entered in the cash book that the bank has not yet deducted, so it is deducted from the bank statement balance. An outstanding banking is a receipt not yet credited by the bank, so it is added.
What is the difference between a direct debit and a standing order? A direct debit is collected by the payee under the business’s authority and the amount can vary. A standing order is a fixed amount set up by the business itself.
Are bank errors corrected in the cash book? No. Cash book errors are corrected in the cash book, while bank errors are dealt with on the reconciliation statement.
Why is a favourable balance a debit in the cash book but a credit on the bank statement? The two records look at the same account from opposite sides. Money in the bank is an asset of the business (debit) but an amount the bank owes the business (credit).
What can a bank reconciliation not show? It checks the bank account only, so it will not reveal an error that appears in both the cash book and the bank statement.
Official syllabus
OxfordAQA International GCSE Accounting (9215) specification, version 1.2, for International GCSE exams May/June 2026 onwards, published by OxfordAQA. Section 3.2, Verification of accounting records: prepare and understand the use and purpose of bank reconciliation statements.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
OxfordAQA IGCSE Accounting: Correcting errors and the effect of errors on profit (9215)
Journal entries, the suspense account and corrected profit for every error type in OxfordAQA International GCSE Accounting 9215, with full worked examples.
Accounting · OxfordAQA · IGCSE
Read guide -
Practice questions
OxfordAQA IGCSE Accounting: Correcting errors and the effect of errors on profit (9215) – Practice Questions
Twelve original questions with worked answers on journal corrections, the suspense account and corrected profit for OxfordAQA Accounting 9215.
Accounting · OxfordAQA · IGCSE
Try questions -
Revision notes
OxfordAQA IGCSE Accounting: Correcting errors and the effect of errors on profit (9215) – Revision Notes
Condensed recall notes, method steps and a ten-question self-test on journal corrections, the suspense account and corrected profit for OxfordAQA 9215.
Accounting · OxfordAQA · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
OxfordAQA Accounting teachers at Marlbridge

