
Study Guides
OxfordAQA IGCSE Business: Technology and Ethical and environmental considerations (9225)
A full teaching guide to e-commerce, digital communication, ethics, the environment and sustainability for OxfordAQA International GCSE Business.
- Subject
- Business
- Level
- IGCSE
- Topic
- Influences on business
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to OxfordAQA IGCSE Business (9225), First teaching September 2020, first examined May/June 2022. Official specification .
Syllabus page (what it covers and how it is assessed): OxfordAQA IGCSE Business.
Syllabus points this page covers
9225
- 3.2.1 Technology
- 3.2.2 Ethical and environmental considerations
Found an error? Report a correction.
Need help with this topic? Request a free trial class for IGCSE Business (9225).
This guide teaches sections 3.2.1 Technology and 3.2.2 Ethical and environmental considerations of the OxfordAQA International GCSE Business (9225) specification, version 3.1, first teaching September 2020 and first examined May/June 2022. Both sit in section 3.2, Influences on business, which the specification says is assessed on both written papers. Use it with the revision notes and the practice questions. The wider topic is in the Influences on business study guide, revision notes and practice set. Course links: the OxfordAQA IGCSE Business hub, the checklist and the free diagnostics.
What you need to cover
| Section | Content point | Skill needed |
|---|---|---|
| 3.2.1 | Impact of changing use of ICT | Explain how Information and Communication Technology influences business activity |
| 3.2.1 | e-Commerce | Explain how it gives access to wider markets |
| 3.2.1 | Digital communication | Explain its use with stakeholders, with examples such as email and video conferencing |
| 3.2.2 | Ethical considerations | Identify and analyse trade-offs between ethics and profit; know that ethical behaviour means behaving in a manner stakeholders judge fair and honest, including religious observance and charitable giving; give examples, benefits and drawbacks |
| 3.2.2 | Environmental considerations | Explain why society and consumers expect more environmental responsibility; weigh costs and benefits; the named areas are traffic congestion, recycling, waste disposal, noise pollution and air pollution |
| 3.2.2 | Sustainability | Identify and analyse trade-offs between sustainability and profit; cover global warming and using scarce resources |
3.2.1 Technology
ICT and business activity
ICT stands for Information and Communication Technology. The specification asks you to understand how the shifting use of ICT affects what a business does. “Changing use” is the key phrase: the same business does different things as technology develops. Think about which activity changes, then what happens to cost, revenue or customers.
- Selling: orders can be taken on a website or app as well as in a shop.
- Buying: suppliers can be contacted and orders placed online.
- Staff roles: some jobs shrink while others, such as running the website, appear. Staff may need training.
- Costs: equipment, software, security and training cost money. Savings can come later, for example on printing, postage or travel.
Link the change to an outcome: “a website lets customers order outside opening hours, which raises sales” is analysis; “a business uses a website” is not.
e-Commerce and wider markets
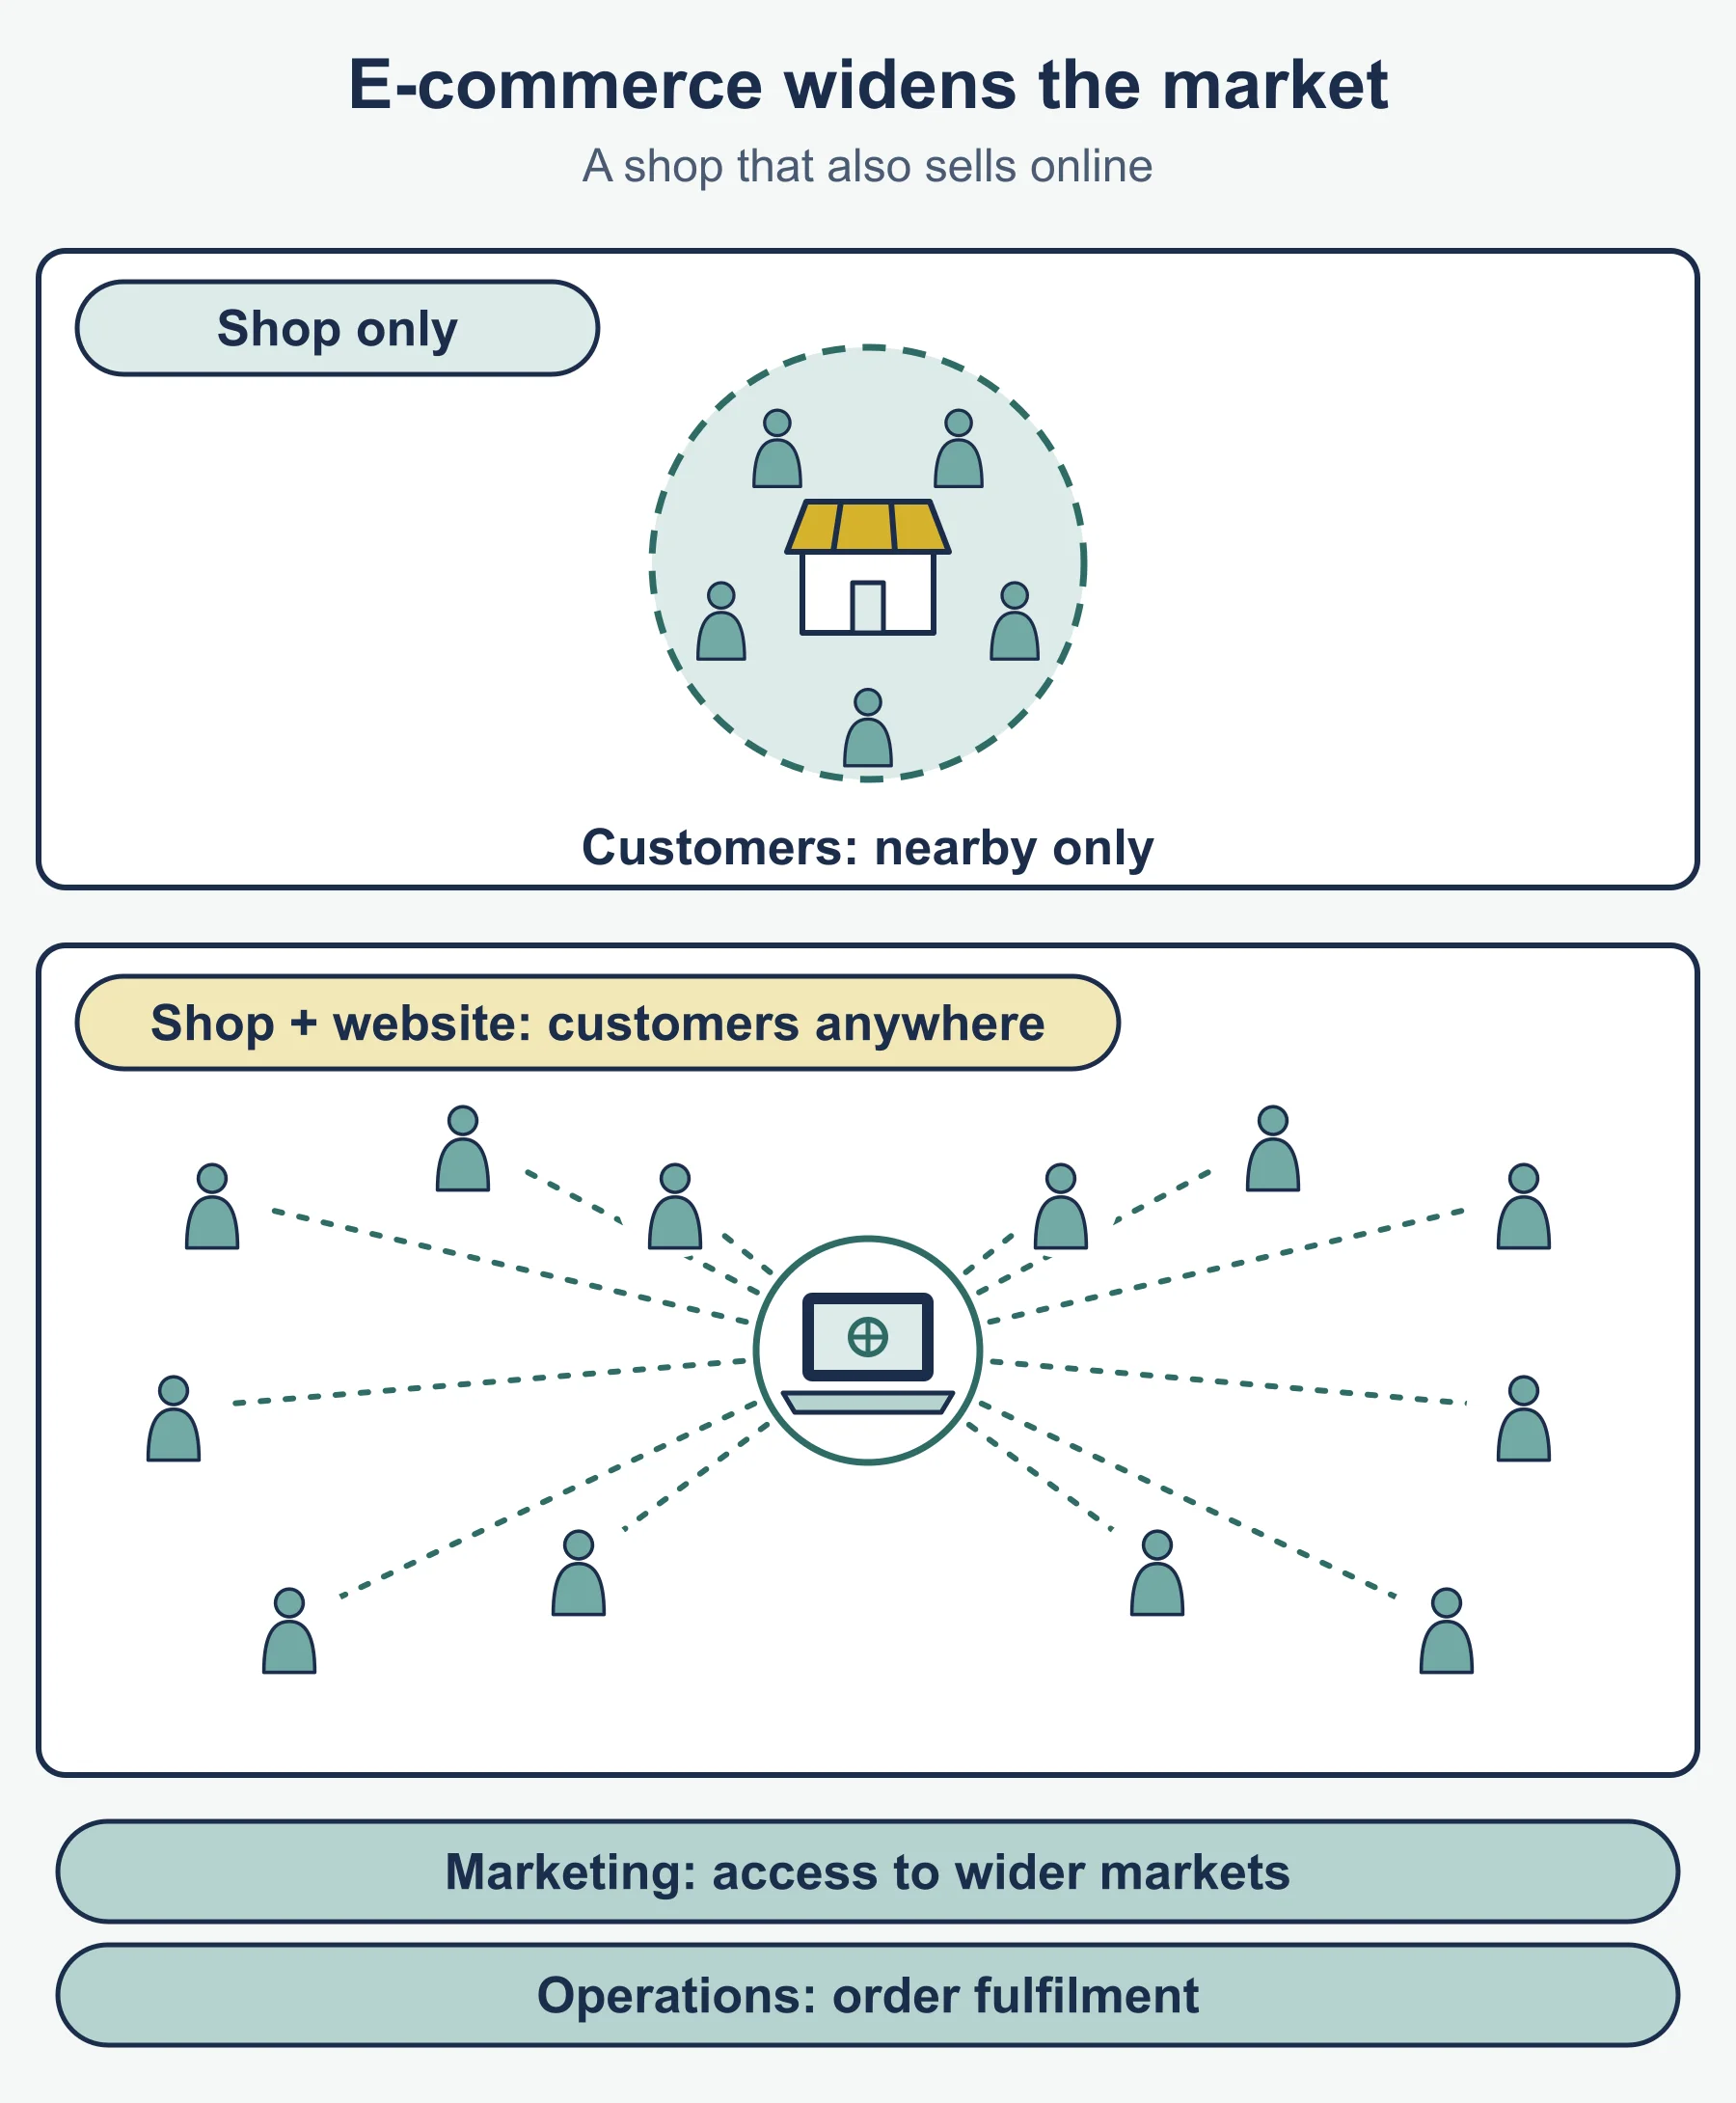
e-Commerce means buying and selling goods and services over the internet. The specification wants you to know how a business uses it to access wider markets. A shop reaches customers who can walk in. A website reaches anyone with a connection and a delivery address, in another town or another country.
Advantages for the business:
- A larger customer base, so more potential sales.
- Selling at any time of day without paying staff to stand in a shop.
Drawbacks:
- Delivery, packaging and returns cost money.
- Website, payment and security systems cost money to build and maintain.
- Customers cannot touch the product, so some will not buy.
- Some sales may simply move from the shop to the website, so revenue does not rise by the full amount of the online sales.
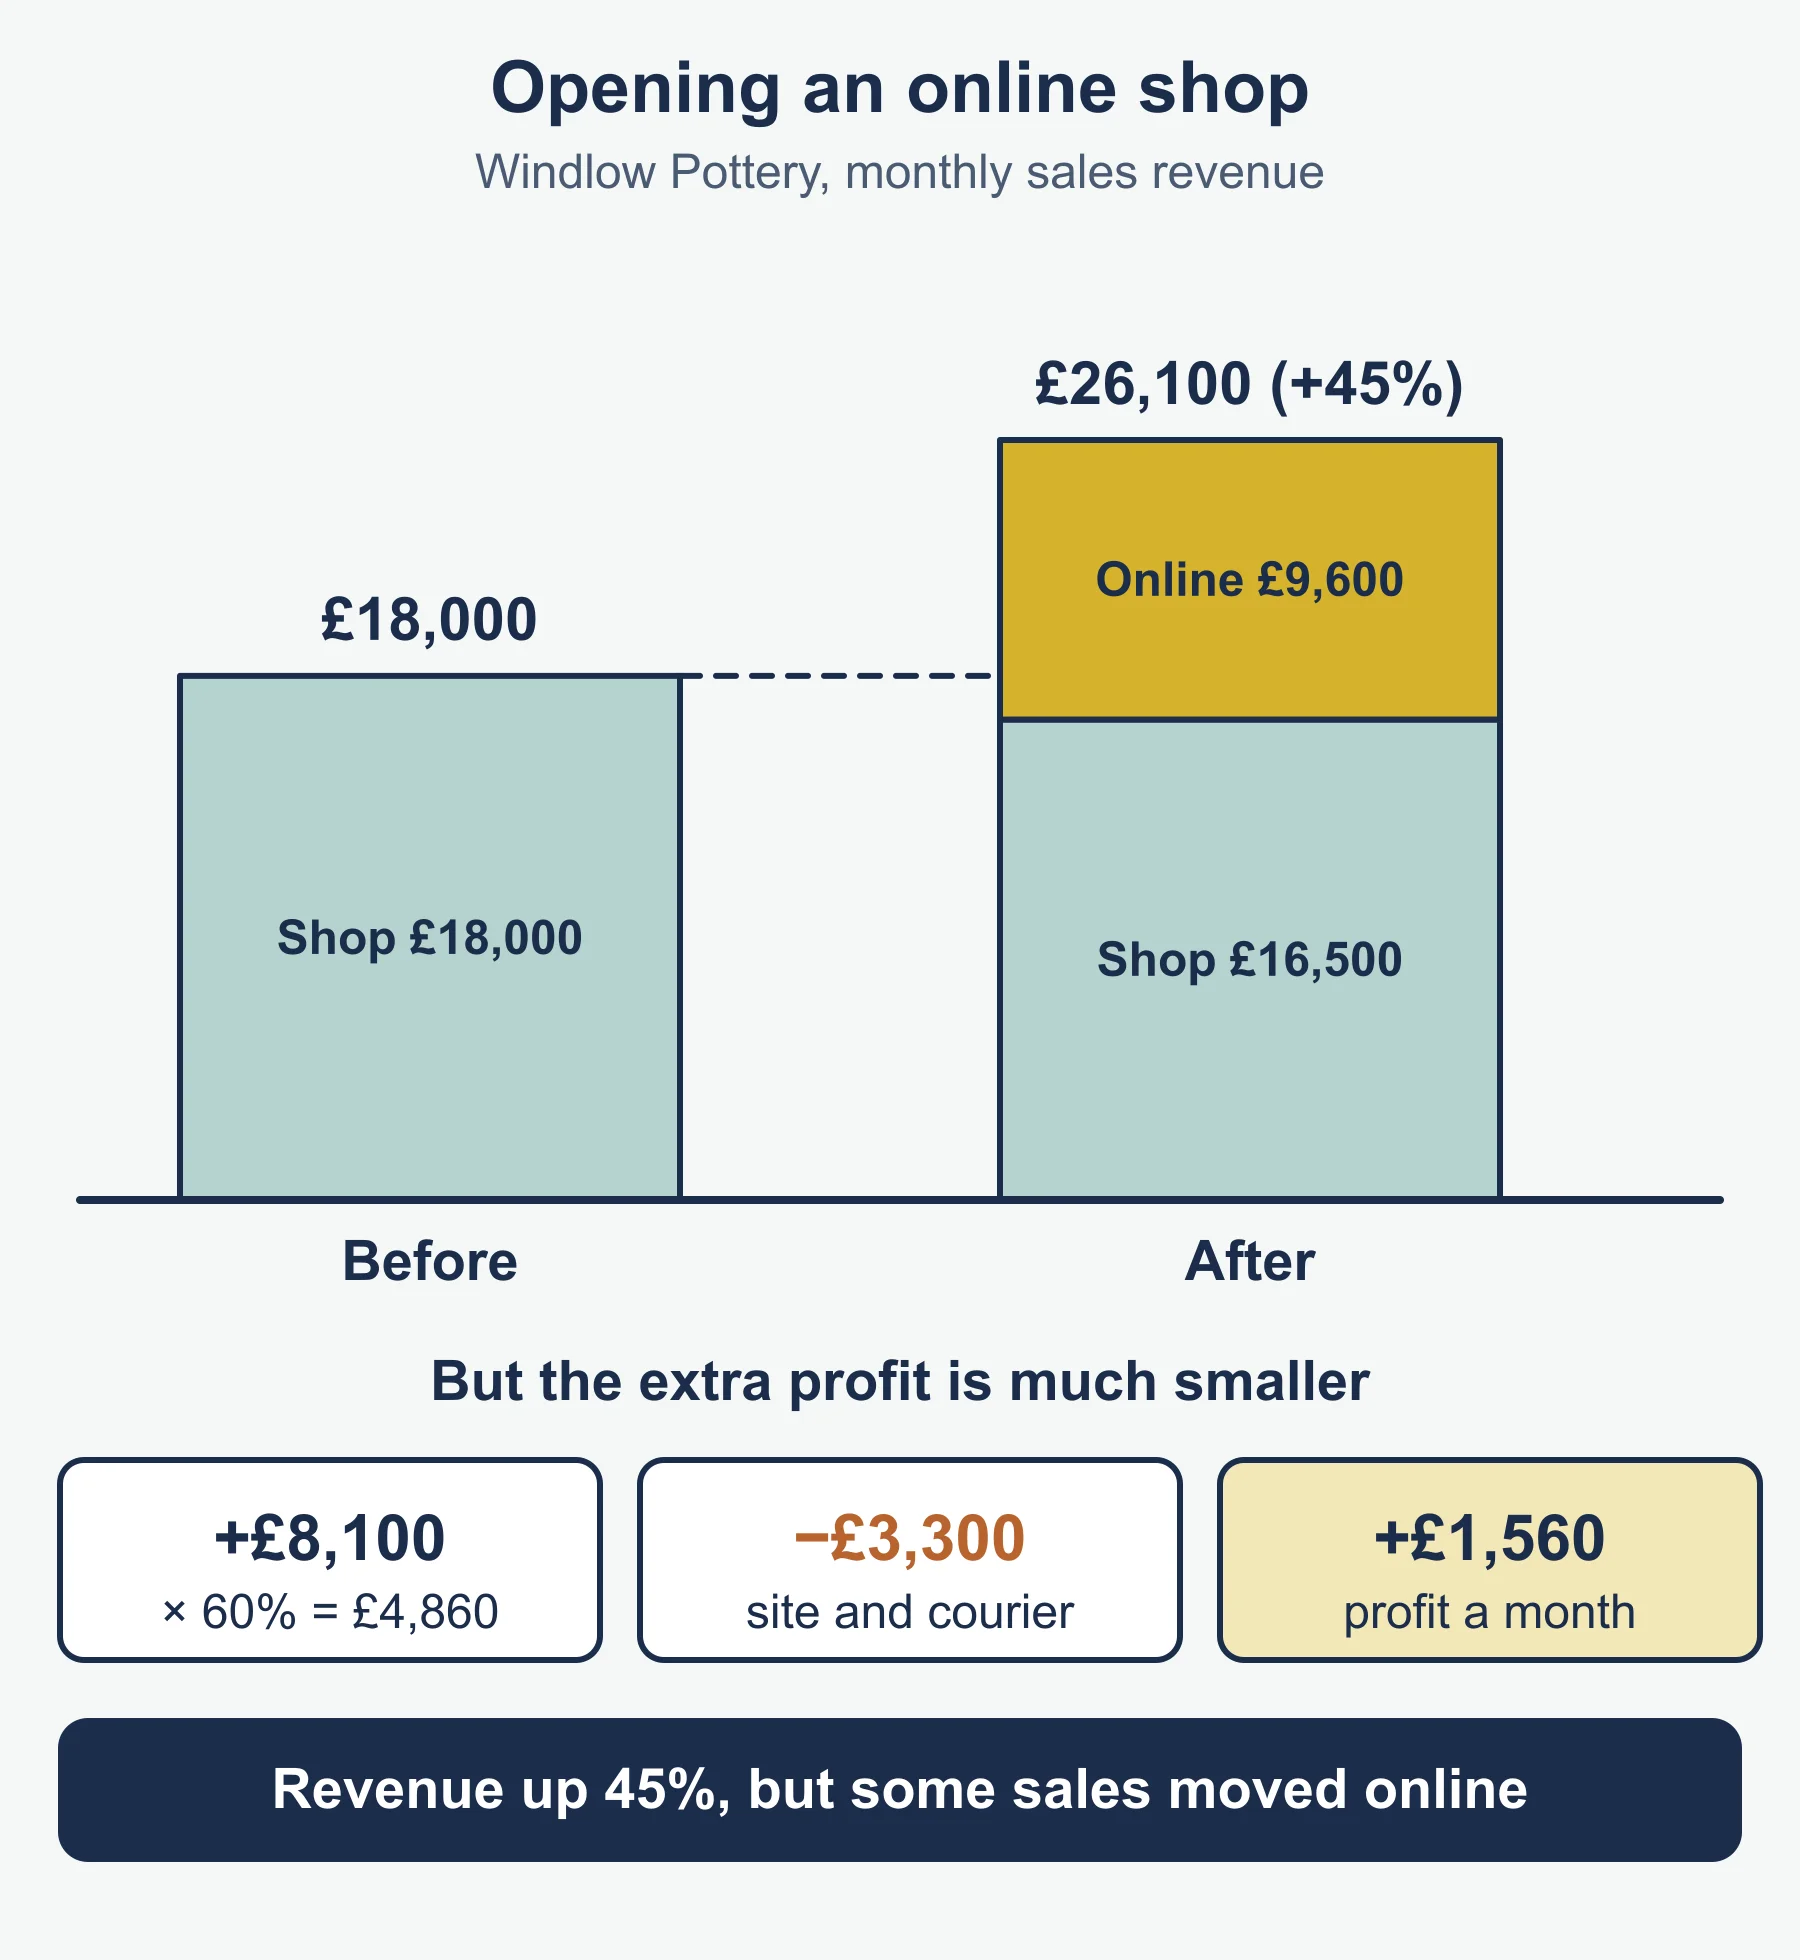
Worked example 1: opening an online shop (calculation). Windlow Pottery sells hand-made mugs and bowls from one shop. Monthly sales revenue is £18,000. After launching a website, monthly sales revenue from the shop falls to £16,500 and online sales are £9,600. Cost of sales is 40% of sales revenue. The website and courier costs add £3,300 a month. Is the website worth keeping?
- Total sales revenue now = 16,500 + 9,600 = £26,100.
- Change in sales revenue = 26,100 - 18,000 = £8,100.
- Percentage change = 8,100 ÷ 18,000 × 100 = 45%.
- Online share of total revenue = 9,600 ÷ 26,100 × 100 = 36.8% (1 d.p.).
- Extra gross profit = 8,100 × 60% = £4,860, because 60% of each extra pound is left after cost of sales.
- Extra profit after the new costs = 4,860 - 3,300 = £1,560 a month.
The website raises monthly profit, but by much less than the 45% rise in revenue suggests. The shop lost £1,500, so the gain is £8,100, not £9,600: sales moved across.
Digital communication with stakeholders
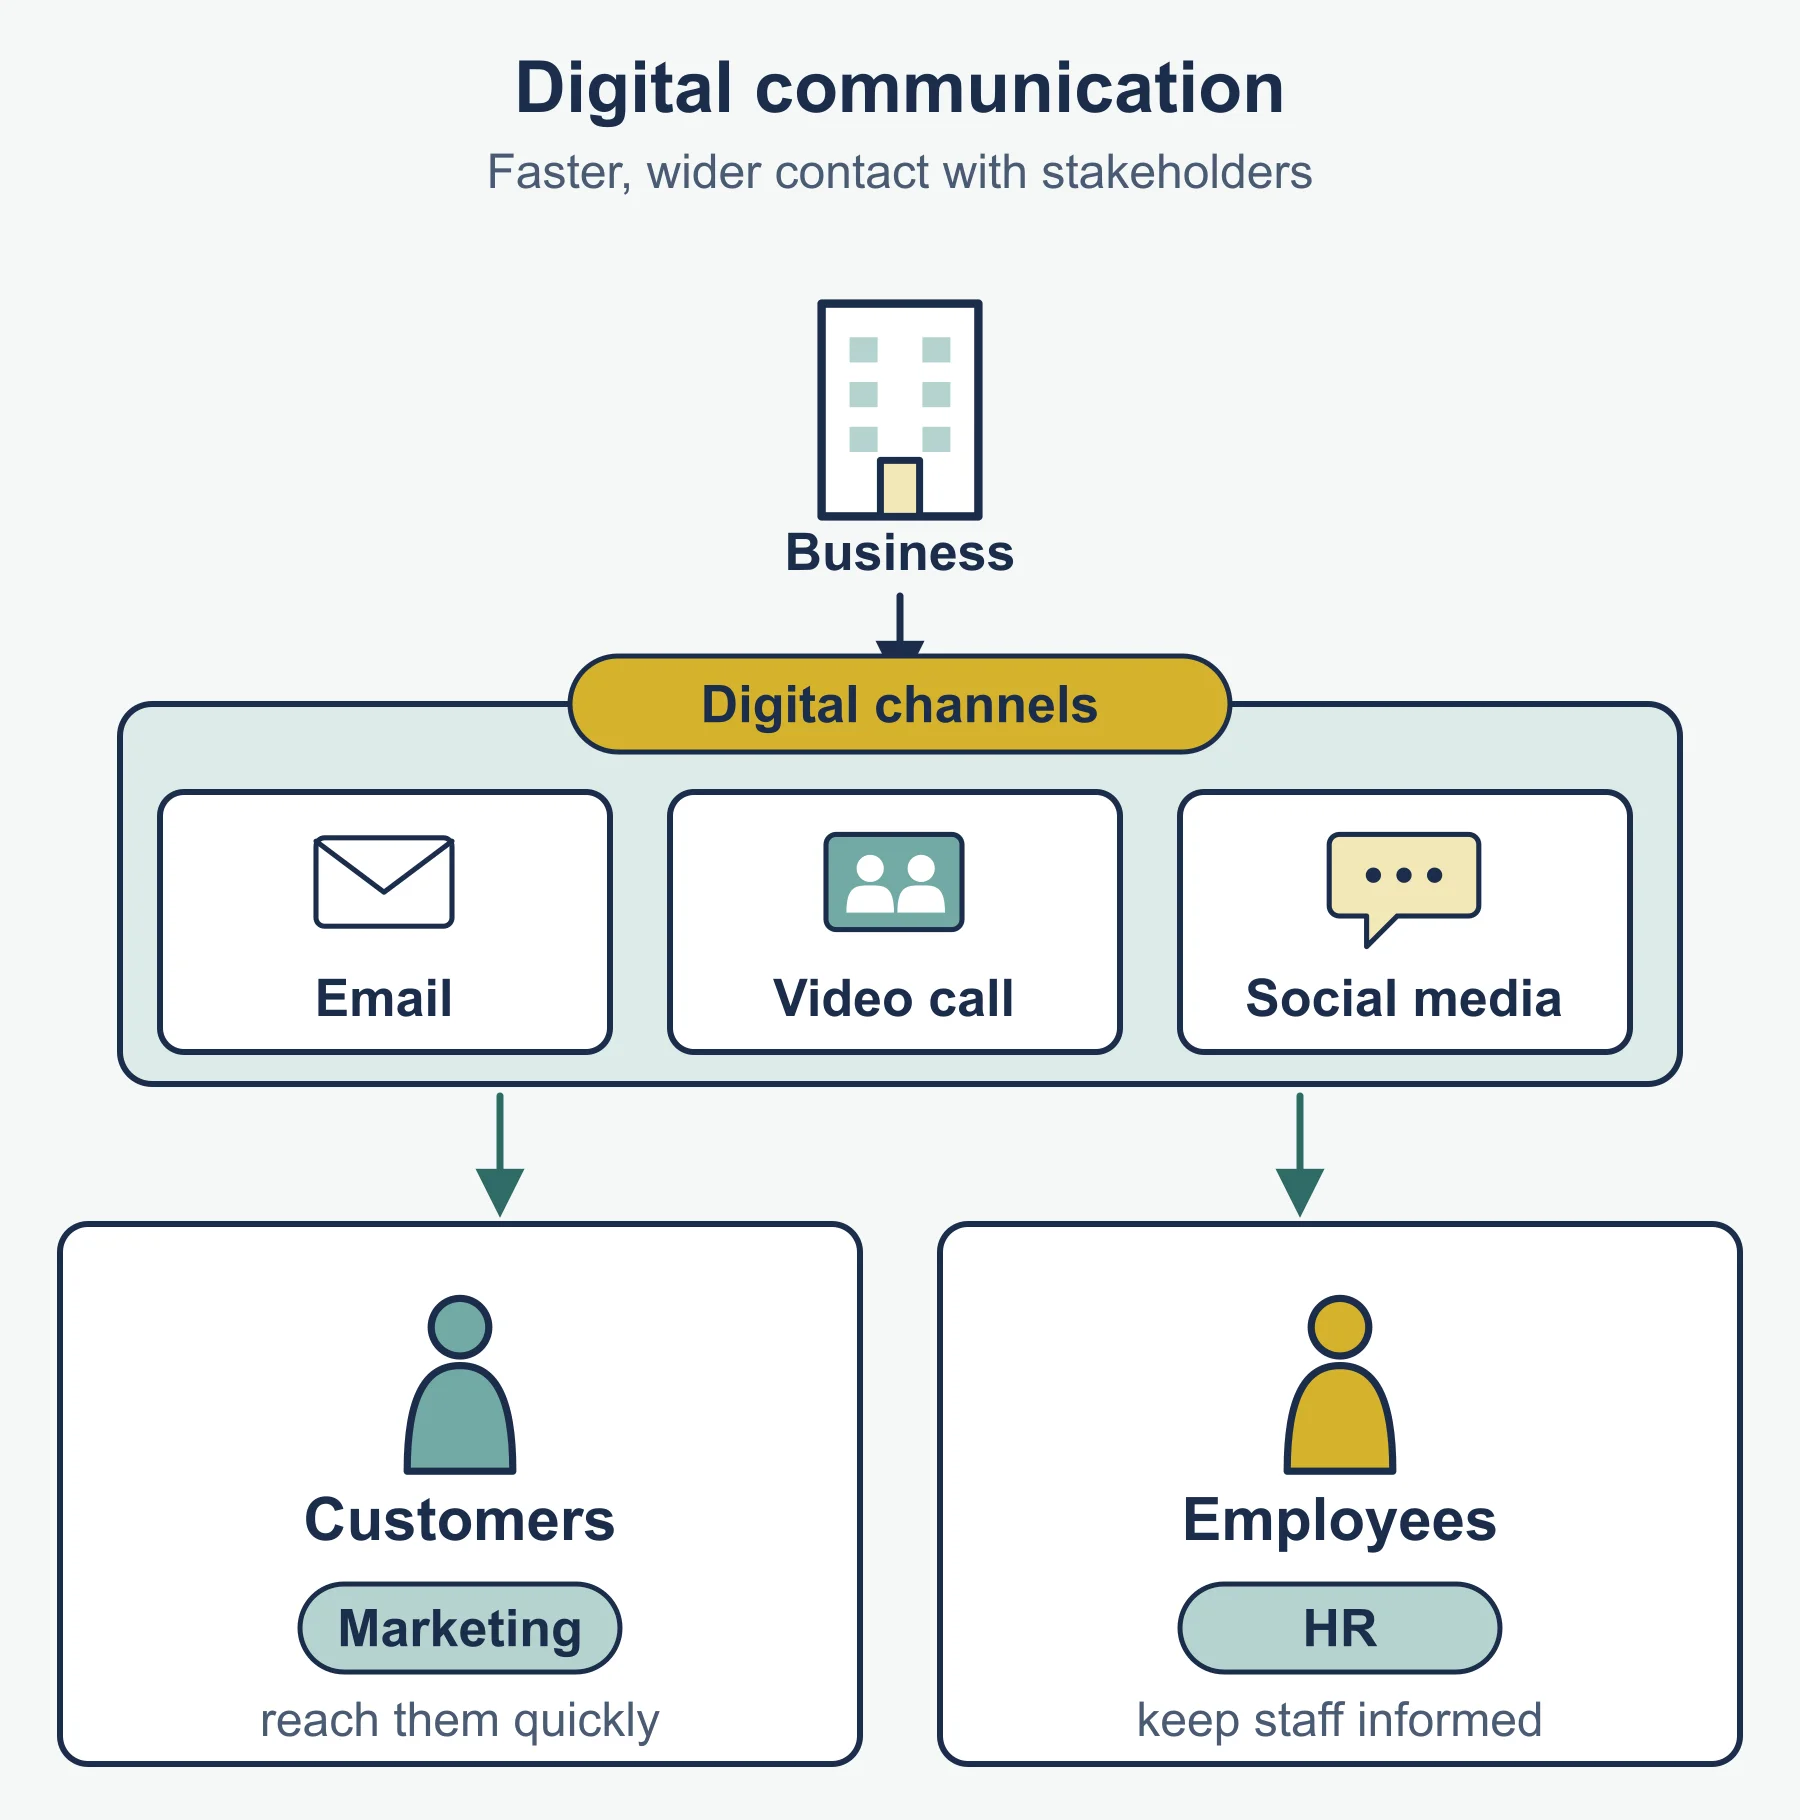
Stakeholders are the groups with an interest in a business: owners, employees, customers, suppliers, lenders, the local community. Digital communication means using electronic channels to share information with them. The specification expects you to know relevant examples, such as email and video conferencing.
| Method | Typical stakeholder | Benefit | Drawback |
|---|---|---|---|
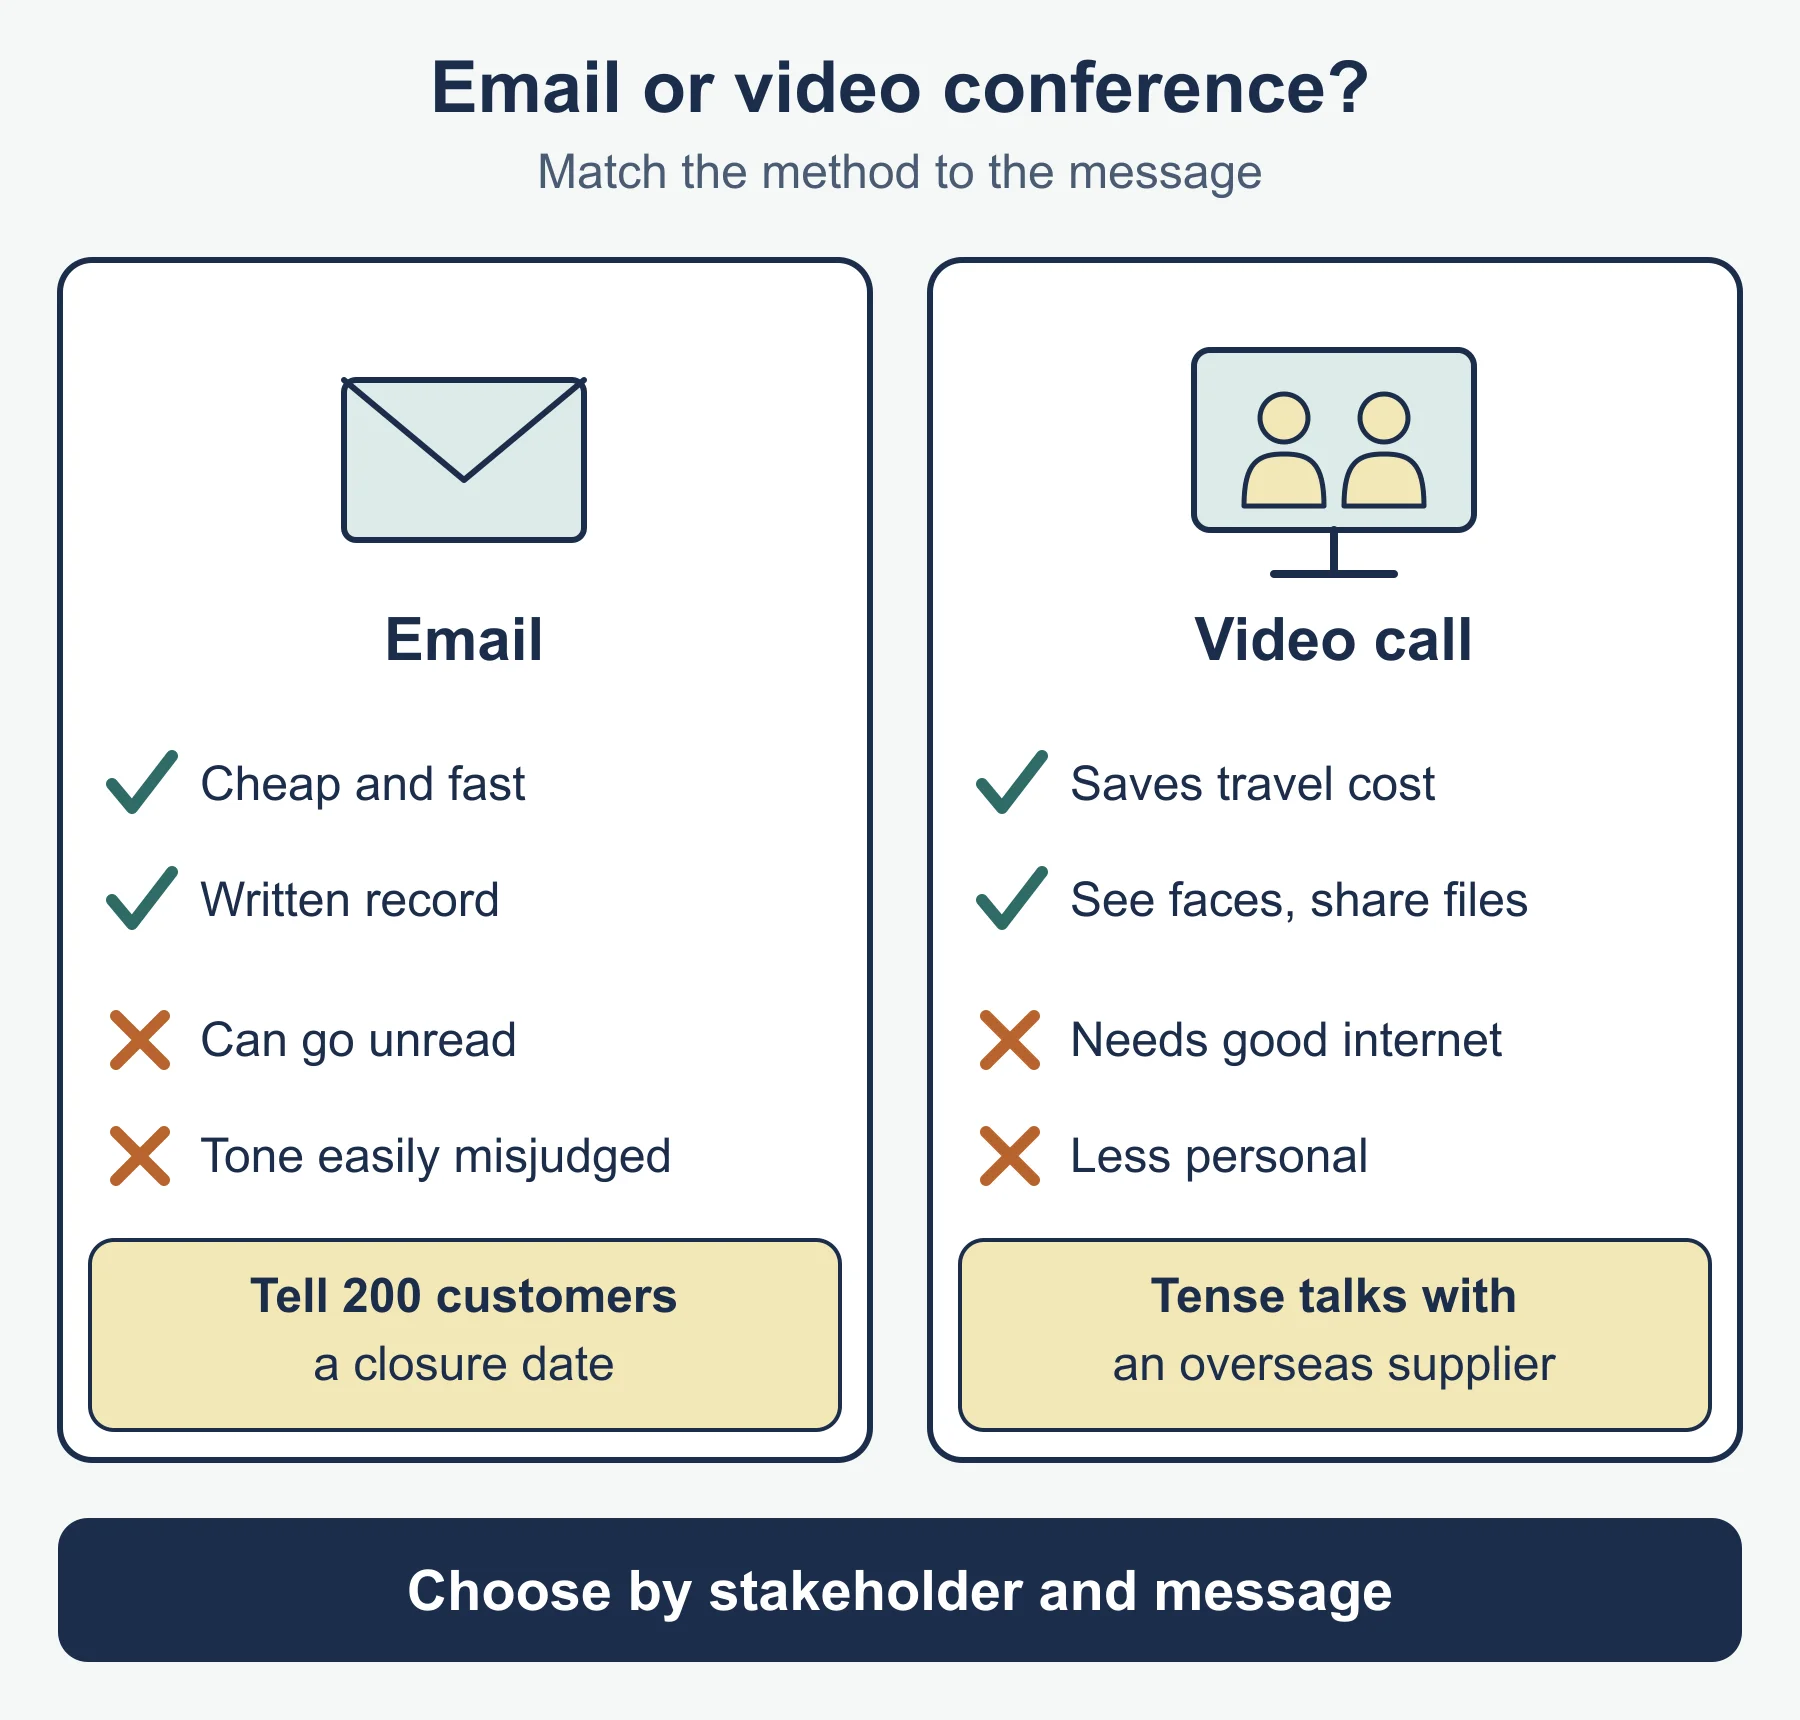
| Suppliers, customers, staff | Cheap, fast, creates a written record, can reach many people at once | Can be ignored or go unread; tone is easy to misjudge; no immediate answer | |
| Video conferencing | Staff in different sites, overseas suppliers, lenders | Saves travel time and cost; people see each other and can share documents | Needs good internet and equipment; technical faults; less personal than meeting in person |
| Business website or social media | Customers, local community | Shares news and answers questions around the clock | Needs updating; negative comments are public |
Choose the method to fit the stakeholder and the message. Telling 200 customers about a closure date suits email. A tense negotiation with a supplier abroad may suit video conferencing, because tone and expression matter.
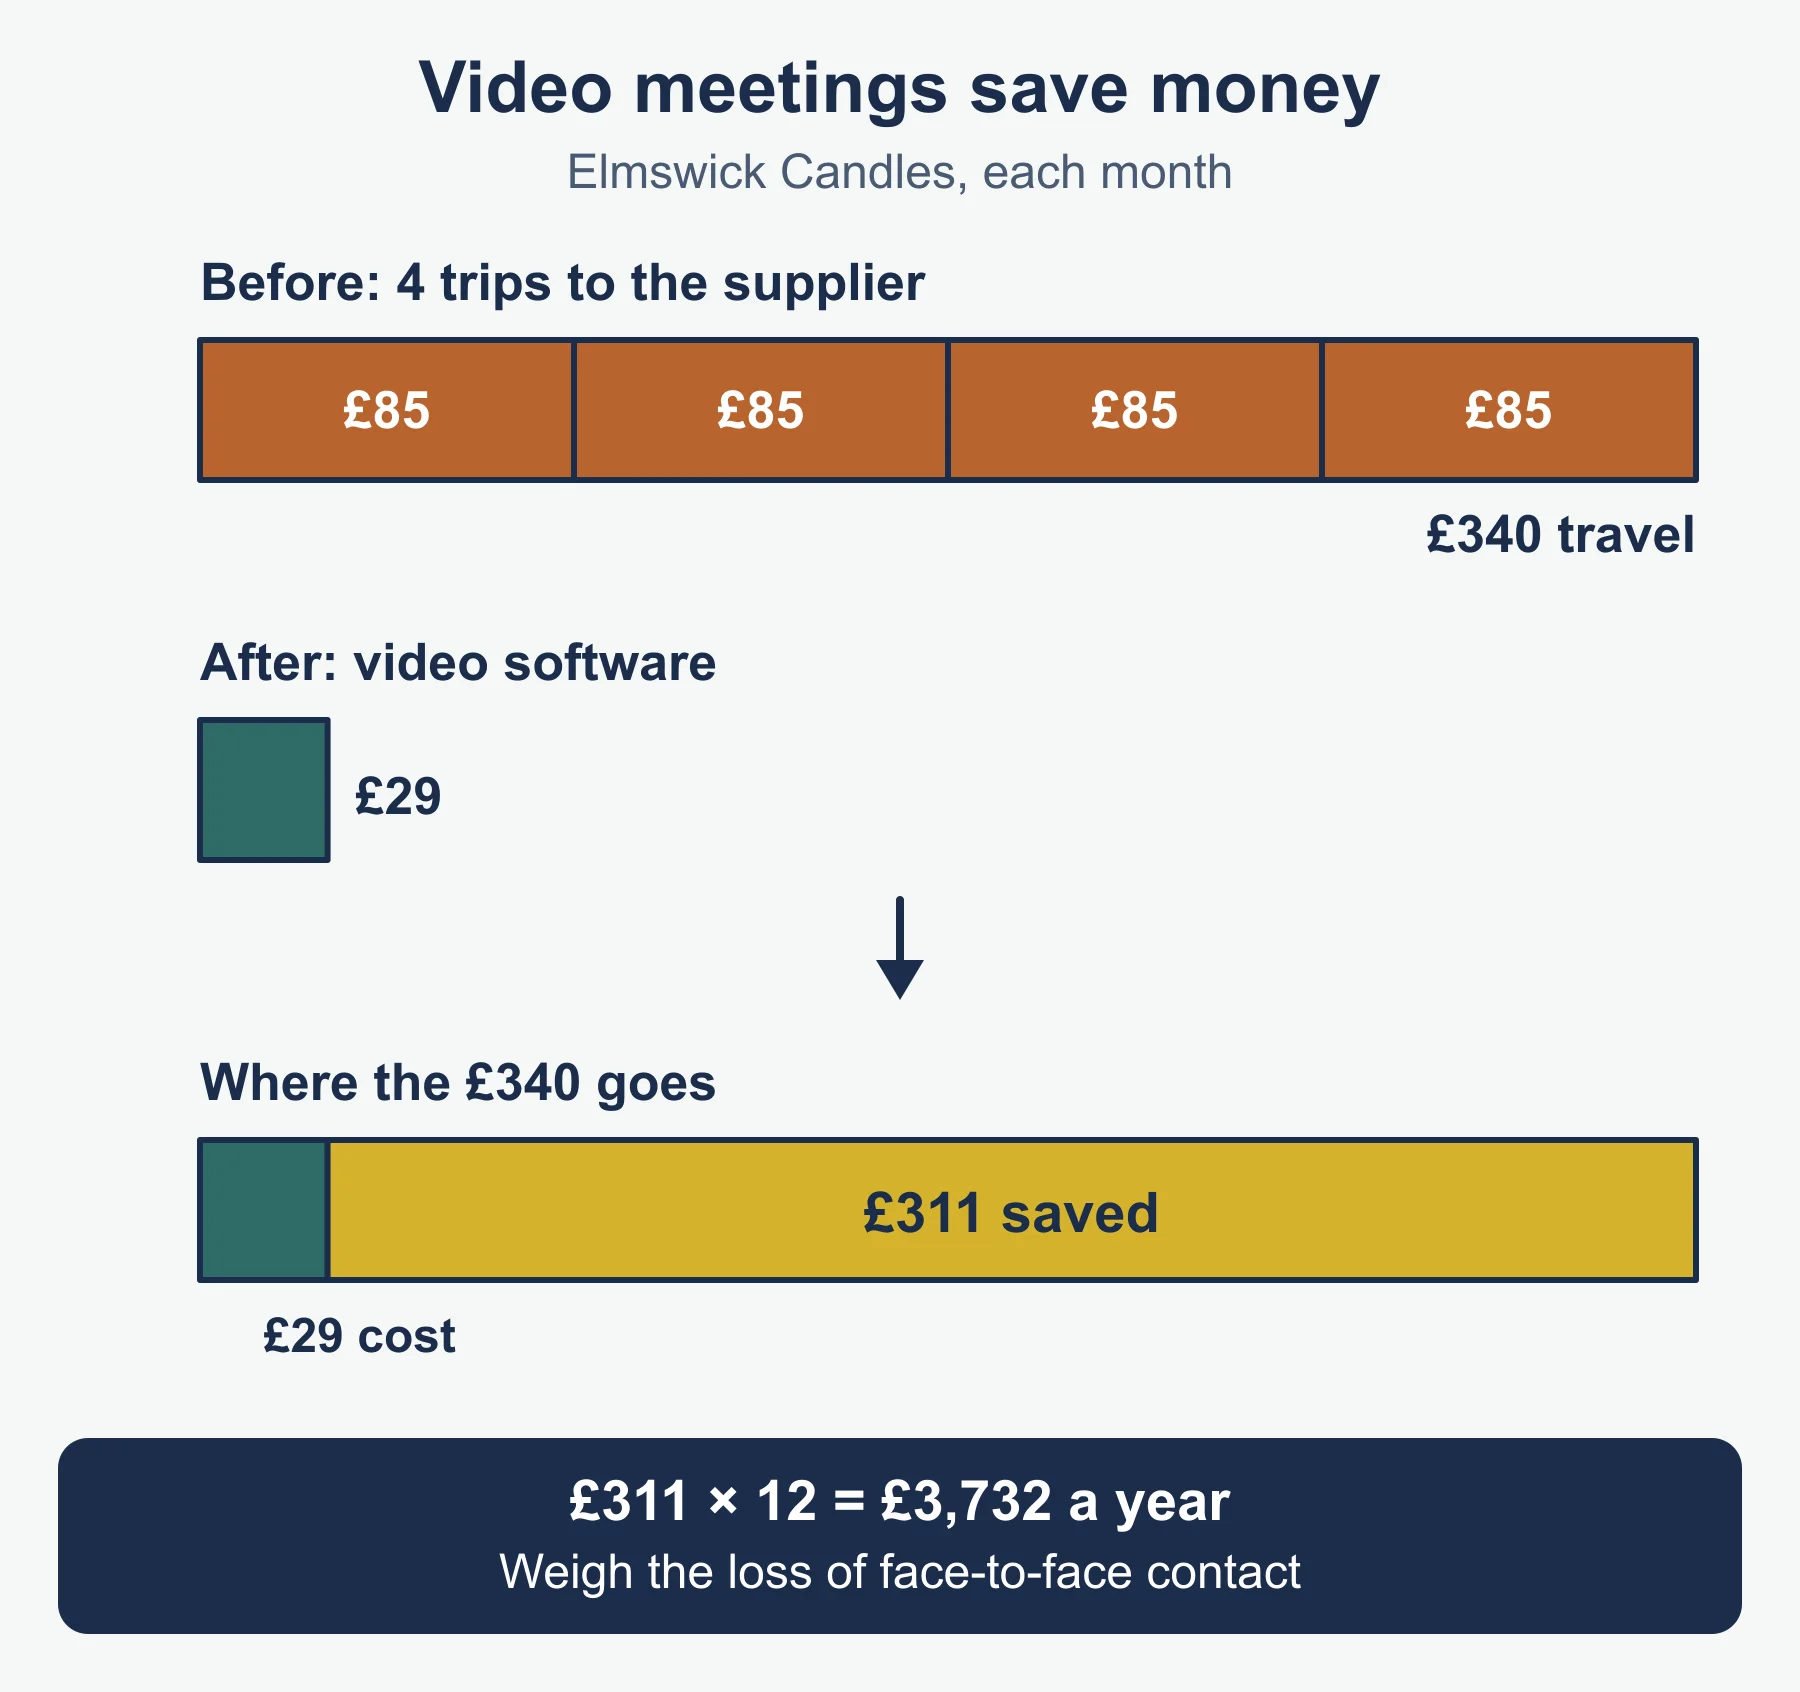
Worked example 2: video conferencing (calculation). Elmswick Candles makes four trips a month to meet a wax supplier, at £85 per trip in travel costs. It switches to video meetings costing £29 a month for the software.
- Monthly travel cost saved = 4 × 85 = £340.
- Net monthly saving = 340 - 29 = £311.
- Annual saving = 311 × 12 = £3,732.
The saving is real, but the owner should also weigh the loss of face-to-face contact with a key supplier.
3.2.2 Ethical and environmental considerations
Ethical considerations
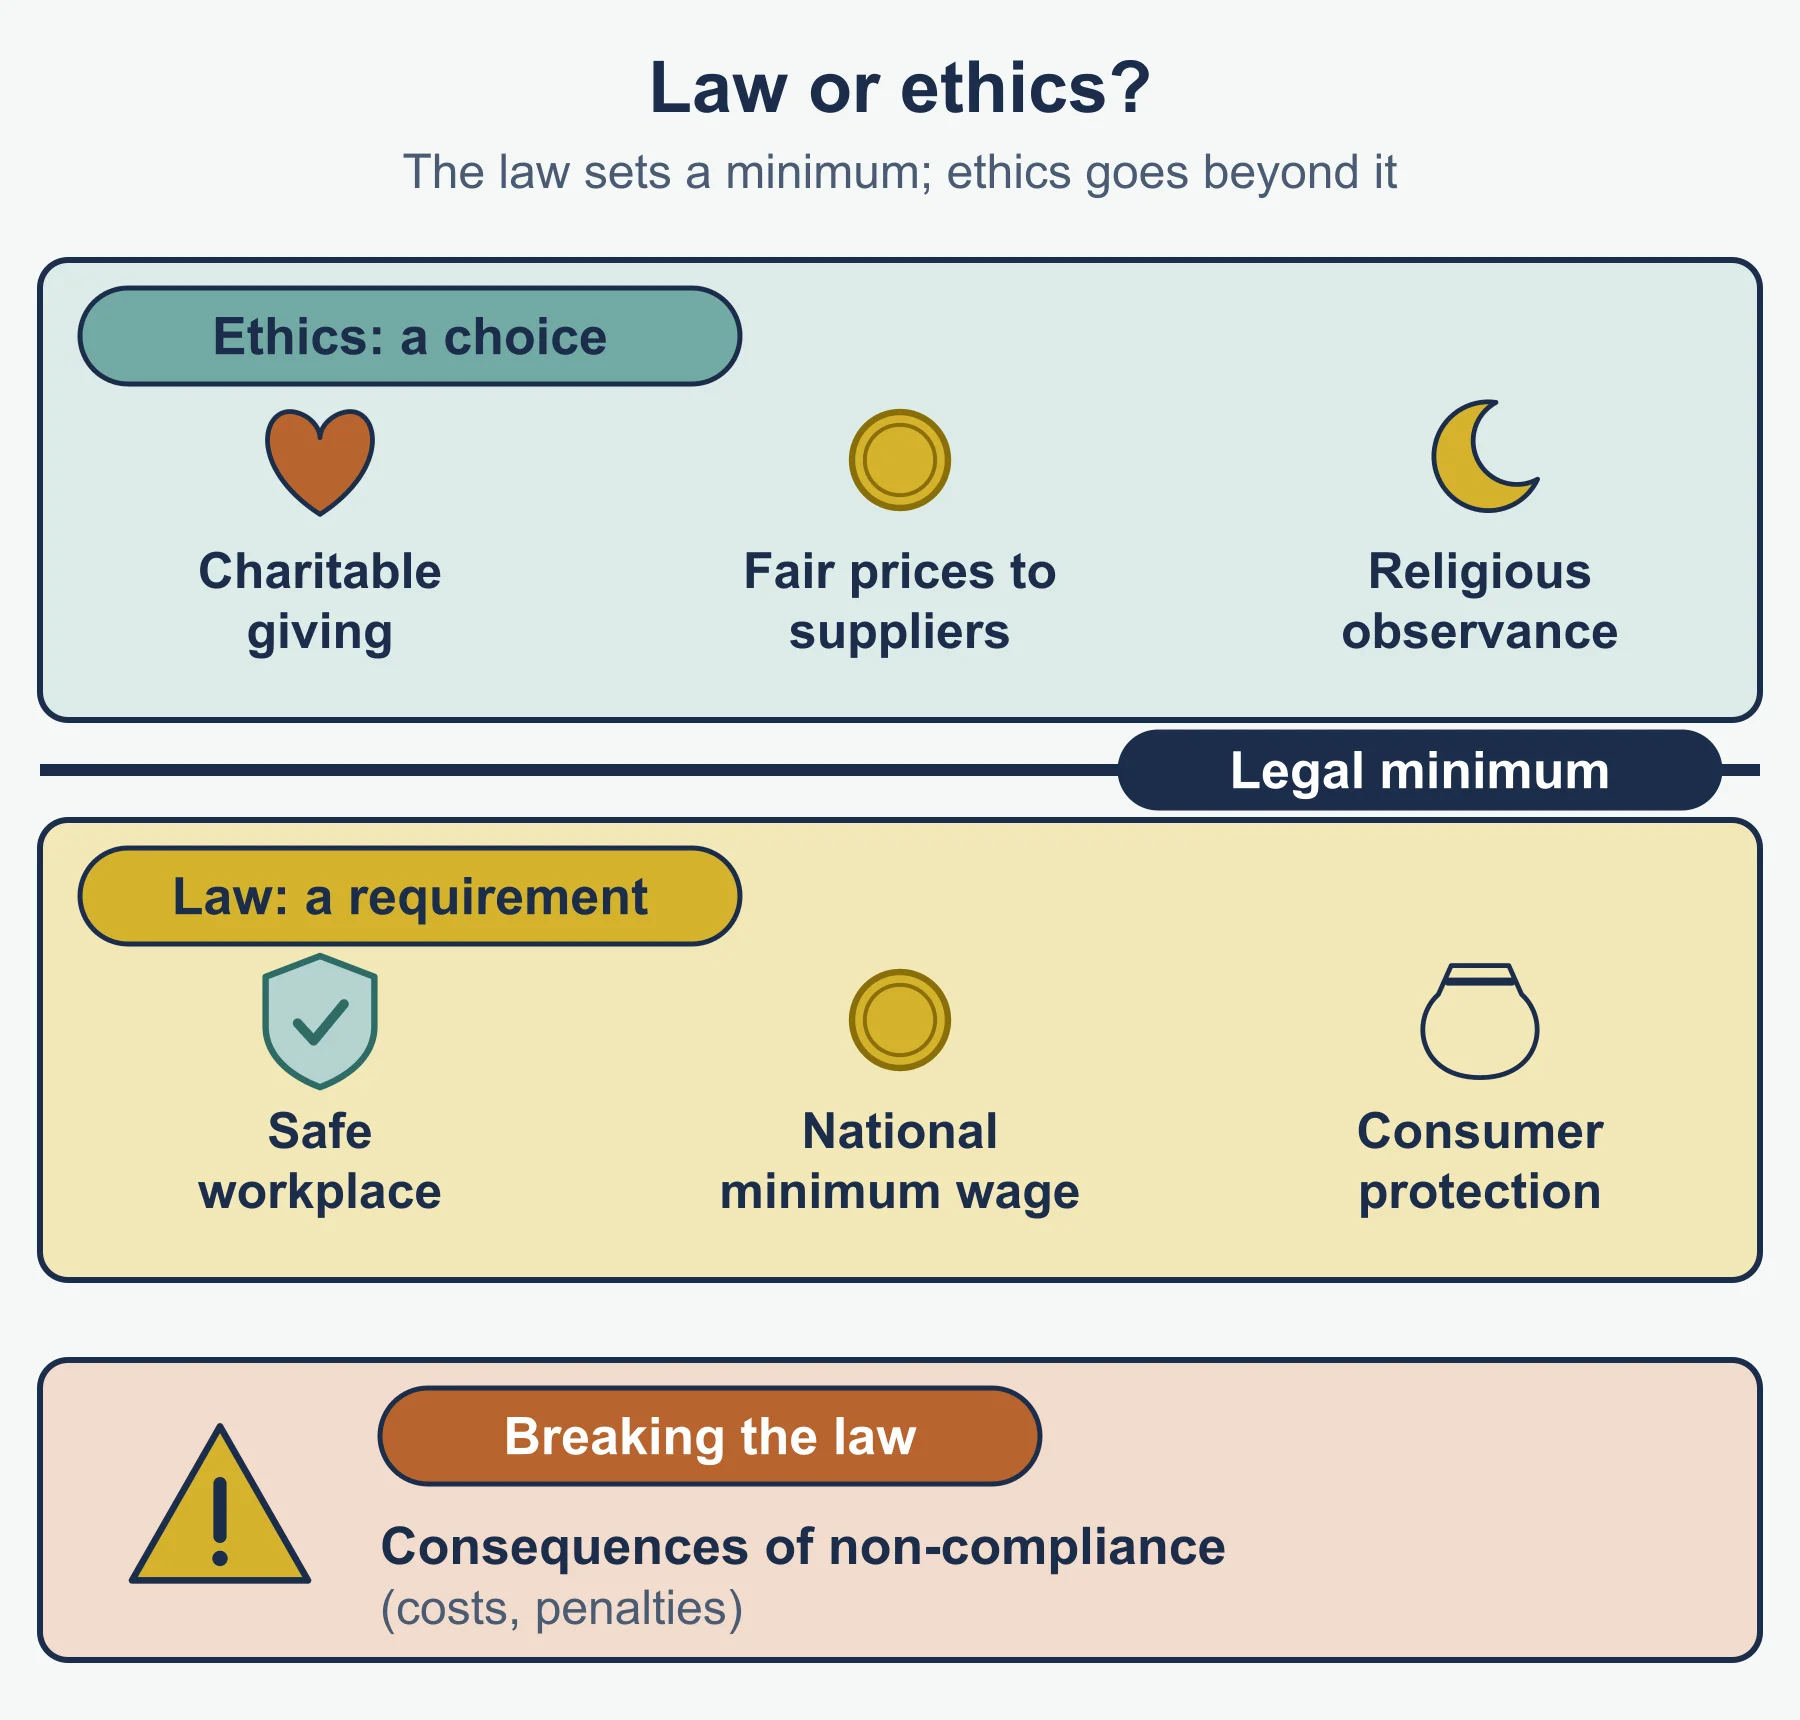
The specification says ethical behaviour expects a business to behave so that its stakeholders regard it as both fair and honest. It names religious observance and charitable giving as part of this. Ethics is a choice about how to behave. It is different from obeying the law, which is not optional.
Examples you can use:
- Paying suppliers a fair price and on time.
- Honest advertising and labelling, with no false claims.
- Treating employees fairly, including allowing time for prayer or religious festivals where this can be arranged.
- Giving a share of profit or time to charity.
- Being open with customers about faults or problems.
Benefits of ethical behaviour:
- Customers who value fairness may buy more and stay loyal.
- Good reputation, which helps recruit staff.
- Better relationships with suppliers, who may offer better terms.
Drawbacks:
- It often raises costs, so profit per unit falls.
- Competitors who ignore ethics may charge lower prices.
- Charity giving or religious observance may reduce money or hours available.
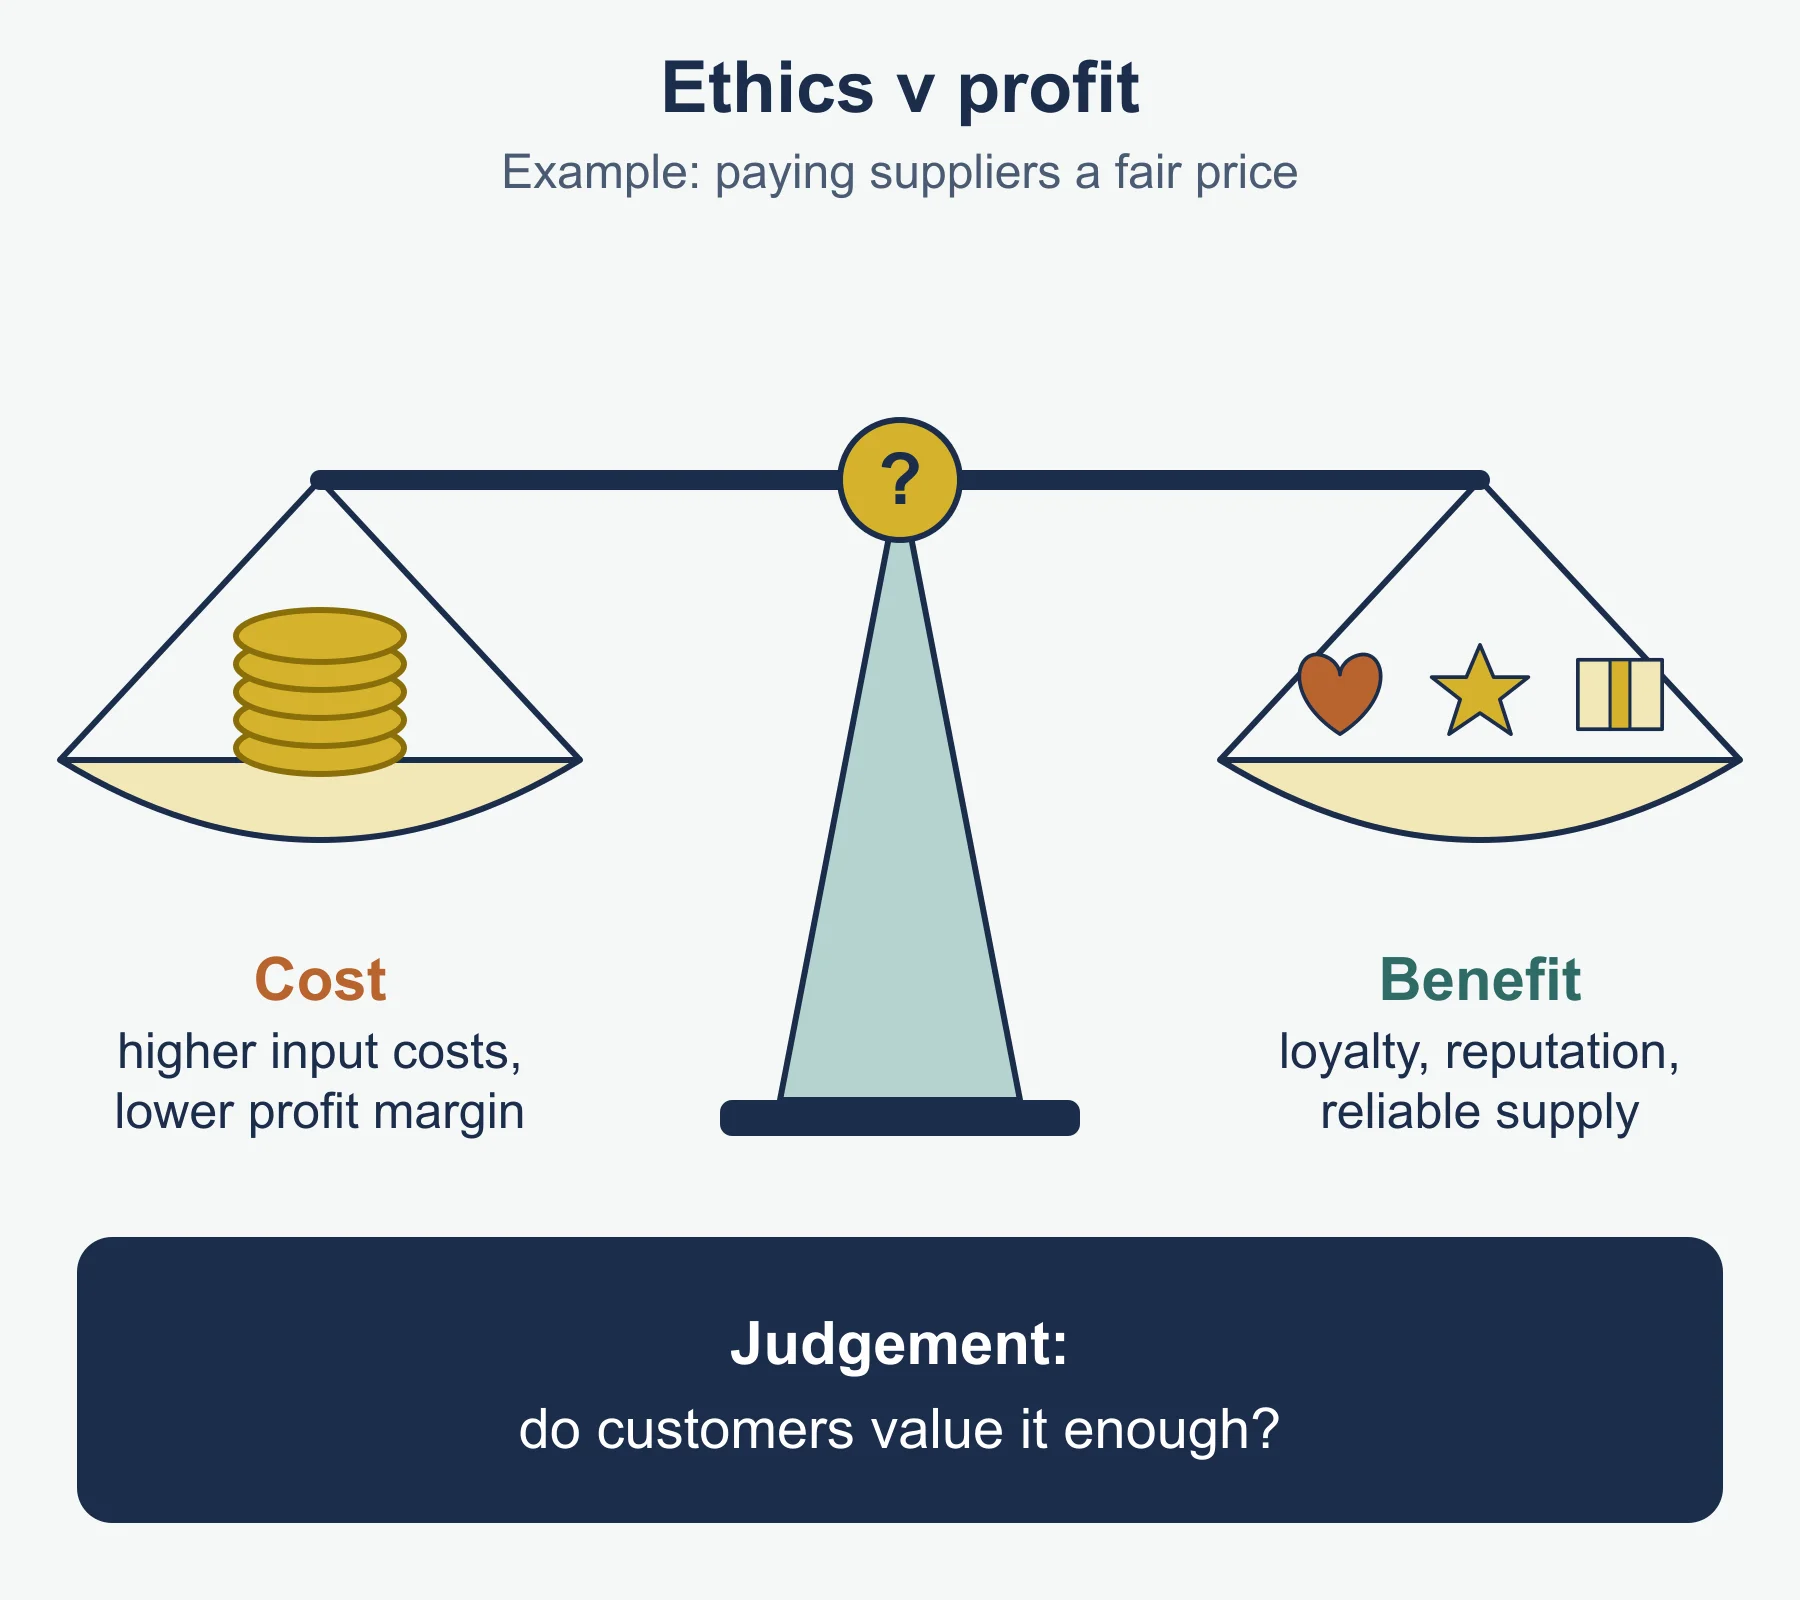
The trade-off between ethics and profit. The specification asks you to identify and analyse cases where there may be a trade-off. Use four steps: name the ethical choice, say what it costs, say what benefit may follow, then judge which matters more for this business.
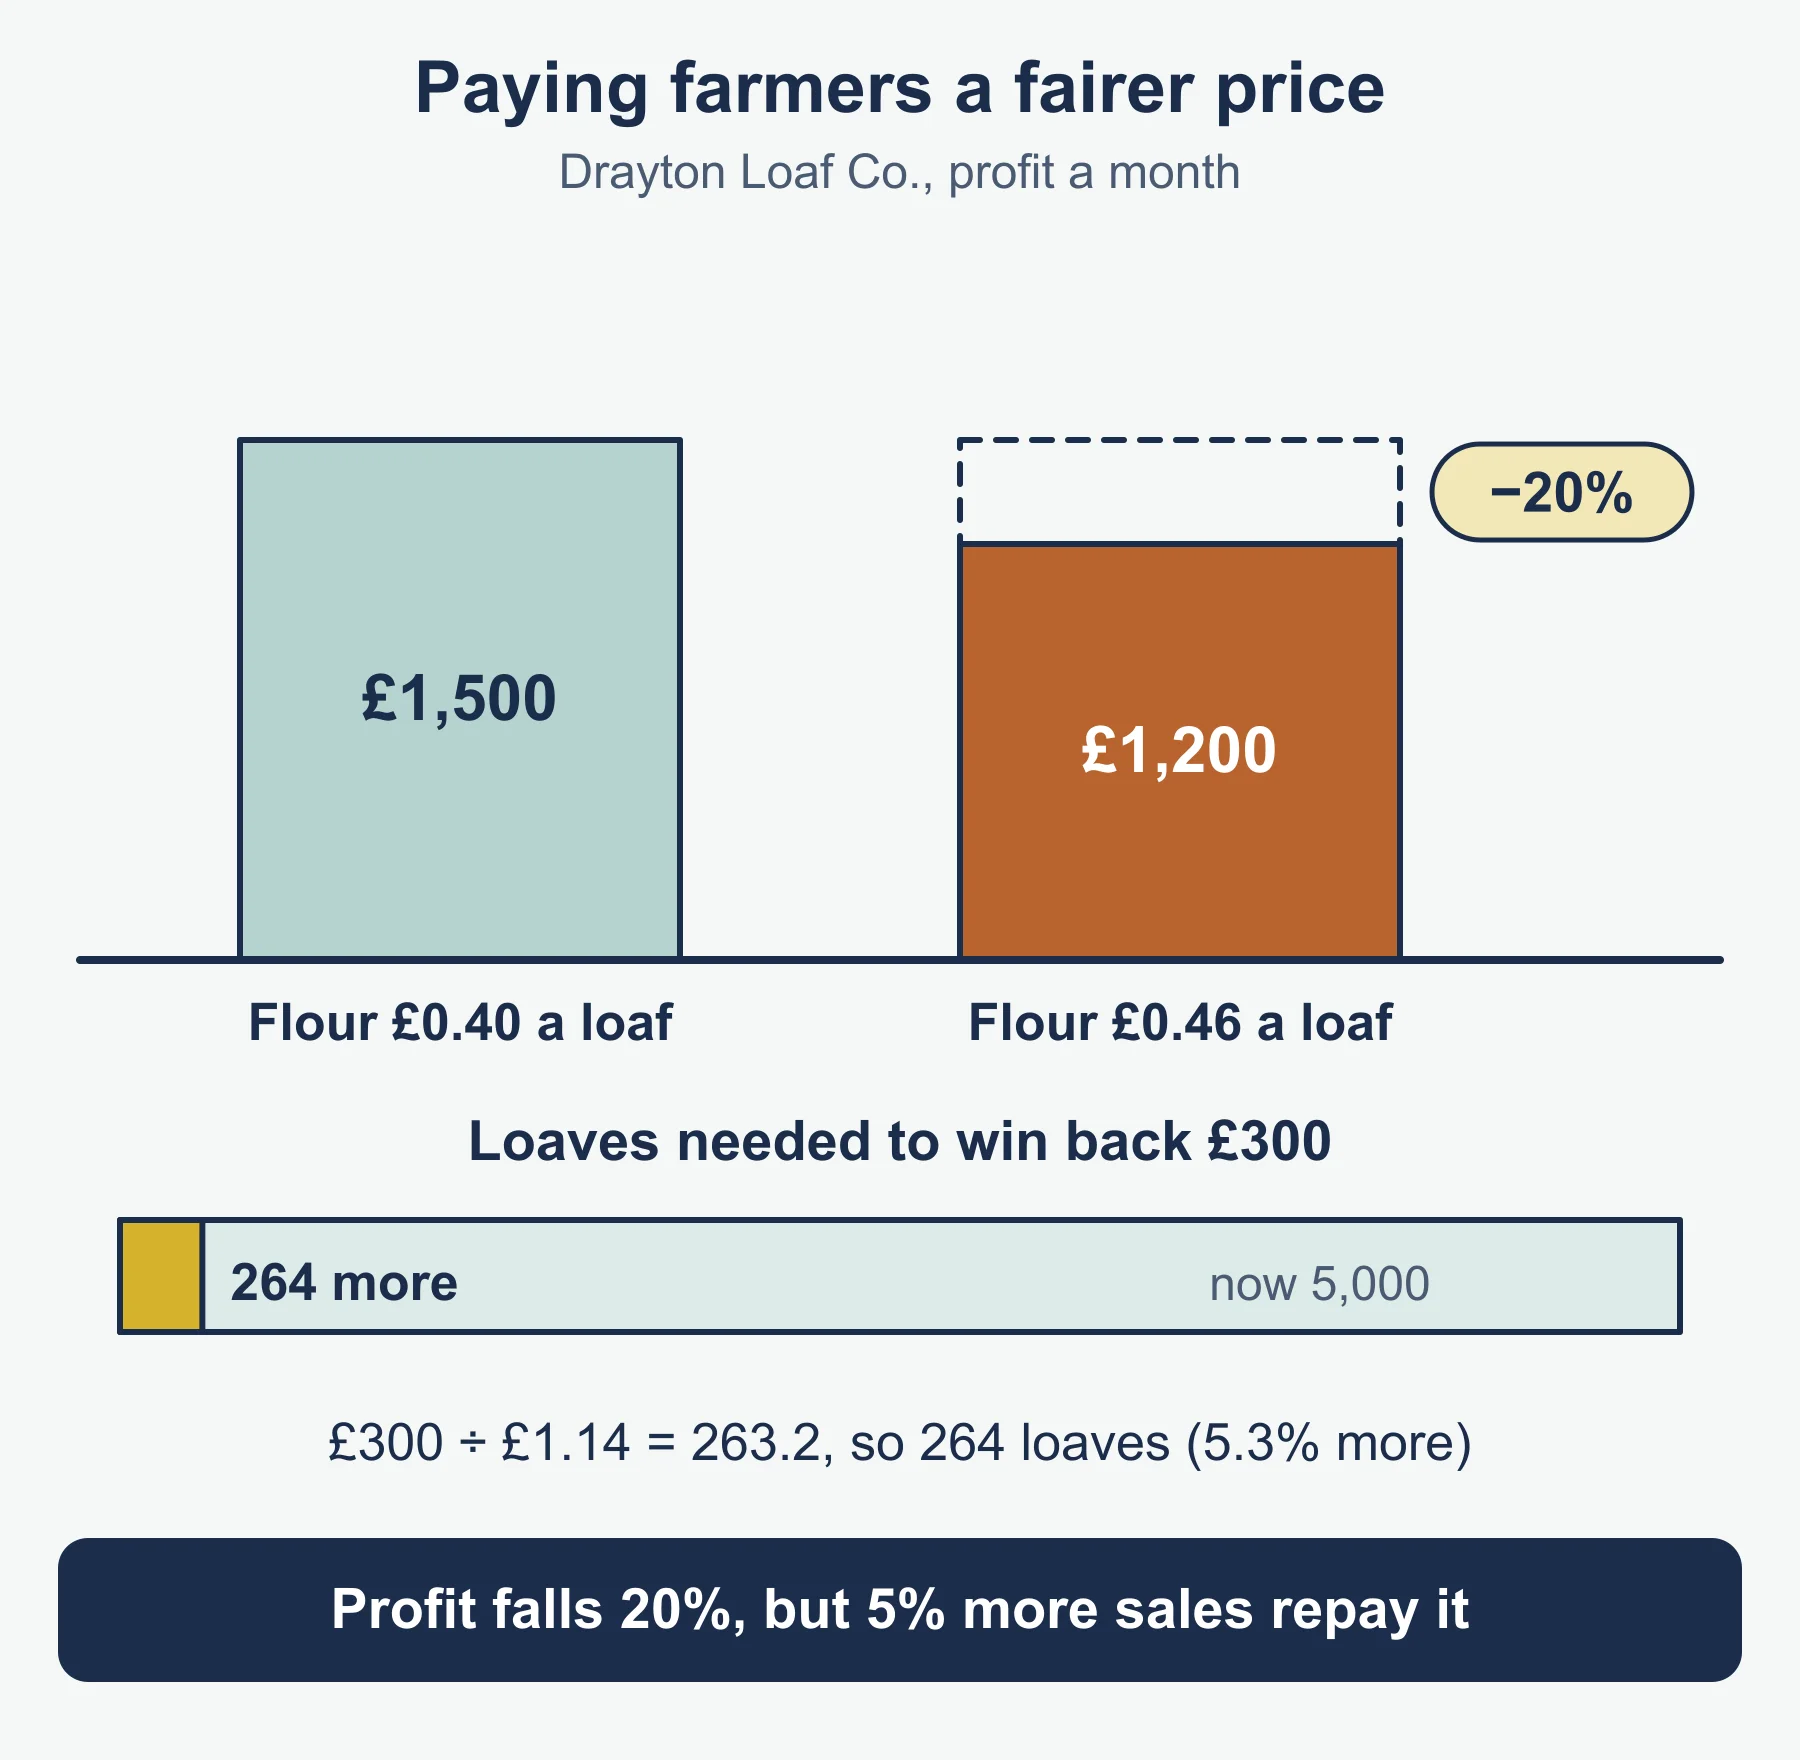
Worked example 3: paying farmers more (calculation). Drayton Loaf Co. bakes and sells 5,000 loaves a month at £2.50. Flour costs £0.40 a loaf and other variable costs are £0.90 a loaf. Fixed costs are £4,500 a month. The owner considers paying her farmers a fairer price, which would raise flour cost to £0.46 a loaf.
- Profit now = 5,000 × (2.50 - 1.30) - 4,500 = £1,500.
- New variable cost = 0.46 + 0.90 = £1.36 a loaf.
- Profit after = 5,000 × (2.50 - 1.36) - 4,500 = £1,200.
- Fall in profit = 300 ÷ 1,500 × 100 = 20%.
- New contribution per loaf = 2.50 - 1.36 = £1.14.
- Extra loaves needed to restore the £300 = 300 ÷ 1.14 = 263.2, so 264 loaves, a rise of 5.3% on current sales.
Judgement: a 20% fall in profit is large, but about 5% more sales would repay it. The decision depends on whether customers will notice and care.
Environmental considerations
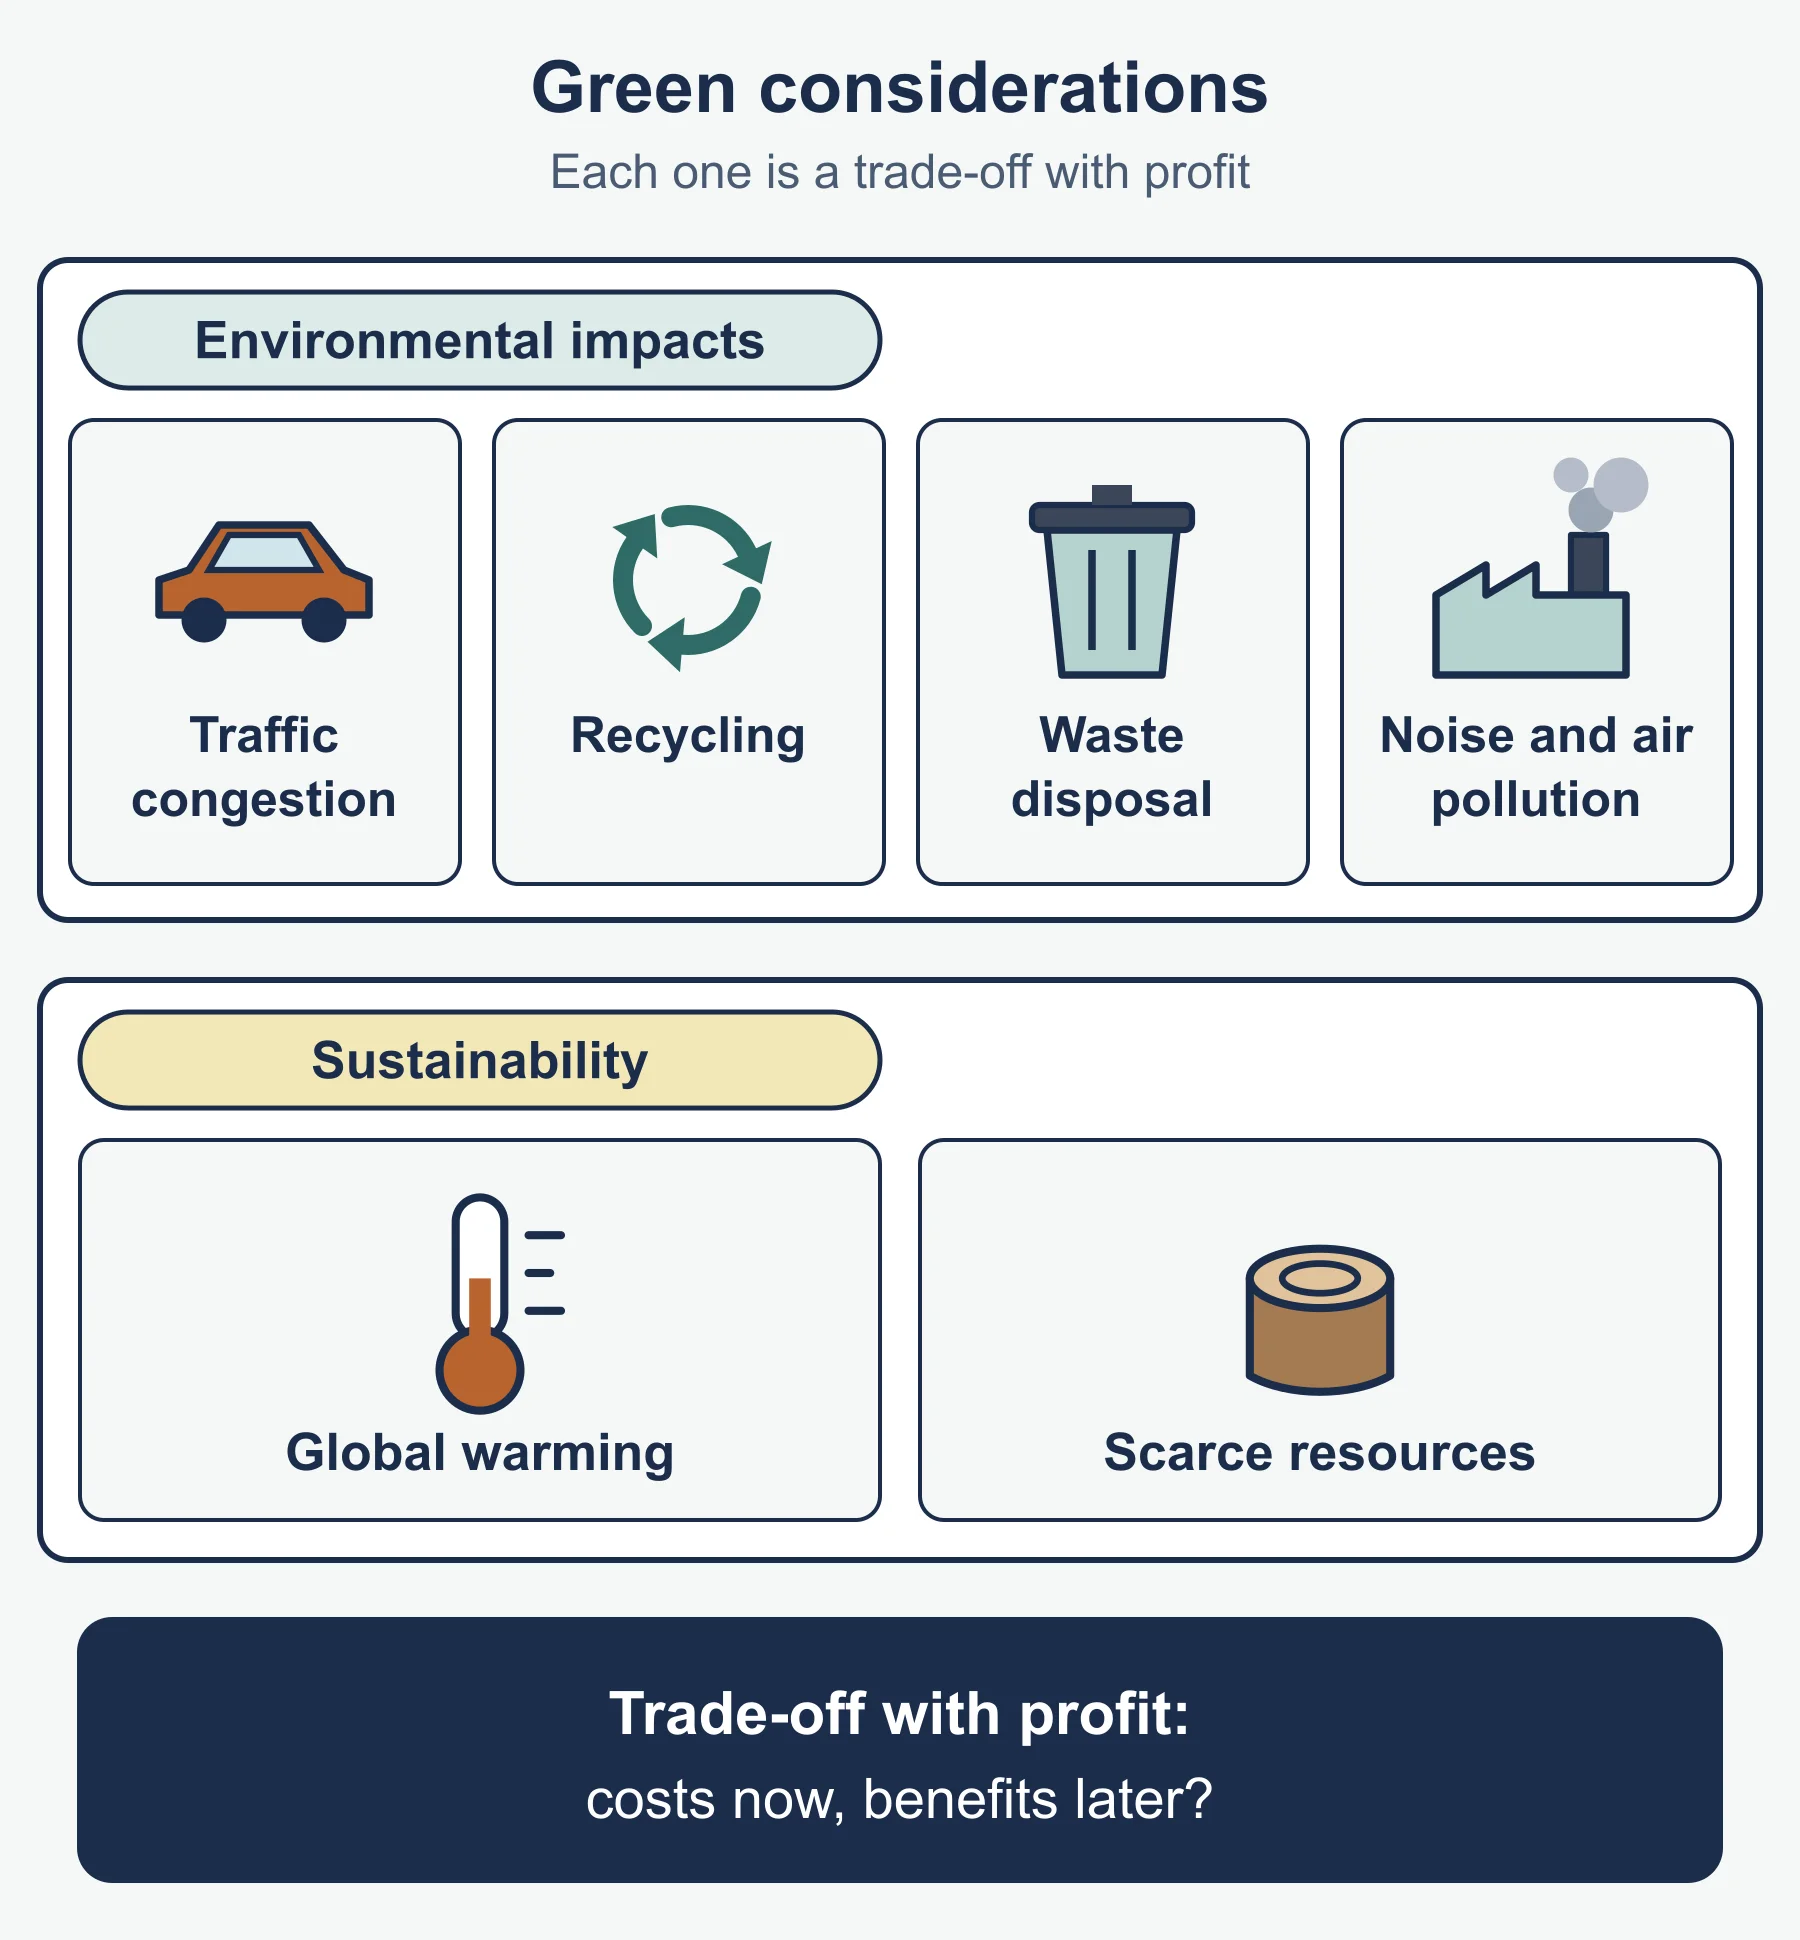
The specification says you should understand how society and consumers expect greater environmental responsibility in businesses’ decision-making, and the costs and benefits of behaving this way. The named areas are below.
| Area | The problem | What a business can do |
|---|---|---|
| Traffic congestion | Delivery vehicles and customer cars block local roads and annoy residents | Plan fewer, fuller deliveries; deliver outside rush hours; encourage car sharing |
| Recycling | Materials thrown away are lost and must be replaced | Use recycled materials and packaging; sort waste; take back used products |
| Disposing of waste | Rubbish costs money to remove and can harm land and water | Reduce waste at source; treat harmful waste properly |
| Noise pollution | Machines and vehicles disturb neighbours and workers | Insulate buildings; limit noisy work to set hours |
| Air pollution | Fumes and dust harm health and the local area | Use cleaner vehicles and fuels; fit filters |
Costs of acting responsibly: new equipment, dearer recycled inputs, staff training, slower delivery. Benefits: a better reputation, customers who prefer green products, lower waste costs and fewer neighbour complaints.
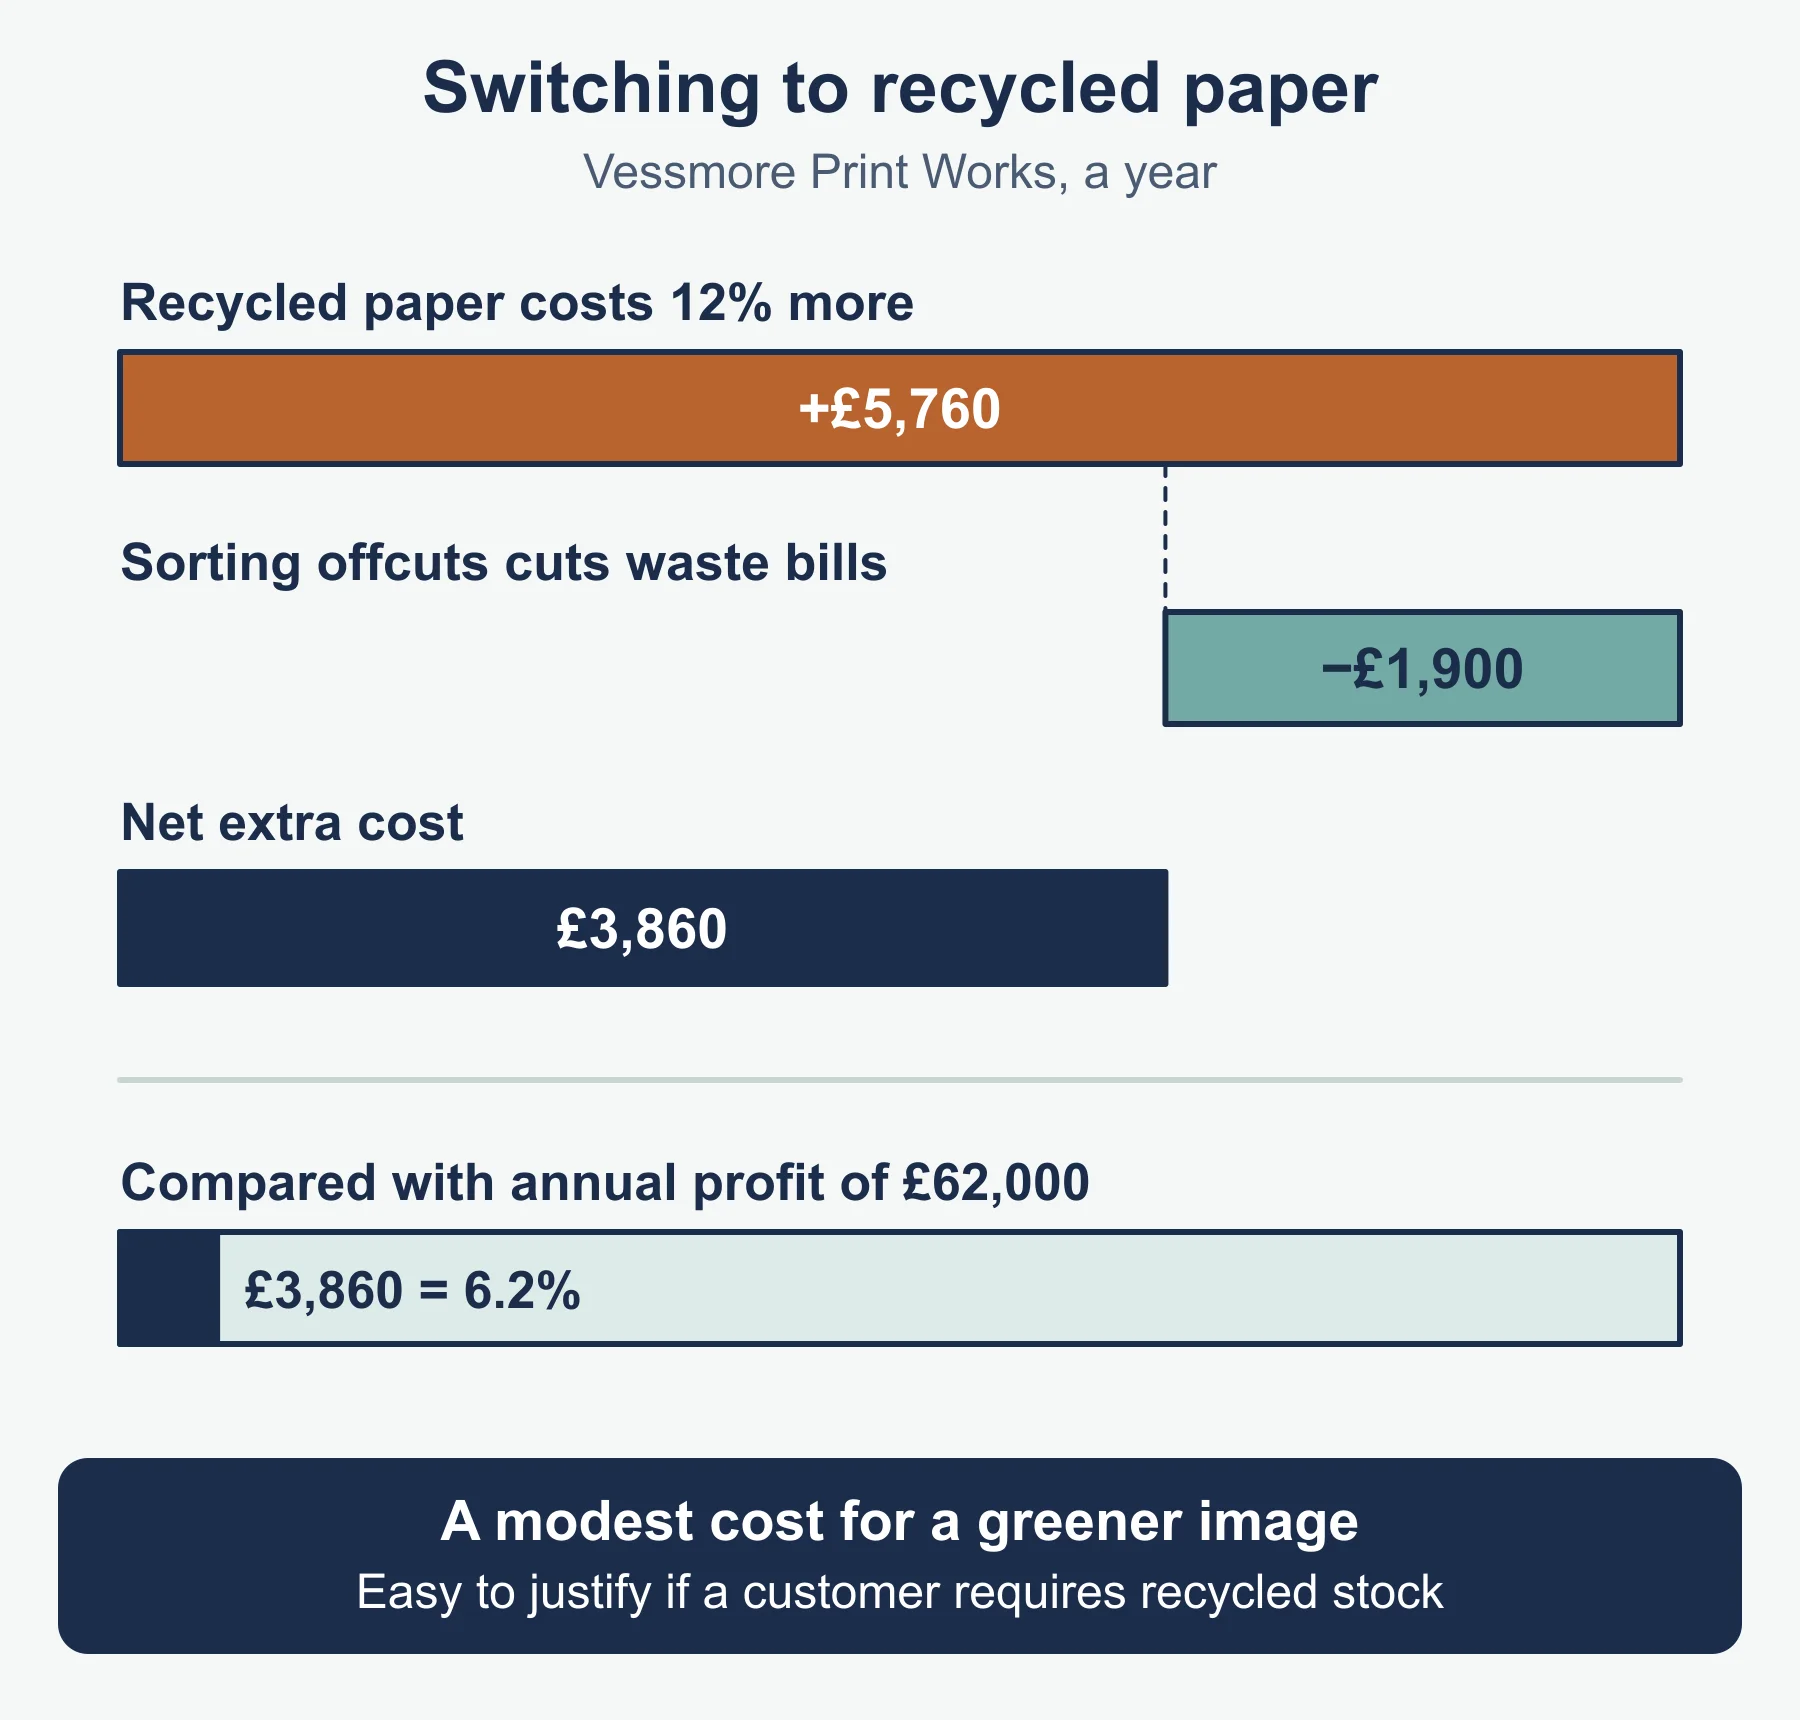
Worked example 4: switching to recycled paper (calculation). Vessmore Print Works spends £48,000 a year on paper. Recycled paper costs 12% more. Sorting offcuts for recycling cuts waste disposal bills by £1,900 a year. Annual profit is £62,000.
- Extra paper cost = 48,000 × 0.12 = £5,760.
- Net extra cost = 5,760 - 1,900 = £3,860.
- As a share of profit = 3,860 ÷ 62,000 × 100 = 6.2% (1 d.p.).
The net cost is modest. If it wins a contract with a customer who requires recycled stock, the decision is easy to justify.
Sustainability
The specification gives no definition. In the usual textbook sense, sustainability means a business operates so that today’s demand is served without leaving later generations short of what they will need. For business, it means using resources and operating in ways that can continue over time. The specification names two ideas.
- Global warming: burning fossil fuels in factories, vehicles and heating releases gases that warm the planet. Society expects businesses to cut their emissions, for example by using renewable energy.
- Using scarce resources: some materials, such as certain metals, fuels and clean water, are limited. Using them quickly raises future costs and may eventually run them out.
The trade-off between sustainability and profit often has a time dimension. Spending now cuts profit now, while savings or reputation arrive later.
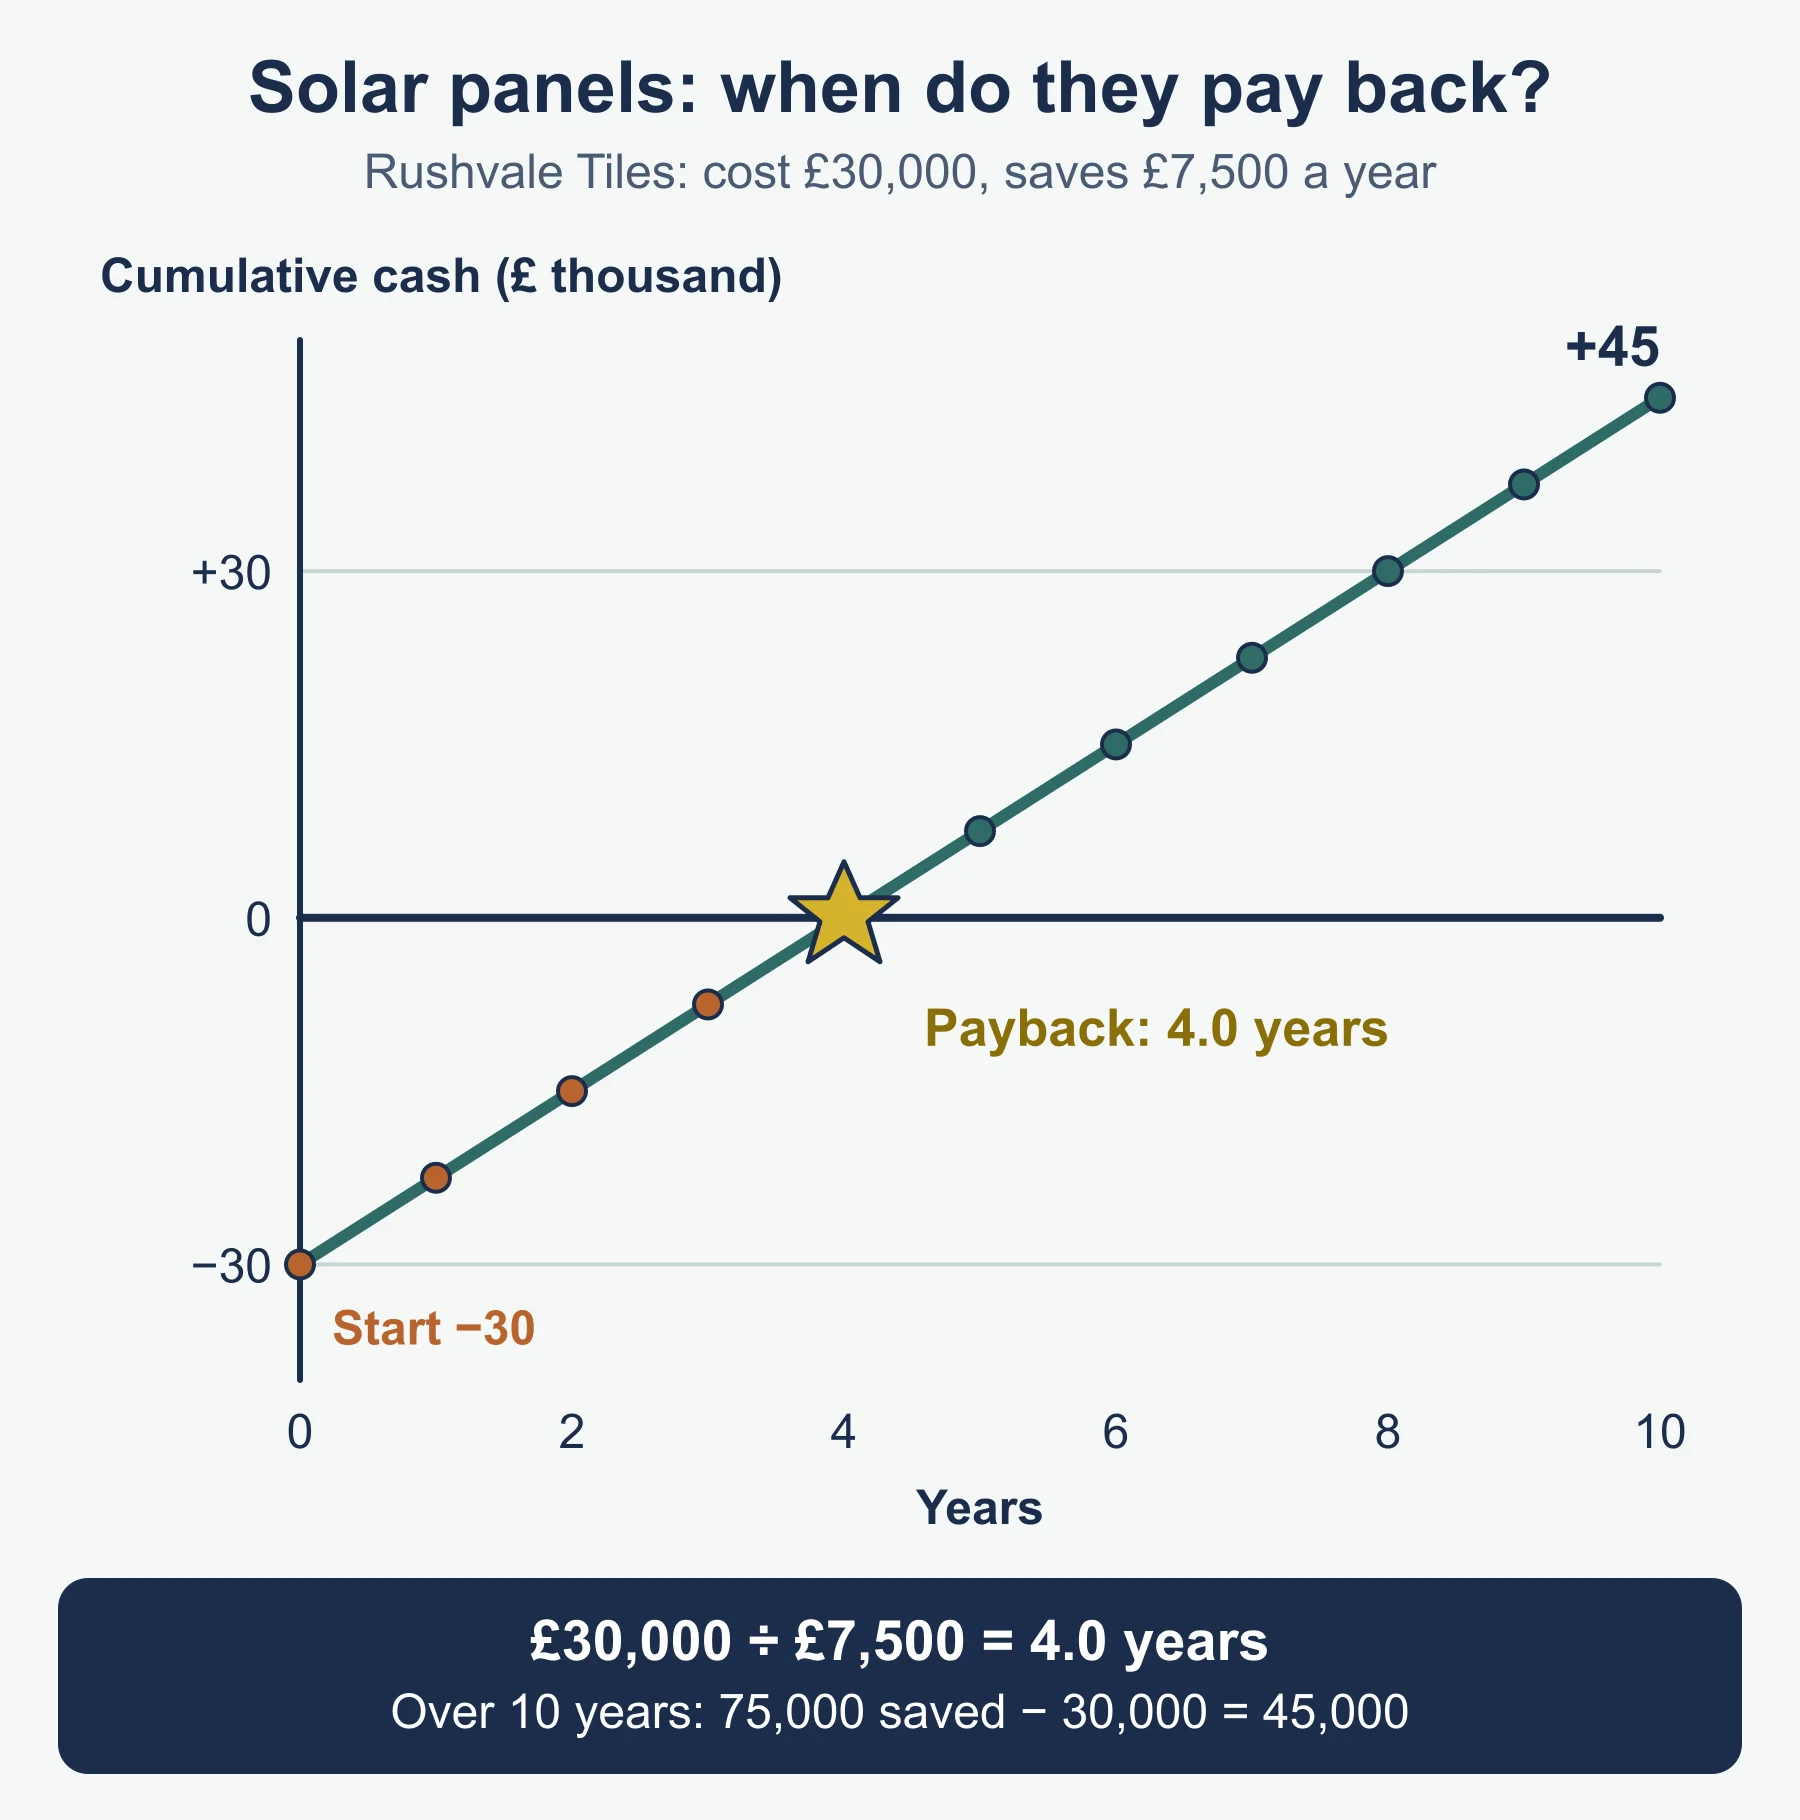
Worked example 5: solar panels (calculation). Rushvale Tiles considers fitting solar panels to its factory roof for £30,000. They would cut electricity bills by £7,500 a year.
- Payback = 30,000 ÷ 7,500 = 4.0 years.
- If the panels last 10 years, savings = 7,500 × 10 = £75,000.
- Net gain over their life = 75,000 - 30,000 = £45,000.
Profit falls in the year of purchase if paid from cash, but emissions and later costs fall. The owner must be confident the panels will last.
How to write an analysis or evaluation answer
- Make a point, such as “this raises costs”, and explain why using the case details.
- State the effect on a stakeholder or on profit.
- For evaluation, give the other side, then reach a judgement that depends on something in the case, such as the size of the cost, the type of customer, or the time scale.
Common errors
- Describing a technology without saying how it changes sales, costs or stakeholders.
- Treating e-commerce as only a benefit and missing delivery cost.
- Mixing up ethics (a choice) with legal duties.
- Saying ethical behaviour always increases profit. It often does not, at least at first.
- Listing environmental issues without a cost and a benefit for the business.
Frequently asked questions
What is the trade-off between ethics and profit? Ethical choices such as paying suppliers more often raise costs and cut profit per unit, but they may bring loyalty, a better reputation and more sales. Weigh the cost against the likely benefit for the specific business before reaching a judgement.
How does sustainability affect profit over time? The trade-off between sustainability and profit often has a time dimension. Spending now cuts profit now, while savings or reputation benefits arrive later.
What two sustainability ideas does the 9225 specification name? The two ideas are global warming, caused by burning fossil fuels in factories, vehicles and heating, and the use of scarce resources such as certain metals, fuels and clean water.
How should a business choose a digital communication method? Choose the method to fit the stakeholder and the message. Telling many customers about a closure date suits email, while a tense negotiation with a supplier abroad may suit video conferencing, because tone and expression matter.
What are the drawbacks of e-commerce for a business? Delivery, packaging and returns cost money, website, payment and security systems cost money to build and maintain, and customers cannot touch the product. Some sales may also simply move from the shop to the website, so revenue does not rise by the full amount of online sales.
Next steps
Try the practice questions, then a free diagnostic.
Official syllabus
OxfordAQA International GCSE Business (9225) specification, version 3.1, for International GCSE exams May/June 2022 onwards, published by OxfordAQA. Sections 3.2.1 and 3.2.2.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
OxfordAQA IGCSE Business: Technology and Ethical and environmental considerations (9225) – Practice Questions
Twelve original questions with worked answers on ICT, e-commerce, ethics, the environment and sustainability for OxfordAQA International GCSE Business.
Business · OxfordAQA · IGCSE
Try questions -
Revision notes
OxfordAQA IGCSE Business: Technology and Ethical and environmental considerations (9225) – Revision Notes
Condensed recall notes, tables and a self-test on ICT, e-commerce, ethics, the environment and sustainability for OxfordAQA International GCSE Business.
Business · OxfordAQA · IGCSE
Revise topic -
Study guides
OxfordAQA IGCSE Business: The economic climate on business and Globalisation (9225)
Study guide to interest rates, employment, spending, globalisation and exchange rates for OxfordAQA International GCSE Business, sections 3.2.3-3.2.4.
Business · OxfordAQA · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
OxfordAQA Business teachers at Marlbridge
