
Revision Notes
AQA AS-Level Business: Financial management (7137) – Revision Notes
Condensed revision notes for AQA AS Business (7137) 3.1.4 financial management: formulas, methods, key distinctions and a self-test with answers.
- Subject
- Business
- Level
- AS LEVEL
- Topic
- What is business? Managing marketing and finance
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to AQA AS Level Business (7137), For first teaching from September 2026. Official specification .
Syllabus page (what it covers and how it is assessed): AQA AS Level Business.
Syllabus points this page covers
7137
- 3.1.4 Financial management
Found an error? Report a correction.
Need help with this topic? Request a free trial class for AS Level Business (7137).
Condensed notes for 3.1.4 Financial management in AQA AS Business (7137), for first teaching from September 2026. For full explanations and worked examples, read the study guide. Test yourself afterwards with the practice questions, and see the course structure guide for how the sub-topic fits the course. Course hub: AQA AS Business. Tick-off list: checklist. To find weak spots first, try all free 10-minute diagnostics.
The notes were checked on 5 November 2026 against AQA’s AS and A-level Business specification (7137/7138), Version 1.1, November 2025. They follow its headings: managing finance, sources of finance, break-even, profit, budgets, cash flow and liquidity, financial reporting, and assessing financial position and performance. Formulas are those in the specification’s annex. Ethics in finance is A-level only and is left out.
Key definitions
| Term | Meaning |
|---|---|
| Cash flow | Money moving into and out of the business |
| Profit | Revenue minus costs over a period |
| Gross profit | Revenue − cost of sales |
| Operating profit | Gross profit − operating expenses |
| Profit for the year | Operating profit + profit from other activities − net finance costs − tax |
| Profitability | Profit measured against revenue or capital |
| Liquidity | Ability to pay short-term debts as they fall due |
| Budget | A financial plan for income and spending |
| Zero-based budget | A budget built from zero, every item justified afresh |
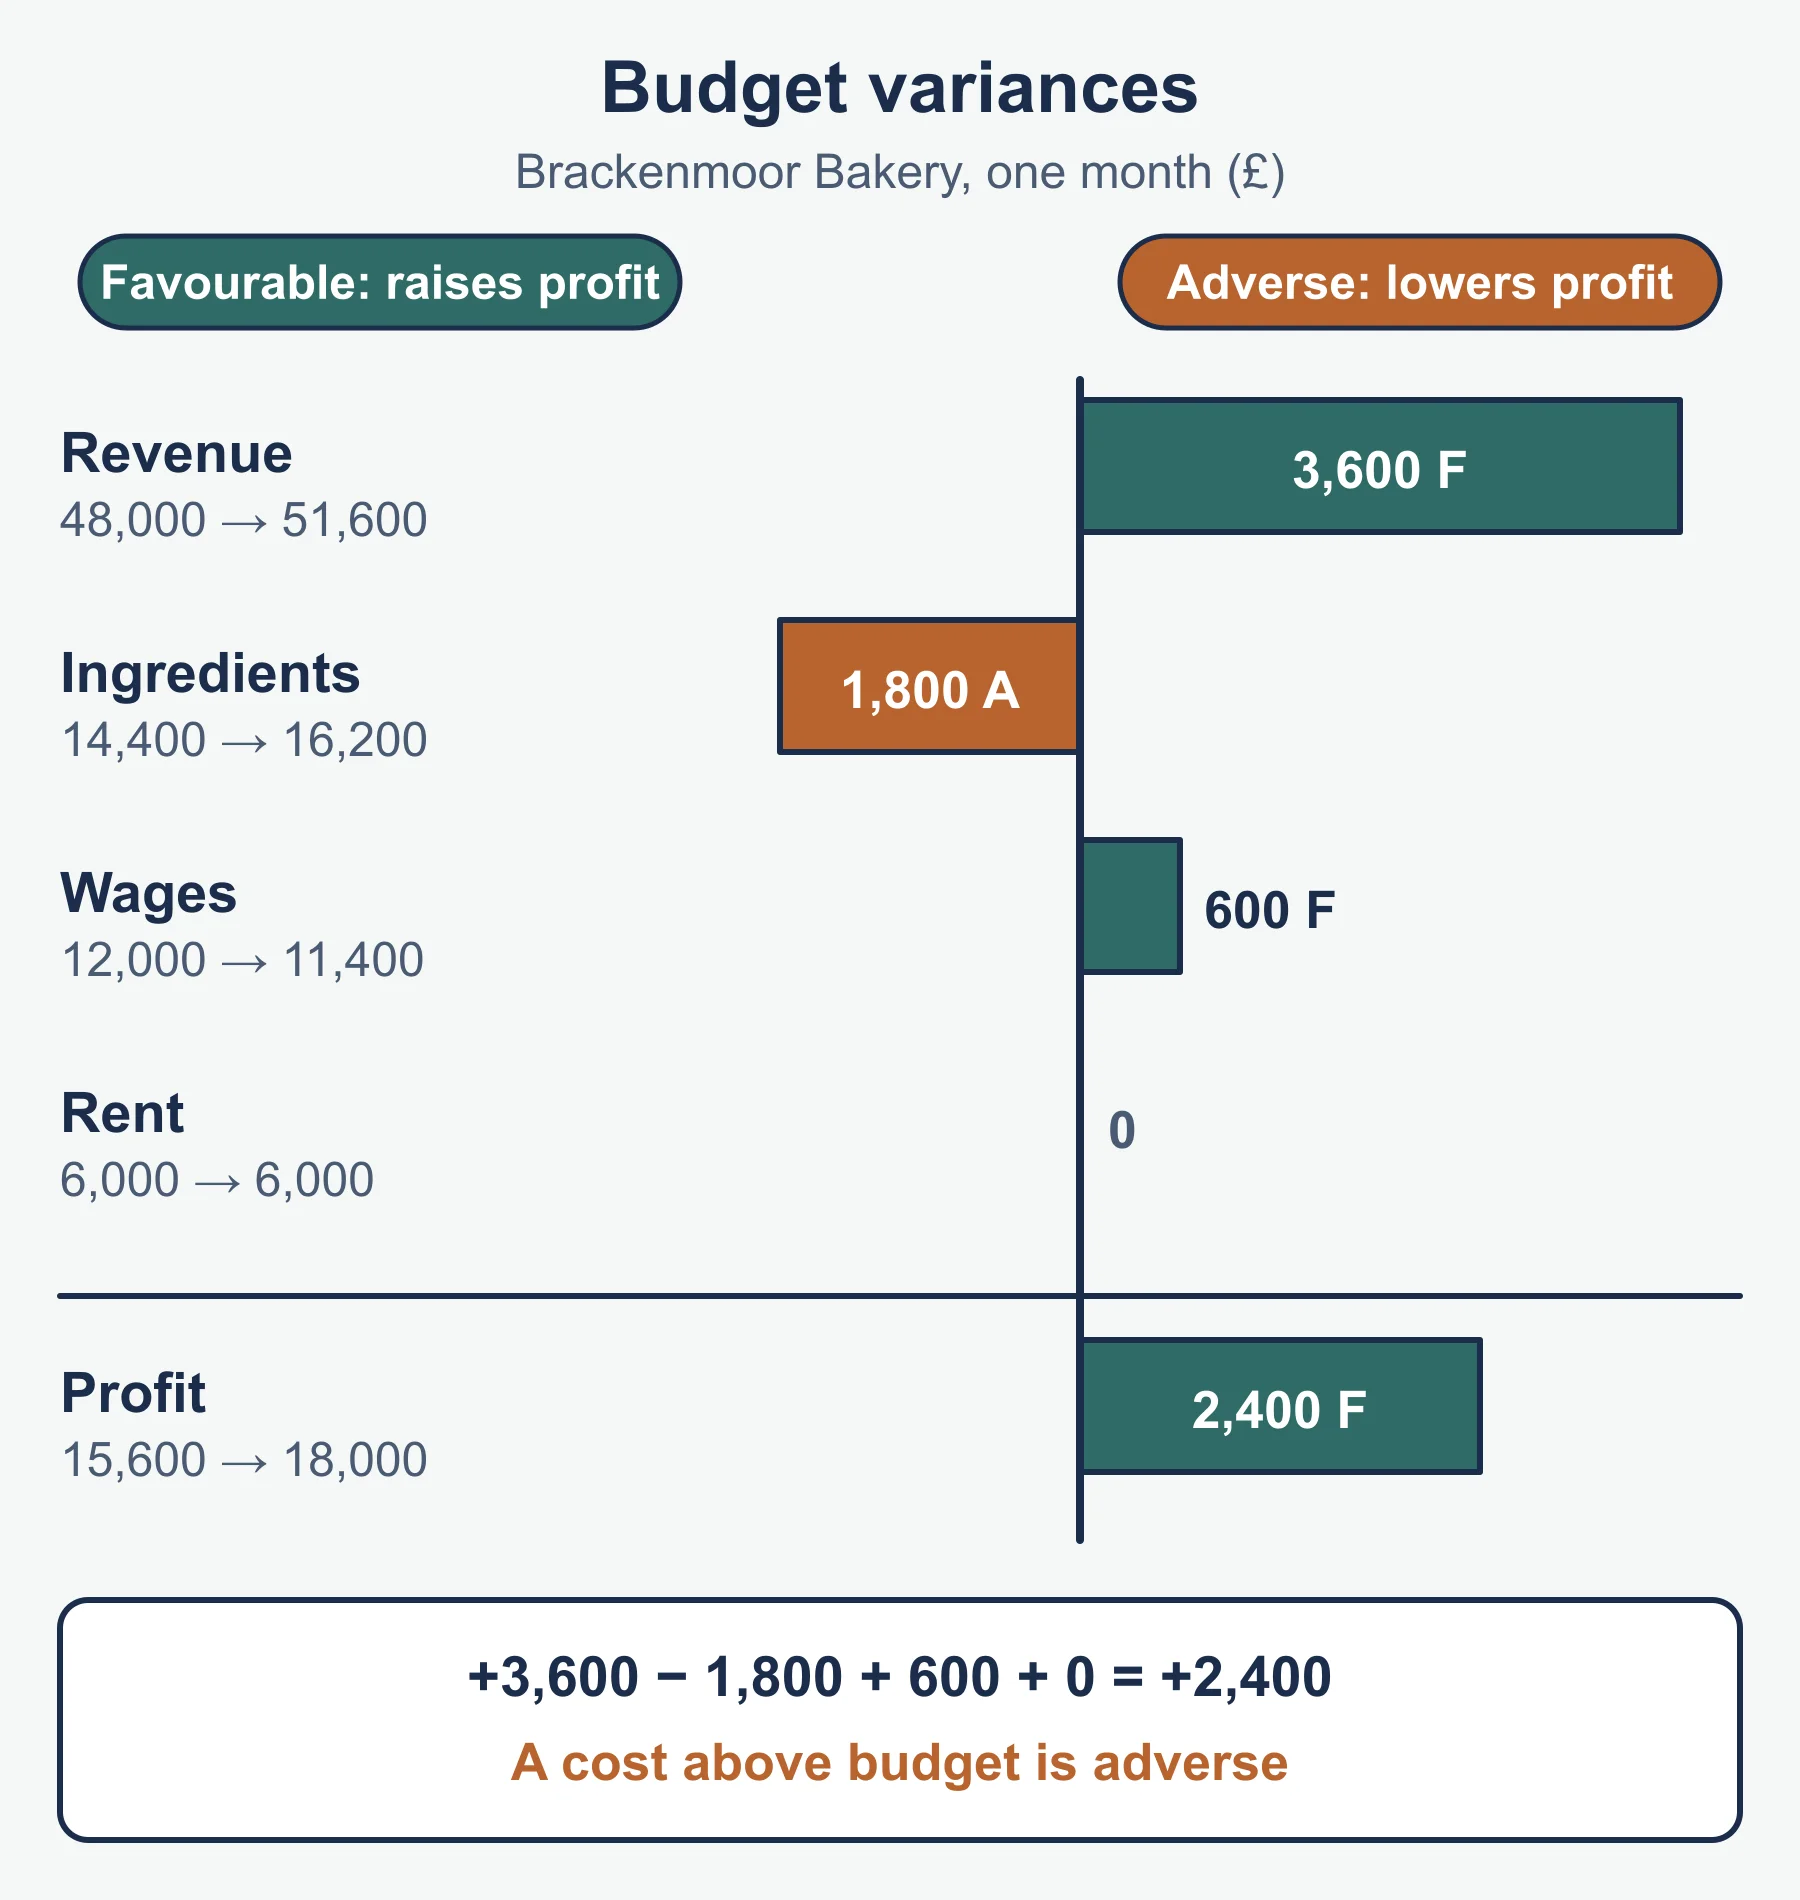
| Budget variance | Budgeted figure − actual figure |
| Favourable variance | Improves profit |
| Adverse variance | Reduces profit |
| Contribution per unit | Selling price − variable cost per unit |
| Margin of safety | Planned output − break-even output |
| Receivables | Customers who owe the business money |
| Payables | Suppliers the business owes |
Formulas
As in the specification’s annex of formulae (closing cash balance is the standard method).
| Measure | Formula |
|---|---|
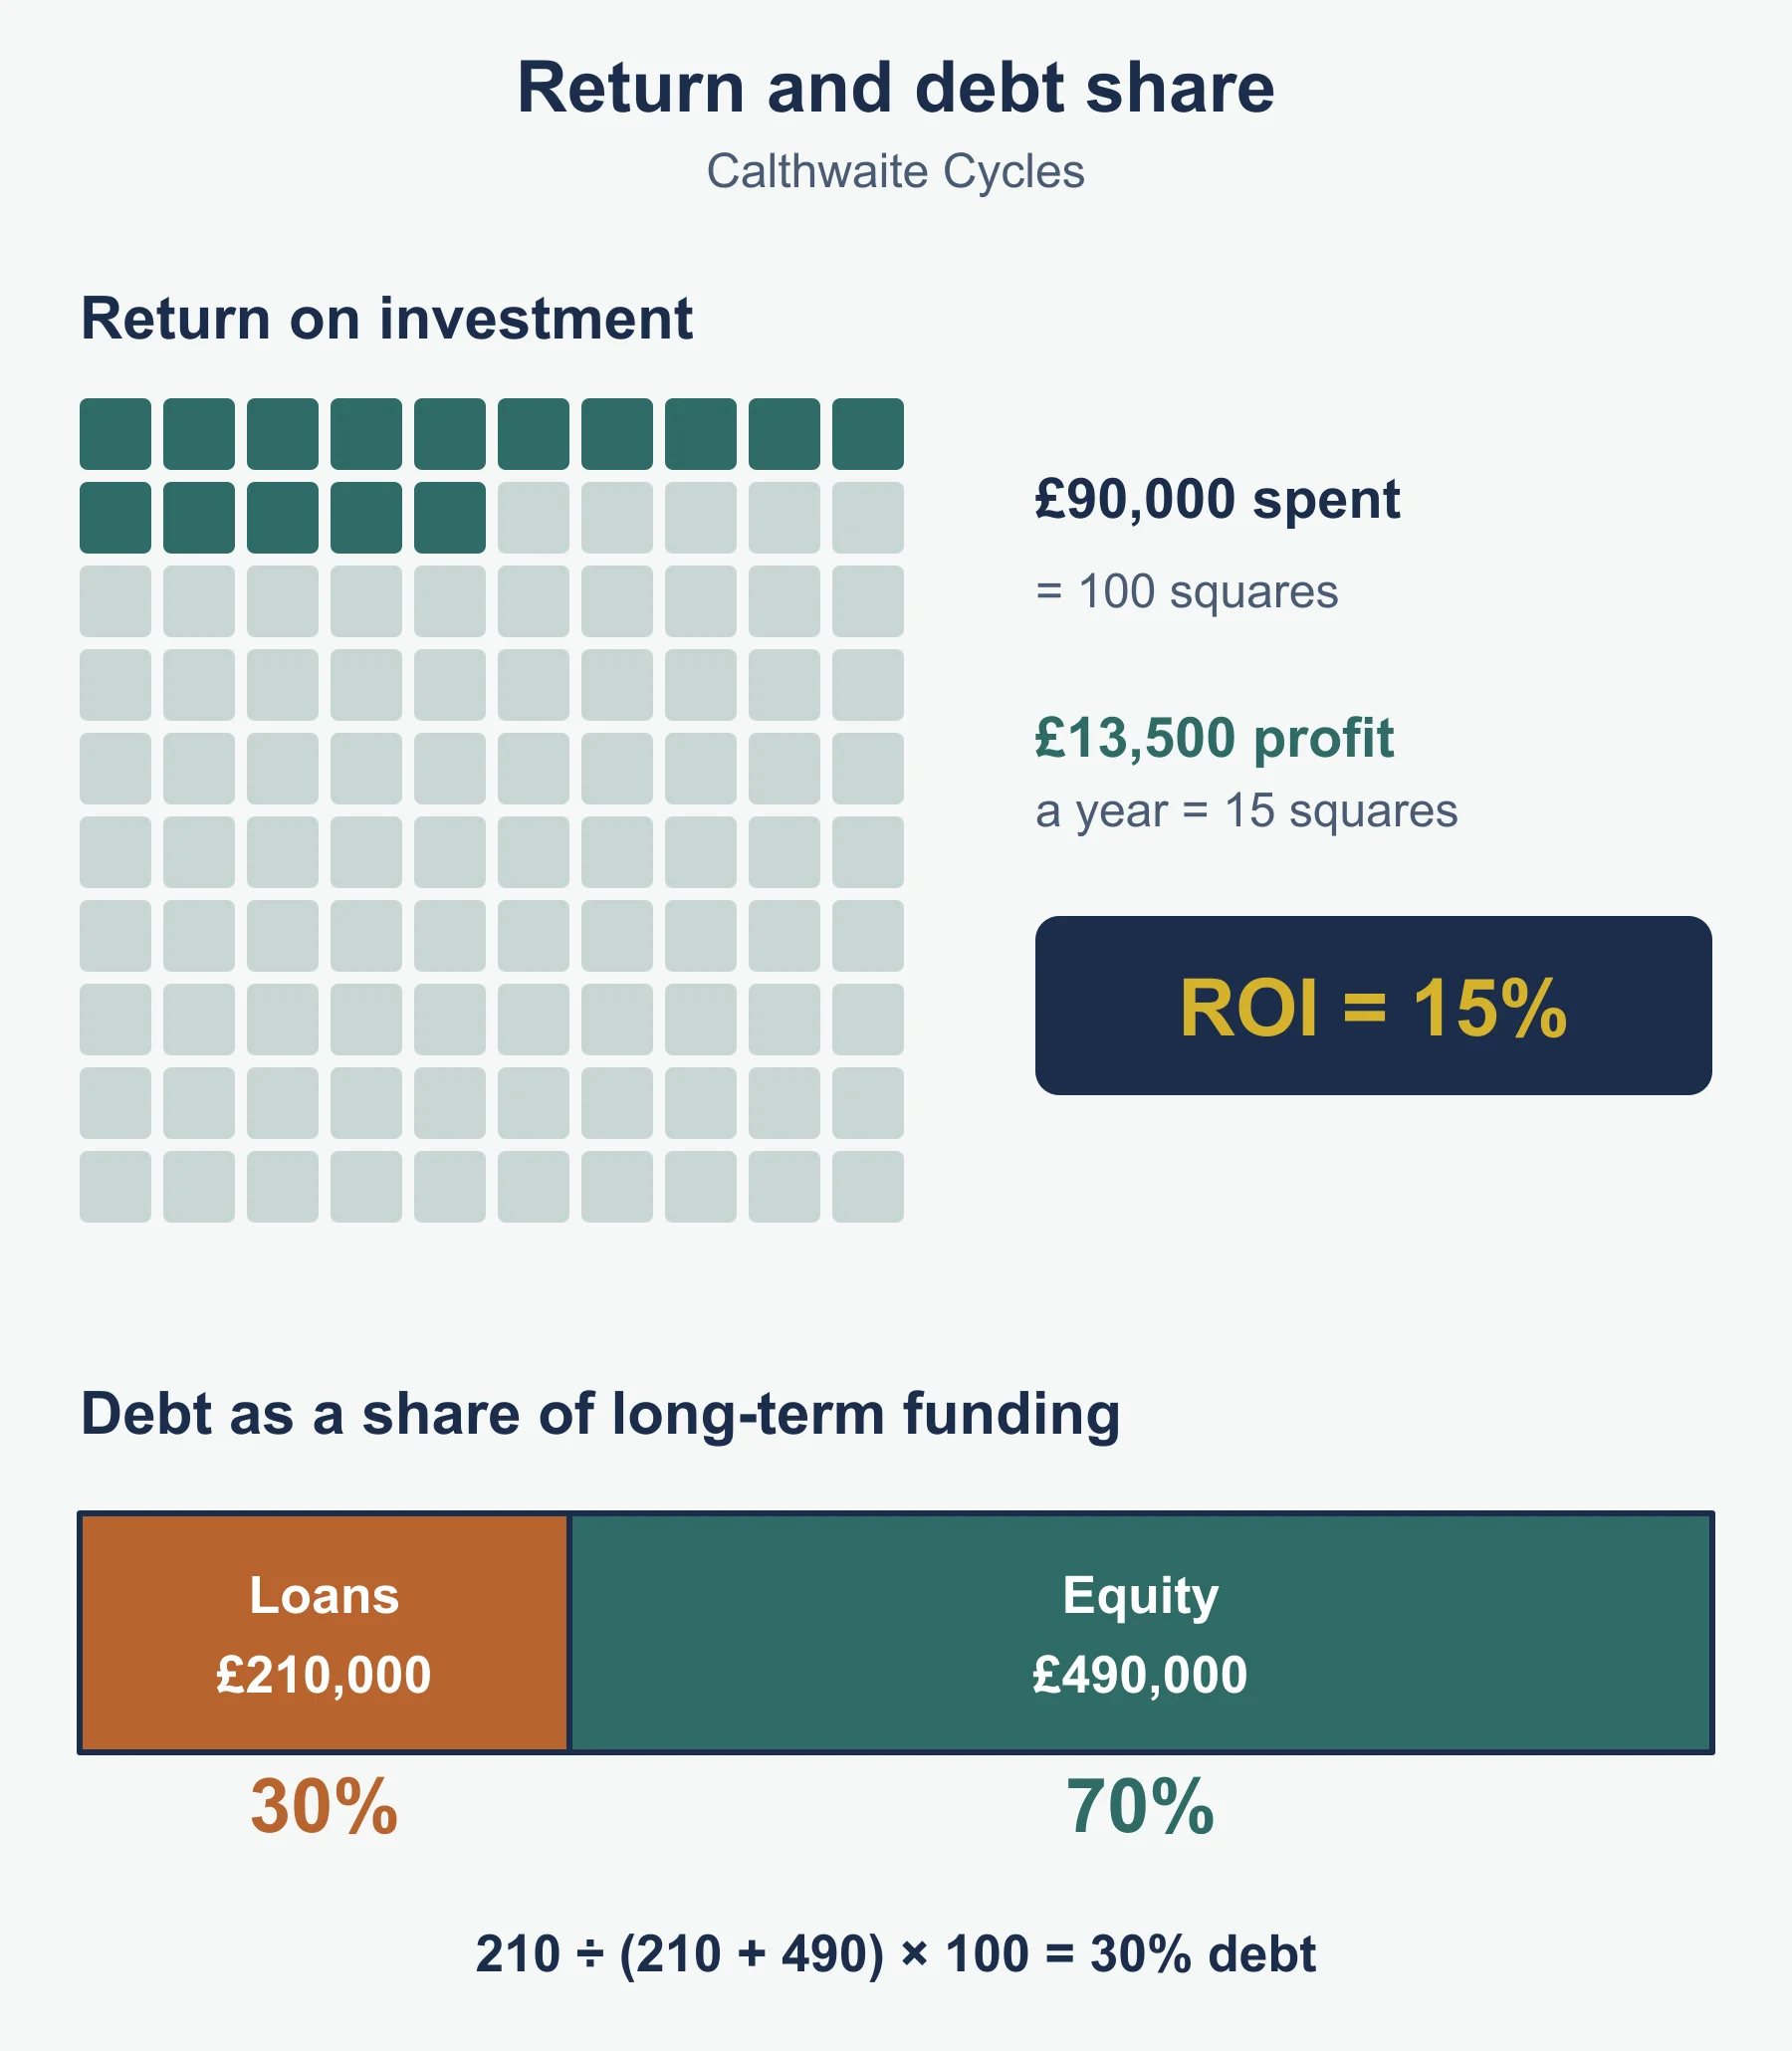
| Return on investment (%) | Profit from the investment ÷ cost of the investment × 100 |
| Gearing (%) | Non-current liabilities ÷ (total equity + non-current liabilities) × 100 |
| ROCE (%) | Operating profit ÷ (total equity + non-current liabilities) × 100 |
| Gross profit margin (%) | Gross profit ÷ revenue × 100 |
| Operating profit margin (%) | Operating profit ÷ revenue × 100 |
| Profit for the year margin (%) | Profit for the year ÷ revenue × 100 |
| Current ratio | Current assets ÷ current liabilities |
| Acid test ratio | (Current assets − inventory) ÷ current liabilities |
| Payables days | Payables ÷ cost of sales × 365 |
| Receivables days | Receivables ÷ revenue × 365 |
| Dividend per share | Total dividend paid ÷ number of ordinary shares in issue |
| Dividend yield (%) | Dividend per share (pence) ÷ share price (pence) × 100 |
| Break-even output | Fixed costs ÷ contribution per unit |
| Total contribution | Contribution per unit × units sold |
| Profit (break-even setting) | Total contribution − fixed costs |
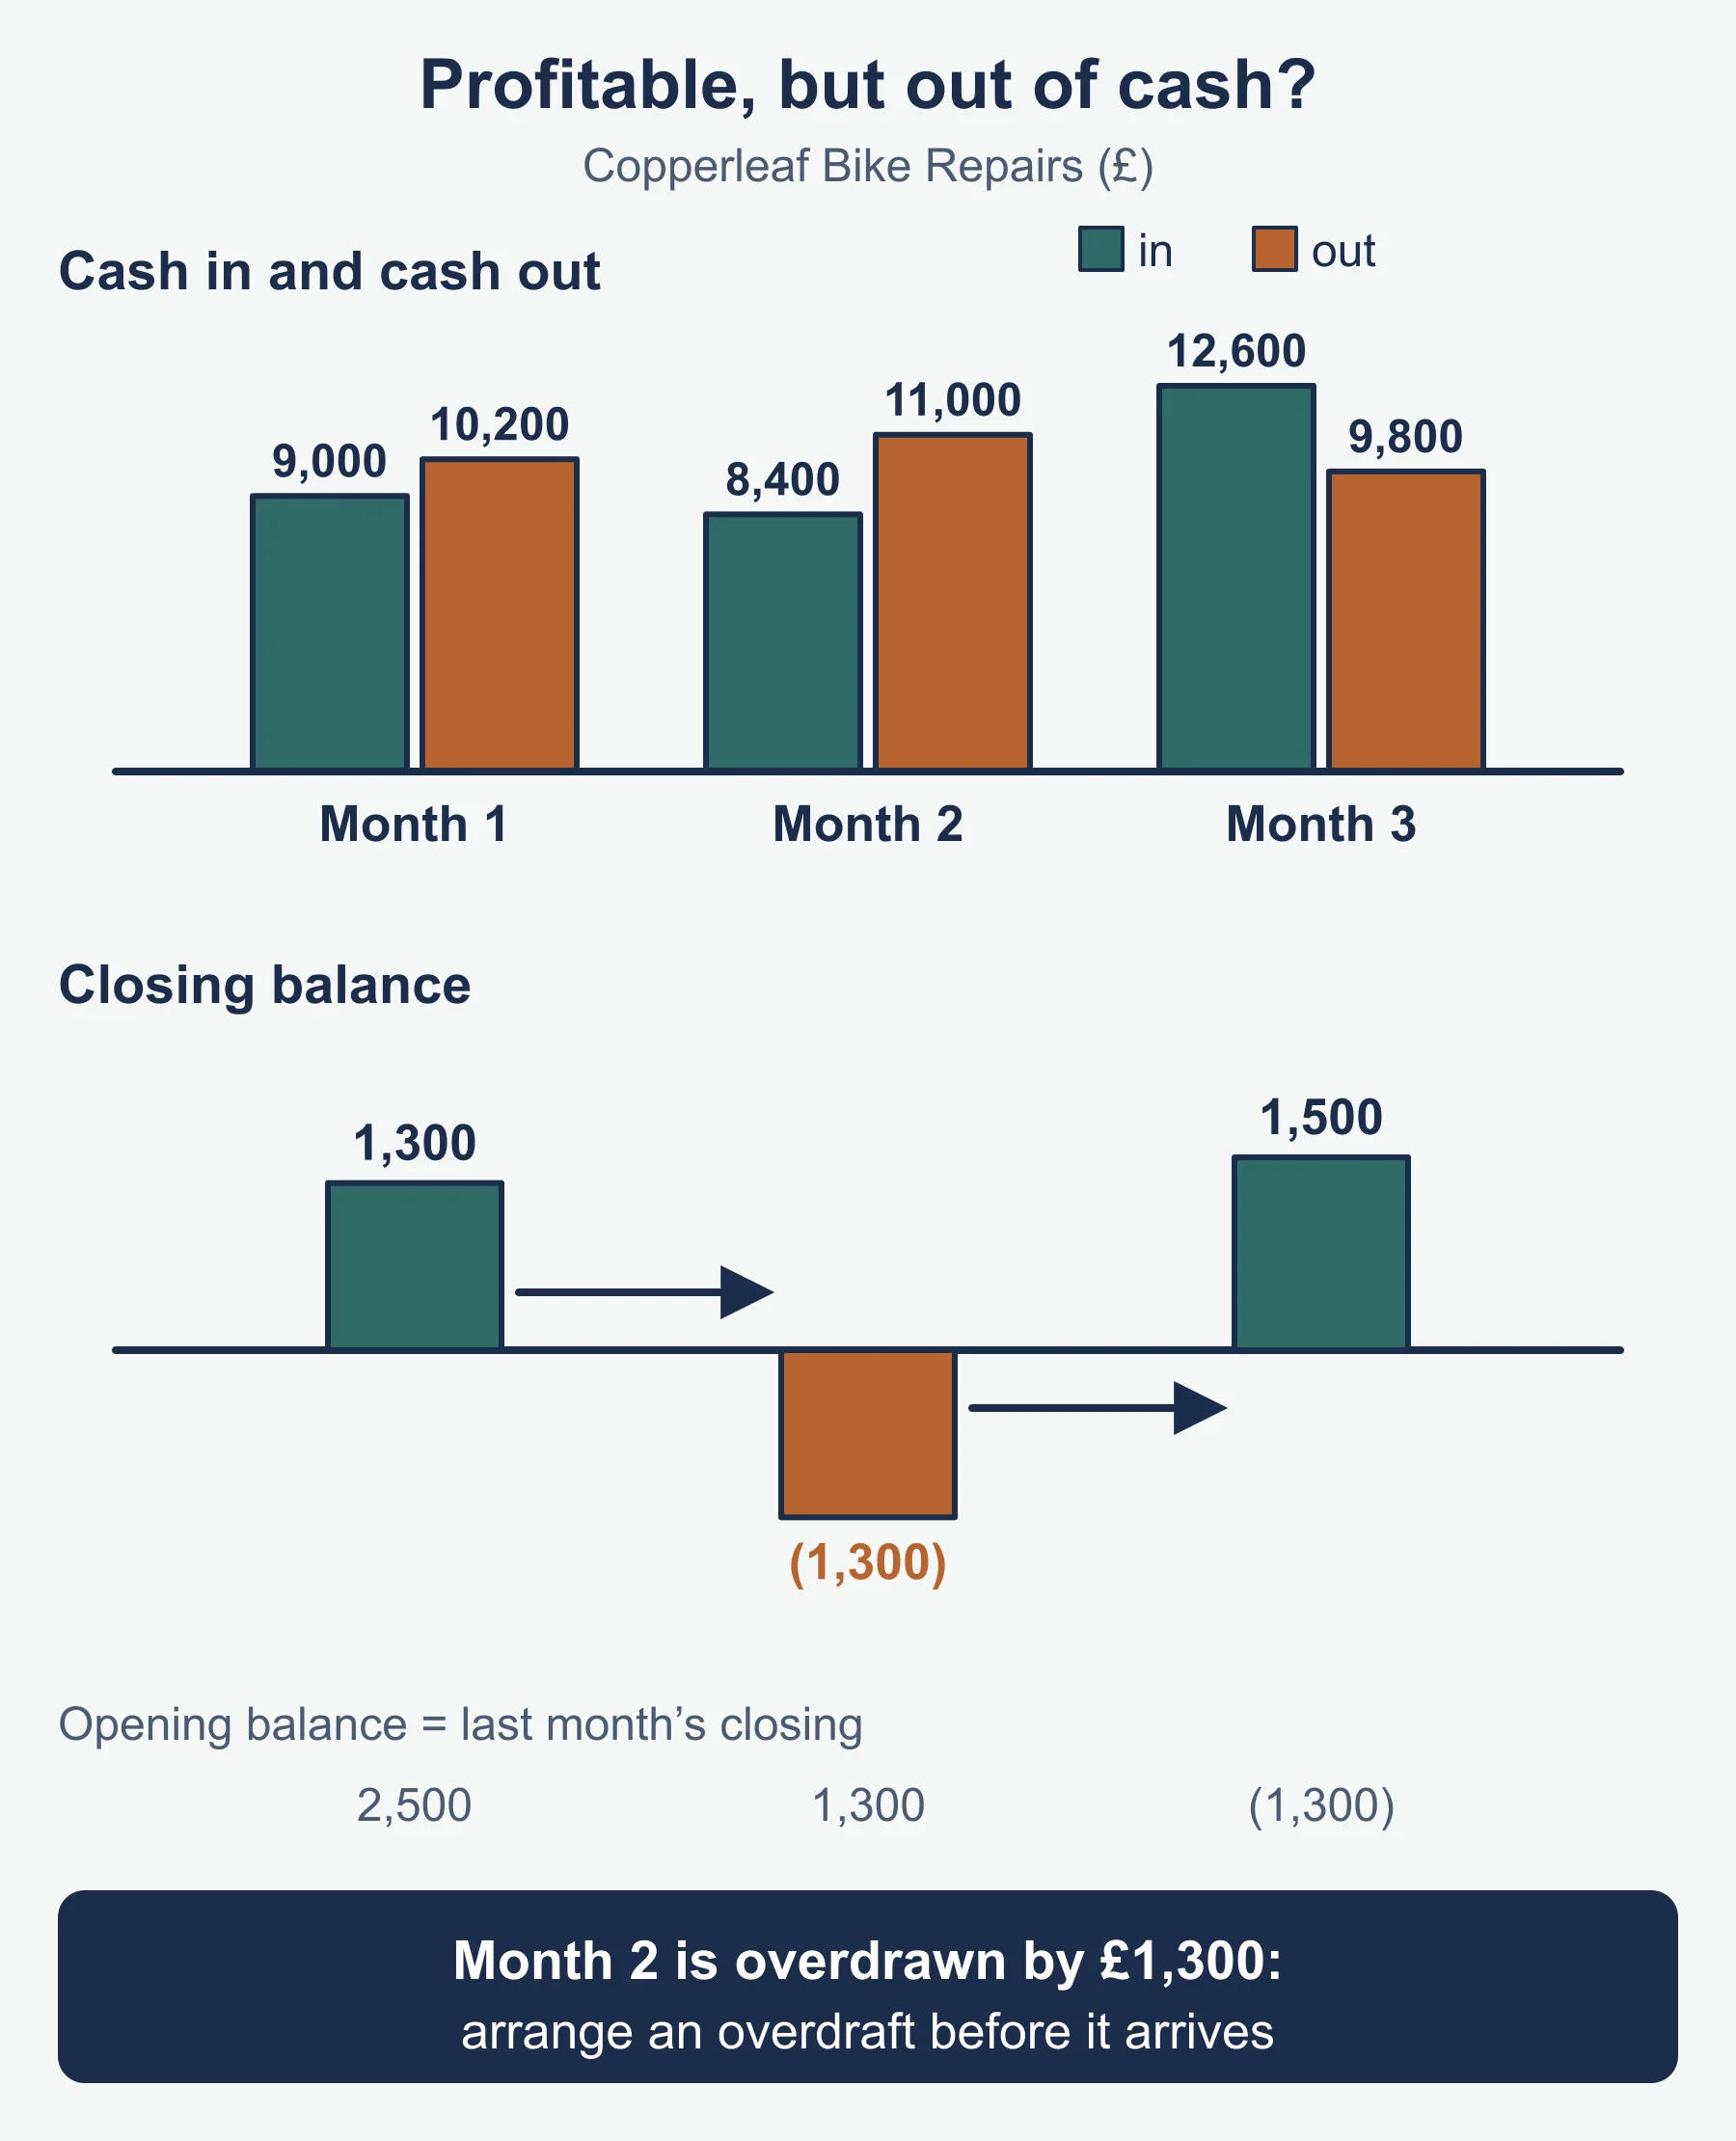
| Closing cash balance | Opening balance + cash in − cash out |
Managing finance: what to remember
- Value of objectives: they give targets, allow comparison with results and guide other functions.
- Five financial objectives in the specification: profit, profitability, cash flow, liquidity and levels of borrowing.
- Cash flow is not profit. Profit can be earned on credit sales long before cash arrives, and cash can arrive (from a loan) without any profit.
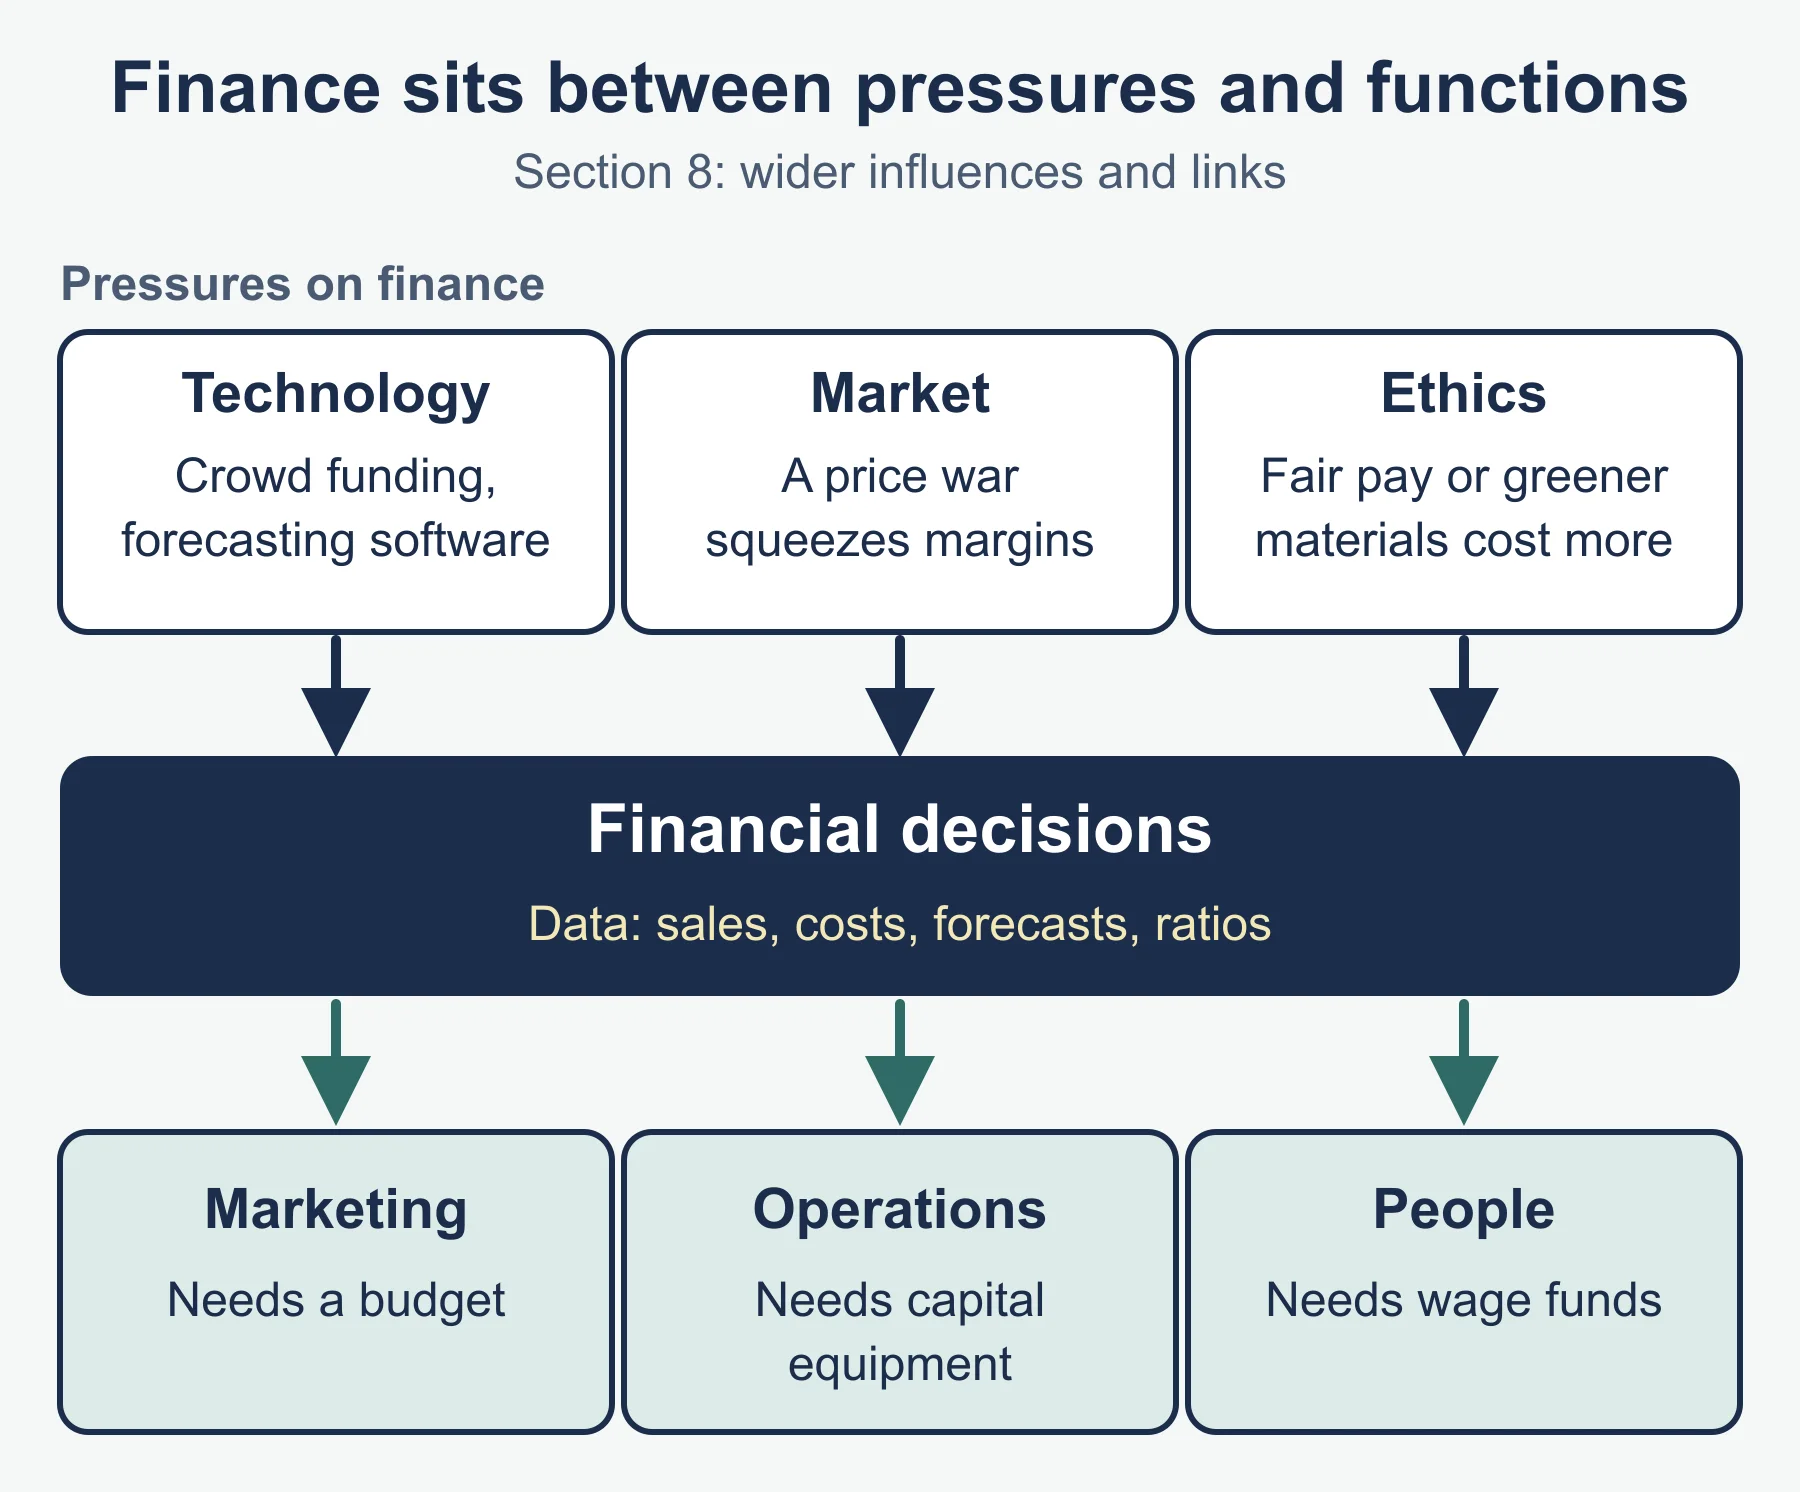
- Internal influences: owners’ attitude to risk, size, cash position, other functions’ needs. External influences: interest rates, competitors, the economic climate, lenders, ethical expectations.
- High borrowing raises the commitment to repay and pay interest; low borrowing may mean growth is slower because retained profits and share capital are limited.
- Financial decisions link to every other function, and affect competitiveness.
Worked reminder. Zelmore Ltd earns extra profit of £8,400 a year from a £60,000 machine. ROI = 8,400 ÷ 60,000 × 100 = 14%. Its long-term funding is £80,000 of loans and £240,000 of equity, so gearing = 80,000 ÷ 320,000 × 100 = 25%.
Budgets and variances
Method in steps:
- Find budgeted minus actual for each line.
- Decide the label by the effect on profit: higher revenue or lower cost is favourable; lower revenue or higher cost is adverse.
- Find the profit variance by comparing budgeted and actual profit.
- Give a cause, then say what action management might take.
Example: Zelmore budgeted £18,000 for materials and spent £16,200. The variance is £1,800 (10% of budget) and favourable, though a good answer asks whether cheaper materials lowered quality.
Value of budgeting: sets targets, controls spending, gives responsibility, coordinates departments, flags problems early. Limits: forecasts may be wrong, rigid budgets discourage flexibility, and variances only show what changed, not why. Zero-based budgeting makes every item justify itself from zero: it cuts spending that is no longer needed but takes much more management time.
Cash flow forecast: method
- List all cash in each month (not sales on credit until they are paid).
- List all cash out.
- Net cash flow = in − out.
- Closing balance = opening balance + net cash flow.
- Carry the closing balance to the next month’s opening balance.
- Look for months where the balance goes negative and plan short-term finance.
Common fixes: an overdraft for a short gap, plus the ways of improving cash flow listed below.
Break-even: method
- Contribution per unit = price − variable cost per unit.
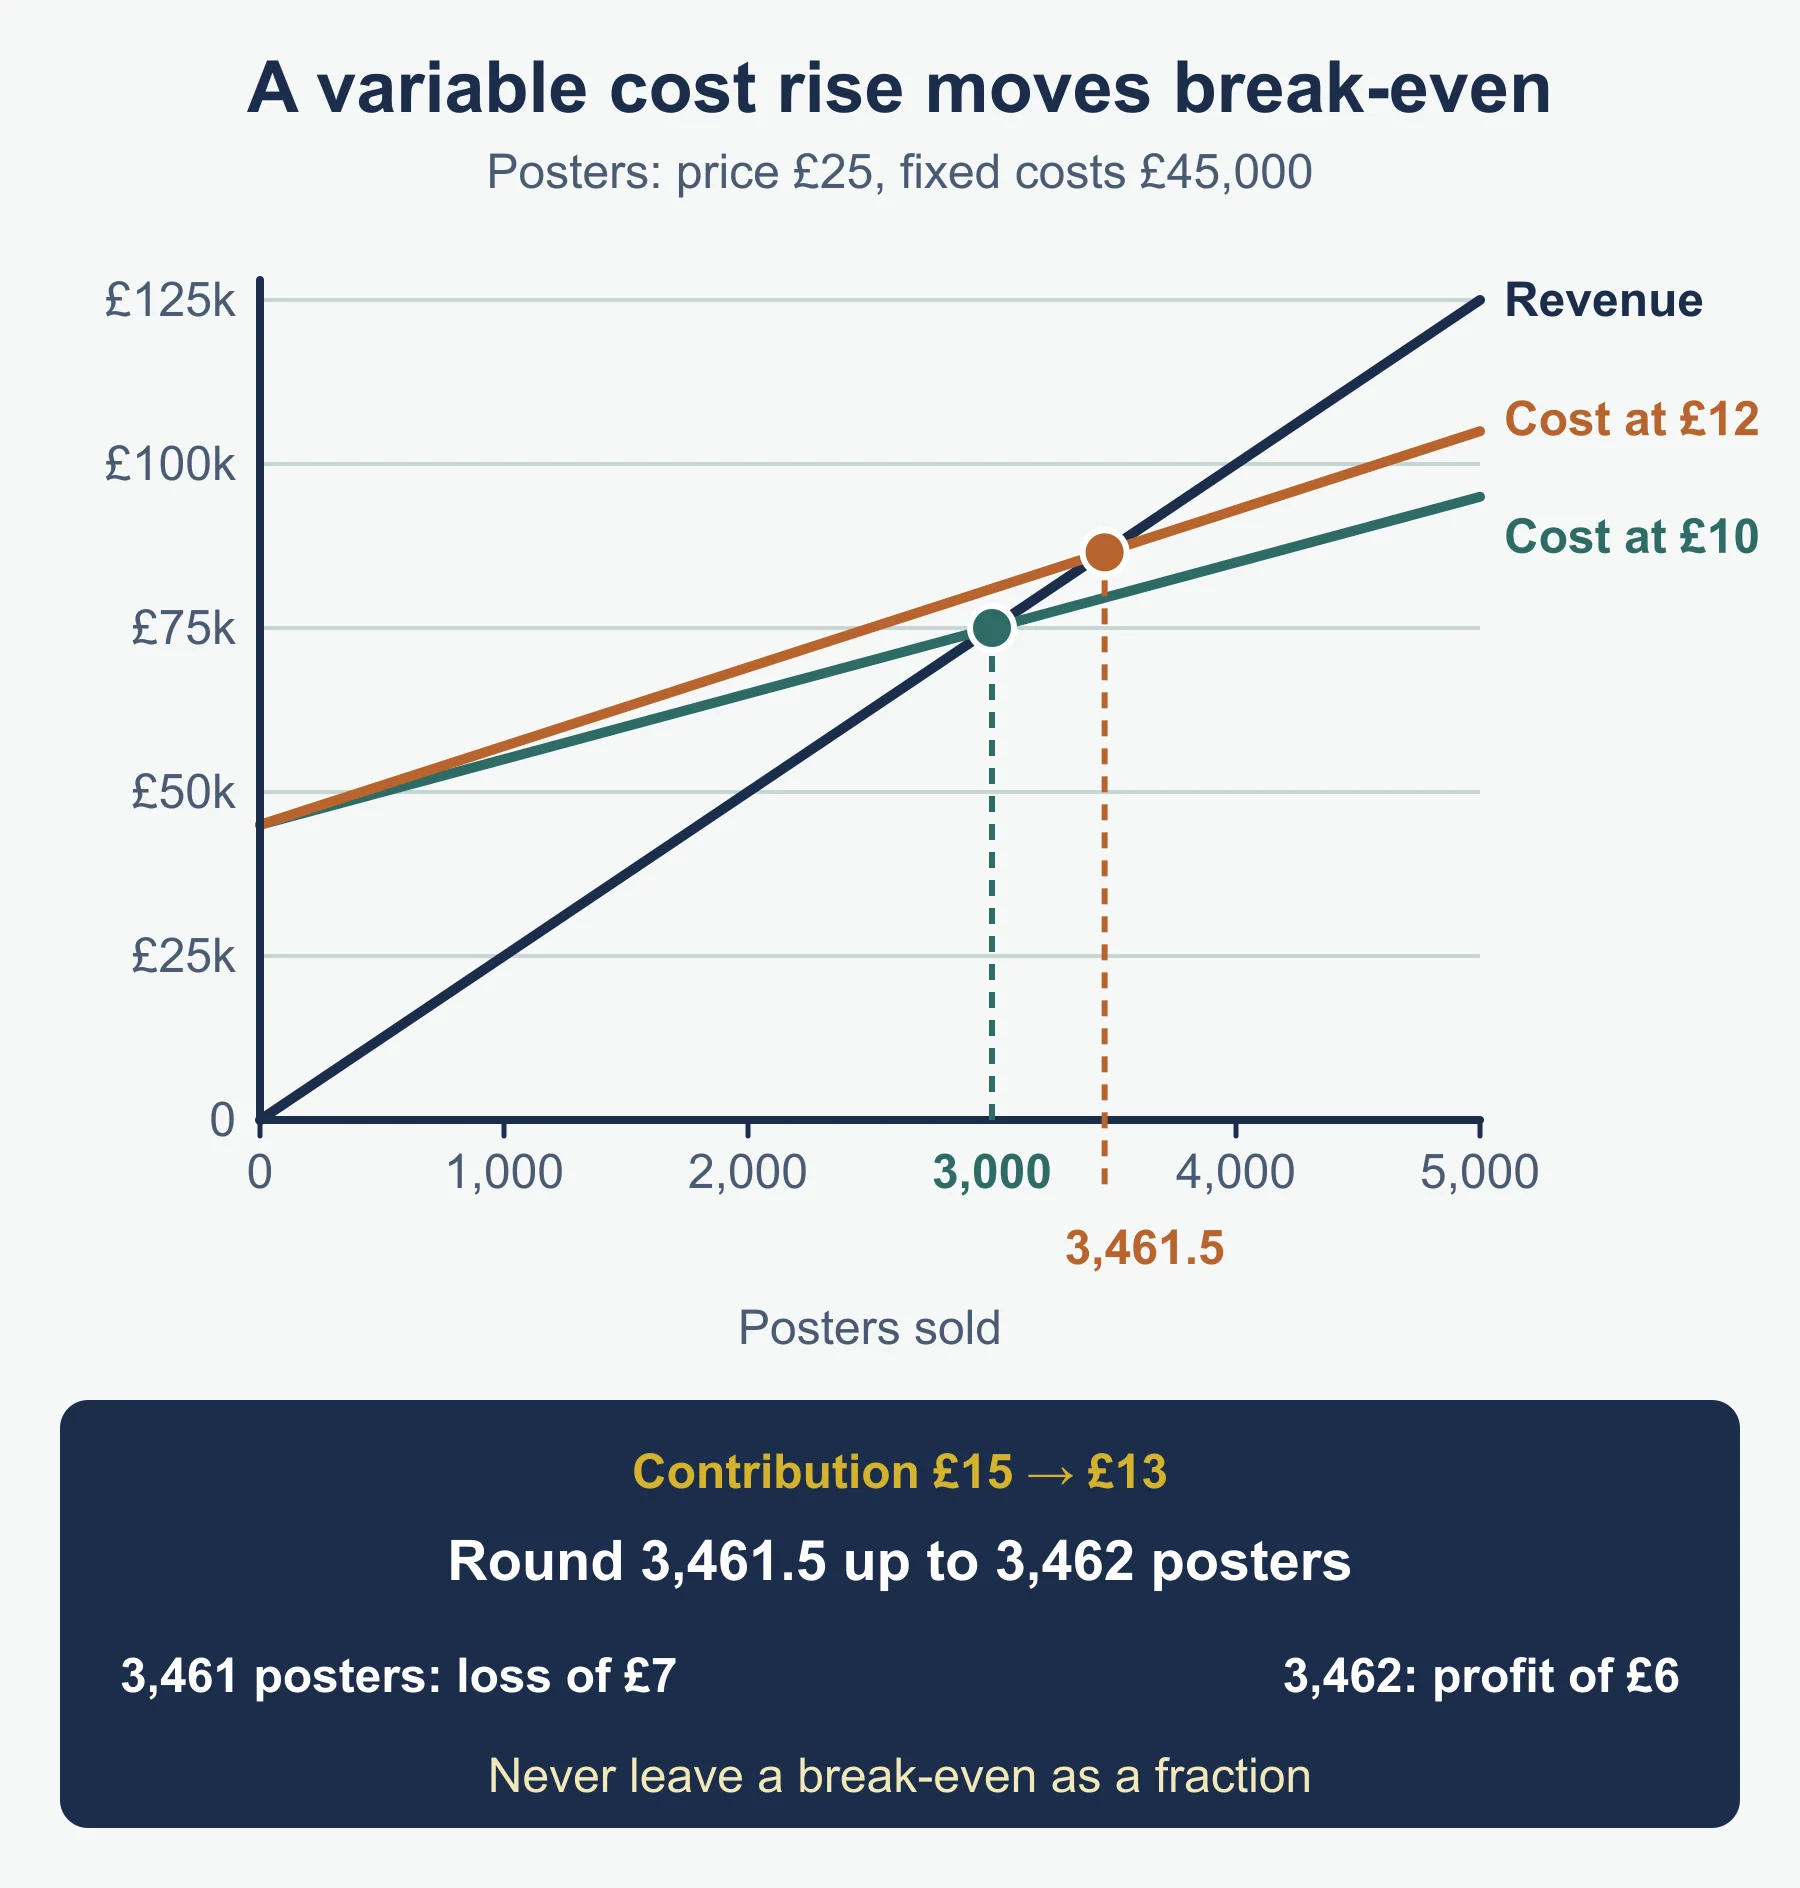
- Break-even output = fixed costs ÷ contribution per unit (round up).
- Margin of safety = planned output − break-even output.
- Total contribution = contribution per unit × output; profit = total contribution − fixed costs.
Worked reminder. Zelmore sells a product at £40 with variable cost £24 and fixed costs £56,000, planning 4,200 units.
- Contribution = £16.
- Break-even output = 56,000 ÷ 16 = 3,500 units.
- Margin of safety = 700 units (16.7% of planned output).
- Total contribution = £67,200; profit = £11,200.
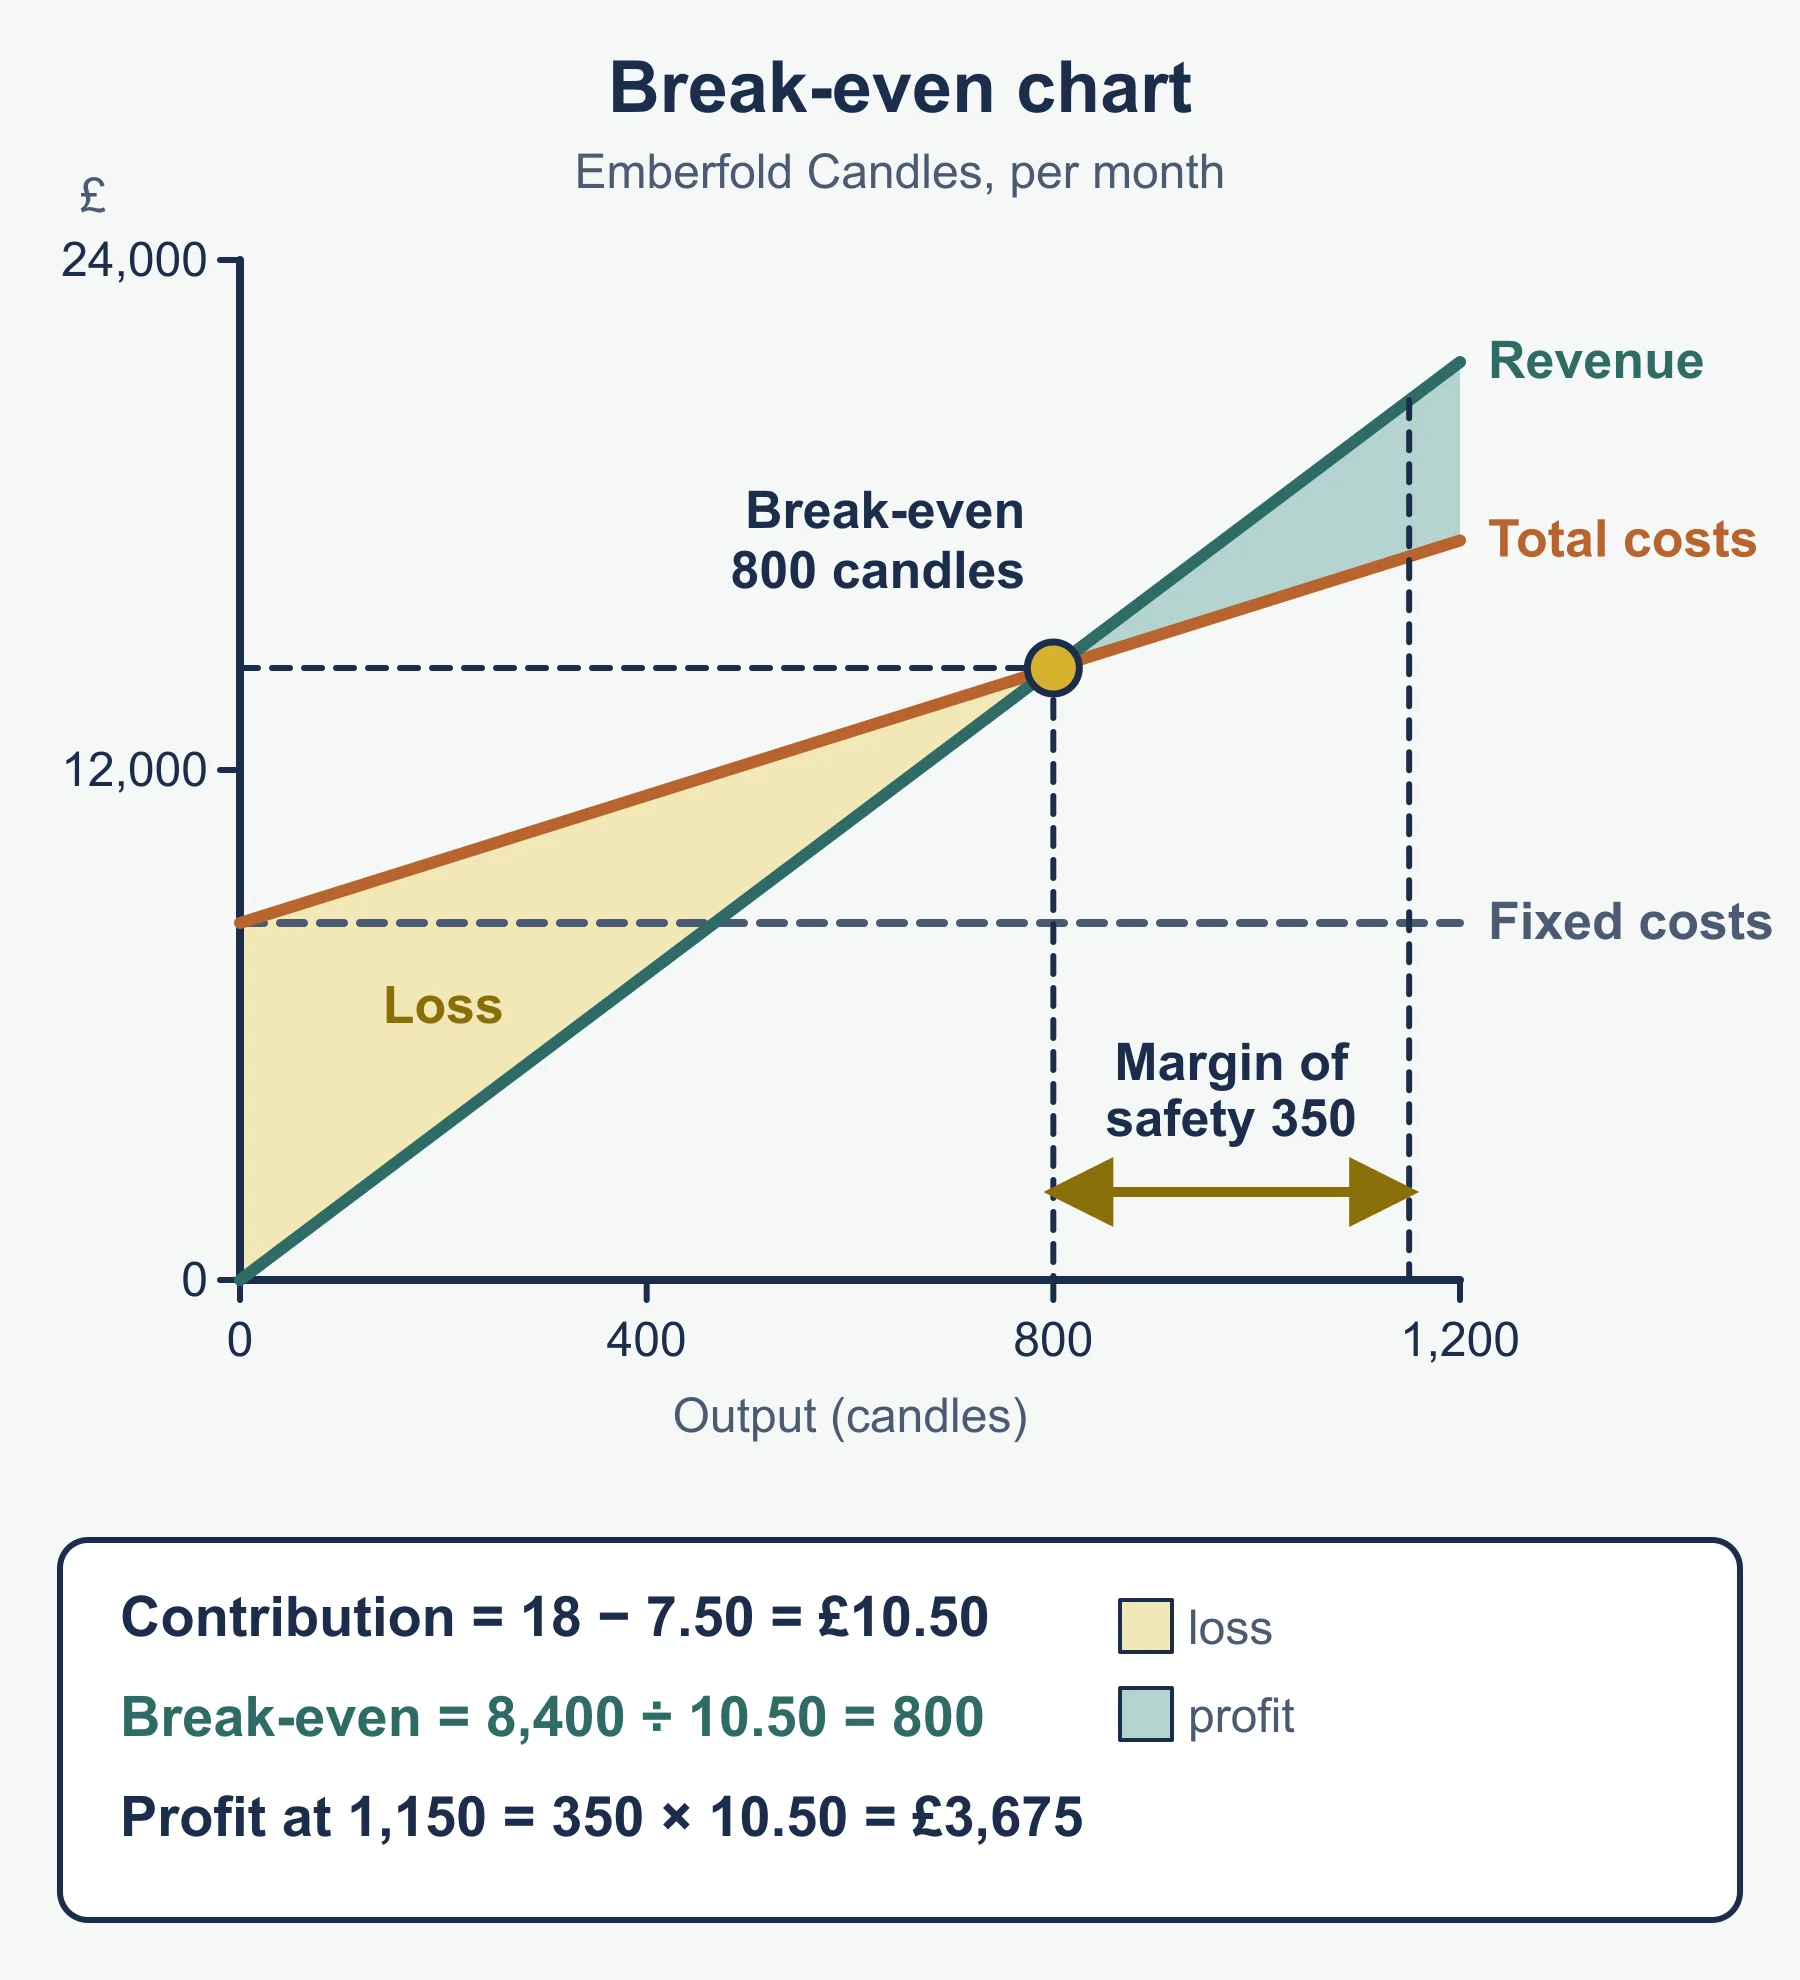
Chart reminders. Output on the horizontal axis, money on the vertical. Three lines: fixed costs (flat), total costs (from the fixed cost level upwards) and revenue (from the origin). Break-even is where revenue meets total costs.
| Change | Effect on break-even | Chart effect |
|---|---|---|
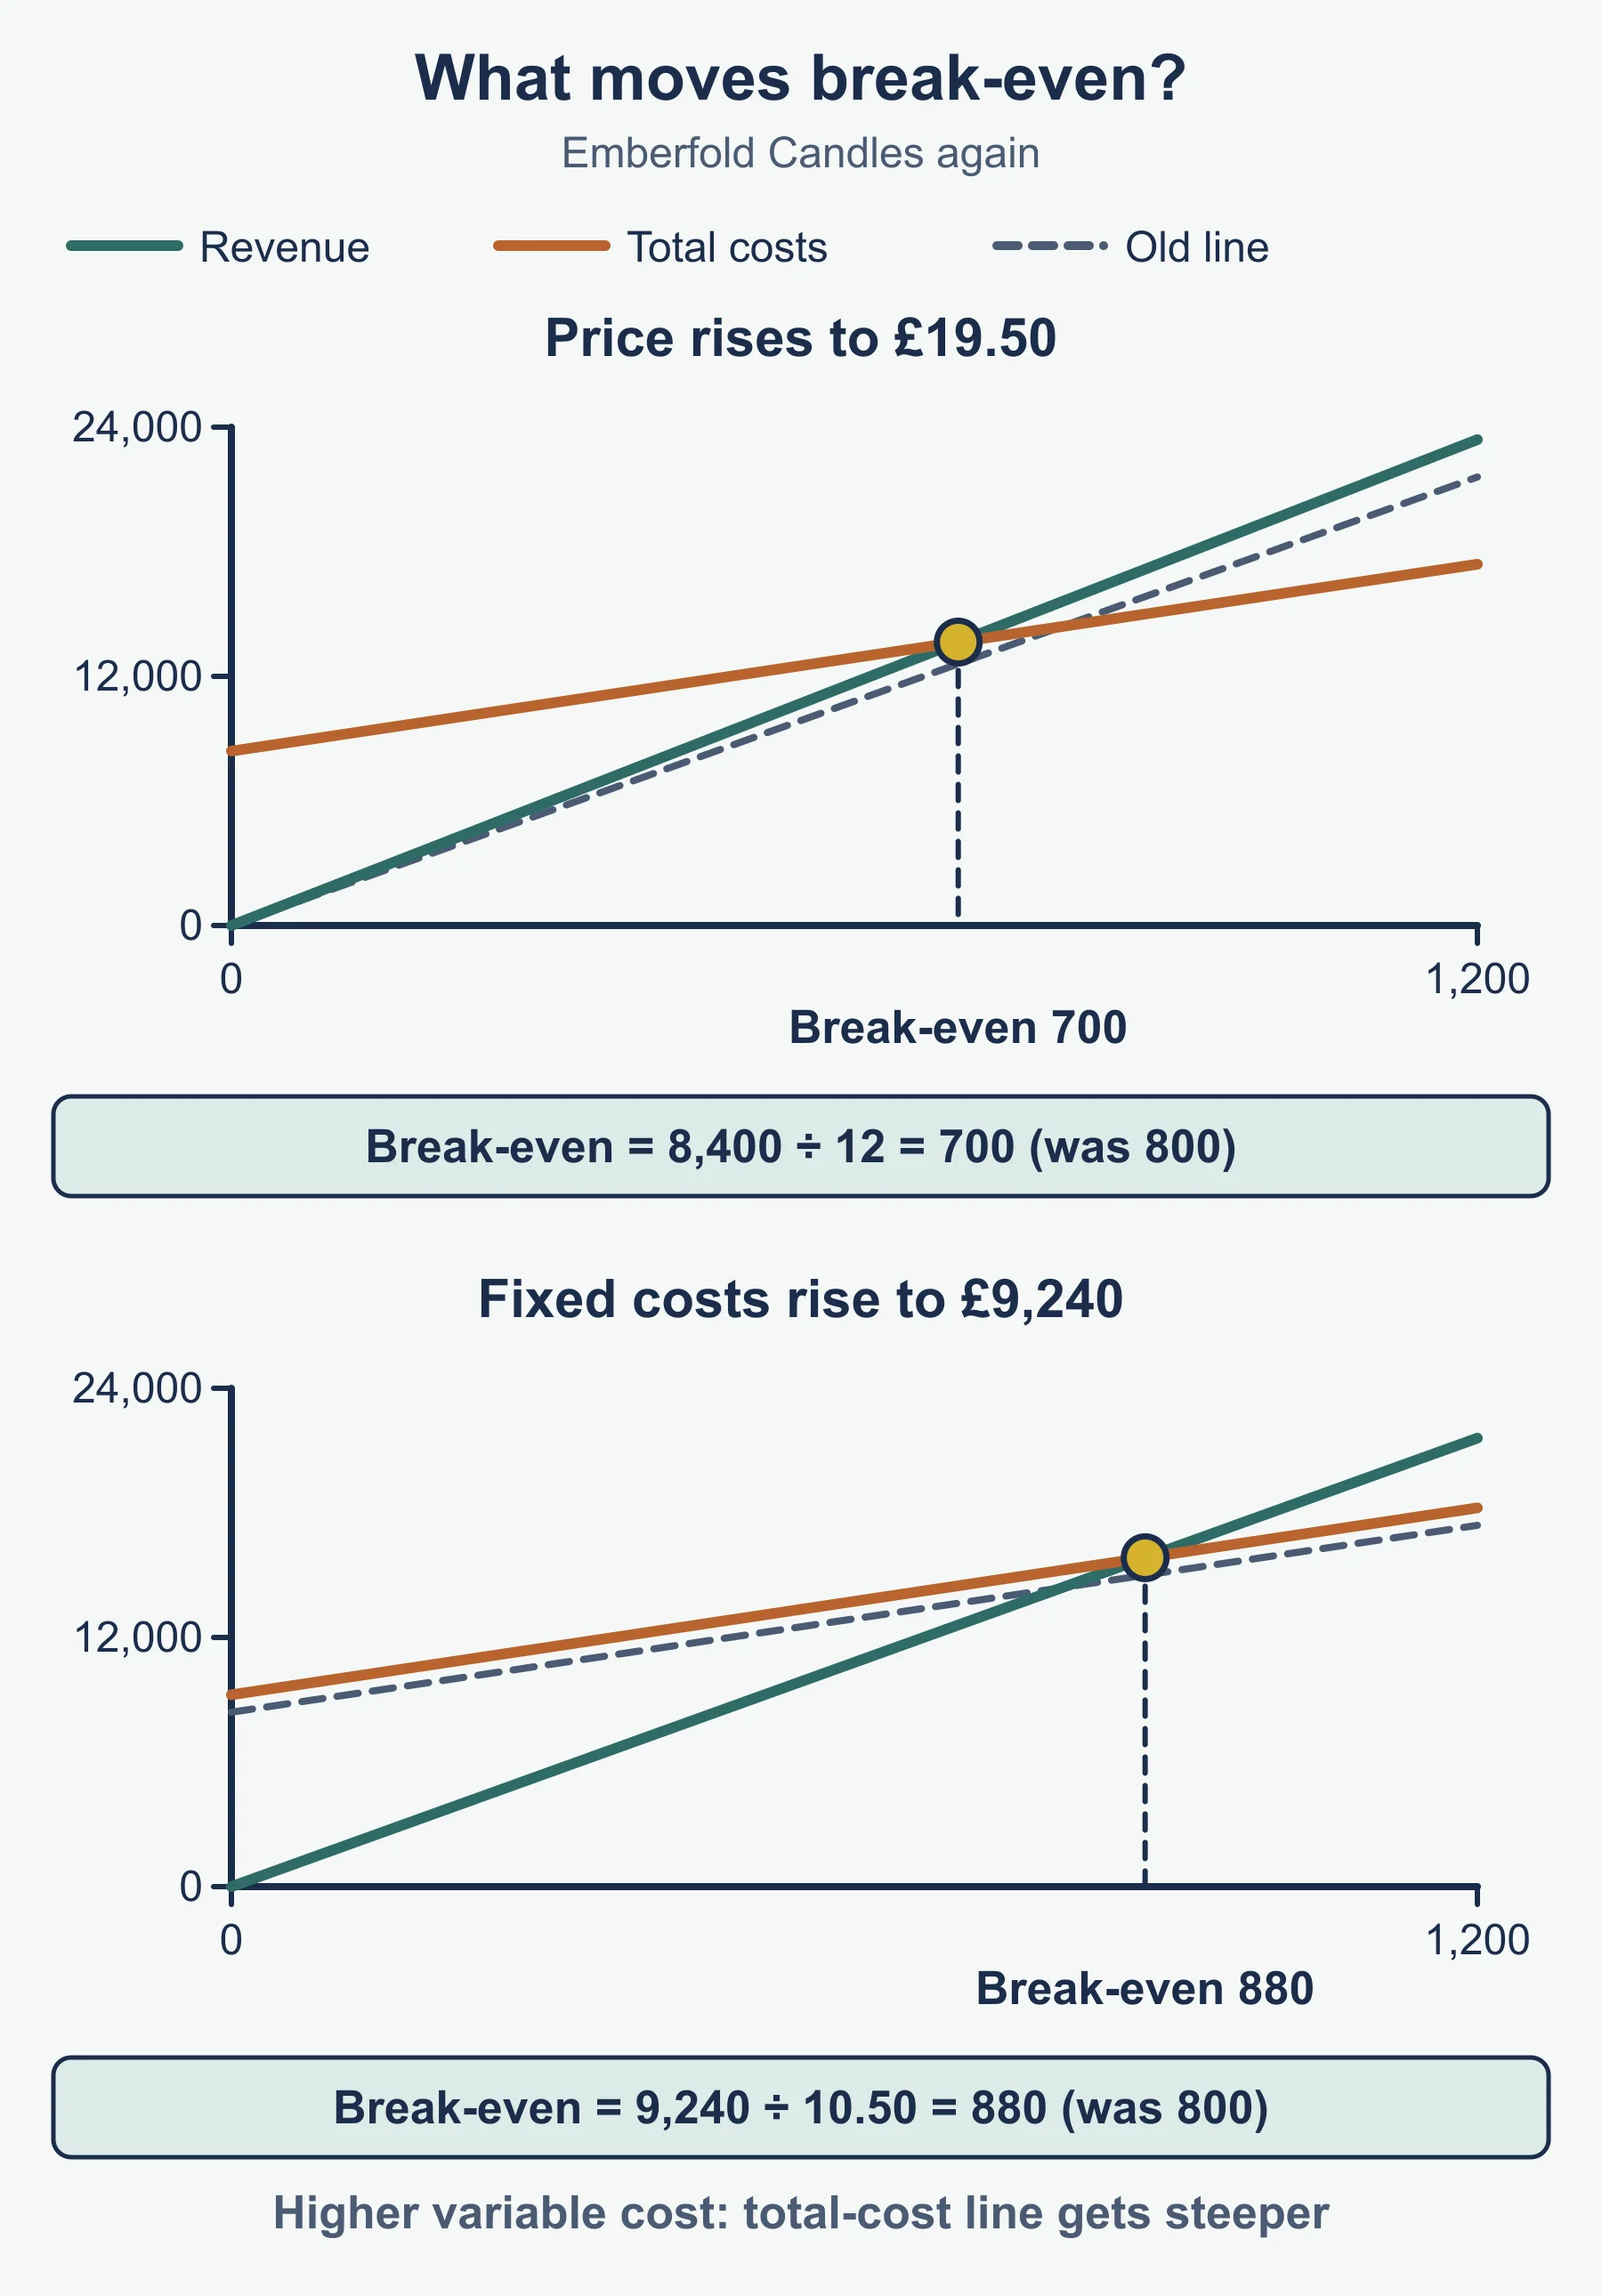
| Price rises | Falls | Revenue line steeper |
| Variable cost rises | Rises | Total cost line steeper |
| Fixed costs rise | Rises | Total cost line starts higher |
| Output rises | No change in break-even; margin of safety grows | Move along the lines |
Value of break-even: simple, supports pricing and risk judgements. Limits: assumes everything made is sold, a constant price, and straight-line costs.
Profit and financial reporting
- Profit is not cash, and profit is not profitability (profit relative to revenue or capital).
- Interpret and amend an income statement and a statement of financial position.
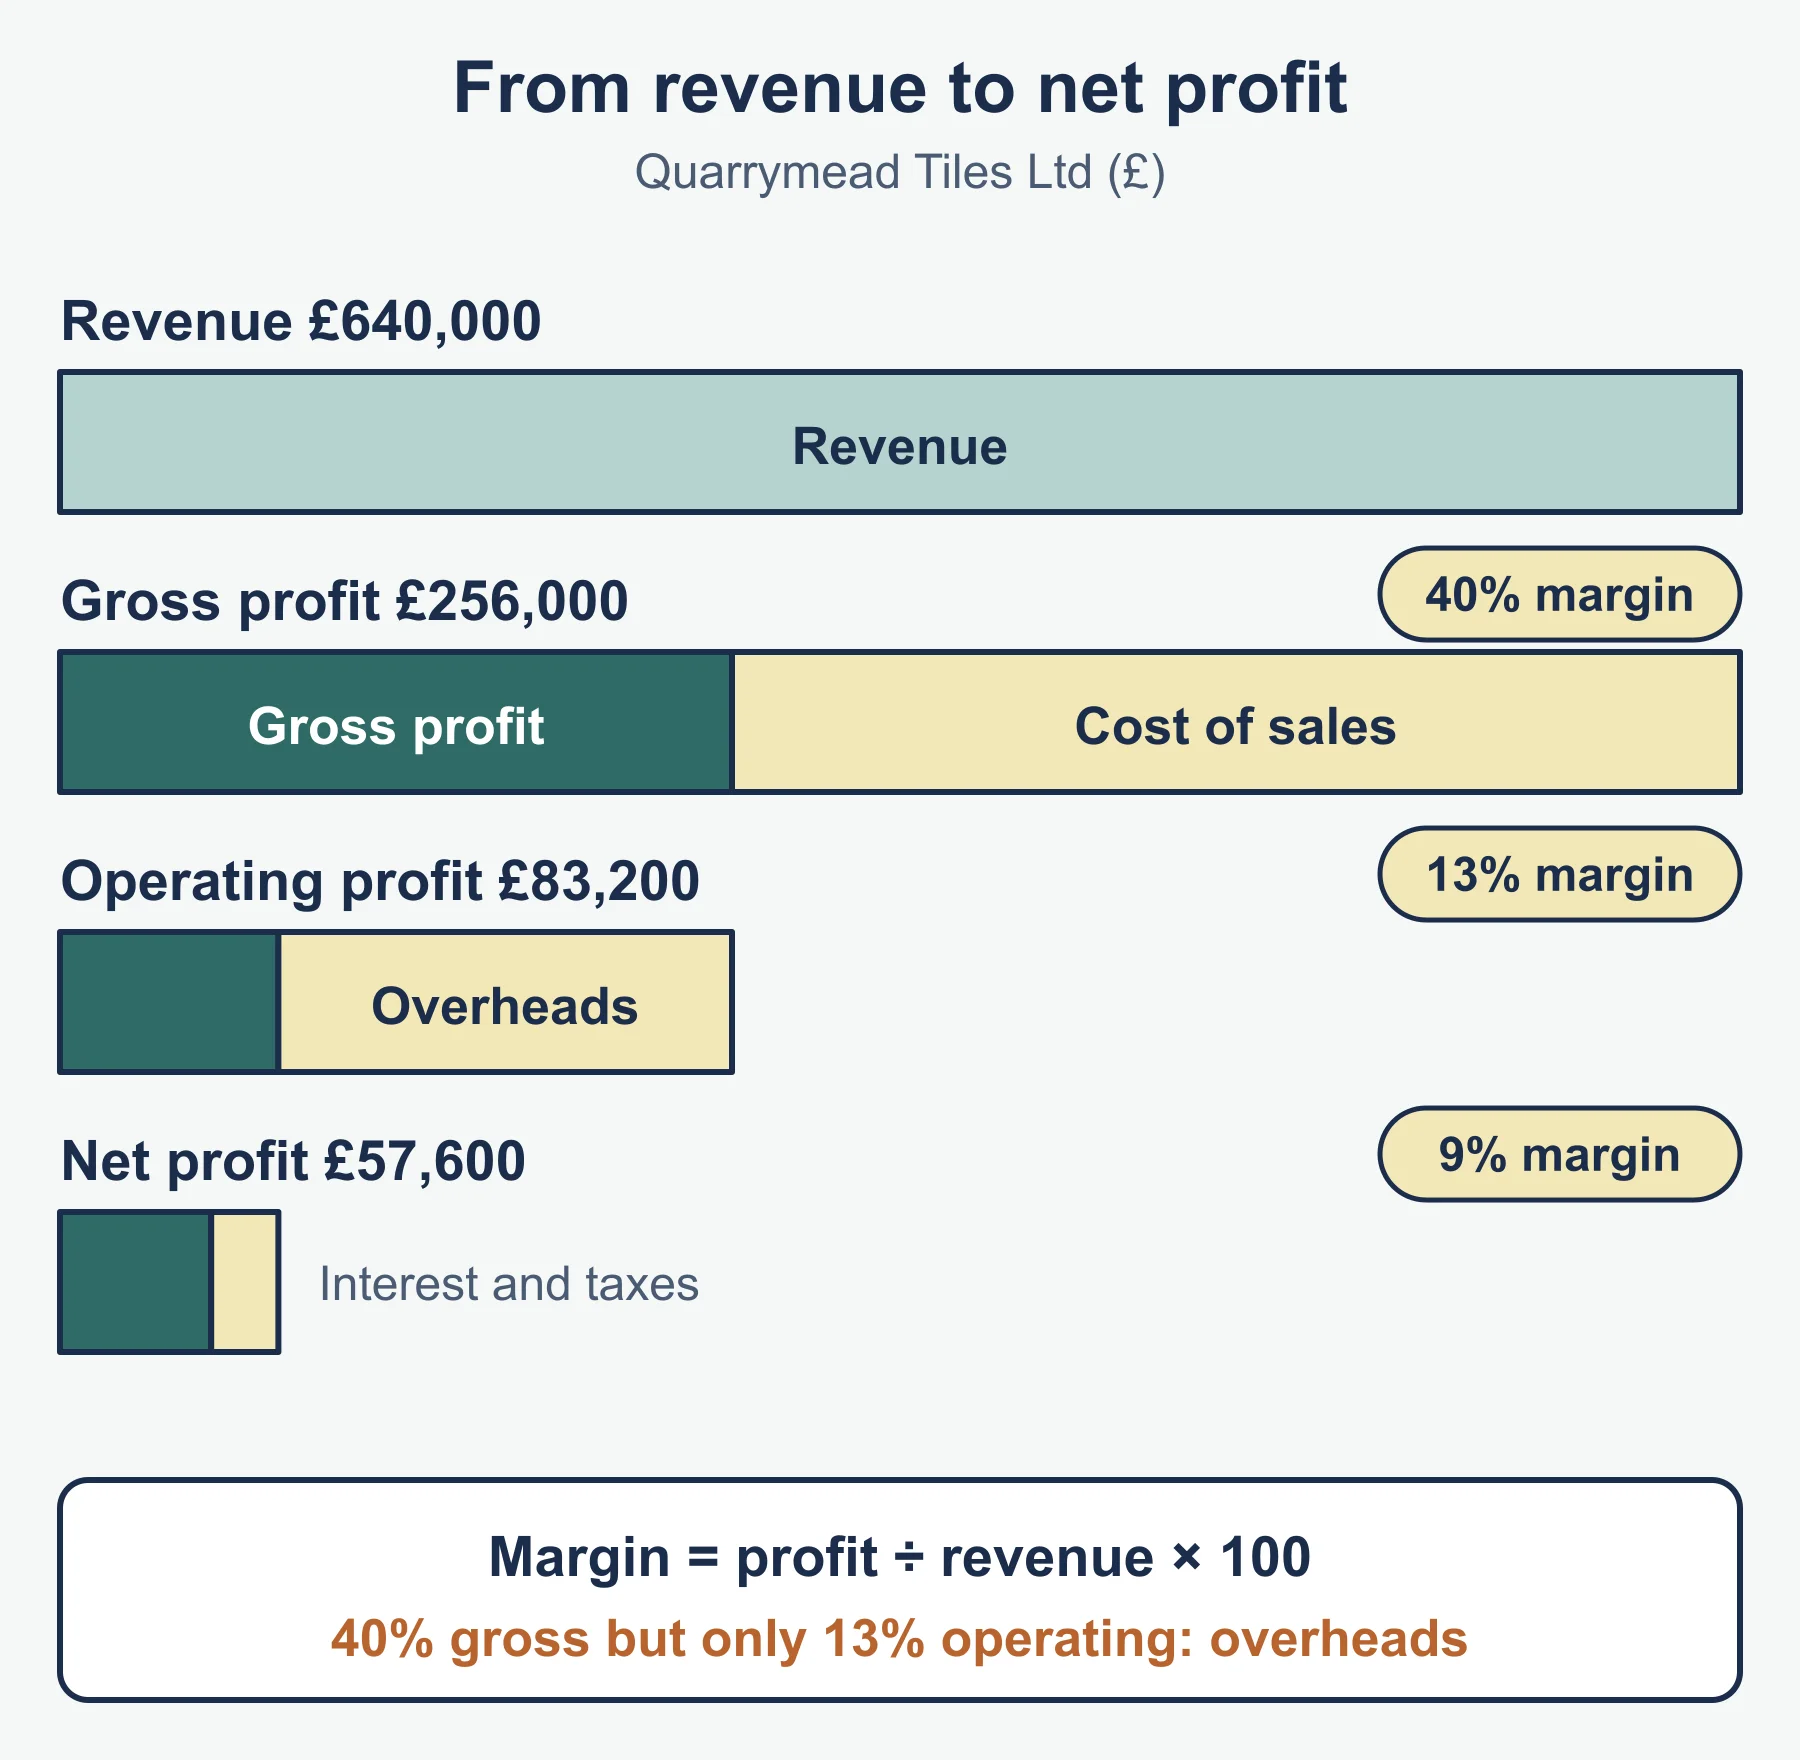
- Compare gross, operating and profit for the year margins, ROCE, ROI and gearing with earlier years (trends), with competitors (benchmarking) and with objectives; use index numbers and percentage changes.
- A fall in gross margin points to higher cost of sales or lower prices; a fall in operating margin with a steady gross margin points to rising operating expenses; a gap between operating margin and profit-for-the-year margin points to finance costs and tax.
- Example: Zelmore has revenue £90,000, cost of sales £54,000 and operating expenses £25,200. Gross profit £36,000 (40%); operating profit £10,800 (12%). With capital employed of £320,000 (above), ROCE = 10,800 ÷ 320,000 × 100 = 3.4%.
- Limitations of financial reporting: historic figures; leaves out morale, brand reputation and environmental impact.
Cash flow and liquidity
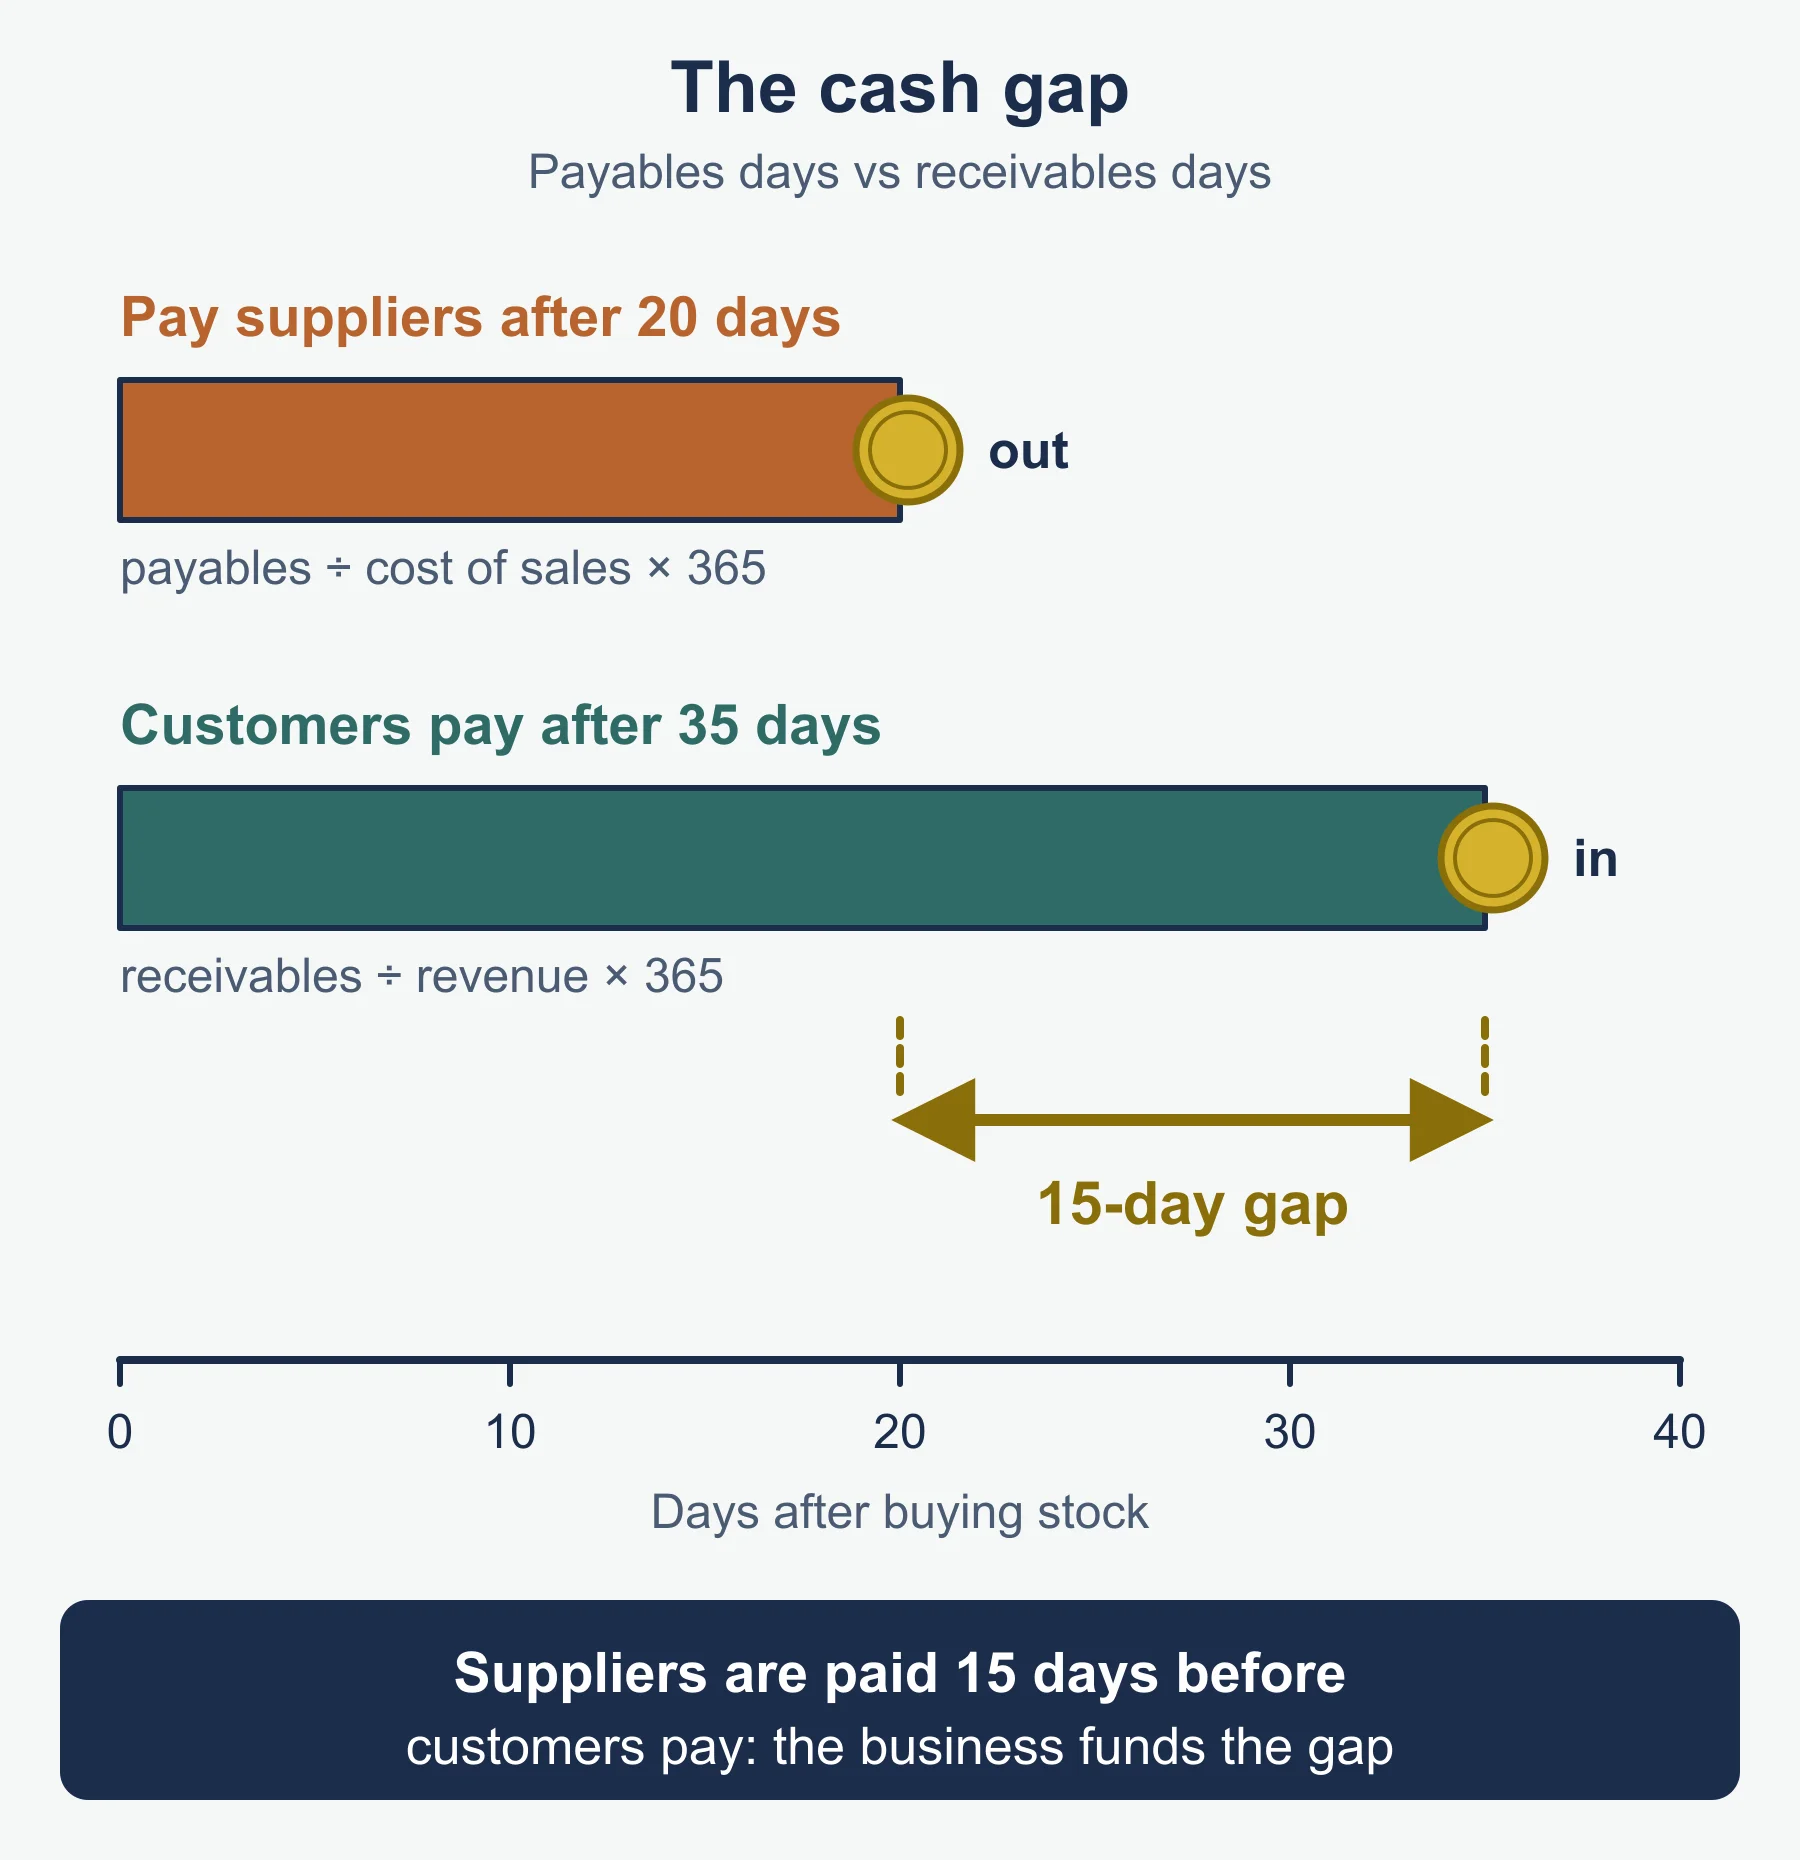
- Cash trouble arises when payables are paid before receivables arrive.
- Liquidity ratios: current ratio, acid test ratio, payables days, receivables days (formulas above).
- Example: current assets £60,000 including inventory £18,000; current liabilities £30,000. Current ratio = 2.0; acid test = 42,000 ÷ 30,000 = 1.4.
Sources of finance
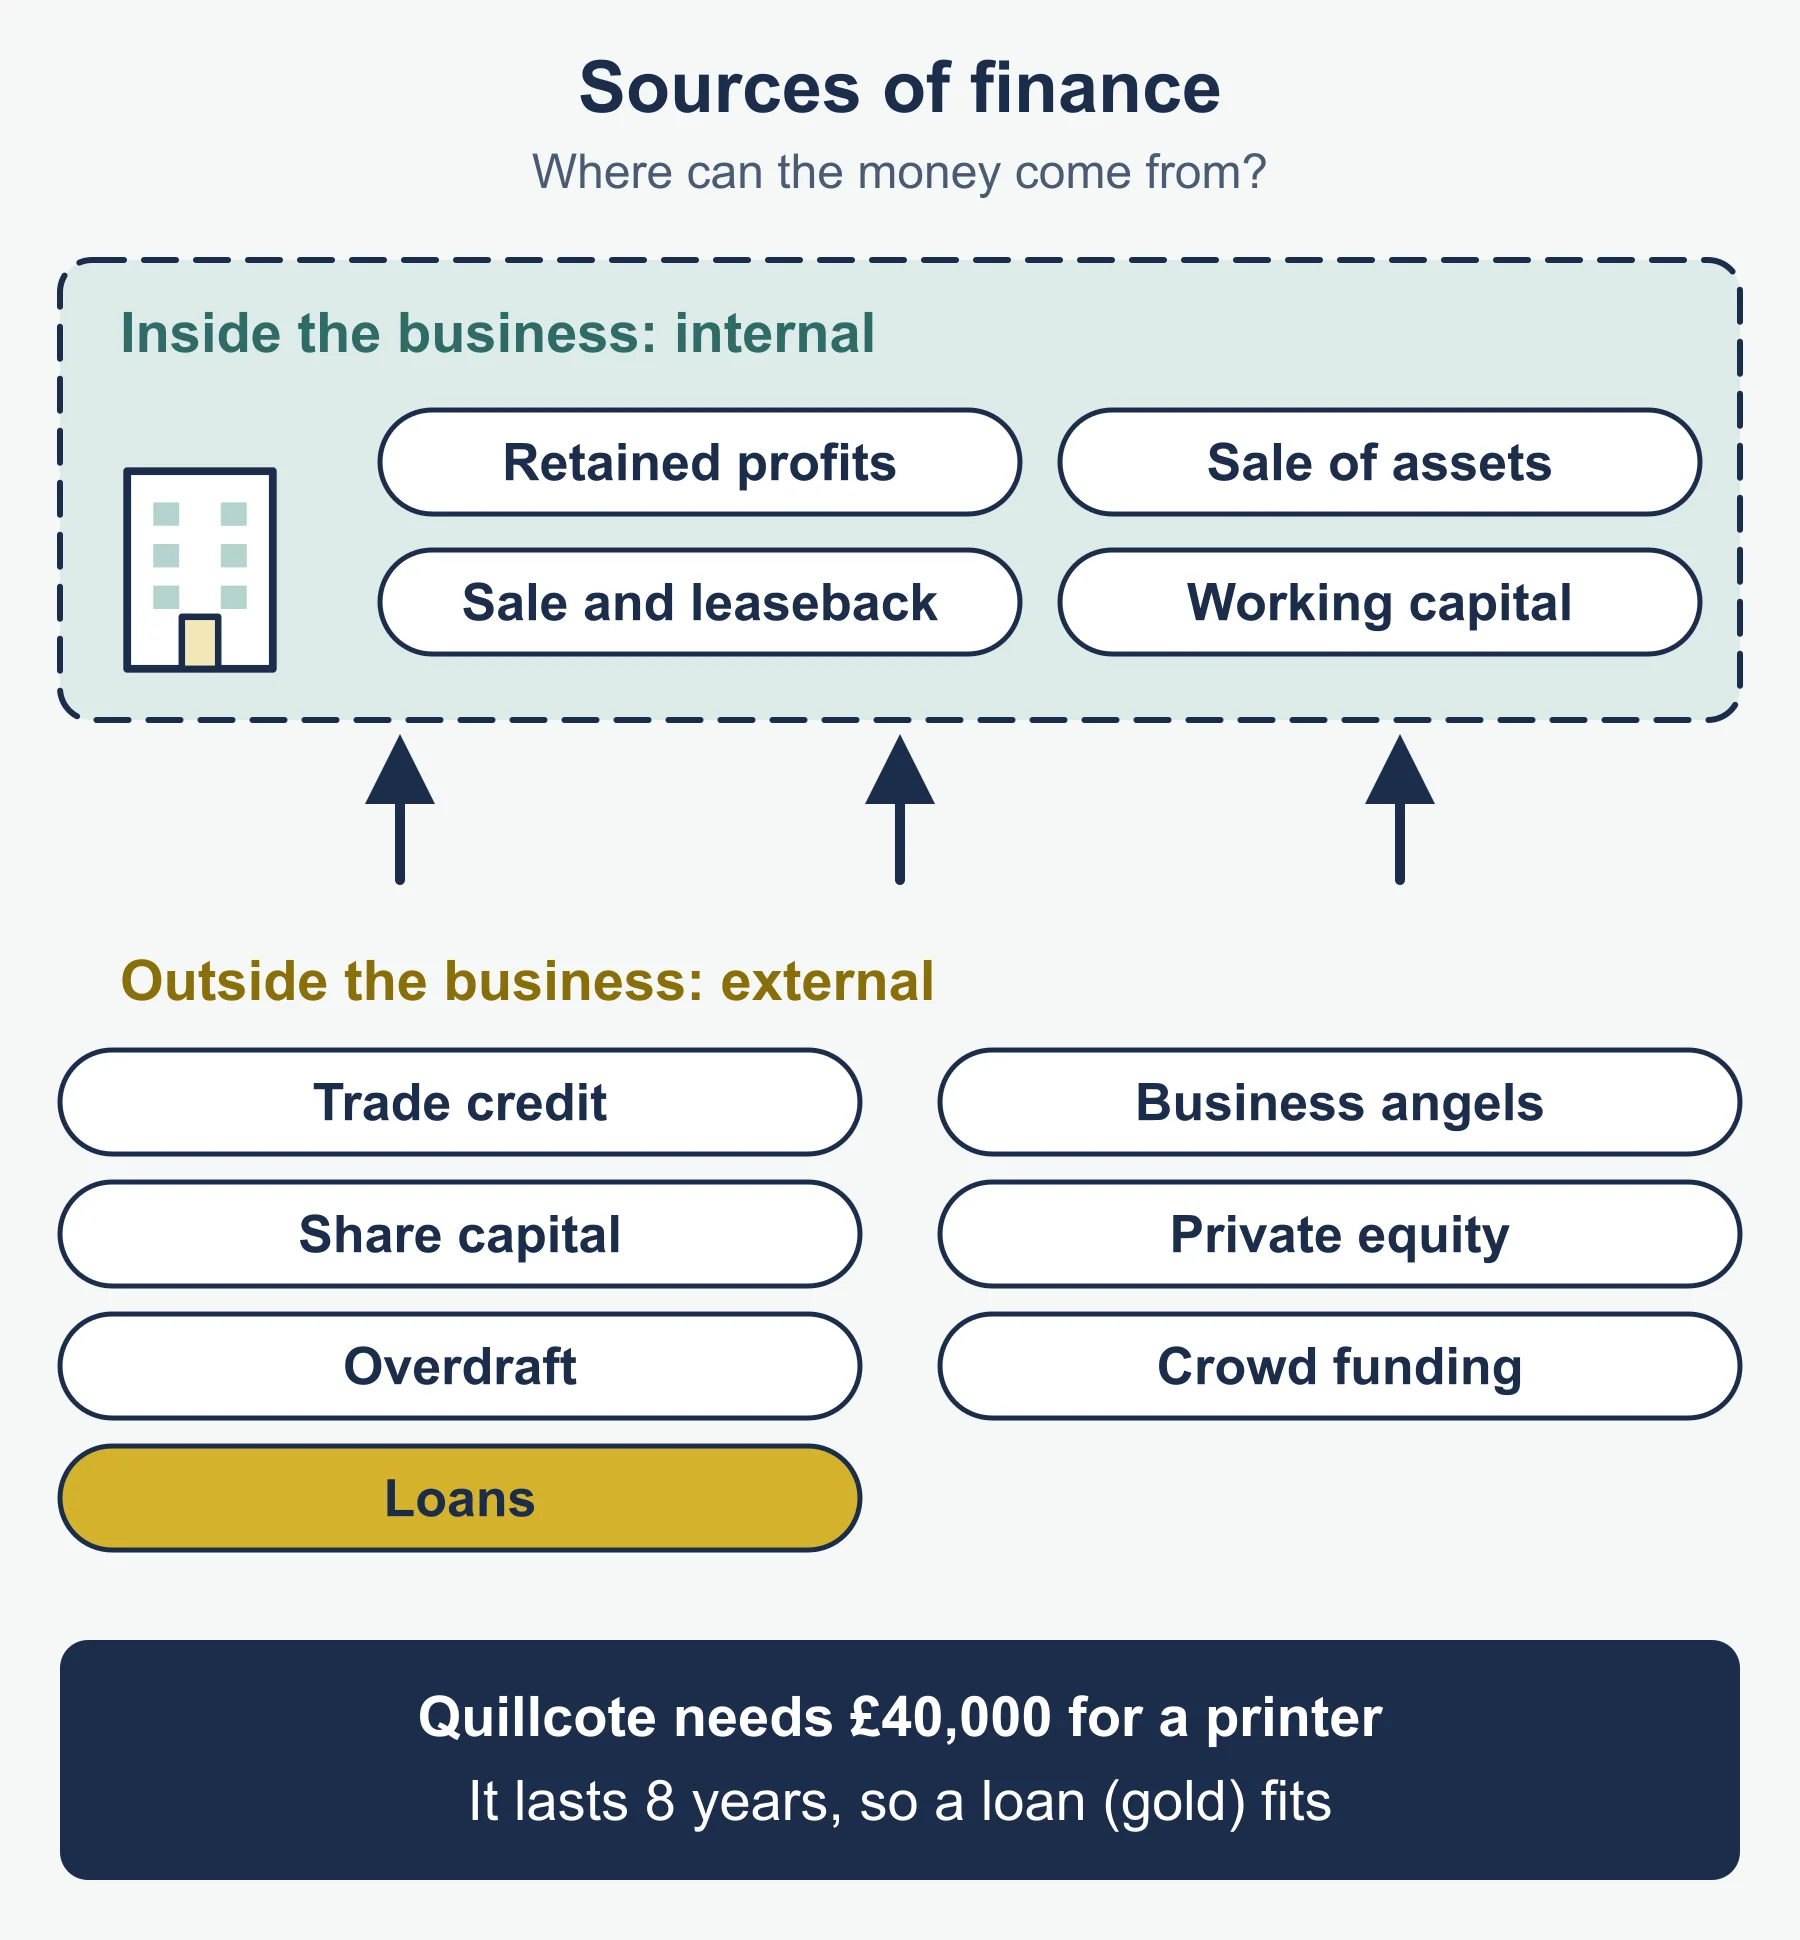
| Source | Internal or external | Best for | Main drawback |
|---|---|---|---|
| Owners’ investment | Internal | Start-ups and small firms | Limited by owners’ wealth |
| Retained profits | Internal | Growth without outside help | Limited by profits earned |
| Sale of assets | Internal | Raising cash from unused assets | Asset is lost; forced sales fetch less |
| Sale and leaseback | Internal | Releasing cash from assets still needed | Lease payments; asset no longer owned |
| Working capital | Internal | Freeing cash from inventory and receivables | Too little leaves orders or bills unmet |
| Trade credit | External | Paying for supplies later | Strains supplier relations if abused |
| Share capital | External | Long-term funds with no repayment | Dilutes ownership |
| Overdraft | External | Short-term gaps | Costly if used for long; can be withdrawn |
| Loans | External | Medium and long-term assets | Interest and repayment commitment |
| Business angels | External | Small, growing firms needing money and advice | Angel takes a share of ownership |
| Private equity | External | Large sums for growth or buy-outs | Investors want high returns and control |
| Crowd funding | External | Raising many small sums online | Fees, effort, and the target may be missed |
Improving cash flow and profit
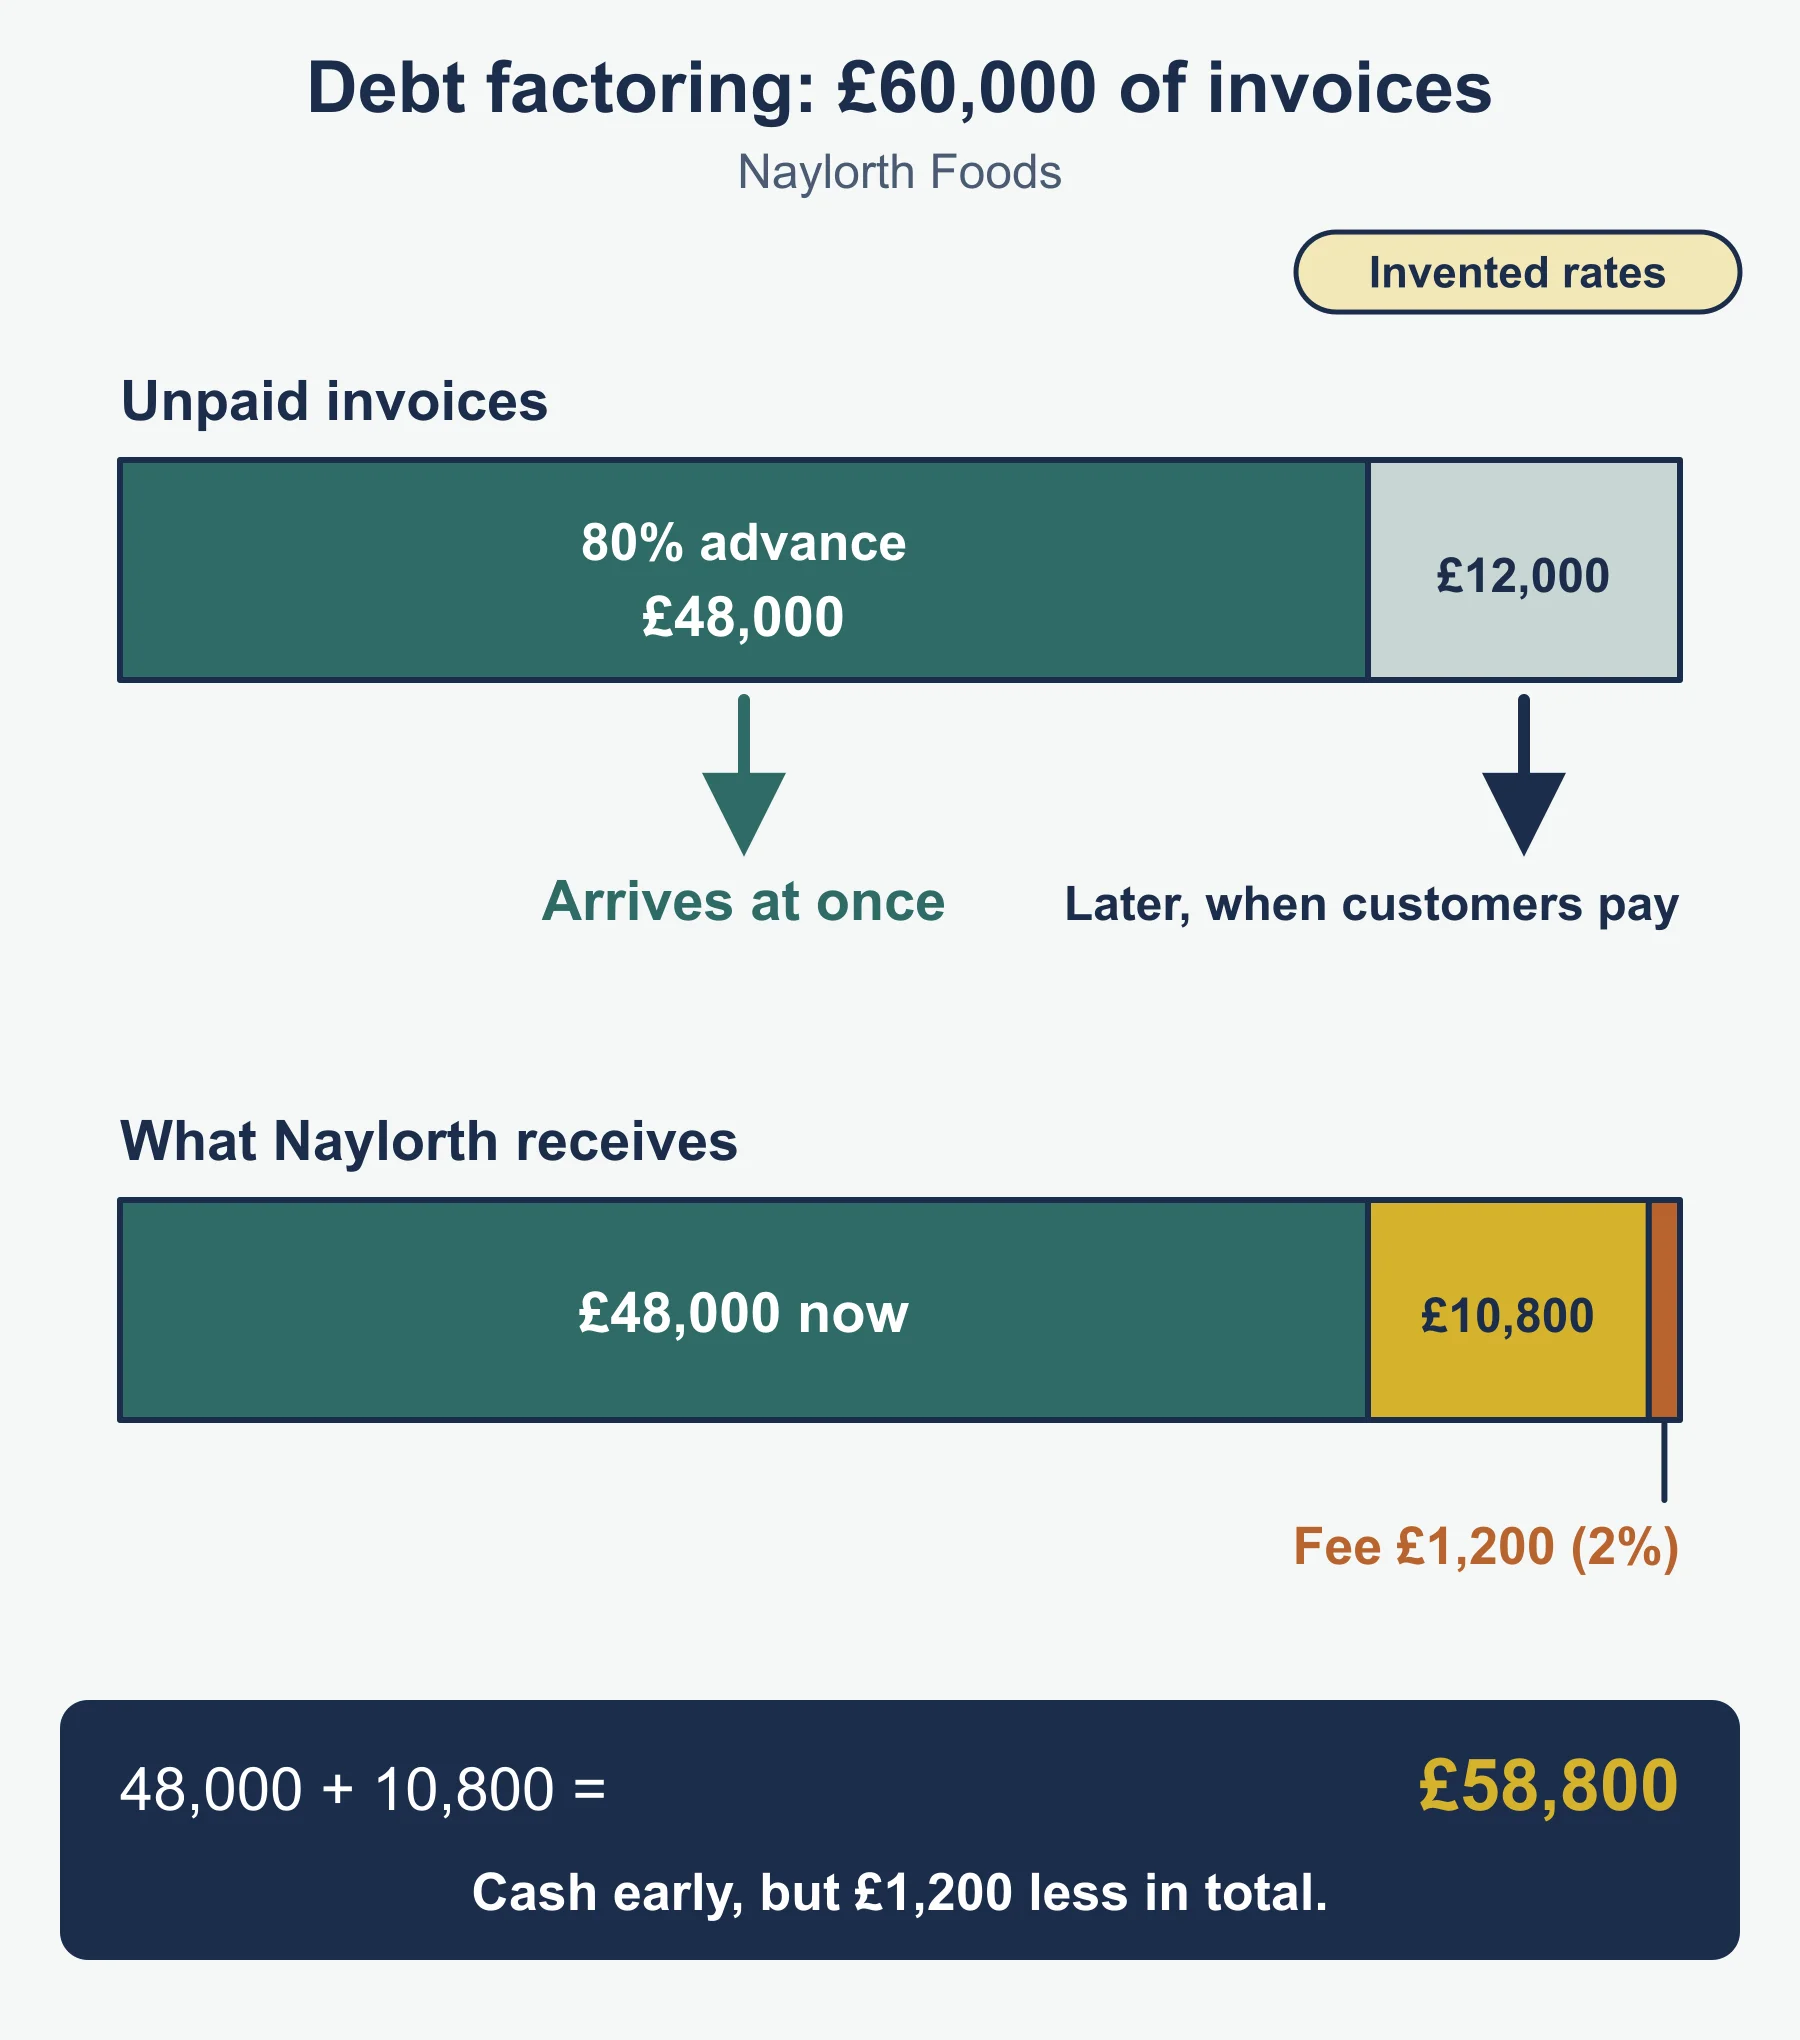
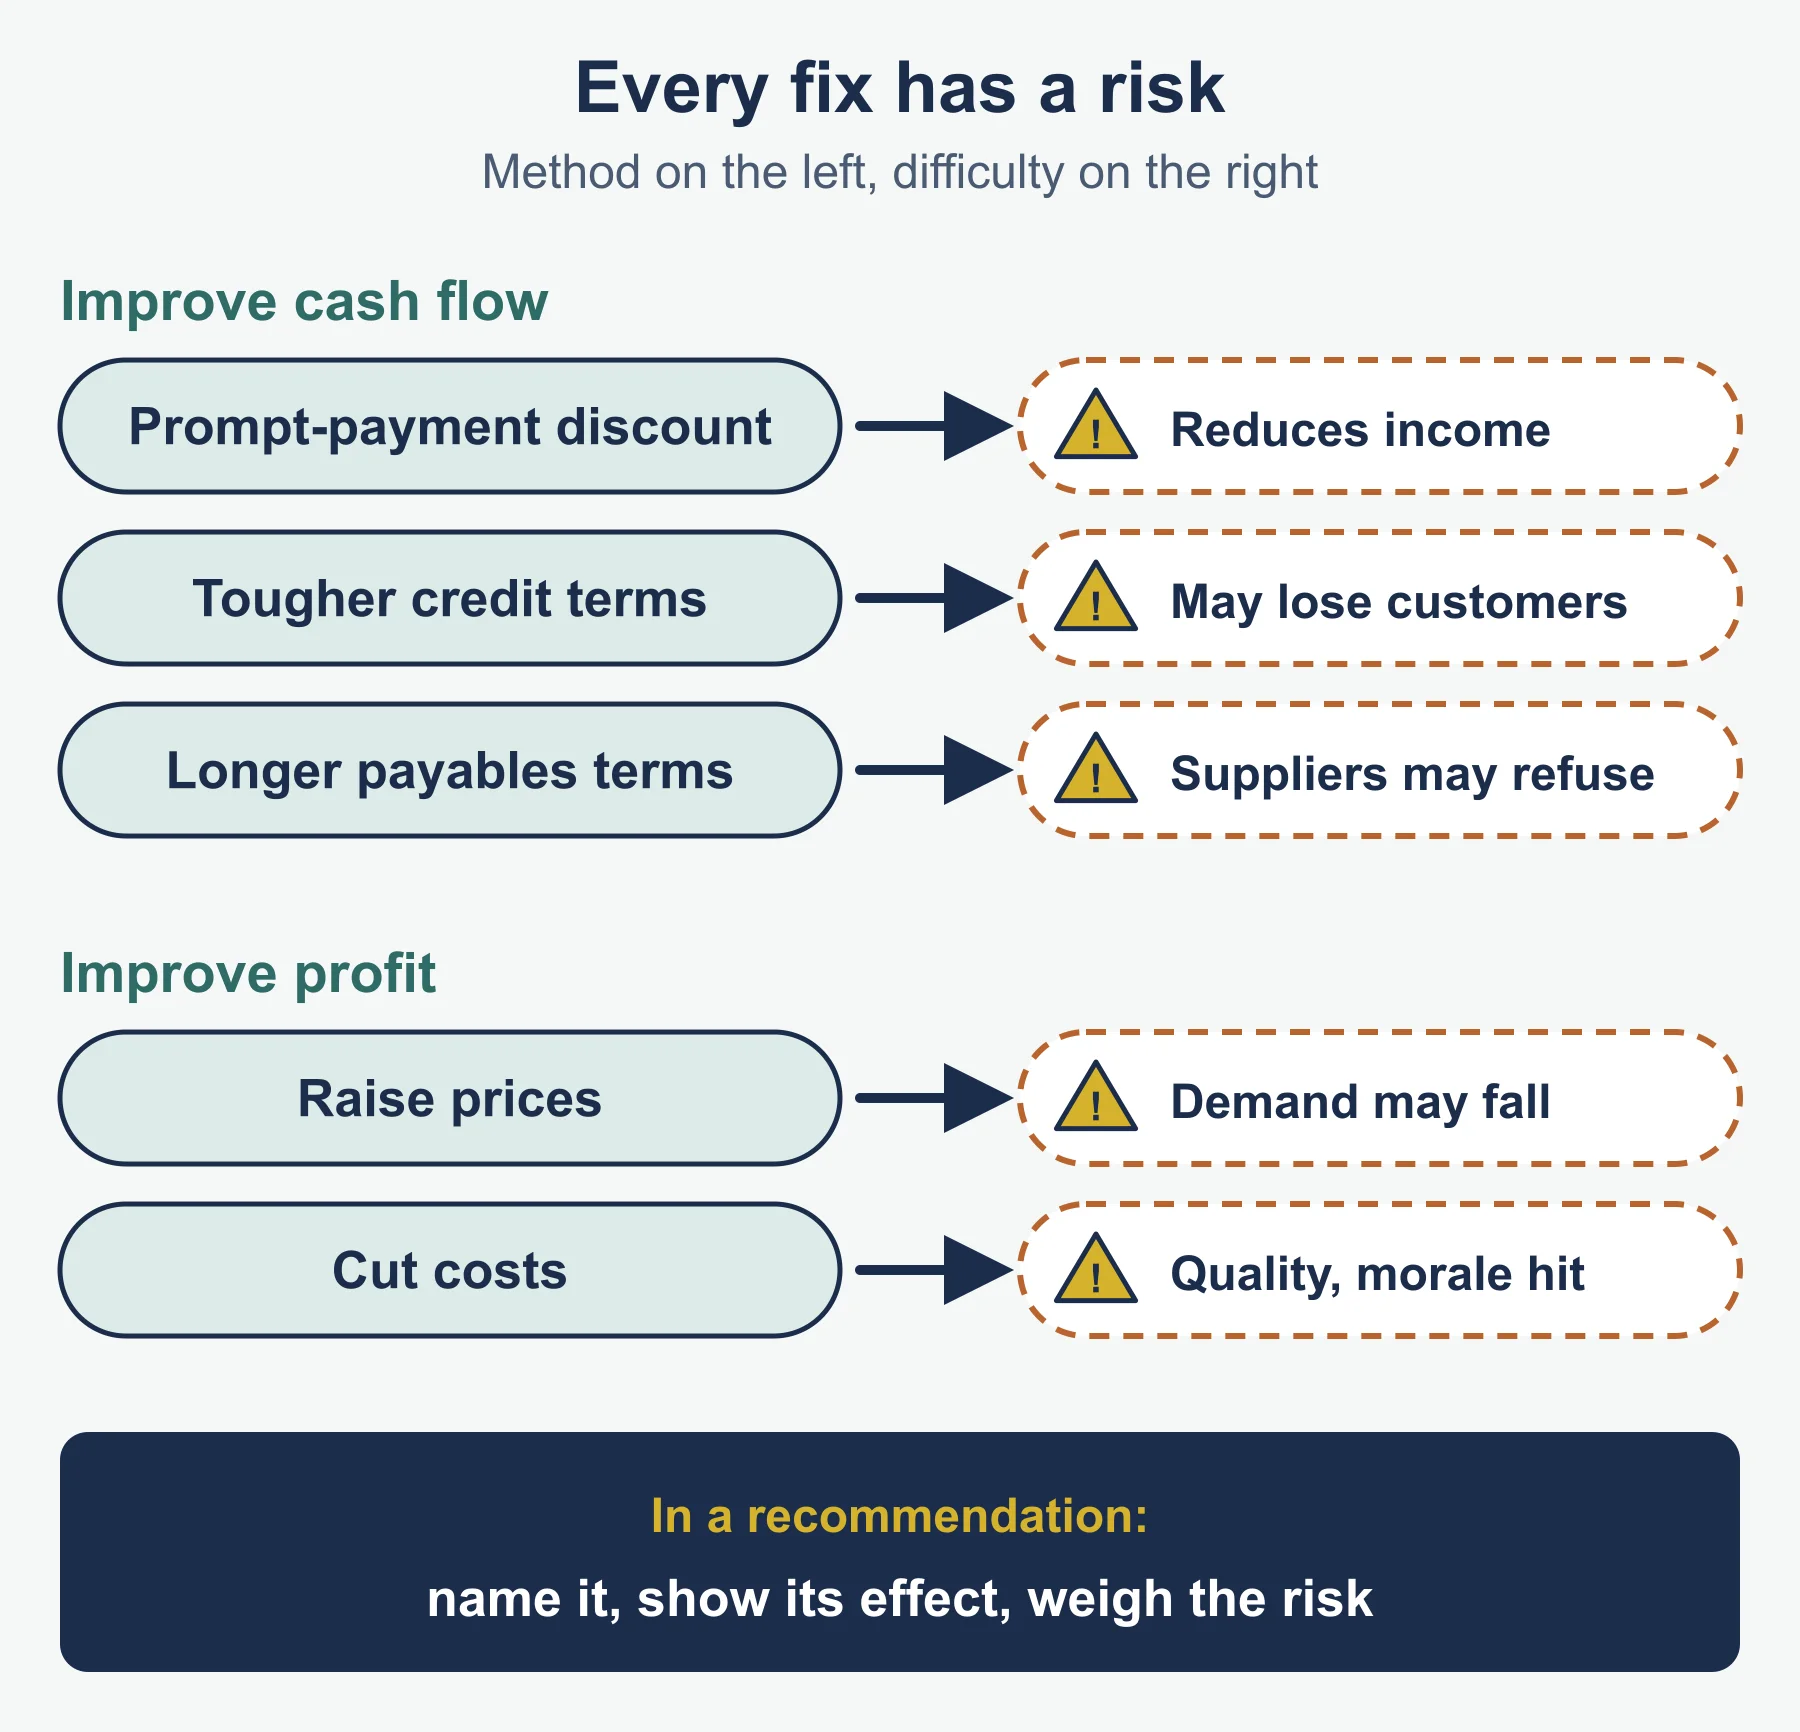
- Cash flow (the specification’s list): debt factoring, shortening payment time from customers, early payment incentives, credit checks, increasing payment time to suppliers, reducing outgoings, better invoice management.
- Gross and operating profit: increase revenue and/or decrease costs.
- Difficulties: factoring costs a fee, discounts reduce income, tough terms may lose customers, suppliers may refuse longer terms, price rises may cut demand, and cost cuts can lower quality.
- A recommendation needs a figure, a reason and a risk.
Assessing financial position and performance
Judge profits and margins, ROCE, ROI, cash flow and liquidity, gearing, shareholder rewards (dividend per share and dividend yield), break-even output, margin of safety and budget variances relative to objectives, competitors, business plans and the context of the business. Use data from the case and say how reliable it is.
Quick self-test
- State the formula for contribution per unit.
- A product sells for £40, has variable cost £24 and fixed costs are £56,000. Find break-even output.
- Planned output is 4,200 units. Find the margin of safety as a percentage of planned output, to one decimal place.
- Fixed costs in question 2 rise by 10%. Find the new break-even output.
- The price in question 2 rises to £44, with other figures unchanged. Find the new break-even output.
- A cost budget is £18,000 and actual spending is £16,200. State the variance and whether it is favourable or adverse.
- A business has revenue £90,000 and cost of sales £54,000. Find the gross profit margin.
- Opening cash £4,000, cash in £12,500, cash out £15,800. Find the closing balance.
- Non-current liabilities are £80,000 and total equity is £240,000. Find gearing.
- Give one internal source of finance and one external source.
- State one difference between cash flow and profit.
- Define receivables.
Answers
- Selling price − variable cost per unit.
- Contribution £16; 56,000 ÷ 16 = 3,500 units.
- Margin of safety 700; 700 ÷ 4,200 × 100 = 16.7%.
- Fixed costs £61,600; 61,600 ÷ 16 = 3,850 units.
- Contribution £20; 56,000 ÷ 20 = 2,800 units.
- 18,000 − 16,200 = £1,800 favourable (spending was below budget).
- Gross profit £36,000; 36,000 ÷ 90,000 × 100 = 40%.
- 4,000 + 12,500 − 15,800 = £700.
- 80,000 ÷ 320,000 × 100 = 25%.
- Internal: any of owners’ investment, retained profits, sale of assets, sale and leaseback or working capital. External: any of trade credit, share capital, overdraft, loans, business angels, private equity or crowd funding.
- Profit counts revenue earned whether or not cash has been received; cash flow records only money actually moving.
- Customers who owe the business money for goods or services supplied on credit.
Where marks are usually lost
- Calling a variance adverse or favourable by its sign rather than its effect on profit.
- Using total variable costs instead of variable cost per unit in the contribution formula.
- Giving break-even output with decimals (for example 3,461.5 units) instead of whole units.
- Confusing margin of safety with break-even output.
- Writing “profit” when the question asks about cash flow, or the other way round.
- Listing benefits of a source of finance without matching it to the business’s need and time horizon.
- Making recommendations without a figure from the case.
- “Evaluate” answers that end without a judgement.
Frequently asked questions
What are the five financial objectives in AQA AS Business 7137? Profit, profitability, cash flow, liquidity and levels of borrowing.
How do you calculate the current ratio and acid test ratio? Current ratio = current assets ÷ current liabilities. Acid test ratio = (current assets − inventory) ÷ current liabilities.
What is the difference between profit and profitability? Profit is an amount in pounds, while profitability measures profit relative to revenue or capital, for example as a margin or ROCE.
What are the limitations of financial reporting? Financial statements use historic figures and leave out factors such as staff morale, brand reputation and environmental impact.
Official syllabus
AQA AS and A-level Business (7137, 7138) specification, Version 1.1 (November 2025), for first teaching from September 2026: section 3.1.4 Financial management and Annex 7, Formulae and key data. Checked against these notes on 5 November 2026.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
AQA AS-Level Business: Marketing management (7137)
Study guide to marketing management in AQA AS-Level Business (7137), section 3.1.3: market research, data calculations, demand, segmentation and the mix.
Business · AQA · AS Level
Read guide -
Practice questions
AQA AS-Level Business: Marketing management (7137) – Practice Questions
Original practice questions with worked answers on AQA AS Business (7137) section 3.1.3 Marketing management: data, elasticity, segmentation and the mix.
Business · AQA · AS Level
Try questions -
Revision notes
AQA AS-Level Business: Marketing management (7137) – Revision Notes
Revision notes for AQA AS-Level Business (7137) section 3.1.3 Marketing management: research, data formulas, elasticity, segmentation and the mix.
Business · AQA · AS Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business AS LEVEL?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
AQA Business teachers at Marlbridge
