
Revision Notes
Edexcel IGCSE Accounting: Capital and revenue expenditure and depreciation (4AC1) – Revision Notes
Revision notes on capital and revenue expenditure, depreciation methods, ledger entries and disposals for Edexcel IGCSE Accounting 4AC1, with a self-test.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Introduction to bookkeeping
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Pearson Edexcel IGCSE Accounting (4AC1), Issue 1, October 2016. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Accounting.
Syllabus points this page covers
4AC1
- 2 Introduction to bookkeeping (whole topic)
- 2.4 Capital expenditure and revenue expenditure
- 2.5 Depreciation
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
These notes condense sections 2.4 (Capital expenditure and revenue expenditure) and 2.5 (Depreciation) of Topic 2, Introduction to bookkeeping, in the Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016. Depreciation is repeated in Topic 5, which sits in Paper 2, so learn it once and use it in both papers. For full explanations and worked examples, use the study guide.
Links: Edexcel IGCSE Accounting hub, printable checklist, free 10-minute diagnostics. For exam-style questions, use the practice set. All figures are invented and in dollars.
2.4 Capital and revenue expenditure
| Term | Meaning | Where it goes |
|---|---|---|
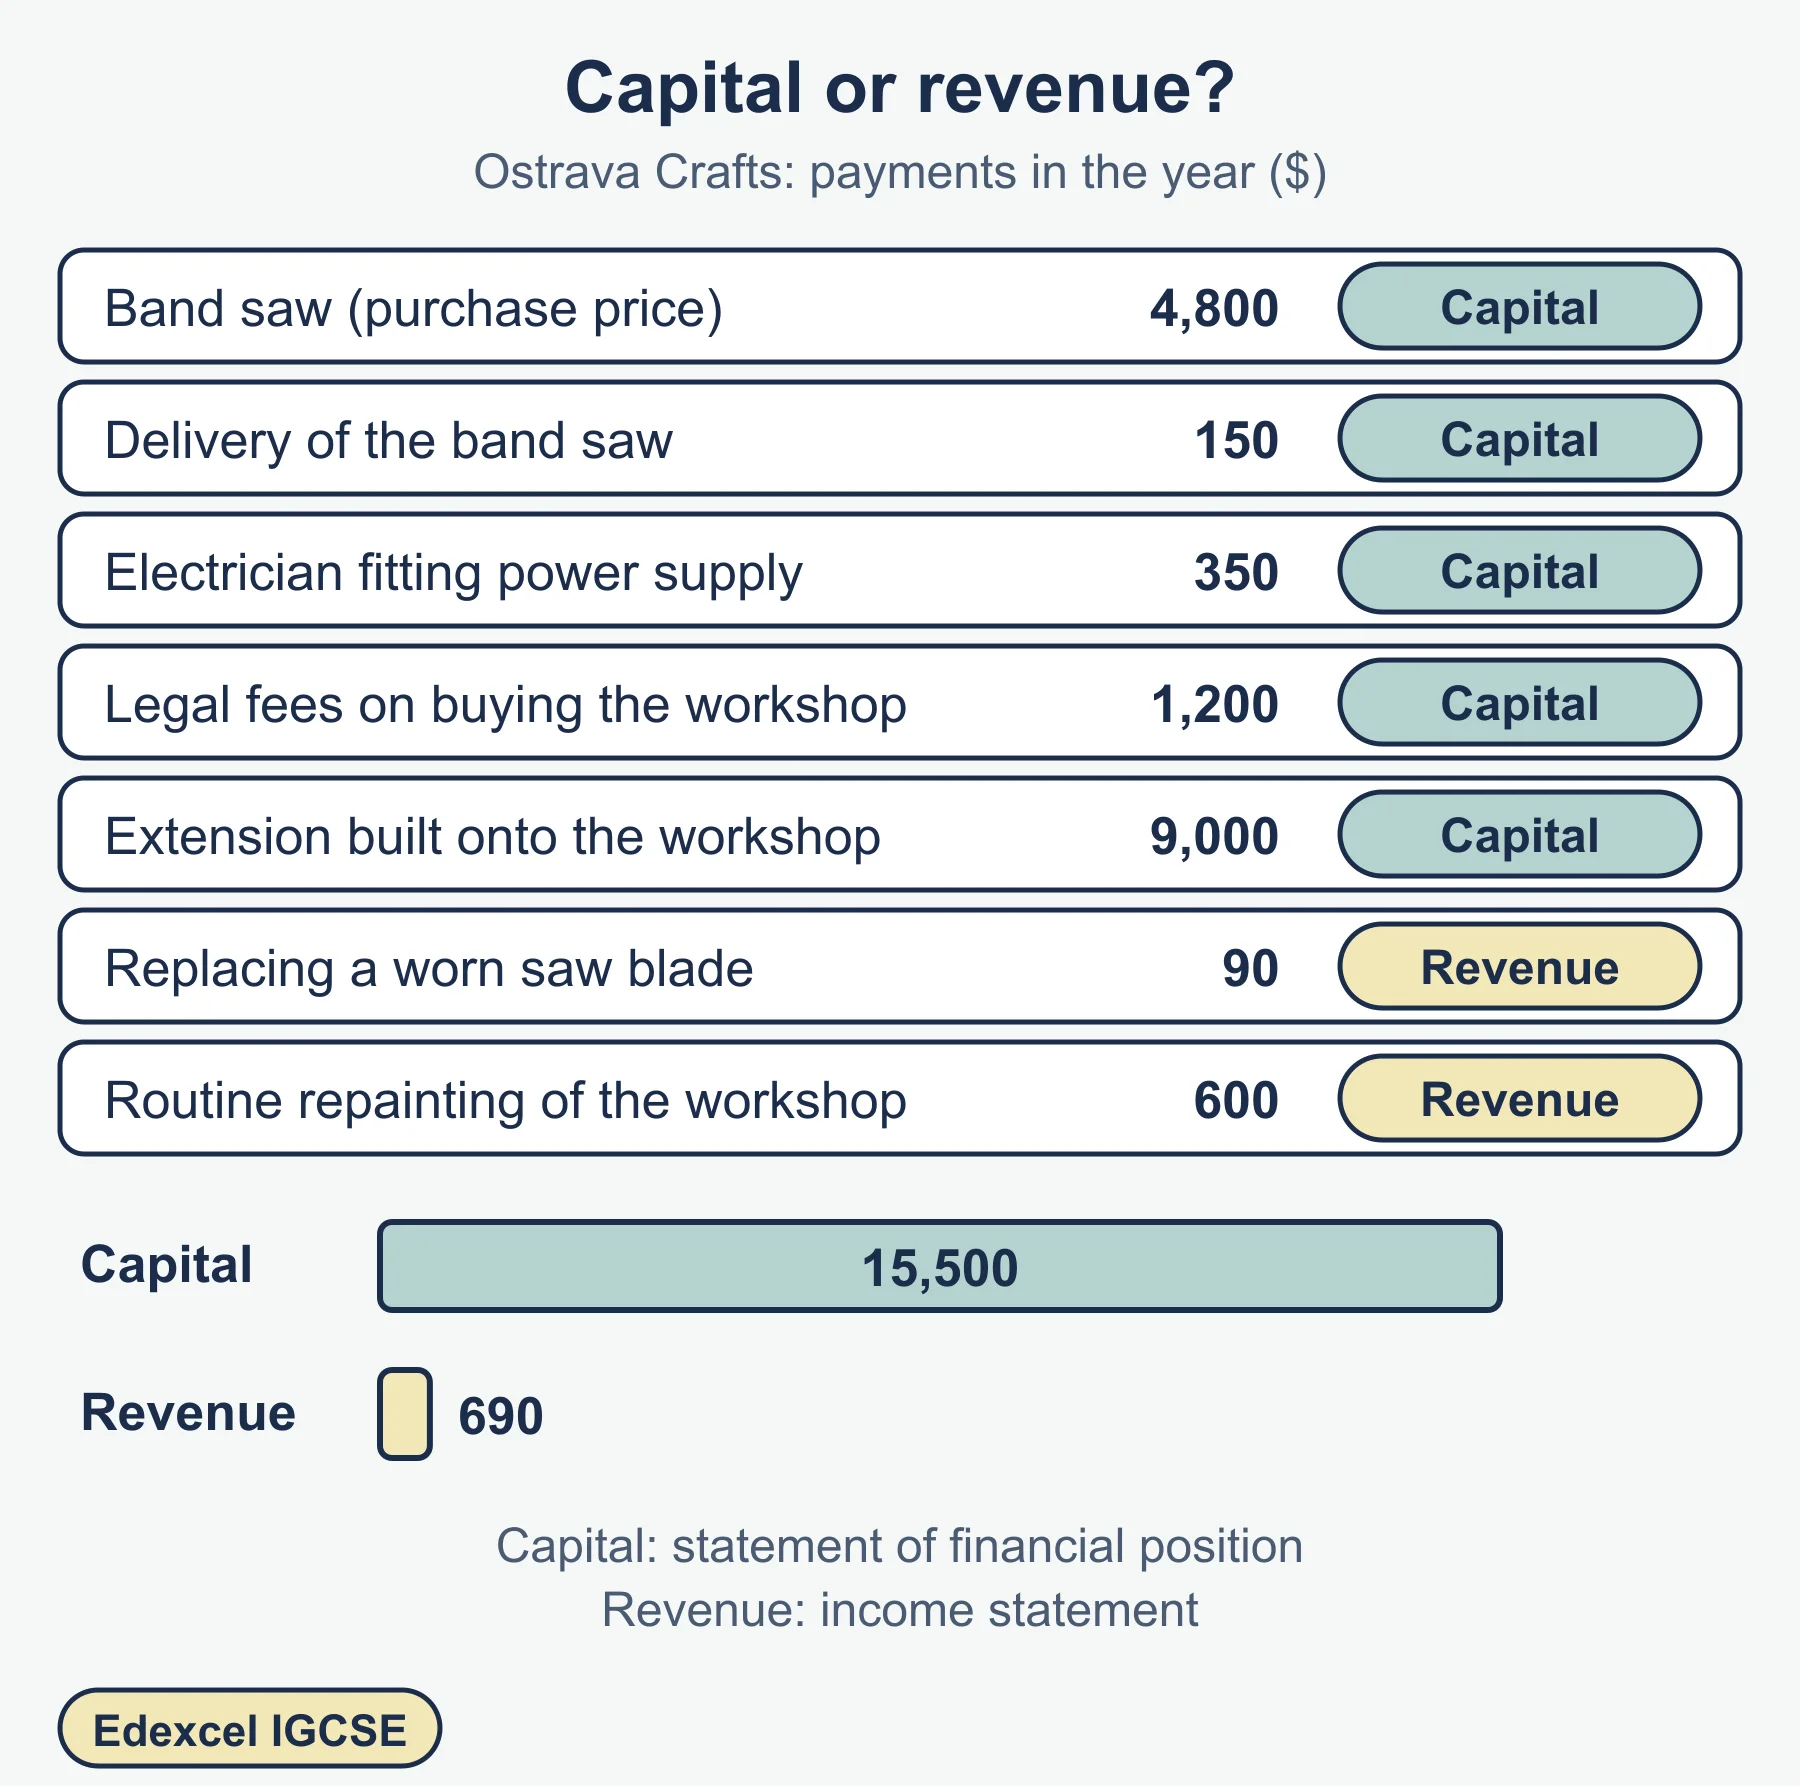
| Capital expenditure | Buying, adding to or improving a non-current asset | Asset account, then the statement of financial position |
| Revenue expenditure | Running costs and keeping an asset in working order | Expense account, then the income statement |
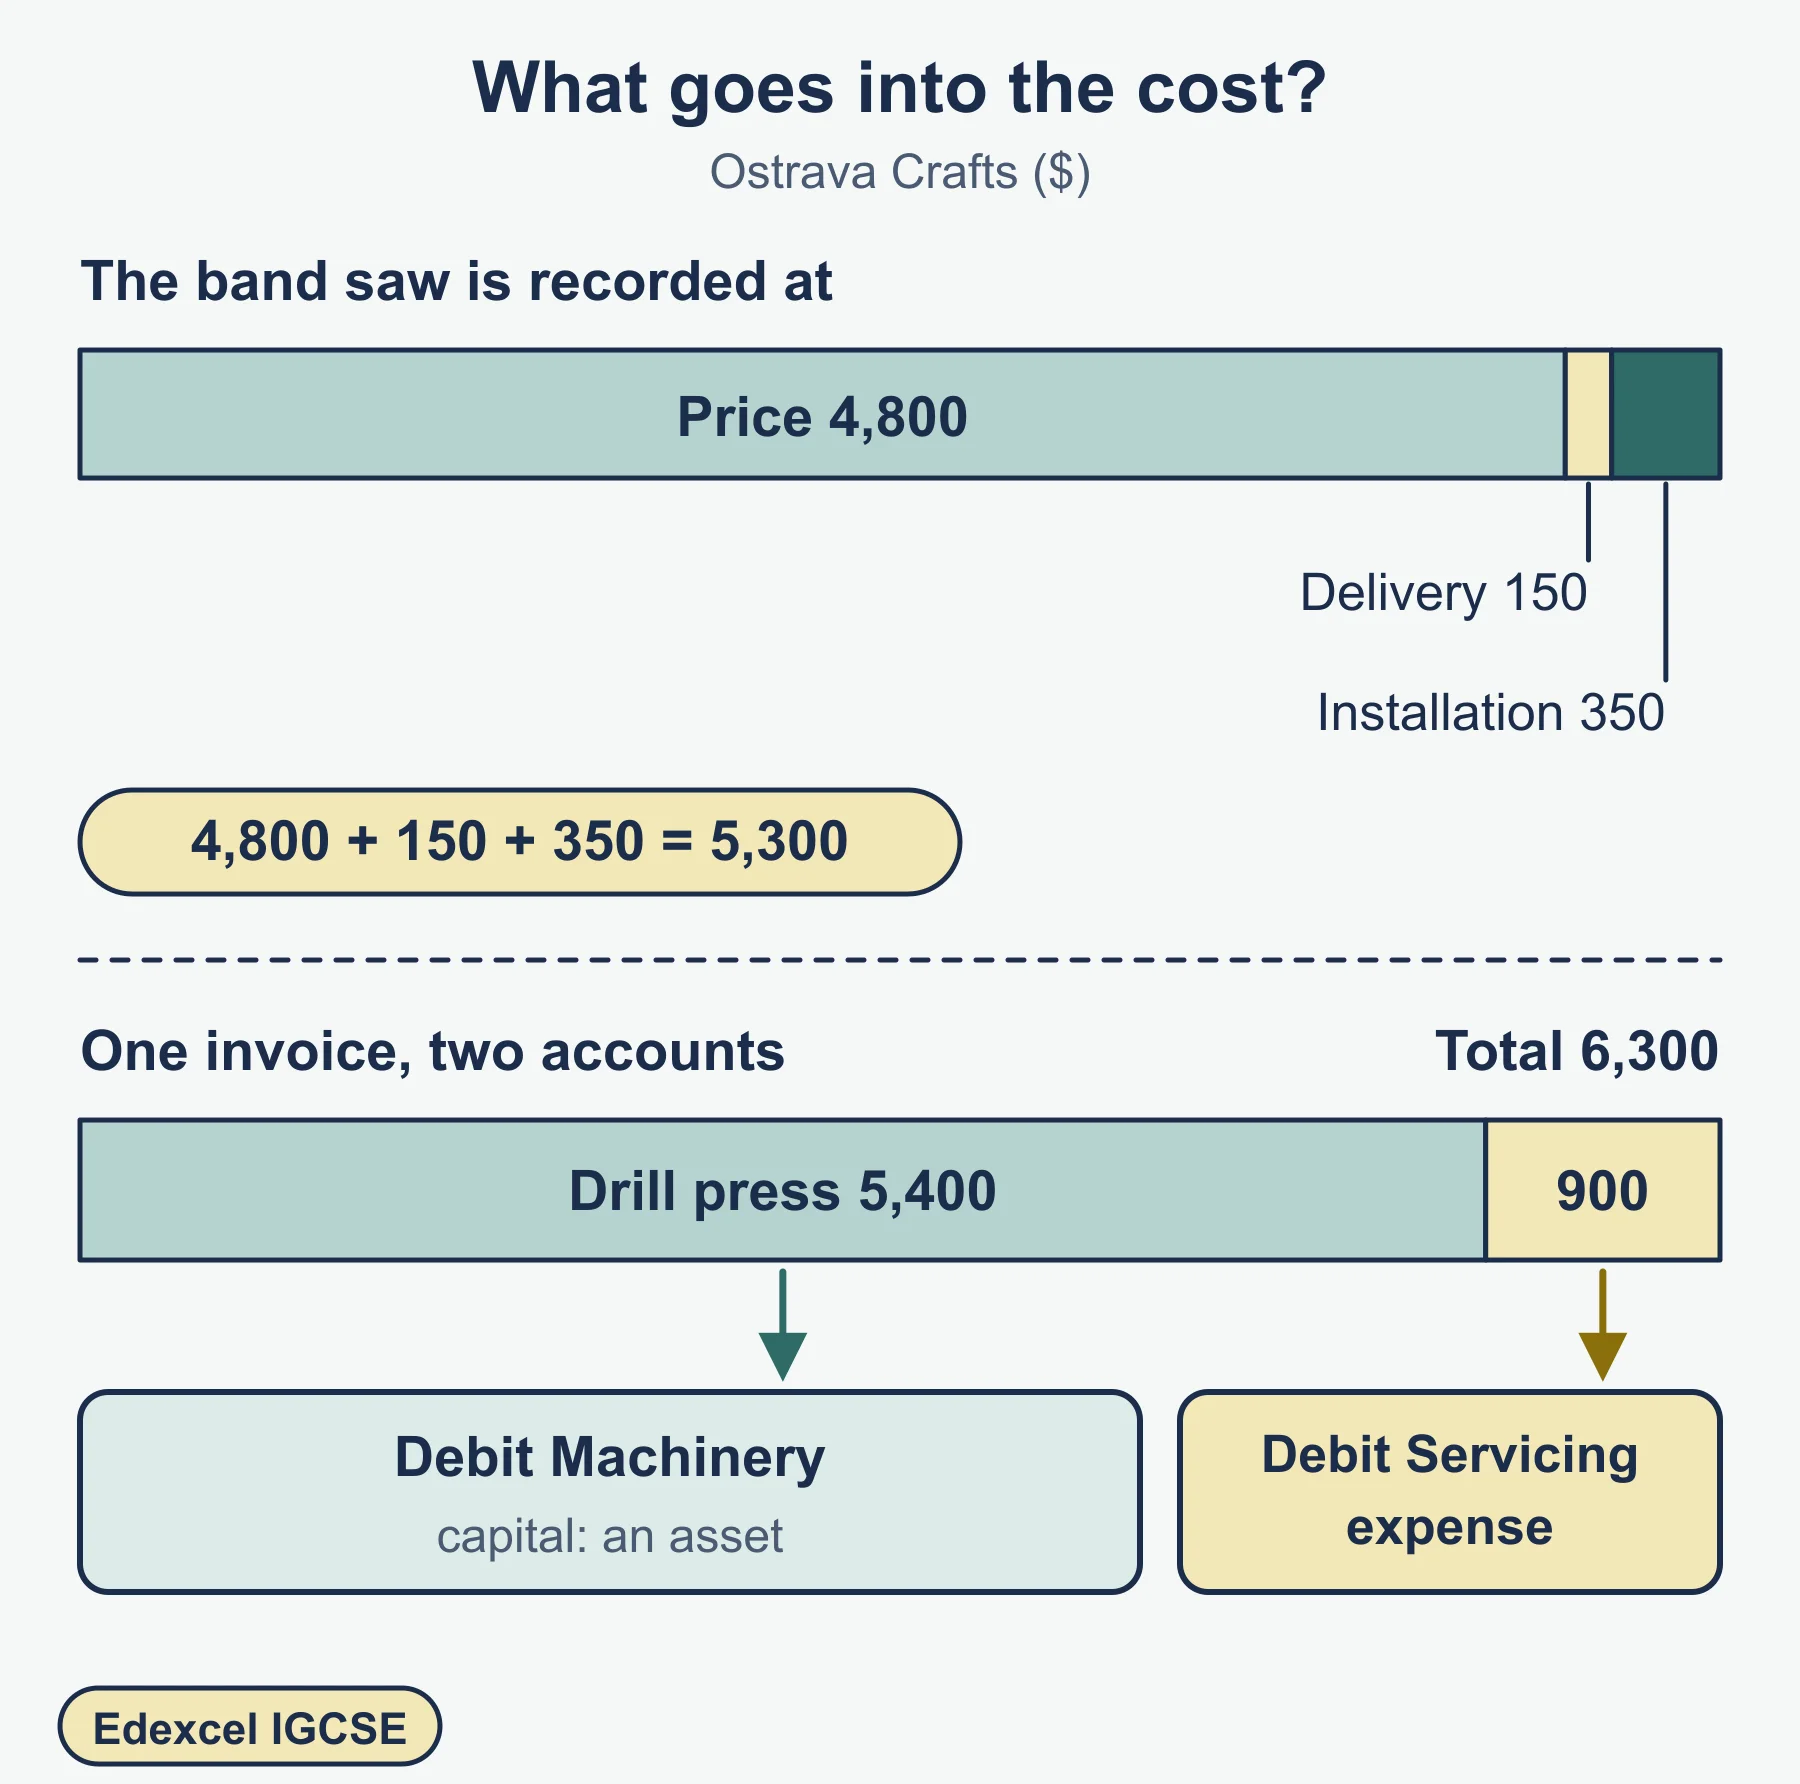
Cost of an asset = purchase price + delivery + installation + legal fees on property (anything needed to get it ready for use).
Quick sorting guide
| Item | Type |
|---|---|
| New delivery van | Capital |
| Fuel for the van | Revenue |
| Fitting shelves in a new shop | Capital |
| Repair of a broken window | Revenue |
| Adding a second floor to a warehouse | Capital |
| Annual service of a machine | Revenue |
Why correct treatment matters (2.4 b)
| Mistake | Profit | Assets | Later years |
|---|---|---|---|
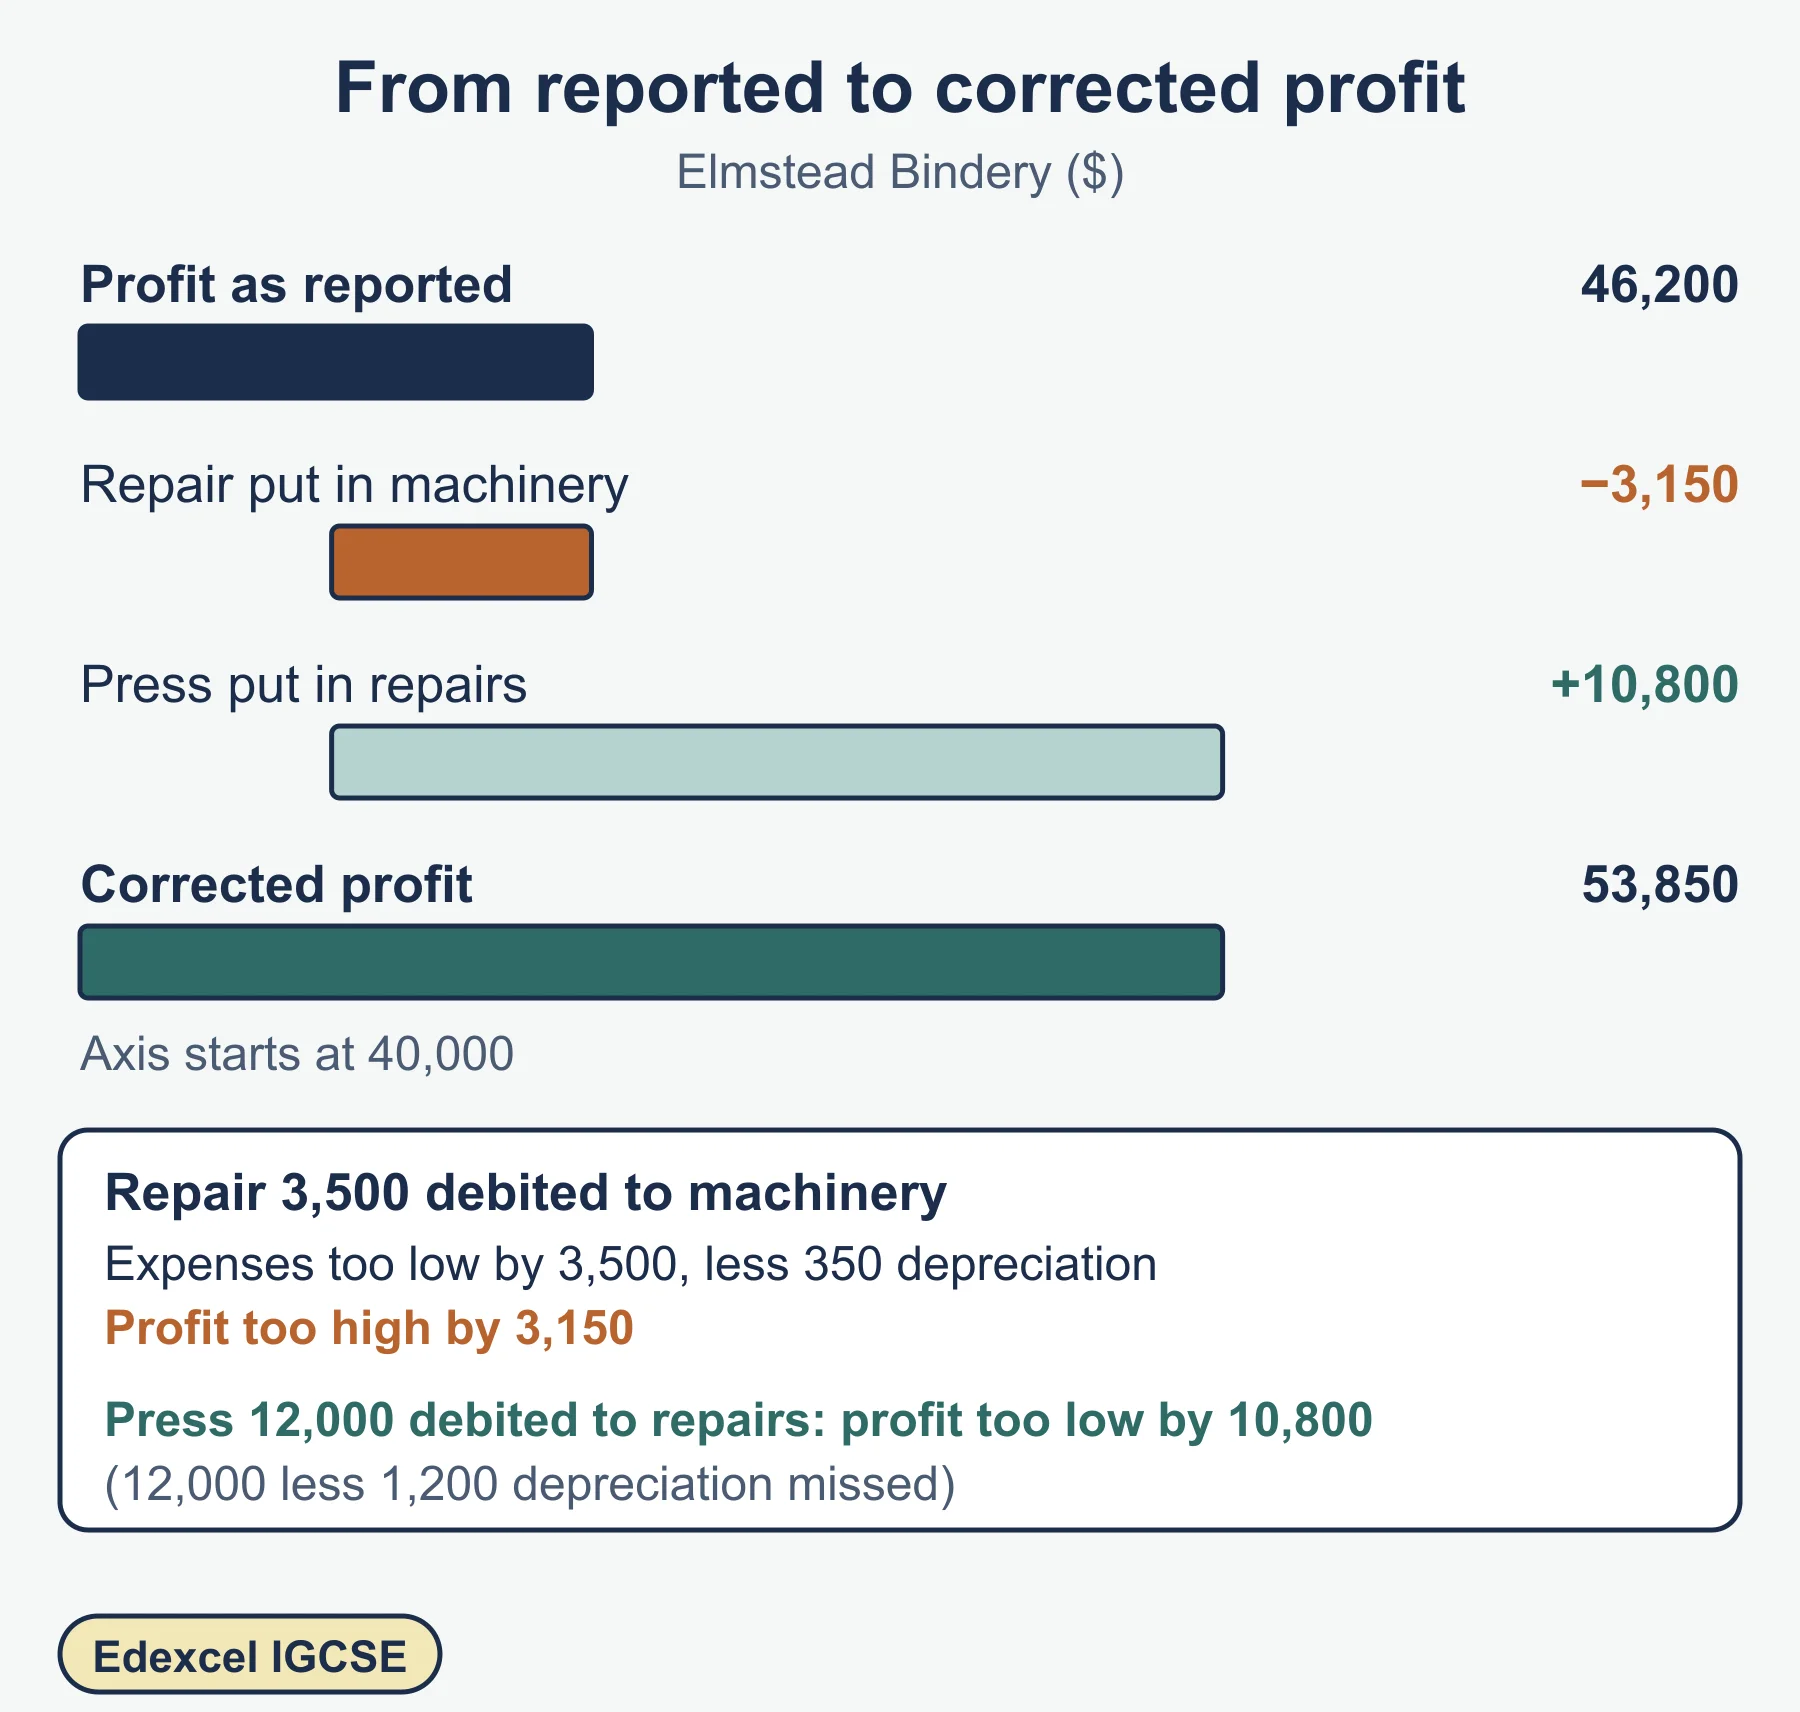
| Capital item charged as an expense | Understated | Understated | Depreciation is missed |
| Expense put into an asset account | Overstated | Overstated | Depreciation is charged on a cost that is not an asset |
Worked reminder. Greywell Printing debits a 1,000 repair to its equipment account. Depreciation is 20% of cost. Profit is overstated by 1,000 − 200 = 800. In a second case it debits a 5,000 new guillotine to repairs. Profit is understated by 5,000 − 1,000 = 4,000 because 1,000 of depreciation should have been charged.
Give the effect on both profit and assets in the same answer, and add the reason (a cost belongs to the years it benefits). An answer that names only one of the two usually reads as incomplete.
2.5 a Causes of depreciation
Depreciation spreads what a non-current asset cost across the years it is used. No cash is paid out when it is charged.
| Cause | Meaning |
|---|---|
| Wear and tear | Physical use and ageing |
| Obsolescence | Newer technology or design makes the asset out of date |
| Passage of time | The asset has a fixed term, for example a lease |
| Inadequacy | The asset is too small or no longer suits demand |
2.5 b and c Methods and calculations
| Feature | Straight line | Reducing balance |
|---|---|---|
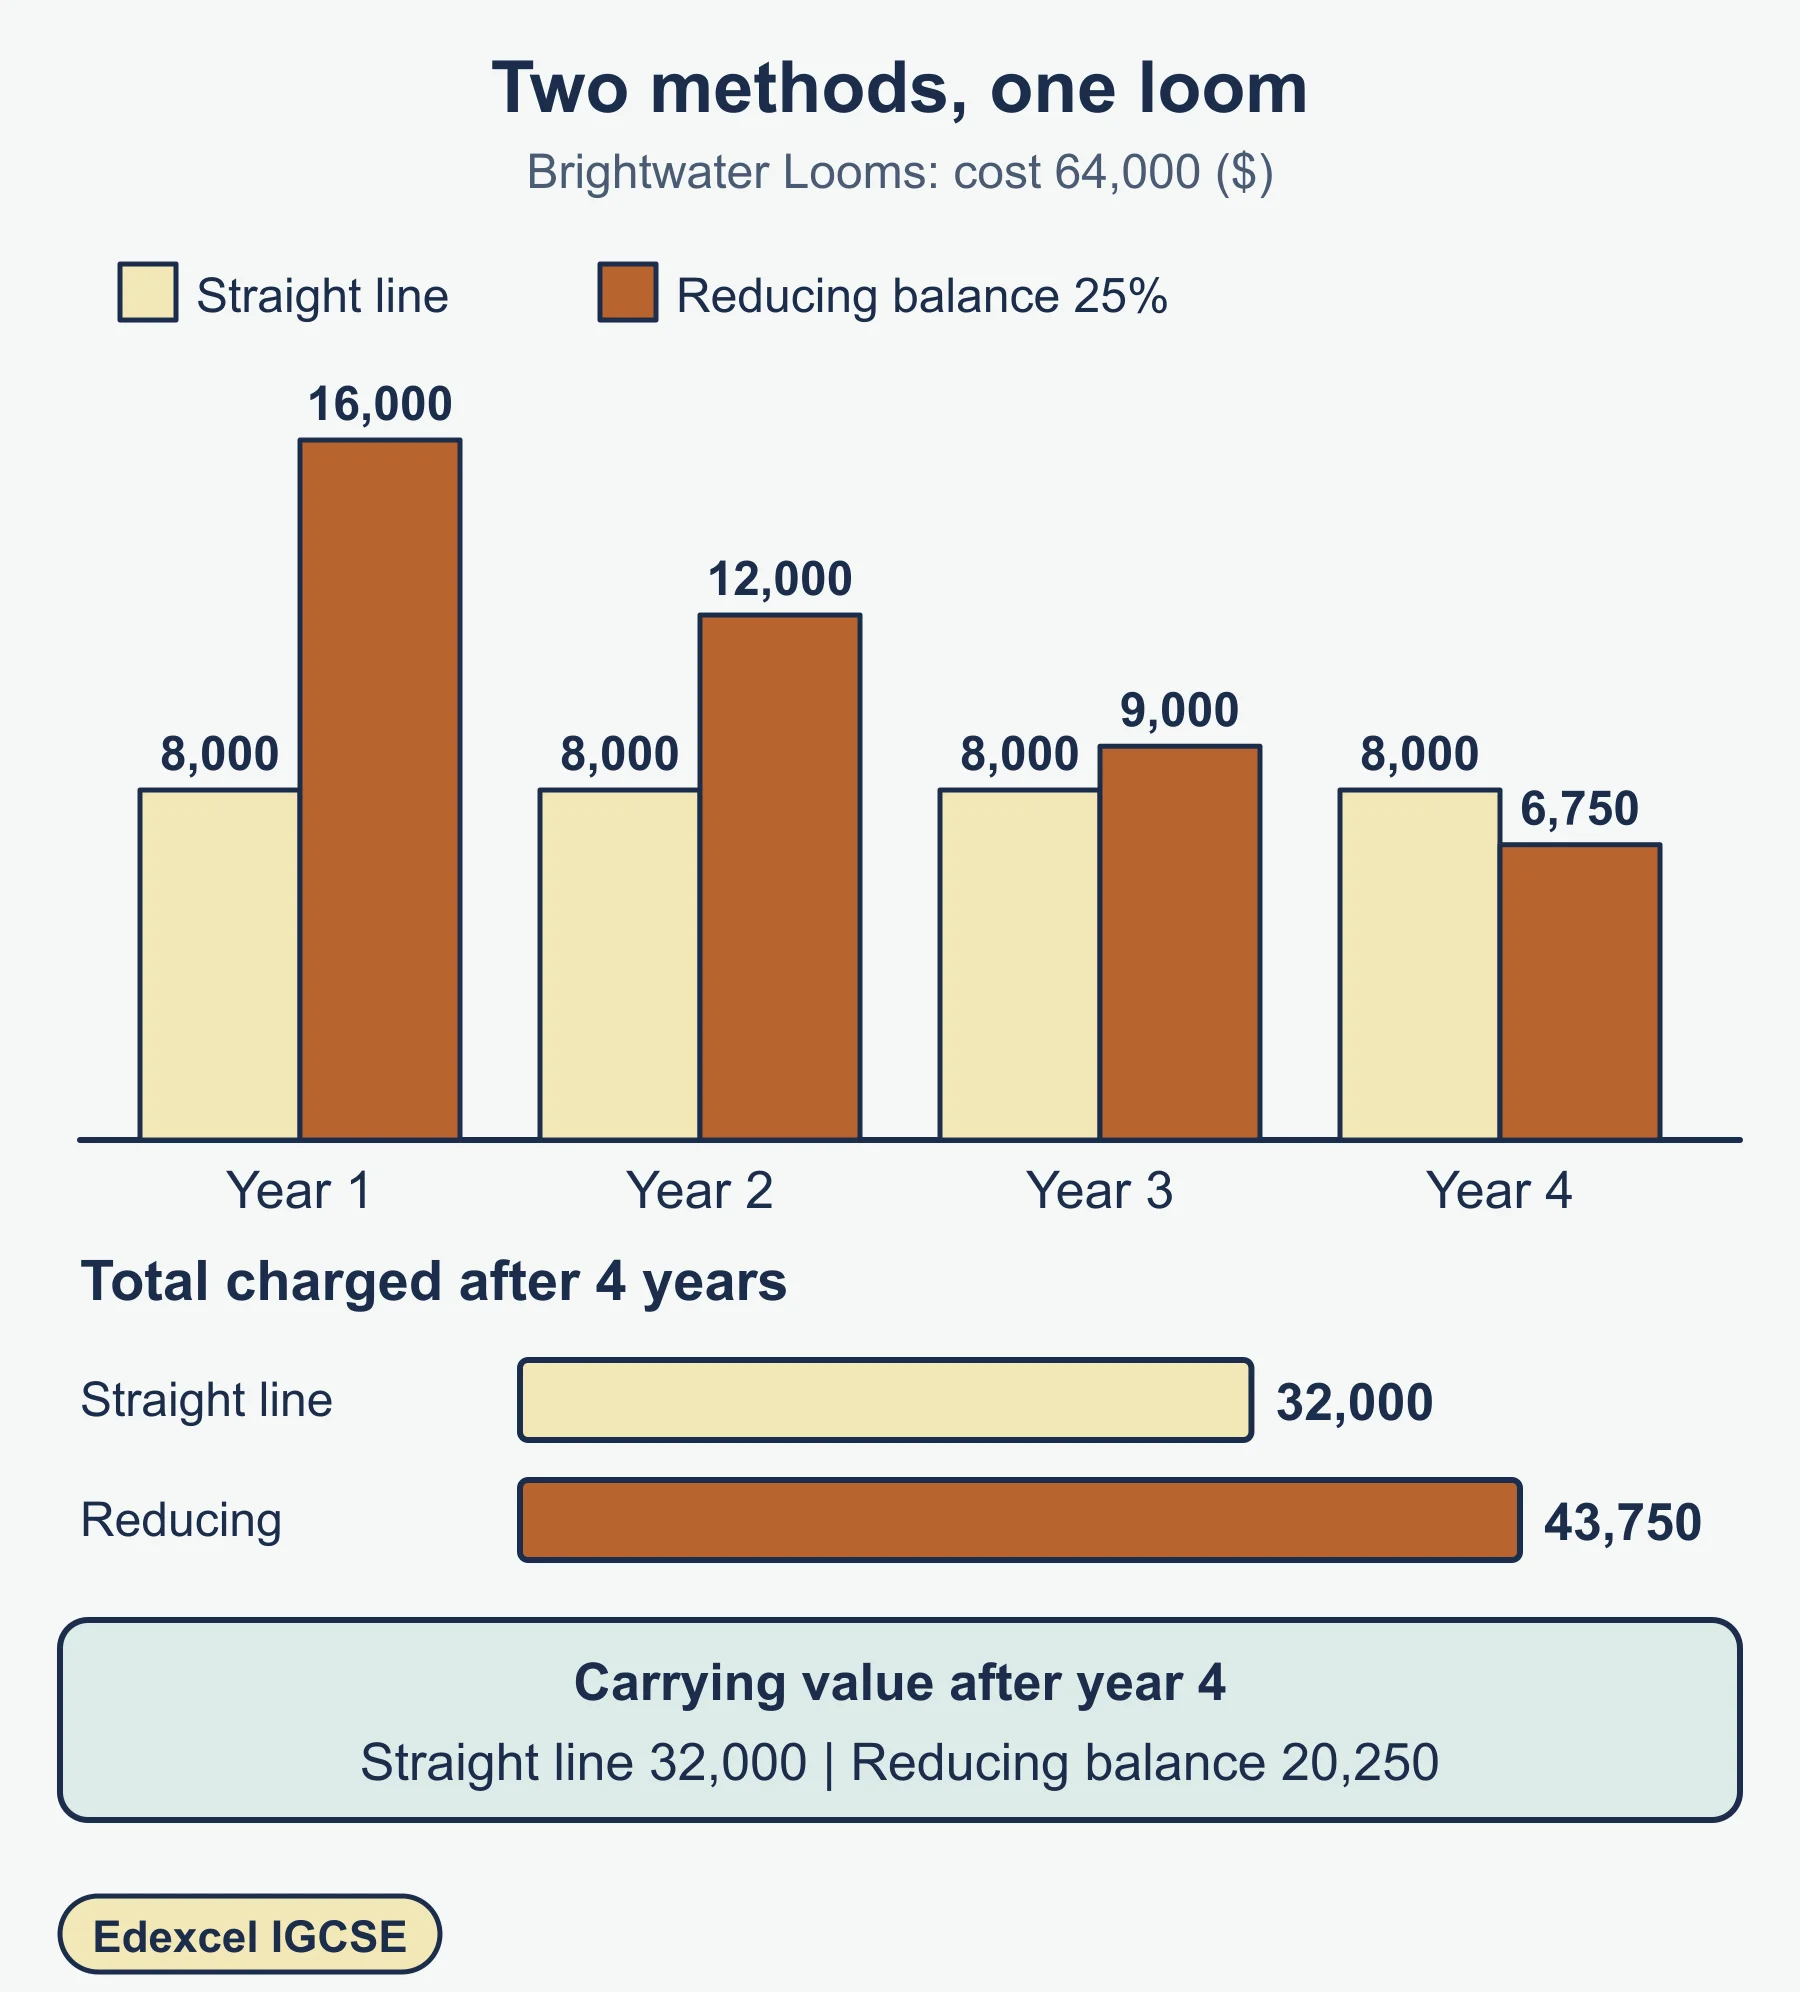
| Charge | Same each year | Falls each year |
| Formula | (cost − residual value) ÷ life, or a % of cost | % × carrying value at the start of the year |
| Residual value used? | Yes | No, the percentage is applied to carrying value |
| Suits | Assets used evenly | Assets that lose usefulness faster early on |
Carrying value = cost − accumulated depreciation.
Method in steps (calculation)
- Read the method, rate, life and residual value from the question.
- Straight line: work out one yearly charge. Reducing balance: start with cost, then multiply by the rate each year using the new carrying value.
- Keep a table: year, opening carrying value, charge, closing carrying value.
- Check that cost minus the total of the charges equals the closing carrying value.
Worked reminder. Greywell Printing buys a press for 18,400, residual value 2,400, life 5 years.
- Straight line: (18,400 − 2,400) ÷ 5 = 3,200 a year.
- Reducing balance at 40%: year 1 = 18,400 × 40% = 7,360; carrying value 11,040. Year 2 = 11,040 × 40% = 4,416; carrying value 6,624.
2.5 c Recording depreciation
| Step | Debit | Credit |
|---|---|---|
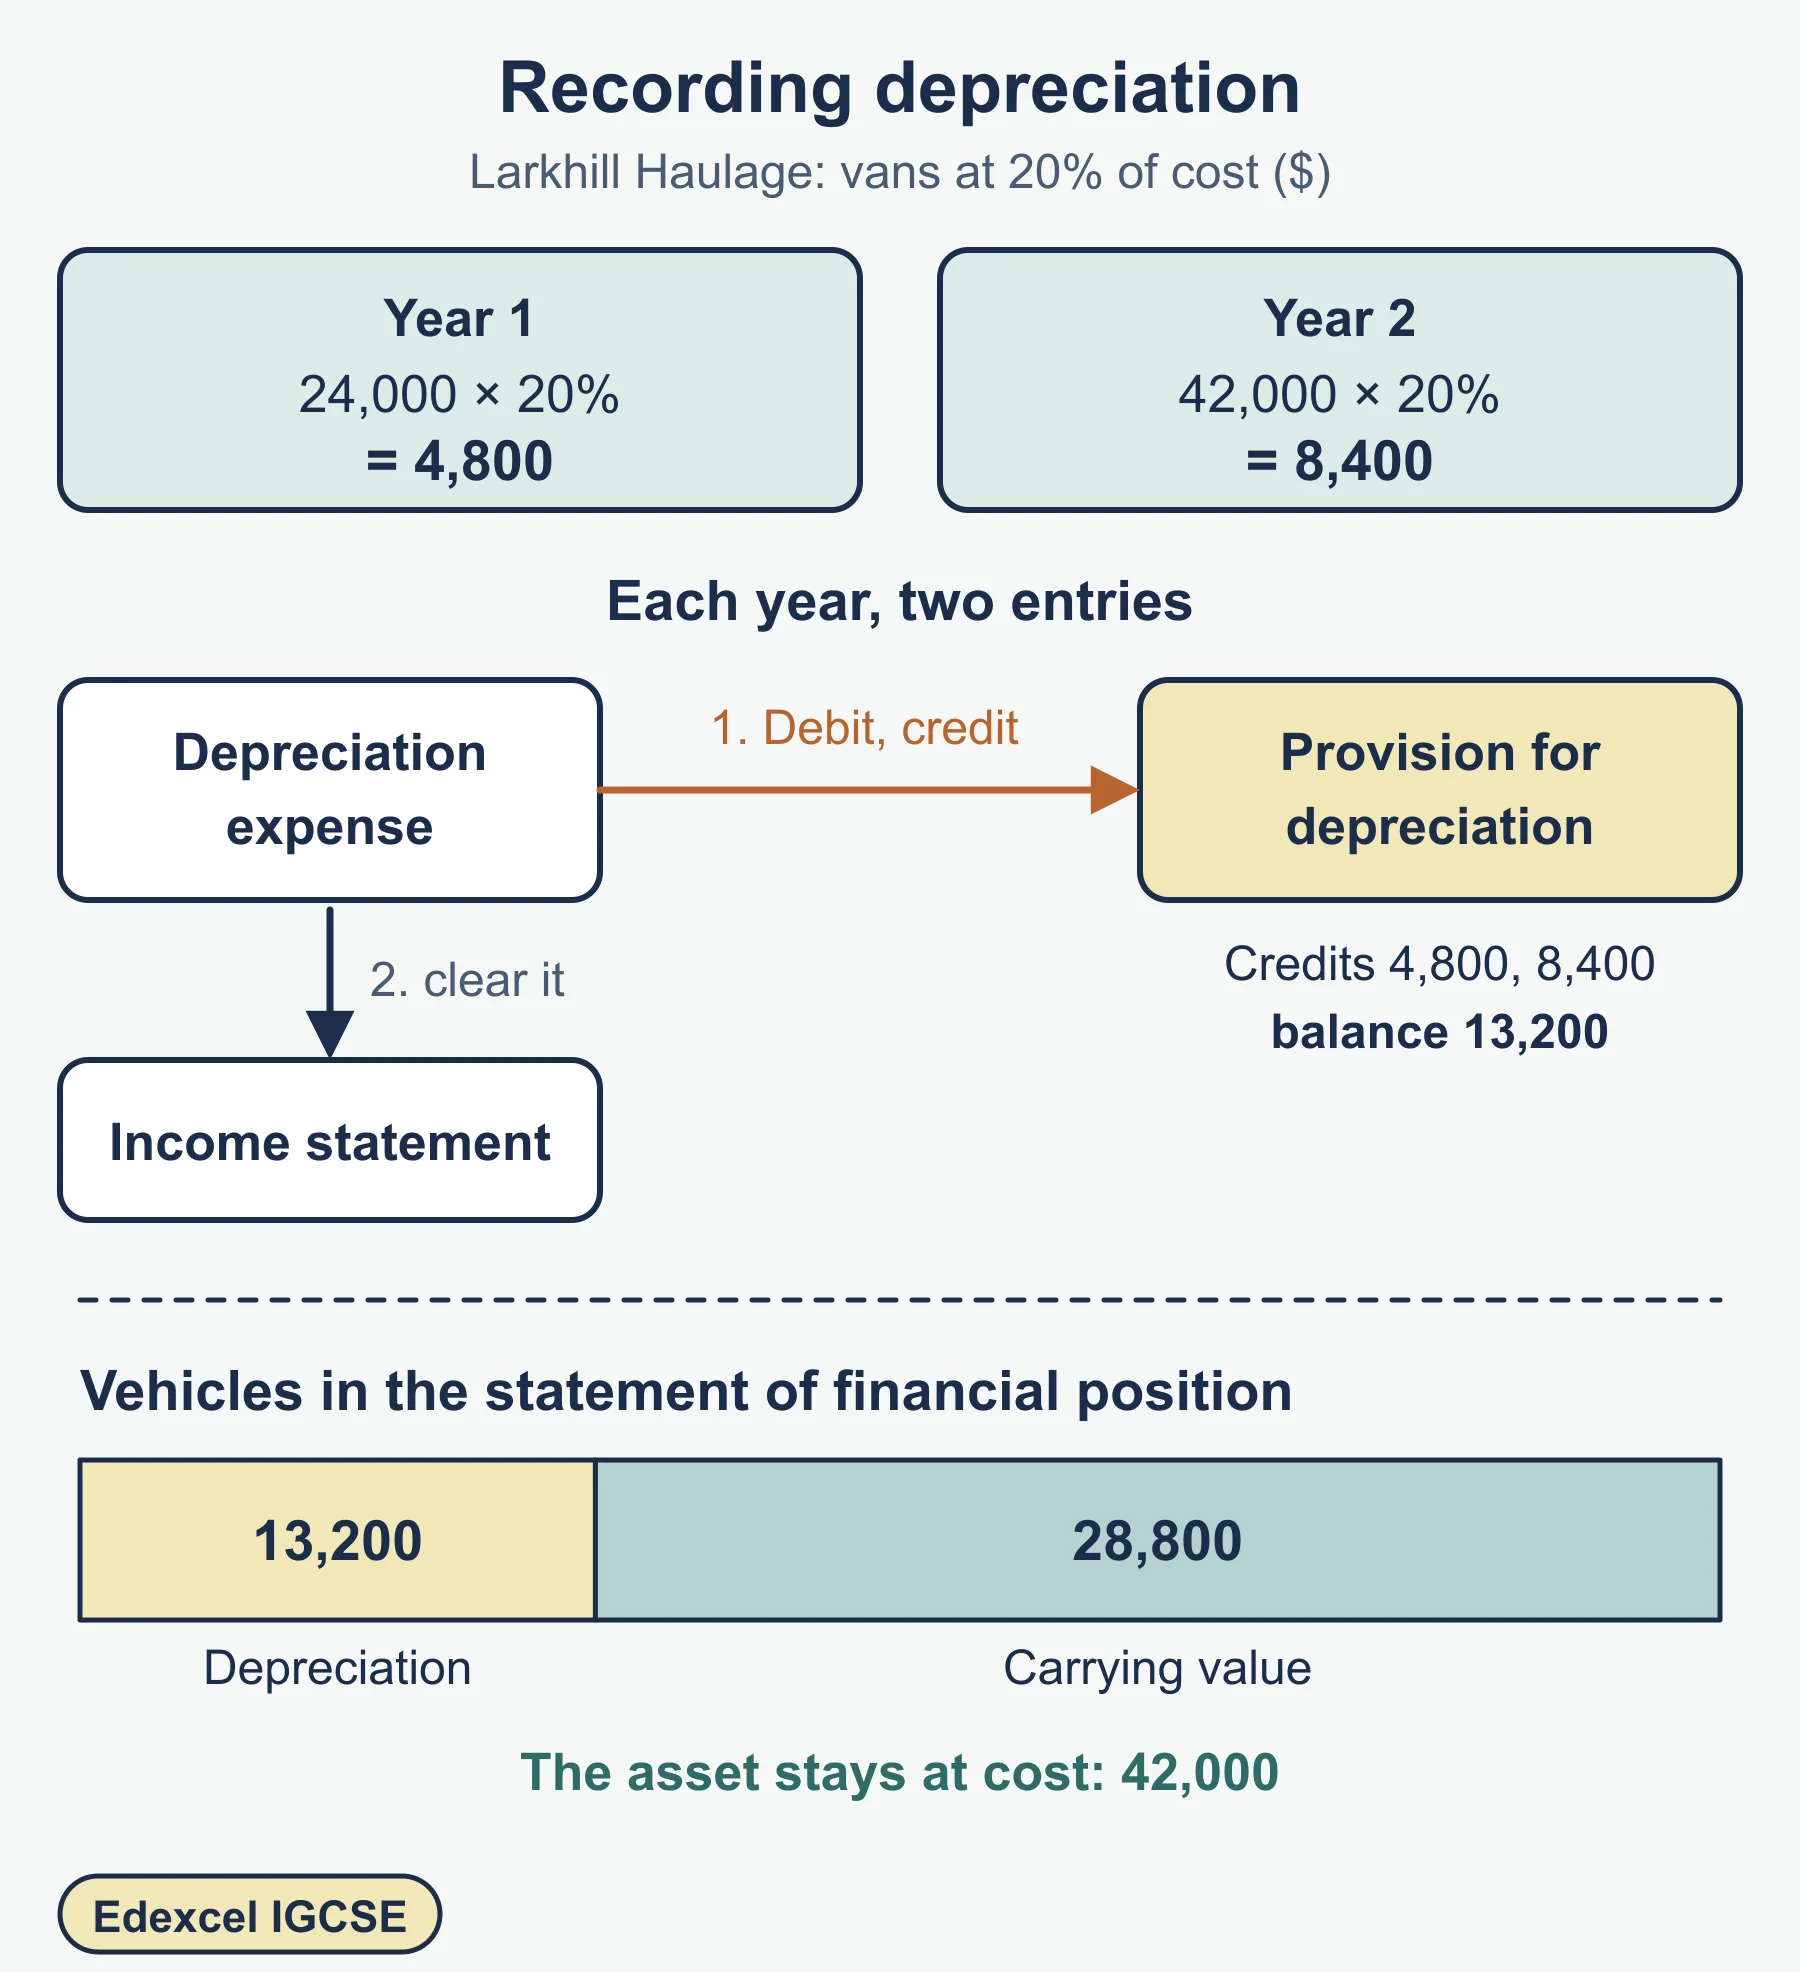
| Charge for the year | Depreciation expense | Provision for depreciation |
| Close off at year end | Income statement | Depreciation expense |
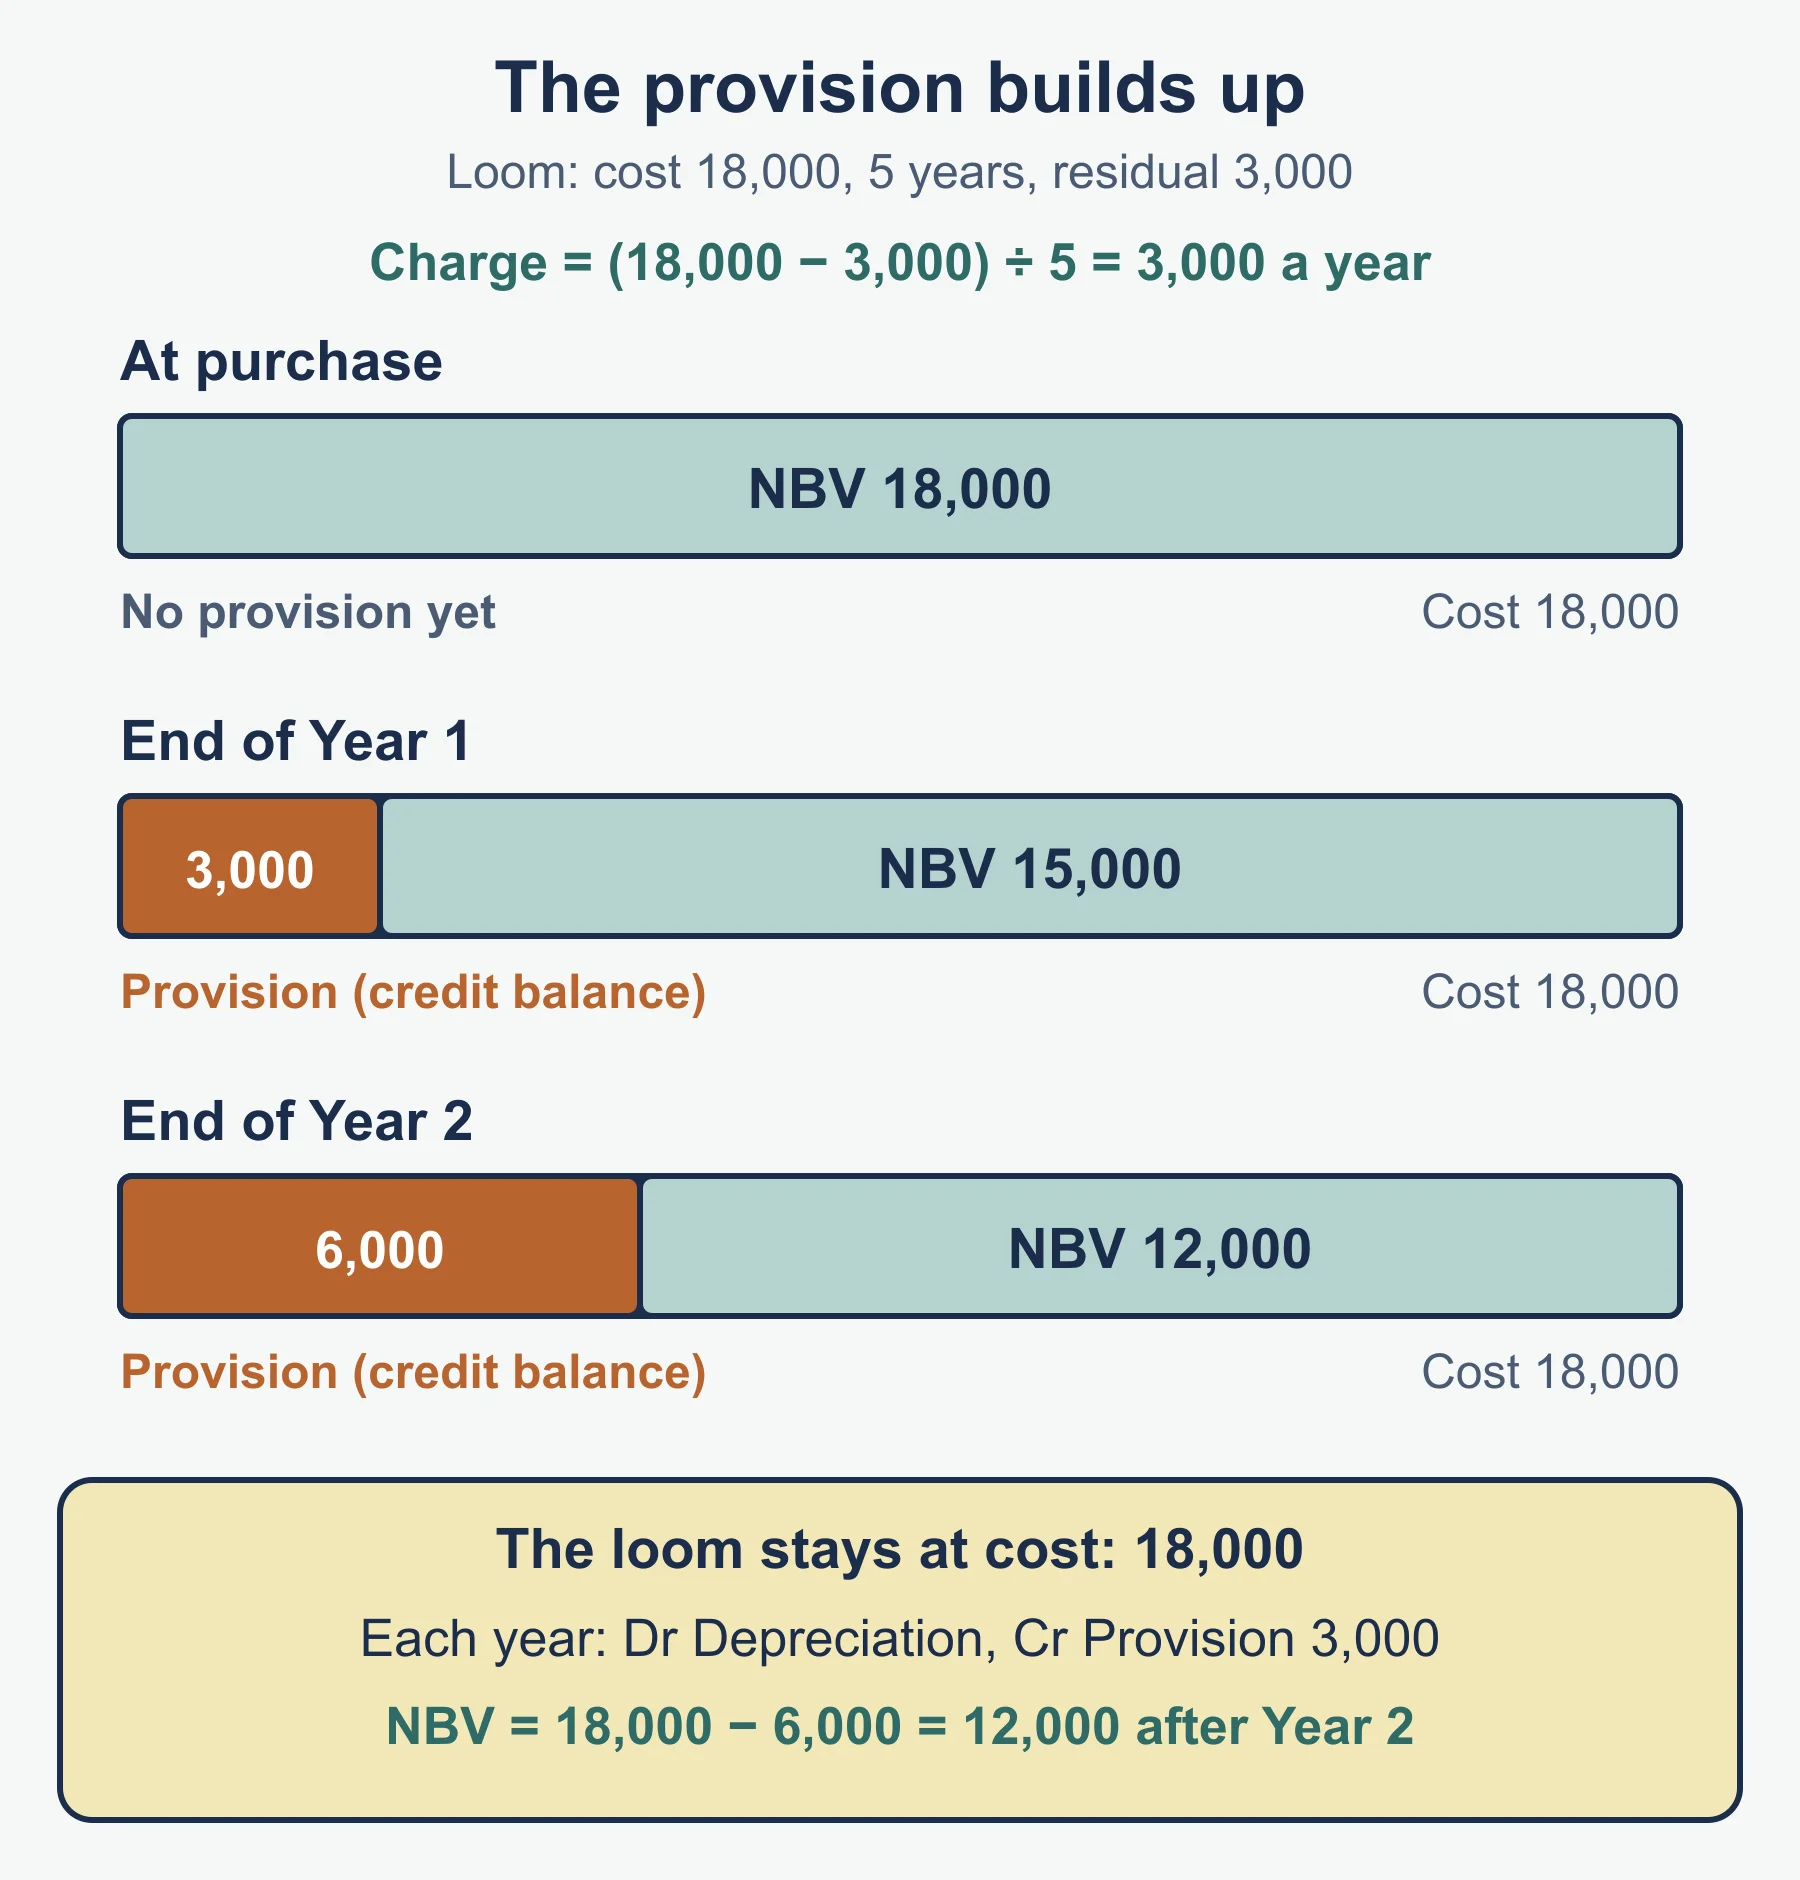
- The asset account stays at cost.
- The provision account builds up year by year. Its closing balance is carried down and brought down.
- In the statement of financial position, each class of asset appears with its cost, the depreciation to date and the resulting carrying value.
Worked reminder. The Greywell Printing press (cost 18,400, charge 3,200 a year) is bought on 1 January of Year 1. At the end of Year 1 the entries are debit depreciation expense 3,200 and credit provision for depreciation 3,200. The statement of financial position then shows cost 18,400, accumulated depreciation 3,200 and carrying value 15,200. At the end of Year 2 the provision has risen to 3,200 + 3,200 = 6,400, so carrying value is 18,400 − 6,400 = 12,000.
Method in steps (ledger)
- Work out the depreciation charge for the year on the assets held at the year end (follow any instruction on purchases during the year).
- Post the charge to the depreciation expense and the provision accounts.
- Balance the provision account. Carry the balance down.
- Transfer the expense to the income statement.
- Show cost less accumulated depreciation in the statement of financial position.
2.5 d Disposal of non-current assets
| Step | Debit | Credit |
|---|---|---|
| Remove cost | Disposal | Asset at cost |
| Remove accumulated depreciation | Provision for depreciation | Disposal |
| Record proceeds | Bank (or cash) | Disposal |
| Balancing figure | Disposal if profit, Income statement if loss | Income statement if profit, Disposal if loss |
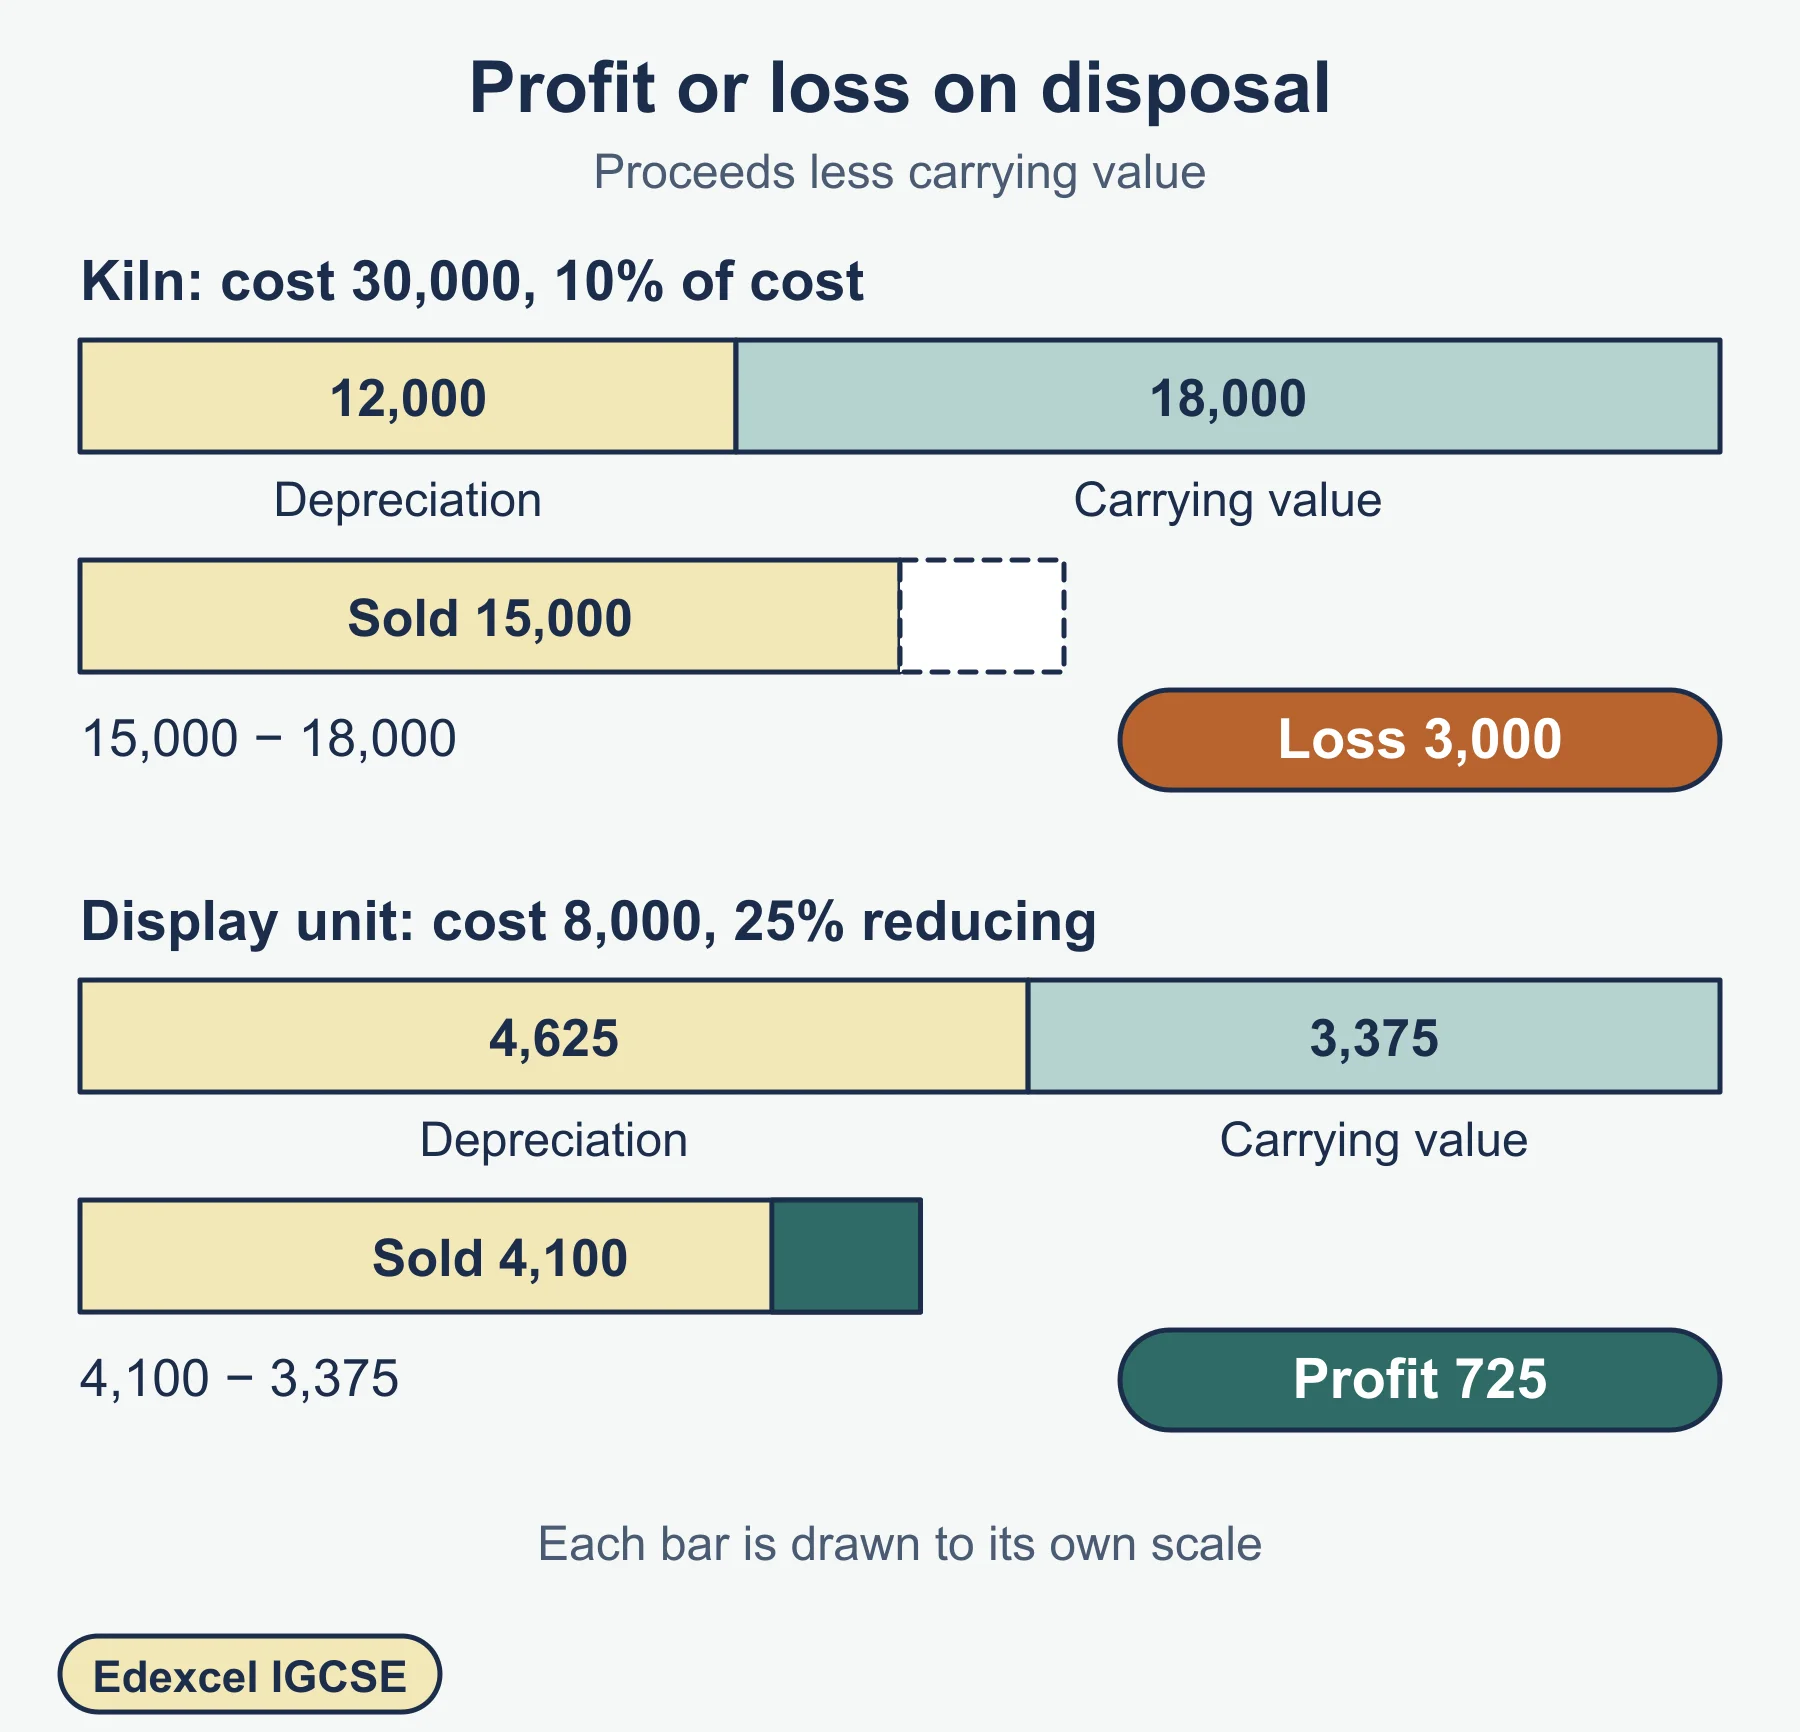
Profit or loss = proceeds − carrying value.
- Proceeds above carrying value: profit, shown as income in the income statement.
- Proceeds below carrying value: loss, shown as an expense in the income statement.
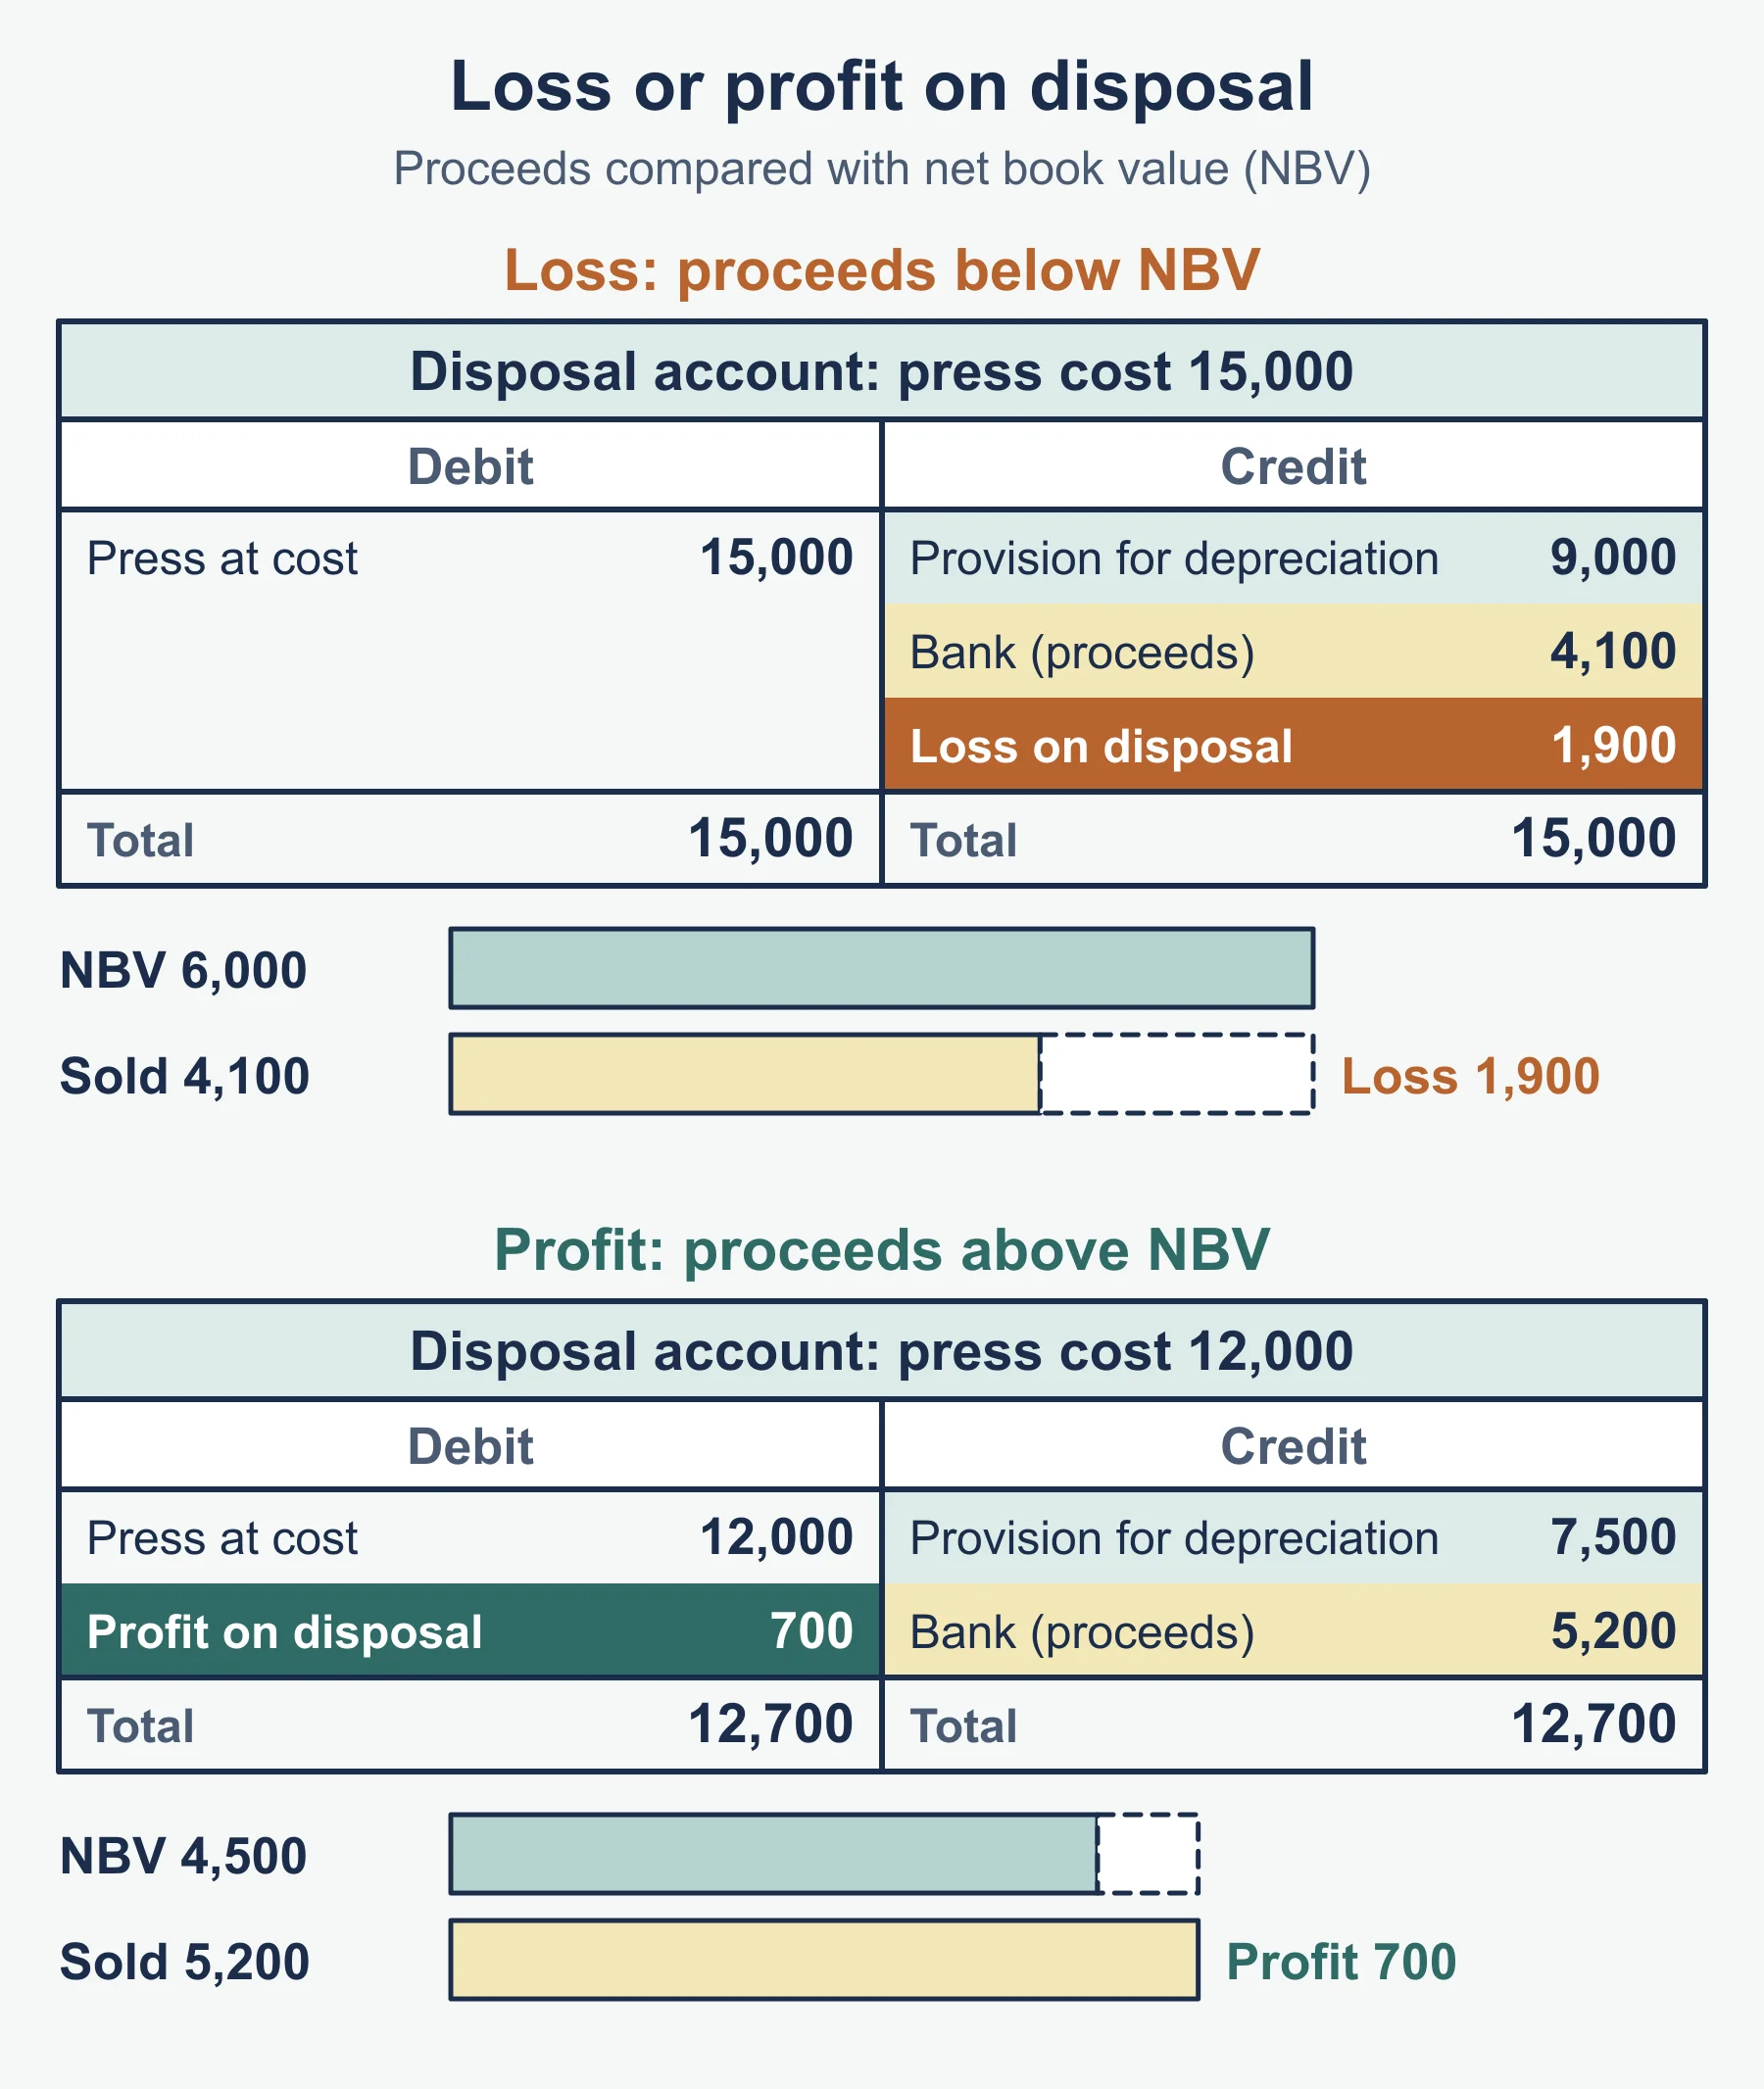
Before you build the disposal account, make sure the depreciation charged up to the date of sale is in the provision. The full cost of the asset, and the full accumulated depreciation on it, move to the disposal account.
Worked reminder. Oakvale Laundry sells a machine that cost 12,000, with accumulated depreciation of 7,500. Carrying value = 12,000 − 7,500 = 4,500. It sells for 5,200, so profit = 5,200 − 4,500 = 700.
Must-know distinctions
- Capital vs revenue: asset kept for more than a year vs day-to-day or maintenance cost.
- Straight line vs reducing balance: equal charges vs falling charges; residual value used vs not used.
- Cost vs carrying value: original price plus costs vs cost less accumulated depreciation.
- Depreciation expense vs provision for depreciation: the yearly cost in the income statement vs the running total in the statement of financial position.
- Depreciation vs cash: depreciation is an allocation of past spending, not money paid out in the year.
Quick self-test
- Define capital expenditure.
- Is repainting an office wall routine capital or revenue expenditure? Is fitting a new lift?
- Give two effects of treating a repair as capital expenditure.
- A machine costs 27,000, residual value 3,000, life 4 years. What is the straight line charge?
- An asset costs 15,000 and is depreciated at 20% reducing balance. Give the year 2 charge and the carrying value at the end of year 2.
- Is residual value used when applying a reducing balance percentage?
- State the double entry for the yearly depreciation charge.
- Define carrying value.
- An asset cost 10,000, accumulated depreciation is 6,400 and it is sold for 3,100. State the carrying value and the profit or loss.
- Where is a loss on disposal shown?
- State two causes of depreciation.
Answers
- Spending on buying, adding to or improving a non-current asset.
- Repainting is revenue; the new lift is capital.
- Profit is overstated; non-current assets are overstated (and depreciation is wrongly charged on the repair).
- (27,000 − 3,000) ÷ 4 = 6,000.
- Year 1 charge 3,000, carrying value 12,000. Year 2 charge = 12,000 × 20% = 2,400; carrying value 9,600.
- No. The percentage is applied to the carrying value.
- Debit depreciation expense, credit provision for depreciation.
- Cost less accumulated depreciation.
- Carrying value = 10,000 − 6,400 = 3,600. Loss = 3,100 − 3,600 = 500 loss.
- In the income statement, as an expense.
- Two from: wear and tear, obsolescence, time running out (a lease), inadequacy.
Where marks are usually lost
- Classifying delivery or installation of a new asset as revenue expenditure.
- Saying “profit is wrong” without stating whether it is overstated or understated, and why.
- Using the straight line formula for a reducing balance question, or subtracting residual value before applying the percentage.
- Using cost, not carrying value, as the base for the reducing balance percentage in the second year.
- Crediting the asset account with the depreciation charge when the question uses a provision account.
- Forgetting to carry down and bring down the provision balance.
- Leaving accumulated depreciation out of the disposal account, so the balancing figure is wrong.
- Writing profit on disposal as a loss (or the reverse) because the sides of the disposal account were not checked.
- Describing depreciation as “putting money aside” or “the asset’s market value”.
- Giving one cause of depreciation when the question asks for two.
Frequently asked questions
What are the causes of depreciation? The usual causes are wear and tear from physical use, obsolescence when better equipment appears, the passage of time, as with a lease, and inadequacy or a change in demand. When a question asks for two causes, give two.
How is depreciation recorded using a provision for depreciation account? Each year debit the depreciation expense account and credit the provision for depreciation account with the charge, then transfer the expense to the income statement. The asset account stays at cost, and the provision balance is carried down and brought down.
What is carrying value? Carrying value is the cost of a non-current asset less accumulated depreciation to date. The Edexcel IGCSE glossary uses this term in place of net book value.
Why is depreciation charged? Depreciation spreads the cost of a non-current asset across the years that benefit from it, so profit is not distorted by one large purchase. This follows the accruals concept.
Official syllabus
Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016, published by Pearson Education Limited – Topic 2, Introduction to bookkeeping, sections 2.4 and 2.5 (and the matching Depreciation points in Topic 5).
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
Edexcel IGCSE Accounting: Irrecoverable debts and other receivables and other payables (4AC1)
Study guide to Edexcel International GCSE Accounting 4AC1 sections 2.6 and 2.7: irrecoverable debts, provisions, other receivables and other payables.
Accounting · Pearson Edexcel · IGCSE
Read guide -
Practice questions
Edexcel IGCSE Accounting: Irrecoverable debts and other receivables and other payables (4AC1) – Practice Questions
Original practice questions with worked answers for Edexcel International GCSE Accounting 4AC1 sections 2.6 and 2.7: provisions, accruals and prepayments.
Accounting · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Accounting: Irrecoverable debts and other receivables and other payables (4AC1) – Revision Notes
Condensed revision notes for Edexcel International GCSE Accounting 4AC1 sections 2.6 and 2.7: irrecoverable debts, provisions, accruals and prepayments.
Accounting · Pearson Edexcel · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Accounting teachers at Marlbridge

