
Study Guides
Edexcel IGCSE Accounting: Irrecoverable debts and other receivables and other payables (4AC1)
Study guide to Edexcel International GCSE Accounting 4AC1 sections 2.6 and 2.7: irrecoverable debts, provisions, other receivables and other payables.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Introduction to bookkeeping
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Pearson Edexcel IGCSE Accounting (4AC1), Issue 1, October 2016. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Accounting.
Syllabus points this page covers
4AC1
- 2 Introduction to bookkeeping (whole topic)
- 2.6 Irrecoverable debts
- 2.7 Other receivables and other payables
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
This guide teaches sections 2.6 (Irrecoverable debts) and 2.7 (Other receivables and other payables) of Topic 2, Introduction to bookkeeping, in the Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016. The specification describes two papers and does not divide them into tiers. Paper 1 is drawn only from topics 1 to 3, while Paper 2 adds topics 4 and 5 to that base, so this bookkeeping carries into the financial statements you prepare later.
Links: 4AC1 course hub, printable checklist, revision notes for this unit, practice questions for this unit and the free 10-minute diagnostics.
What these sections cover
| Section | What you must be able to do |
|---|---|
| 2.6 a | Explain why a provision for irrecoverable debts is necessary |
| 2.6 b | Distinguish between an irrecoverable debt and a provision for an irrecoverable debt |
| 2.6 c | Calculate and record irrecoverable debts and the provision in the books of account |
| 2.7 a | Explain why other receivables and other payables must be accounted for |
| 2.7 b | Distinguish between other receivables and other payables |
| 2.7 c | Calculate and record other receivables and other payables in the books of account |
The specification’s own glossary links the older and newer names: other receivables replace “prepayments”, other payables replace “accruals”, and an allowance for doubtful debt replaces “provision for doubtful debt”. The content tables themselves say “provision for irrecoverable debts”, so this guide uses that wording. The glossary also says trade receivables replace “debtors”, and that is the term used here.
The businesses and numbers here are fictional. Currency is dollars, and the sign is left off in the working.
Irrecoverable debts (2.6)
Why a debt becomes irrecoverable
A business that sells on credit records the sale as revenue and the customer as a trade receivable. Some customers never pay. When the business decides that a particular amount will not be received, because the customer is bankrupt, has disappeared or is not worth pursuing, that amount is an irrecoverable debt. It is a loss, so it is an expense.
The accounting is a write-off. The customer’s account in the receivables ledger is cleared, and the loss is collected in an expense account.
Journal for a write-off: Dr Irrecoverable debts, Cr the customer’s account (the trade receivable).
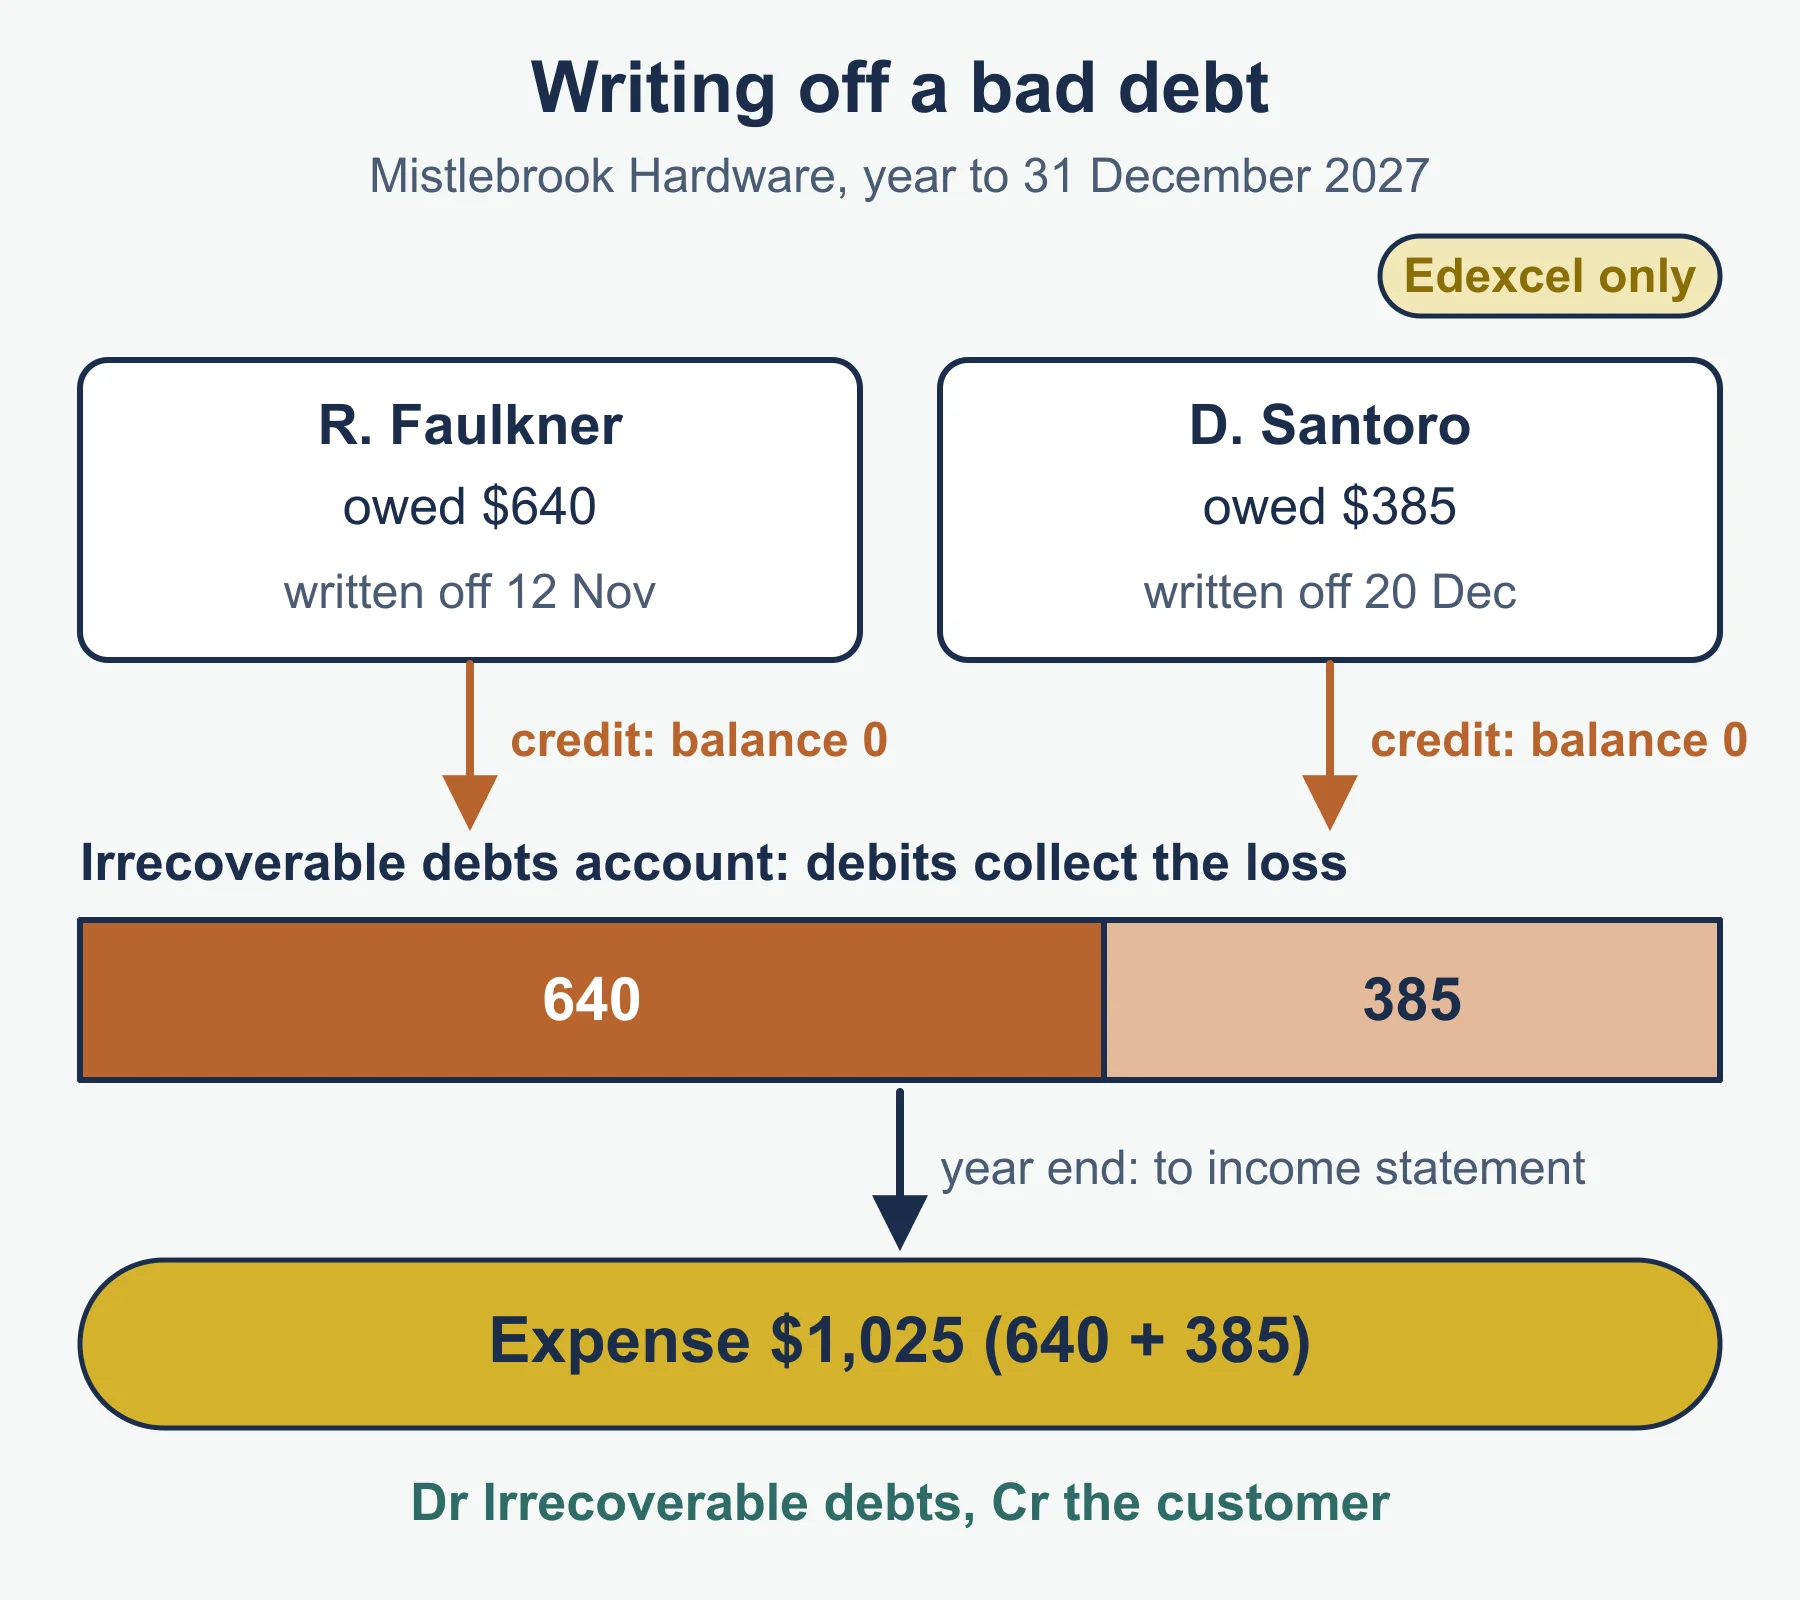
Mistlebrook Hardware has a 31 December year end. In November 2027 it learns that R. Faulkner, who owes 640, has been declared bankrupt and will pay nothing. In December it also gives up on D. Santoro, who owes 385.
                 R. Faulkner account
2027                          2027
1 Jan   Balance b/d      640   12 Nov Irrecoverable debts 640

                 D. Santoro account
2027                          2027
1 Jan   Balance b/d      385   20 Dec Irrecoverable debts 385

                 Irrecoverable debts account
2027                          2027
12 Nov  R. Faulkner      640   31 Dec Income statement  1,025
20 Dec  D. Santoro       385
                       1,025                            1,025
The two customer accounts now have no balance. The irrecoverable debts account holds the total loss of 1,025, which is transferred to the income statement at the year end as an expense (640 + 385 = 1,025).
Why a provision is necessary
At the year end, the other customers still owe the business money, and experience says that some of those balances will also go unpaid. Nobody knows which ones yet, so they cannot be written off one by one. Three accounting reasons explain why a provision is still made:
- Prudence. Neither profit nor assets should be shown too high when a loss is likely.
- Accruals (matching). The sales that produce the doubtful debts were made this year, so the expected loss belongs in the same year’s income statement, not next year’s.
- A realistic statement of financial position. Without a provision, trade receivables would be shown at an amount the business does not expect to collect in full.
Irrecoverable debt or provision
| Irrecoverable debt | Provision for irrecoverable debts | |
|---|---|---|
| What it is | A specific debt that will not be paid | An estimate of debts that may not be paid |
| Certainty | Decided, treated as lost | Not certain, judged from experience |
| Which customer | Named customers | No named customer |
| Customer account | Closed by the write-off | Customer accounts stay open and unchanged |
| Ledger | Credits the trade receivable | Own account, a credit balance |
| Statement of financial position | Debt removed from trade receivables | Deducted from trade receivables |
Recording the provision
Follow this order every time:
- Write off the known irrecoverable debts first.
- Take the provision as a percentage of the trade receivables that remain.
- Compare the new provision with the opening provision (the balance already in the account).
- Record only the difference.
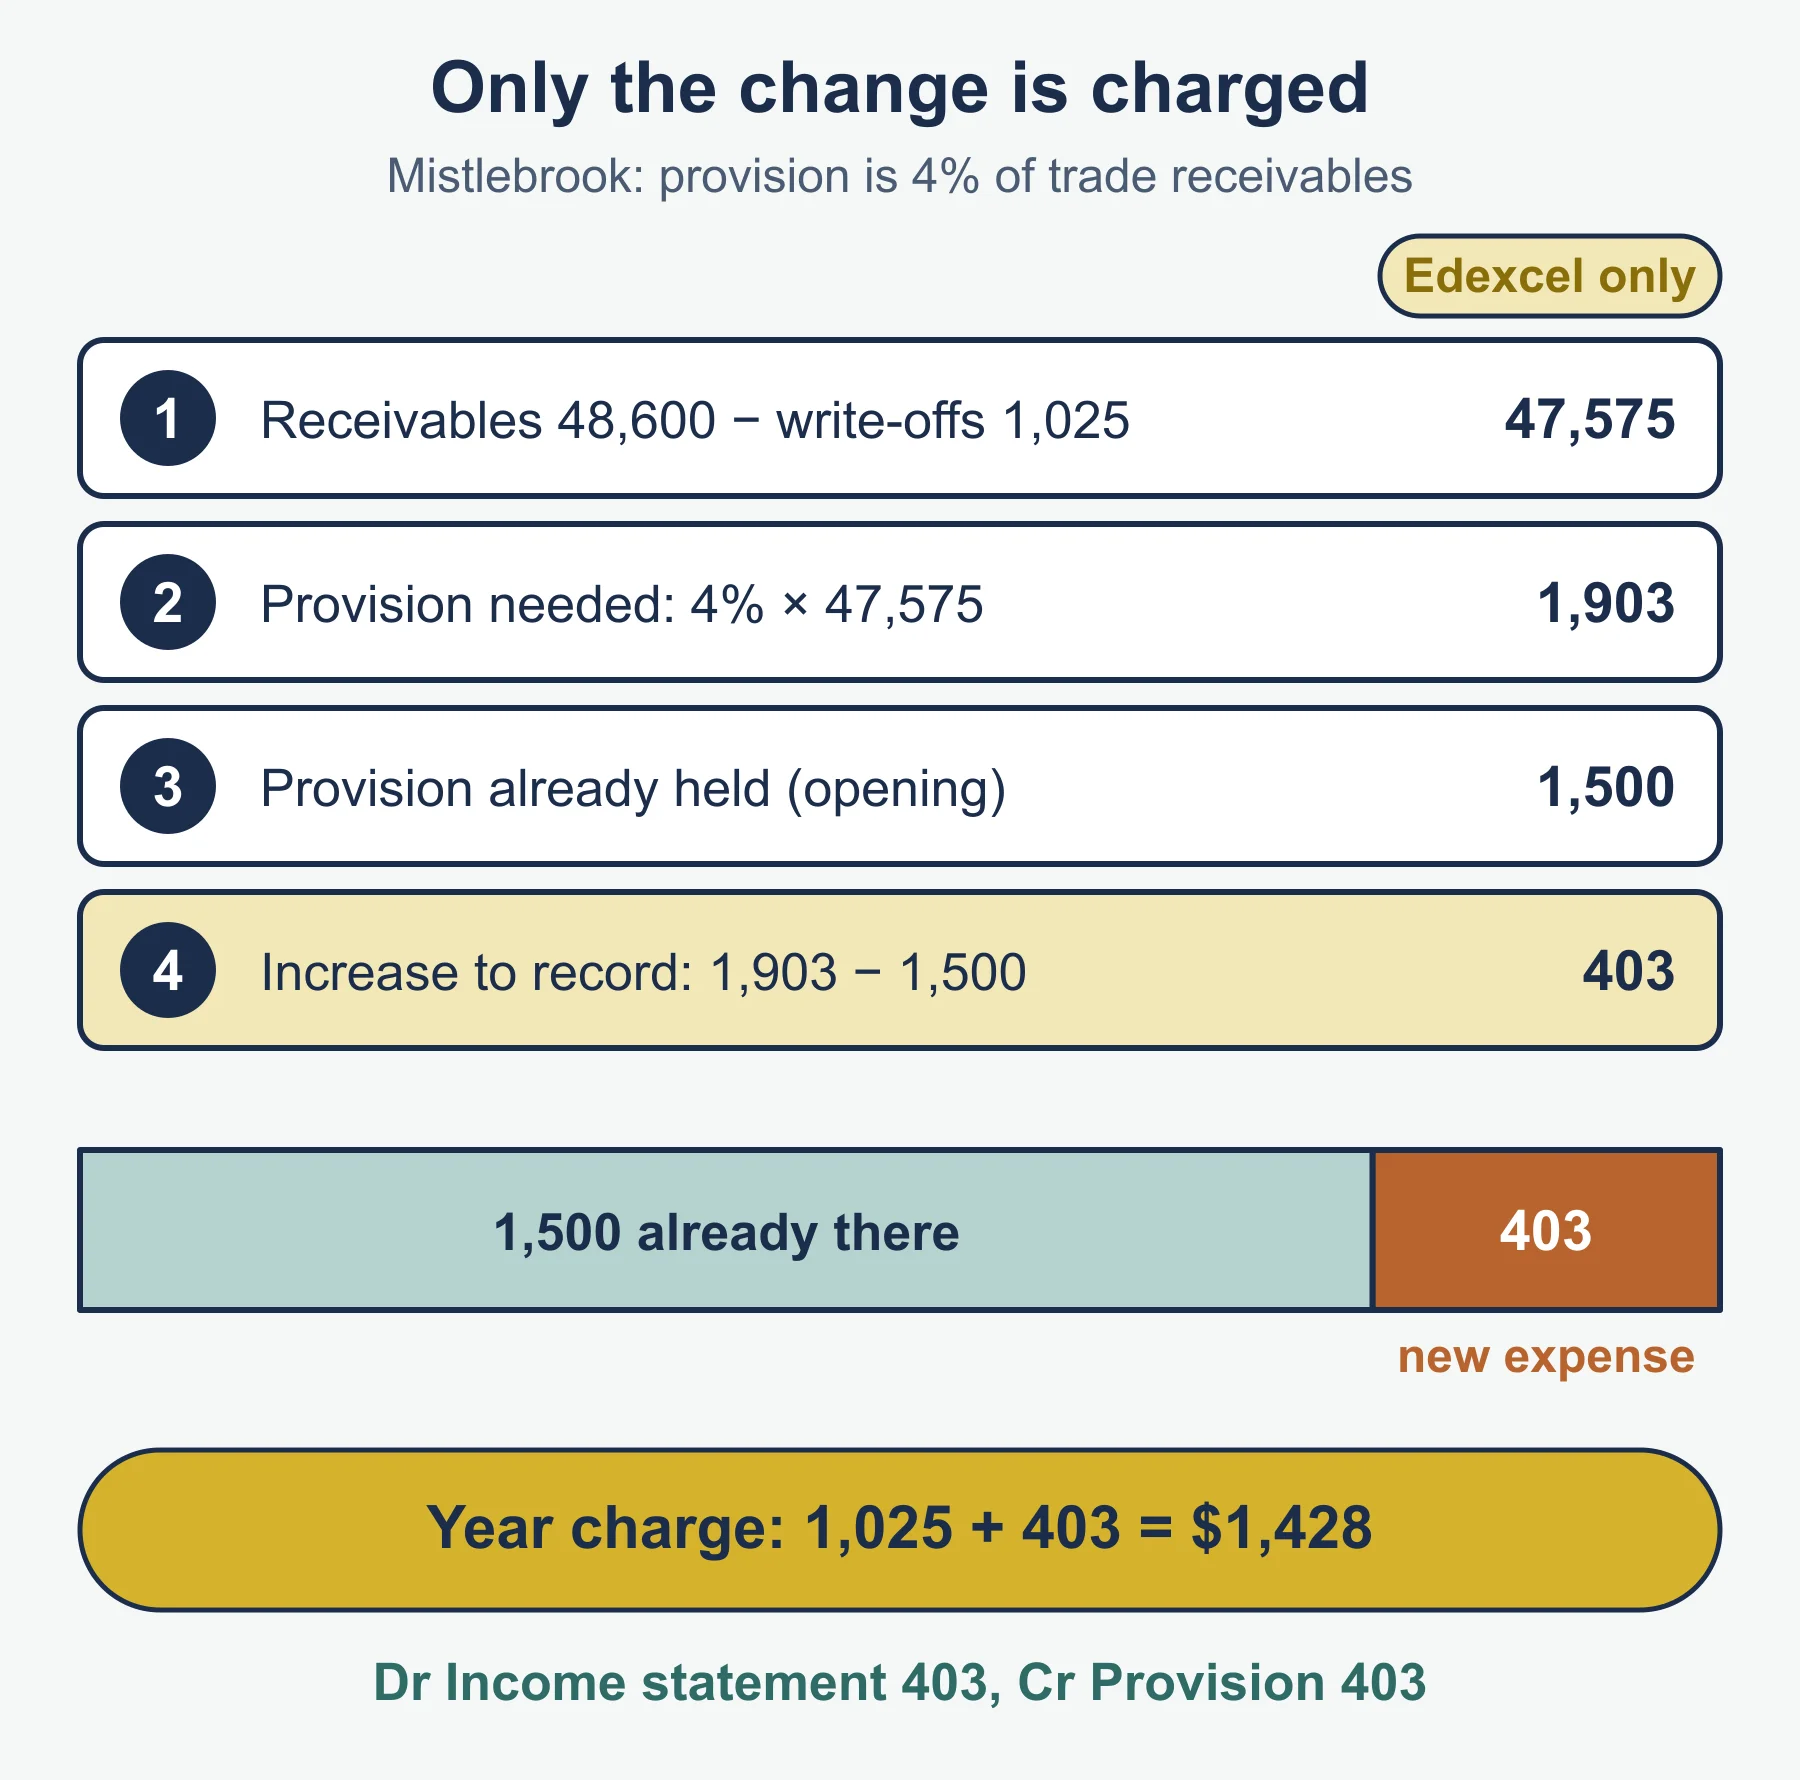
Mistlebrook’s receivables ledger totals 48,600 before the write-offs. The provision is 4% of trade receivables, and the provision account already holds a credit balance of 1,500.
Trade receivables after write-offs  48,600 - 1,025 = 47,575
Provision required                  4% x 47,575    = 1,903
Opening provision                                    1,500
Increase needed                     1,903 - 1,500  =   403
An increase is an extra expense: Dr Income statement (increase in provision), Cr Provision for irrecoverable debts.
            Provision for irrecoverable debts account
2027                          2027
31 Dec Balance c/d      1,903  1 Jan  Opening balance   1,500
                               31 Dec Income statement   403
                        1,903                          1,903
                               2028
                               1 Jan  Balance b/d      1,903
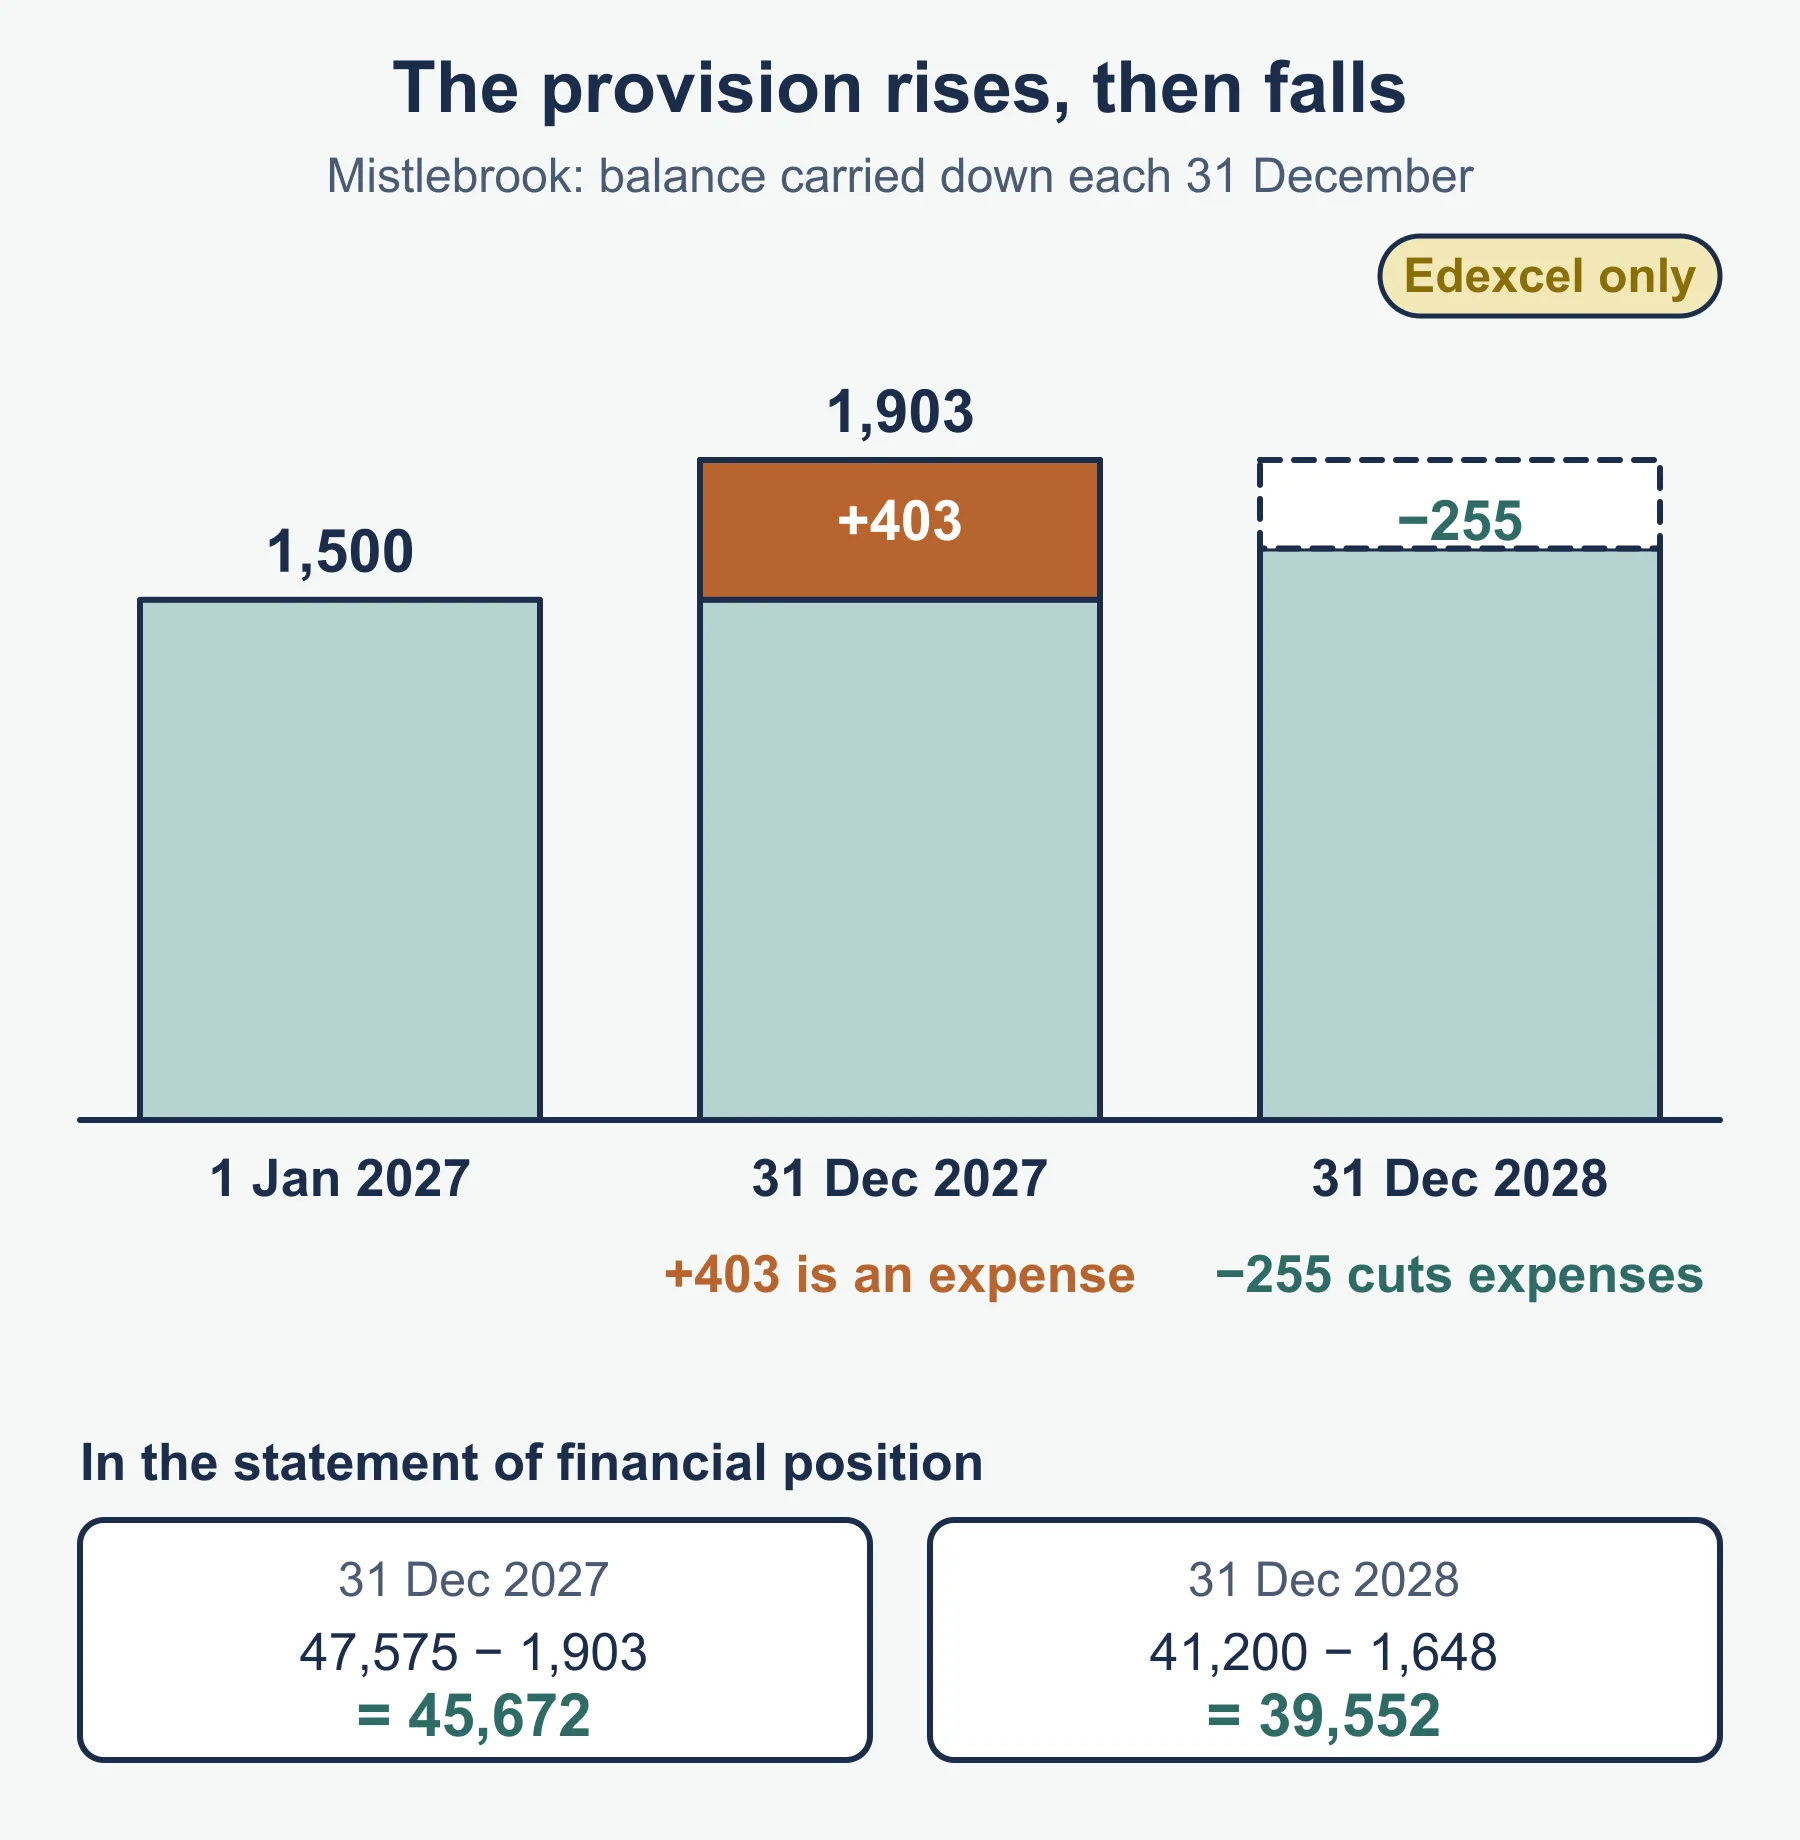
The year’s total charge for irrecoverable debts is 1,025 + 403 = 1,428. In the statement of financial position, current assets show:
Trade receivables               47,575
Less provision for irrecoverable debts  (1,903)
                                45,672
In 2028 trade receivables after write-offs are 41,200, so the provision required is 4% x 41,200 = 1,648. The opening balance of 1,903 is too high by 255. A decrease is recorded the other way round: Dr Provision for irrecoverable debts 255, Cr Income statement 255. It reduces the expenses, or is shown as income, and the net amount in the statement of financial position is 41,200 - 1,648 = 39,552.
If the business had no provision at all before, the whole new provision is the charge. If the required provision equals the opening balance, no entry is made.
Other receivables and other payables (2.7)
Why they must be accounted for
Cash paid or received in a year is often not the same as the cost or income of that year. The accruals concept says to match expenses and income to the period they belong to. If the year-end adjustments are missed, expenses and income are wrong, so profit is wrong, and the statement of financial position leaves out an asset or a liability that really exists.
Mistlebrook has an electricity bill for November and December of 420 that arrives after the year end. Without an accrual, the expense is 420 too low and profit is 420 too high.
The four situations
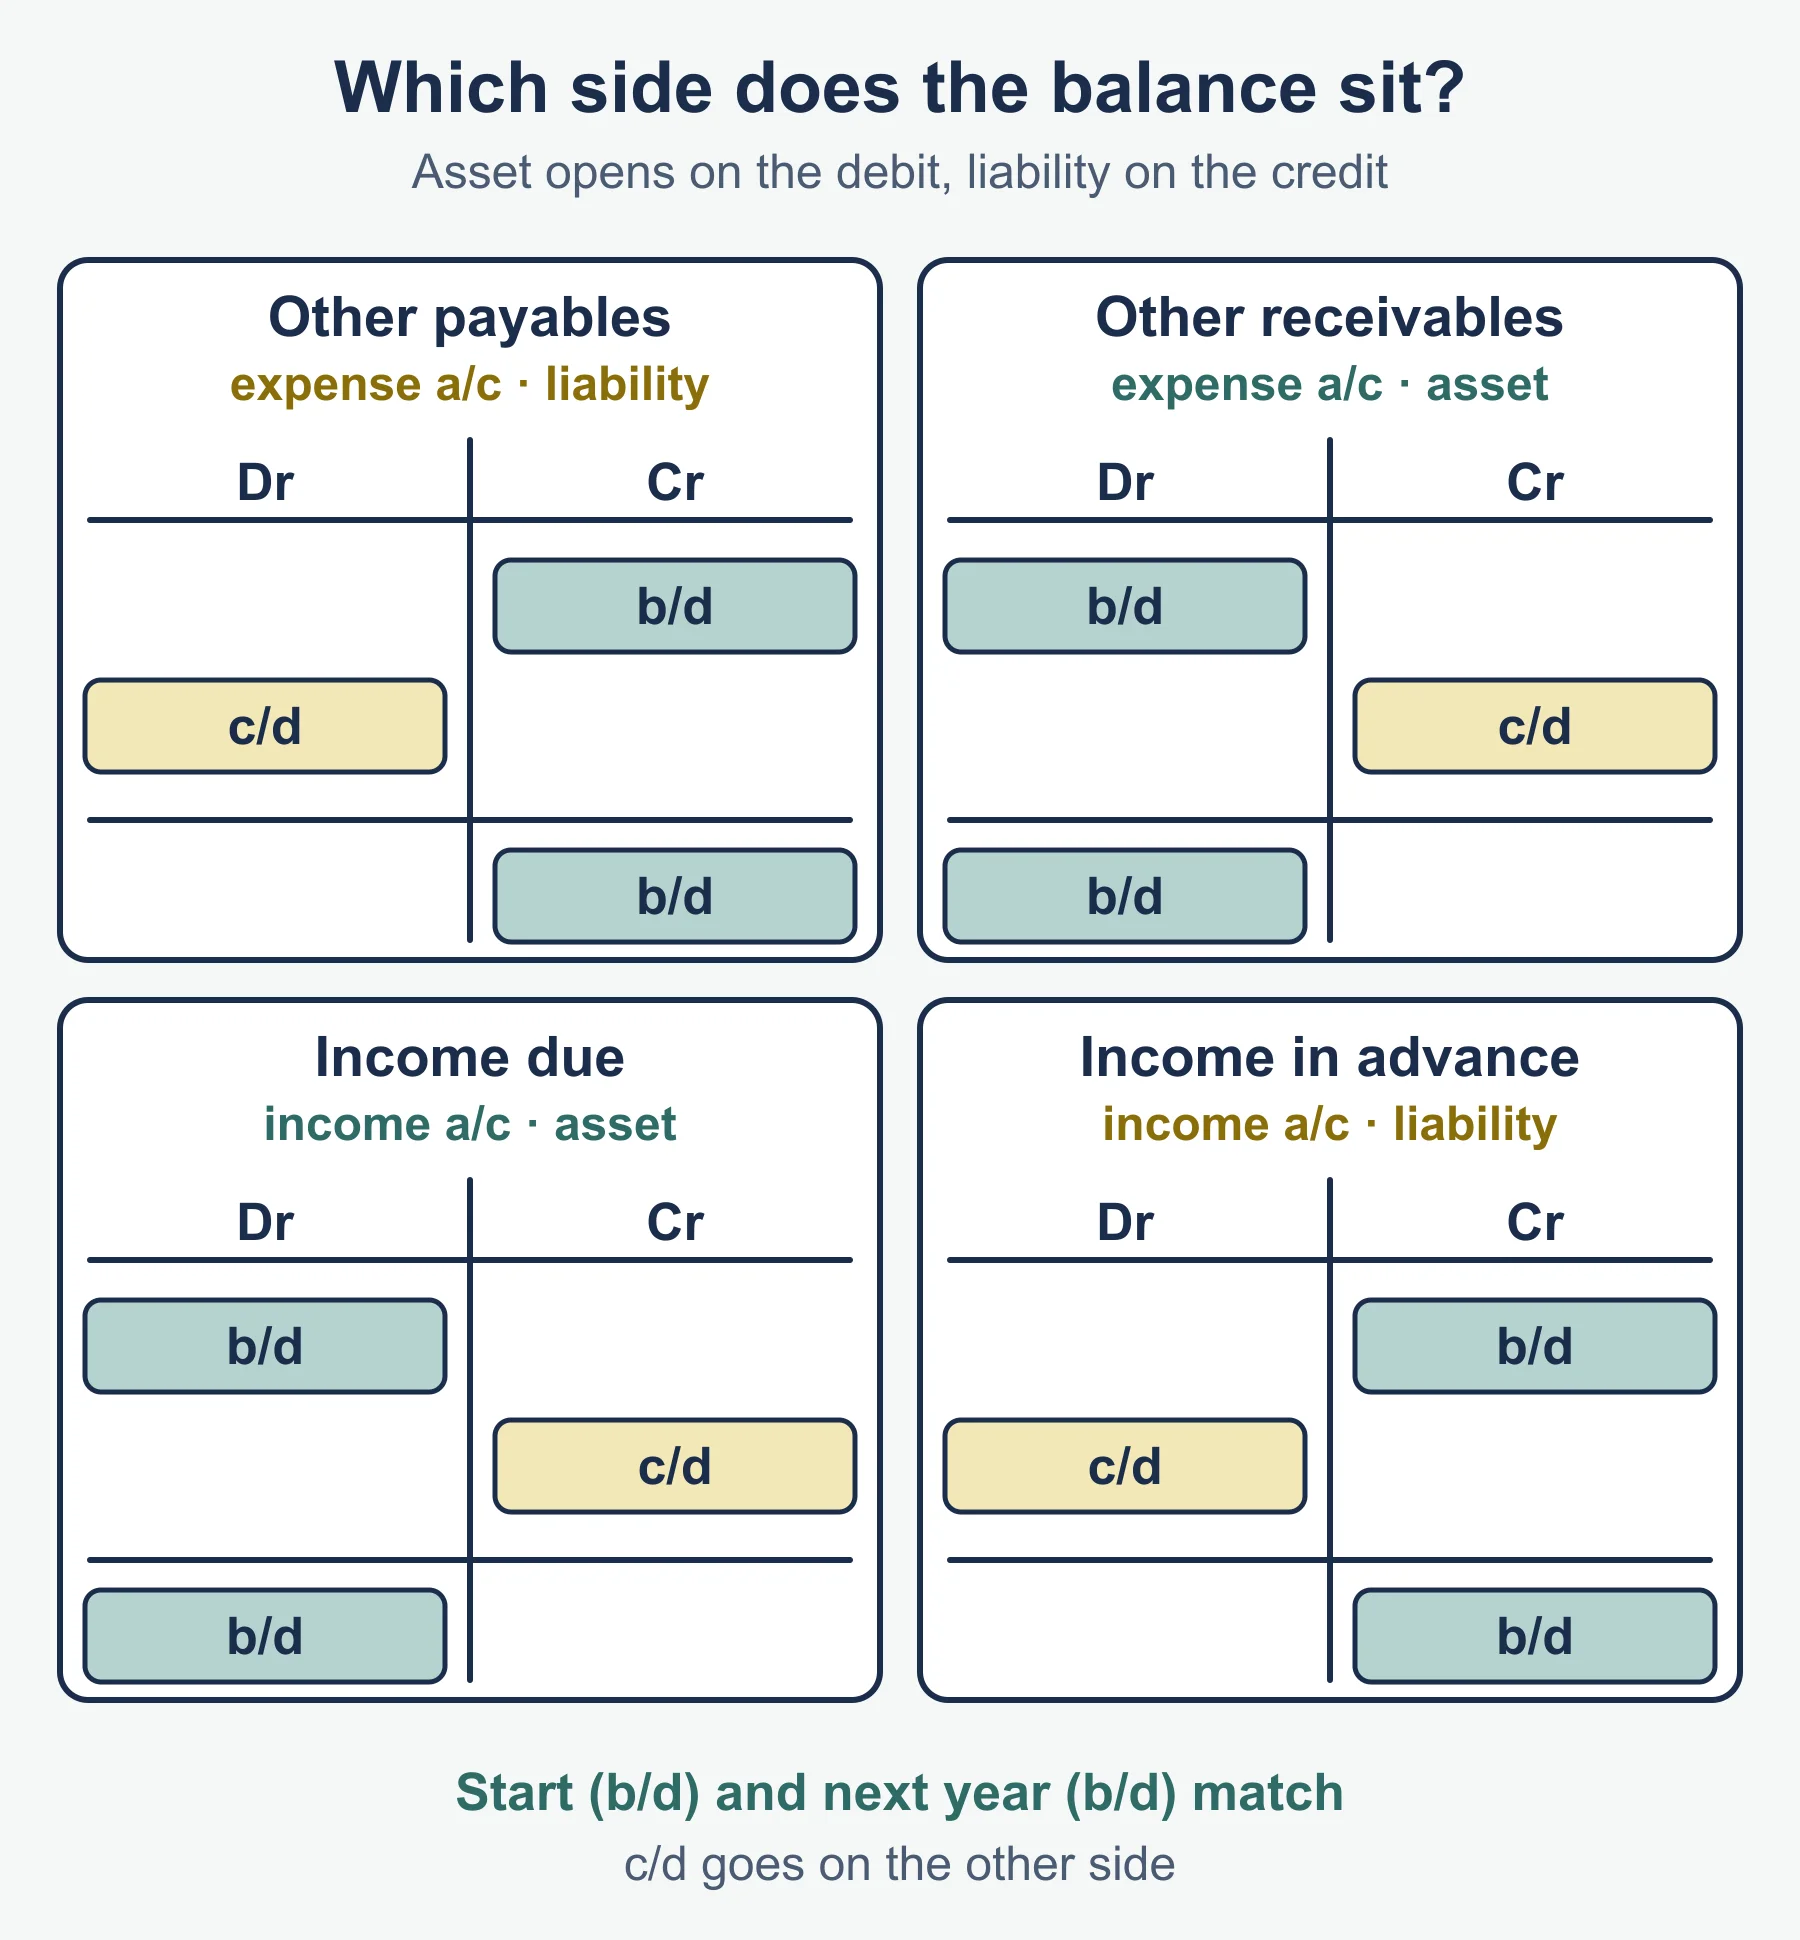
| Other payables | Other receivables | |
|---|---|---|
| Expense | Accrued expense: used, not yet paid | Prepaid expense: paid, not yet used |
| Income | Income received in advance | Accrued income: earned, not yet received |
| Statement of financial position | Current liability | Current asset |
| Balance in the account | Credit | Debit |
The distinction is simple. Other payables are sums the business owes for things other than goods bought for resale. Other receivables are amounts owed to the business, or paid ahead by it, that are not from trade customers. The specification words these only in general terms, so treat both expenses and incomes as in scope.
Calculating the amount for the income statement
For an expense:
Expense for the year = cash paid
                       - opening accrual     + closing accrual
                       + opening prepayment  - closing prepayment
For income, reverse the direction: add an amount owed to you at the year end, and take away income already received in advance.
Worked example 1: an accrued expense
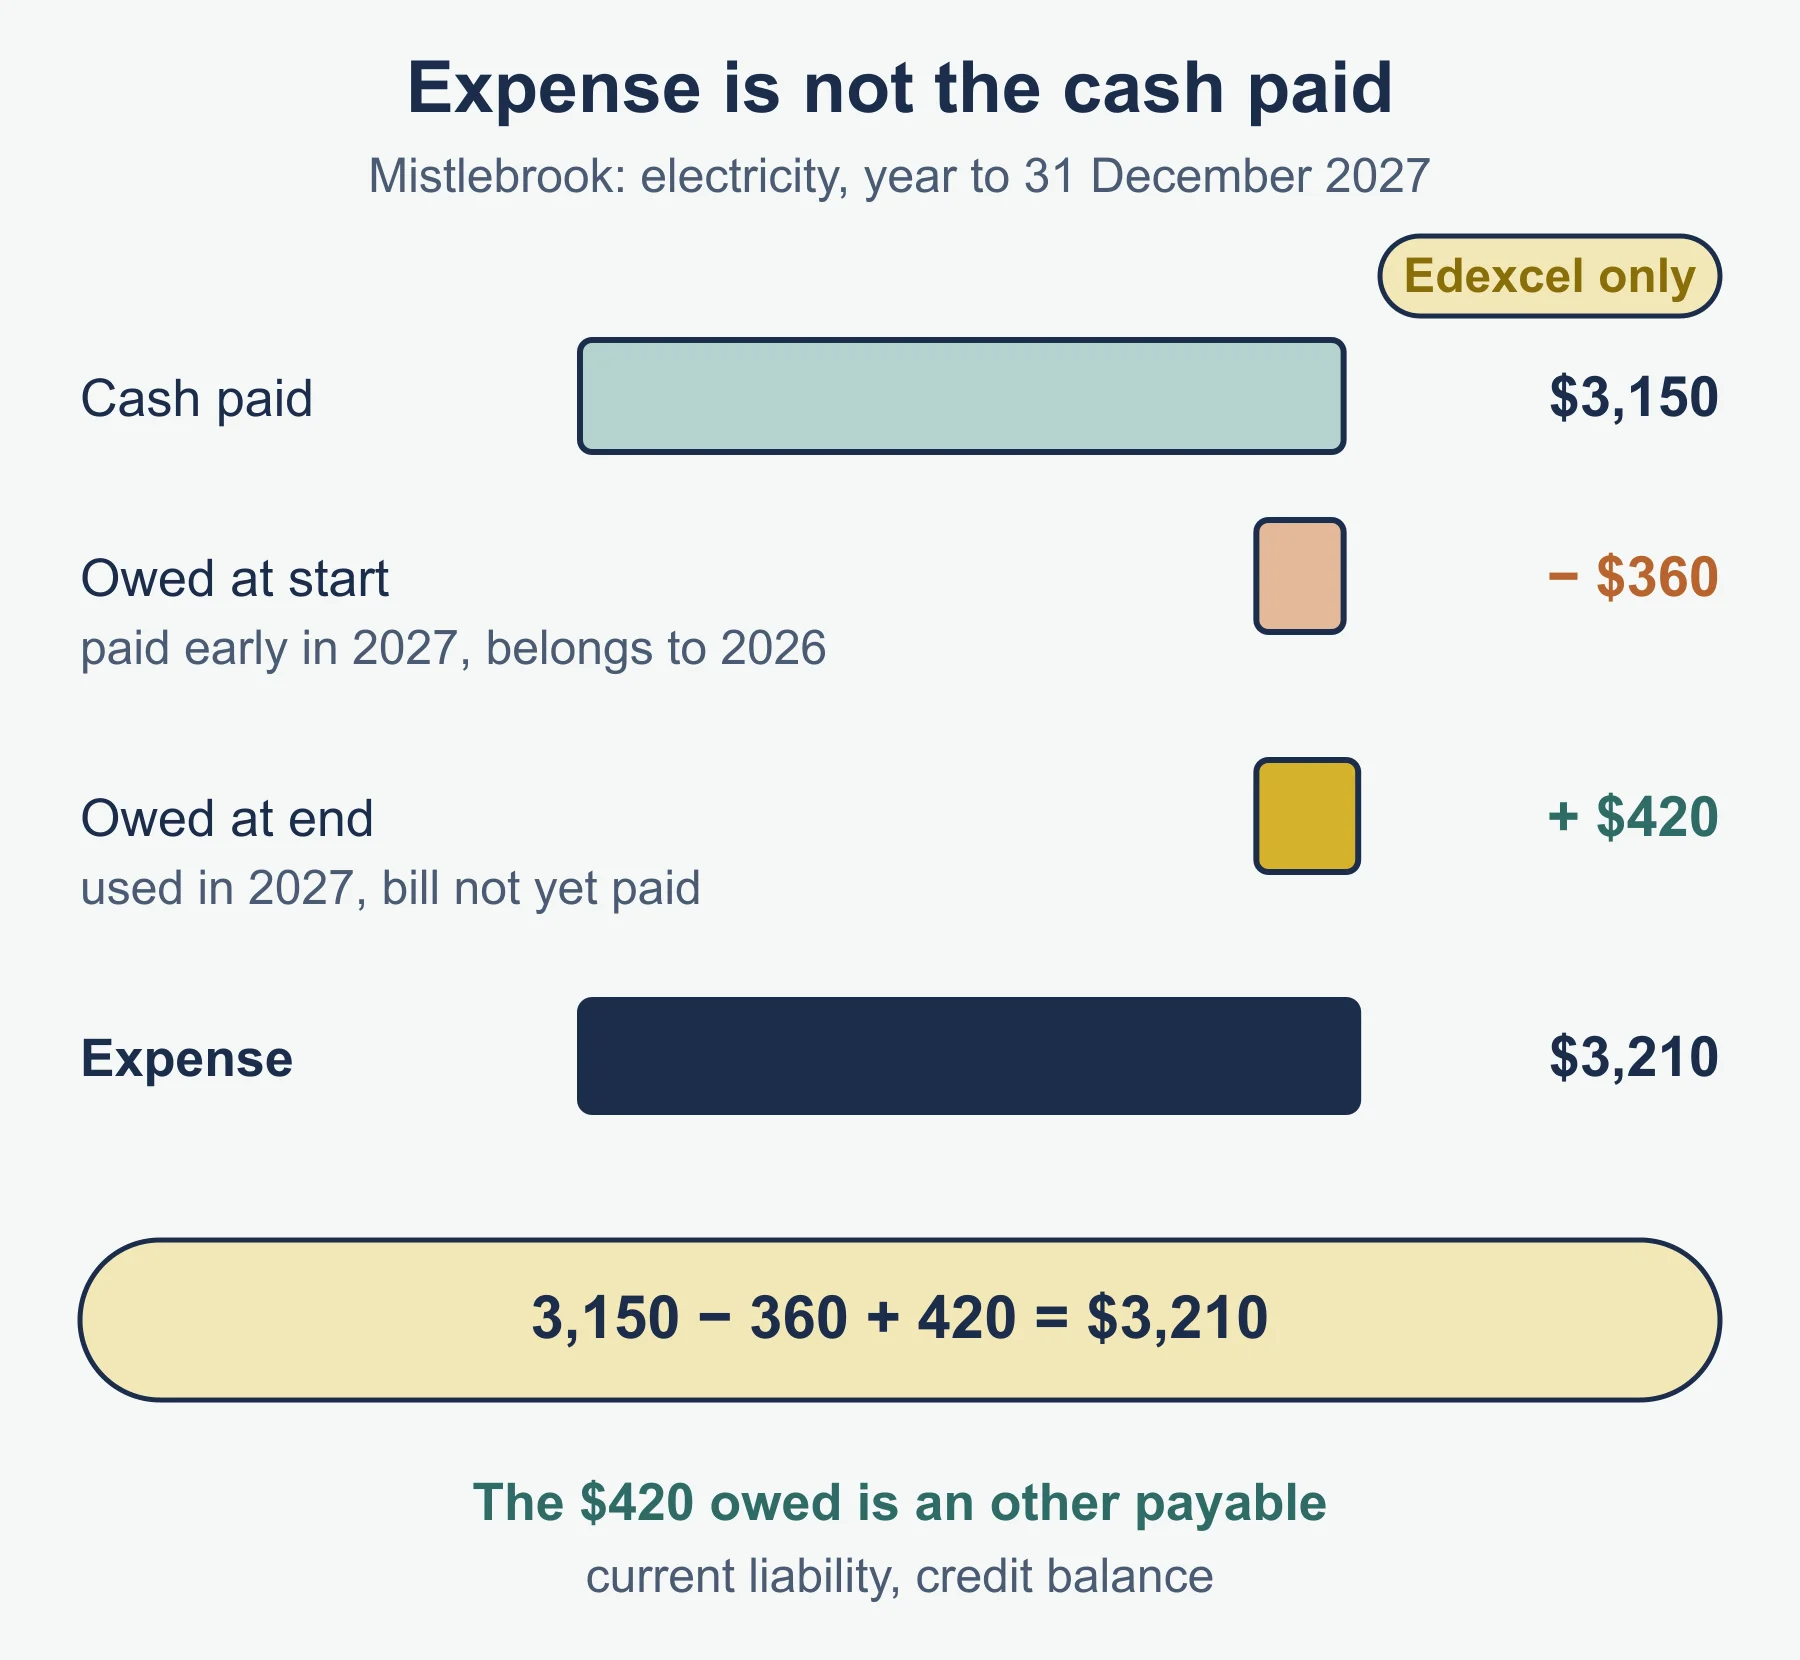
Mistlebrook paid 3,150 for electricity in 2027. The accrual at the start of the year was 360 (it was paid early in 2027), and at the year end 420 is owed.
Charge = 3,150 - 360 + 420 = 3,210 Electricity account
2027 2027
Bank (paid in year) 3,150 1 Jan Balance b/d (owed) 360
31 Dec Balance c/d (owed) 420 31 Dec Income statement 3,210
3,570 3,570
2028
1 Jan Opening balance (owed) 420The accrued amounts are carried down on the debit side because the account needs a credit balance to show a liability. Check the totals: 3,150 + 420 = 3,570 and 360 + 3,210 = 3,570. The 420 appears under other payables in current liabilities.
Worked example 2: a prepaid expense with time apportionment
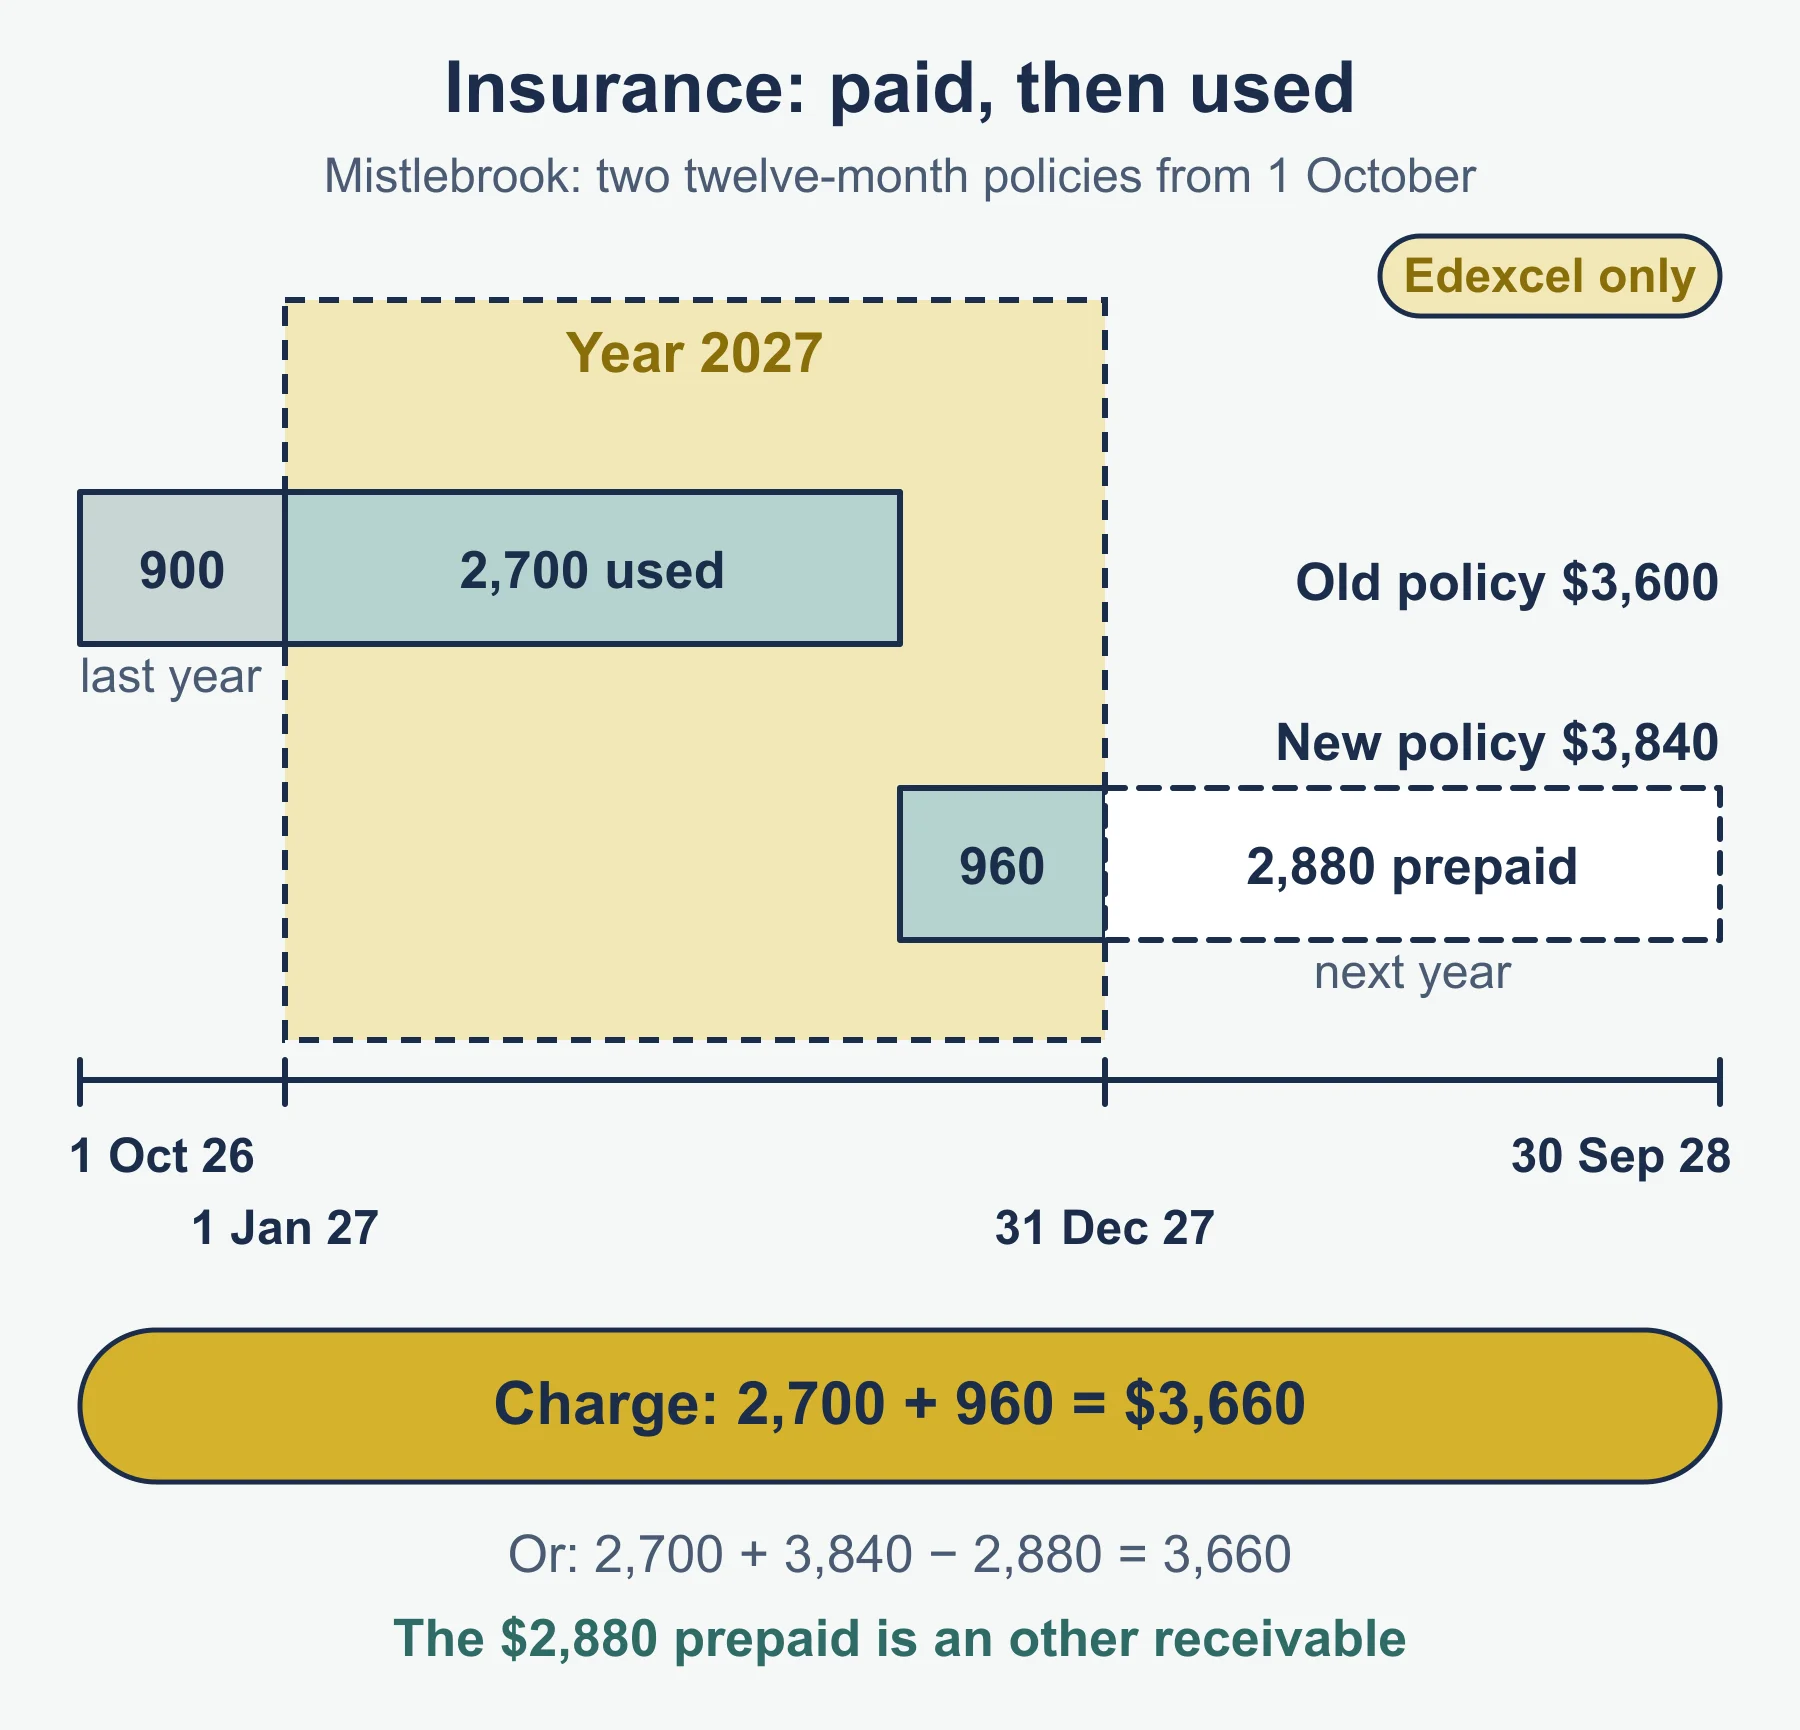
The old insurance policy was paid on 1 October 2026 for 3,600 for twelve months, so at 1 January 2027 nine months were prepaid: 3,600 x 9/12 = 2,700. A new policy costing 3,840 was paid on 1 October 2027 for twelve months. At 31 December 2027 three months have been used, so nine months are prepaid: 3,840 / 12 x 9 = 2,880.
Charge = 2,700 + 3,840 - 2,880 = 3,660
Check: old policy Jan-Sep 2,700 + new policy Oct-Dec (3 x 320 = 960) = 3,660
Insurance account
2027 2027
1 Jan Balance b/d 2,700 31 Dec Income statement 3,660
1 Oct Bank 3,840 31 Dec Balance c/d 2,880
6,540 6,540
2028
1 Jan Balance b/d 2,880The 2,880 is an other receivable (a current asset).
Worked example 3: accrued income
Mistlebrook lets a spare storeroom. It received 7,200 of rent in 2027, and the tenant still owes 600 for the final month. Income earned is 7,200 + 600 = 7,800.
                  Rent received account
2027                          2027
31 Dec Income statement 7,800  Bank                     7,200
                               31 Dec Balance c/d         600
                        7,800                           7,800
2028
1 Jan  Balance b/d        600
The balance carried down is a debit of 600, so it is written on the credit side to balance the account and brought down on the debit side. It is an other receivable. If a tenant had paid ahead instead, the balance would be a credit and the amount would be an other payable (income received in advance).
At the start of the next period the opening balance stays in the same account. Cash received later clears the opening balance first, so only the part that belongs to the new period becomes income of that period.
Common errors
- Provision on gross receivables. Always deduct the write-offs first.
- Recording the whole provision as the charge. Only the change is charged, unless there was no opening provision.
- Treating a decrease as an expense. It reduces the expenses (or is income).
- Putting a prepayment among liabilities. A prepayment is an asset, an accrual a liability.
- Using the wrong sign in the formula. Add a closing accrual, take away a closing prepayment.
- Calculating the provision on other receivables. The provision relates only to trade receivables.
- Writing a bare figure. Label each closing balance (other receivables, other payables, trade receivables less provision) so the reader can see what the number is.
Next steps
Revise from the revision notes, then test yourself on the practice questions or take a free diagnostic. The course hub lists the rest of the 4AC1 pages.
Frequently asked questions
When is a debt written off as irrecoverable? A debt is written off when the business decides a particular amount will not be received, for example because the customer is bankrupt or has disappeared. The journal is debit irrecoverable debts, credit the customer’s account, and the total is an expense in the income statement.
Why does a business need a provision for irrecoverable debts? Some remaining customers are likely not to pay, but nobody knows which ones yet. A provision follows prudence and the accruals concept, and gives a realistic trade receivables figure in the statement of financial position.
How do you record a decrease in the provision for irrecoverable debts? Debit the provision for irrecoverable debts account and credit the income statement with the decrease, which increases profit. An increase is recorded the other way round, as an extra expense.
What is the difference between other receivables and other payables? Other payables are amounts the business owes for things other than goods for resale, such as accrued expenses. Other receivables are amounts owed to the business or paid in advance by it that are not from trade customers, such as prepaid expenses and accrued income.
What do the newer and older names for accruals and prepayments mean? The 4AC1 specification glossary links the names: other receivables replace “prepayments”, other payables replace “accruals”, and allowance for doubtful debt replaces “provision for doubtful debt”.
Official syllabus
Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016, published by Pearson Education Limited – Topic 2: Introduction to bookkeeping, sections 2.6 Irrecoverable debts and 2.7 Other receivables and other payables. First assessment: June 2019.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
Edexcel IGCSE Accounting: Irrecoverable debts and other receivables and other payables (4AC1) – Practice Questions
Original practice questions with worked answers for Edexcel International GCSE Accounting 4AC1 sections 2.6 and 2.7: provisions, accruals and prepayments.
Accounting · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Accounting: Irrecoverable debts and other receivables and other payables (4AC1) – Revision Notes
Condensed revision notes for Edexcel International GCSE Accounting 4AC1 sections 2.6 and 2.7: irrecoverable debts, provisions, accruals and prepayments.
Accounting · Pearson Edexcel · IGCSE
Revise topic -
Study guides
Edexcel IGCSE Accounting: Ledger accounting (4AC1)
Study guide to ledger accounting for Pearson Edexcel IGCSE Accounting: the three ledgers, debit and credit rules, balancing, with worked examples.
Accounting · Pearson Edexcel · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Accounting teachers at Marlbridge

