
Study Guides
Edexcel IGCSE Accounting: Ledger accounting (4AC1)
Study guide to ledger accounting for Pearson Edexcel IGCSE Accounting: the three ledgers, debit and credit rules, balancing, with worked examples.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Introduction to bookkeeping
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Pearson Edexcel IGCSE Accounting (4AC1), Issue 1, October 2016. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Accounting.
Syllabus points this page covers
4AC1
- 2 Introduction to bookkeeping (whole topic)
- 2.3 Ledger accounting
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
This guide covers section 2.3, Ledger accounting, of Topic 2, Introduction to bookkeeping, in the Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016. The section has two points: explain the purpose of the nominal ledger, the receivables ledger and the payables ledger, and record transactions in ledger accounts using double entry principles. The specification lists no tiers and no paper-only markers for this content. It says Paper 1 draws exclusively from topics 1 to 3, and that Paper 2 builds on the knowledge, understanding and skills from those topics.
Links: Edexcel IGCSE Accounting course hub, printable checklist and all free 10-minute diagnostics. For condensed recall use the ledger accounting revision notes. For exam-style questions use the ledger accounting practice set.
All amounts are in dollars. Every business, person and figure in this guide is invented.
What you need to be able to do
| Ref | Specification point | Where it is taught here |
|---|---|---|
| 2.3a | Explain the purpose of the nominal ledger, the receivables ledger and the payables ledger | The three ledgers |
| 2.3b | Record transactions in ledger accounts using double entry principles | Double entry rules, layout, worked examples 1 and 2, balancing |
Why a business keeps ledgers
A transaction is first written in a book of original entry, such as a day book or the cash book (section 2.2). Ledger accounts then sort the same information by account. One page shows everything about rent, another everything about one customer. You can then see a total or a balance at any date without searching through every document. In this guide you record straight from a description of each transaction. Posting from a book of original entry uses the same debit and credit rules.
The three ledgers (2.3a)
| Ledger | What it holds | Purpose |
|---|---|---|
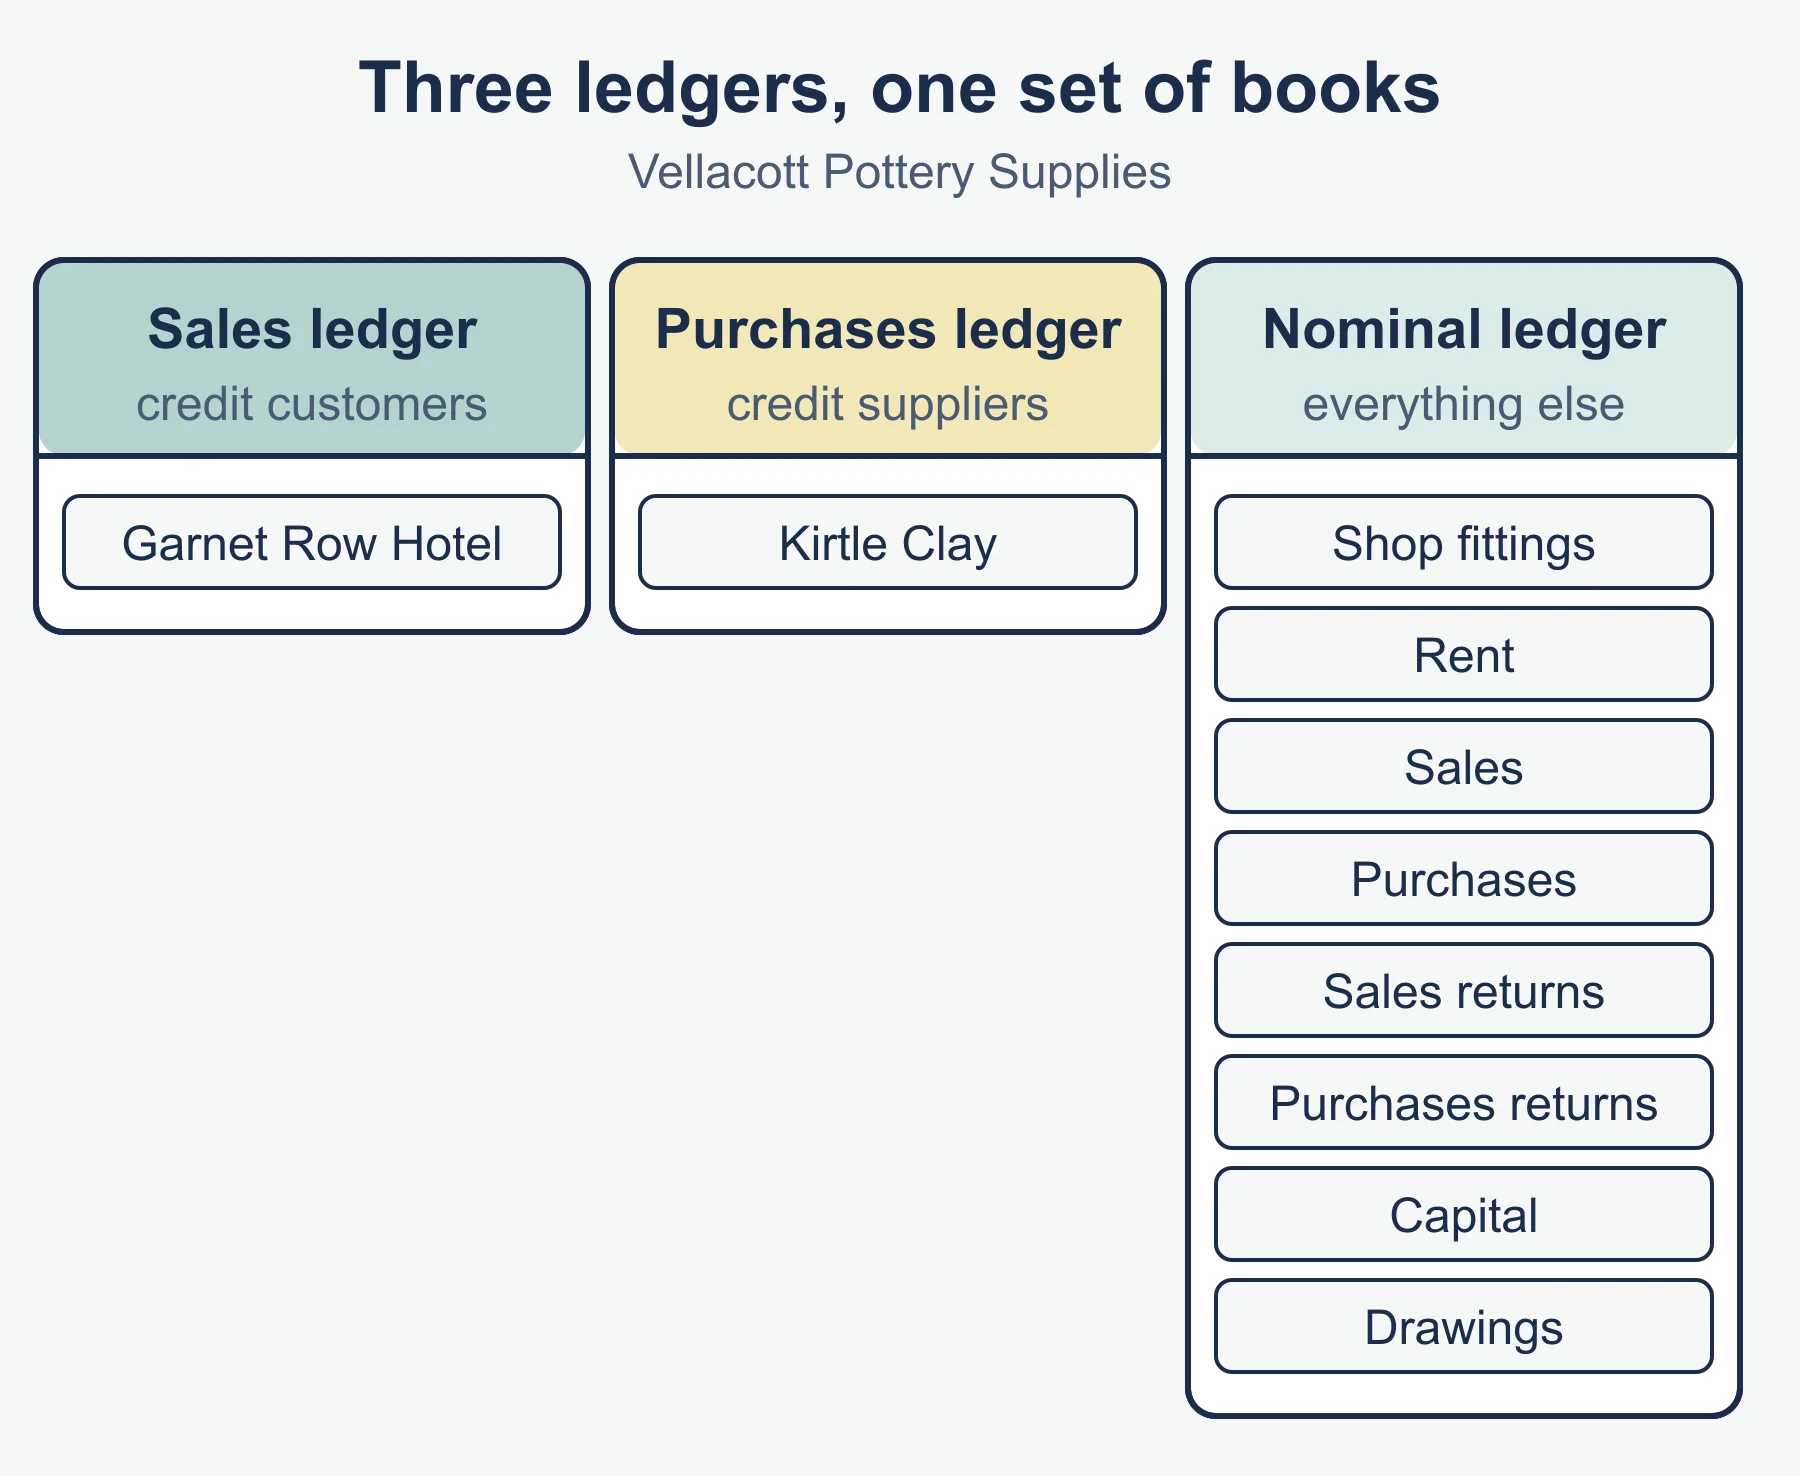
| Nominal ledger | The accounts for assets, liabilities, capital, drawings, income and expenses: bank, cash, shop fittings, loans, capital, sales, purchases, returns, rent, wages and so on | Shows the total of each type of item and the balance on each account. These are the figures later used for the trial balance and the financial statements |
| Receivables ledger | One personal account for each customer who buys on credit | Shows how much each customer owes and which invoices, returns and payments make up that balance. A business uses it to send statements of account, chase late payers and decide credit limits |
| Payables ledger | One personal account for each supplier who sells to the business on credit | Shows how much the business owes each supplier and when it is due. A business uses it to plan payments and to check supplier statements |
A cash sale has no customer account, because nobody owes the business anything. It is recorded only in the nominal ledger. The total of all the individual balances in the receivables ledger is what a trade receivables control account checks (Topic 3, section 2). The same applies to payables.
Double entry principles (2.3b)
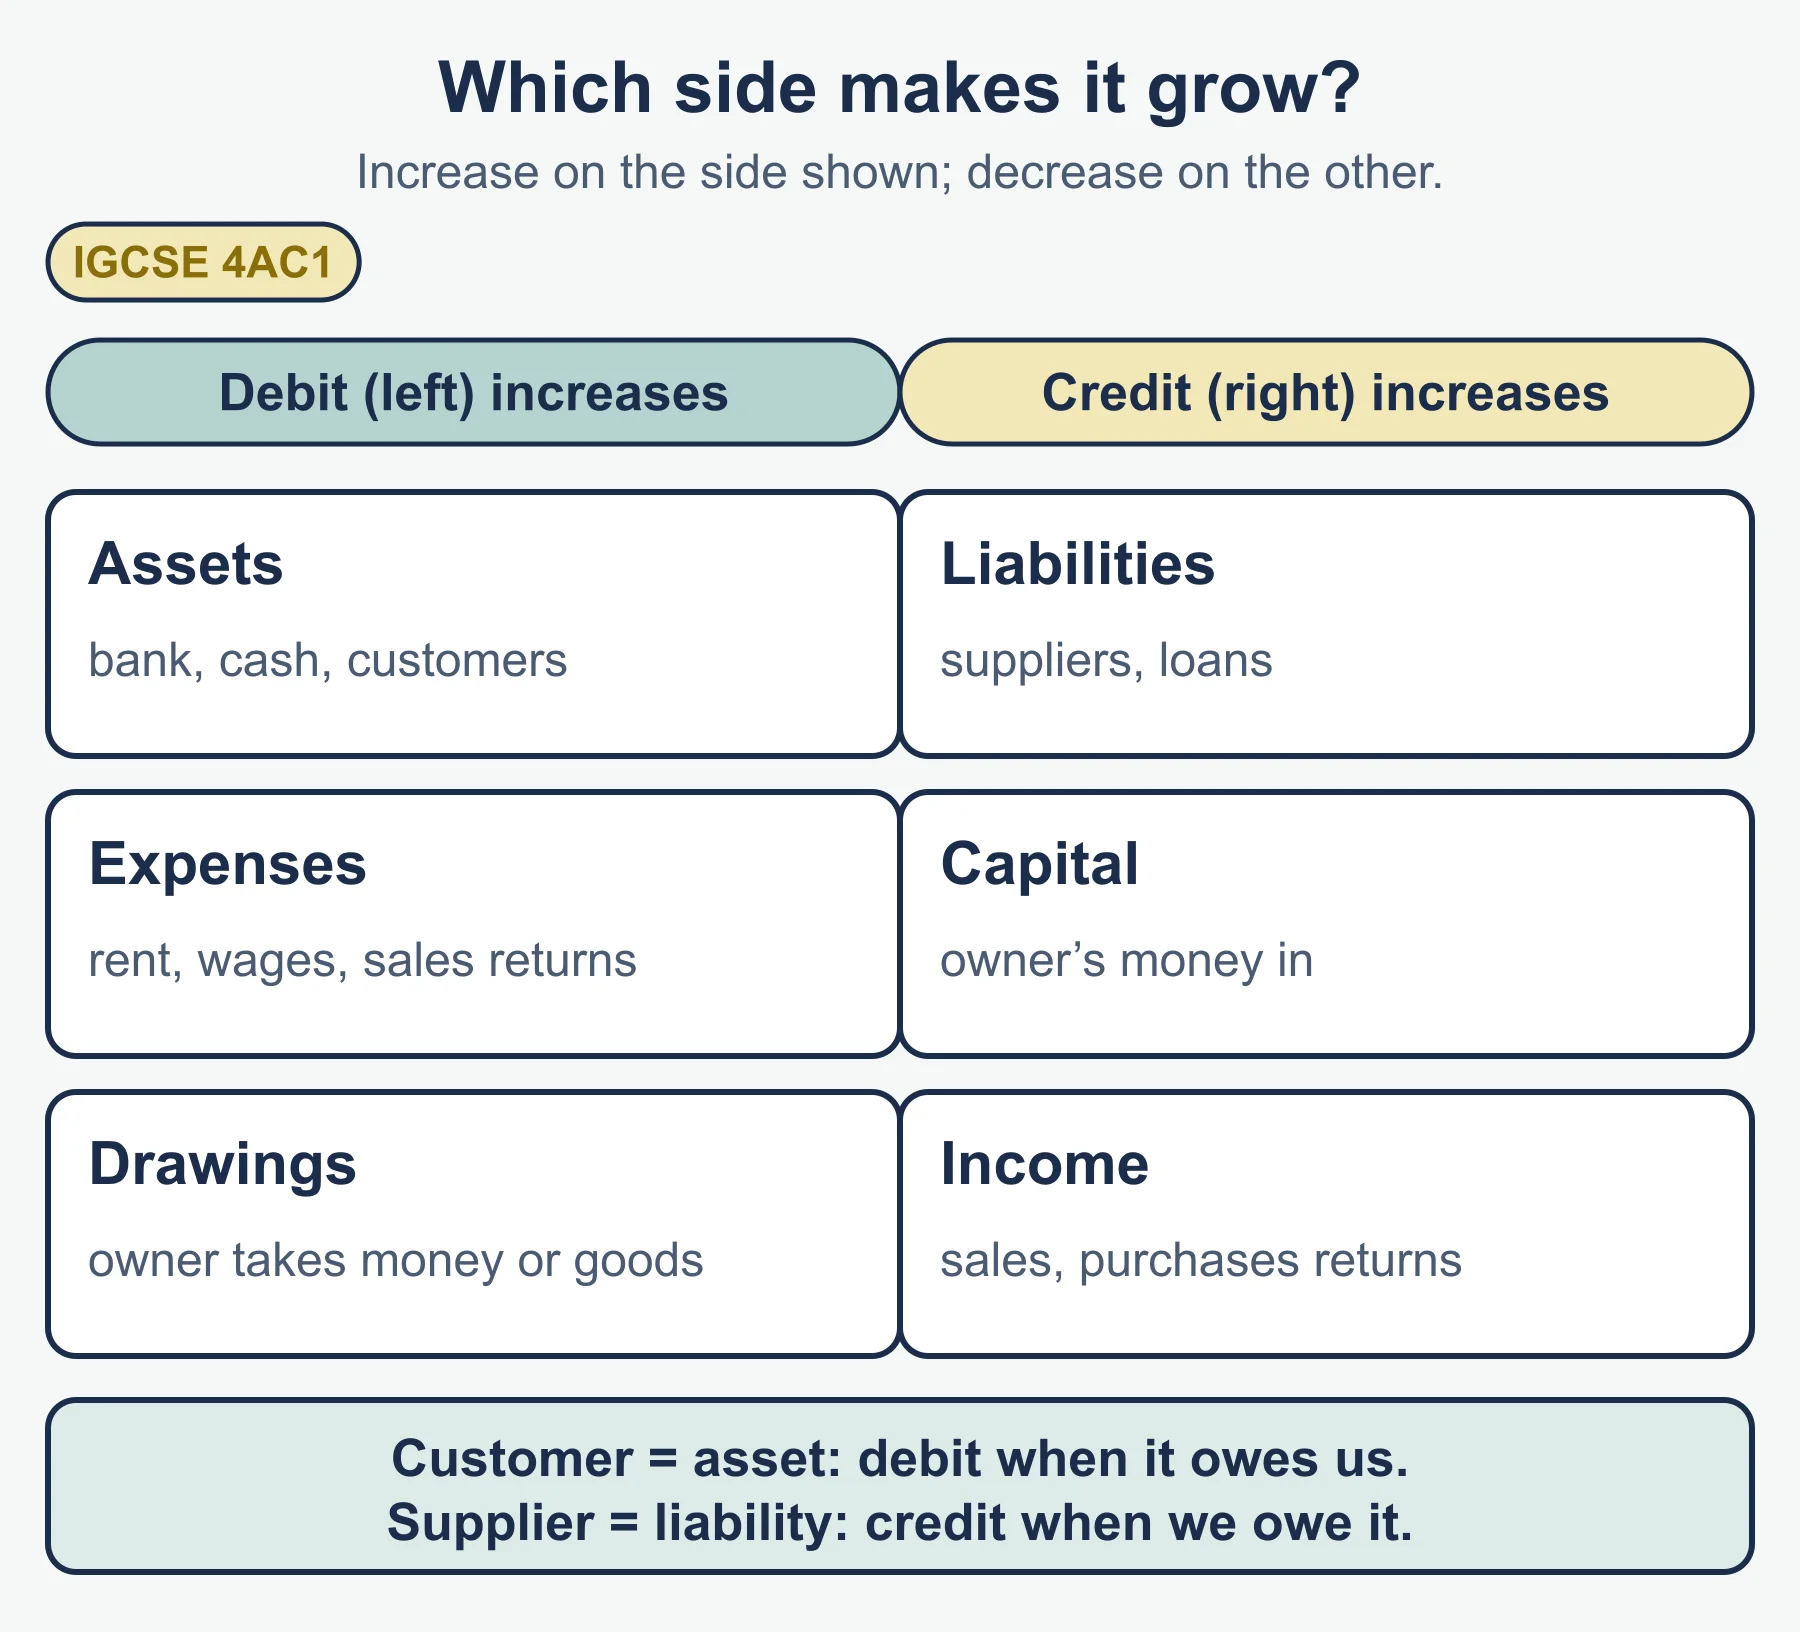
Every transaction has two effects. You debit one account (left-hand side) and credit another (right-hand side) with the same amount. The side depends on the type of account and on whether it is increasing or decreasing.
| Type of account | To increase it | To decrease it |
|---|---|---|
| Assets: bank, cash, shop fittings, customers (receivables) | Debit | Credit |
| Expenses: rent, wages, purchases, sales returns | Debit | Credit |
| Drawings | Debit | Not decreased by ordinary transactions |
| Liabilities: suppliers (payables), loans | Credit | Debit |
| Capital | Credit | Debit |
| Income: sales, purchases returns | Credit | Debit |
Use two questions for every transaction.
- Which two accounts are affected?
- Is each one increasing or decreasing, so which side does it go?
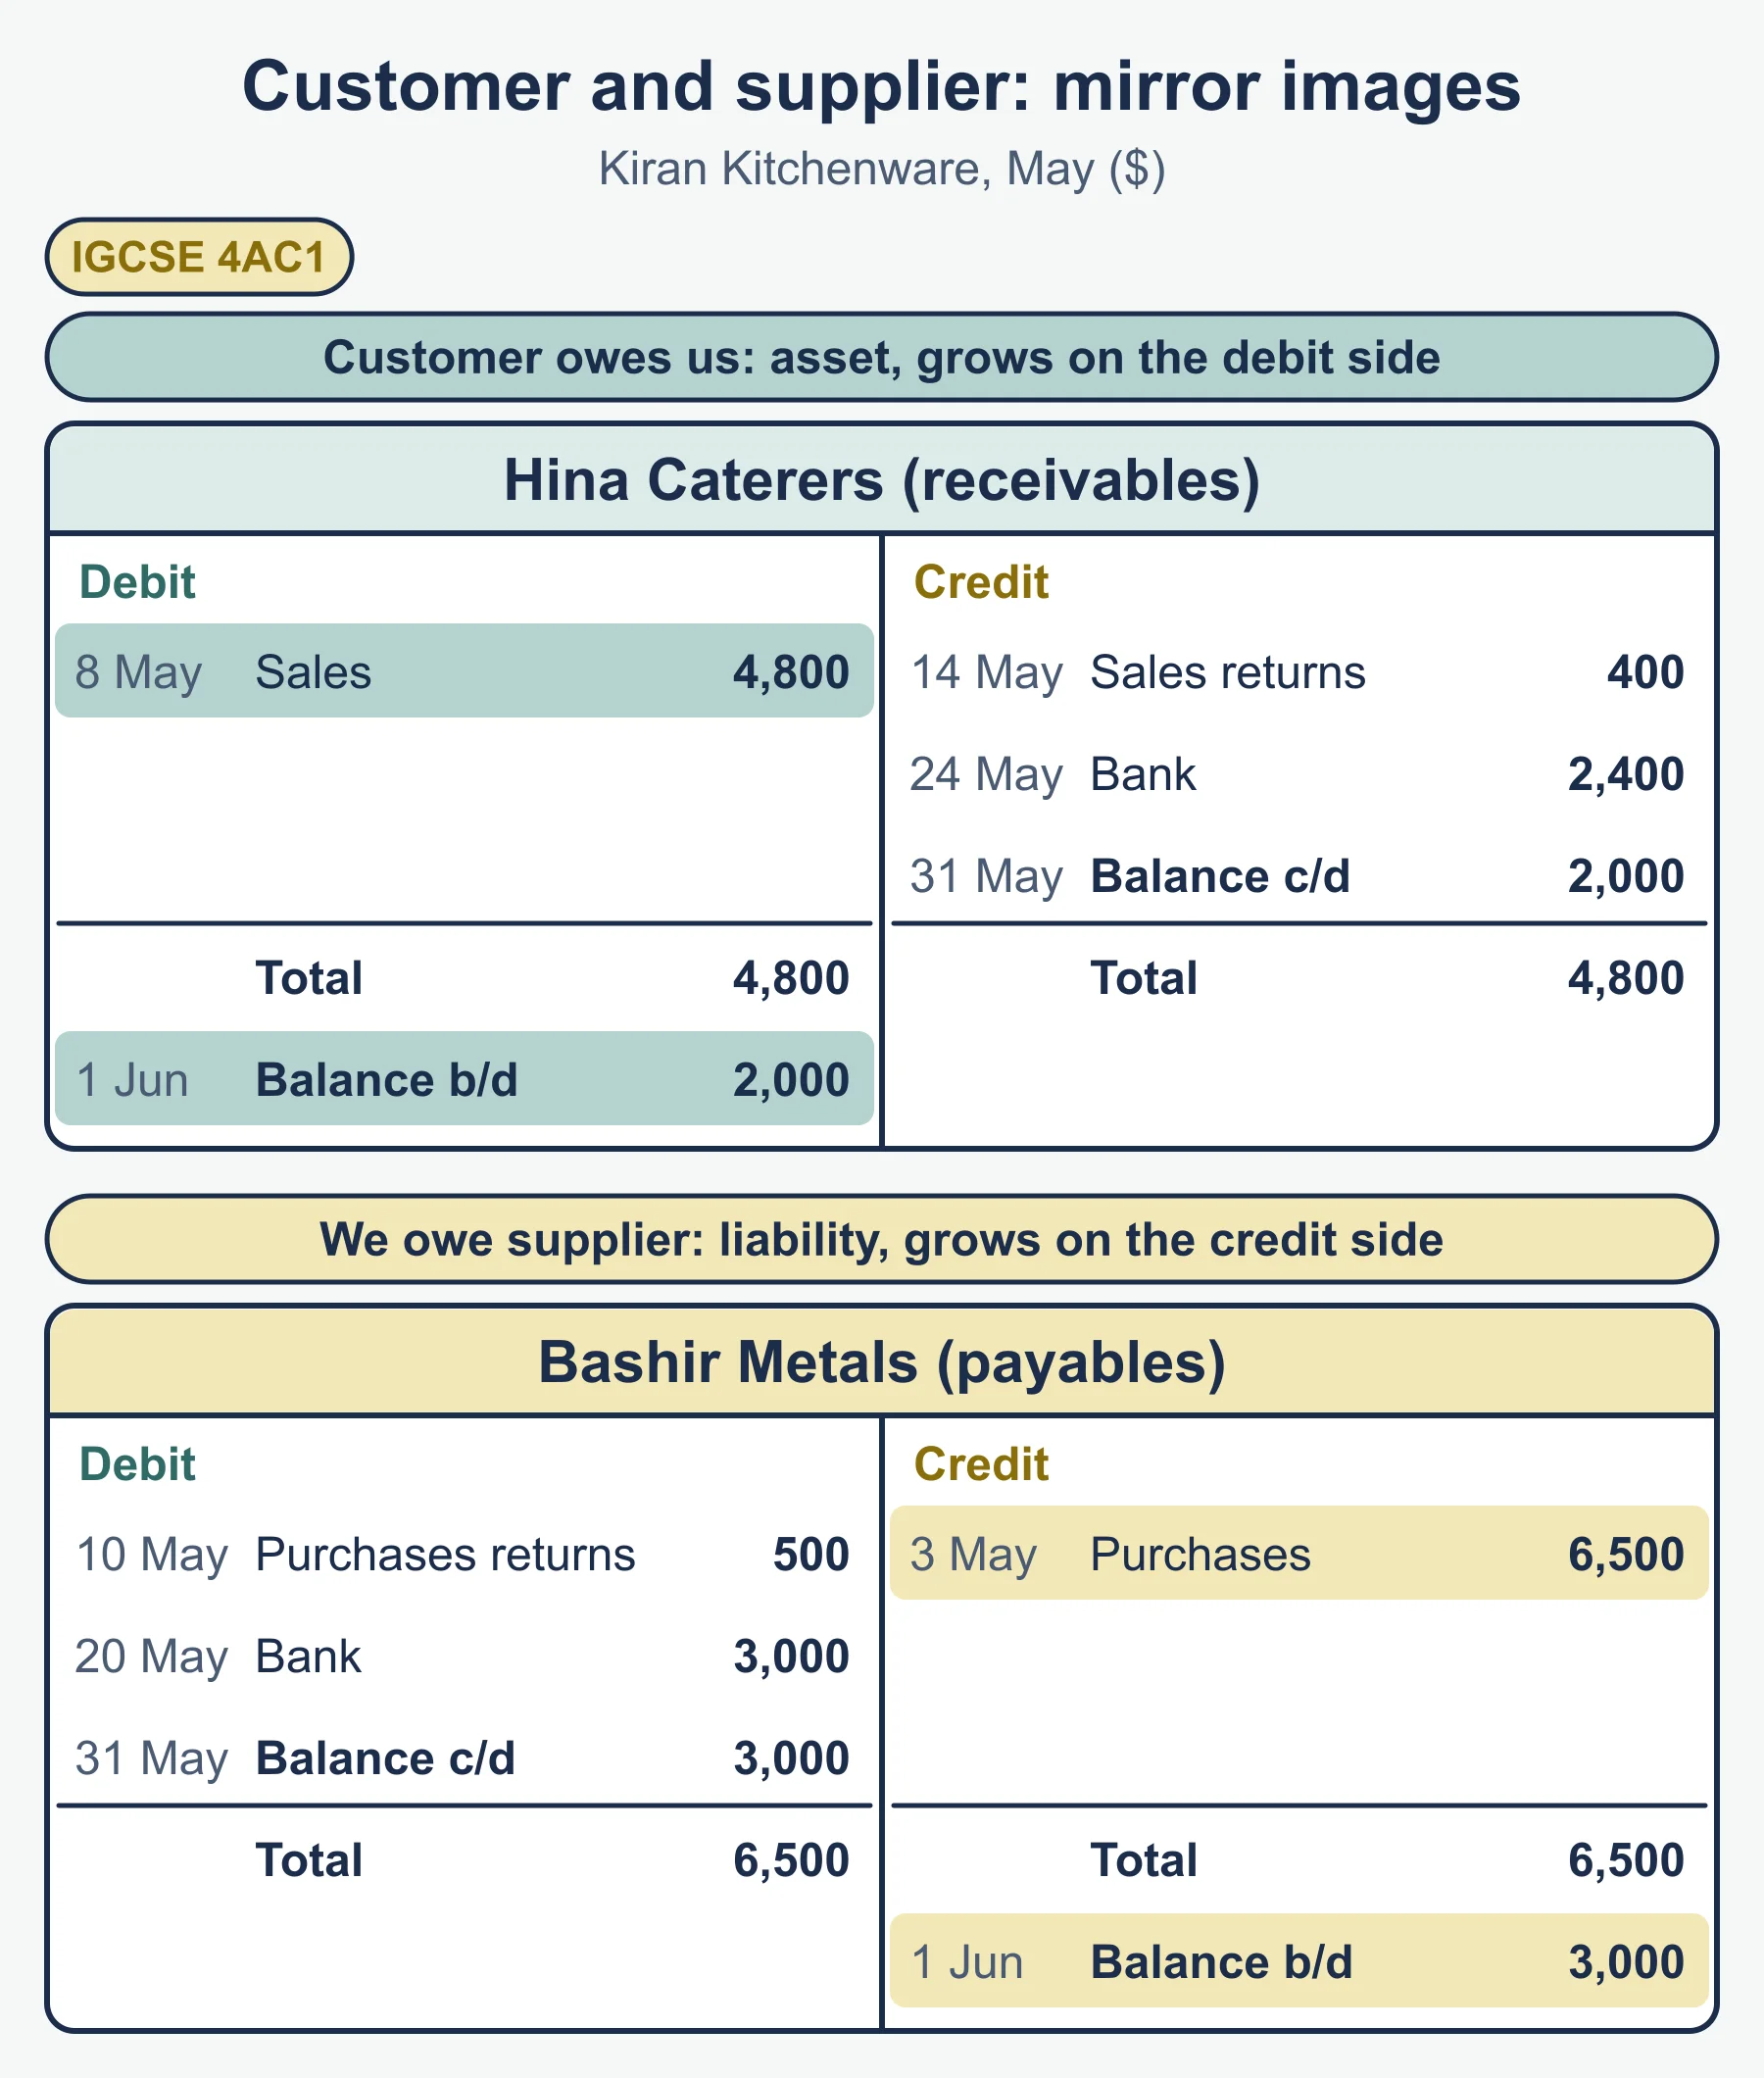
Bank and cash are assets. Money coming in is a debit and money going out is a credit. A customer owes you, so the customer account is an asset: a credit sale debits the customer and a payment from the customer credits it. A supplier is owed money, so the supplier account is a liability: a credit purchase credits the supplier and a payment to the supplier debits it.
Layout of a ledger account
Each account has a debit side on the left and a credit side on the right. Each side has a date, a details column and an amount. The details column names the other account in the double entry, never the account you are writing in. An opening balance carried over from the last period is written as Balance b/d (brought down).
Worked example 1: Kiran Kitchenware, May
Kiran starts a kitchenware shop on 1 May. Her transactions, with the two accounts for each, are below.
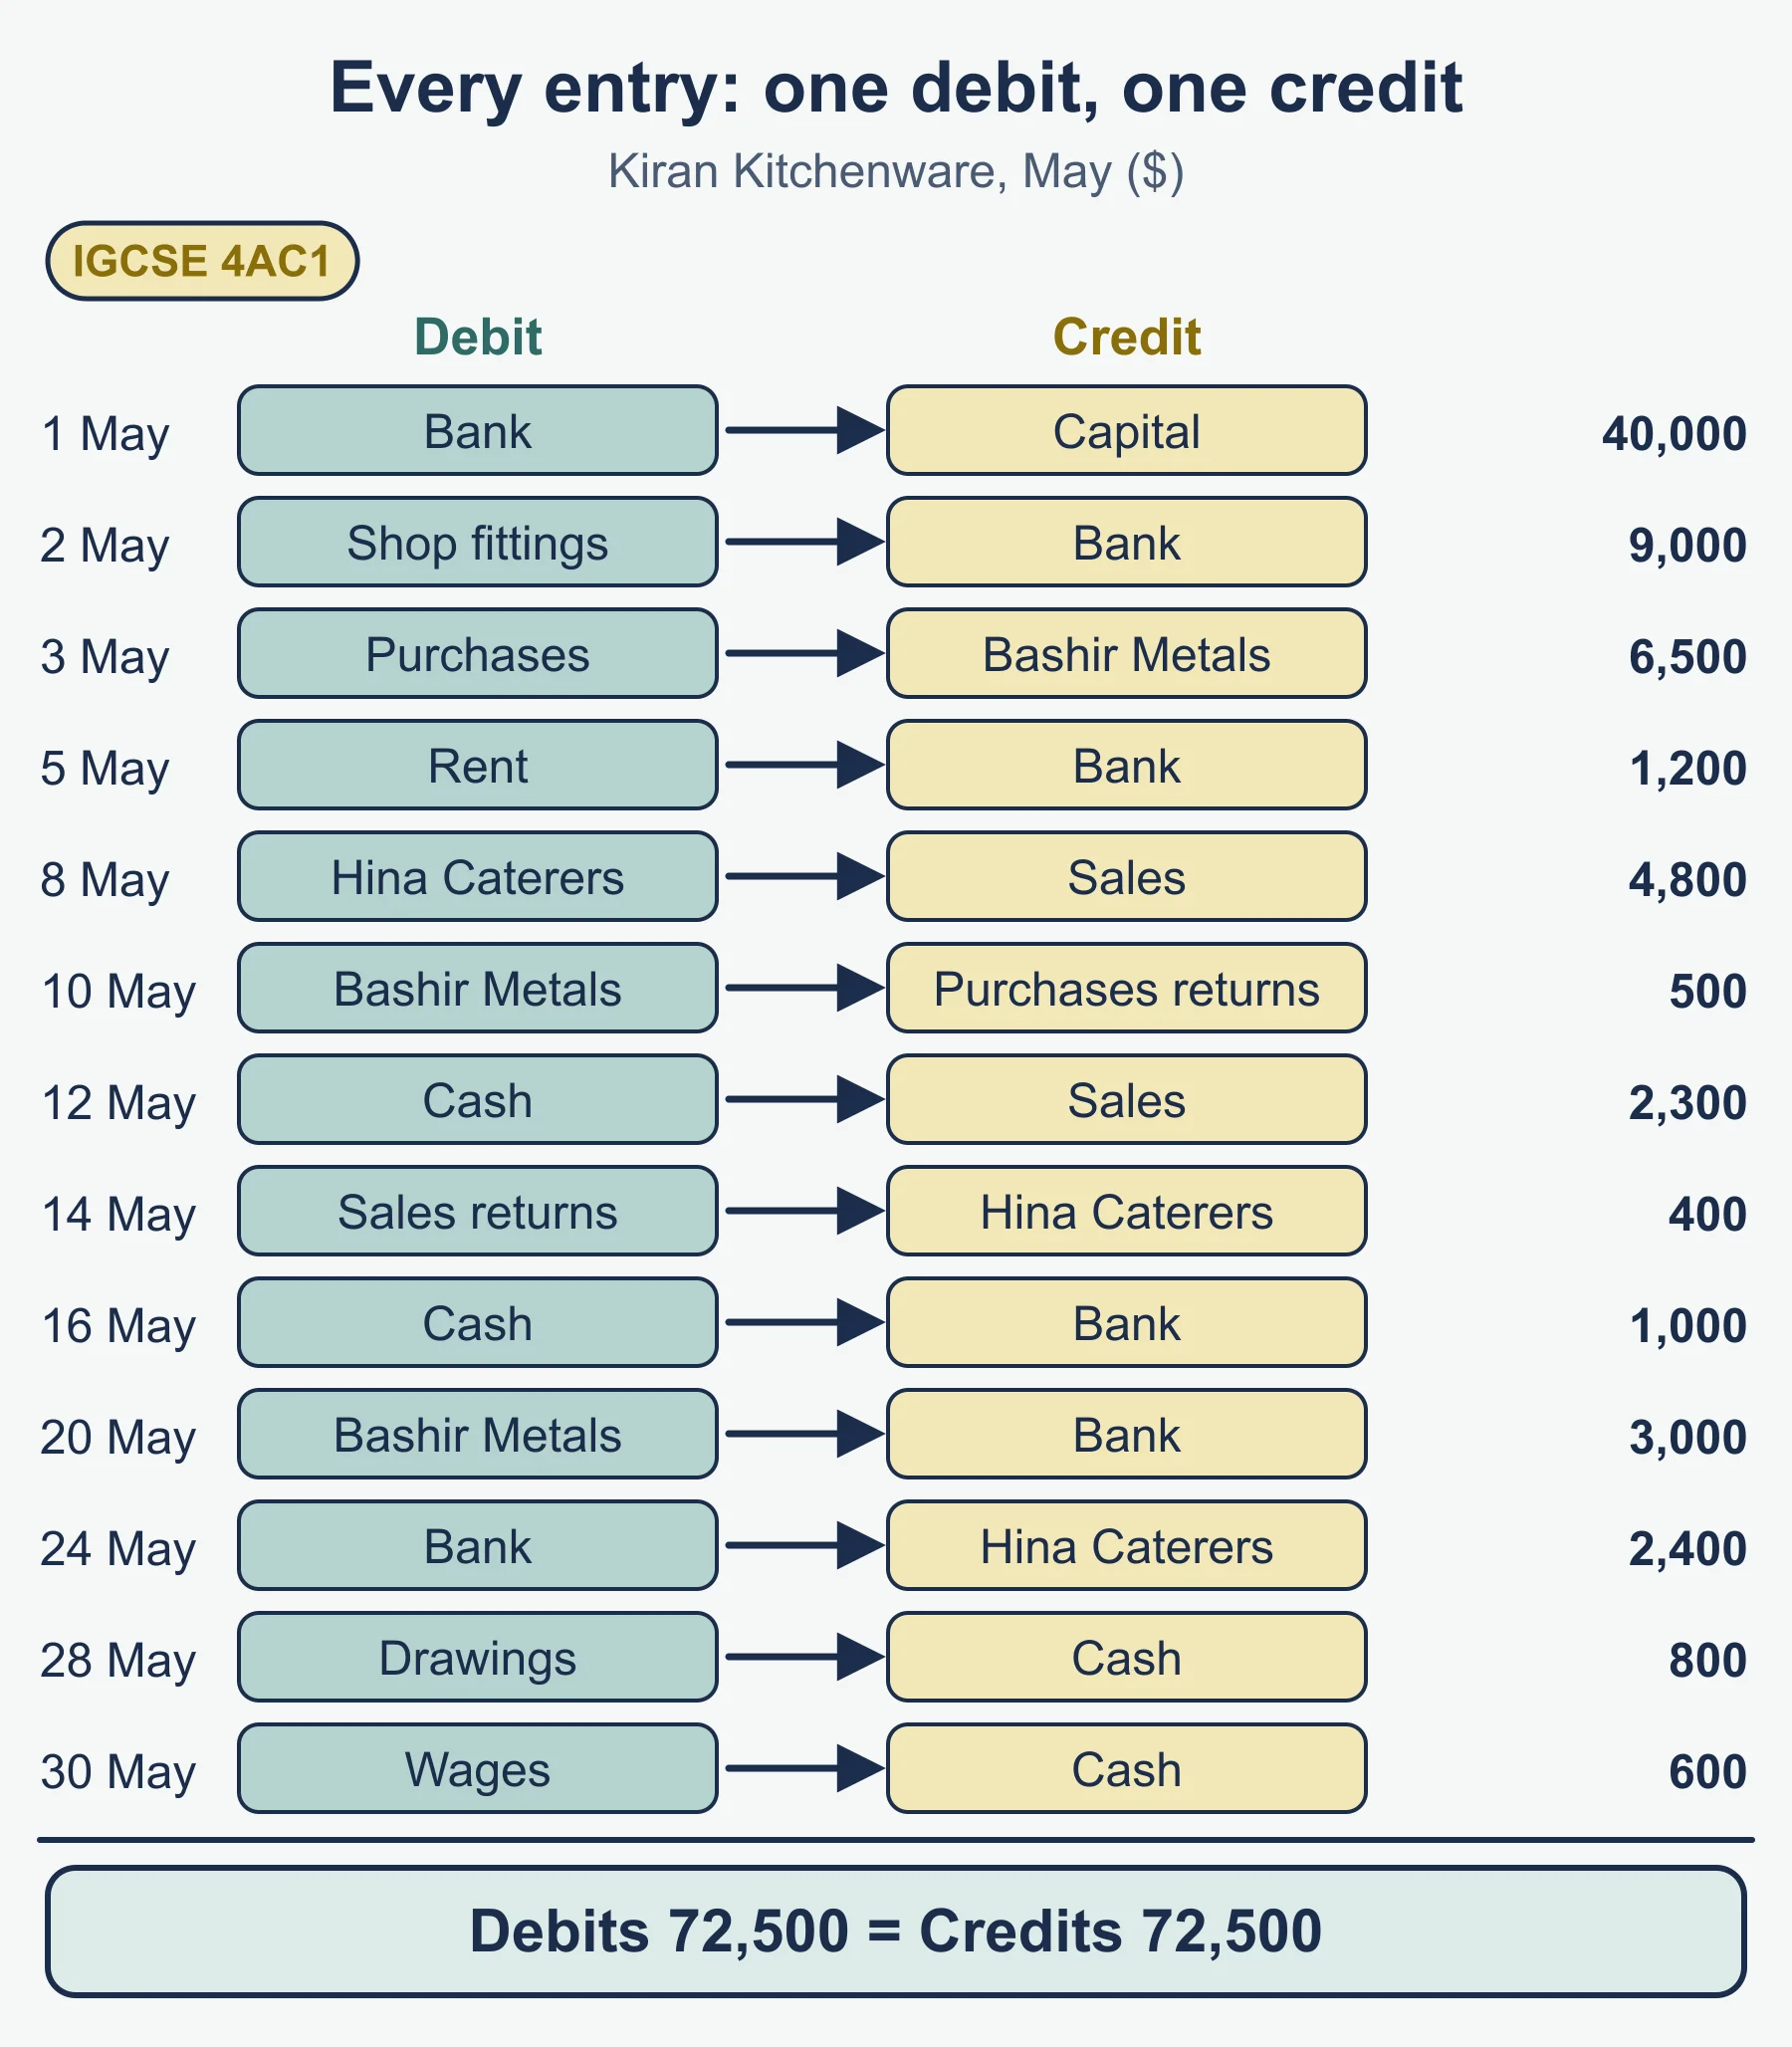
| Date | Transaction | Debit | Credit | Amount |
|---|---|---|---|---|
| 1 May | Kiran pays 40,000 of her own money into the business bank account | Bank | Capital | 40,000 |
| 2 May | Shop fittings bought, paid by bank | Shop fittings | Bank | 9,000 |
| 3 May | Inventory bought on credit from Bashir Metals | Purchases | Bashir Metals | 6,500 |
| 5 May | Rent paid by bank | Rent | Bank | 1,200 |
| 8 May | Goods sold on credit to Hina Caterers | Hina Caterers | Sales | 4,800 |
| 10 May | Faulty goods returned to Bashir Metals | Bashir Metals | Purchases returns | 500 |
| 12 May | Cash sales | Cash | Sales | 2,300 |
| 14 May | Hina Caterers returns goods | Sales returns | Hina Caterers | 400 |
| 16 May | Cash withdrawn from the bank for the till | Cash | Bank | 1,000 |
| 20 May | Bashir Metals paid by bank | Bashir Metals | Bank | 3,000 |
| 24 May | Hina Caterers pays by bank | Bank | Hina Caterers | 2,400 |
| 28 May | Kiran takes cash for private use | Drawings | Cash | 800 |
| 30 May | Wages paid in cash | Wages | Cash | 600 |
Look at 3 May. Purchases is an expense, which increases on the debit side. Bashir Metals is a supplier, a liability, which increases on the credit side. On 14 May Hina Caterers is an asset that decreases, so it is credited, and Sales returns is an expense that increases, so it is debited.
The accounts that hold a customer or a supplier belong to the receivables or payables ledger. All the others are nominal ledger accounts. Here are four of them, balanced at 31 May.
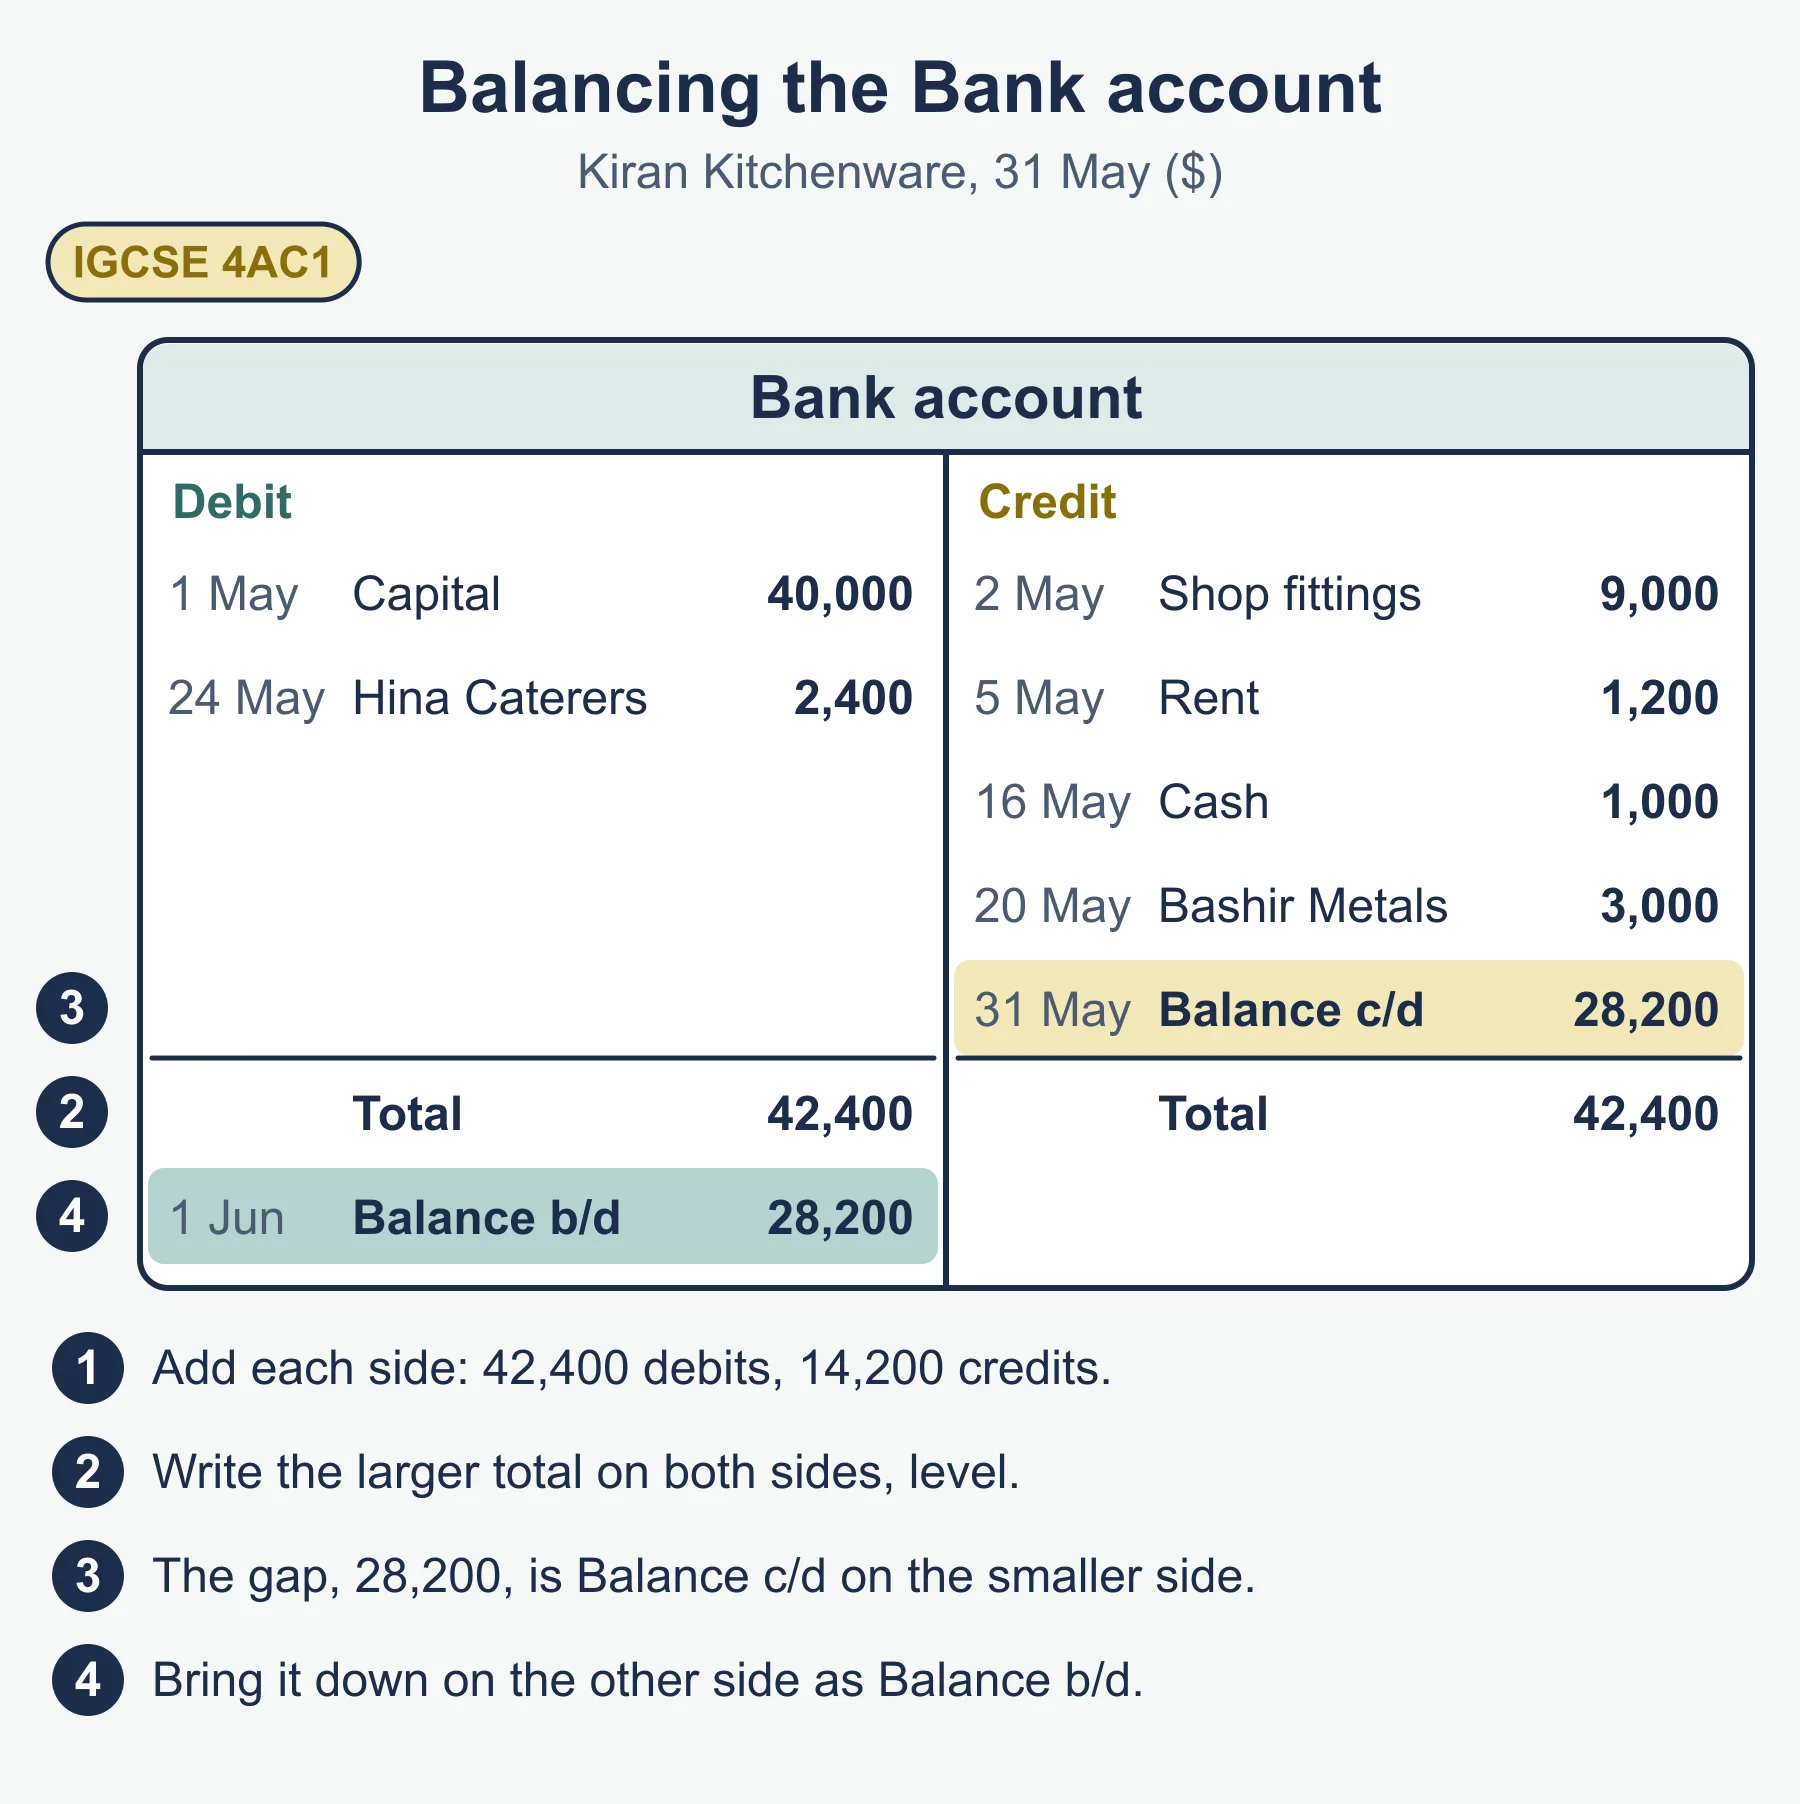
Bank account
| Date | Details (Dr) | Amount | Date | Details (Cr) | Amount |
|---|---|---|---|---|---|
| 1 May | Capital | 40,000 | 2 May | Shop fittings | 9,000 |
| 24 May | Hina Caterers | 2,400 | 5 May | Rent | 1,200 |
| 16 May | Cash | 1,000 | |||
| 20 May | Bashir Metals | 3,000 | |||
| 31 May | Balance c/d | 28,200 | |||
| Total | 42,400 | Total | 42,400 | ||
| 1 Jun | Balance b/d | 28,200 |
Cash account
| Date | Details (Dr) | Amount | Date | Details (Cr) | Amount |
|---|---|---|---|---|---|
| 12 May | Sales | 2,300 | 28 May | Drawings | 800 |
| 16 May | Bank | 1,000 | 30 May | Wages | 600 |
| 31 May | Balance c/d | 1,900 | |||
| Total | 3,300 | Total | 3,300 | ||
| 1 Jun | Balance b/d | 1,900 |
Bashir Metals account
| Date | Details (Dr) | Amount | Date | Details (Cr) | Amount |
|---|---|---|---|---|---|
| 10 May | Purchases returns | 500 | 3 May | Purchases | 6,500 |
| 20 May | Bank | 3,000 | |||
| 31 May | Balance c/d | 3,000 | |||
| Total | 6,500 | Total | 6,500 | ||
| 1 Jun | Balance b/d | 3,000 |
Hina Caterers account
| Date | Details (Dr) | Amount | Date | Details (Cr) | Amount |
|---|---|---|---|---|---|
| 8 May | Sales | 4,800 | 14 May | Sales returns | 400 |
| 24 May | Bank | 2,400 | |||
| 31 May | Balance c/d | 2,000 | |||
| Total | 4,800 | Total | 4,800 | ||
| 1 Jun | Balance b/d | 2,000 |
Bank and Cash are nominal ledger accounts. Bashir Metals is in the payables ledger and Hina Caterers is in the receivables ledger. The closing balances say that Kiran has 28,200 in the bank and 1,900 in cash, she owes Bashir Metals 3,000, and Hina Caterers owes her 2,000.
The remaining nominal accounts each need no balancing, because they have entries on one side only or one entry each. Capital is a credit of 40,000. Shop fittings is a debit of 9,000. Purchases is a debit of 6,500. Rent is a debit of 1,200. Sales is two credits, 4,800 and 2,300, giving 7,100. Purchases returns is a credit of 500. Sales returns is a debit of 400. Drawings is a debit of 800. Wages is a debit of 600.
Check your work: every amount in the analysis was entered once as a debit and once as a credit, so the debit entries and the credit entries both total 72,500.
Balancing an account
- Add up each side separately.
- Write the larger total in the total boxes on both sides, level with each other.
- The difference goes on the smaller side as Balance c/d (carried down) on the last day of the period, so that both sides add to the same total.
- Bring the balance down on the opposite side, dated the next day, as Balance b/d.
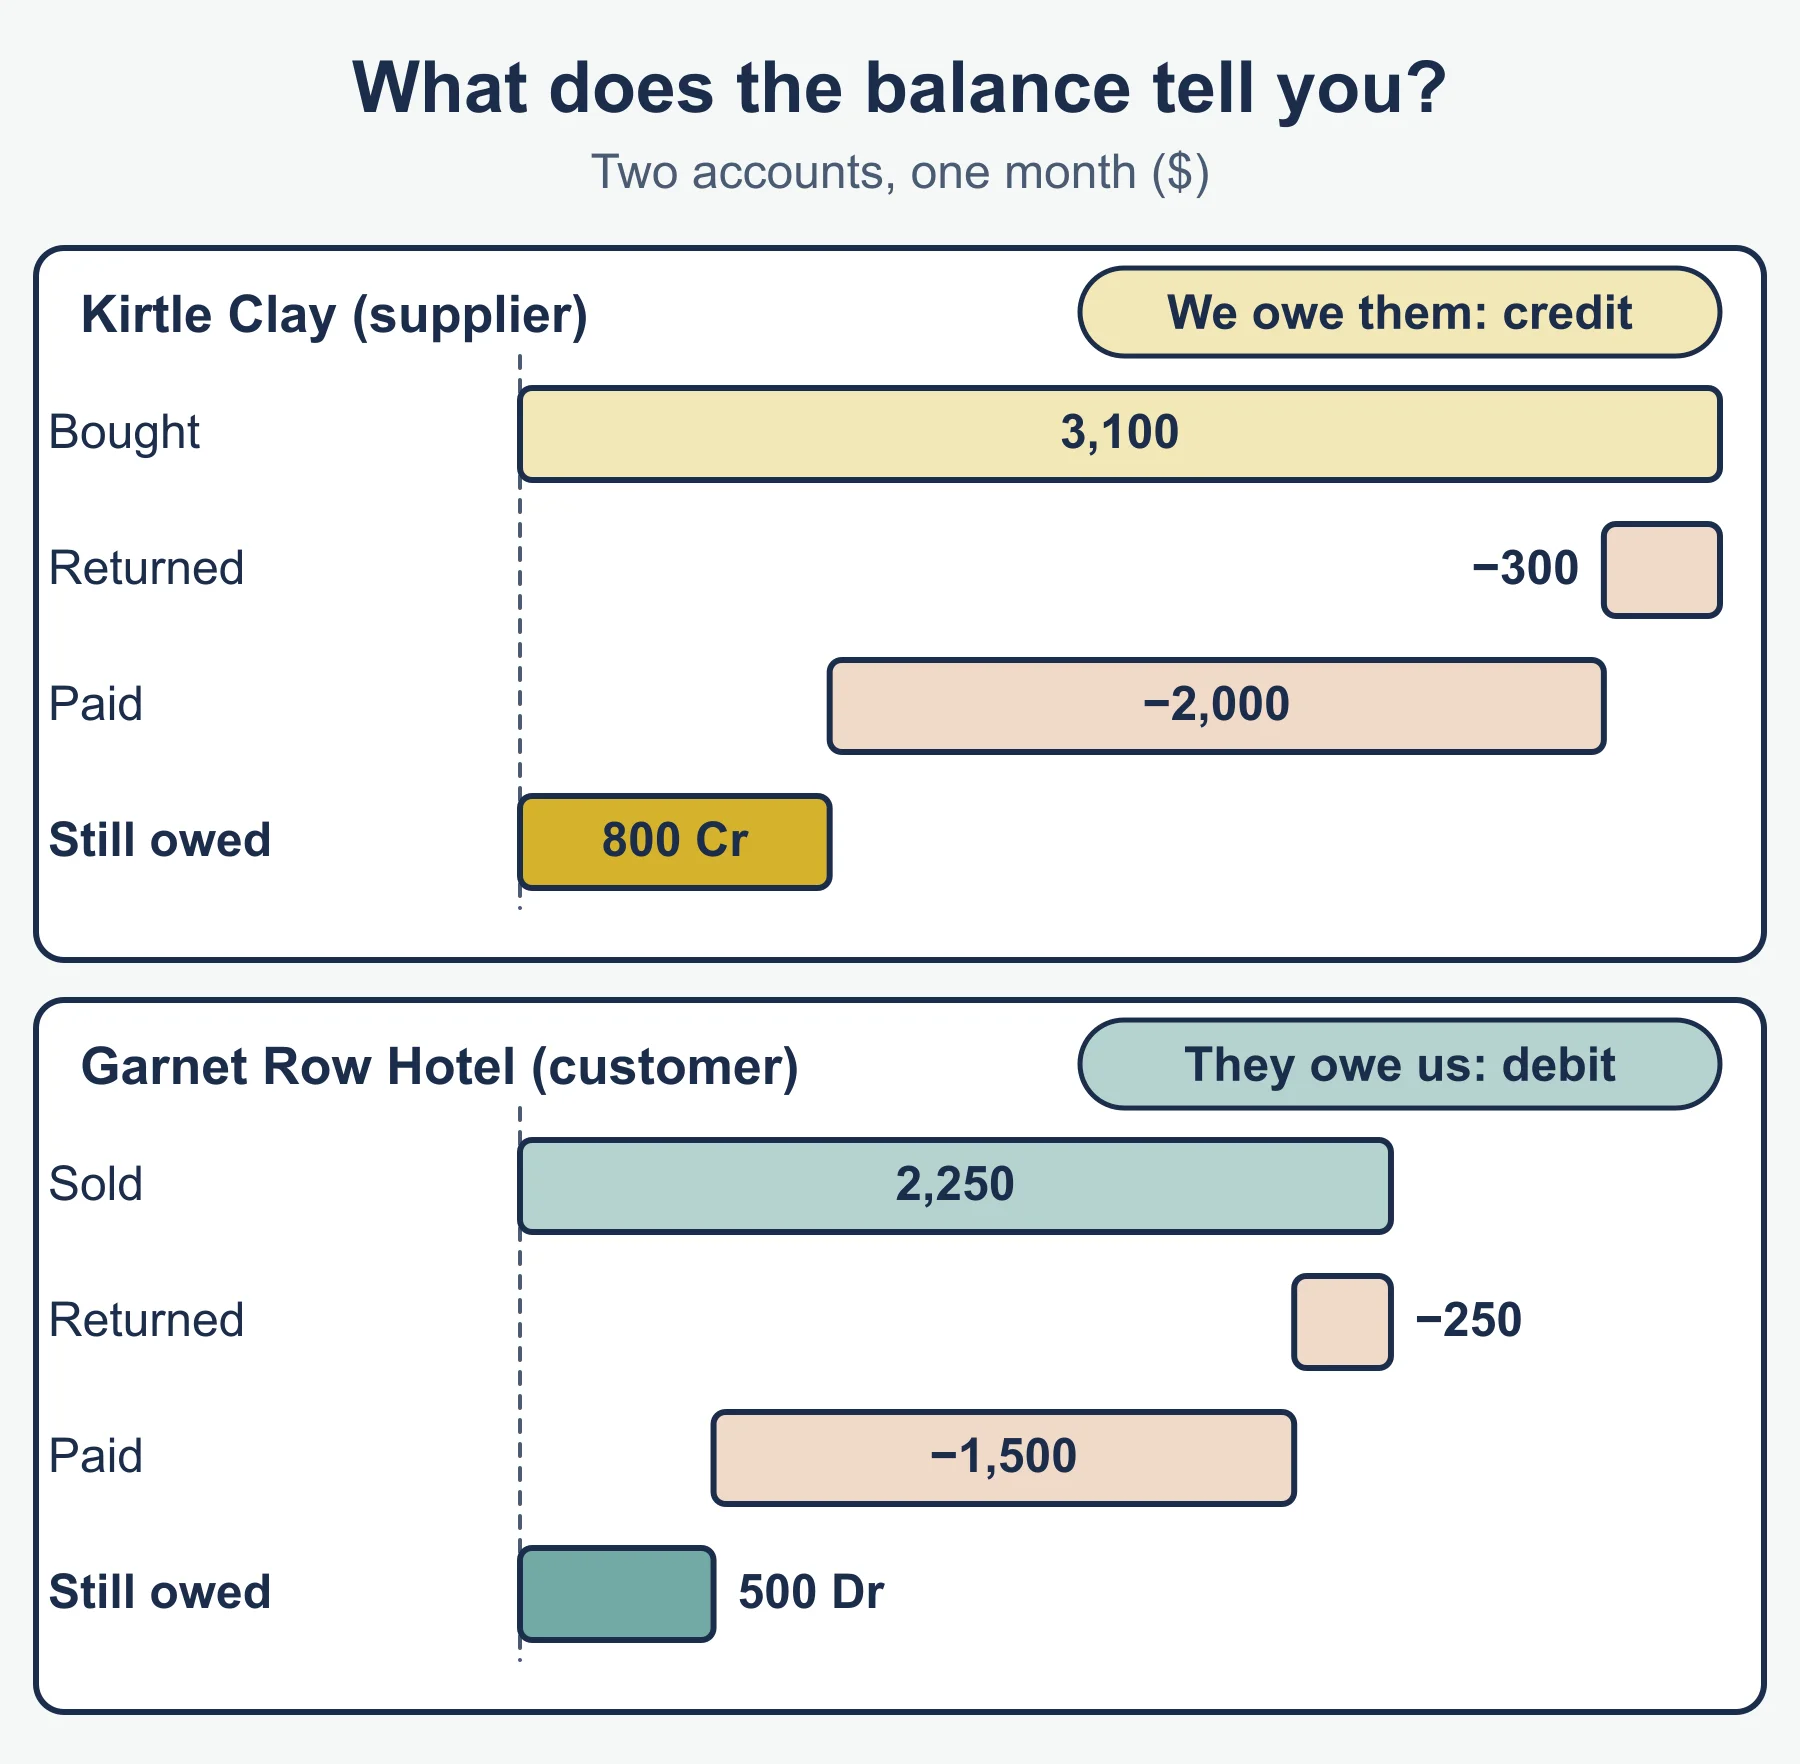
A debit balance on Bank or Cash means money held. A debit balance on a customer account means the customer owes the business. A credit balance on a supplier account means the business owes the supplier. A credit balance on Bank means the account is overdrawn.
Worked example 2: the two-question method
For each transaction, name the account debited and the account credited.
| Transaction | Debit | Credit | Reason |
|---|---|---|---|
| A customer settles an old invoice in cash | Cash | Customer | Cash asset up, receivable down |
| A loan is paid into the business bank account | Bank | Loan | Asset up, liability up |
| Insurance is paid by bank | Insurance | Bank | Expense up, asset down |
| The owner pays a further sum into the bank | Bank | Capital | Asset up, capital up |
| A customer returns goods bought on credit | Sales returns | Customer | Expense up, receivable down |
| Goods are bought for cash | Purchases | Cash | Expense up, asset down |
Common errors
- Writing the name of the account you are in, instead of the other account, in the details column.
- Reversing the customer and supplier rules. A customer is debited when it buys on credit. A supplier is credited when the business buys on credit.
- Treating Bank like a liability. Money in is a debit.
- Posting a return to the Sales or Purchases account instead of Sales returns or Purchases returns.
- Making only one entry. Every transaction needs a debit and a credit, including a cash sale.
- Balancing with the totals not level, or bringing the balance down on the same side as the Balance c/d.
- Treating drawings as an expense of the business. They have their own account, debited when the owner takes money or goods.
Next steps
Test yourself with the ledger accounting practice set, revise with the revision notes, tick off topics on the checklist, and try a free diagnostic. The course hub lists the rest of the course.
Frequently asked questions
What are the three ledgers in Edexcel IGCSE Accounting? The 4AC1 specification uses the nominal ledger, the receivables ledger and the payables ledger. Customer accounts go in the receivables ledger, supplier accounts in the payables ledger, and all other accounts, such as sales, purchases, expenses, capital, bank and cash, in the nominal ledger.
How do you decide which side of a ledger account to use? Ask which two accounts are affected and whether each is increasing or decreasing. Assets and expenses increase on the debit side, while liabilities, capital and income increase on the credit side.
What goes in the details column of a ledger account? The details column names the other account in the double entry, never the account you are writing in. Writing the account’s own name is a common error.
How do you balance a ledger account? Add each side, write the larger total on both sides level with each other, and put the difference on the smaller side as Balance c/d. Then bring it down on the opposite side, dated the next day, as Balance b/d.
What does a credit balance on the bank account mean? Bank is normally an asset with a debit balance, meaning money is held. A credit balance on the bank account means the account is overdrawn.
Official syllabus
Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016, published by Pearson Education Limited – Topic 2 Introduction to bookkeeping, section 2.3 Ledger accounting, points 2.3a and 2.3b.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
Edexcel IGCSE Accounting: Ledger accounting (4AC1) – Practice Questions
Original practice questions with worked answers on ledger accounting for Pearson Edexcel IGCSE Accounting: the three ledgers and double entry.
Accounting · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Accounting: Ledger accounting (4AC1) – Revision Notes
Condensed revision notes on ledger accounting for Pearson Edexcel IGCSE Accounting: ledgers, debit and credit rules, balancing, and a self-test.
Accounting · Pearson Edexcel · IGCSE
Revise topic -
Study guides
Edexcel IGCSE Accounting: Business documentation and books of original entry (4AC1)
Study guide to Edexcel IGCSE Accounting 4AC1 business documents, day books, cash book, petty cash book and journal, with five worked examples.
Accounting · Pearson Edexcel · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Accounting teachers at Marlbridge

