
Study Guides
Edexcel IGCSE Accounting: Correction of errors and bank reconciliation statements (4AC1)
Study guide to Edexcel IGCSE Accounting errors, correcting journals, the suspense account and bank reconciliation statements, with worked examples.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Introduction to control processes
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Pearson Edexcel IGCSE Accounting (4AC1), Issue 1, October 2016. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Accounting.
Syllabus points this page covers
4AC1
- 3 Introduction to control processes (whole topic)
- 3.3 Correction of errors
- 3.4 Bank reconciliation statements
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
This guide teaches sections 3.3 Correction of errors and 3.4 Bank reconciliation statements of Topic 3, Introduction to control processes, in the Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1 (October 2016). The specification does not split these sections into tiers. Topic 3 belongs to the content that Paper 1 draws on, and the specification says Paper 2 builds on topics 1 to 3. All amounts are in dollars.
Use the revision notes for quick recall and the practice questions to test yourself. See also the Edexcel IGCSE Accounting hub, the printable checklist and the free diagnostics.
What the specification asks for
| Point | You must be able to | Where below |
|---|---|---|
| 3.3 a | Identify and explain the errors that leave the trial balance agreeing and those that make it disagree | Two groups of error |
| 3.3 b | Prepare journal entries to correct errors | Journal entries |
| 3.3 c | Prepare a suspense account | The suspense account |
| 3.4 a | Explain the purpose of bank reconciliation statements | Why reconcile |
| 3.4 b | Understand the process of bank reconciliation | The process |
| 3.4 c | Prepare a bank reconciliation statement | Worked example |
Two groups of error
A trial balance lists every ledger balance in a debit column and a credit column. If the totals agree, the arithmetic of double entry holds. It does not show that every entry is right. The specification does not name error types, so the usual names below are labels only. In an answer, describe the error in words as well.
Errors that do not affect the balancing. A debit and a credit of the same amount are still posted, so the totals still agree.
| Error | Meaning | Example |
|---|---|---|
| Omission | A transaction is left out completely | A credit sale of 260 to M. Joshi is never recorded |
| Commission | Right type of account, wrong account | A receipt of 340 is credited to S. Okonkwo instead of S. Okoro |
| Principle | Item put in the wrong class of account | A delivery van costing 9,500 is debited to motor expenses |
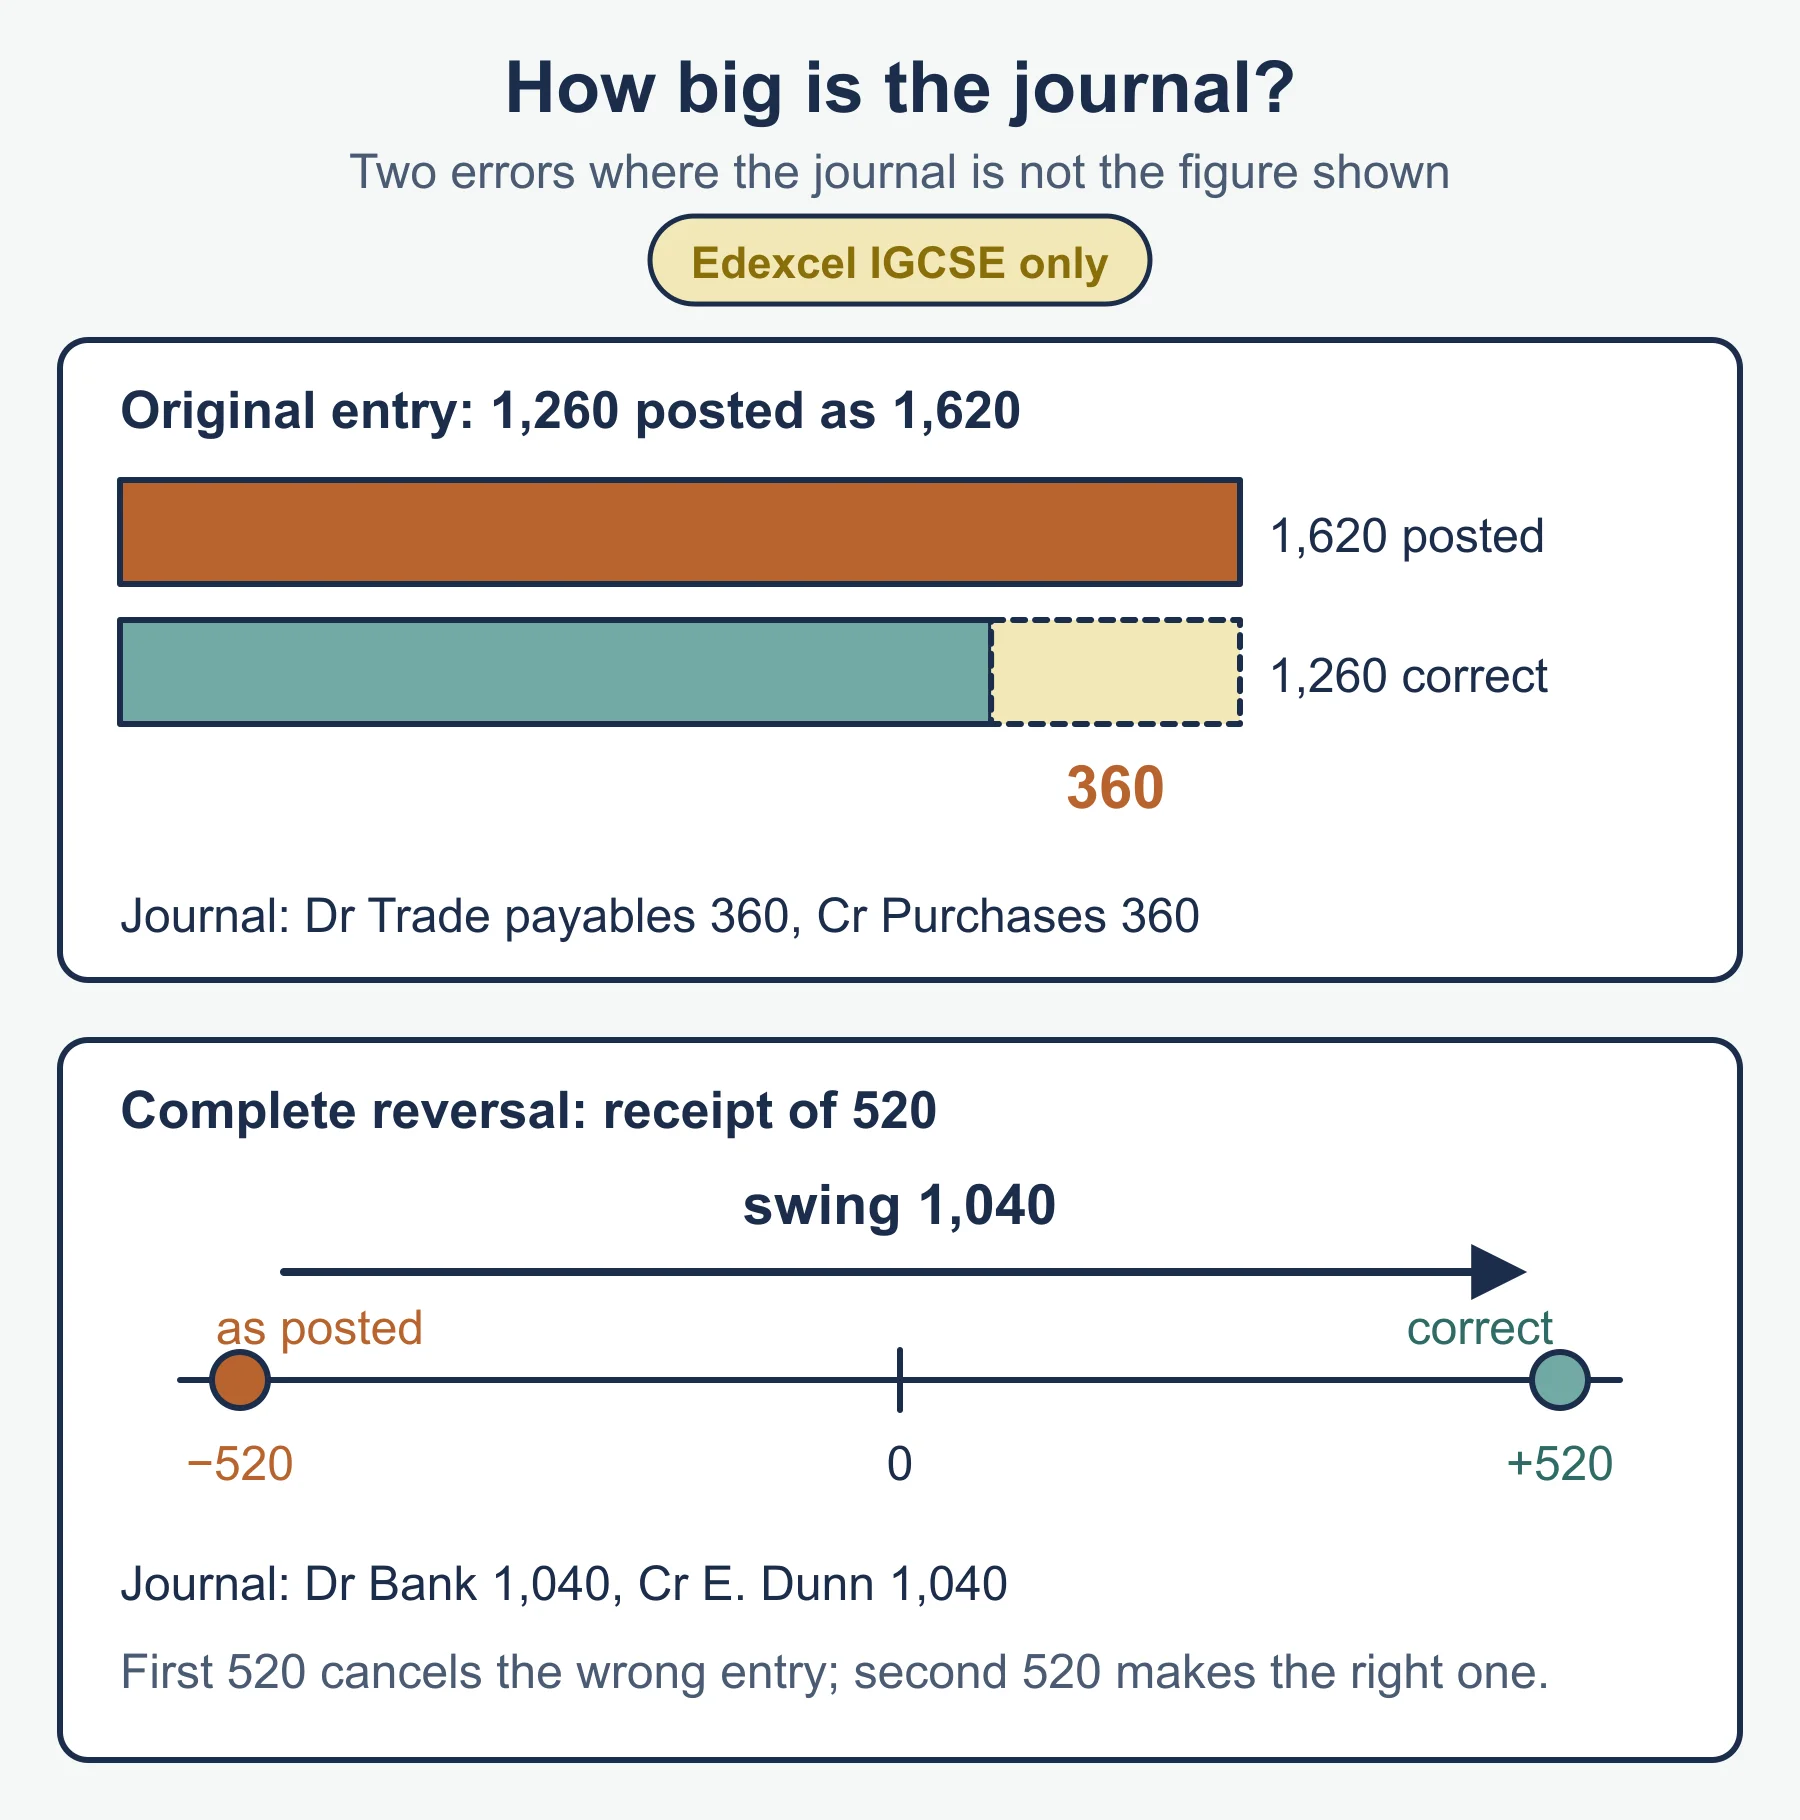
| Original entry | Wrong figure used in both entries | An invoice for 1,260 is recorded as 1,620 in both accounts |
| Compensating | Two errors of equal size on opposite sides cancel | Wages overcast by 400 and rent received overcast by 400 |
| Complete reversal | Correct accounts, each on the wrong side | A receipt of 520 debited to the customer and credited to bank |
Errors that do affect the balancing. The two sides of the trial balance no longer agree.
- A single-sided entry: only the debit or only the credit is posted.
- Different amounts on the two sides: debit 380, credit 308.
- Both entries on the same side: two debits, or two credits.
- An addition error (casting error) in an account, or a balance carried down wrongly.
- A balance copied to the trial balance wrongly or on the wrong side.
Method in steps for any error. Work out what was done. Work out what should have been done. Then write the entry that fixes the difference.
Journal entries to correct errors
A journal entry shows the account to debit, the account to credit, the amount, and a short narrative. Do not erase the original entry. Correct it with a new journal. The six corrections for the table above are:
| Account | Dr | Cr |
|---|---|---|
| M. Joshi (omission) | 260 | |
| Sales | 260 | |
| Narrative: credit sale omitted from the books | ||
| S. Okonkwo (commission) | 340 | |
| S. Okoro | 340 | |
| Narrative: receipt posted to the wrong customer | ||
| Motor vehicles (principle) | 9,500 | |
| Motor expenses | 9,500 | |
| Narrative: van is capital expenditure | ||
| Trade payables, supplier (original entry) | 360 | |
| Purchases | 360 | |
| Narrative: invoice of 1,260 recorded as 1,620 | ||
| Rent received (compensating) | 400 | |
| Wages | 400 | |
| Narrative: both accounts overcast by 400 | ||
| Bank (complete reversal) | 1,040 | |
| E. Dunn | 1,040 | |
| Narrative: receipt of 520 posted to the wrong sides |
The reversal needs 1,040: the first 520 cancels the wrong entry and the second 520 makes the right one. In the original entry error, only the excess of 360 is corrected.
The suspense account
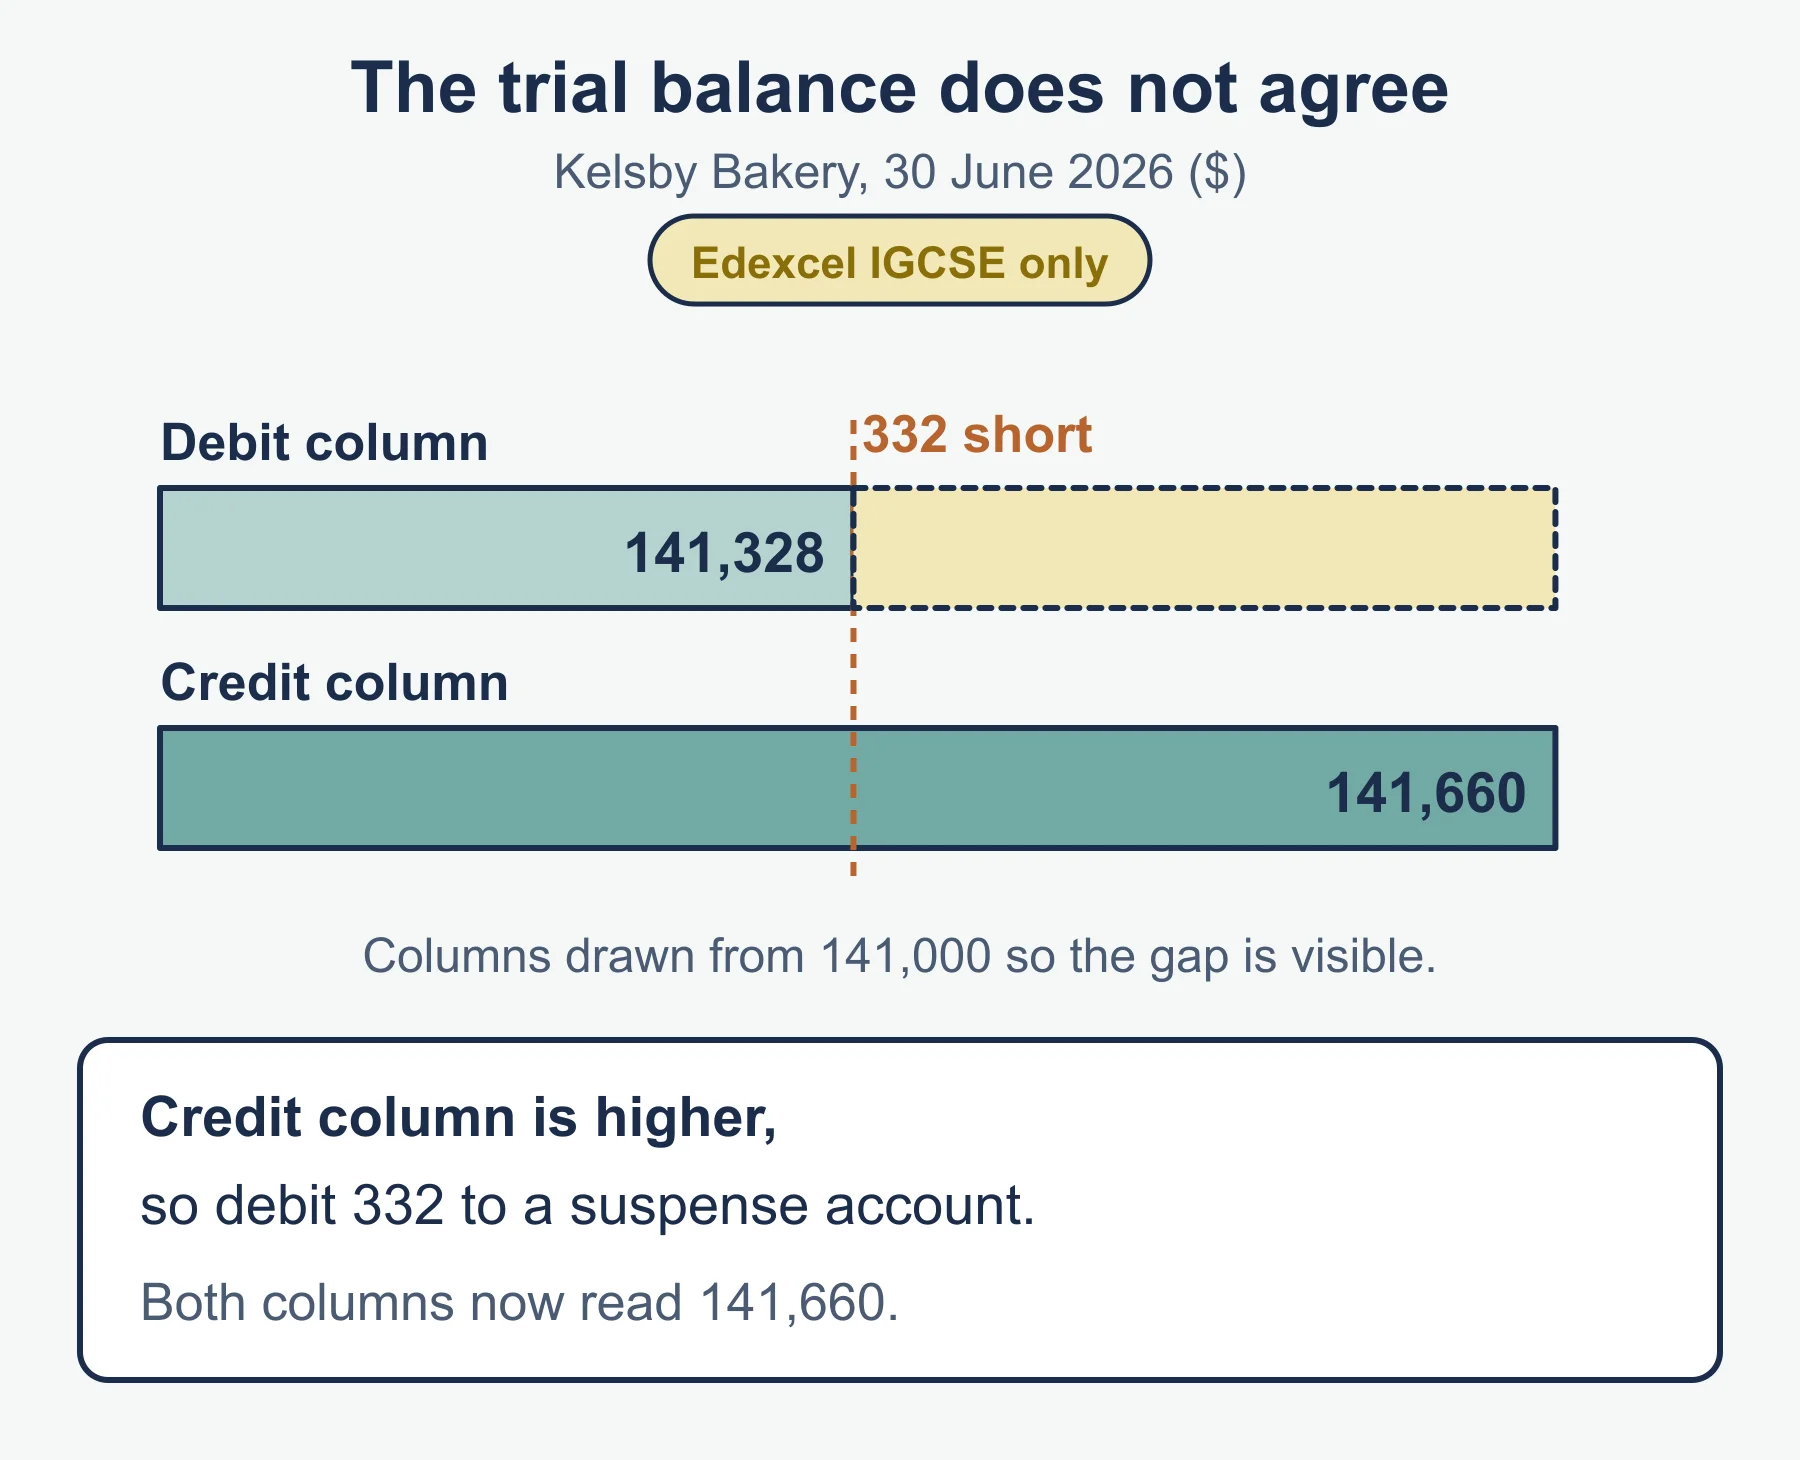
A suspense account is a temporary ledger account. If the trial balance does not agree, the difference goes into it so the totals match for now. The aim is to find the errors, correct them and clear the account to nil. A trial balance with a higher credit total gets the difference as a debit in suspense. A higher debit total gets a credit.
Worked example. Kelsby Bakery’s trial balance at 30 June 2026 is below.
| Account | Dr | Cr |
|---|---|---|
| Premises | 52,000 | |
| Ovens and equipment | 6,800 | |
| Inventory at 1 July 2025 | 8,400 | |
| Purchases | 41,200 | |
| Rent | 308 | |
| Wages | 12,600 | |
| Trade receivables | 6,900 | |
| Bank | 4,120 | |
| Drawings | 9,000 | |
| Sales | 74,000 | |
| Trade payables | 6,200 | |
| Loan | 15,000 | |
| Capital | 45,750 | |
| Discount received | 710 | |
| Totals | 141,328 | 141,660 |
The credit side is 332 higher, so 332 is debited to a suspense account. The totals then both read 141,660. These errors are found.
- A credit sale of 450 to Ellis Ltd was credited to sales. The debit in Ellis’s account was never posted.
- Rent of 380 was paid by bank. The bank entry is right, but the rent account was debited with 308.
- Discount received of 95 was posted to the debit side of the discount received account.
- A computer costing 1,200 was debited to purchases.
Errors 1 to 3 affect the trial balance. Error 4 does not: it is an error of principle.
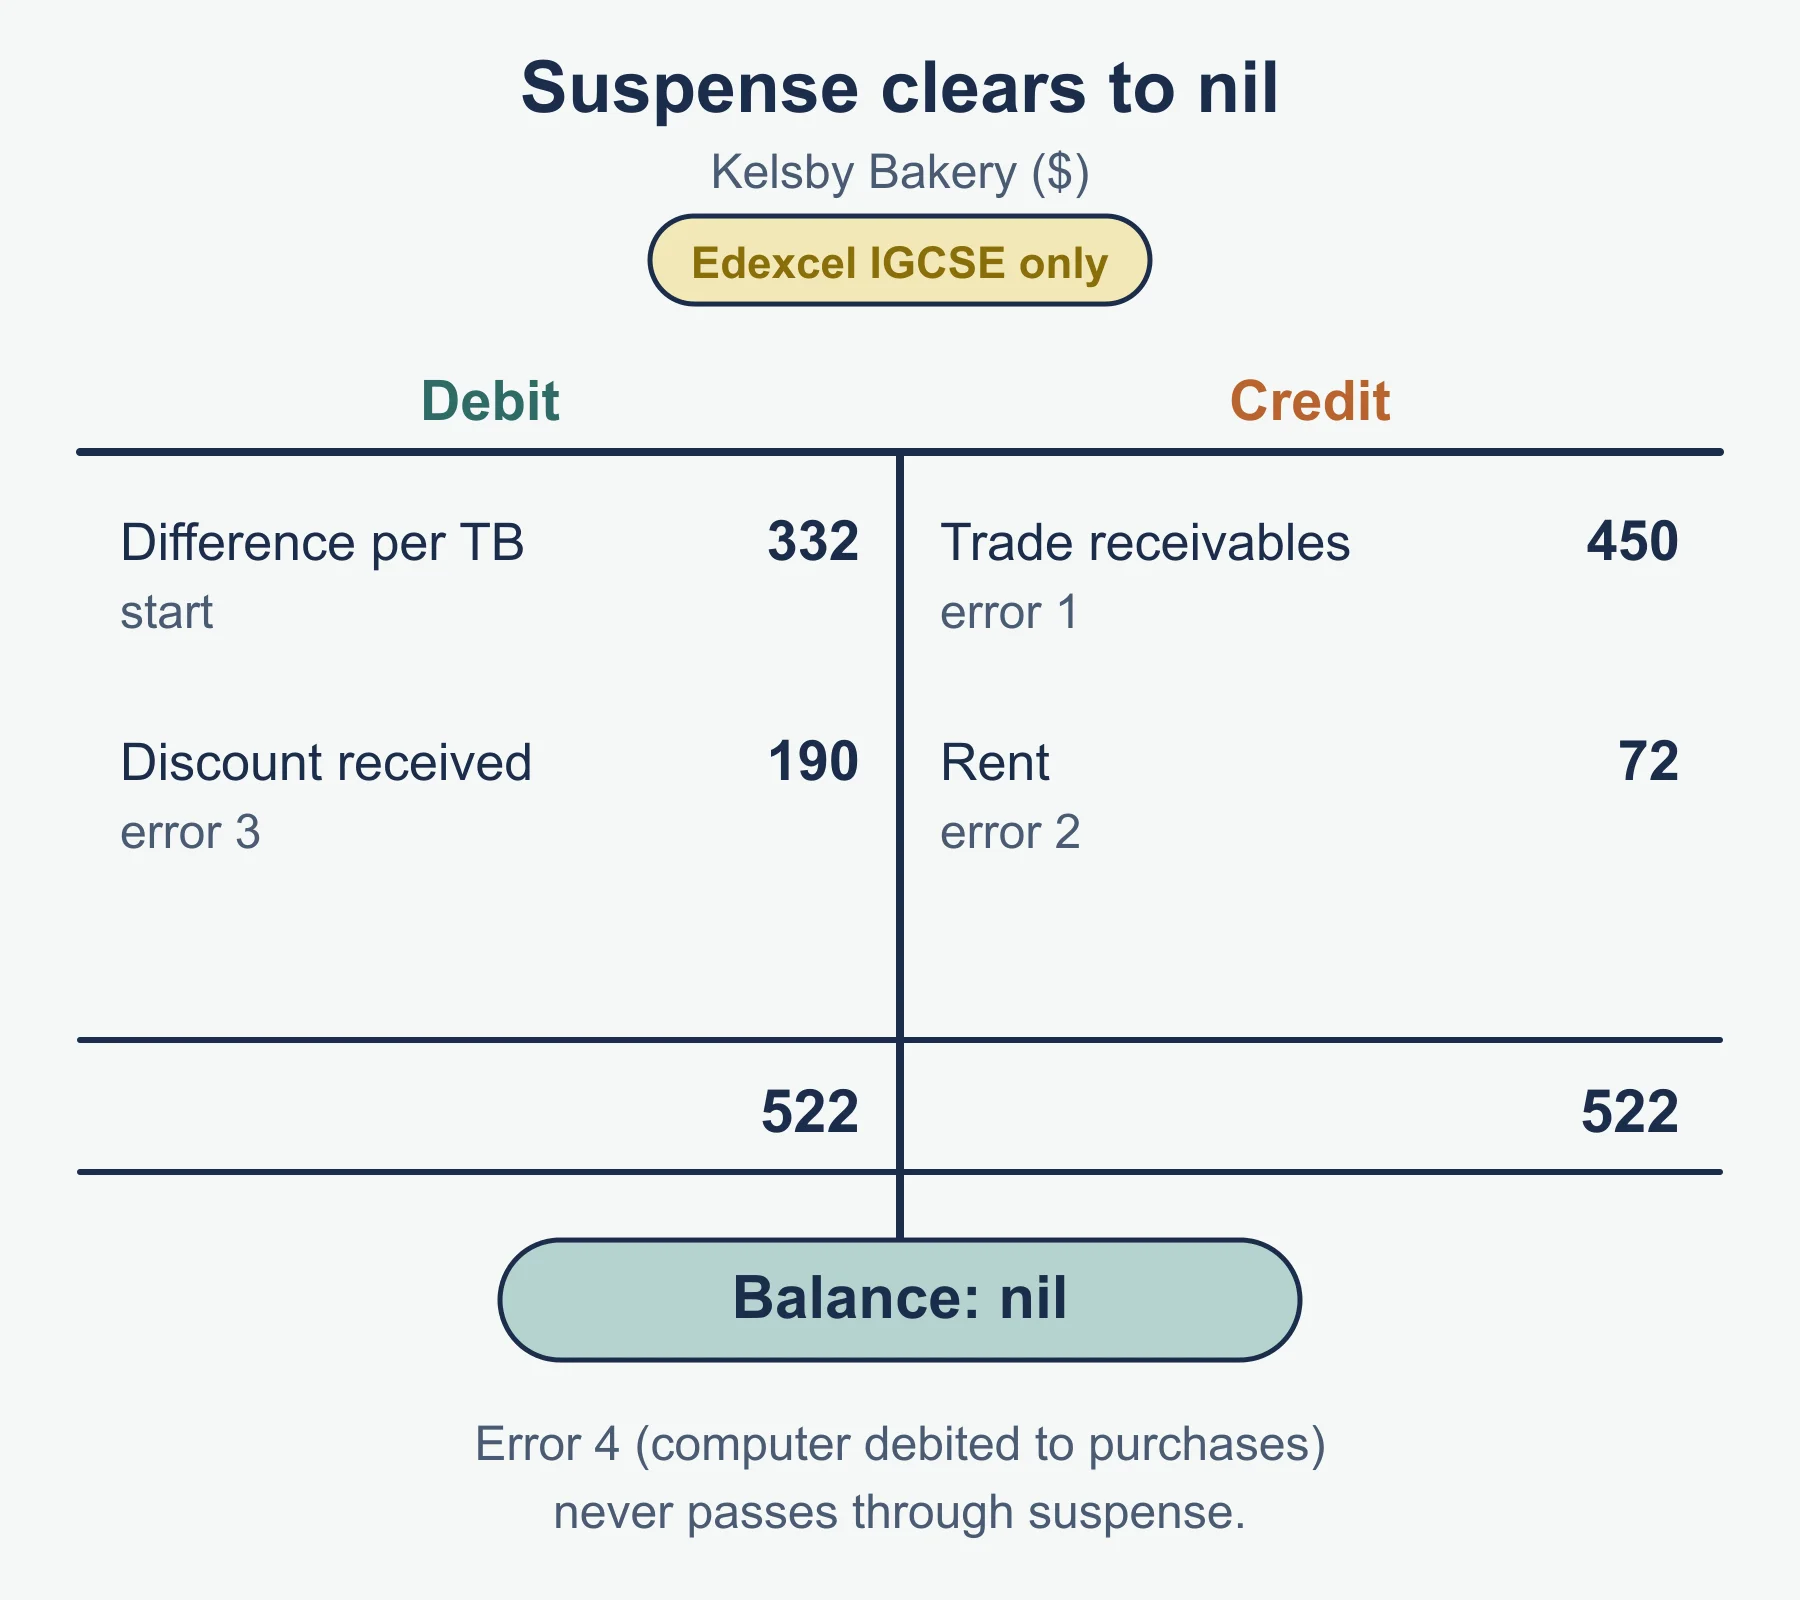
Error 1 is a single-sided entry. Debit Trade receivables (Ellis Ltd) 450 and credit Suspense 450. Error 2 is a different-amounts error. Debit Rent 72 and credit Suspense 72. Error 3 puts a credit item on the debit side, so the account is wrong by twice 95. Debit Suspense 190 and credit Discount received 190. For error 4, debit Office equipment 1,200 and credit Purchases 1,200. Suspense is not involved.
| Suspense account | |||
|---|---|---|---|
| Difference per trial balance | 332 | Trade receivables (Ellis Ltd) | 450 |
| Discount received | 190 | Rent | 72 |
| 522 | 522 |
The account clears to nil, which suggests all the errors have been found. A suspense account that does not clear tells you at least one error is still hidden.
Why reconcile
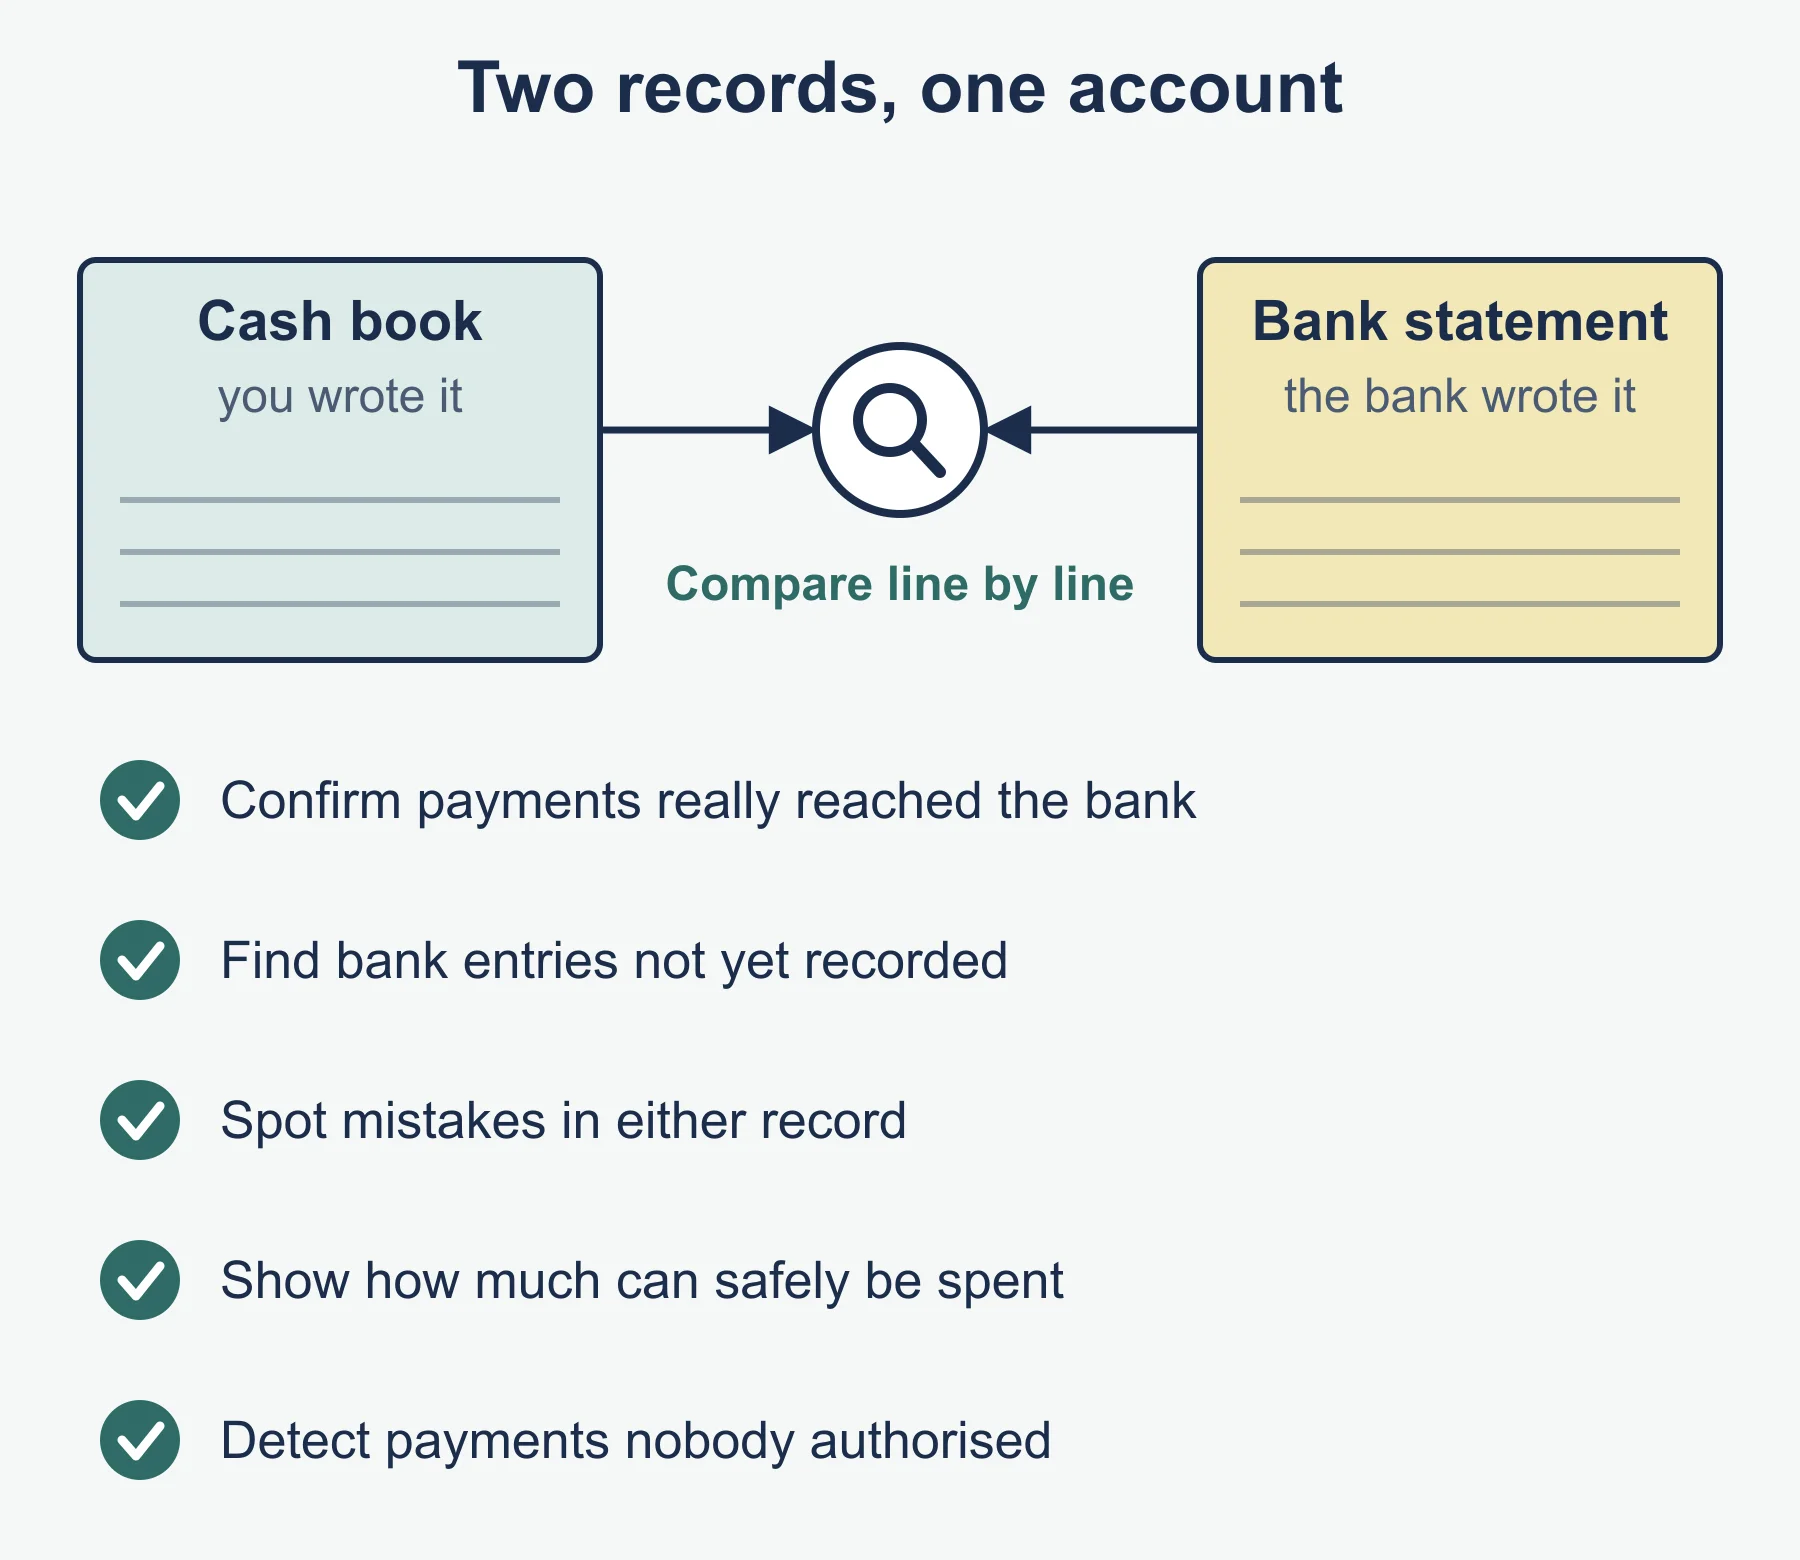
A bank statement is the bank’s own record of the account. The business’s cash book (bank column) is the business’s record of the same account. The two should tell the same story, yet at a given date the balances usually differ. A bank reconciliation statement explains the difference.
Its purposes are to:
- check the accuracy of both records and find mistakes made by the business or the bank;
- spot entries on the statement that are missing from the cash book, such as charges;
- detect fraud or unauthorised payments;
- show the true bank balance the business can rely on, once timing differences are understood.
The process
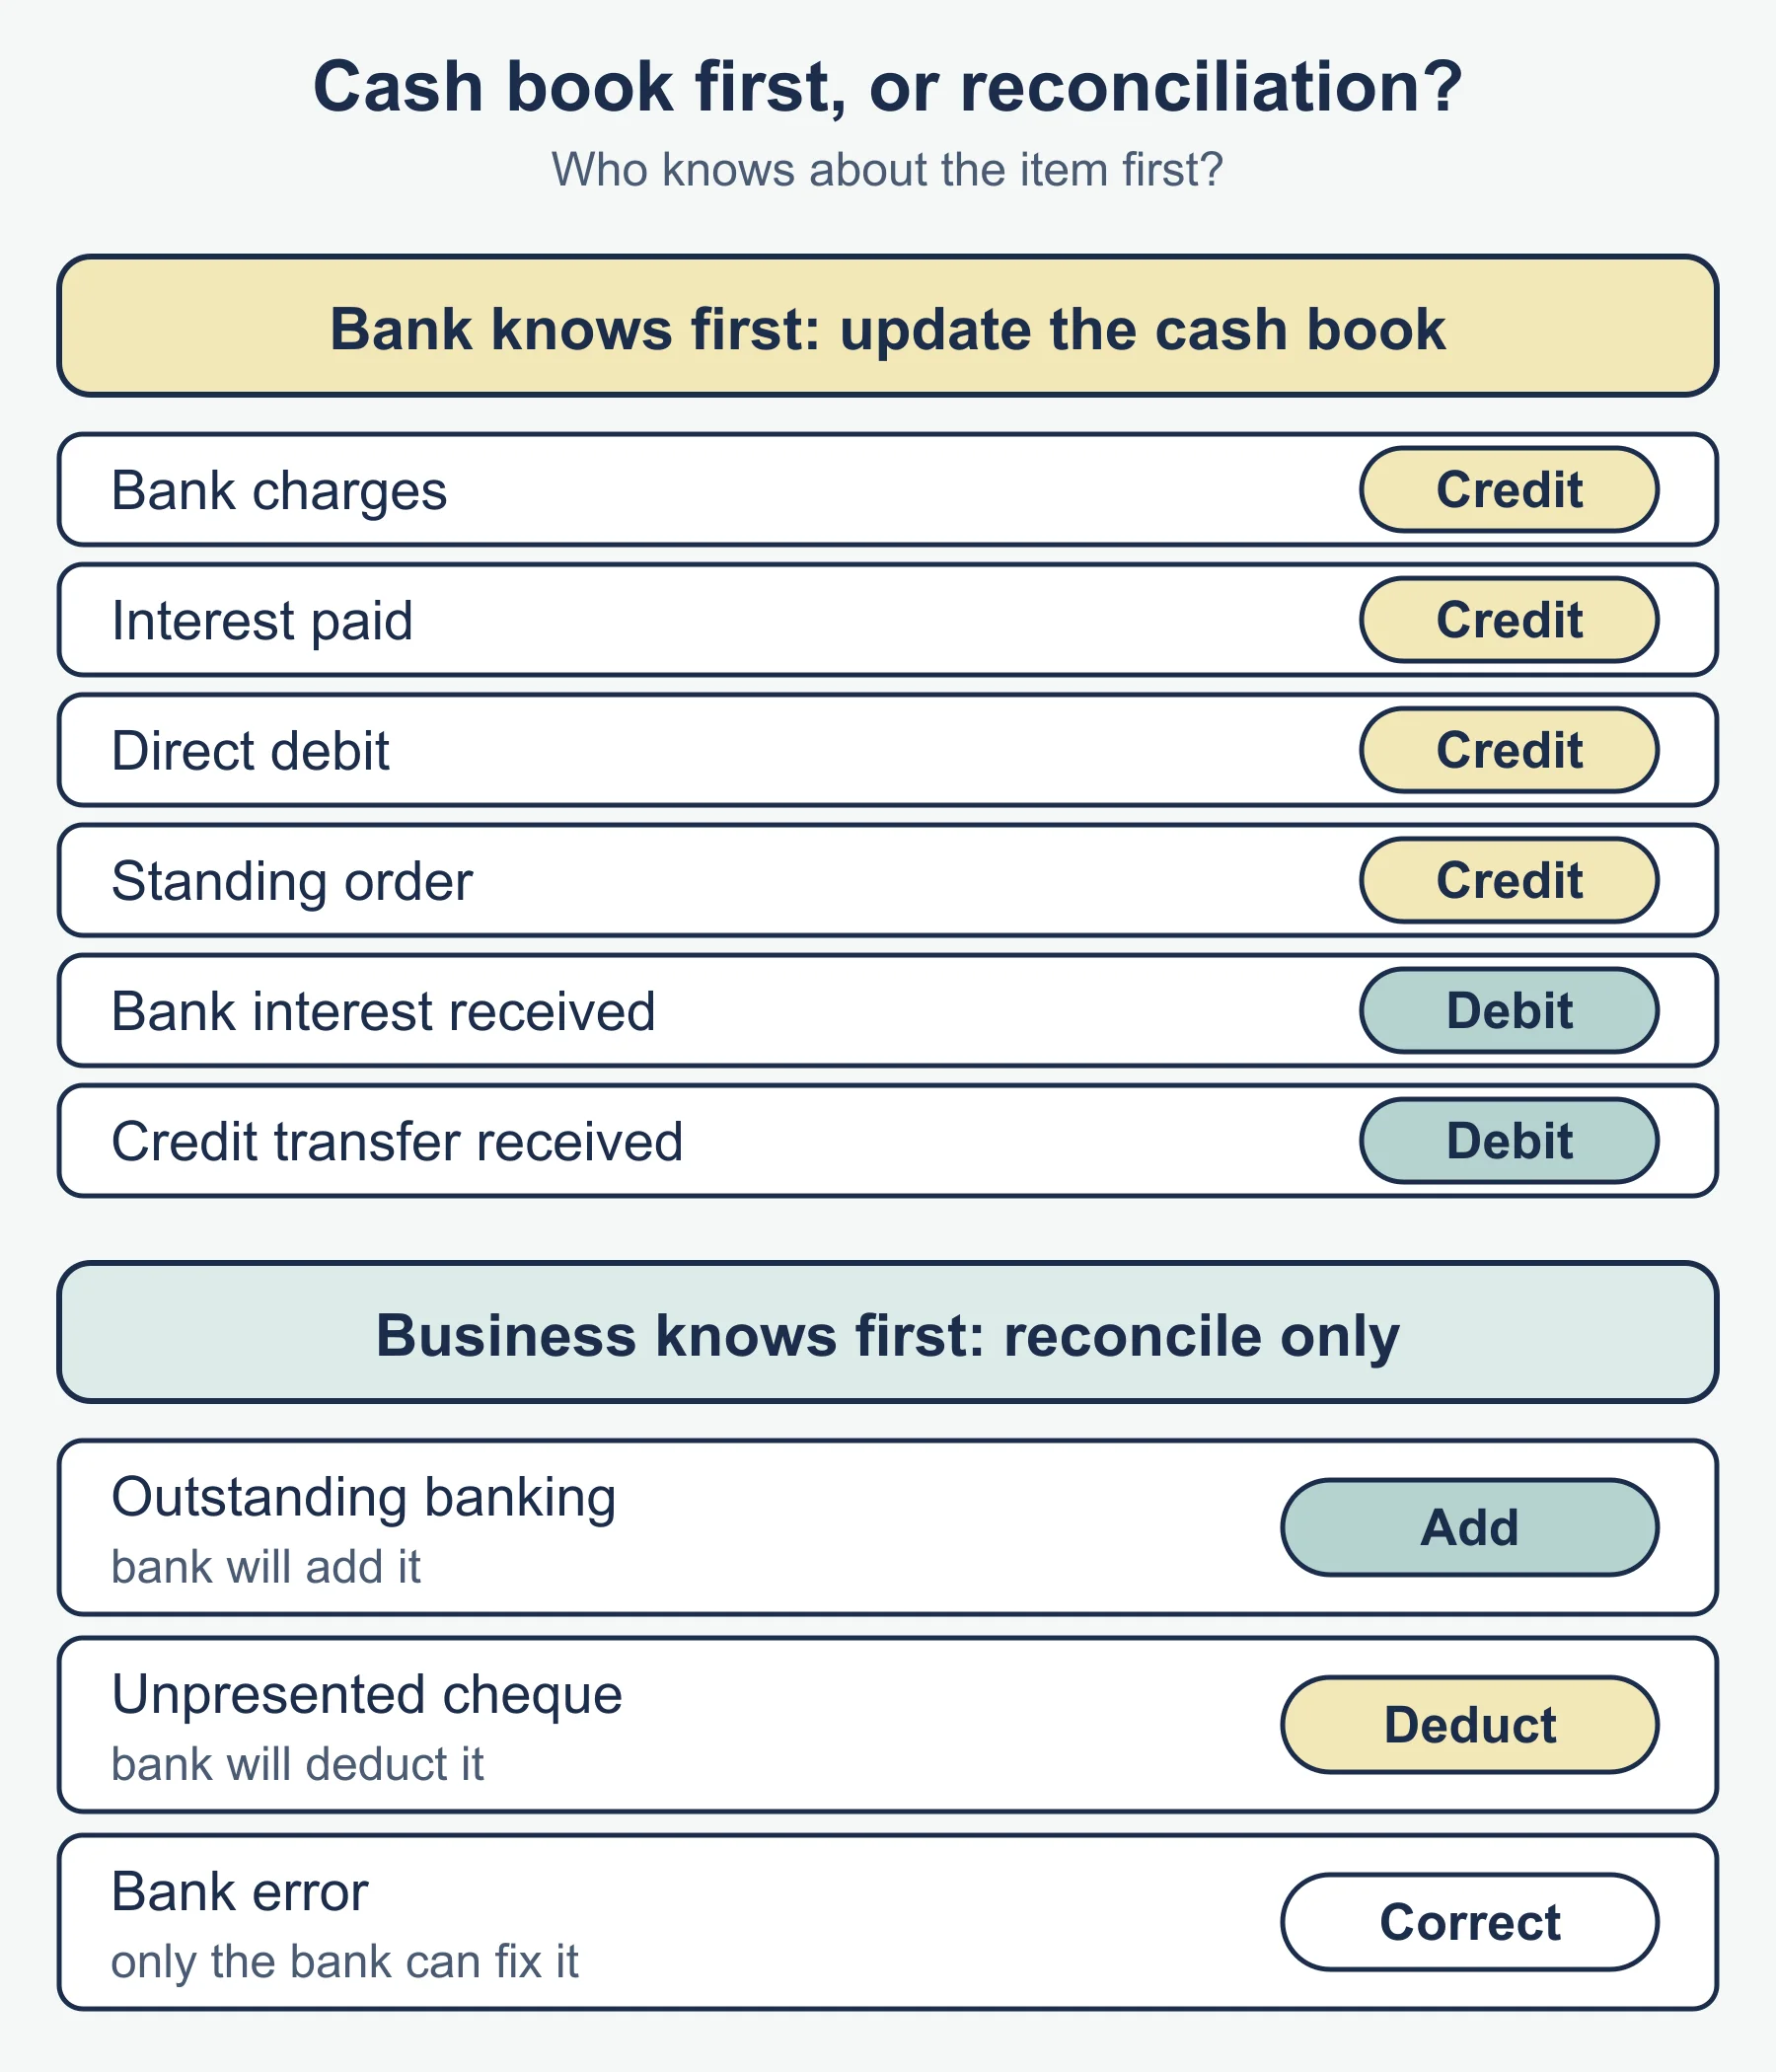
Compare the cash book with the statement line by line, ticking items that appear in both. Then sort what is left.
| Item left over | Cause | What you do |
|---|---|---|
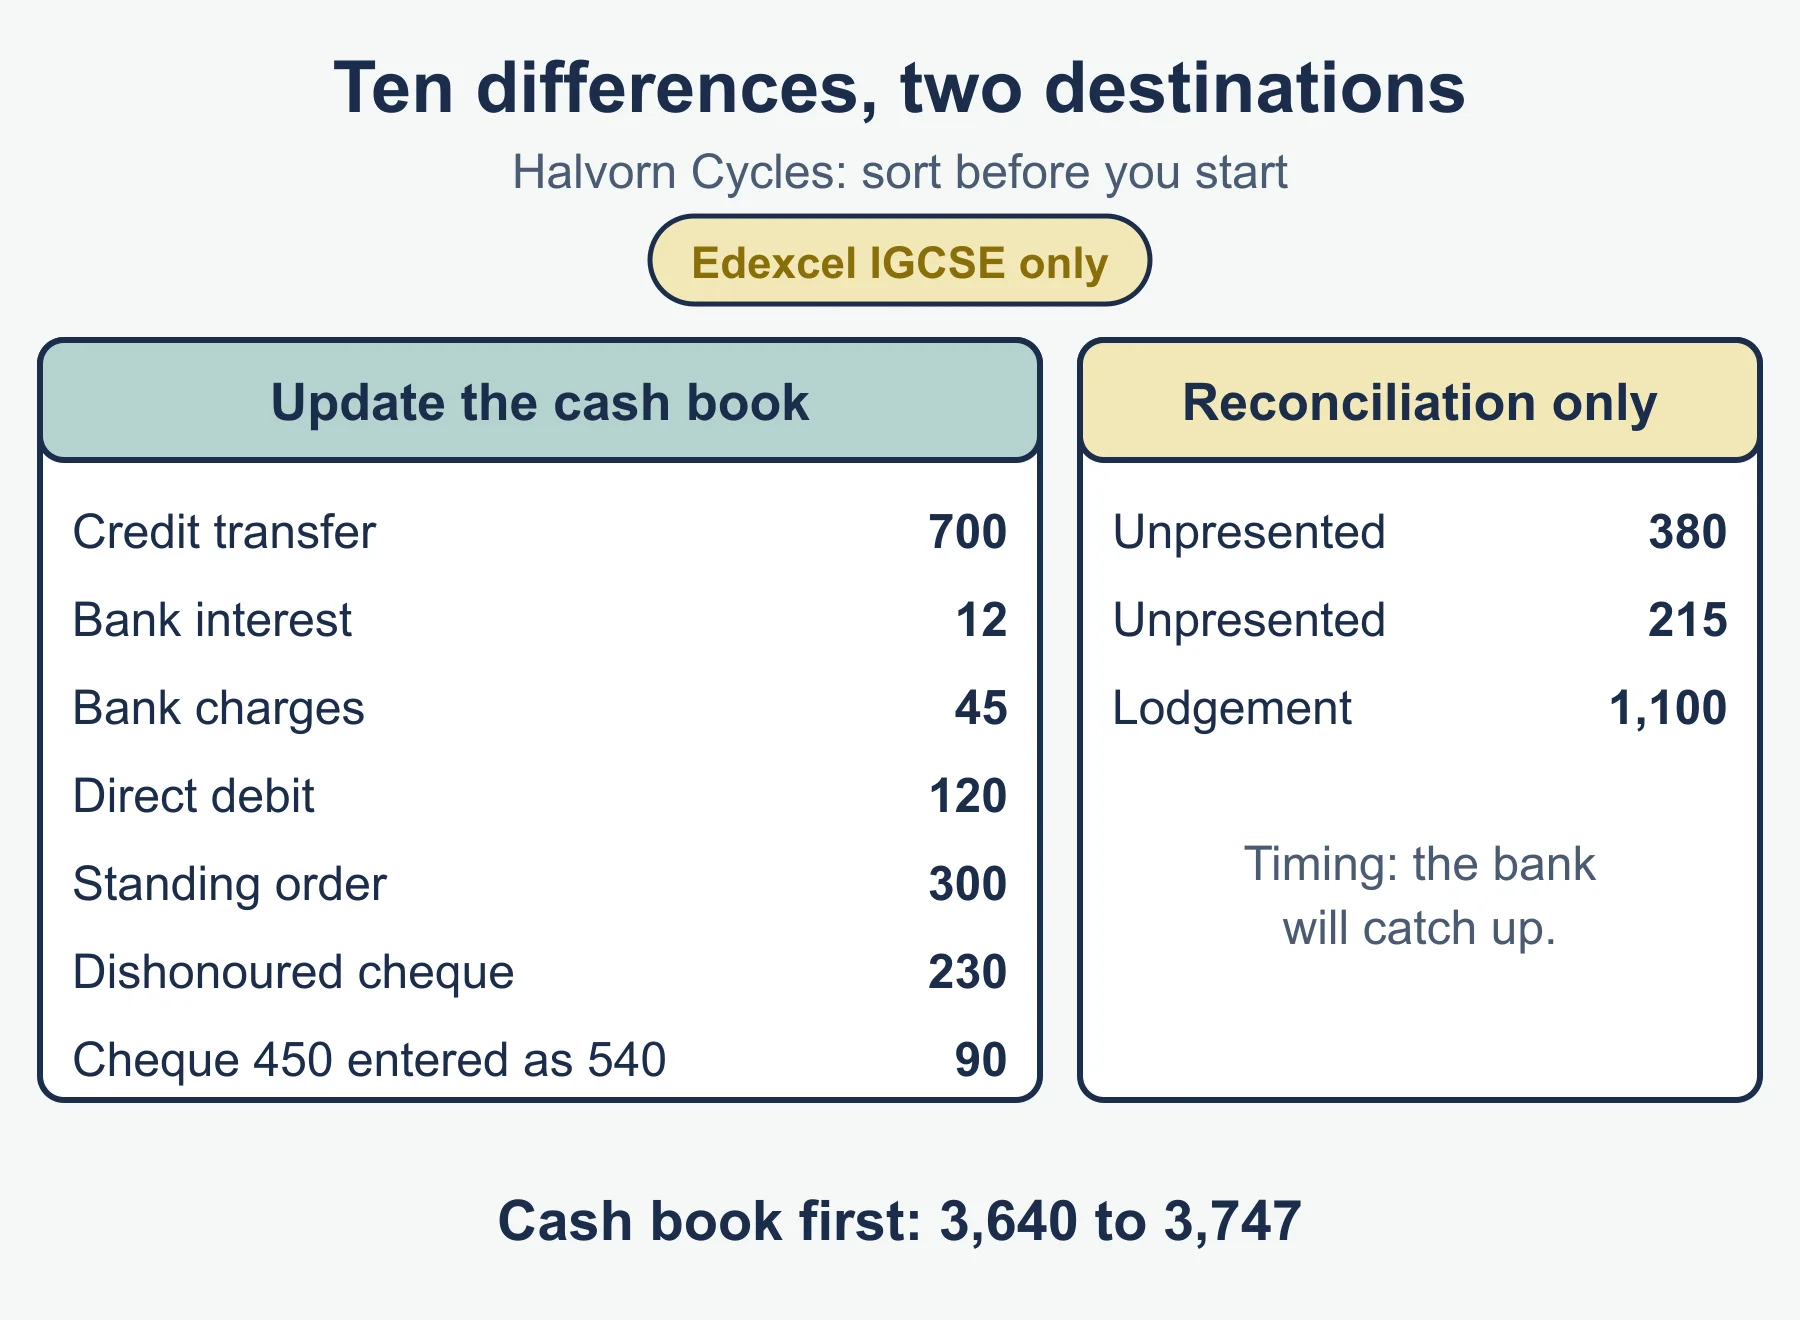
| On the statement, not the cash book | Credit transfers, bank interest, bank charges, standing orders, direct debits, dishonoured cheques | Update the cash book |
| In the cash book wrongly | Error by the business | Correct the cash book |
| In the cash book, not the statement | Unpresented cheques, uncredited lodgements (banked but not yet shown) | Put on the reconciliation statement |
| On the statement wrongly | Bank error | Put on the reconciliation statement and tell the bank |
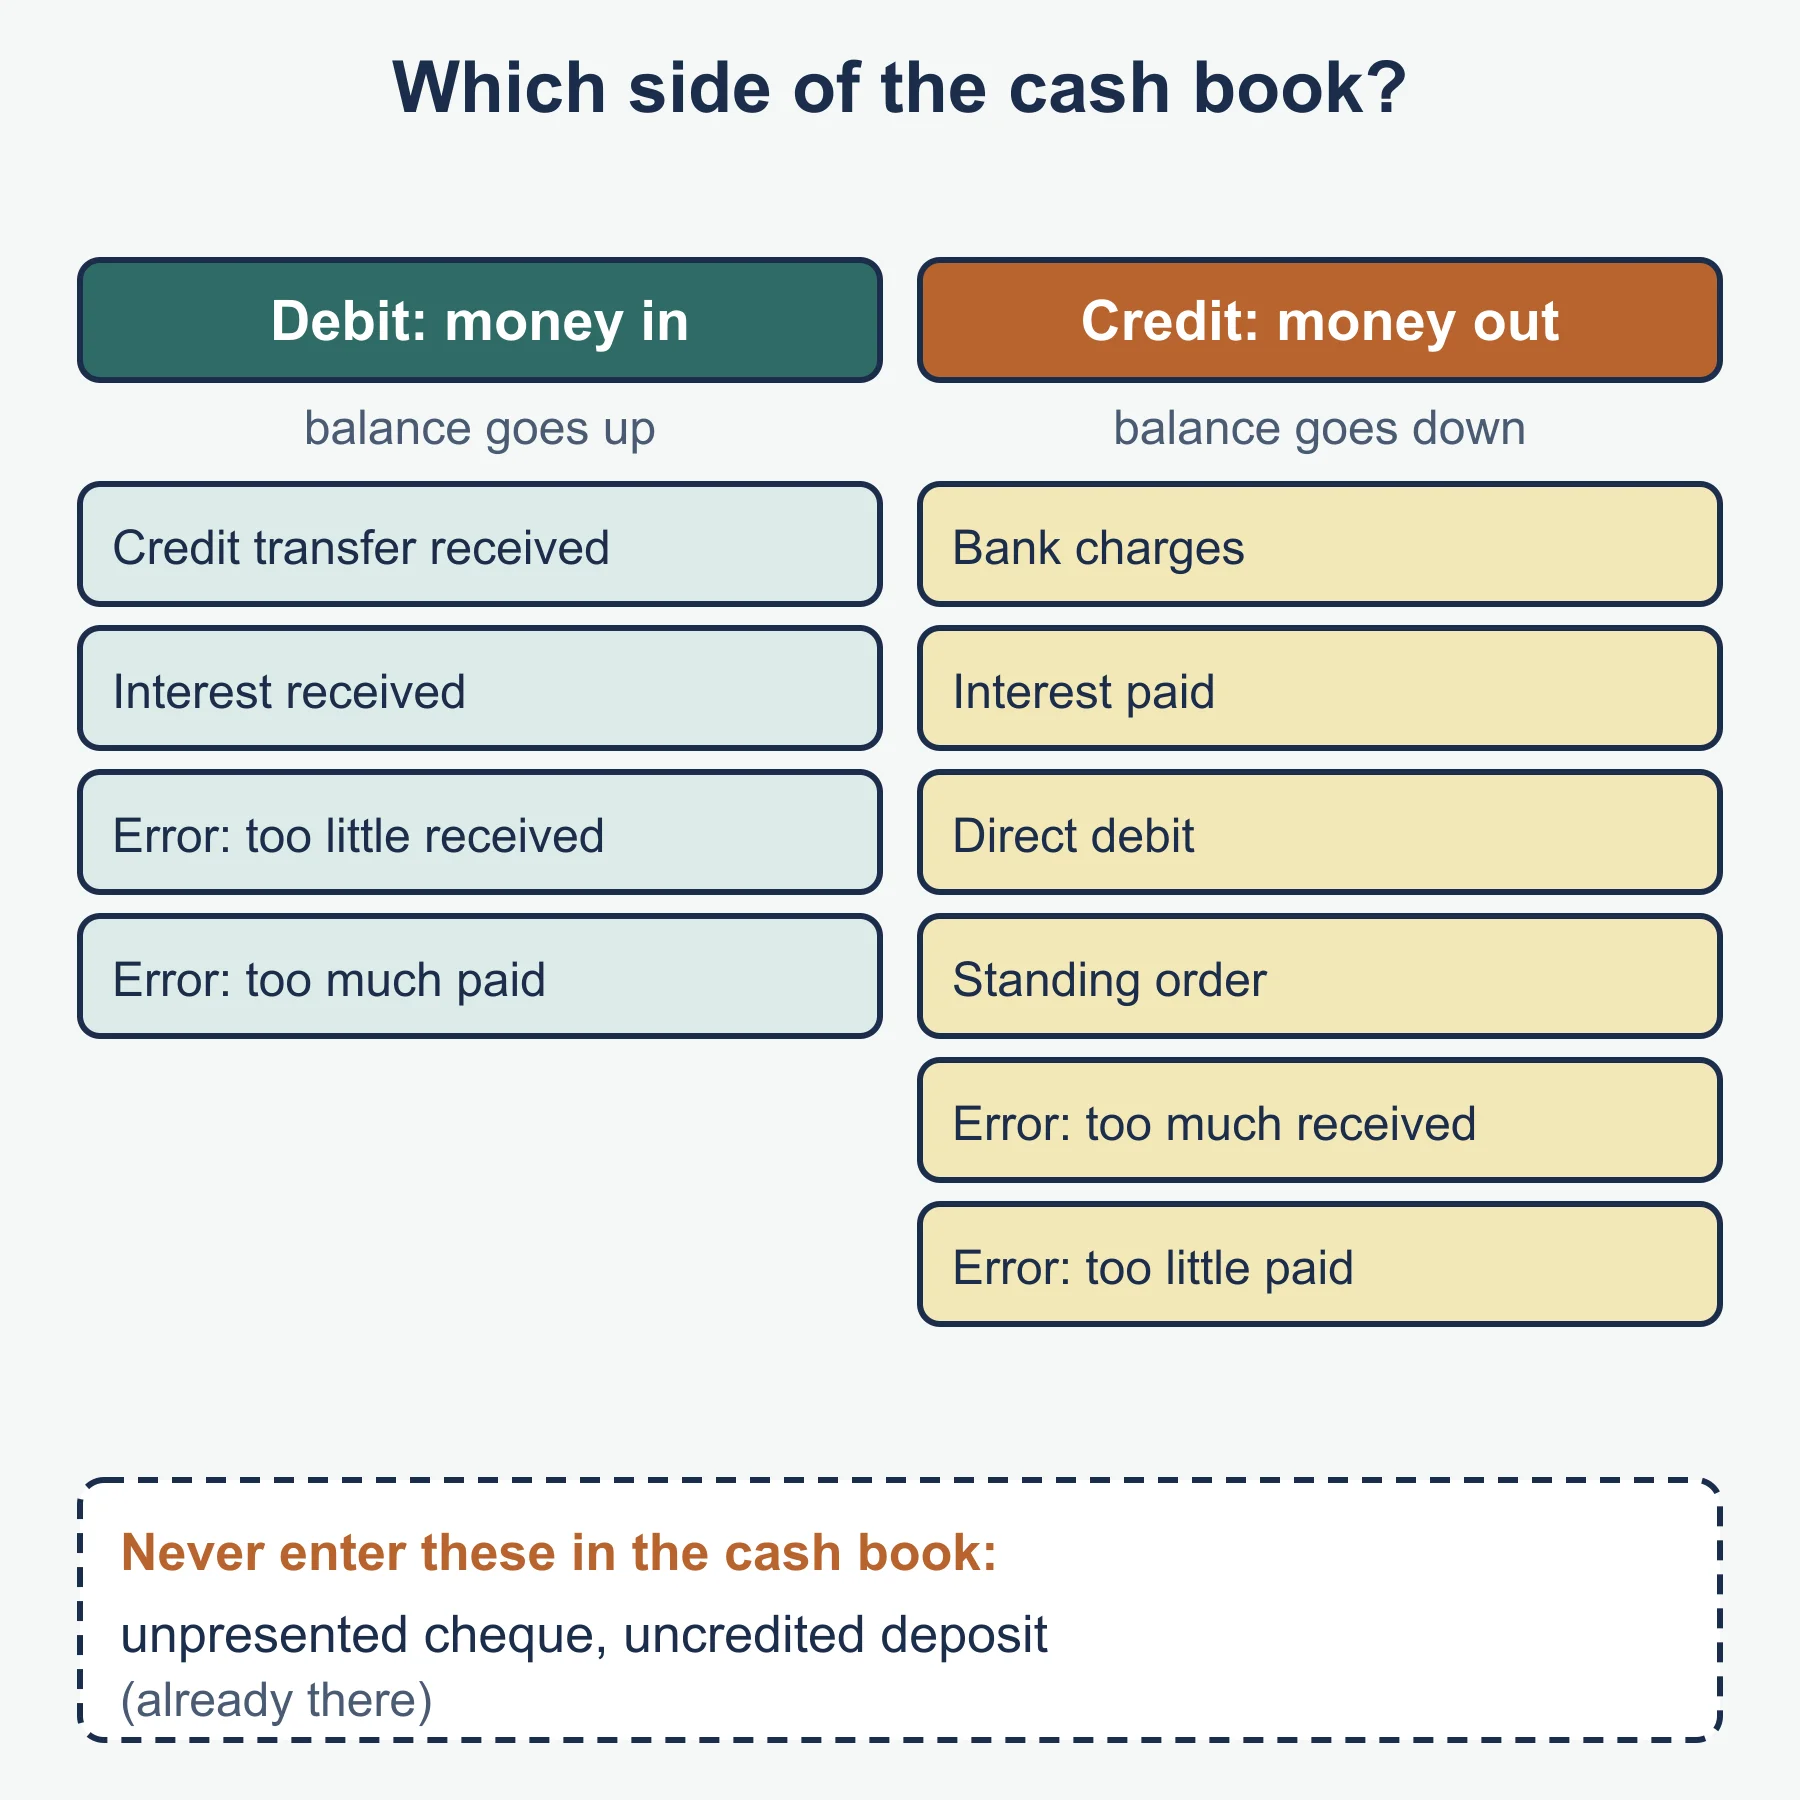
Update the cash book first. Only the timing items, and any bank error, are left for the reconciliation statement. A statement shows a credit balance when the bank holds money for you, because it is a liability of the bank. Your cash book shows the same position as a debit.
Worked example: Halvorn Cycles
At 31 October 2026 the cash book (bank column) of Halvorn Cycles shows a debit balance of 3,640. Comparing it with the bank statement gives these differences.
- Credit transfer from a customer, 700, not in the cash book.
- Bank interest received, 12, not in the cash book.
- Bank charges, 45, not in the cash book.
- Direct debit for insurance, 120, not in the cash book.
- Standing order for a loan repayment, 300, not in the cash book.
- A customer’s cheque for 230 was dishonoured and is on the statement only.
- A cheque to a supplier for 450 was entered in the cash book as 540.
- Cheques of 380 and 215 to suppliers have not been presented.
- A lodgement of 1,100 made on 31 October is not yet on the statement.
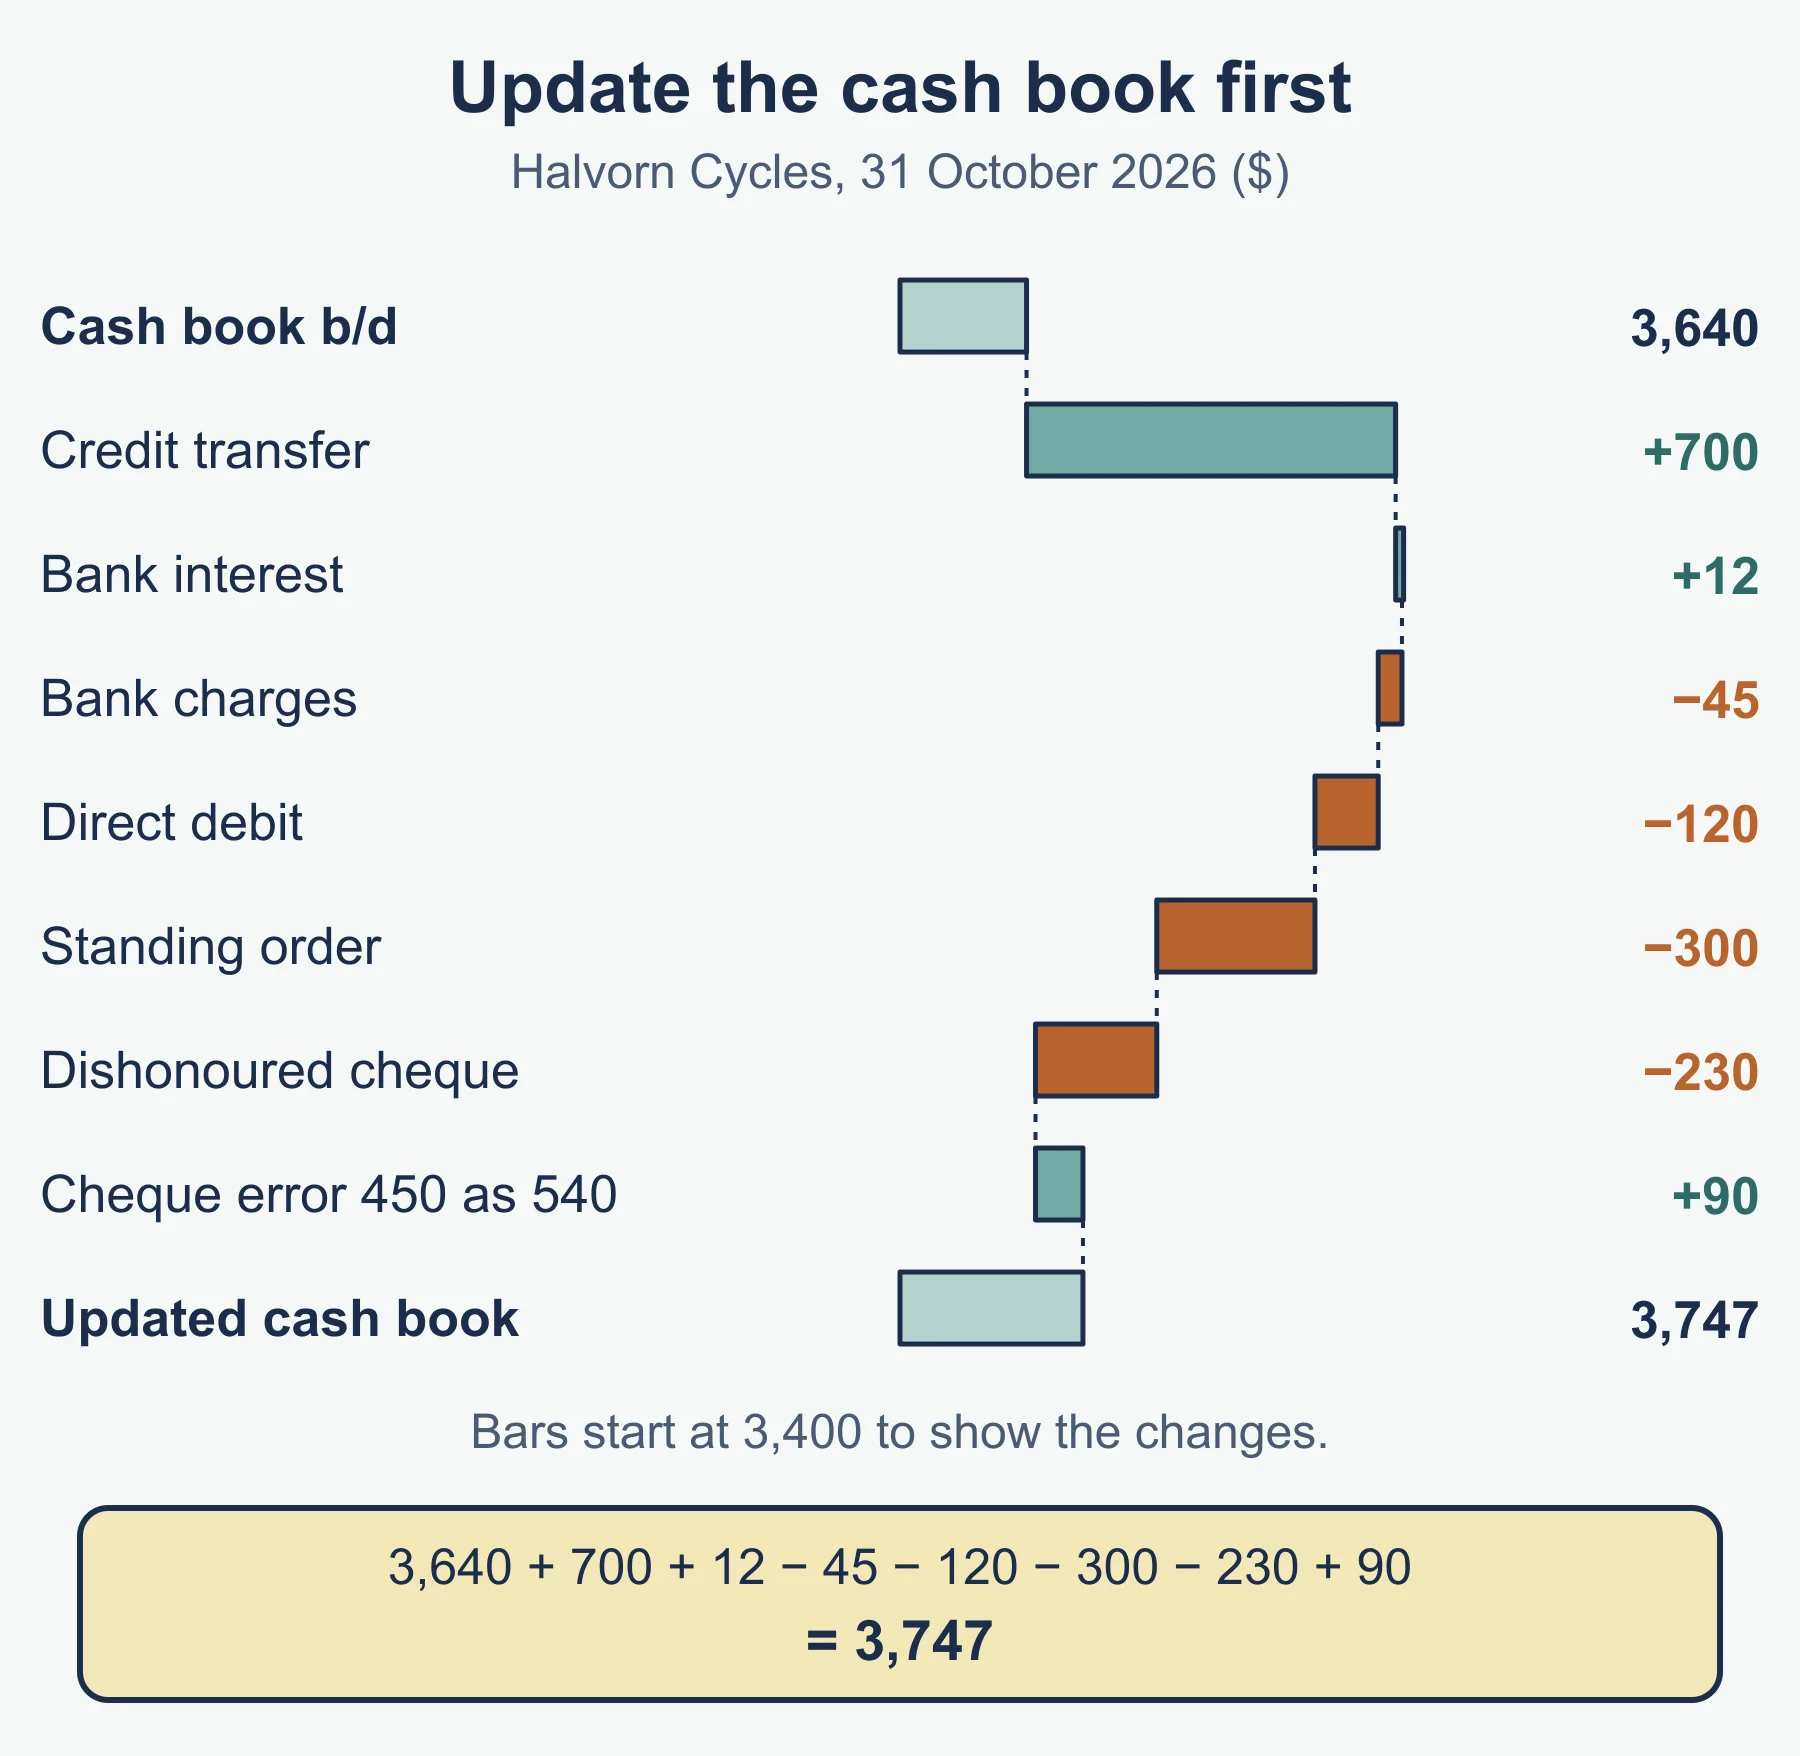
Step 1: update the cash book. The error understated the balance by 90, so it is added back.
| Cash book (bank) | |||
|---|---|---|---|
| Balance b/d | 3,640 | Bank charges | 45 |
| Credit transfer | 700 | Direct debit | 120 |
| Bank interest | 12 | Standing order | 300 |
| Correction: cheque error | 90 | Dishonoured cheque | 230 |
| Balance c/d | 3,747 | ||
| 4,442 | 4,442 |
Step 2: prepare the bank reconciliation statement.
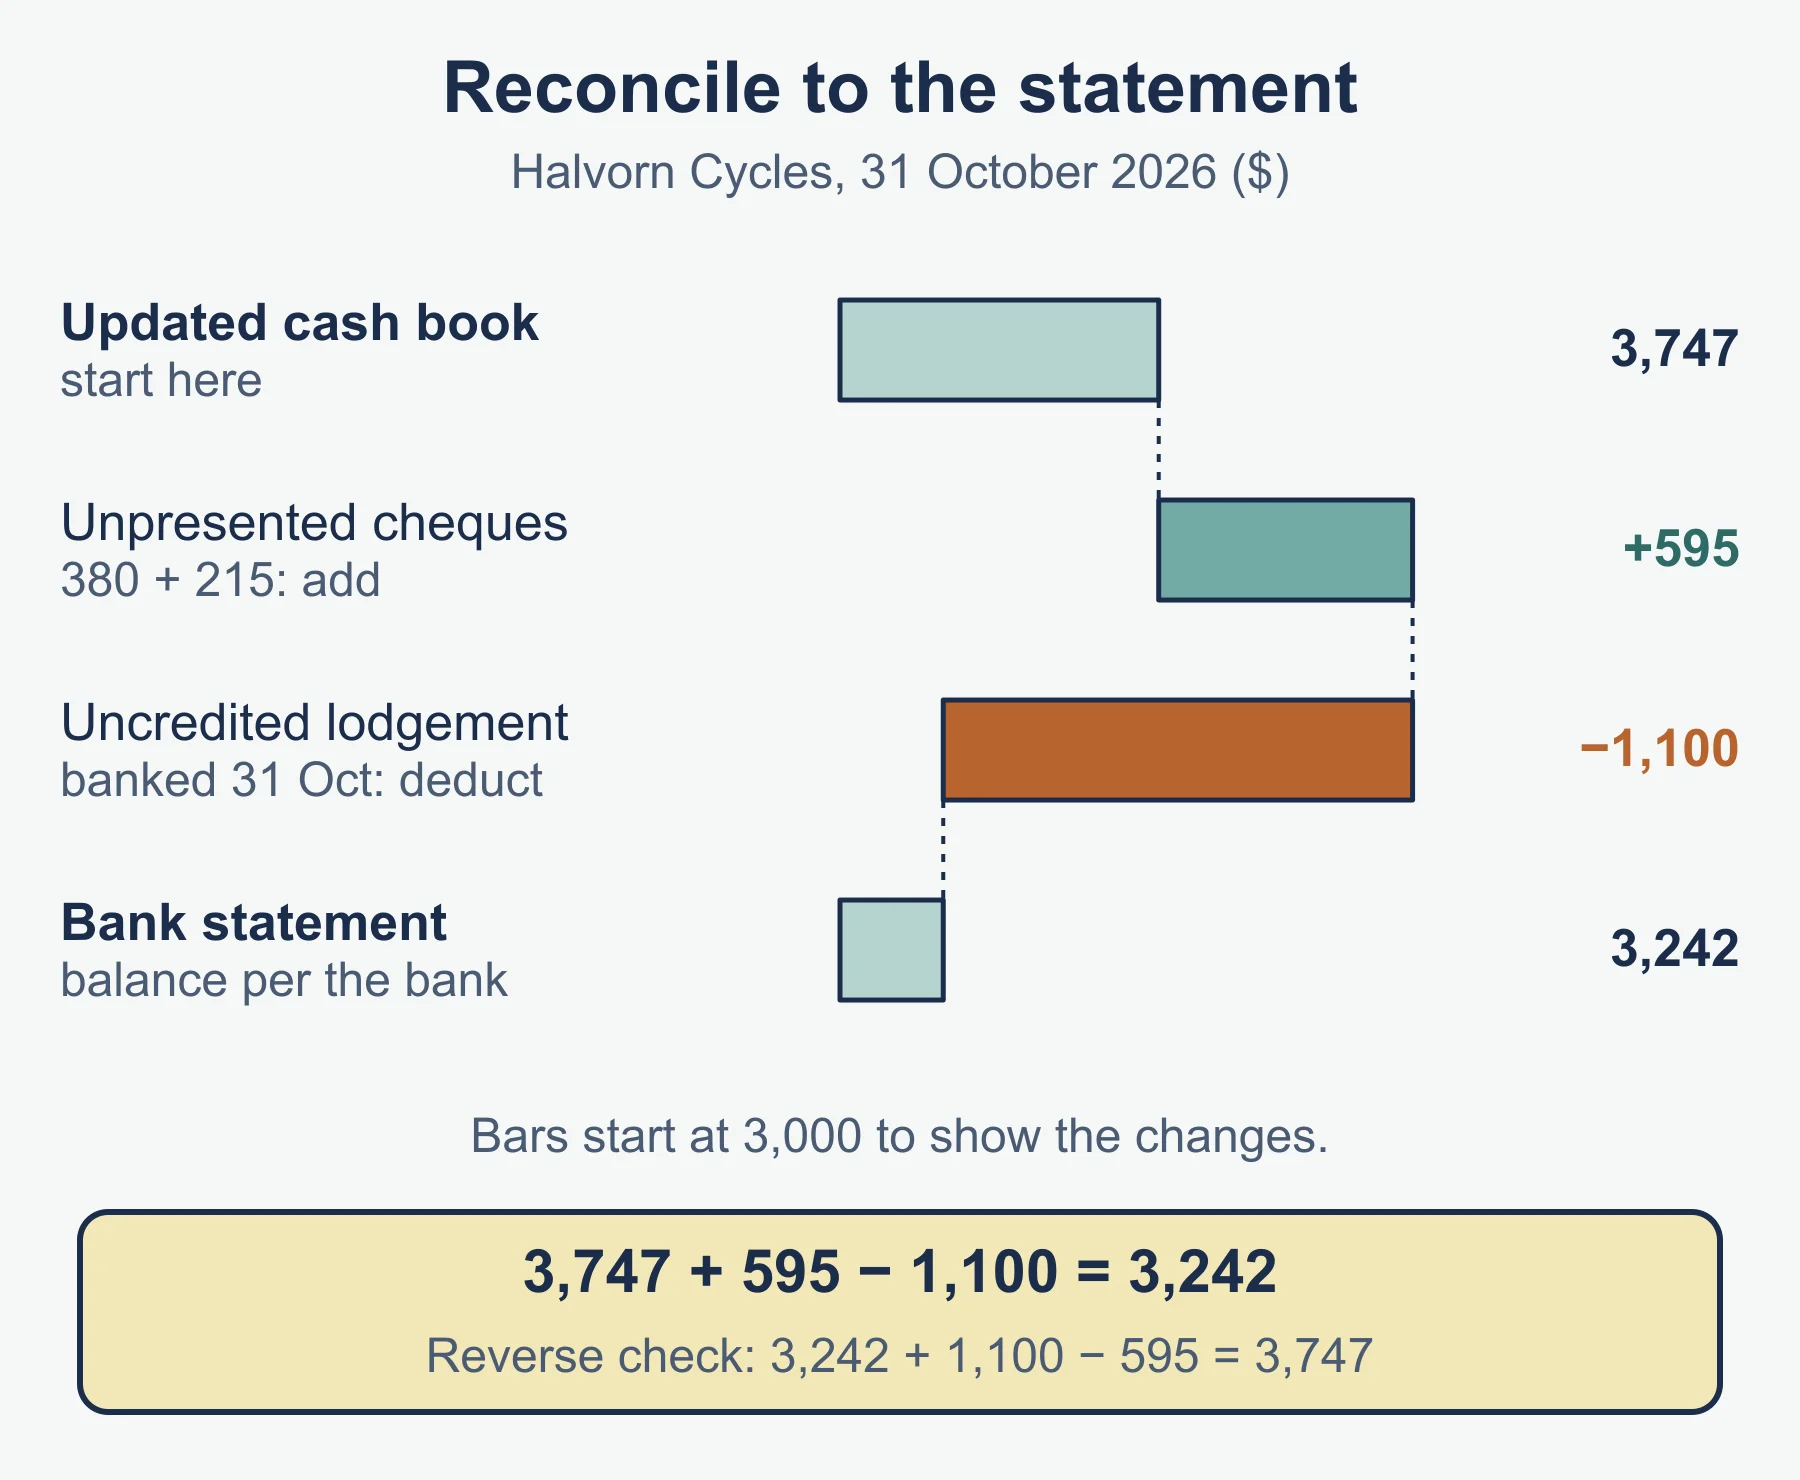
| Bank reconciliation statement at 31 October 2026 | |
|---|---|
| Balance per updated cash book | 3,747 |
| Add: unpresented cheques (380 + 215) | 595 |
| 4,342 | |
| Less: uncredited lodgement | 1,100 |
| Balance per bank statement | 3,242 |
The reverse route gives the same result: 3,242 + 1,100 − 595 = 3,747. Give the statement a heading, a date and a labelled final line.
Common errors
- Putting the suspense difference on the wrong side. Check which total is higher, then put the difference on the side that is lower.
- Posting a one-sided correction to suspense in the wrong direction. Say whether suspense was debited or credited when the error was made, then reverse it.
- Journalising an error of principle without clearing the original wrong account.
- Treating a compensating error as if it needs suspense.
- Using the single amount to correct a complete reversal, when double is needed.
- Adjusting the cash book for unpresented cheques. They belong on the reconciliation only.
- Adding a dishonoured cheque to the cash book. It reduces the balance.
- Starting the reconciliation from the unadjusted cash book balance.
Next, try the practice questions.
Frequently asked questions
What is a bank reconciliation statement in Edexcel IGCSE Accounting? A bank reconciliation statement explains the difference between the balance in the cash book (bank column) and the balance on the bank statement at a given date. It checks both records, finds missing entries such as bank charges, and helps detect fraud.
Why does a bank statement show a credit balance when the business has money in the bank? The bank statement is the bank’s record, and money held for the business is a liability of the bank, so it shows as a credit. The business’s cash book shows the same position as a debit balance.
Which items are entered in the cash book before preparing the reconciliation? Items on the bank statement but missing from the cash book, such as credit transfers, interest, bank charges, direct debits, standing orders and dishonoured cheques, are entered in the cash book first, along with any cash book errors. Only timing items and bank errors are left for the reconciliation statement.
What is a suspense account? A suspense account is a temporary ledger account that holds the difference when a trial balance does not agree. Once the errors are found and corrected, the account should clear to nil.
Which errors do not affect the trial balance? Errors of omission, commission, principle, original entry, compensating errors and complete reversals leave the trial balance agreeing, because equal debits and credits are still posted. The 4AC1 specification does not name these types, so describe each error in words too.
Official syllabus
Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016, published by Pearson Education Limited – Topic 3 Introduction to control processes, sections 3 Correction of errors and 4 Bank reconciliation statements, numbered 3.3 and 3.4 here.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
Edexcel IGCSE Accounting: Correction of errors and bank reconciliation statements (4AC1) – Practice Questions
Twelve original Edexcel IGCSE Accounting questions on error types, correcting journals, suspense accounts and bank reconciliation statements, fully marked.
Accounting · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Accounting: Correction of errors and bank reconciliation statements (4AC1) – Revision Notes
Condensed Edexcel IGCSE Accounting revision notes on error types, correcting journals, suspense accounts and bank reconciliation, with a self-test.
Accounting · Pearson Edexcel · IGCSE
Revise topic -
Study guides
Edexcel IGCSE Accounting: Trial balance and control accounts (4AC1)
Study guide to the trial balance and to trade receivables and trade payables control accounts for Pearson Edexcel International GCSE Accounting 4AC1.
Accounting · Pearson Edexcel · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Accounting teachers at Marlbridge

