
Revision Notes
Edexcel IGCSE Business: Costs and break-even analysis (4BS1) – Revision Notes
Condensed revision notes on costs, profit, break-even output and break-even charts for Edexcel International GCSE Business 4BS1, section 3.3.
- Subject
- Business
- Level
- IGCSE
- Topic
- Business finance
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Asif Iqbal (what this means)
Aligned to Pearson Edexcel IGCSE Business (4BS1), Issue 2, February 2026. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Business.
Syllabus points this page covers
4BS1
- 3 Business finance (whole topic)
- 3.3 Costs and break-even analysis
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Business online. Request a free trial class.
These notes condense section 3.3 Costs and break-even analysis of the Pearson Edexcel International GCSE in Business (4BS1) specification, Issue 2, February 2026. For full explanations and worked examples, read the study guide. When you are ready to test yourself, use the practice questions. Both Paper 1 (small businesses) and Paper 2 (large businesses) can draw on this topic. Course links: Edexcel IGCSE Business hub, the printable checklist and the free 10-minute diagnostics.
The three outcomes at a glance
| Ref | Outcome | One-line summary |
|---|---|---|
| 3.3.1 | Concept and calculation of revenue, fixed and variable costs, total costs, profit and loss | Revenue − total costs = profit or loss |
| 3.3.2 | Concept of break-even and calculation of break-even level of output, from formula or diagram | Output where revenue = total costs |
| 3.3.3 | Interpret break-even charts: impact of changes in revenue and costs; limitations | Lines move, break-even moves; the model has weaknesses |
Definitions
| Term | Meaning |
|---|---|
| Revenue | Money received from sales: price per unit × quantity sold |
| Fixed costs | Costs that do not change with output in the short run (rent, insurance) |
| Variable costs | Costs that change in direct proportion to output (materials, packaging) |
| Total costs | Fixed costs + total variable costs |
| Profit | Revenue − total costs, when the answer is positive |
| Loss | Revenue − total costs, when the answer is negative |
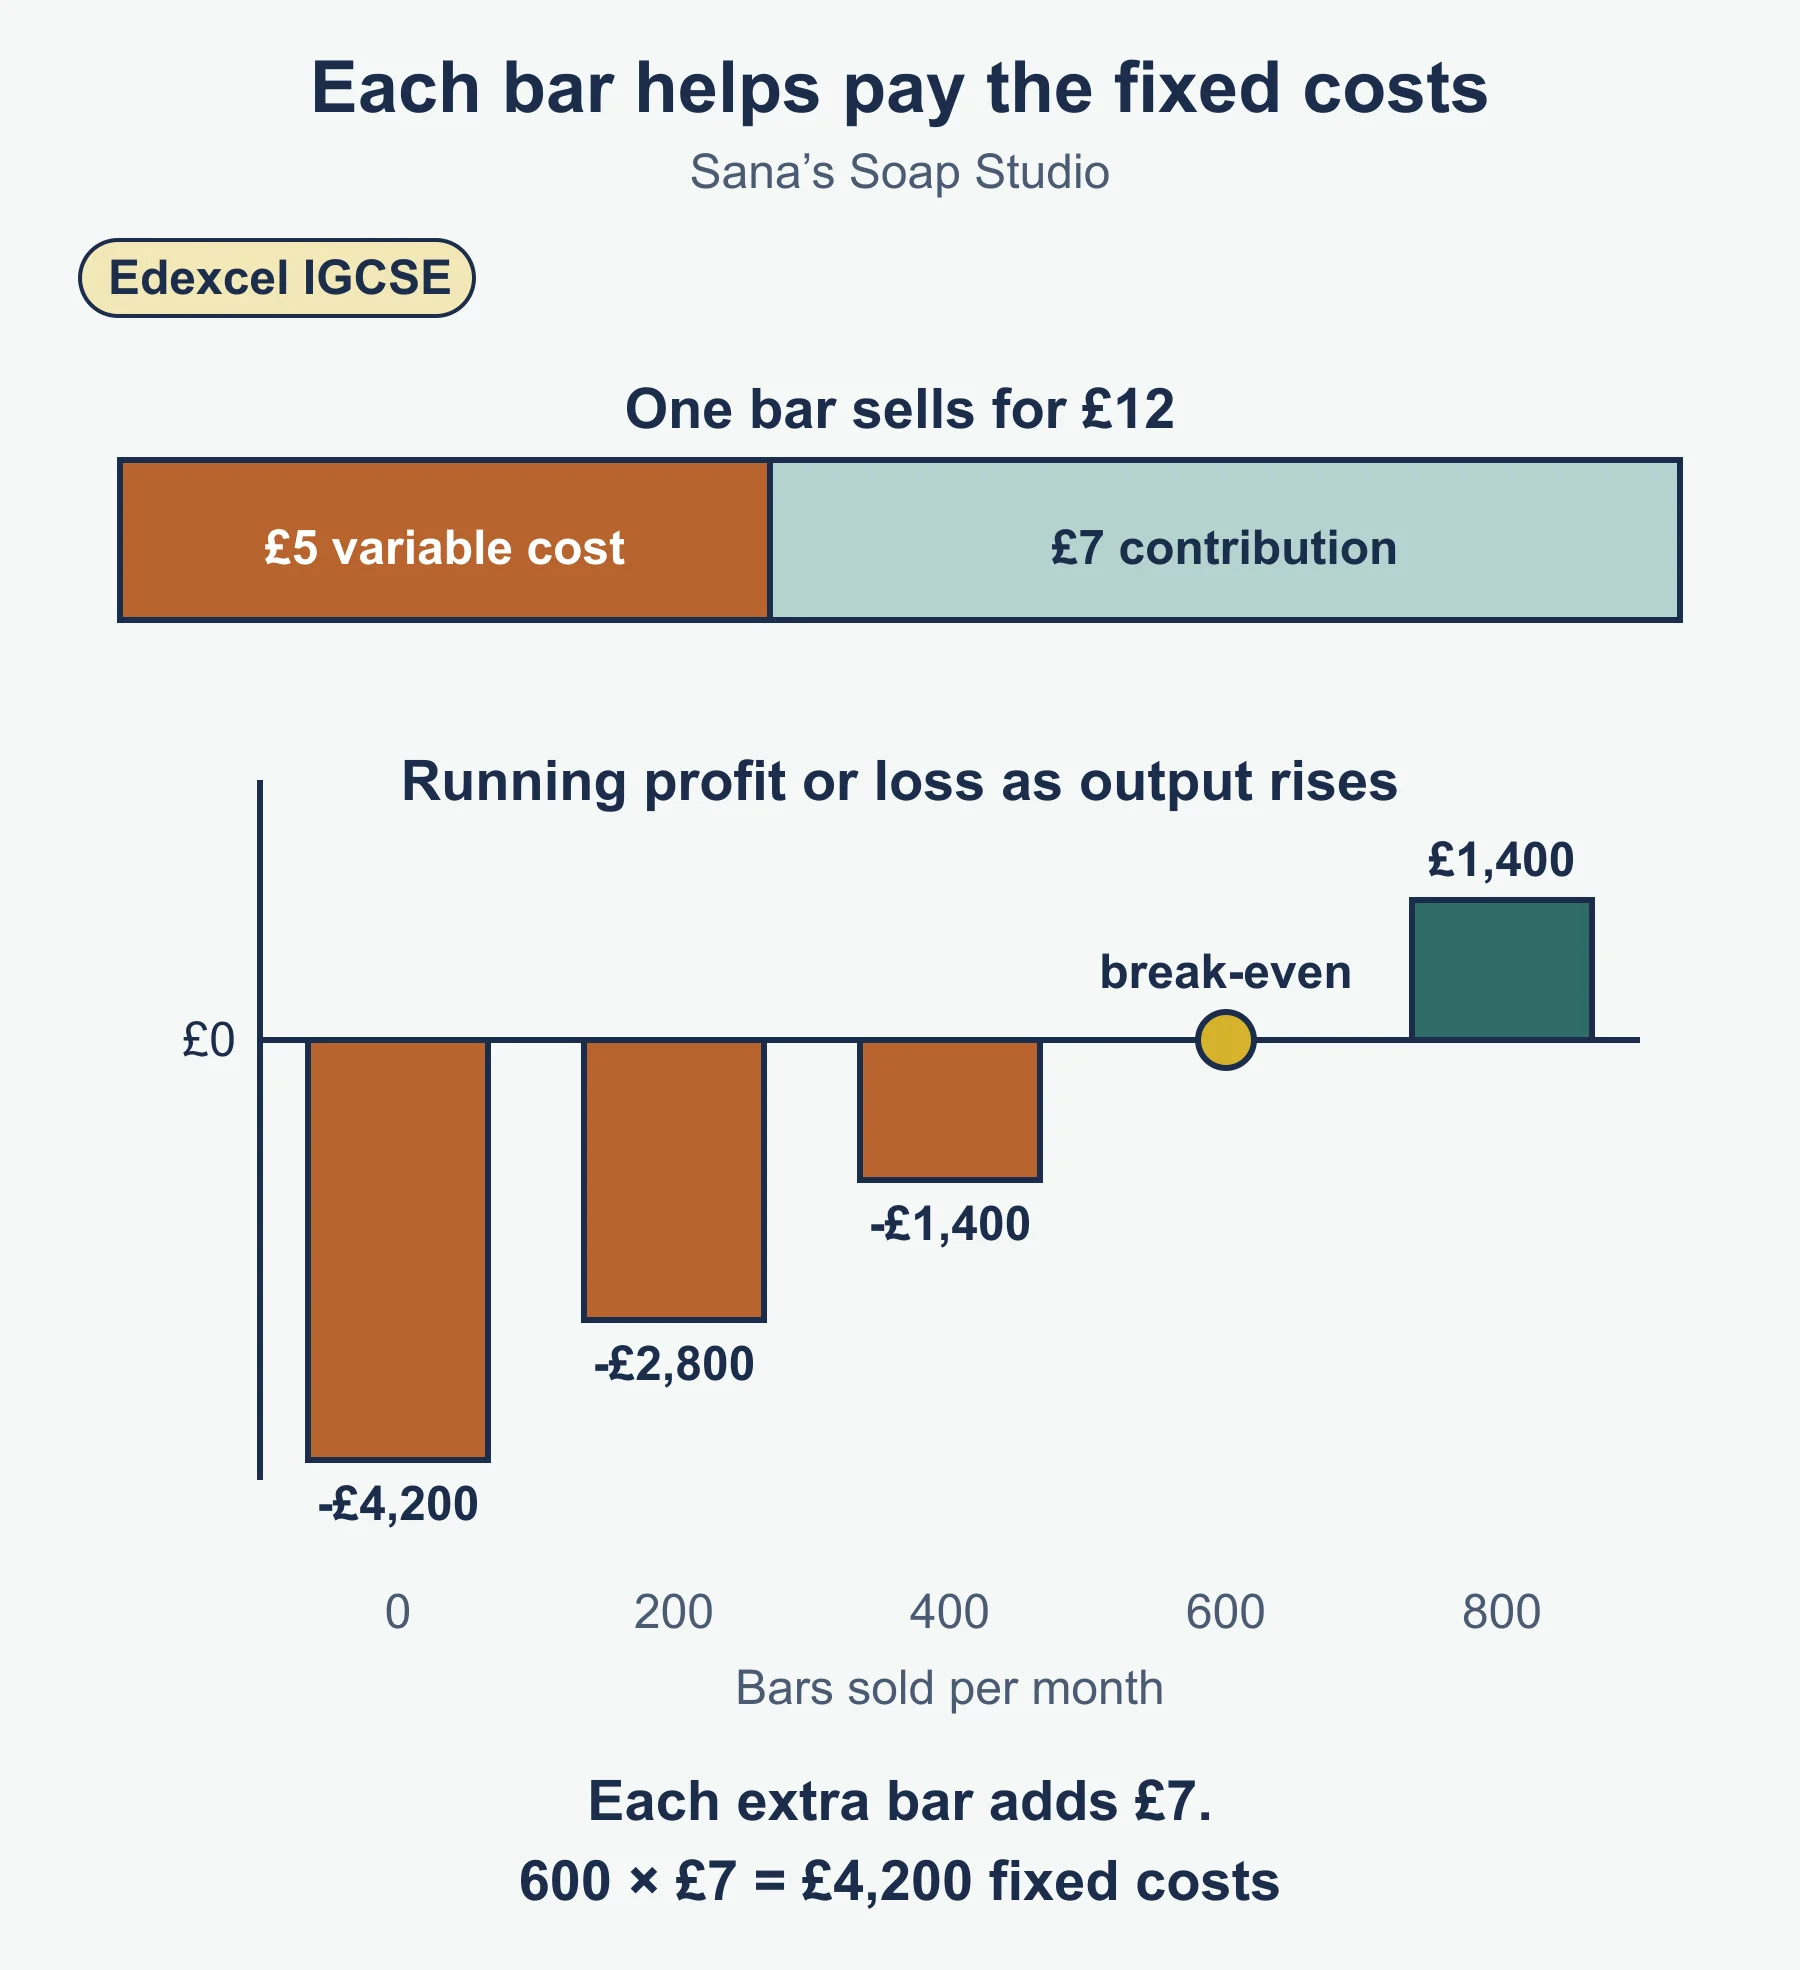
| Break-even level of output | Output at which revenue equals total costs, so profit is zero |
| Contribution per unit | Selling price per unit − variable cost per unit (standard form; not given in the specification) |
Formulas
| What you want | Formula |
|---|---|
| Revenue | price × quantity |
| Total variable cost | variable cost per unit × quantity |
| Total costs | fixed costs + total variable costs |
| Profit or loss | revenue − total costs |
| Break-even output | fixed costs ÷ contribution per unit |
| Profit above break-even | (output − break-even output) × contribution per unit |
| Break-even revenue | break-even output × price |
The specification does not give a break-even formula, so the standard form above is what you learn. Rounding break-even output up to a whole unit is the writer’s own advice, not specification text.
Method in steps: calculating break-even
- Write down price per unit, variable cost per unit and fixed costs.
- Contribution per unit = price − variable cost per unit.
- Break-even output = fixed costs ÷ contribution per unit.
- Round up to a whole unit if needed and state the unit (bars, cups, repairs).
- If asked, find break-even revenue or profit at a given output.
- Check: at that output, does revenue equal total costs?
Worked reminder
A workshop sells wooden stools at £30. Variable cost is £18 a stool. Fixed costs are £6,600 a month.
- Contribution = 30 − 18 = £12.
- Break-even = 6,600 ÷ 12 = 550 stools. Break-even revenue = 550 × 30 = £16,500.
- If variable cost rises to £20, contribution is £10 and break-even is 660.
- If fixed costs rise to £7,800, break-even is 7,800 ÷ 12 = 650.
- If price rises to £32, contribution is £14 and break-even is 6,600 ÷ 14 = 471.4, so 472 stools.
Method in steps: reading a break-even chart
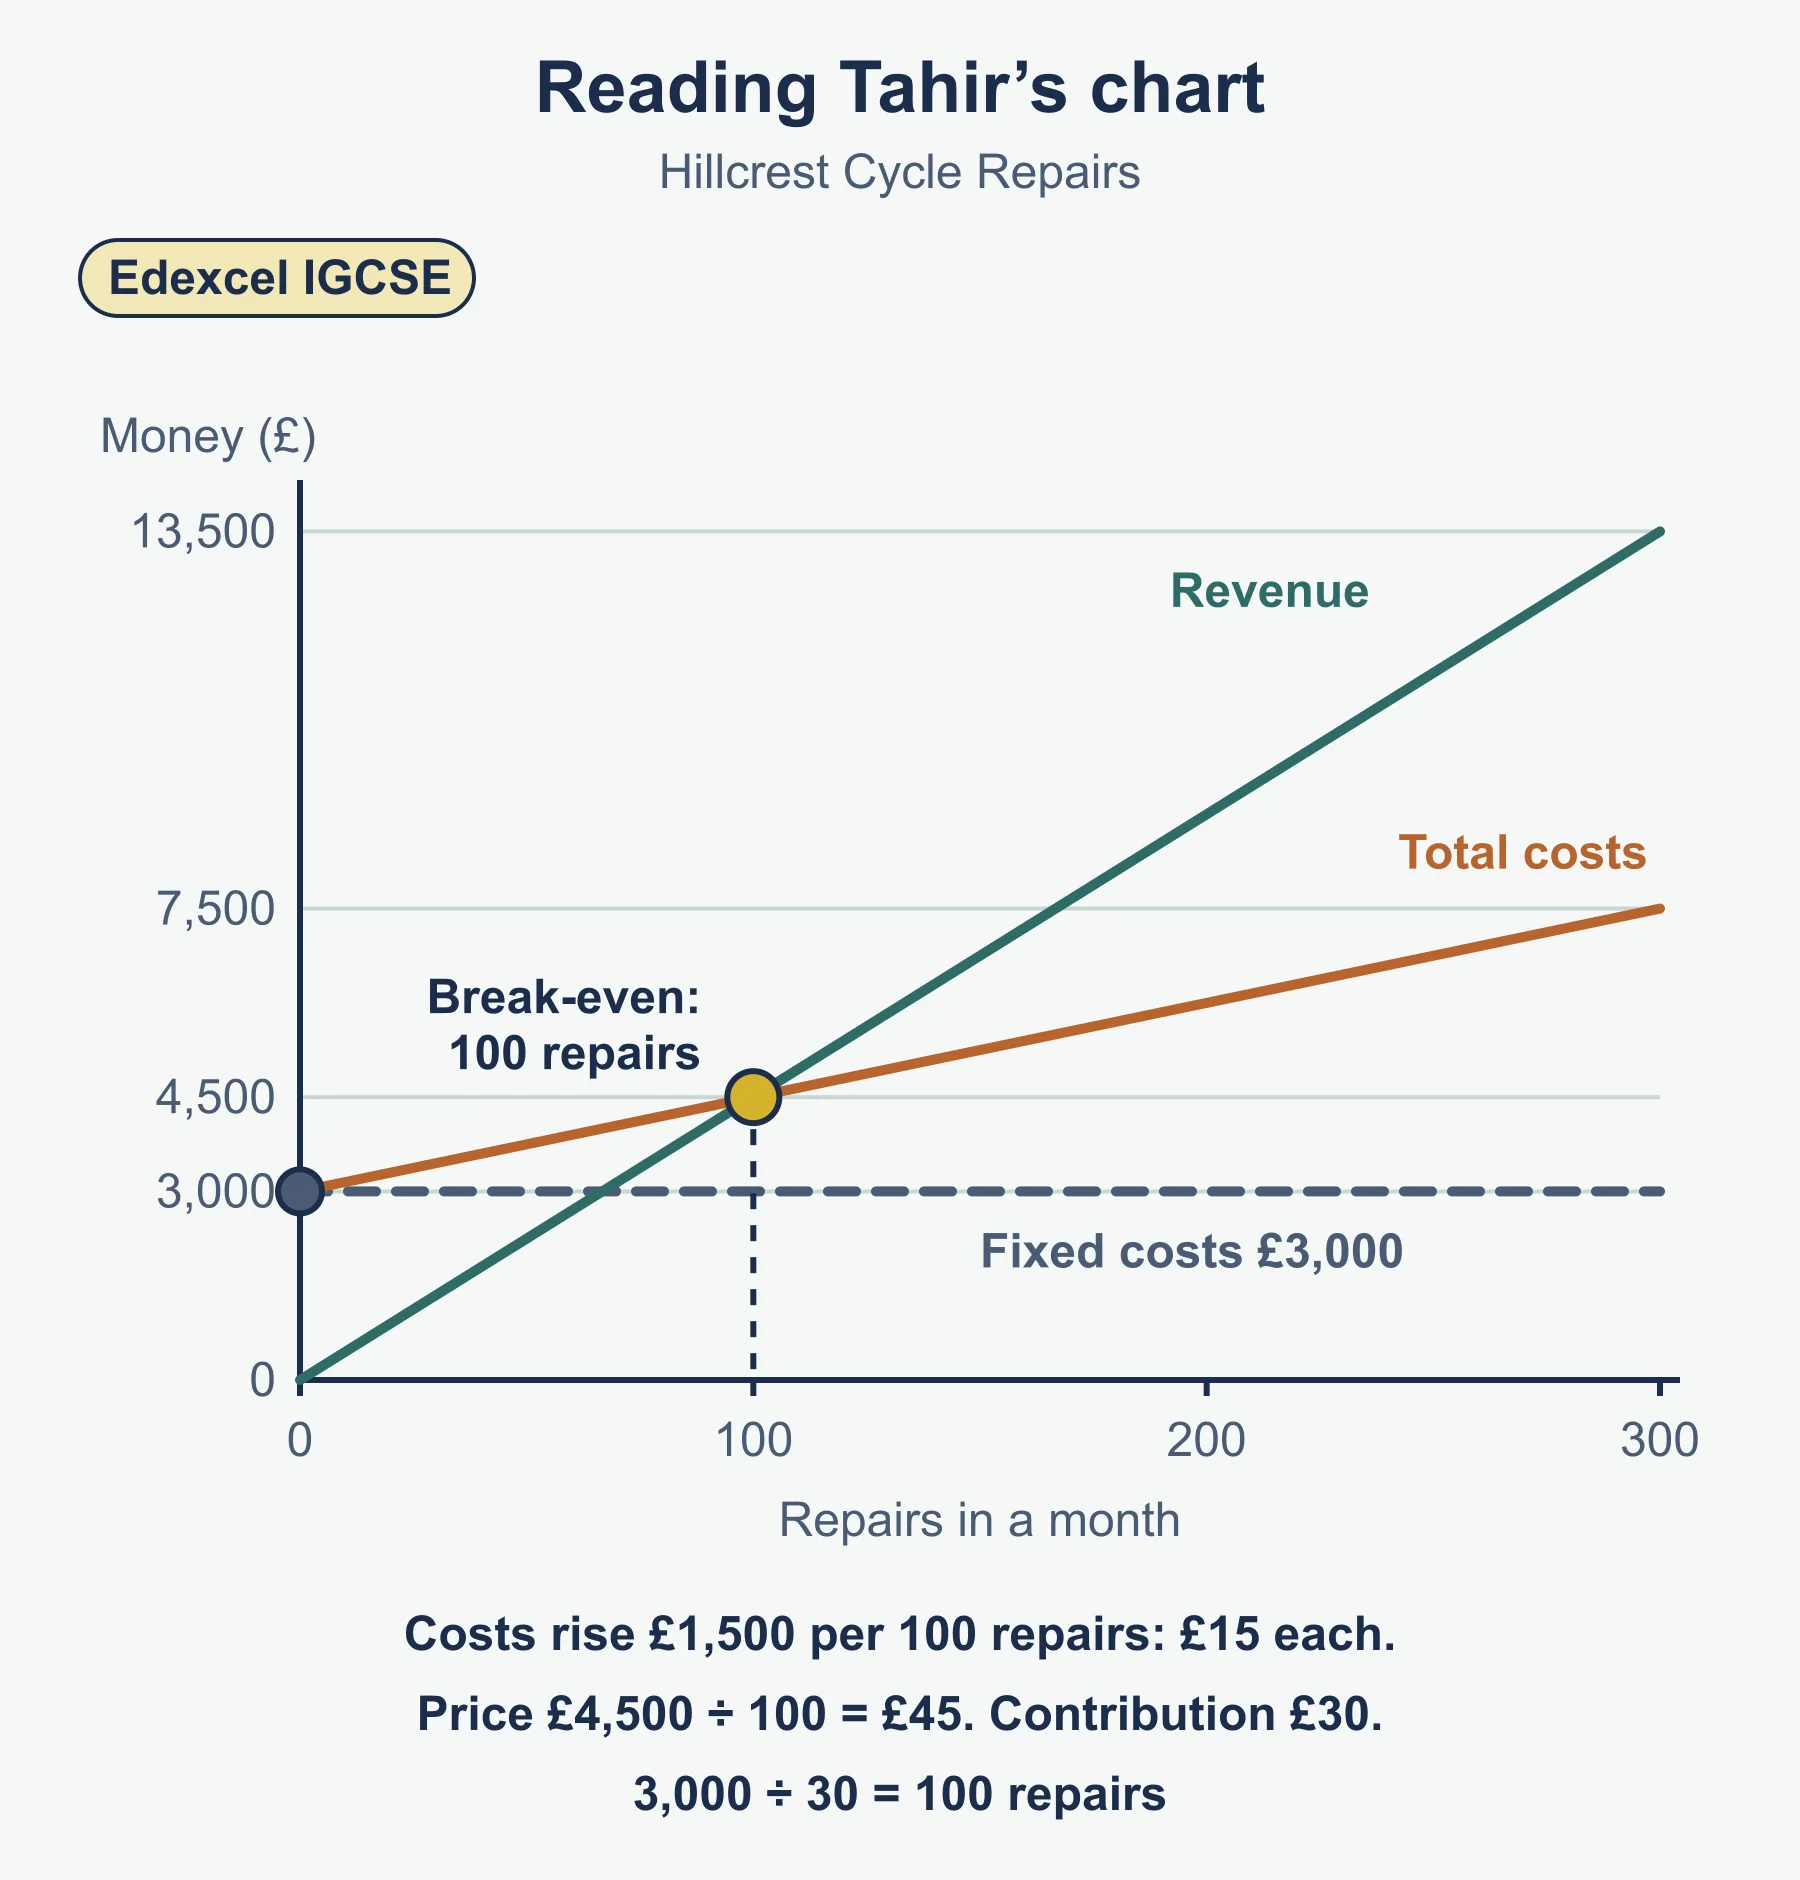
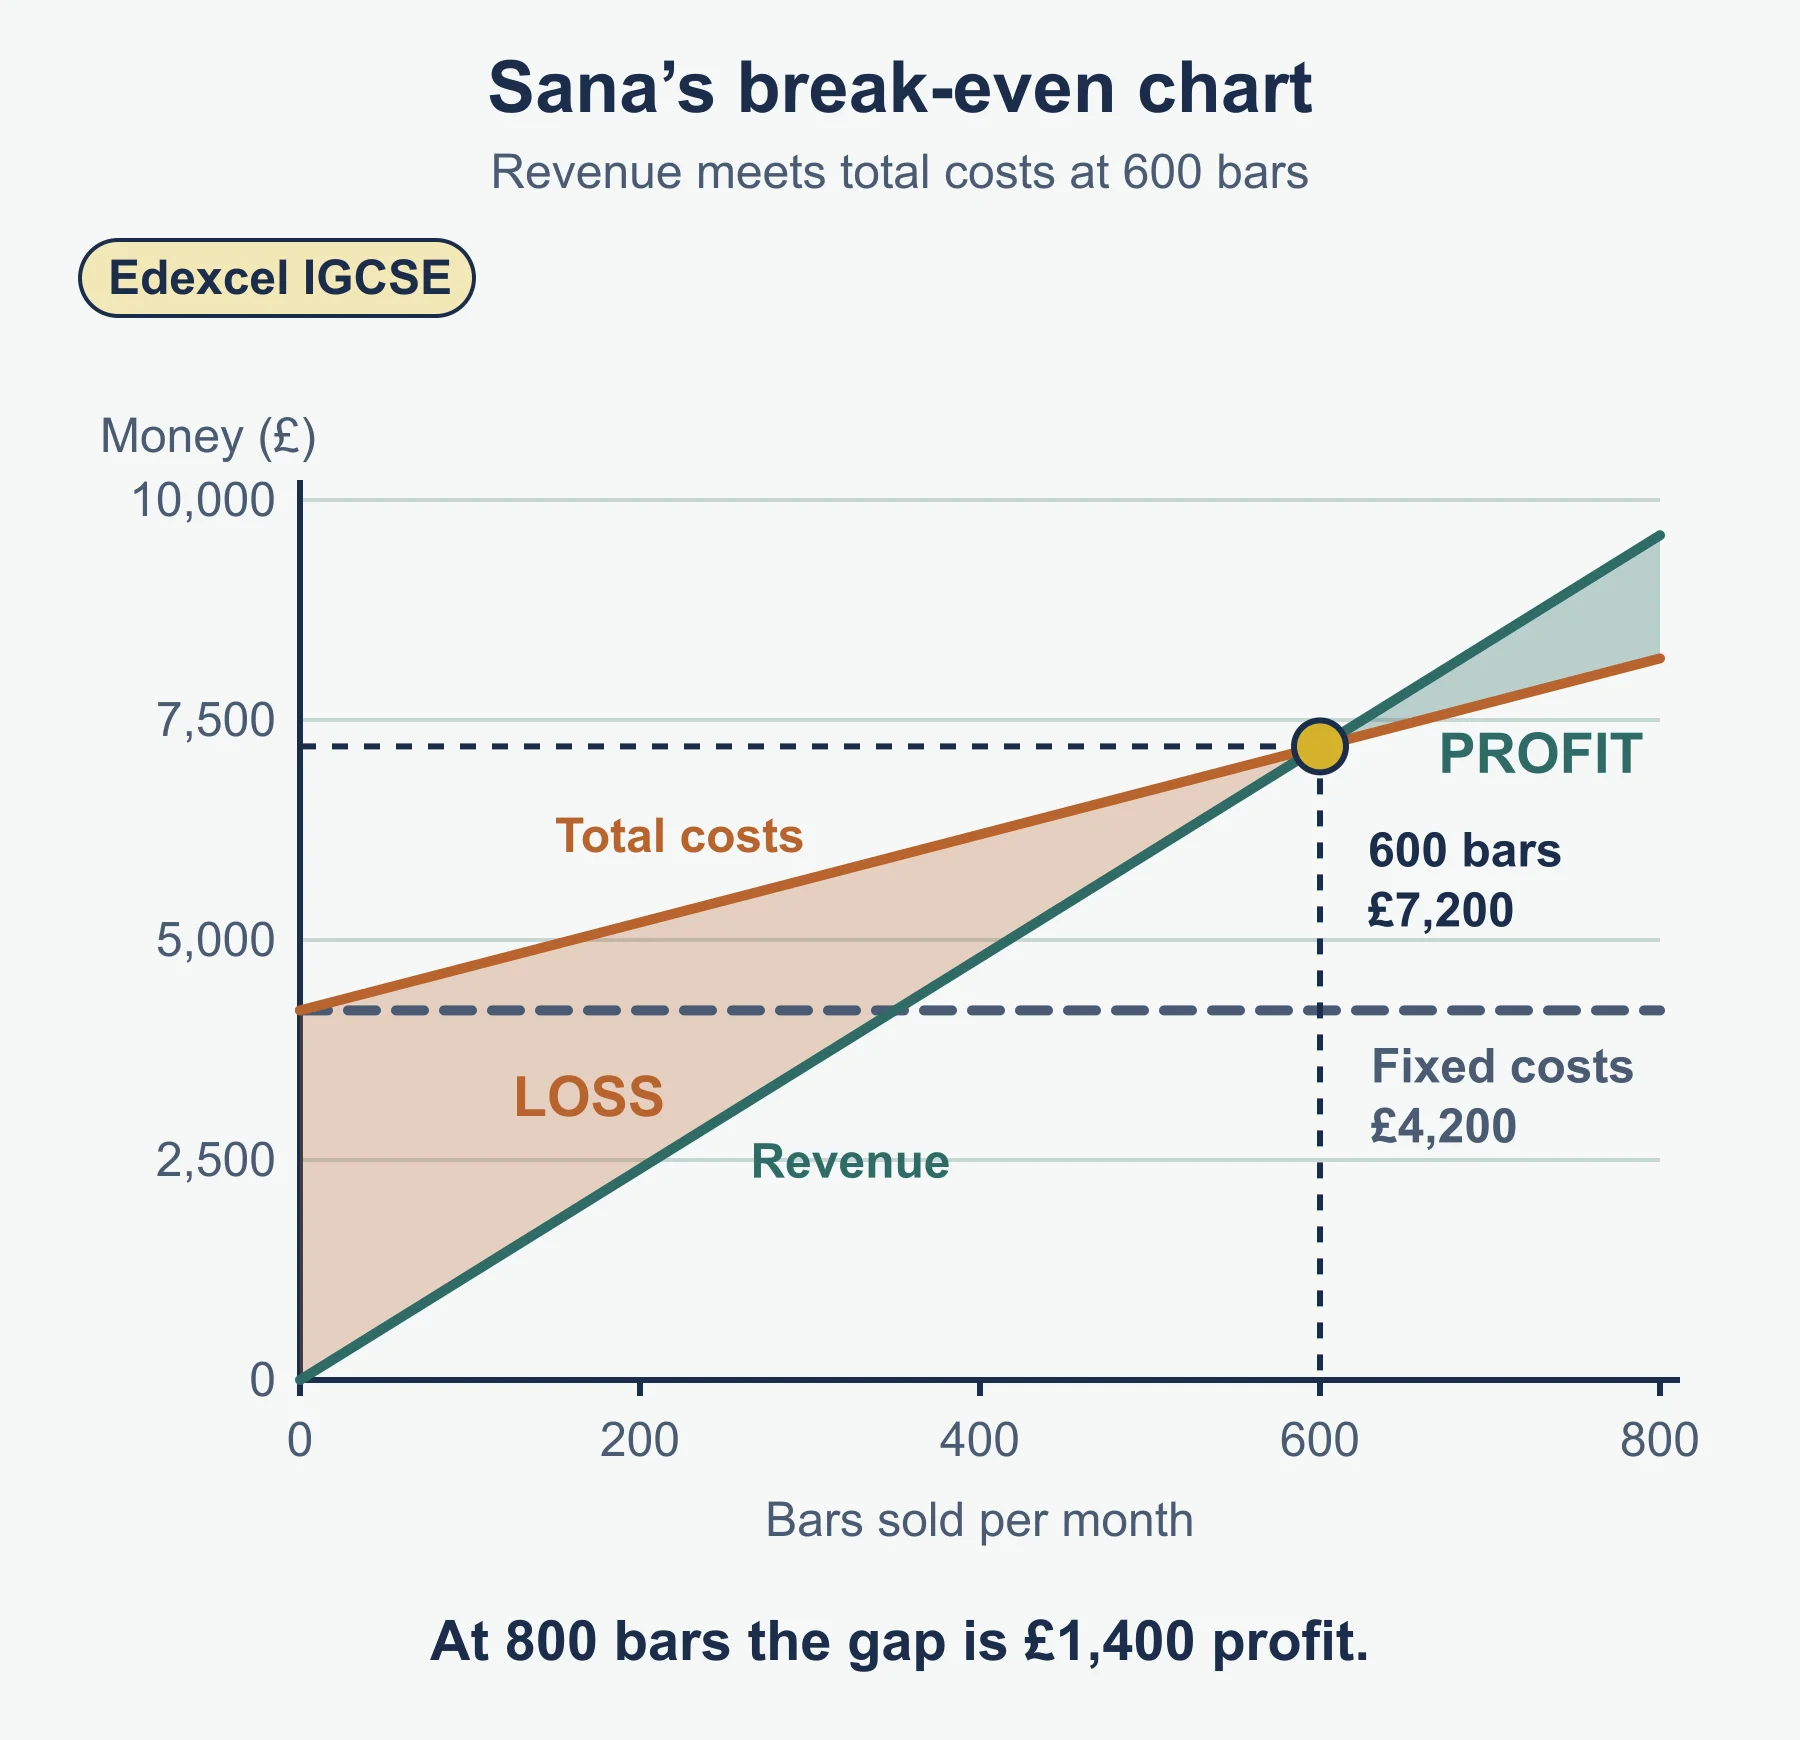
- Find the crossing of the revenue line and the total costs line.
- Read down to the horizontal axis for break-even output.
- Read across to the vertical axis for break-even revenue (equal to total costs there).
- Read the fixed costs from where the total costs line meets the vertical axis.
- At any output, profit or loss is the vertical gap between the revenue and total costs lines. Where the revenue line is below the total costs line the gap is a loss; where it is above, the gap is a profit.
- Variable cost per unit is the rise in total costs per unit of output (divide the rise in total costs by the rise in output).
What each line looks like
| Line | Where it starts | Slope |
|---|---|---|
| Fixed costs | At the fixed cost figure | Flat |
| Total costs | At the fixed cost figure | Rises by the variable cost per unit |
| Revenue | At zero | Rises by the price per unit |
Impact of changes
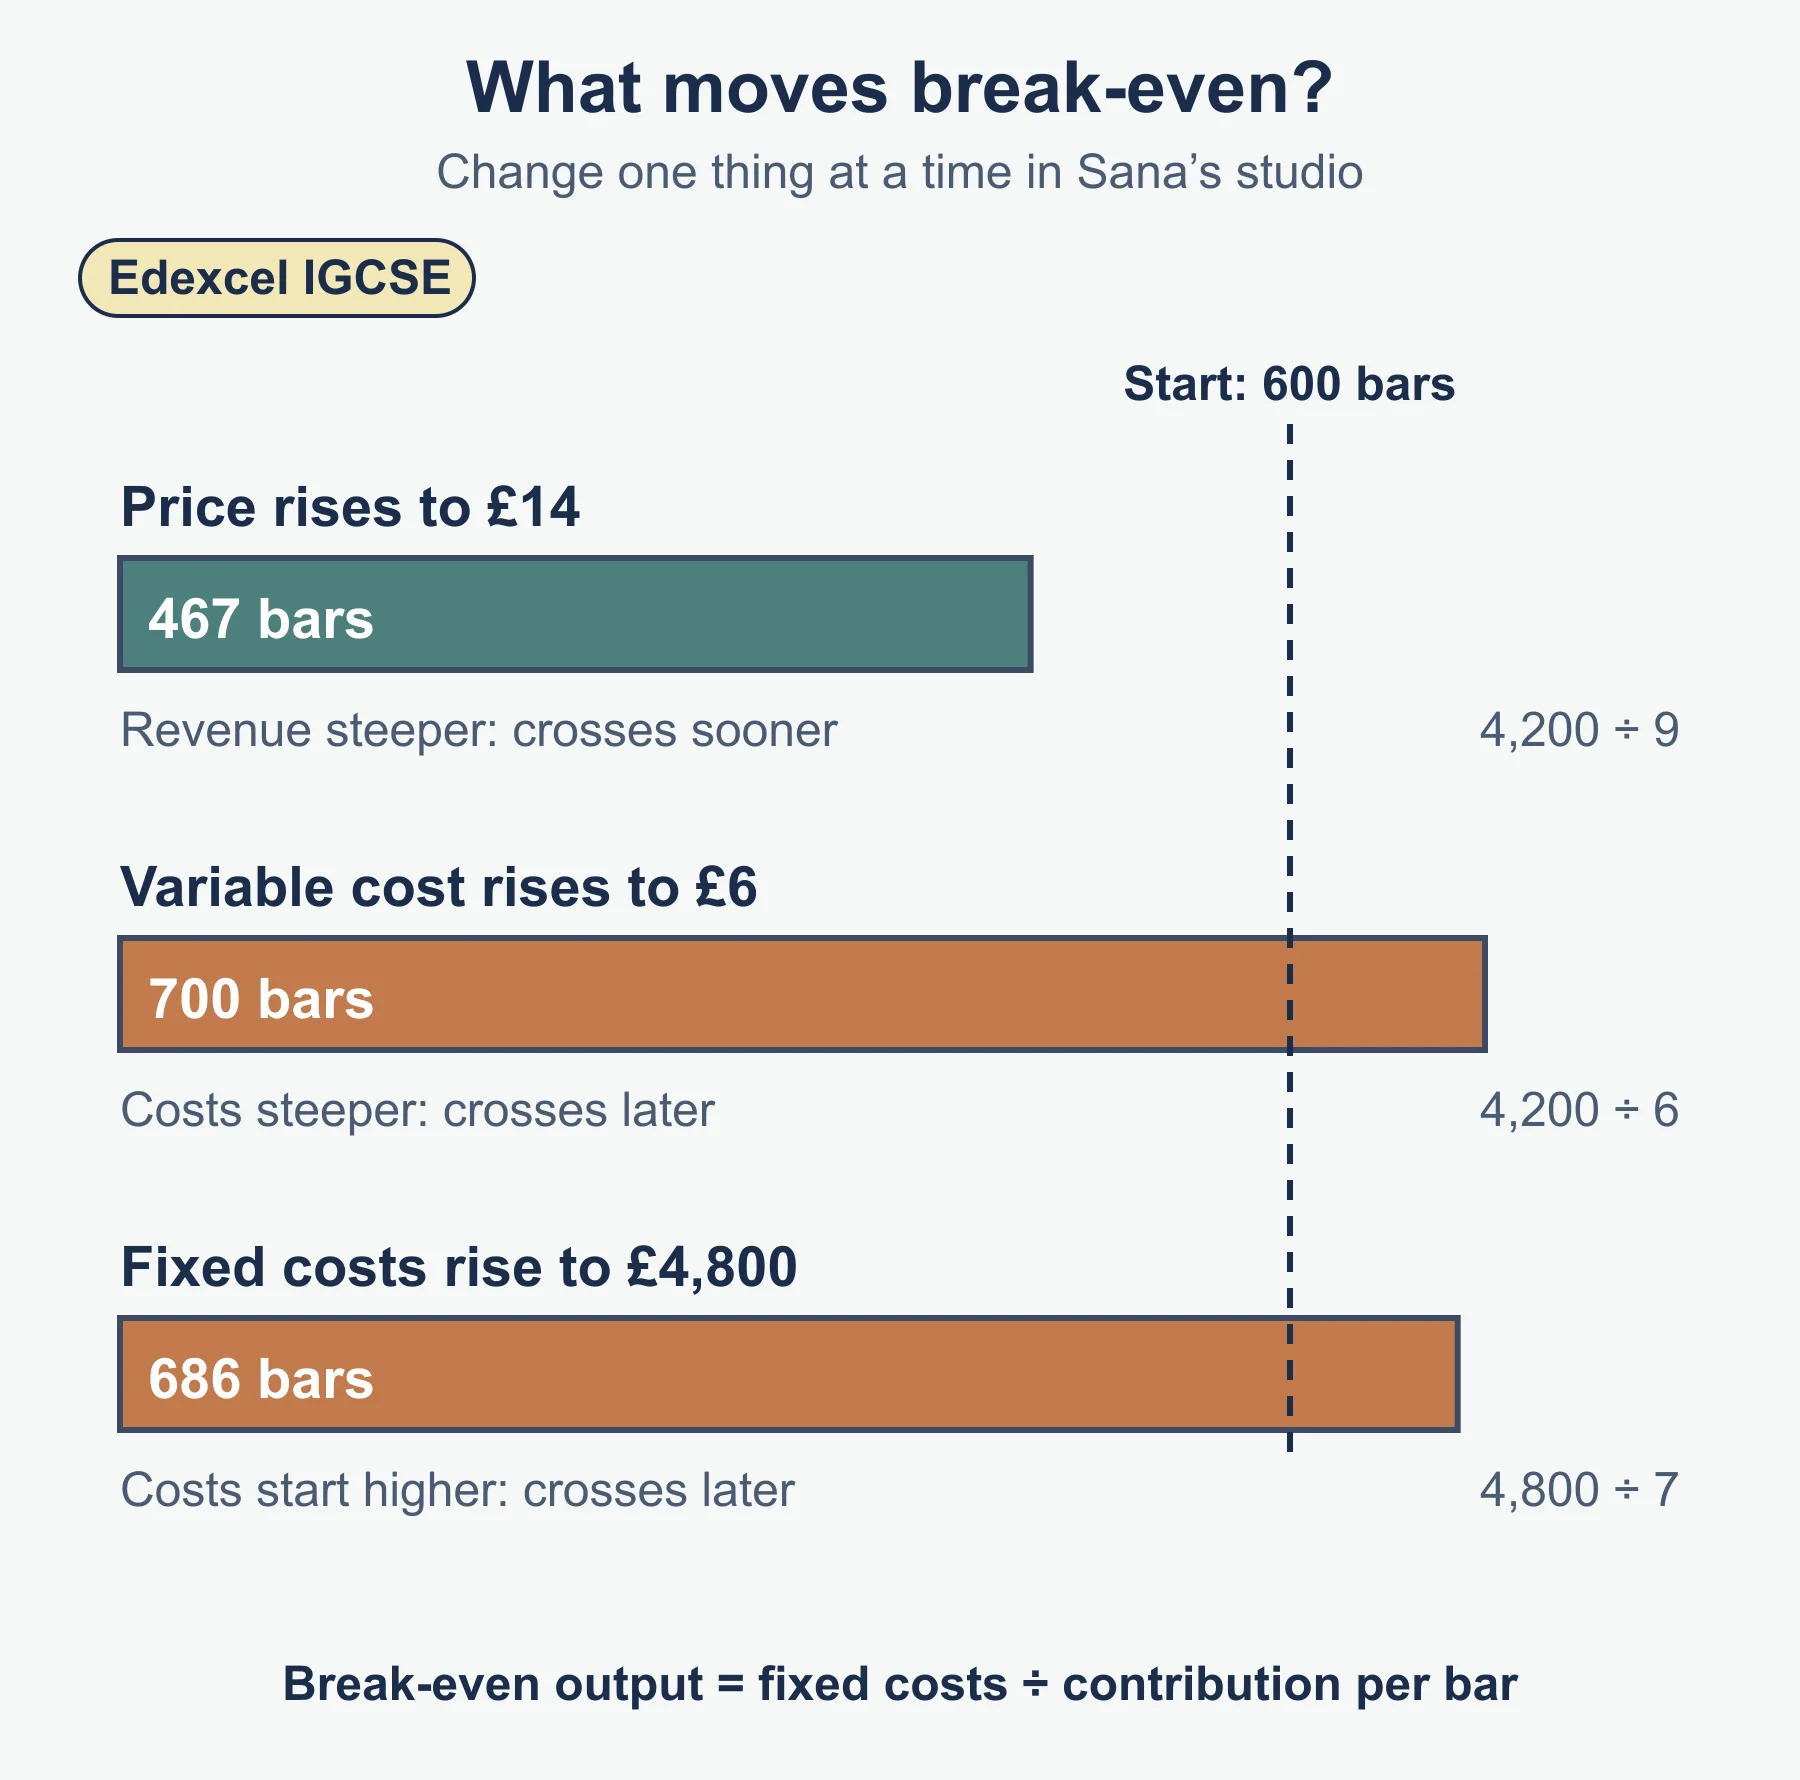
| Change | Line that moves | Break-even output |
|---|---|---|
| Price up | Revenue line steeper | Falls |
| Price down | Revenue line flatter | Rises |
| Variable cost per unit up | Total costs line steeper | Rises |
| Variable cost per unit down | Total costs line flatter | Falls |
| Fixed costs up | Total costs line starts higher | Rises |
| Fixed costs down | Total costs line starts lower | Falls |
A change in sales volume does not move the lines. It moves the business along them, to a different profit or loss.
A lower break-even output is not automatically better. A price rise may lower break-even output but cut the number of customers.
Limitations of break-even charts
| Limitation | Why it matters |
|---|---|
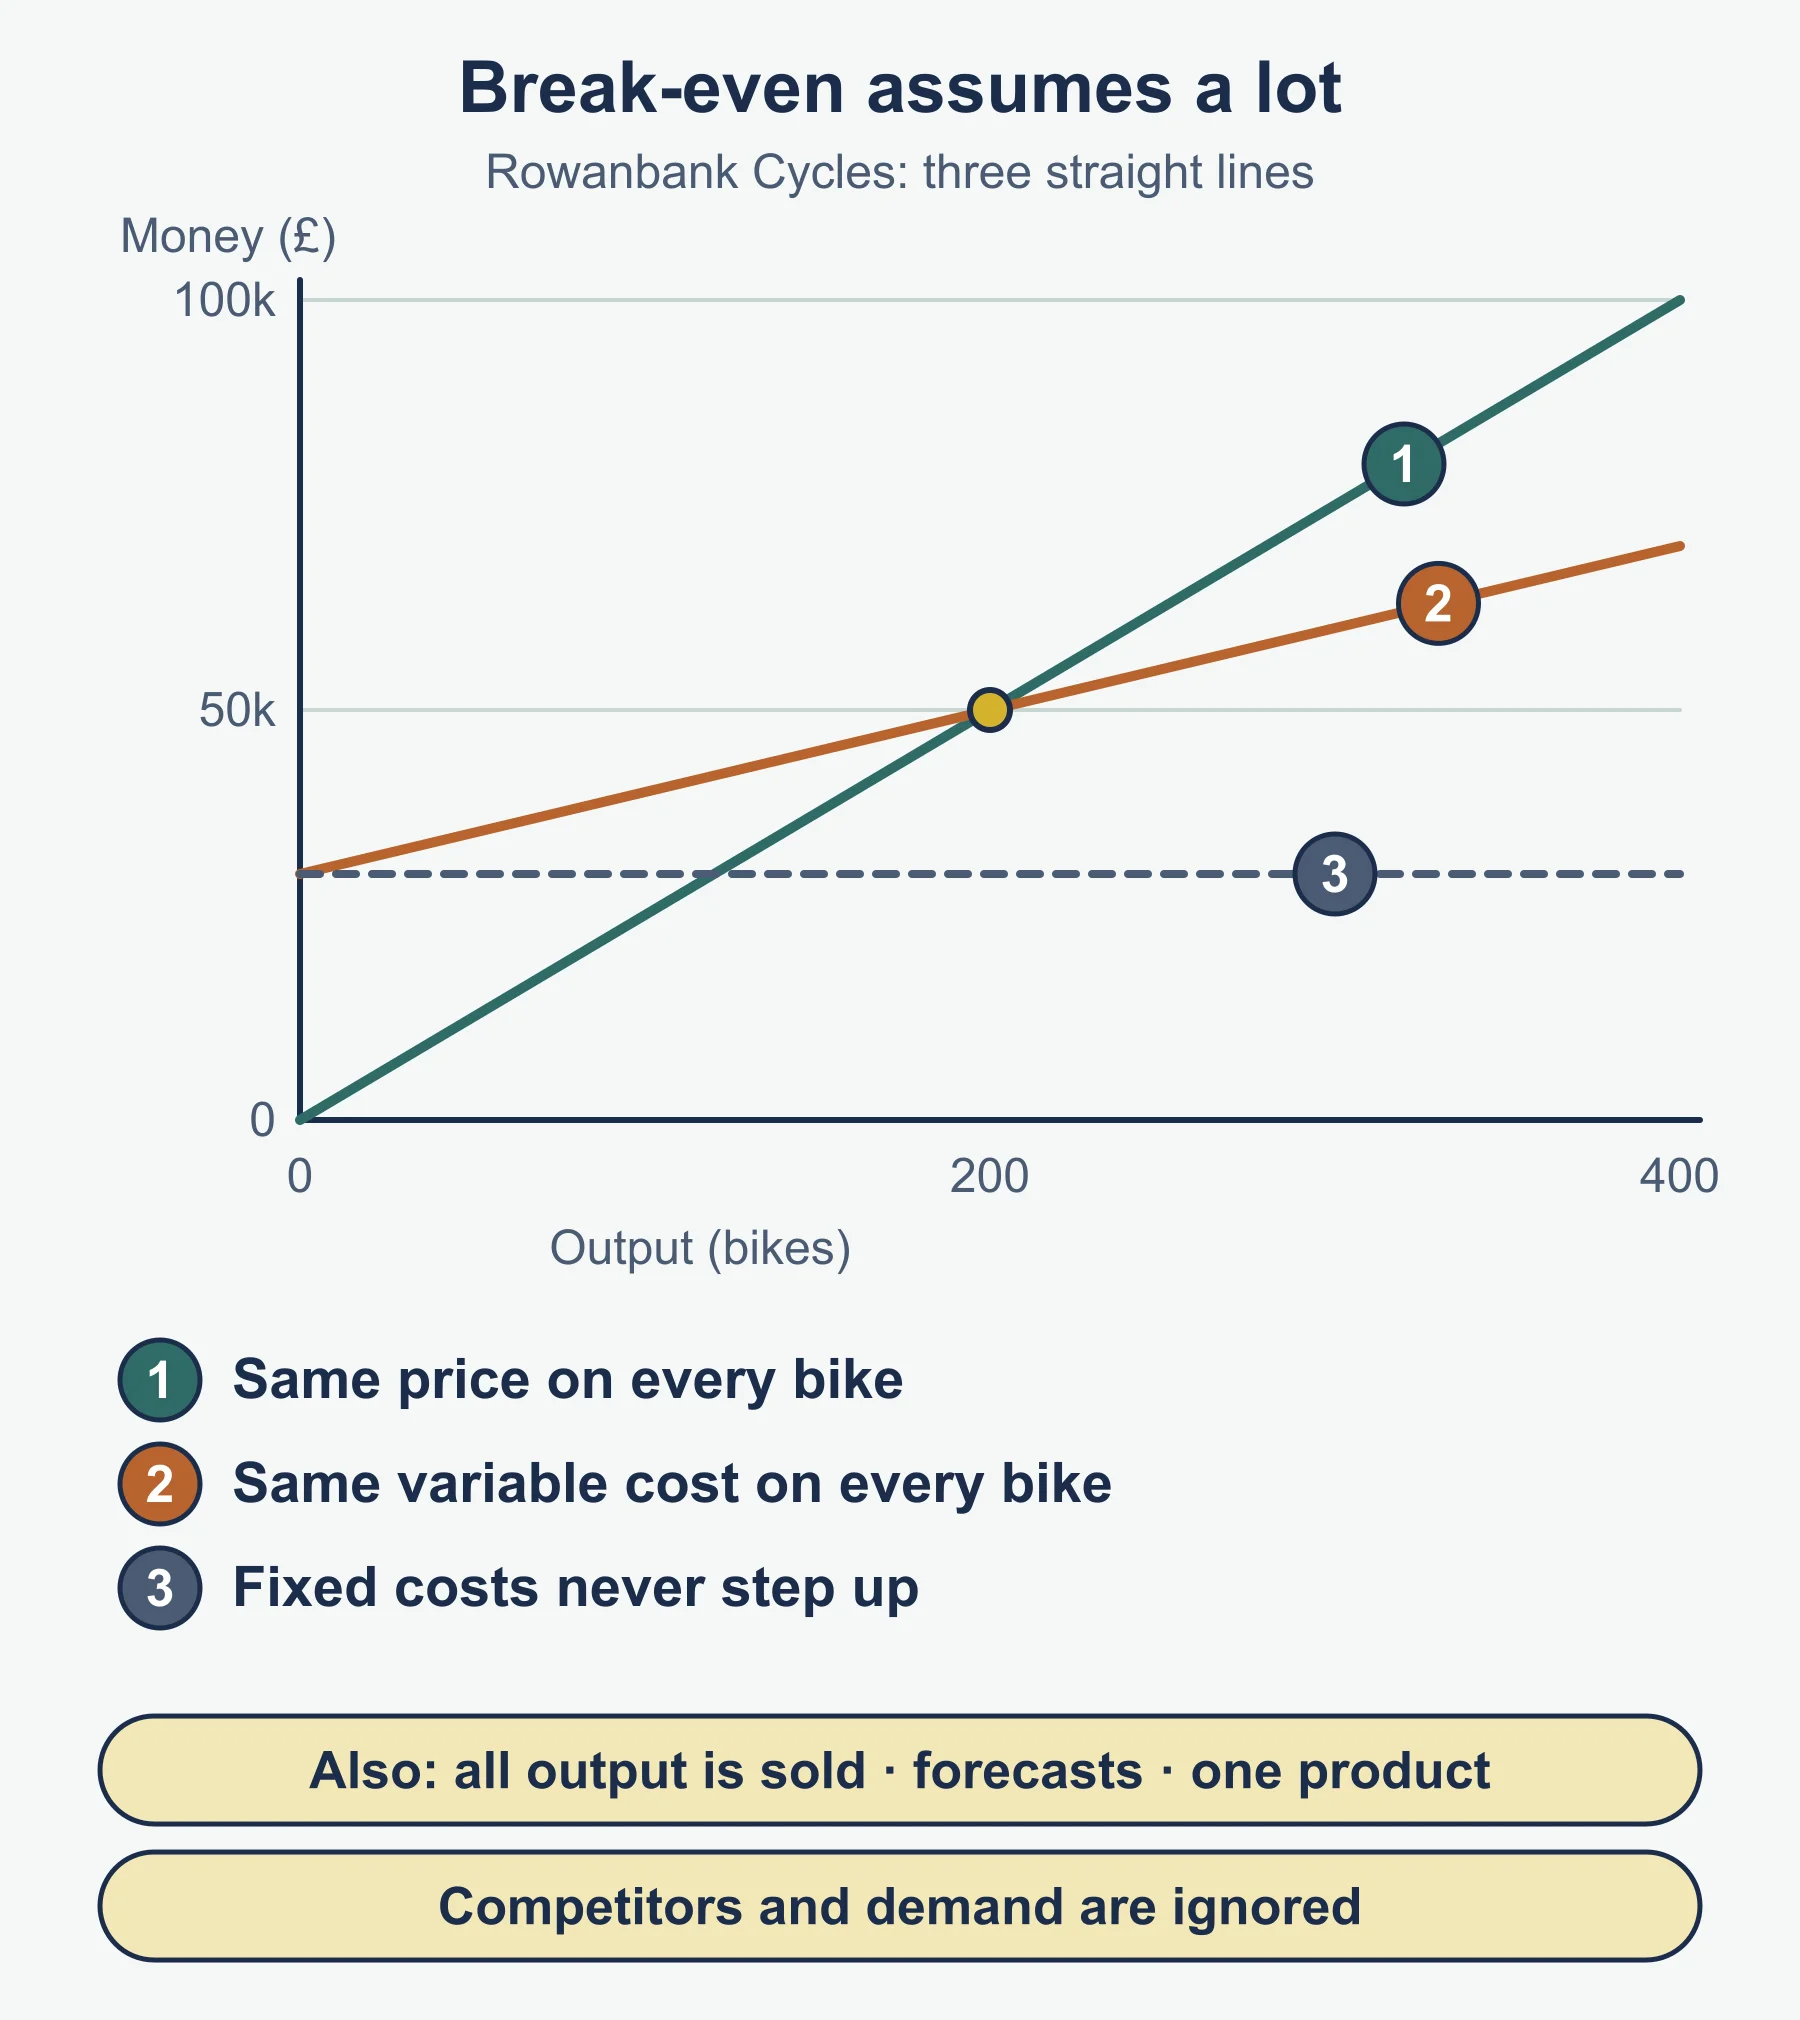
| Straight-line revenue | Discounts and special offers change the price per unit |
| Constant variable cost per unit | Bulk buying or overtime pay changes it |
| Fixed costs stay fixed | A bigger site or extra machine adds a step |
| All output is sold | Unsold stock is a cost, so profit is overstated |
| Based on forecasts | Costs and prices change |
| Does not show demand | A break-even figure says nothing about whether customers will buy it |
| One product | A business selling many products needs more assumptions |
Command words to expect
| Command word | What it asks for here |
|---|---|
| Define | The meaning of a term such as fixed costs or break-even |
| Calculate | Work with given data, with workings shown |
| Identify | Select a value from a chart or table, such as the break-even output |
| Complete the table | Fill in missing revenue, cost or profit values |
| Outline | Two linked points placed in the context given |
| Explain | A statement of fact with two expansion points |
| Analyse | An extended answer, placed in context |
| Justify | Recommend one of two options using the information given |
| Evaluate | A supported conclusion about the situation |
Must-know distinctions
- Variable cost per unit versus total variable cost. The first stays constant; the second grows with output.
- Contribution versus profit. Contribution is per unit, before fixed costs. Profit is after all costs.
- Break-even output versus break-even revenue. One is units, the other is money.
- Moving along a line versus shifting a line. Sales volume moves you along; price and cost changes shift or tilt lines.
- Loss versus low profit. Below break-even is a loss. Above it, any gap is profit.
Quick self-test
- Define revenue.
- A business has revenue of £56,000 and total costs of £61,250. State its profit or loss.
- A firm sells 250 units at £14.40. Calculate revenue.
- Variable cost is £6.25 a unit. Calculate total variable cost for 250 units.
- Fixed costs are £3,000 and total variable costs are £4,800. Calculate total costs.
- Price £20, variable cost £8, fixed costs £15,000. Calculate break-even output.
- Using the same figures, calculate profit when 1,500 units are sold.
- Fixed costs rise to £18,000. Calculate the new break-even output.
- Fixed costs are £2,800 and variable cost is £9 a unit. What price gives break-even at 400 units?
- State where fixed costs can be read from on a break-even chart.
- Outline one reason why a break-even chart may overstate profit.
- Explain why a rise in variable cost per unit raises break-even output.
Answers
- The money a business receives from selling its output (price × quantity sold).
- 56,000 − 61,250 = a loss of £5,250.
- 250 × 14.40 = £3,600.
- 250 × 6.25 = £1,562.50.
- 3,000 + 4,800 = £7,800.
- Contribution = 12. 15,000 ÷ 12 = 1,250 units.
- 250 units above break-even × £12 = £3,000. Check: revenue 30,000, total costs 15,000 + 12,000 = 27,000, profit 3,000.
- 18,000 ÷ 12 = 1,500 units.
- Fixed cost per unit at break-even = 2,800 ÷ 400 = 7. Contribution must be 7, so price = 9 + 7 = £16.
- At the vertical axis: the total costs line starts at the fixed cost figure when output is zero (the flat fixed costs line is at the same height).
- The chart assumes all output is sold. Unsold stock has still been paid for, so the profit shown is too high.
- Each unit now leaves less contribution towards fixed costs, so more units must be sold to cover them. The total costs line is steeper, so it meets the revenue line later.
Where marks are usually lost
- Using the selling price instead of the contribution per unit as the divisor.
- Leaving the answer as 466.7 units rather than a whole unit.
- Mixing up variable cost per unit and total variable cost in a total costs sum.
- Starting the total costs line at zero on a plotted chart.
- Writing “profit” when the answer is negative: say loss.
- Missing units or the pound sign on an answer.
- Giving a limitation as a list word (“assumptions”) with no link to the business.
- Writing that a lower break-even always means more profit.
- Using two points in Explain answers: the command word asks for a statement and two expansion points.
- Skipping the workings, when the Calculate command word asks for them.
Frequently asked questions
What is the difference between fixed and variable costs? Fixed costs, such as rent and insurance, do not change when output changes in the short run. Variable costs, such as raw materials, change in direct proportion to output.
How do you calculate break-even output for Edexcel IGCSE Business? Divide fixed costs by the contribution per unit (selling price minus variable cost per unit). The 4BS1 formulae list does not include a break-even formula, so this is the standard form to learn.
How do you calculate profit at a given output using contribution? Multiply the contribution per unit by the number of units sold, then subtract fixed costs. A negative answer is a loss.
How does a price rise affect the break-even point? A price rise increases contribution per unit, so break-even output falls. It may also reduce the number of units customers buy, so profit does not always rise.
Official syllabus
Pearson Edexcel International GCSE in Business (4BS1), Specification, Issue 2, February 2026, published by Pearson Education Limited. Topic 3: Business finance, section 3.3 Costs and break-even analysis, points 3.3.1 to 3.3.3.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
Edexcel IGCSE Business: Financial documents and accounts analysis (4BS1)
Study guide to statements of comprehensive income, statements of financial position and the six Edexcel IGCSE Business ratios, with worked examples.
Business · Pearson Edexcel · IGCSE
Read guide -
Practice questions
Edexcel IGCSE Business: Financial documents and accounts analysis (4BS1) – Practice Questions
Original practice questions with worked answers on financial documents, ratios and liquidity for Edexcel IGCSE Business, Topic 3 sections 3.4 and 3.5.
Business · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Business: Financial documents and accounts analysis (4BS1) – Revision Notes
Condensed revision notes on financial documents, the six ratios, liquidity and analysis for Edexcel IGCSE Business, Topic 3 sections 3.4 and 3.5.
Business · Pearson Edexcel · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Business teachers at Marlbridge

