
Revision Notes
Edexcel IGCSE Business: Financial documents and accounts analysis (4BS1) – Revision Notes
Condensed revision notes on financial documents, the six ratios, liquidity and analysis for Edexcel IGCSE Business, Topic 3 sections 3.4 and 3.5.
- Subject
- Business
- Level
- IGCSE
- Topic
- Business finance
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Asif Iqbal (what this means)
Aligned to Pearson Edexcel IGCSE Business (4BS1), Issue 2, February 2026. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Business.
Syllabus points this page covers
4BS1
- 3 Business finance (whole topic)
- 3.4 Financial documents
- 3.5 Accounts analysis
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Business online. Request a free trial class.
Use these notes after the study guide for full explanations. They cover Topic 3, sections 3.4 and 3.5 of the Pearson Edexcel International GCSE in Business (4BS1) specification, Issue 2, February 2026. Links: Edexcel IGCSE Business hub, printable checklist, practice questions and free diagnostics. Businesses and figures are invented, in dollars.
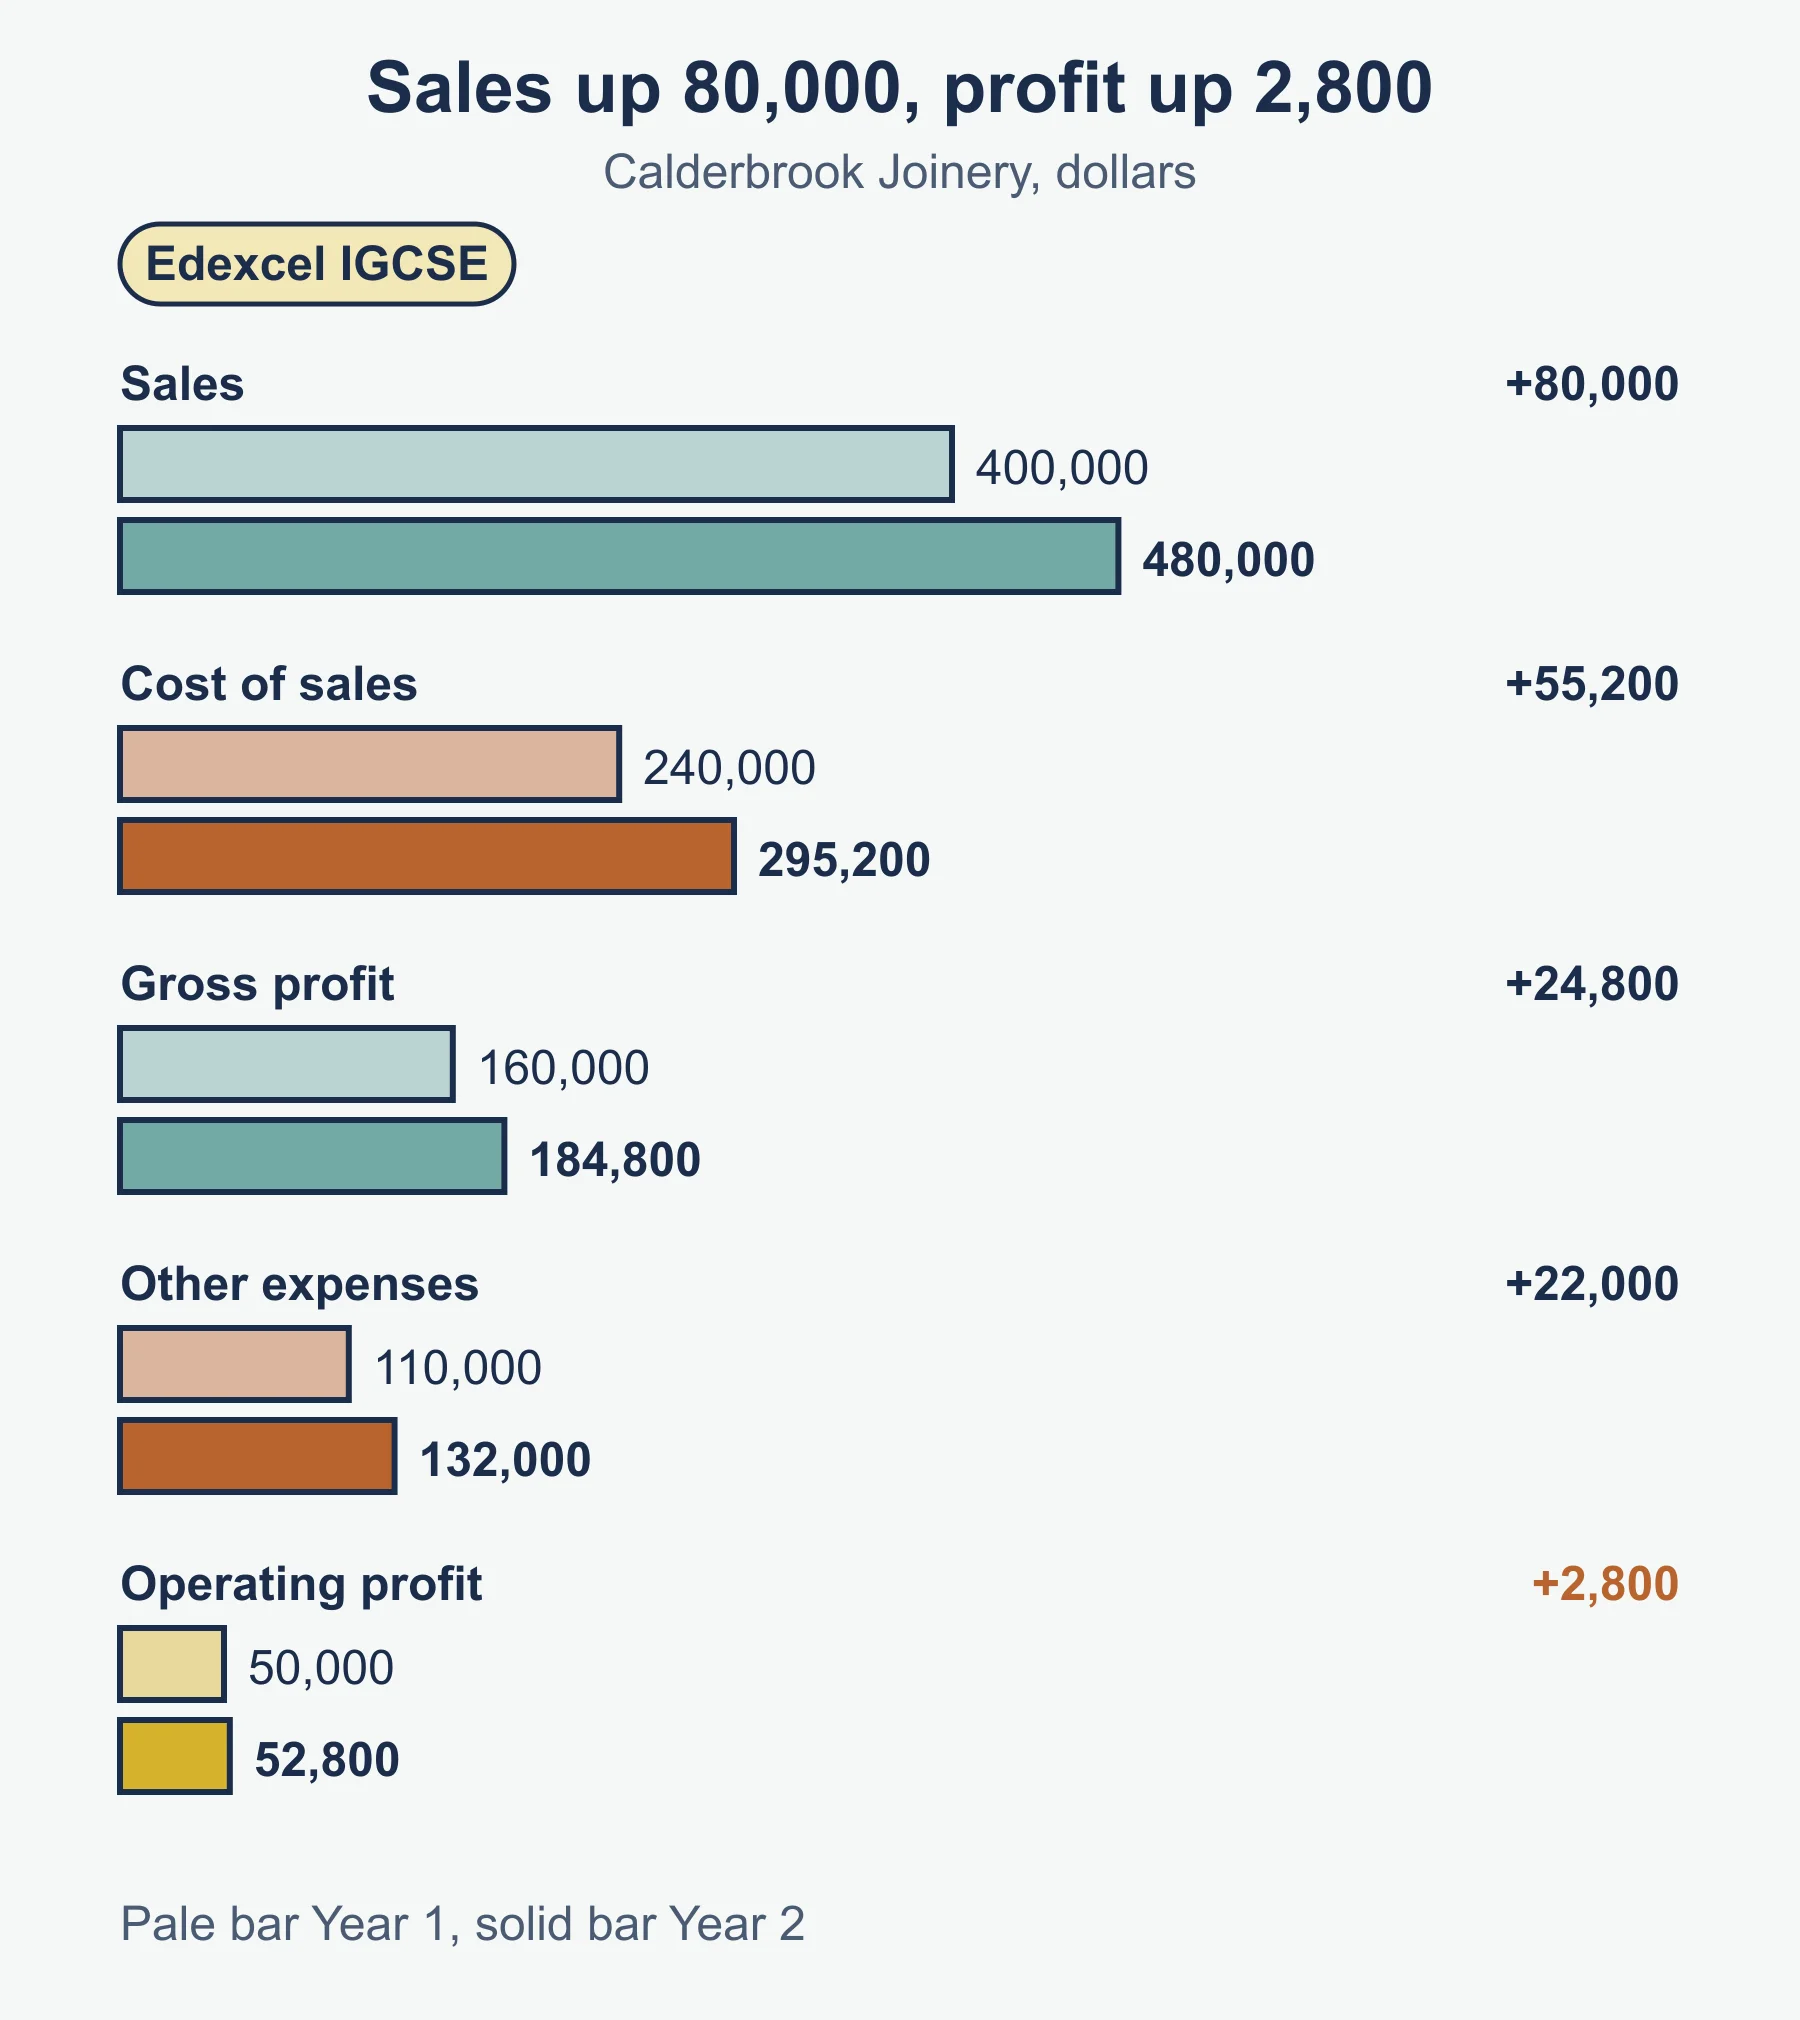
1. Statement of comprehensive income (3.4.1)
Reports performance over a period. You read it; you are not asked to construct one.
| Line | Meaning |
|---|---|
| Sales (revenue) | Value of goods or services sold |
| Cost of sales | What the goods that were sold cost to buy or make |
| Gross profit | Revenue − cost of sales |
| Expenses | Other operating costs: wages, rent, advertising |
| Operating profit | Gross profit − other operating expenses |
Profit = revenue − costs. Why it matters: rewards owners for risk; retained profit funds growth; attracts lenders and investors; measures success. Profit is not cash: a firm can be profitable and still short of money.
Decision making: compare expenses year on year; review prices if gross profit is weak; show lenders that repayments are affordable; judge whether to expand. Limit: historical, and silent on cash.
2. Statement of financial position (3.4.2)
A snapshot of the assets held and liabilities owed on a single date.
| Term | Meaning | Examples |
|---|---|---|
| Non-current assets | Kept for over a year | Machinery, vehicles, premises |
| Current assets | Turn to cash within a year | Inventory, trade receivables, cash |
| Current liabilities | Due within a year | Trade payables, overdraft |
| Non-current liabilities | Due after a year | Long-term bank loan |
| Capital employed | Long-term funds in the business | See below |
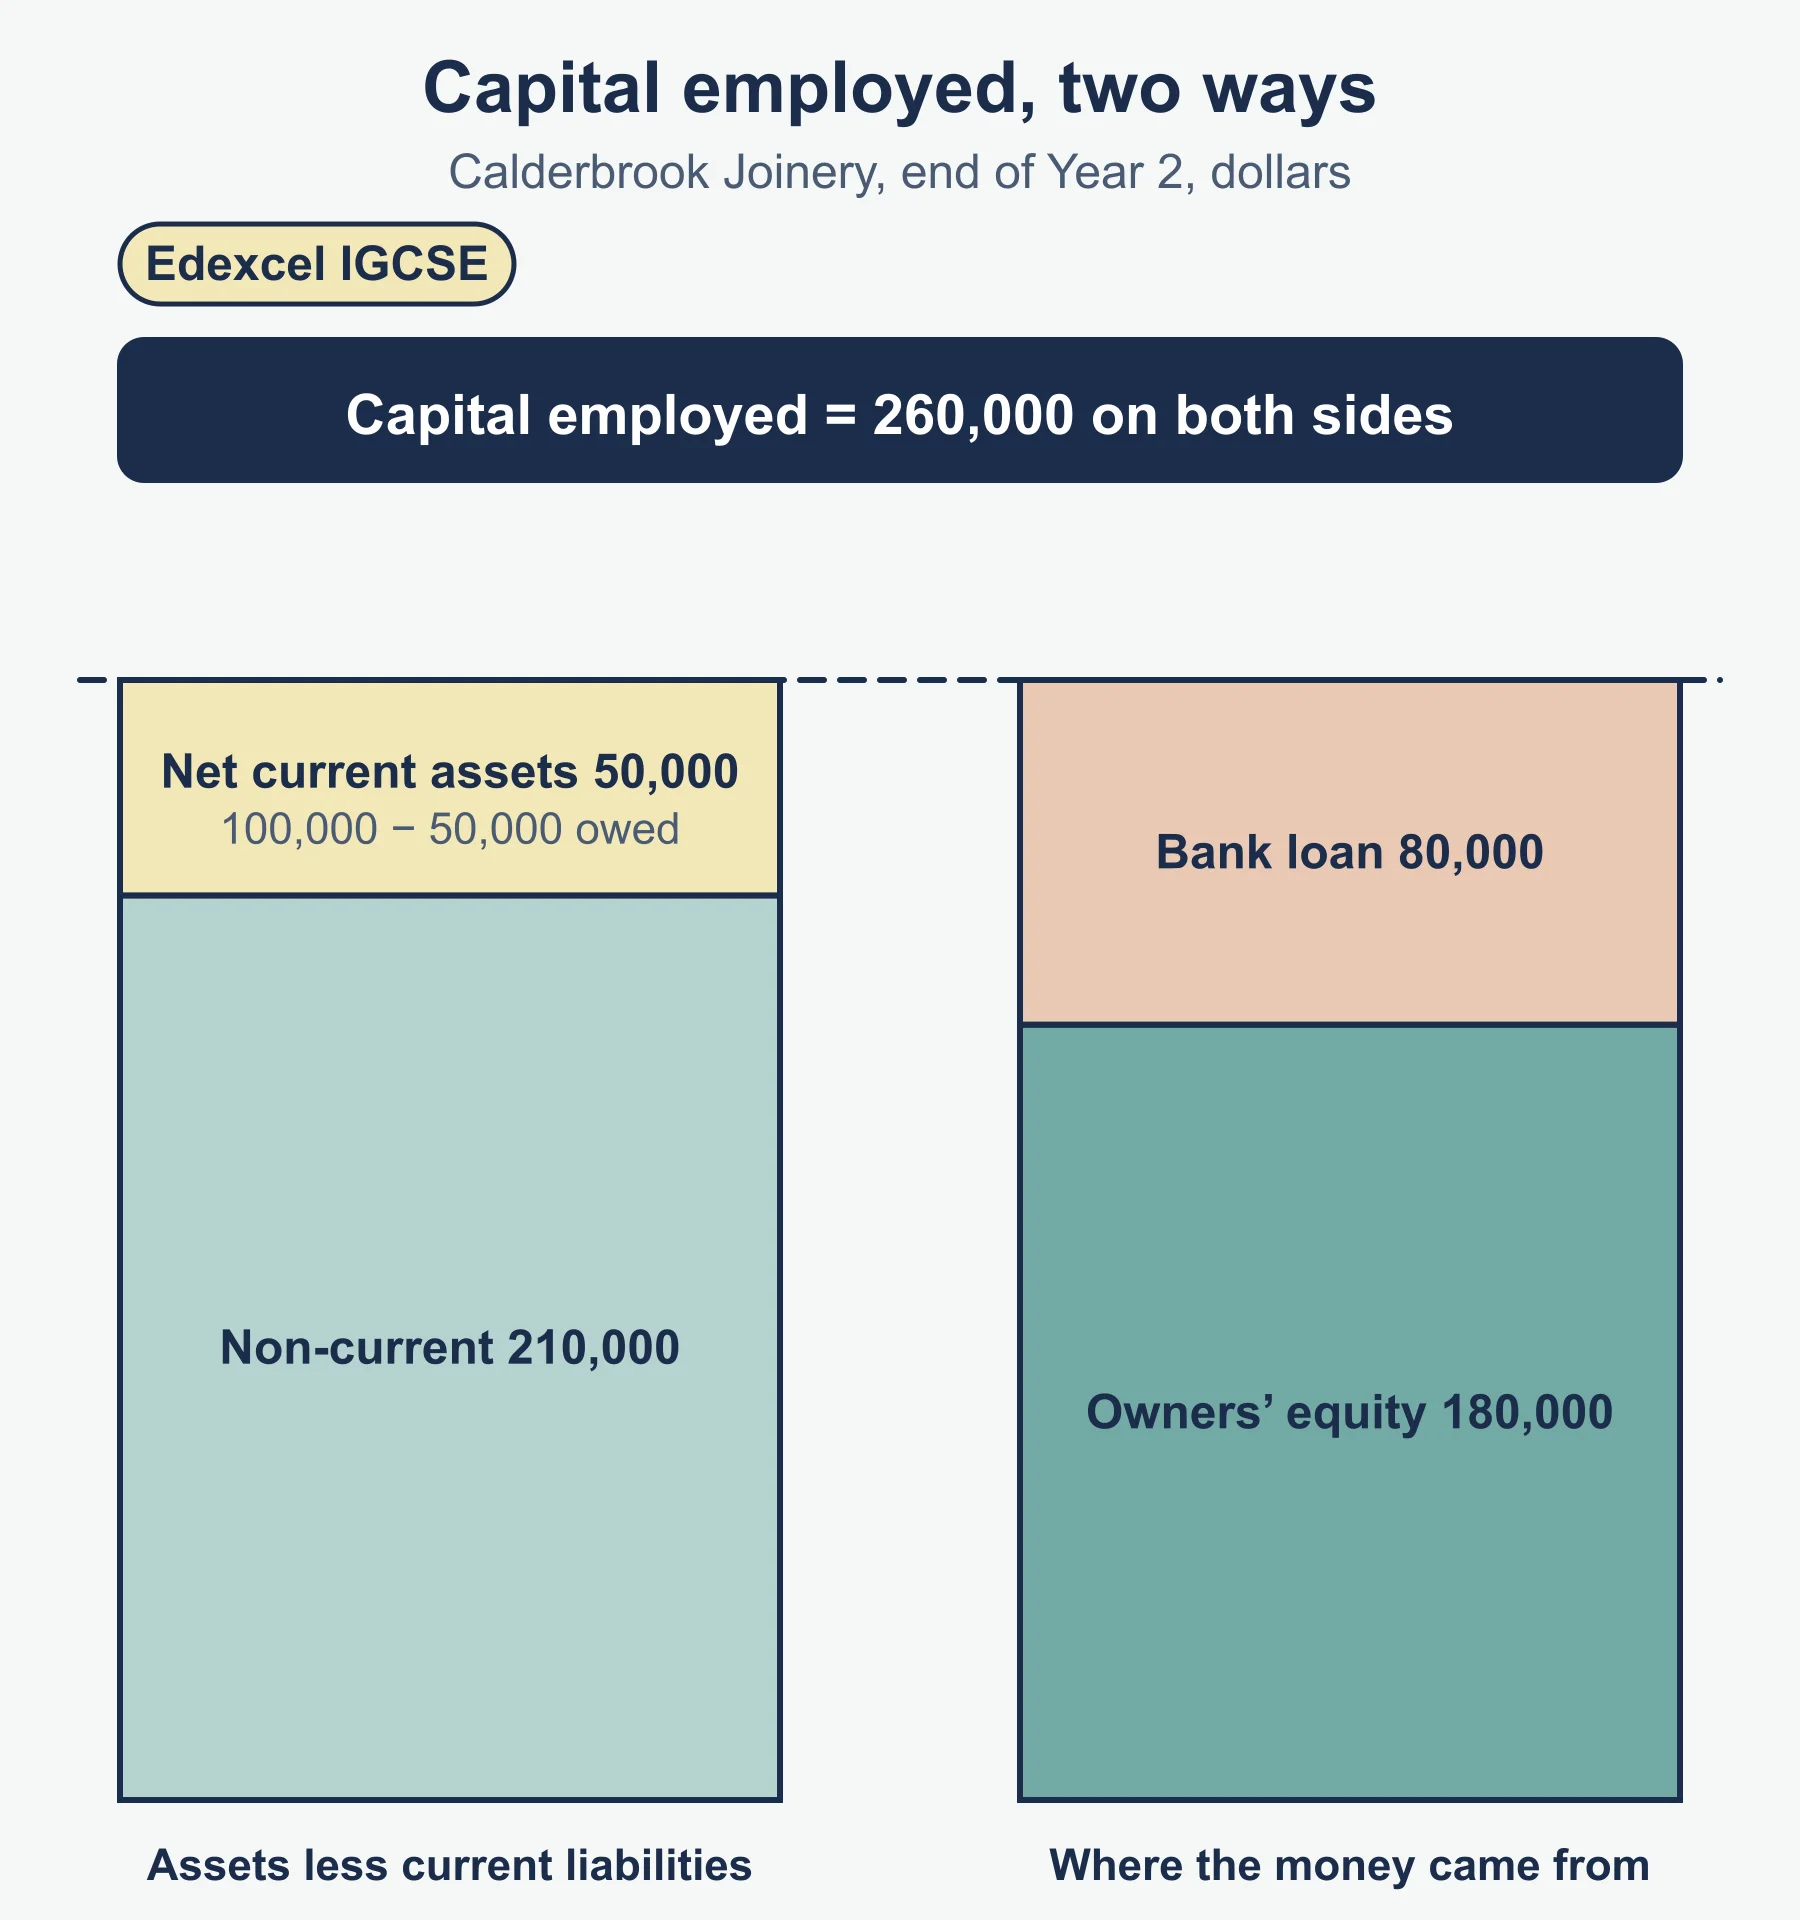
Capital employed (standard form, not given as a formula in the specification) = non-current assets + current assets − current liabilities = equity + non-current liabilities.
To interpret: how much is tied up in inventory; are current assets bigger than current liabilities; how much long-term borrowing; what the owners have put in.
3. Formulae (Appendix 4; supplied in the examination)
| Ratio | Formula | Unit |
|---|---|---|
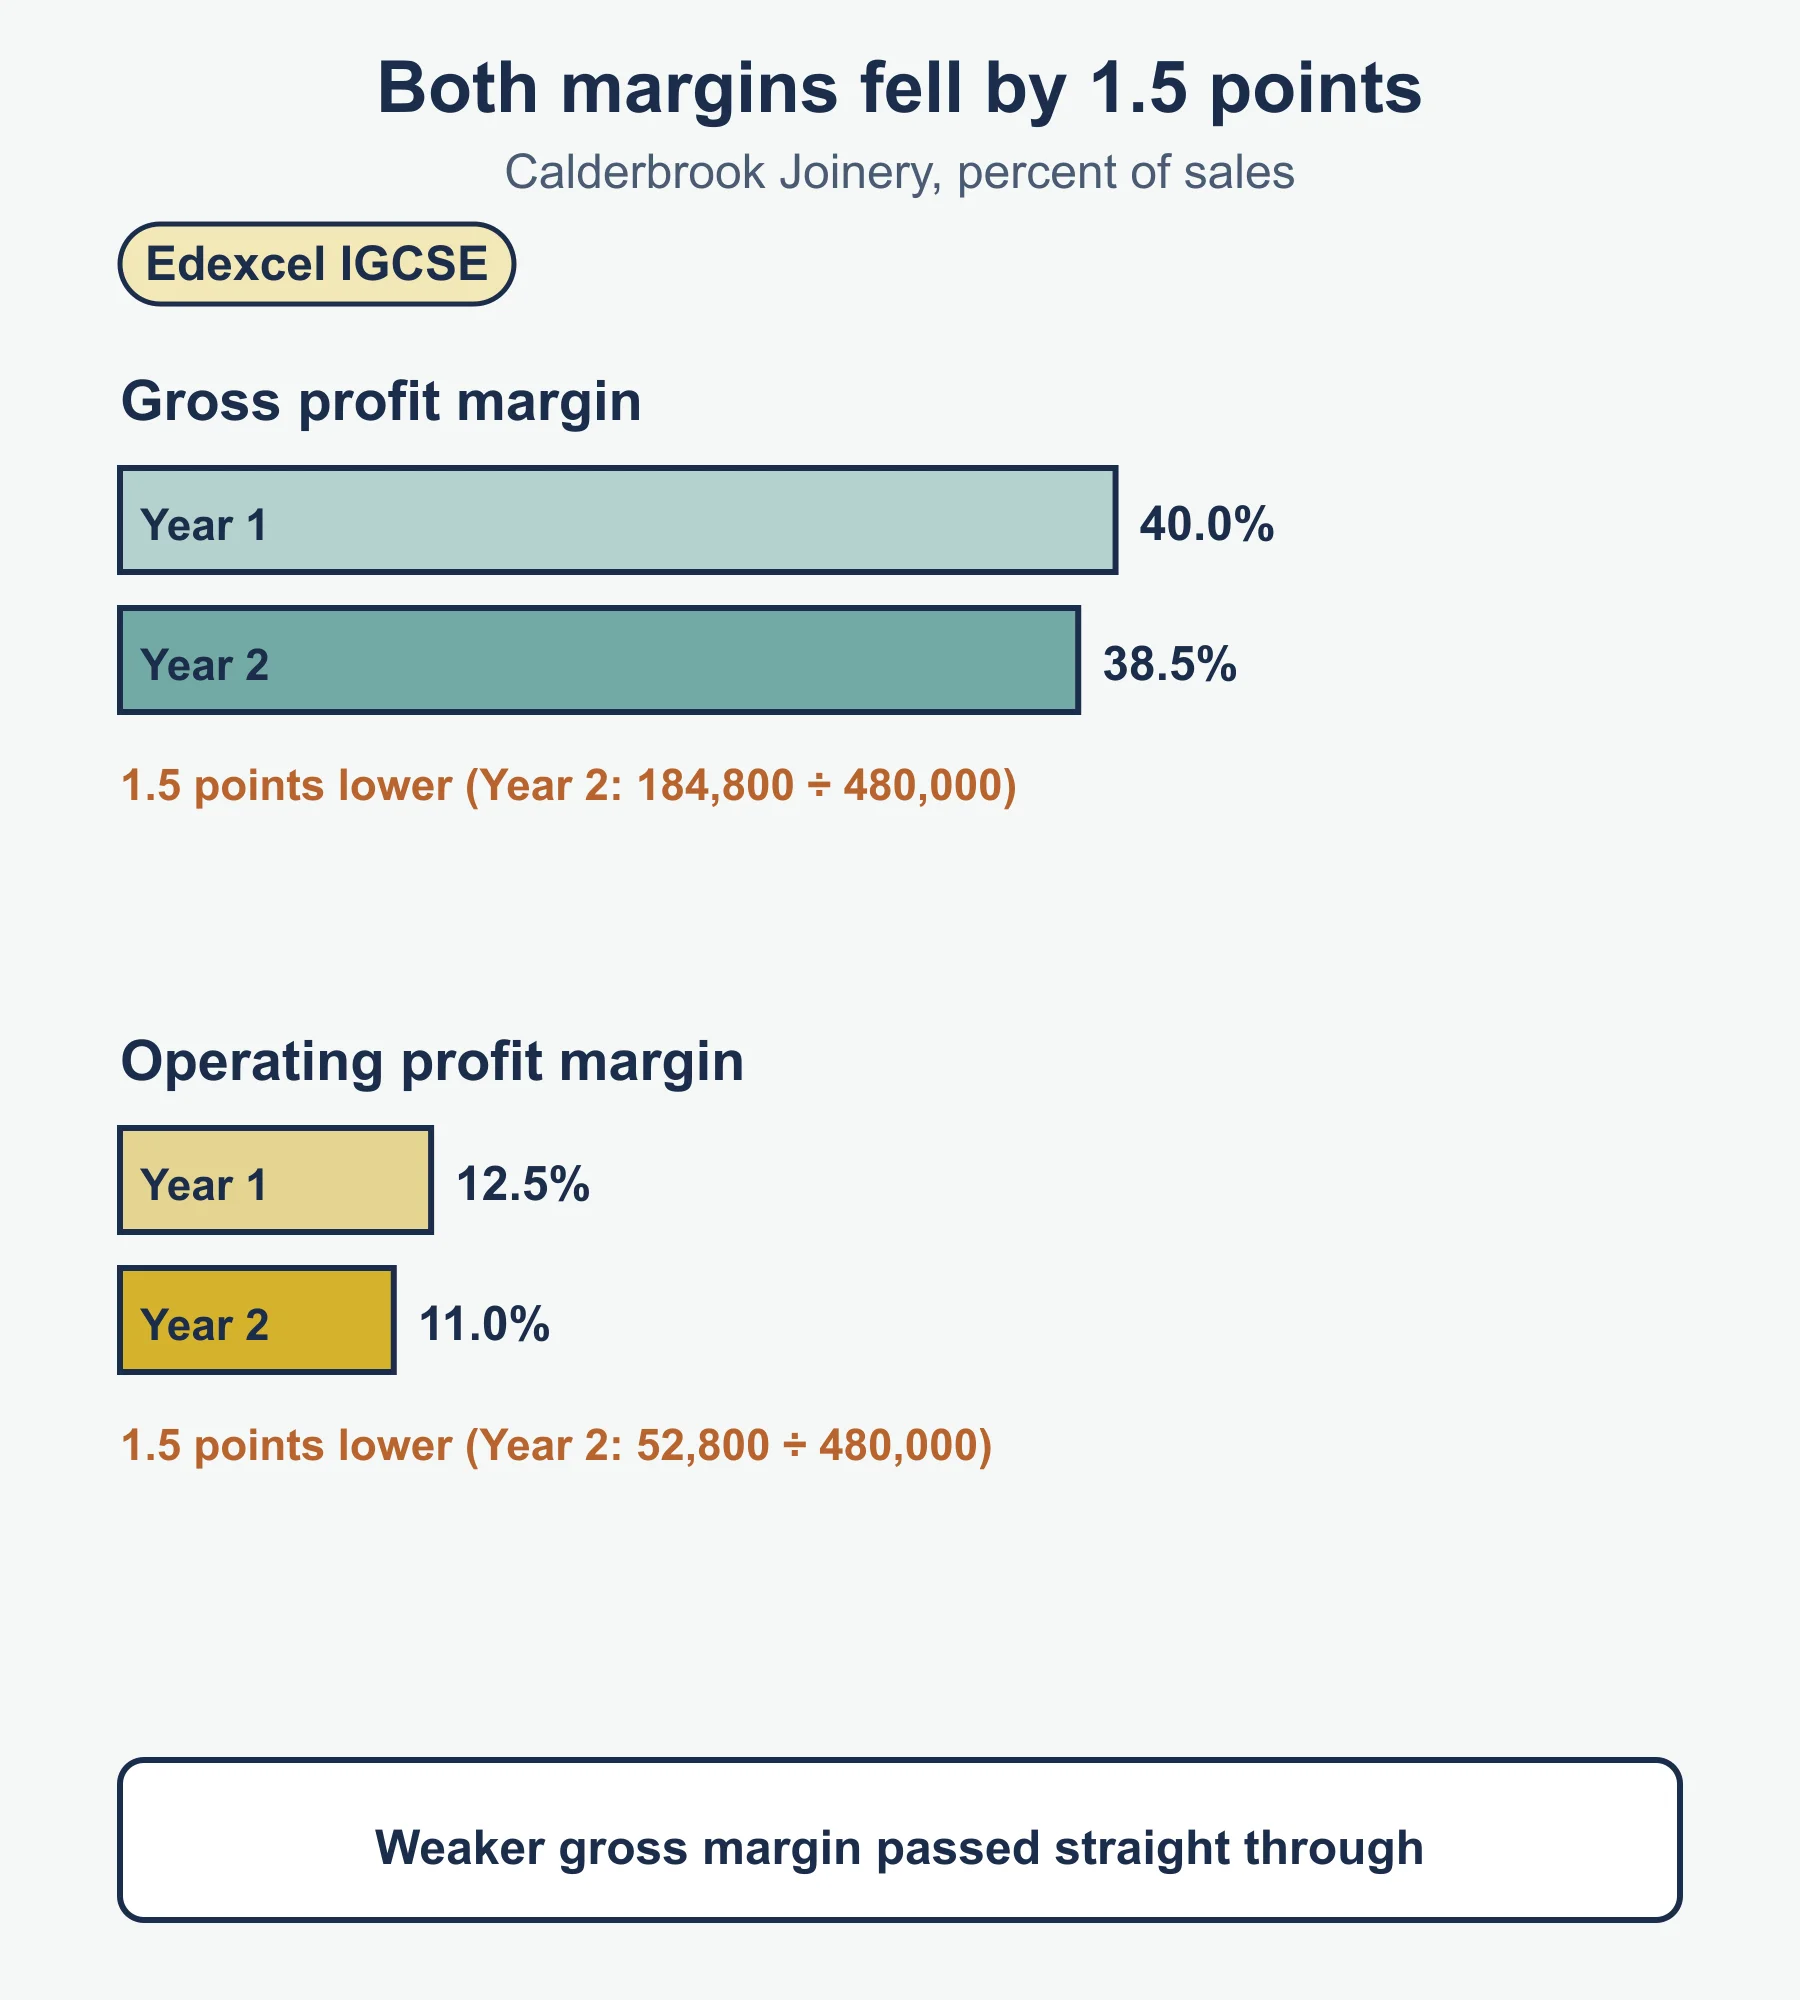
| Gross profit margin | gross profit ÷ revenue × 100 | % |
| Operating profit margin | operating profit ÷ revenue × 100 | % |
| Markup | profit per item ÷ cost per item × 100 | % |
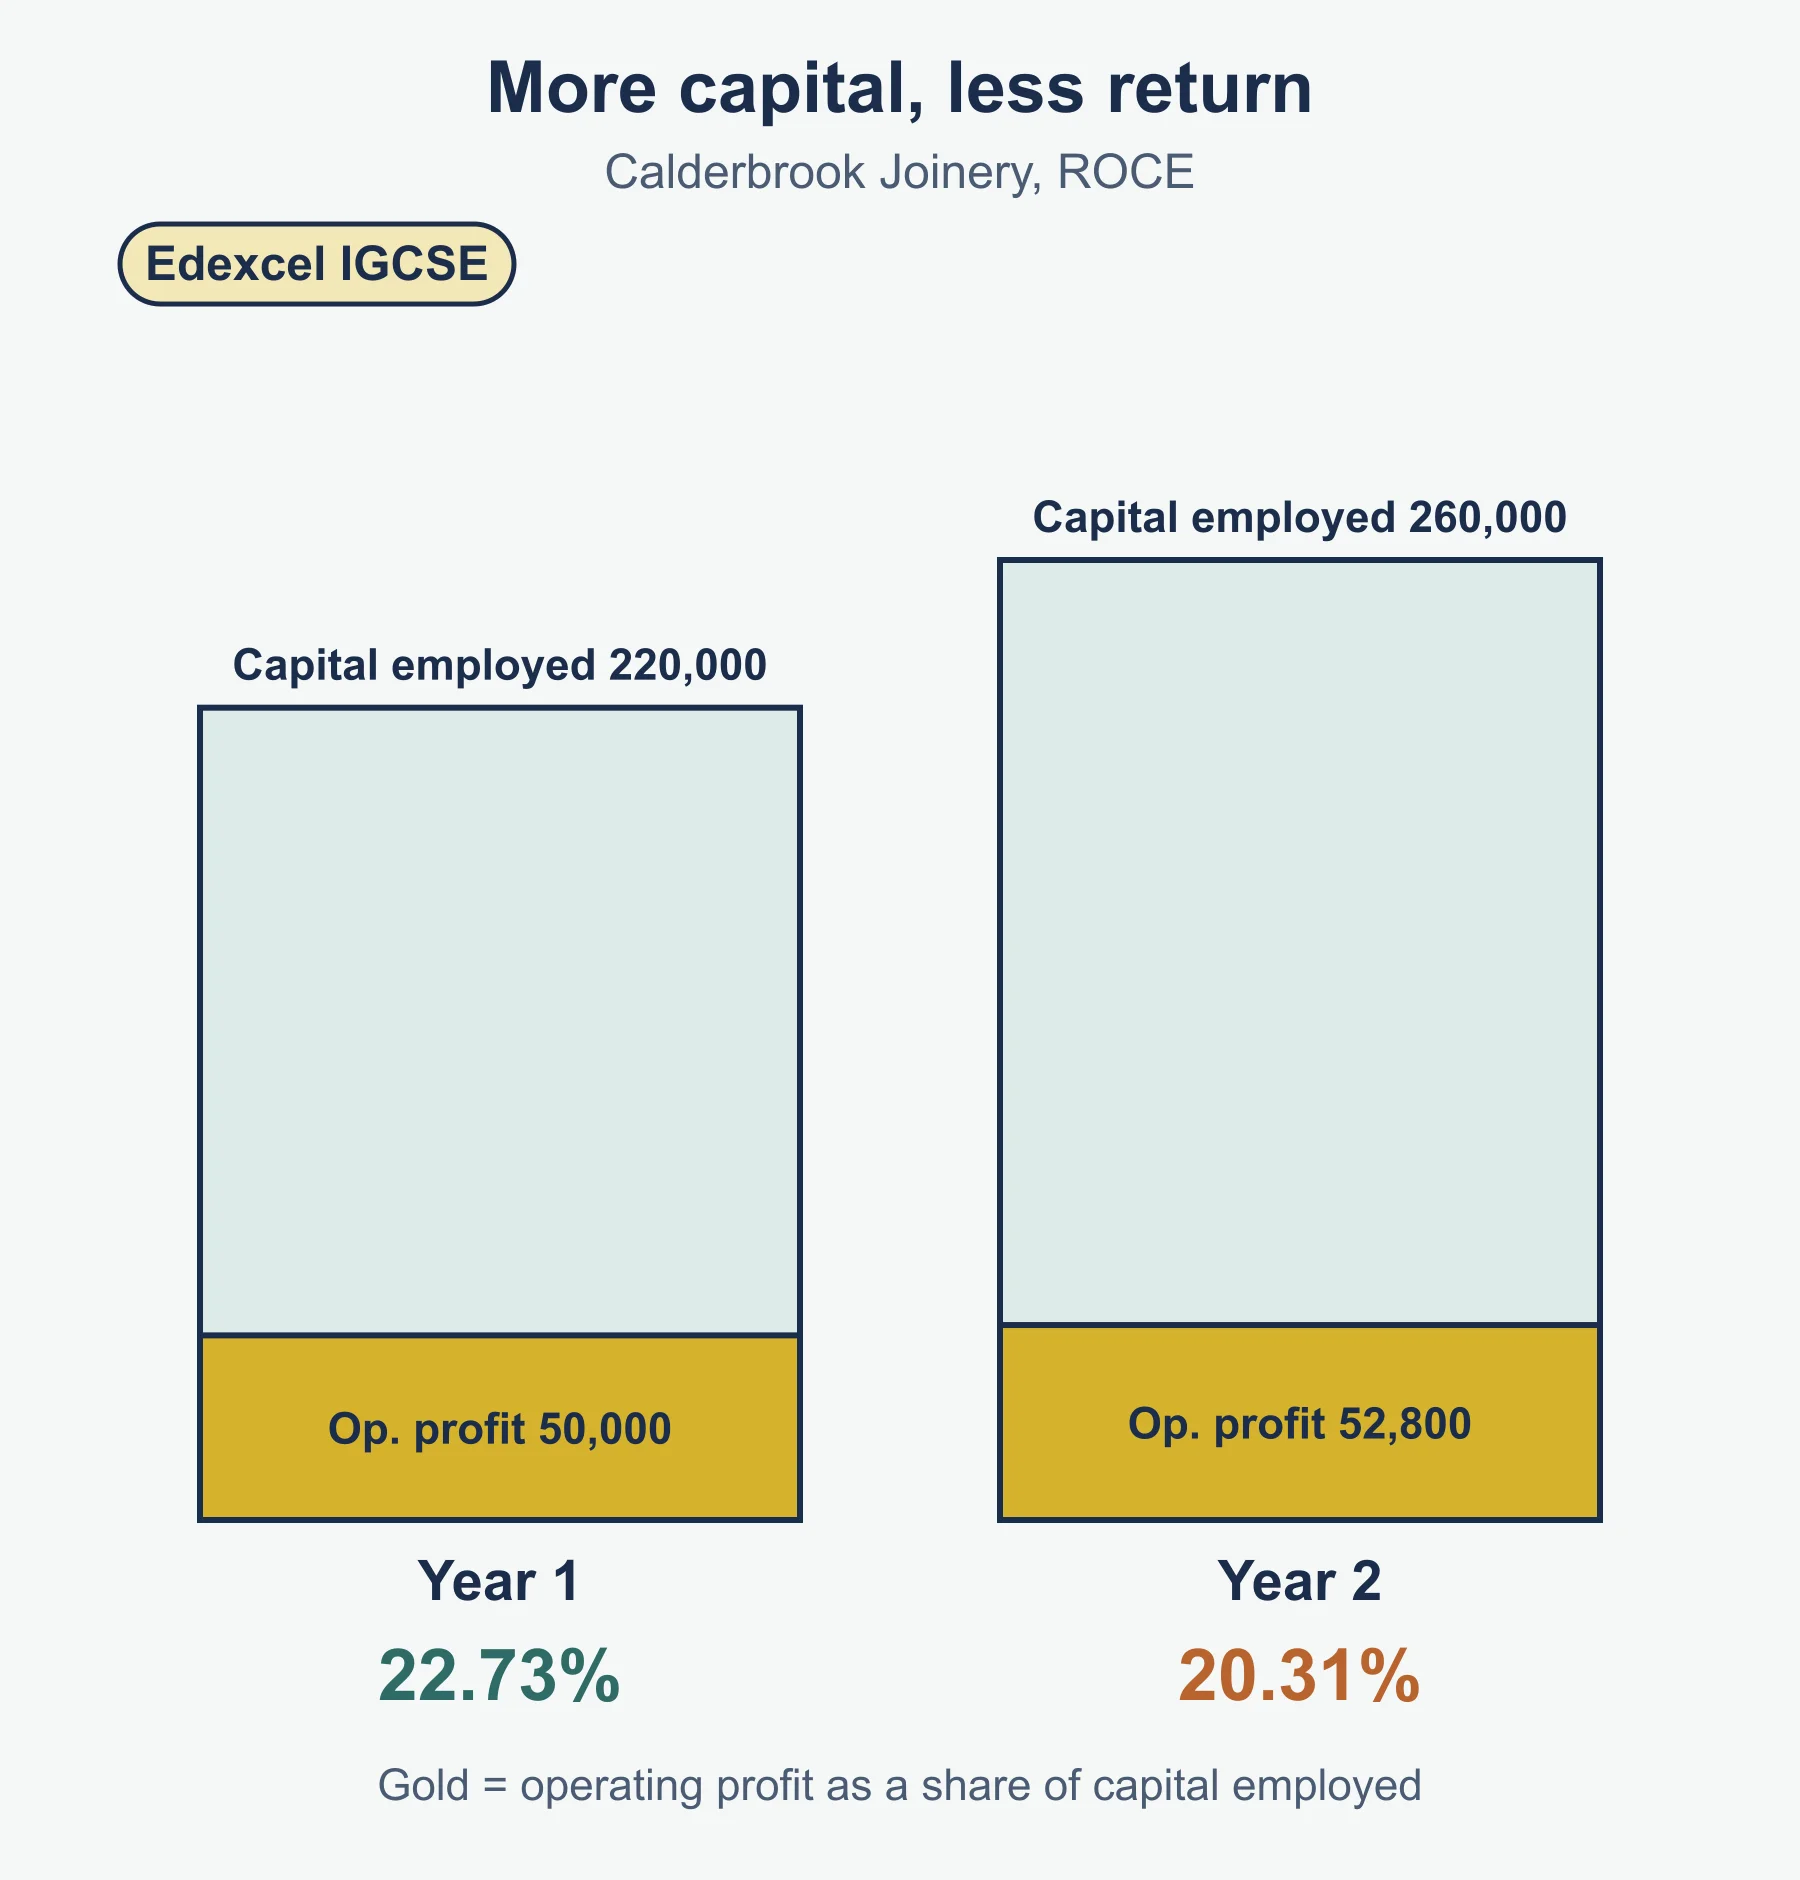
| ROCE | operating profit ÷ capital employed × 100 | % |
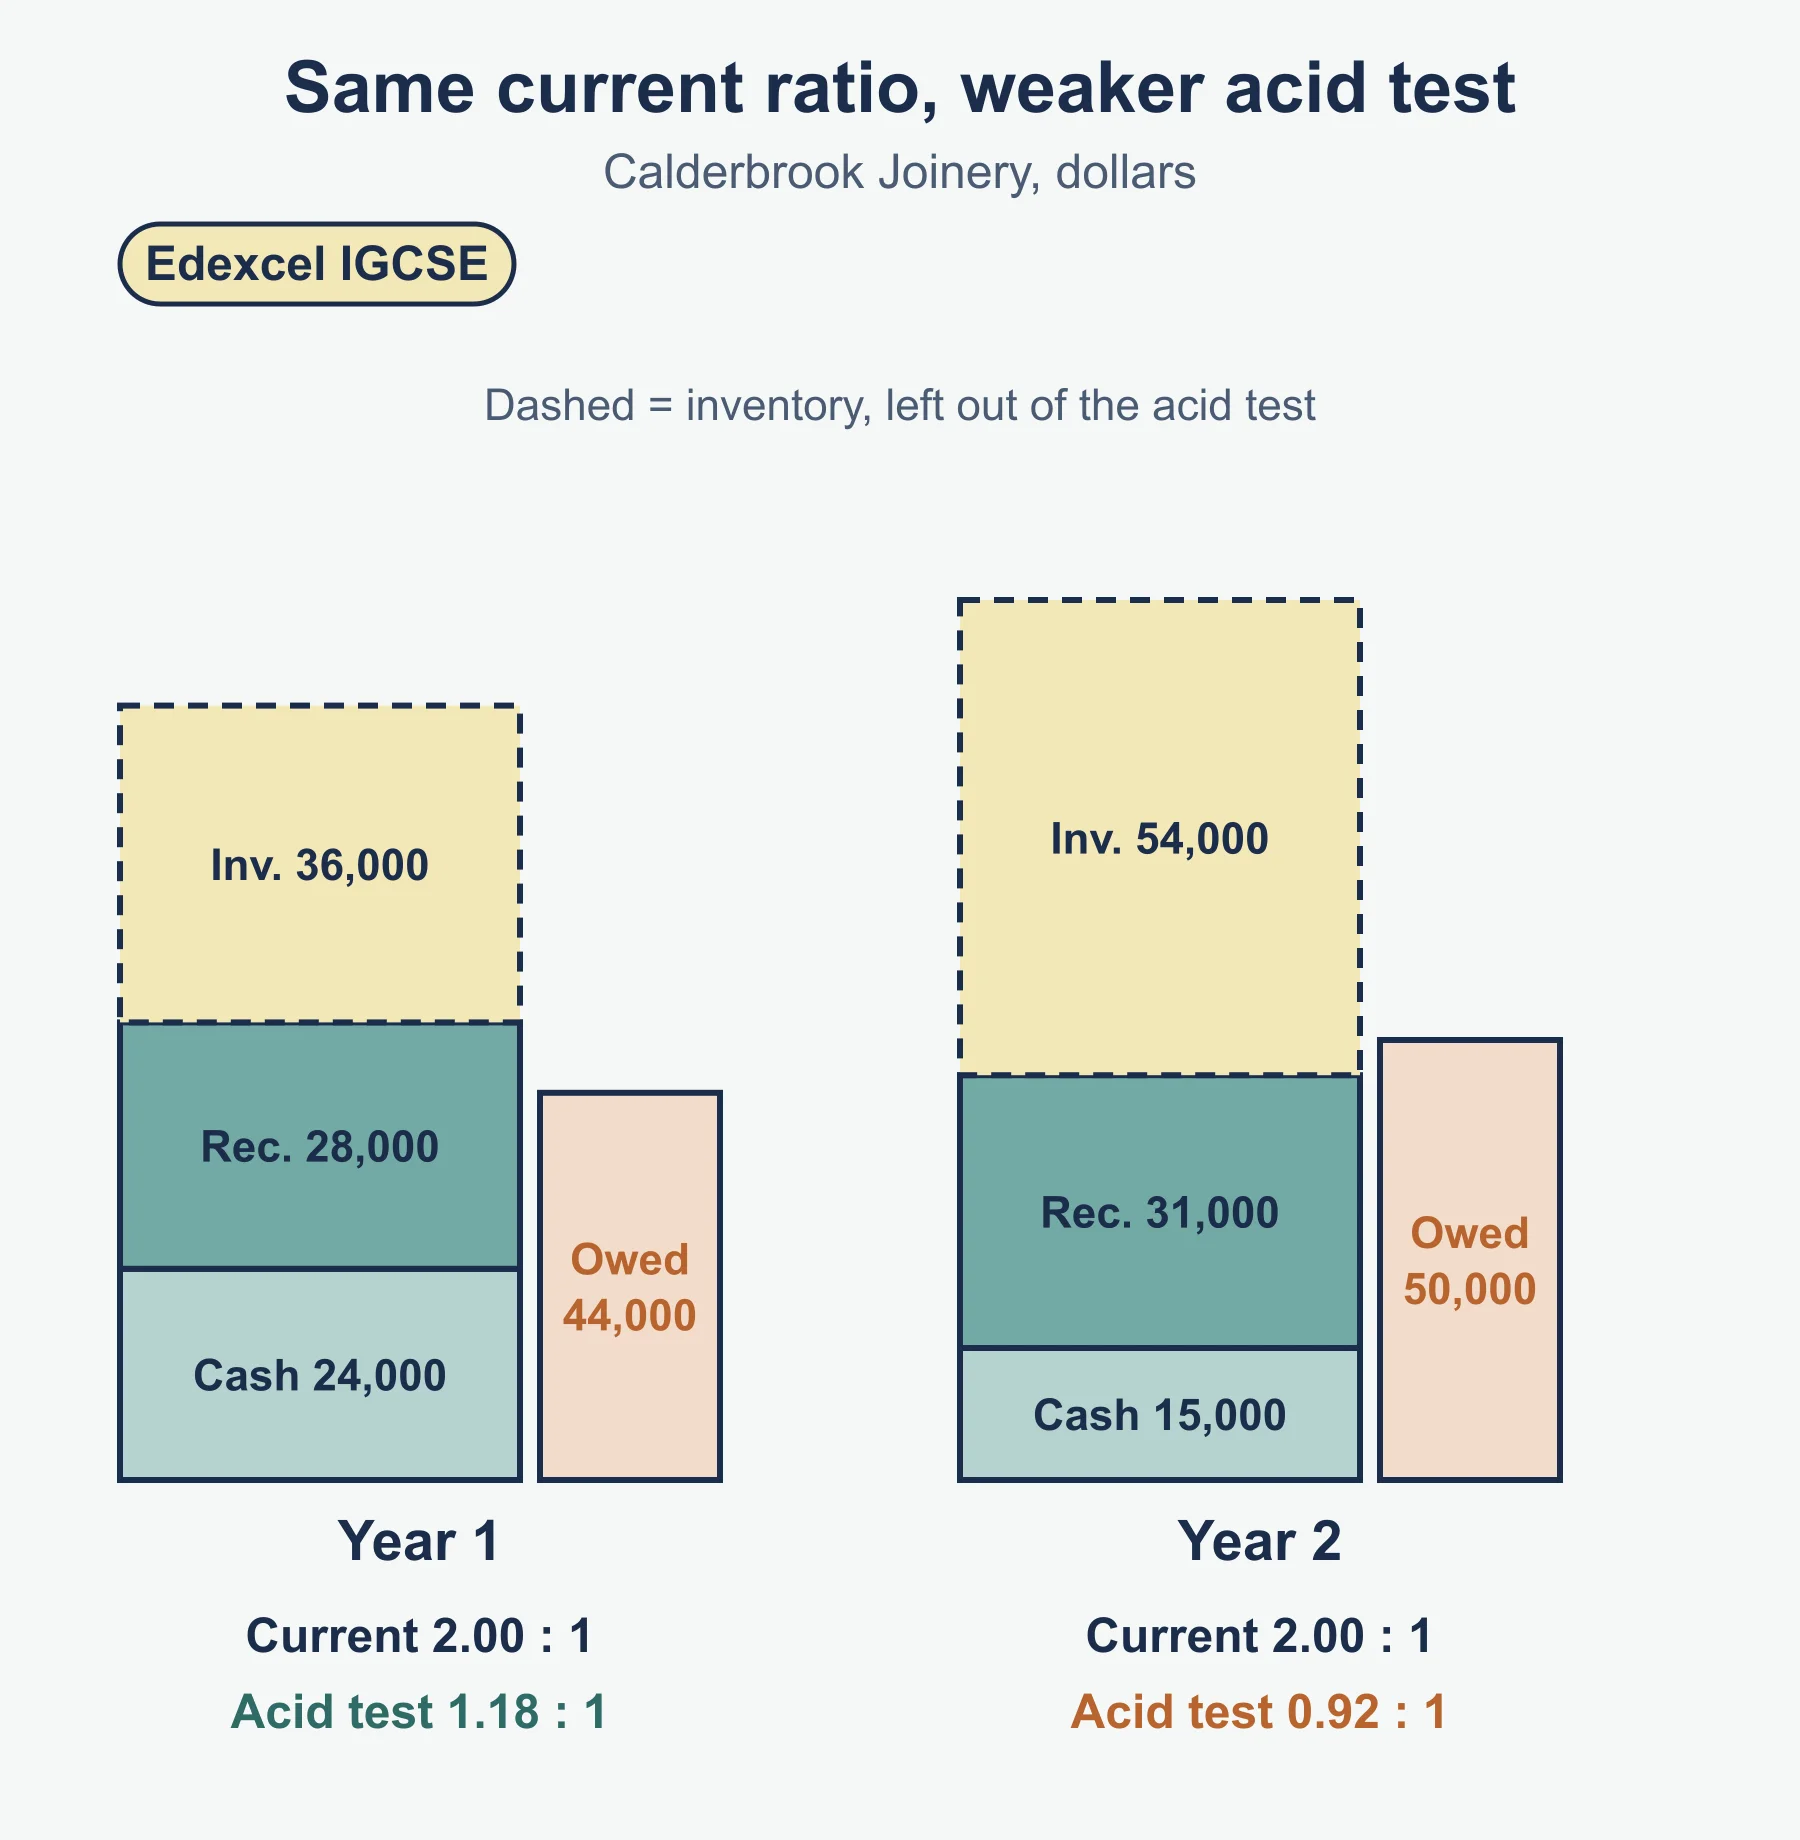
| Current ratio | current assets ÷ current liabilities | x : 1 |
| Acid test ratio | (current assets − inventory) ÷ current liabilities | x : 1 |
Supporting lines: gross profit = revenue − cost of sales; operating profit = gross profit − other operating expenses.
4. Method in steps
- Write the formula. Find each figure on the statement.
- Work out any missing figure first (gross profit, operating profit, capital employed, current assets).
- Calculate and show working. Give the unit: % or x : 1.
- Compare: with the previous year, or with another business.
- Explain the cause, then the consequence, then a suggestion.
5. Worked reminder: Penhallow Print
| Year 1 | Year 2 | |
|---|---|---|
| Revenue | 250,000 | 300,000 |
| Cost of sales | 150,000 | 186,000 |
| Other operating expenses | 70,000 | 84,000 |
| Capital employed | 125,000 | 160,000 |
| Current assets | 60,000 | 66,000 |
| of which inventory | 30,000 | 33,000 |
| Current liabilities | 40,000 | 55,000 |
| Ratio | Year 1 | Year 2 |
|---|---|---|
| Gross profit | 100,000 | 114,000 |
| Gross profit margin | 40.0% | 38.0% |
| Operating profit | 30,000 | 30,000 |
| Operating profit margin | 12.0% | 10.0% |
| ROCE | 24.0% | 18.75% |
| Current ratio | 1.50 : 1 | 1.20 : 1 |
| Acid test ratio | 0.75 : 1 | 0.60 : 1 |
Analysis. Revenue rose by 50,000 but operating profit stayed at 30,000. The gross margin slipped 2 percentage points, and expenses grew at the same pace as revenue (28% of revenue in both years), so the operating margin fell from 12% to 10%. ROCE dropped because 35,000 more capital was employed while profit did not grow. Liquidity weakened on both measures, as current liabilities rose by 15,000 but current assets by only 6,000. An acid test below 1 : 1 means liquid assets do not cover short-term debts. The owner should review material costs, and slow the build-up of short-term debt.
6. Must-know distinctions
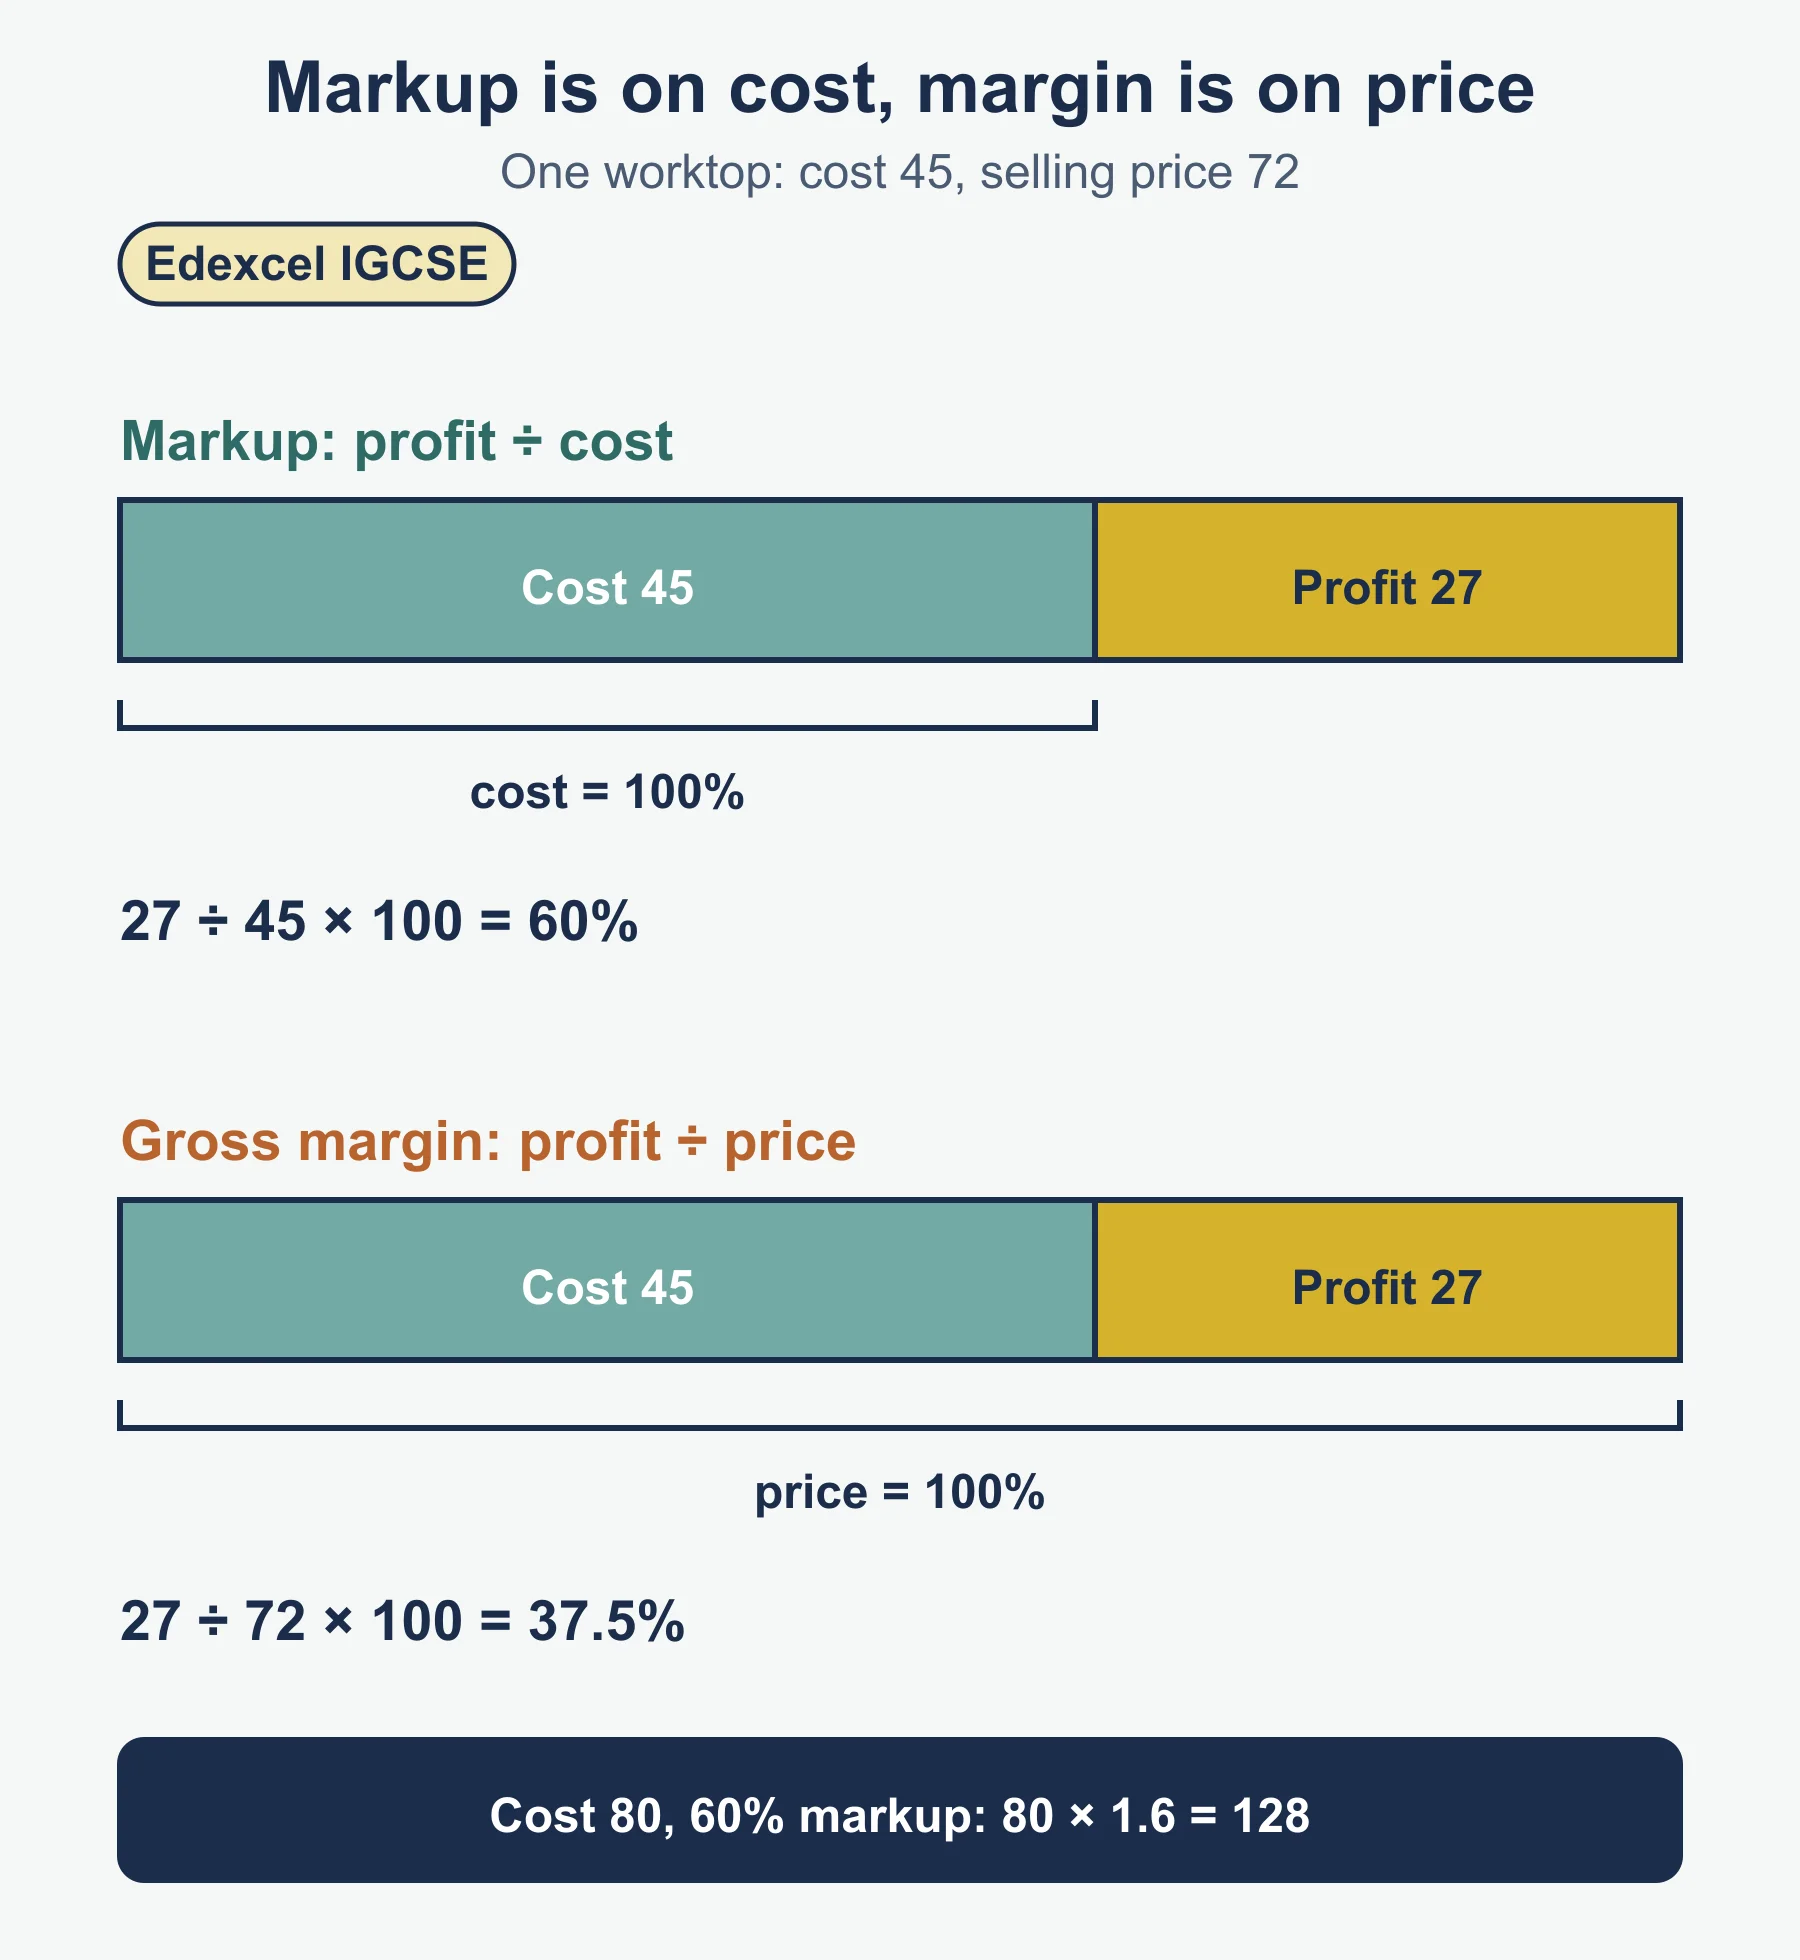
- Markup vs margin. Markup is profit on cost; gross profit margin is profit on selling price. For the same profit, markup is the larger. A cost of 25 sold at 35 gives a markup of 40% and a margin of 28.6%.
- Gross vs operating profit. Operating profit is after other operating expenses.
- Profit vs cash. Profit is a measure of earnings; cash is what is available to pay bills.
- Current ratio vs acid test. The acid test leaves out inventory, which usually takes longest to become cash.
- Margins vs ROCE. Margins use revenue as the base; ROCE uses capital employed.
- Current vs non-current. The dividing line is one year.
- Liquidity vs profitability. Liquidity is about paying short-term debts; profitability is about earning.
6a. Worked reminder: pricing with markup
Penhallow Print buys a pack of paper for 16 and wants a 75% markup. Profit per item = 16 × 0.75 = 12, so the selling price is 16 + 12 = 28. The gross margin on that pack is 12 ÷ 28 × 100 = 42.86%. If a rival sells the same pack at 26, the profit falls to 10, giving a markup of 10 ÷ 16 × 100 = 62.5%. Pricing against a rival means choosing between a lower markup and fewer sales; explain both sides when asked to justify or evaluate.
7. Liquidity and comparisons (3.5.2)
Liquidity means having enough cash, or assets that quickly become cash, to meet bills coming due. Suppliers and employees expect prompt payment, and an illiquid firm can fail even when it makes a profit. Make comparisons with previous years (trend) and with similar businesses (position). Say what is being compared and why the comparison is fair.
8. Using financial documents (3.5.3)
- Assess performance: margins, operating profit and ROCE over time and against rivals.
- Inform decisions: pricing, cost control, stock levels, borrowing, expansion, whether to grant credit.
- Evaluate: weigh strengths against weaknesses, then reach a supported judgement.
Command words in the specification: calculate (give working), explain (a fact with two expansion points), analyse (extended, in context), justify (use the information to recommend one of two options), evaluate (supported conclusion).
9. Quick self-test
- A shop earns gross profit of 63,000 from revenue of 420,000. Find its gross profit margin.
- Gross profit is 54,000, other operating expenses are 39,600 and revenue is 240,000. Find operating profit and the operating profit margin.
- An item costs 25 and makes 10 profit. Find the markup.
- Operating profit is 18,000 and capital employed is 150,000. Find ROCE.
- Current assets are 72,000 (inventory 30,000) and current liabilities are 48,000. Work out both liquidity ratios.
- Non-current assets are 310,000, current assets 90,000 and current liabilities 150,000. Find capital employed.
- Revenue is 70,000 and cost of sales 45,500. Find the gross profit margin.
- A product costs 20 and the markup is 150%. Find the selling price.
- Current assets are 60,000 and current liabilities 50,000. The business pays 10,000 to trade payables from cash. Find the new current ratio.
- Gross profit margin is 30% on revenue of 150,000. Other operating expenses are 27,000. Find the operating profit margin.
Answers
- 63,000 ÷ 420,000 × 100 = 15%.
- 54,000 − 39,600 = 14,400; 14,400 ÷ 240,000 × 100 = 6%.
- 10 ÷ 25 × 100 = 40%.
- 18,000 ÷ 150,000 × 100 = 12%.
- 72,000 ÷ 48,000 = 1.5 : 1; (72,000 − 30,000) ÷ 48,000 = 0.875, or 0.88 : 1 to 2 decimal places.
- 310,000 + 90,000 − 150,000 = 250,000.
- Gross profit 24,500; 24,500 ÷ 70,000 × 100 = 35%.
- Profit 20 × 1.5 = 30; price = 50.
- Current assets 50,000; current liabilities 40,000; 50,000 ÷ 40,000 = 1.25 : 1, up from 1.2 : 1.
- Gross profit 45,000; operating profit 18,000; 18,000 ÷ 150,000 × 100 = 12%.
10. Where marks are usually lost
- Choosing the wrong divisor: revenue in ROCE, or capital employed in a margin.
- Dividing markup by the selling price.
- Leaving out the unit (% or x : 1) on an answer.
- Taking away all current assets, not just inventory, in the acid test.
- Using current liabilities that exclude the overdraft or a short-term amount.
- Stating that a ratio “went up” without saying why or what it means for the business.
- Writing only one side in an evaluate or justify answer, or never reaching a decision.
- Quoting a ratio without comparing it with an earlier year or a rival.
- Calculating capital employed with non-current liabilities left out or counted twice.
- Mixing up profit and cash when explaining why a profitable firm is struggling.
Next steps
Test yourself on the practice questions, return to the study guide, and check the free diagnostics.
Frequently asked questions
What is the difference between gross profit and operating profit? Gross profit is revenue minus cost of sales. Operating profit is gross profit minus other operating expenses such as wages, rent and advertising.
How do you calculate ROCE? Return on capital employed is operating profit divided by capital employed, multiplied by 100. It shows how much operating profit each 100 of long-term funds produced.
What is the difference between markup and profit margin? Markup measures profit per item against the cost per item, while a margin measures profit against revenue. Because the bases differ, markup is always the larger figure for the same profit.
Do you have to construct financial statements in Edexcel IGCSE Business? No. The 4BS1 specification states that you will not be asked to construct an income statement or a statement of financial position; you read them, take figures from them and interpret them.
Official syllabus
Pearson Edexcel International GCSE in Business (4BS1), Specification, Issue 2, February 2026, published by Pearson Education Limited. Topic 3: Business finance, sections 3.4 and 3.5; Appendix 2 (command word taxonomy) and Appendix 4 (formulae).
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
Edexcel IGCSE Business: Sources of business finance and cash flow forecasting (4BS1)
Study guide to sources of business finance, why cash matters, and building and reading a cash-flow forecast for Edexcel IGCSE Business (4BS1).
Business · Pearson Edexcel · IGCSE
Read guide -
Practice questions
Edexcel IGCSE Business: Sources of business finance and cash flow forecasting (4BS1) – Practice Questions
Original practice questions with worked answers on sources of finance, cash versus profit and cash-flow forecasts for Edexcel IGCSE Business.
Business · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Business: Sources of business finance and cash flow forecasting (4BS1) – Revision Notes
Condensed revision notes on sources of finance, cash versus profit and cash-flow forecasts for Edexcel IGCSE Business, with a quick self-test.
Business · Pearson Edexcel · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Business teachers at Marlbridge

