
Study Guides
IGCSE Accounting: Capital and revenue items, depreciation and disposals (Cambridge 0452)
Study guide to capital and revenue items, depreciation methods, and ledger accounts for disposals in Cambridge IGCSE Accounting 0452 (2027-2029).
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- Accounting procedures
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus points this page covers
0452
- 4.1 Capital and revenue expenditure and receipts
- 4.2 Accounting for depreciation and disposal of non-current assets
7707
- 4.1 Capital and revenue expenditure and receipts
- 4.2 Accounting for depreciation and disposal of non-current assets
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. For this topic, the 2026 syllabus says “recovery of debts written off” where the 2027-2029 syllabus says “irrecoverable debts recovered”, asks for simple inventory valuation statements, and does not separately list choosing a depreciation method for each type of non-current asset, journal entries for purchasing a non-current asset, or calculating the profit or loss on disposal. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
This guide covers syllabus sections 4.1 Capital and revenue expenditure and receipts and 4.2 Accounting for depreciation and disposal of non-current assets in Cambridge IGCSE Accounting 0452, for exams in 2027, 2028 and 2029 (version 1). Both sit inside Topic 4, Accounting procedures, and the syllabus does not split them into tiers. All amounts are in dollars. The wider topic is in the Topic 4 study guide, whose examples this page does not repeat. Use the revision notes and the practice questions next. Correcting misposted items links to Verification of Accounting Records. The course hub is Cambridge IGCSE Accounting, the printable checklist tracks progress, and the free diagnostics show where to start.
What the syllabus asks you to do
| Syllabus point | Taught under |
|---|---|
| 4.1 capital and revenue expenditure: the distinction and the accounting | Capital and revenue expenditure |
| 4.1 capital and revenue receipts: the distinction and the accounting | Capital and revenue receipts |
| 4.1 effect on profit and on asset valuations of incorrect treatment | Effect of incorrect treatment |
| 4.2 meaning of depreciation; the need to account for it | What depreciation is |
| 4.2 straight-line, reducing balance and revaluation; the right method for each asset | Three methods; Choosing a method |
| 4.2 journal entries and ledger accounts for depreciation, purchase and sale; the three accounts; profit or loss on disposal | Recording depreciation, purchase and sale |
Capital and revenue expenditure
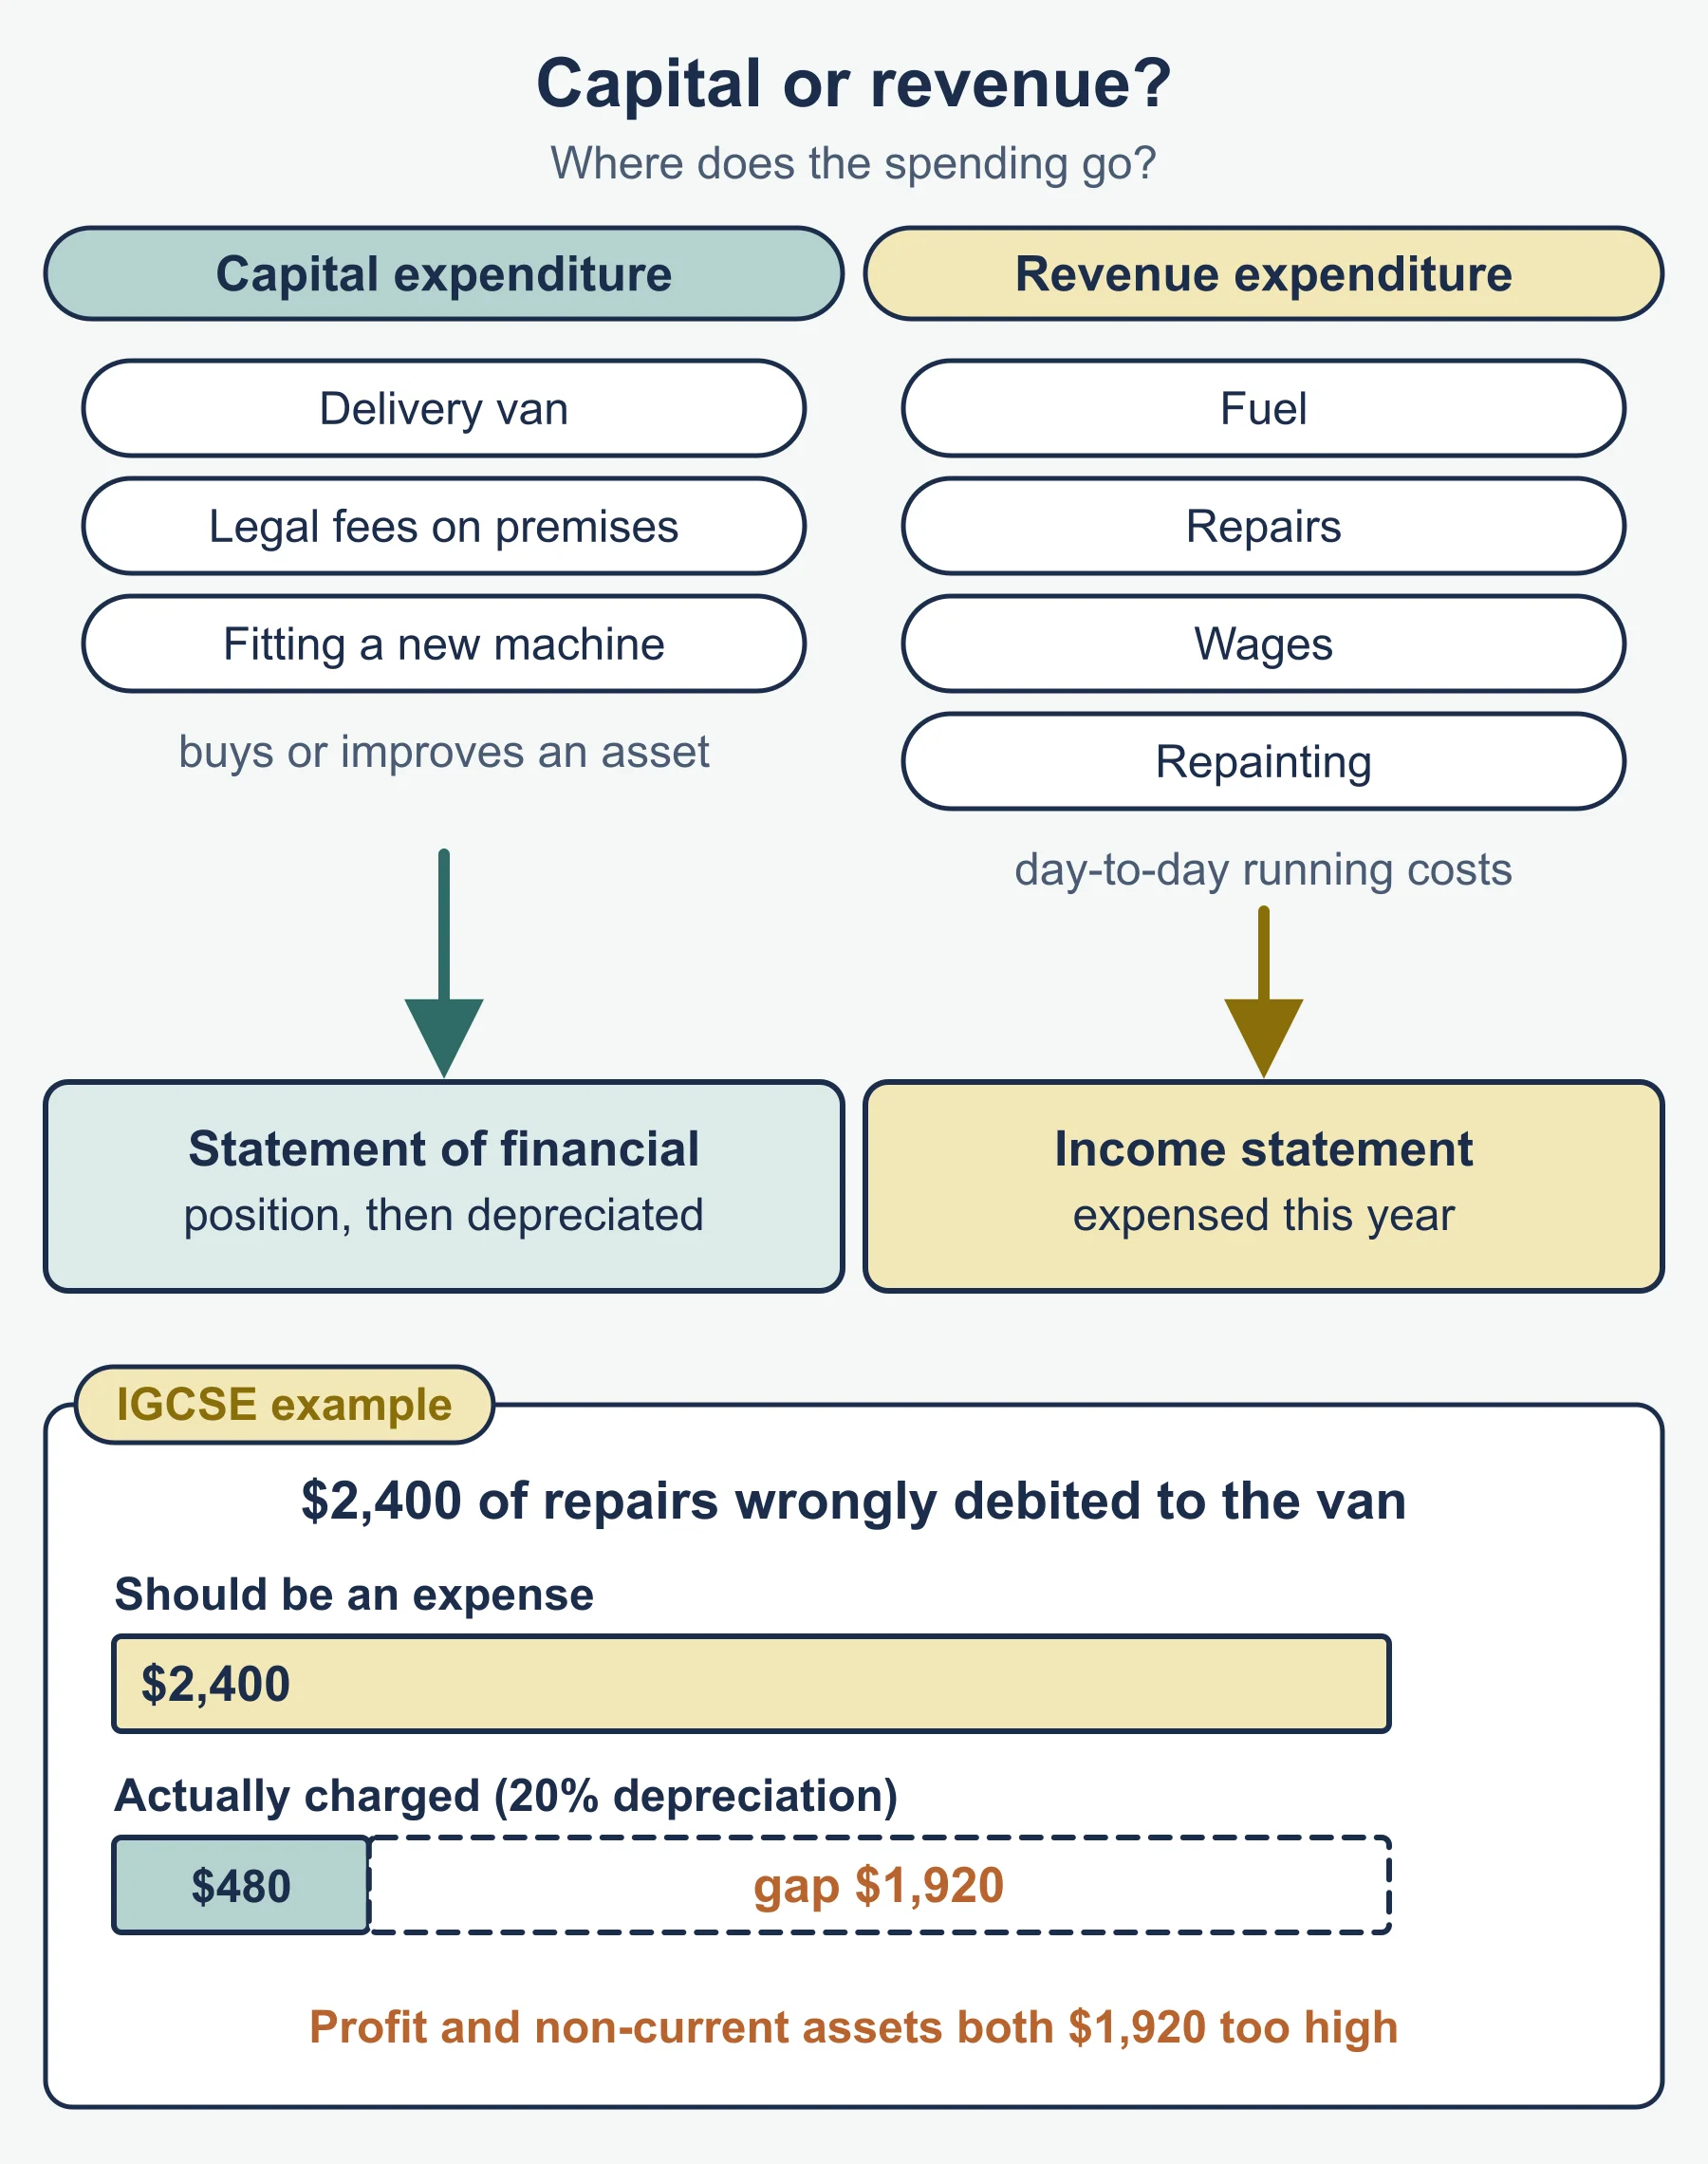
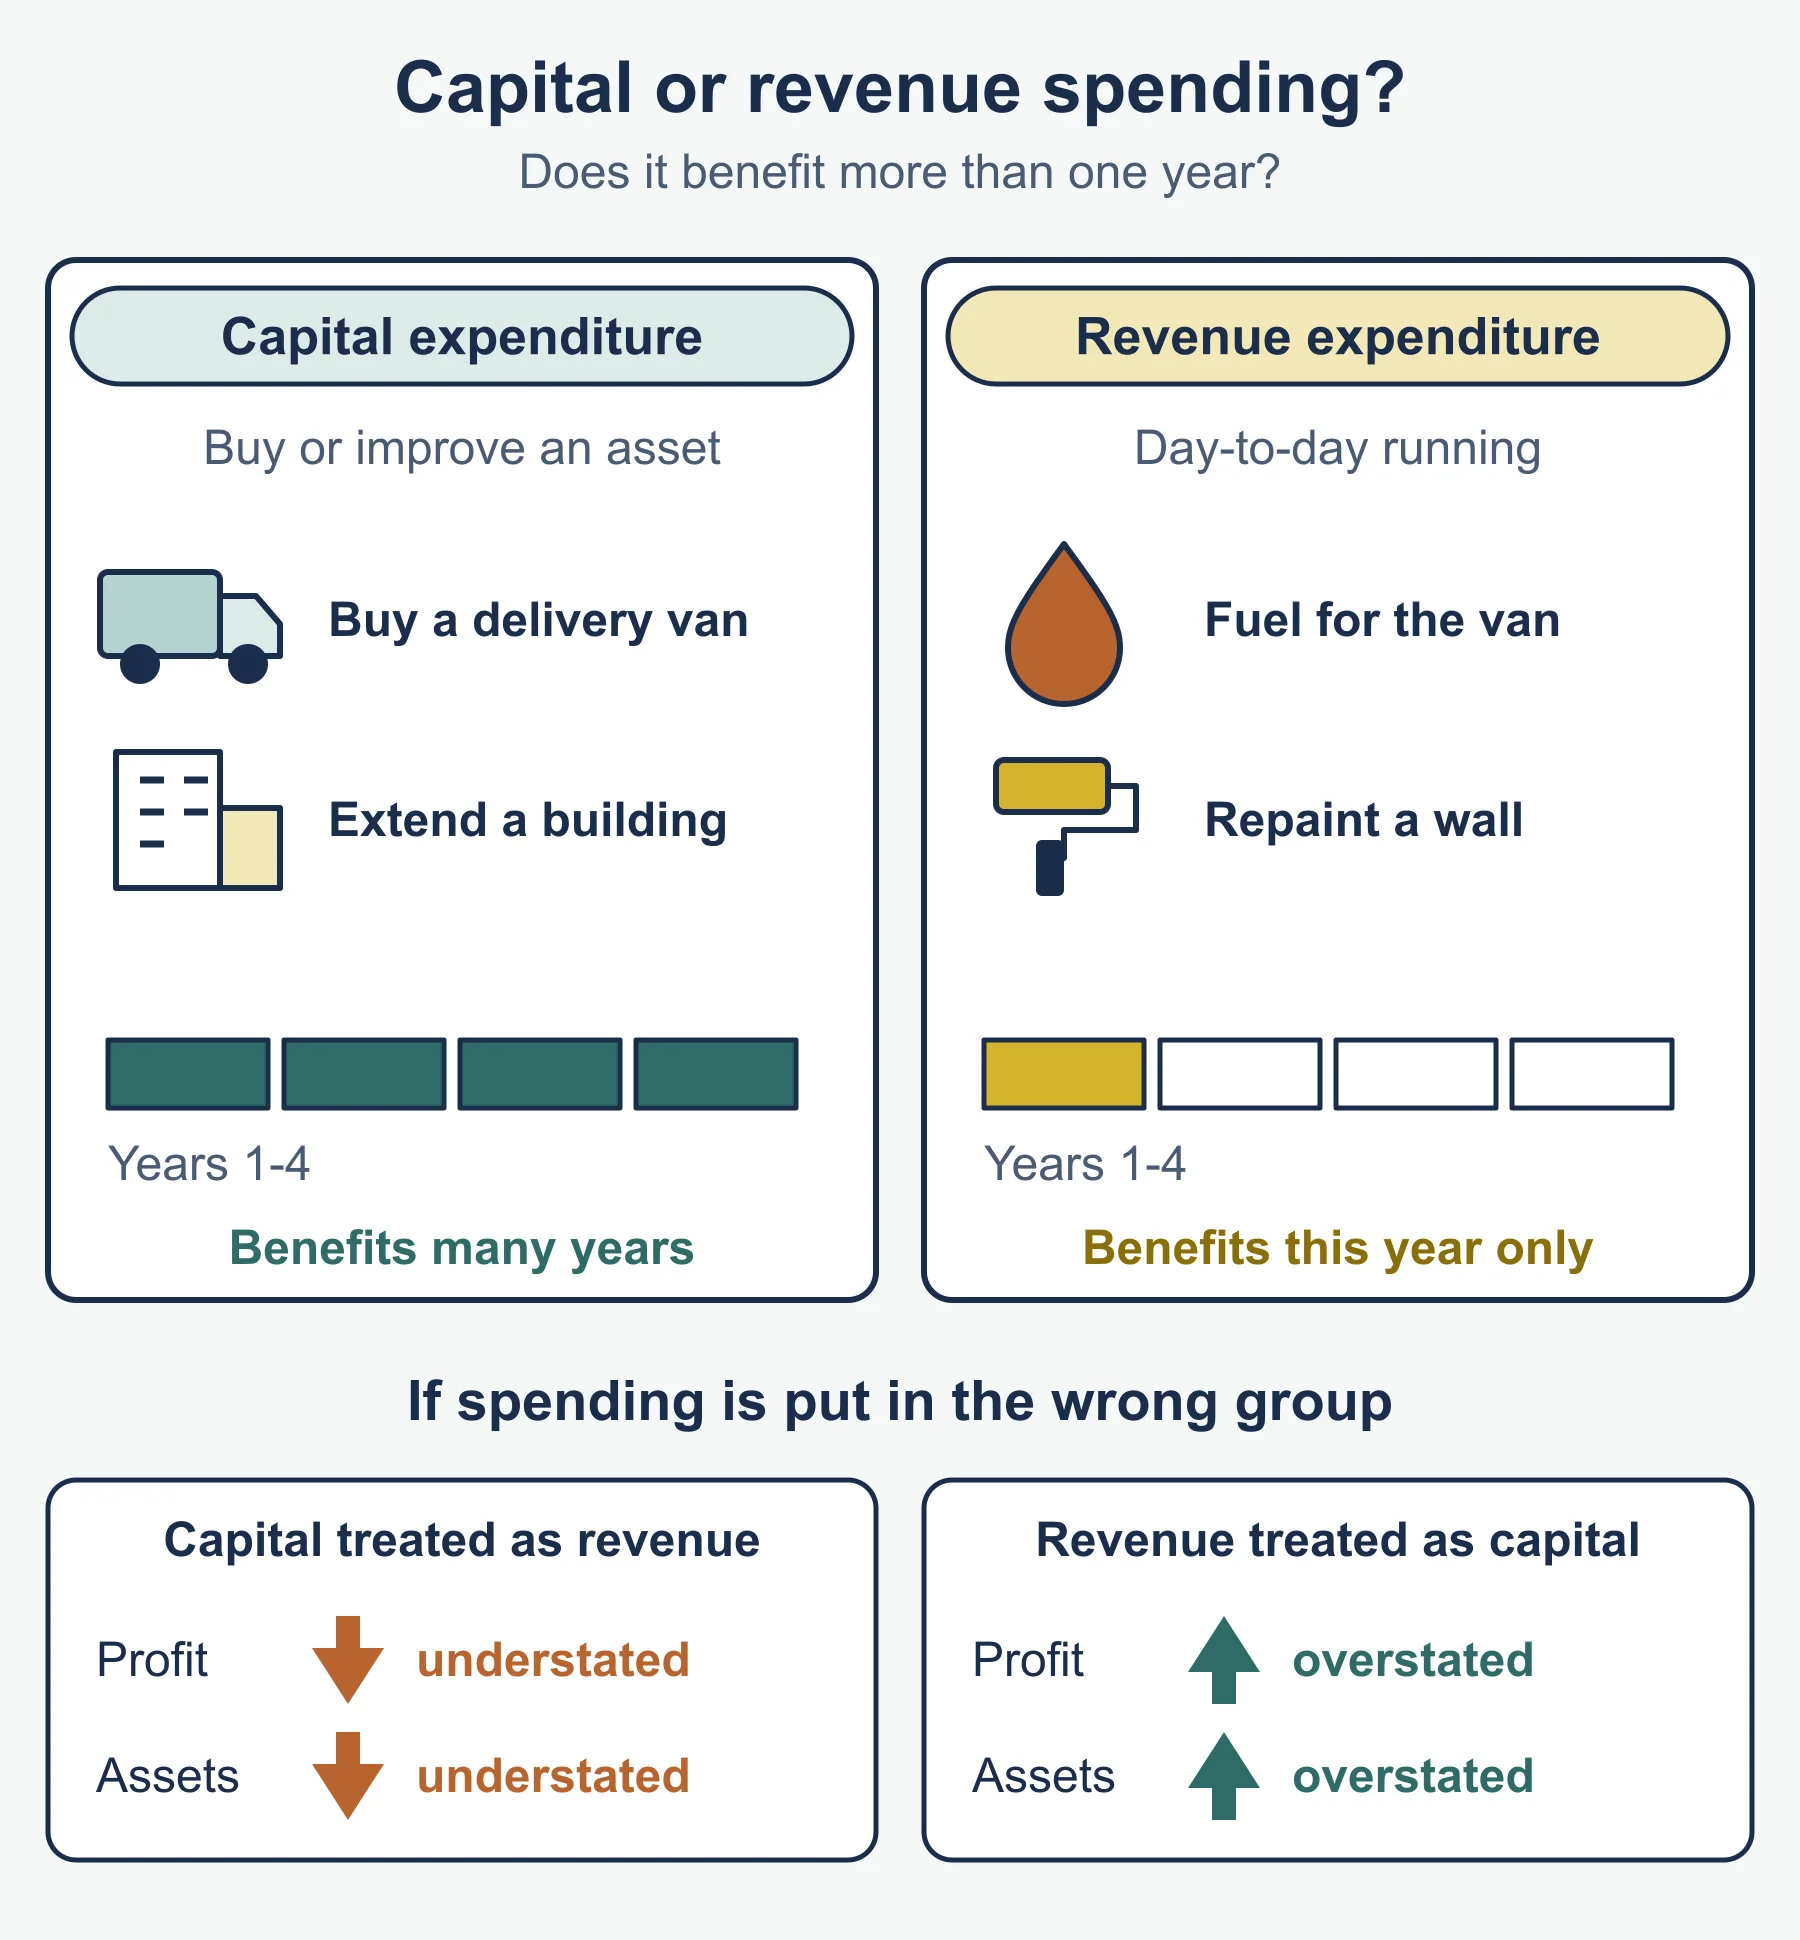
Capital expenditure is spending on buying a non-current asset, on improving it, or on getting it ready for use, such as delivery and installation. Revenue expenditure is spending that keeps the business running from day to day and keeps assets in their present condition, such as repairs, servicing and decoration.
Ask of every payment: does it add to what the business owns, or keep it running? Thornlea Joinery makes kitchen cabinets. These are its payments this year.
| Payment | Type | Debited to |
|---|---|---|
| Band saw 9,600 | Capital | Machinery |
| Delivery of the saw 400 | Capital (getting it ready for use) | Machinery |
| Wiring to power the saw 750 | Capital (getting it ready for use) | Machinery |
| Replacement saw blades 460 | Revenue | Repairs |
| Annual service of machines 380 | Revenue | Repairs |
| Extension to the workshop 18,000 | Capital (improvement) | Premises |
| Repainting workshop walls 1,150 | Revenue (maintenance) | Repairs |
| Legal fees on buying the workshop 2,200 | Capital (cost of acquiring) | Premises |
How to account for them. Capital expenditure is debited to the non-current asset account and appears in the statement of financial position, reaching the statement of profit or loss only through depreciation. Revenue expenditure is debited to an expense account and is moved into the statement of profit or loss when the year closes. If the saw is bought on credit from Norwood Machinery Supplies, the journal entry is debit Machinery 9,600, credit Norwood Machinery Supplies 9,600.
Capital and revenue receipts
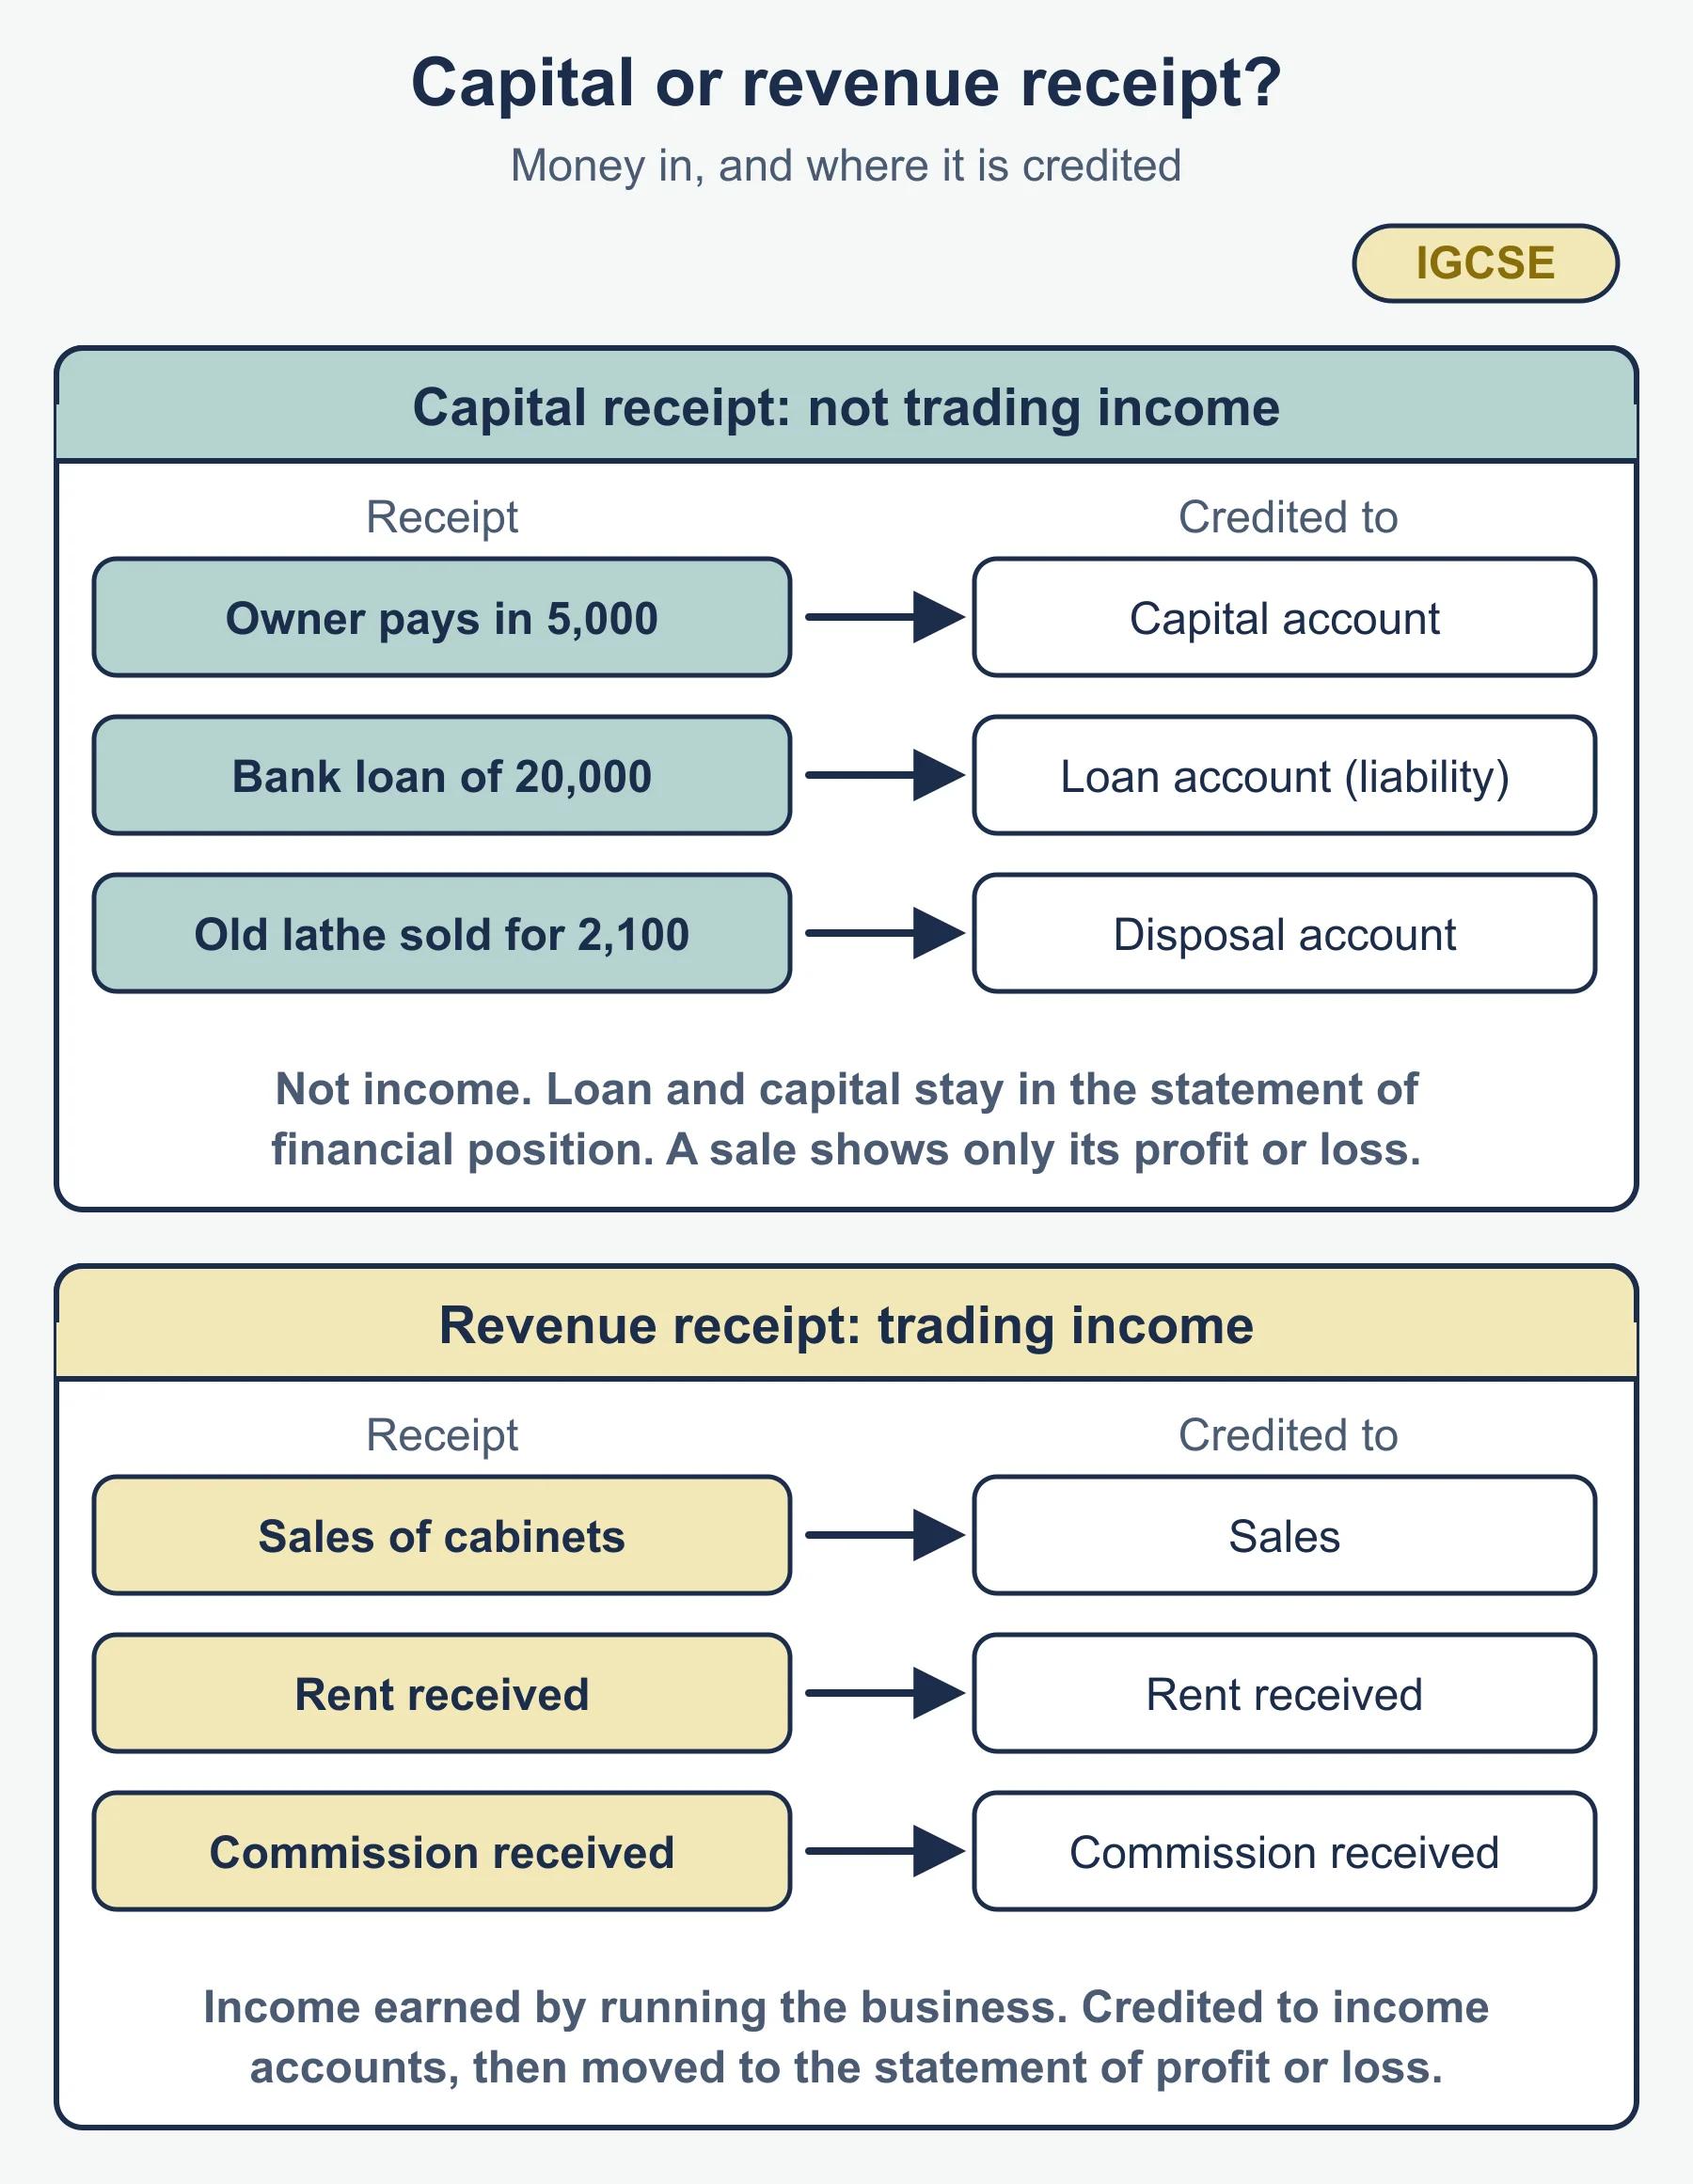
A capital receipt is money received that is not income from trading: the owner paying in capital, a loan, or the proceeds of selling a non-current asset. A revenue receipt is income earned from running the business, such as sales, rent received and commission received.
| Receipt | Type | Credited to |
|---|---|---|
| Old lathe sold for 2,100 | Capital | Disposal account |
| Owner pays in 5,000 | Capital | Capital account |
| Bank loan of 20,000 | Capital | Loan account (a liability) |
| Sales of cabinets | Revenue | Sales |
| Rent received or commission received | Revenue | Rent received or commission received |
Revenue receipts are credited to income accounts and are transferred to the statement of profit or loss. Capital receipts are not income. A loan and the owner’s capital stay in the statement of financial position; when a non-current asset is sold, only the resulting profit or loss on disposal is taken to the statement of profit or loss.
Effect of incorrect treatment
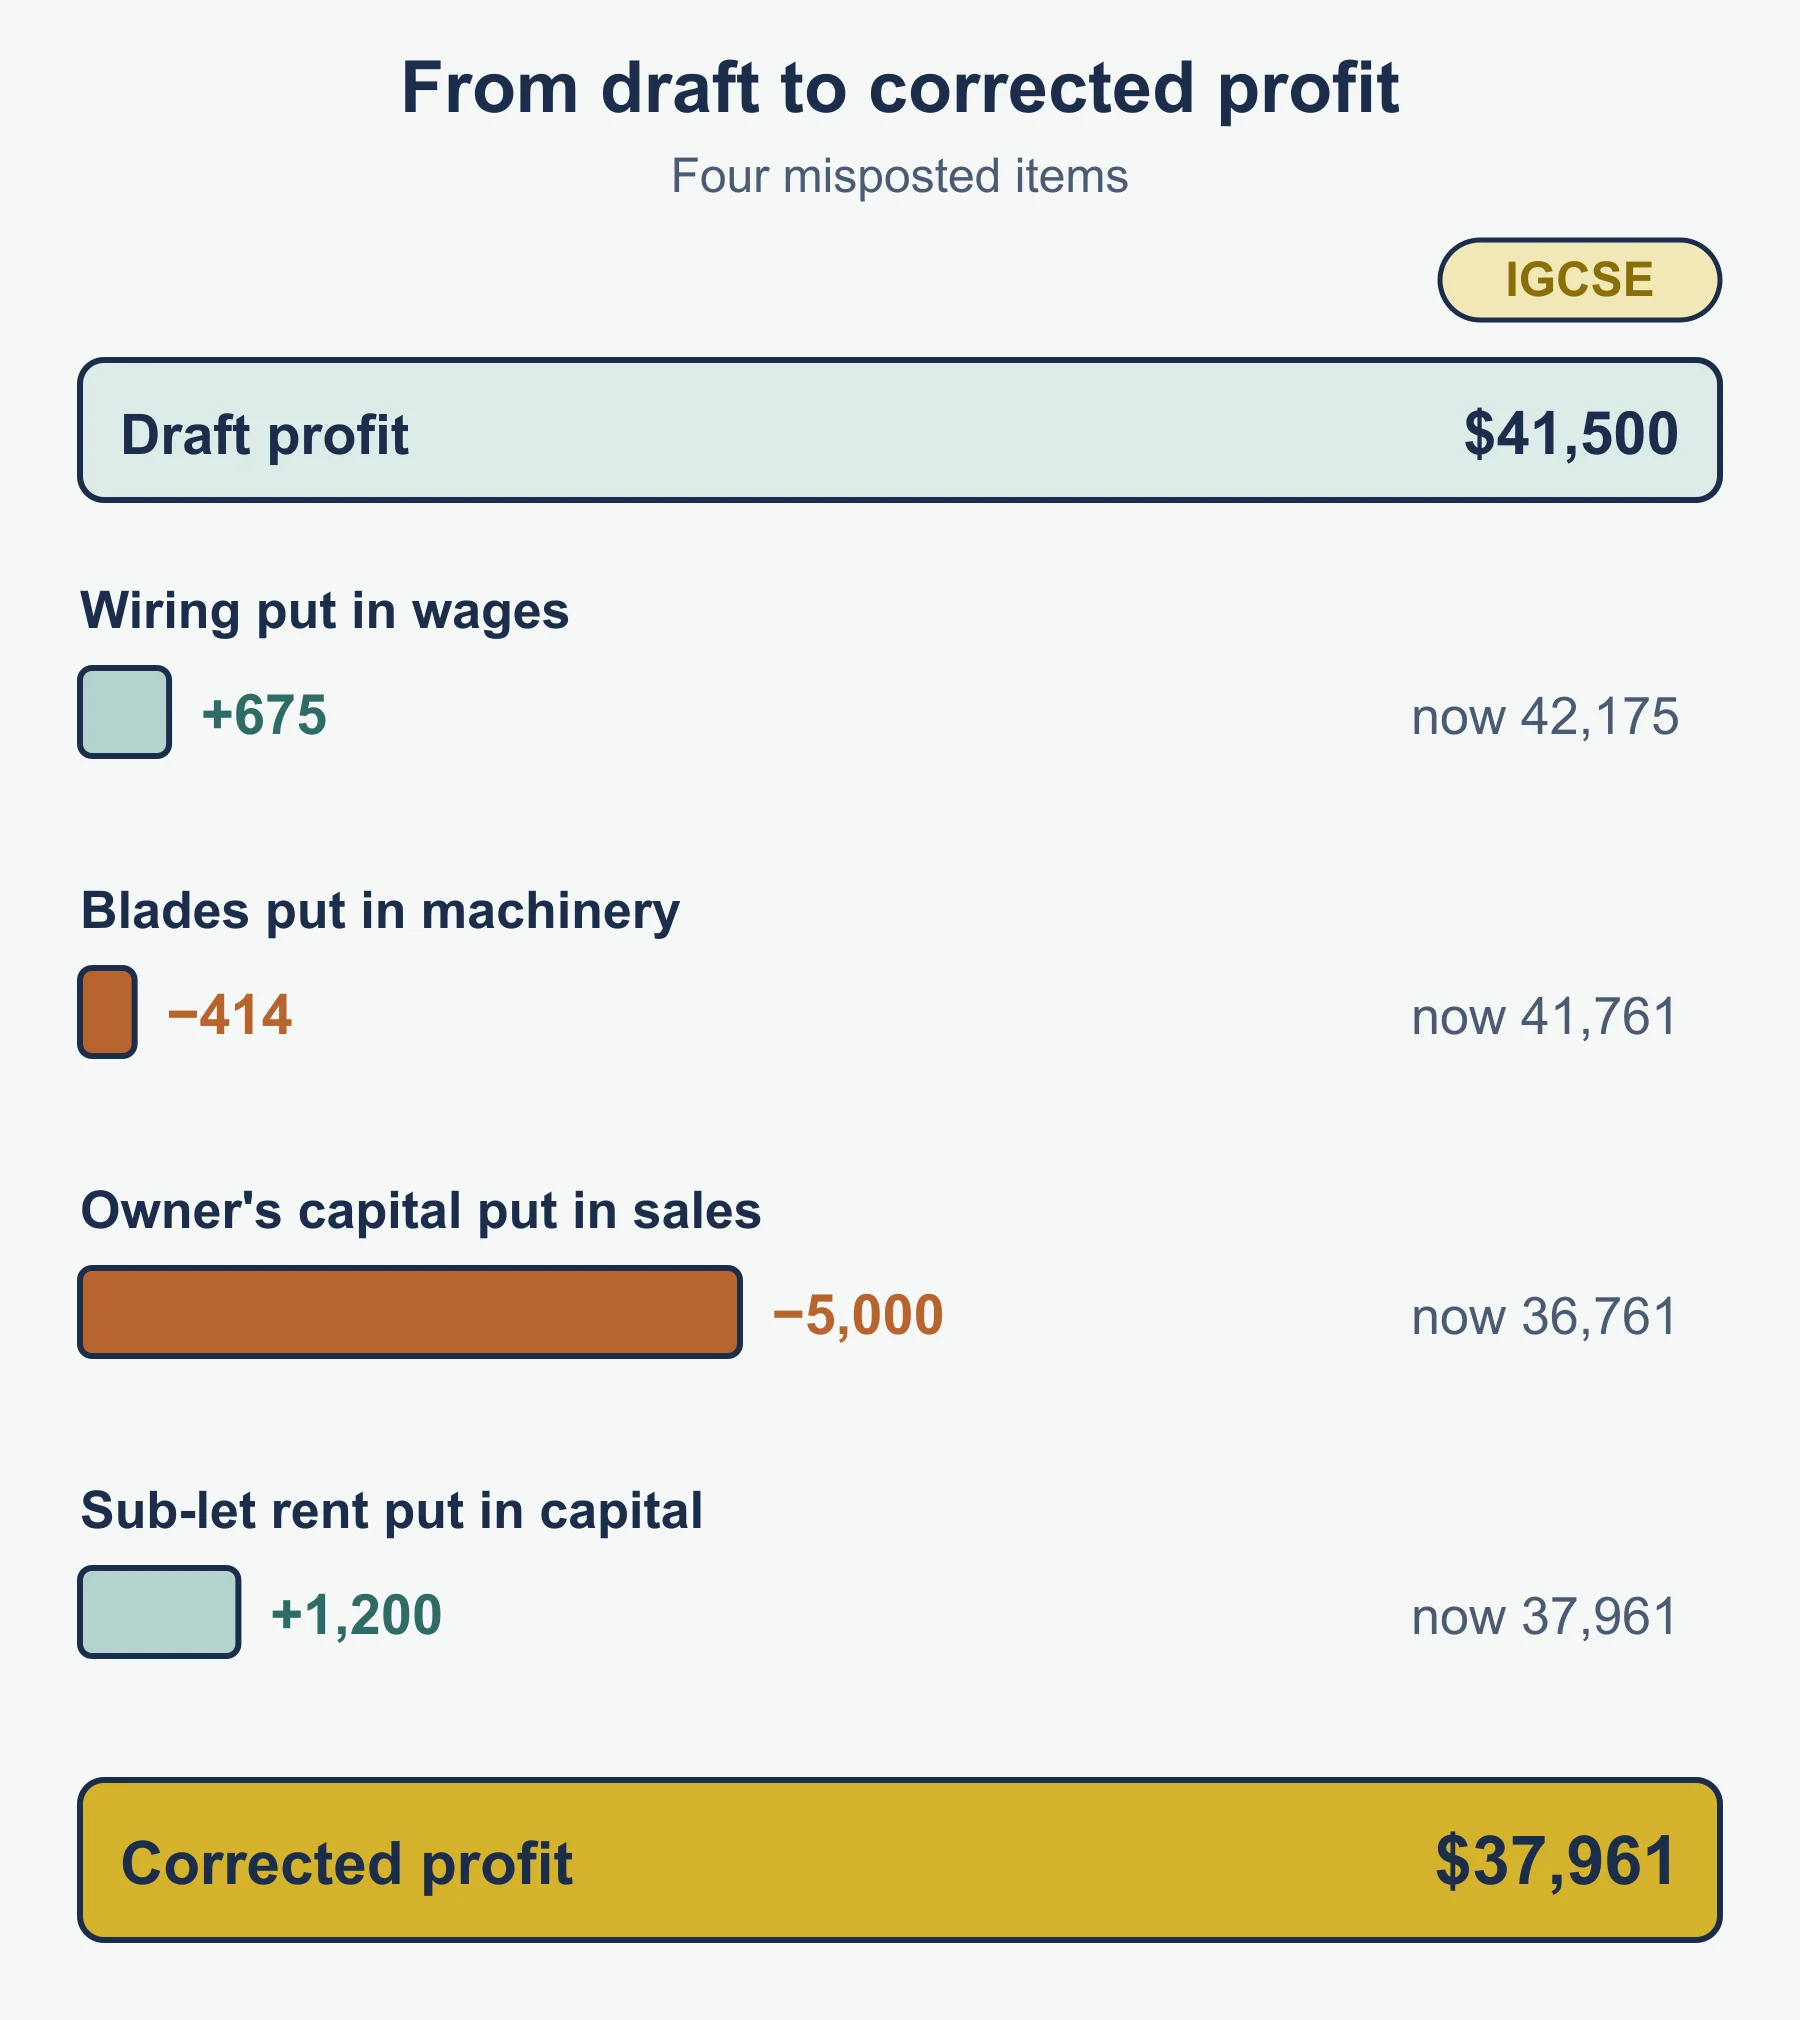
Thornlea’s draft profit was 41,500. It depreciates machinery at 10% a year on cost, straight-line, charging a whole year in the year an asset is bought. Four items were misposted.
| Item | Posted wrongly | Effect on profit | Effect on non-current assets |
|---|---|---|---|
| 750 wiring for a new machine | Debited to wages | Charged 750 instead of 75 depreciation, so understated by 675 | Machinery understated by 675 |
| 460 replacement blades | Debited to machinery, then depreciated | Charged 46 instead of 460, so overstated by 414 | Machinery overstated by 414 |
| 5,000 paid in by the owner | Credited to sales | Overstated by 5,000 | None: bank was debited correctly |
| 1,200 rent received for sub-letting | Credited to the capital account | Understated by 1,200 | None |
Corrected profit
Draft profit                        41,500
Add: wiring capitalised, net of depreciation   675
Less: blades expensed, net of depreciation     414
Less: capital wrongly counted as sales       5,000
Add: rent received counted as capital        1,200
Corrected profit                    37,961
Net effect on non-current assets: 675 less 414 gives an increase of 261. Treating revenue expenditure as capital overstates profit and assets, but by less than the full amount because some depreciation has been charged. Treating capital as revenue does the opposite. A receipt put in the wrong class changes profit but leaves asset values alone, unless an asset sold is left in the books.
What depreciation is
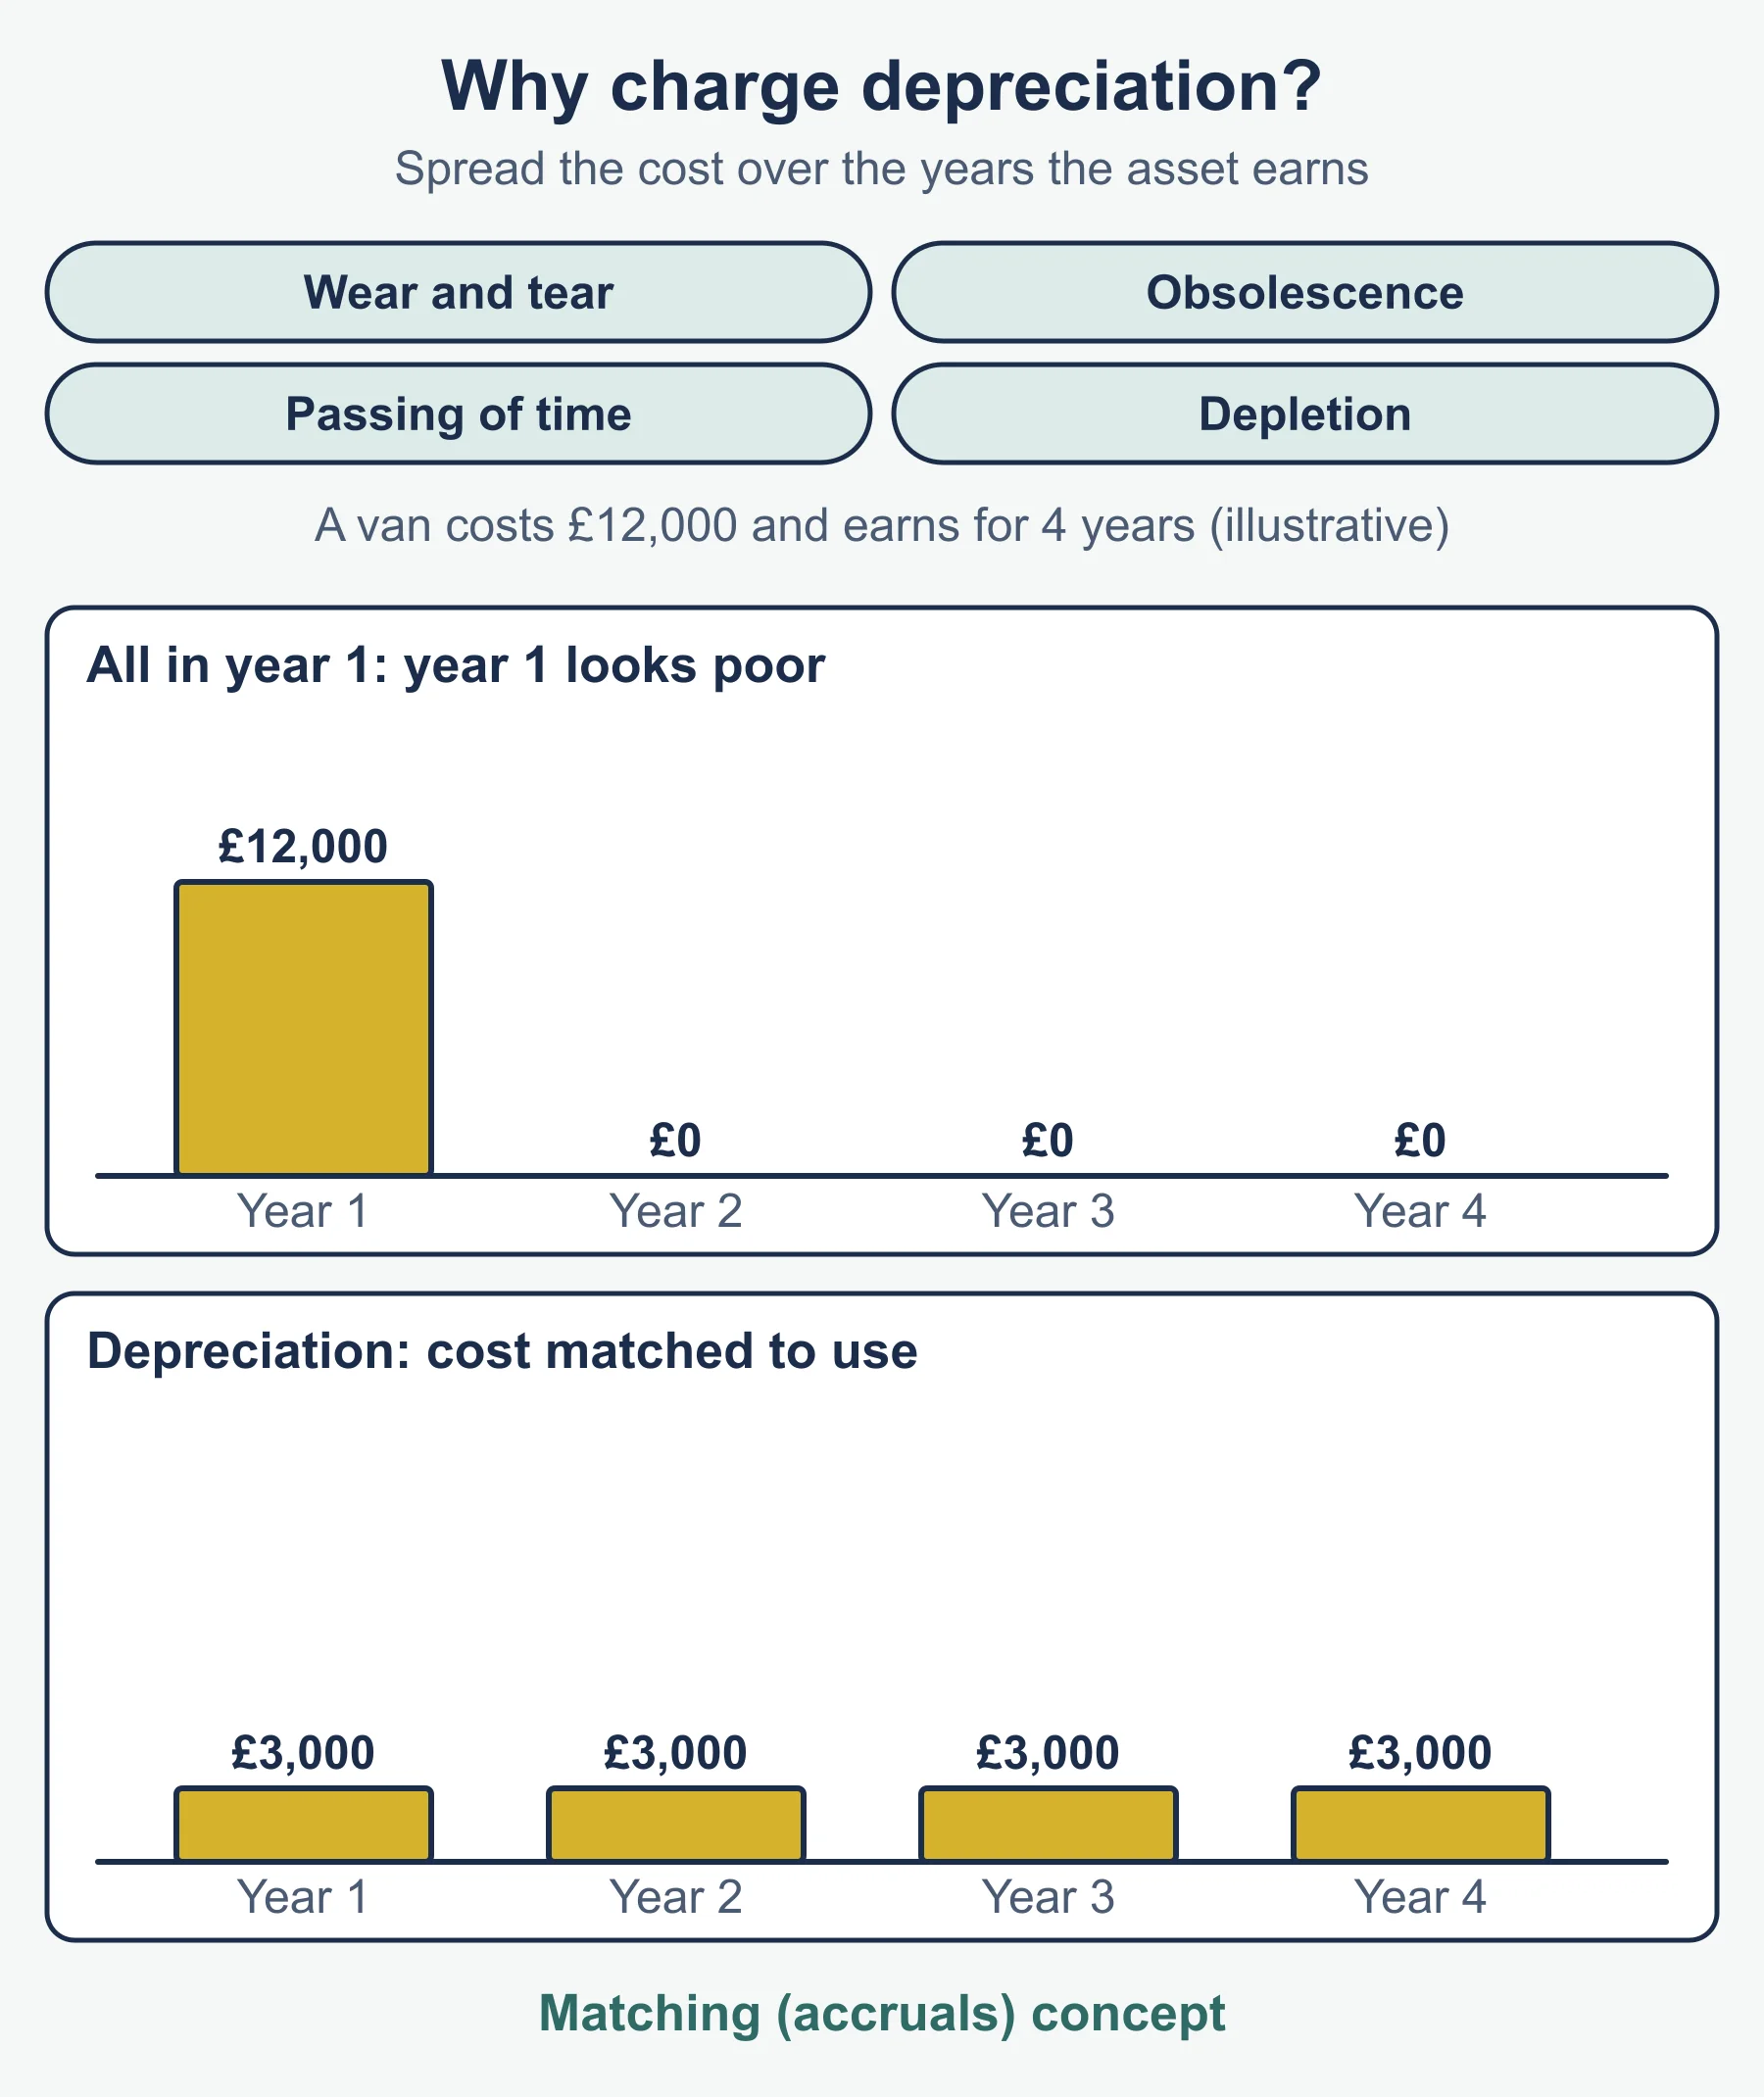
Depreciation is the share of a non-current asset’s cost consumed during an accounting period by wear and tear, the passage of time or obsolescence. No cash leaves the business when it is charged. It is not money set aside to replace the asset.
It must be accounted for because the asset helps earn revenue over several years, so its cost should be matched against those years, not charged all in the year of purchase. Without it, profit would be overstated and the statement of financial position would show assets at more than a realistic value.
Three methods
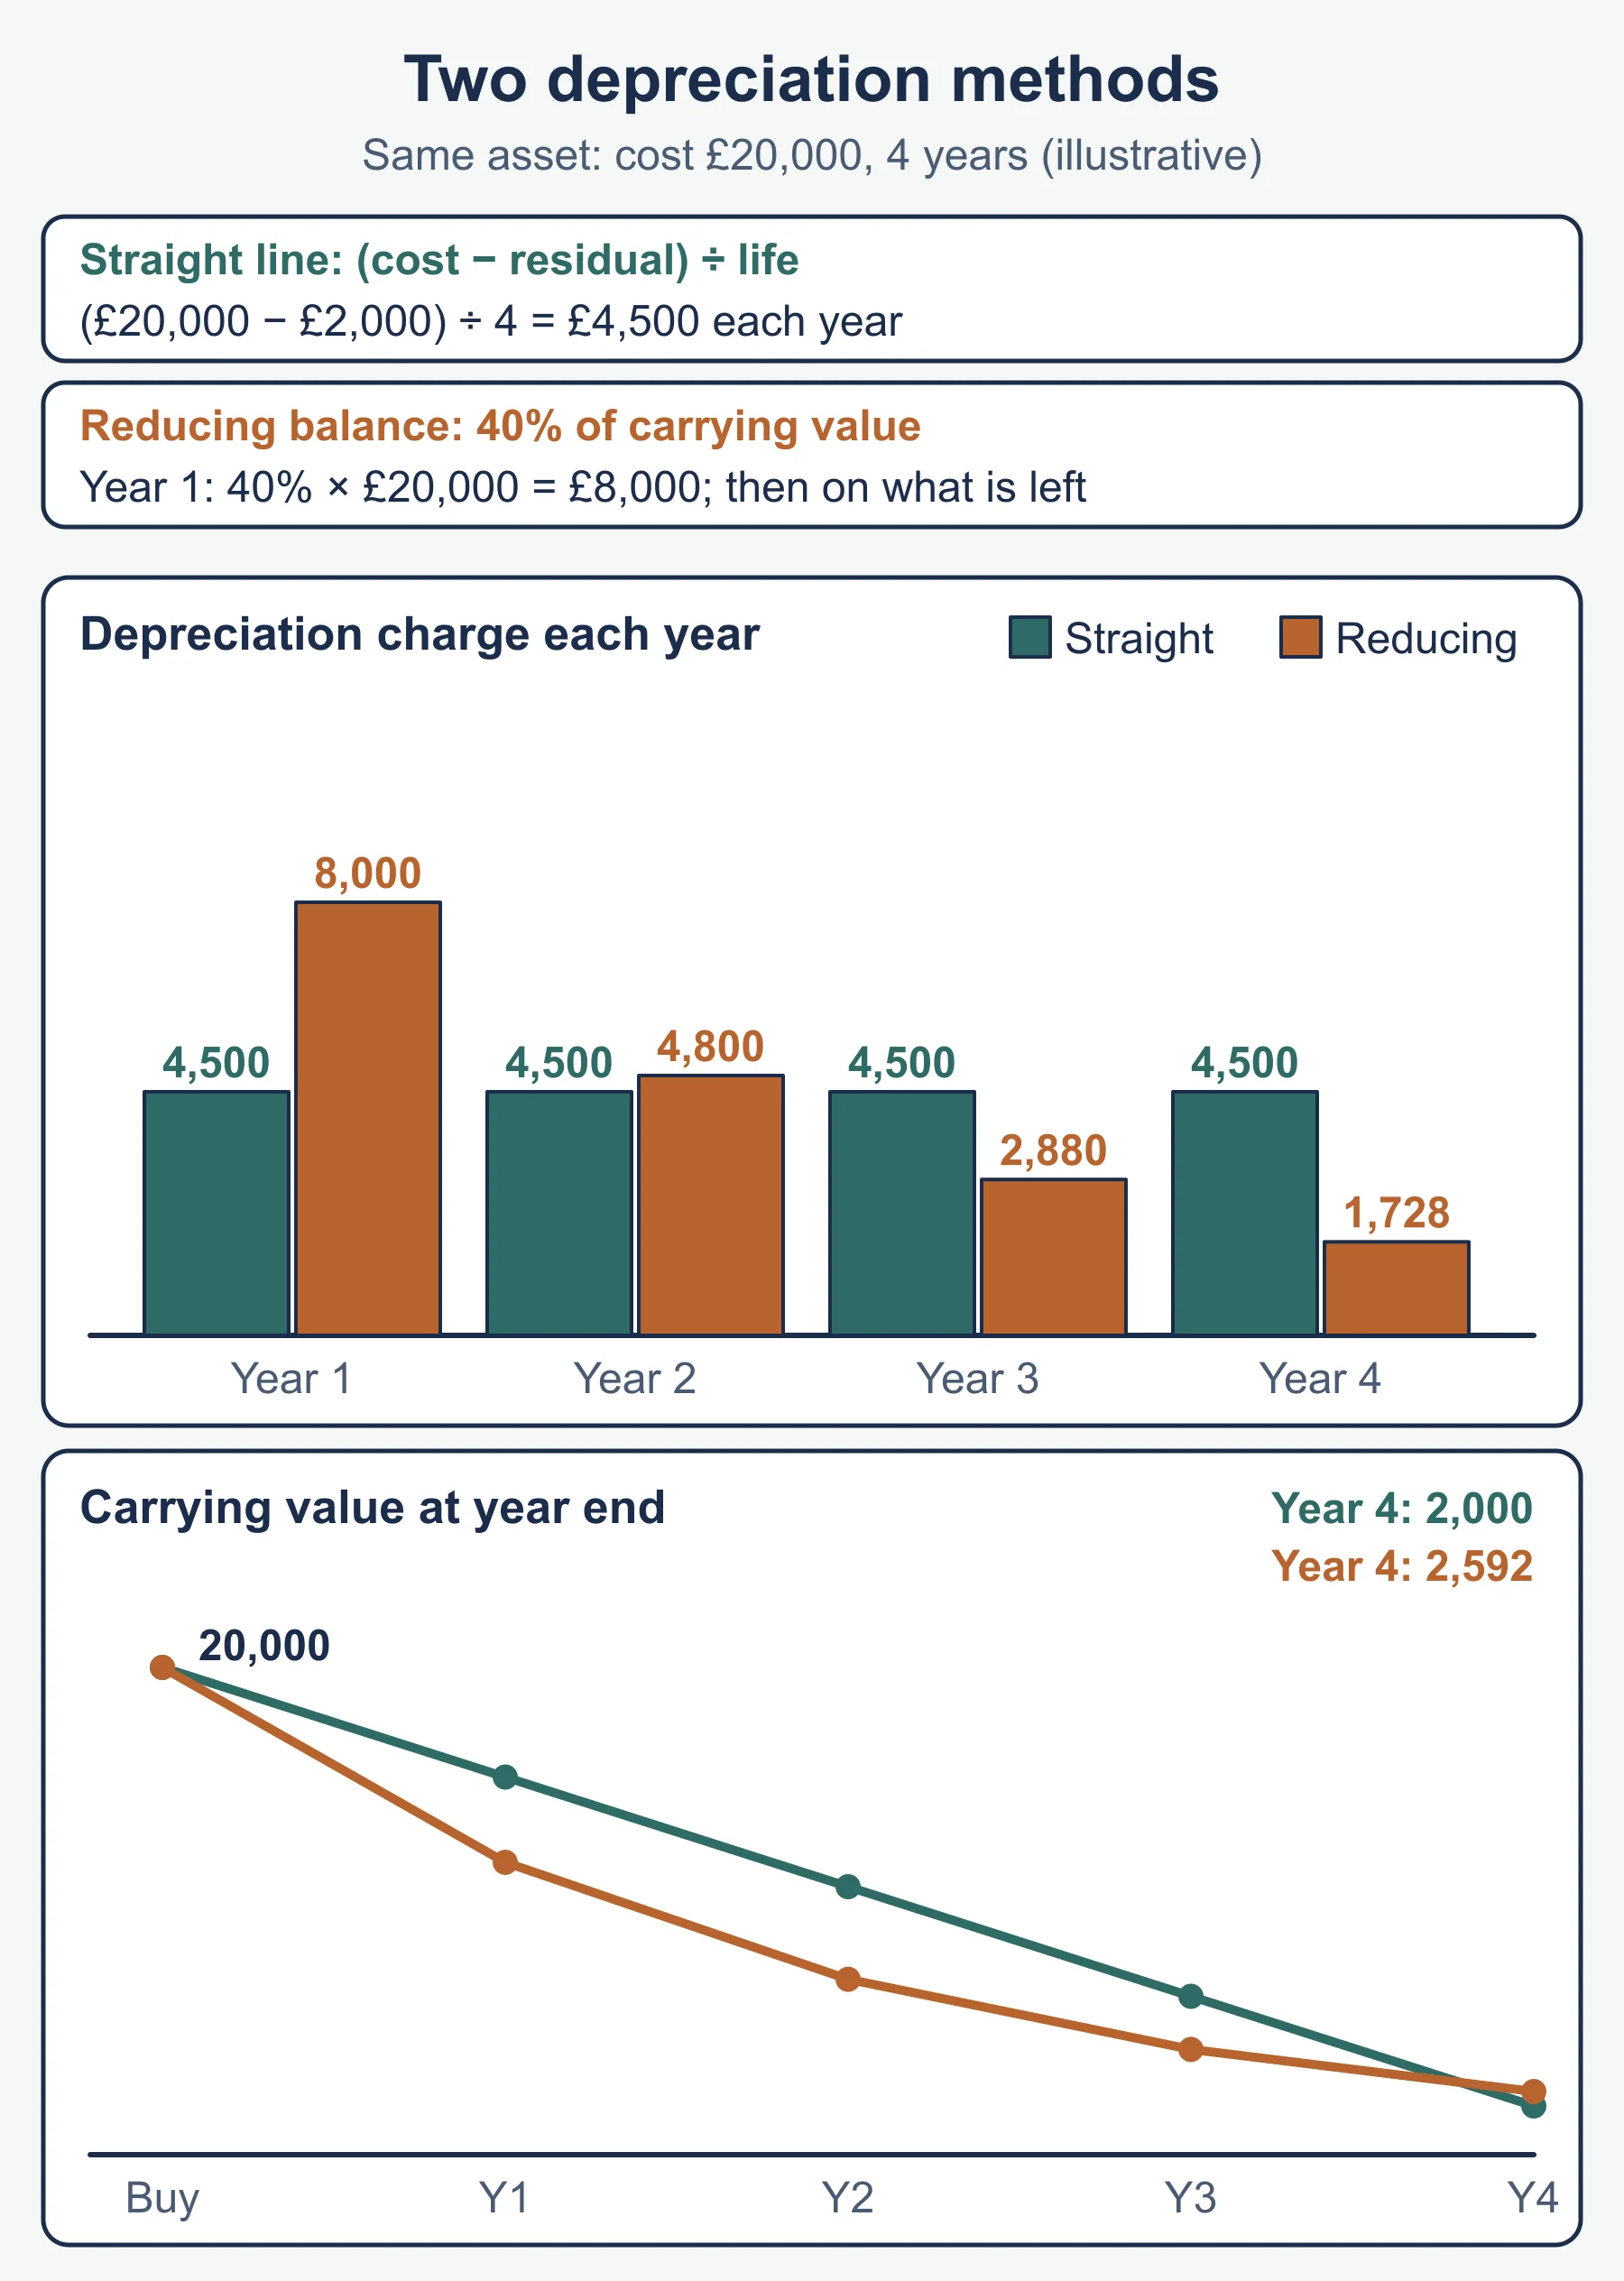
Straight-line gives the same charge every year. A printing press costs 48,000, is expected to last seven years and to be worth 6,000 at the end: (48,000 − 6,000) ÷ 7 = 6,000 a year.
Reducing balance charges a fixed percentage of net book value, so the charge falls each year. A computer network costs 15,000 and is depreciated at 40%.
Year   Net book value at start   Depreciation   Net book value at end
1               15,000              6,000              9,000
2                9,000              3,600              5,400
3                5,400              2,160              3,240
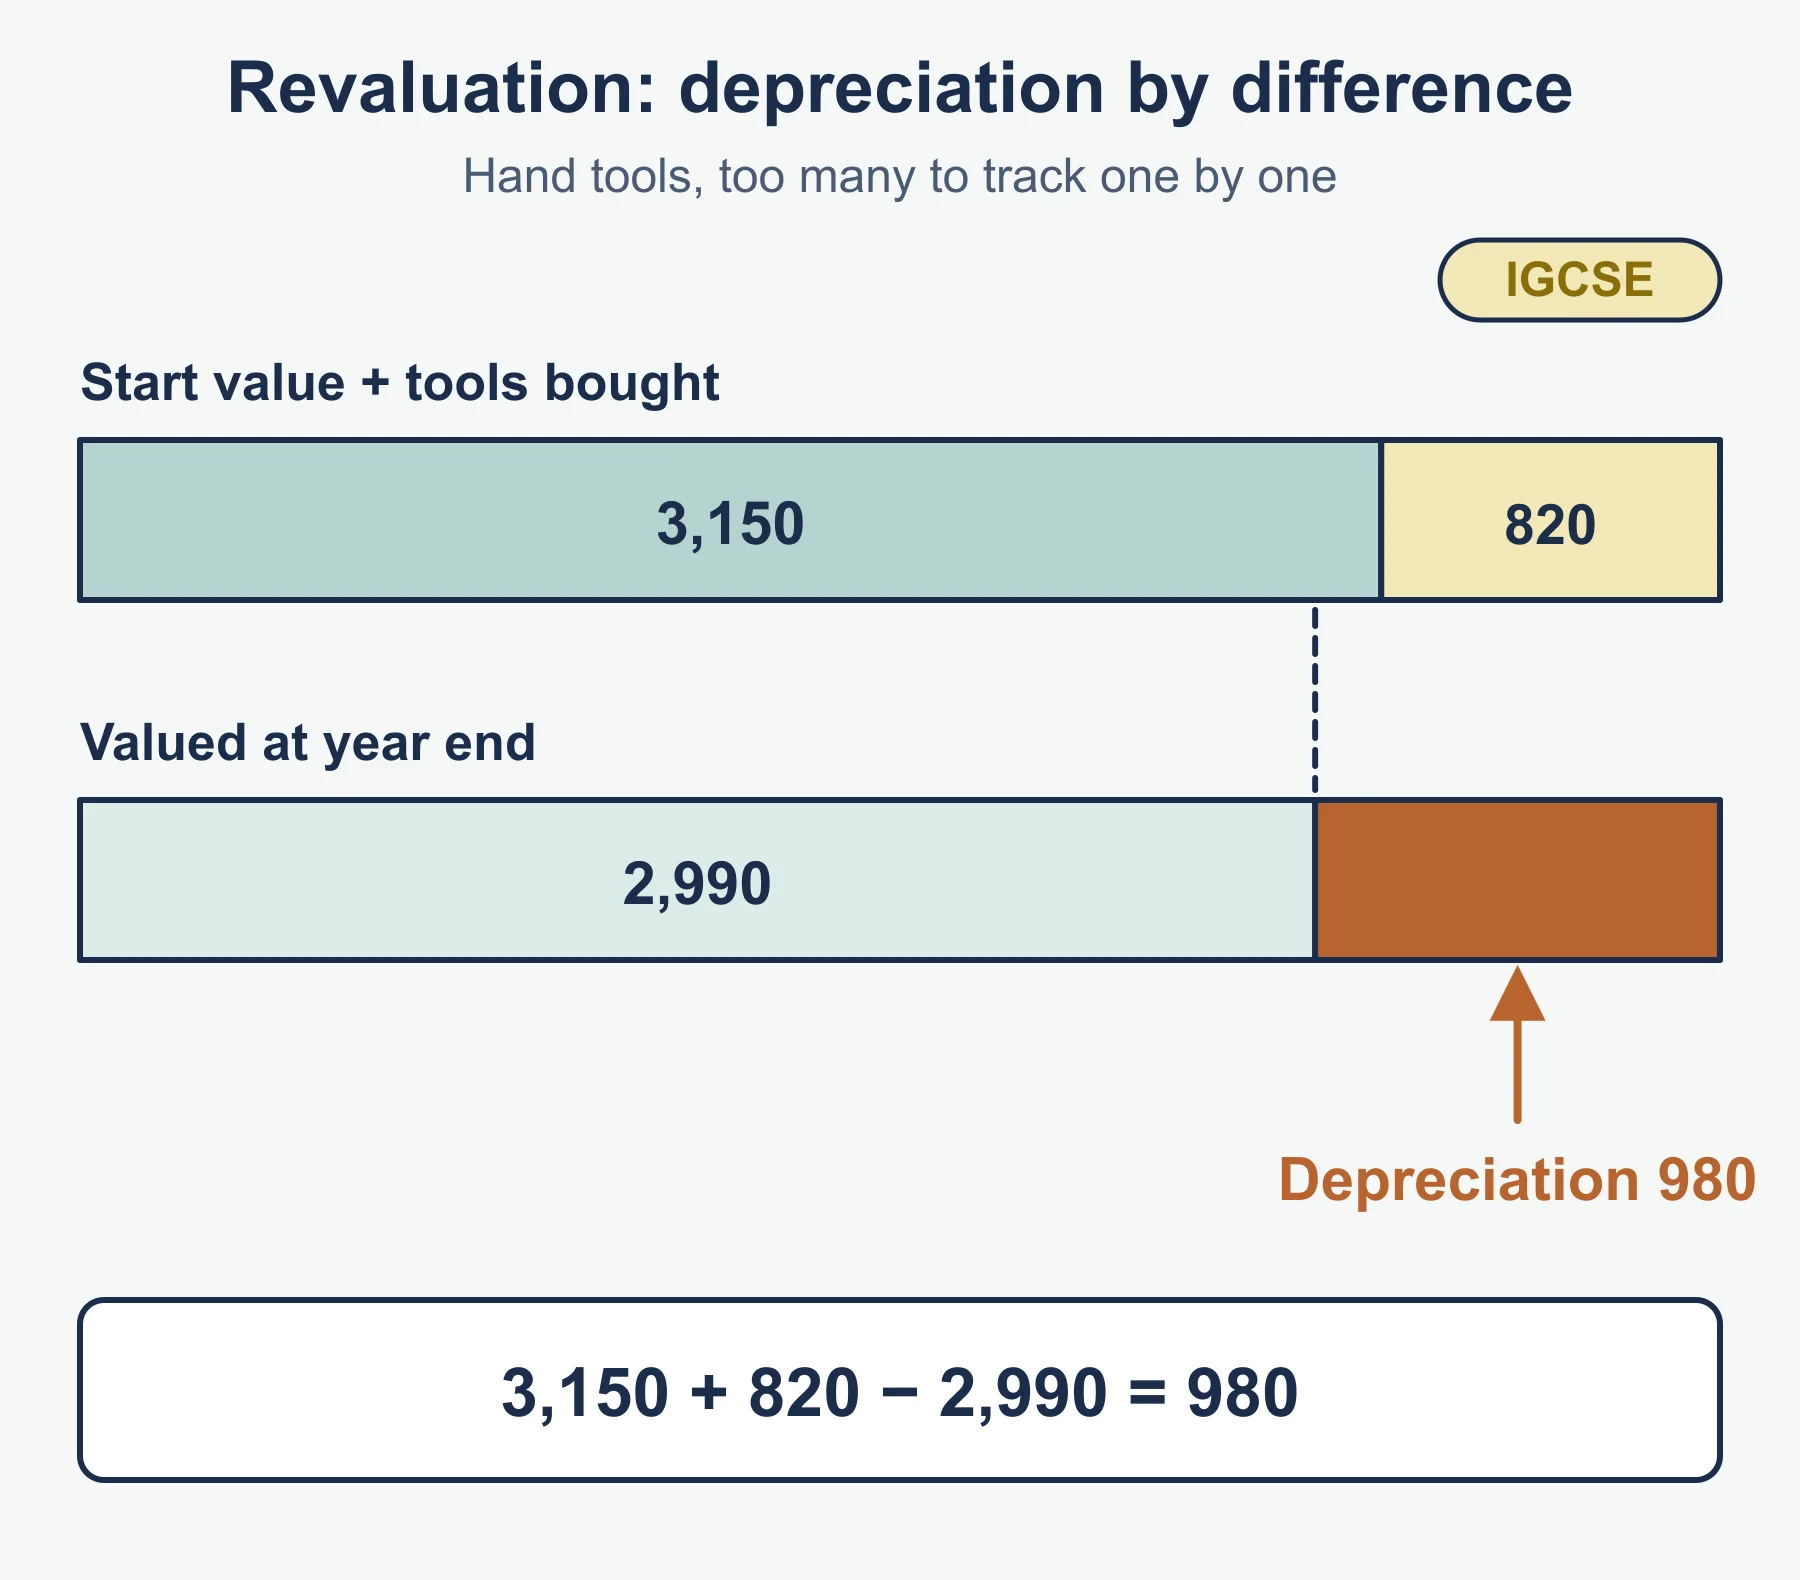
Revaluation suits collections of small items. Hand tools are valued at 3,150 at the start of the year, 820 of tools are bought, and they are valued at 2,990 at the end. Depreciation = 3,150 + 820 − 2,990 = 980.
Choosing a method
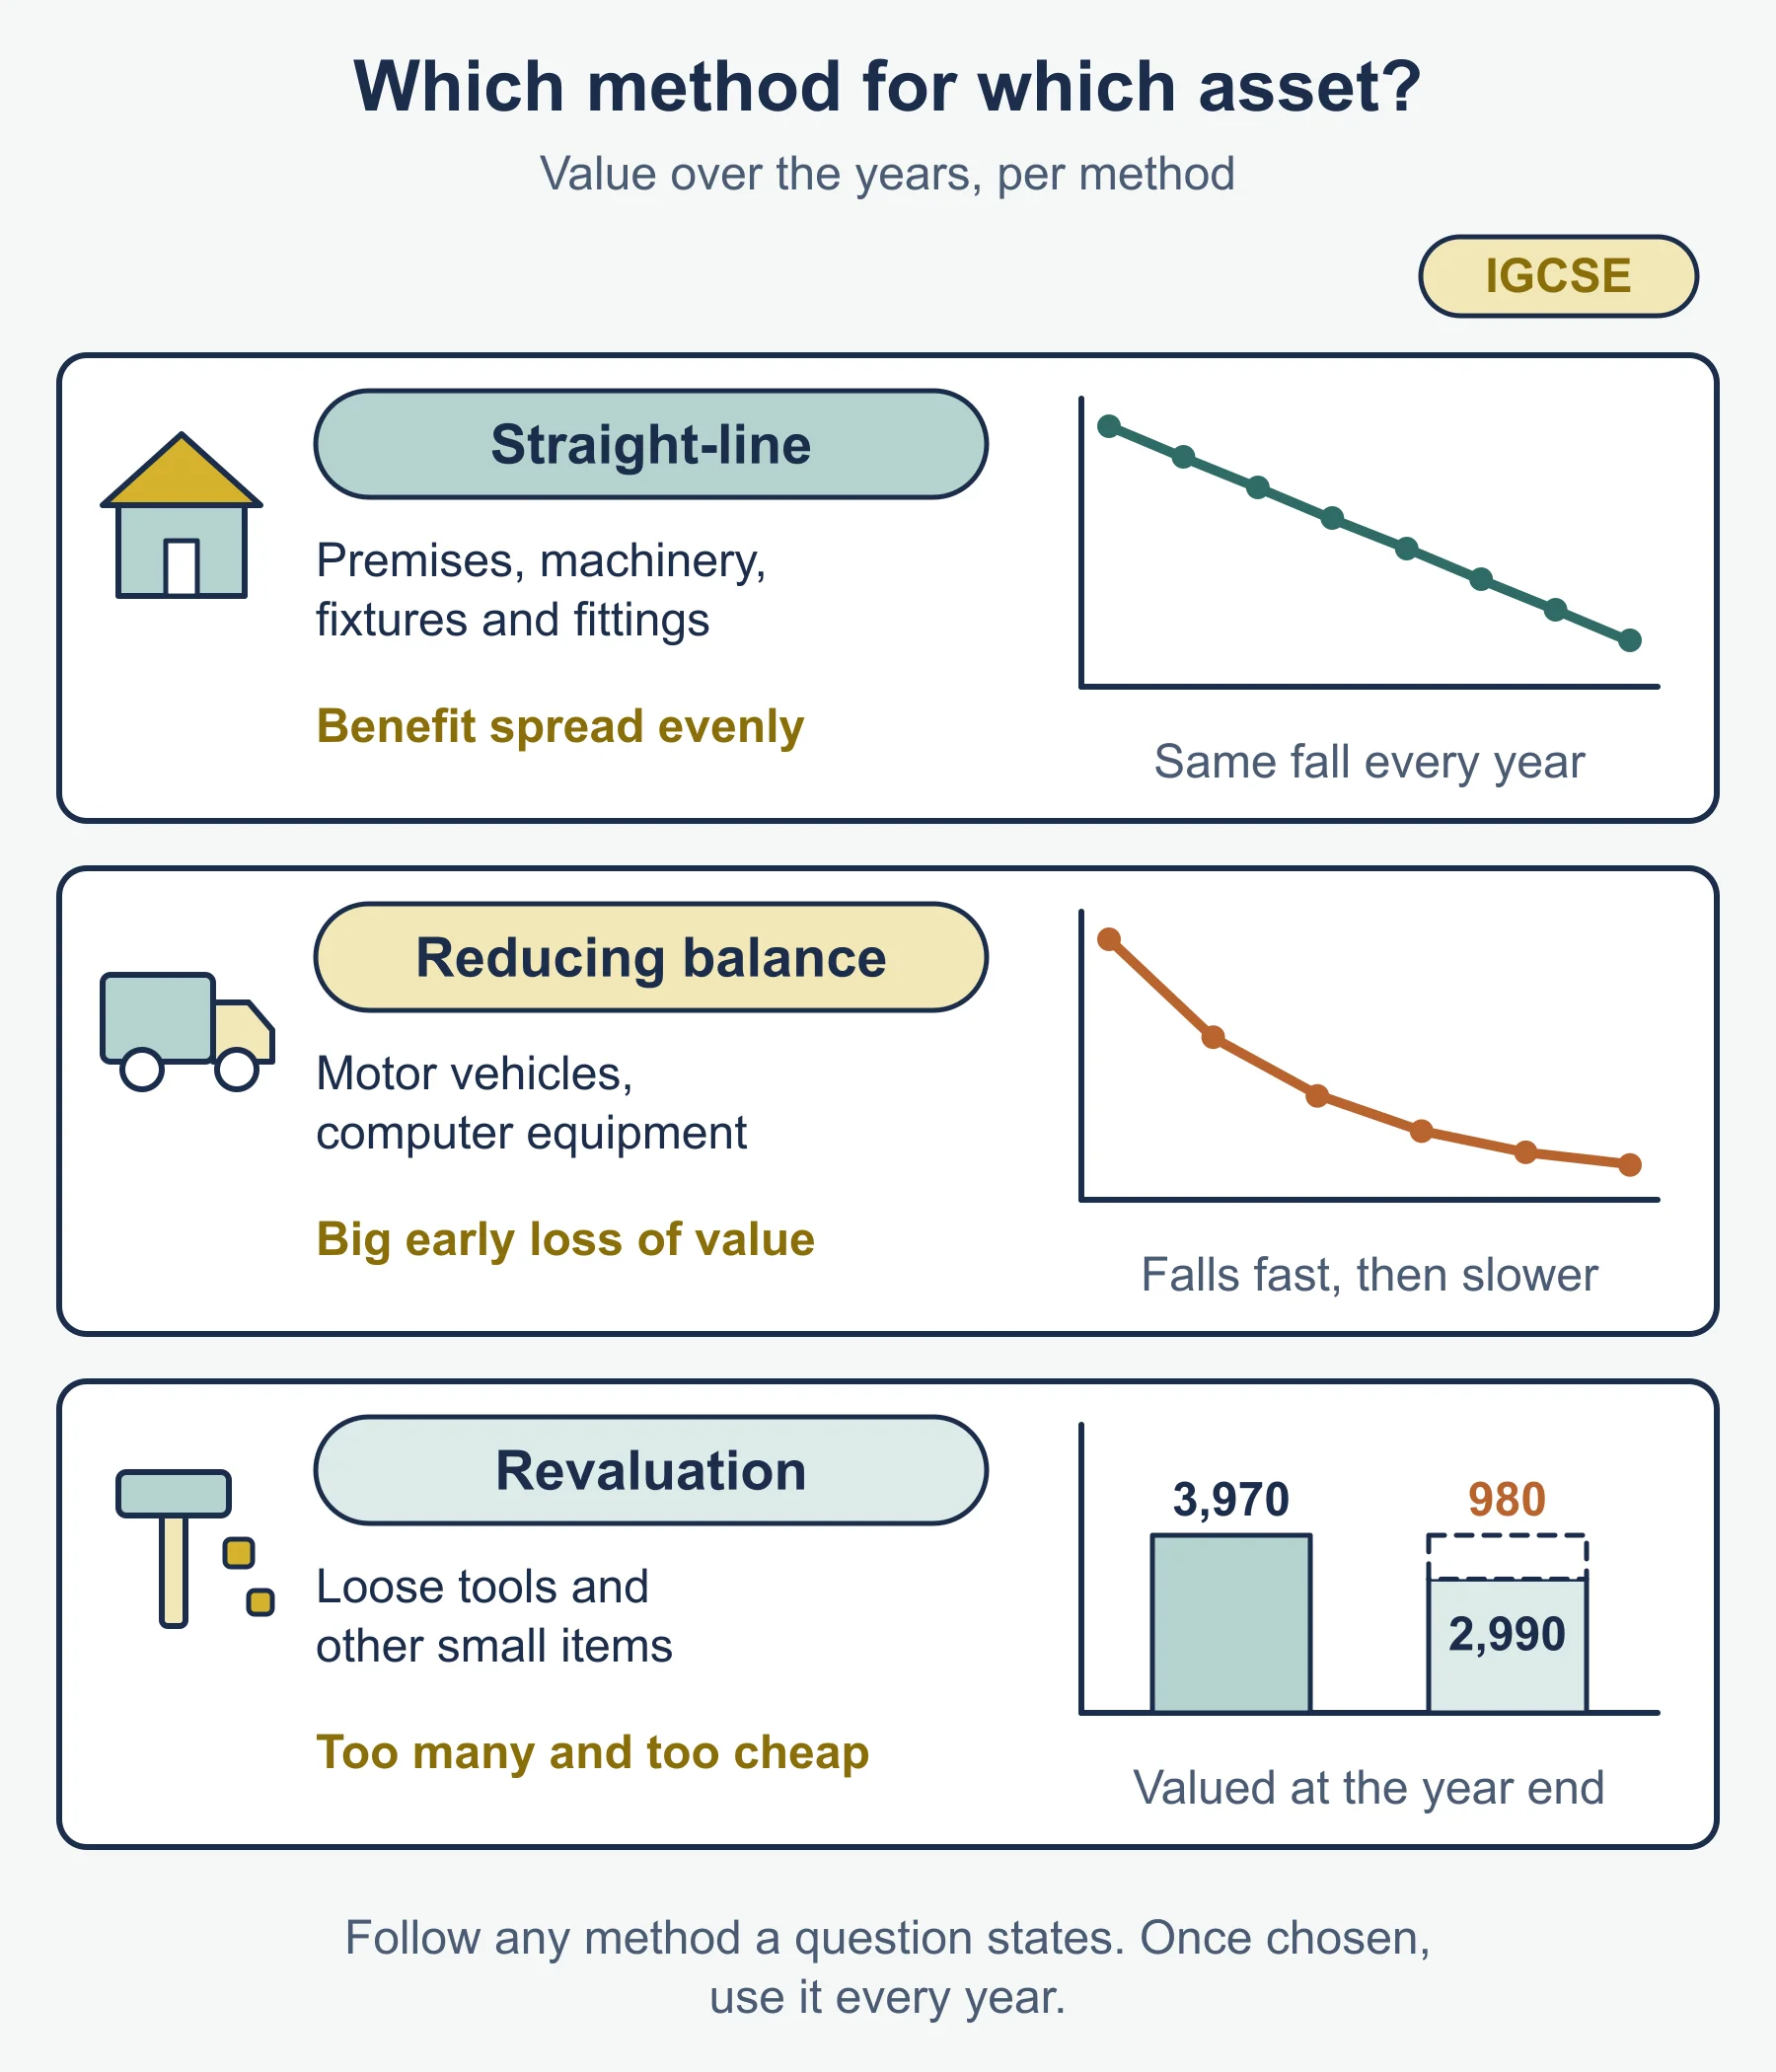
| Asset | Suitable method | Reason |
|---|---|---|
| Premises, machinery, fixtures and fittings | Straight-line | Benefit is spread fairly evenly |
| Motor vehicles, computer equipment | Reducing balance | Heavier loss of value and out-of-date risk early on |
| Loose tools and similar small items | Revaluation | Items are too many and too cheap to track one by one |
Follow any method, rate or policy a question states. Once chosen, a method is applied consistently each year.
Recording depreciation, purchase and sale
Depreciation: debit statement of profit or loss, credit provision for depreciation. The asset account stays at cost, so net book value is cost less the provision. Under revaluation the tools account is usually credited until it equals the closing valuation; follow the layout the question gives.
Purchase: debit the non-current asset account, credit bank, or the supplier if bought on credit.
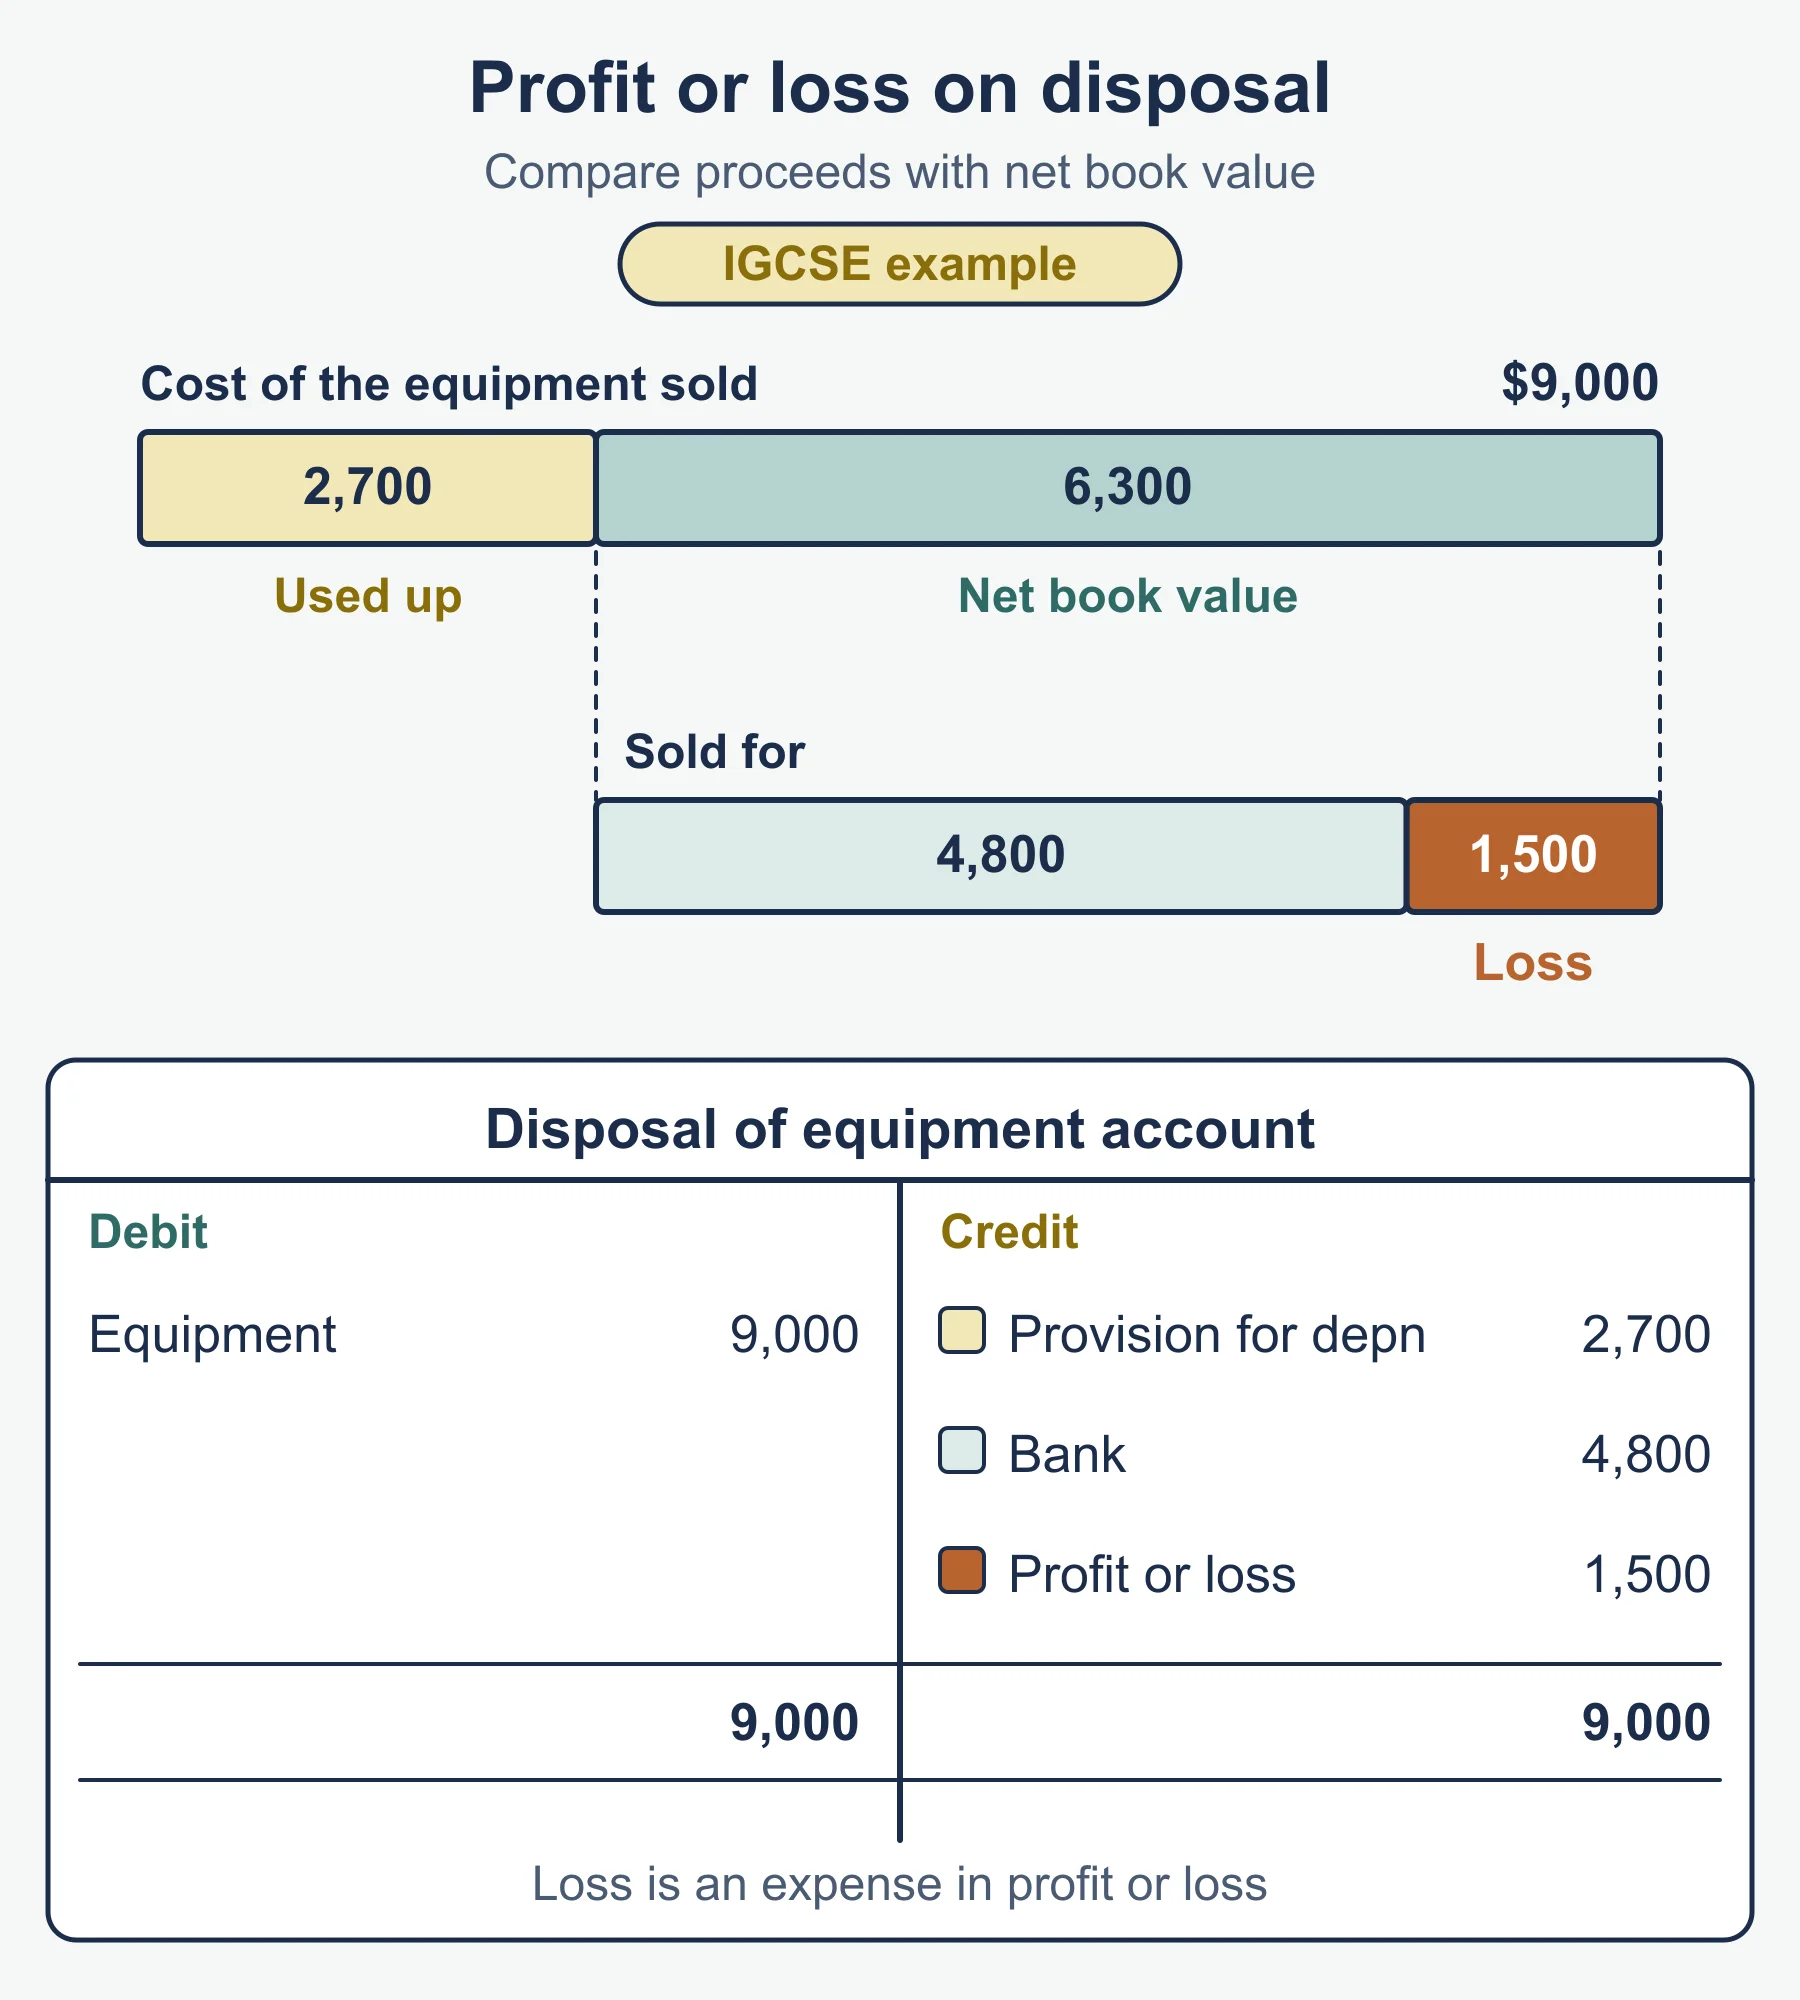
Sale: use the disposal account. Debit it with the asset’s cost and credit it with the asset’s accumulated depreciation and the proceeds; whatever is needed to balance it is the profit or loss. Profit on disposal equals proceeds minus net book value.
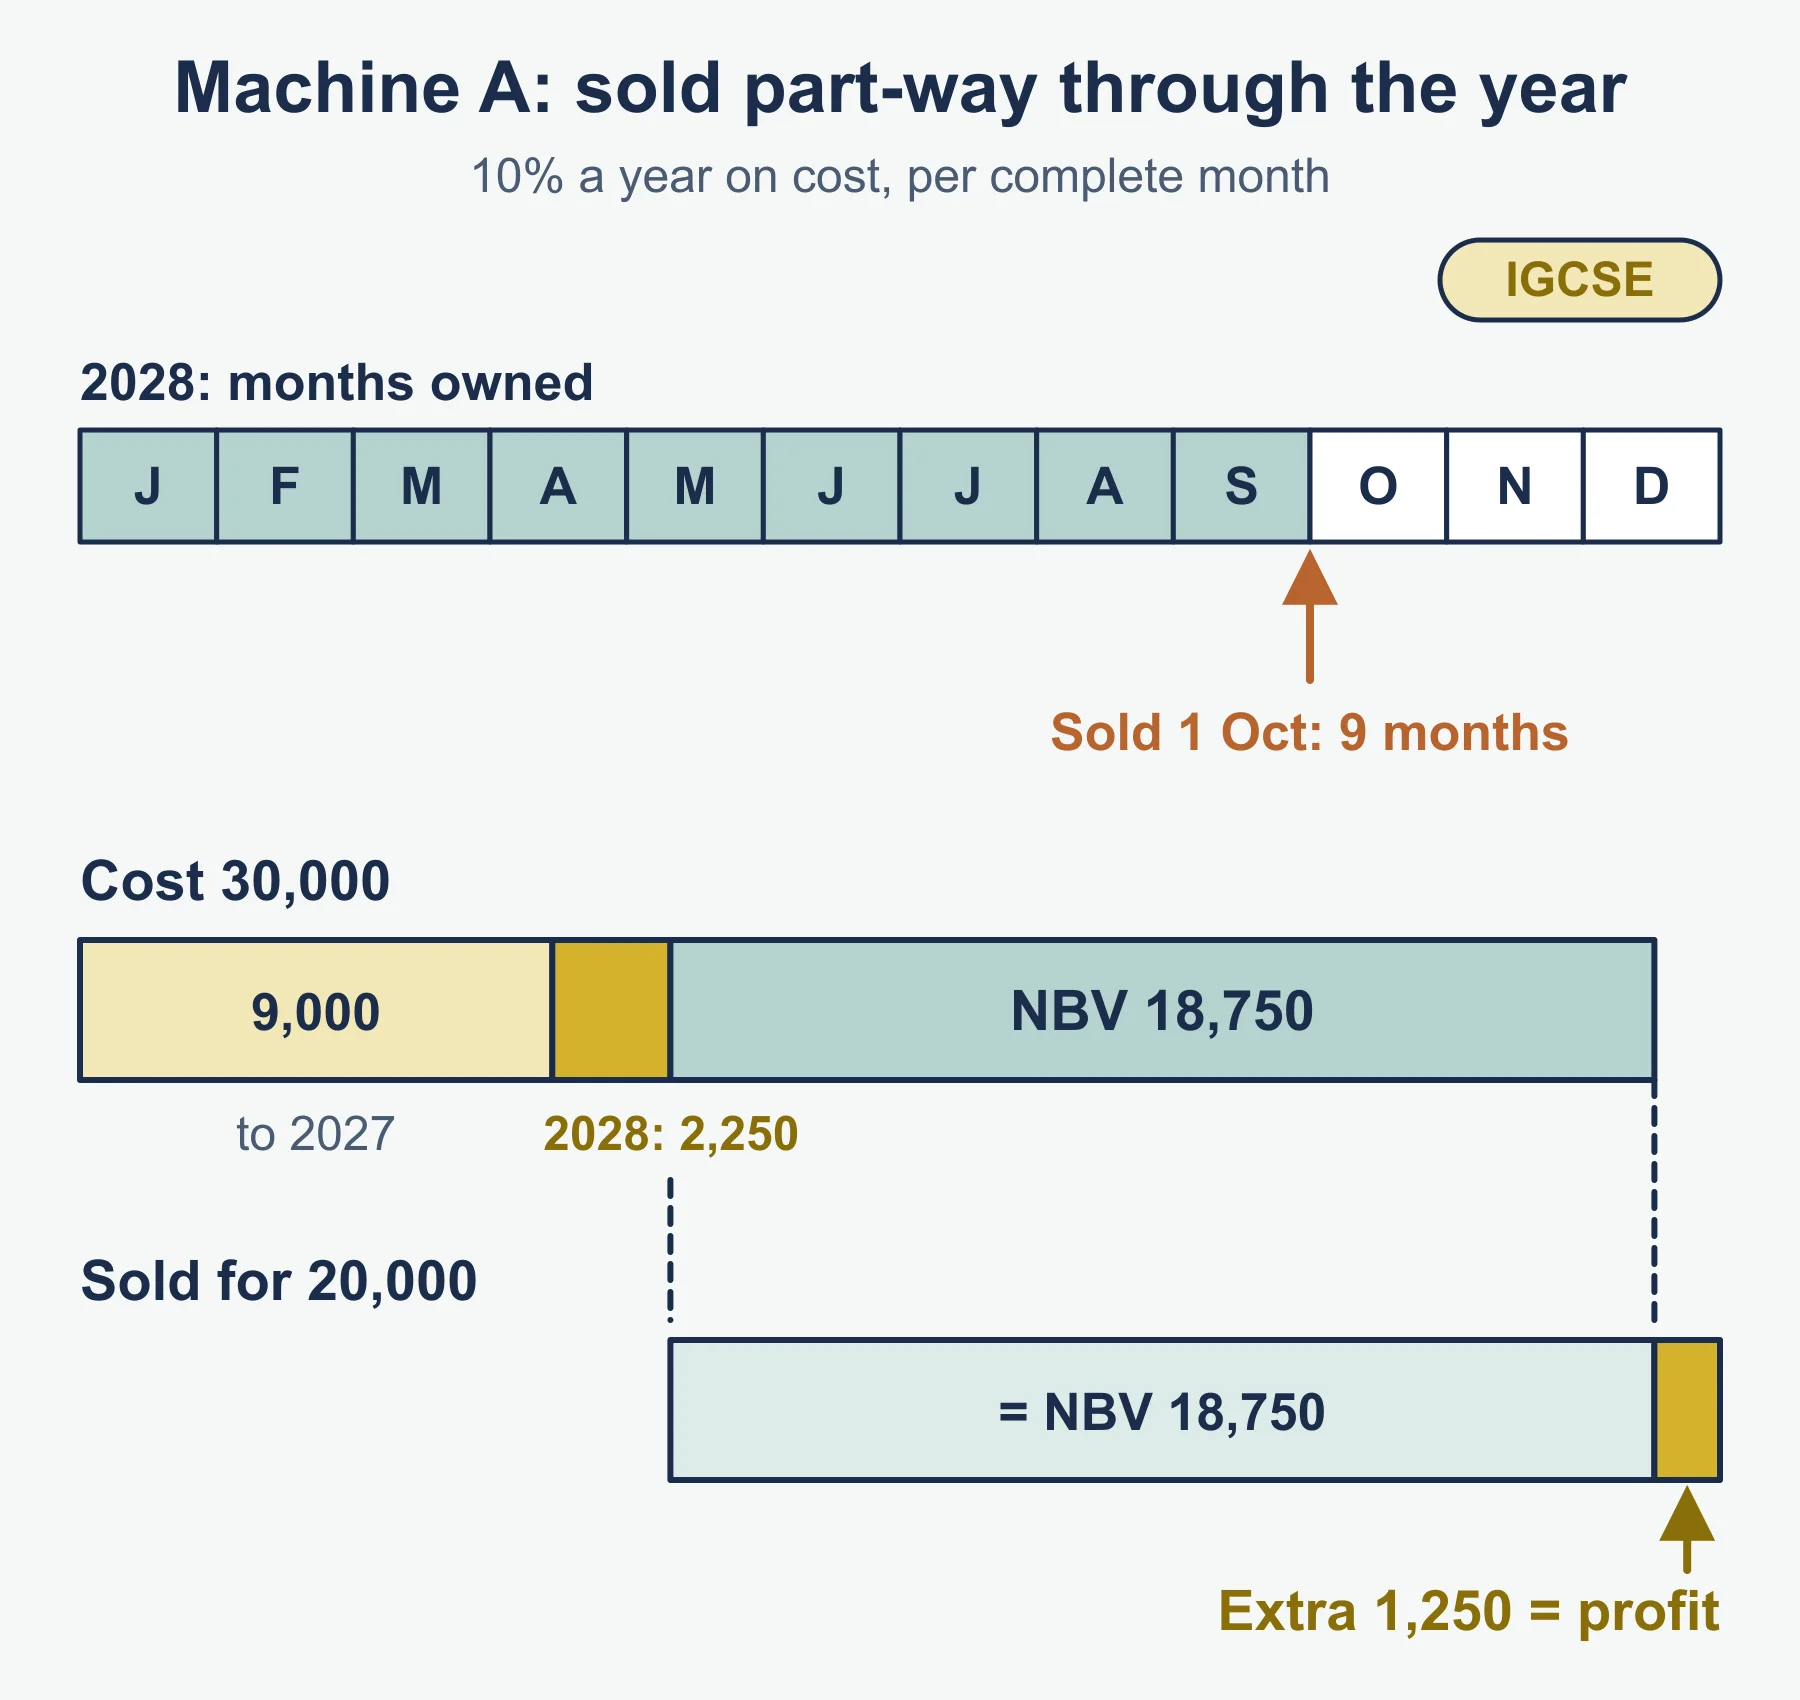
Wexford Print Works has a year end of 31 December 2028. It depreciates machinery at 10% a year on cost, straight-line, for each complete month owned. At 1 January 2028 the machinery account held three machines: A, bought 1 January 2025 for 30,000; B, bought 1 July 2026 for 24,000; and C, bought 1 January 2027 for 18,000. The provision for depreciation was 14,400 (A 9,000, B 3,600, C 1,800).
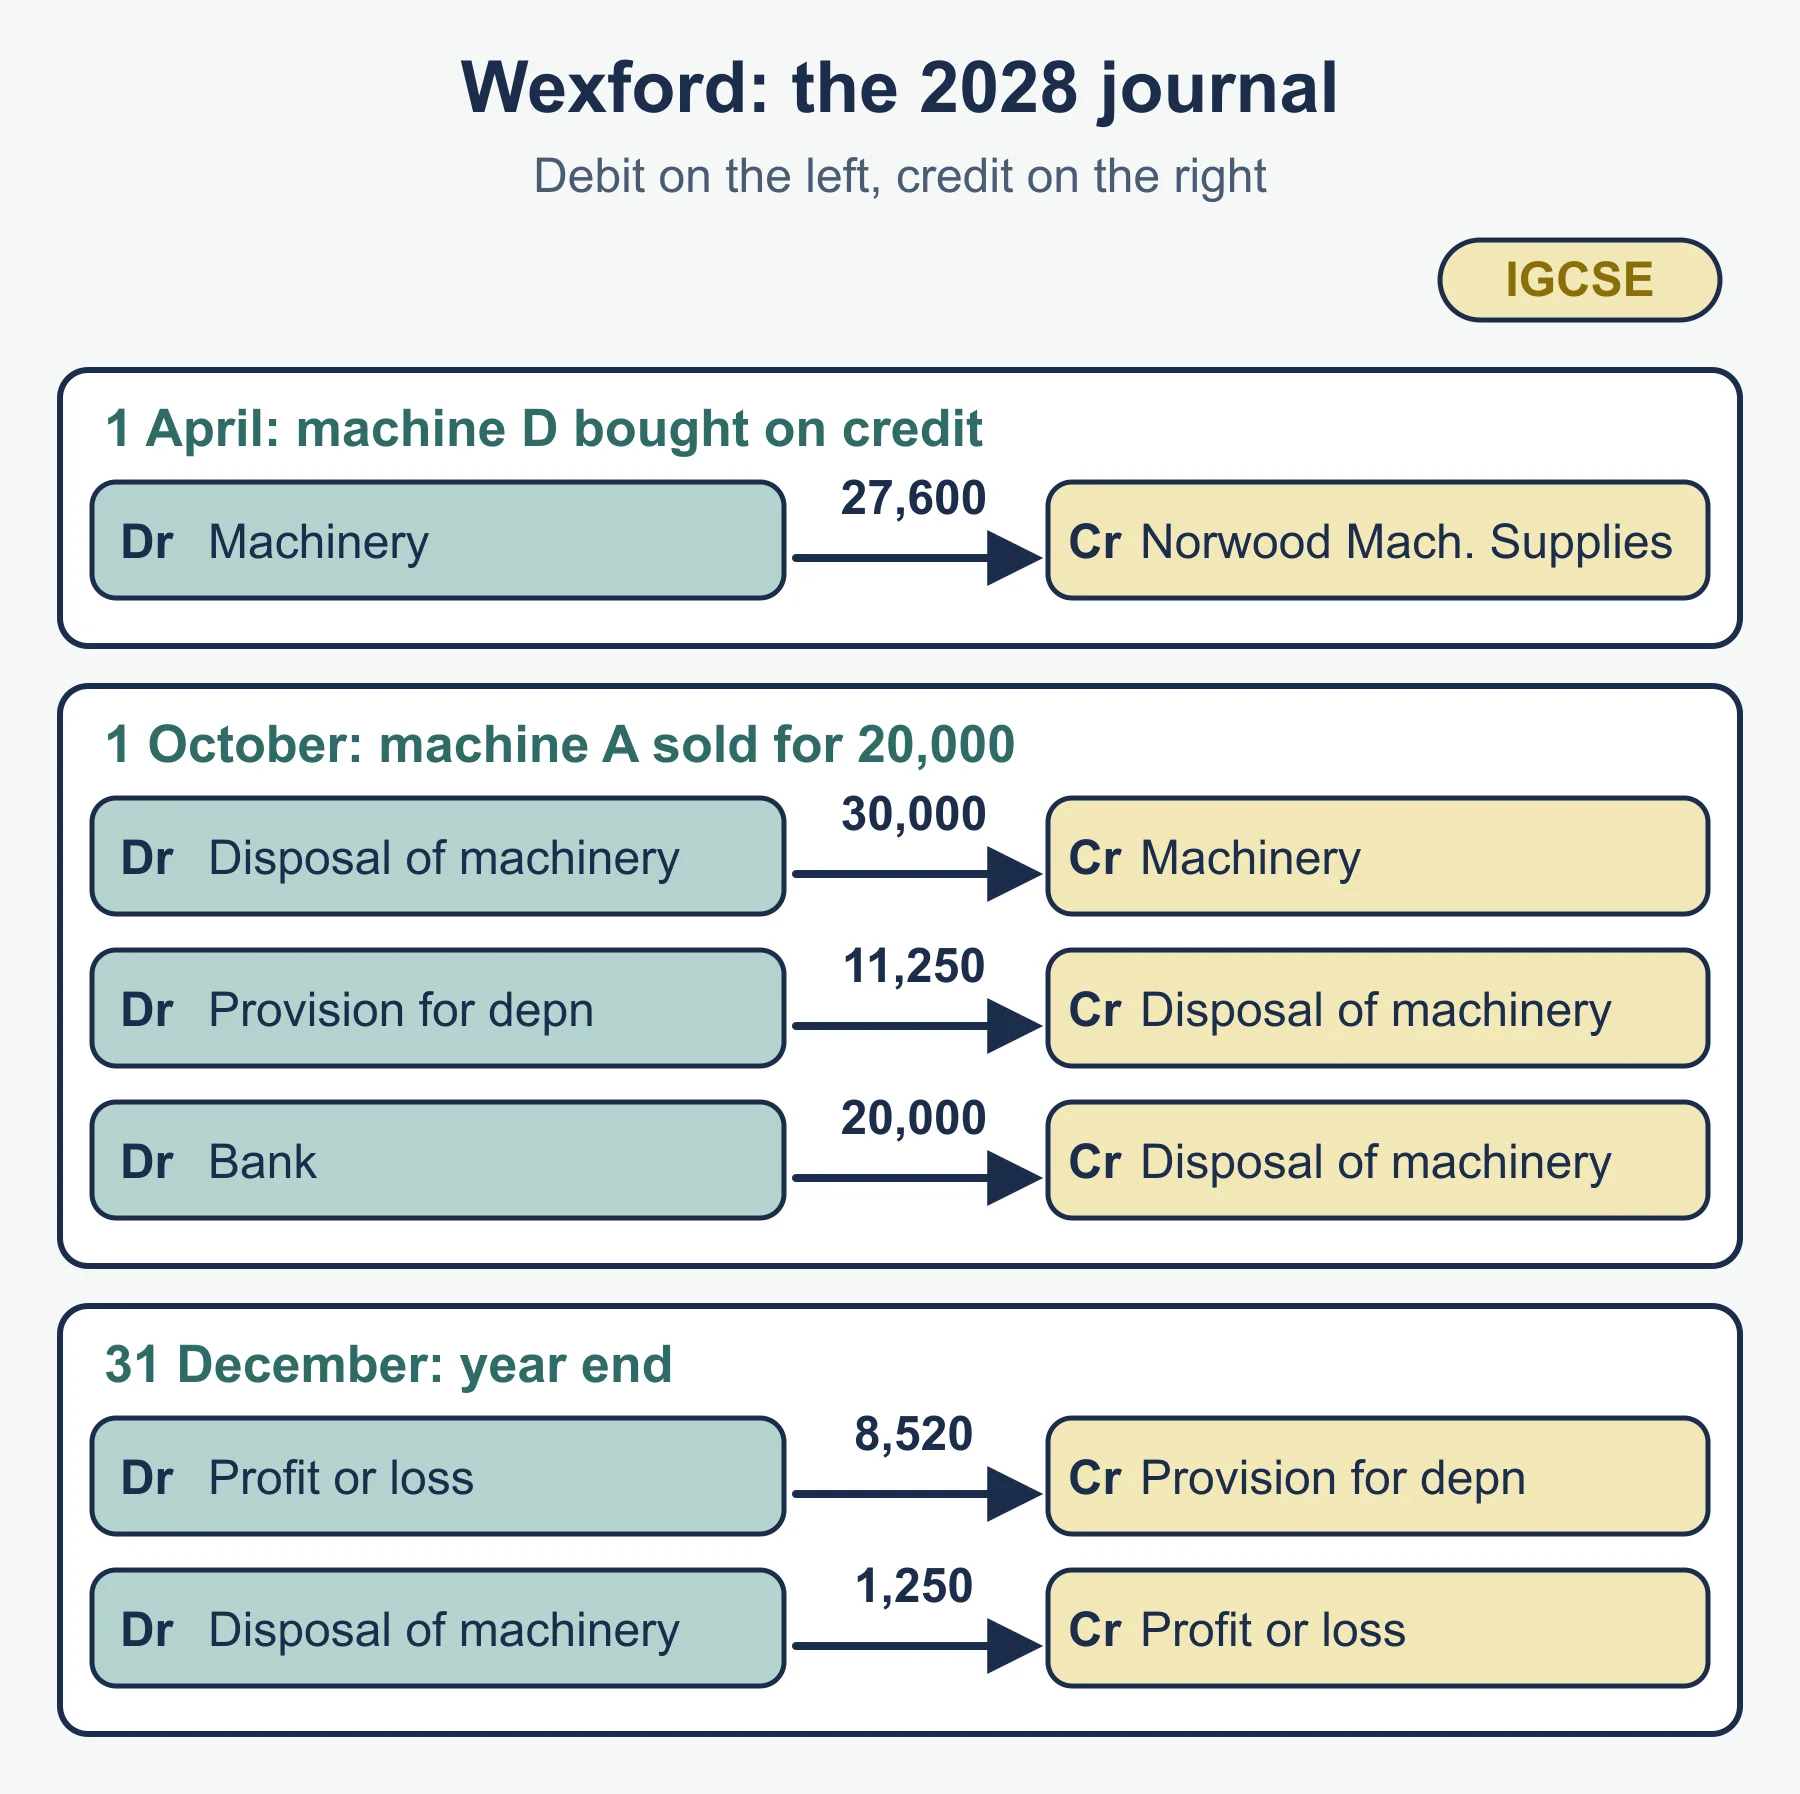
- 1 April: machine D bought on credit from Norwood Machinery Supplies for 27,600.
- 1 October: machine A sold for 20,000 by bank transfer.
Machine A was owned for nine months of 2028, so its 2028 charge is 30,000 × 10% × 9/12 = 2,250, and its accumulated depreciation is 9,000 + 2,250 = 11,250. Net book value is 30,000 − 11,250 = 18,750, so profit on disposal is 20,000 − 18,750 = 1,250. The year’s charge is A 2,250 + B 2,400 + C 1,800 + D 2,070 (27,600 × 10% × 9/12) = 8,520.
| Date | Account | Debit | Credit |
|---|---|---|---|
| 1 Apr | Machinery | 27,600 | |
| Norwood Machinery Supplies | 27,600 | ||
| 1 Oct | Disposal of machinery | 30,000 | |
| Machinery | 30,000 | ||
| 1 Oct | Provision for depreciation of machinery | 11,250 | |
| Disposal of machinery | 11,250 | ||
| 1 Oct | Bank | 20,000 | |
| Disposal of machinery | 20,000 | ||
| 31 Dec | Statement of profit or loss | 8,520 | |
| Provision for depreciation of machinery | 8,520 | ||
| 31 Dec | Disposal of machinery | 1,250 | |
| Statement of profit or loss (profit on disposal) | 1,250 |
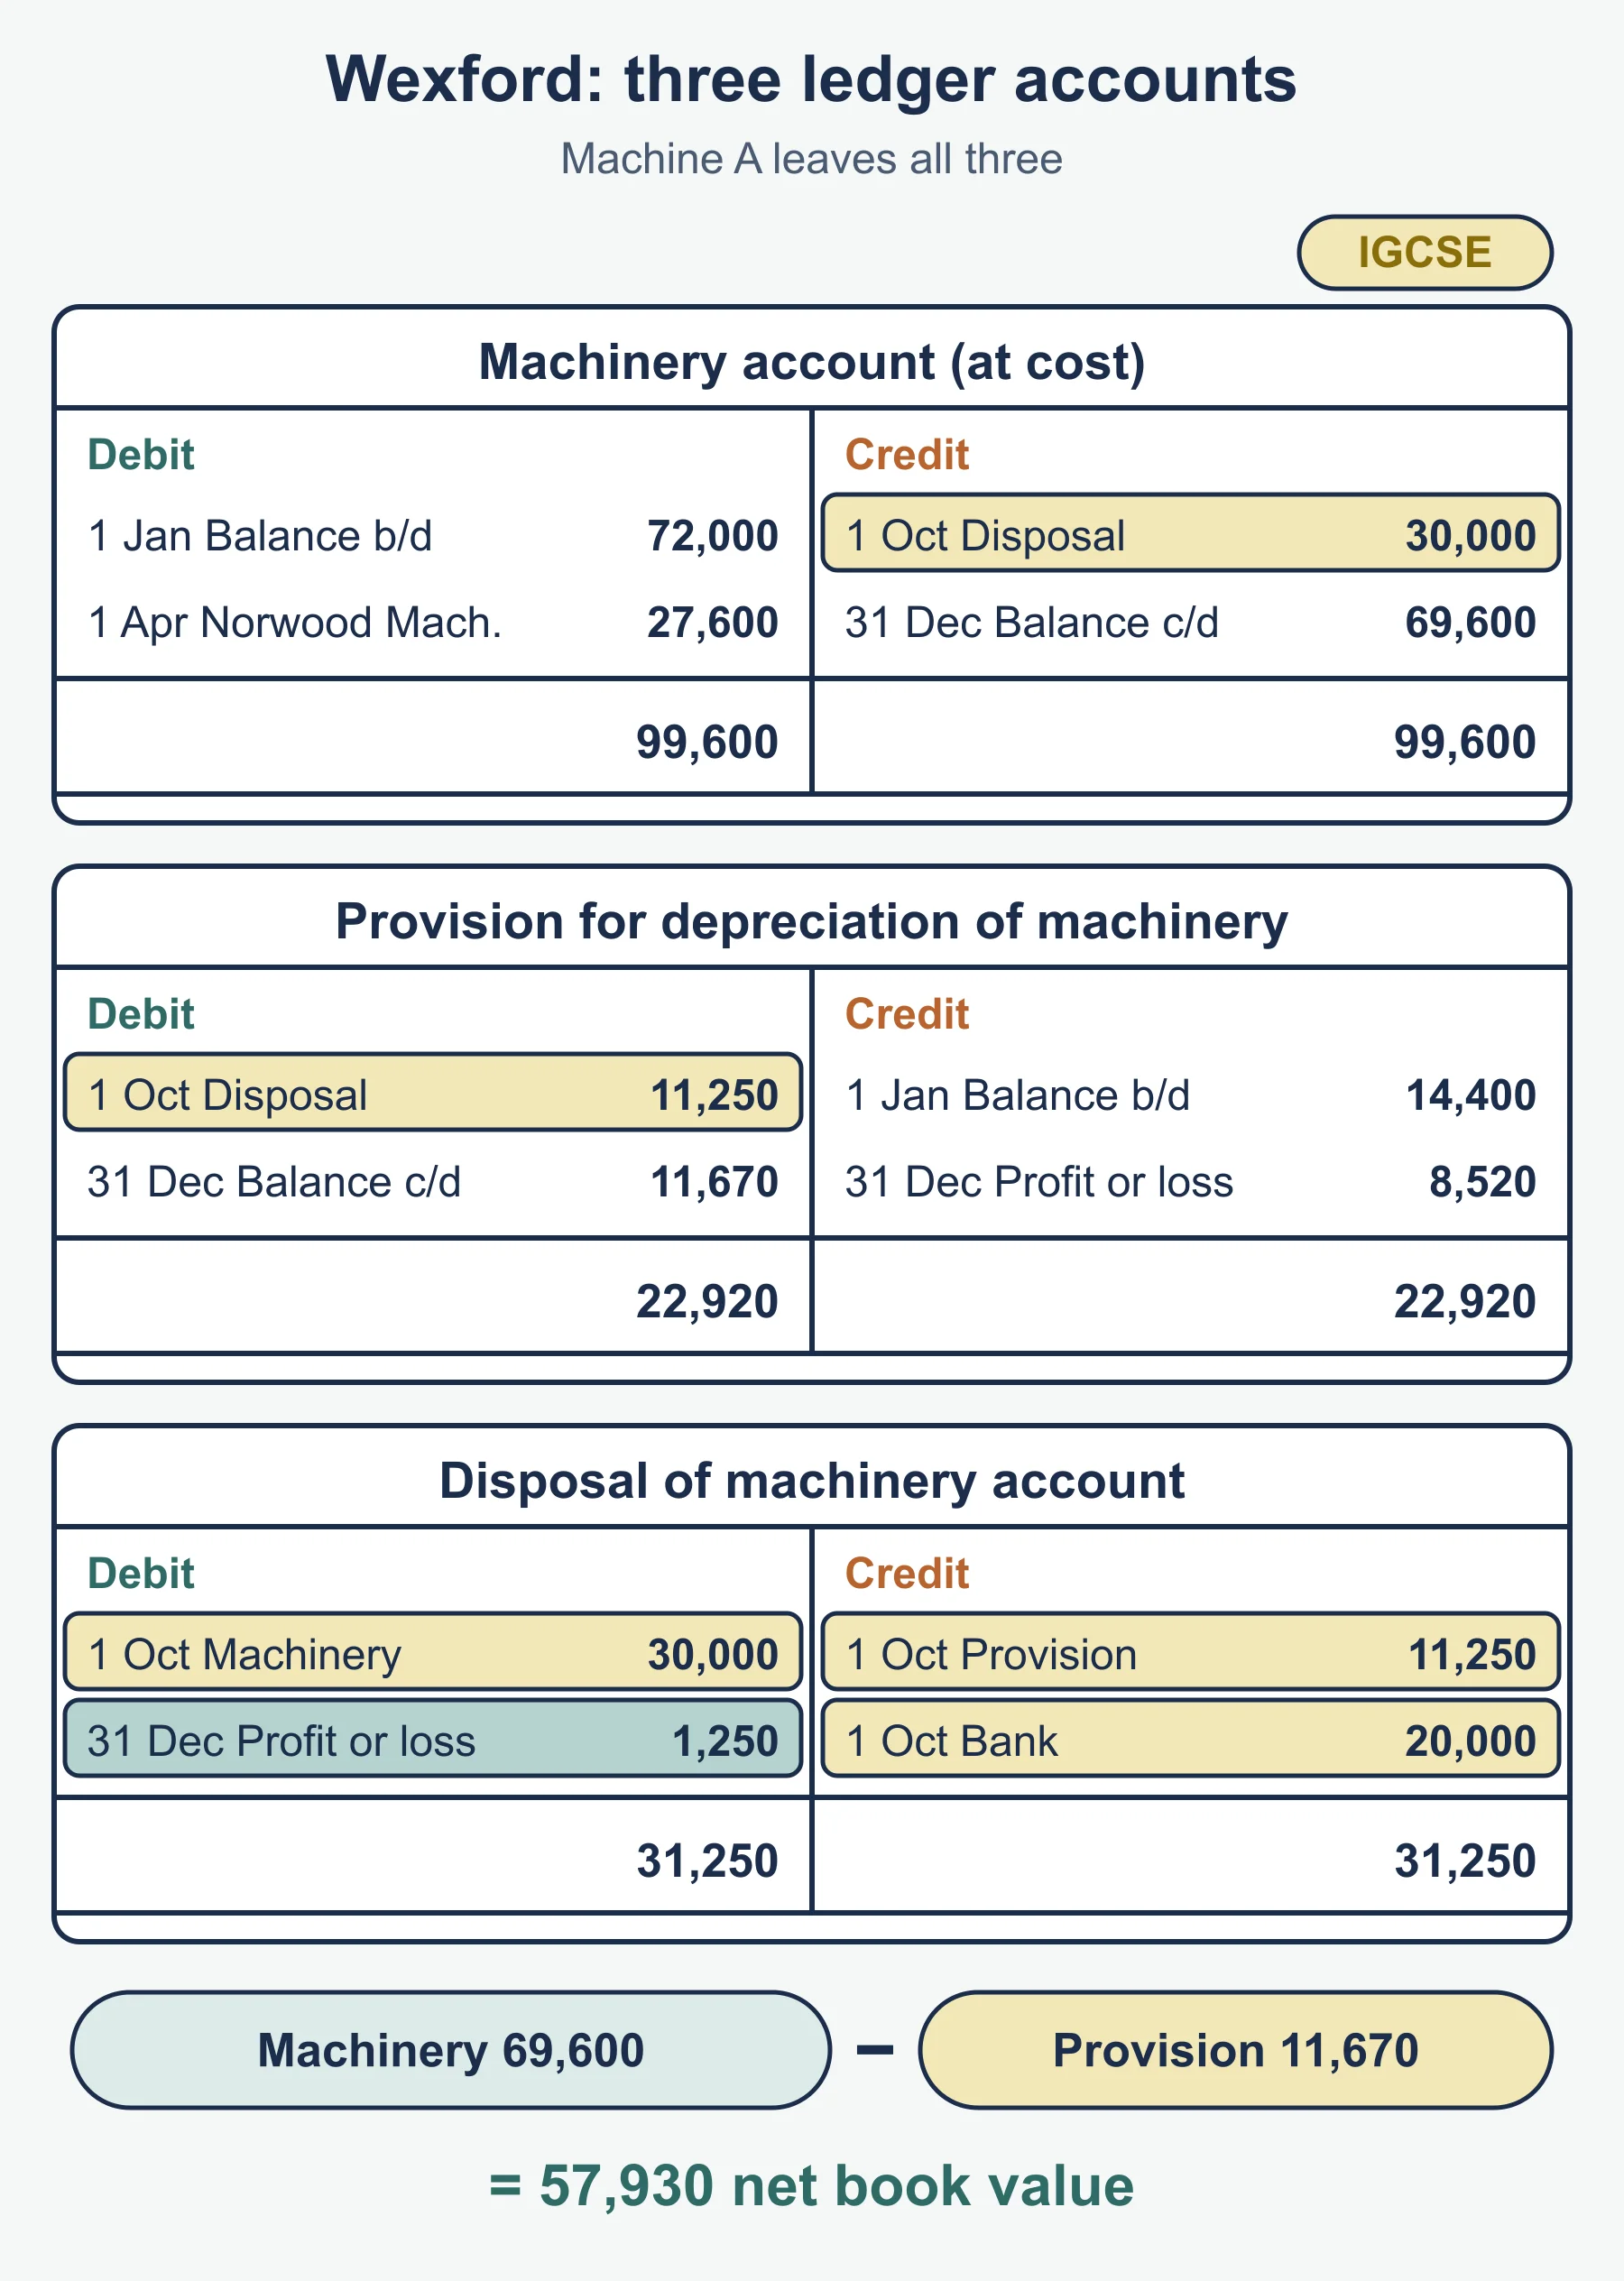
Machinery account
2028                                      2028
1 Jan  Balance b/d              72,000    1 Oct  Disposal              30,000
1 Apr  Norwood Mach. Supplies   27,600    31 Dec Balance c/d           69,600
                                99,600                                 99,600

Provision for depreciation of machinery account
2028                                      2028
1 Oct  Disposal                 11,250    1 Jan  Balance b/d           14,400
31 Dec Balance c/d              11,670    31 Dec Profit or loss         8,520
                                22,920                                 22,920

Disposal of machinery account
2028                                      2028
1 Oct  Machinery                30,000    1 Oct  Provision for depn    11,250
31 Dec Profit or loss (profit)   1,250    1 Oct  Bank                  20,000
                                31,250                                 31,250
The statement of financial position shows machinery at cost 69,600, less accumulated depreciation 11,670, giving a net book value of 57,930. The profit of 1,250 is income in the statement of profit or loss; a loss would be an expense.
Common errors
- Putting delivery and installation of a new asset into expenses, or putting repairs into the asset account.
- Crediting the proceeds of selling an asset to sales, or a loan to income.
- Applying the reducing balance percentage to original cost every year.
- Crediting depreciation to the asset account (when a provision account is used) or leaving the sold asset’s depreciation in the provision.
- Comparing proceeds with cost instead of net book value.
Frequently asked questions
What is the difference between capital and revenue expenditure in Cambridge IGCSE Accounting 0452? Capital expenditure is spending on buying, improving or getting a non-current asset ready for use, such as delivery and installation. Revenue expenditure keeps the business running day to day and keeps assets in working order, such as repairs.
What is a capital receipt? A capital receipt is money received that is not income from trading, such as capital paid in by the owner, a loan received or the proceeds of selling a non-current asset. Capital receipts are not credited to sales or income.
How does the revaluation method of depreciation work? Revaluation suits collections of small items such as hand tools. Depreciation is the opening valuation plus purchases during the year minus the closing valuation.
Why must depreciation be accounted for? A non-current asset helps earn revenue over several years, so its cost is matched against those years rather than charged all in the year of purchase. Without depreciation, profit and the asset’s value in the statement of financial position would be overstated.
What happens to profit if revenue expenditure is treated as capital expenditure? Profit and non-current assets are overstated, but by less than the full amount when depreciation has been charged on the wrongly capitalised item. The effect on profit is the amount minus that depreciation.
Official syllabus
Cambridge IGCSE Accounting 0452 syllabus for exams in 2027, 2028 and 2029 (version 1), Cambridge University Press & Assessment: section 4.1 Capital and revenue expenditure and receipts and section 4.2 Accounting for depreciation and disposal of non-current assets.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Revision notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
Accounting · Cambridge · IGCSE, O Level
Revise topic -
Practice questions
IGCSE Accounting: Capital and revenue items, depreciation and disposals (Cambridge 0452) – Practice Questions
Original practice questions with worked answers on capital and revenue items, depreciation and disposals for Cambridge IGCSE Accounting 0452 (2027-2029).
Accounting · Cambridge · IGCSE, O Level
Try questions -
Revision notes
IGCSE Accounting: Capital and revenue items, depreciation and disposals (Cambridge 0452) – Revision Notes
Condensed revision notes on capital versus revenue items, depreciation methods and disposal accounts for Cambridge IGCSE Accounting 0452 (2027-2029).
Accounting · Cambridge · IGCSE, O Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

