
Revision Notes
OCR A Level Business: Decision making and Decision trees (H431) – Revision Notes
Condensed OCR A Level Business revision notes on decision types, decision-making tools, expected values and evaluating decision trees.
- Subject
- Business
- Level
- A LEVELS
- Topic
- Business objectives and strategic decisions
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to OCR A Level Business (H431), Version 2.1 (January 2026), for first assessment in 2017; final assessment summer 2027. Official specification .
Syllabus page (what it covers and how it is assessed): OCR A Level Business.
Syllabus points this page covers
H431
- 1.13 Decision making
- 1.14 Decision trees
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Business (H431).
Quick recall for OCR A Level Business (H431) sections 1.13 Decision making and 1.14 Decision trees, from the Version 2.1 specification. For full explanations and two worked trees, use the study guide. Test yourself with the practice questions, see the wider area in the strategy revision notes, and tick off topics on the checklist. The course page is the OCR A Level Business hub, and the free diagnostics show what to revise first.
1.13 Decision making at a glance
| Idea | Recall |
|---|---|
| Nature | A choice between alternative courses of action, made by identifying the issue, gathering information, comparing options and choosing |
| Purpose | Move the business towards its aims and objectives with limited resources and less guesswork |
| Importance | Effective decisions protect cash, use resources well and keep the business on course; the effects differ for owners, staff, customers, suppliers, lenders and the community |
| Aims and objectives | Aims are broad purposes; objectives are measurable targets. Objectives supply the criteria for judging options, and results show if the objective is met |
Types of decision
| Distinction | Categories | Memory hook |
|---|---|---|
| Time | Short-term, medium-term, long-term | How far ahead the effects run. The specification sets no fixed years, so state your own horizon |
| Level | Strategic, tactical, operational | Direction, delivery, daily running |
| Tools | Quantitative, qualitative | Numbers versus judgement |
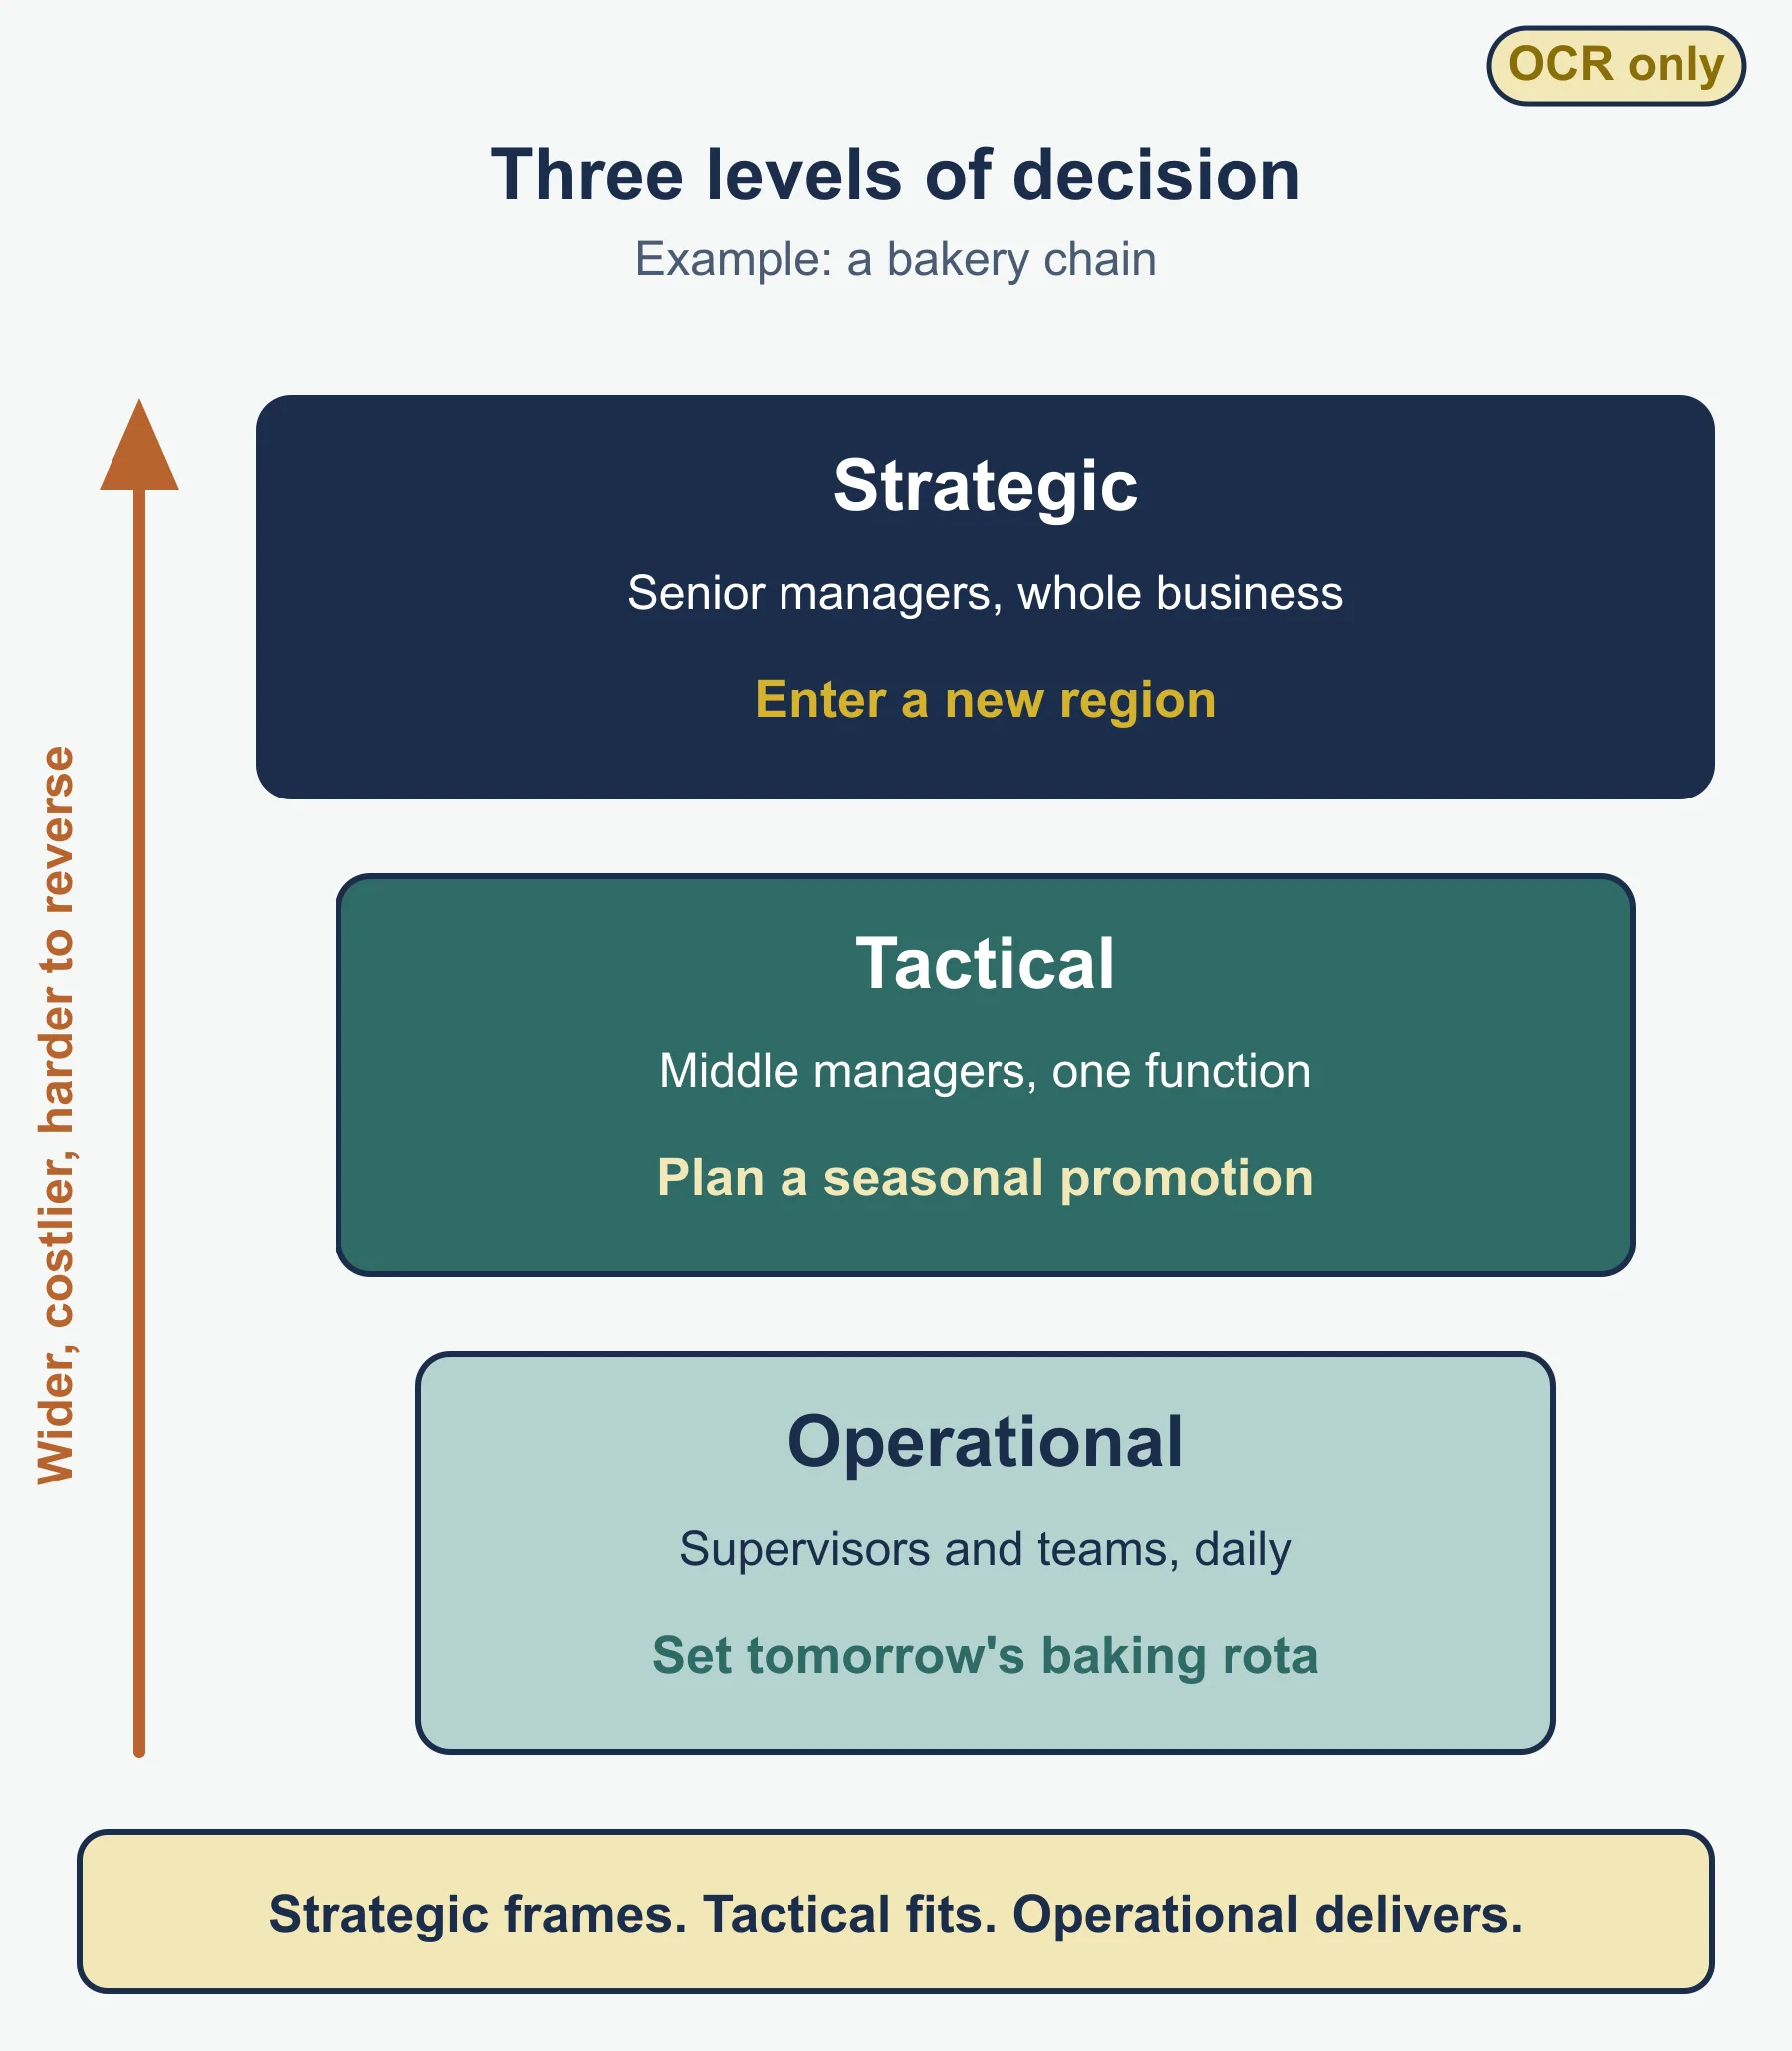
- Strategic: senior managers, whole business, costly, hard to reverse.
- Tactical: middle managers, one function or period, serves the strategy.
- Operational: supervisors and teams, routine, short-term.
Time and level often line up, but they are separate ideas. A decision can be short-term and still strategic.
Factors to weigh before deciding
- Level of risk: size of possible loss against possible gain, set against reserves.
- Nature of risk: quantifiable (can have probabilities) or unquantifiable.
- Accuracy of forecasts: weak inputs give a misleading answer.
- Volatility: unstable markets shorten the life of assumptions and favour flexible options.
- Potential for bias: pet projects, over-confidence, ignoring contrary evidence.
Quantitative and qualitative tools
| Quantitative | Qualitative | |
|---|---|---|
| Based on | Figures, forecasts, calculations | Opinion, judgement, context |
| Strength | Objective, comparable | Captures reputation, morale, ethics |
| Weakness | Ignores what cannot be measured; depends on estimates | Subjective; harder to compare |
| Example | Expected value from a decision tree | Staff views on a relocation |
Performance measures
- Financial: profit, margins, cash flow, return on capital. Backward-looking and tied to the accounts.
- Non-financial: market share, customer satisfaction, quality, staff turnover, environmental impact. Can warn earlier and show what the accounts hide.
- Test a measure by asking whether it fits the objective, is reliable, is timely and has a benchmark.
- Use both. Neither gives the whole picture.
Method: choosing a course of action
- State the objective and the criteria for success.
- List the options, including doing nothing.
- Compare quantitative evidence (profit, cost, EV, cash flow).
- Add qualitative evidence (reputation, staff, ethics, stakeholders).
- Weigh risk, forecast reliability and volatility.
- Recommend one option and state the condition under which you would change your mind.
Method: extent of success
Compare results with objectives, with previous years, with competitors and from each stakeholder’s view. Reach a judgement of degree: successful in some respects, not in others, and say which matter most. A business that meets its growth target but misses its profit target is partly successful, and the weight you give each depends on the objective and on the stakeholder.
1.14 Decision trees at a glance
Symbols and rules
| Feature (standard conventions, not specification wording) | Rule |
|---|---|
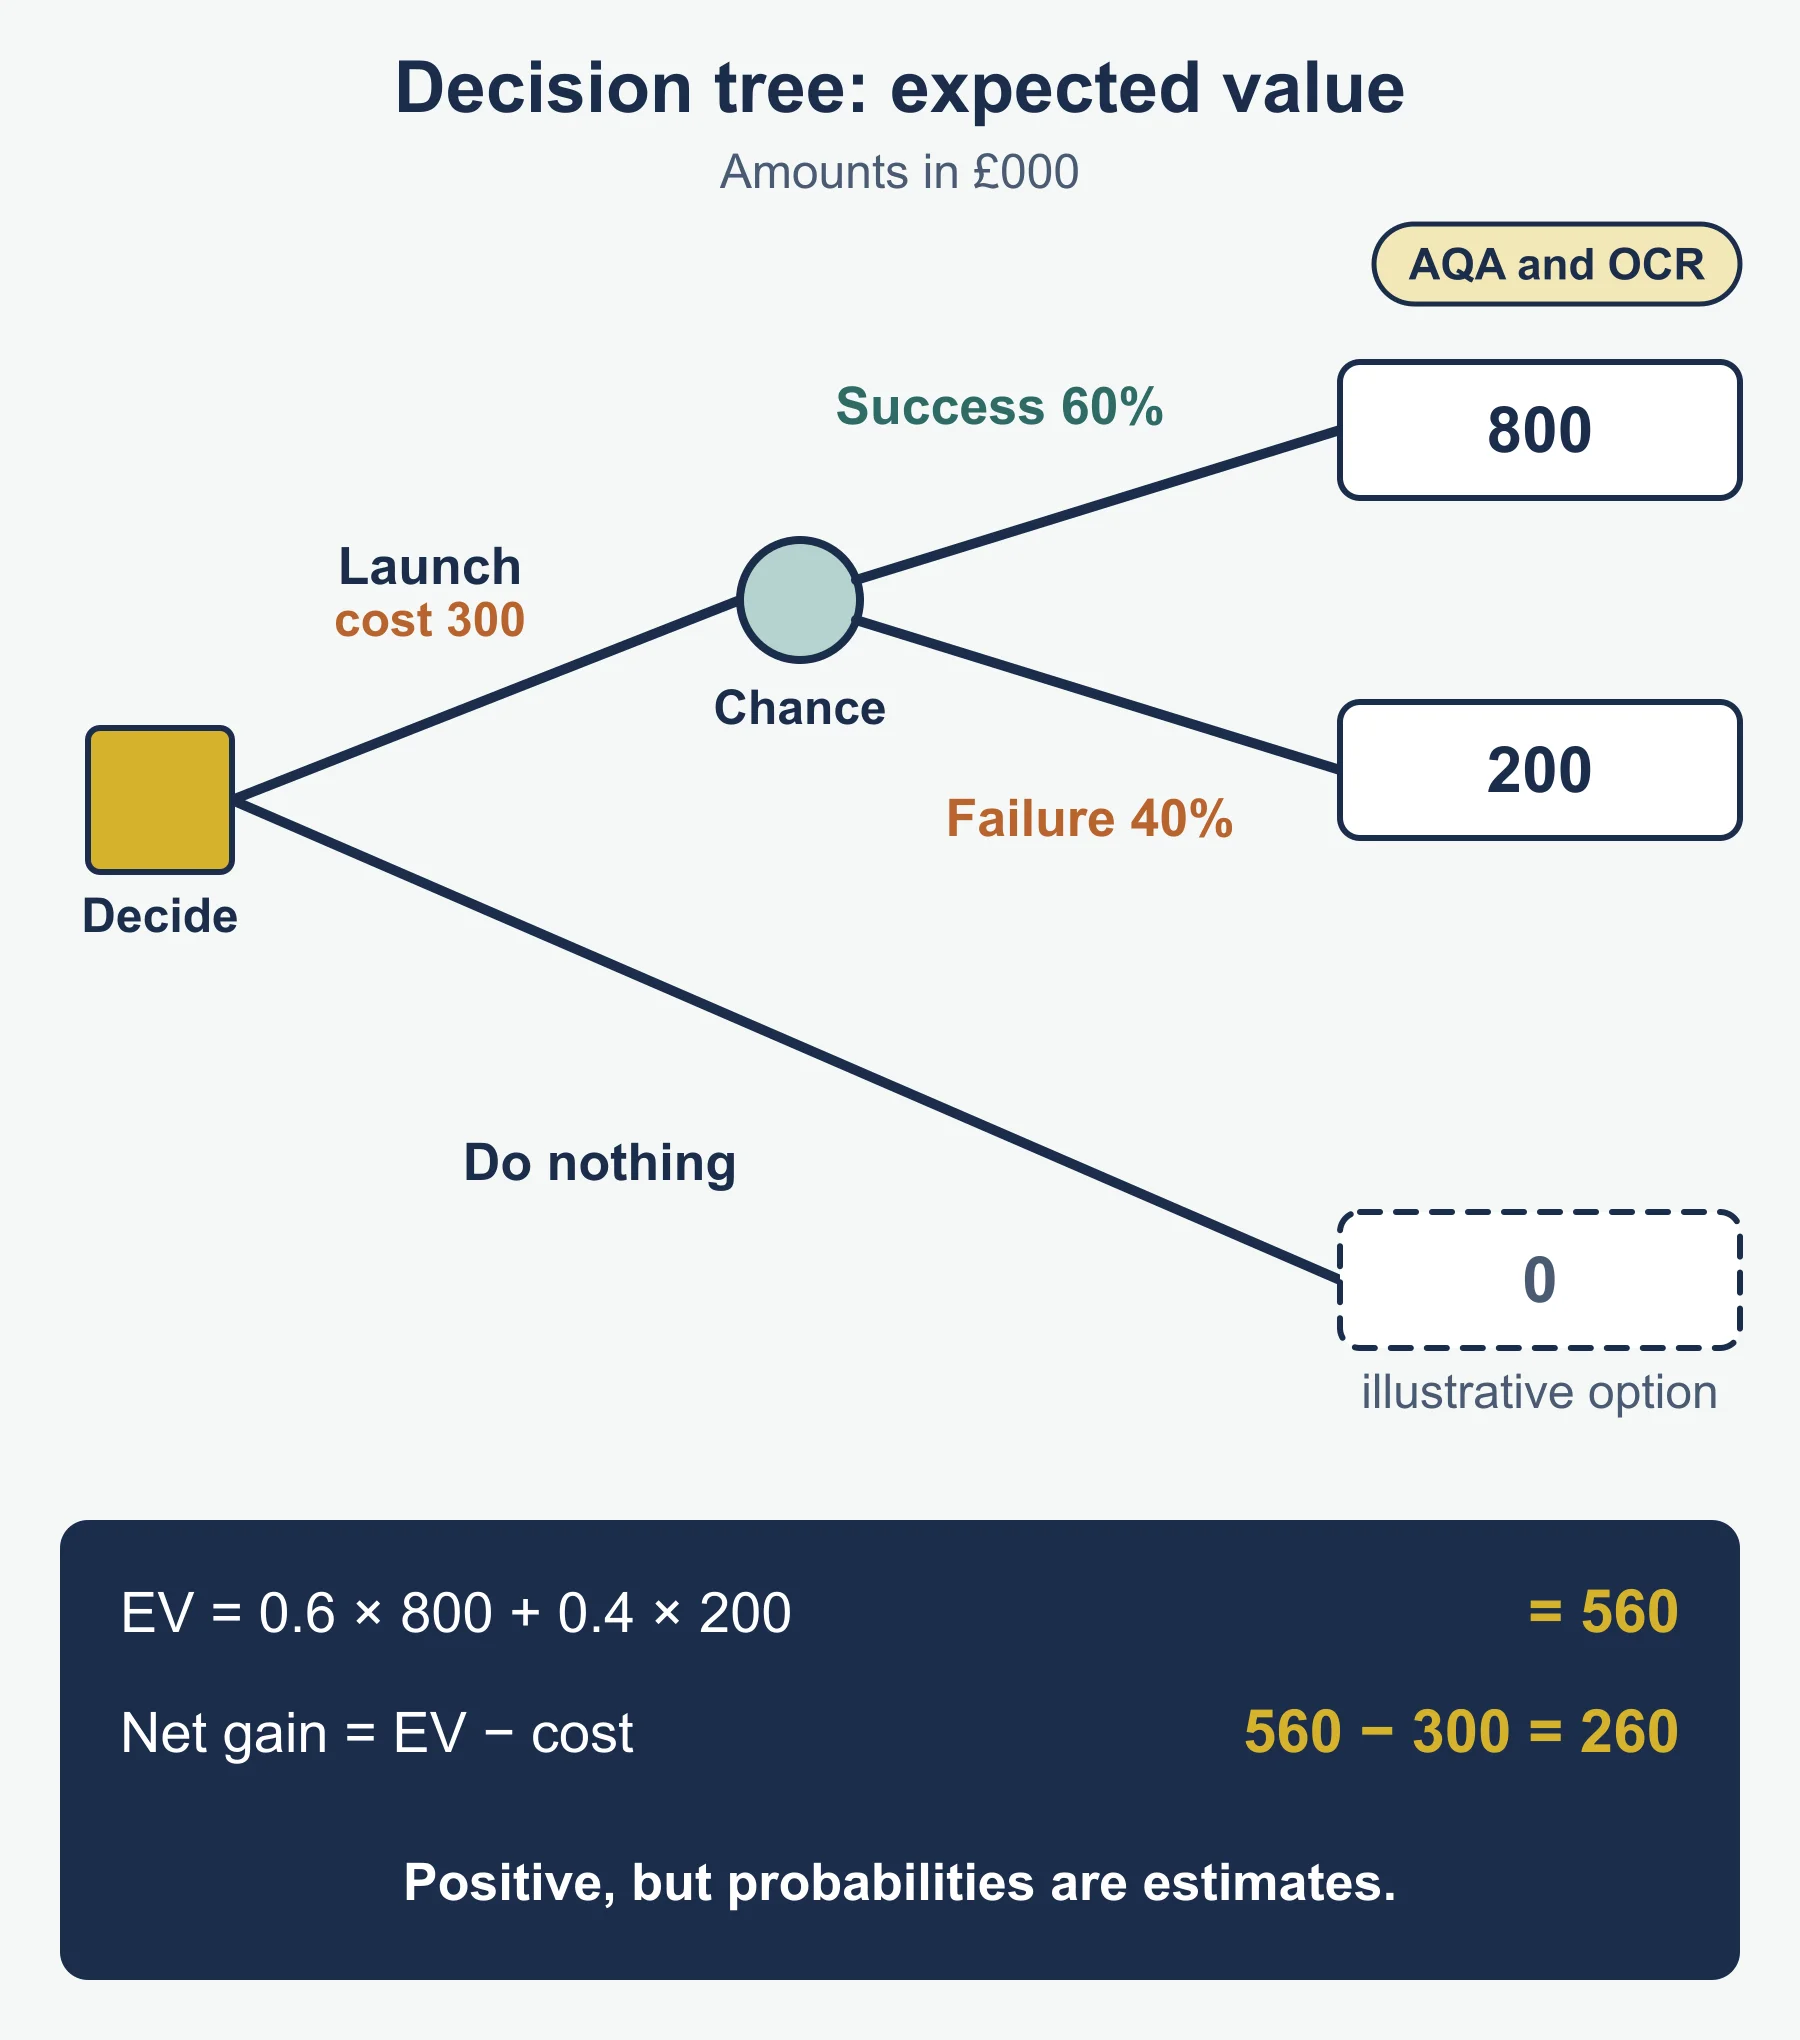
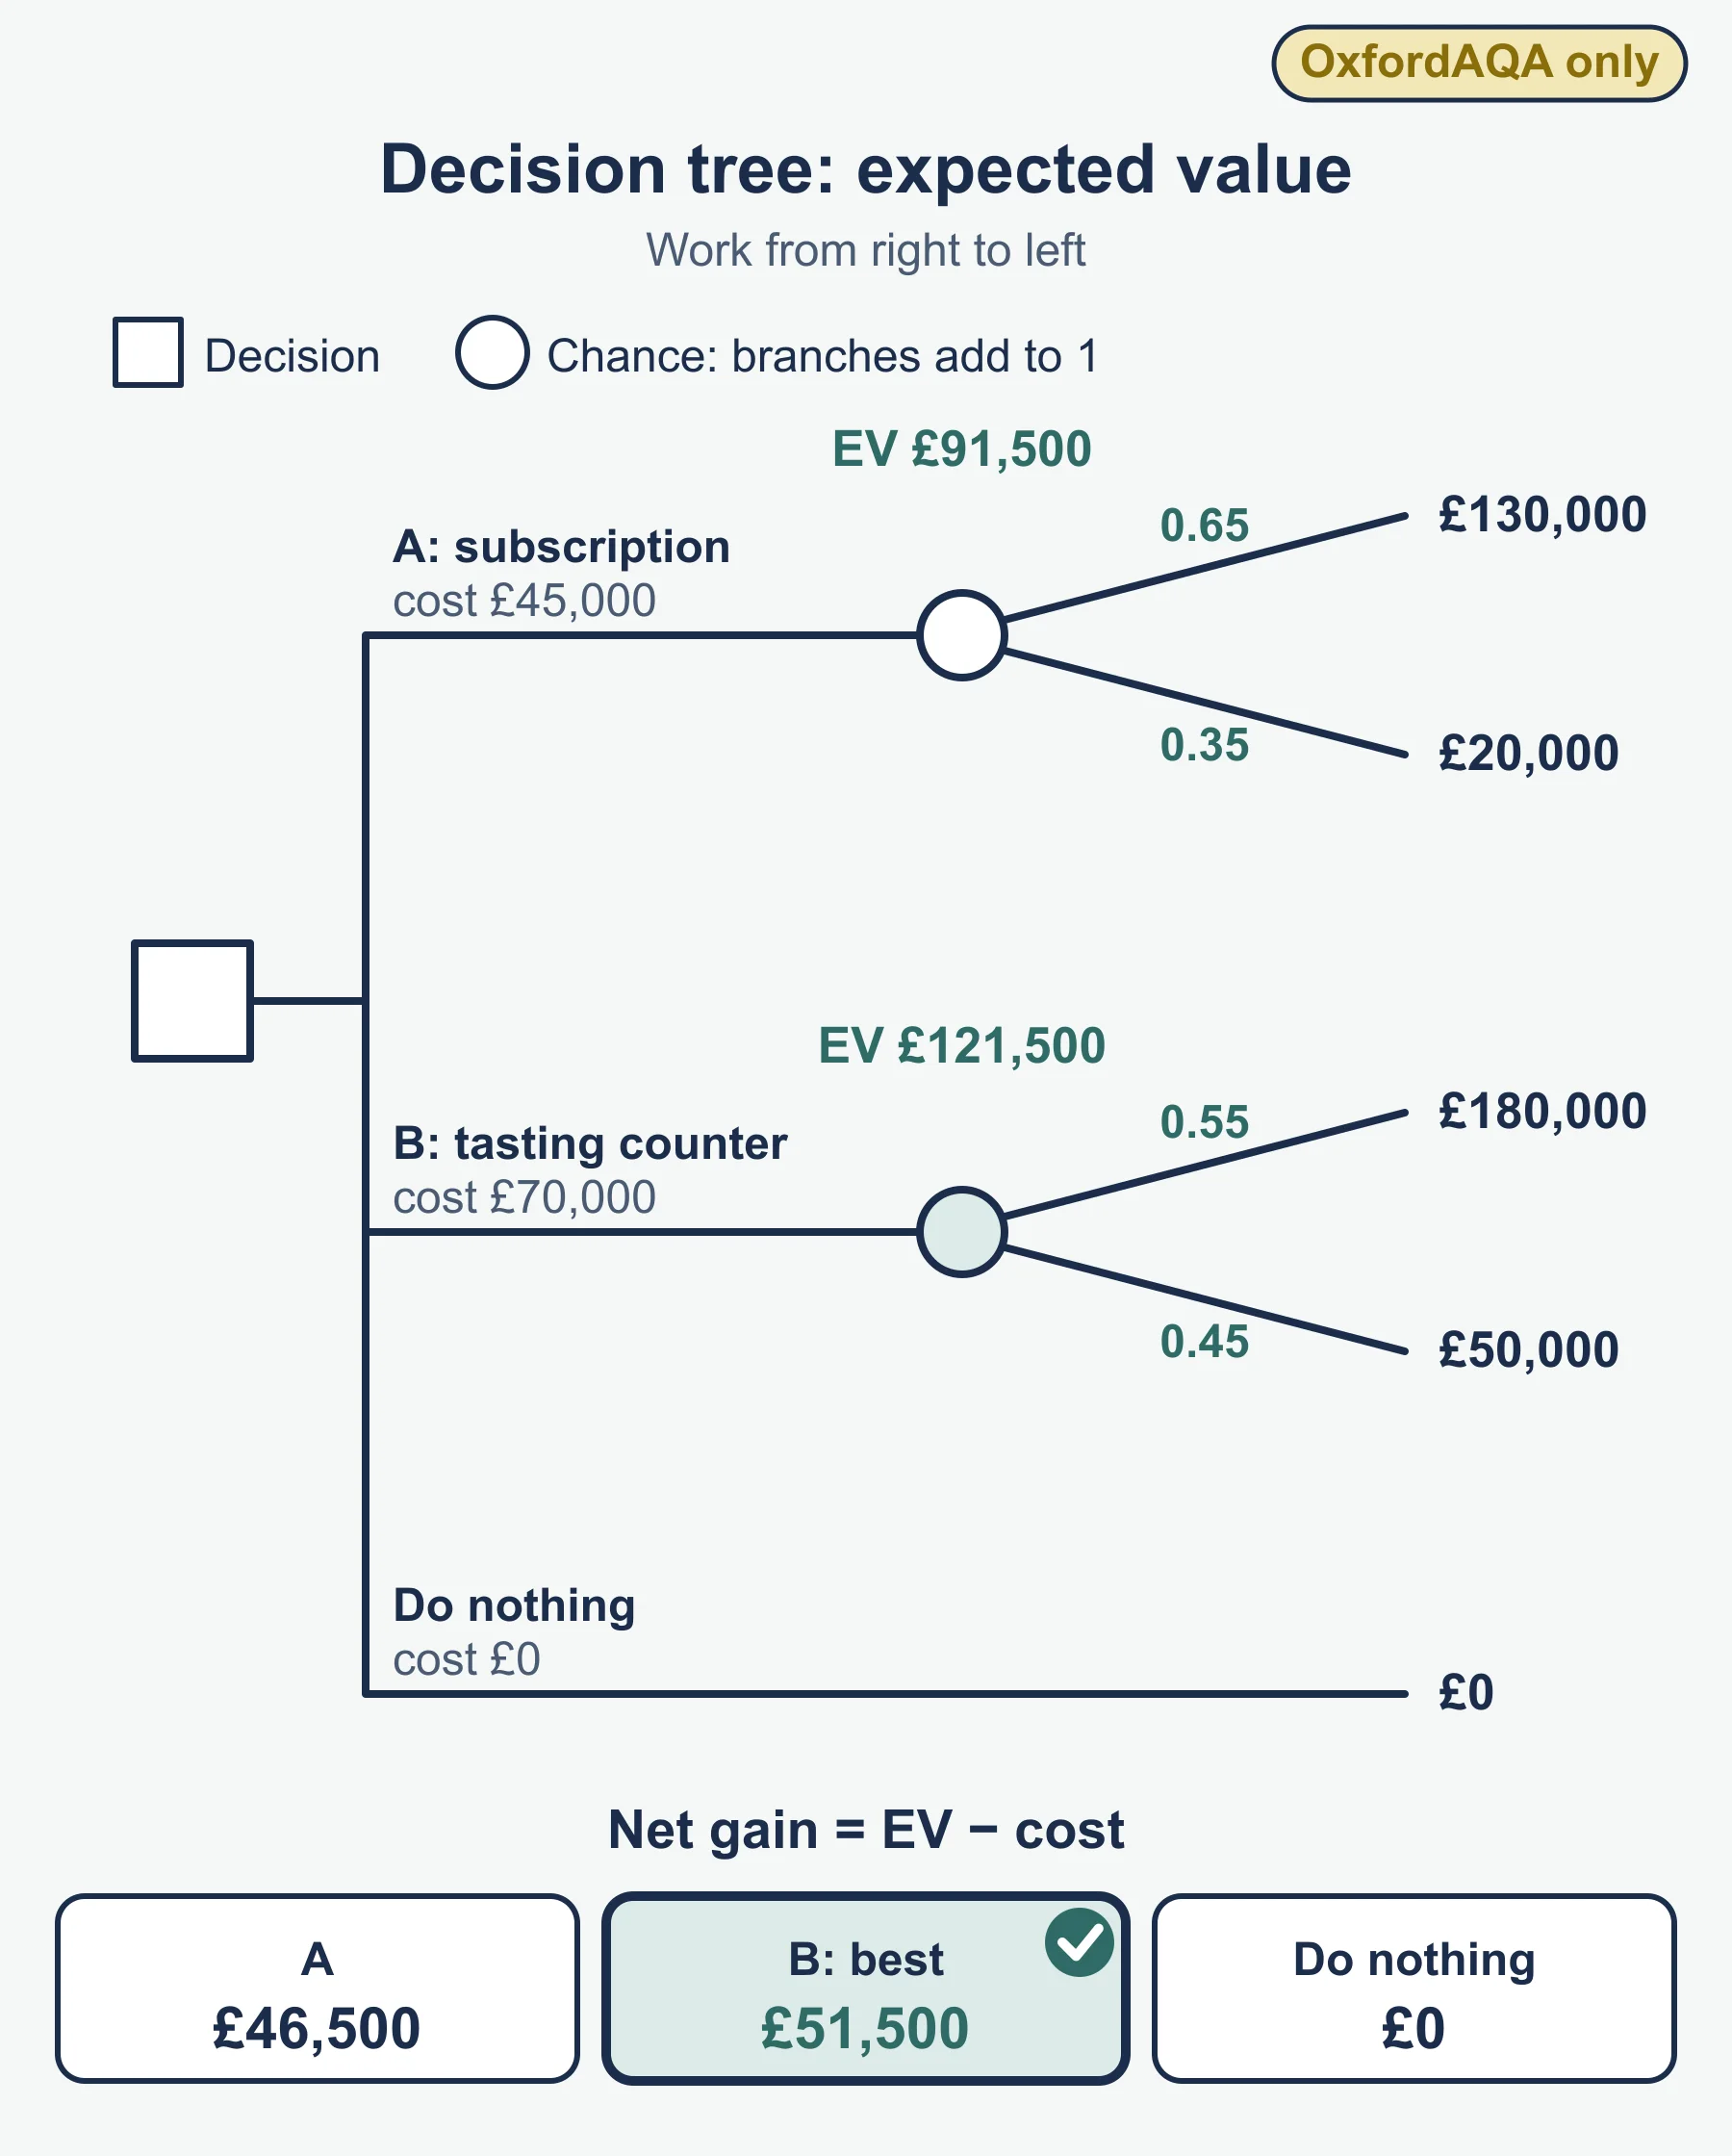
| Decision node | Square. The business chooses. |
| Chance node | Circle. Probability decides. |
| Probabilities | Decimals or percentages; total 1.0 (100%) at each chance node |
| Costs | On the branch where they are spent |
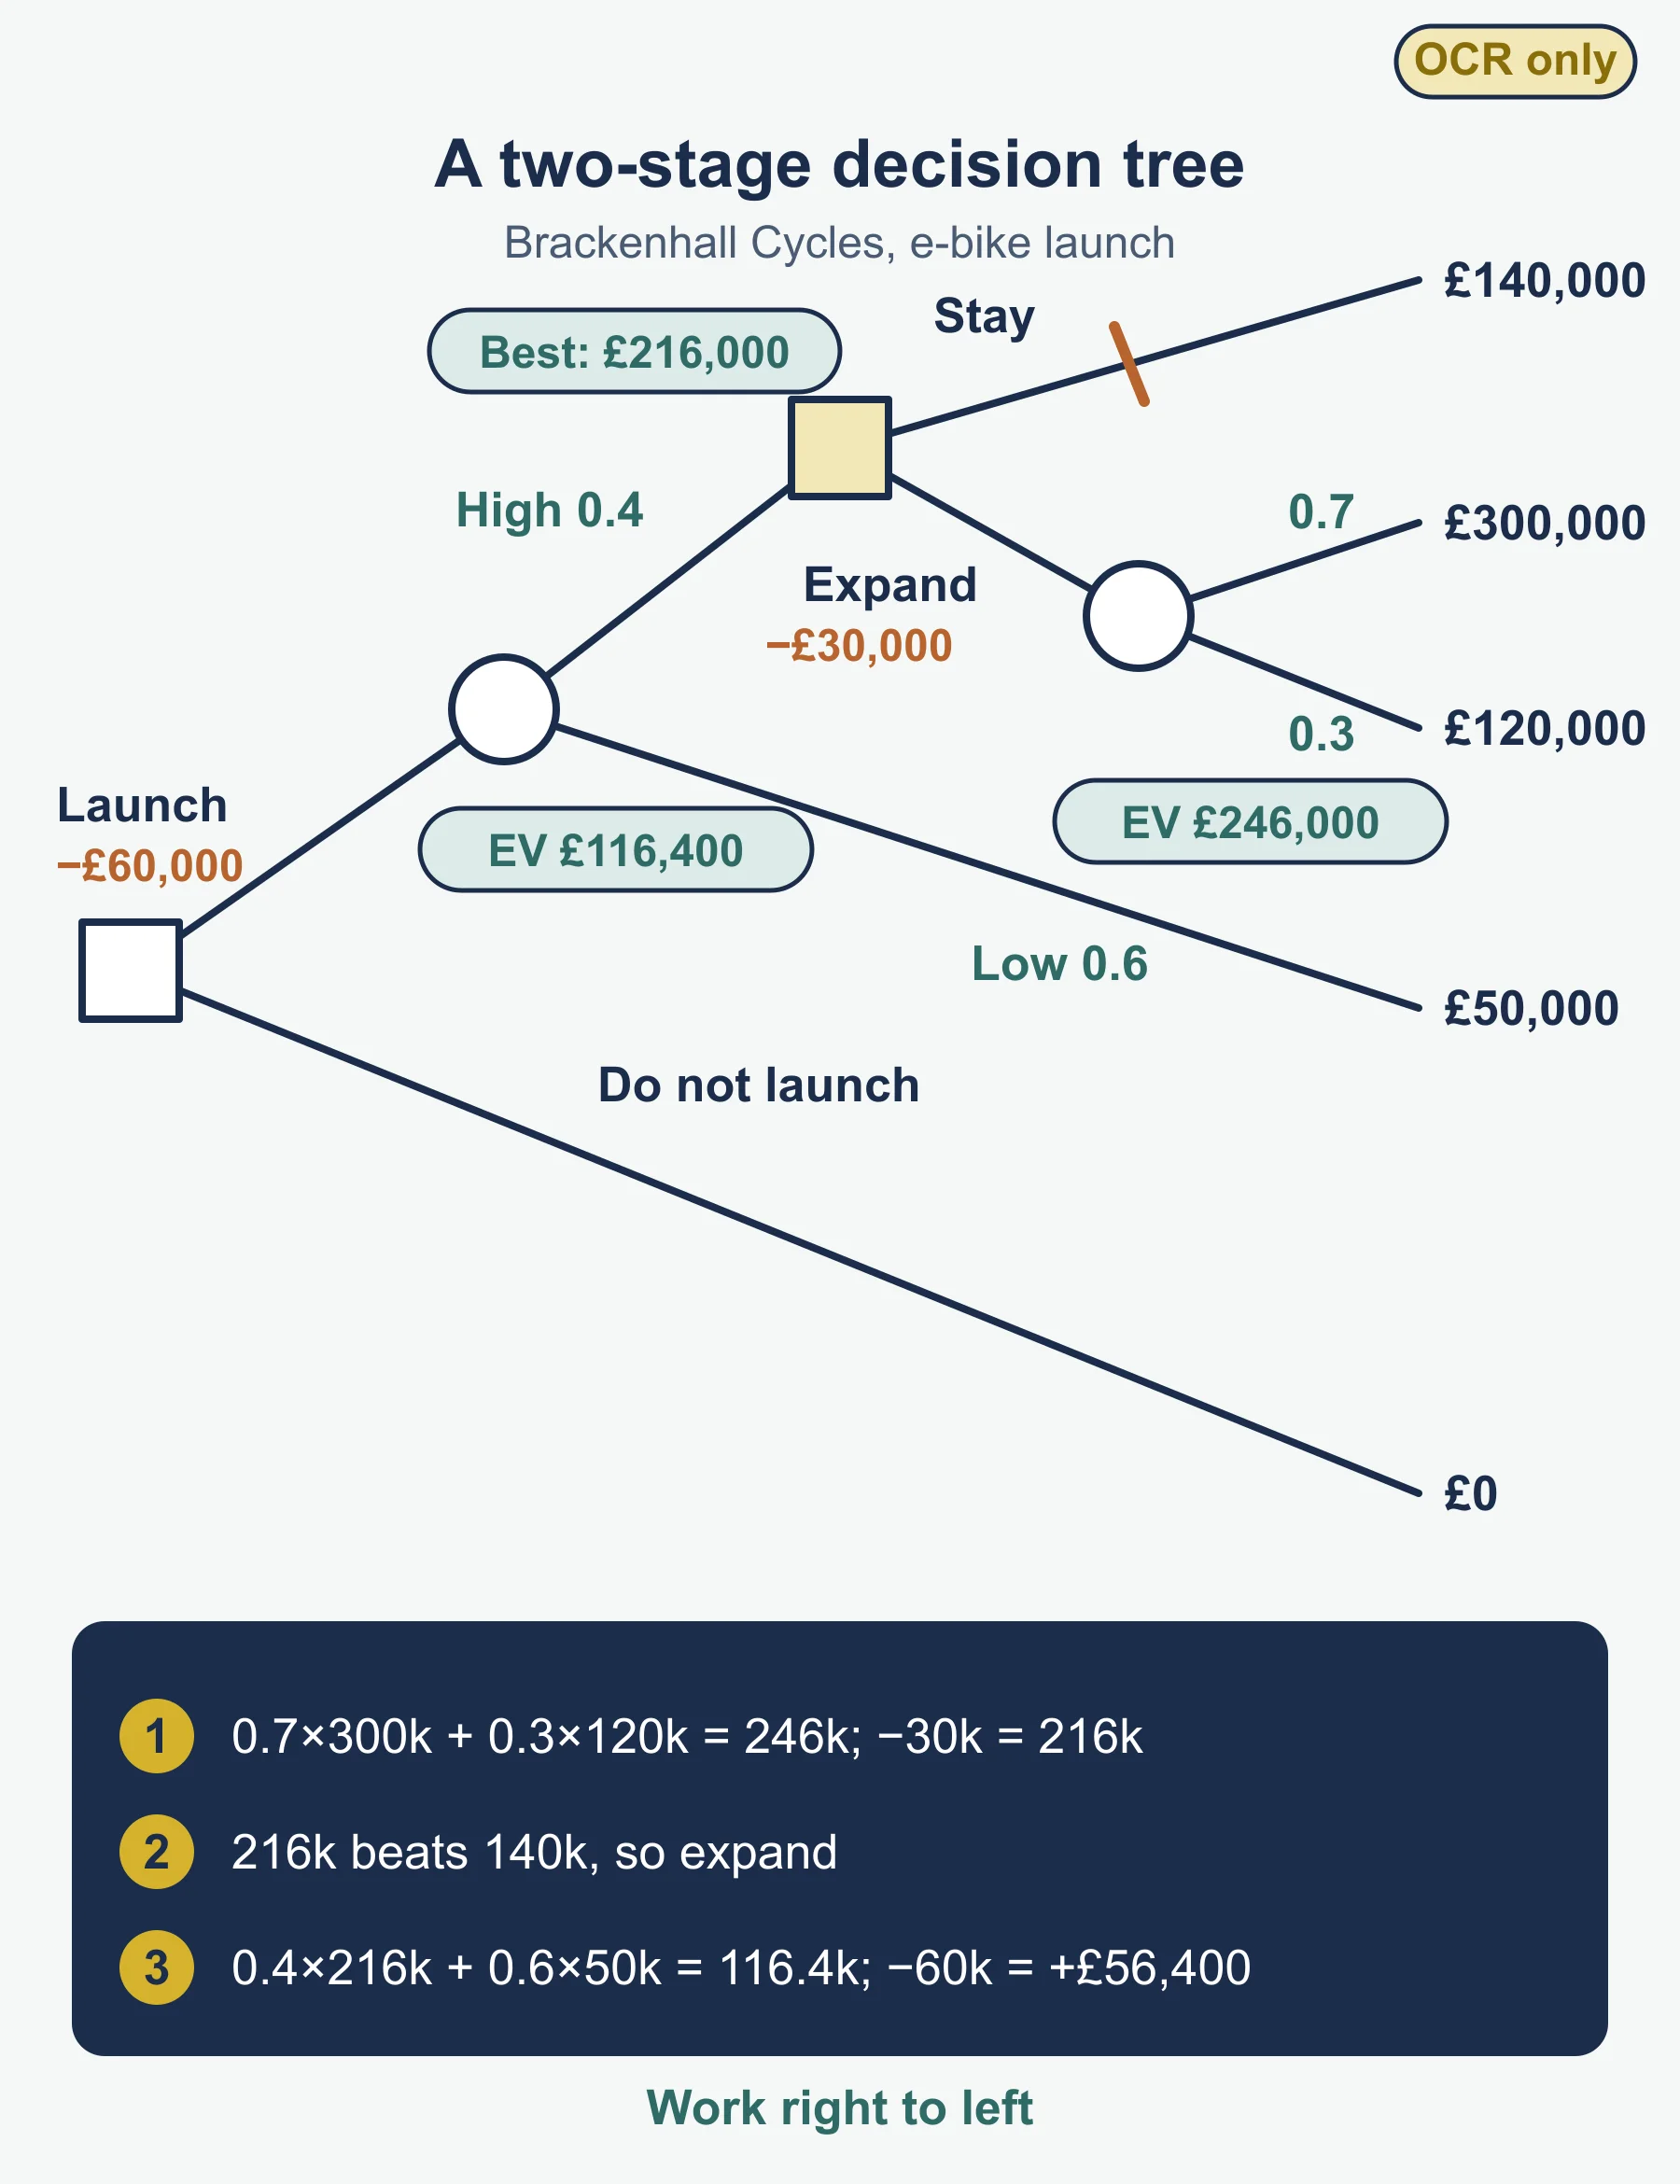
| Direction | Build left to right, calculate right to left |
Formulas (standard form, not specification wording)
EV = sum of (probability x payoff)
economic outcome of a branch = payoff - costs on that path
net gain of an option = EV - cost of the option
Method in steps
- Check the probabilities at each chance node total 1.0. Find a missing one by subtraction.
- Start at the right. Work out the EV of each chance node.
- At a decision node, pick the branch with the best figure, taking account of its cost.
- Move left, using that figure as the payoff for the earlier branch.
- Deduct the cost of the option to find its net gain.
- Compare options, including doing nothing (net gain nil).
- Interpret: say what the figure means, then evaluate.
Reminder example: sensitivity to a probability
Stoneyfold Bakery can open a second shop for £45,000. If it succeeds (probability p) the payoff is £120,000. If not, £15,000.
- EV = 120,000p + 15,000(1 - p) = 15,000 + 105,000p.
- Net gain = 15,000 + 105,000p - 45,000 = 105,000p - 30,000.
- Net gain is zero when p = 30,000 / 105,000 = 0.286 (28.6%).
| Success probability | Net gain |
|---|---|
| 20% | -£9,000 |
| 30% | £1,500 |
| 40% | £12,000 |
| 50% | £22,500 |
Interpretation: the shop pays off on average only if the owners believe success is more than about 29% likely. Because that probability is a judgement, they should ask how confident they are in it. This is a good way to evaluate how to respond to a tree.
Evaluating a tree
| Question | Points to make |
|---|---|
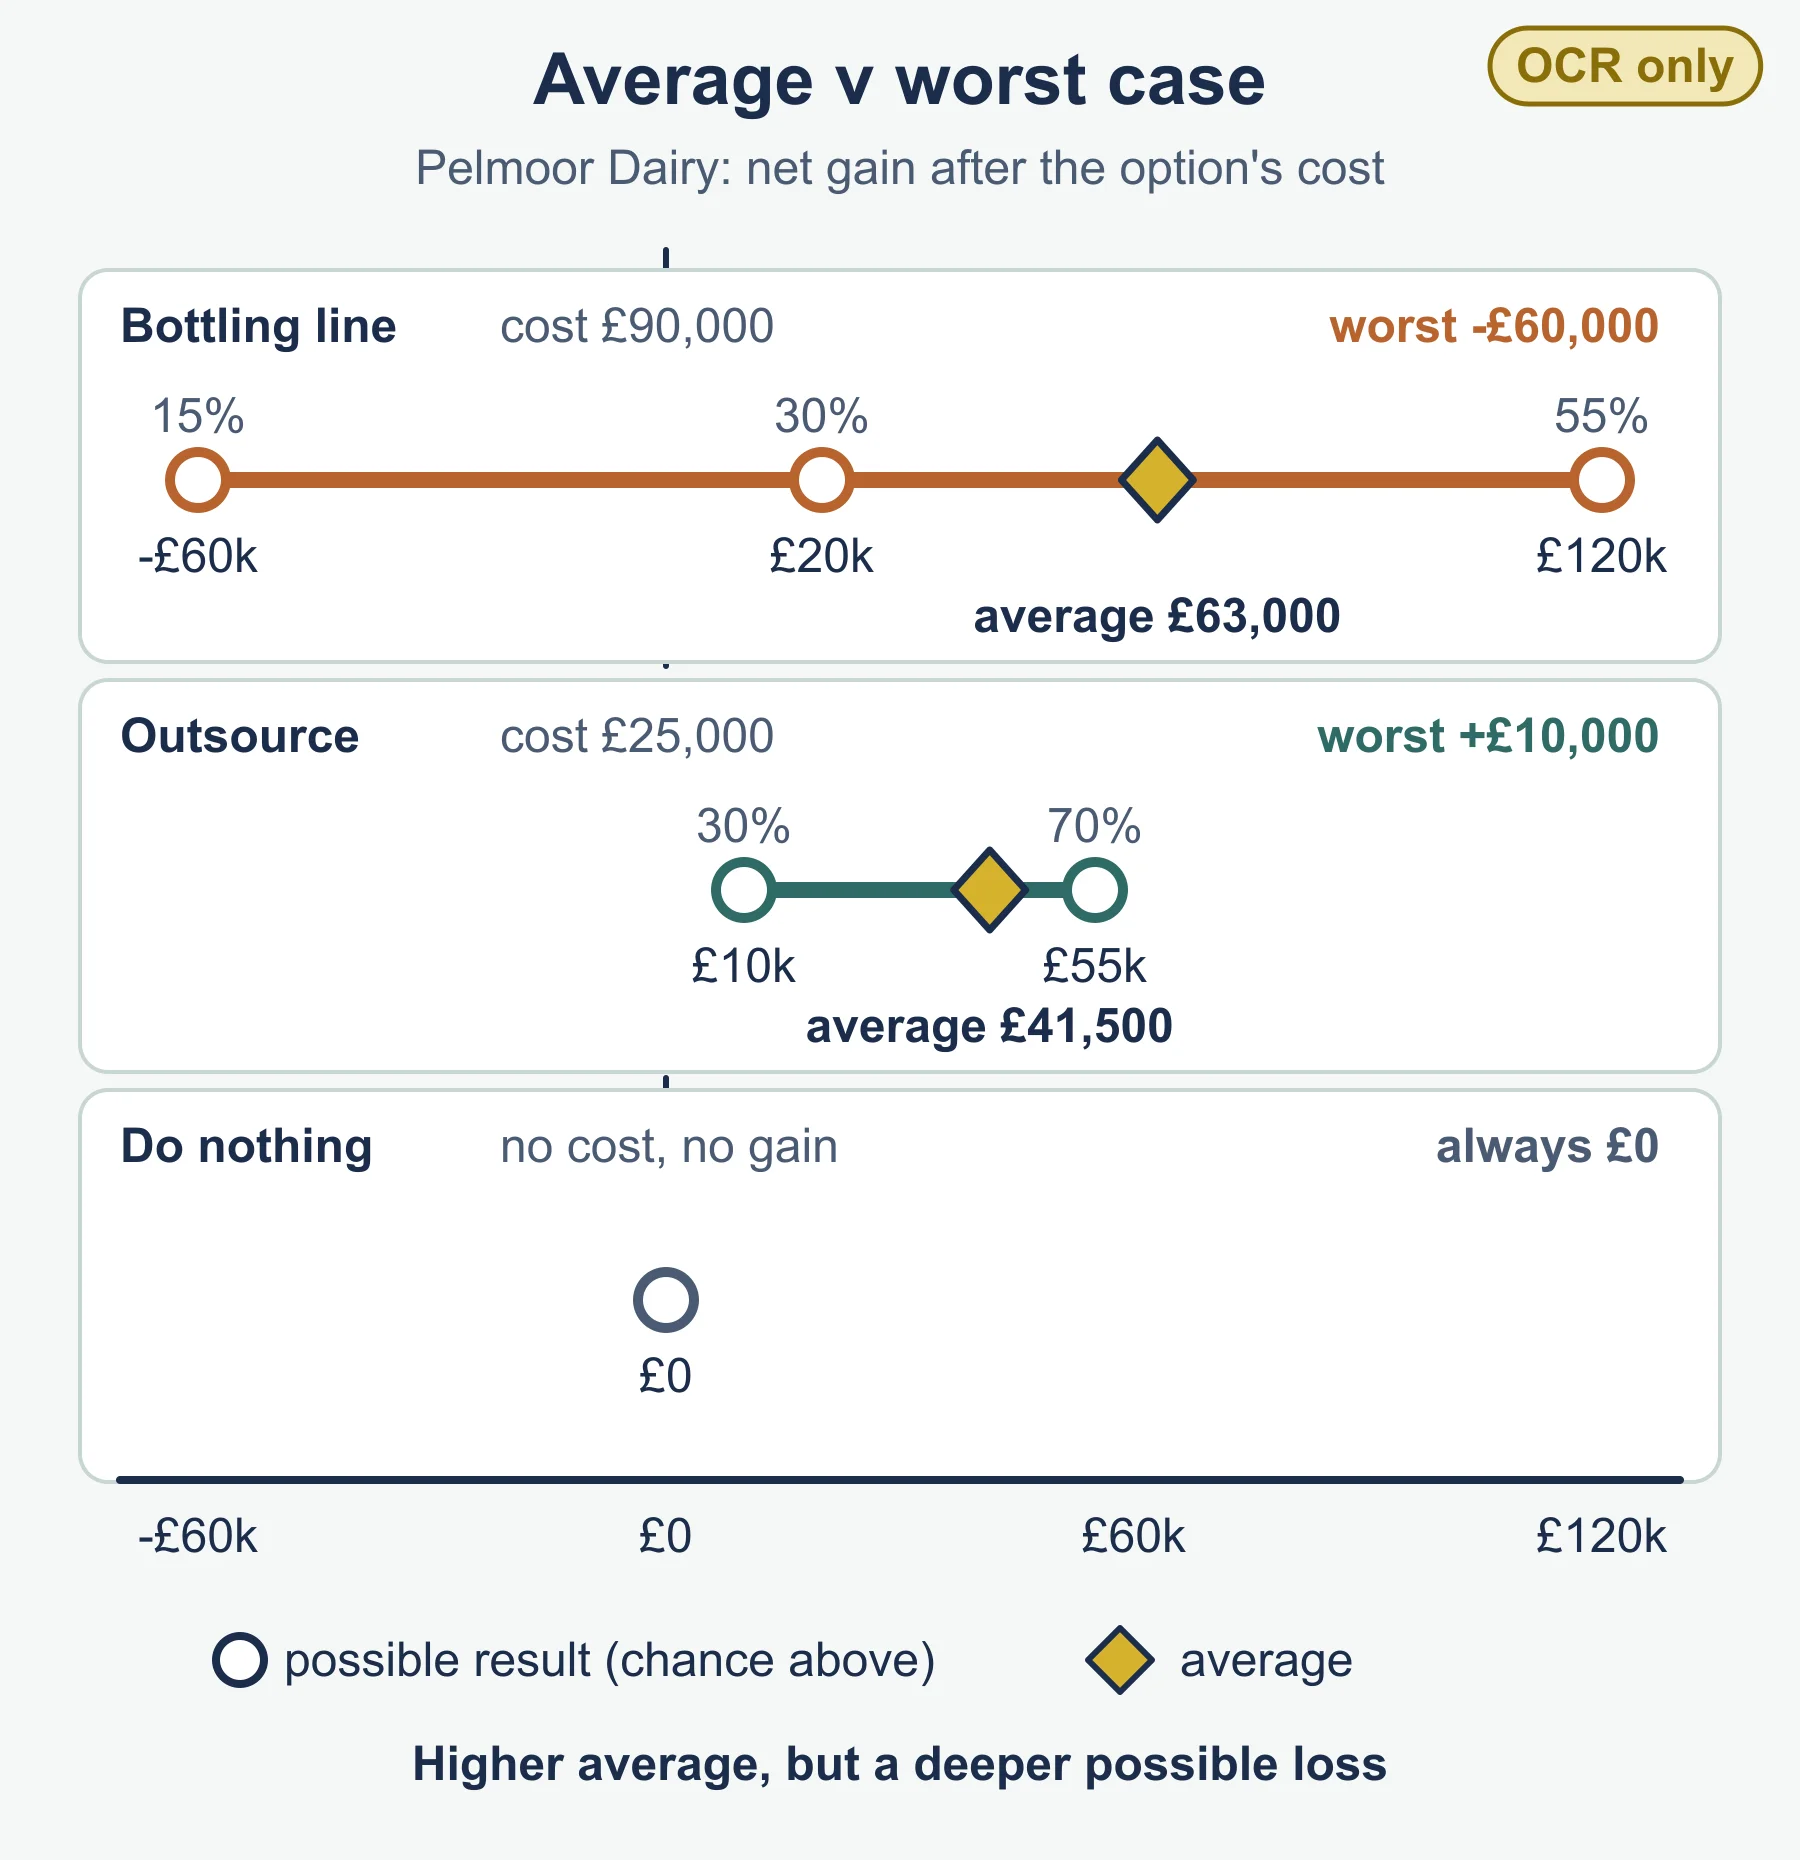
| Outcomes | Compare EVs and the range between best and worst cases; EV may never actually occur |
| Response | Test the probabilities, check the worst case is survivable, add qualitative factors |
| Importance | Greatest for costly, hard-to-reverse choices; shows who bears the downside |
| Usefulness | Strengths: clear, shows assumptions, compares options, handles sequences. Limits: estimates, subjective, ignores qualitative factors and timing of cash flows, false precision |
Must-know distinctions
Be ready to explain each of these pairs in a sentence and apply it to a case.
- Strategic versus tactical versus operational (level), not the same as long versus short term (time).
- Expected value versus net gain: the second deducts cost.
- Quantifiable versus unquantifiable risk: only the first can be put on a tree.
- Financial versus non-financial measures.
- Decision node versus chance node.
Quick self-test
- Define decision making in one sentence.
- Give two differences between strategic and operational decisions.
- Name the five factors the specification lists as needing to be taken into account.
- Why might a business with a growth objective reject the option with the highest profit?
- A chance node has branches of 40%, 35% and one more. State the missing probability as a decimal.
- A branch has a 35% chance of £80,000 and a 65% chance of £20,000, and costs £30,000. Calculate EV and net gain.
- Why is a decision tree a poor tool if the risks are unquantifiable?
- Give one financial and one non-financial measure of performance and say what each shows.
- State two ways a decision tree helps a business and two limits.
- How should a business respond if its tree favours Option A only when a probability is 0.3 or higher, and the manager is unsure whether it is 0.3?
Answers
- Choosing between alternative courses of action to meet aims and objectives.
- Strategic: long-term, whole business, senior managers, hard to reverse. Operational: day-to-day, one team, supervisors, easily changed.
- Level of risk, nature of risk, accuracy of forecasts, volatility, potential for bias.
- Because the option may not deliver the growth, for example market share, that the objective requires. Objectives set the criteria.
- 1 - 0.40 - 0.35 = 0.25.
- EV = 0.35 x 80,000 + 0.65 x 20,000 = 28,000 + 13,000 = £41,000. Net gain = 41,000 - 30,000 = £11,000.
- Probabilities cannot be attached to them, so the EV has no sound basis and the numbers give false precision.
- For example net profit margin shows profitability. Customer satisfaction shows how well customers are served, which the accounts may not reveal.
- Helps: makes assumptions visible; allows options to be compared on one measure. Limits: probabilities are estimates; qualitative factors and cash-flow timing are ignored.
- Treat the choice as sensitive. Gather more evidence on the probability, check the downside is affordable, weigh qualitative factors and consider a smaller or more flexible version of A.
Where marks are usually lost
- Calculating EV but not subtracting the option’s cost before comparing.
- Giving probabilities that do not sum to 1.0 or 100%.
- Defining strategic, tactical and operational only by time, ignoring level and scope.
- Listing limits of decision trees without applying them to the business in the case.
- Naming the factors (risk, forecasts, bias) with no link to the business described.
- Treating the highest EV as the answer without discussing risk, objectives and qualitative evidence.
- Judging success only on profit, ignoring non-financial measures and stakeholders.
- Conclusions that say “it depends” without saying on what.
- No units or no pound sign on money results.
Frequently asked questions
What do the squares and circles on a decision tree mean? A square is a decision node, where the business chooses a branch. A circle is a chance node, where chance decides the outcome; these drawing conventions are standard practice rather than specification wording.
How do you calculate expected value? EV = the sum of (probability × payoff) at a chance node, and net gain = EV − the cost of the option. These are standard forms, since the specification does not set a formula.
In which direction do you work through a two-stage decision tree? Work from right to left, calculating expected values at chance nodes and choosing the best option at each decision node. Rolling forward from left to right is a common error.
Should business success be judged on profit alone? No. Use non-financial measures as well, such as market share, customer satisfaction and staff turnover, and consider different stakeholders.
Official syllabus
OCR Level 3 Advanced GCE in Business (H431) specification, Version 2.1, sections 1.13 Decision making and 1.14 Decision trees, published by OCR (Oxford Cambridge and RSA).
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
OCR A Level Business: Different stakeholder and business objectives and Stakeholders (H431)
Study guide to aims, the hierarchy of objectives, SMART objectives and stakeholder conflict for OCR A Level Business H431, sections 1.1 and 1.2.
Business · OCR · A Level
Read guide -
Practice questions
OCR A Level Business: Different stakeholder and business objectives and Stakeholders (H431) – Practice Questions
Original practice questions with worked answers on objectives, SMART targets and stakeholder conflict for OCR A Level Business H431, sections 1.1 and 1.2.
Business · OCR · A Level
Try questions -
Revision notes
OCR A Level Business: Different stakeholder and business objectives and Stakeholders (H431) – Revision Notes
Condensed recall notes on the hierarchy of objectives, SMART targets and stakeholder conflict for OCR A Level Business H431, sections 1.1 and 1.2.
Business · OCR · A Level
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business A LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one, online in your own time zone. One-to-one only for this course: Rs 6,000 per class in Pakistan, with other currencies on the fees page. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
OCR Business teachers at Marlbridge
