
Study Guides
OxfordAQA IGCSE Accounting: Accounting ratios and financial measures (9215)
Study guide to the nine financial ratios and measures in OxfordAQA International GCSE Accounting 9215: standard forms, worked examples and interpretation.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Interpretation, analysis and communication of financial information
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to OxfordAQA IGCSE Accounting (9215), First teaching 2024, first examined 2026. Official specification .
Syllabus page (what it covers and how it is assessed): OxfordAQA IGCSE Accounting.
Syllabus points this page covers
9215
- Accounting ratios and financial measures
Found an error? Report a correction.
Need help with this topic? Request a free trial class for IGCSE Accounting (9215).
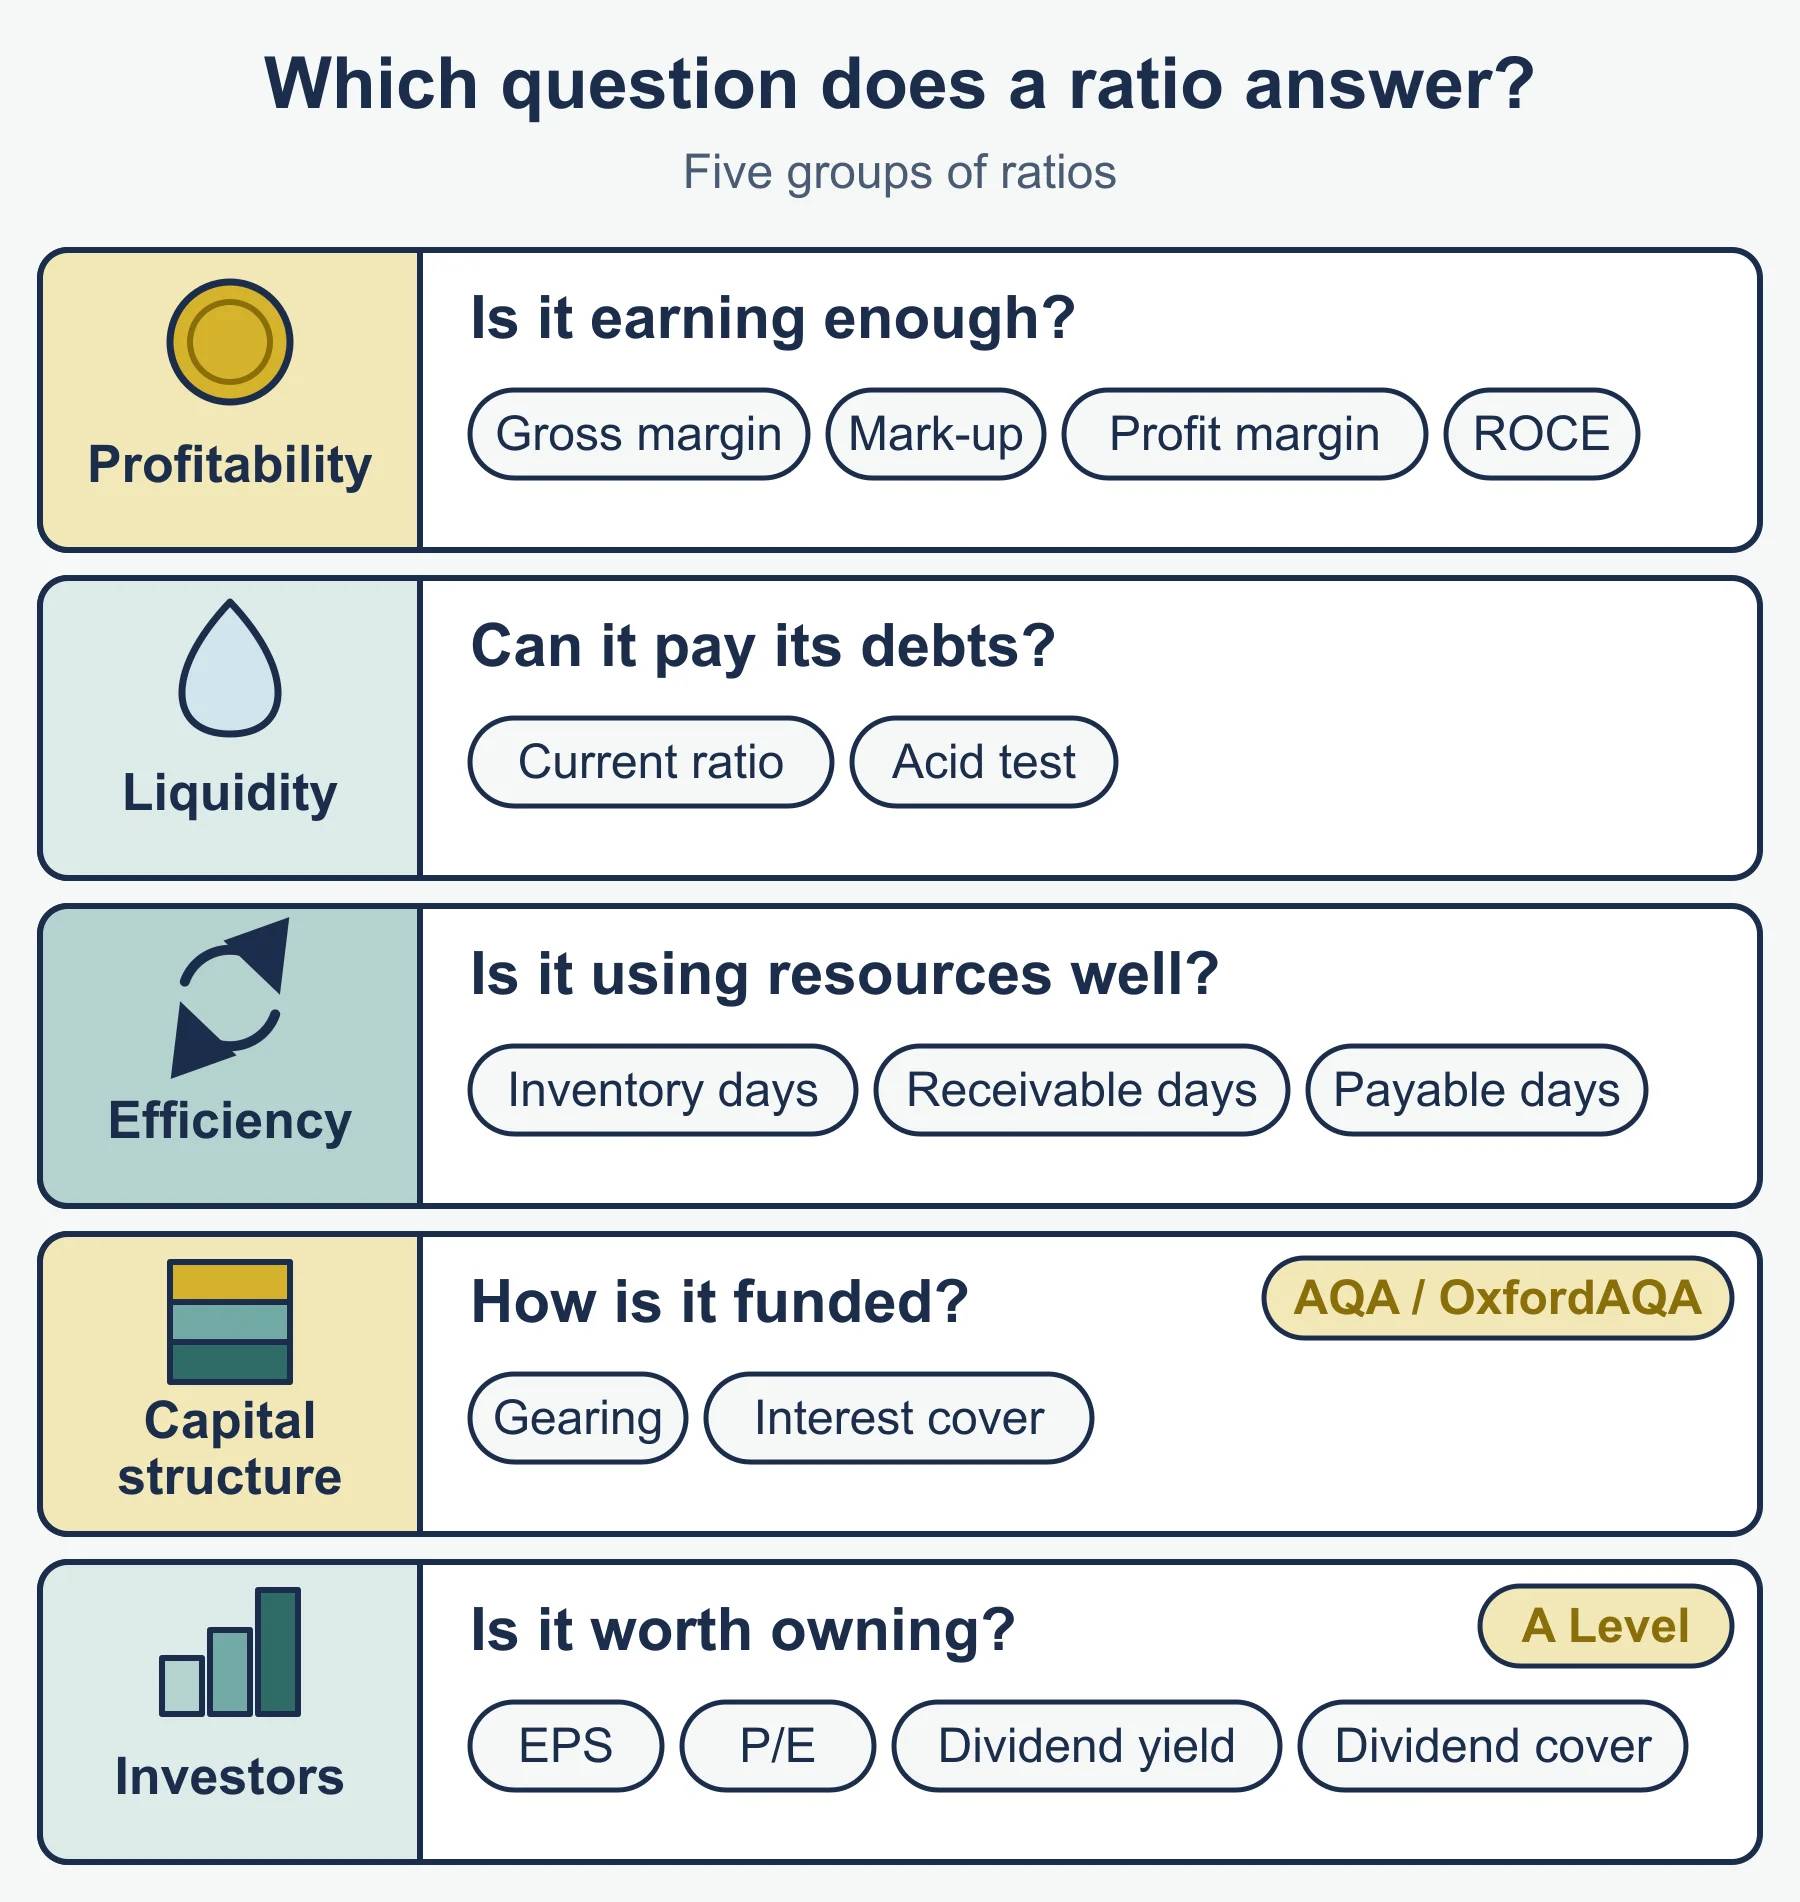
This guide is aligned to the OxfordAQA International GCSE Accounting (9215) specification, version 1.2, for exams from May/June 2026 onwards. It covers the content point in section 3.5 (topic 5, Interpretation, analysis and communication of financial information) on the calculation and interpretation of financial measures and ratios. The specification names nine of them. It says the formulae are in a separate OxfordAQA guide, “Formulae for accounting ratios”, which is not part of the specification. The forms below are the standard textbook forms. Check them against that guide, because your exam will use the board’s own versions. All amounts are in dollars.
Use this page with the revision notes and the practice questions. Other links: course hub, checklist and the free diagnostics. For the statements the ratios come from, see the sources and recording study guide.
What the specification lists
| Measure | Question it answers | Group |
|---|---|---|
| Gross profit margin % | How much of each dollar of revenue is left after the cost of the goods sold? | Profitability |
| Markup % | By what percentage is cost increased to reach the selling price? | Profitability |
| Rate of inventory turnover | How many times is the inventory sold and replaced in a year? | Efficiency |
| Profit in relation to revenue % | How much of each dollar of revenue ends as profit? | Profitability |
| Return on capital employed % | How well is the money invested in the business used? | Profitability |
| Current ratio | Can current assets cover current liabilities? | Liquidity |
| Liquid capital ratio | Can the business cover them without selling inventory? | Liquidity |
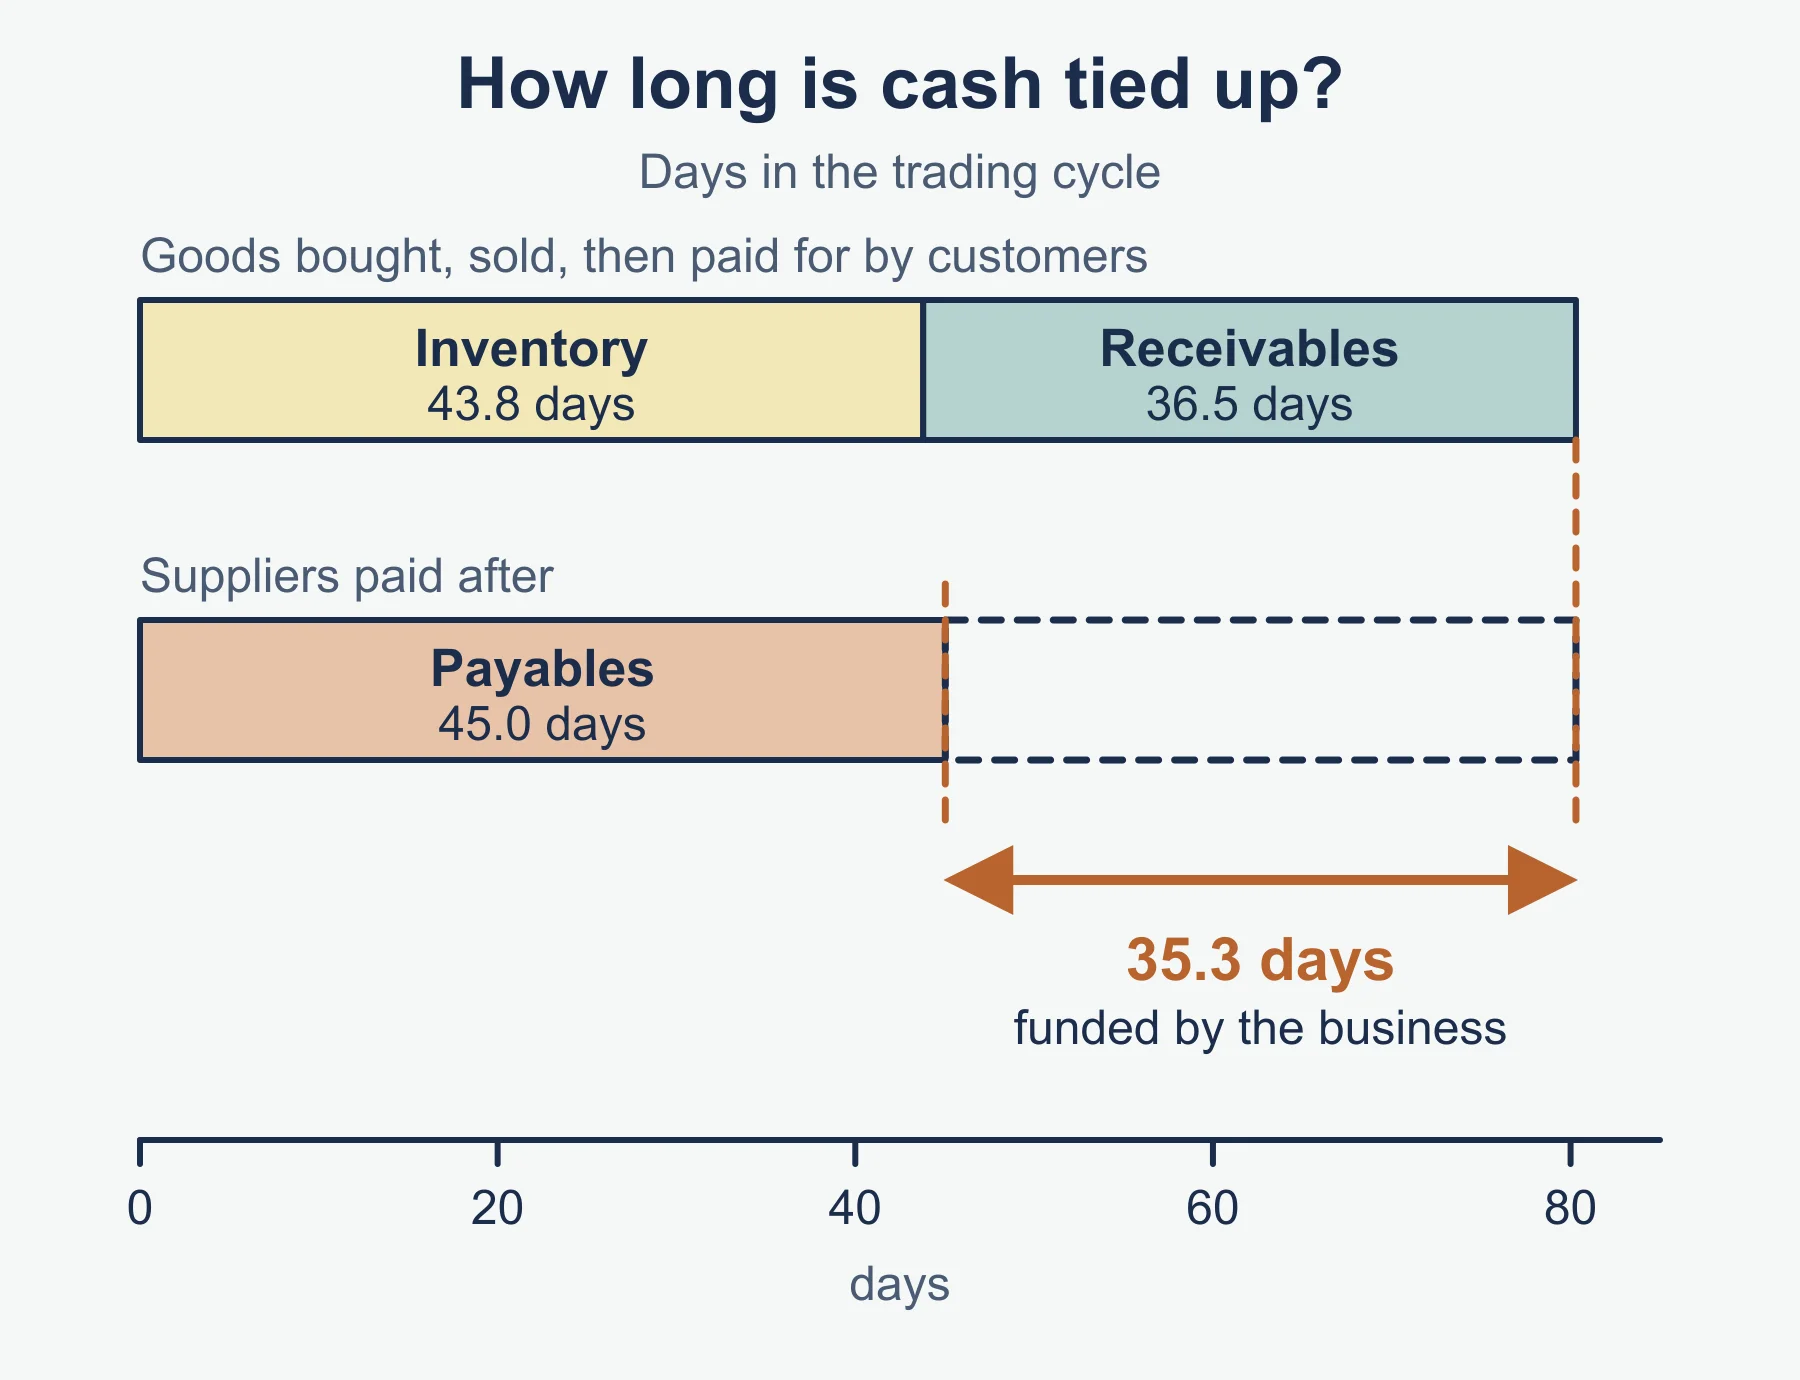
| Trade receivable days | How long do customers take to pay? | Efficiency |
| Trade payable days | How long does the business take to pay suppliers? | Efficiency |
The same section also asks you to appraise business performance on profitability and liquidity, to know the difference between cash and profit, and to know the limitations of ratio analysis. The last three sections of this guide cover those uses of the ratios.
The standard forms
| Measure | Standard form |
|---|---|
| Gross profit margin % | gross profit / revenue x 100 |
| Markup % | gross profit / cost of sales x 100 |
| Rate of inventory turnover | cost of sales / average inventory (times per year) |
| Profit in relation to revenue % | profit from operations / revenue x 100 |
| Return on capital employed % | profit from operations / capital employed x 100 |
| Current ratio | current assets : current liabilities |
| Liquid capital ratio | (current assets - inventory) : current liabilities |
| Trade receivable days | trade receivables / credit revenue x 365 |
| Trade payable days | trade payables / credit purchases x 365 |
Where the pieces come from:
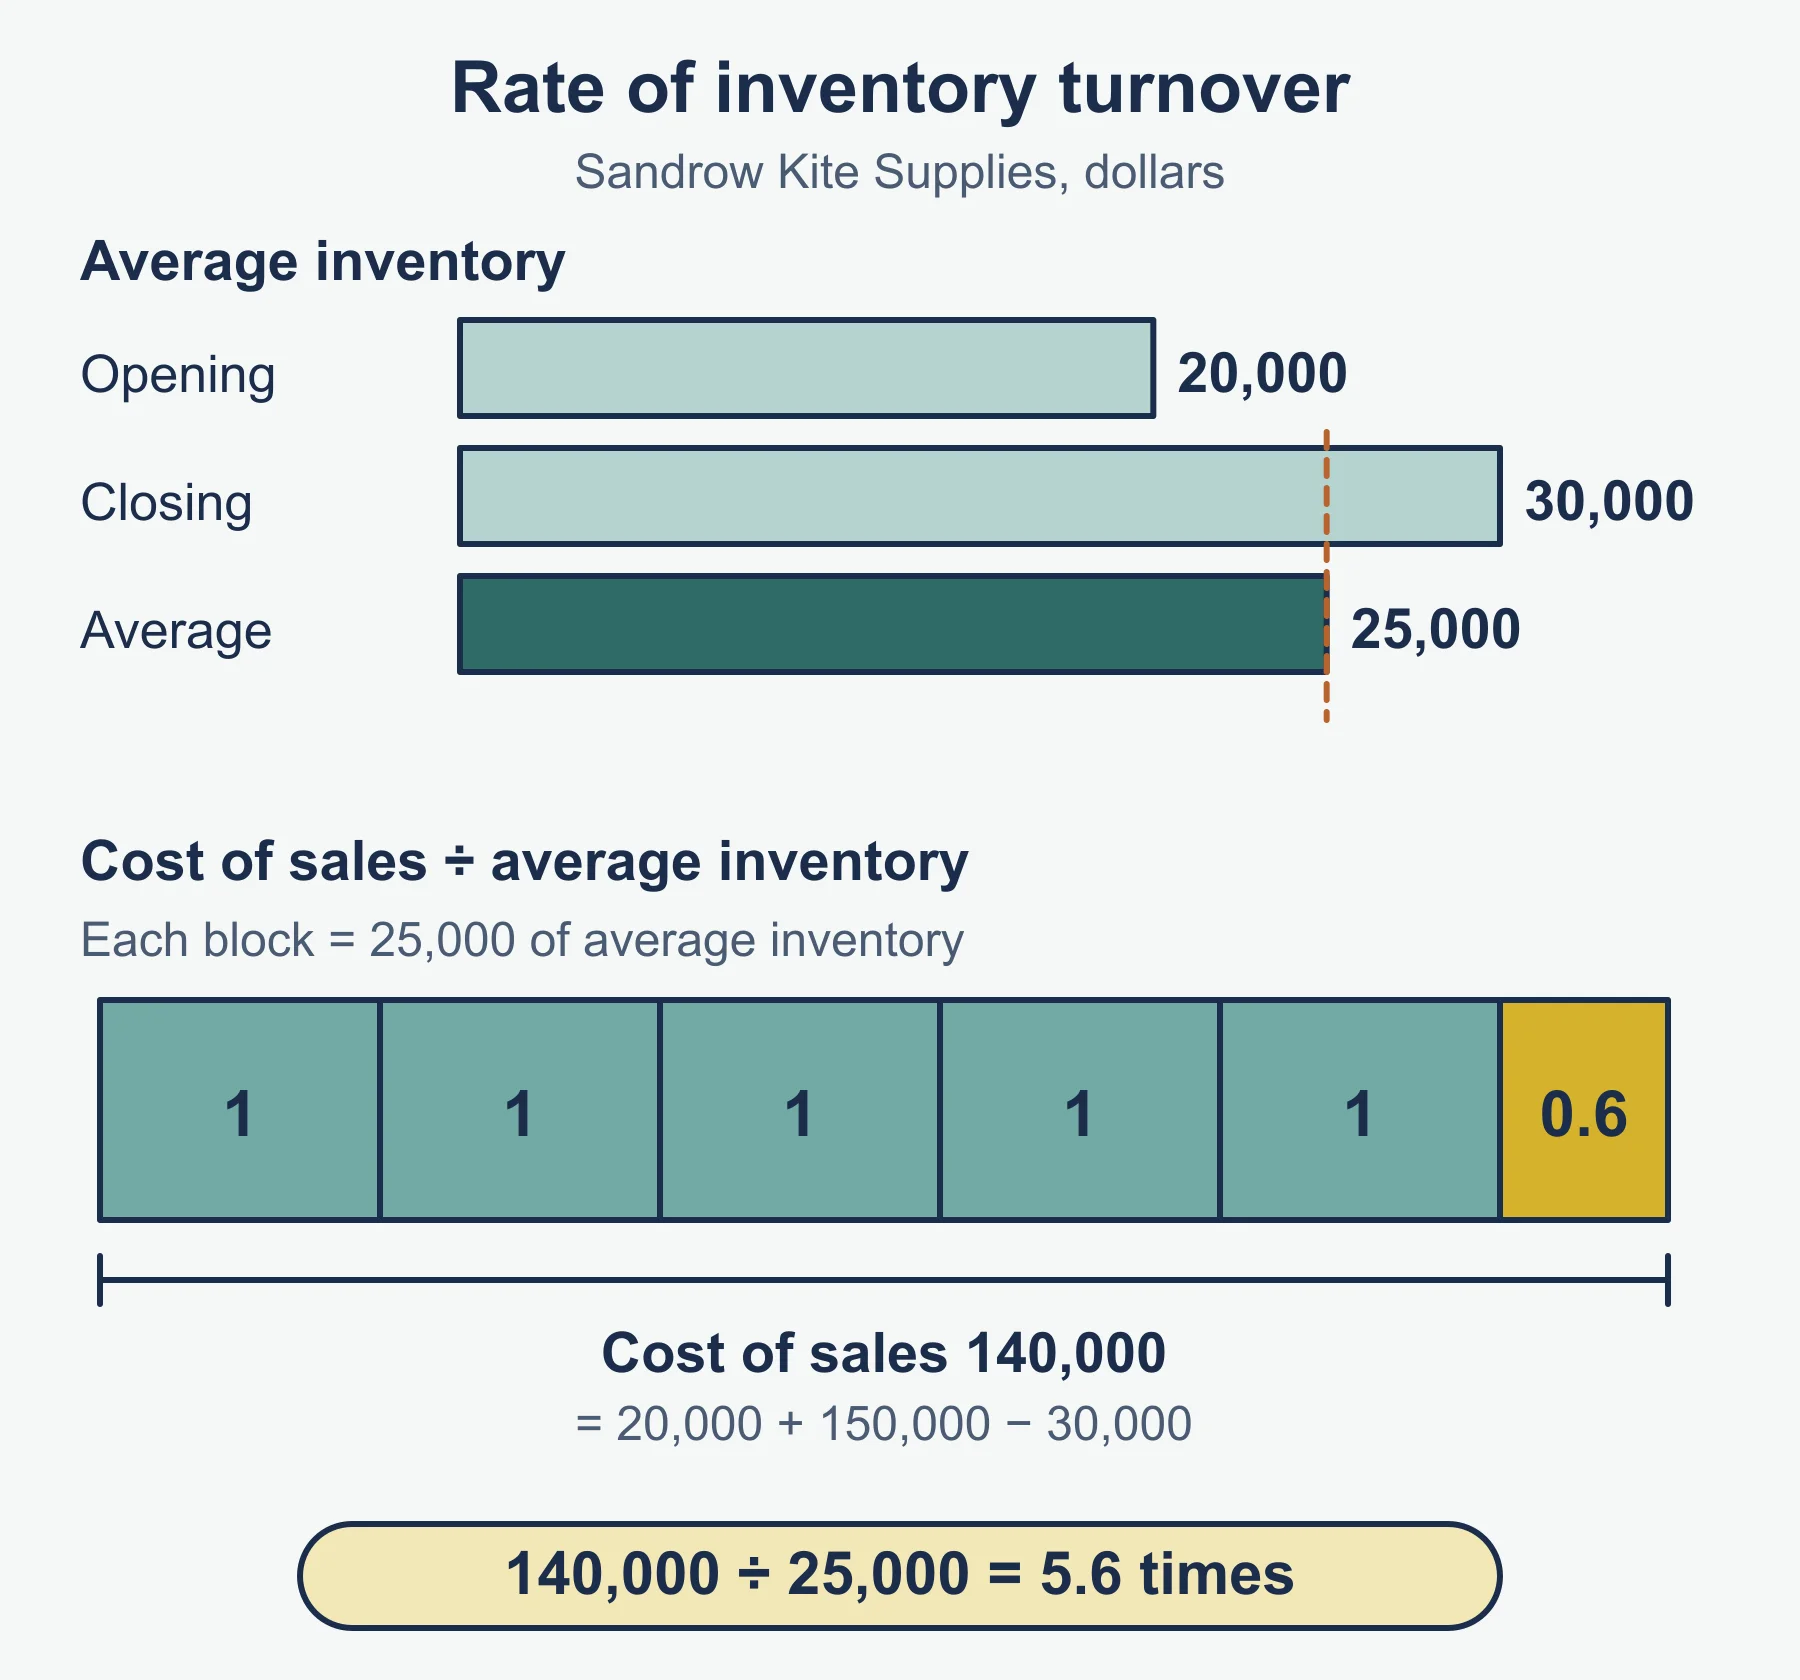
- Cost of sales = opening inventory + purchases - closing inventory.
- Average inventory = (opening inventory + closing inventory) / 2.
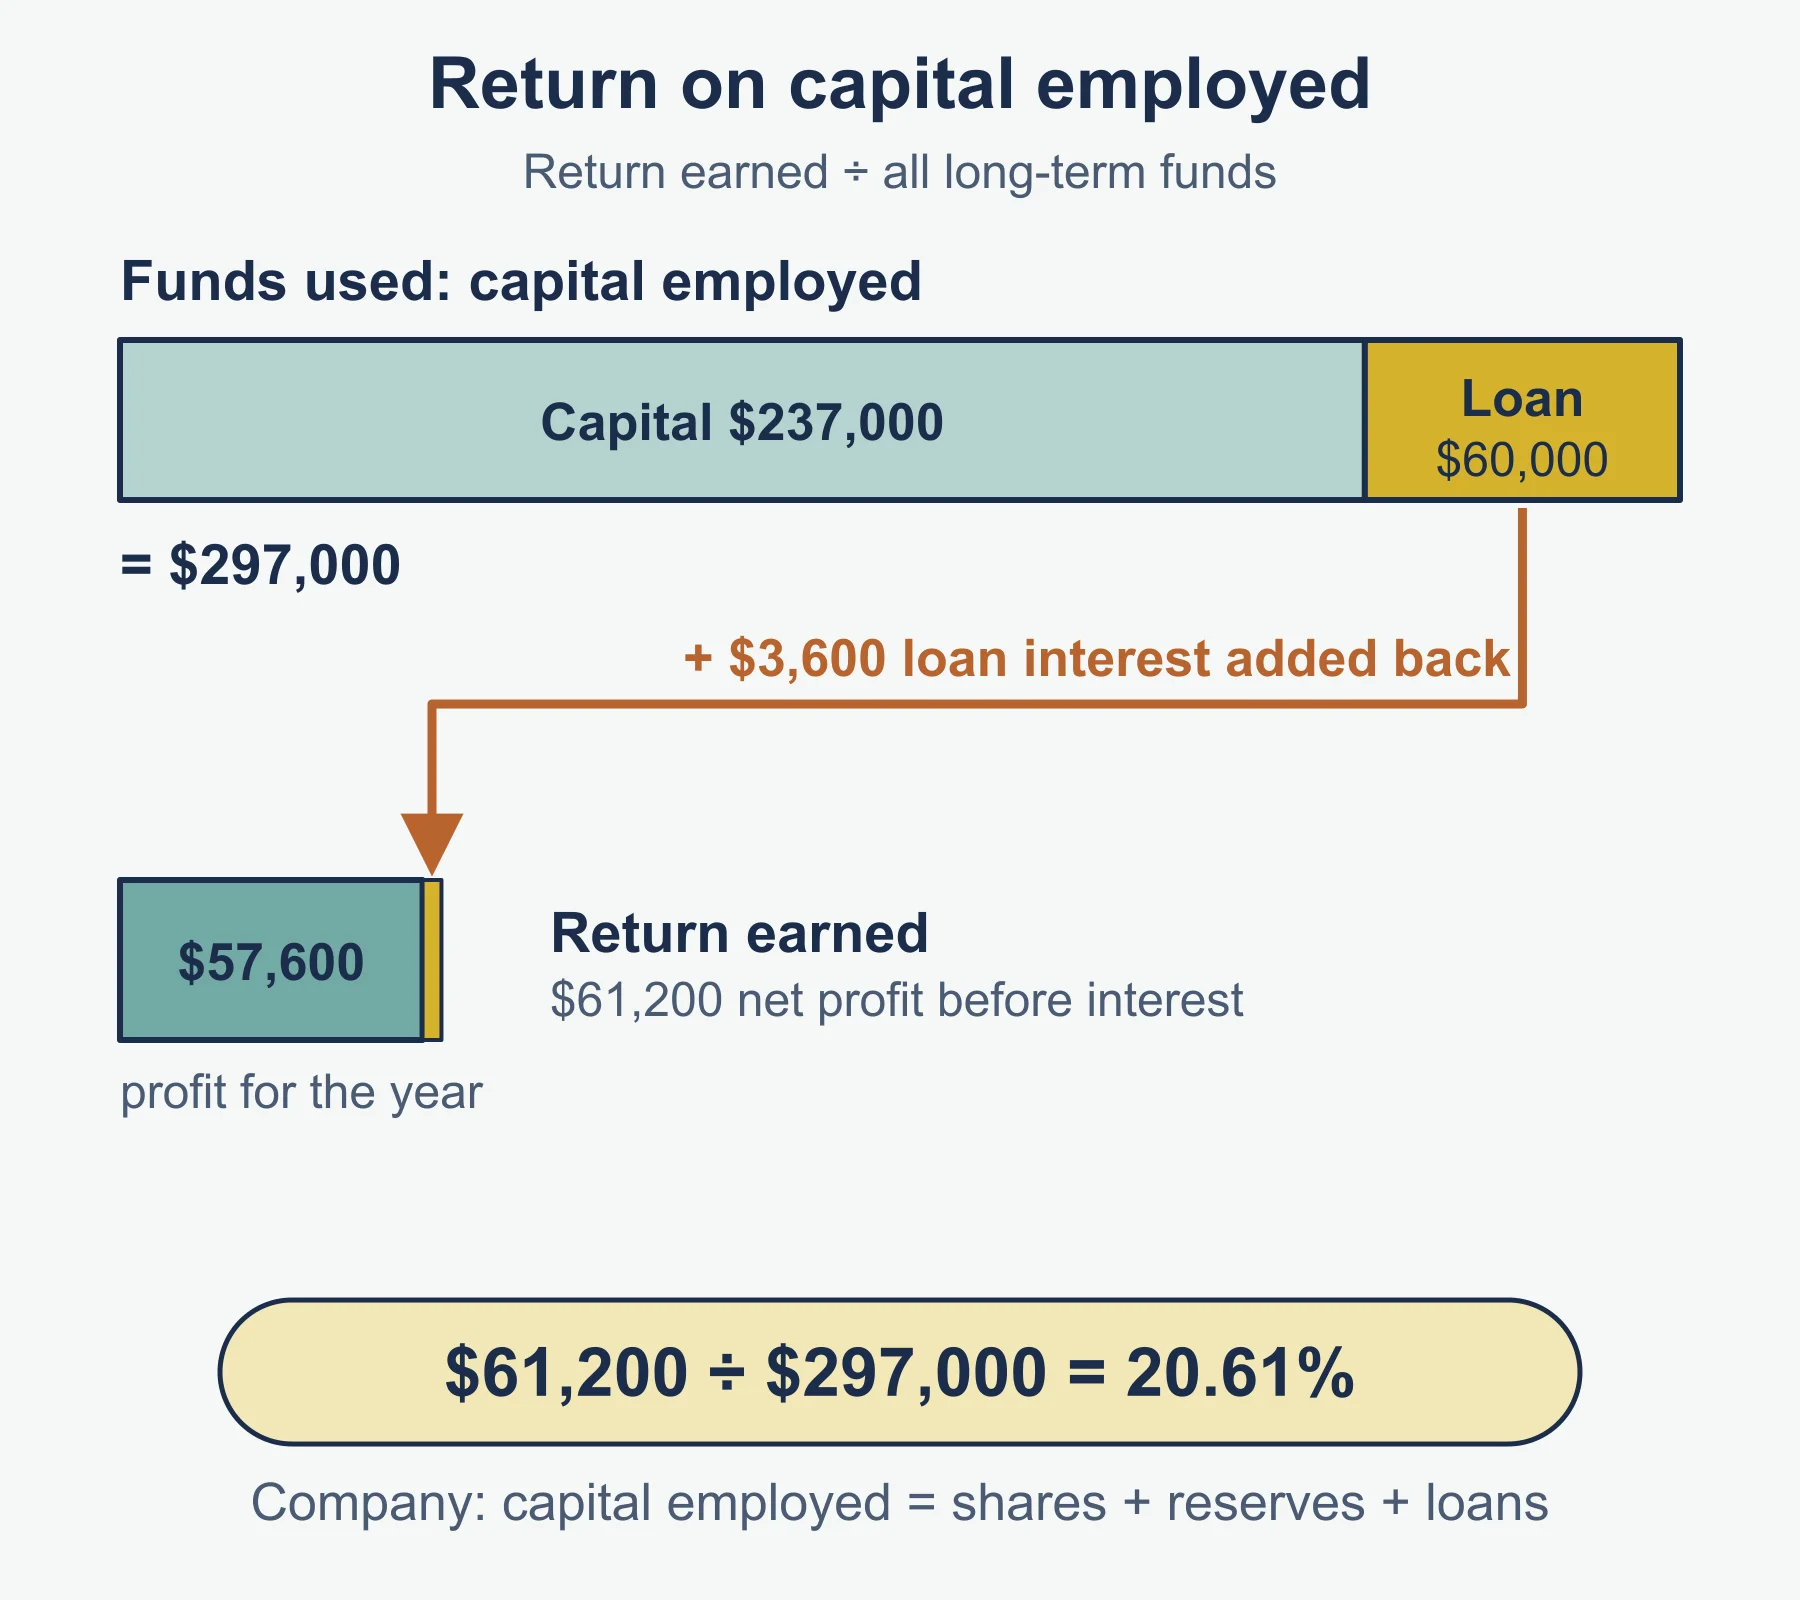
- Profit from operations is the profit before interest on loans is deducted. Profit for the year is after that interest. Profit in relation to revenue and ROCE both use profit from operations, as OxfordAQA’s own 9215 mark scheme (Paper 2, May/June 2026) does. OxfordAQA’s 9215 vocabulary list defines profit from operations as the profit for the year before finance charges and taxation, and the 9215 materials give no separate version of ROCE for a sole trader.
- Capital employed = total assets - current liabilities. This equals equity plus non-current liabilities.
- Use credit revenue and credit purchases for the days measures. If the question only gives total revenue, say that you have used it.
Worked example: one business, all nine measures
Sandrow Kite Supplies has these figures for the year ended 30 June. Total revenue was 240,000, of which 180,000 was on credit. Opening inventory was 20,000, purchases were 150,000 (120,000 on credit) and closing inventory was 30,000. Operating expenses were 60,000 and loan interest was 4,000.
Statement of financial position extract at 30 June:
| Item | Amount |
|---|---|
| Non-current assets | 120,000 |
| Inventory | 30,000 |
| Trade receivables | 27,000 |
| Bank | 9,000 |
| Current assets | 66,000 |
| Trade payables | 22,000 |
| Other payables | 8,000 |
| Current liabilities | 30,000 |
| Non-current liabilities (loan) | 40,000 |
Step 1: the income statement figures.
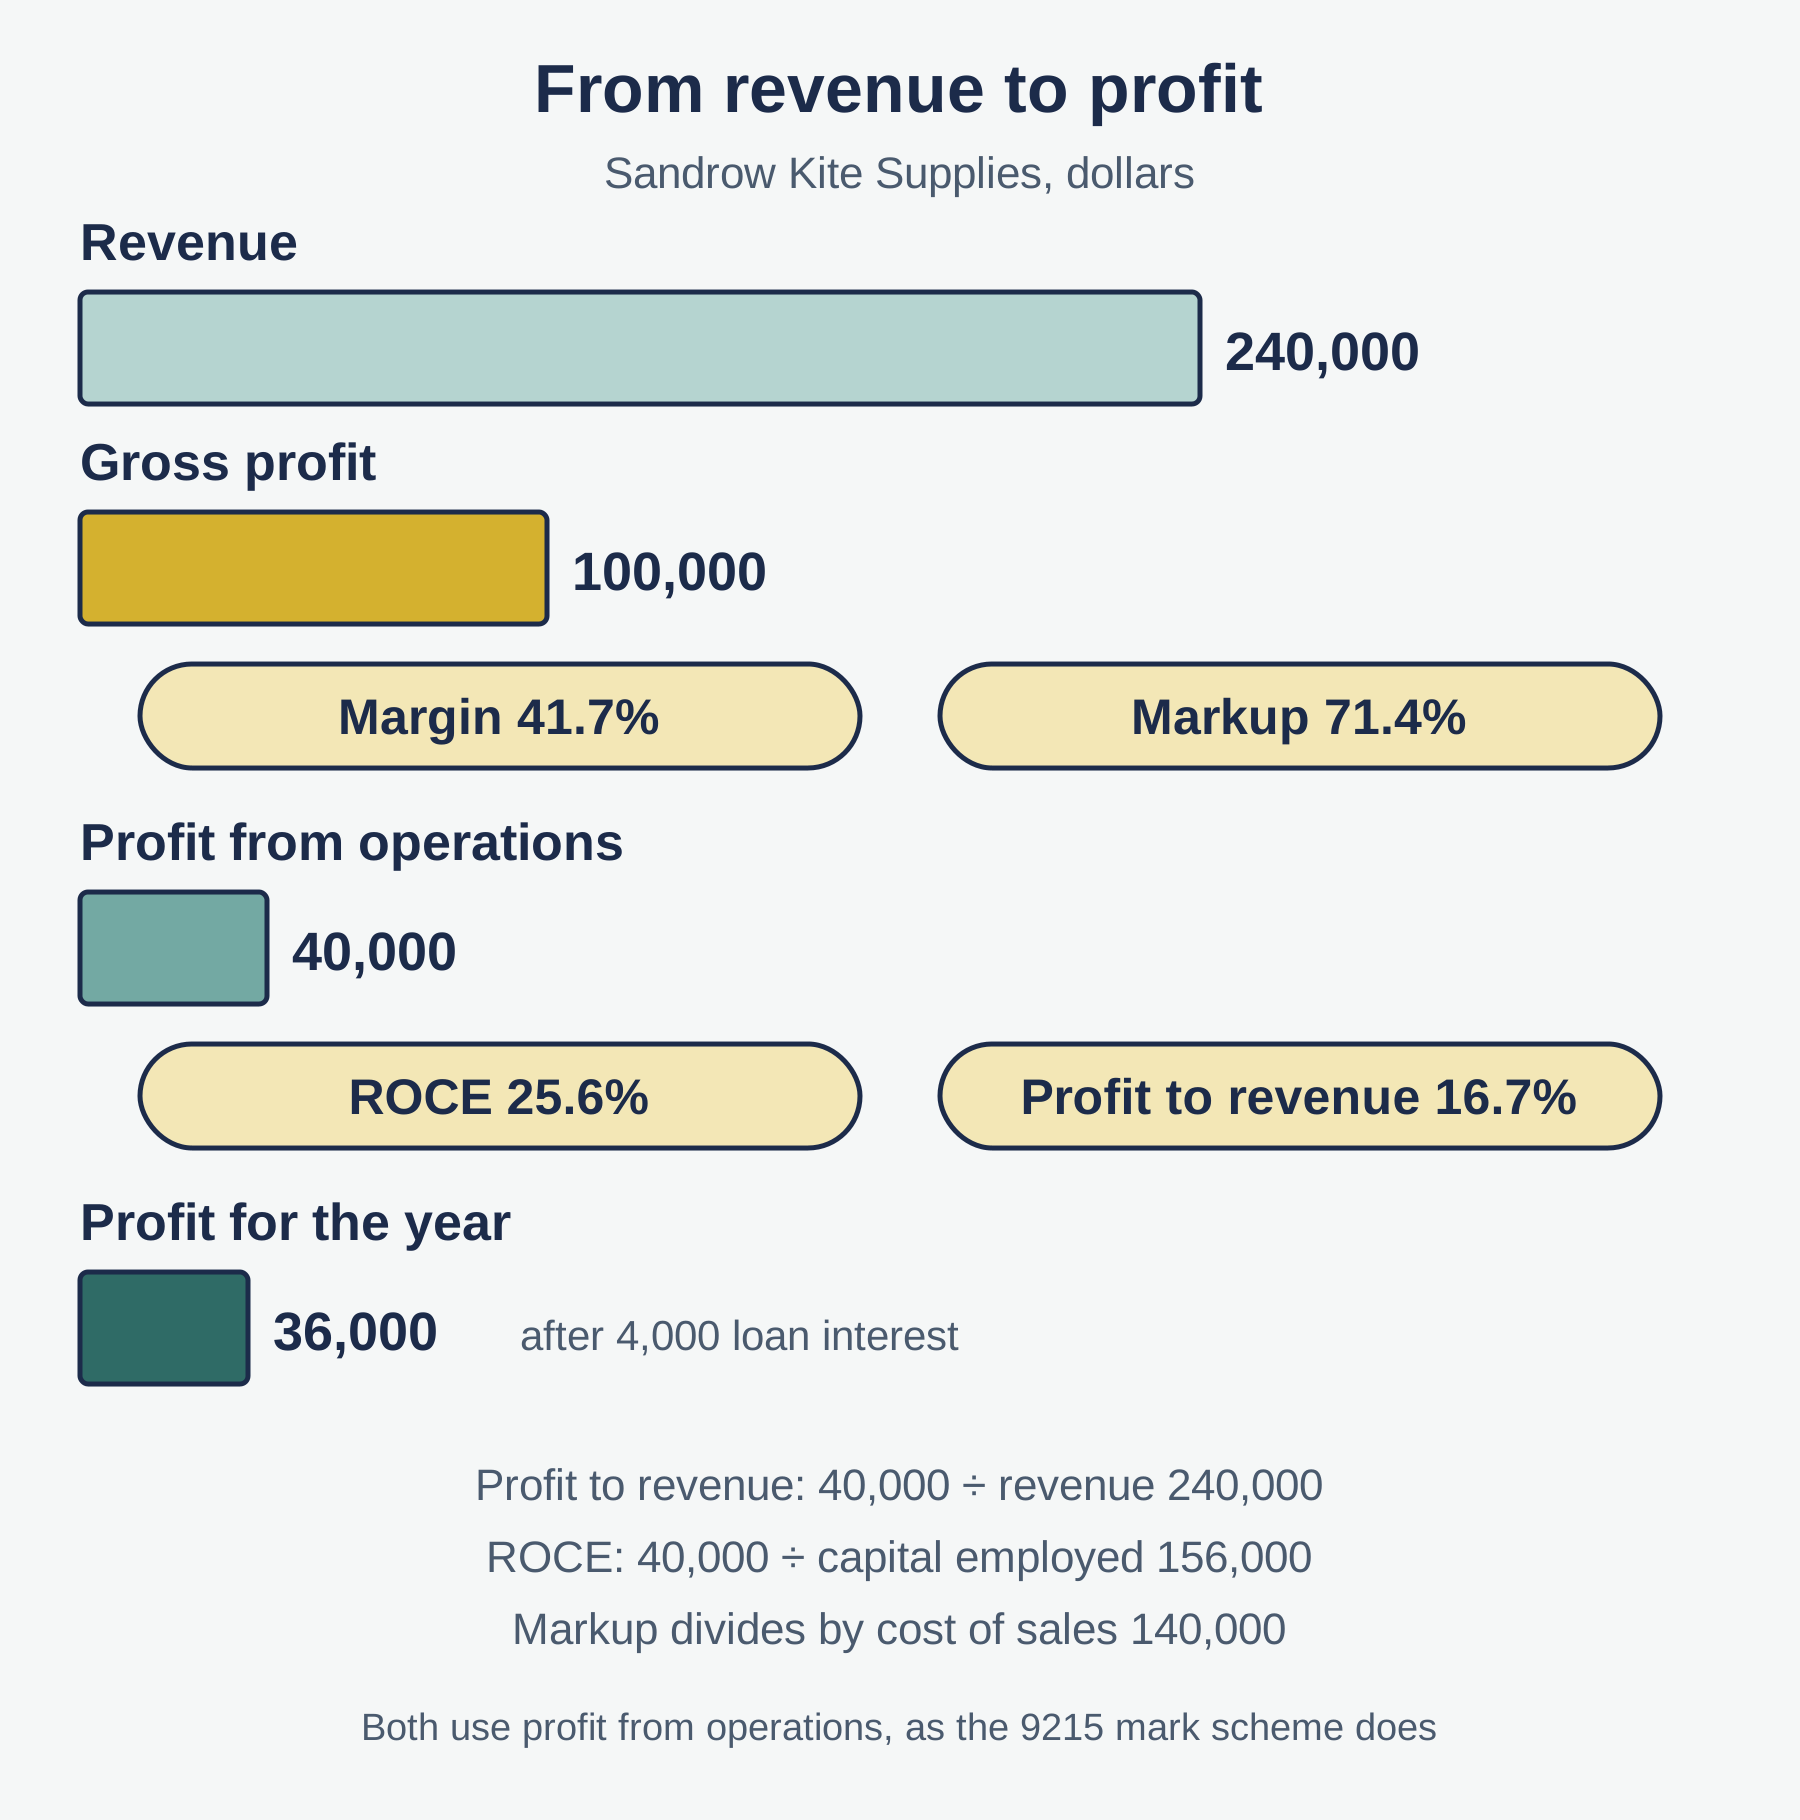
- Cost of sales = 20,000 + 150,000 - 30,000 = 140,000.
- Gross profit = 240,000 - 140,000 = 100,000.
- Profit from operations = 100,000 - 60,000 = 40,000.
- Profit for the year = 40,000 - 4,000 = 36,000.
Step 2: profitability.
- Gross profit margin = 100,000 / 240,000 x 100 = 41.7%.
- Markup = 100,000 / 140,000 x 100 = 71.4%.
- Profit in relation to revenue = 40,000 / 240,000 x 100 = 16.7%.
- Capital employed = (120,000 + 66,000) - 30,000 = 156,000. Check: equity of 116,000 plus the loan of 40,000 is 156,000.
- Return on capital employed = 40,000 / 156,000 x 100 = 25.6%.
Step 3: efficiency.
- Average inventory = (20,000 + 30,000) / 2 = 25,000. Rate of inventory turnover = 140,000 / 25,000 = 5.6 times.
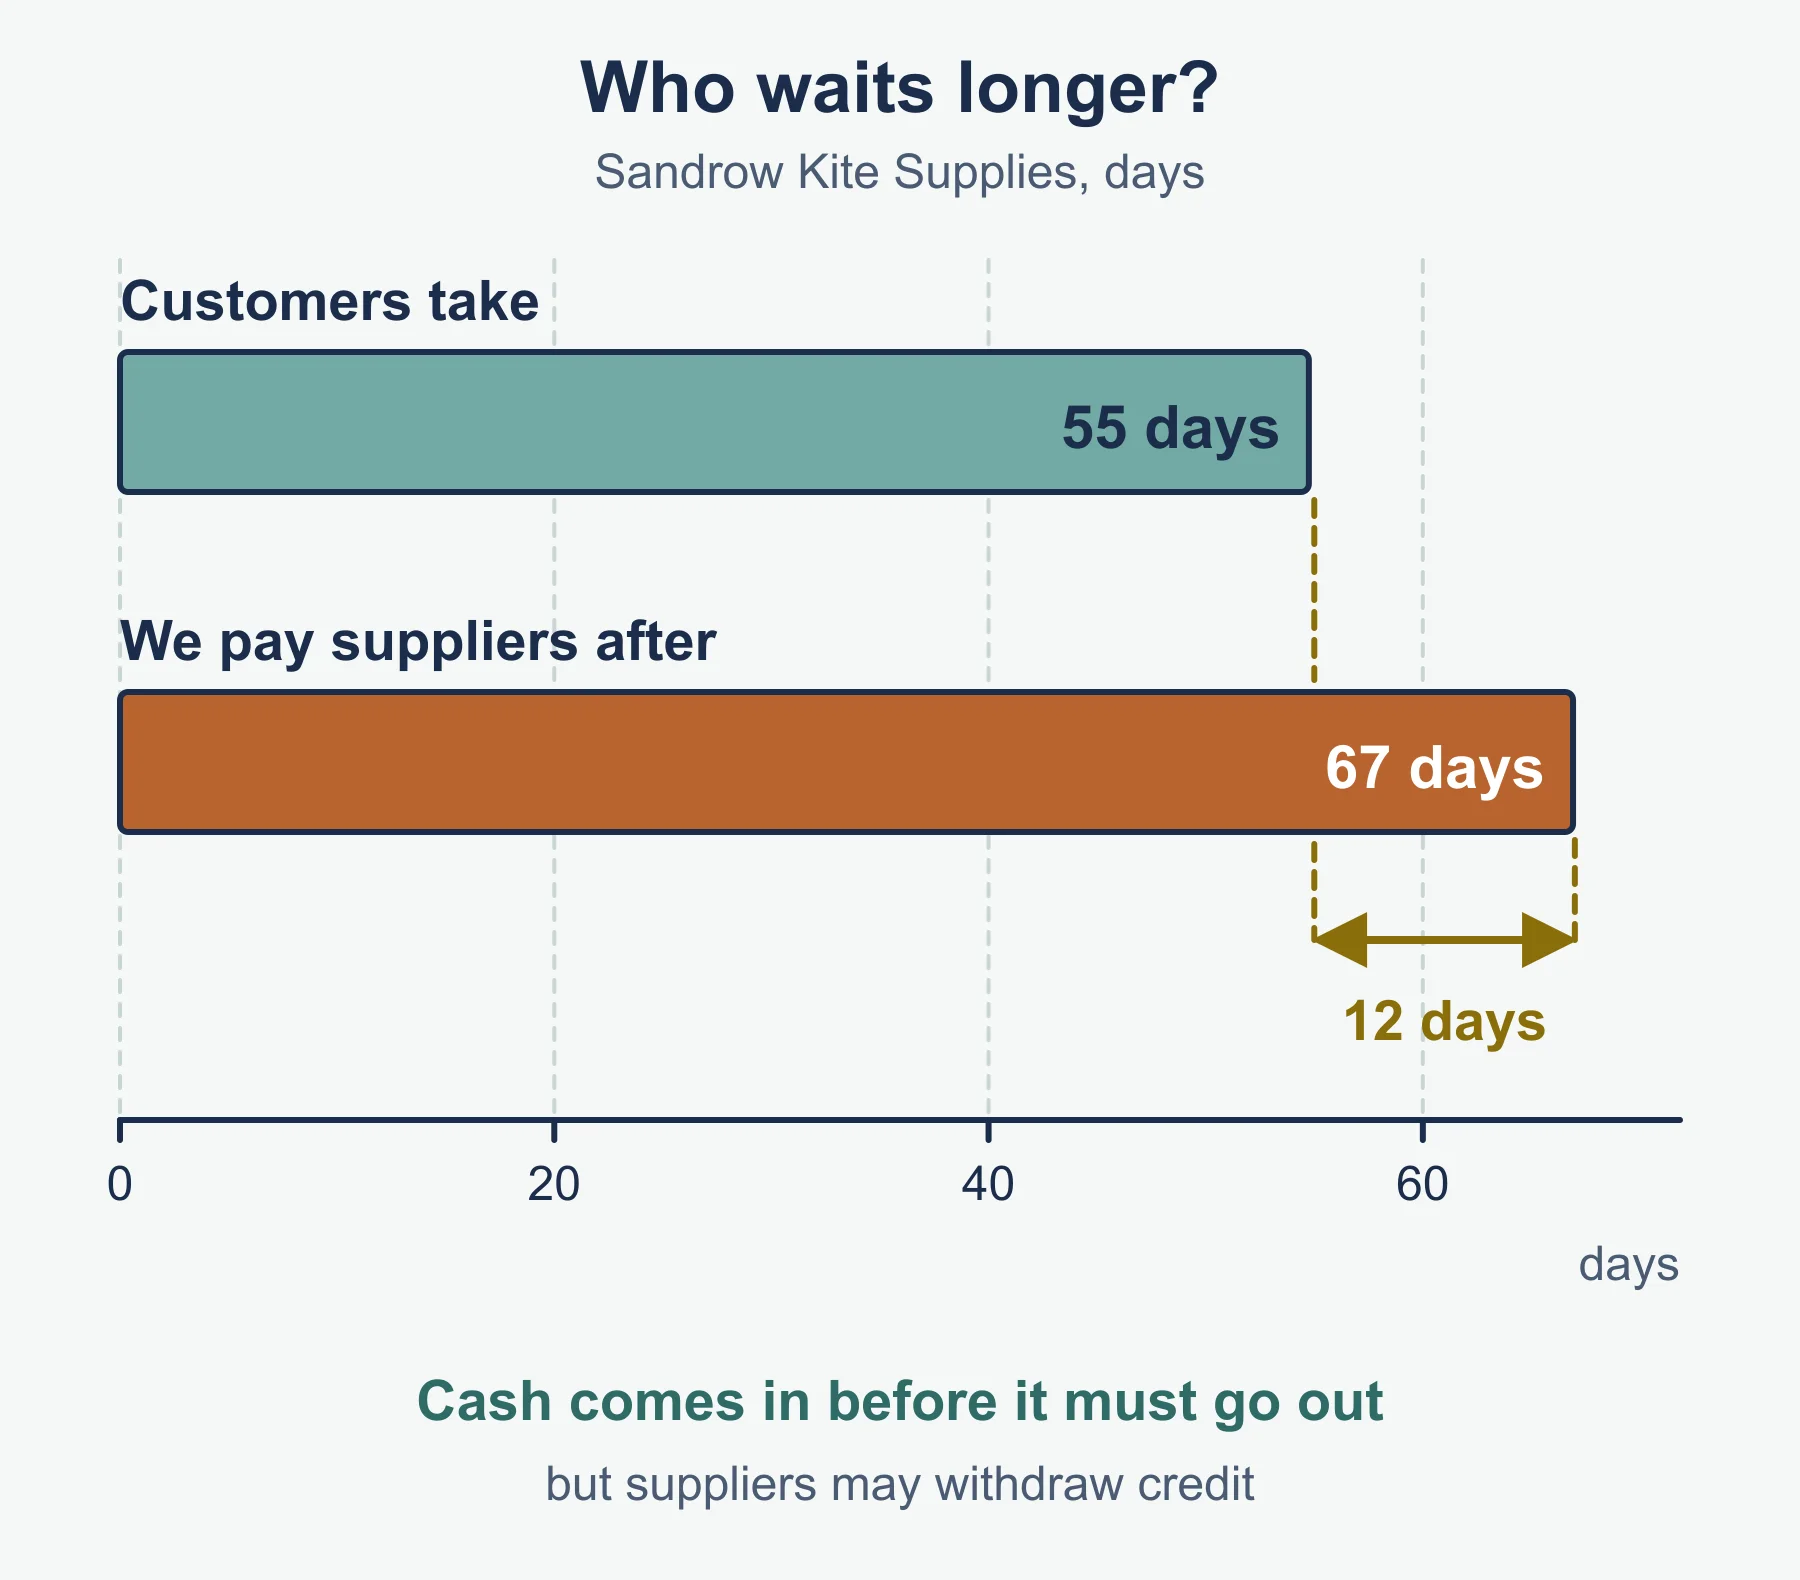
- Trade receivable days = 27,000 / 180,000 x 365 = 54.75, so about 55 days.
- Trade payable days = 22,000 / 120,000 x 365 = 66.9, so about 67 days.
Step 4: liquidity.
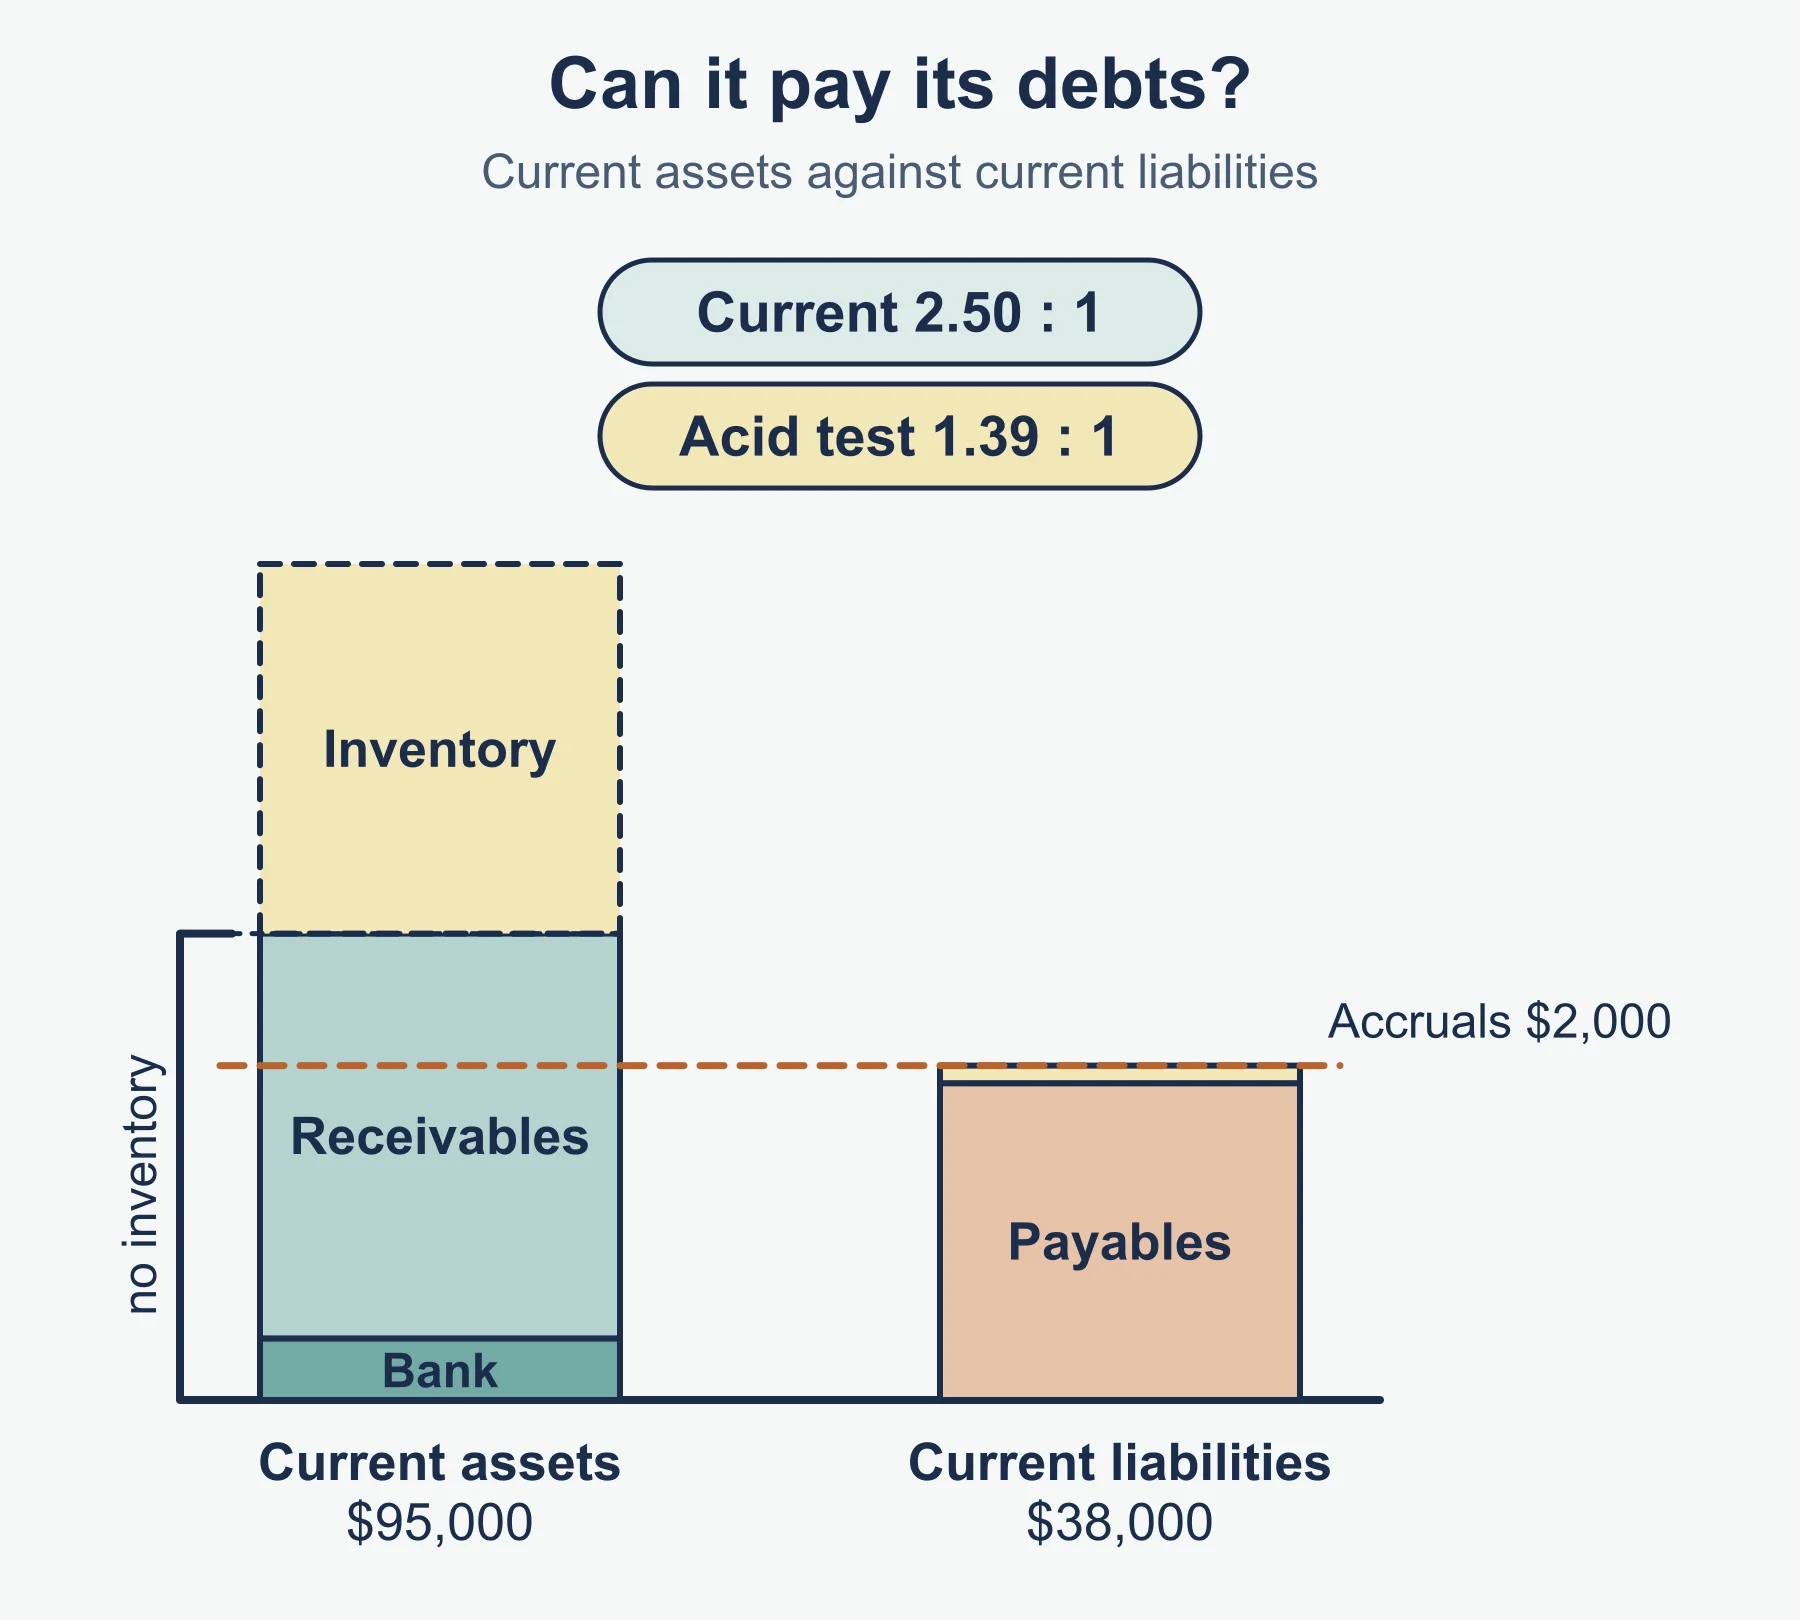
- Current ratio = 66,000 : 30,000 = 2.2 : 1.
- Liquid capital ratio = (66,000 - 30,000) : 30,000 = 1.2 : 1.
Reading the results. Customers take about 55 days to pay but the business takes about 67 days to pay its own suppliers. That helps cash, but suppliers may withdraw credit terms if the gap grows. A current ratio of 2.2 : 1 looks safe, and the liquid capital ratio of 1.2 : 1 shows the business does not rely on selling kites to meet its short-term debts.
Markup and margin are not the same
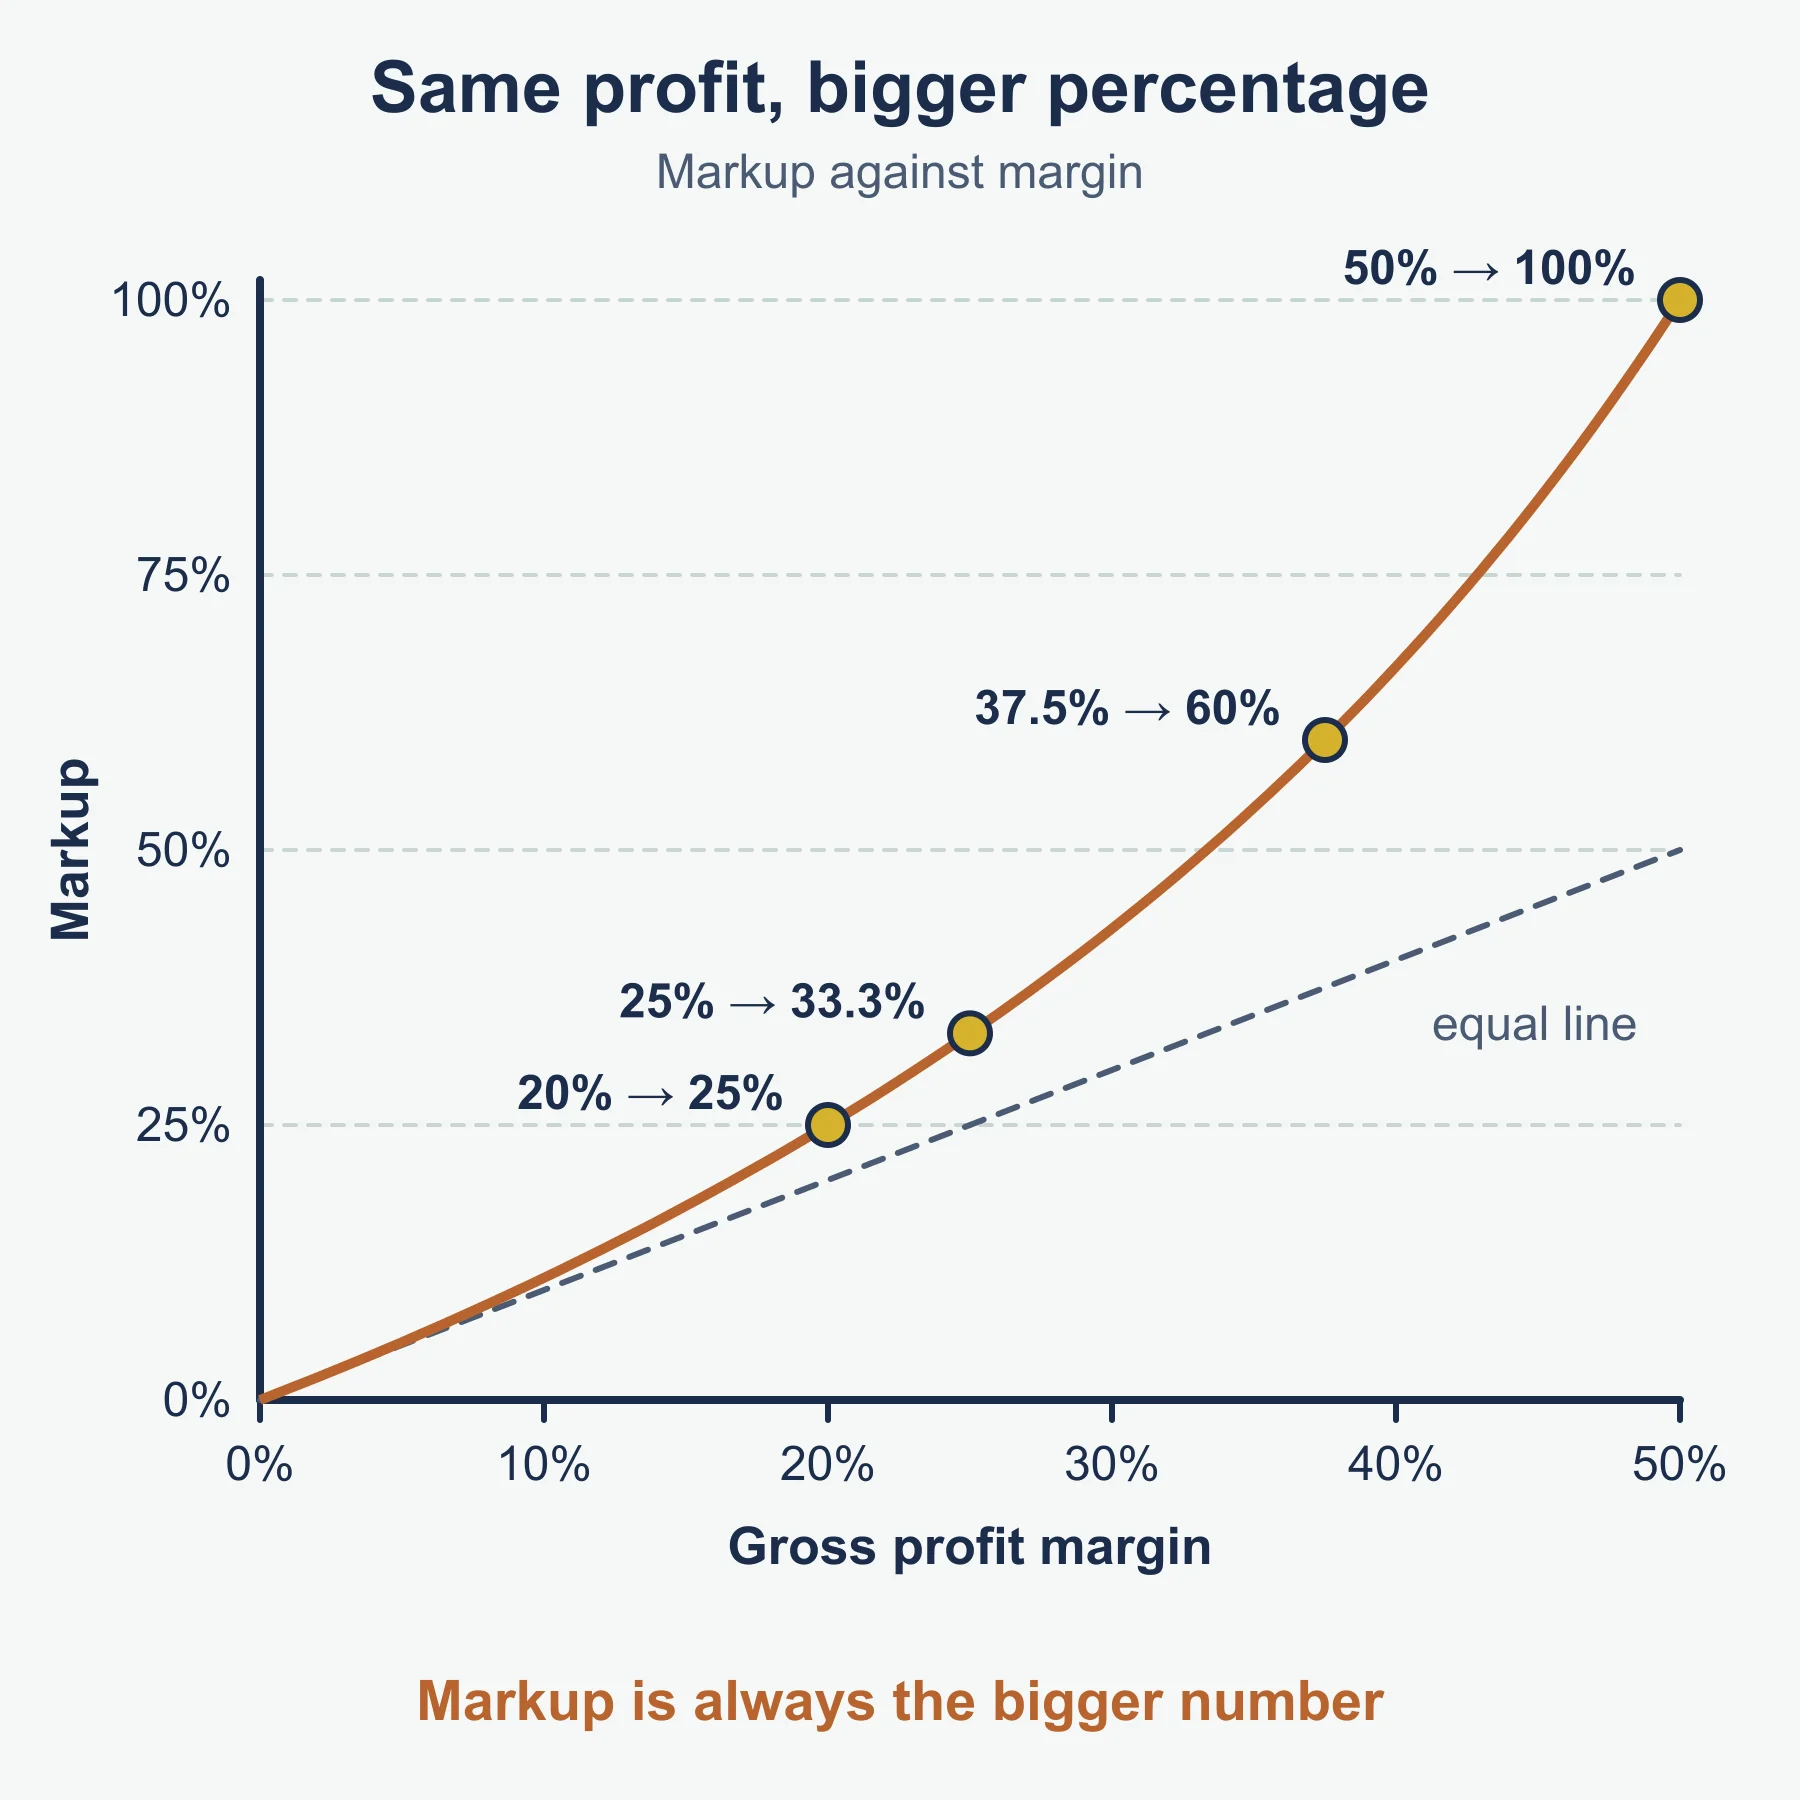
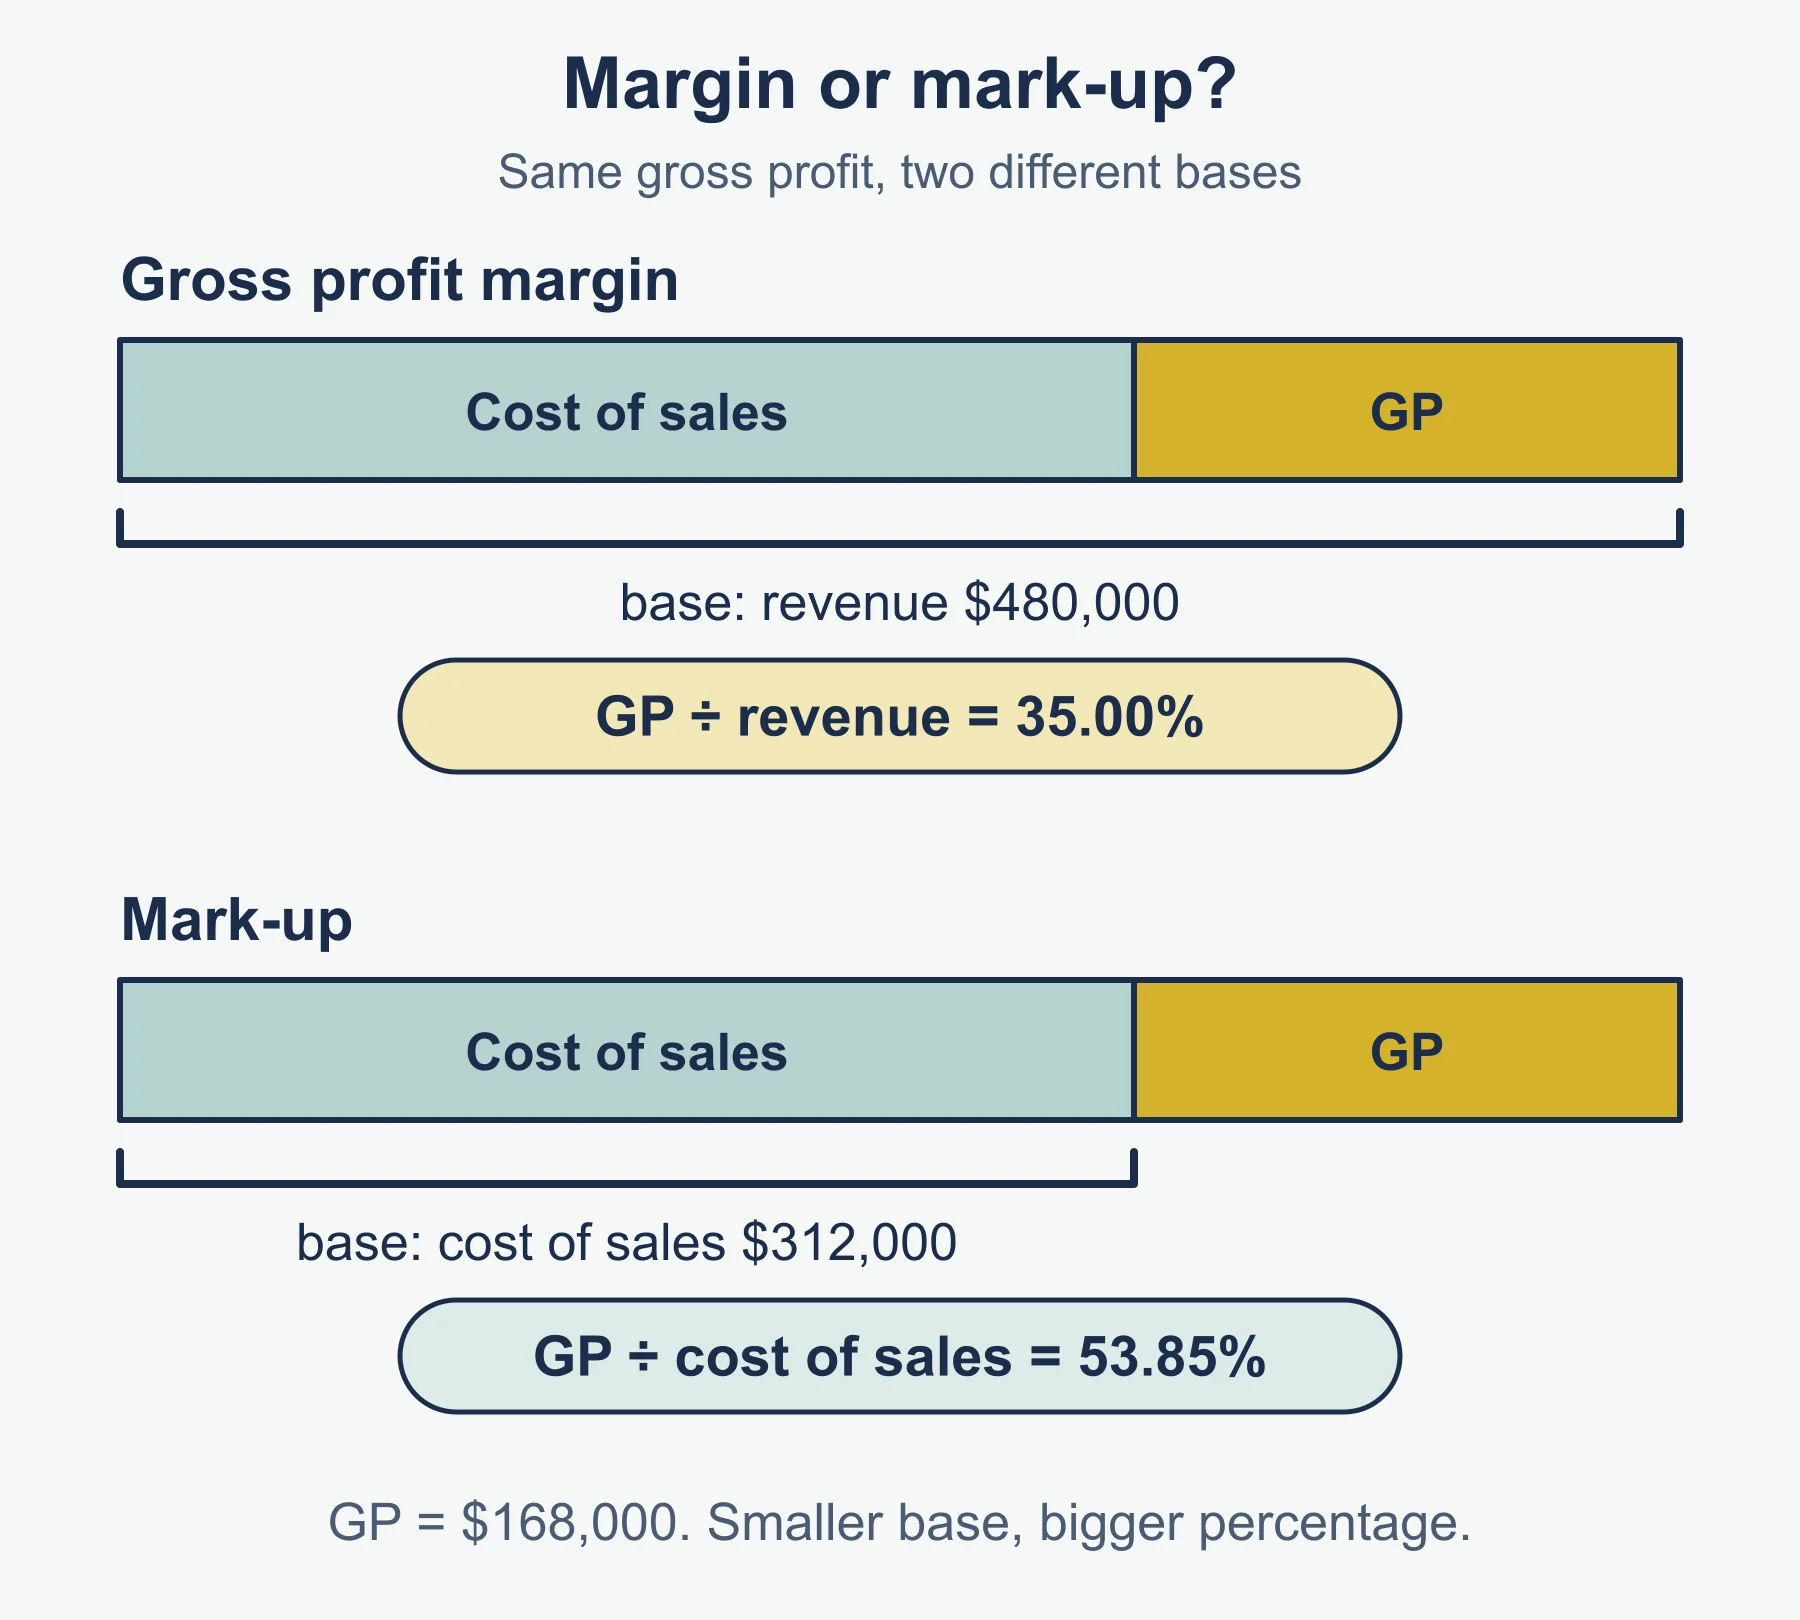
Both use gross profit. Margin divides by revenue. Markup divides by cost of sales. For the same trading, markup is always the bigger number.
| Gross profit margin | Markup |
|---|---|
| 20% | 25% |
| 25% | 33.3% |
| 37.5% | 60% |
| 50% | 100% |
To convert, imagine revenue of 100. A margin of 20% means gross profit of 20 and cost of sales of 80, so markup is 20 / 80 = 25%. A markup of 60% means cost of 100 and gross profit of 60, so revenue is 160 and margin is 60 / 160 = 37.5%.
Finding a missing figure uses the same idea. A trader has a 25% margin and cost of sales of 45,000. Cost of sales is 75% of revenue, so revenue is 45,000 / 0.75 = 60,000 and gross profit is 15,000.
Interpreting each measure
A single ratio means little. Compare it with the same business last year, a budget, or a similar business, and say why it moved. These are the usual readings.
| Measure | A higher figure usually means | Possible causes of a change |
|---|---|---|
| Gross profit margin | More profit kept from each sale | Higher selling prices, cheaper suppliers, or the reverse if it falls; changes in sales mix |
| Markup | A larger addition to cost | Same causes as margin |
| Profit in relation to revenue | Expenses are well controlled | Rent, wages, advertising or loan interest rising faster than revenue |
| Return on capital employed | Capital is earning a better return | New assets not yet earning, falling profit, or more borrowing |
| Rate of inventory turnover | Inventory sells faster, with less cash tied up | Promotions or tighter buying; too high can mean stock-outs |
| Current ratio | More cover for short-term debts | Too high can mean idle cash or slow-moving inventory |
| Liquid capital ratio | More cover without selling inventory | A figure below 1 : 1 suggests reliance on selling inventory |
| Receivable days | Customers pay more slowly | Weak credit control or generous terms |
| Payable days | The business pays suppliers more slowly | Good for cash, but it risks supplier goodwill |
Higher is not always better. A very high payable days figure may mean the business is struggling to pay. A very low current ratio may mean it cannot. The reading depends on the measure and the situation.
Cash is not profit
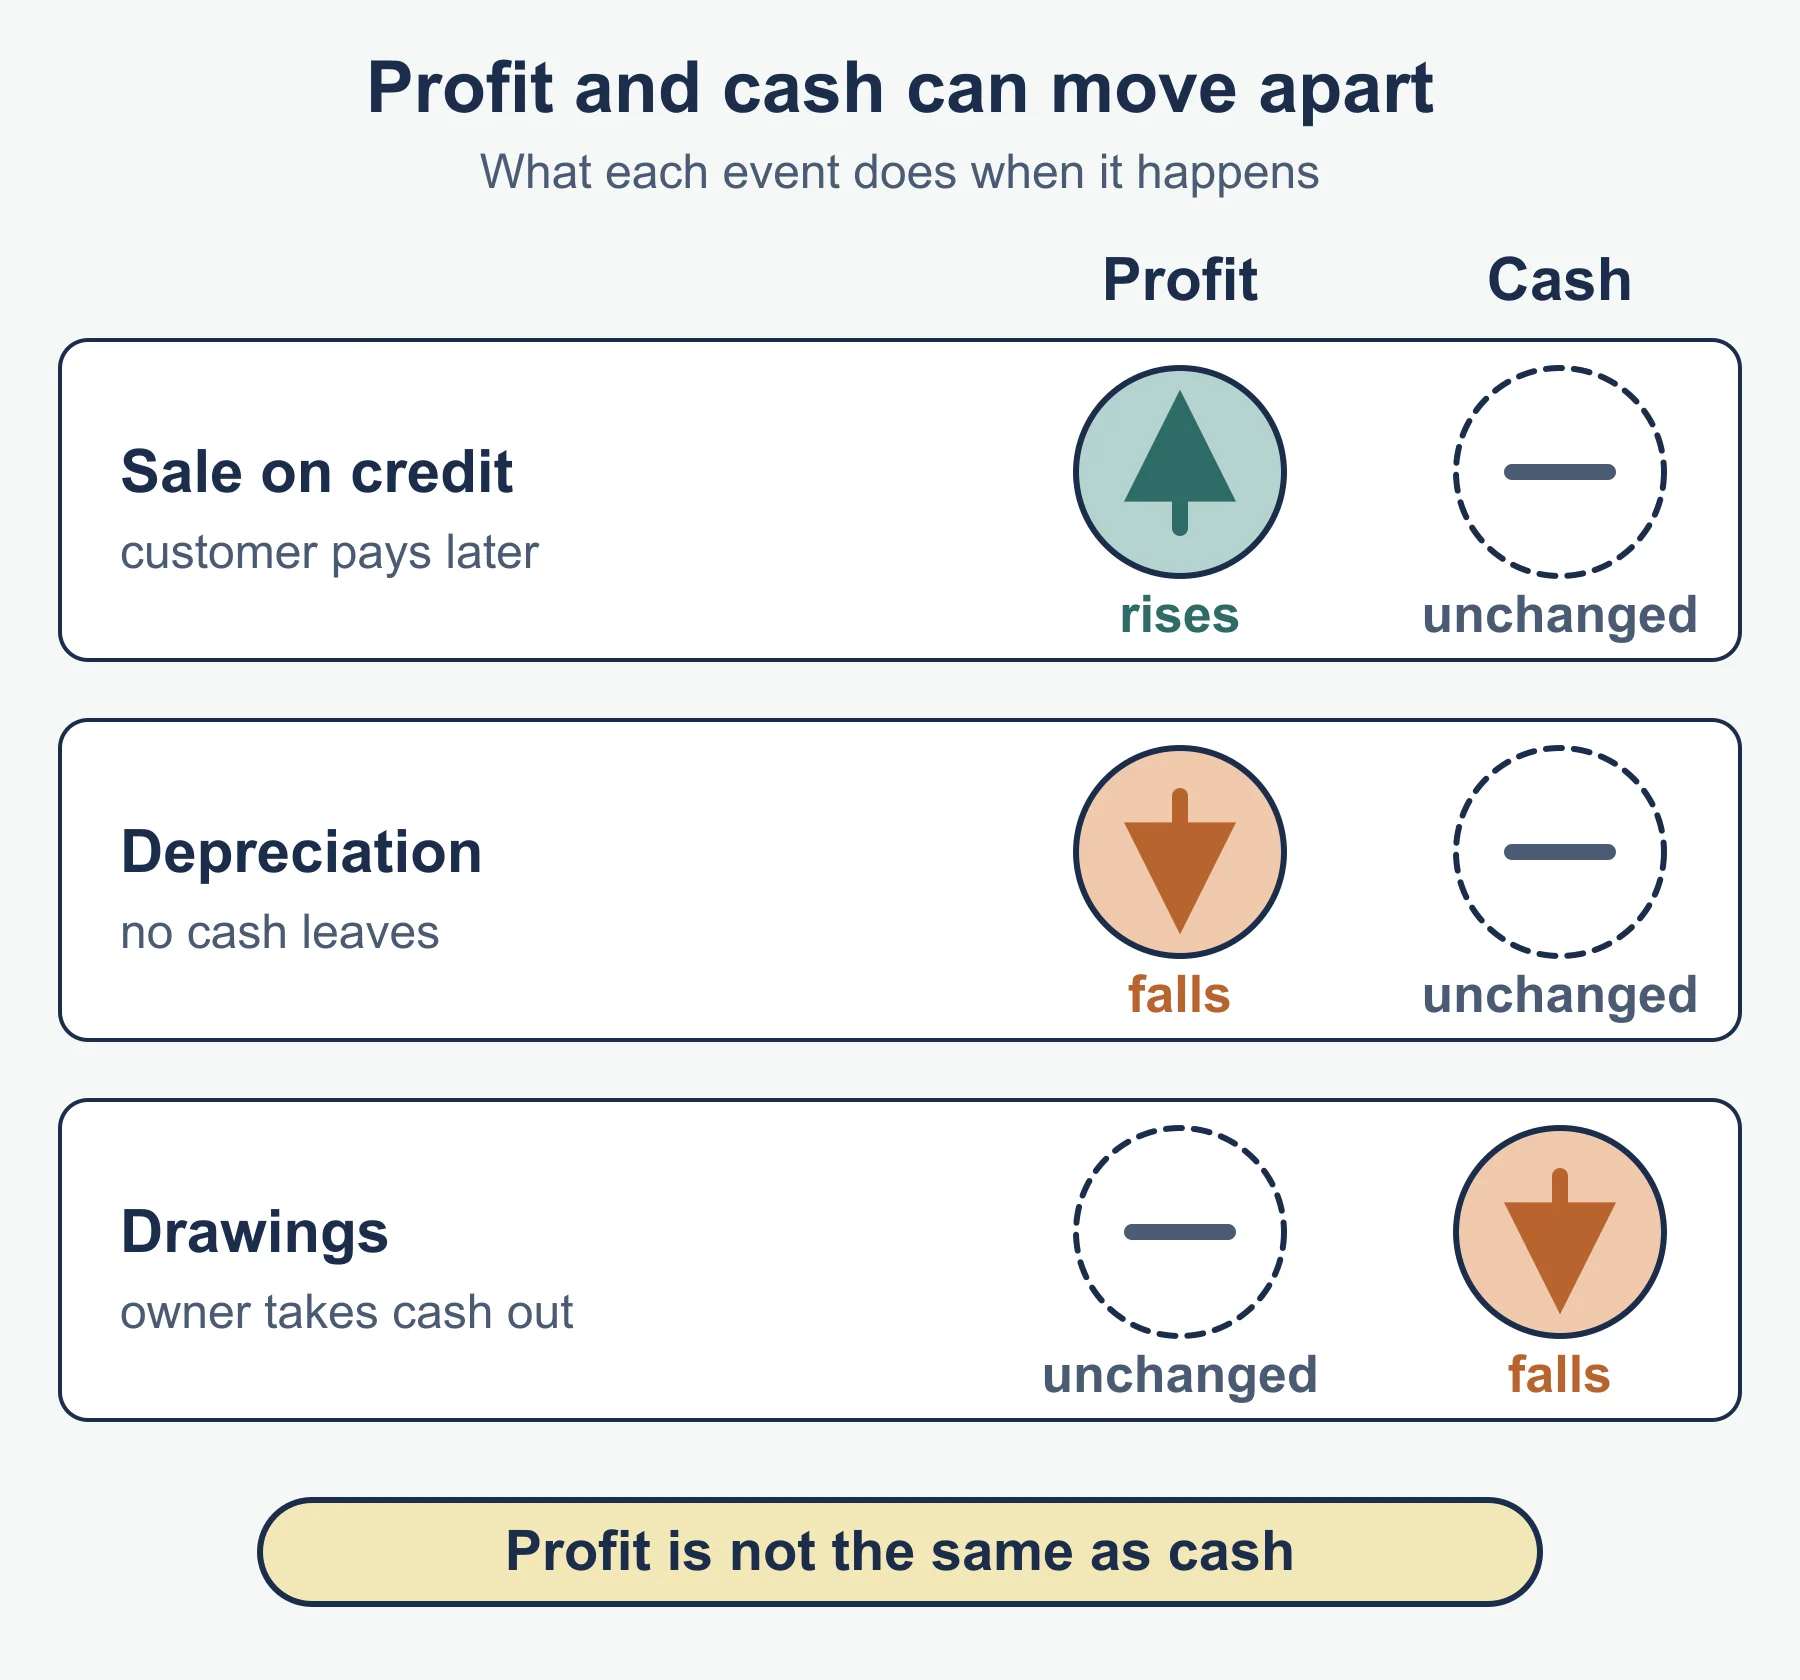
Profit is revenue minus expenses for the period, recognised when earned or incurred. Cash is money moving in and out of the bank. They differ because of credit sales, credit purchases, buying non-current assets, depreciation, drawings and loan repayments.
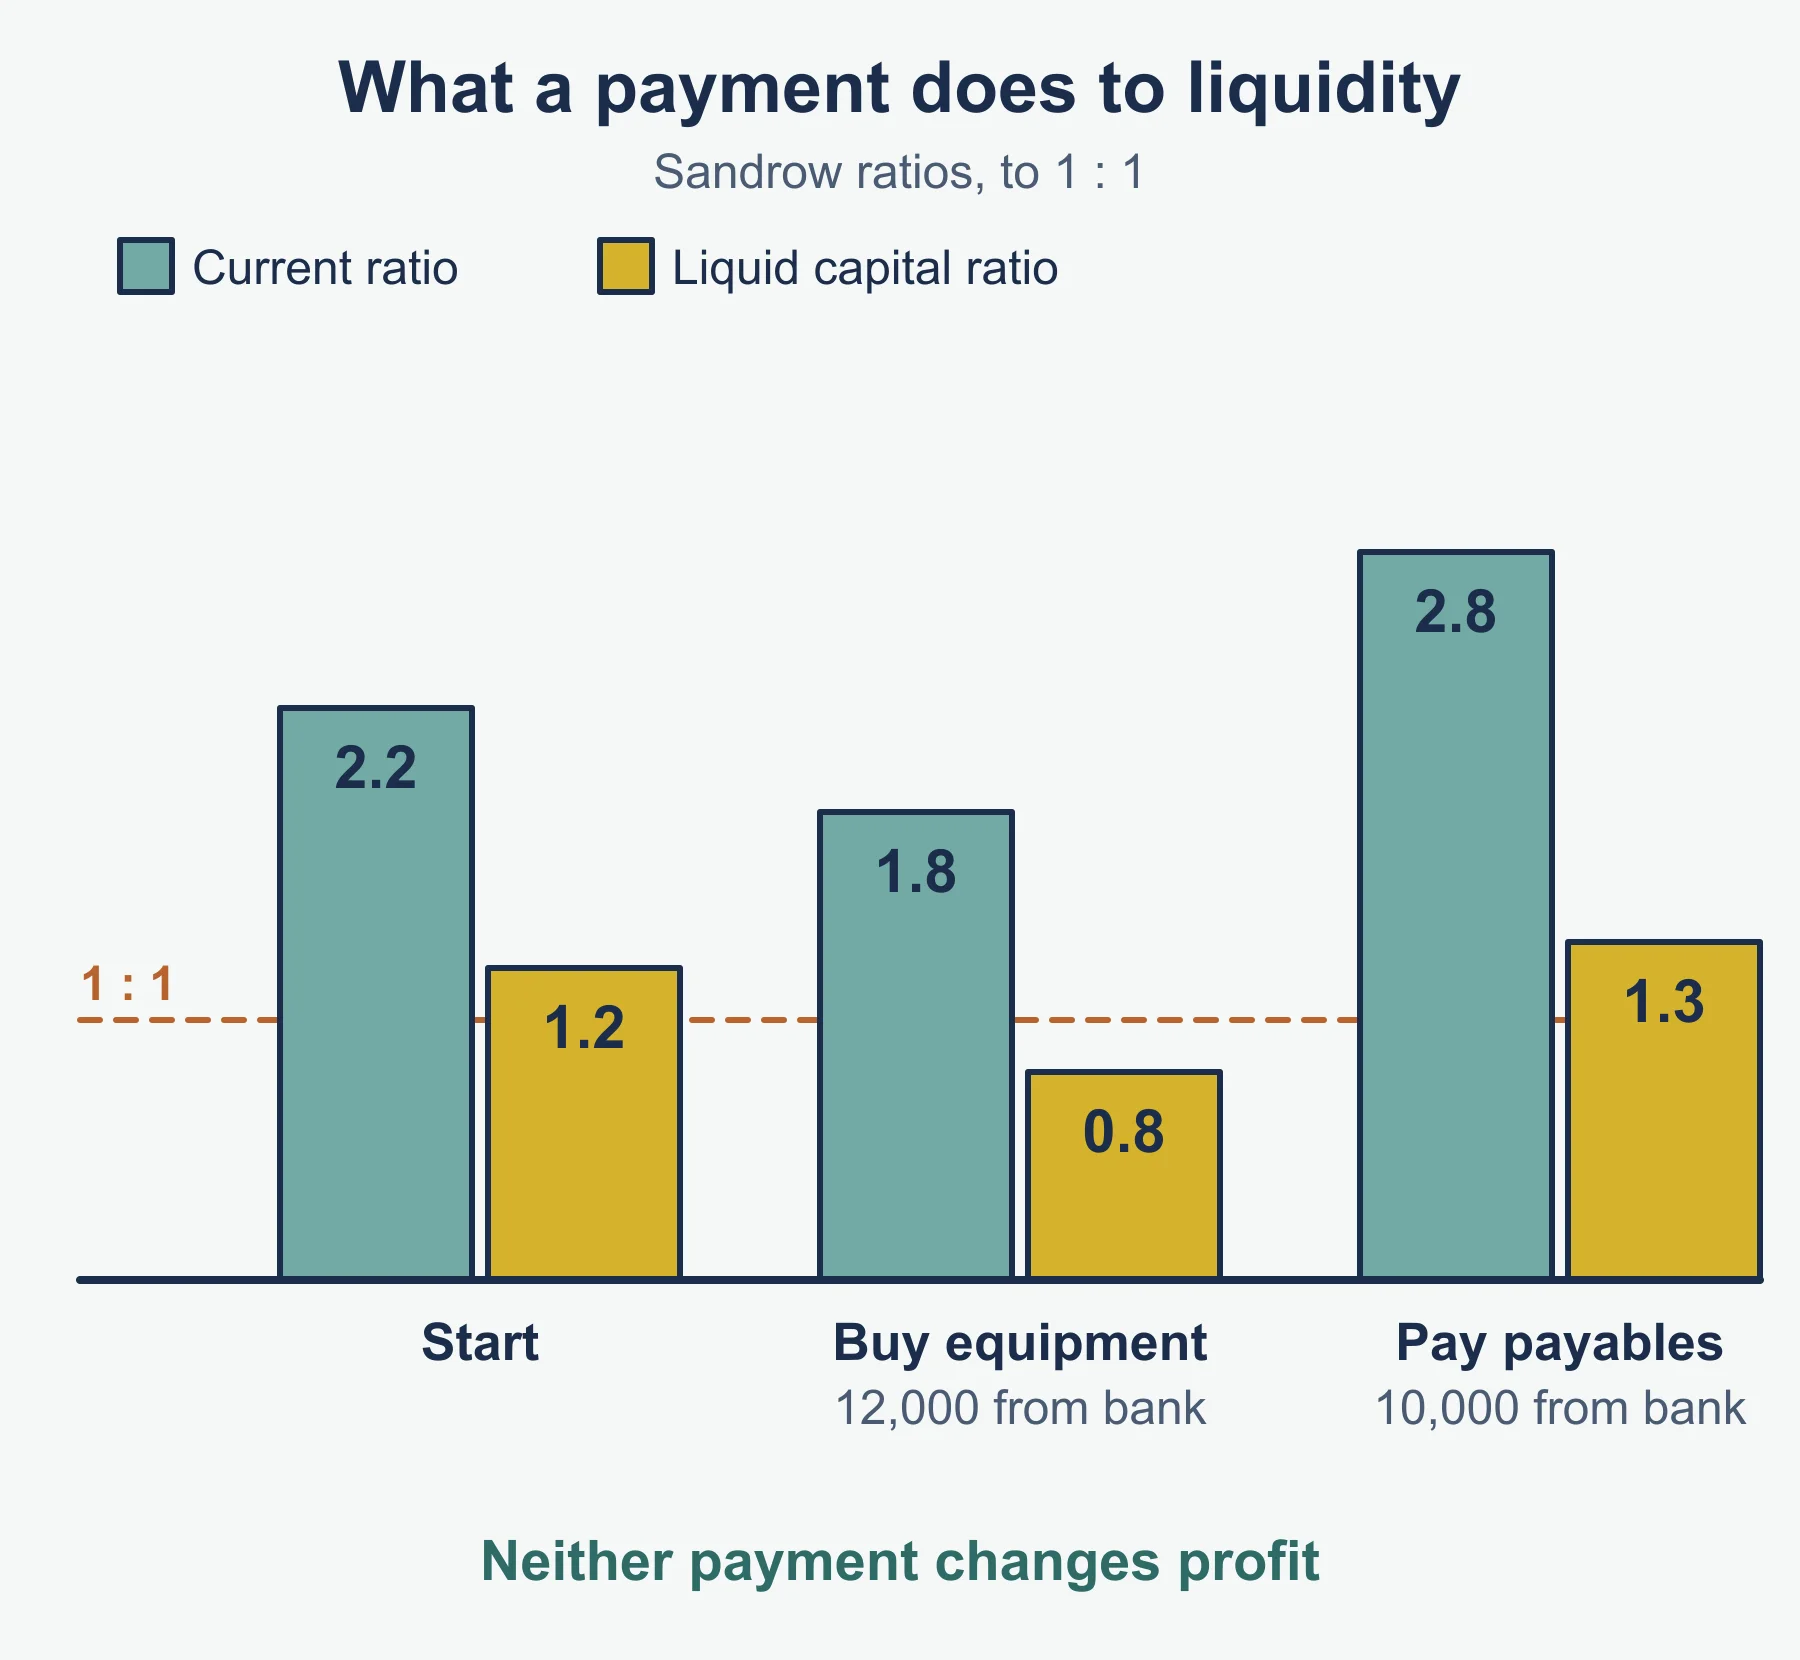
Using the Sandrow figures (current assets 66,000, inventory 30,000, current liabilities 30,000), see what three transactions do to liquidity:
| Transaction | Effect on profit | Current ratio after | Liquid capital ratio after |
|---|---|---|---|
| Starting position | none | 2.2 : 1 | 1.2 : 1 |
| Buy equipment for 12,000 from the bank | none now (depreciation later) | 54,000 : 30,000 = 1.8 : 1 | 24,000 : 30,000 = 0.8 : 1 |
| Pay 10,000 to trade payables from the bank | none | 56,000 : 20,000 = 2.8 : 1 | 26,000 : 20,000 = 1.3 : 1 |
Paying a short-term debt improves both ratios even though cash falls. Buying equipment lowers them. Neither changes profit when it happens. A sale on credit does the opposite: profit rises at once, but cash does not until the customer pays. Depreciation reduces profit without any cash leaving. Drawings reduce cash without reducing profit.
Appraising performance on profitability and liquidity
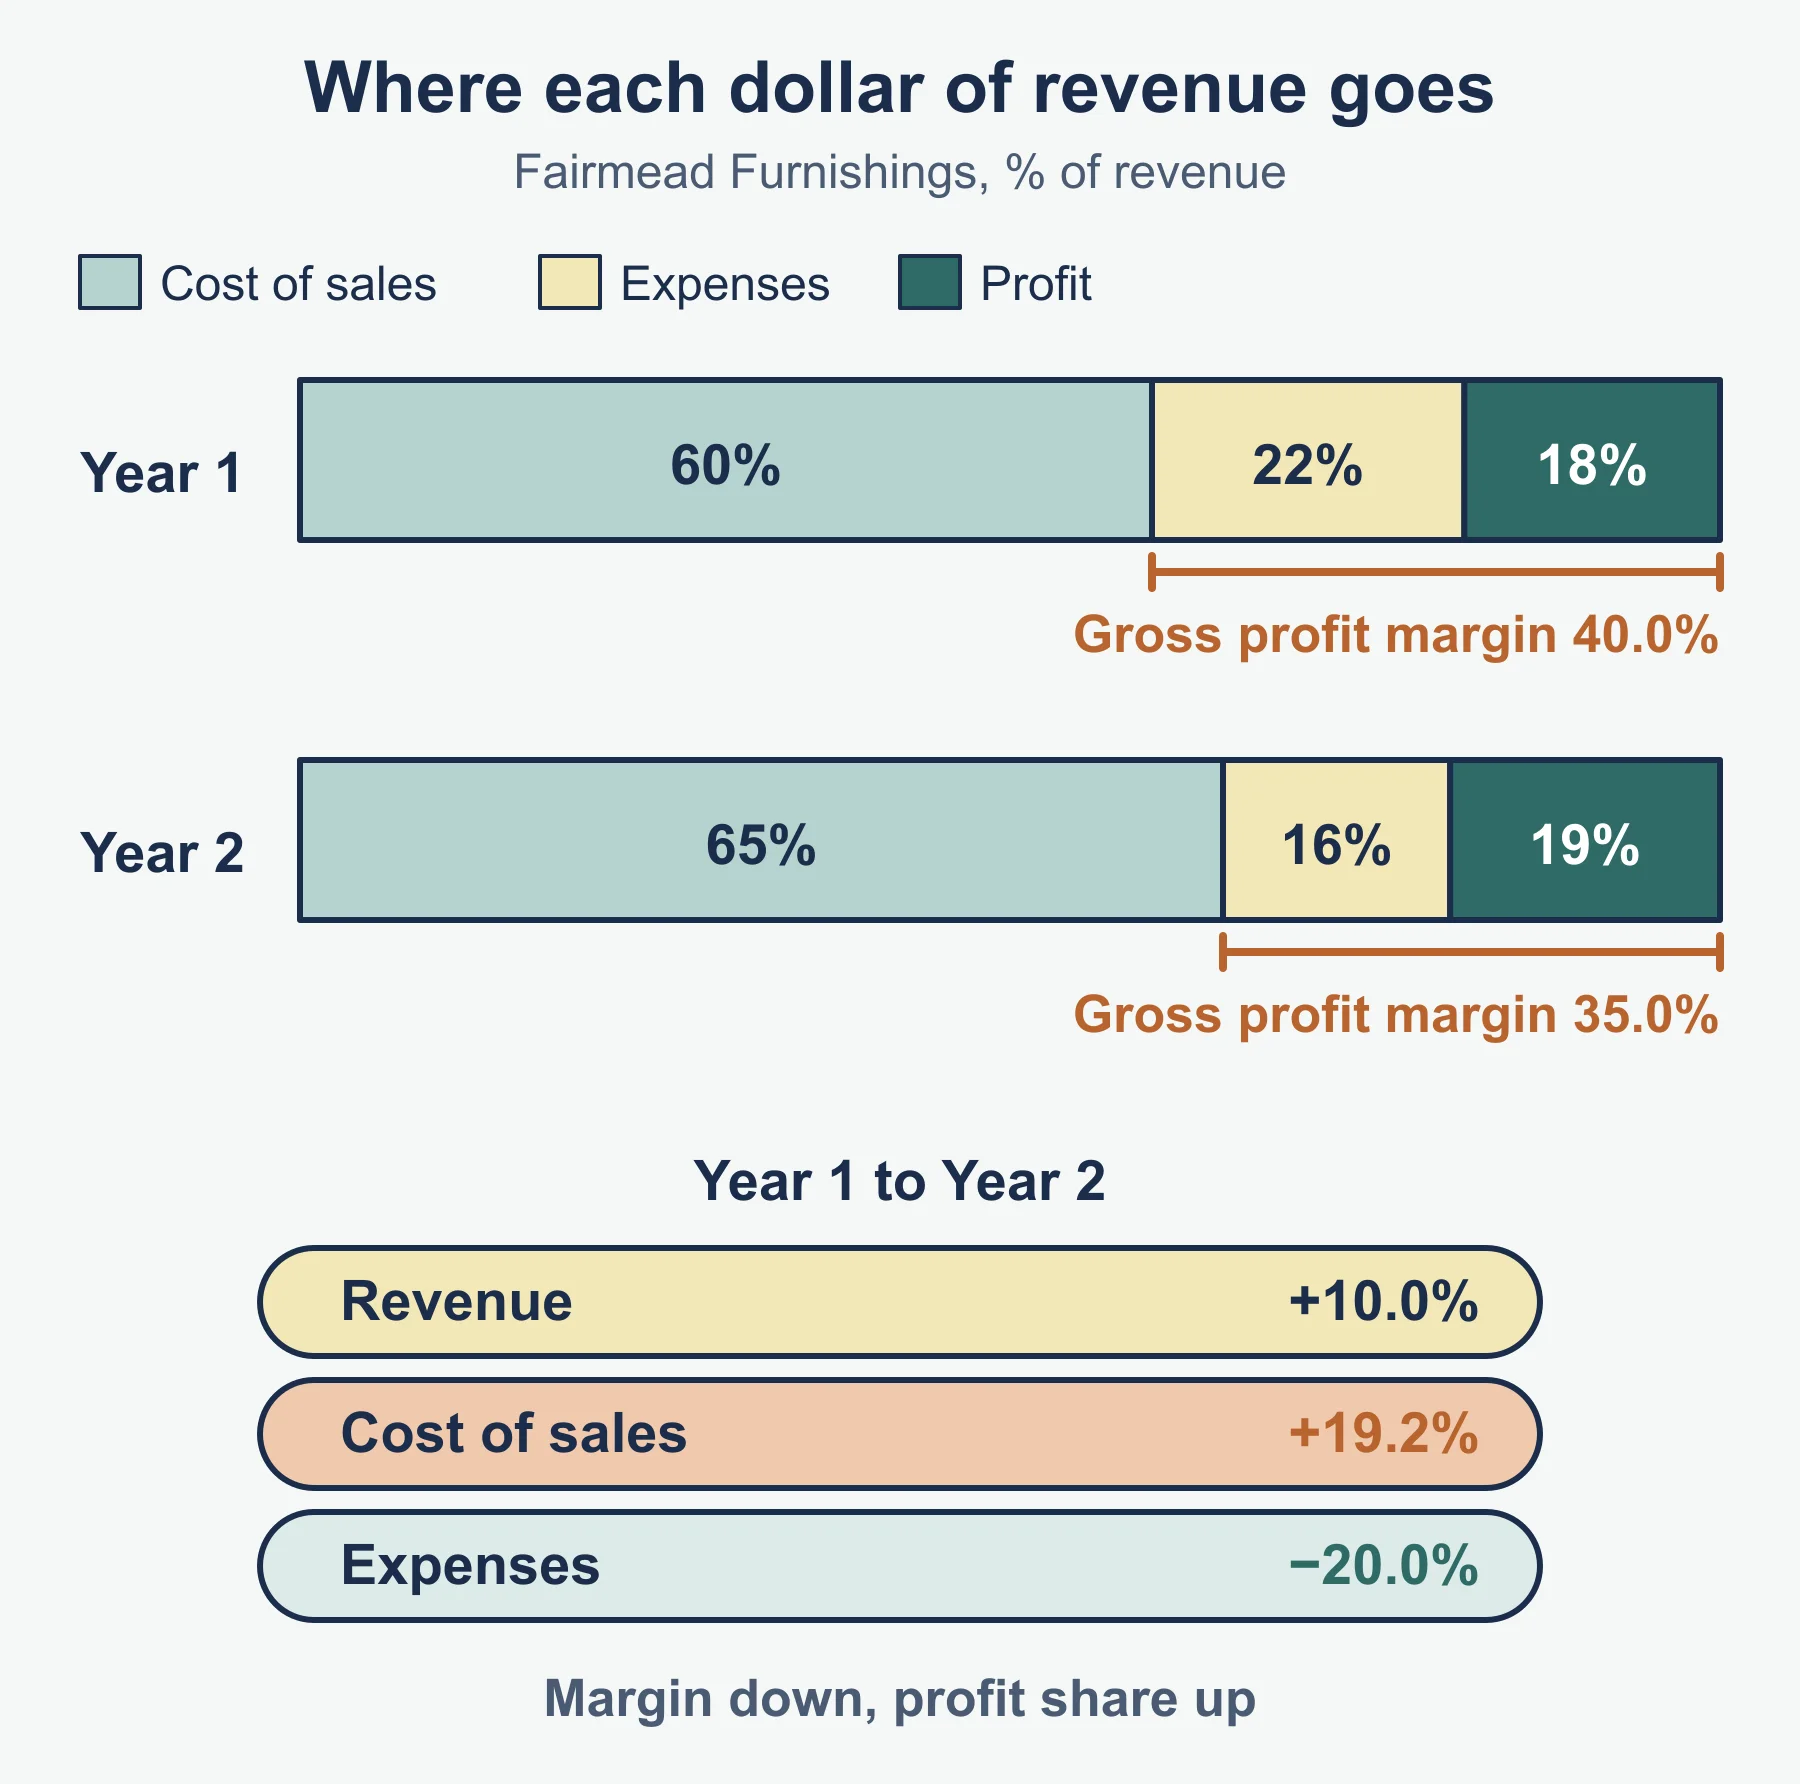
Fairmead Furnishings has two years of figures (revenue and cost of sales in dollars).
| Measure | Year 1 | Year 2 |
|---|---|---|
| Revenue | 250,000 | 275,000 |
| Cost of sales | 150,000 | 178,750 |
| Gross profit | 100,000 | 96,250 |
| Expenses | 55,000 | 44,000 |
| Profit from operations (no loan interest) | 45,000 | 52,250 |
| Gross profit margin | 40.0% | 35.0% |
| Profit in relation to revenue | 18.0% | 19.0% |
An appraisal uses the numbers, says what they show, gives a reason and reaches a judgement:
- Revenue grew by 10%, but cost of sales grew by 19.2%, so the gross profit margin fell from 40.0% to 35.0%. Possible reasons are dearer suppliers or discounts to win sales.
- Expenses fell by 20%, so profit in relation to revenue still rose from 18.0% to 19.0%.
- Judgement: profit improved, but it relies on cutting expenses. If that is not repeatable and the margin keeps falling, the gain may not last.
For liquidity, do the same with the current and liquid capital ratios and the days measures. Say whether the business can pay its debts as they fall due, and whether slow receivables or heavy inventory are the cause.
Limitations of financial statements and ratio analysis
The specification includes both financial and non-financial limitations. Point to specific ones.
Financial limitations:
- The figures are historic and may not predict the future.
- Ratios use year-end balances, which may not be typical of the whole year. Seasonal trading can distort inventory and receivables.
- Businesses can use different accounting policies, such as depreciation methods, so comparisons may mislead.
- Inflation makes comparison across years harder.
- Ratios show what changed, not why.
Non-financial limitations, which no ratio captures:
- Staff skills and morale, customer loyalty and reputation.
- The state of the market, competitors and the economy.
- The quality of management and the owner’s plans.
Common errors
- Dividing gross profit by revenue and calling it markup.
- Using total revenue for receivable days without saying so, when credit revenue is given.
- Using closing inventory instead of average inventory for turnover when both are given.
- Writing a ratio as a percentage when it should be a ratio, and the reverse.
- Describing a ratio as “good” or “bad” without comparing it with anything.
- Listing limitations in general terms with no link to the business in the question.
Frequently asked questions
How many ratios and financial measures are in OxfordAQA International GCSE Accounting 9215? Nine. The specification also asks you to appraise performance on profitability and liquidity, and to know the limitations of financial statements and ratio analysis.
How is the rate of inventory turnover calculated? Divide cost of sales by average inventory, where average inventory is opening inventory plus closing inventory, divided by two.
Is a higher ratio always better? No. A single ratio means little until it is compared with last year, a budget or a similar business, and higher is not always better: a very high payable days figure may mean the business is struggling to pay.
What are the limitations of ratio analysis? Financial limitations include historic figures that may not predict the future and year-end balances that may not be typical. Non-financial factors such as staff skills, morale, customer loyalty, reputation and the state of the market are not captured by any ratio.
Why does paying a short-term debt improve the current ratio? Paying a trade payable from the bank lowers current assets and current liabilities by the same amount, so a current ratio above 1 : 1 rises even though cash falls.
Official syllabus
OxfordAQA International GCSE Accounting (9215), specification version 1.2, for exams from May/June 2026 onwards, section 3.5: Interpretation, analysis and communication of financial information. This page deals with the ratios, appraisal, cash and profit, and limitations content points. Stakeholders and the use of computers in accounting are other content points in the same section and are not covered here.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
OxfordAQA IGCSE Accounting: Accounting ratios and financial measures (9215) – Practice Questions
Eleven original practice questions with worked answers on the nine ratios and financial measures in OxfordAQA International GCSE Accounting 9215.
Accounting · OxfordAQA · IGCSE
Try questions -
Revision notes
OxfordAQA IGCSE Accounting: Accounting ratios and financial measures (9215) – Revision Notes
Condensed formulae, method steps, interpretation cues and a ten-question self-test on the nine ratios in OxfordAQA International GCSE Accounting 9215.
Accounting · OxfordAQA · IGCSE
Revise topic -
Study guides
OxfordAQA IGCSE Accounting: Appraising business performance, cash and profit (9215)
Calculate and interpret profitability and liquidity ratios, then explain how cash differs from profit, for OxfordAQA International GCSE Accounting 9215.
Accounting · OxfordAQA · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
OxfordAQA Accounting teachers at Marlbridge

