
Revision Notes
OxfordAQA IGCSE Accounting: Trade payables and trade receivables control accounts (9215) – Revision Notes
Condensed revision notes on trade receivables and trade payables control accounts, with a self-test, for OxfordAQA International GCSE Accounting.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- Verification of accounting records
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to OxfordAQA IGCSE Accounting (9215), First teaching 2024, first examined 2026. Official specification .
Syllabus page (what it covers and how it is assessed): OxfordAQA IGCSE Accounting.
Syllabus points this page covers
9215
- Prepare, understand and interpret trade payables and trade receivables ledger control accounts
Found an error? Report a correction.
Need help with this topic? Request a free trial class for IGCSE Accounting (9215).
These notes condense section 3.2 (Verification of accounting records) of the OxfordAQA International GCSE Accounting (9215) specification, version 1.2, for the control accounts content only. Full explanations and longer worked examples are in the control accounts study guide. Broader topic notes are in the Topic 2 revision notes. Amounts are in dollars. Go to the course hub, the checklist or a free diagnostic to check your progress, and use the practice questions once you have learned these notes.
Definitions
- Trade receivables ledger control account: a summary of all the individual customer accounts in the receivables ledger.
- Trade payables ledger control account: a summary of all the individual supplier accounts in the payables ledger.
- Memorandum record: a record kept for checking that is not part of the double-entry system.
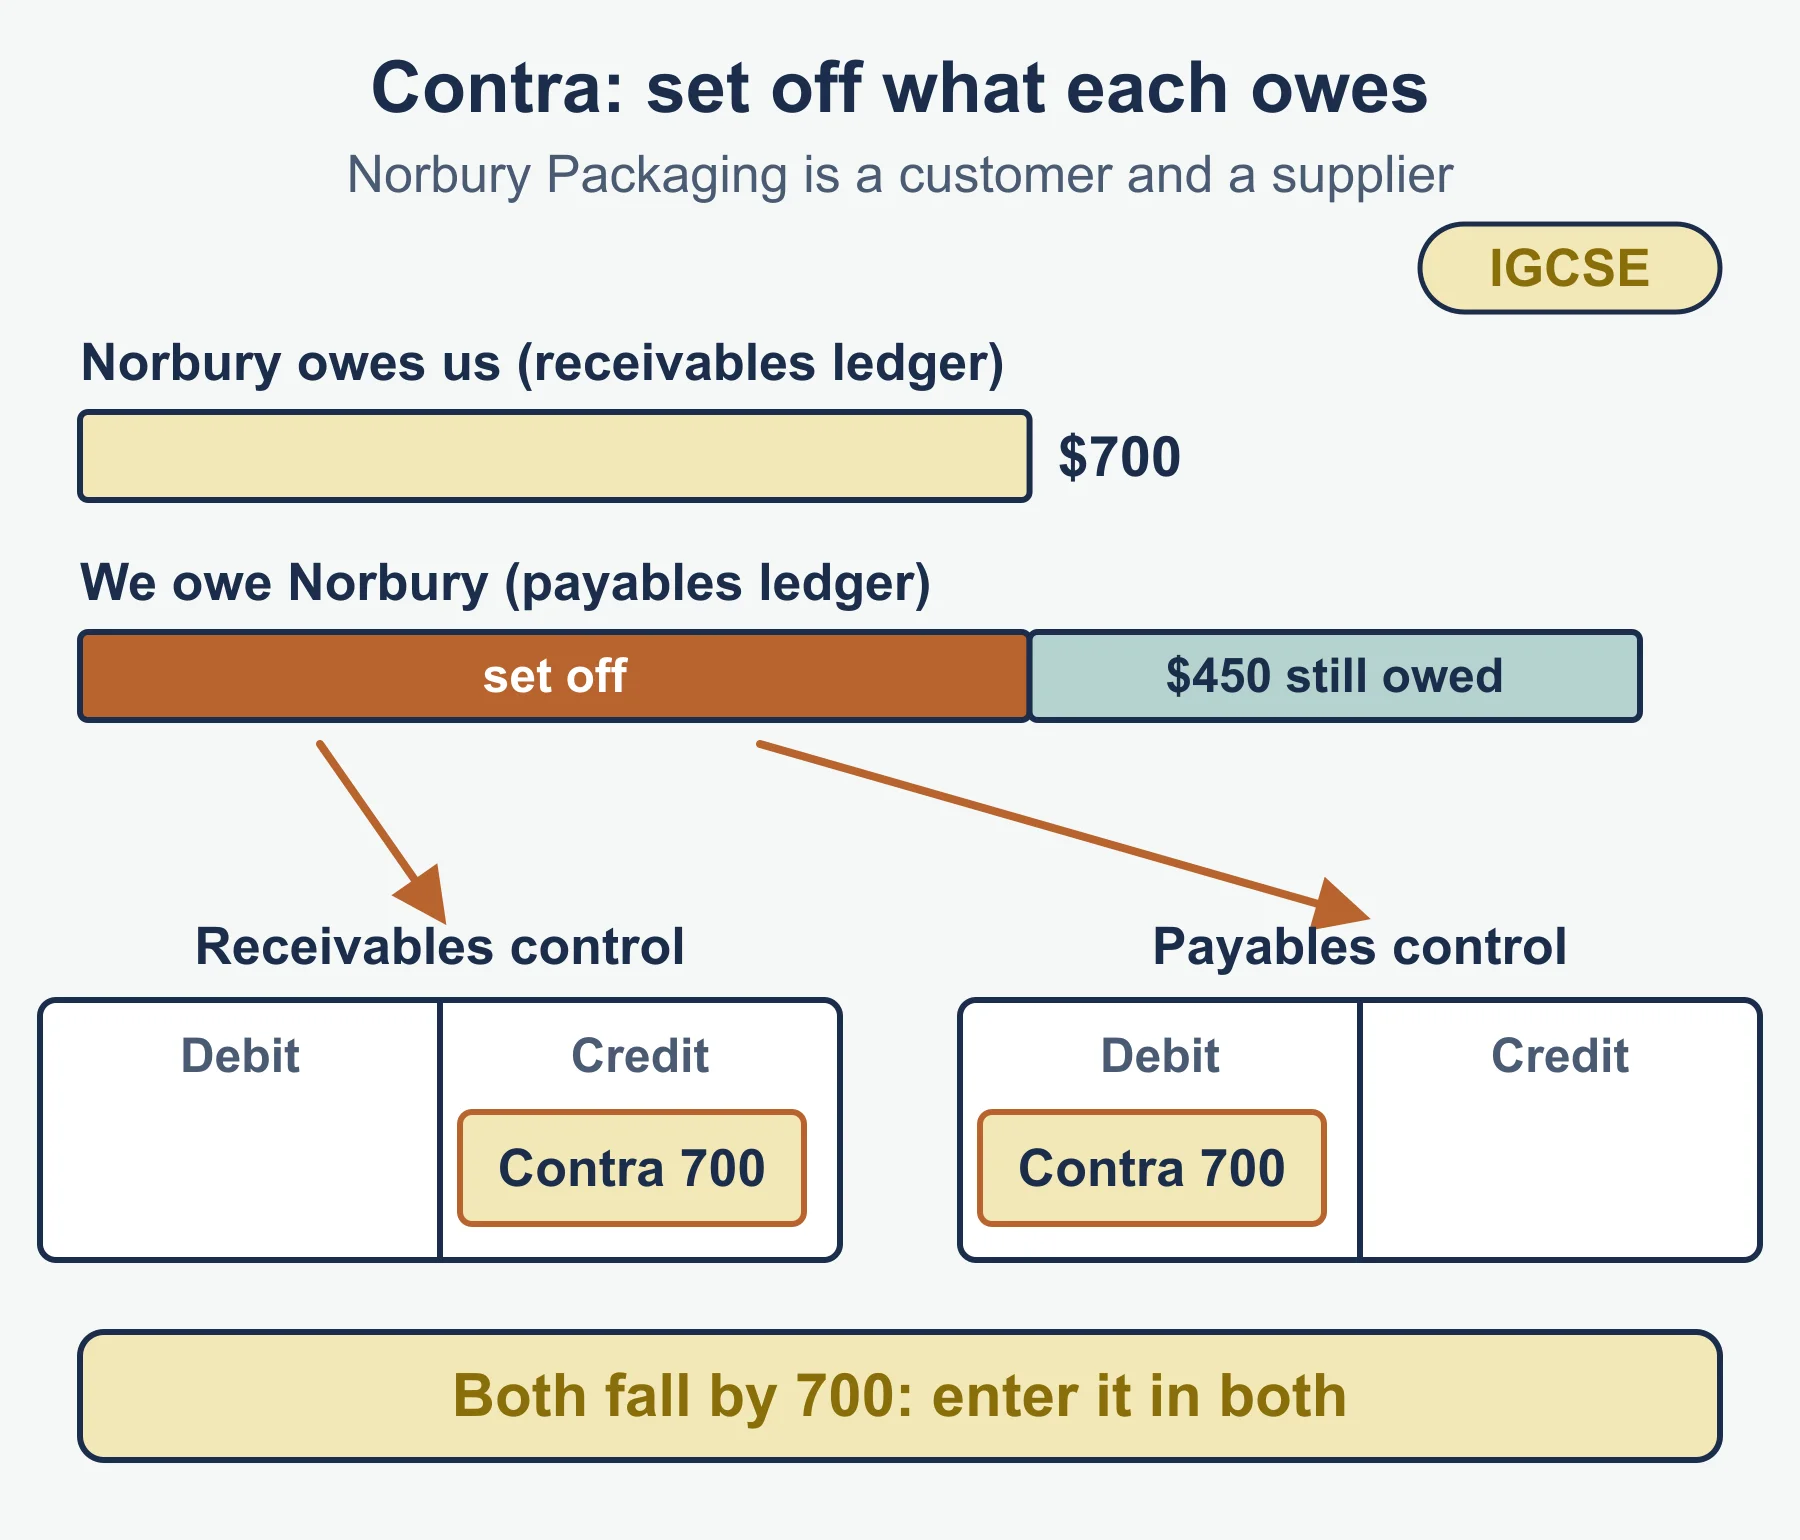
- Contra entry: setting off an amount owed by a trader who is both a customer and a supplier against an amount owed to that trader.
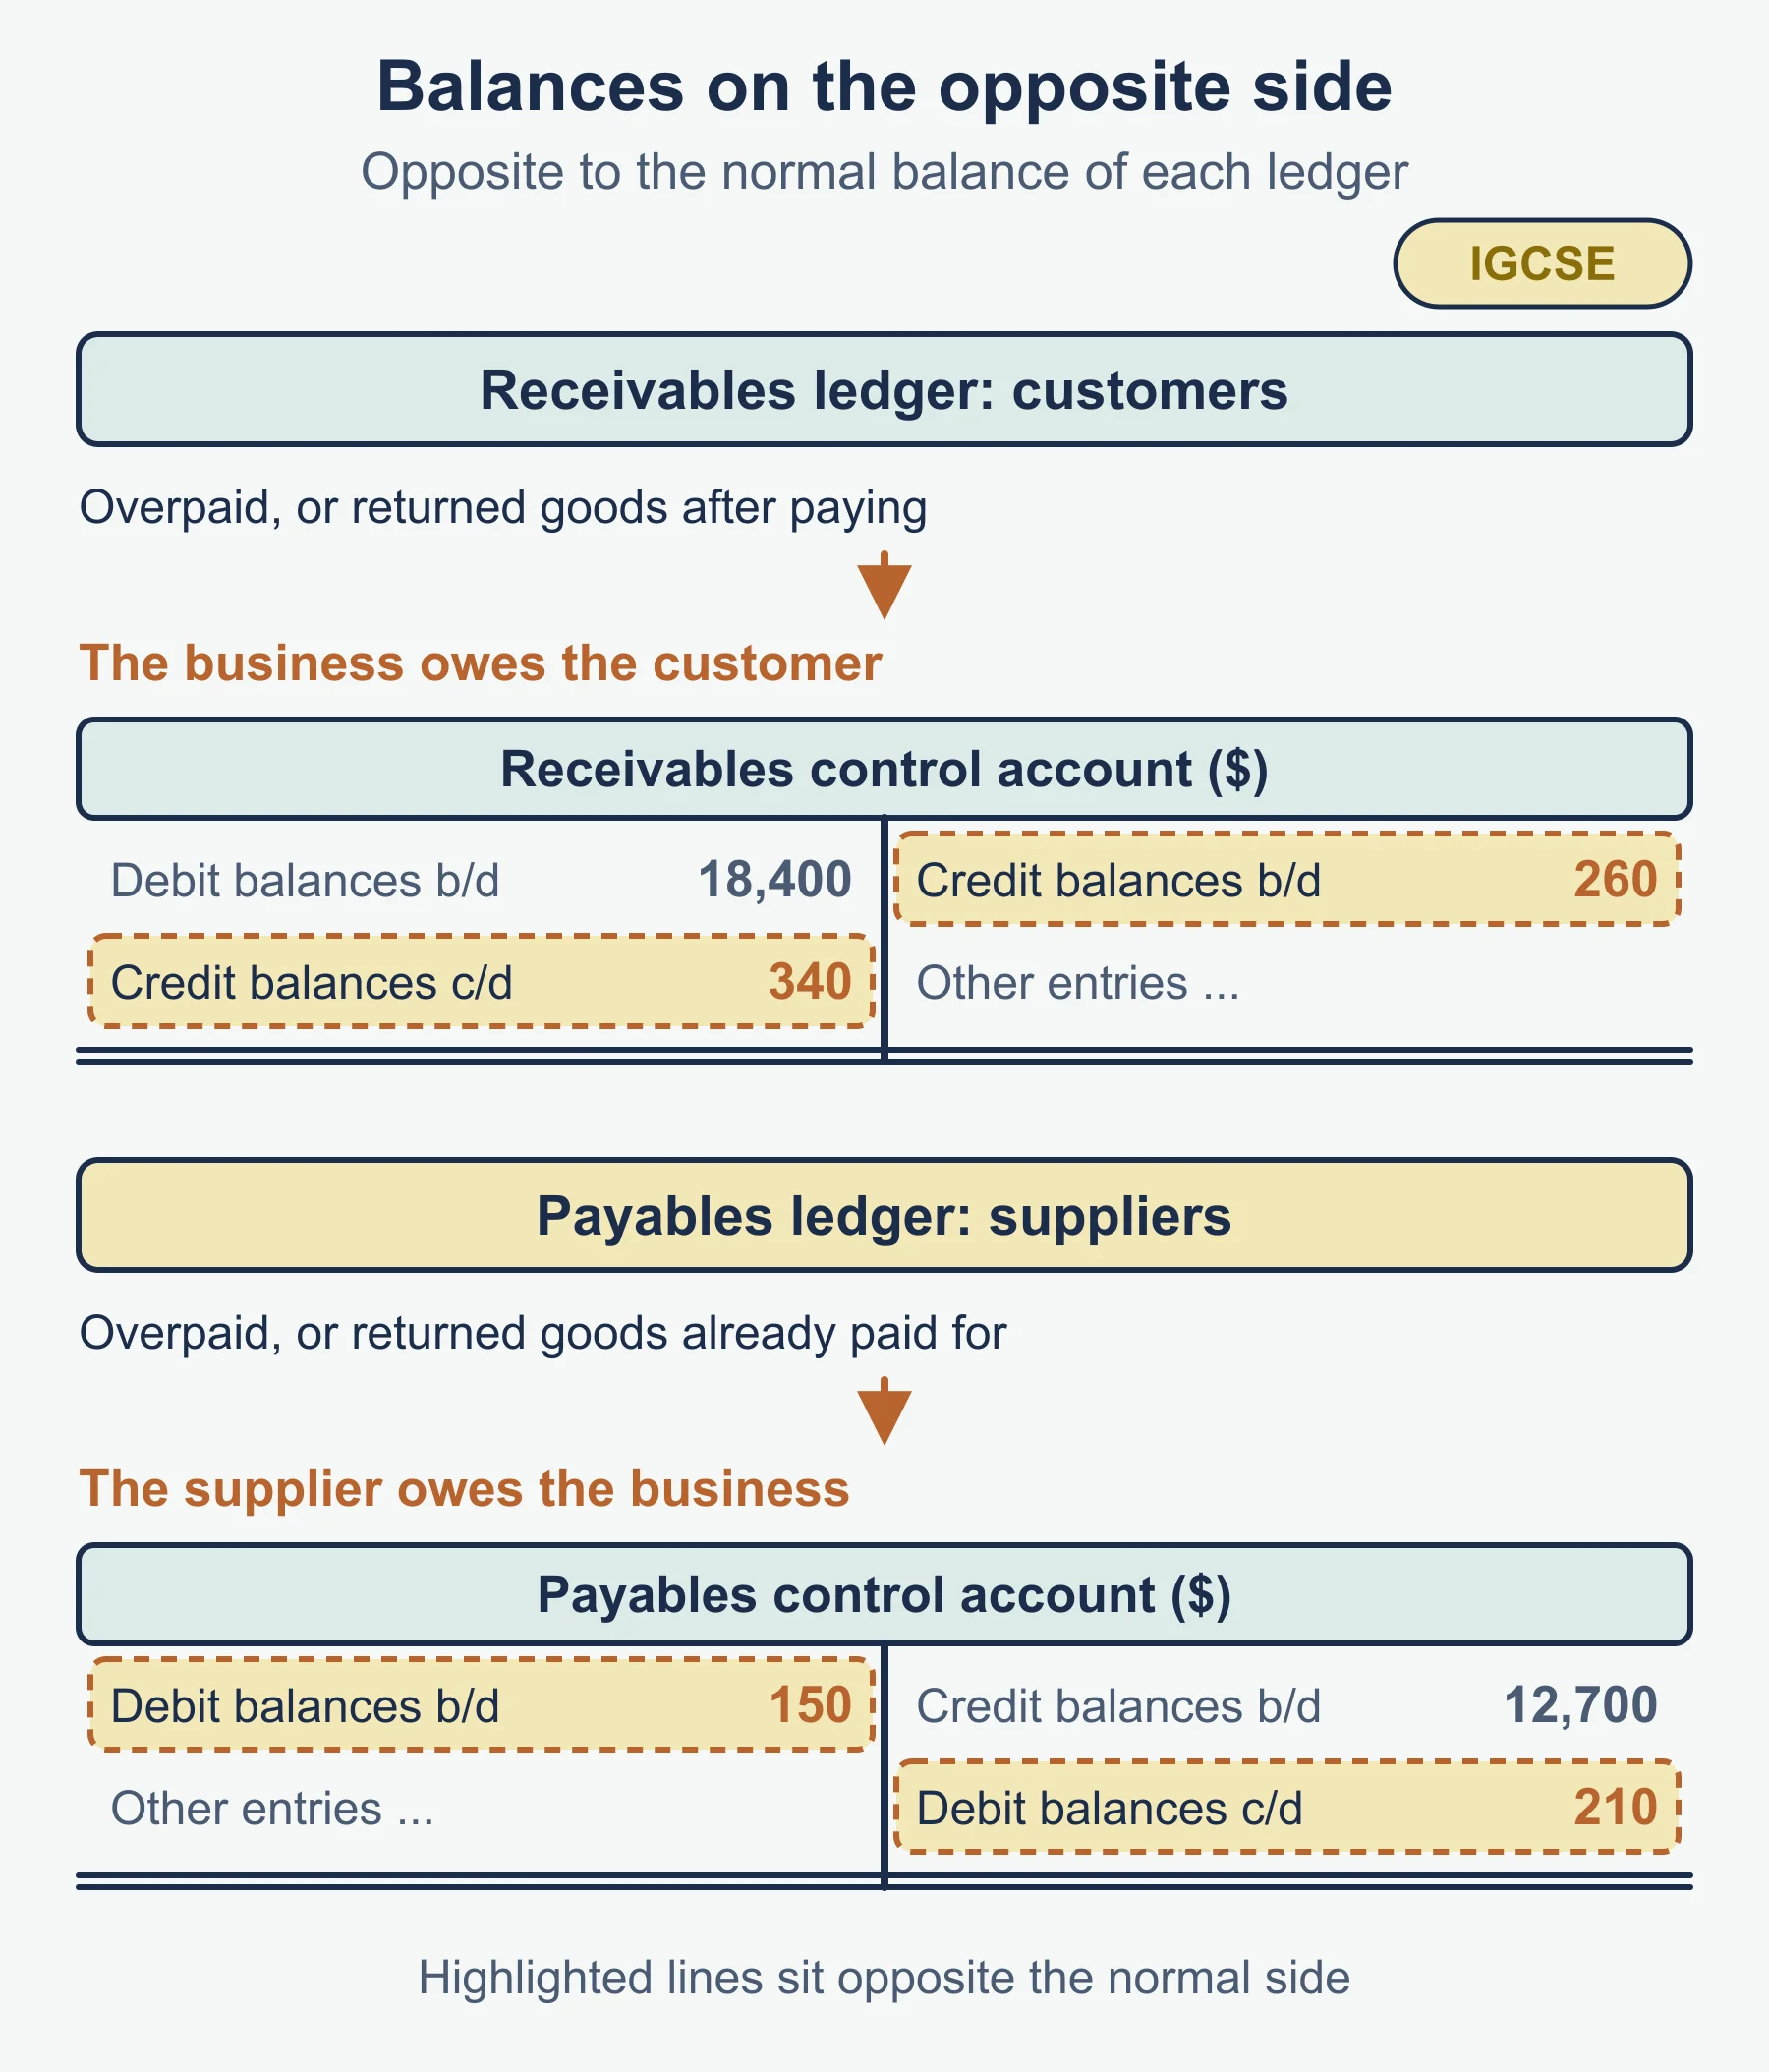
- Credit balance in the receivables ledger: a customer to whom the business owes money, for example after an overpayment.
- Debit balance in the payables ledger: a supplier who owes the business money, for example after an overpayment.
Which side does each item go on?
| Item | Receivables control | Payables control |
|---|---|---|
| Opening normal balances | Debit | Credit |
| Credit sales | Debit | Not used |
| Credit purchases | Not used | Credit |
| Sales returns | Credit | Not used |
| Purchases returns | Not used | Debit |
| Money received from customers | Credit | Not used |
| Money paid to suppliers | Not used | Debit |
| Cash discount allowed | Credit | Not used |
| Cash discount received | Not used | Debit |
| Irrecoverable debts | Credit | Not used |
| Dishonoured cheque from a customer | Debit | Not used |
| Interest charged on overdue accounts | Debit (charged to a customer) | Credit (charged by a supplier) |
| Contra entry | Credit | Debit |
| Opening credit balances in receivables ledger | Credit | Not used |
| Opening debit balances in payables ledger | Not used | Debit |
| Closing credit balances in receivables ledger | Debit (carried down) | Not used |
| Closing debit balances in payables ledger | Not used | Credit (carried down) |
The rule behind the table: a receivables control account behaves like a customer account, and a payables control account behaves like a supplier account.
Method in steps
- Head the account with the correct ledger and write the opening balances. Normal balances go on the normal side. Unusual balances go on the opposite side.
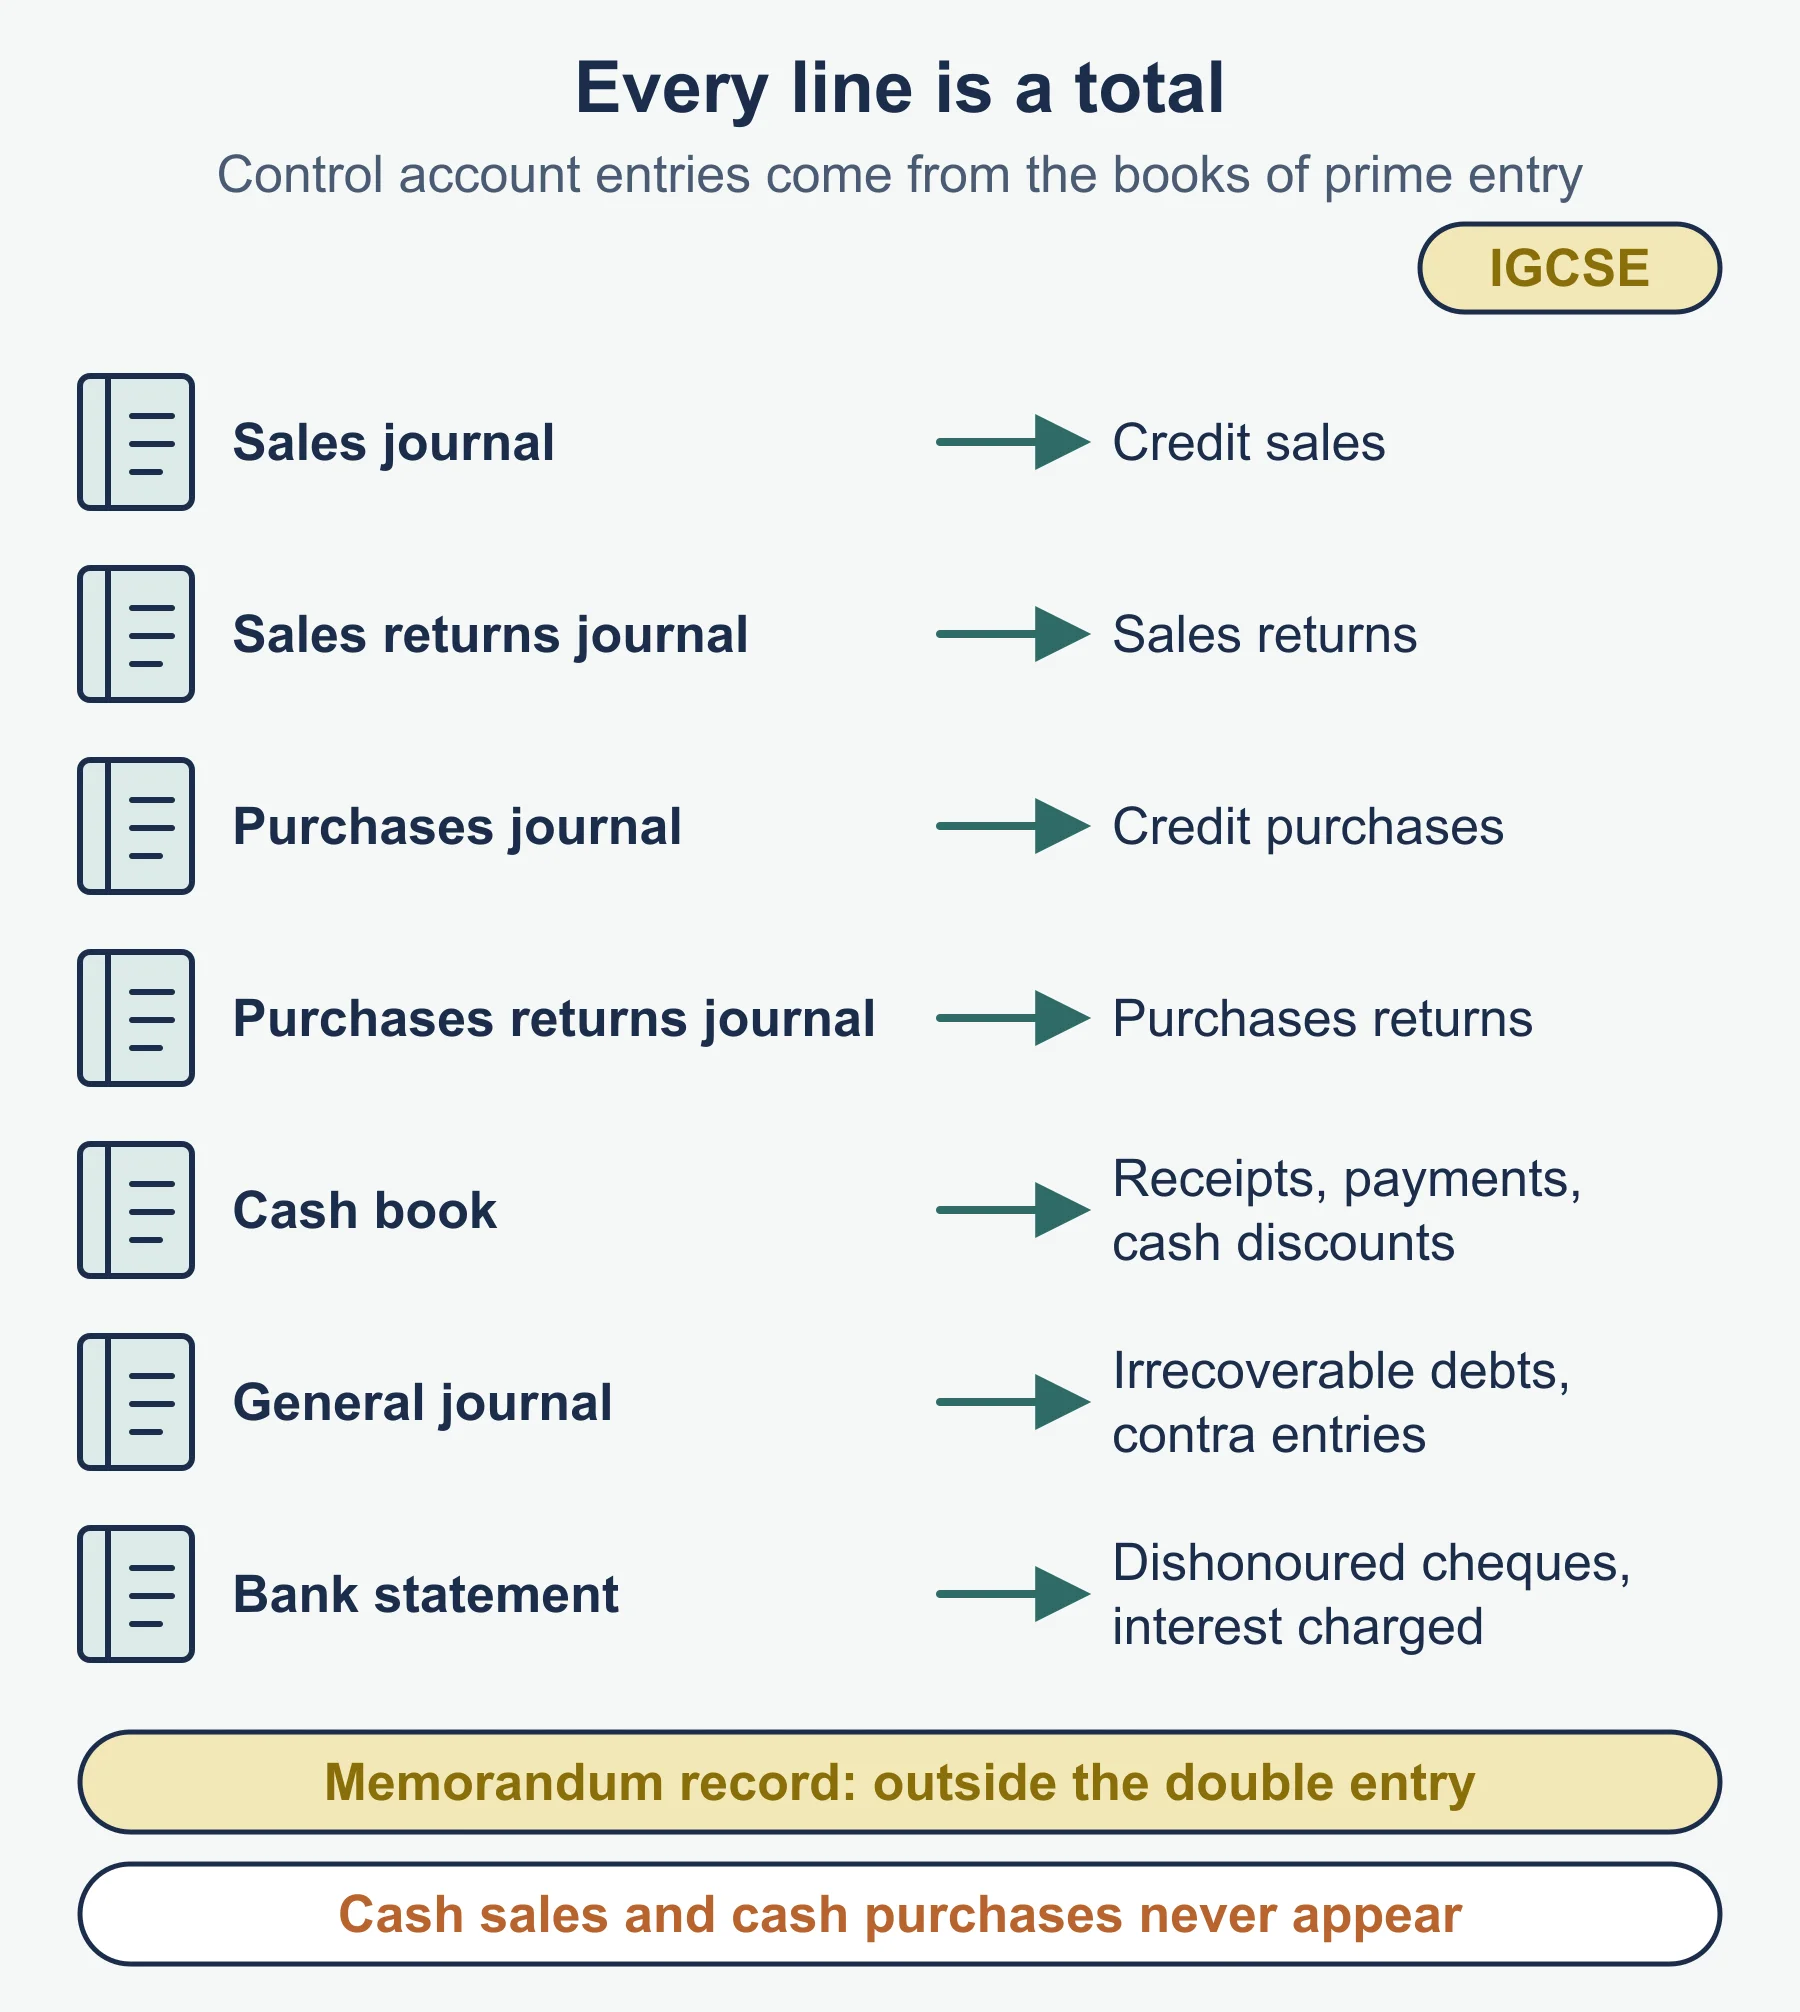
- Take each total from its source: sales journal, purchases journal, returns journals, cash book, general journal.
- Place each item on its side using the table above.
- Put the unusual closing balances (credit balances in receivables, debit balances in payables) on the side that increases the total of normal balances.
- Total the larger side and find the balancing figure on the other side. That is the closing balance of normal balances.
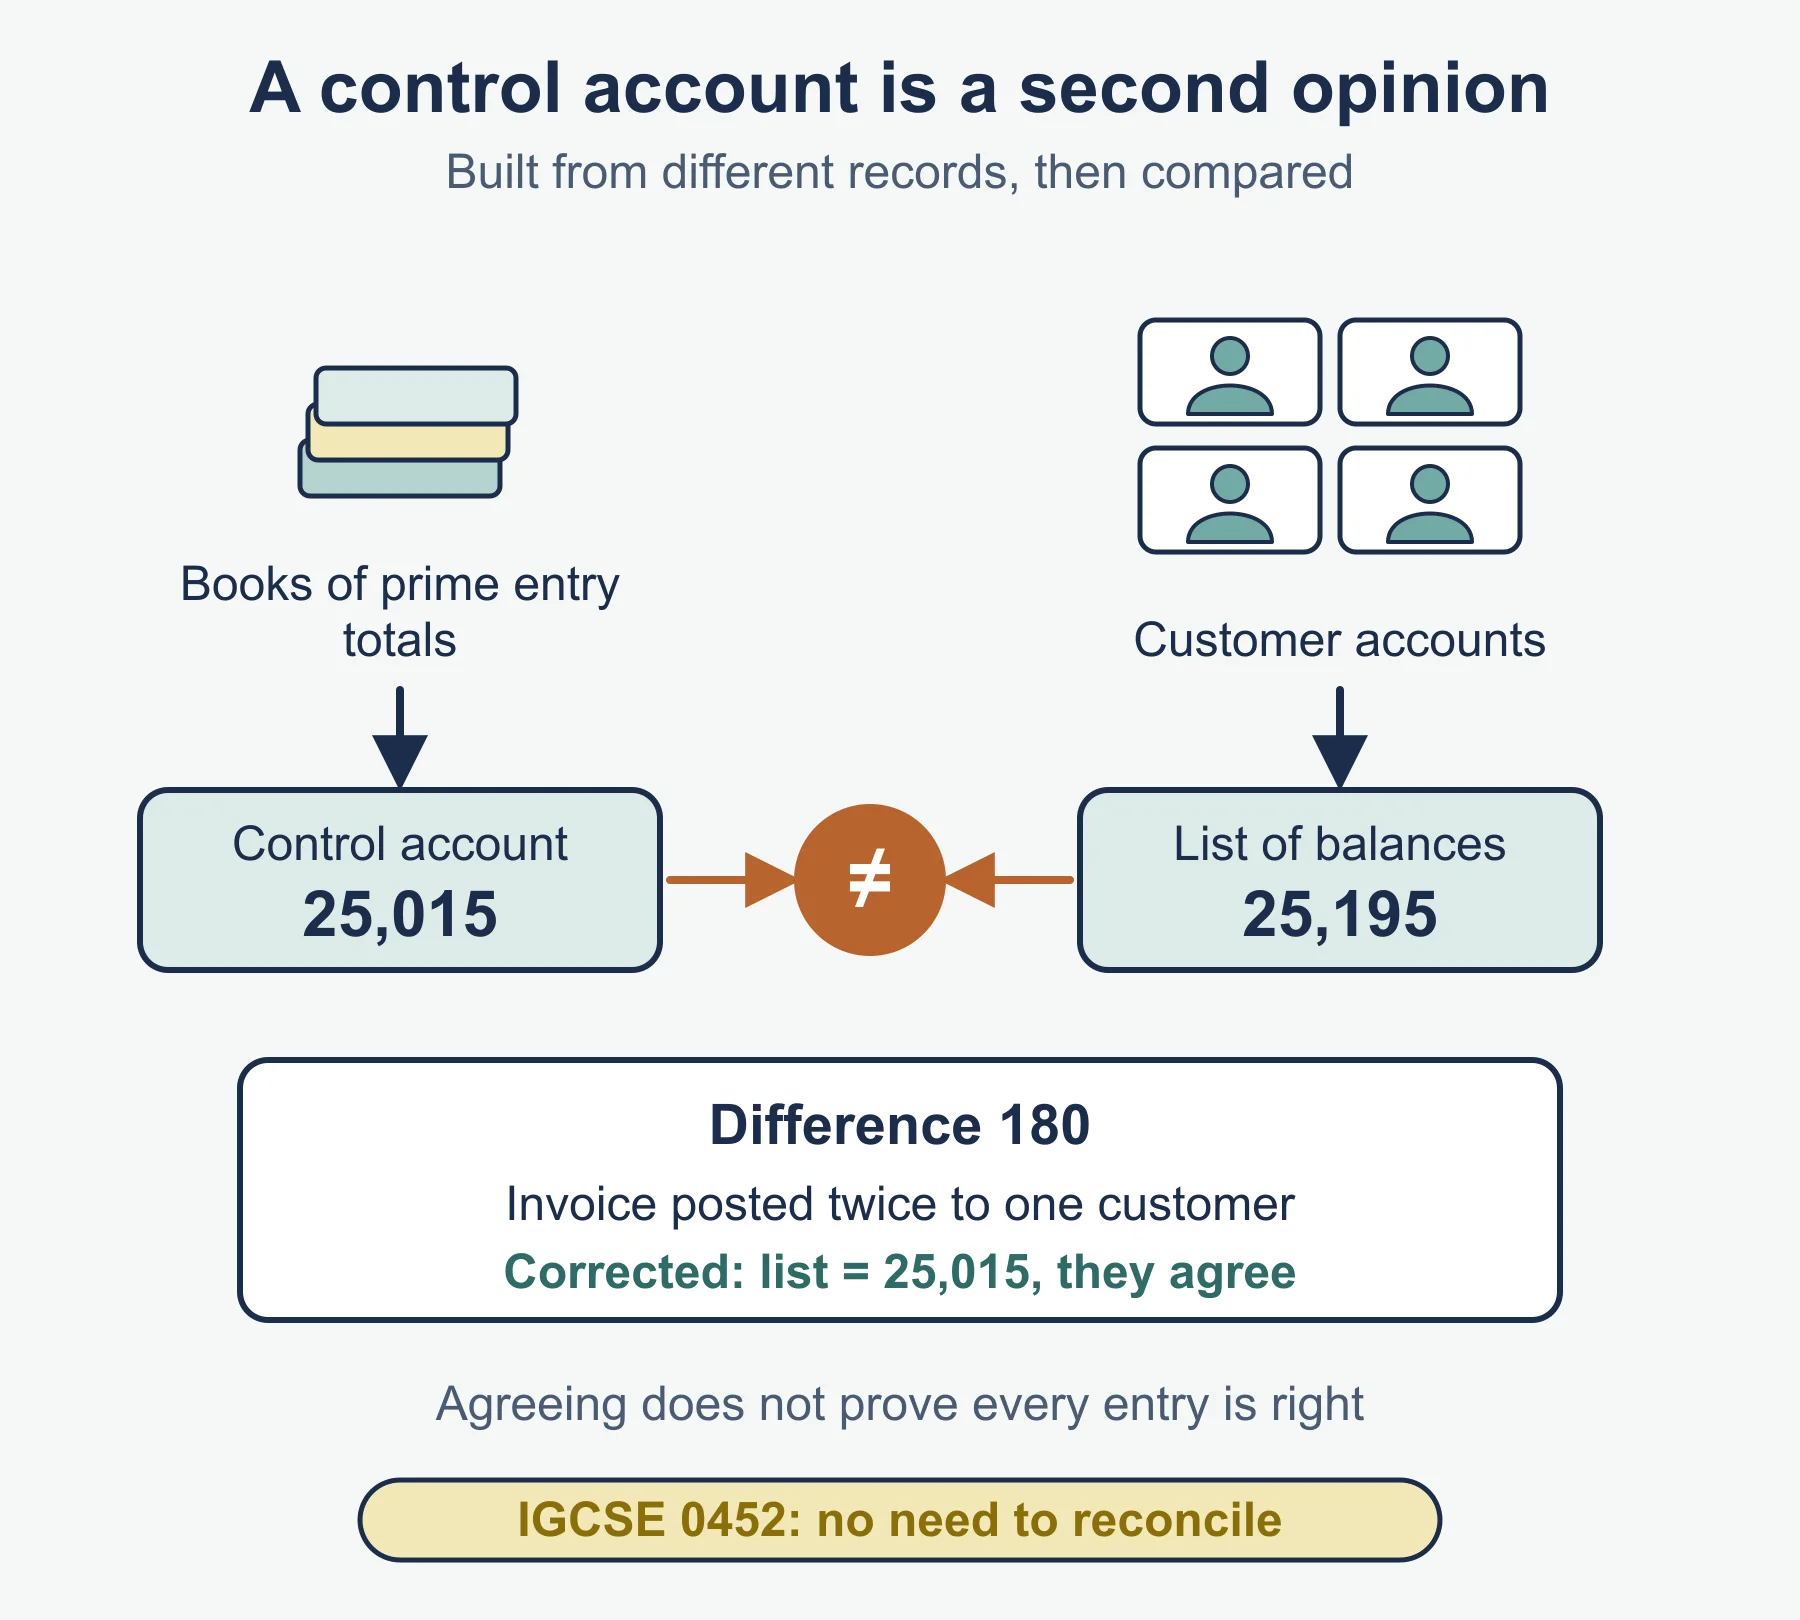
- Compare it with the total of the list of balances taken from the ledger and explain any difference.
Small worked reminder: Ravensby Toys
Receivables: opening debit balances 7,200; credit sales 15,800; money received 14,100; sales returns 650; cash discount allowed 190. There were no other items.
Closing = 7,200 + 15,800 - 14,100 - 650 - 190 = 8,060.
Payables: opening credit balances 5,400; credit purchases 11,300; payments 10,250; purchases returns 480; cash discount received 160.
Closing = 5,400 + 11,300 - 10,250 - 480 - 160 = 5,810.
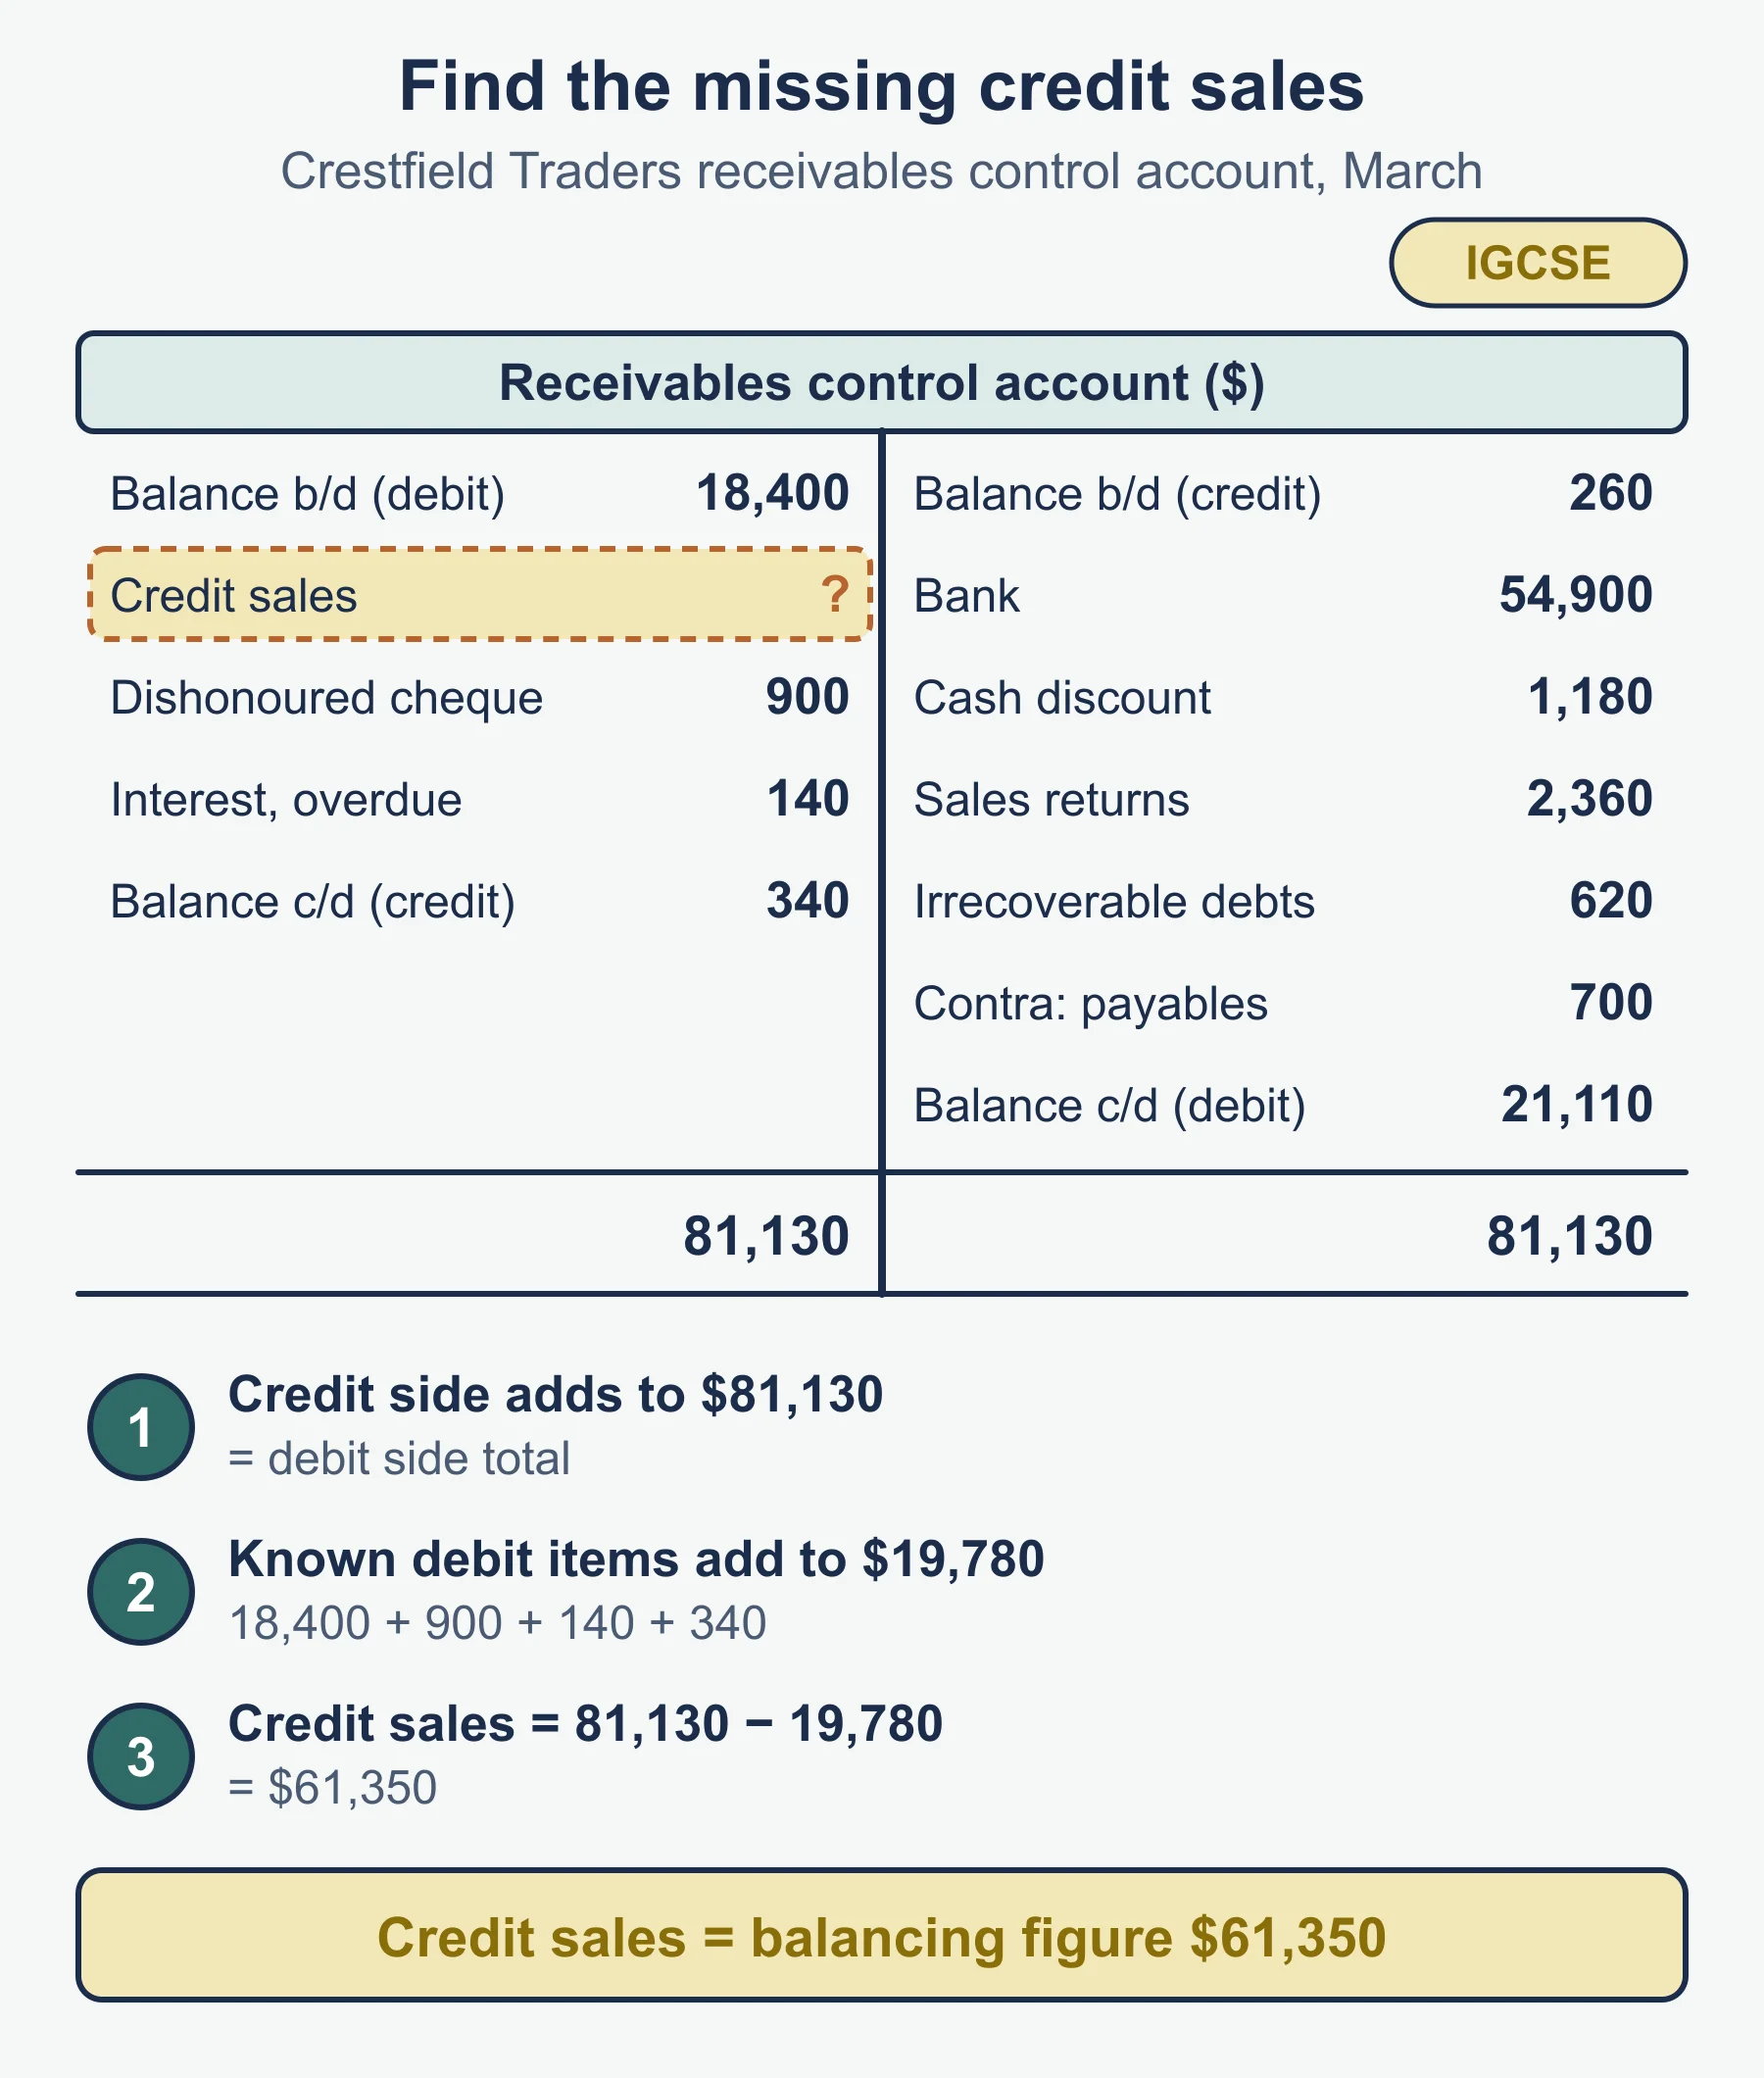
Missing figure: a business has opening receivables 9,000, closing receivables 8,350, receipts 21,700 and cash discount allowed 450, and no other items. Credit sales = 8,350 - 9,000 + 21,700 + 450 = 21,500.
Contra: a trader owes the business 940 and is owed 1,310 by it. The contra is the smaller figure, 940, leaving 370 still payable.
Interest: if the stated rate is 1.5% per month on an overdue balance of 4,000 for two months, the interest is 4,000 x 1.5% x 2 = 120.
Must-know distinctions
| Pair | Difference |
|---|---|
| Control account and ledger account | The control account is a memorandum summary. The ledger account is a real double-entry account. |
| Receivables and payables control | Opposite sides for the same event. |
| Dishonoured cheque and sales returns | The cheque makes the customer owe the money again, so it is a debit. A return reduces the debt, so it is a credit. |
| Credit balance in receivables and debit balance in payables | Both are unusual balances. The first is an amount owed to a customer, the second an amount owed by a supplier. |
| Interest to a customer and interest from a supplier | The first increases receivables, the second increases payables. |
Interpreting a difference
If the closing balance and the list of balances differ:
- check the arithmetic on the list first
- check each journal total used in the control account
- check postings from the journals to individual accounts
- remember an error may sit in the control account, not the ledger
- the control account cannot say which account is wrong
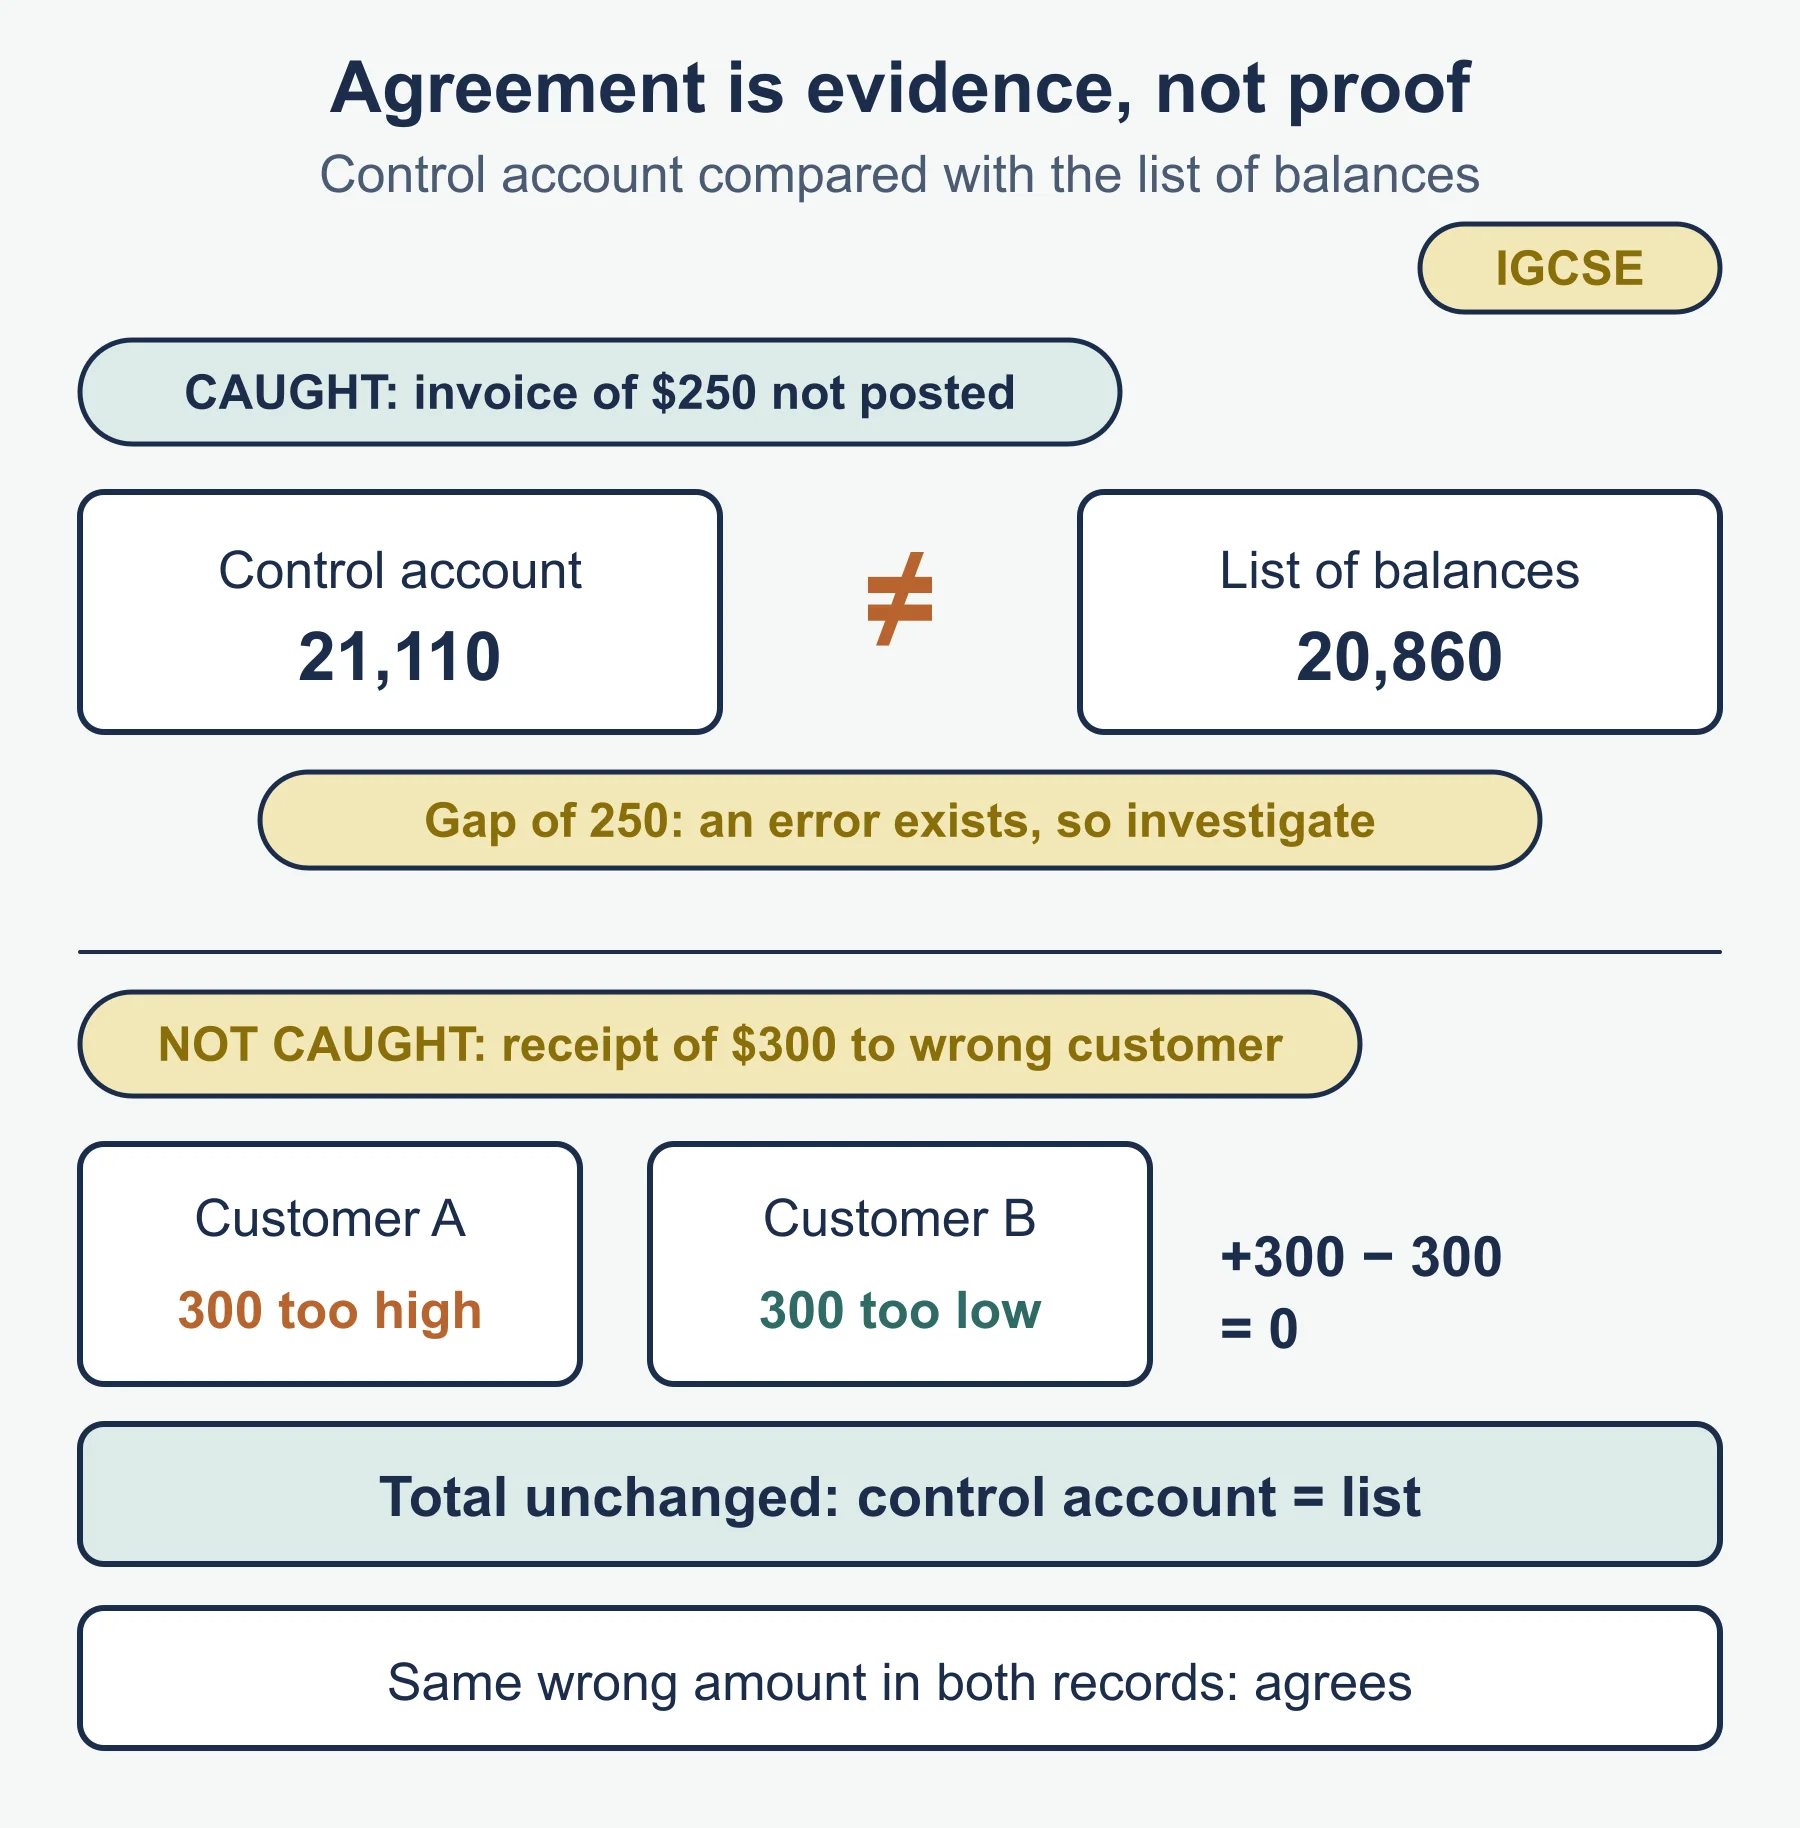
Agreement does not prove the ledger is correct: for example, a receipt posted to the wrong customer leaves the totals unchanged.
Why a business keeps control accounts
- They give the total owed by customers, or owed to suppliers, without adding every personal account.
- They provide a check on the ledger: the closing balance should agree with the list of individual balances.
- They narrow the search when the two disagree, because the difference is known.
- They can give a missing figure, such as credit sales, when records are incomplete.
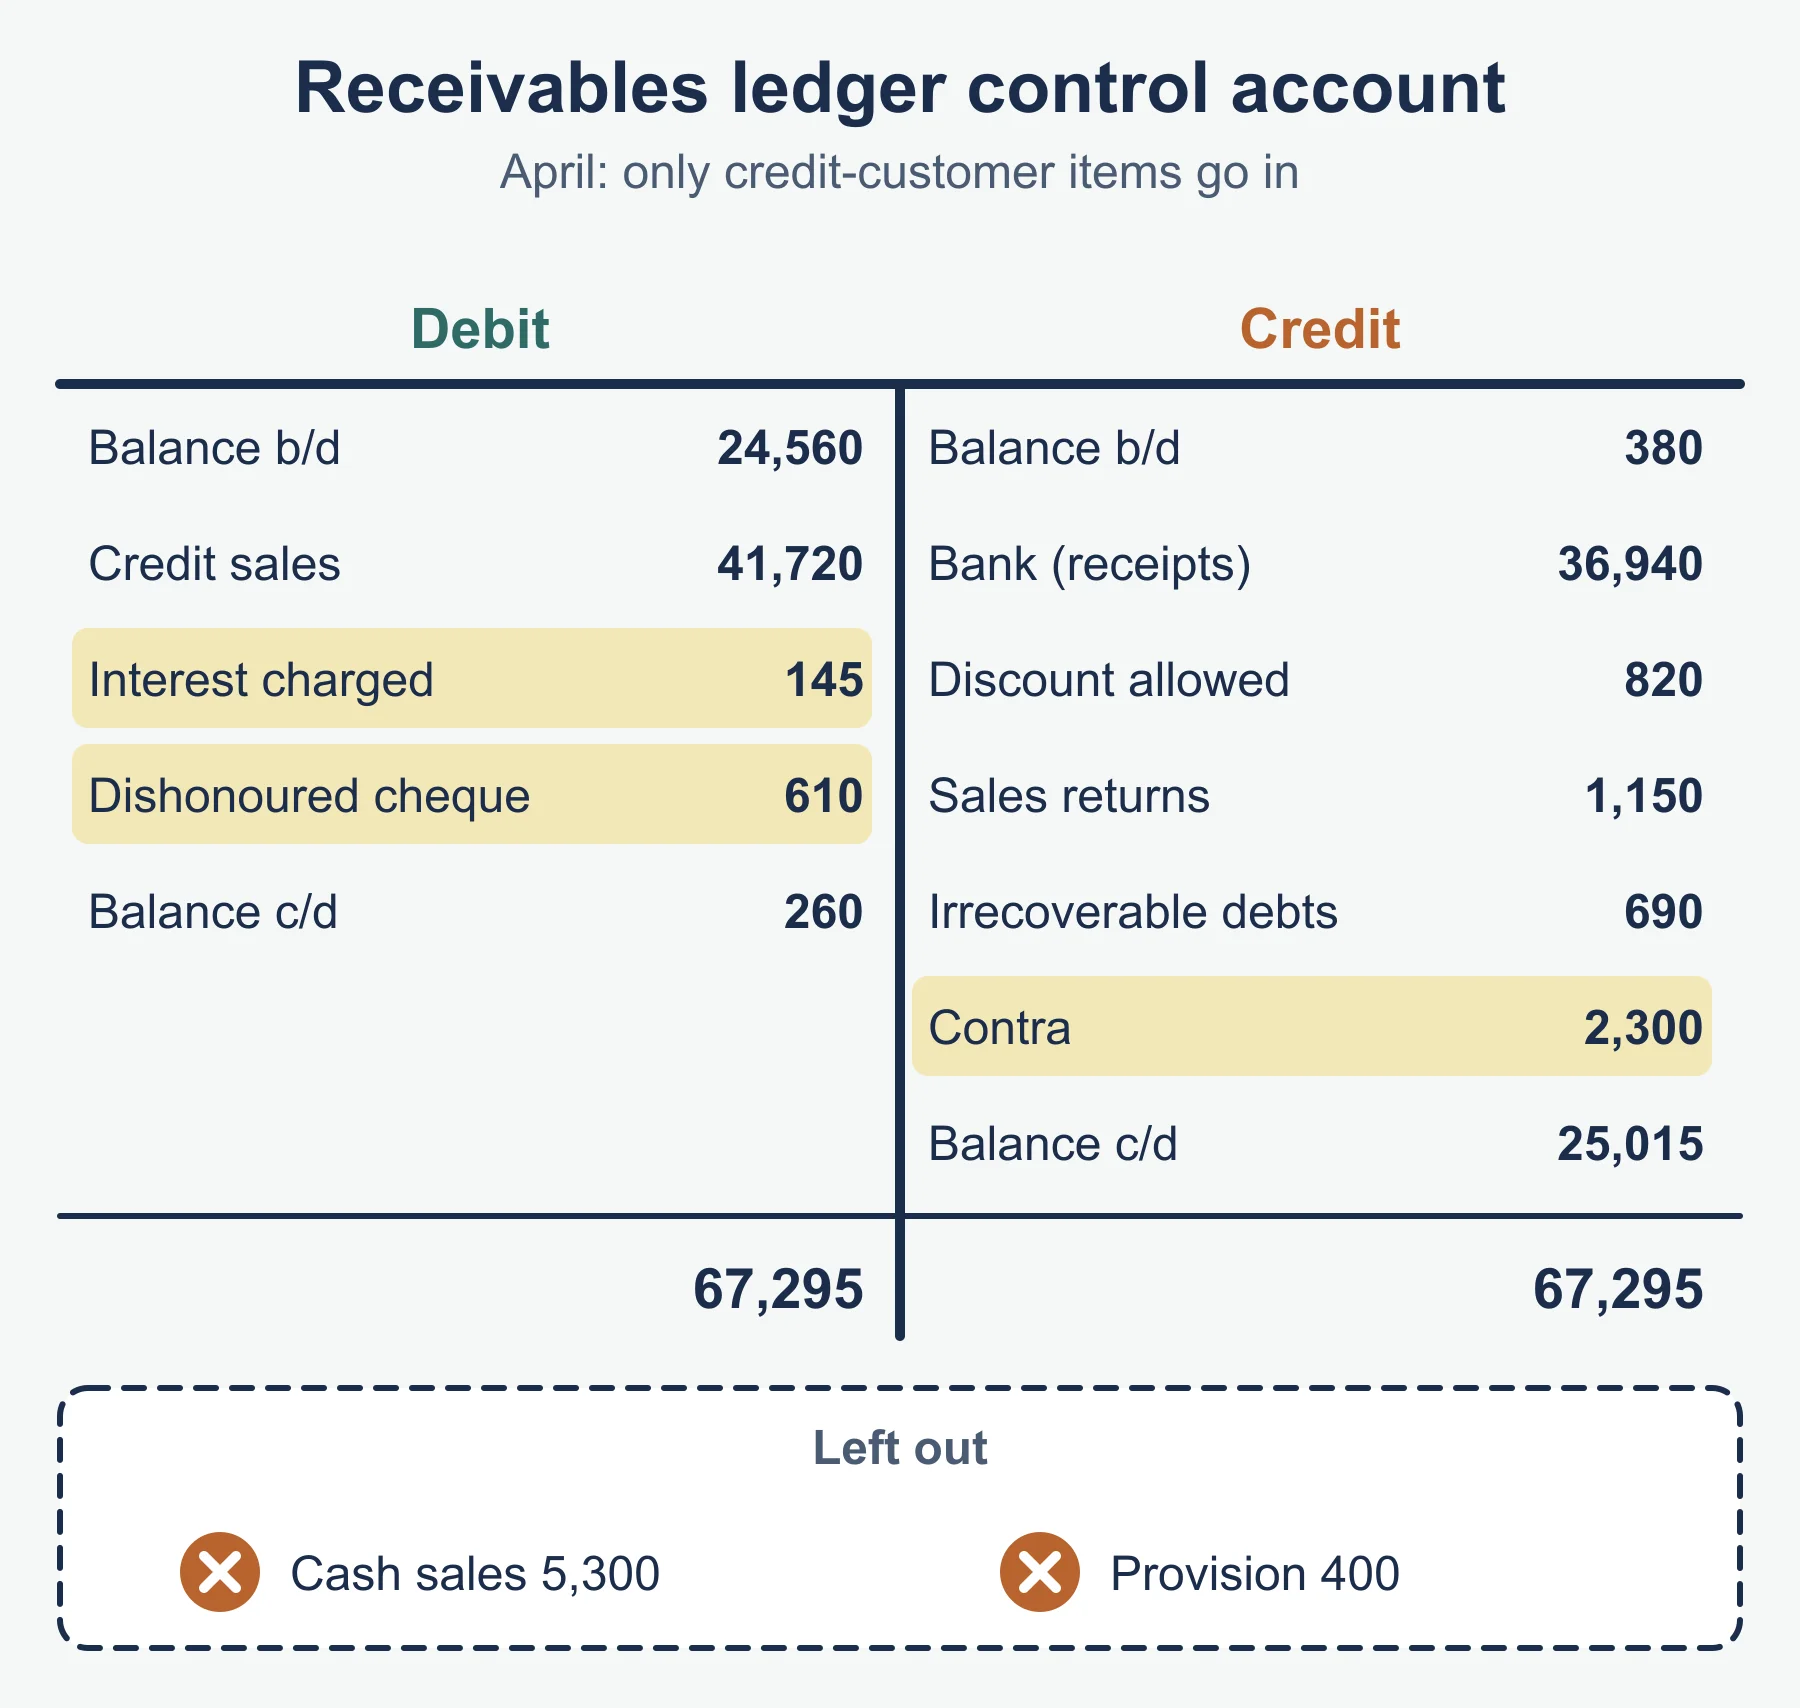
Layout to learn
Trade receivables ledger control account
Debit                                Credit
Balance b/d (debit balances)         Balance b/d (credit balances)
Credit sales                         Bank
Dishonoured cheques                  Cash discount allowed
Interest on overdue accounts         Sales returns
Balance c/d (credit balances)        Irrecoverable debts
                                     Contra: payables ledger
                                     Balance c/d (debit balances)

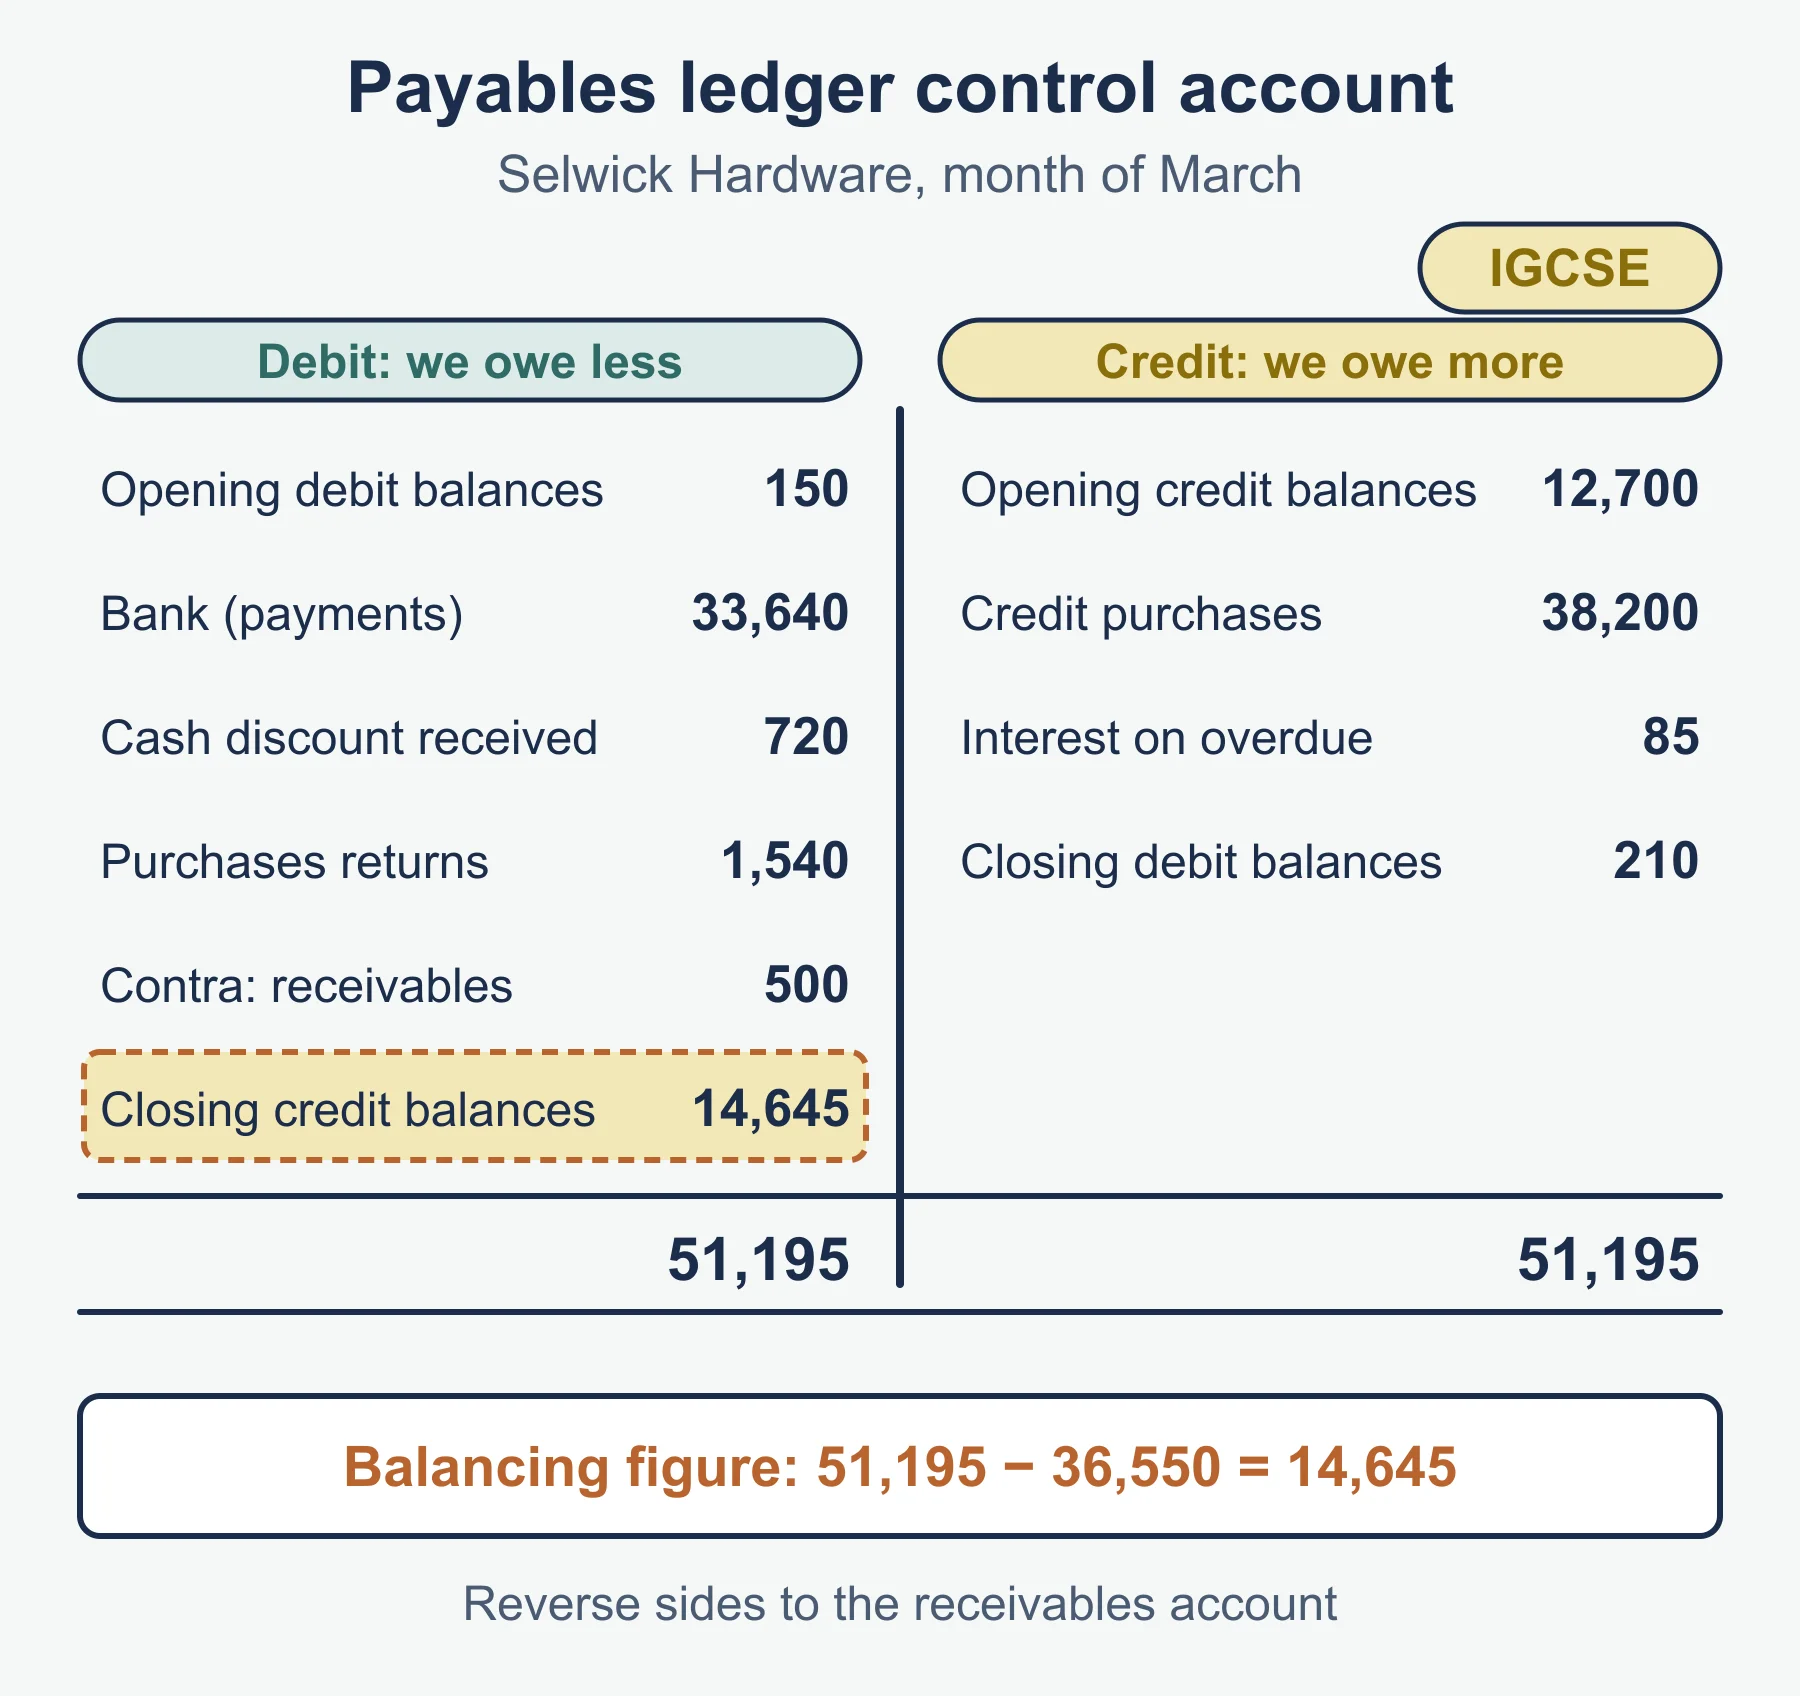
Trade payables ledger control account
Debit                                Credit
Balance b/d (debit balances)         Balance b/d (credit balances)
Bank                                 Credit purchases
Cash discount received               Interest on overdue accounts
Purchases returns                    Balance c/d (debit balances)
Contra: receivables ledger
Balance c/d (credit balances)
Contra entry journal
For a contra of 940, the general journal shows: debit the trader’s account in the payables ledger 940, credit the same trader’s account in the receivables ledger 940. The narrative should say that it is a set-off between ledgers.
Quick self-test
- Is a control account part of the double-entry system?
- State the side on which a dishonoured cheque from a customer goes in the receivables control account.
- Why are cash sales left out of the receivables control account?
- Calculate closing receivables: opening 12,400; credit sales 30,100; receipts 28,650; sales returns 900; discount allowed 350; irrecoverable debts 400.
- Calculate credit purchases from: opening payables 8,300; closing payables 9,150; payments 22,400; discount received 280; purchases returns 520.
- A customer owes the business 1,800 and is also owed 2,500 by it. State the contra amount and the amount still owed to the customer.
- On which side of the payables control account do debit balances in the payables ledger go when they are brought down at the start of the period?
- The control account balance is 14,950 and the list totals 14,740. State the difference and one possible cause.
- State one reason why the control account and list may agree even though a customer account is wrong.
- A supplier charges the business 60 interest on an overdue account. On which side of the payables control account does this go?
Answers
- No. It is a memorandum record.
- The debit side.
- Cash sales do not pass through a customer account, so they are not part of the receivables ledger.
- 12,400 + 30,100 - 28,650 - 900 - 350 - 400 = 12,200.
- 9,150 - 8,300 + 22,400 + 280 + 520 = 24,050.
- The contra is 1,800, and the business still owes the customer 700.
- The debit side.
- The difference is 210 (the list is lower). One cause: a sales invoice not posted to a customer account.
- A payment or receipt posted to the wrong customer’s account, which leaves the total unchanged.
- The credit side.
Where marks are usually lost
- Putting a receivables item on the payables side because the sides are opposite.
- Forgetting the opening credit balances in the receivables ledger or the opening debit balances in the payables ledger.
- Showing a contra in one control account only.
- Treating a dishonoured cheque as a credit.
- Omitting a clear statement that the control account is a memorandum record when the question asks for its nature.
- Adding the discount to the wrong side.
- Writing a balancing figure without totalling both sides.
- Stating that agreement between the control account and the list proves the ledger is correct.
Frequently asked questions
What is a trade receivables ledger control account? It is a summary account showing the totals of all transactions with credit customers for a period: opening balances, credit sales, receipts, returns, discounts allowed, irrecoverable debts and contras. Its closing balance should equal the total of the individual customer accounts.
Is a control account part of the double-entry system? In OxfordAQA IGCSE Accounting 9215, control accounts are treated as memorandum records. They check the accuracy of the ledger and give a quick total of amounts owed, rather than forming part of the double entry.
Does an agreeing control account prove the ledger is correct? No. Some errors do not affect the totals, such as a receipt posted to the wrong customer’s account, so the control account balance and the list of balances can still agree while an individual account is wrong.
How do you find a missing figure such as credit sales using a control account? Enter all the known figures in the control account, including the opening and closing balances, and the missing item is the amount needed to make the two sides total the same.
Official syllabus
These notes are based on the OxfordAQA International GCSE Accounting (9215) specification, version 1.2, section 3.2, Verification of accounting records, published by OxfordAQA.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
OxfordAQA IGCSE Accounting: Verification of double entry records and the trial balance (9215)
Guide to preparing, correcting and judging a trial balance, with every error type it does and does not reveal, for OxfordAQA IGCSE Accounting 9215.
Accounting · OxfordAQA · IGCSE
Read guide -
Practice questions
OxfordAQA IGCSE Accounting: Double entry verification and the trial balance (9215) – Practice Questions
Ten original questions with worked answers on preparing, correcting and evaluating a trial balance for OxfordAQA International GCSE Accounting 9215.
Accounting · OxfordAQA · IGCSE
Try questions -
Revision notes
OxfordAQA IGCSE Accounting: Double entry verification and the trial balance (9215) – Revision Notes
Condensed recall notes on preparing and correcting a trial balance and on the ten error types, for OxfordAQA International GCSE Accounting 9215.
Accounting · OxfordAQA · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
OxfordAQA Accounting teachers at Marlbridge

