
Revision Notes
A Level Business: The nature of operations (Cambridge 9609) – Revision Notes
Condensed revision notes for Cambridge AS & A Level Business section 4.1: added value, productivity, sustainability and operations methods.
- Subject
- Business
- Level
- AS LEVEL
- Topic
- Operations management
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to Cambridge A Level Business (9609), For examination in 2026, 2027 and 2028. Official specification .
Syllabus page (what it covers and how it is assessed): Cambridge A Level Business.
Syllabus points this page covers
9609 (AS Level)
- 4.1 The nature of operations
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Business (9609).
These notes condense section 4.1, The nature of operations, from the Cambridge International AS & A Level Business 9609 syllabus for examination in 2026, 2027 and 2028 (AS Level topic 4). For full explanations and worked examples, read the study guide. Then test yourself with the practice questions.
Related pages: the operations practice questions for section 4.2, the Cambridge A Level Business hub, the printable checklist and the free diagnostics.
4.1.1 The transformational process
- Stages: inputs, then transformation, then outputs.
- Inputs: materials, components, labour, machines, energy, finance.
- Output: a good or a service. Services have a process too.
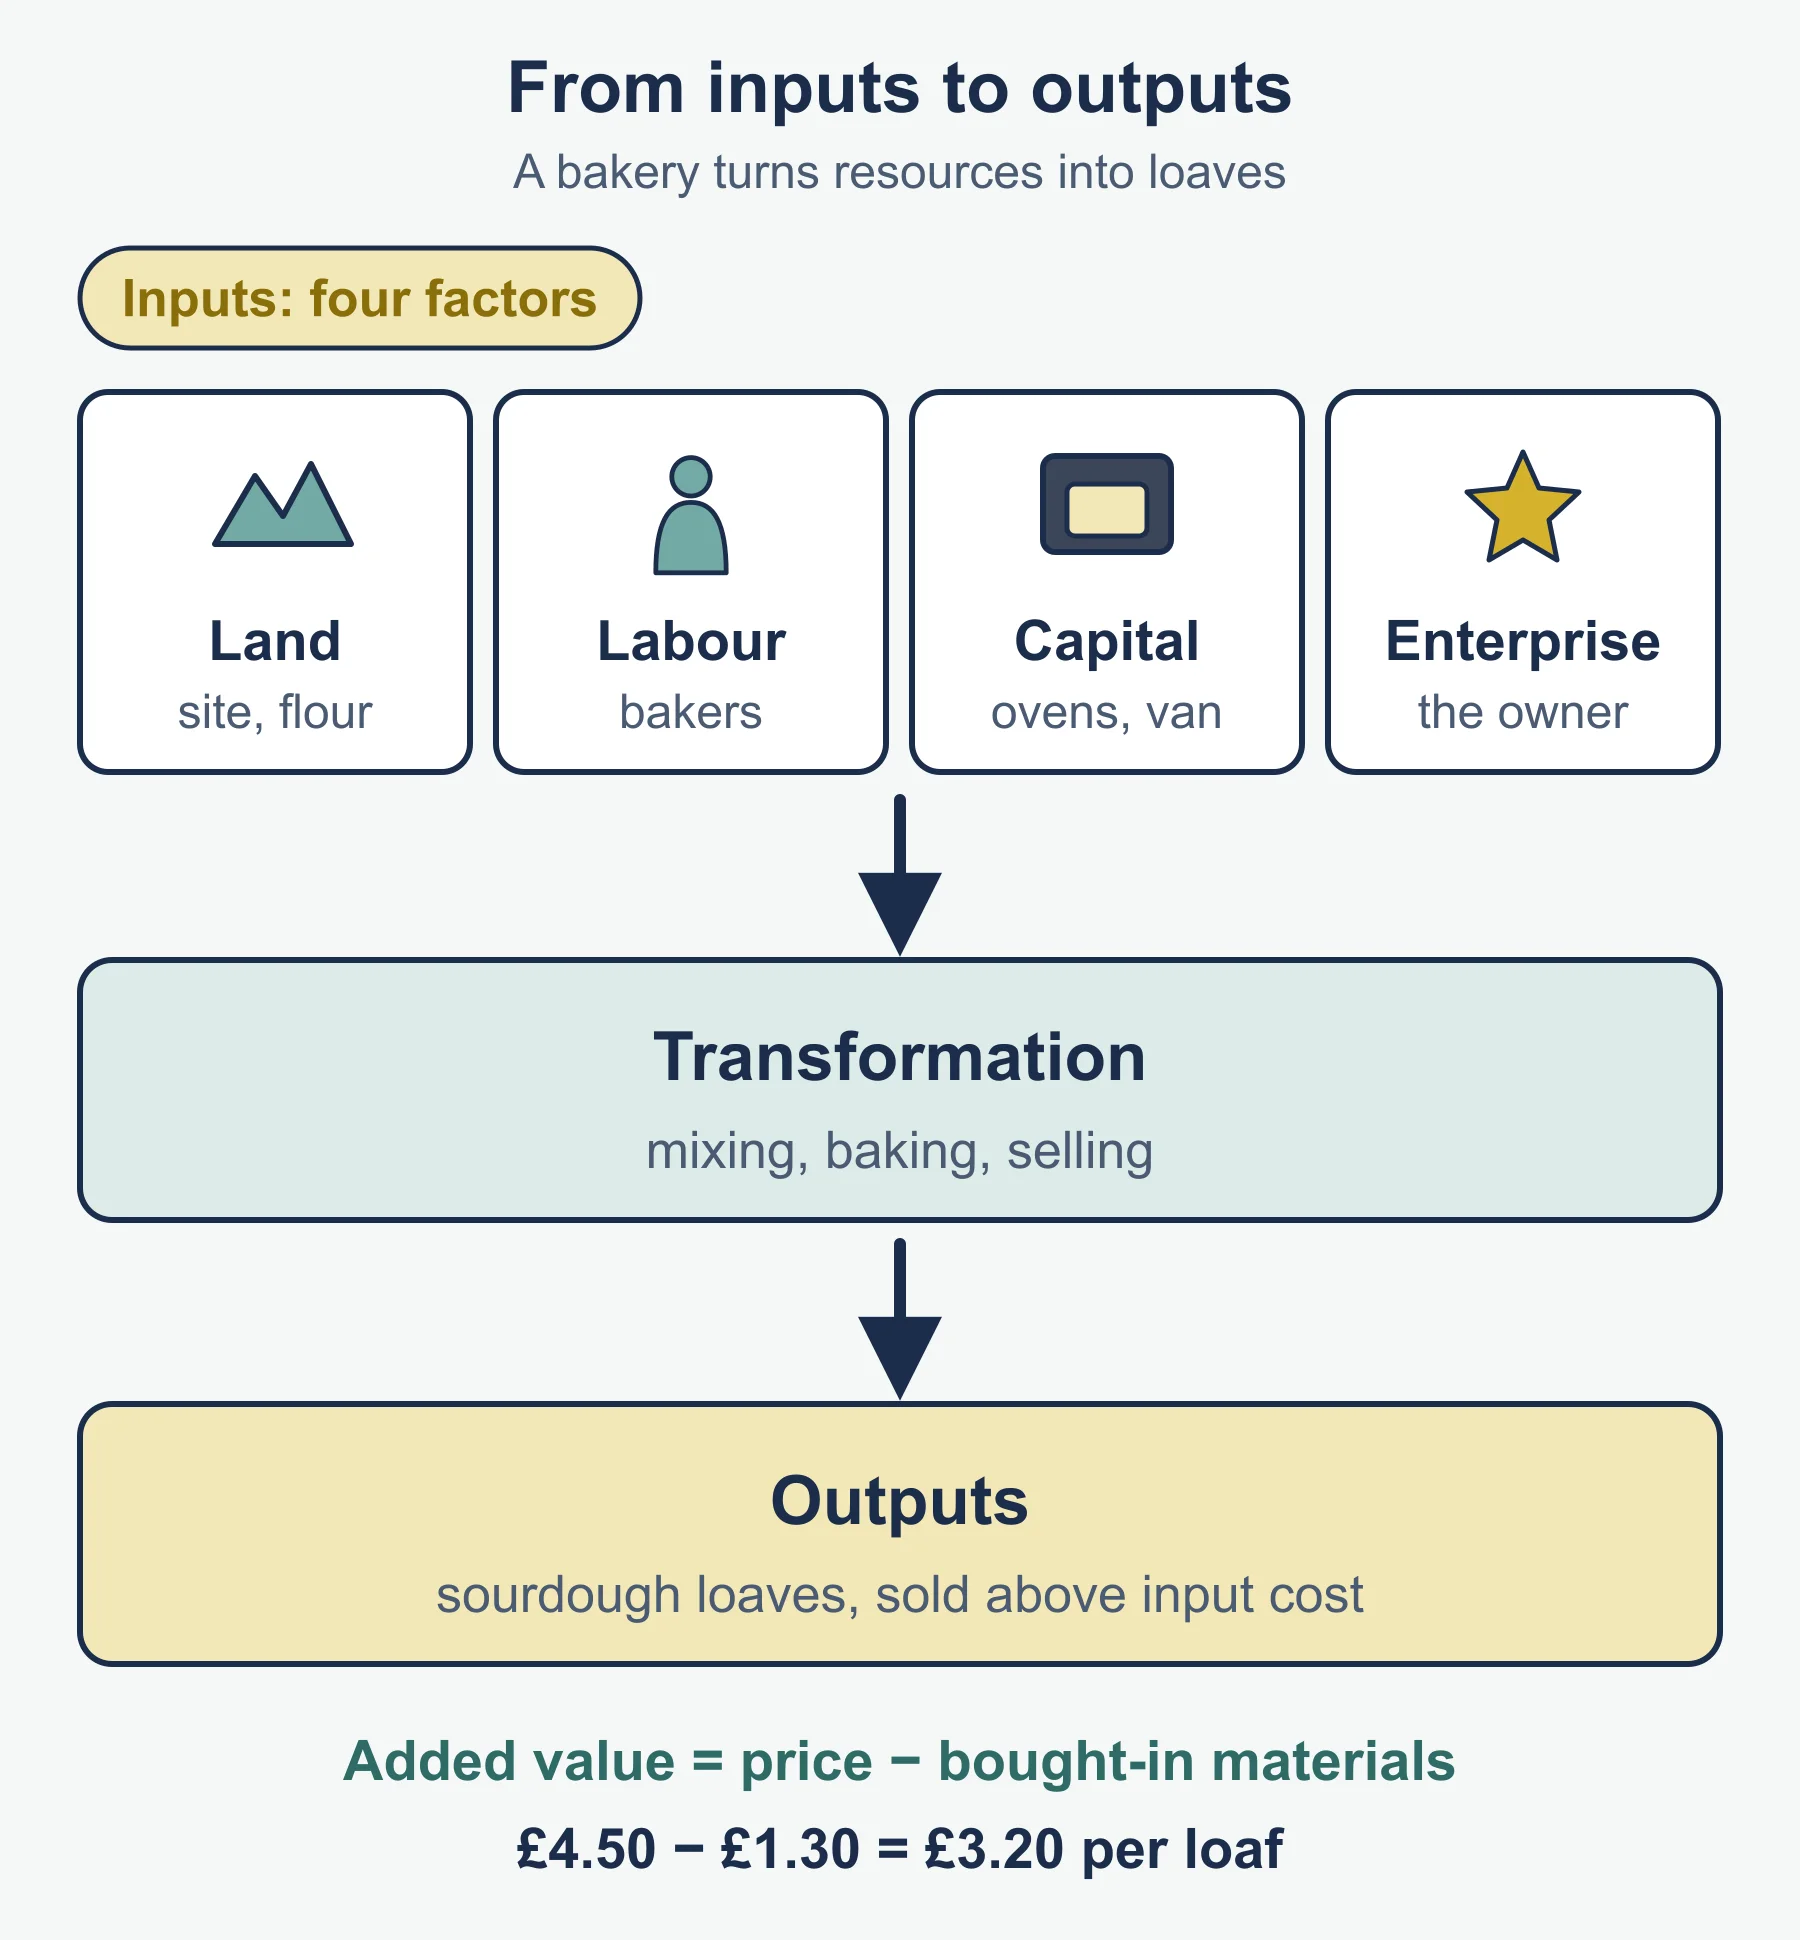
- Factors of production: land, labour, capital, enterprise.
| Factor | One-line meaning | Quick example |
|---|---|---|
| Land | Natural resources and the site | A farm, a shop site |
| Labour | Human effort | A chef, a driver |
| Capital | Man-made resources used to produce | An oven, a van |
| Enterprise | Organising the factors and taking risk | The owner |
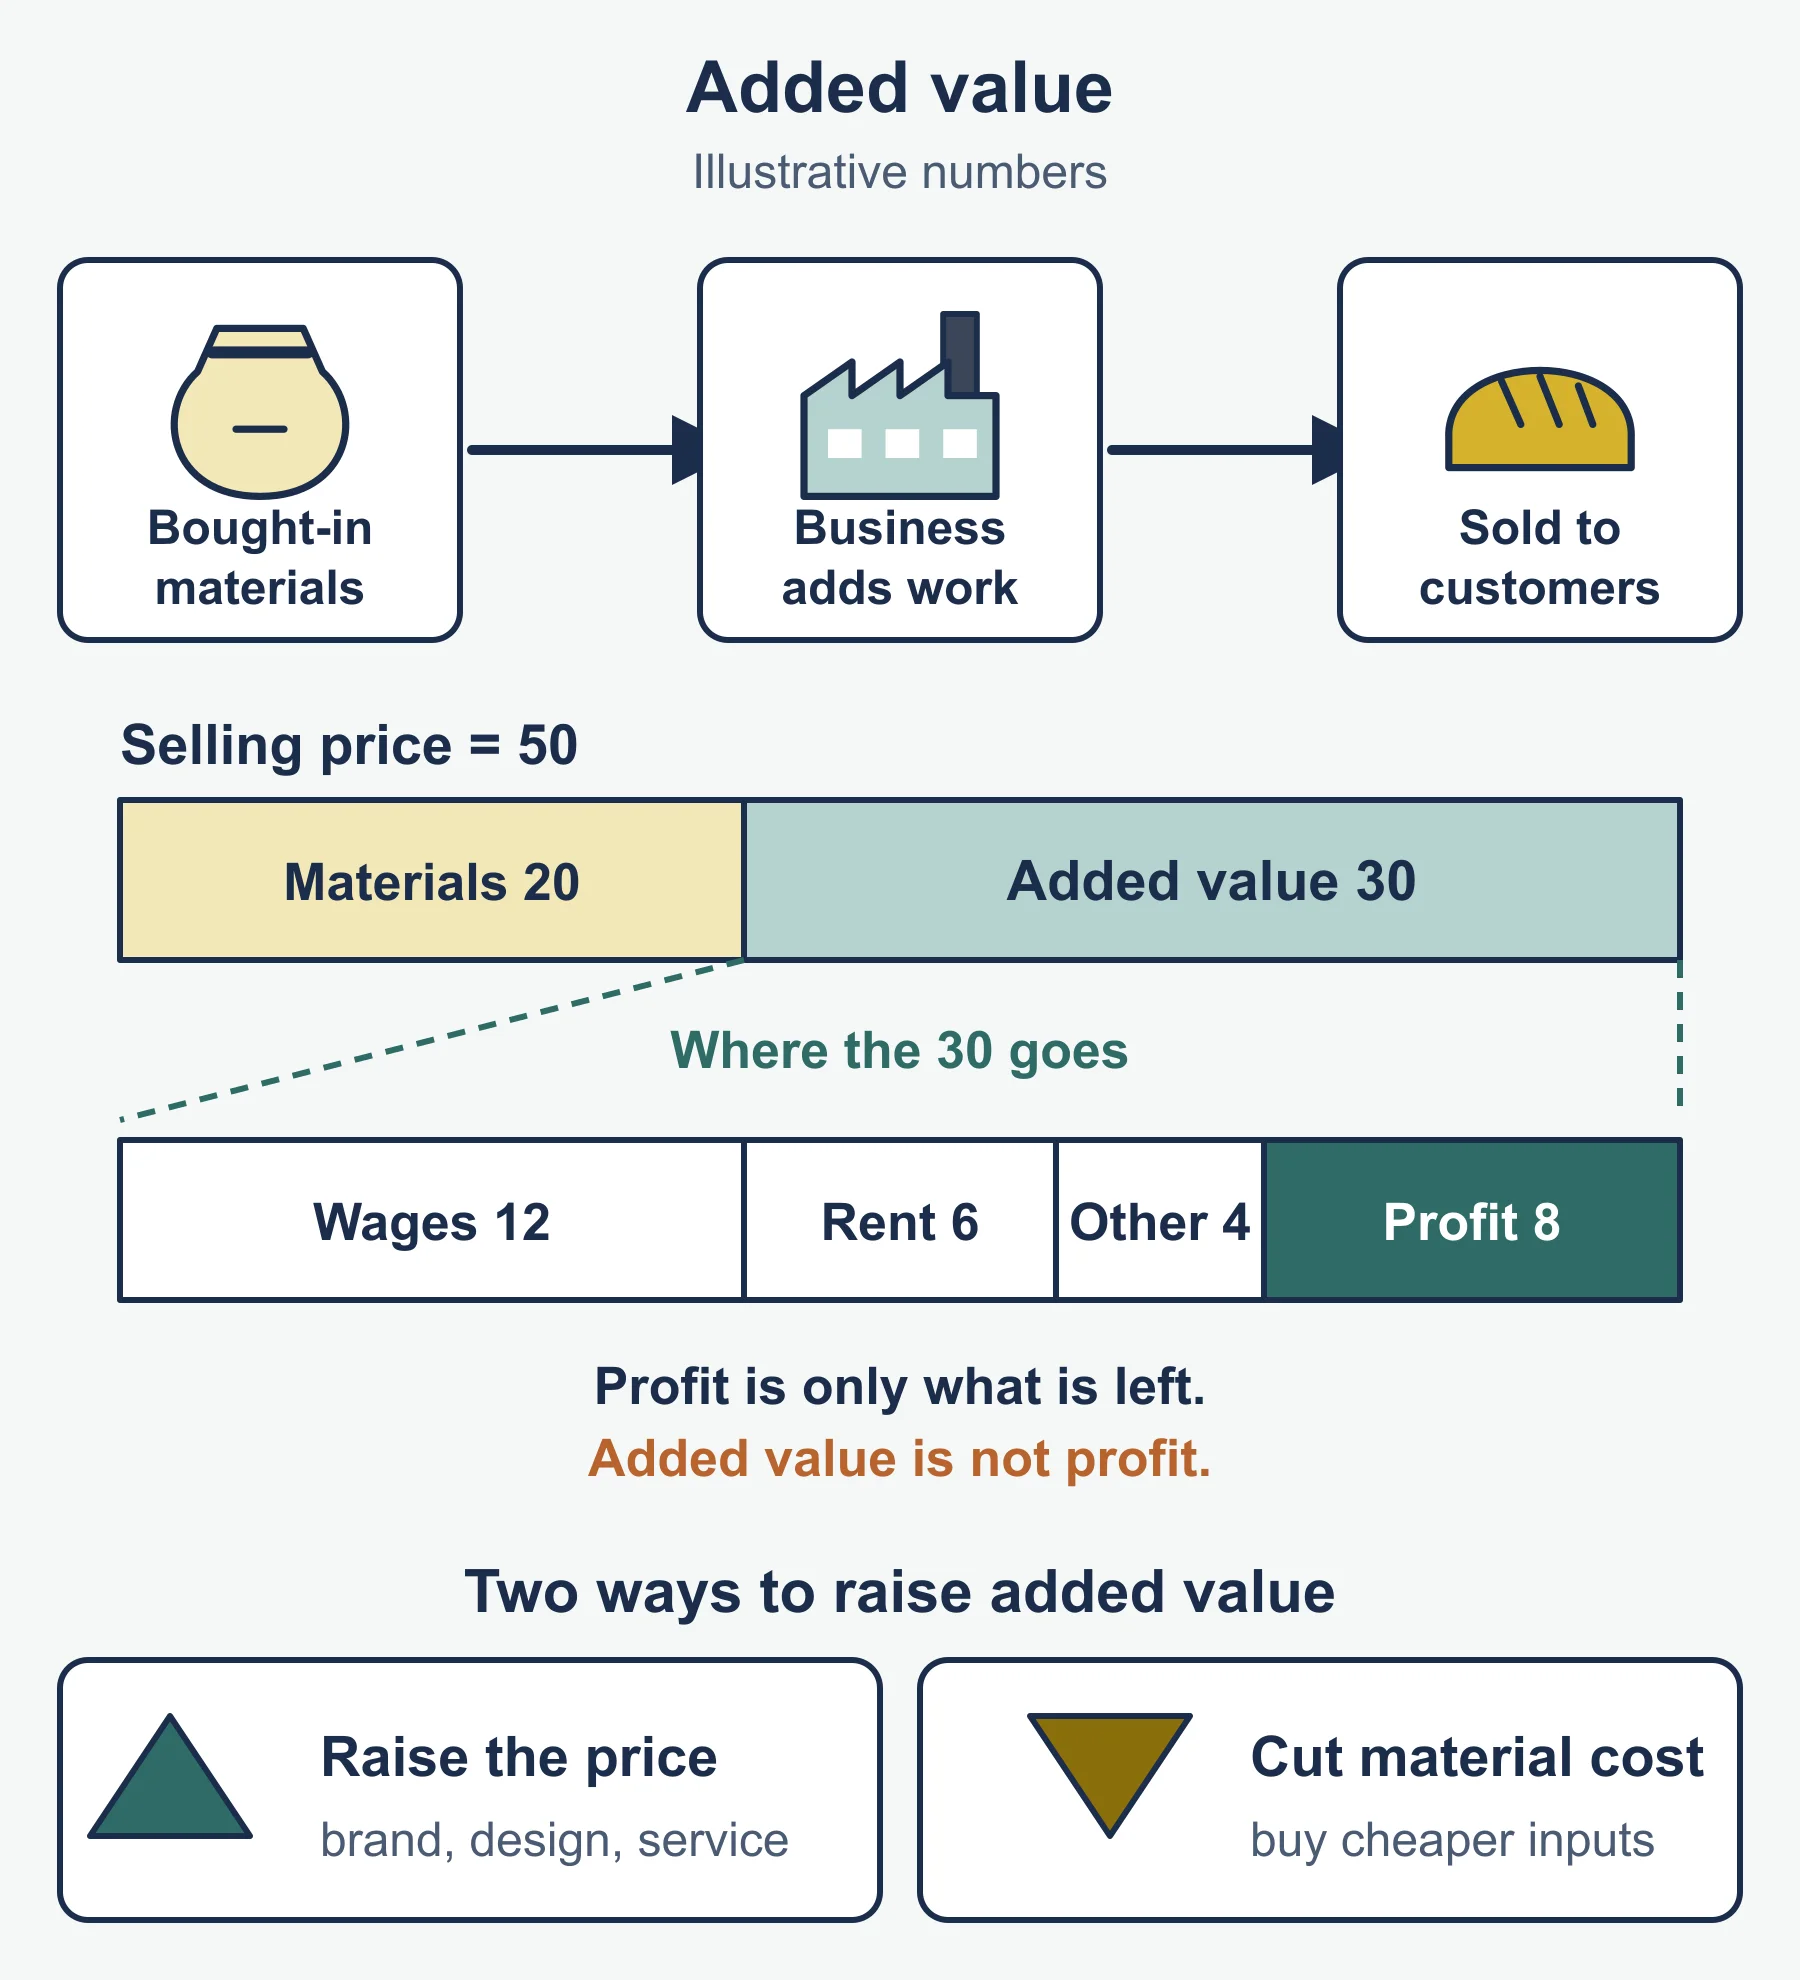
Added value = selling price - cost of bought-in materials and components (standard form). It is not profit. Operations add value by transforming inputs. Raise it by raising the price customers accept or cutting input costs.
Reminder: price £12, bought-in inputs £7.50. Added value = £4.50 per unit. At 3,000 units, £13,500 in total.
4.1.2 Efficiency, effectiveness, productivity, sustainability
| Term | Meaning | Why it matters |
|---|---|---|
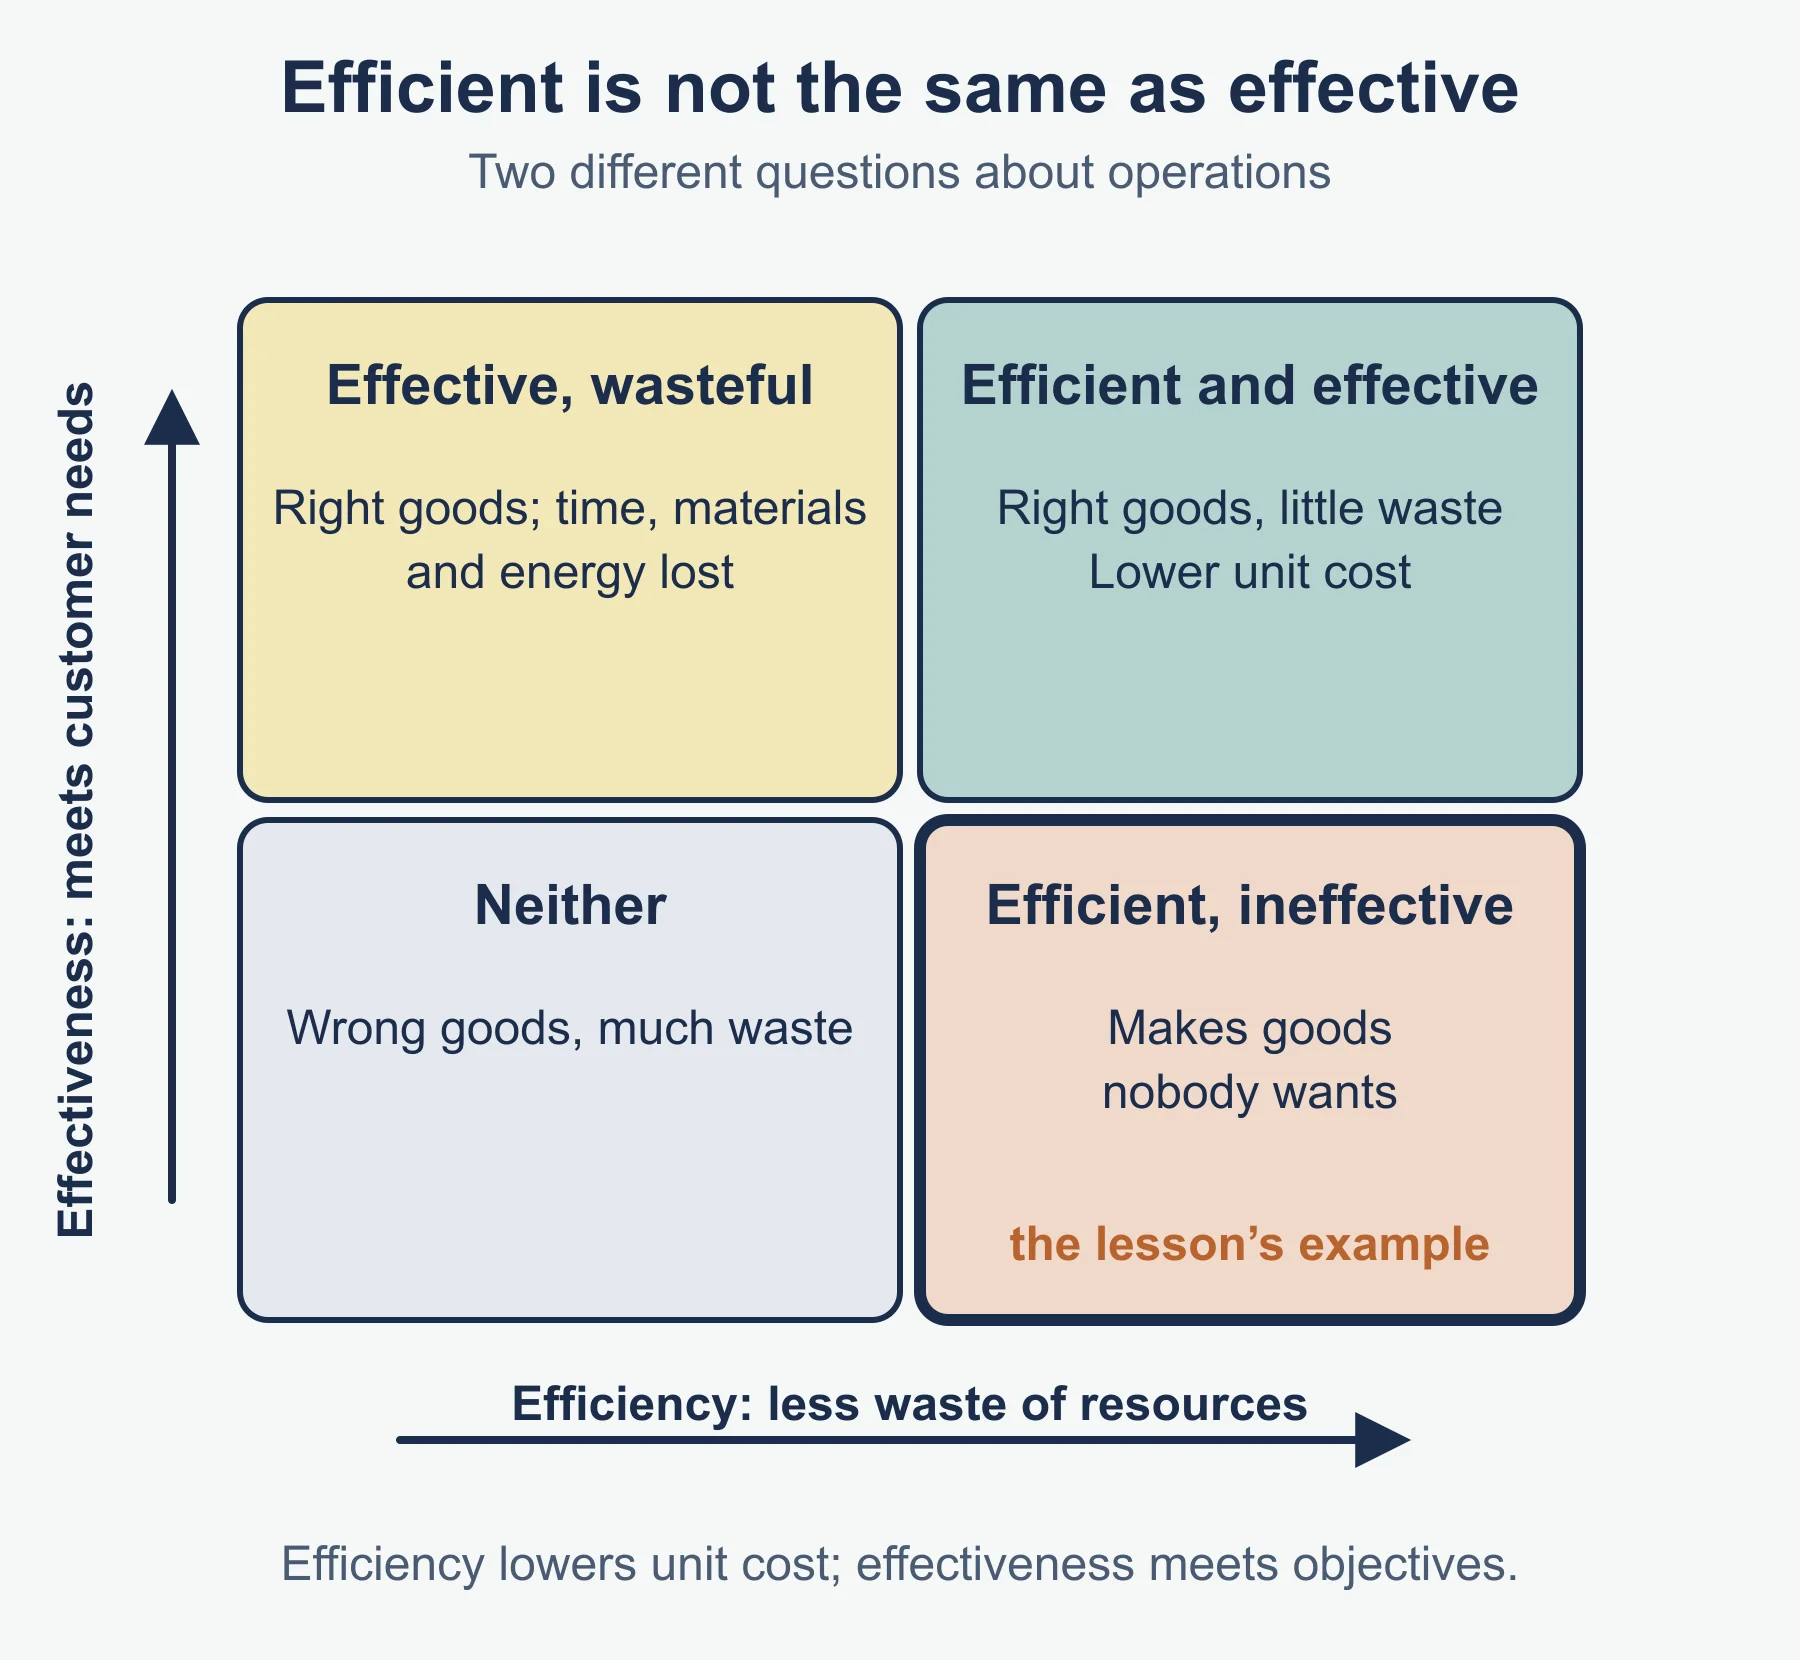
| Efficiency | Output with least waste of resources | Lower unit costs |
| Effectiveness | Achieving the business’s aims and customer needs | Sales, reputation, objectives |
| Productivity | Output compared with inputs used | Lower cost per unit, more competitive |
| Sustainability | Operating without using up resources or harming the environment | Long-term survival, image, rules |
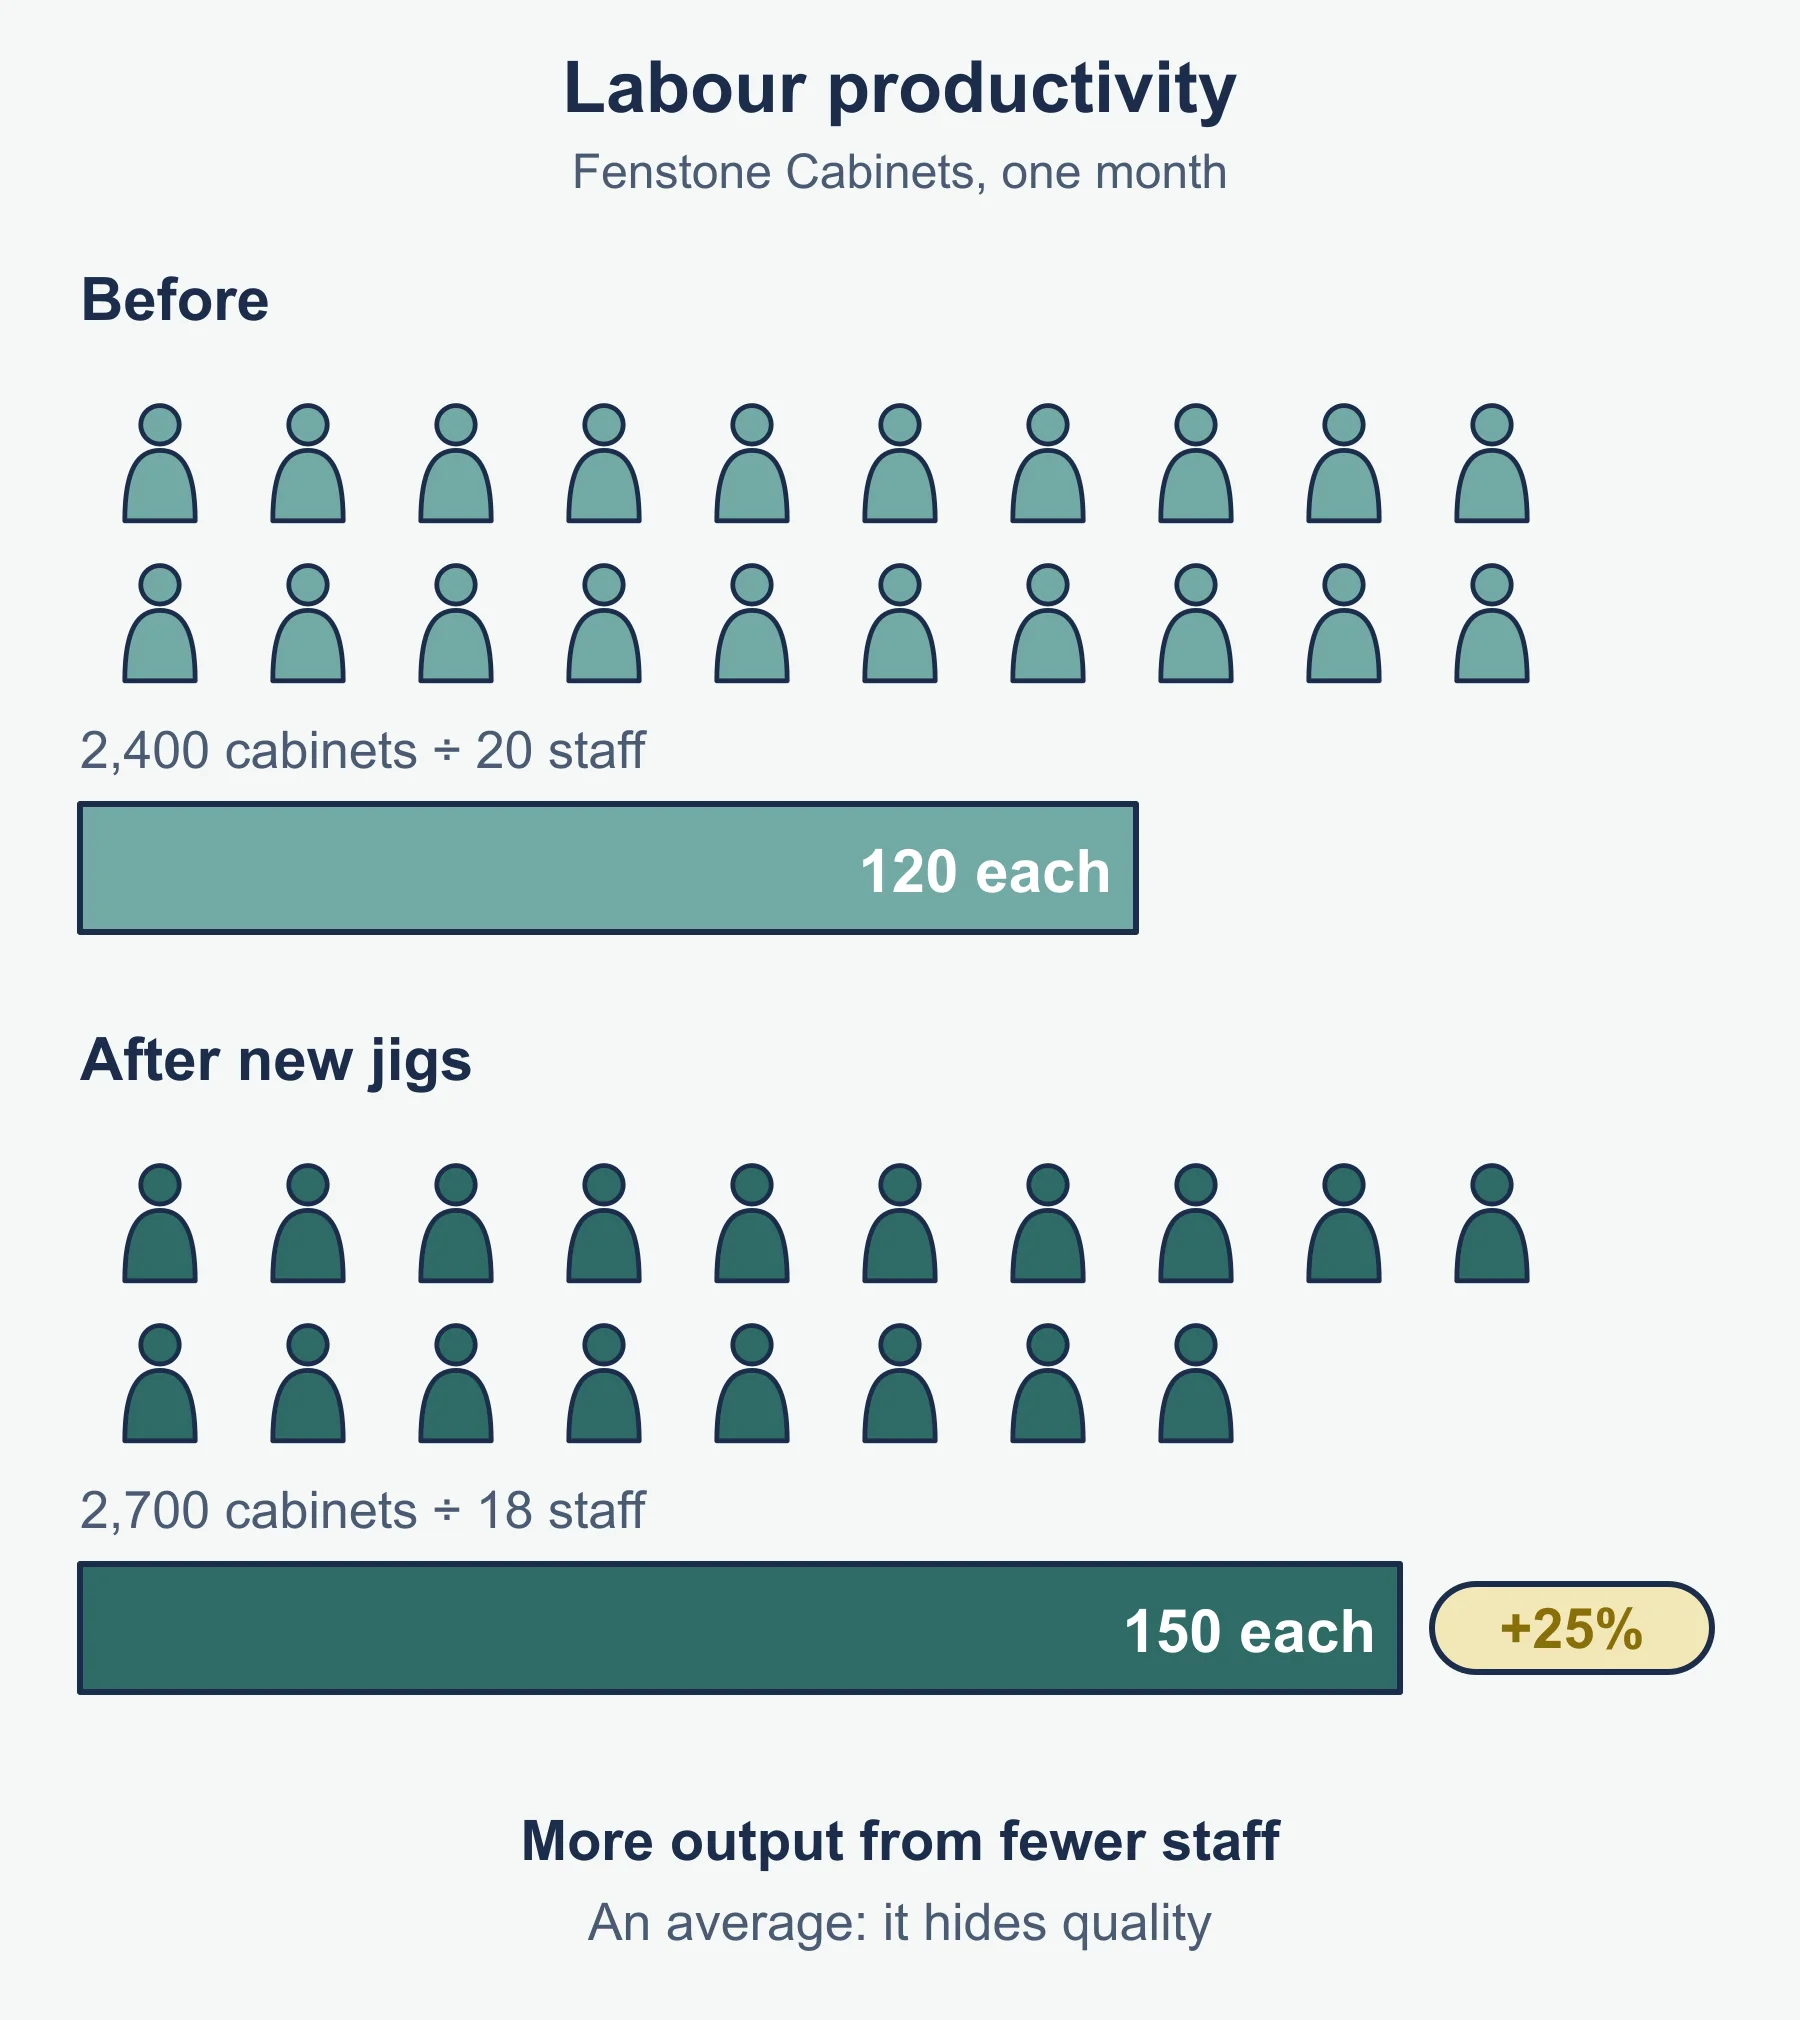
Labour productivity (standard form) = output in a period / number of employees in that period.
Method in steps:
- Find the output for the period.
- Find the number of employees (or hours worked).
- Divide output by employees.
- For change: (new - old) / old x 100.
Reminder: 5,400 units from 30 workers = 180 per worker. Next month 5,880 from 28 workers = 210 per worker. Change = (210 - 180) / 180 x 100 = +16.7%.
Sustainability measures: cut energy use, recycle or reuse waste, renewable energy, responsible sourcing.
| Impact | Direction |
|---|---|
| Running costs | Often fall (less energy, less waste) |
| Set-up costs | Often rise (equipment, training) |
| Demand and image | May improve for customers who care |
| Risk | Lower exposure to rules and objections |
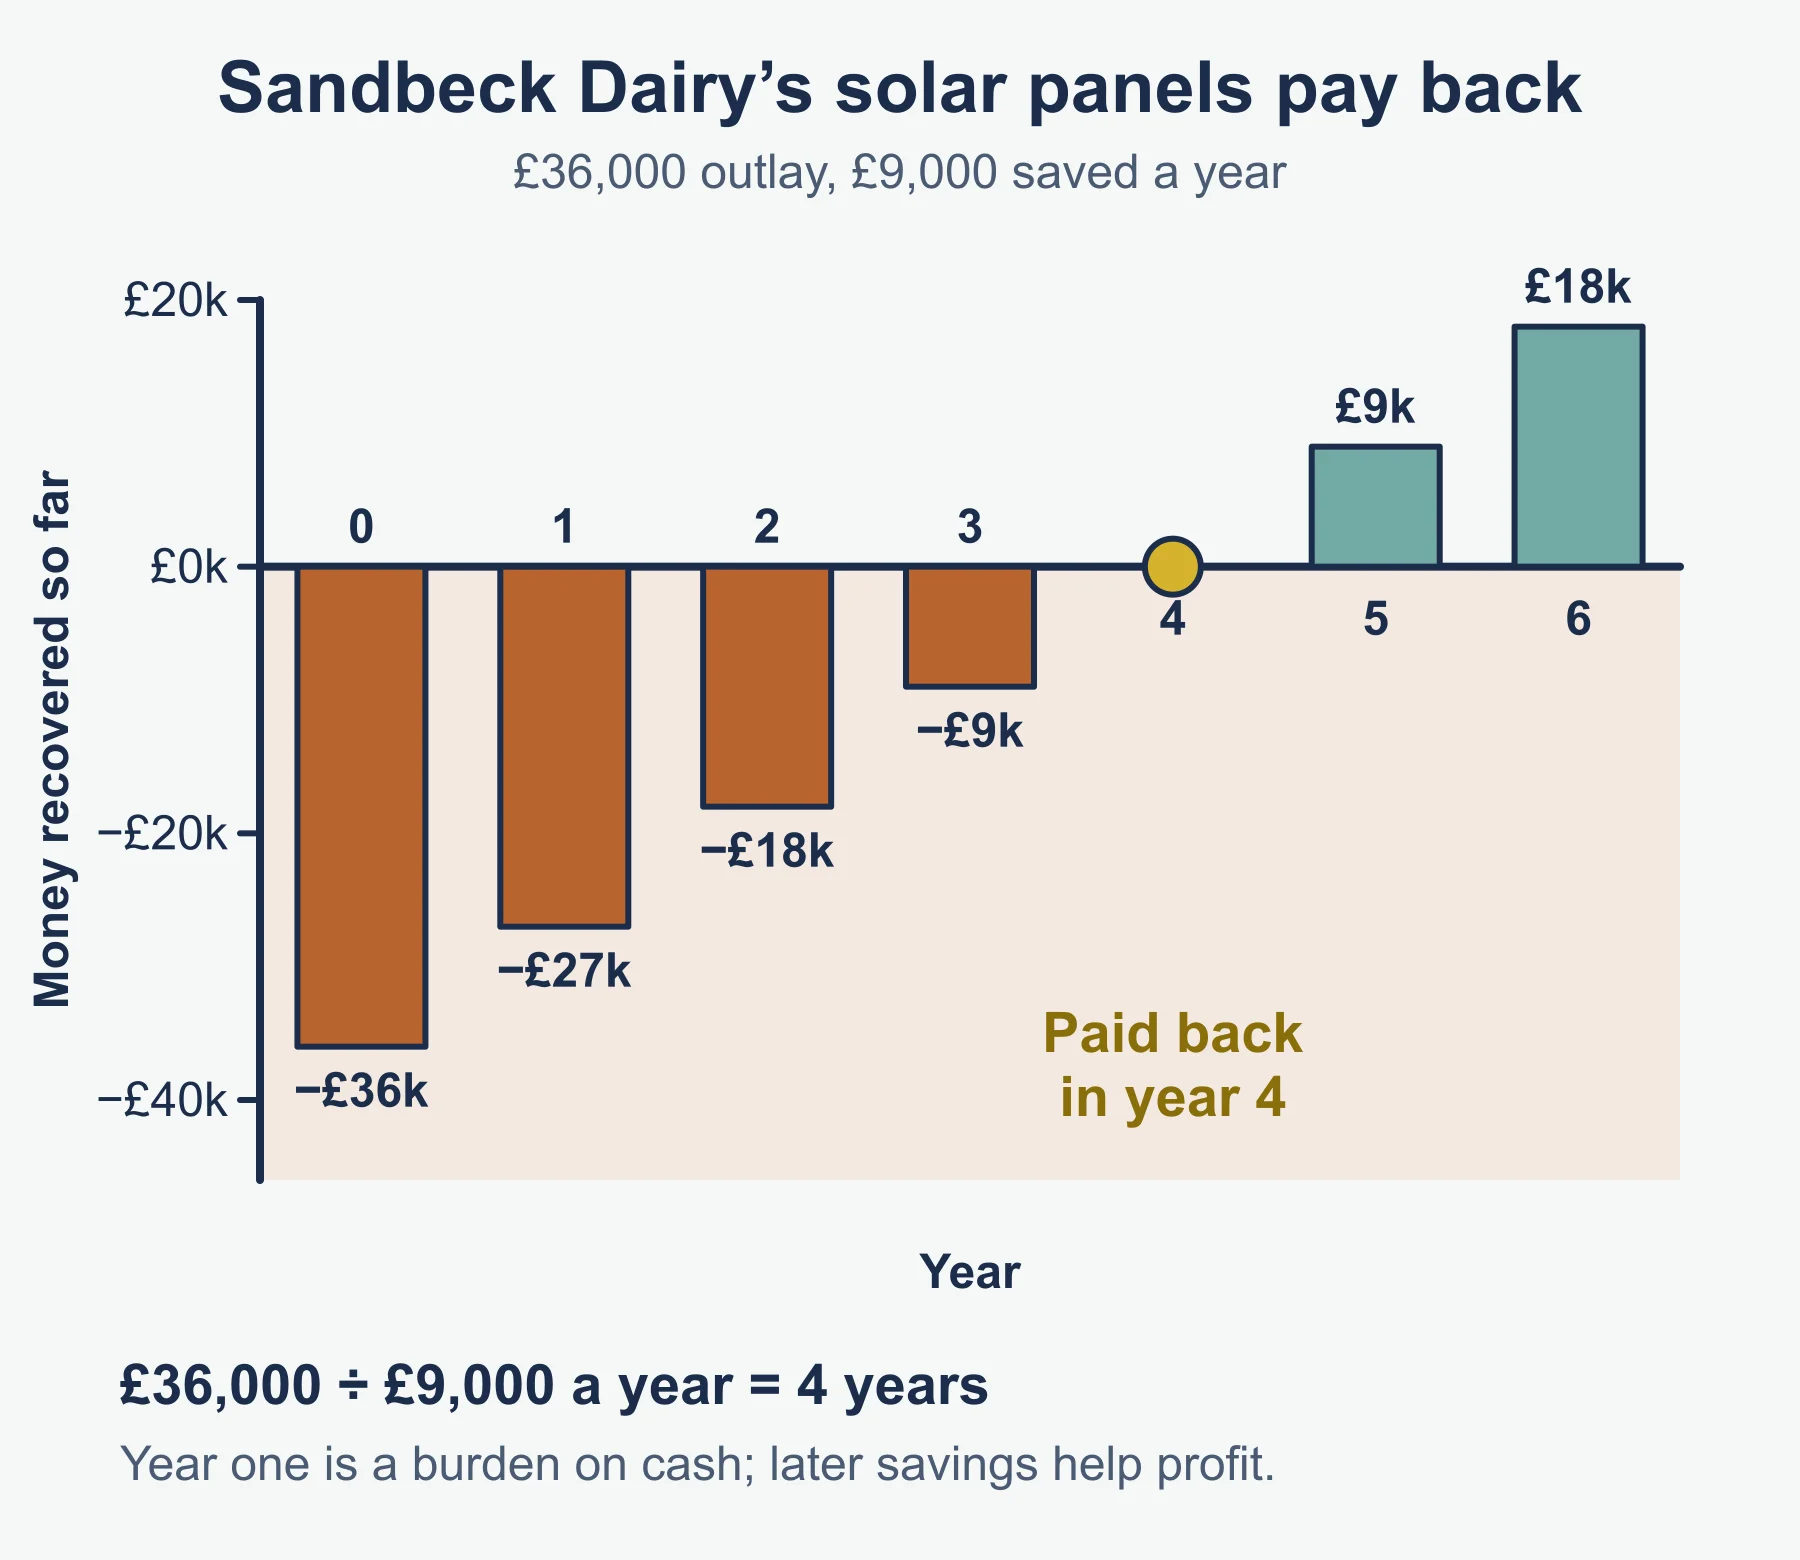
Decision rule: compare the outlay with the yearly saving and the time the business expects to stay. £24,000 outlay saving £6,000 a year is recovered in 4 years.
4.1.3 Capital intensive and labour intensive
| Benefits | Limitations | |
|---|---|---|
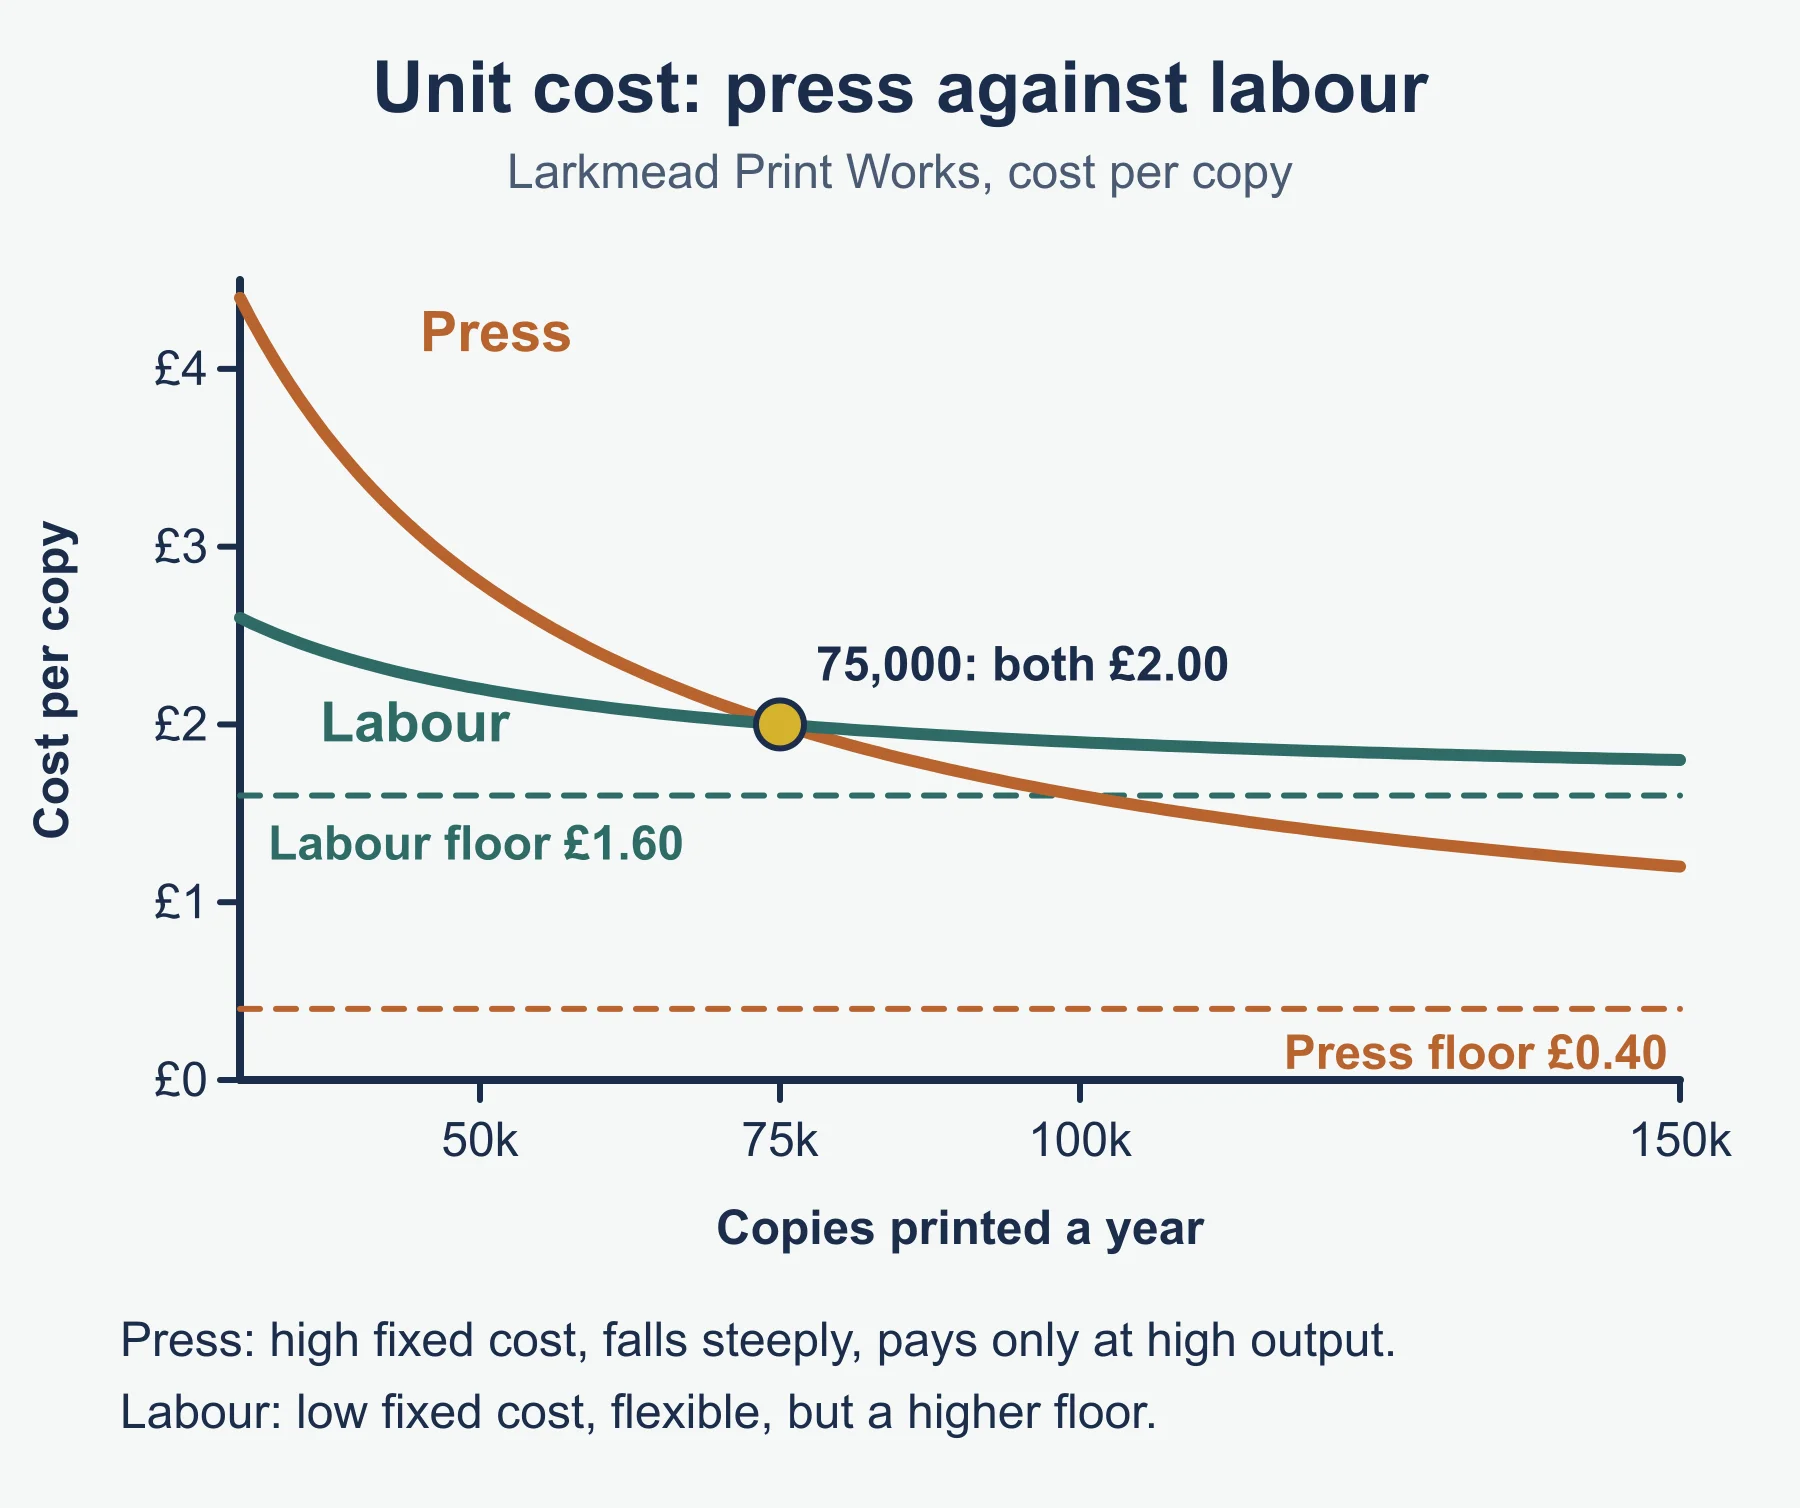
| Capital intensive | Low variable cost per unit. Consistent quality. Long running hours. | High fixed costs. Inflexible. Breakdowns halt output. Needs high volume. |
| Labour intensive | Flexible. Personal service. Low fixed costs. | Higher cost per unit. Variable quality. Output limited by staff numbers. |
Method in steps for choosing between two set-ups:
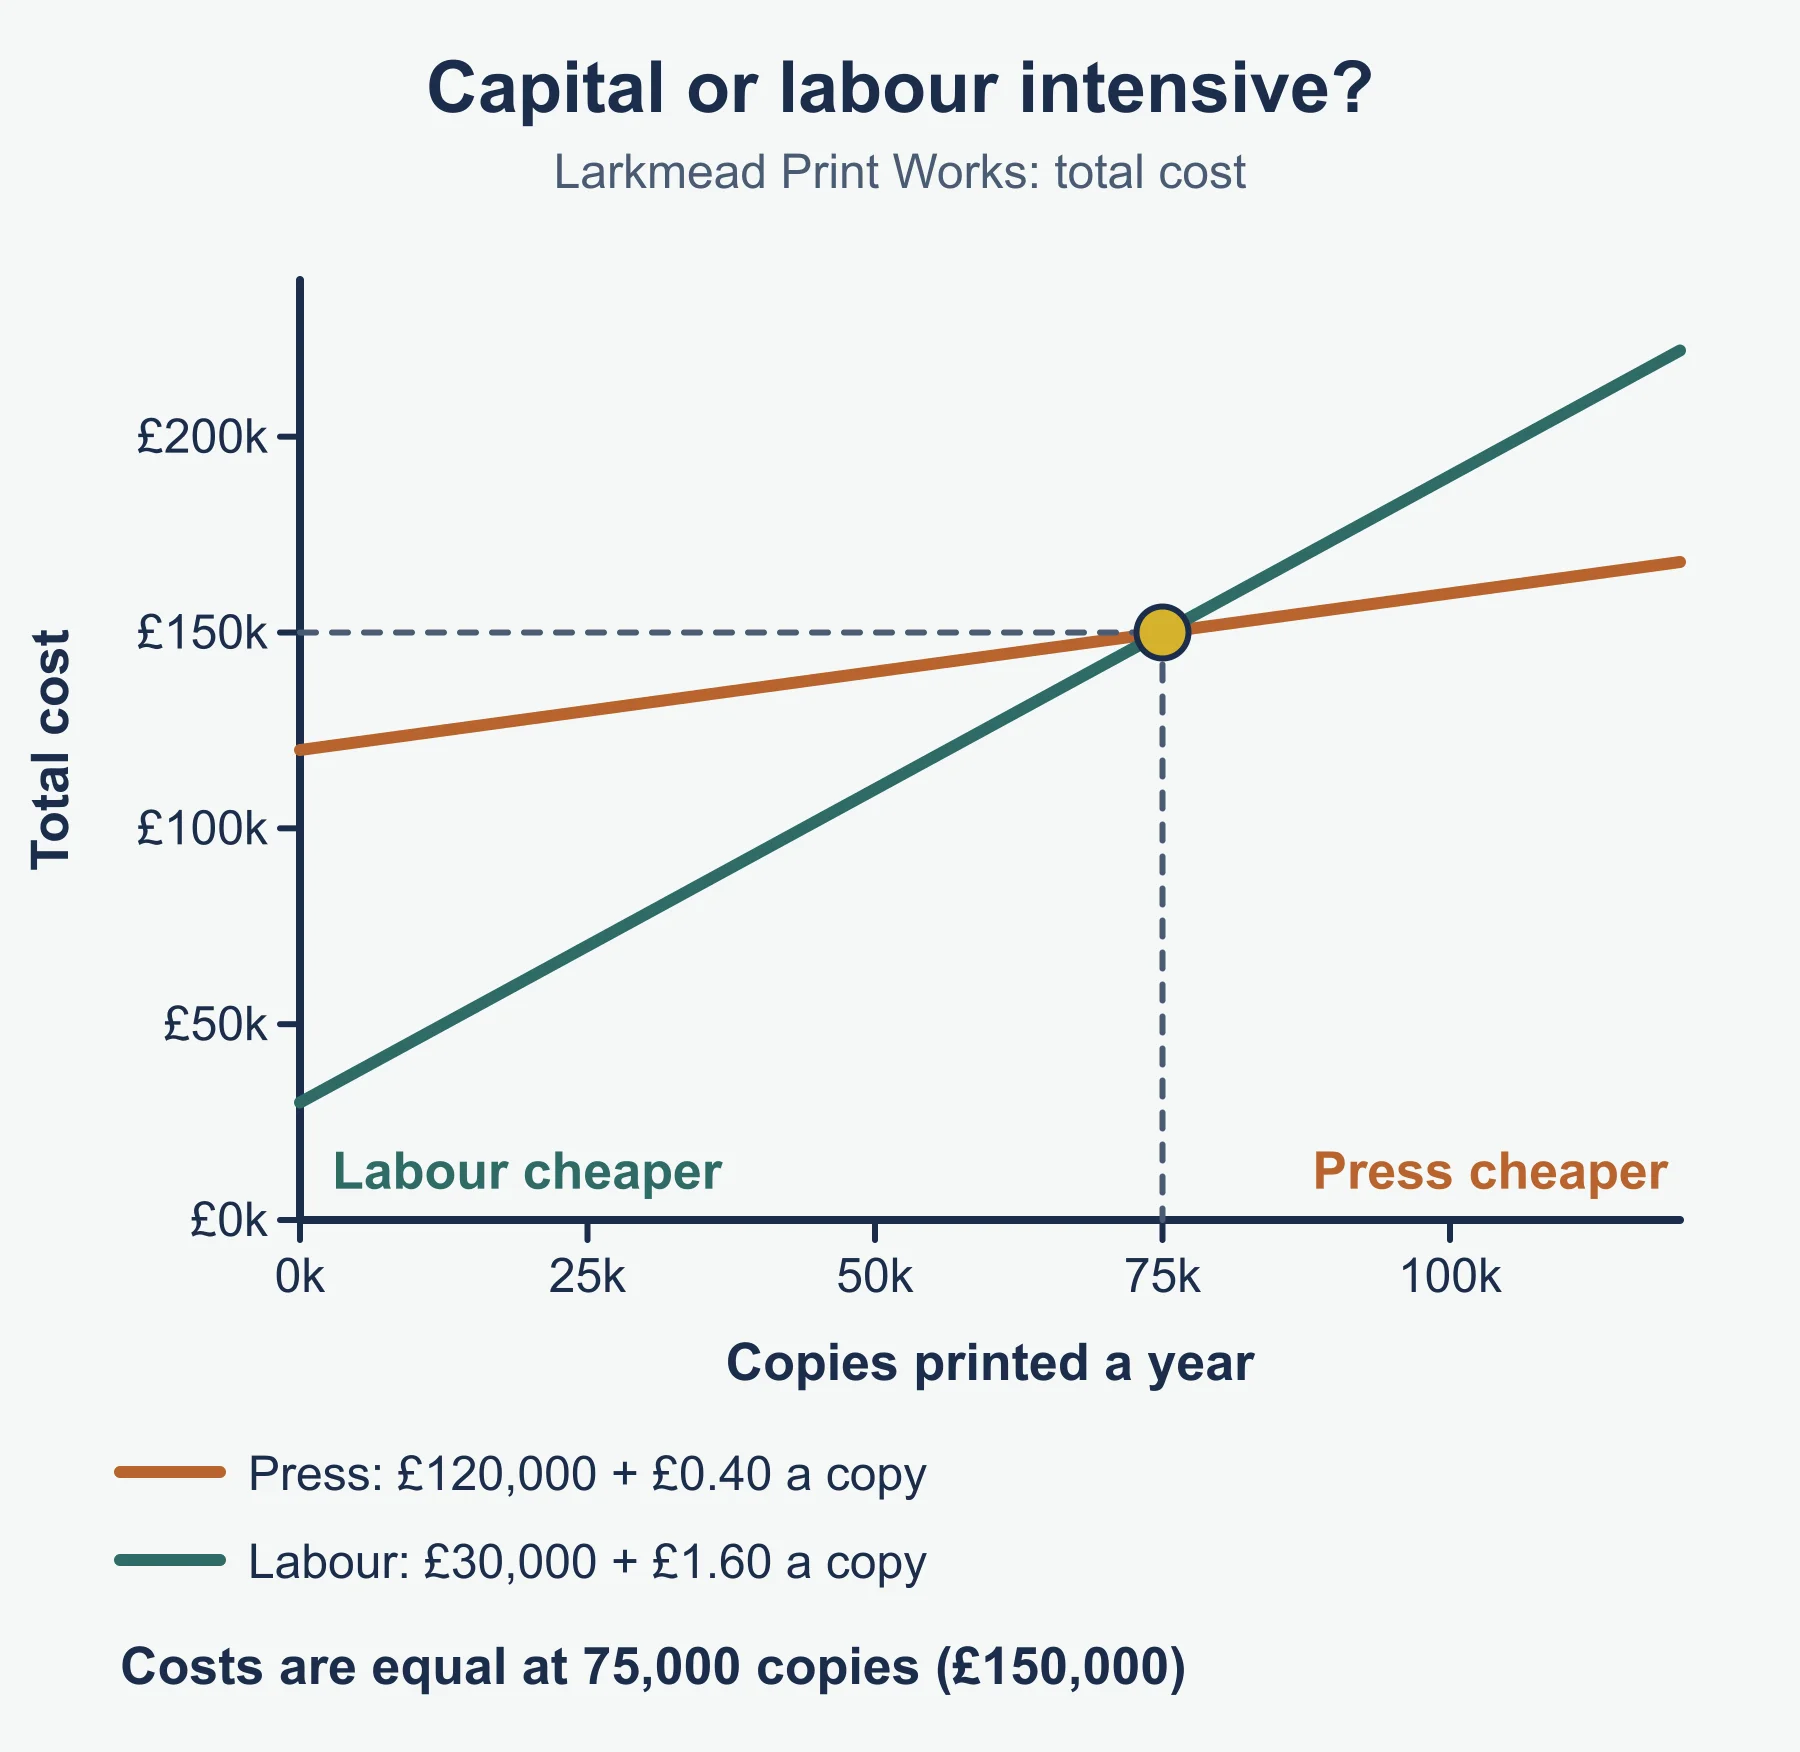
- Write total cost = fixed cost + variable cost x output for each.
- Set the two equal and solve for output.
- Below that output, the lower fixed-cost option is cheaper. Above it, the lower variable-cost option is cheaper.
- Compare the crossover with expected demand.
- Add non-numbers: flexibility, quality, jobs, risk.
Reminder: fixed £80,000 and £0.50 per unit against fixed £20,000 and £1.10 per unit. Equal when 60,000 = 0.60Q, so Q = 100,000.
4.1.4 Operations methods
| Method | Key feature | Best for | Main drawback |
|---|---|---|---|
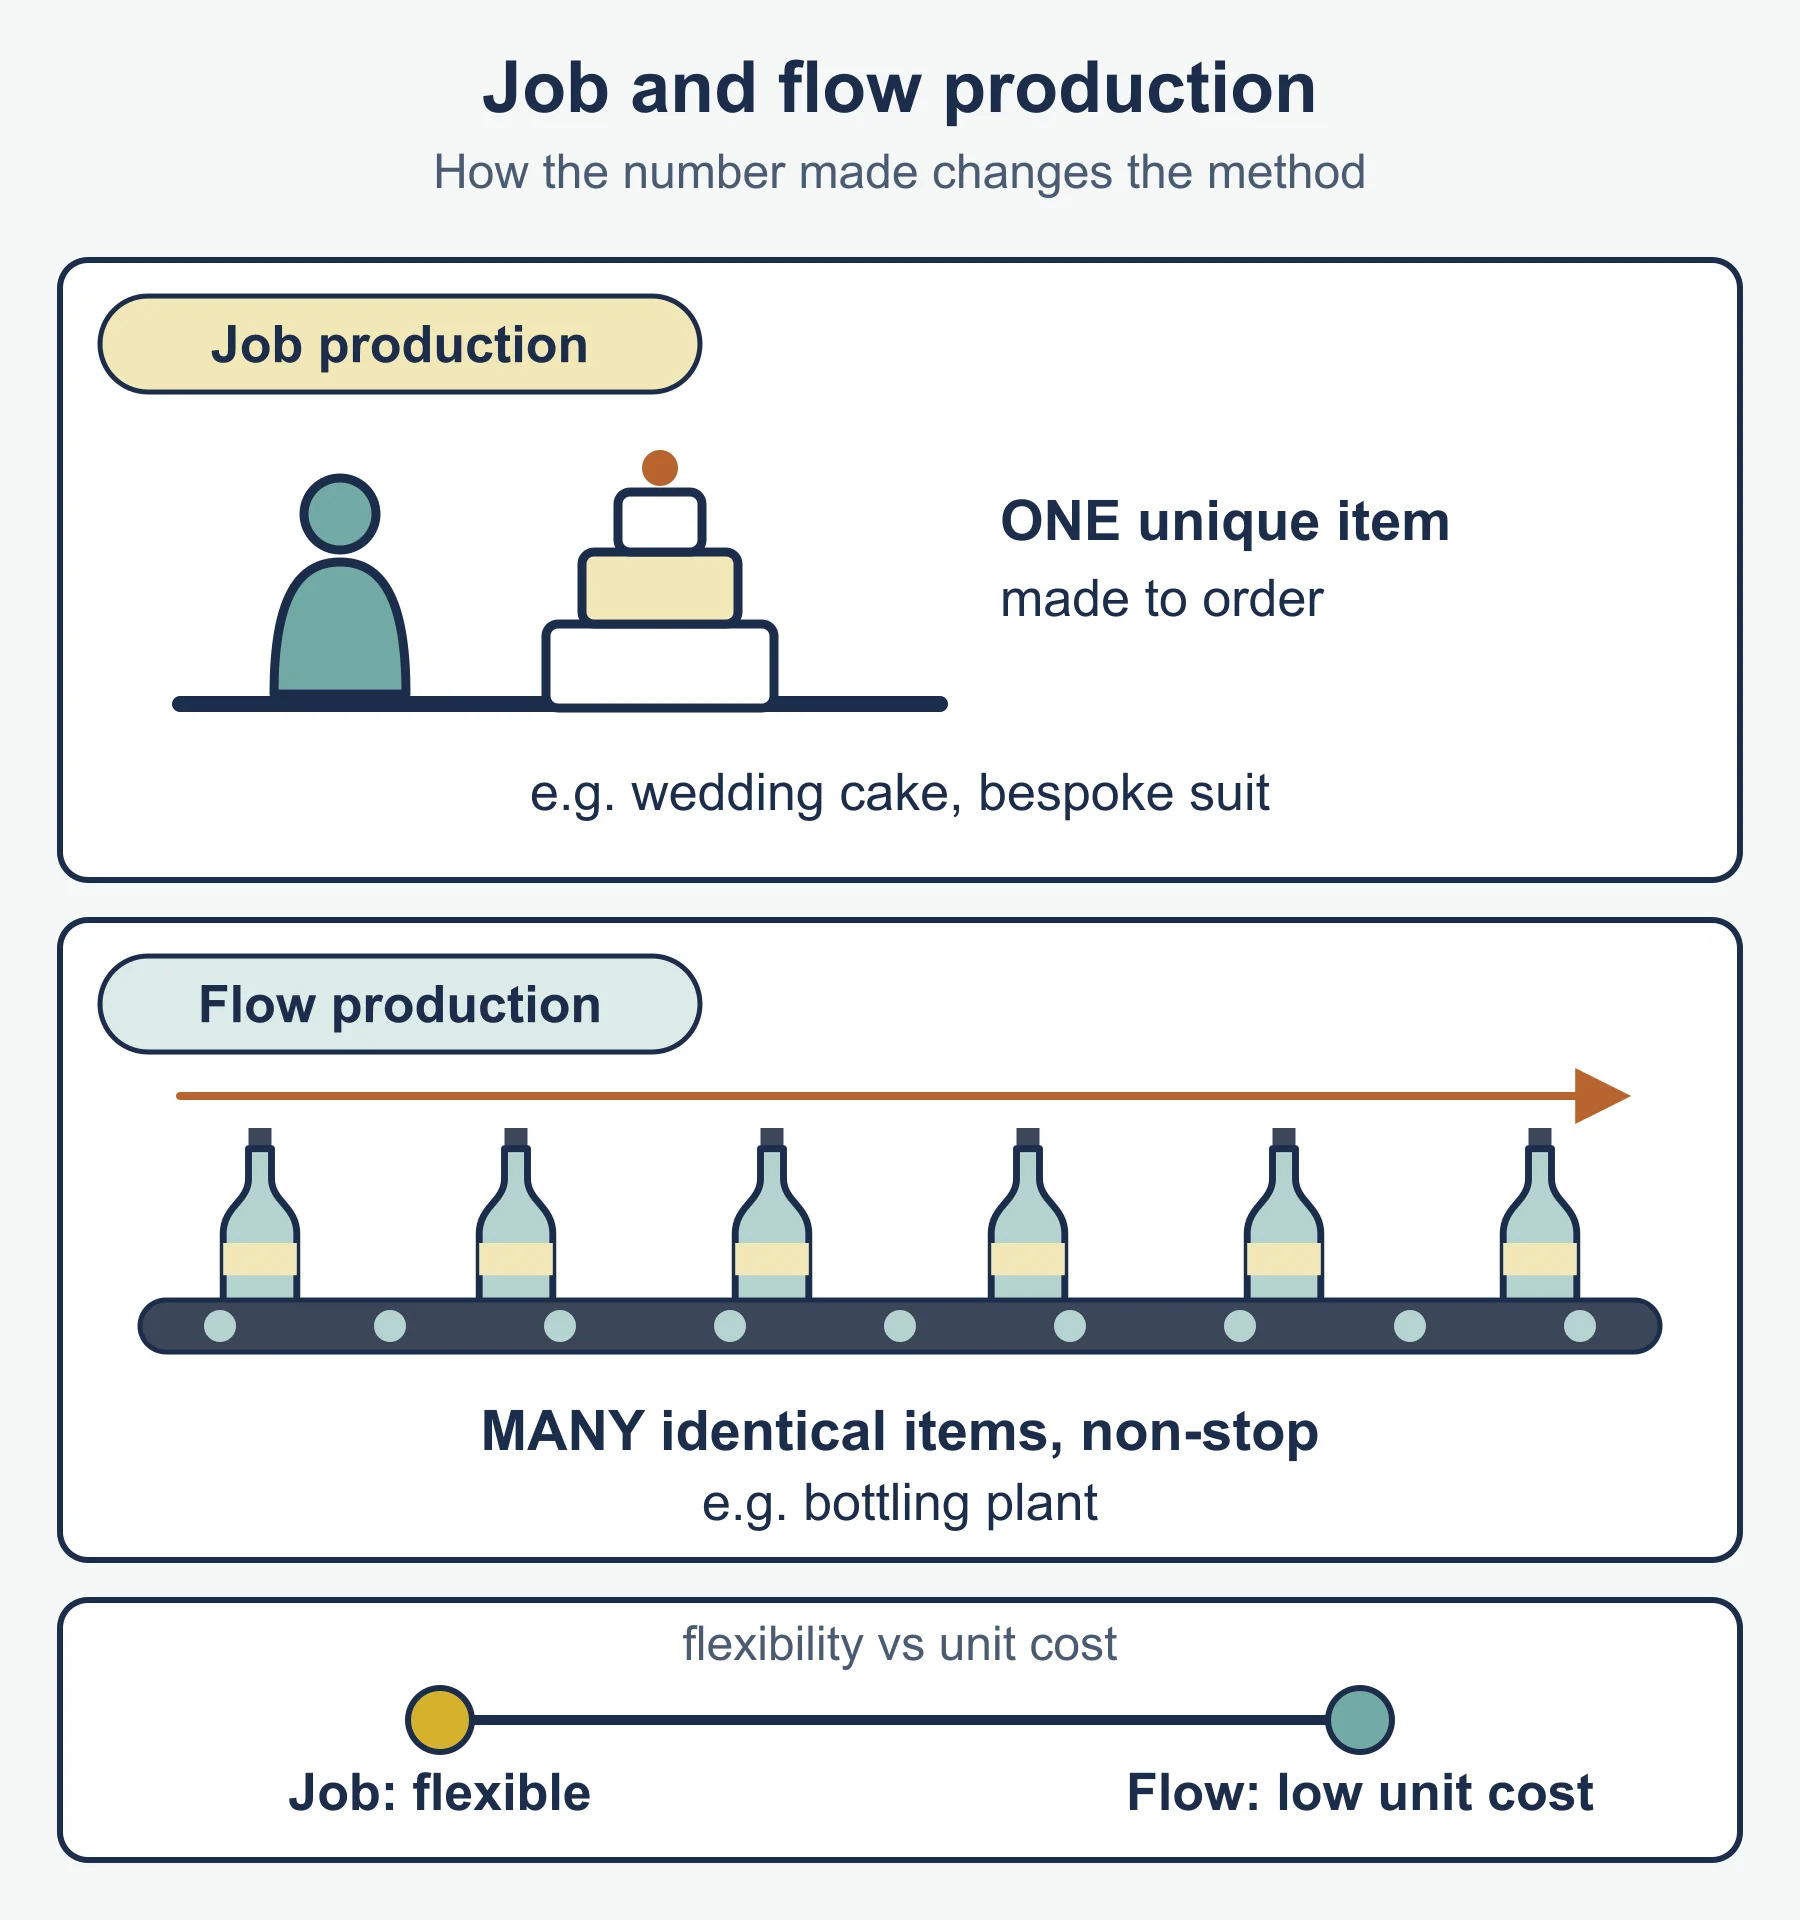
| Job | One-off to customer order | Bespoke, high-price items | Slow, high cost per unit |
| Batch | Group of identical items, then switch | Moderate volumes of varied items | Changeover time, work-in-progress |
| Flow | Continuous standardised output | High volume, steady demand | High set-up cost, inflexible |
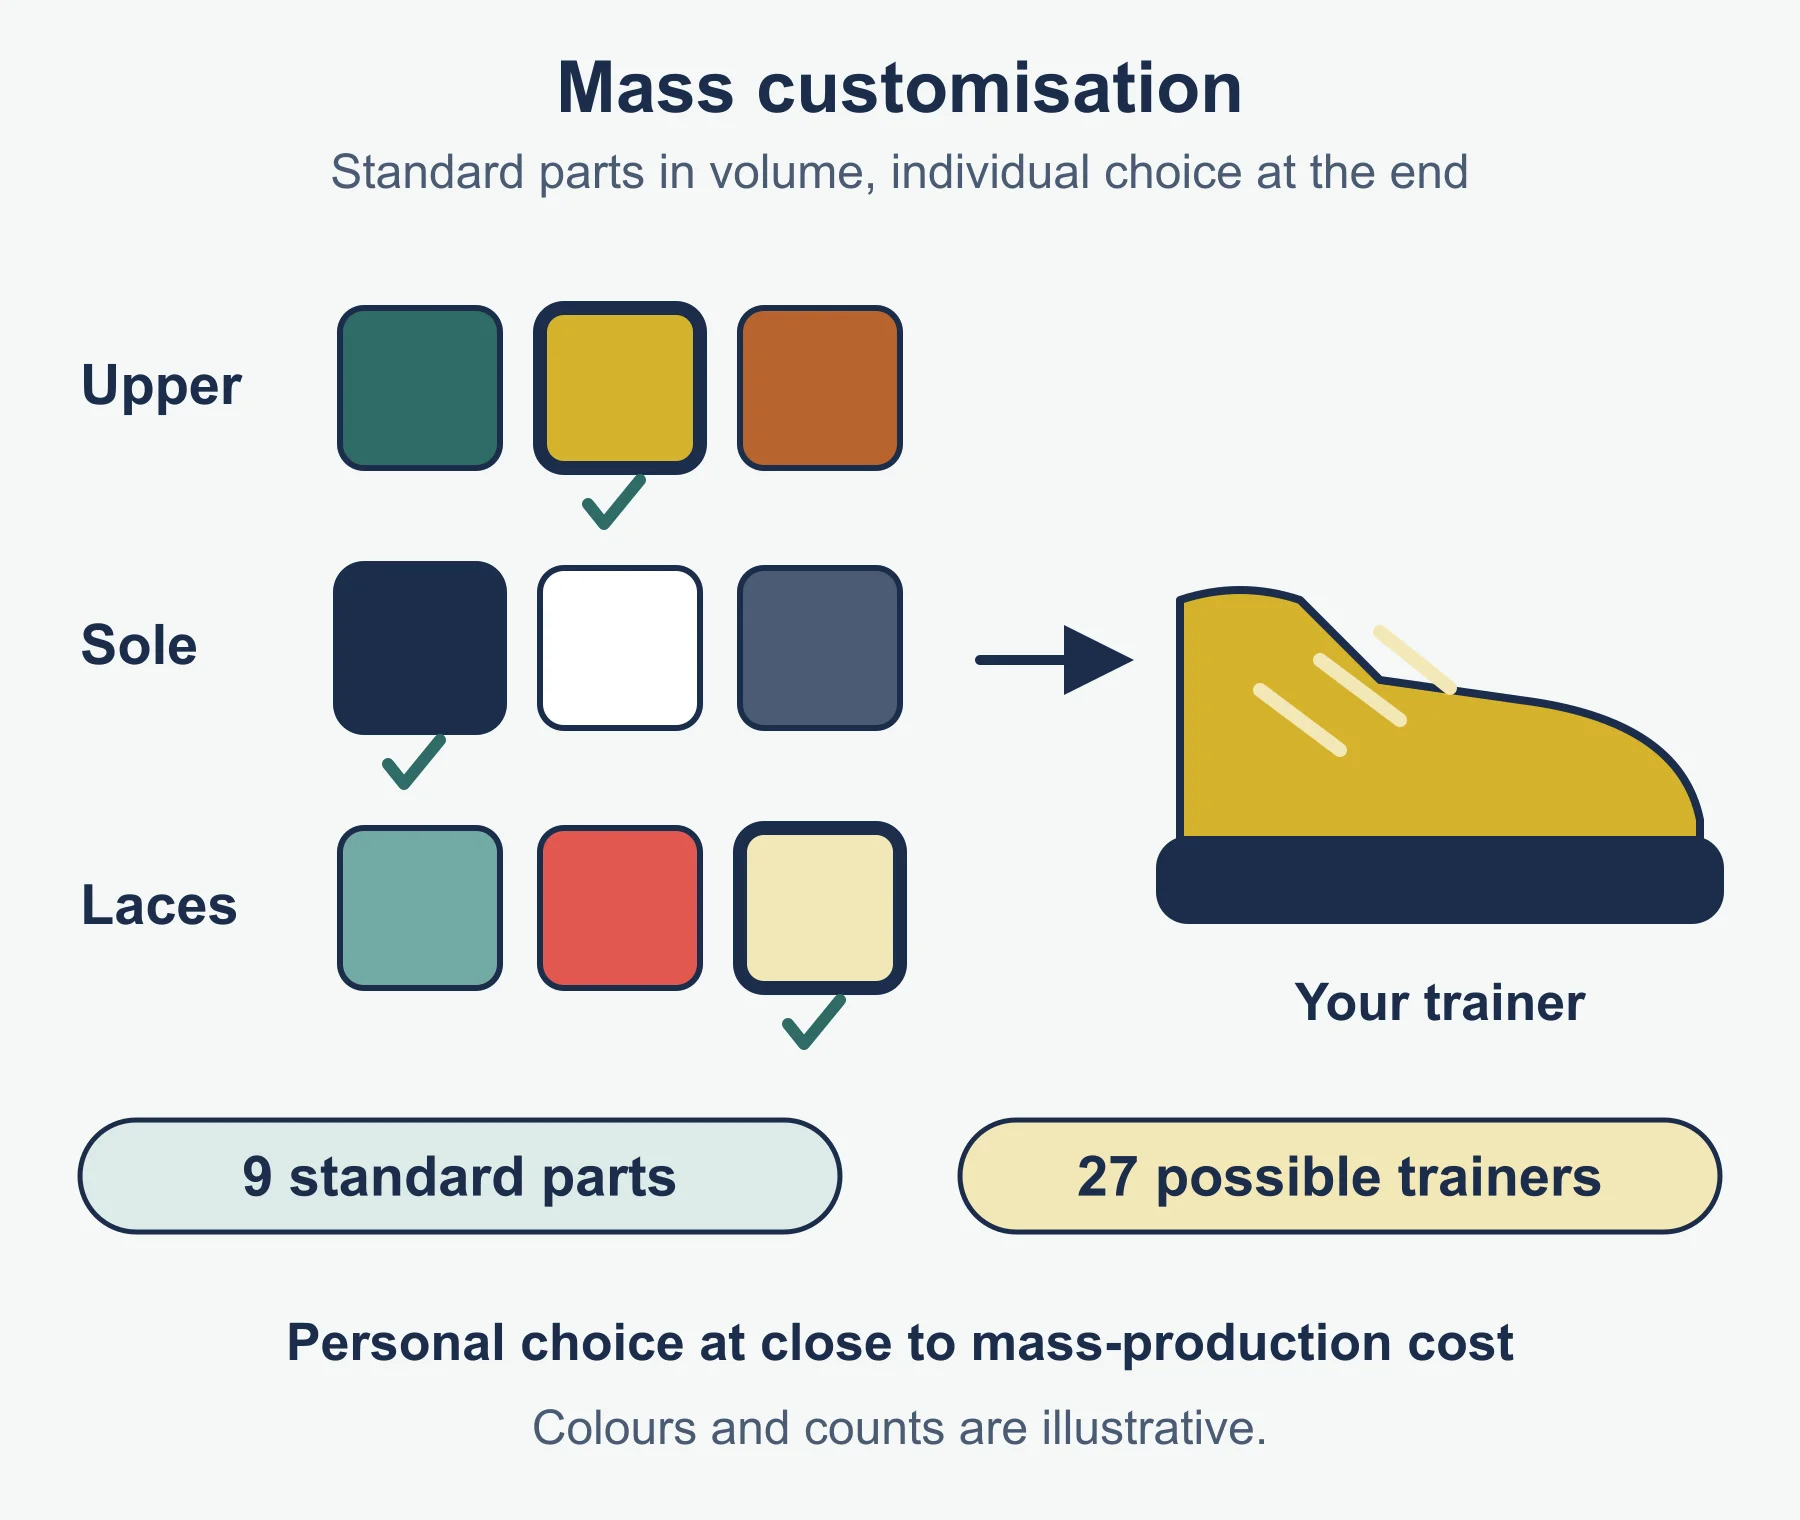
| Mass customisation | Standard parts in volume, personal combinations | Customers want choice at lower cost | Complex systems, waiting time |
Must-know distinctions
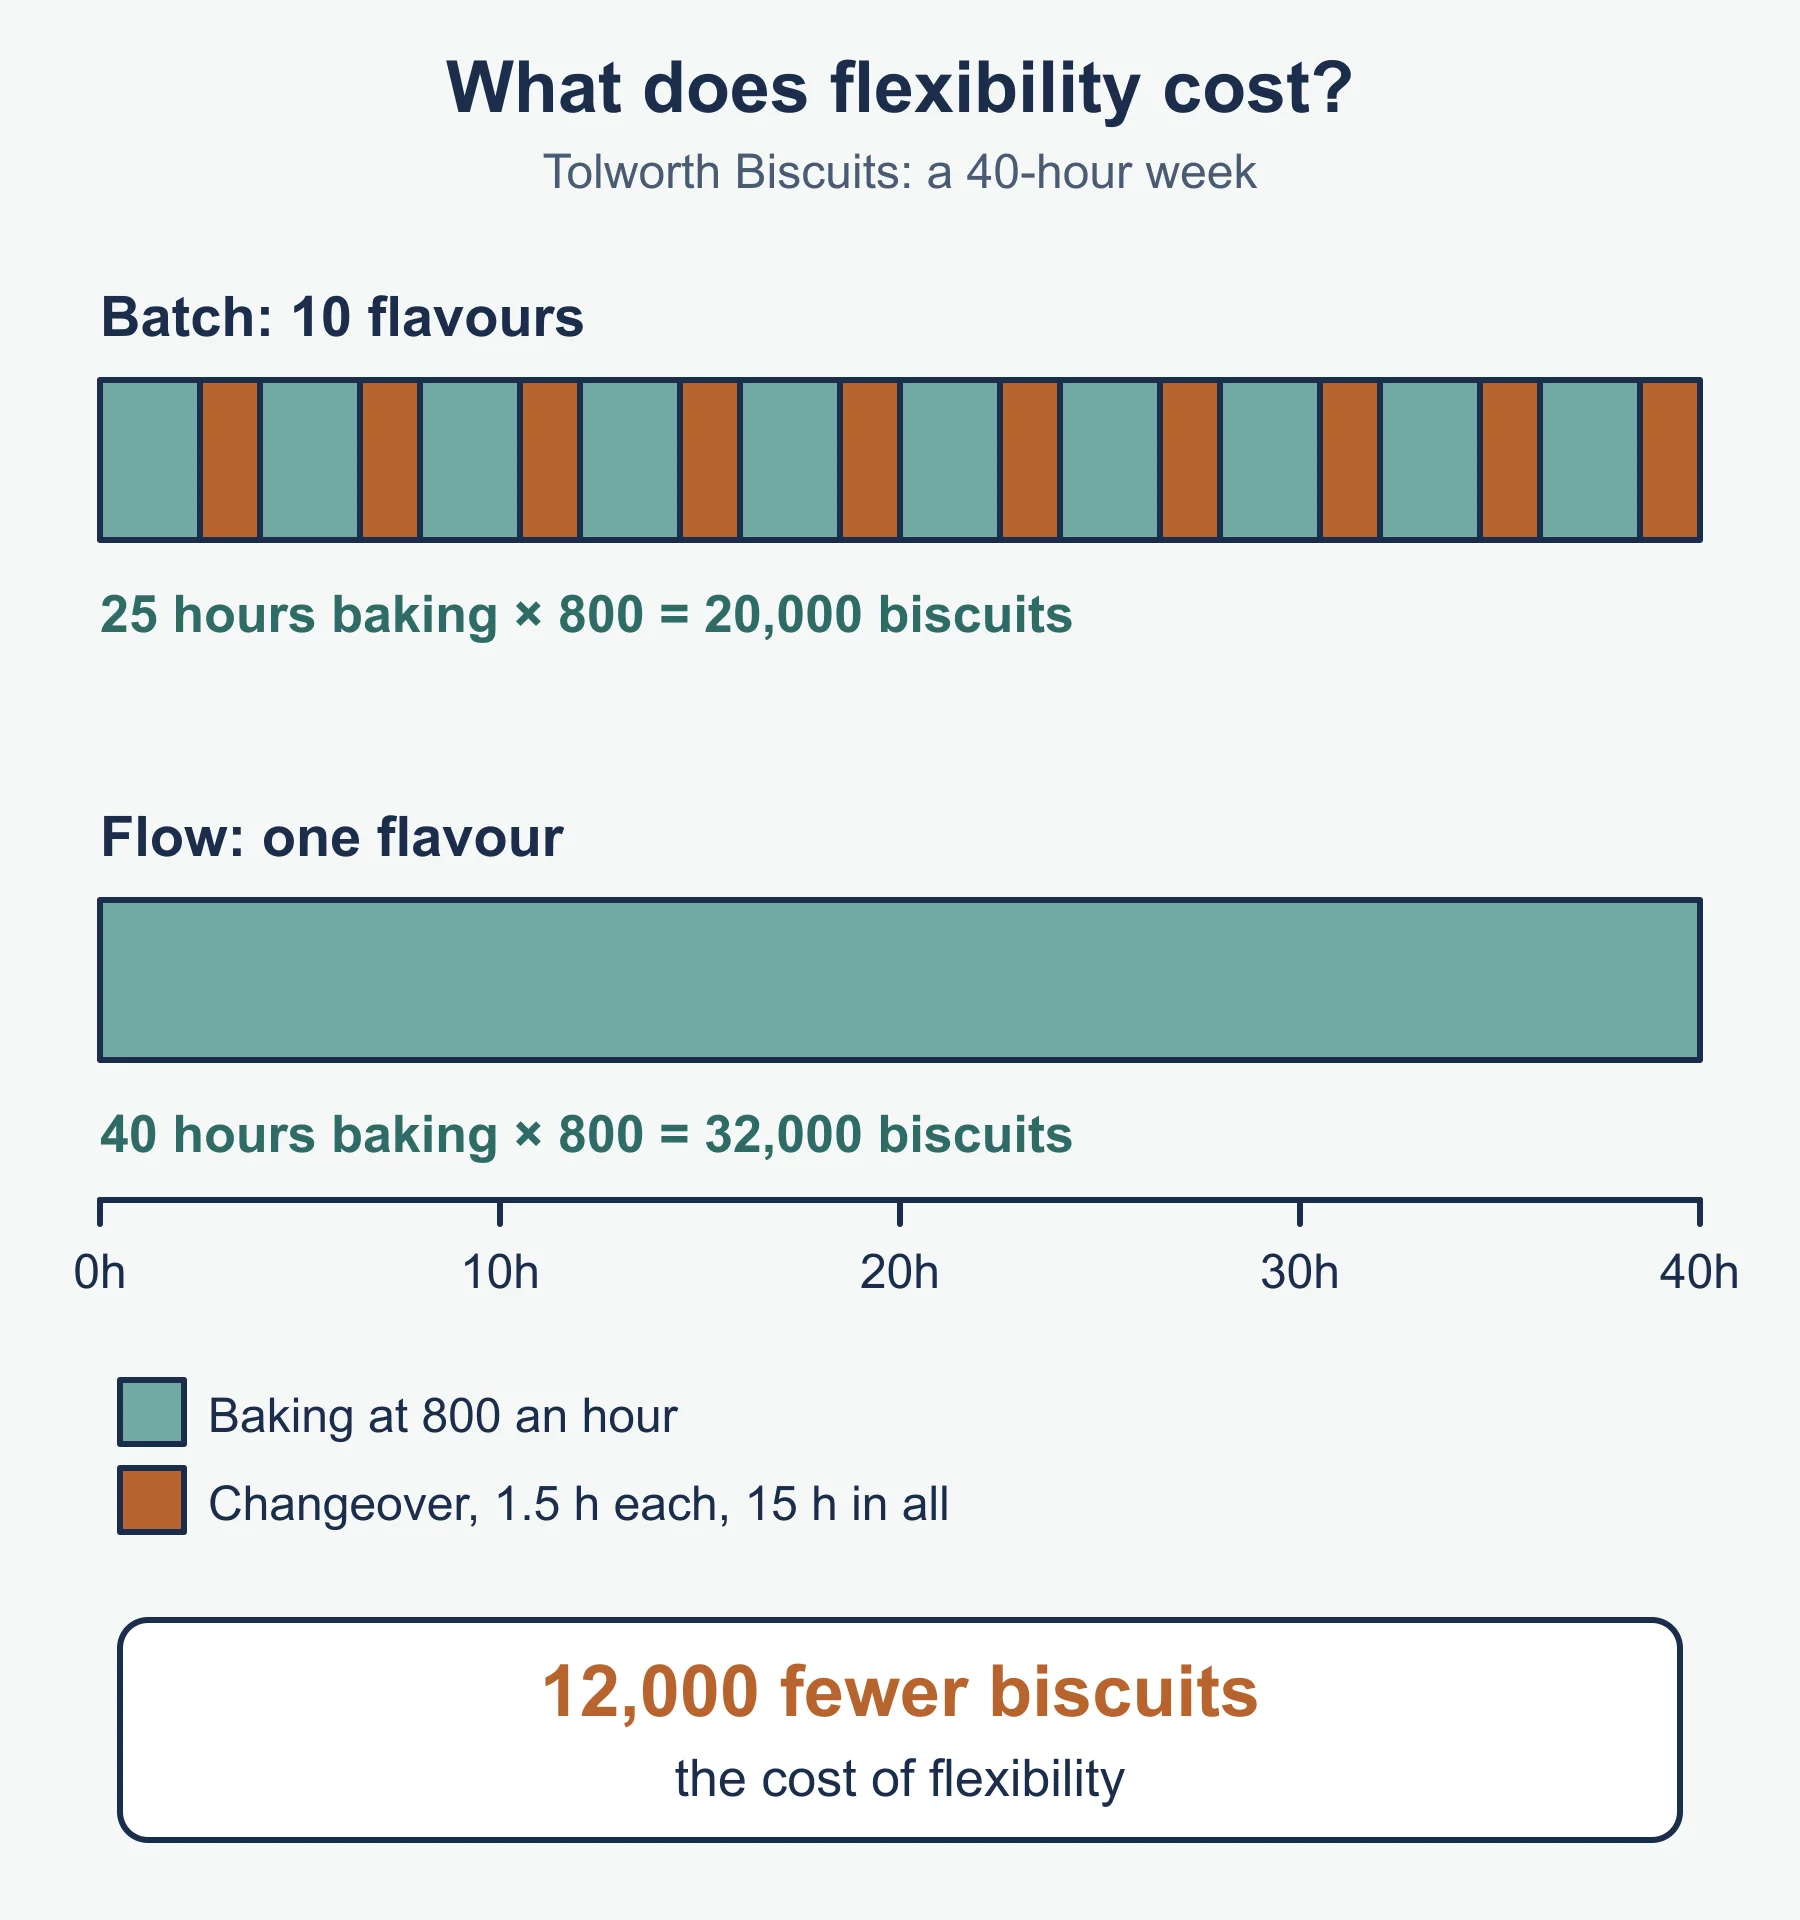
- Batch against flow: batch stops and restarts between product types. Flow runs continuously on one standard product.
- Job against mass customisation: both give the customer something personal. Job is made from scratch each time. Mass customisation assembles from a standard range of parts using flexible systems.
- Productivity against production: production is the total output. Productivity is output per input.
- Added value against profit: added value takes off only bought-in inputs. Profit takes off all costs.
Matching method to situation
- A one-off wedding dress for a named customer: job.
- A cheese maker producing 400 kg of one recipe, then 300 kg of another on the same equipment: batch.
- A bottling plant filling the same drink all week: flow.
- A cycle firm that builds each frame from a menu of colours and sizes chosen online: mass customisation.
Always check what the question says about volume, variety and price before choosing.
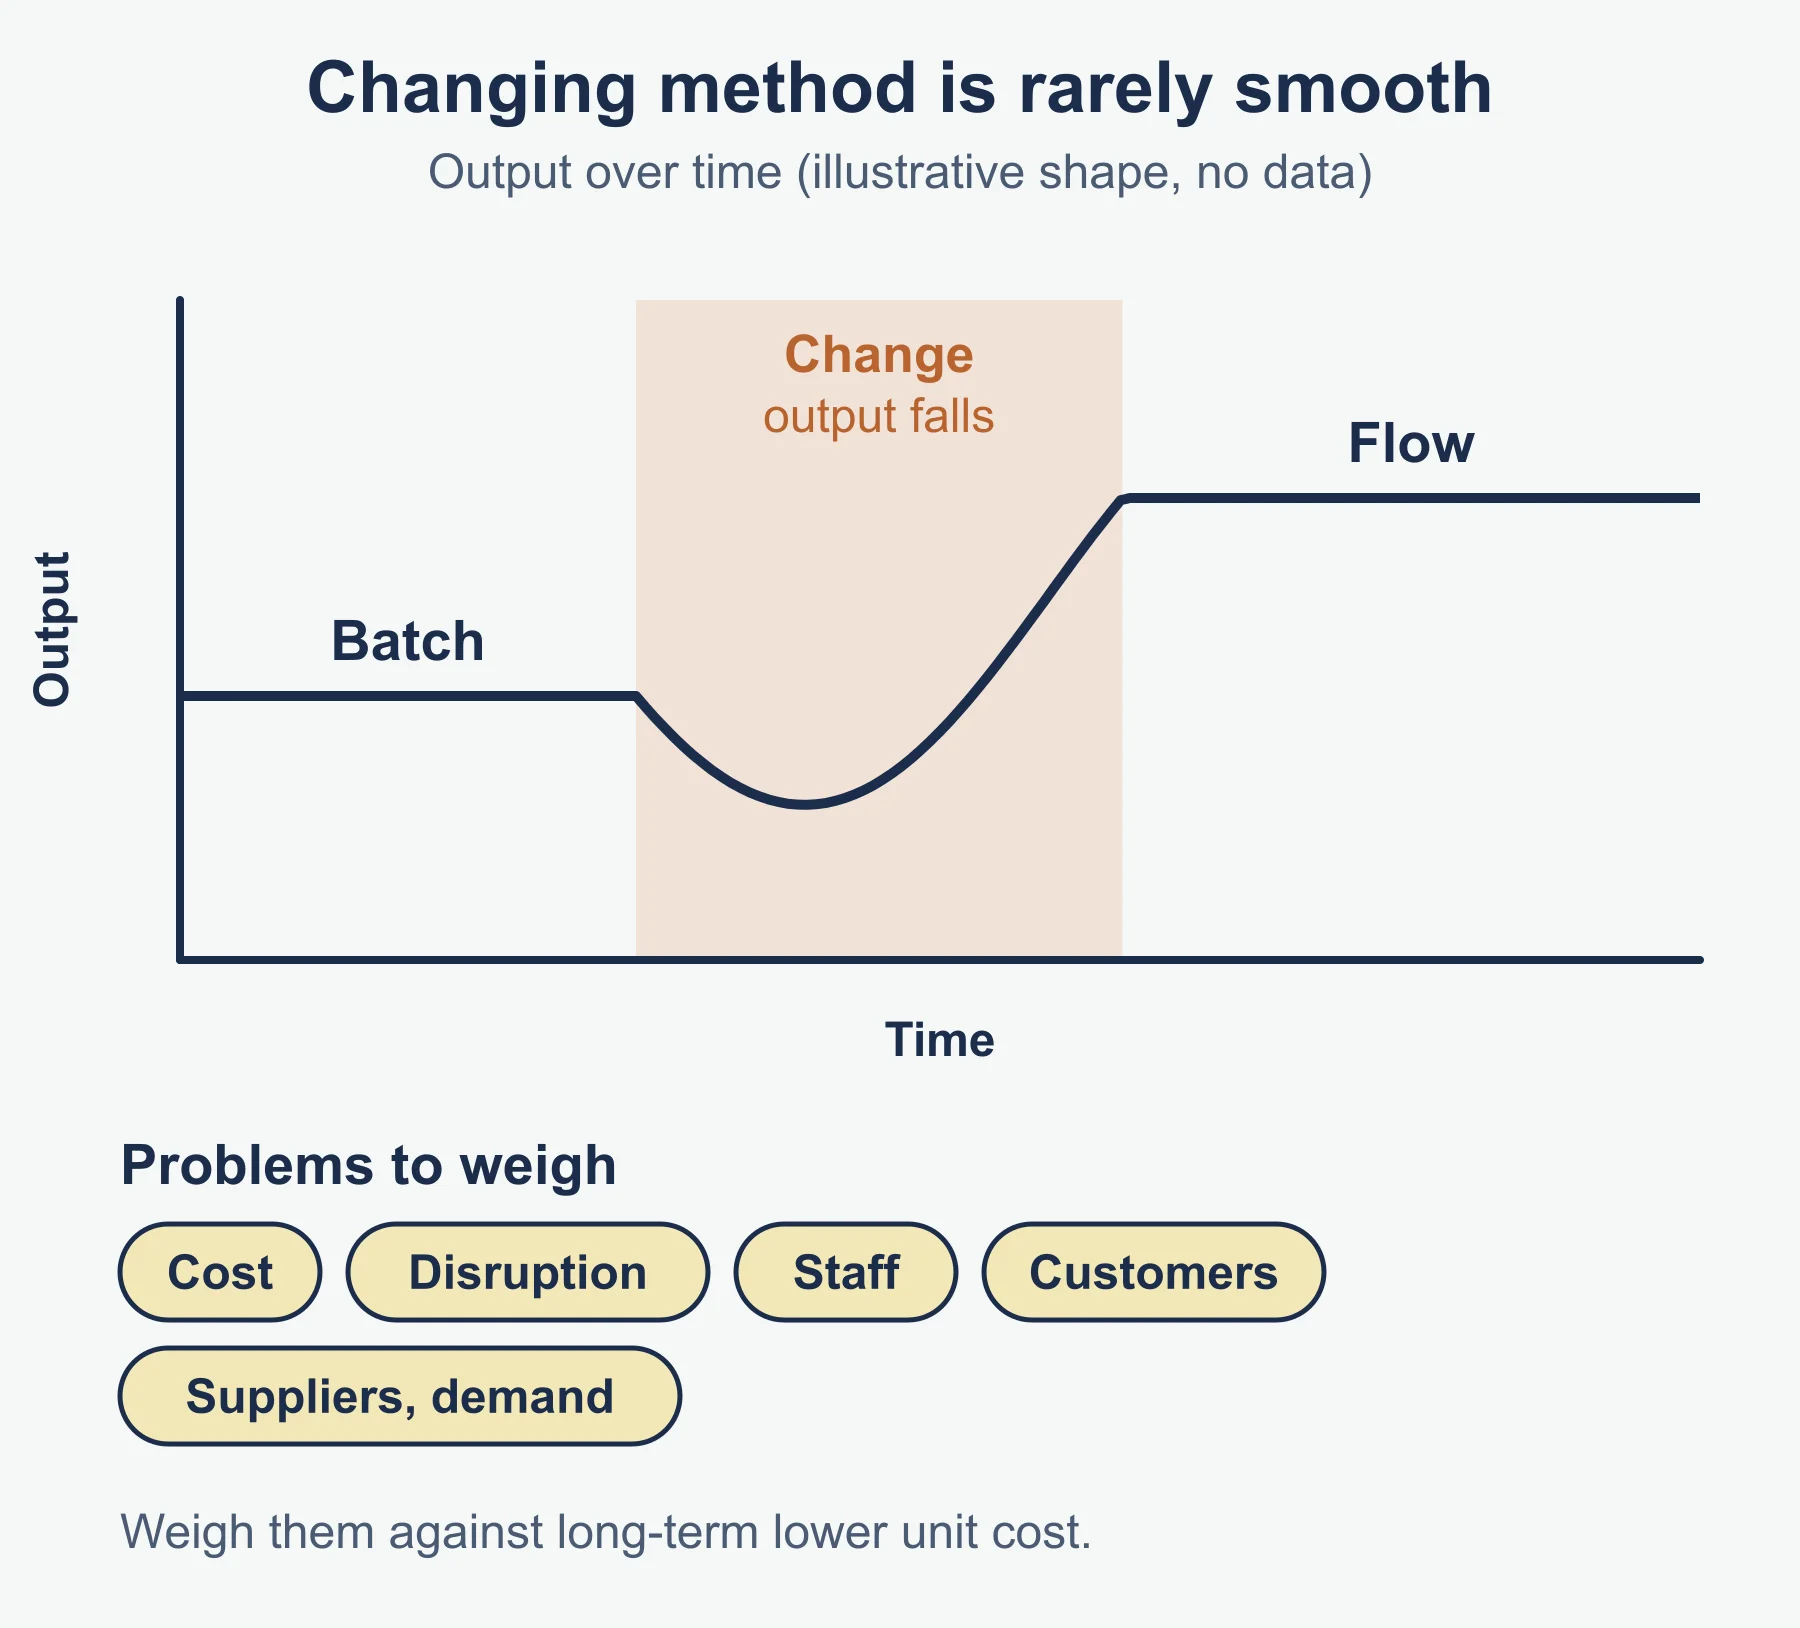
Problems of changing method
- Cost of machinery, layout and training.
- Disruption and lost output during the change.
- Staff worries about job changes, new skills and resistance.
- Risk to quality or the brand image (for example bespoke to standard).
- Suppliers, demand and cash flow must support the new method.
Applying the content in answers
Cambridge questions reward answers that use the case, not generic lists. For each point, use this chain: point, case evidence, effect on the business.
| Command word | What the answer needs |
|---|---|
| State, identify | A short answer with no explanation |
| Define | A precise meaning, in the standard form where one exists |
| Calculate | Formula, working and units |
| Explain | A point with a reason, linked to the business |
| Analyse | A developed chain of cause and effect, usually with figures from the case |
| Evaluate, justify, recommend | Both sides weighed, then a reasoned judgement that fits the case |
Judgement prompts for evaluation
- Method choice: how large and how steady is demand? Do customers want variety or the lowest price?
- Capital or labour: is output above or below the point where the two total costs are equal? Can the business afford the fixed cost?
- Changing method: is the long-term gain big enough to outweigh disruption, cost and staff reaction? Could the change be phased?
- Sustainability: is the saving large and certain, or is the main benefit image? Is the payback short compared with the time the business will stay?
- Productivity: did output rise because of staff effort, new machines or both? Did quality hold up?
Two further worked reminders
Added value from the other side. A business wants added value of £9 per unit and its bought-in inputs cost £14. The price needed is £14 + £9 = £23.
Batch time lost. A line runs 35 hours a week, with 8 changeovers of 1.25 hours each. Time lost = 8 x 1.25 = 10 hours. Production time = 25 hours, which is 71.4% of the week.
Quick self-test
- Name the four factors of production.
- A scarf sells for £28. Bought-in materials cost £9. Find the added value.
- 4,200 items are made by 14 workers. Find labour productivity.
- Output rises from 150 to 168 per worker. State the percentage change.
- Give one limitation of a capital intensive operation.
- Give one benefit of a labour intensive operation.
- Which operations method makes one-off items to a customer’s own order?
- State one disadvantage of batch production.
- A business moves from job to flow. Give one problem of the change.
- Define mass customisation.
- State one way sustainability measures may raise costs and one way they may lower them.
Answers
- Land, labour, capital and enterprise.
- £28 - £9 = £19.
- 4,200 / 14 = 300 items per worker.
- (168 - 150) / 150 x 100 = 12% increase.
- For example, high fixed costs, or inflexibility.
- For example, flexibility, or personal service.
- Job production.
- For example, time lost changing between batches.
- For example, retraining staff, high machinery cost, or loss of the bespoke image.
- Producing in volume from standard parts while letting each customer choose a personalised combination.
- Raise: equipment or training outlay. Lower: reduced energy use or waste.
Where marks are usually lost
- Defining added value as profit, or forgetting to subtract only bought-in inputs.
- Listing the four factors of production without applying them to the business.
- Calculating productivity with the wrong denominator, such as using total workers when the question gives hours.
- Giving a percentage change with the new figure as the base instead of the old one.
- Writing that machines are always cheaper. They only win above a certain output.
- Mixing up batch and flow, or job and mass customisation.
- Naming an advantage or disadvantage but not explaining what it does to costs, quality or customers in the case.
- Judging a sustainability measure without weighing its cost against its saving or image effect.
- Describing the problems of changing method in general, rather than for the business and the method in the question.
Frequently asked questions
What is the difference between efficiency and effectiveness? Efficiency means producing output with the least waste of resources, which lowers unit costs. Effectiveness means achieving the business’s aims and meeting customer needs.
How do you calculate labour productivity? The standard form is output in a period divided by the number of employees in that period. You can also divide by hours worked when staff work different hours.
What is the difference between batch and flow production? Batch production makes a group of identical items and then stops to switch to another product. Flow production runs continuously, making standardised items along a line.
Do sustainability measures always raise costs? No. Set-up costs often rise because of new equipment or training, but running costs often fall through lower energy use and less waste, so compare the outlay with the yearly saving.
Official syllabus
Cambridge International AS & A Level Business 9609 syllabus, for examination in 2026, 2027 and 2028, published by Cambridge University Press & Assessment (Cambridge International). Section 4.1, The nature of operations.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
A Level Business: Operations Management (A Level) — Practice Questions (Cambridge 9609)
Worked practice questions on TQM, quality assurance, kaizen, critical path analysis, location decisions and diseconomies of scale for Cambridge 9609 Business.
Business · Cambridge · A Level
Try questions -
Practice questions
A Level Business: Operations Management — Practice Questions (Cambridge 9609)
Practice questions with worked answers on inventory, re-order levels, buffer inventory, JIT, capacity utilisation and productivity for Cambridge 9609 Topic 4.
Business · Cambridge · AS Level
Try questions -
Study guides
A Level Business: Capacity utilisation and outsourcing (Cambridge 9609)
Study guide to 4.3 Capacity utilisation and outsourcing for Cambridge AS & A Level Business 9609, with worked calculations, impacts and evaluation.
Business · Cambridge · AS Level
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business AS LEVEL?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Business teachers at Marlbridge

