
Revision Notes
Edexcel IGCSE Accounting: Financial statements of a partnership (4AC1) – Revision Notes
Condensed revision notes on partnership accounts for Edexcel IGCSE Accounting 4AC1: Section 24, appropriation, current accounts and a self-test.
- Subject
- Accounting
- Level
- IGCSE
- Topic
- The preparation of financial statements
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Pearson Edexcel IGCSE Accounting (4AC1), Issue 1, October 2016. Official specification .
Syllabus page (what it covers and how it is assessed): Pearson Edexcel IGCSE Accounting.
Syllabus points this page covers
4AC1
- 4 The preparation of financial statements (whole topic)
- 4.2 Financial statements of a partnership
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
These notes condense Topic 4, section 2 (financial statements of a partnership) of the Pearson Edexcel International GCSE in Accounting (4AC1) specification, Issue 1, October 2016, points a to g. For full explanations and a complete set of statements, read the study guide. Test yourself with the practice questions. Course home: Edexcel IGCSE Accounting, the printable checklist and the free diagnostics. Amounts are in dollars and all businesses are invented.
Nature of a partnership and an LLP (points a and b)
| Term | Remember |
|---|---|
| Partnership | Two or more owners sharing profit or loss, usually under a written agreement |
| Reasons to form | Extra capital, a mix of skills, shared workload and risk, someone to cover absences |
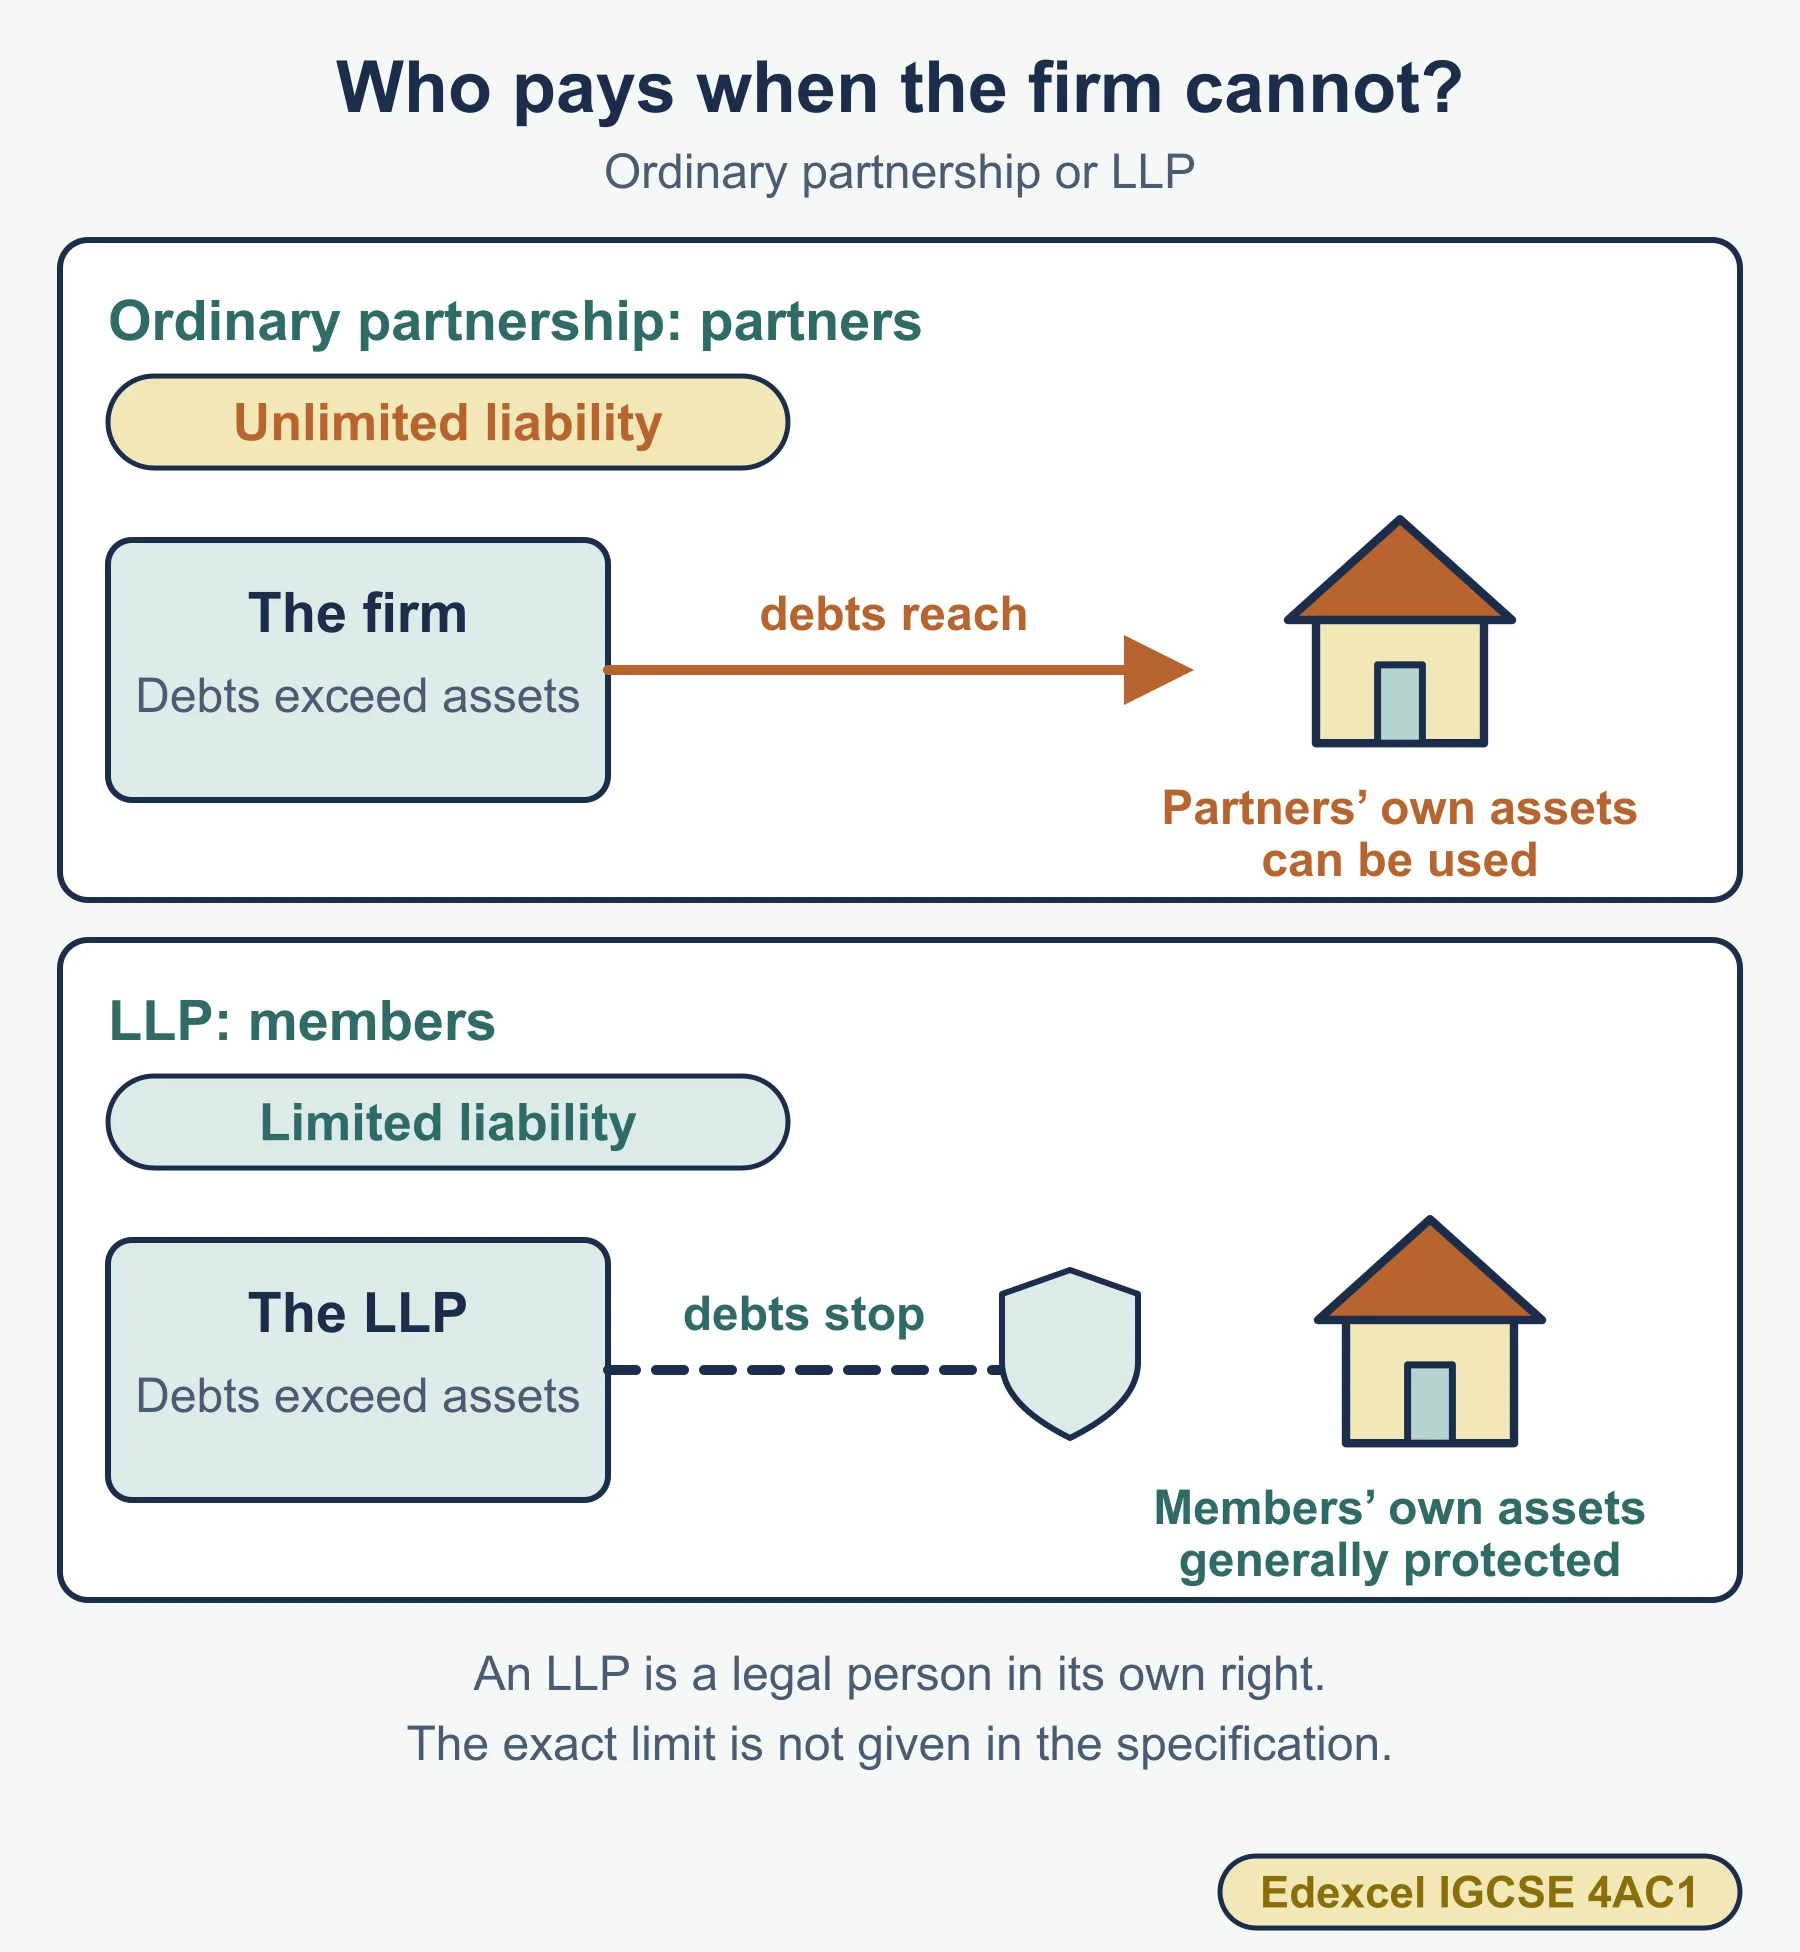
| Ordinary partnership liability | Unlimited. Personal assets can be used to pay the firm’s debts |
| Limited liability partnership (LLP) | A separate legal person (general knowledge). Its members have limited liability, so personal assets are generally protected |
| LLP structure | The owners are called members. Profit is shared as the members agree |
An answer that compares the two should state the difference in liability and then say why it matters: an LLP member’s personal assets are not at risk in the way an ordinary partner’s are, so the LLP form suits owners who want to limit what they could lose.
Section 24 defaults (point c)
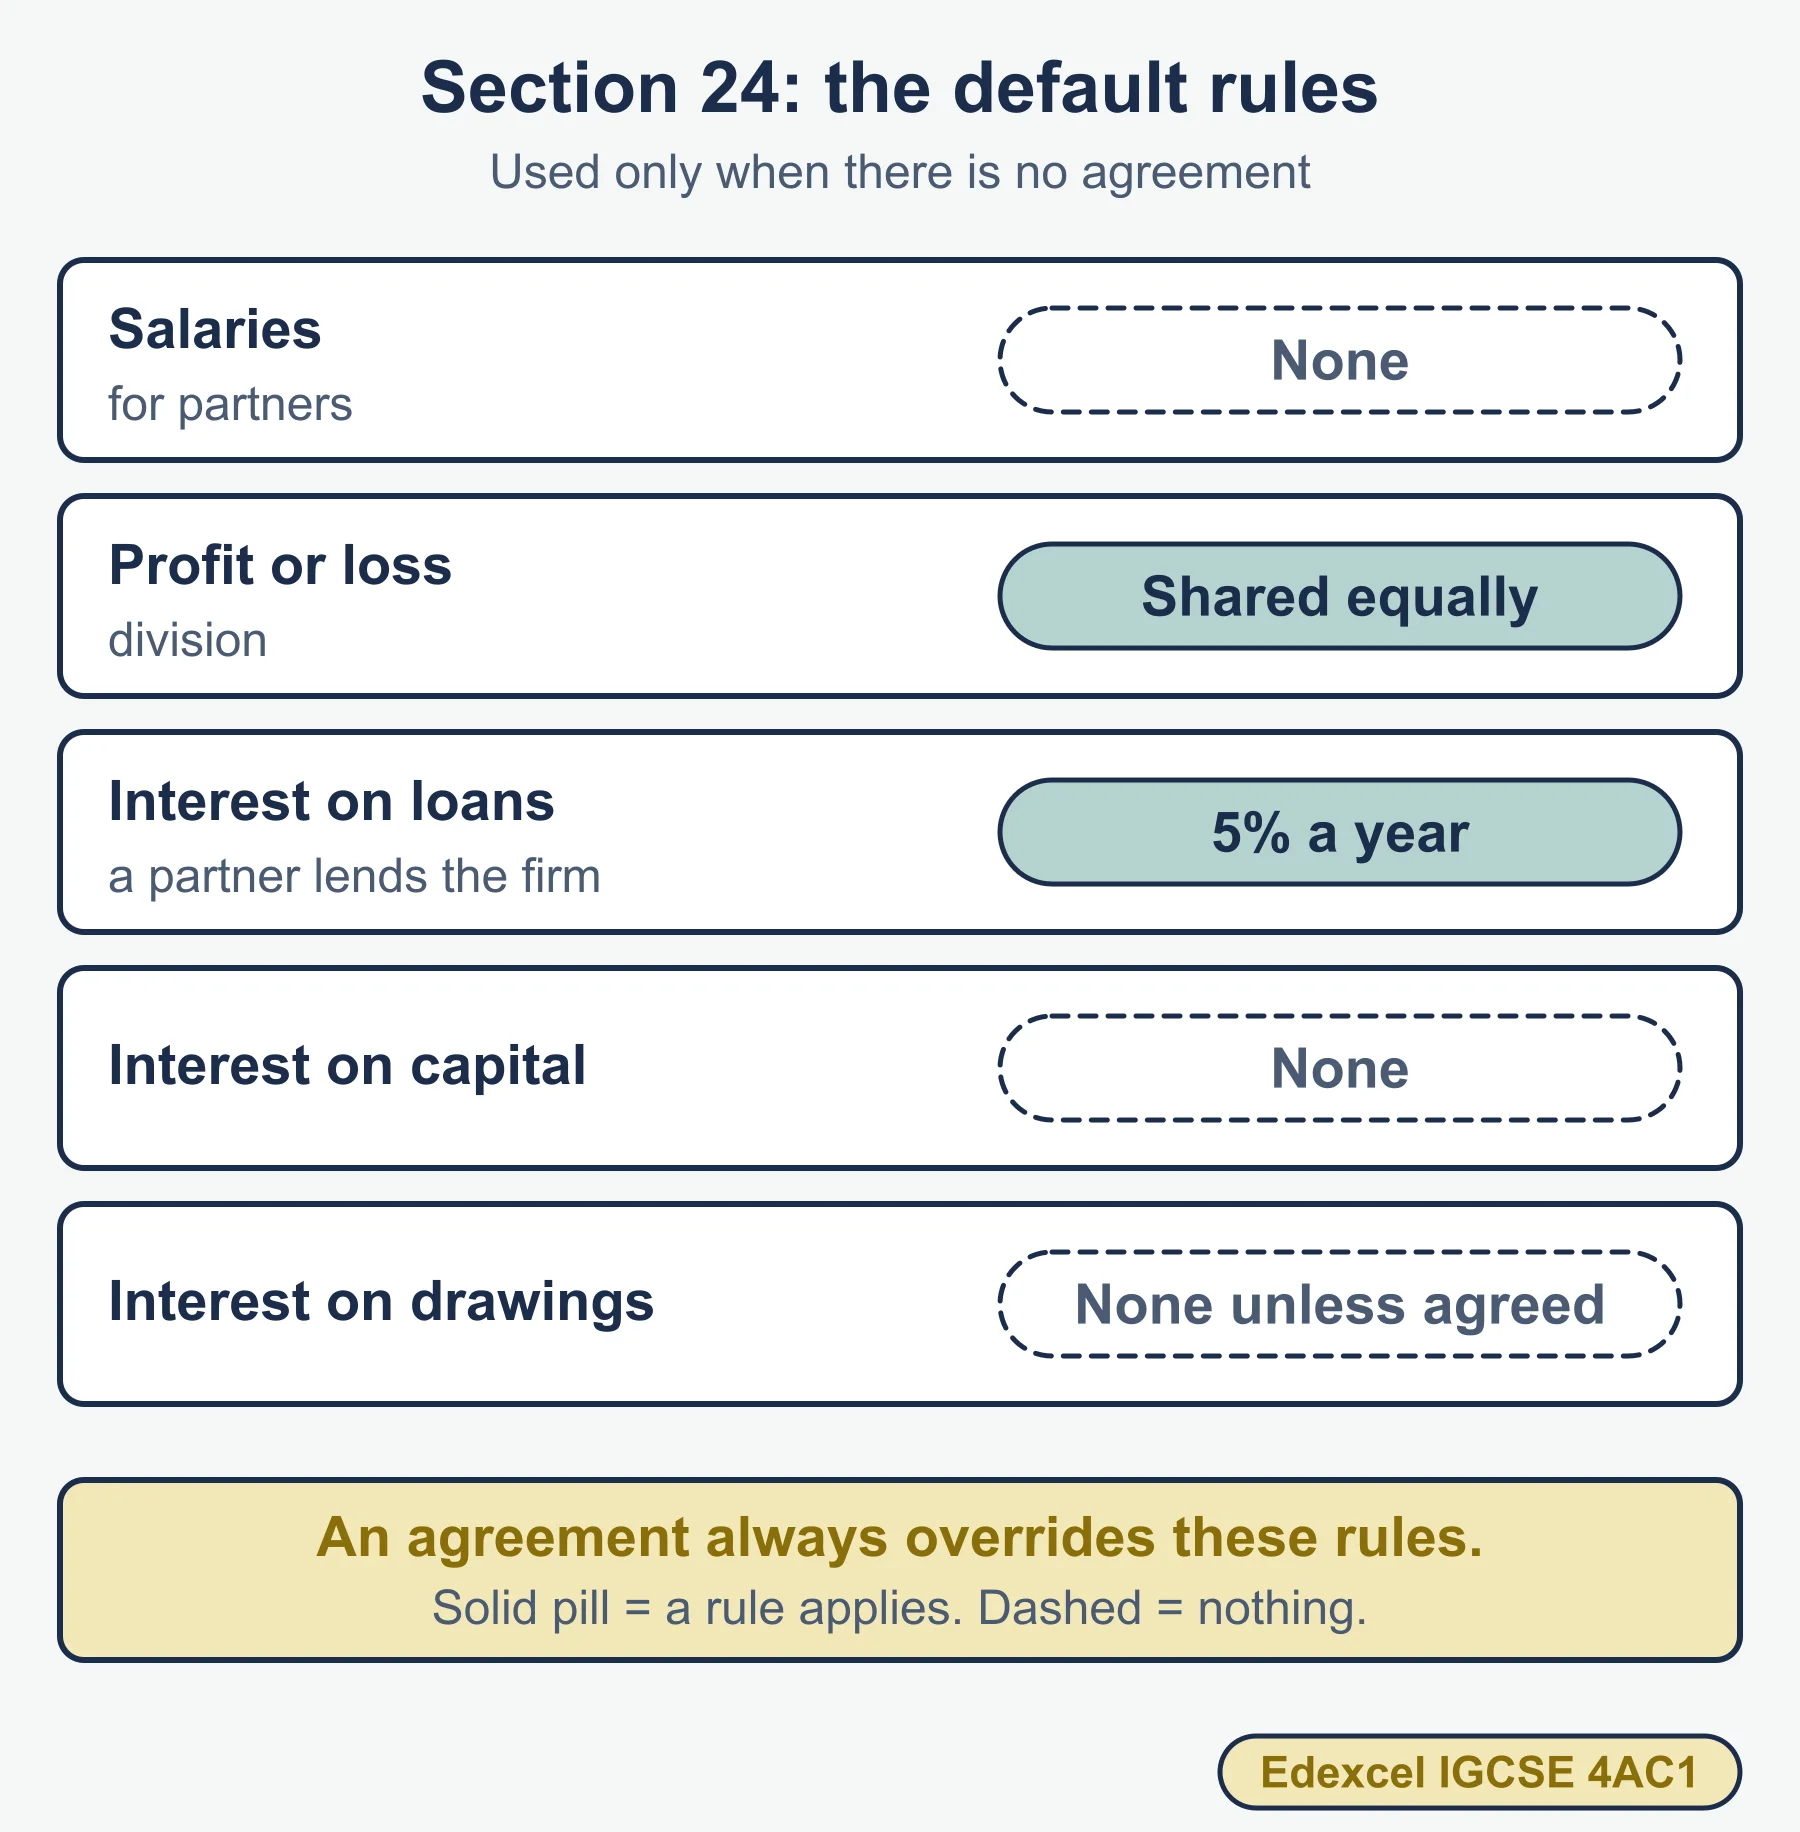
These apply when there is no agreement, or the agreement is silent on a point. An agreement beats them. The table gives general knowledge of the Act and the usual textbook position, not specification wording.
| Item | Default under Section 24 of the Partnership Act 1890 |
|---|---|
| Salaries | None |
| Profit or loss | Shared equally |
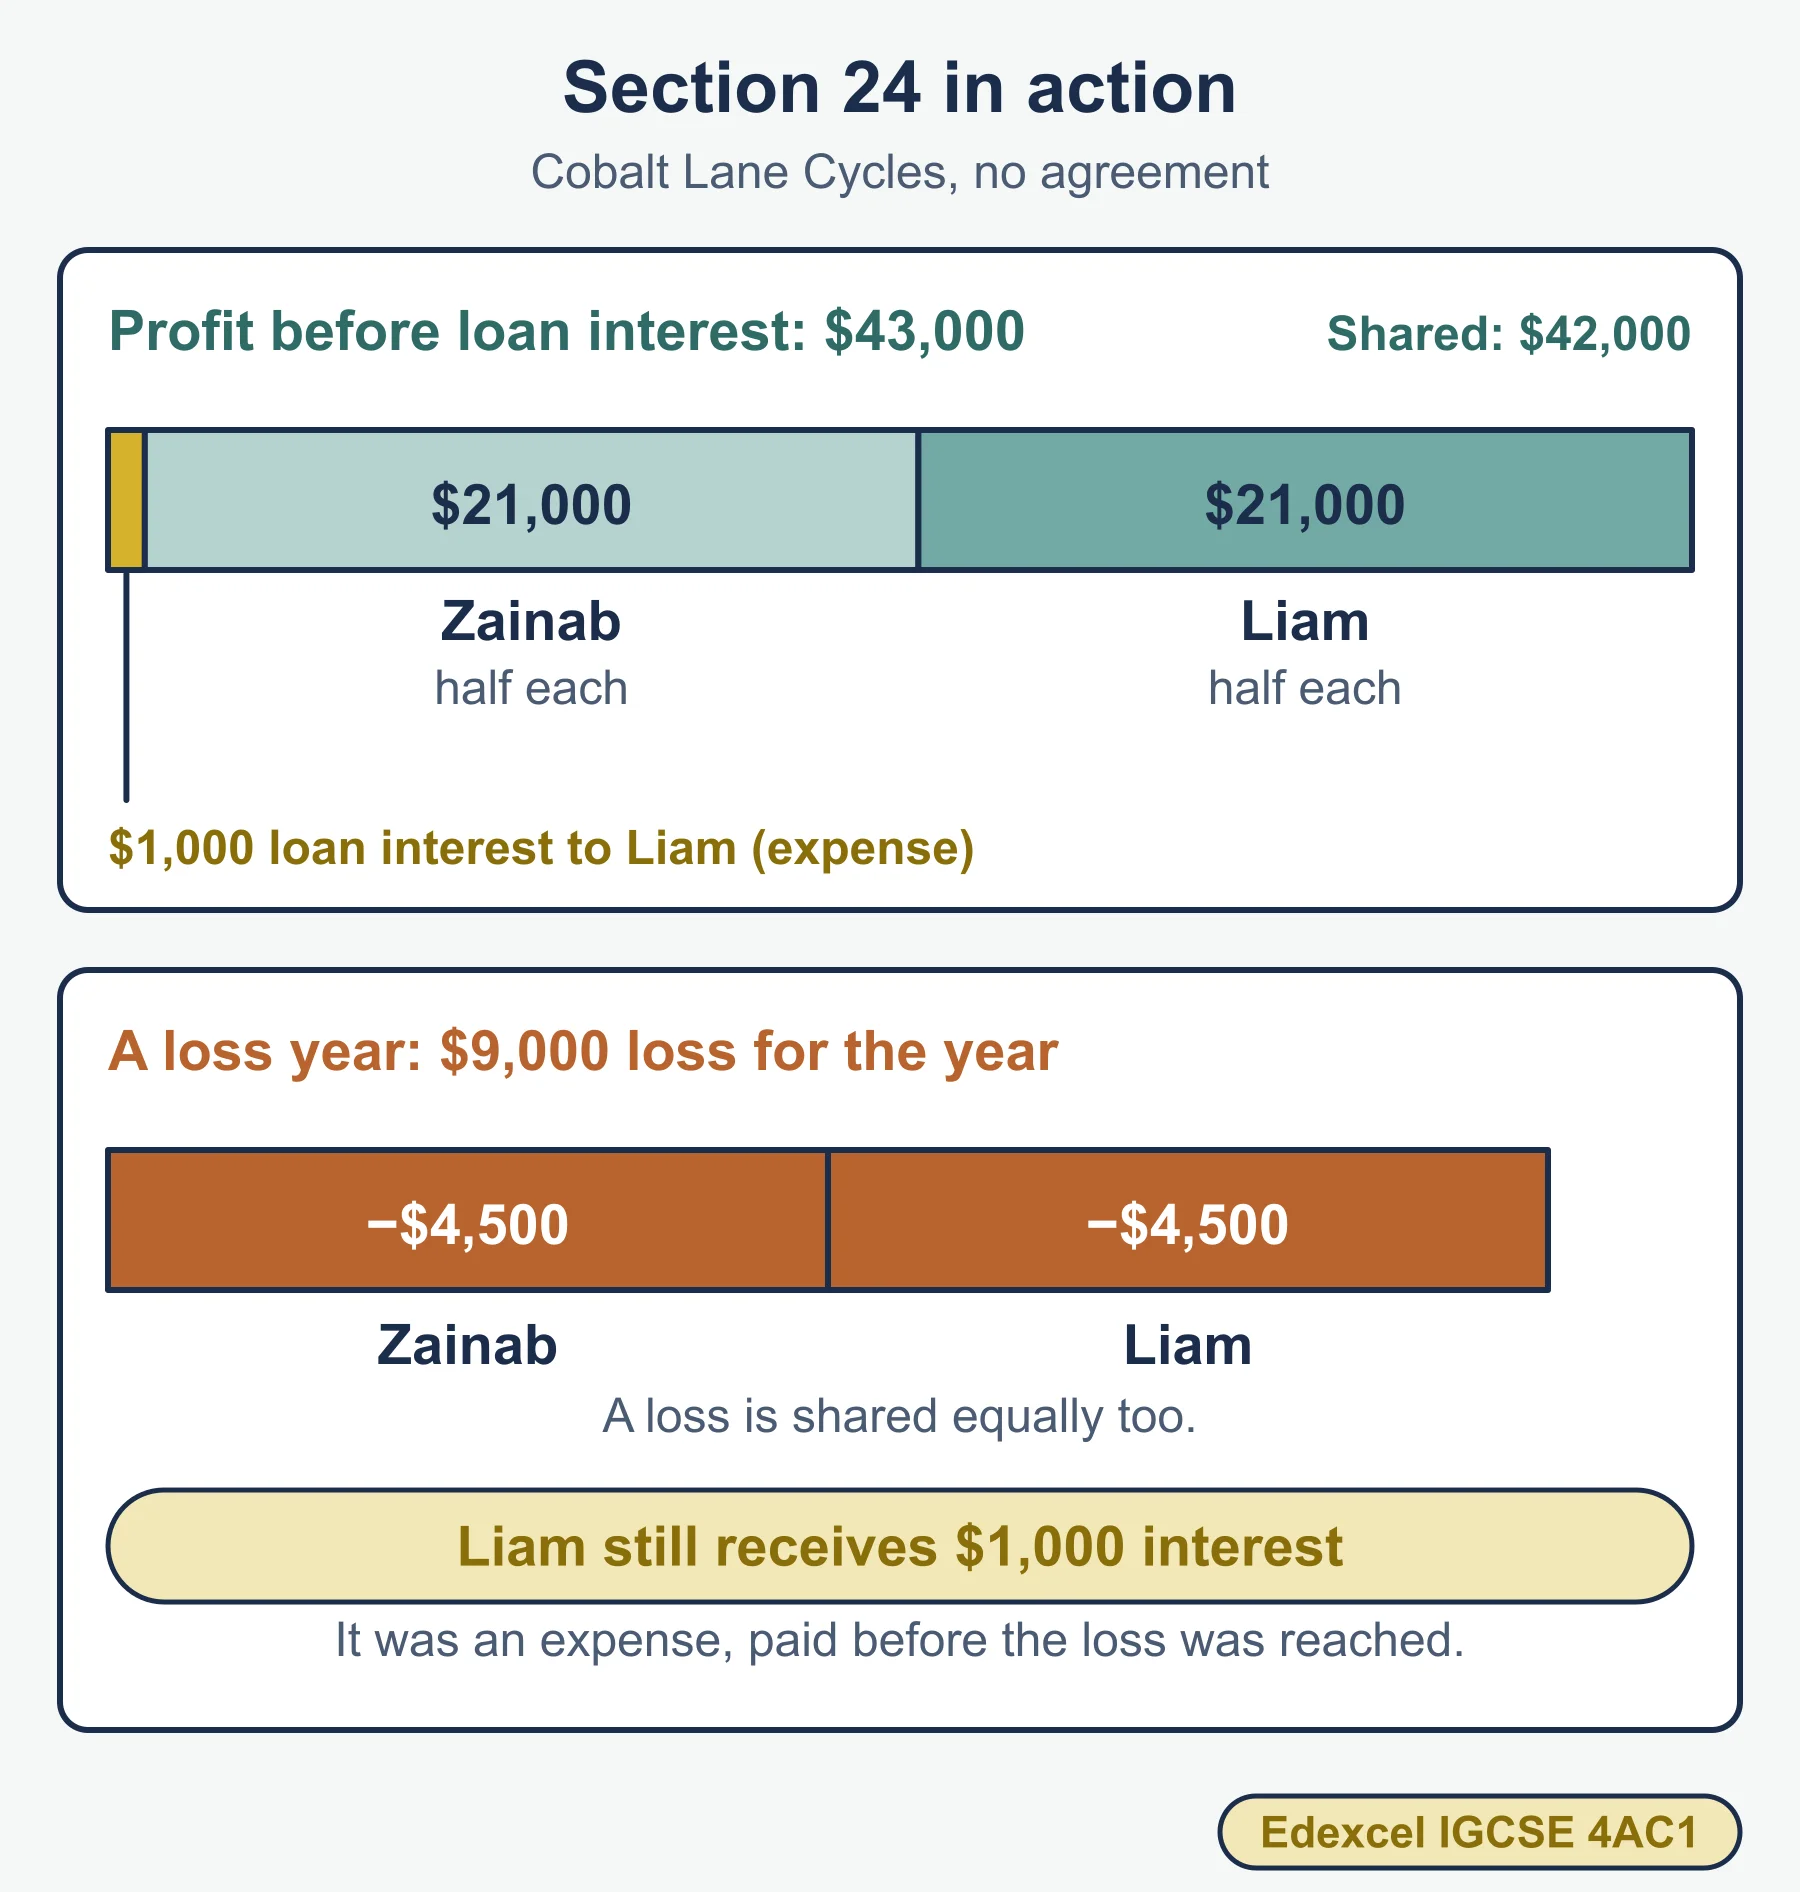
| Interest on a partner’s loan | 5% a year |
| Interest on capital | None |
| Interest on drawings | None charged unless agreed |
The appropriation account (points d and e)
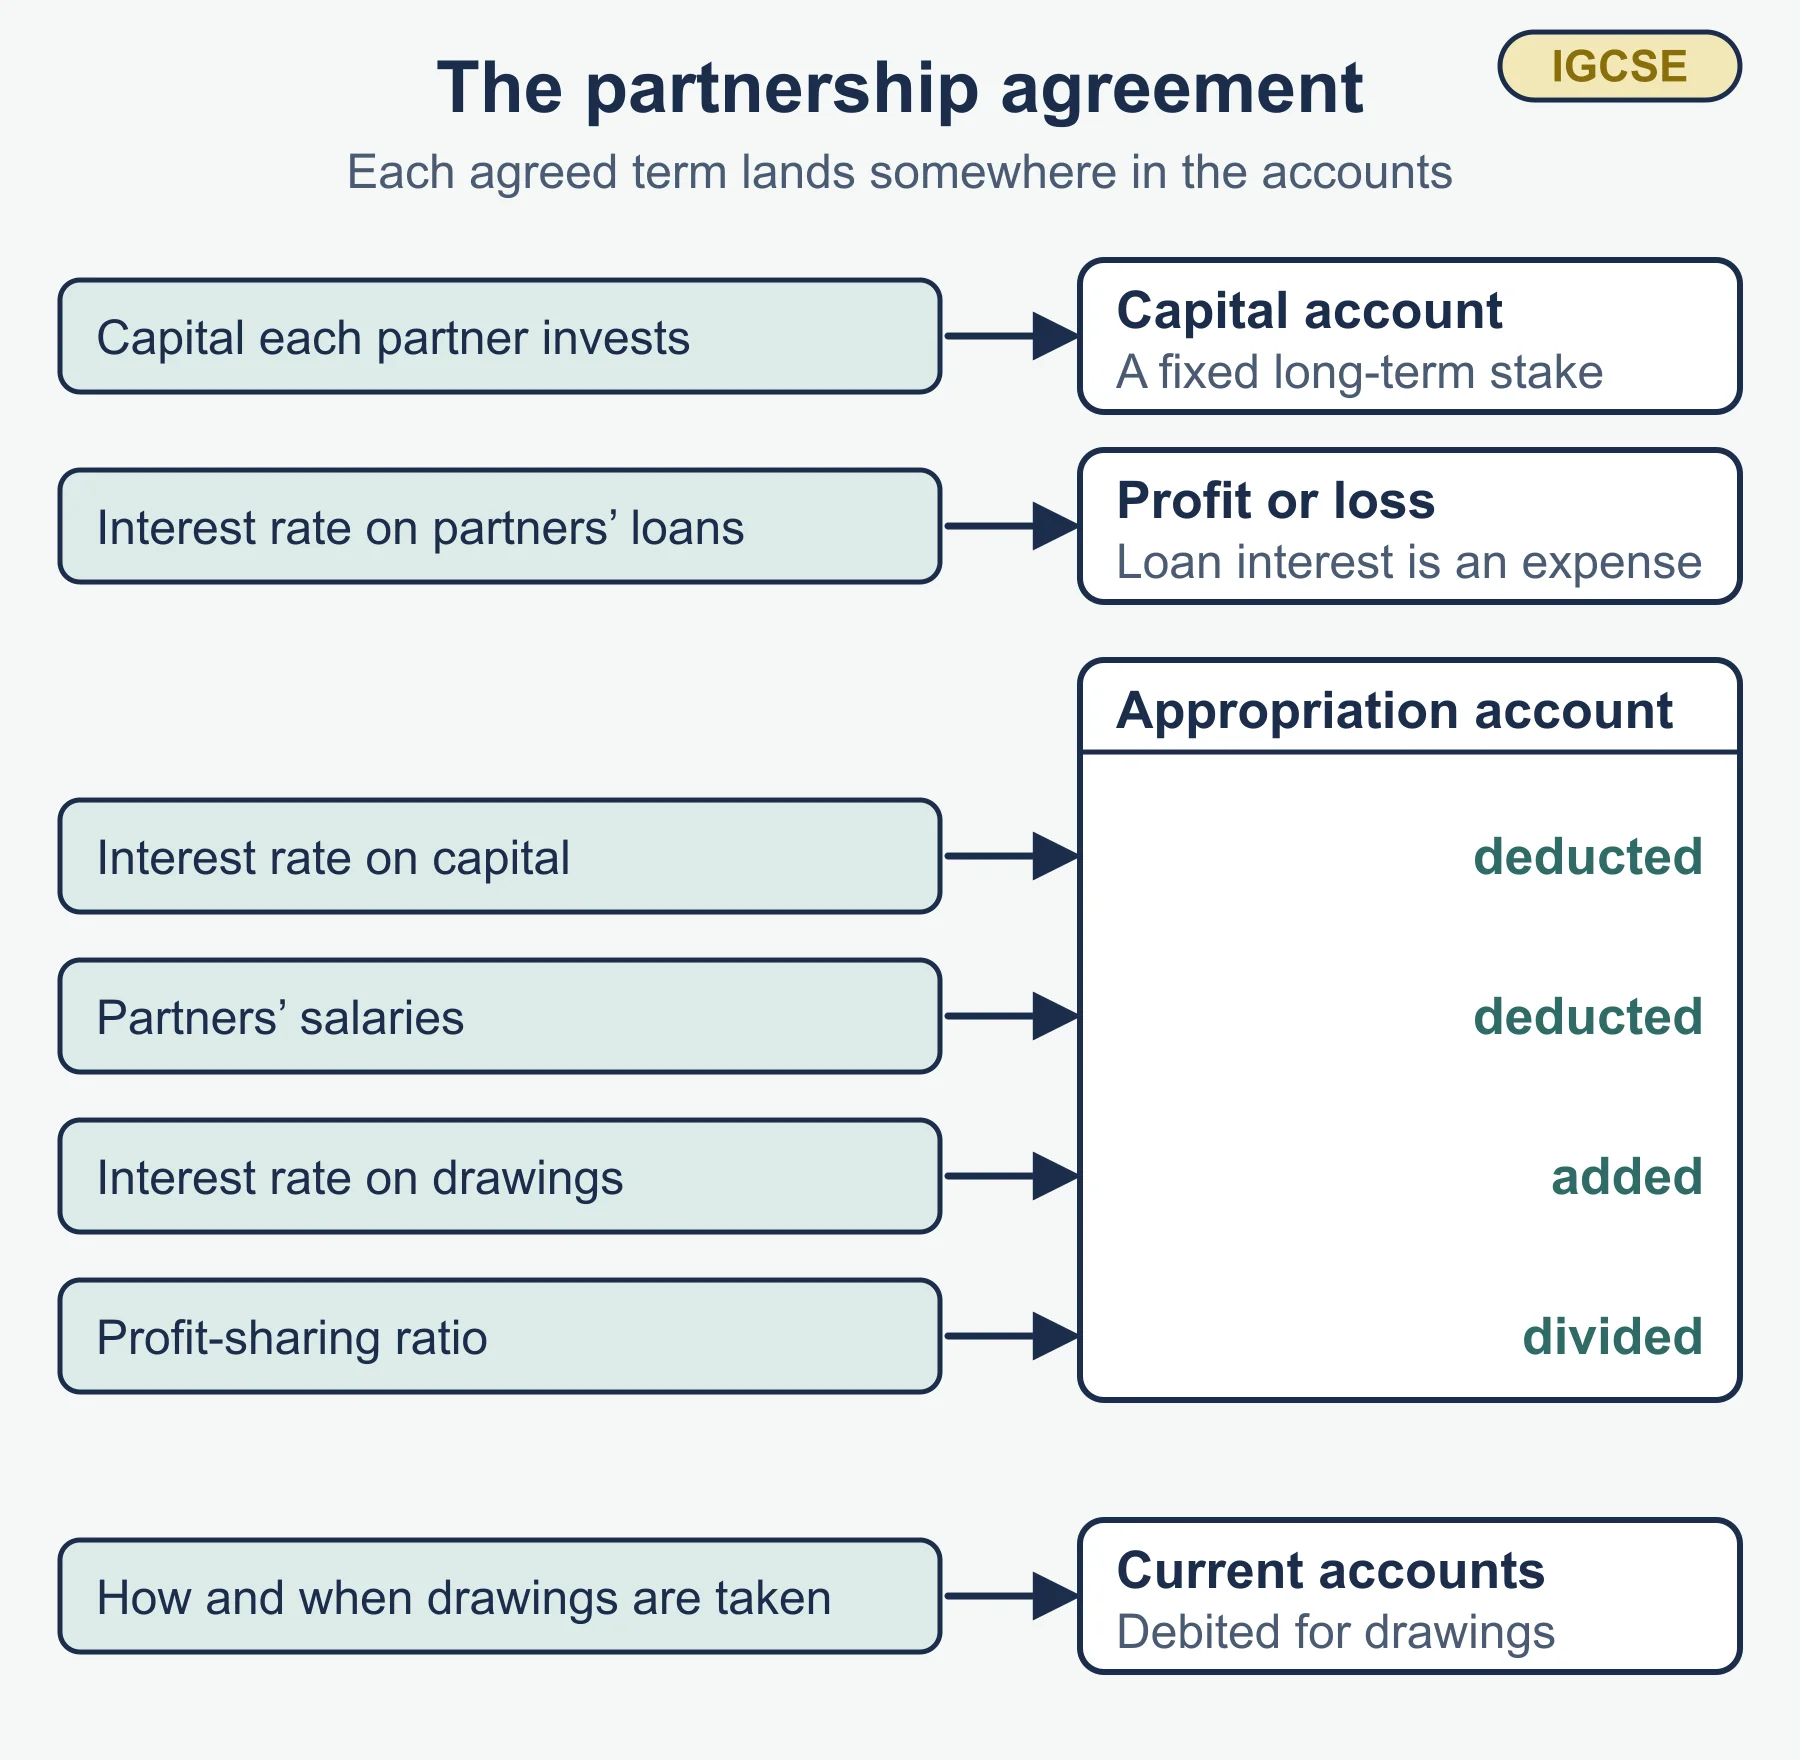
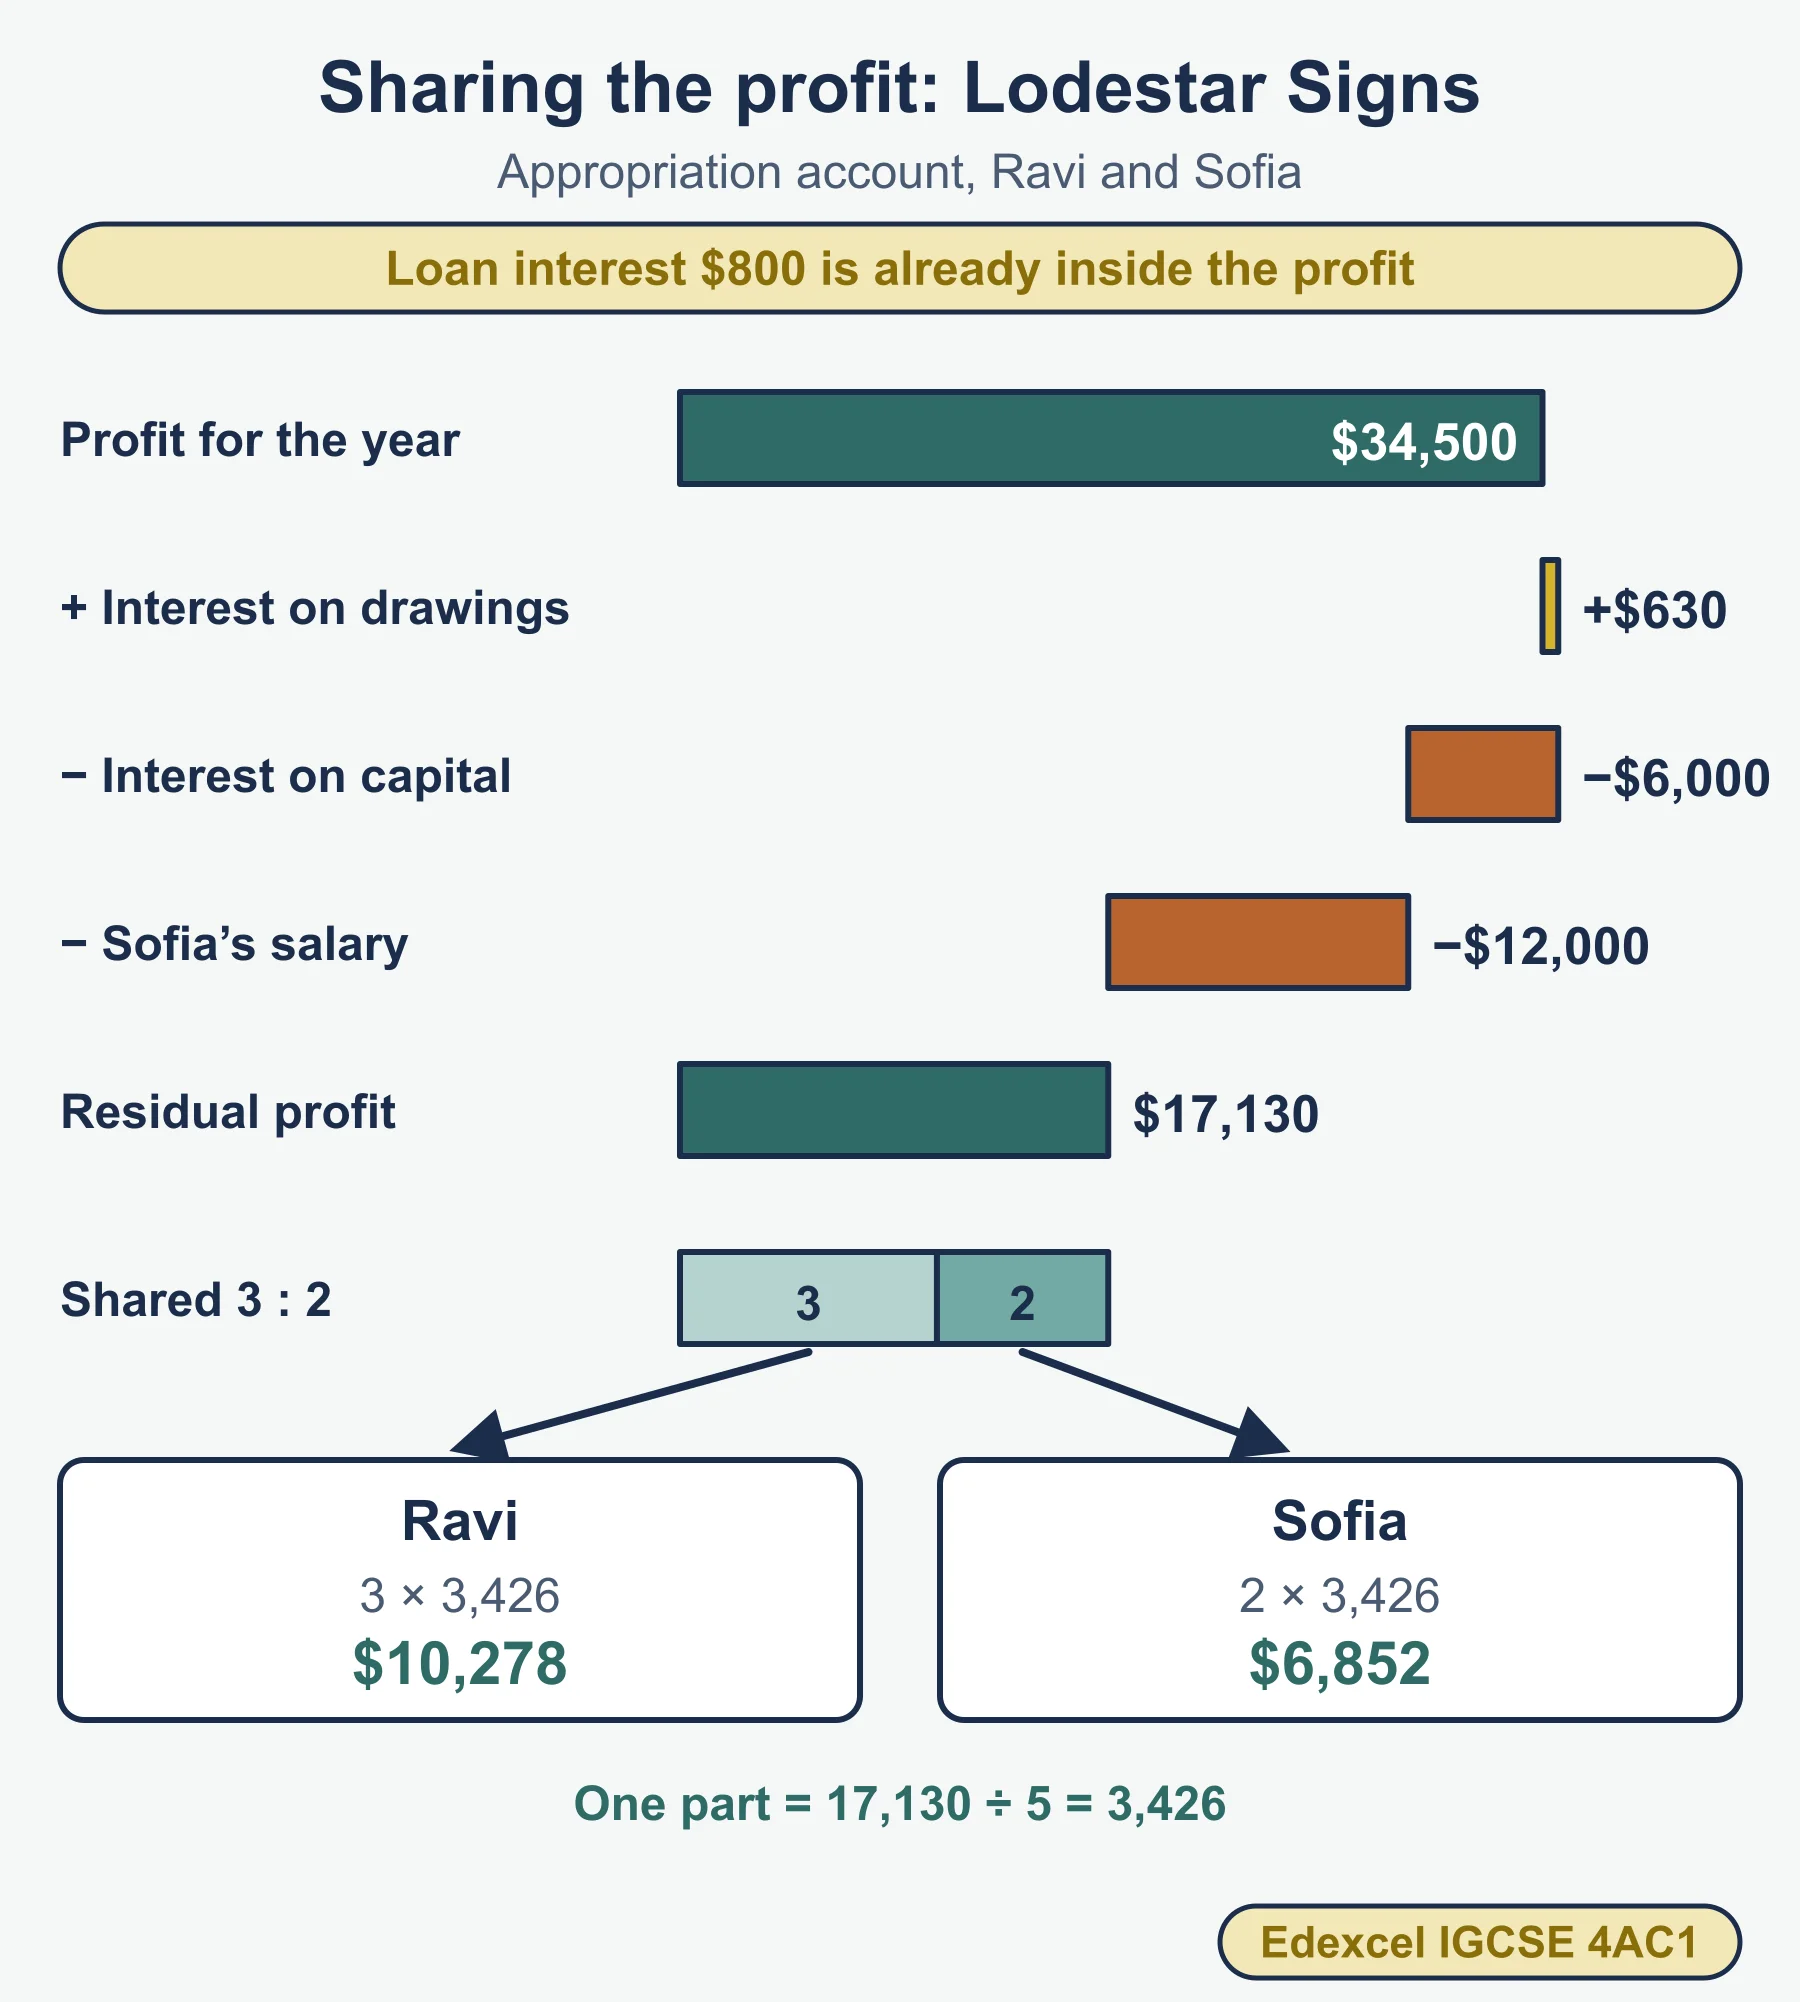
Purpose: it shows how the profit for the year is divided between partners. It follows the income statement and starts from profit for the year.
Layout to learn:
| Line | Treatment |
|---|---|
| Profit for the year | Starting figure |
| Add interest on drawings | Added, because partners are charged it |
| Less interest on capital | Fixed amount for each partner |
| Less salaries | Fixed amount for each partner |
| = Residual profit or deficit | Shared in the profit-sharing ratio |
Method in steps:
- Finish the income statement, including interest on any partner’s loan as an expense.
- Write profit for the year at the top of the appropriation account.
- Add interest on drawings.
- Deduct interest on capital and salaries, partner by partner.
- Find the residual and split it in the ratio.
- Check: total interest on capital, salaries and shares of residual, less interest on drawings, must equal profit for the year.
Capital and current accounts (point f)
| Account | Typical entries |
|---|---|
| Capital (fixed) | Capital paid in or withdrawn on a long-term basis. The balance carried down is the capital shown in the statement of financial position |
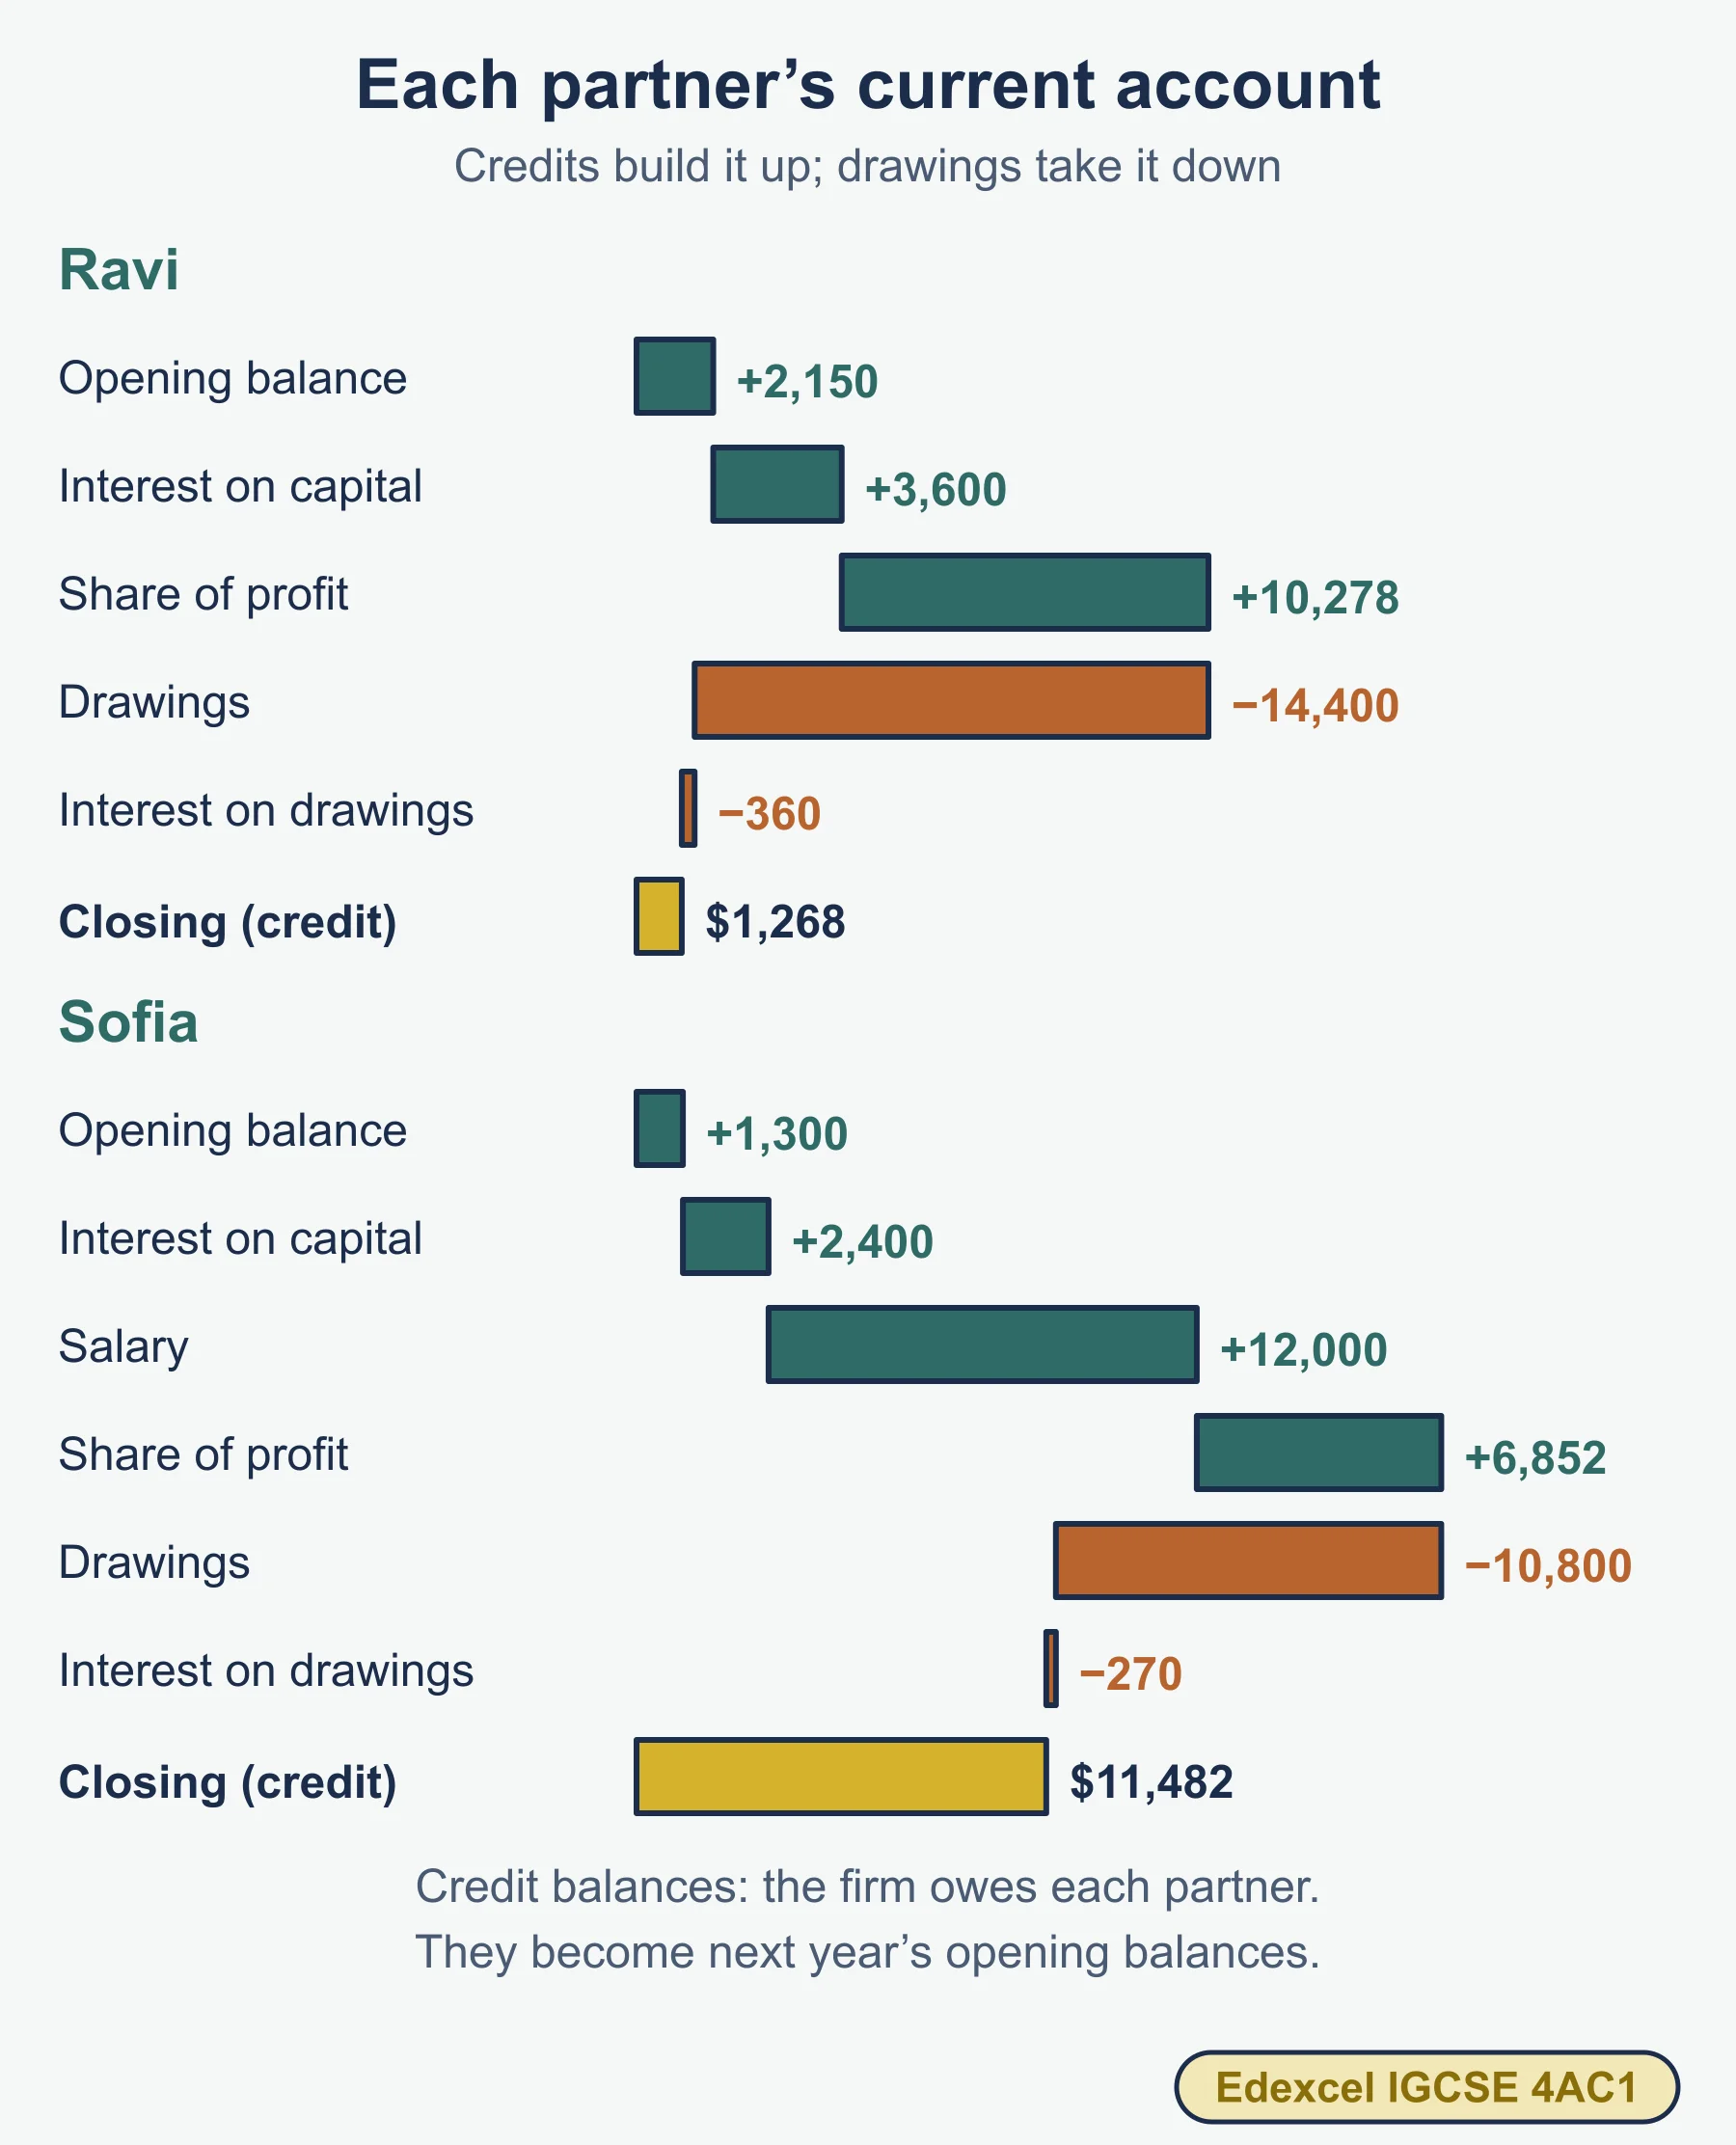
| Current | Credit: interest on capital, salary, share of profit. Debit: drawings, interest on drawings, share of loss. The balance can be credit or debit |
A credit balance on a current account means the firm owes the partner. A debit balance means the partner has taken out more than they have earned from the firm.
Statement of financial position (point g)
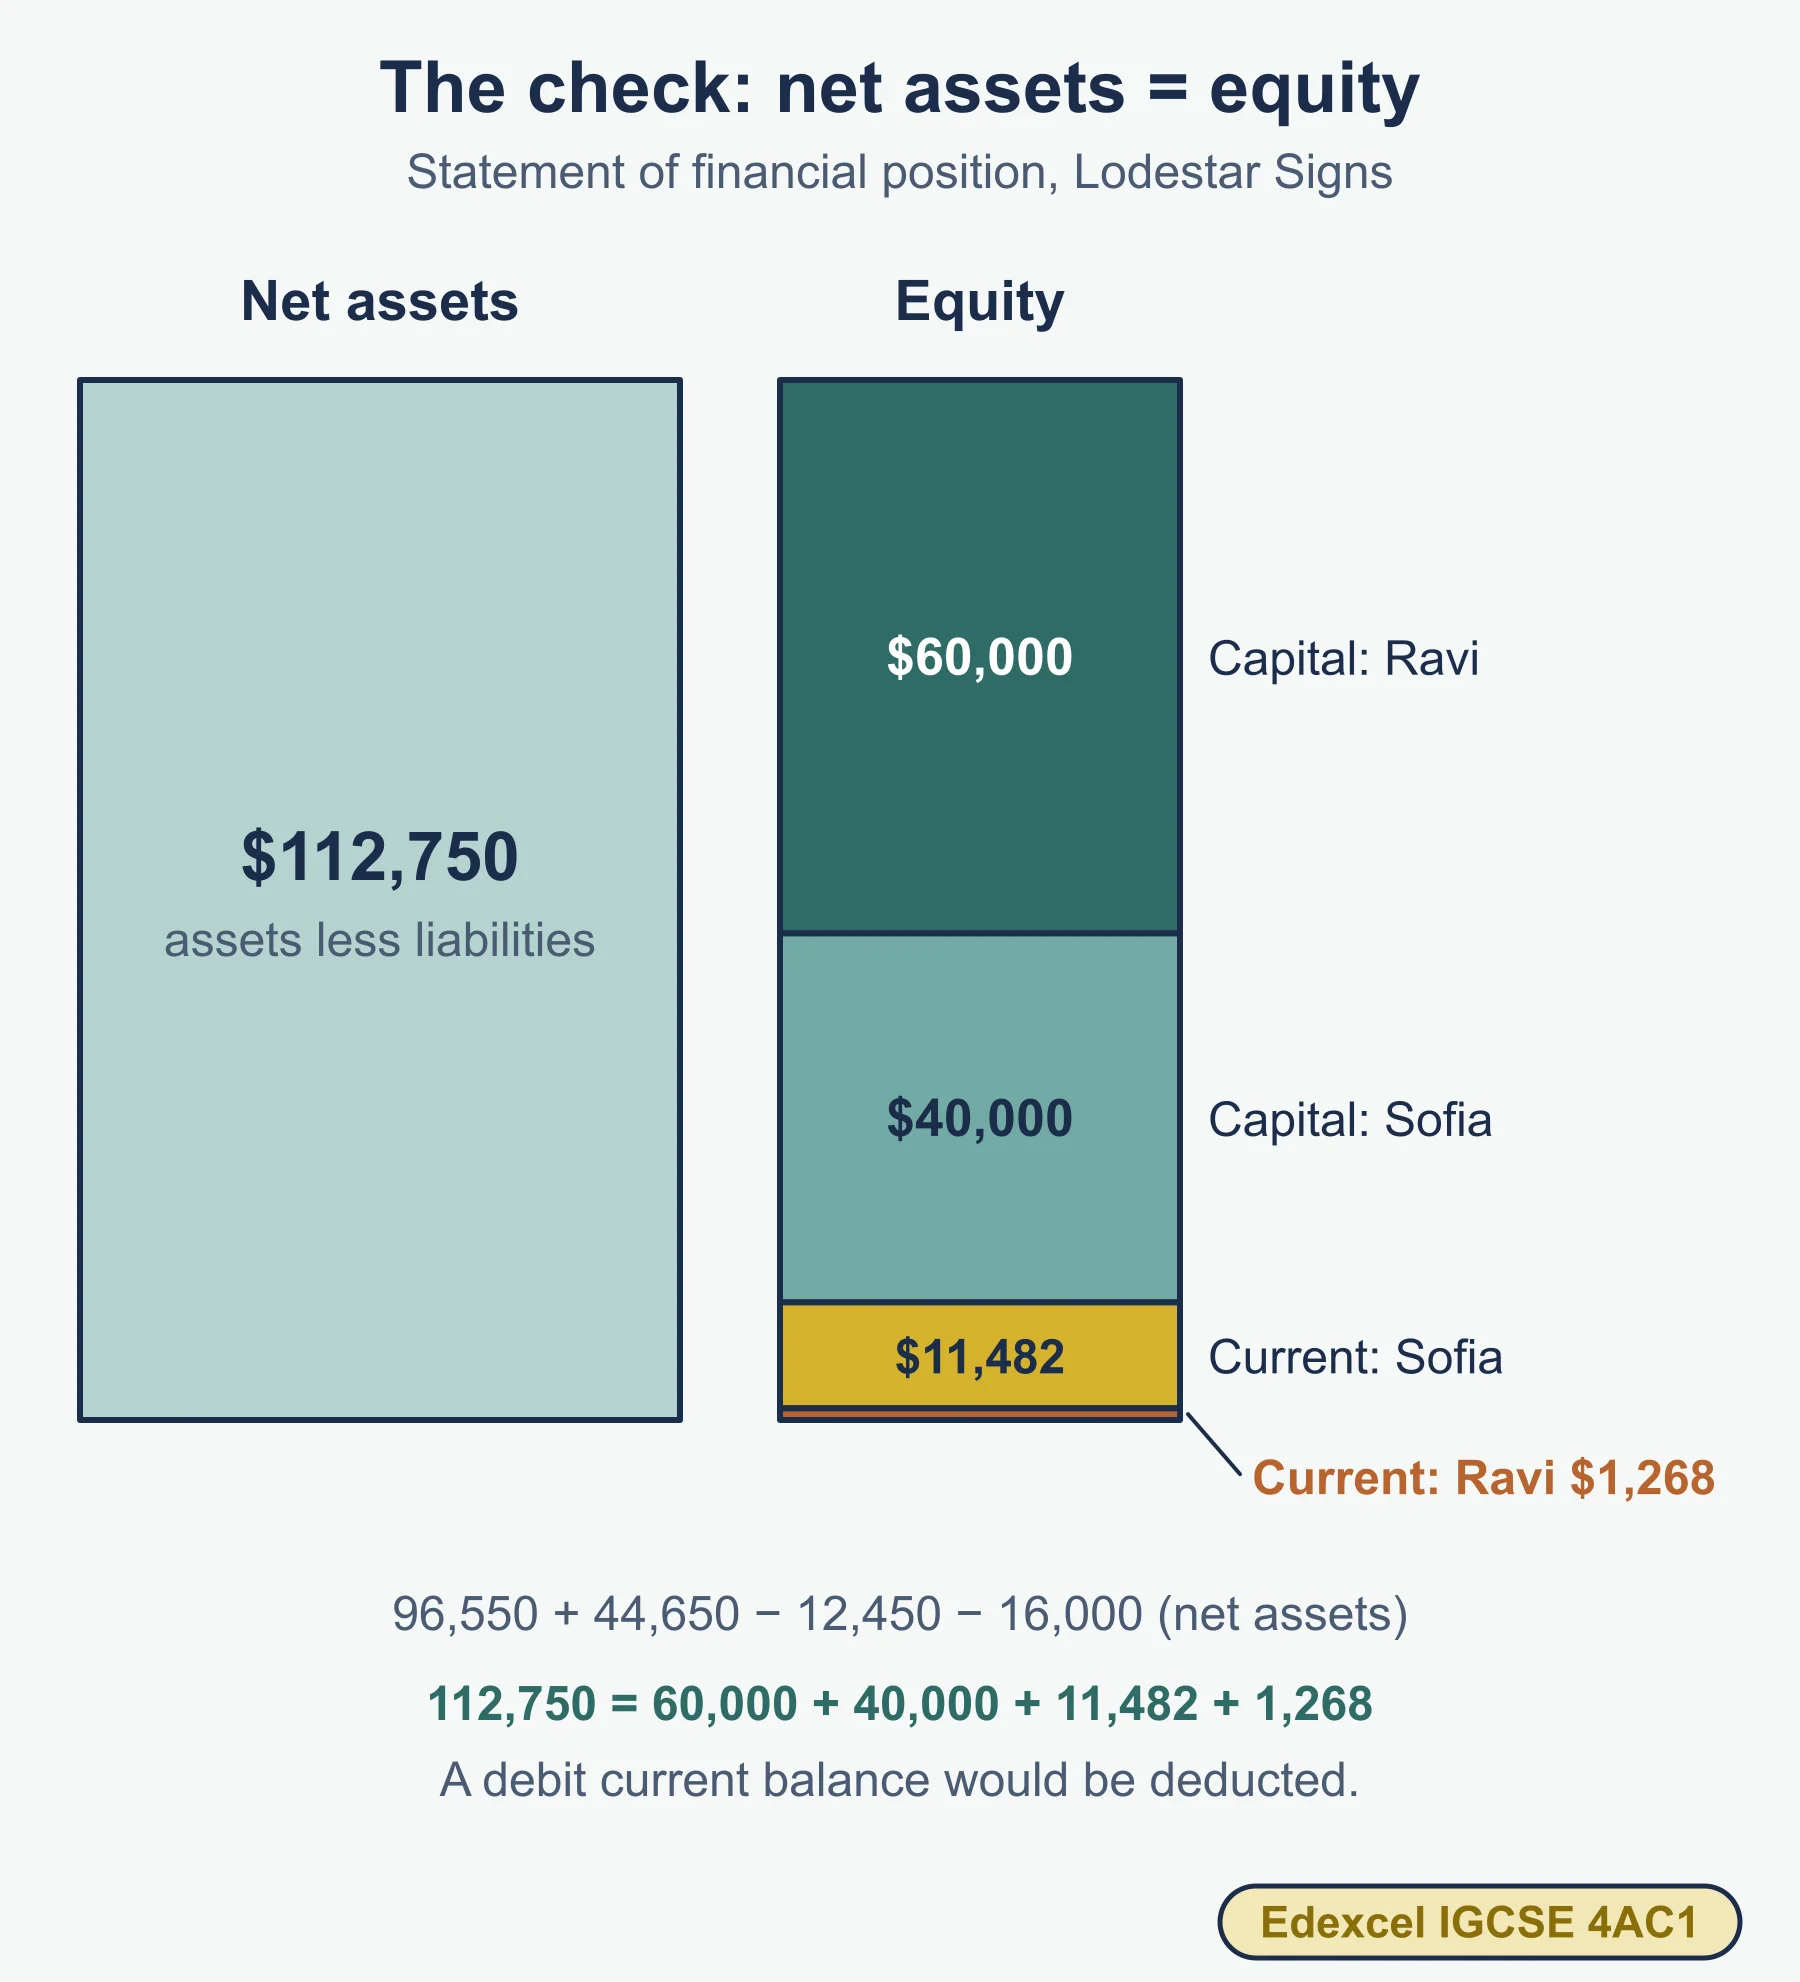
The equity section lists each partner’s capital, then each partner’s current account. A credit current account balance is added. A debit balance is deducted. Total equity must equal net assets.
Worked reminder A: three partners
Sundial Row Optics is owned by Dalia Haddad, Kwame Osei and Irina Volkov. Profit for the year is 48,000. The agreement gives:
- interest on capital at 5% (capitals 50,000, 40,000 and 30,000);
- a salary of 9,000 to Kwame;
- interest on drawings charged on drawings taken evenly through the year at 5% for an average of six months: Dalia 400, Kwame 250, Irina 150;
- the residual shared 4 : 3 : 3.
| Line | Dalia | Kwame | Irina | Total |
|---|---|---|---|---|
| Profit for the year | 48,000 | |||
| Add interest on drawings | 400 | 250 | 150 | 800 |
| Less interest on capital | 2,500 | 2,000 | 1,500 | (6,000) |
| Less salary | 9,000 | (9,000) | ||
| Residual profit | 33,800 | |||
| Share 4 : 3 : 3 | 13,520 | 10,140 | 10,140 | 33,800 |
Current account balances, using opening balances of Dalia 1,000 credit, Kwame 300 debit and Irina nil, and drawings of 16,000, 10,000 and 6,000:
| Line | Dalia | Kwame | Irina |
|---|---|---|---|
| Opening (credit +, debit -) | 1,000 | -300 | 0 |
| Interest on capital | 2,500 | 2,000 | 1,500 |
| Salary | 9,000 | ||
| Share of residual | 13,520 | 10,140 | 10,140 |
| Drawings | -16,000 | -10,000 | -6,000 |
| Interest on drawings | -400 | -250 | -150 |
| Closing balance | 620 credit | 10,590 credit | 5,490 credit |
Worked reminder B: when the residual is a deficit
Ember Court Catering is owned by Pradeep Nair and Chiara Lund, who share equally. Profit for the year is only 5,500. The agreement gives Chiara a salary of 8,000 and 3,000 of interest on capital (Pradeep 1,800 and Chiara 1,200).
| Line | Pradeep | Chiara | Total |
|---|---|---|---|
| Profit for the year | 5,500 | ||
| Less interest on capital | 1,800 | 1,200 | (3,000) |
| Less salary | 8,000 | (8,000) | |
| Deficit | (5,500) | ||
| Share of deficit, equally | (2,750) | (2,750) | (5,500) |
Net effect on the current accounts: Pradeep 1,800 - 2,750 = 950 debit and Chiara 1,200 + 8,000 - 2,750 = 6,450 credit. The two net effects add to the 5,500 profit. The firm still honours the agreed salary and interest, and the partners bear the deficit in the ratio.
Must-know distinctions
Learn these as pairs. Questions can test whether you can tell the two halves apart.
- Loan interest or interest on capital. Loan interest is an expense in the income statement. Interest on capital is an appropriation.
- Drawings or interest on drawings. Drawings go to the current account only. Interest on drawings is a charge that increases the profit shared.
- Capital account or current account. Capital is the long-term investment. The current account is the yearly running balance.
- Income statement or appropriation account. The first measures profit. The second shares it.
- Fixed amounts or the ratio. Salaries and interest are fixed. Only the residual follows the ratio.
Quick self-test
- A partner with no agreement lends 8,000 to the firm for a full year. How much interest is due, and where is it shown?
- Under Section 24, how is a profit shared when the partners have said nothing?
- Calculate interest on capital at 8% on a capital of 25,000.
- Drawings of 7,200 were taken evenly through the year and the agreement charges 6% a year. Calculate interest on drawings.
- On which side of a current account are drawings recorded?
- A residual of 12,000 is shared 3 : 1. What does each partner receive?
- A current account has an opening credit of 900, interest on capital 1,500, a share of profit 4,200 and drawings of 6,000. Find the closing balance.
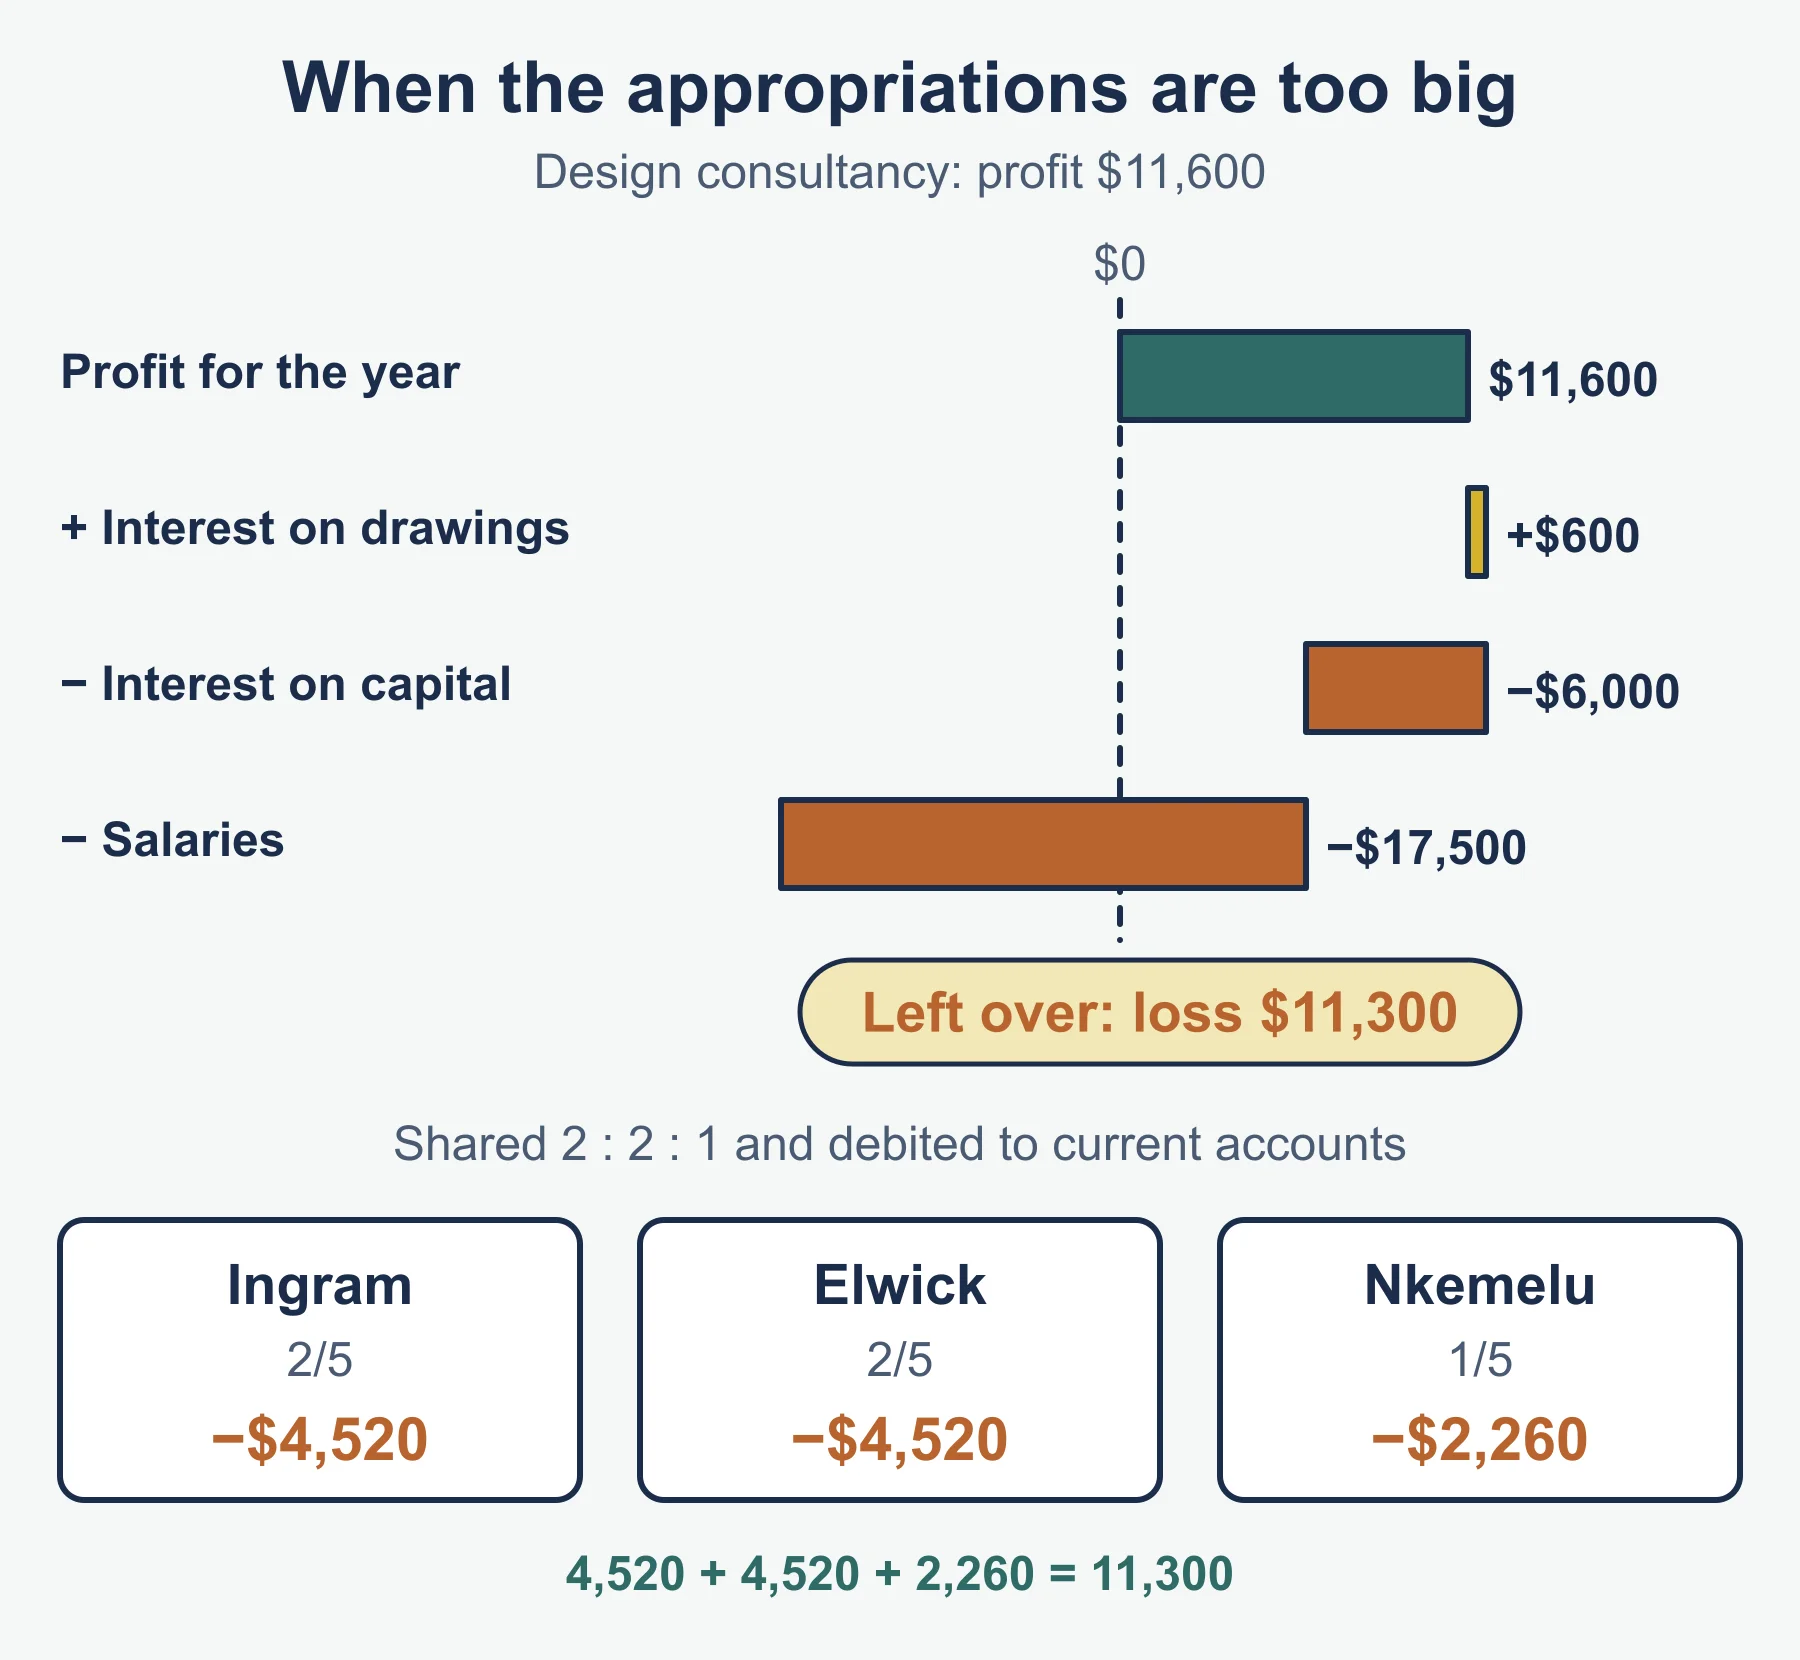
- Explain what happens if the agreed salary is larger than the profit for the year.
- State one difference between an LLP and an ordinary partnership.
- How is a debit current account balance shown in the statement of financial position?
- Give two reasons for forming a partnership rather than trading alone.
- Why is interest on a partner’s loan not found in the appropriation account?
Answers
- 8,000 x 5% = 400. It is an expense in the income statement.
- Equally, and losses are shared equally too.
- 25,000 x 8% = 2,000.
- 7,200 x 6% x 6/12 = 216.
- The debit side.
- 9,000 and 3,000.
- 900 + 1,500 + 4,200 - 6,000 = 600 credit.
- The salary is still credited to the partner. The residual becomes a deficit, shared in the ratio.
- Members of an LLP have limited liability, whereas partners in an ordinary partnership have unlimited liability.
- It is deducted in the equity section.
- For example more capital and shared skills.
- It is a cost of using money borrowed from a partner, so it is charged before the profit for the year is found.
Where marks are usually lost
- Putting loan interest in the appropriation account instead of the income statement.
- Subtracting interest on drawings instead of adding it.
- Sharing salary and interest on capital in the ratio, rather than as fixed amounts.
- Forgetting that a debit opening balance on a current account reduces the closing balance.
- Treating a negative residual as a reason to drop salary and interest. They are still credited.
- Misreading “evenly through the year” and charging interest for twelve months.
- Writing “limited liability” for an ordinary partnership.
- Showing a current account in equity but leaving the capital accounts out, so total equity does not match net assets.
Frequently asked questions
What is an appropriation account? An appropriation account shows how the profit for the year is shared among the partners. It starts from profit for the year and is not part of the income statement.
Are partners’ drawings shown in the appropriation account? No. Drawings are the partner taking out money that has already been earned, so they are debited to the partner’s current account rather than appropriated.
Why do people form a partnership? A partnership brings in more capital, shared skills, a shared workload and risk, and continuity. The drawbacks include unlimited liability in an ordinary partnership and possible disagreements between partners.
How are partners’ accounts shown in the statement of financial position? The equity section shows each partner’s capital account and current account balance, with a debit current account balance deducted. Total equity should equal net assets, which checks the workings.
Official syllabus
Pearson Edexcel International GCSE in Accounting (4AC1), Specification, Issue 1, October 2016, published by Pearson Education Limited. Topic 4: The preparation of financial statements, section 2 (Financial statements of a partnership), points a to g.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Study guides
Edexcel IGCSE Accounting: Financial statements of a sole trader (4AC1)
Step-by-step guide to a sole trader's income statement and statement of financial position, with two worked examples, for Edexcel IGCSE Accounting.
Accounting · Pearson Edexcel · IGCSE
Read guide -
Practice questions
Edexcel IGCSE Accounting: Financial statements of a sole trader (4AC1) – Practice Questions
Ten original questions with worked answers on preparing a sole trader's income statement and statement of financial position, for Edexcel IGCSE Accounting.
Accounting · Pearson Edexcel · IGCSE
Try questions -
Revision notes
Edexcel IGCSE Accounting: Financial statements of a sole trader (4AC1) – Revision Notes
Condensed notes on sole trader income statements and statements of financial position: layouts, classification tables, a worked reminder and a self-test.
Accounting · Pearson Edexcel · IGCSE
Revise topic
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Pearson Edexcel Accounting teachers at Marlbridge

