
Revision Notes
IGCSE Accounting: Valuation of inventory (Cambridge 0452) – Revision Notes
Condensed revision notes for Cambridge IGCSE Accounting 0452 section 4.5: NRV rule, count-date adjustments, effects of inventory errors, and a self-test.
- Subject
- Accounting
- Level
- IGCSE, O LEVELS
- Topic
- Accounting procedures
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Javaid Iqbal Sabri (what this means)
Aligned to Cambridge IGCSE O Level Accounting (0452, 7707), 2027-2029. Official specification (IGCSE) ; Official specification (O Level) .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Accounting; Cambridge O Level Accounting.
Syllabus points this page covers
0452
- 4.5 Valuation of inventory
7707
- 4.5 Valuation of inventory
Found an error? Report a correction.
Want a teacher for this? Marlbridge teaches Accounting online. Request a free trial class.
Syllabus edition note. This resource follows the Cambridge IGCSE Accounting 0452 syllabus (and Cambridge O Level Accounting 7707, which has the same subject content for the same series) for exams in 2027, 2028 and 2029 (version 1), first examined in the March 2027 series in India and the June 2027 series elsewhere. If you sit 0452 in November 2026, you sit the 2026 syllabus (version 2), which differs: Paper 1 has 35 multiple-choice marks in 1 hour 15 minutes, not 40 marks in 1 hour 30 minutes; Topic 7 is “Accounting principles and policies”, without 7.2 Ethical considerations or 7.3 Technology and sustainability; 4.4 is “Irrecoverable debts and provision for doubtful debts”; income statements are named instead of statements of profit or loss; three-column running balance accounts are not required; Clubs and societies is 5.4 and Manufacturing accounts 5.5; and 6.3 is “Inter-firm comparison”. For this topic, the 2026 syllabus says “recovery of debts written off” where the 2027-2029 syllabus says “irrecoverable debts recovered”, asks for simple inventory valuation statements, and does not separately list choosing a depreciation method for each type of non-current asset, journal entries for purchasing a non-current asset, or calculating the profit or loss on disposal. If you sit in November 2026, work from the 2026 syllabus on the Cambridge International website.
Condensed recall for section 4.5 of Cambridge IGCSE Accounting 0452 (syllabus for exams in 2027, 2028 and 2029, version 1). For the full explanation and longer worked examples, use the study guide. Then test yourself with the practice questions. Related pages: the Cambridge IGCSE Accounting hub, the printable checklist, the free diagnostics and the wider Accounting Procedures revision notes. Amounts are in dollars ($).
The three official points
- The valuation of inventory at the lower of cost and net realisable value.
- How to calculate the value of inventory.
- The effect of an incorrect valuation of inventory on gross profit, profit for the year, equity and asset valuation.
Key terms
| Term | Meaning |
|---|---|
| Cost | What the business paid for the units (given per unit in a question) |
| Selling price | What the units are expected to sell for |
| Costs still to pay | Repairs, repackaging, commission, delivery to the customer |
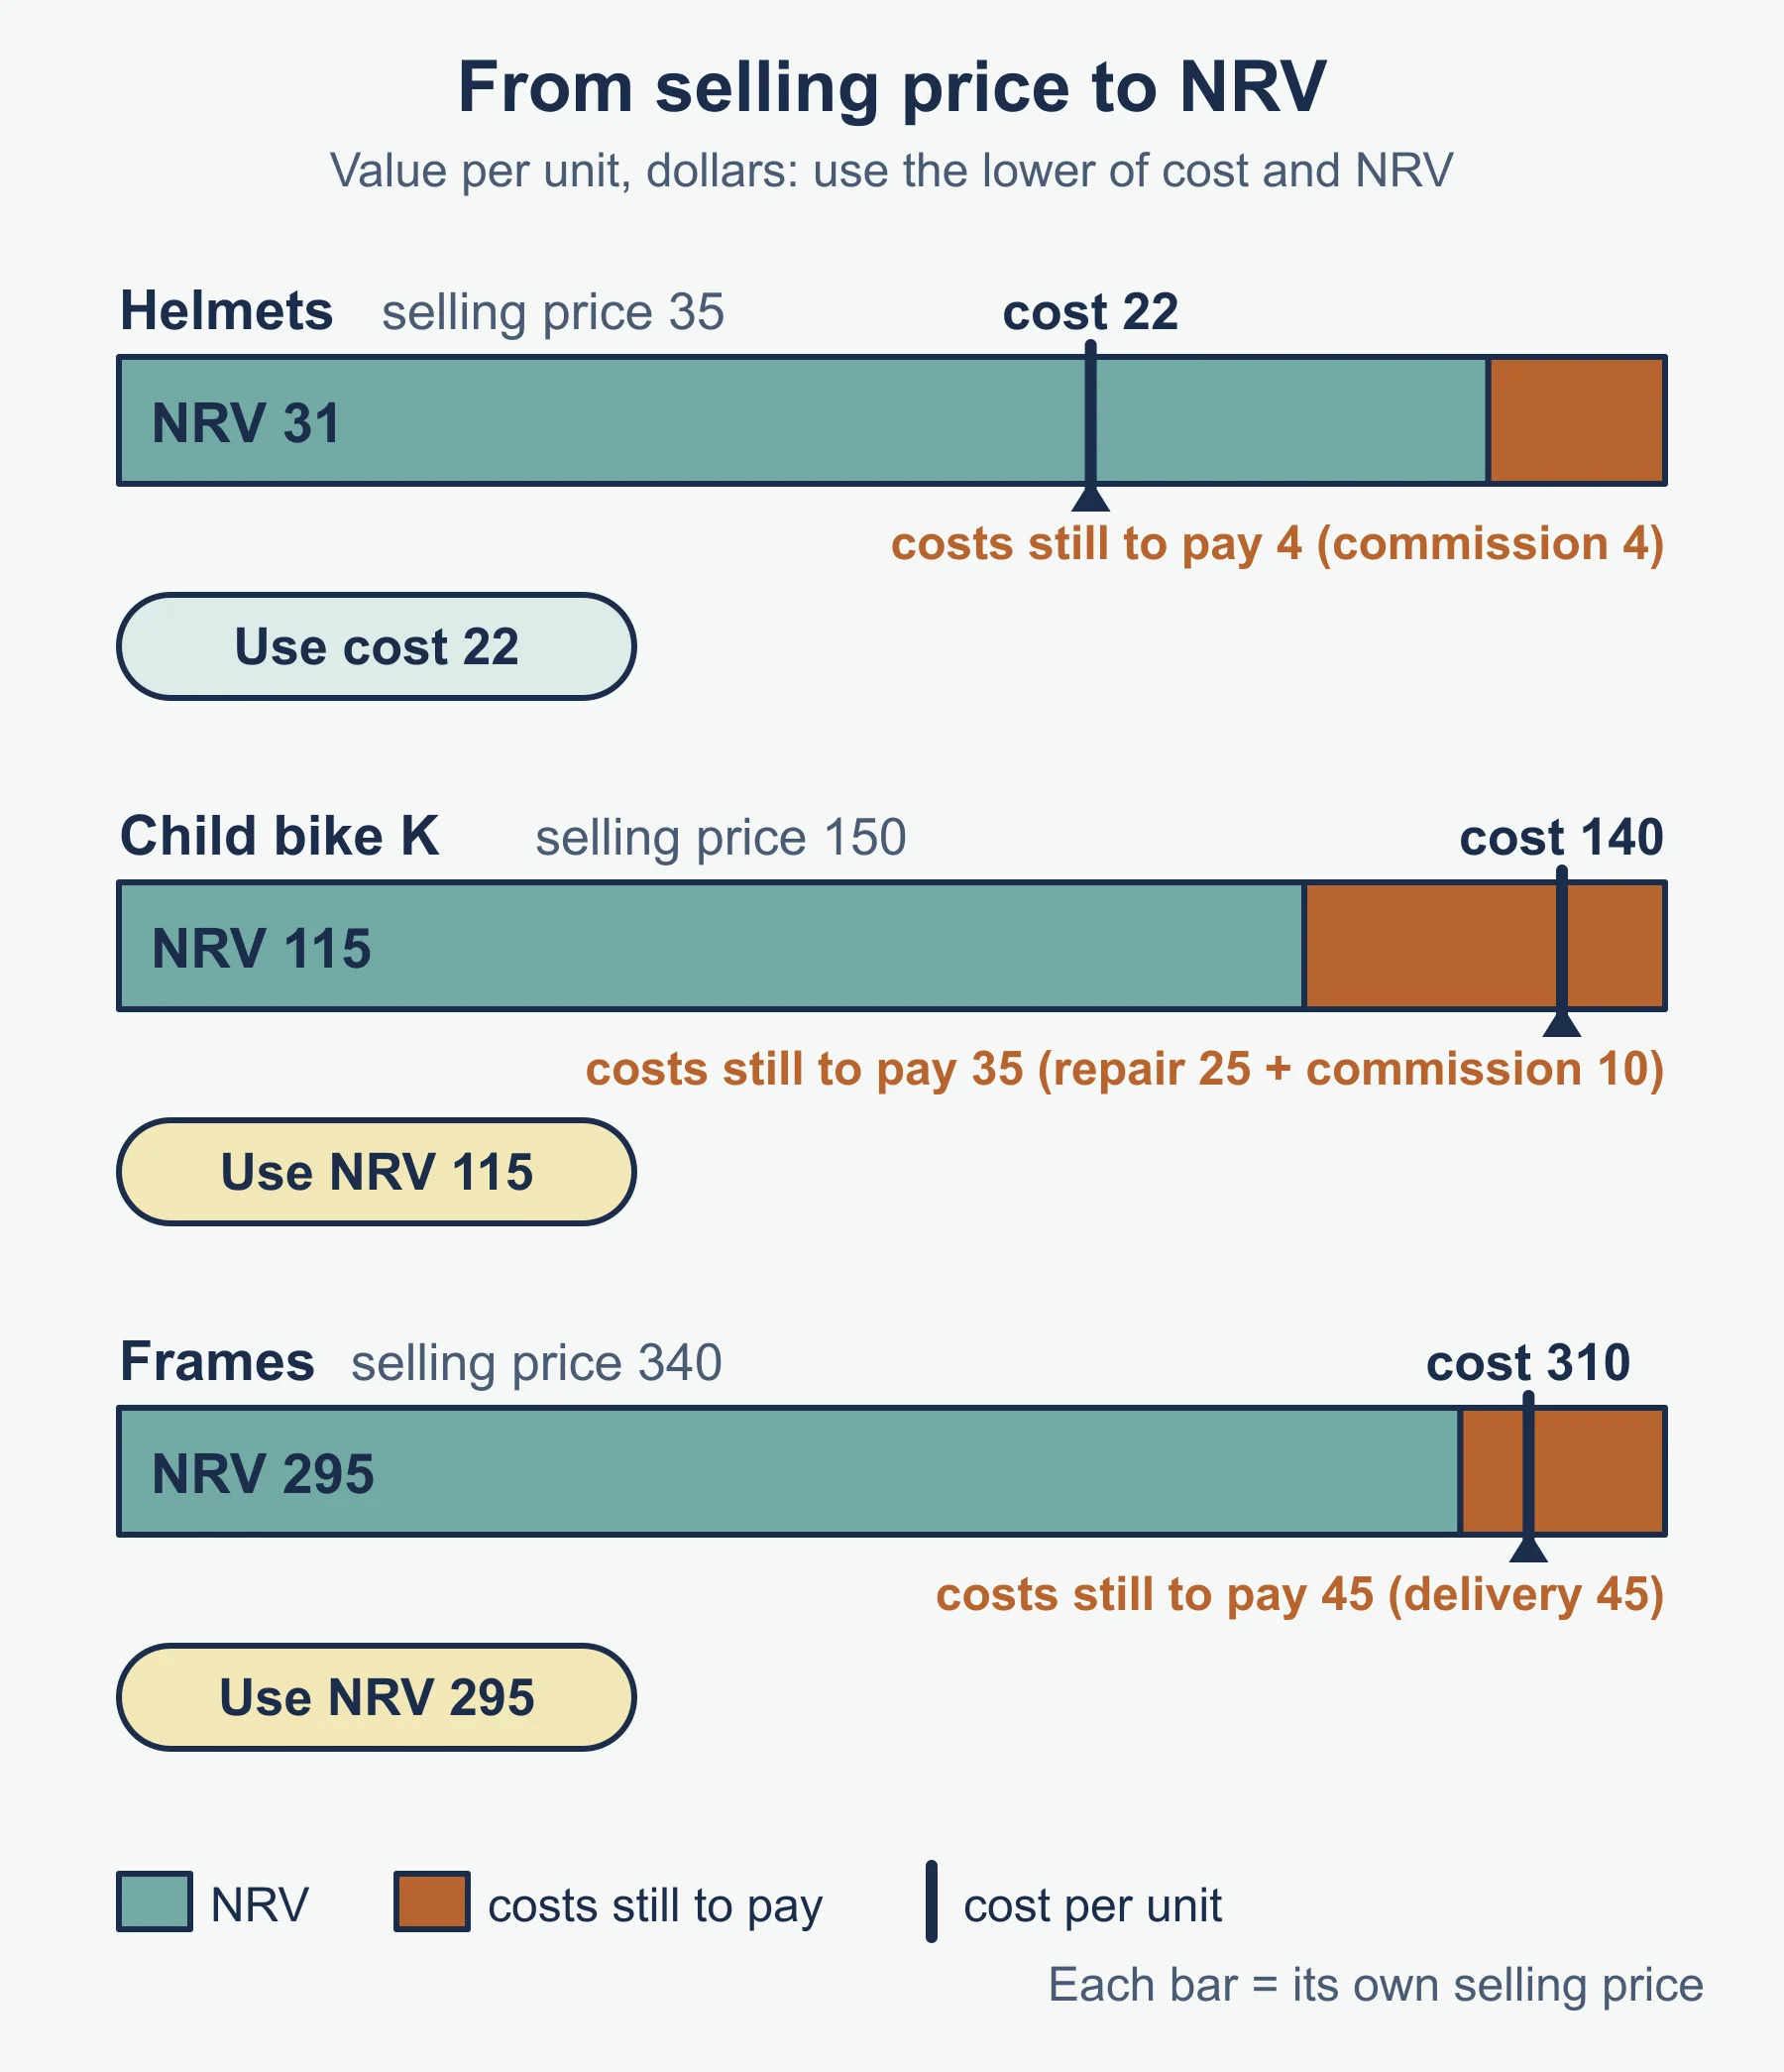
| Net realisable value (NRV) | Expected selling price less costs still to pay |
| Value per unit | The lower of cost and NRV |
| Mark-up | Profit as a percentage of cost |
| Margin | Profit as a percentage of selling price |
Method: valuing inventory
- List each item (or group of identical items) with its units.
- Find NRV per unit: selling price − repair, repackaging, commission or delivery.
- Choose the lower of cost and NRV for that item.
- Multiply by the number of units.
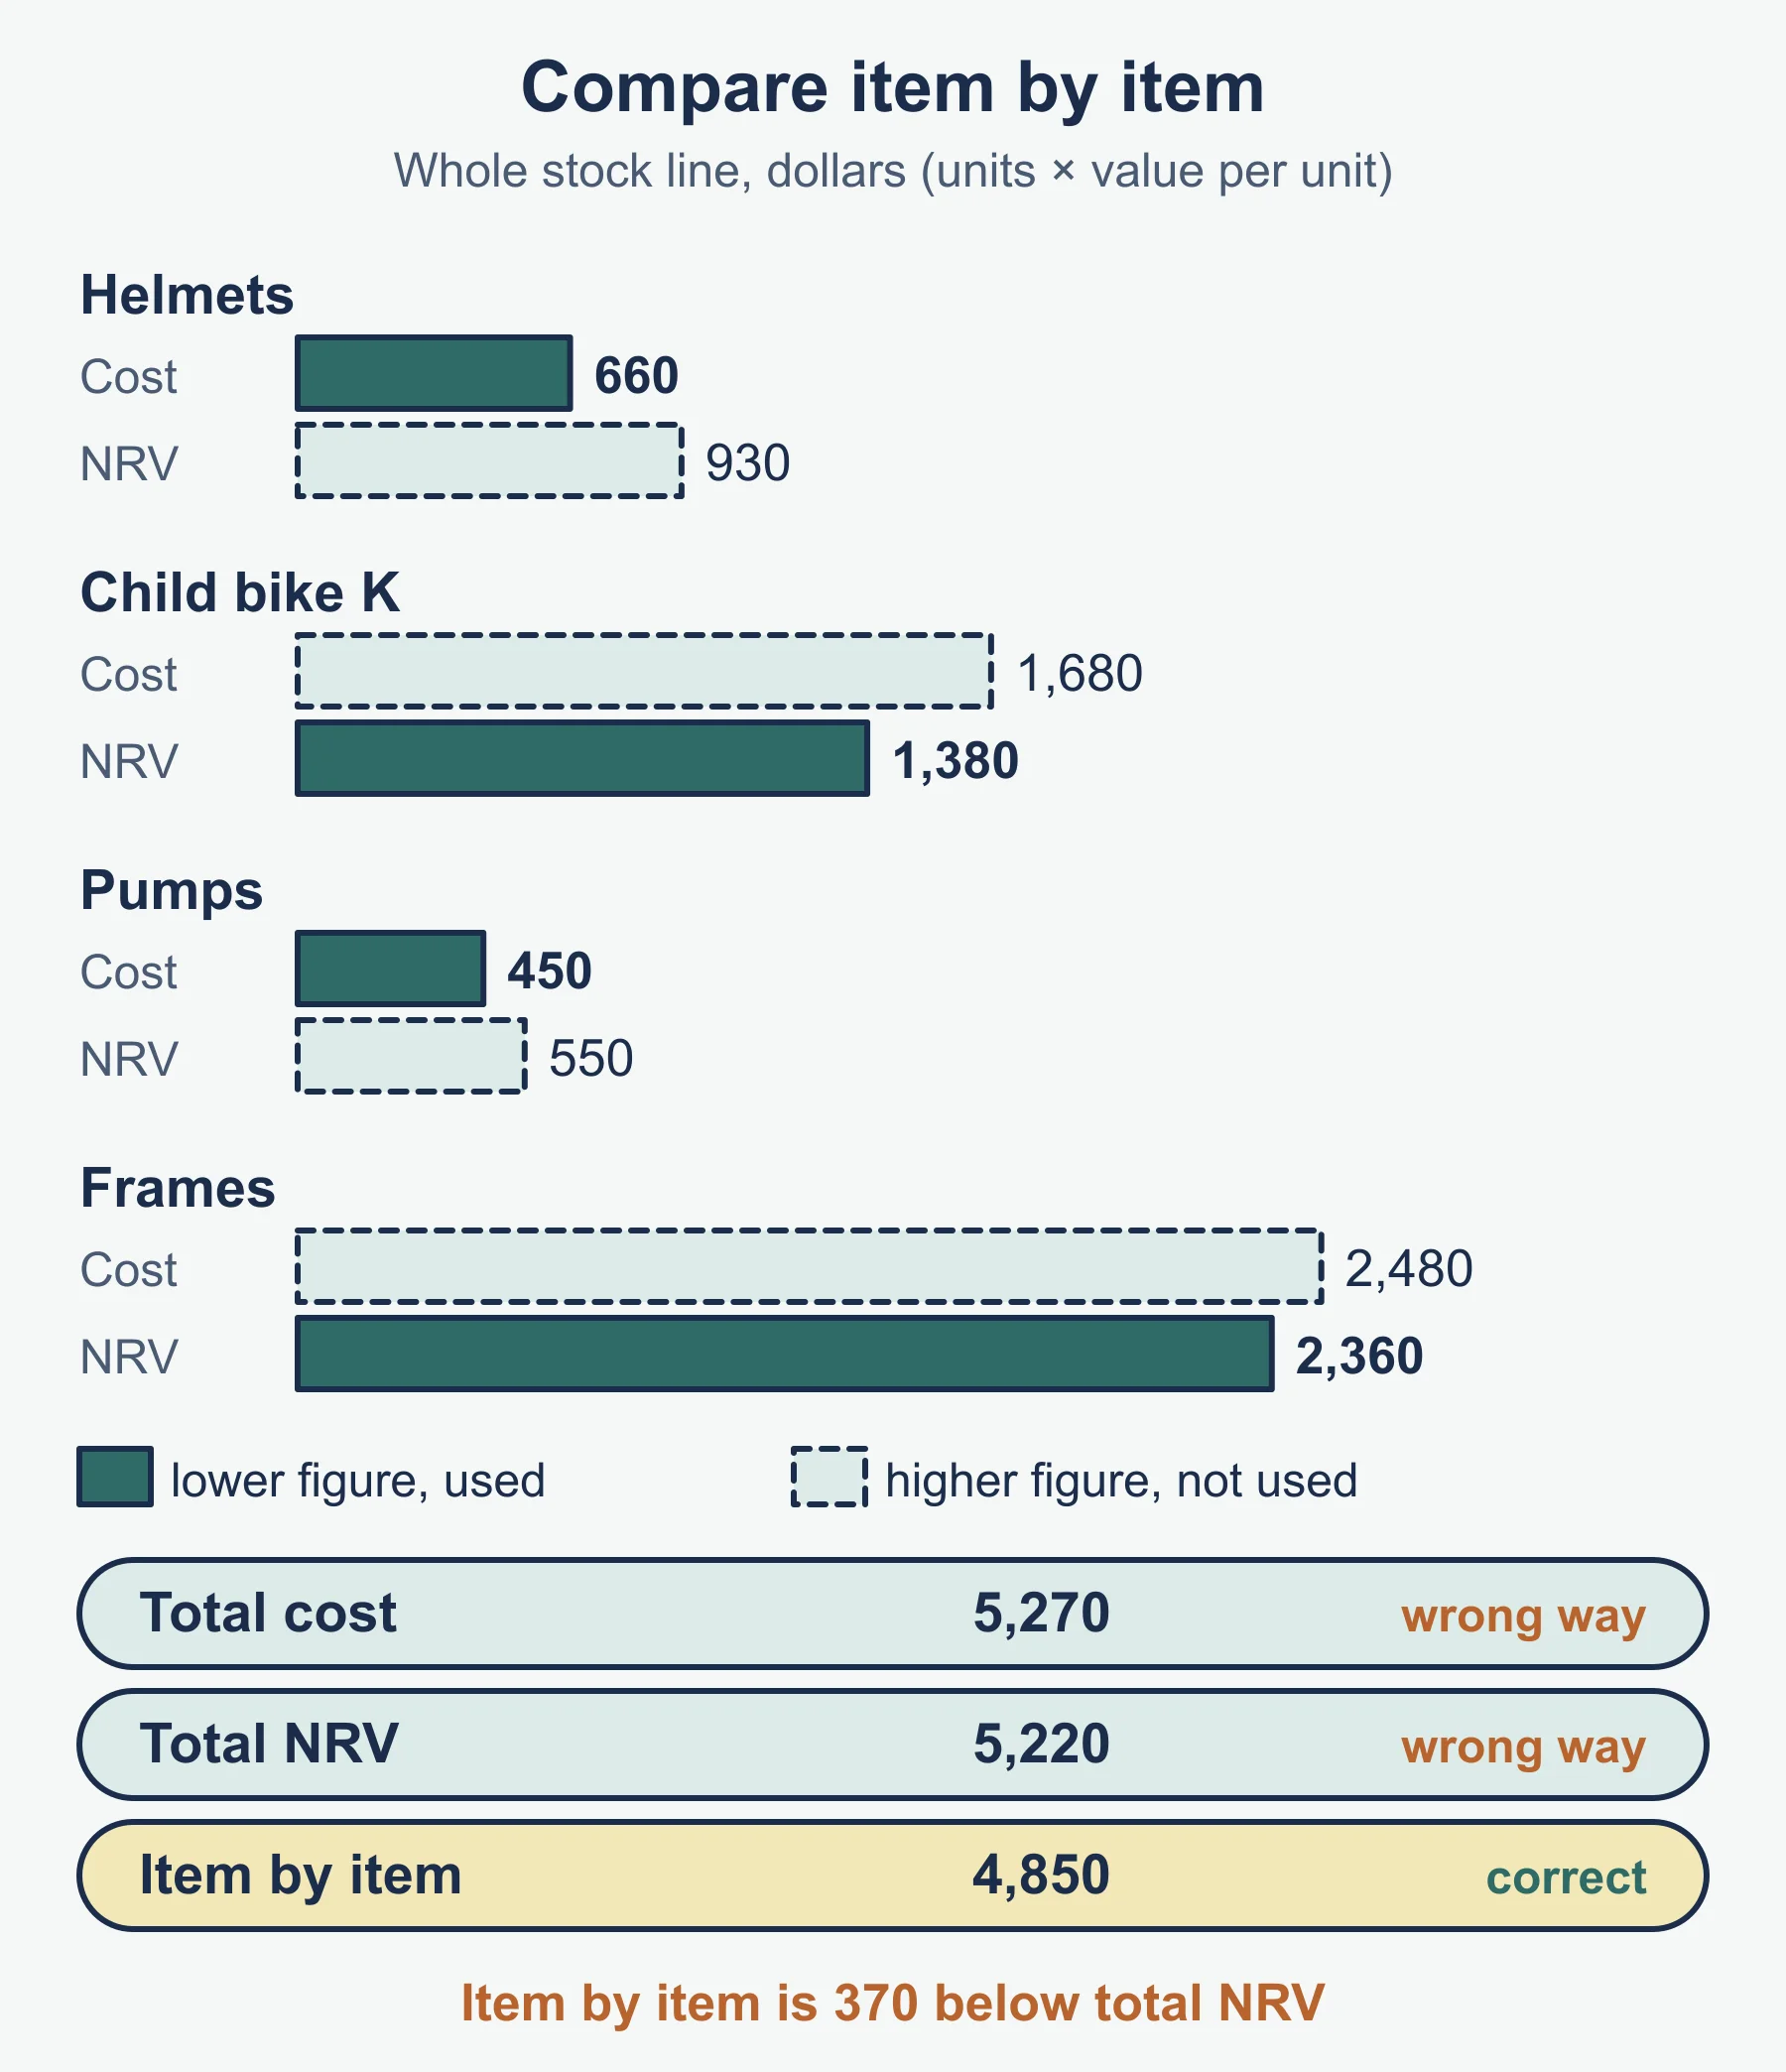
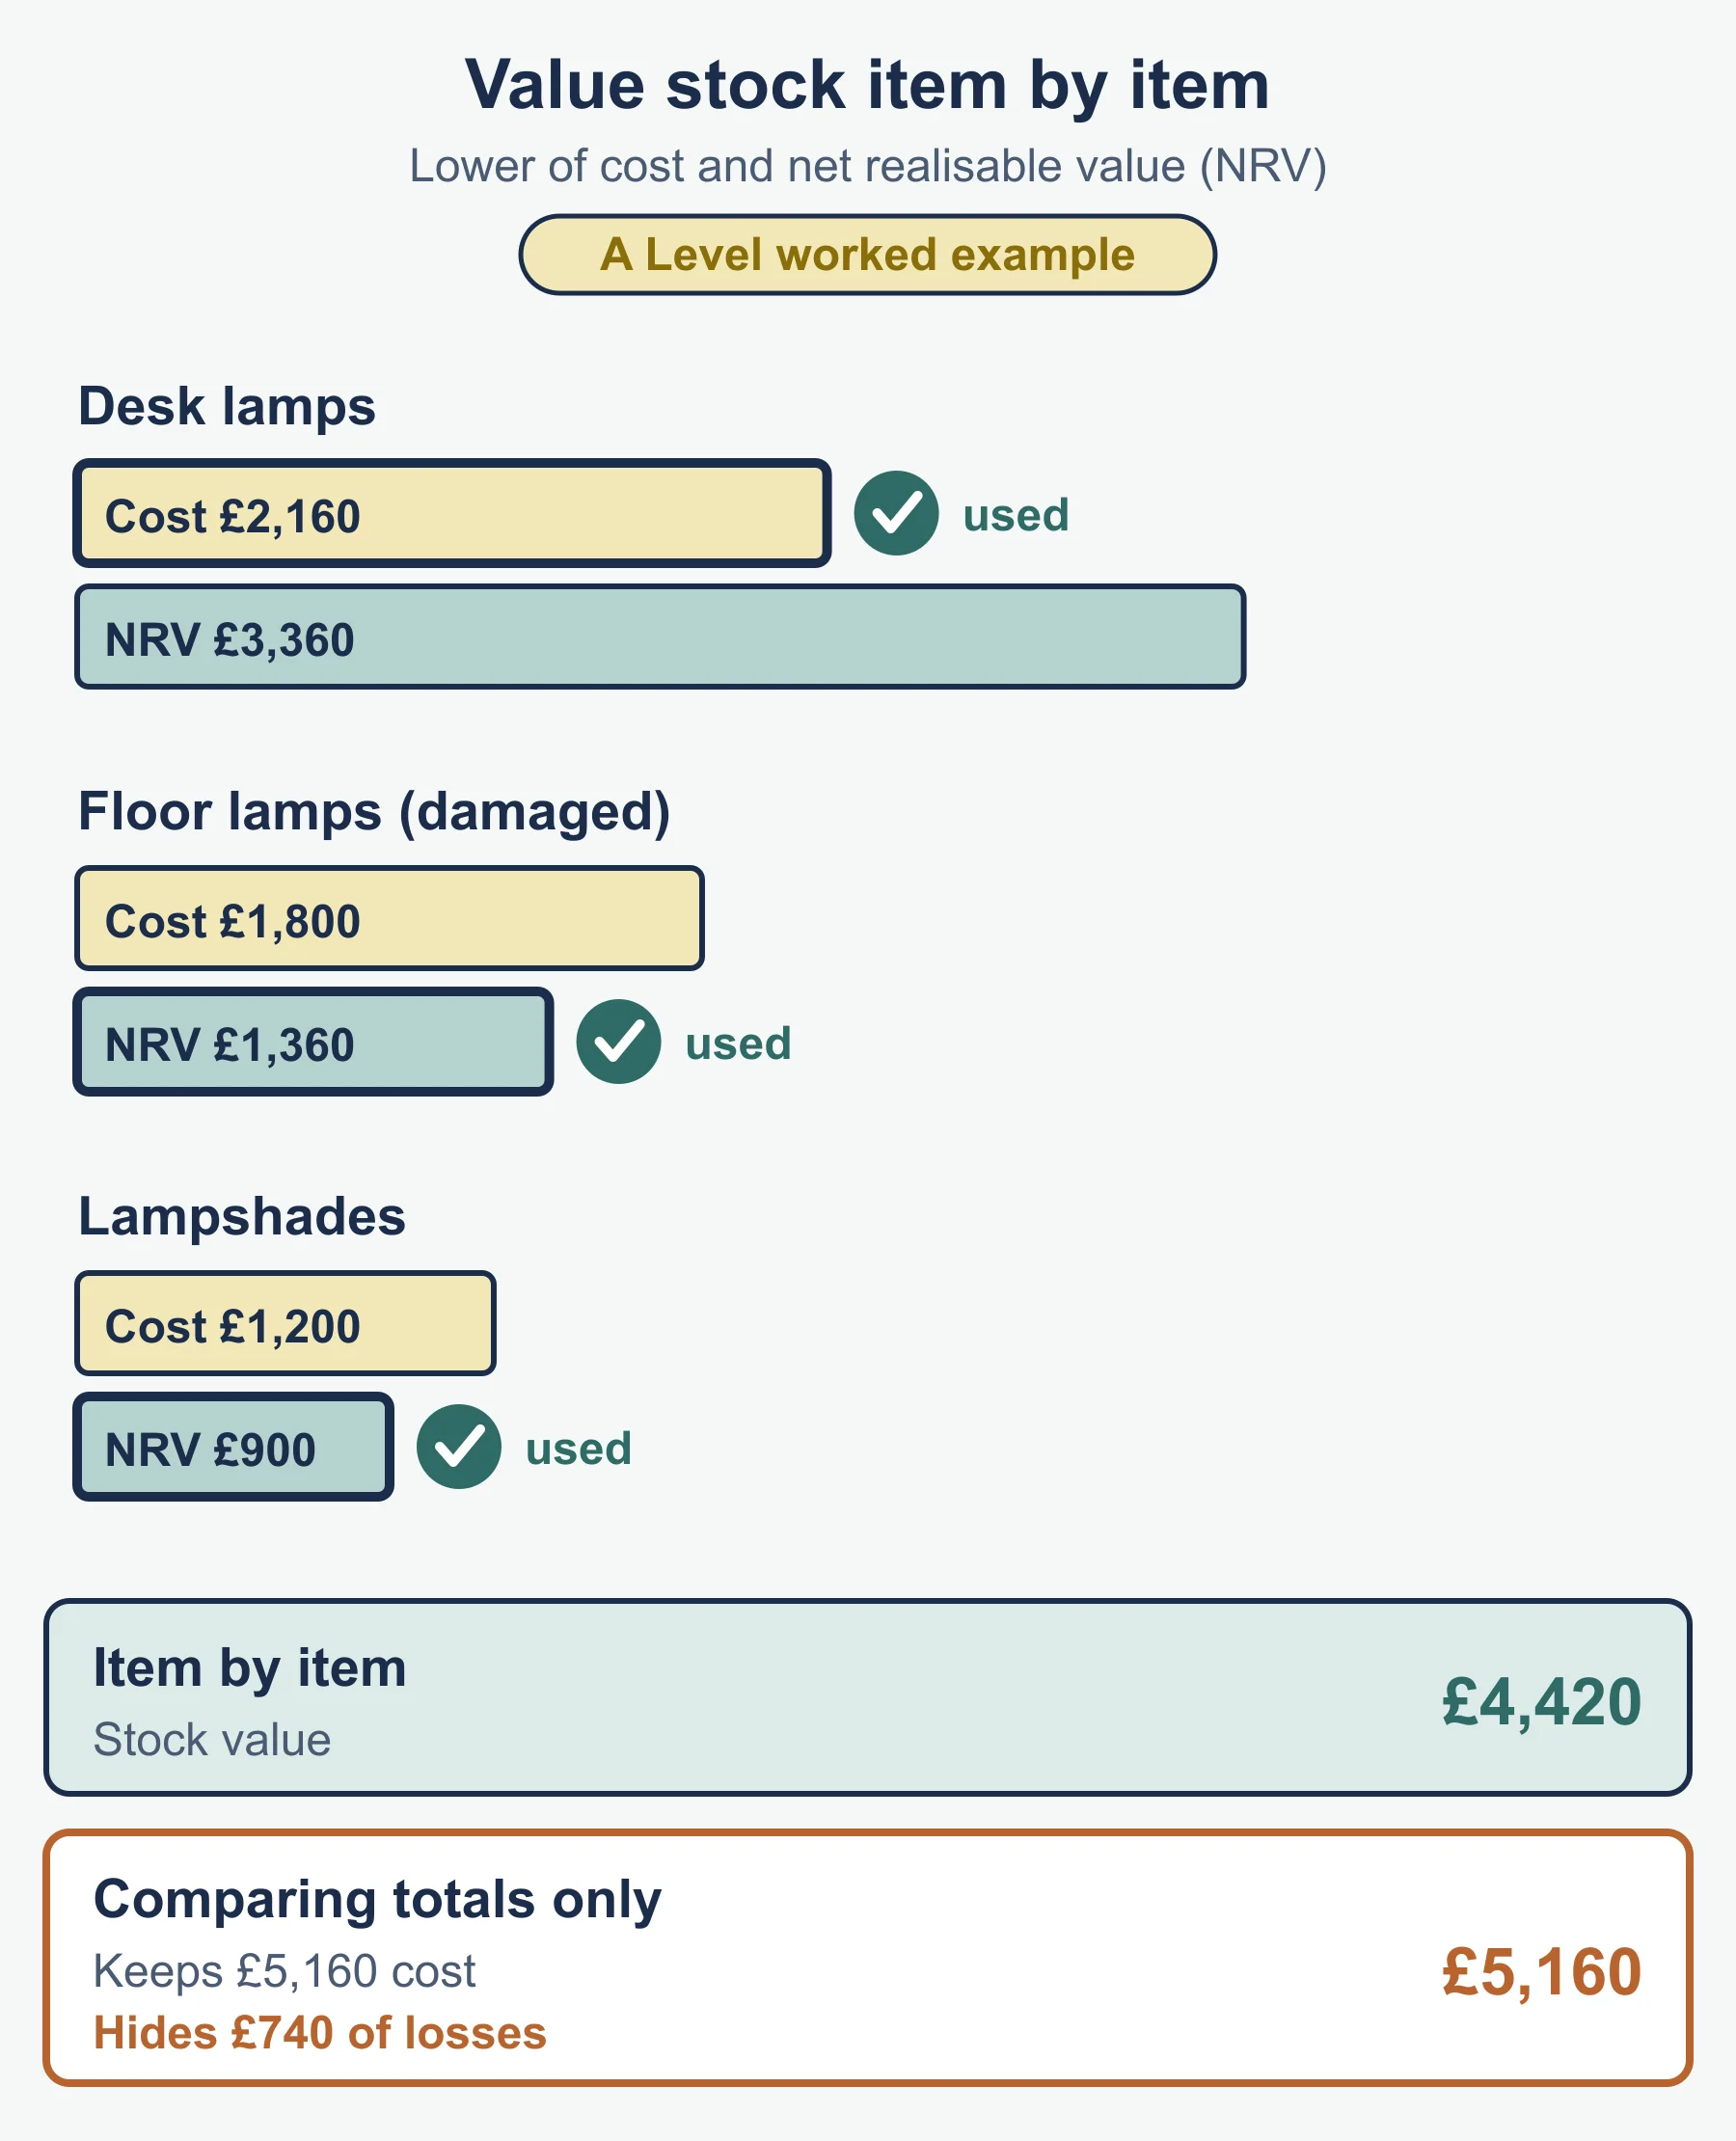
- Add the item values. Never compare the two grand totals.
- If NRV was lower, the write-down is units × (cost − NRV).
Why: prudence says expected losses are recognised now. Realisation and historic cost say expected profits are not recognised until the goods are sold, so inventory is never shown above cost.
Worked reminders
Cost is lower. Roddick Rugs holds 40 rugs that cost 18.50 each. They sell for 29.00 each with 3.50 commission. NRV = 29.00 − 3.50 = 25.50. Cost is lower, so value = 40 × 18.50 = 740.
NRV is lower. Roddick Rugs also holds 60 lamps that cost 34 each. After a repair costing 6 per lamp they sell for 45, and delivery costs 7.
NRV per lamp   45 − 6 − 7           = 32
Lower          32 (NRV, not 34)
Value          60 × 32              = 1,920
Write-down     60 × (34 − 32)       =   120
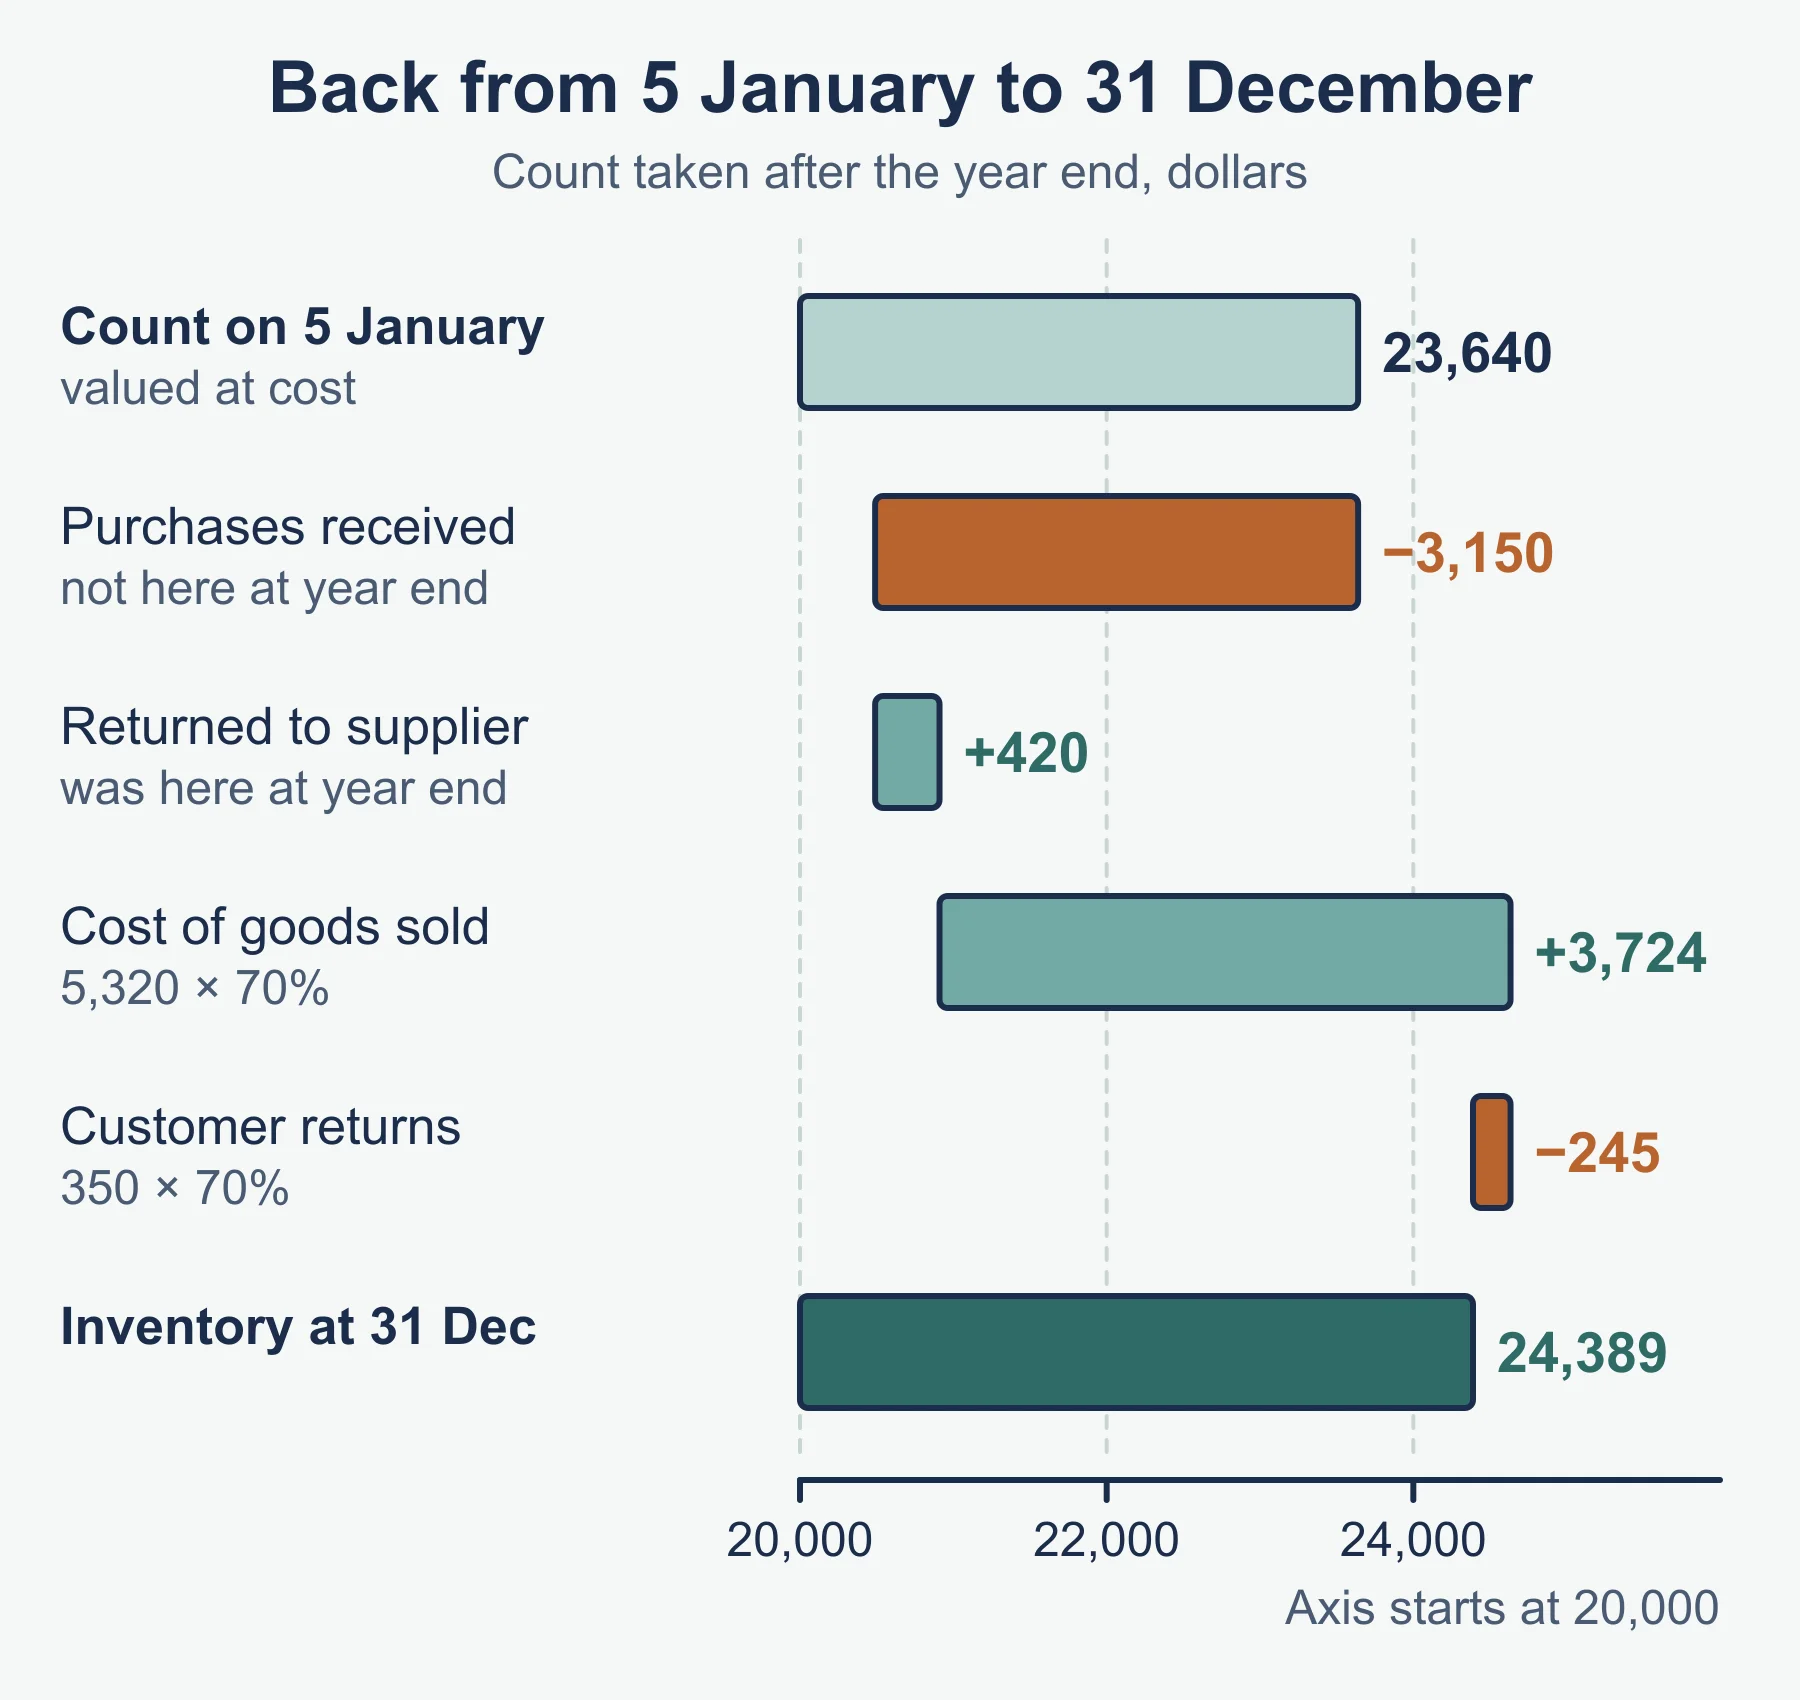
Method: adjusting a count taken on another date
| Count taken | Start with | Purchases since | Cost of goods sold since |
|---|---|---|---|
| After the year end | counted value | subtract | add |
| Before the year end | counted value | add | subtract |
Convert sales to cost first: cost = selling price ÷ (1 + mark-up), or cost = selling price × (1 − margin). Goods returned by customers change the adjustment in the opposite direction to sales. Goods returned to suppliers change it in the opposite direction to purchases.
Count after year end. Counted at cost on 4 January: 12,300. Purchases 1–4 January: 2,150. Sales in that period: 3,900 at a 20% margin.
Cost of goods sold    3,900 × 80%   = 3,120
Inventory at 31 December  12,300 − 2,150 + 3,120 = 13,270
Count before year end. Counted at cost on 28 December: 9,860. Purchases 28–31 December: 1,740. Sales in that period: 2,800 at a 25% mark-up.
Cost of goods sold    2,800 ÷ 1.25  = 2,240
Inventory at 31 December  9,860 + 1,740 − 2,240 = 9,360
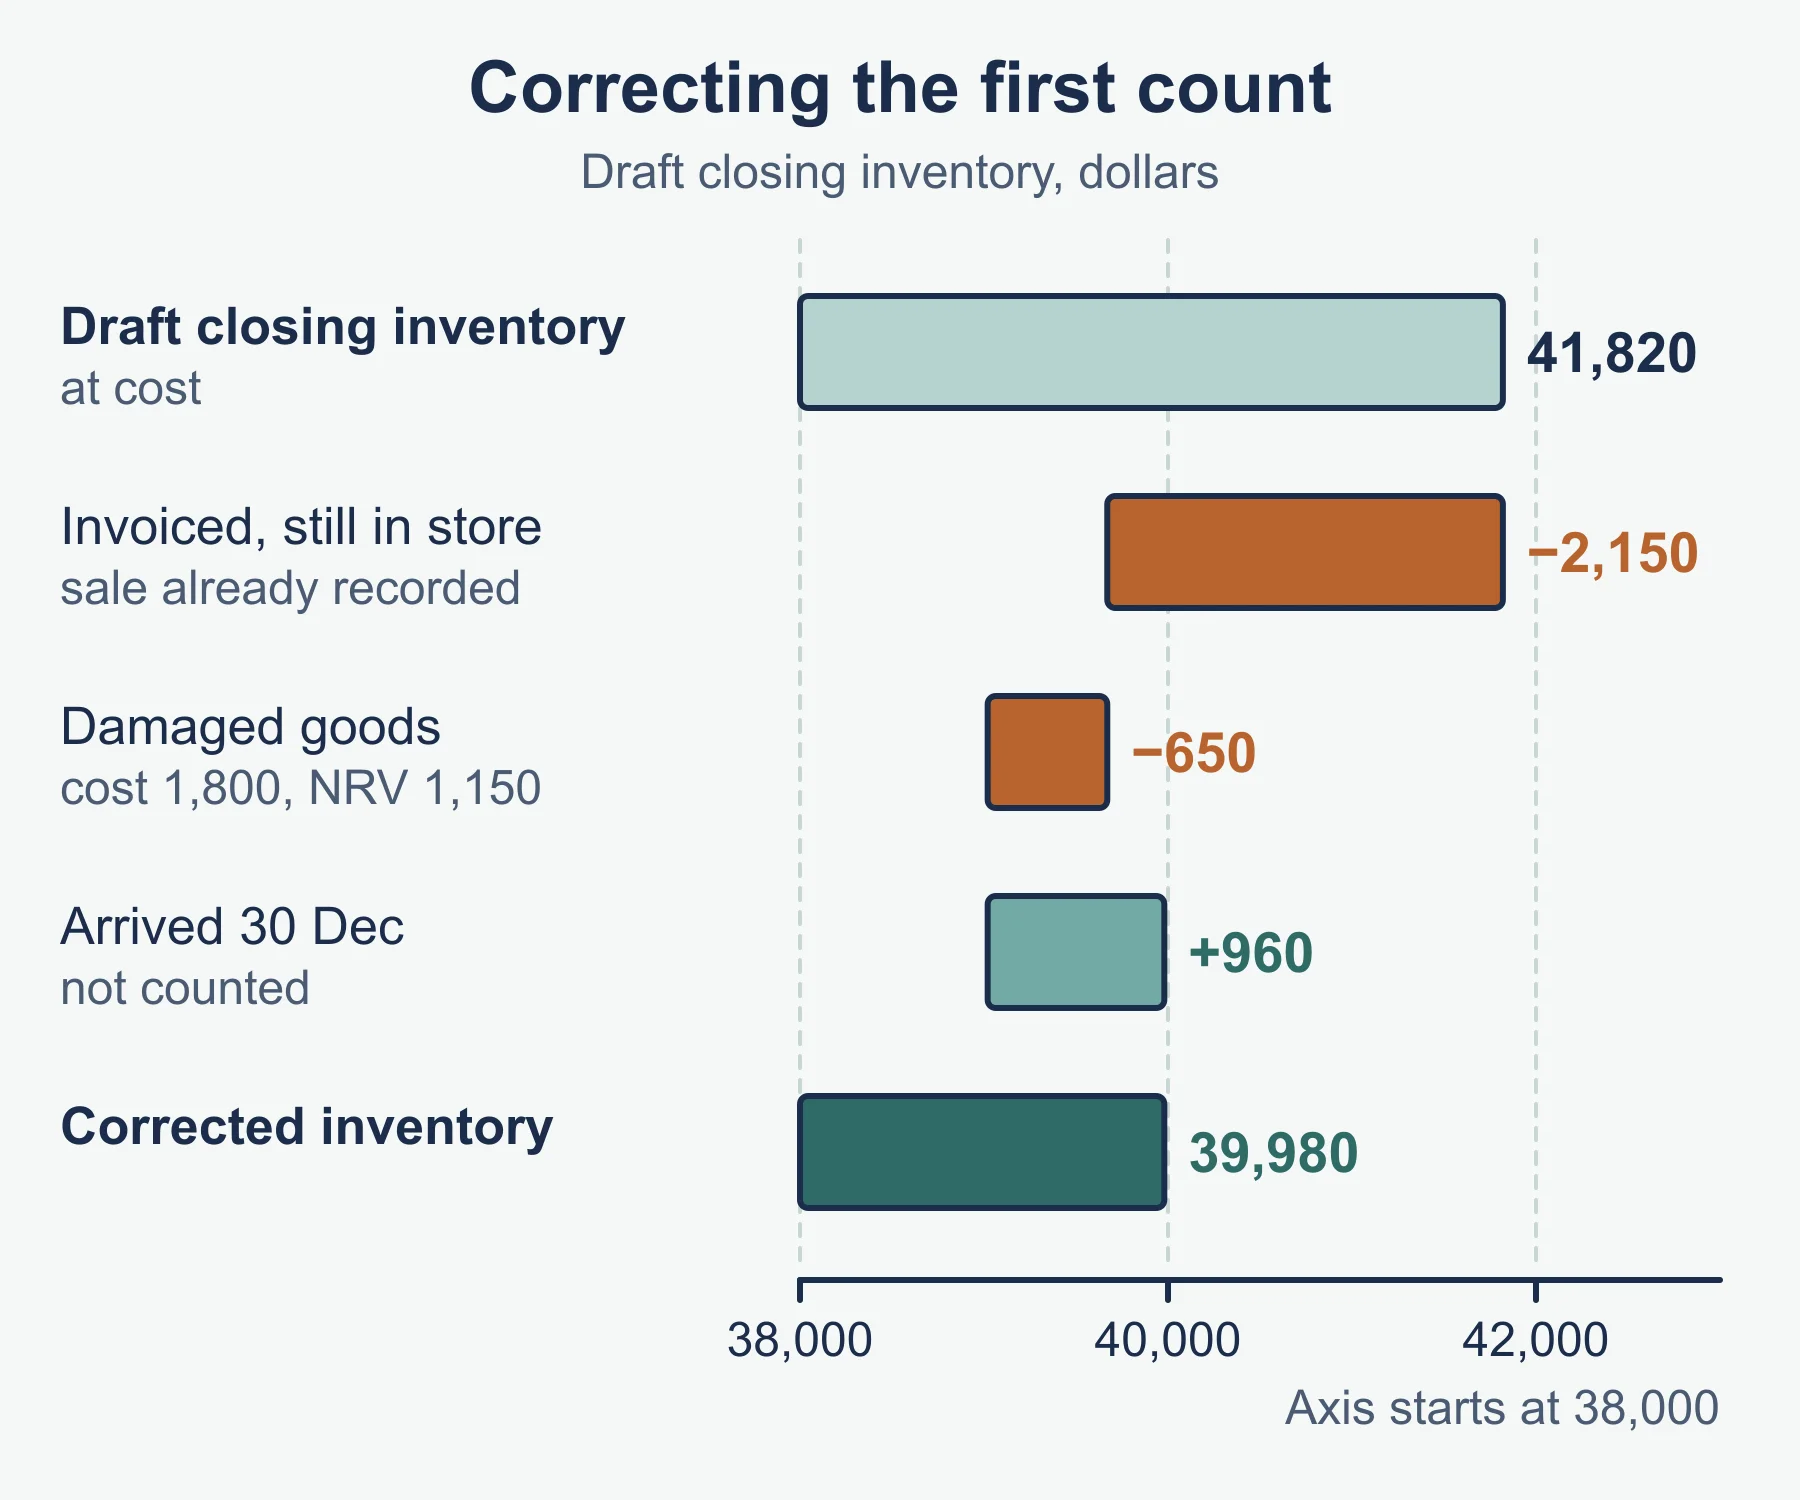
Other corrections to a draft count. Goods already sold and invoiced: deduct. Goods owned but not counted: add. Counted twice: deduct one count. Damaged or obsolete goods: reduce to NRV if that is lower than cost.
Method: effect of an incorrect valuation
Cost of sales = opening inventory + purchases − closing inventory| If closing inventory is | Cost of sales | Gross profit | Profit for the year | Equity | Inventory asset |
|---|---|---|---|---|---|
| Overstated | Understated | Overstated | Overstated | Overstated | Overstated |
| Understated | Overstated | Understated | Understated | Understated | Understated |
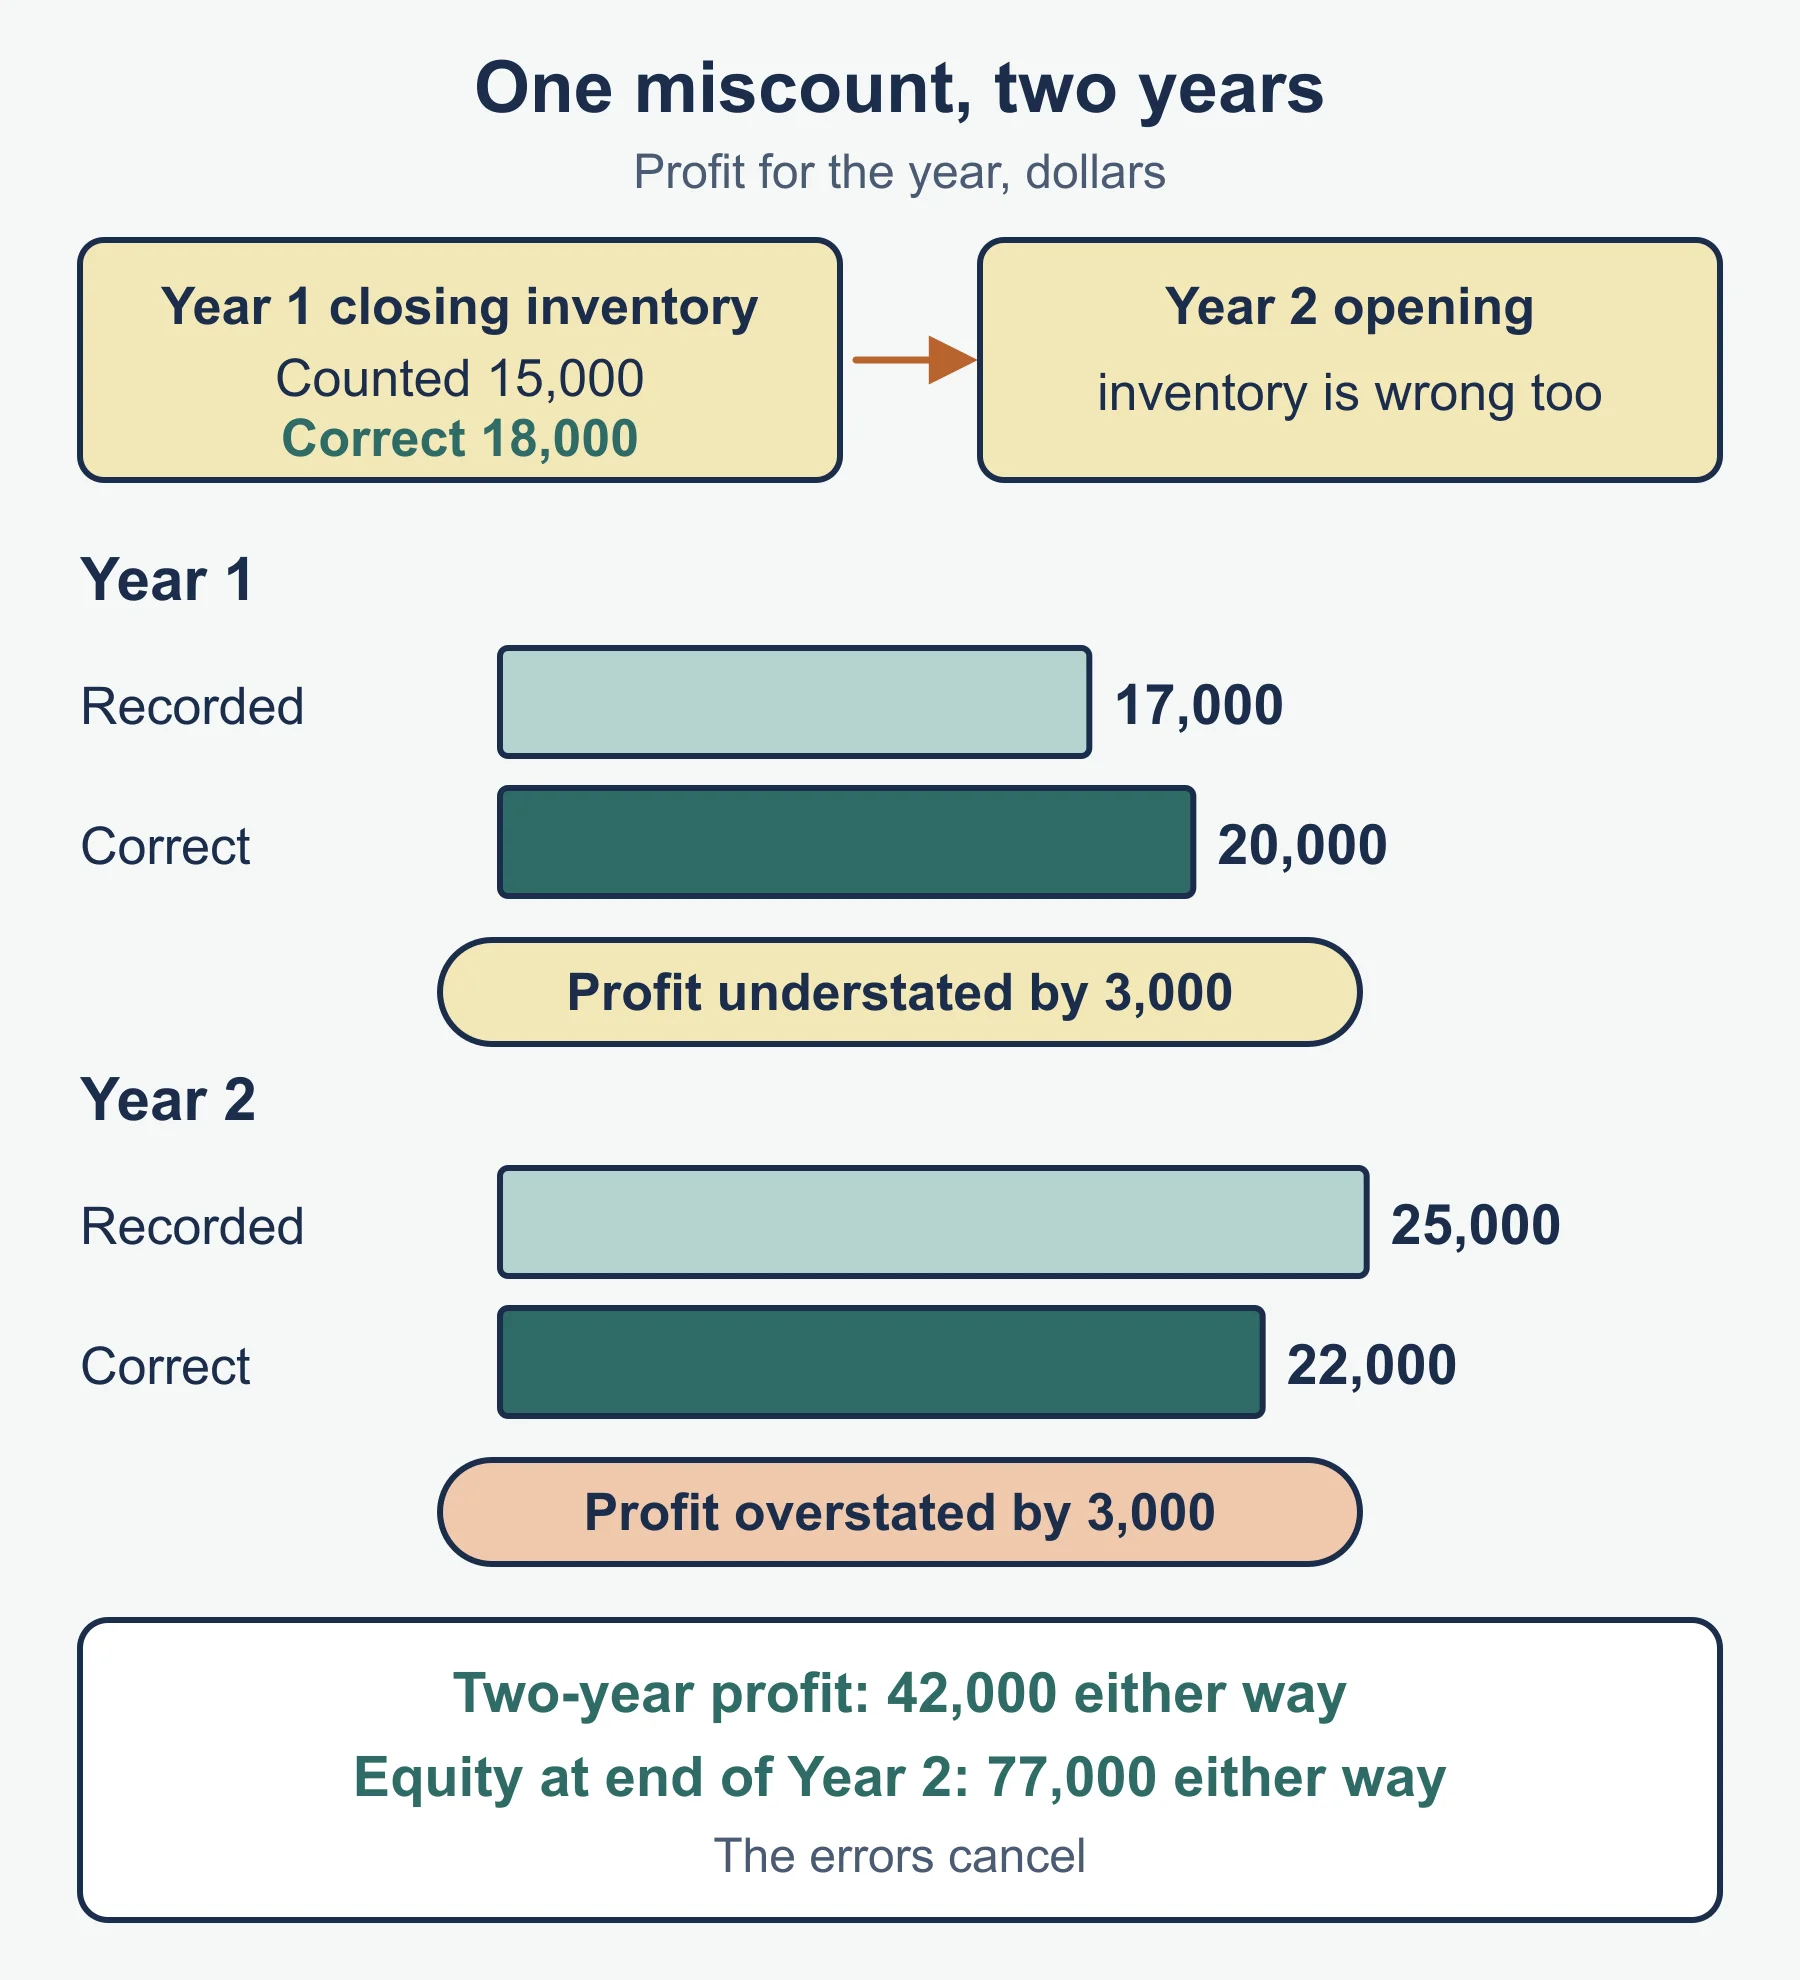
Next year: the wrong closing figure is the next year’s opening inventory, so next year’s cost of sales is wrong by the same amount the other way, and gross profit and profit for the year move in the opposite direction to the first year. Equity at the end of the second year is correct, provided the second closing inventory is right. Profit over the two years combined is unchanged.
Worked reminder. Closing inventory is overstated by 800. Gross profit shown is 25,800 when it should be 25,000, and profit for the year shown is 12,800 when it should be 12,000. If the opening inventory of the next year is also 800 too high, that year’s gross profit is 800 too low.
Corrected profit. Corrected profit = draft profit ± the change in closing inventory (an increase in closing inventory increases profit).
Must-know distinctions
- Cost versus NRV: the lower is used, item by item, not in total.
- NRV versus selling price: NRV is selling price after deducting the costs still to pay.
- Mark-up versus margin: mark-up is on cost, margin is on selling price.
- Closing versus opening inventory: an error in closing inventory is in the following year’s opening inventory.
- Profit versus equity: both are wrong at the end of the first year, but at the end of the second year only the profits are wrong, not equity.
Quick self-test
- Define net realisable value.
- A unit cost 36. It will sell for 41 with 8 of selling costs. State its value per unit.
- 25 units cost 12.40 each and have an NRV of 10.60 each. Calculate their value.
- Item A: 30 units, cost 8, NRV 9. Item B: 20 units, cost 15, NRV 11. Calculate the inventory value item by item.
- Closing inventory is understated by 1,500. Give the effect on this year’s profit and the effect on next year’s gross profit.
- A count on 2 January valued inventory at 15,800. Purchases since year end were 2,600 and the cost of goods sold since year end was 2,100. Calculate inventory at 31 December.
- Sales of 4,500 at selling price. Calculate their cost with (a) a 50% mark-up and (b) a 40% margin.
- Draft profit is 14,400. Closing inventory was recorded as 8,100 and should be 9,300. State the corrected profit.
- Why is inventory not valued at expected selling price?
- A closing inventory error is made in Year 1 only. State the effect on the total profit of the two years combined.
Answers
- Expected selling price less the costs still to be paid before and when the goods are sold.
- NRV = 41 − 8 = 33, which is lower than cost, so 33 per unit.
- 25 × 10.60 = 265 (NRV is lower).
- A: cost is lower, 30 × 8 = 240. B: NRV is lower, 20 × 11 = 220. Total 460 (comparing totals would wrongly give 490).
- Profit for the year is understated by 1,500. Next year’s gross profit is overstated by 1,500.
- 15,800 − 2,600 + 2,100 = 15,300.
- (a) 4,500 ÷ 1.5 = 3,000; (b) 4,500 × 60% = 2,700.
- 14,400 + (9,300 − 8,100) = 14,400 + 1,200 = 15,600.
- A profit is recognised only when goods are sold (realisation), and assets are recorded at historic cost, not at an expected price. Valuing at cost or NRV avoids overstating profit.
- No effect: the first year’s error is reversed in the second year.
Where marks are usually lost
- Comparing the grand totals of cost and NRV instead of choosing the lower figure for each item.
- Taking selling costs off cost instead of off the selling price.
- Forgetting repair costs when the selling price is the price after repair.
- Valuing at NRV when NRV is higher than cost.
- Adding purchases to a count taken after the year end (they should be subtracted), or the reverse.
- Using sales at selling price in a count adjustment without converting to cost.
- Applying mark-up to selling price, or margin to cost.
- Giving the effect for the first year only and omitting the next year’s opposite effect.
- Writing “overstated” or “understated” without the amount.
- Describing equity as wrong at the end of the second year when it has corrected itself.
Frequently asked questions
What is net realisable value? Net realisable value is the expected selling price less the costs still to be paid before and when the goods are sold, such as repair, repackaging, commission or delivery. Inventory is valued at the lower of cost and net realisable value.
How do you convert sales to cost when adjusting an inventory count? Use cost = selling price ÷ (1 + mark-up), or cost = selling price × (1 − margin). Sales must be converted to cost before they are added to or deducted from a count valued at cost.
How does an incorrect closing inventory affect the next year? The wrong closing figure becomes the next year’s opening inventory, so next year’s cost of sales is wrong by the same amount the other way, and next year’s profit moves in the opposite direction.
Why is inventory not valued at its selling price? Prudence means expected losses are recognised now, while realisation and historic cost mean expected profits are not recognised until the goods are sold. Valuing at the lower of cost and net realisable value applies both ideas.
Official syllabus
Cambridge IGCSE Accounting 0452 syllabus for 2027, 2028 and 2029 (version 1), section 4.5 Valuation of inventory, published by Cambridge International Education (September 2024).
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Revision notes
IGCSE Accounting: Analysis and Interpretation — Revision Notes
Quick recall for Cambridge IGCSE Accounting 0452 Topic 6: ten ratios, reading them, profit versus cash, comparing businesses, users and statement limits.
Accounting · Cambridge · IGCSE, O Level
Revise topic -
Study guides
IGCSE Accounting: Accounting Procedures (Cambridge 0452)
Cambridge IGCSE Accounting 0452 Topic 4 guide: capital and revenue items, depreciation and disposals, accruals, irrecoverable debts and inventory valuation.
Accounting · Cambridge · IGCSE, O Level
Read guide -
Study guides
IGCSE Accounting: Capital and revenue items, depreciation and disposals (Cambridge 0452)
Study guide to capital and revenue items, depreciation methods, and ledger accounts for disposals in Cambridge IGCSE Accounting 0452 (2027-2029).
Accounting · Cambridge · IGCSE, O Level
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Accounting IGCSE, O LEVELS?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Accounting classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Accounting teachers at Marlbridge

