
Study Guides
OxfordAQA A-Level Business: The nature and purpose of business and Types of business ownership (9625/9725)
Study guide to OxfordAQA International AS Business 3.1.1.1 and 3.1.1.2: entrepreneurs, objectives, plans, ownership, shareholders and stakeholders.
- Subject
- Business
- Level
- AS LEVEL
- Topic
- What is business?
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to OxfordAQA A Level Business (9625, 9725), 9625: first teaching September 2018 (current cohorts). 9725: first teaching September 2026 (AS) / September 2027 (A2), the successor specification.. Official specification .
Syllabus page (what it covers and how it is assessed): OxfordAQA A Level Business.
Found an error? Report a correction.
Need help with this topic? Request a free trial class for A Level Business (9625 / 9725).
This guide covers sections 3.1.1.1 The nature and purpose of business and 3.1.1.2 Types of business ownership of the OxfordAQA International AS and A-level Business specifications: 9625 (AS exams May/June 2019 onwards) and the successor 9725 (AS exams May/June 2027 onwards). Both are International AS content, assessed in Unit 1 (any content from section 3.1 Business and markets). The two specifications word these sections differently, so each point is tagged both, 9625 or 9725. Examples of motivations, challenges, why start-ups fail, and advantages and disadvantages are Marlbridge’s own wording, not lists from either specification.
Links: course hub · printable checklist · revision notes · practice questions · free 10-minute diagnostics. Earlier overview pages on the topic: What is business? study guide, revision notes and practice paper. All businesses here are invented.
What the sections list
| Section | Content points | Spec |
|---|---|---|
| 3.1.1.1 | Key business terms, from inputs to customers and consumers | 9625 |
| 3.1.1.1 | Decision making: basic decision trees, expected value, net gain | 9625 |
| 3.1.1.1 | Entrepreneurs, objectives, business plans (SMART and plan elements 9725) | both |
| 3.1.1.1 | Start-ups, government support, why they fail, impact on society | 9625 |
| 3.1.1.2 | Types of business, choosing and changing form | both (partnerships 9725; co-operatives 9625) |
| 3.1.1.2 | Sectors, family businesses, business population | both |
| 3.1.1.2 | Small business (9725); SMEs against large businesses (9625) | each as tagged |
| 3.1.1.2 | Shareholders: equity, share price, dividends, yield, market capitalisation | both |
| 3.1.1.2 | Stakeholders and the impact of business activity | both (listed in detail in 9725) |
Key business terms (9625)
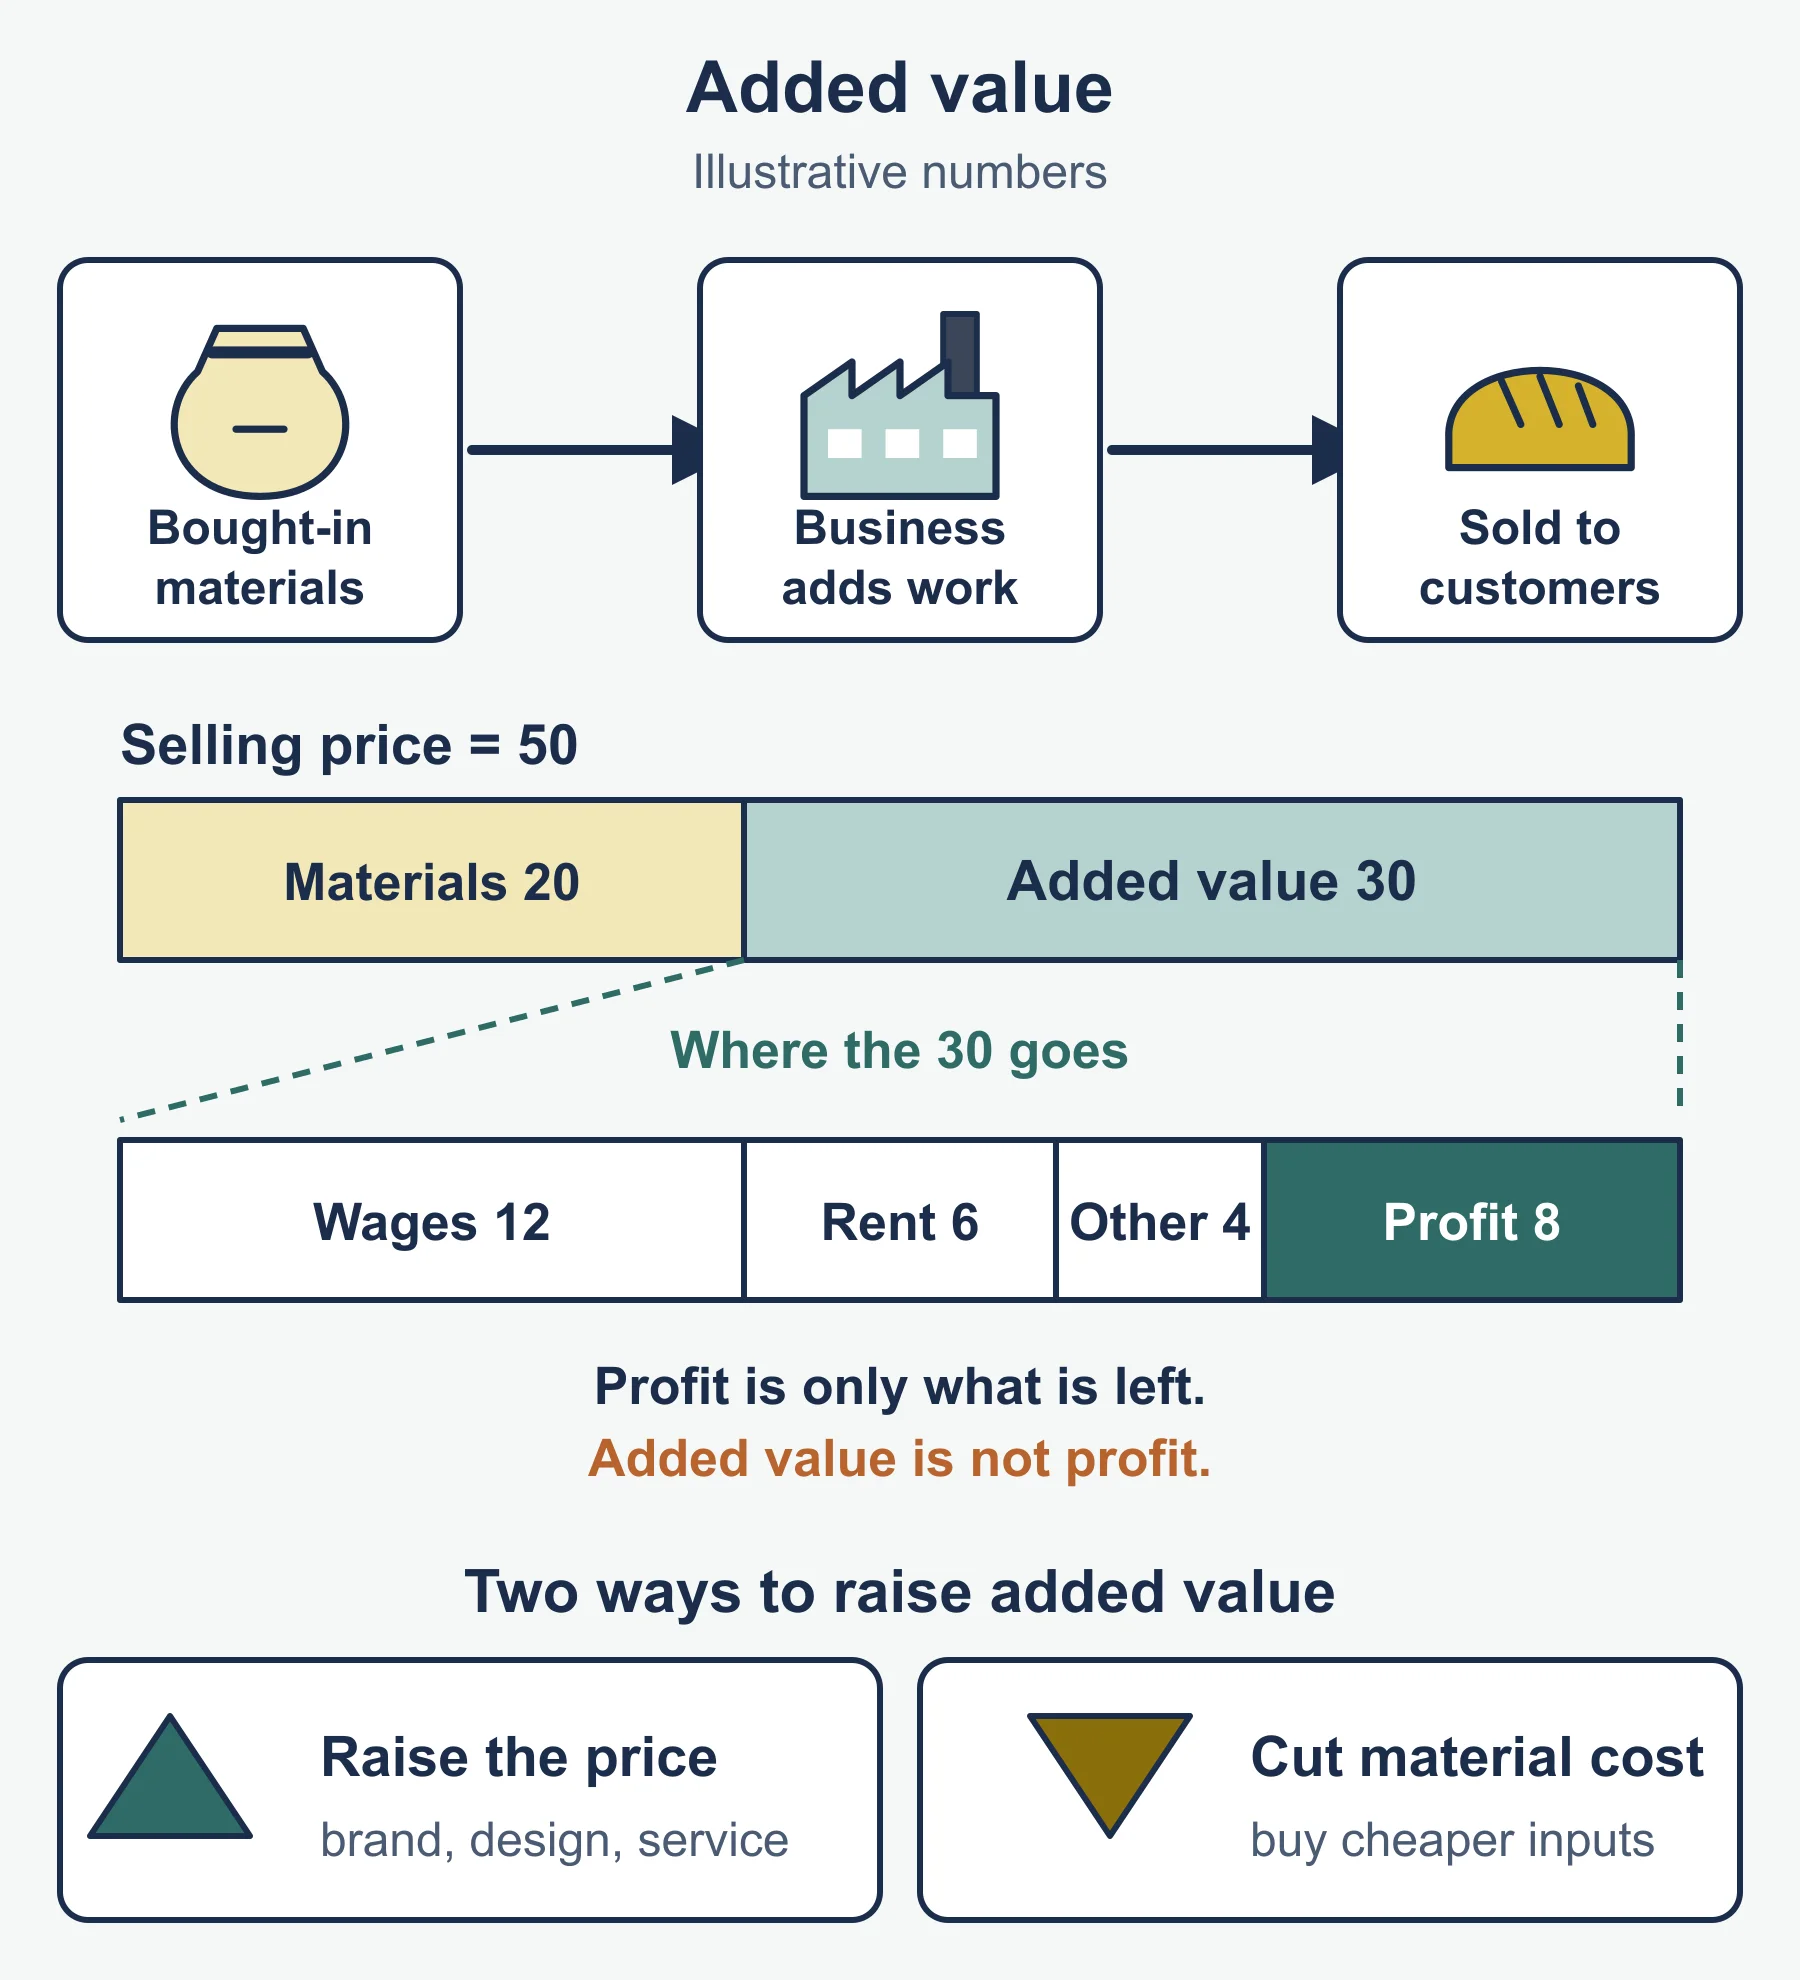
Businesses turn inputs into outputs. The inputs are land, labour, capital and enterprise. The transformation process is whatever the business does to them. Outputs are goods (physical) and services (not physical). Adding value means the output is worth more to customers than the cost of the inputs used.
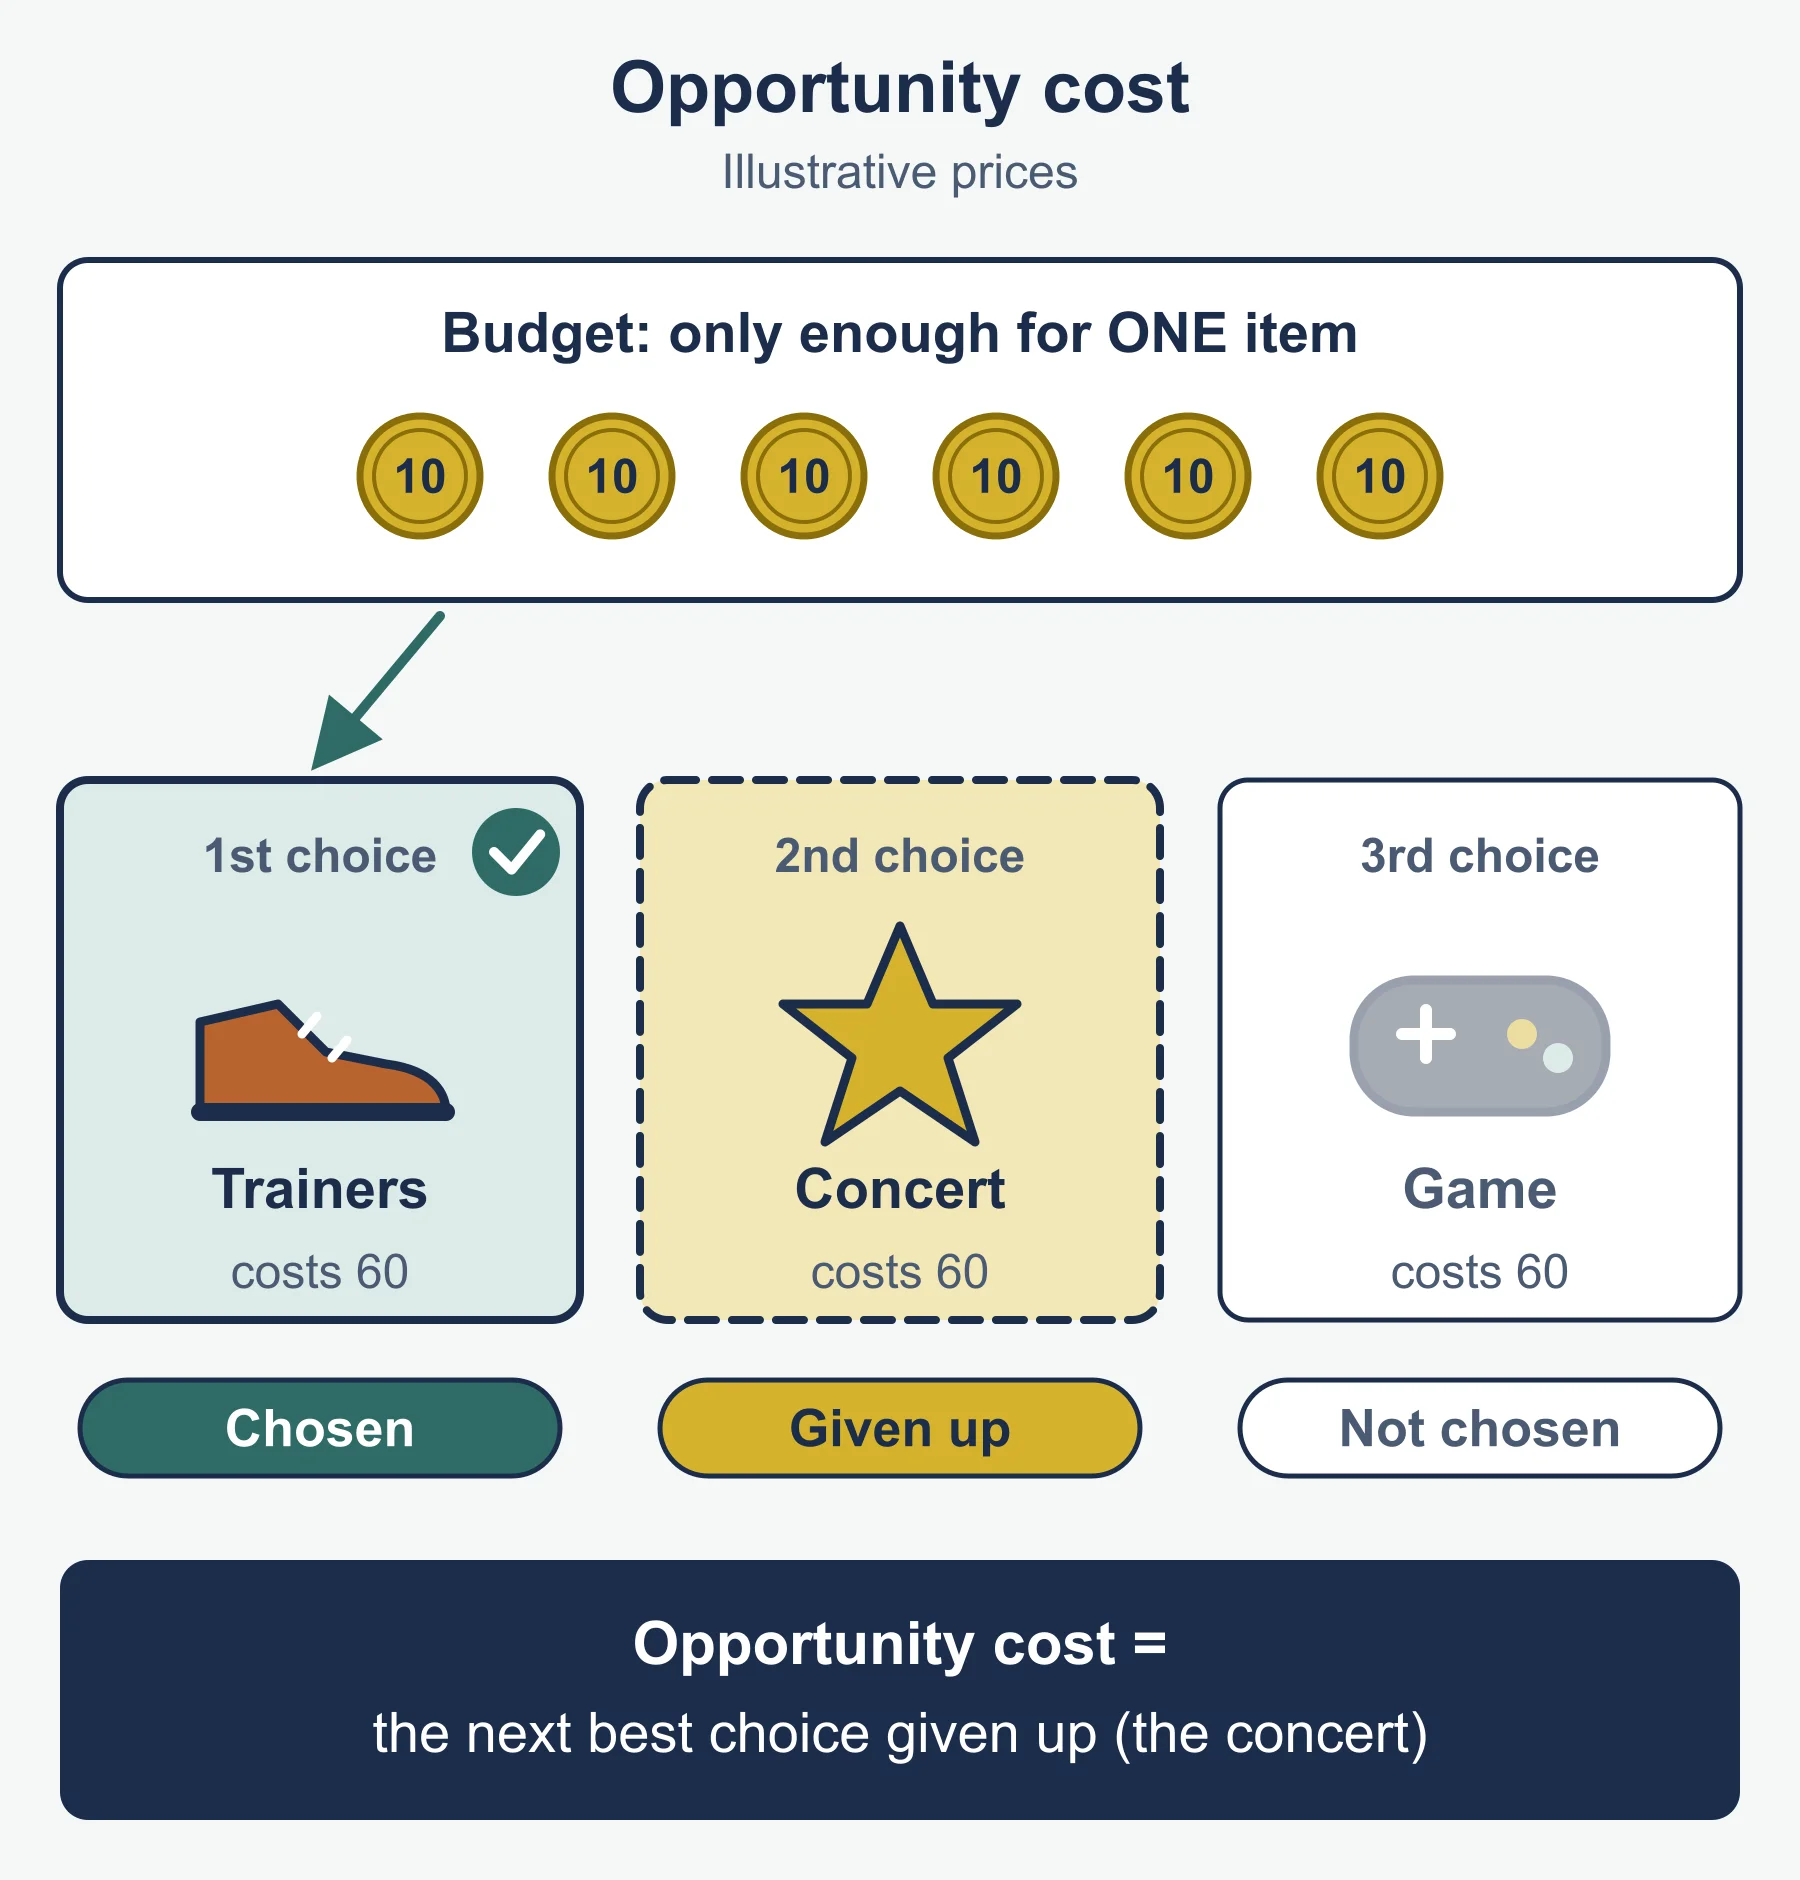
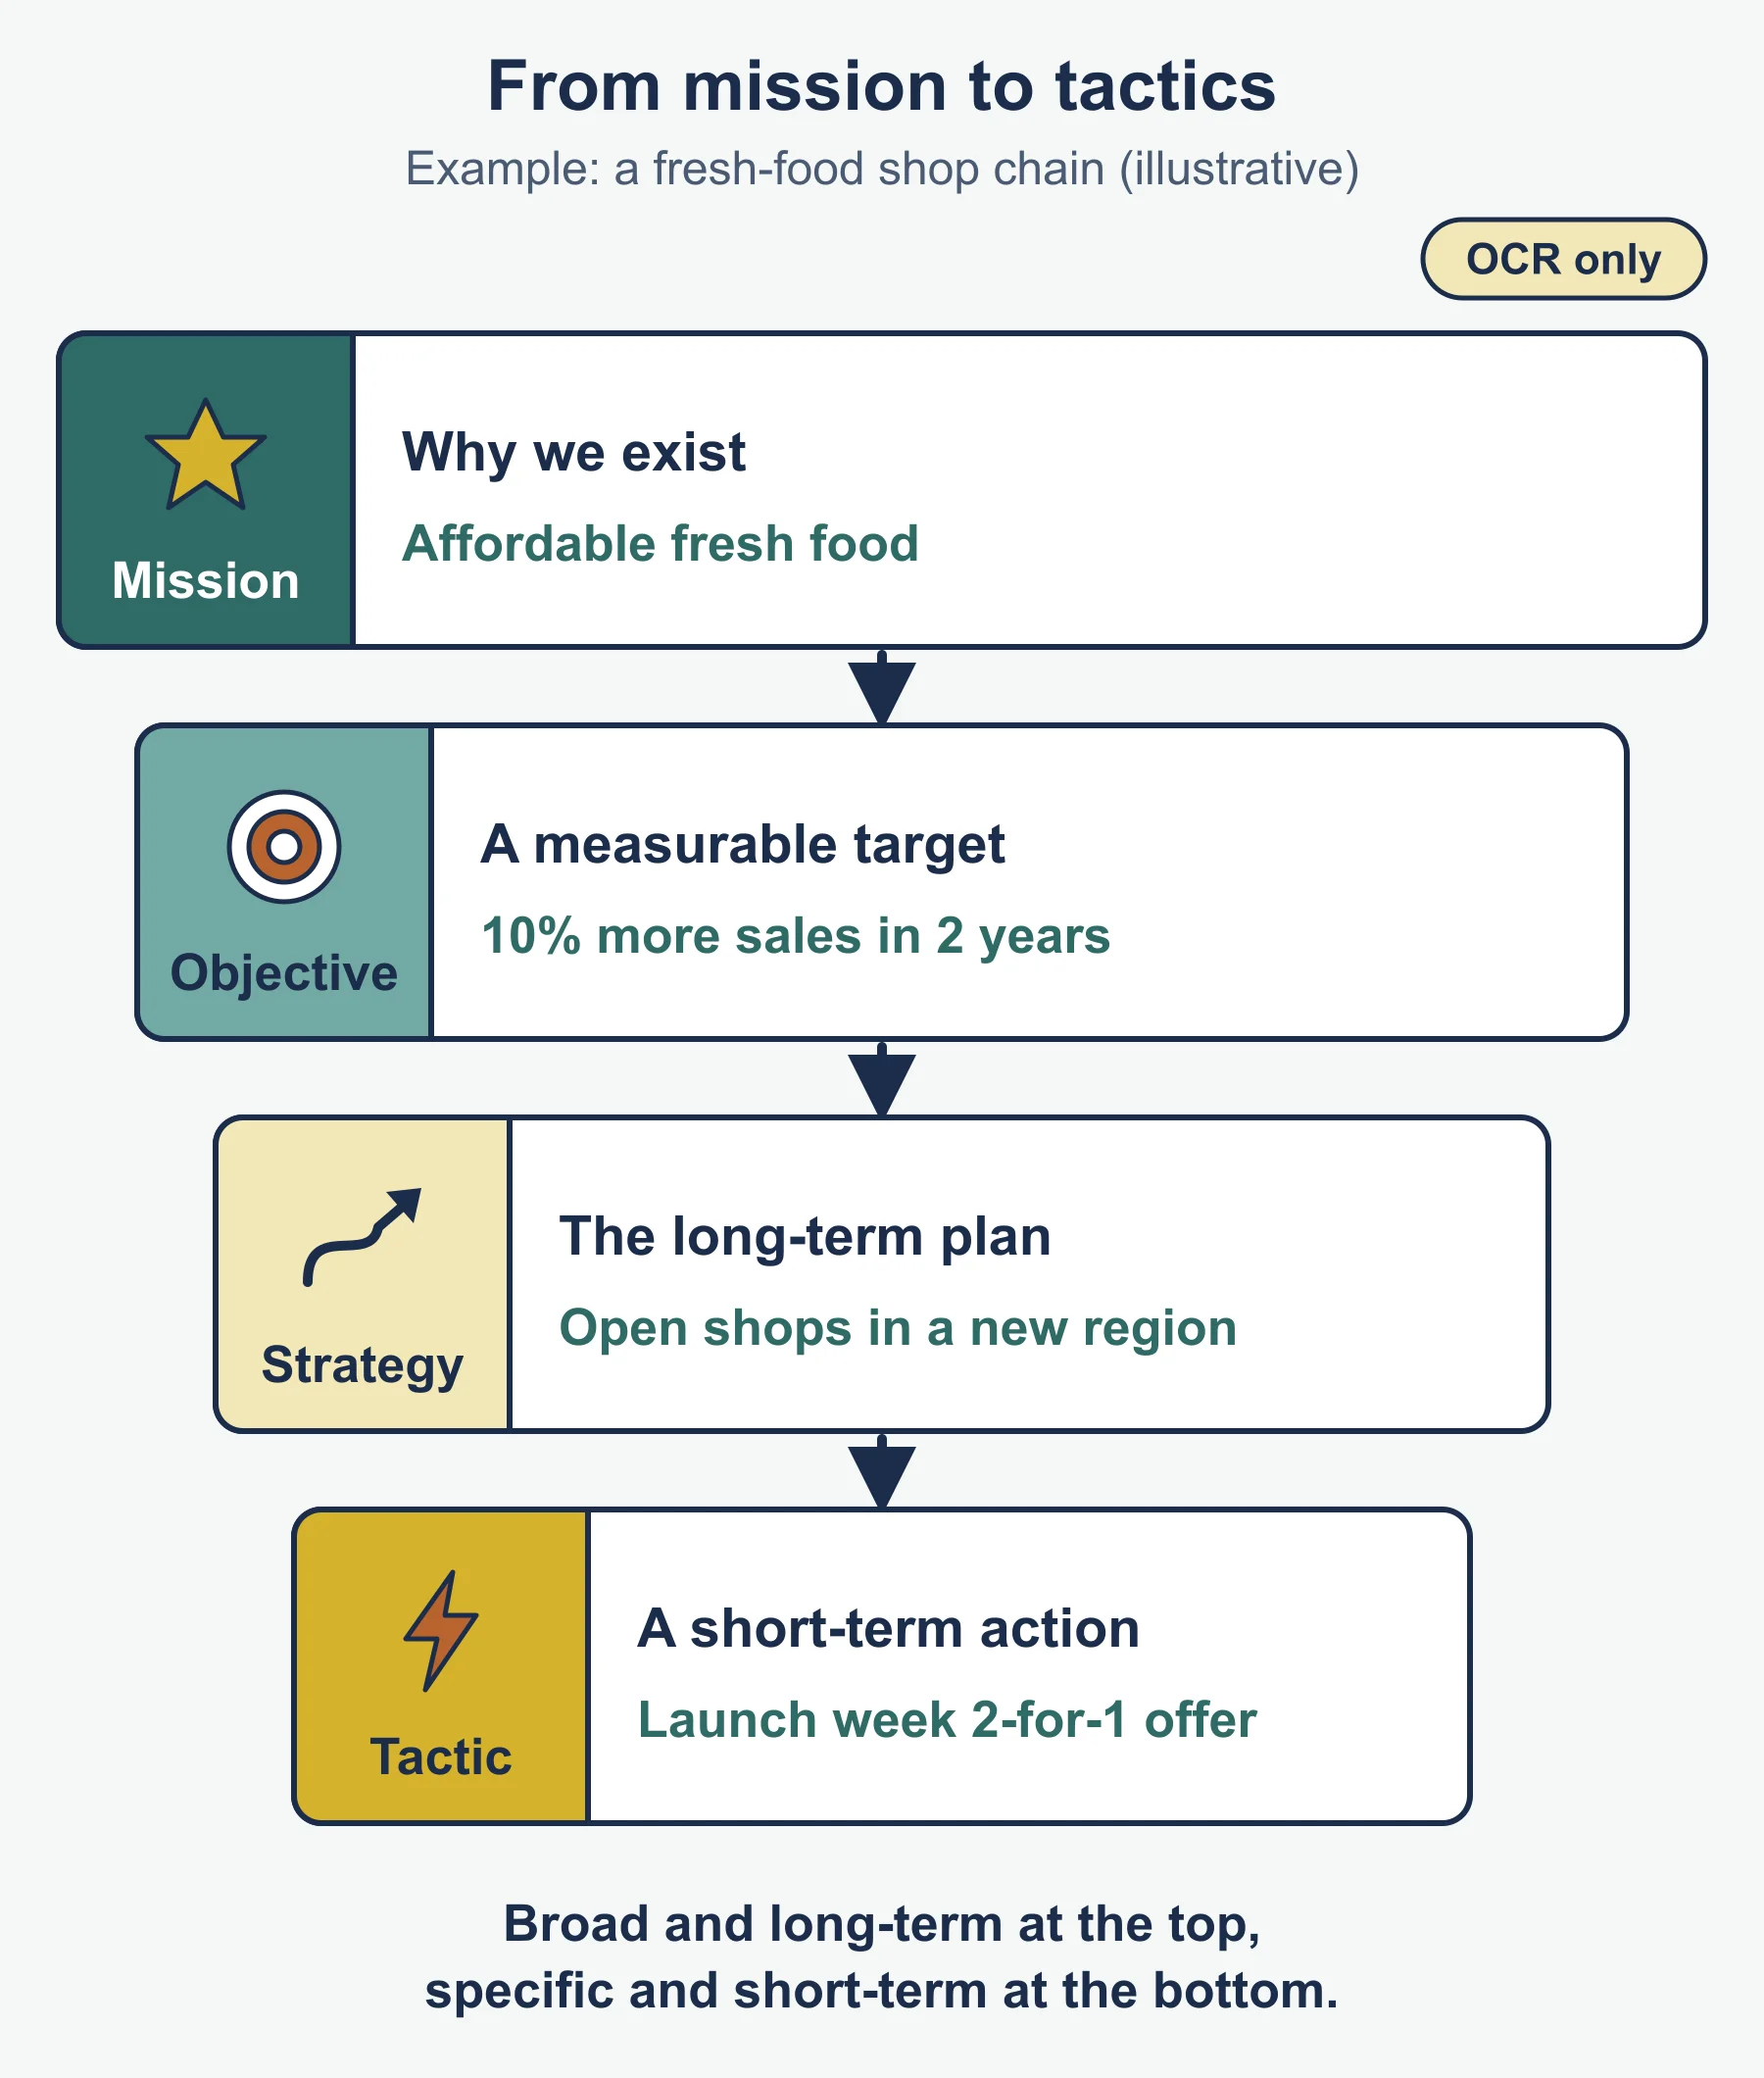
Strategy is the long-term plan to reach objectives. Tactics are the short-term actions that carry it out. Profit is revenue minus costs. Opportunity cost is the value of the best alternative forgone when you choose. Efficiency means producing more from unchanged inputs, or the same from less. Competitiveness is how well a business does against rivals, for example on price, quality or service. Risk is the chance that an outcome is worse than planned.
Owners put in capital and take the risk. Managers run the business day to day, so in a large firm the two groups are different people. Managers organise the business functions (for example marketing, operations, human resources and finance), set targets and monitor results using key performance indicators (KPIs), which are measures such as sales growth or customer complaints. Customers buy from the business. Consumers use the product and may be someone else, such as a child. Ethical influences are beliefs about right and wrong that shape a decision even when a cheaper option exists.
Entrepreneurs (both)
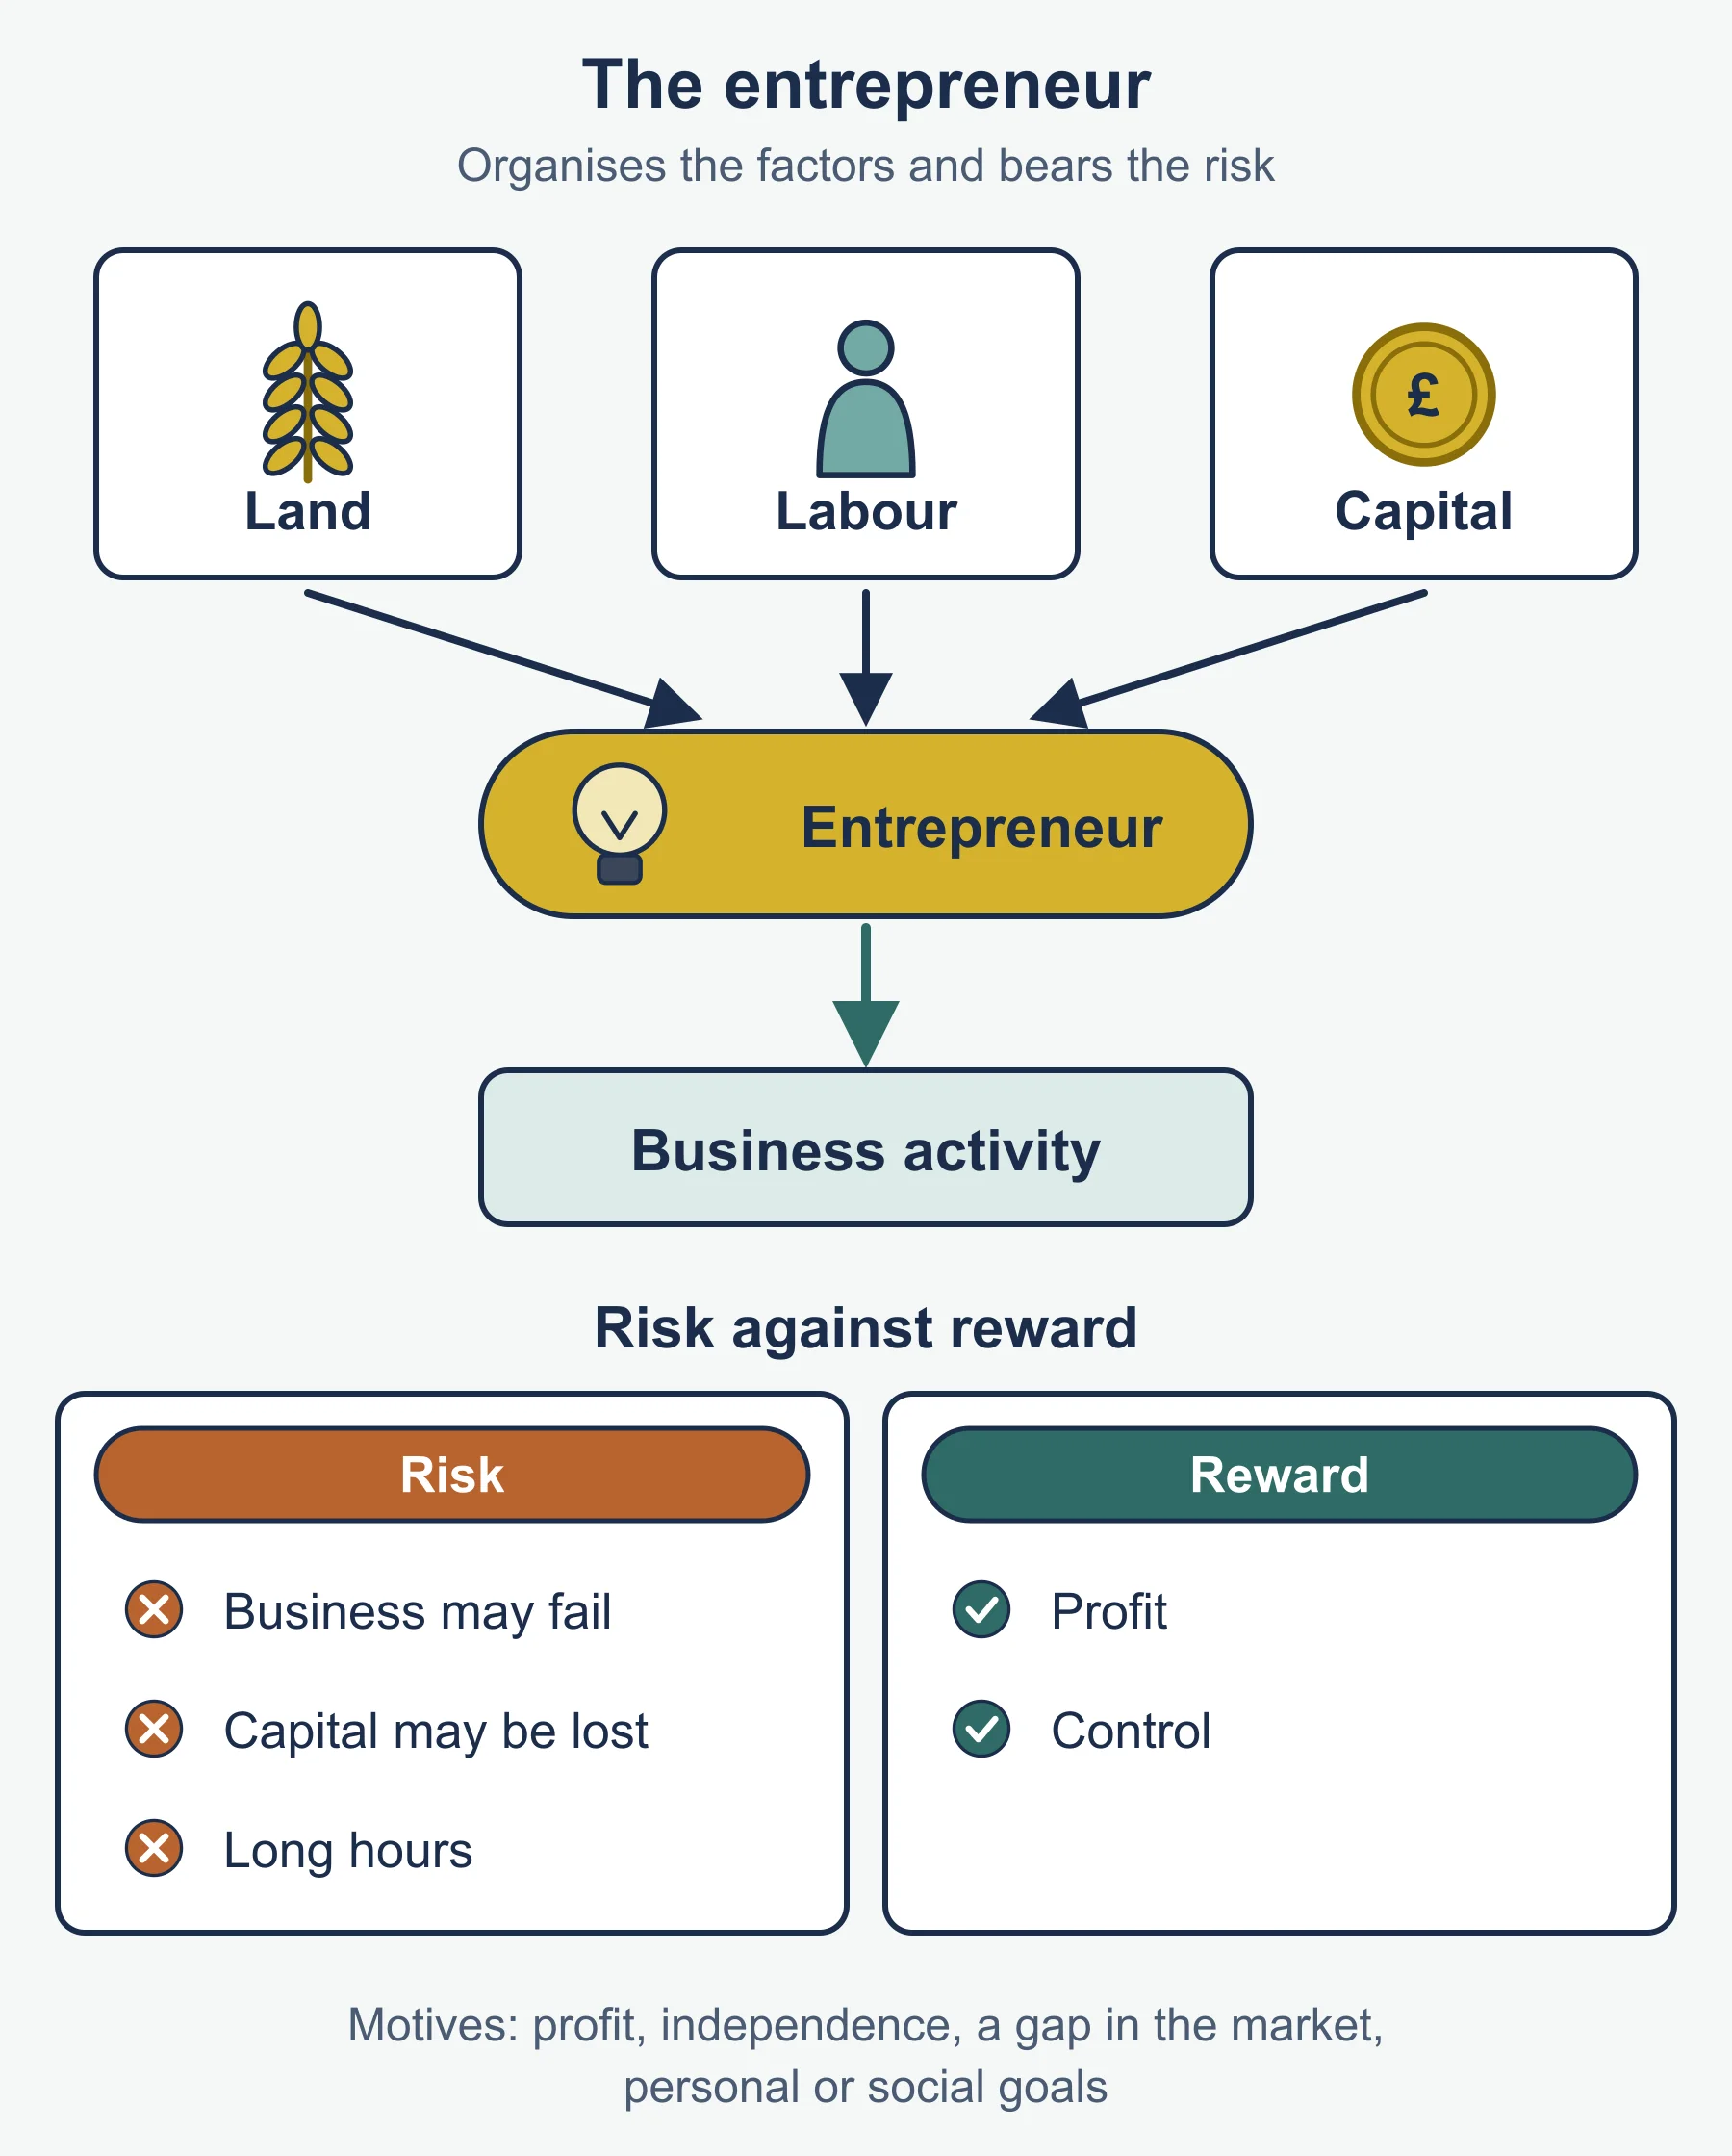
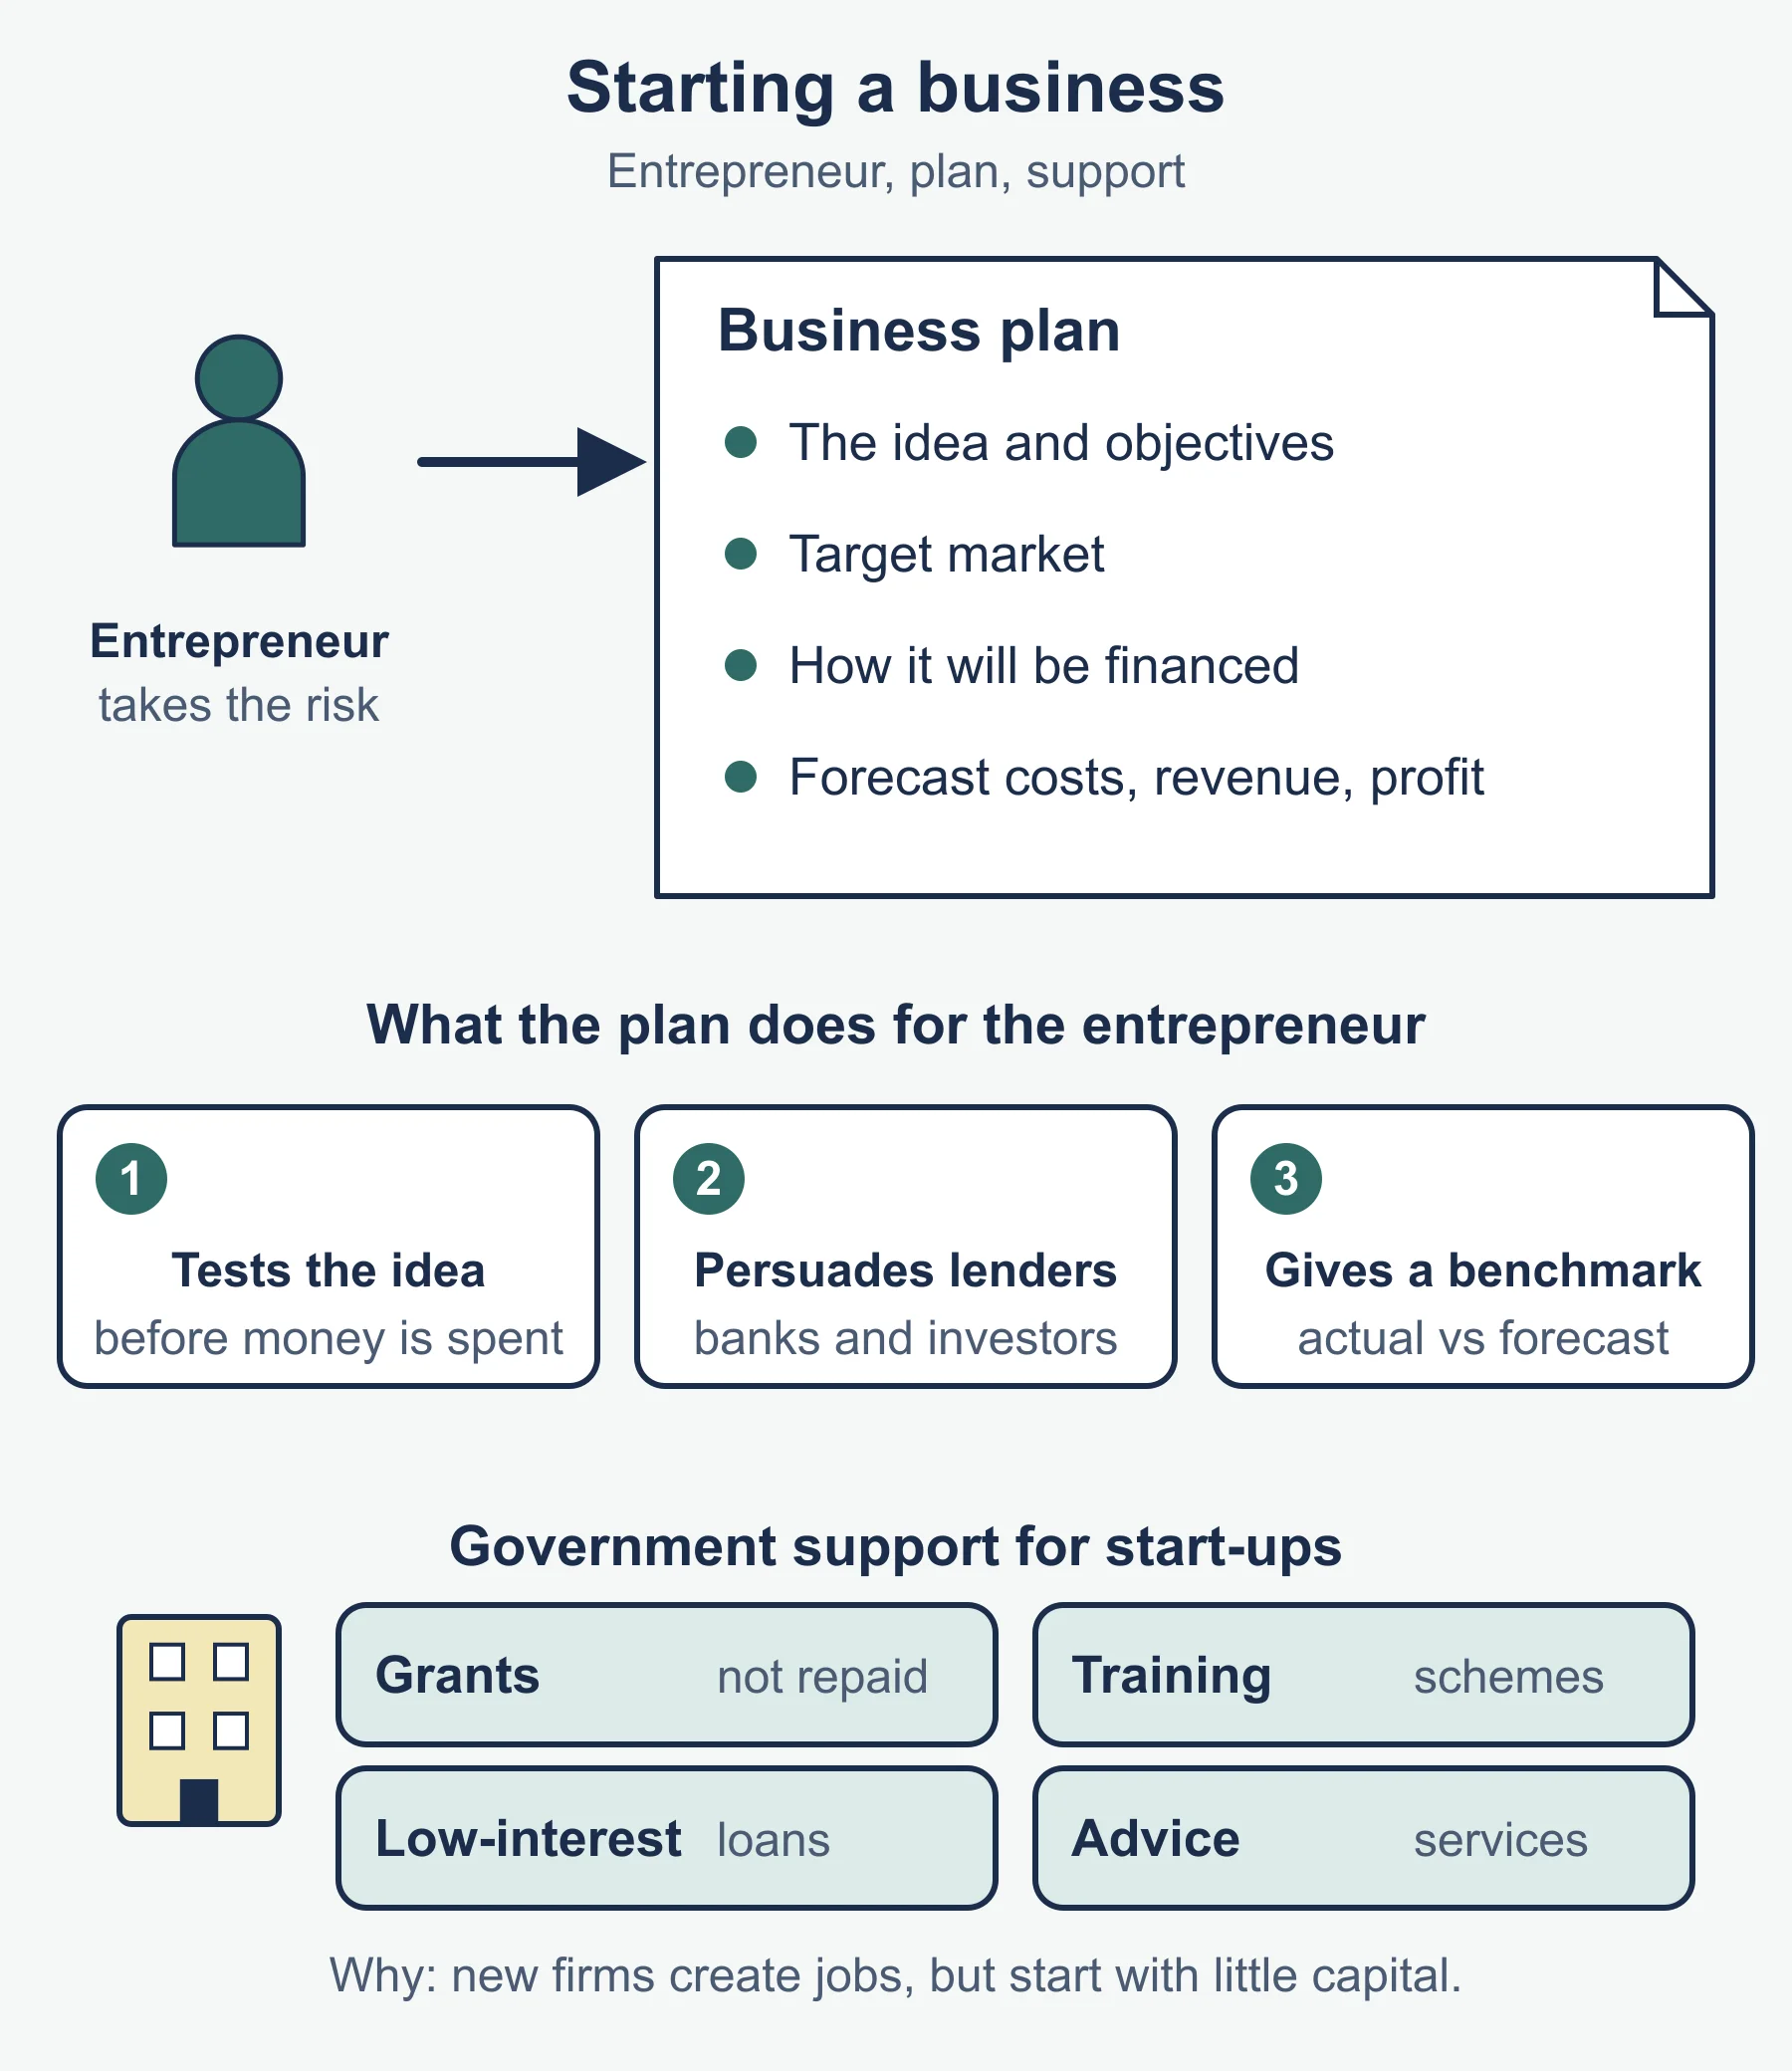
An entrepreneur sets up and takes the risk of a new business.
Motivation (both). 9725 names financial and non-financial motivations; 9625 says only motivation to set up in business. Our examples: higher income or wealth; independence, using a talent, flexible hours, a passion, helping others.
Characteristics (both; 9725 names them). Risk taker, resilient, hard working, creative, passionate, innovative, adaptable.
Identifying an opportunity (9625). Look for an unmet need, a gap in the market, a problem that annoys customers, or a new way to do something.
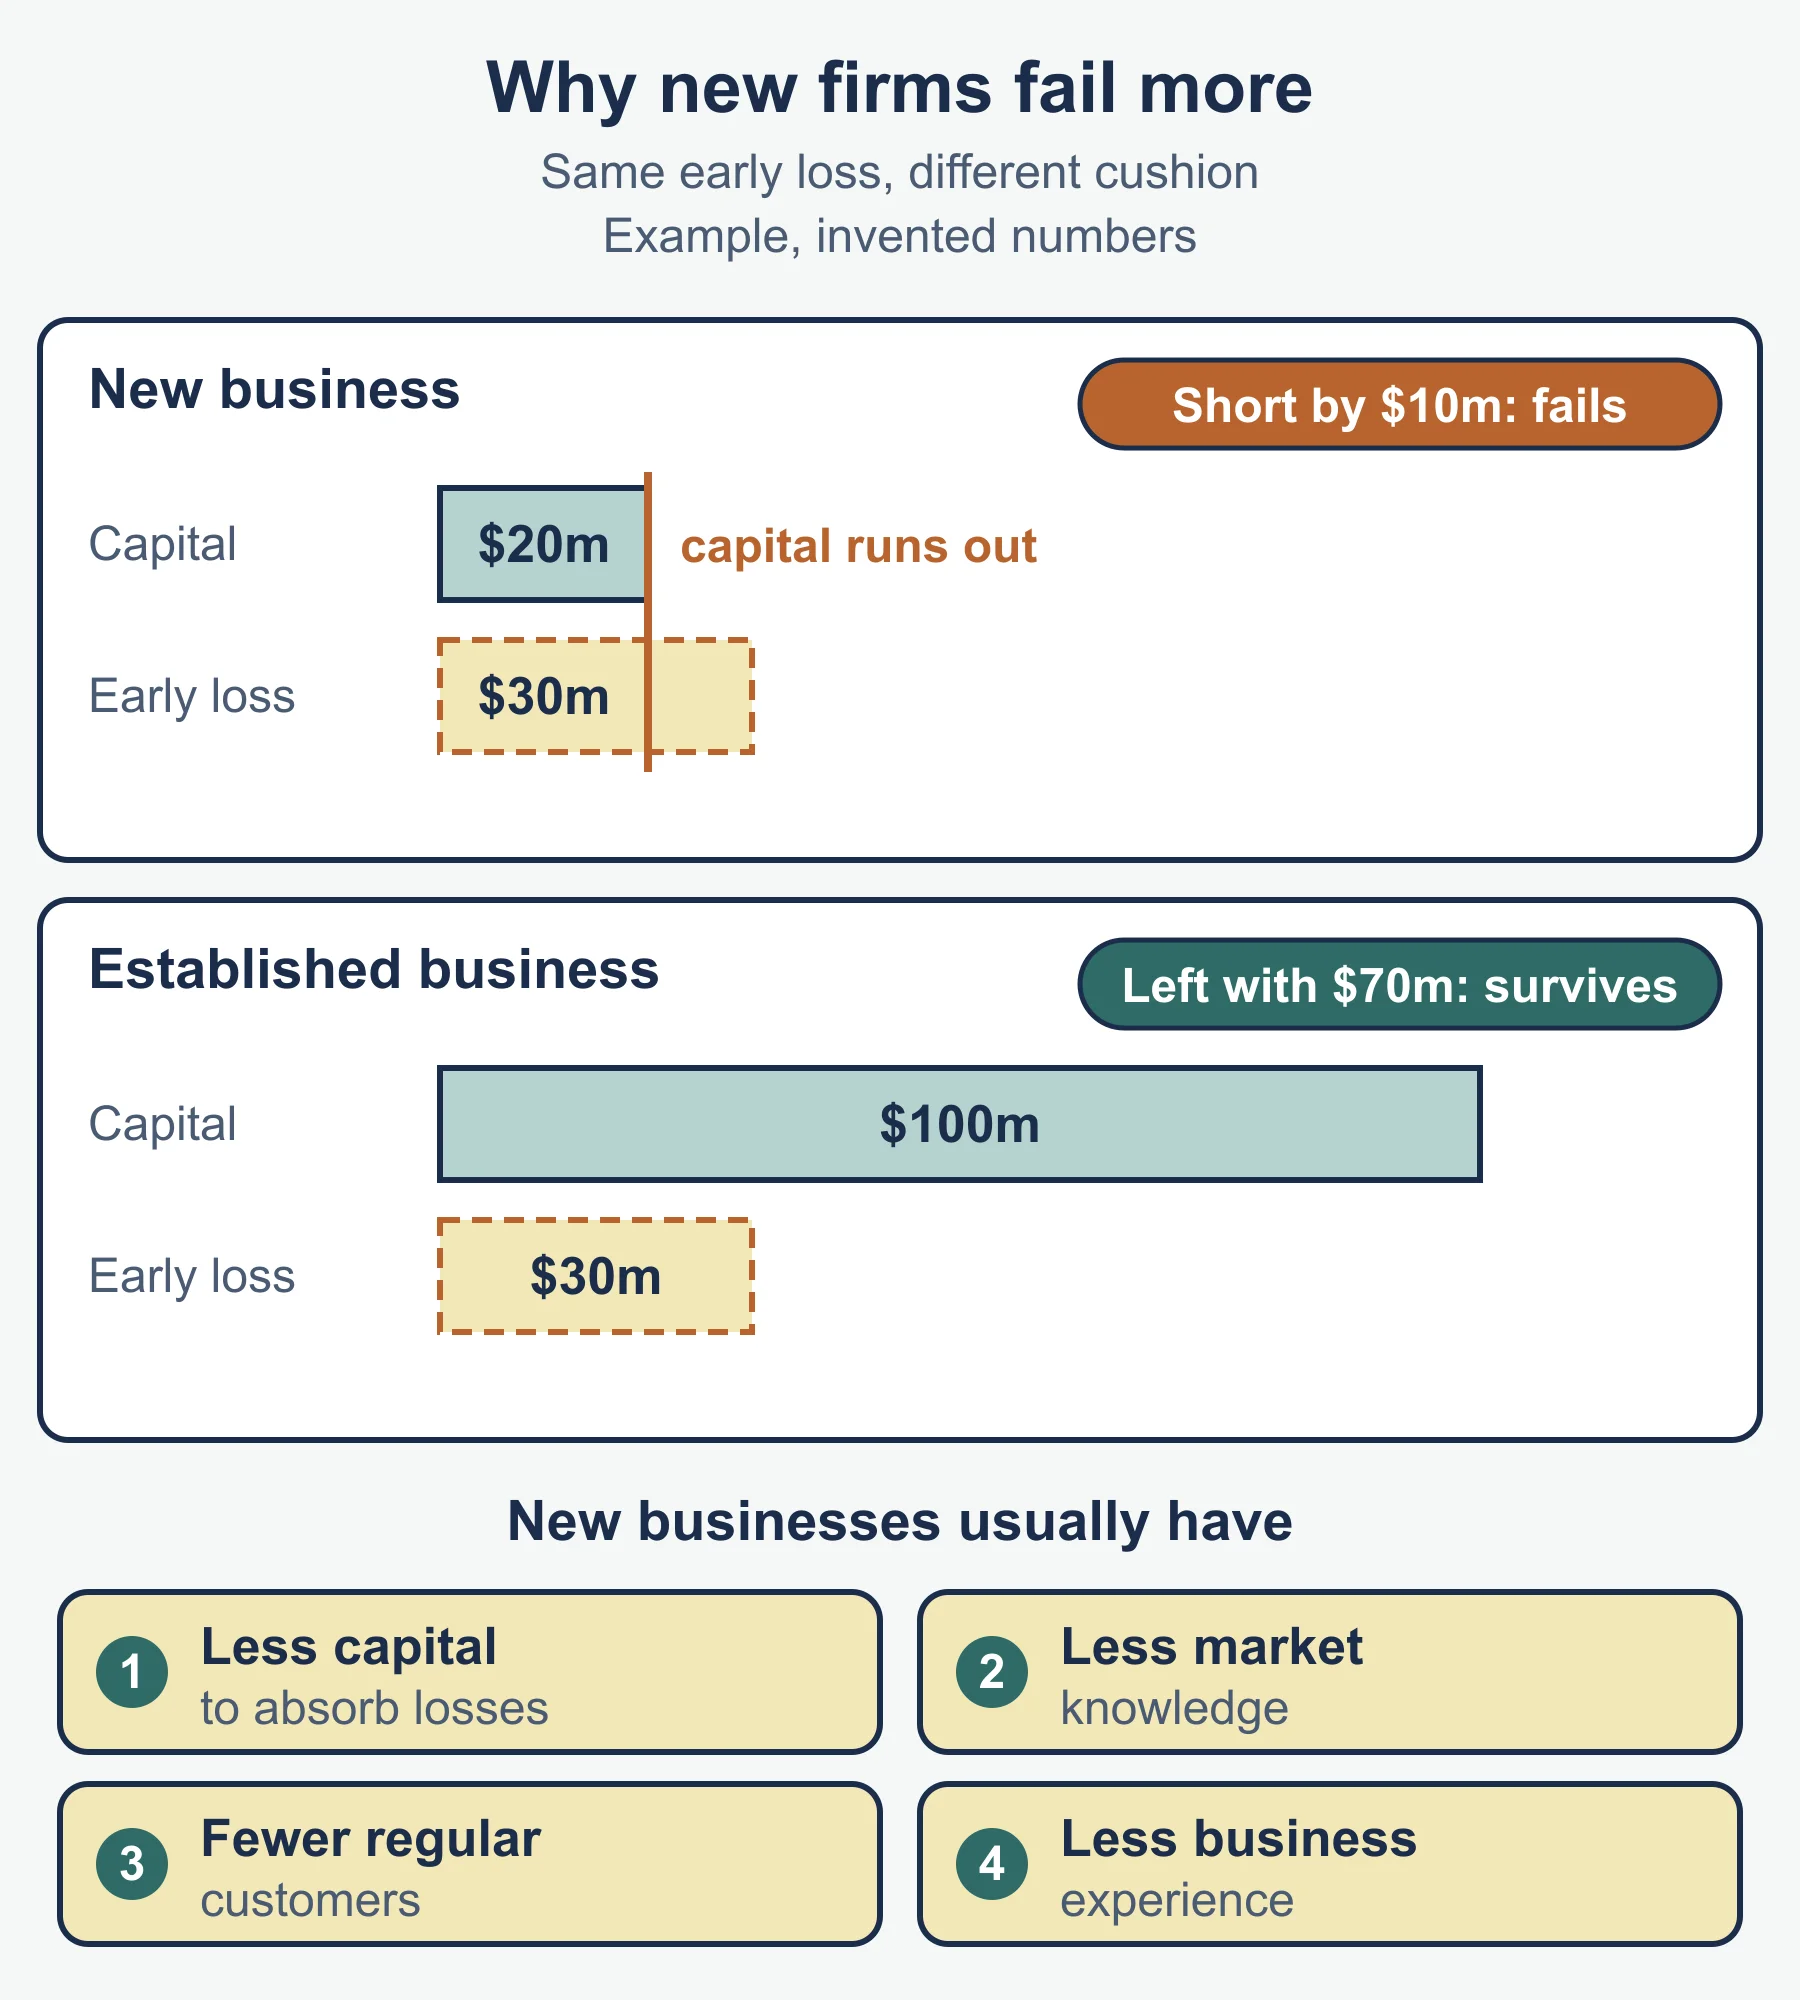
Challenges (both). Raising capital, uncertain demand, cash-flow shortages, long hours, thin experience of every function, established rivals and personal financial risk. Why many start-ups fail (9625, our wording): poor cash-flow control, too little market research, too little capital, weak management skills, and underestimating costs.
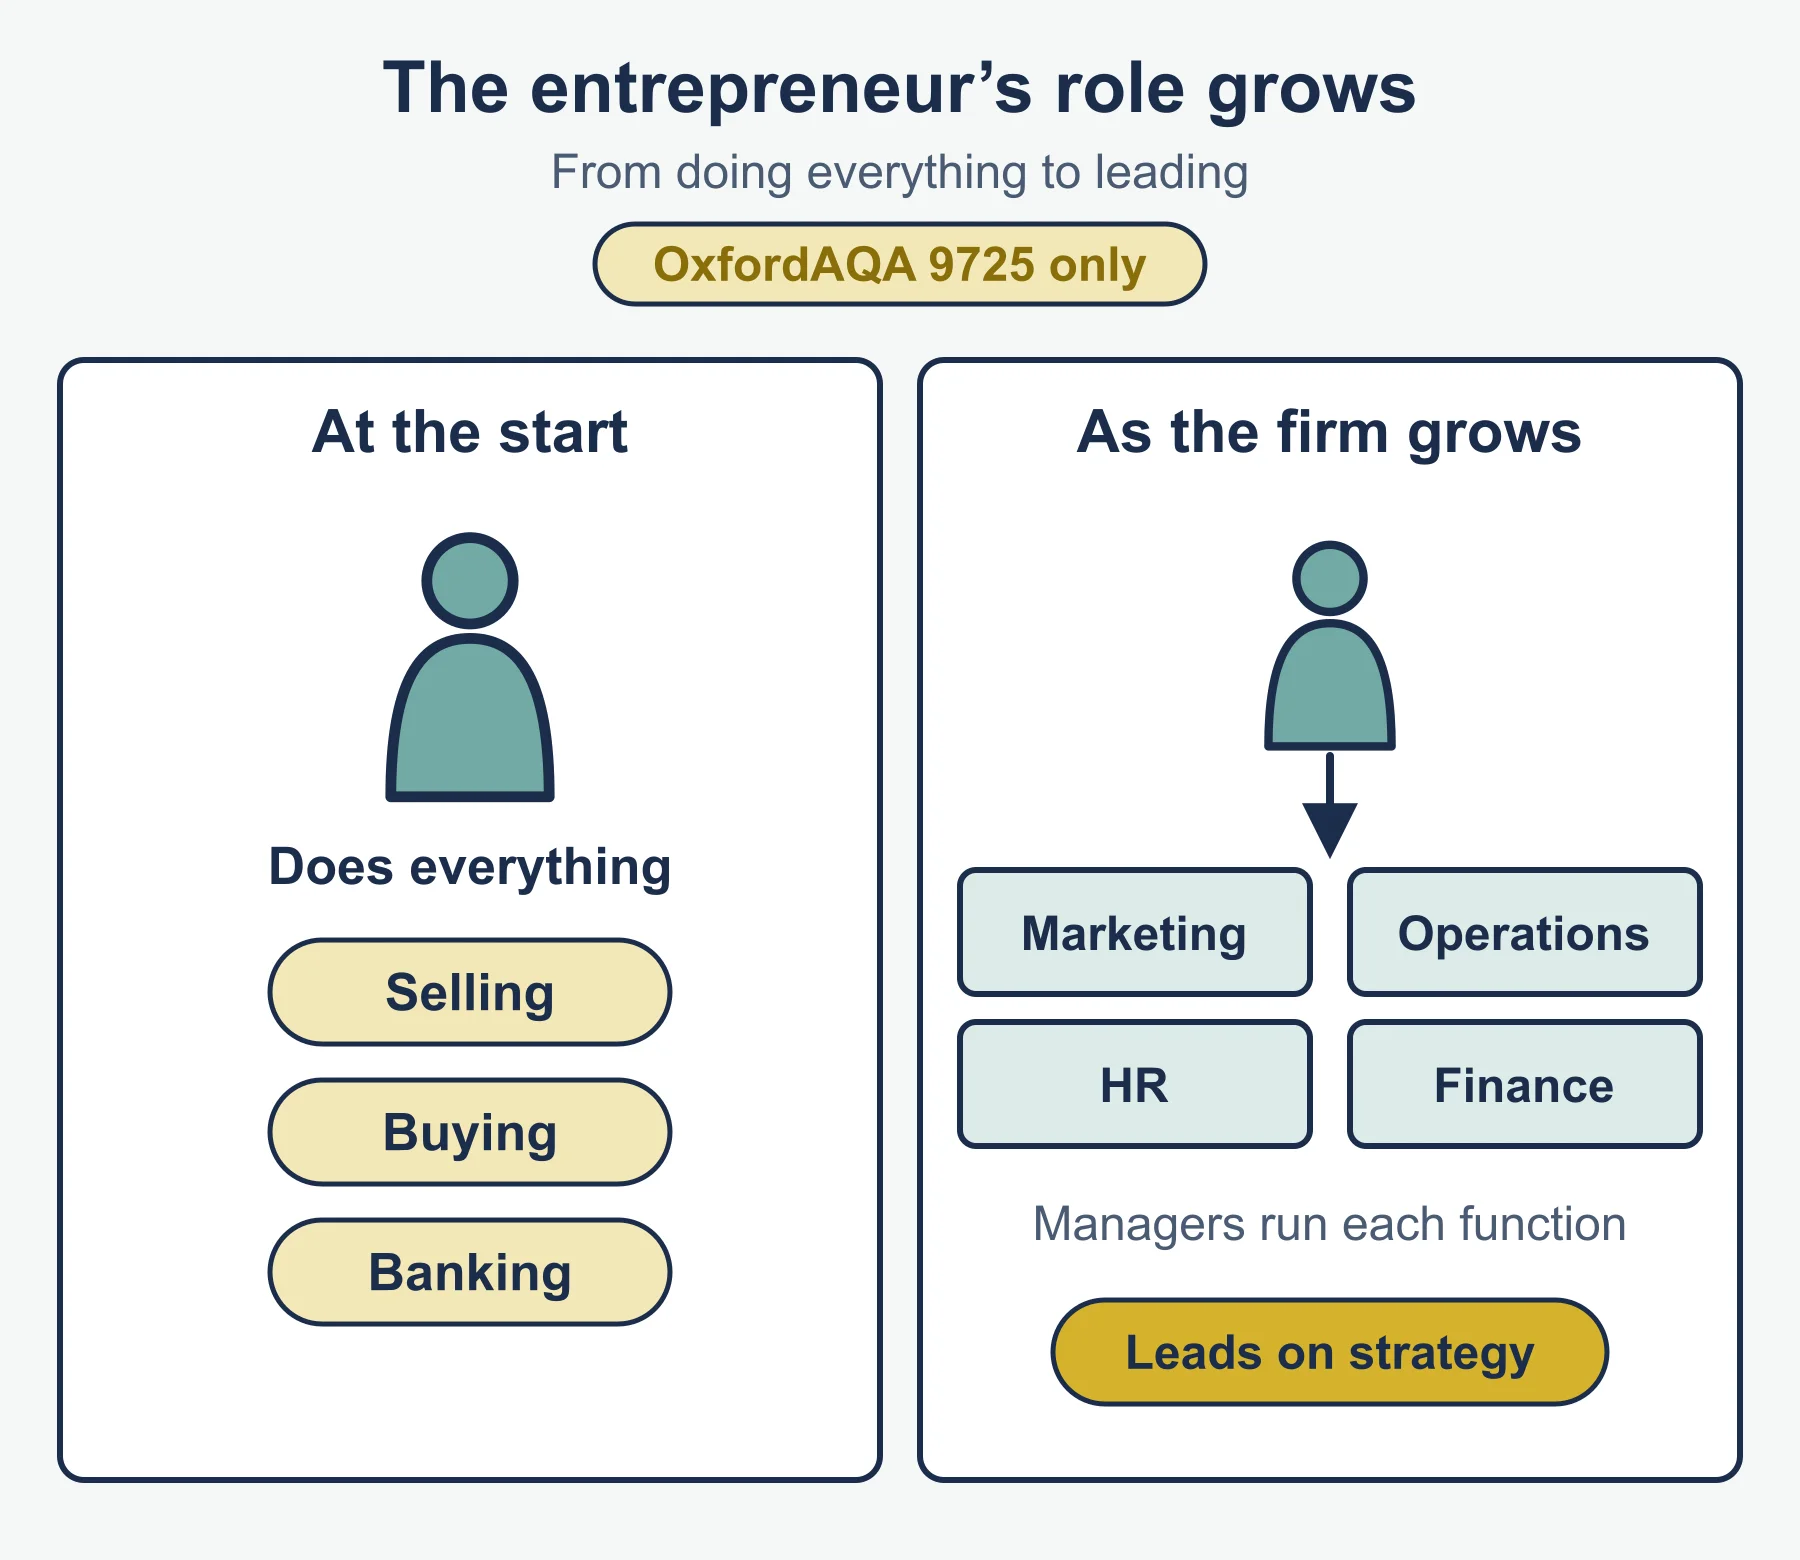
Role changes as the business grows (9725). At first the entrepreneur does everything: selling, buying, banking. As the firm grows, the role moves toward leadership and delegation. Managers are hired for functions, and the entrepreneur spends more time on strategy.
Environment and government (9625). The business environment of a country influences how many entrepreneurs succeed: access to finance, taxes, regulation, infrastructure, skills, stability and demand. Governments may support start-ups because new firms create jobs, competition and tax revenue. Support includes grants, cheap loans, tax breaks, advice and training. Factors influencing the number and type of start-ups include the state of the economy, how easy it is to borrow, attitudes to risk, and the skills available.
Business objectives and SMART (both)
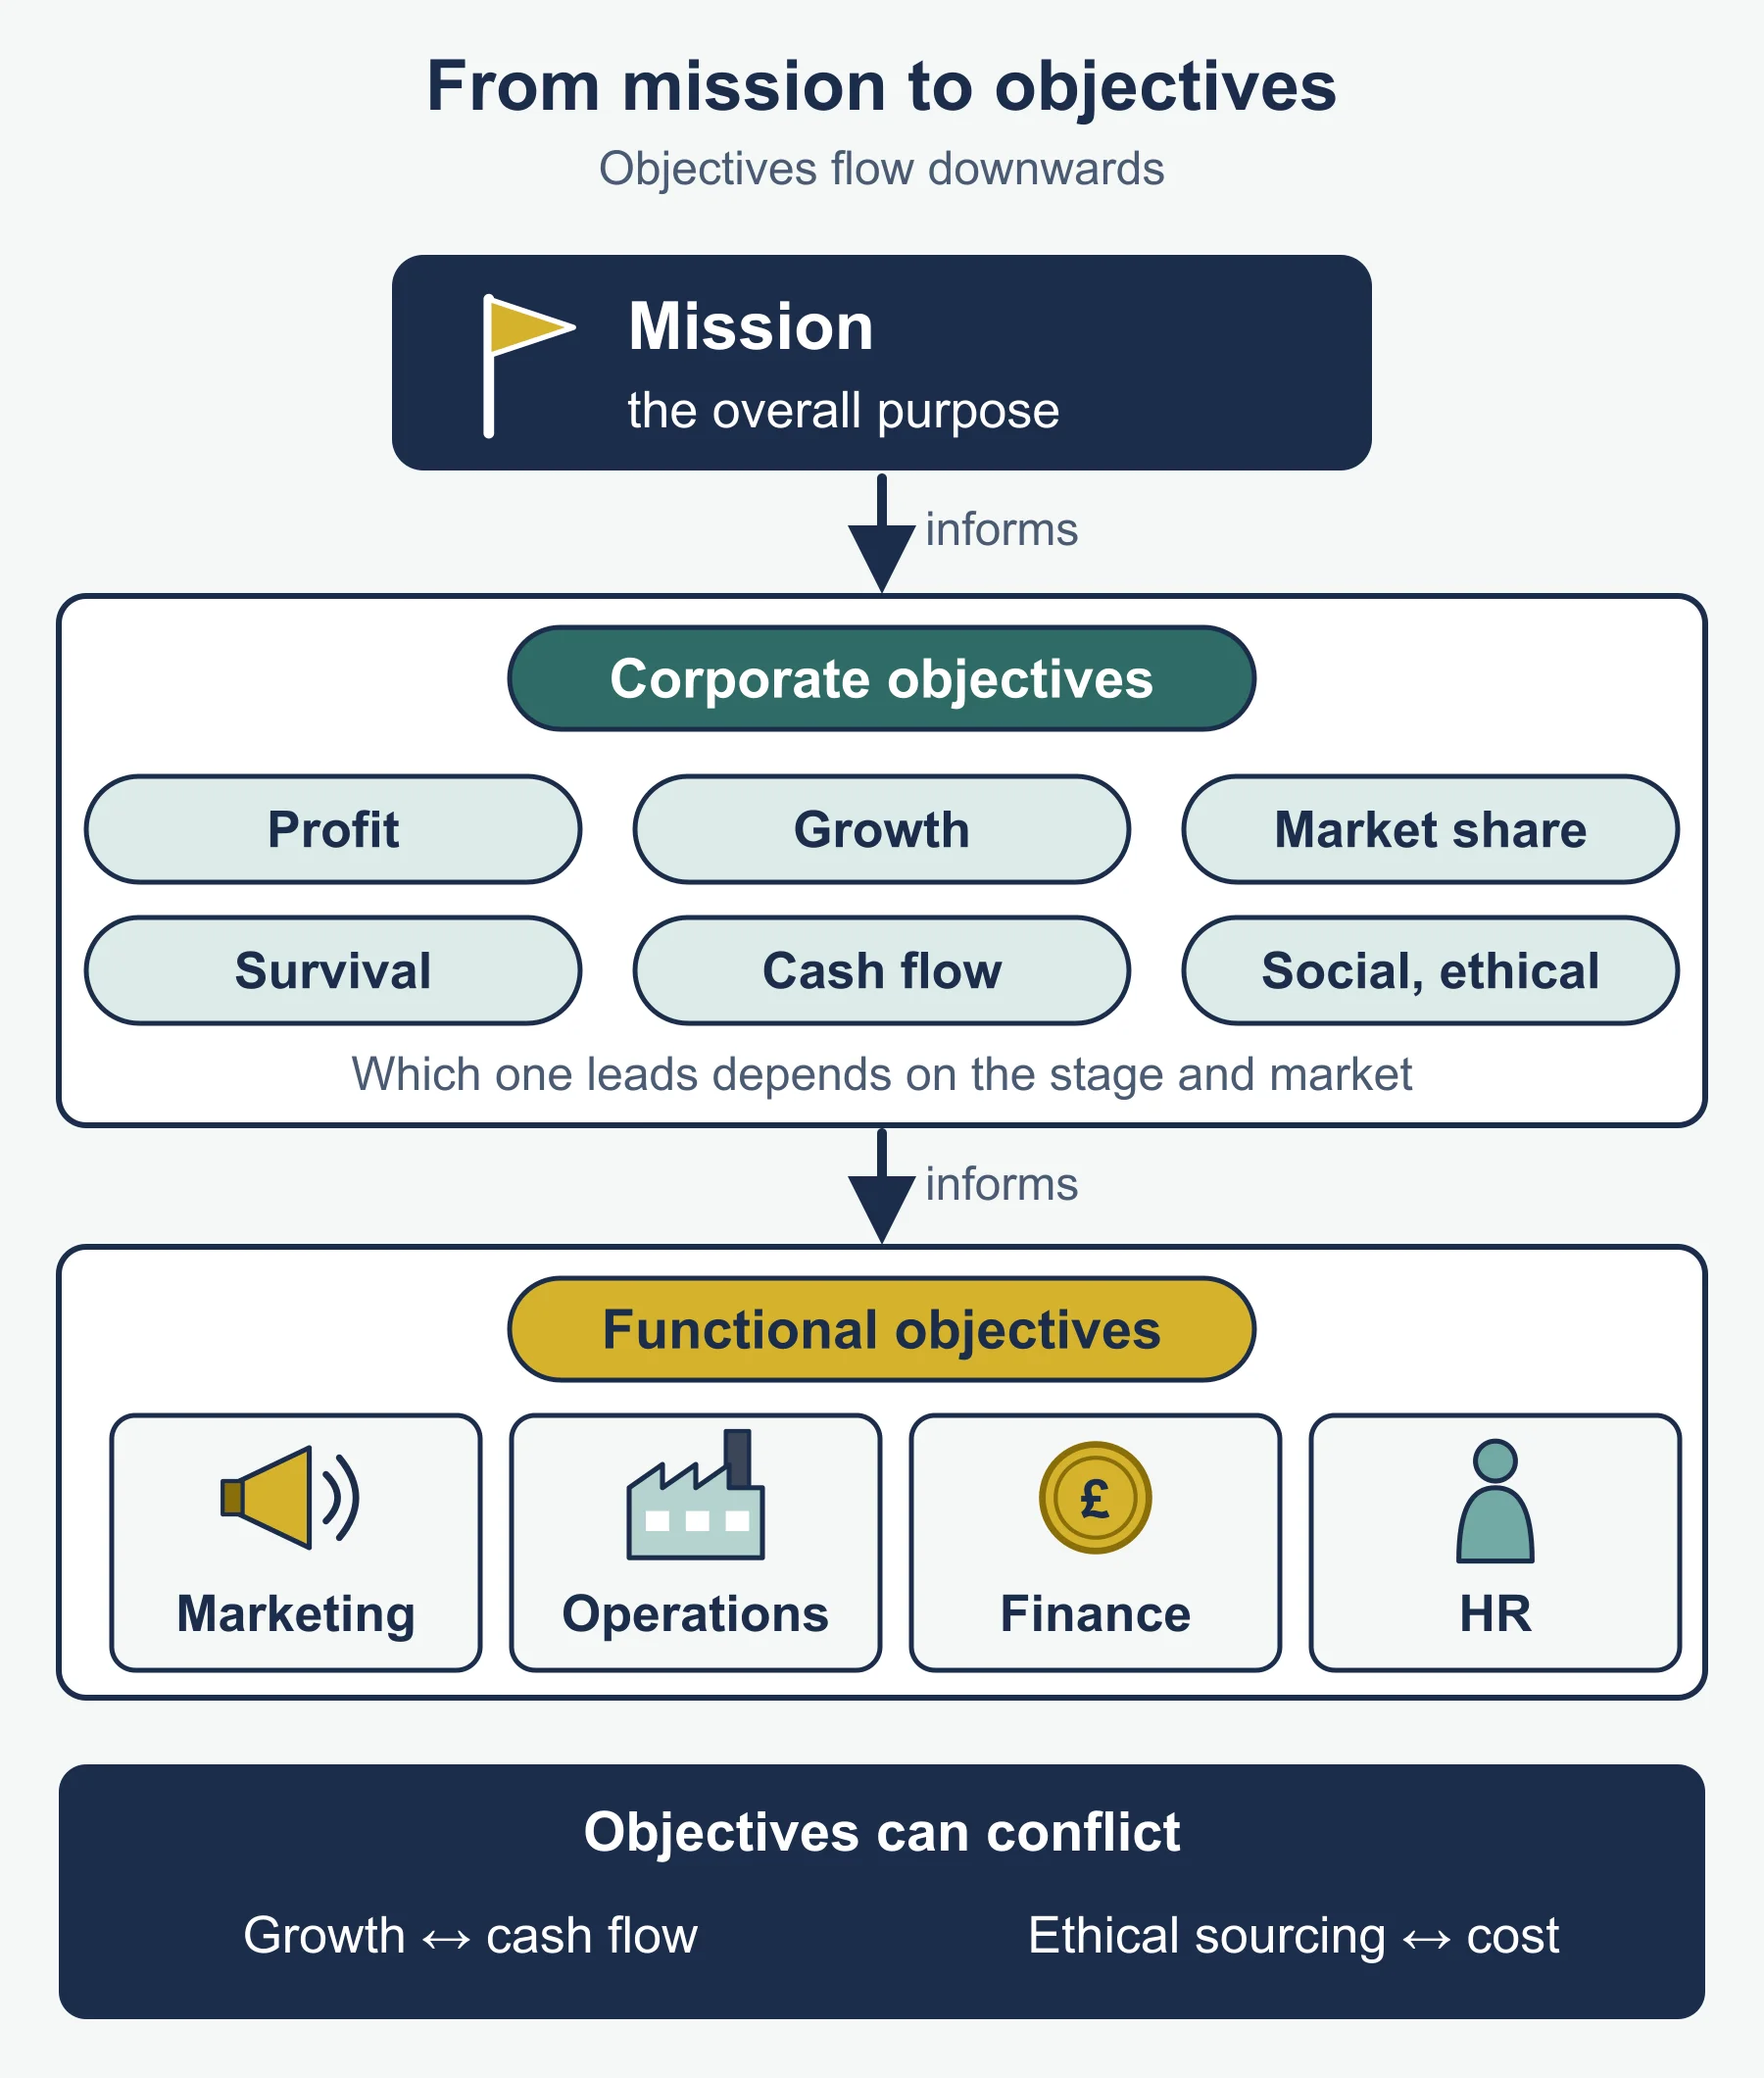
Typical objectives are survival, profit, growth and cash flow (both specifications), social objectives (both), and personal and ethical objectives (9625).
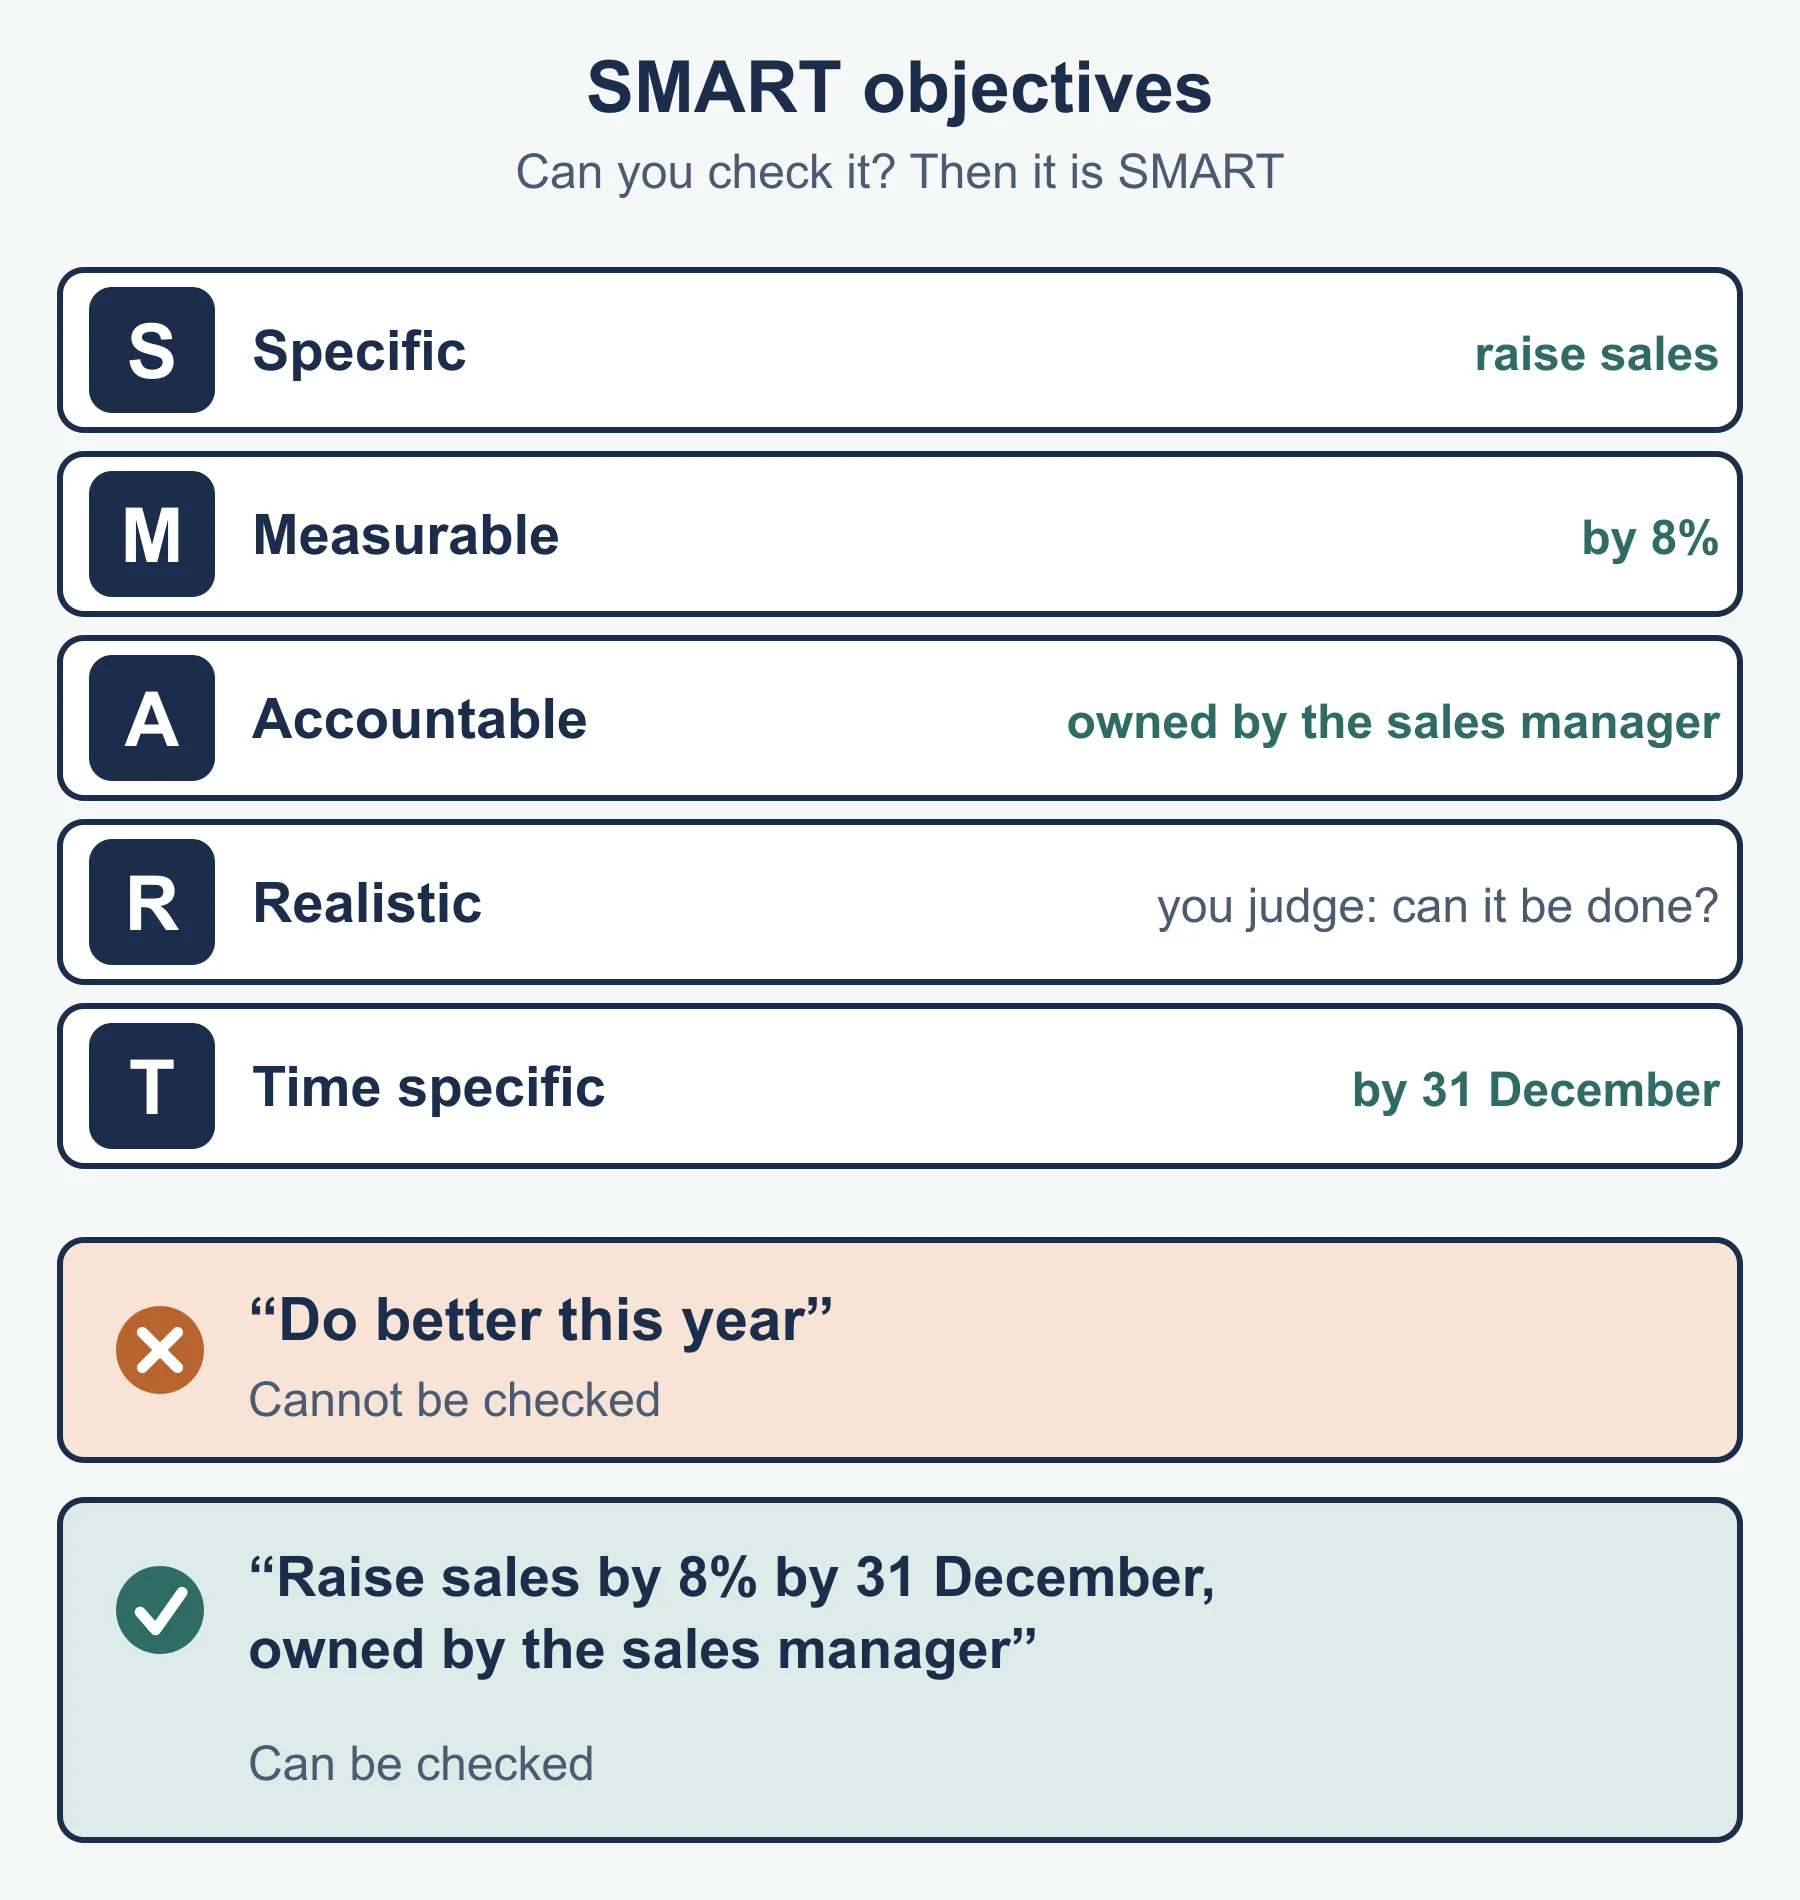
Effective objectives are SMART. The 9725 text spells this out as Specific, Measurable, Accountable, Realistic, Time specific. “Raise sales by 8% by 31 December, owned by the sales manager” can be checked; “do better this year” cannot.
The value of setting objectives: direction, measurable success, motivation and a basis for choosing. Objectives can conflict: growth can drain cash.
Business plans (both)
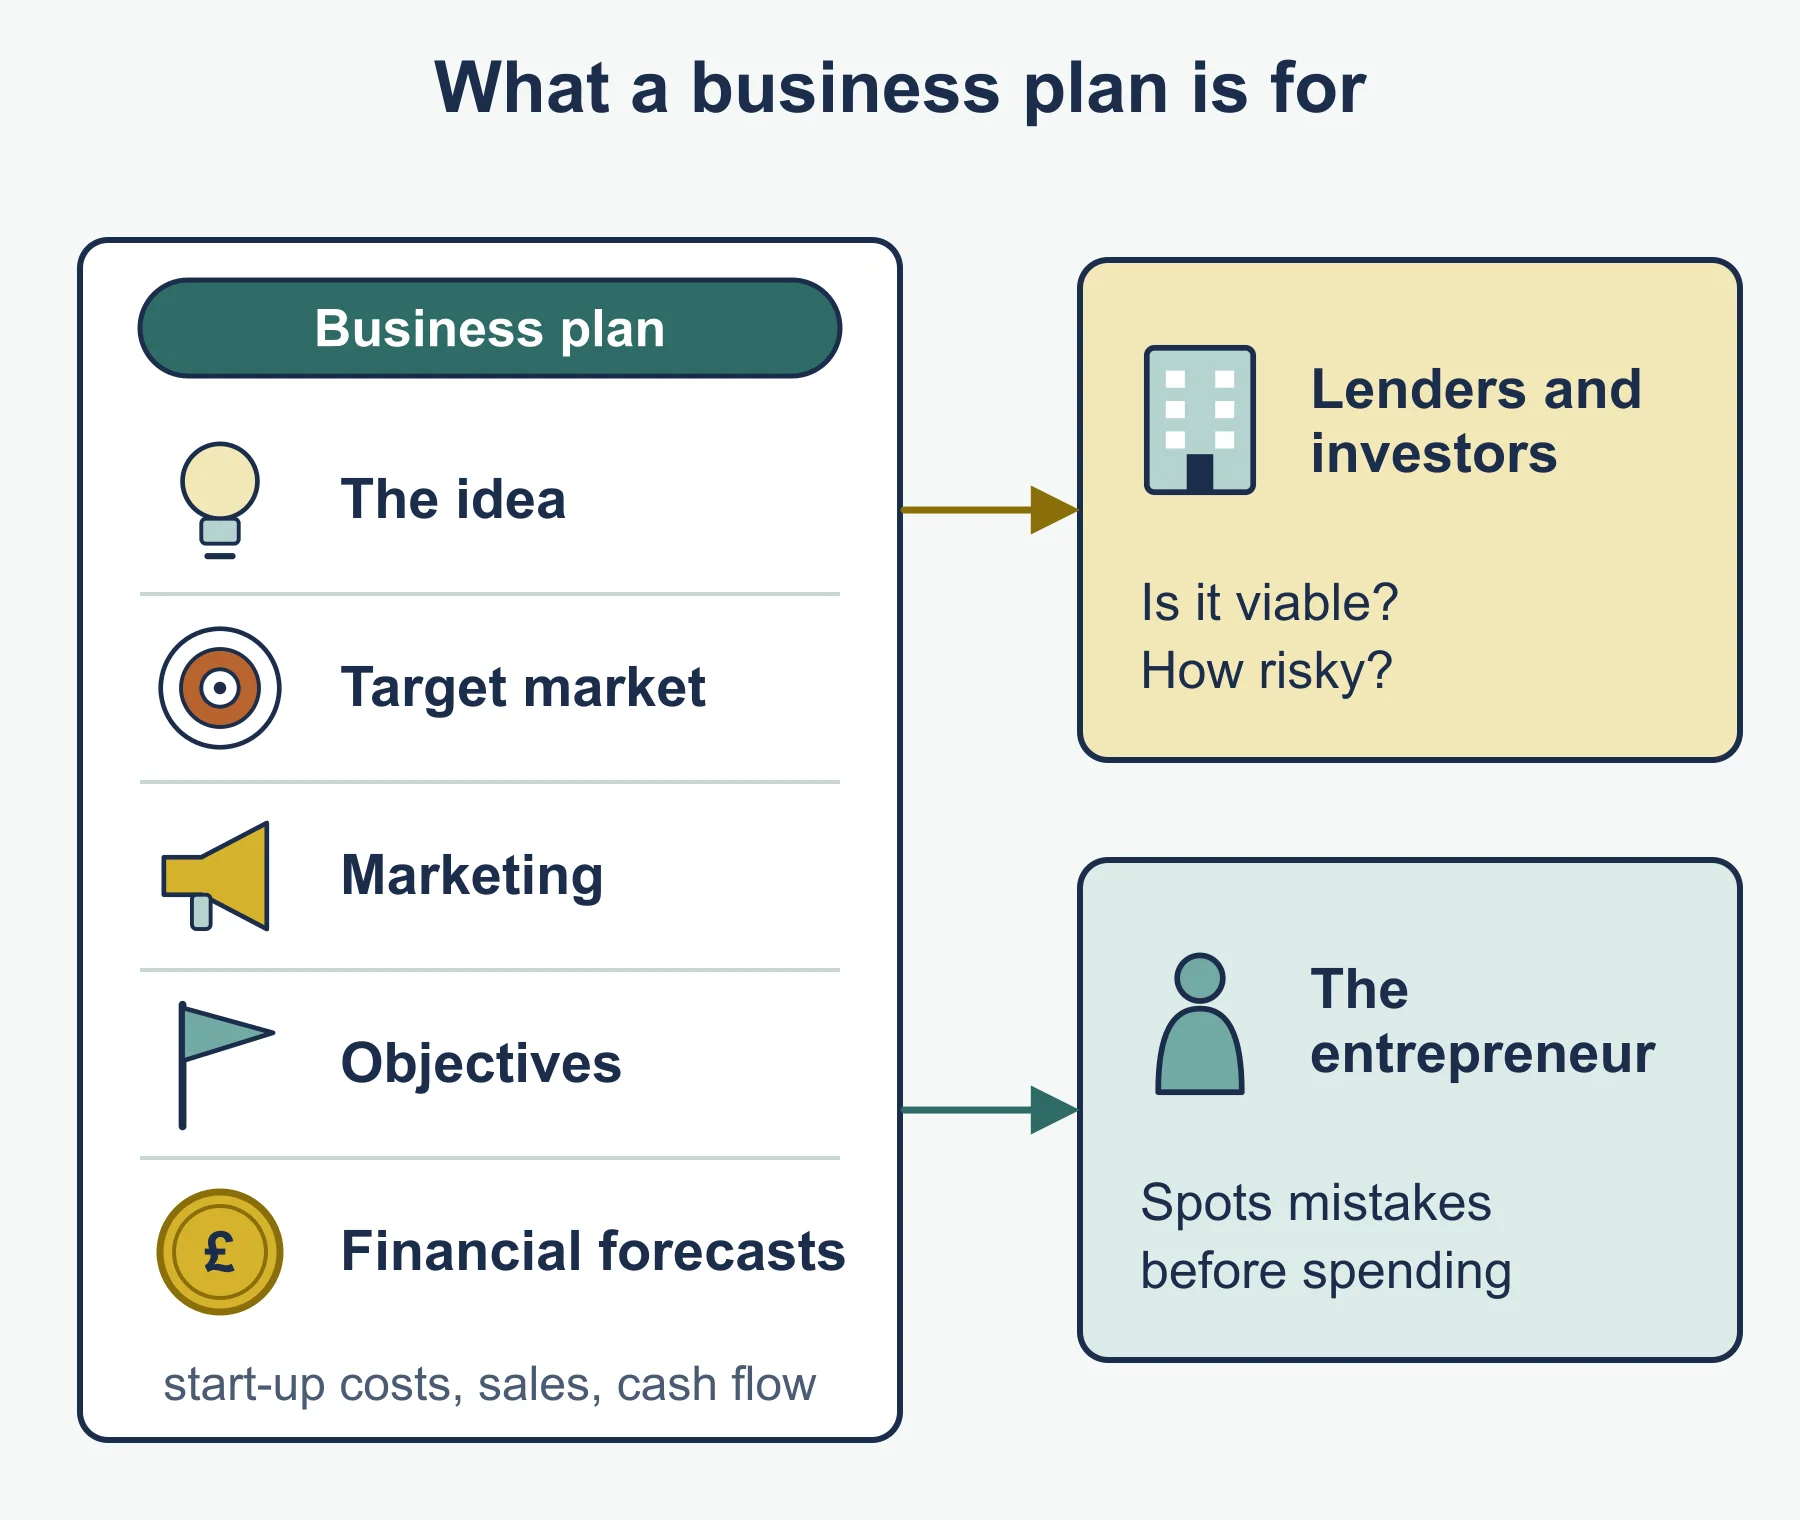
A business plan sets out what a business intends to do and how. The 9725 key elements are ownership, objectives, target market and market analysis, competitor analysis, unique selling point (USP) and financial analysis.
Benefits: it forces careful thinking, shows weaknesses early, helps win loans or investment. Limitations: it takes time, rests on forecasts that can be wrong, can become out of date, and a good plan does not guarantee success.
Competitiveness (both; 9725 adds meaning and significance) is how well a firm can win customers against rivals. A USP, lower costs or better service improve it.
Why business matters (9625)
Business, including start-ups, creates jobs and incomes, produces goods and services people want, pays taxes, and can raise economic growth. It can also cause pollution, congestion or the closure of local shops. Effects on stakeholders are covered below.
Decision trees, expected value and net gain (9625)
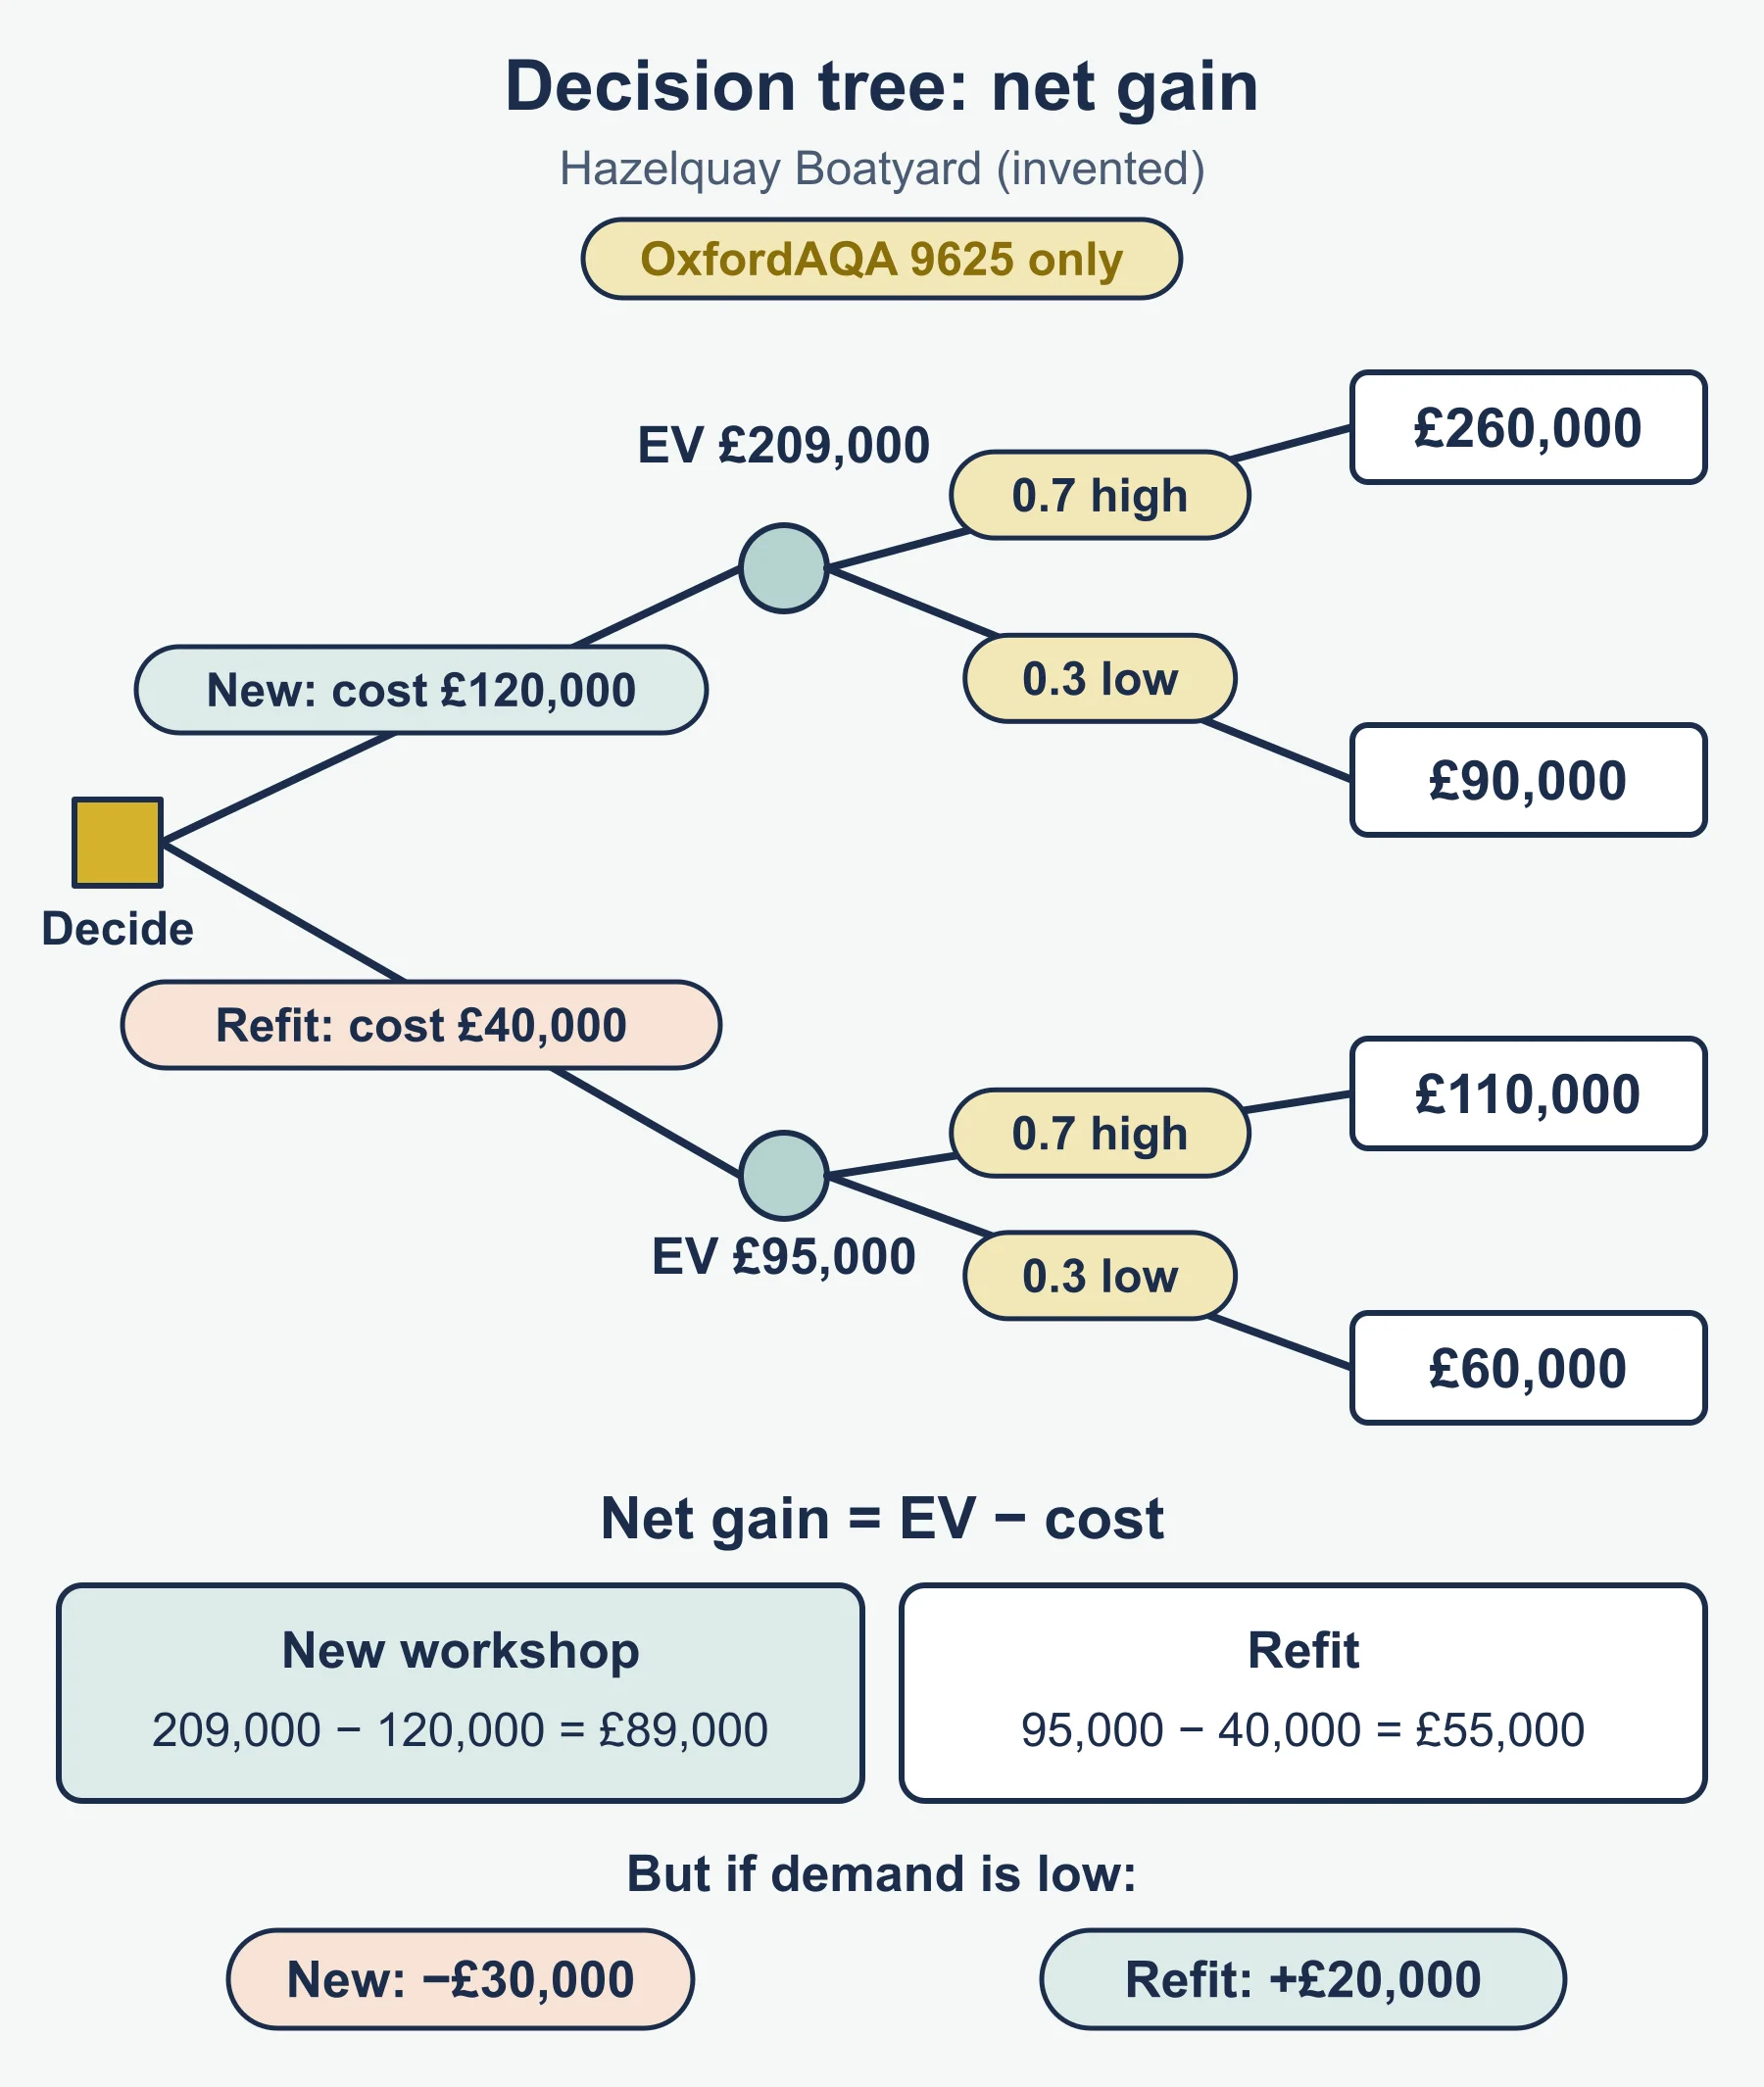
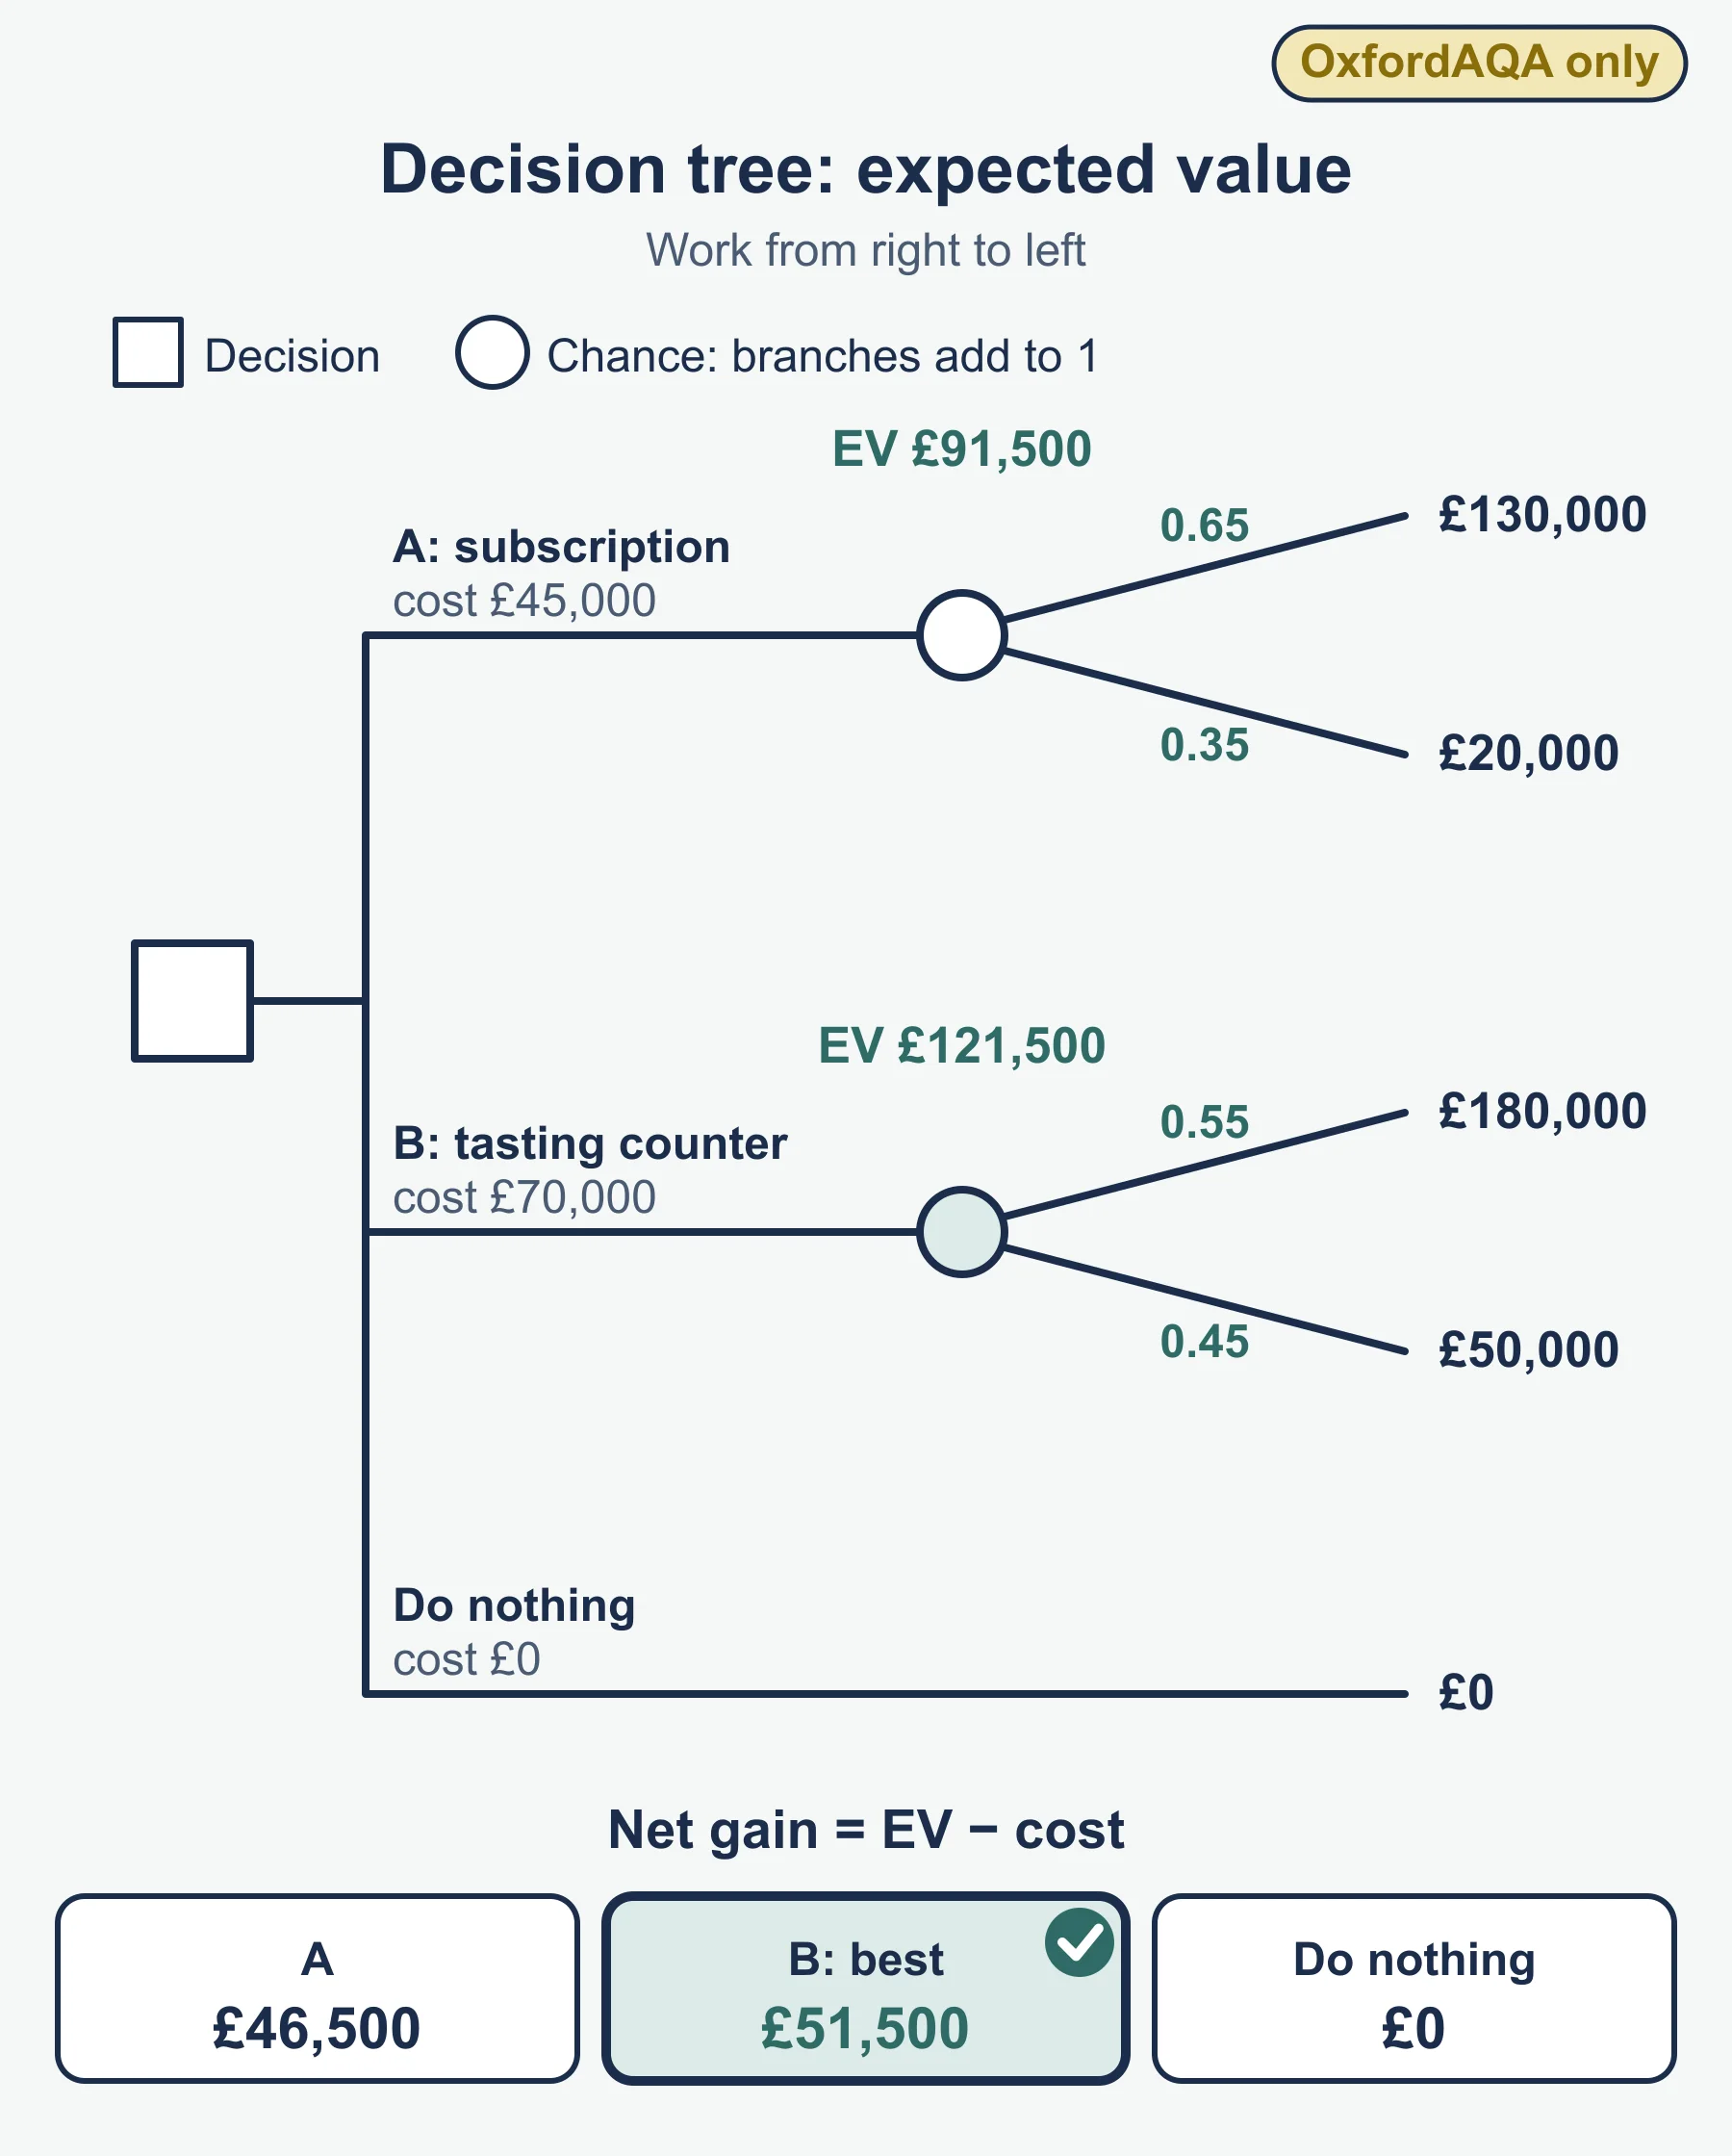
A decision tree maps choices (a square) and uncertain outcomes (a circle, with probabilities adding to 1). Expected value = the sum of probability x outcome. Net gain = expected value minus the cost of that option. These are the standard forms.
Worked example. Hazelquay Boatyard can build a new workshop for £120,000 or refit the old one for £40,000. Demand is high with probability 0.7 and low with probability 0.3.
New workshop: high £260,000, low £90,000
  EV = 0.7 x 260,000 + 0.3 x 90,000 = 182,000 + 27,000 = £209,000
  Net gain = 209,000 - 120,000 = £89,000
Refit: high £110,000, low £60,000
  EV = 0.7 x 110,000 + 0.3 x 60,000 = 77,000 + 18,000 = £95,000
  Net gain = 95,000 - 40,000 = £55,000
The new workshop has the higher net gain. But in the low-demand case it returns £90,000 on £120,000, a loss of £30,000, while the refit still gains £20,000. If the yard cannot survive a loss, the refit is safer. Limitations of trees: guessed probabilities, no non-financial factors or ethics, and an average that may never happen.
Types of business (3.1.1.2)
| Type | Owner(s) and liability | Finance and profit | Spec |
|---|---|---|---|
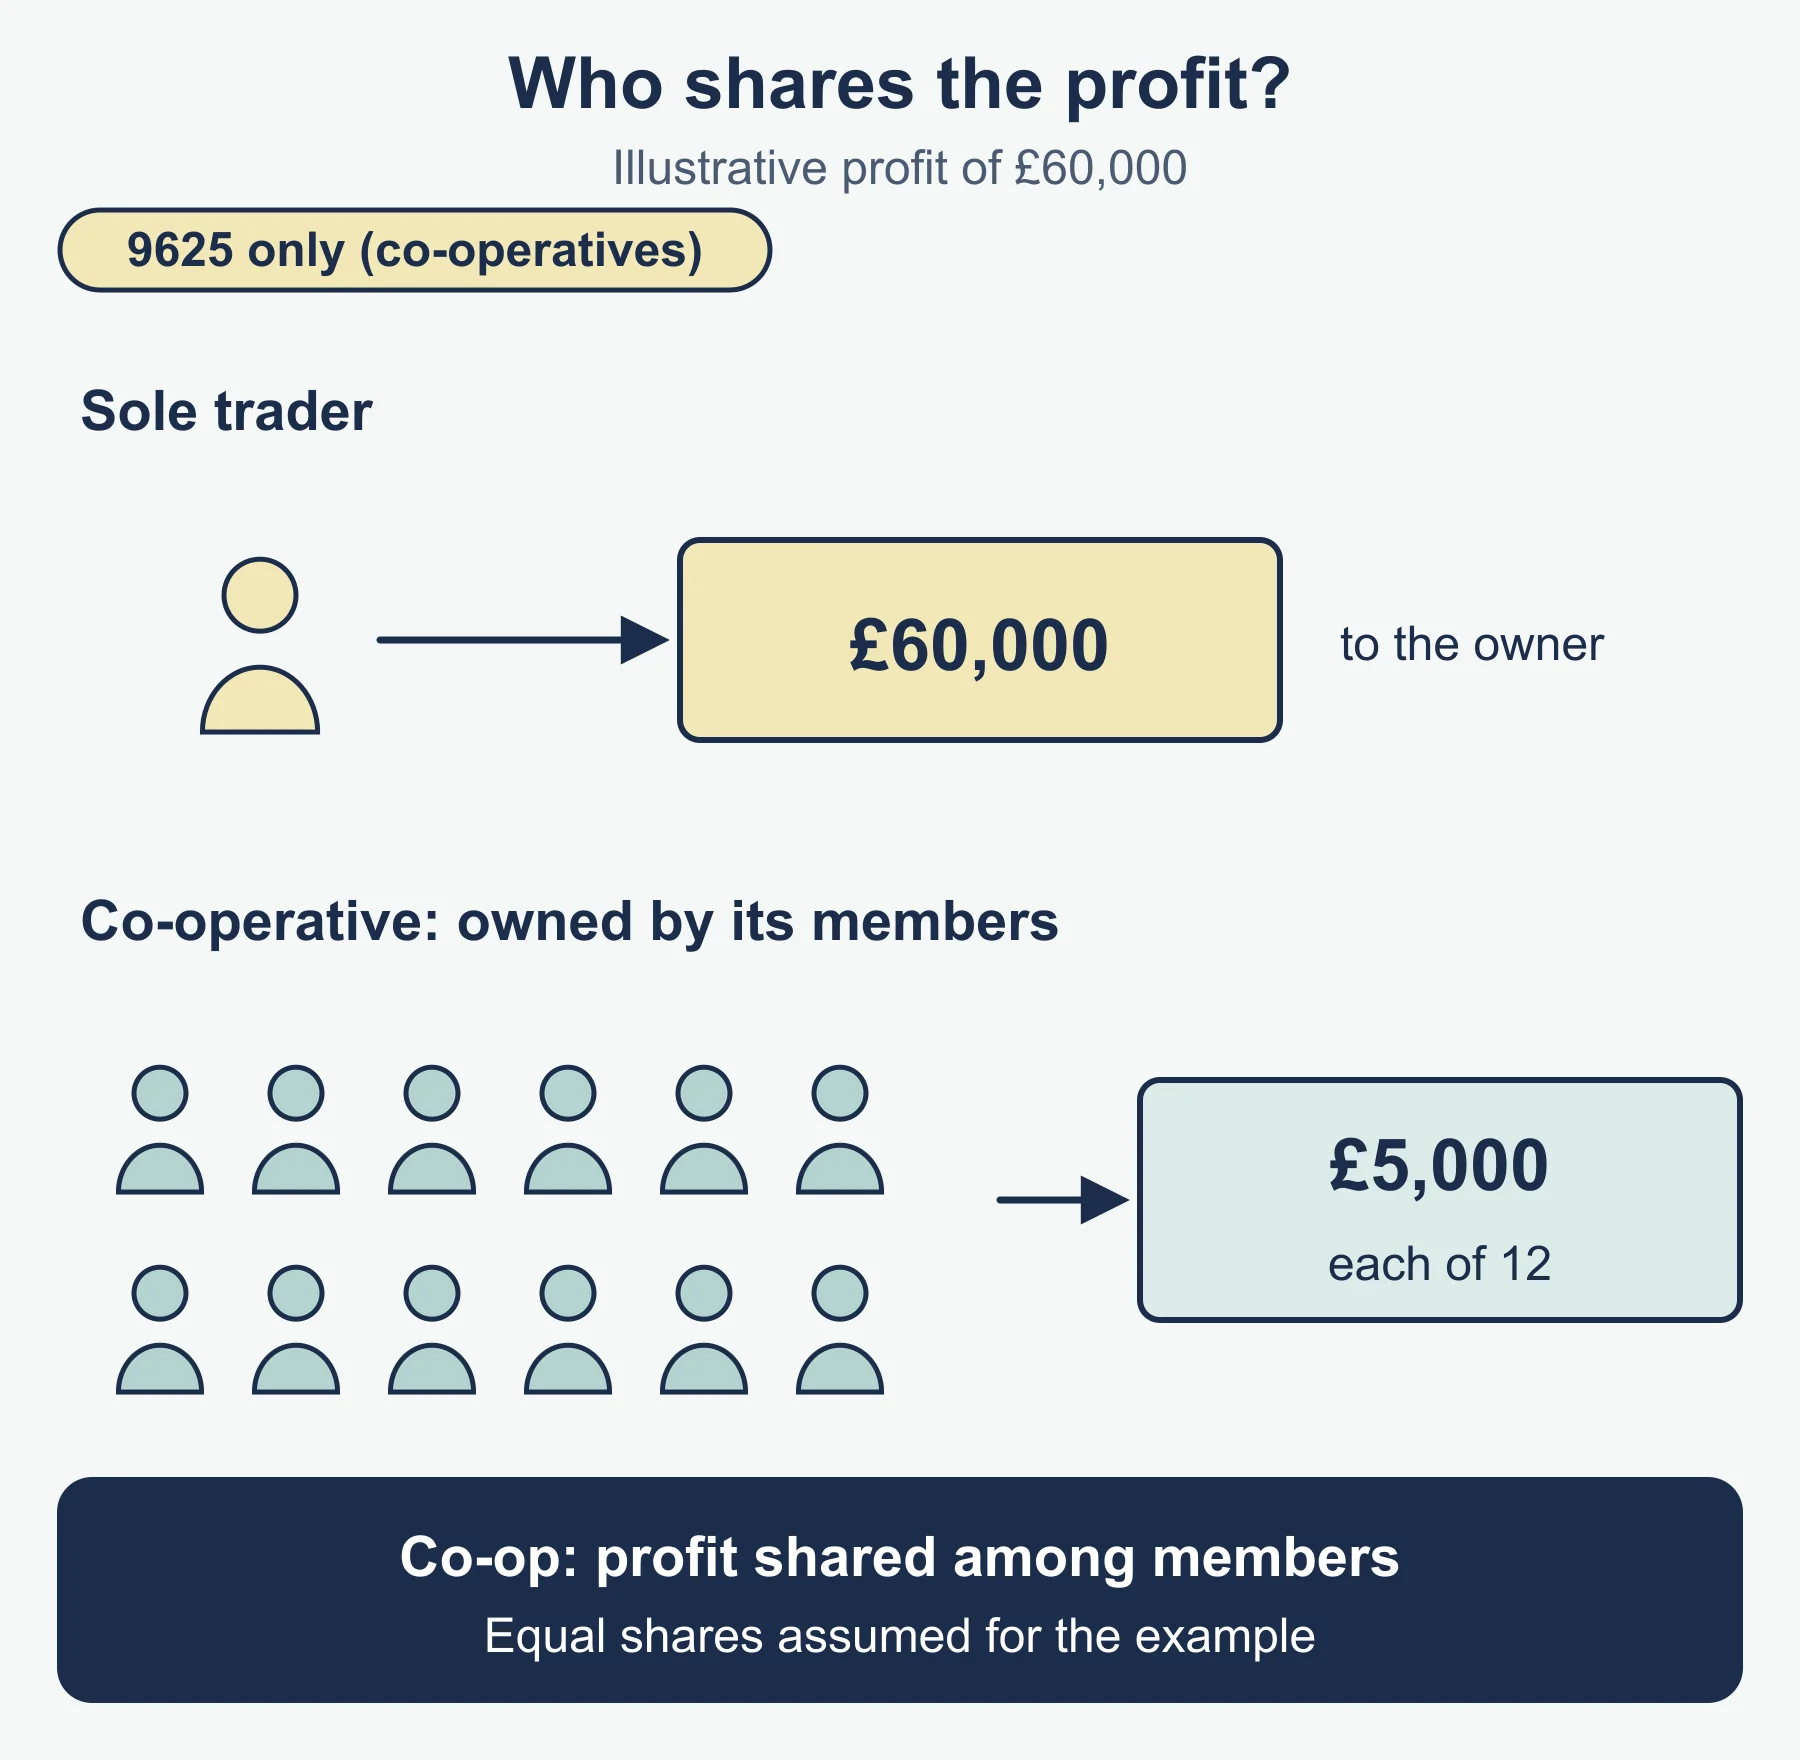
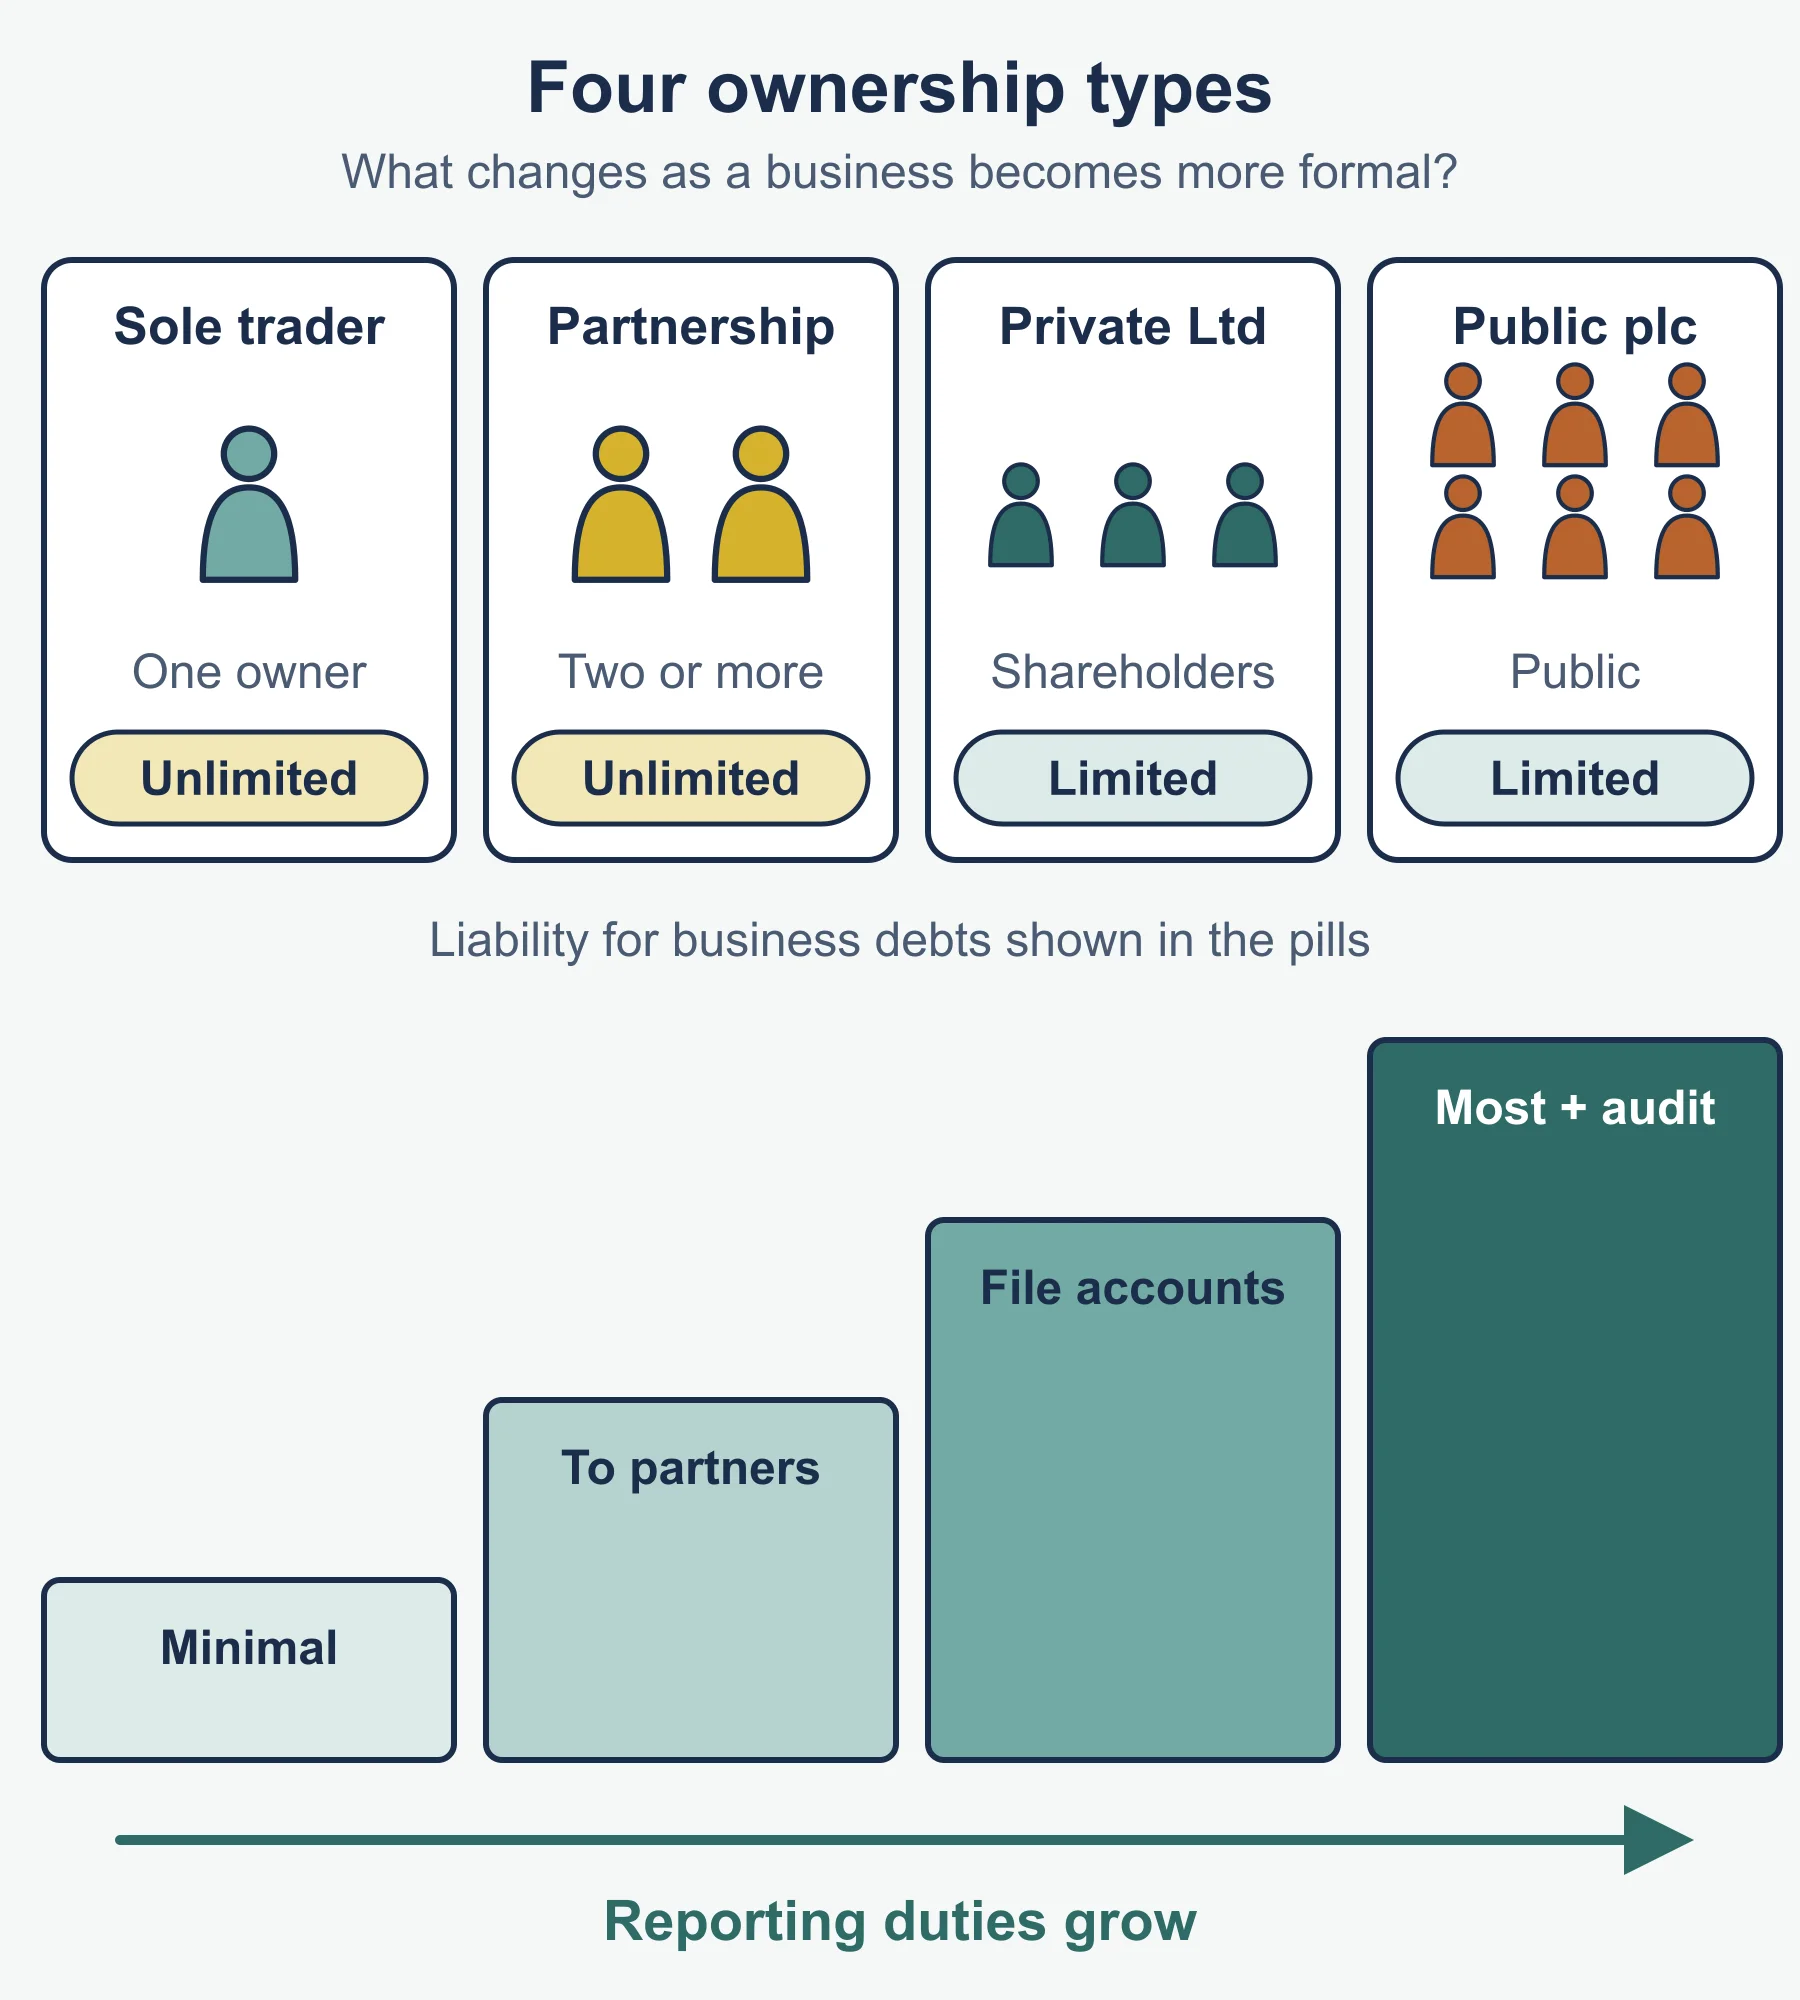
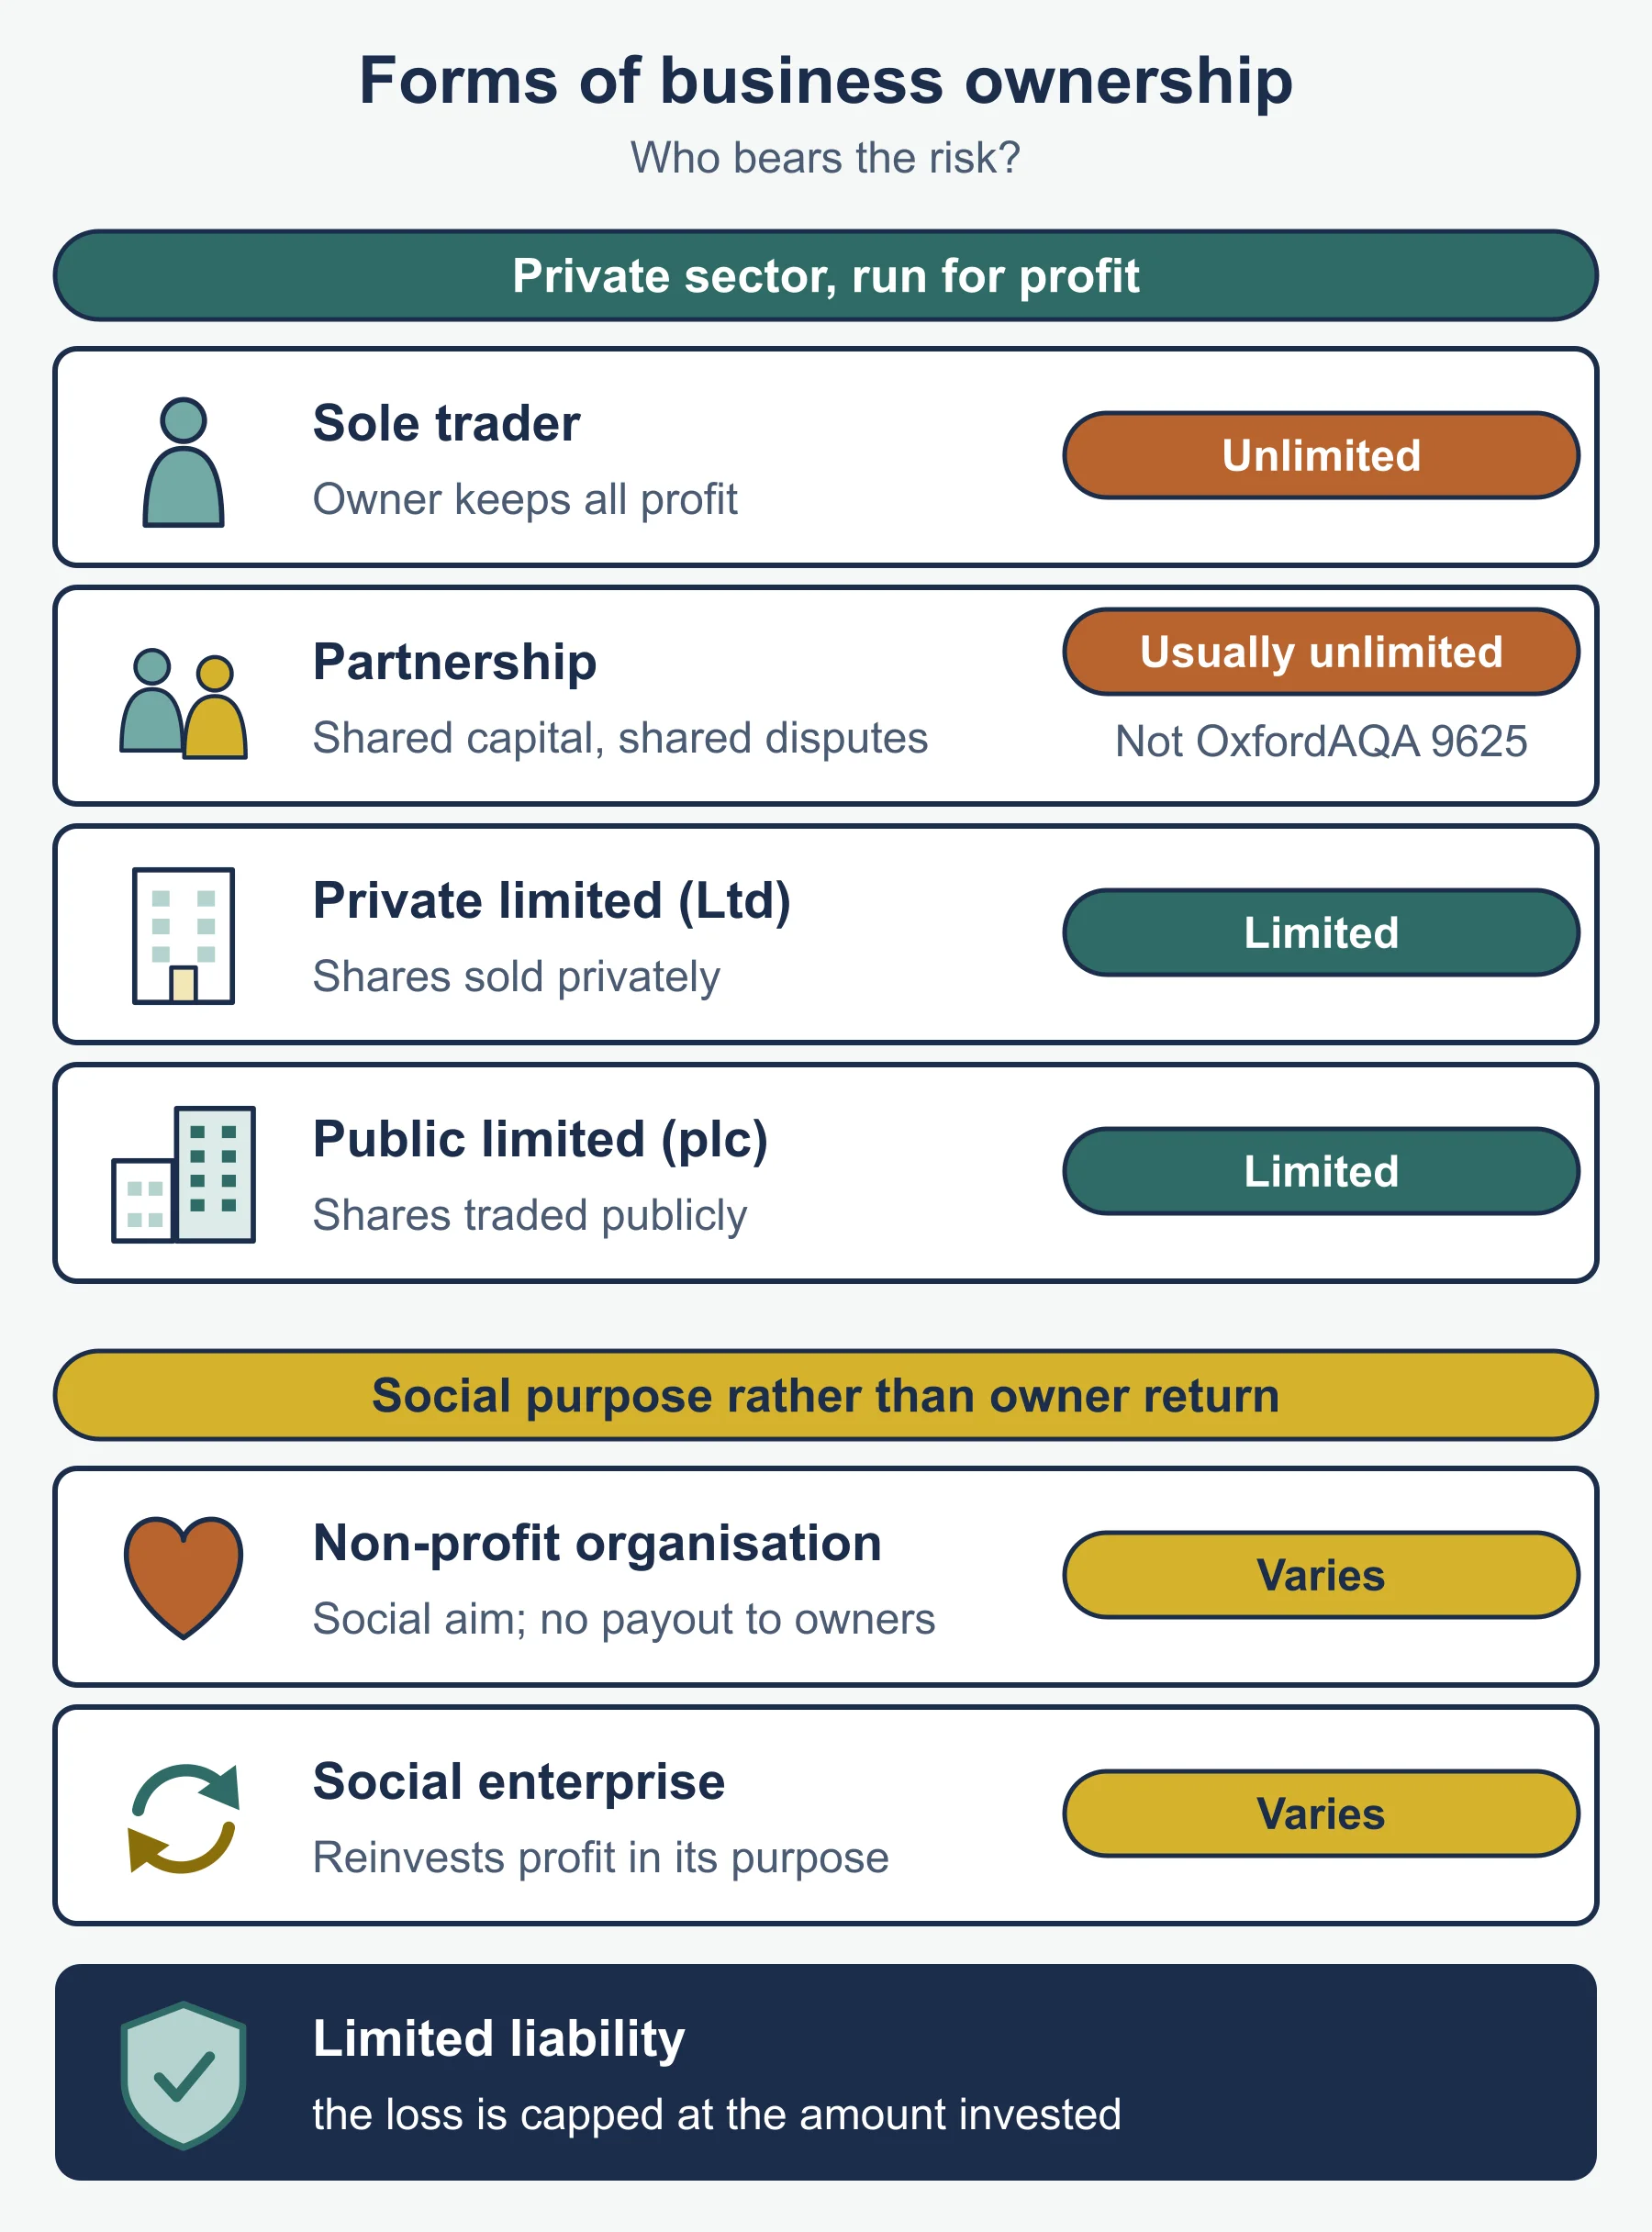
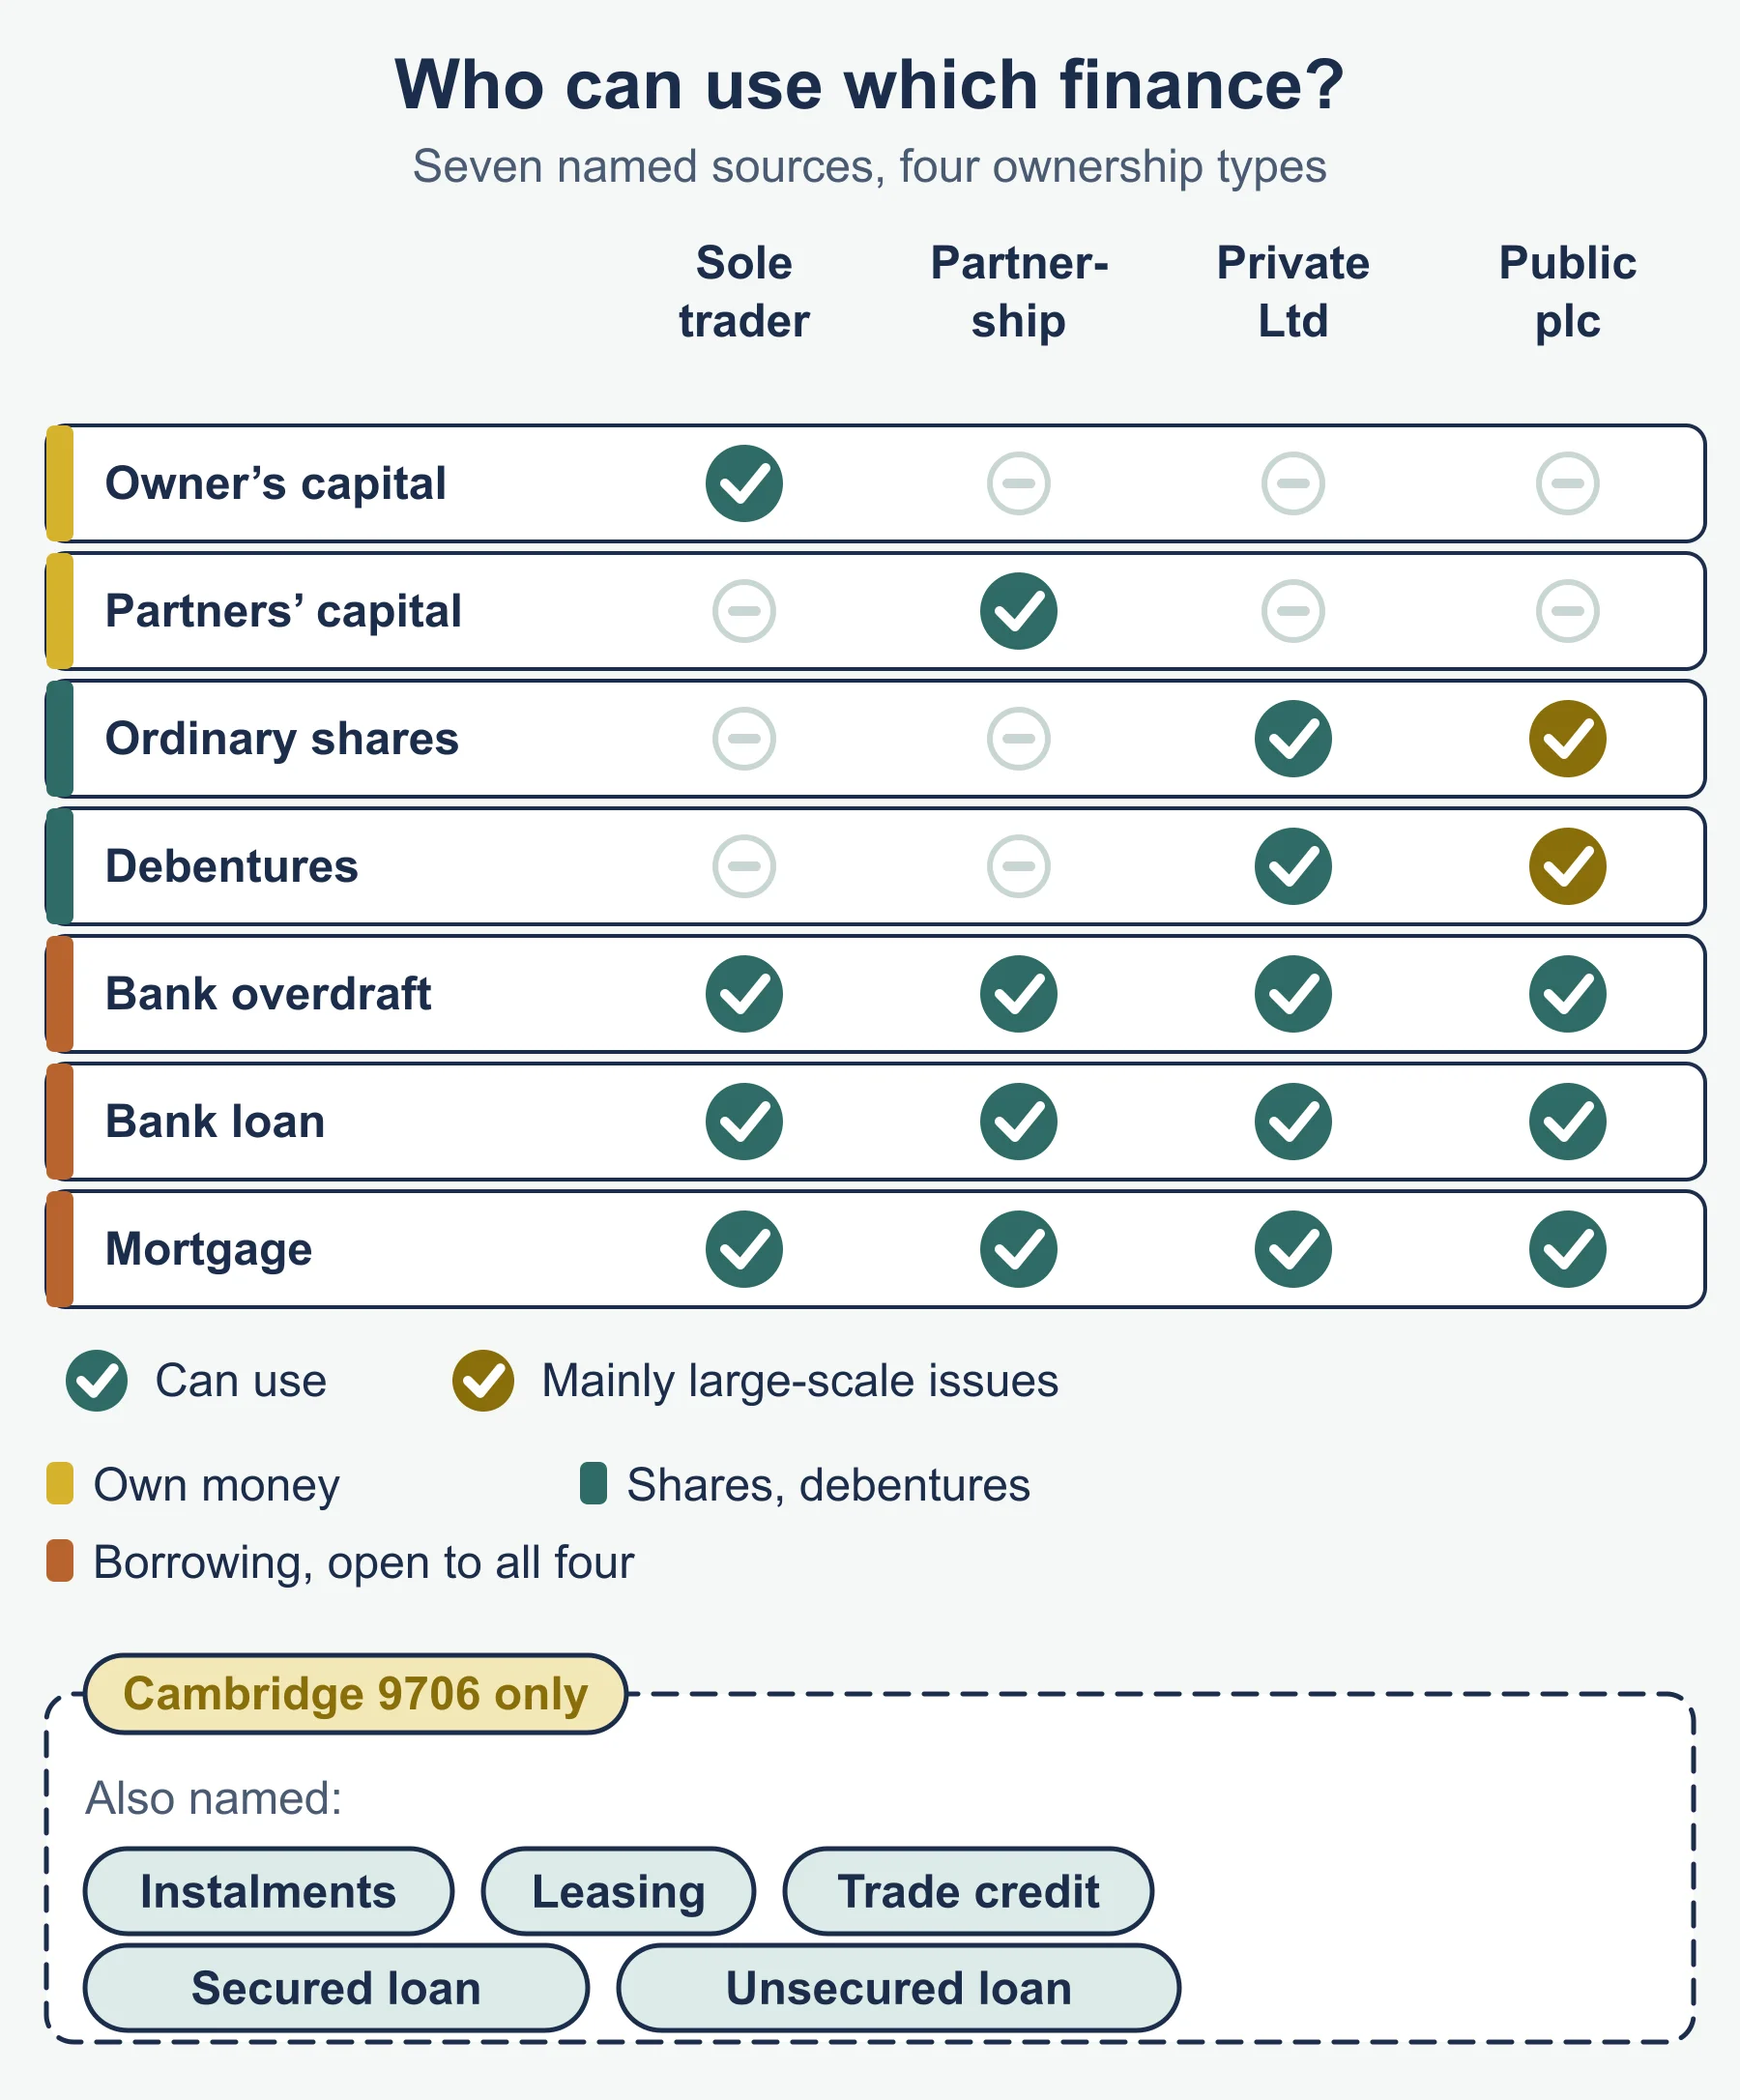
| Sole trader | One owner, unlimited liability | Own savings, loans, retained profit; owner keeps all profit | both |
| Partnership | Two or more owners, usually unlimited liability | Partners’ capital; profit shared | 9725 |
| Private limited company (Ltd) | Shareholders with limited liability; shares not sold to the public | Can sell shares privately; dividends | both |
| Public limited company (plc) | Limited liability; shares can be bought by the public | Large sums from share issues; dividends | both |
| Social enterprise, charity or other non-profit | Social aim first; surplus reinvested | Grants, donations, trading income | both |
| Co-operative | Owned by members | Members’ capital; profit shared among members | 9625 |
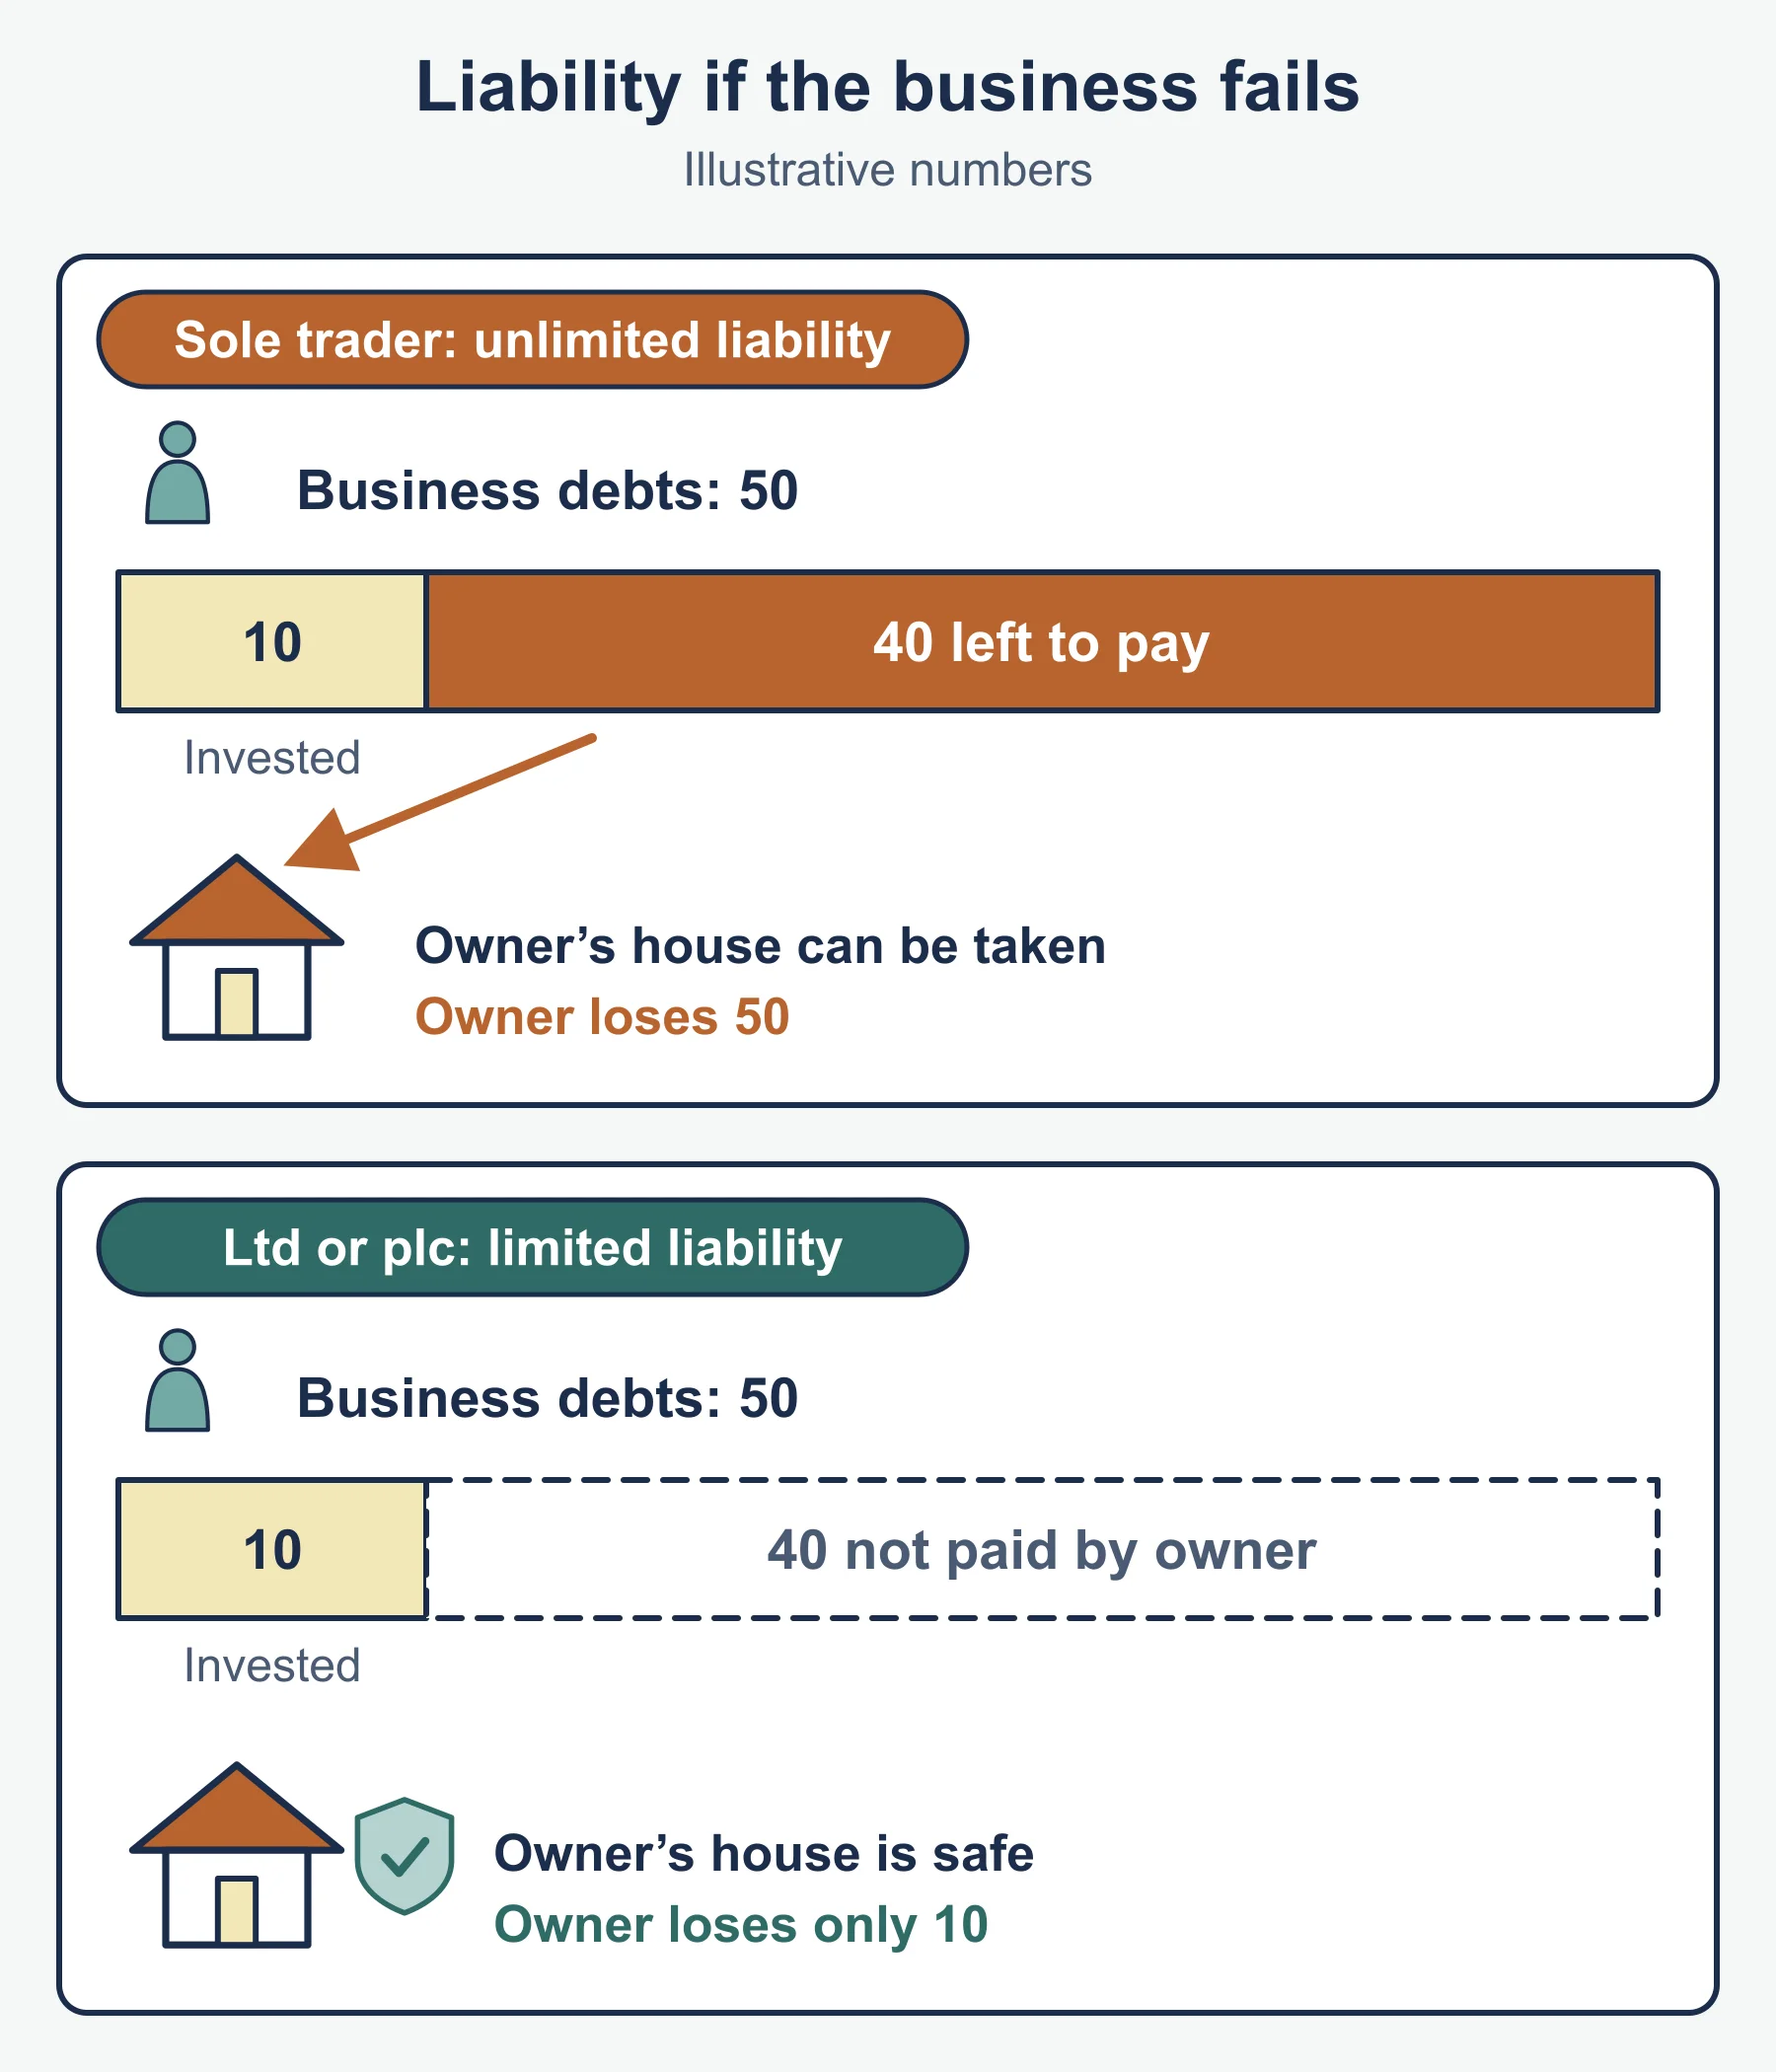
Unlimited liability means the owner’s own assets can be called on to settle business debts. Limited liability means shareholders risk no more than the money they put in.
Compare forms using: objectives, finance, distribution of profits and liability (both), and control (9725).
Reasons for choosing or changing form: wanting full control, protecting personal assets, needing more capital, planning growth, or seeking social impact. A fast-growing sole trader may become a Ltd to limit liability and attract investors. A Ltd may become a plc to raise large sums, but accepts more regulation, public accounts and takeover risk.
Advantages and disadvantages. Sole trader: easy to start, full control and profit, but unlimited liability and limited funds. Partnership: more capital and skills, but disagreements and unlimited liability. Ltd: limited liability, but less control and shared profit. plc: large funds, but loss of control, scrutiny and short-term pressure. Social enterprise: purpose and goodwill, but lower profit and harder fund-raising.
Private sector organisations belong to individuals or shareholders. Public sector organisations are government-owned and government-run. Objectives differ: profit versus public service. A public limited company is private sector.
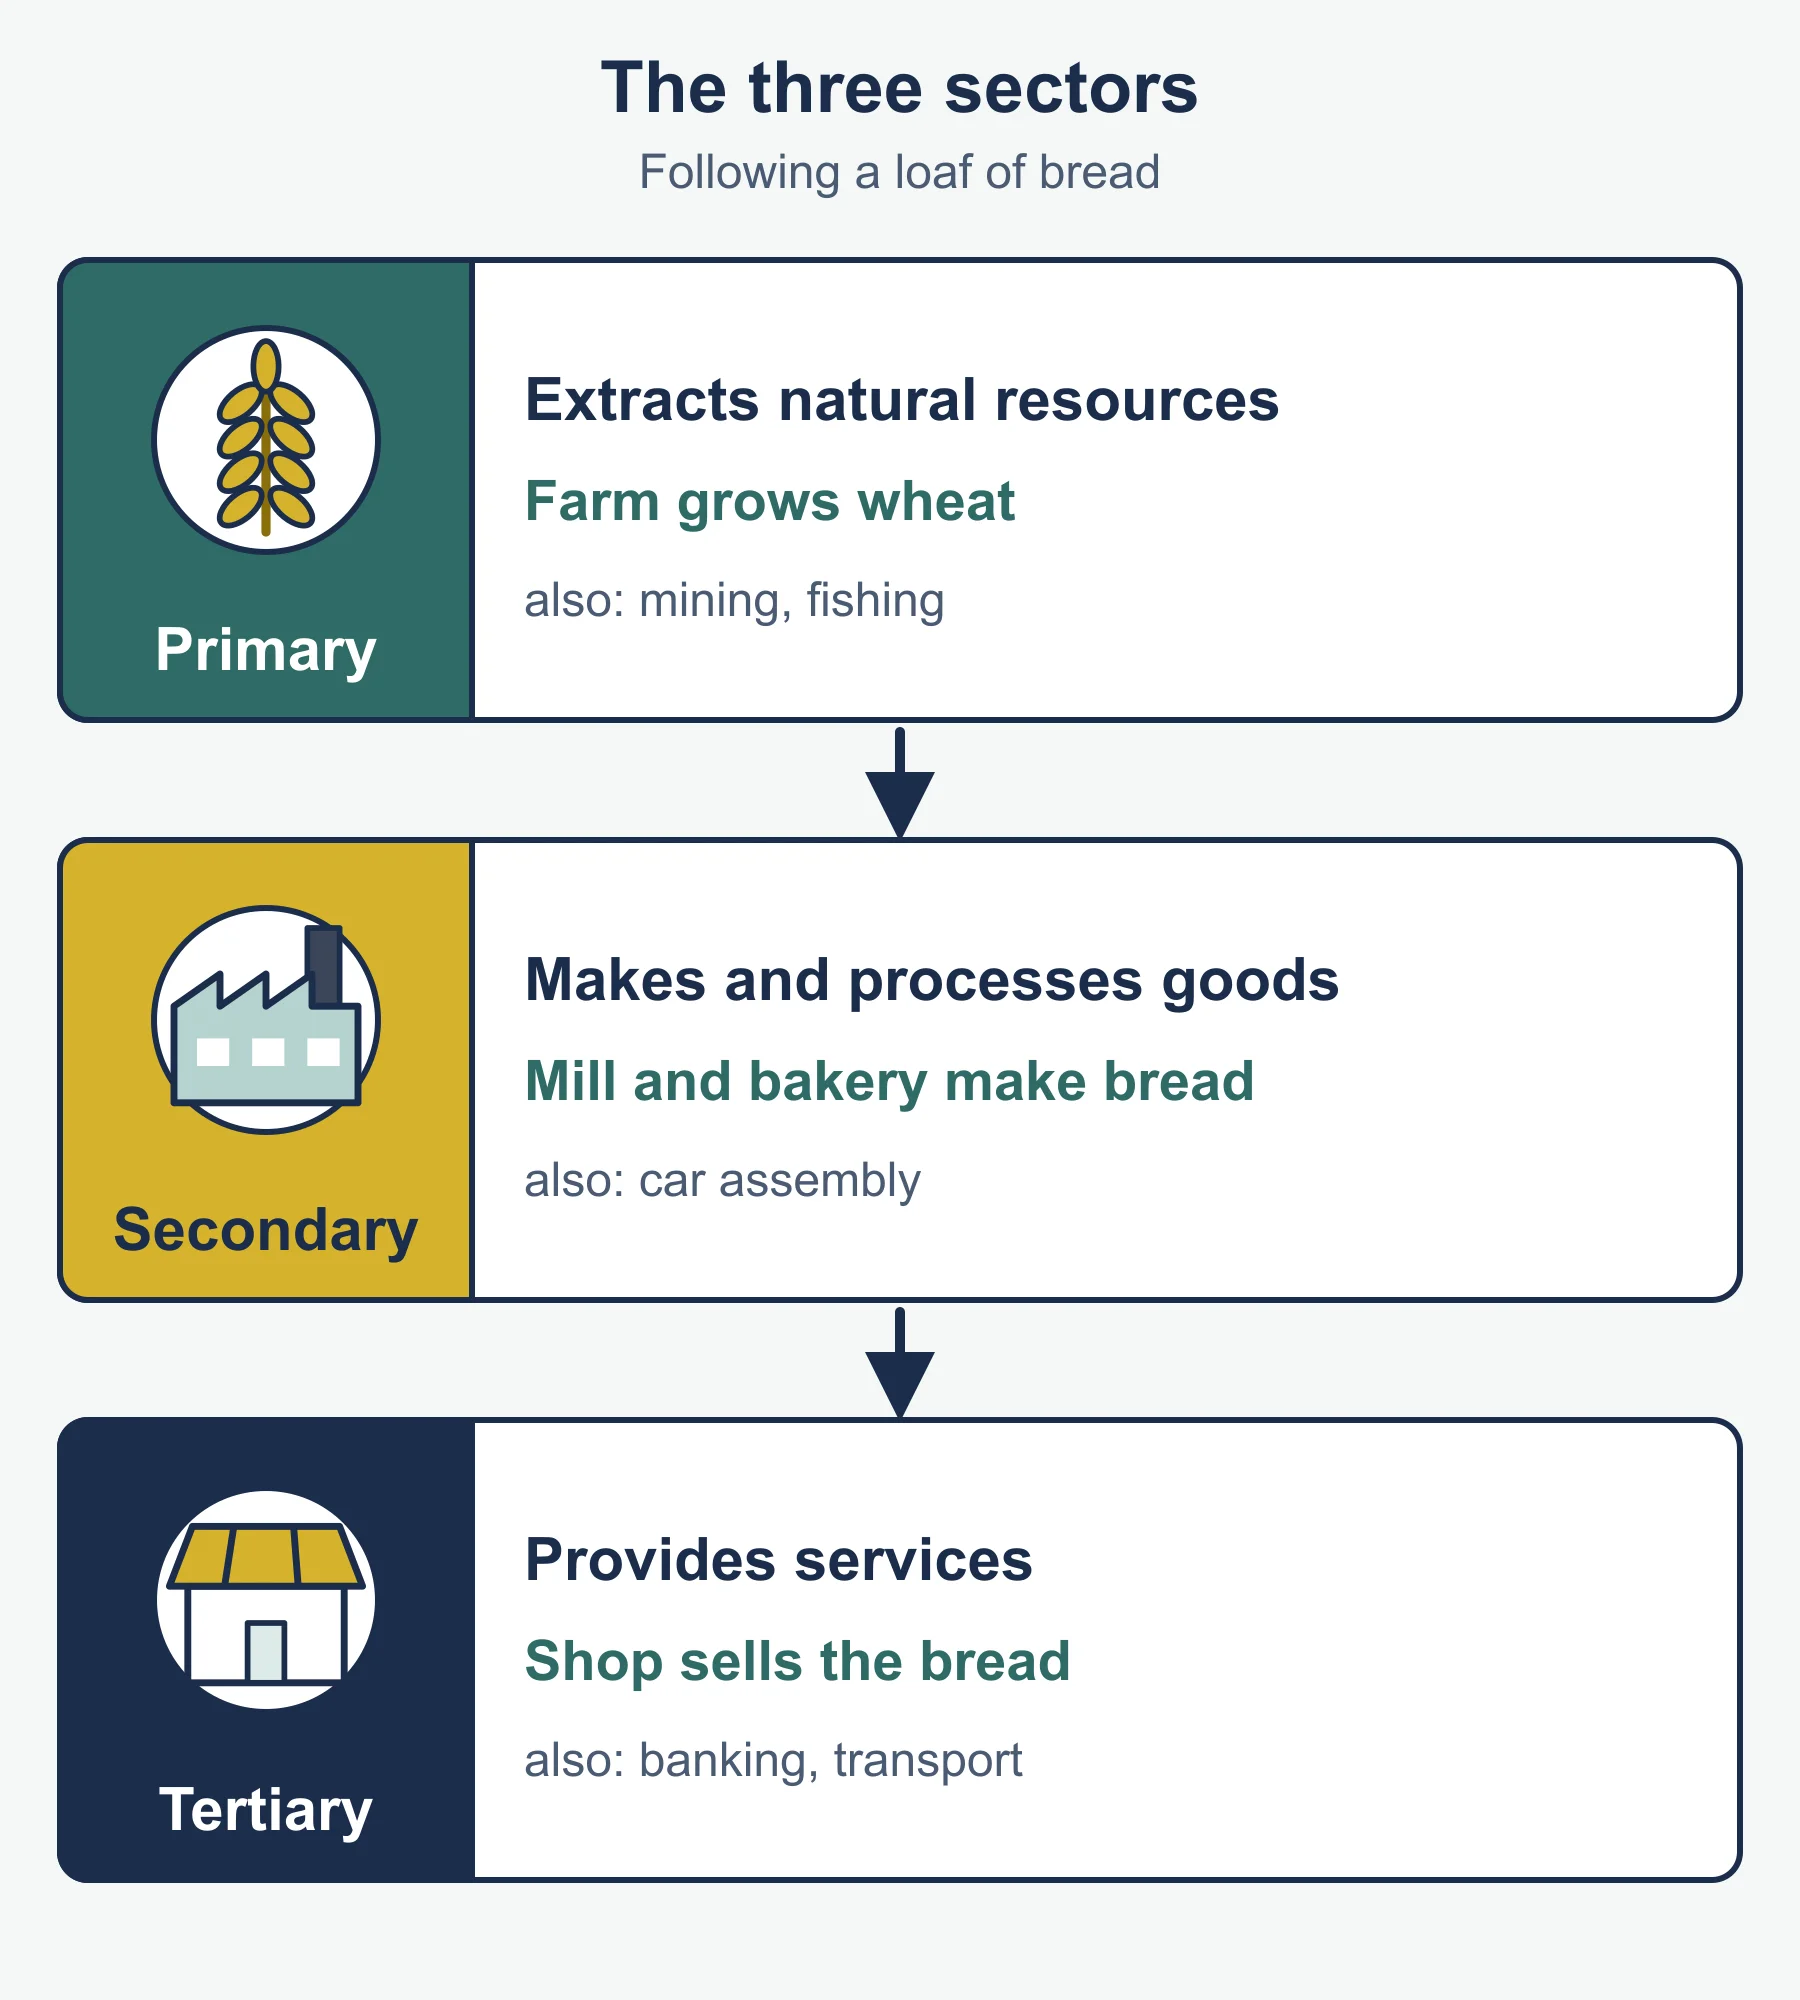
Sectors. Primary extracts natural resources (farming, mining). Secondary makes or builds (manufacturing, construction). Tertiary provides services (retail, banking, teaching).
Influences on the business population (9625, our wording): the economy, ease of raising finance, regulation, attitudes to risk and skills.
Family business (both): advantages are loyalty, shared values, long-term thinking and quick decisions. Disadvantages are conflict, limited finance and skills, and difficult succession. Small business: flexible, personal service and close customer contact, but limited finance, little buying power and weaker brand. In 9625 you also compare small and medium-sized enterprises (SMEs) with large businesses, which gain economies of scale, finance and market power but can be slower and less personal.
Shareholders (both)
Shareholders invest to receive dividends (a share of profit paid out), to gain if the share price rises, and sometimes for a say in decisions or because they back the business’s aims. Share capital (equity) is the money raised by selling shares. Ordinary shares usually carry votes and a dividend that varies with profit (standard definition).
Influences on share price: company profit and forecasts, dividends, the economy, interest rates, rival performance, news and rumours, and supply and demand for the shares. Rises help shareholders and the firm’s ability to raise capital; falls can bring takeover risk.
Standard forms (9725 asks for all three calculations; 9625 names yield calculation and market capitalisation):
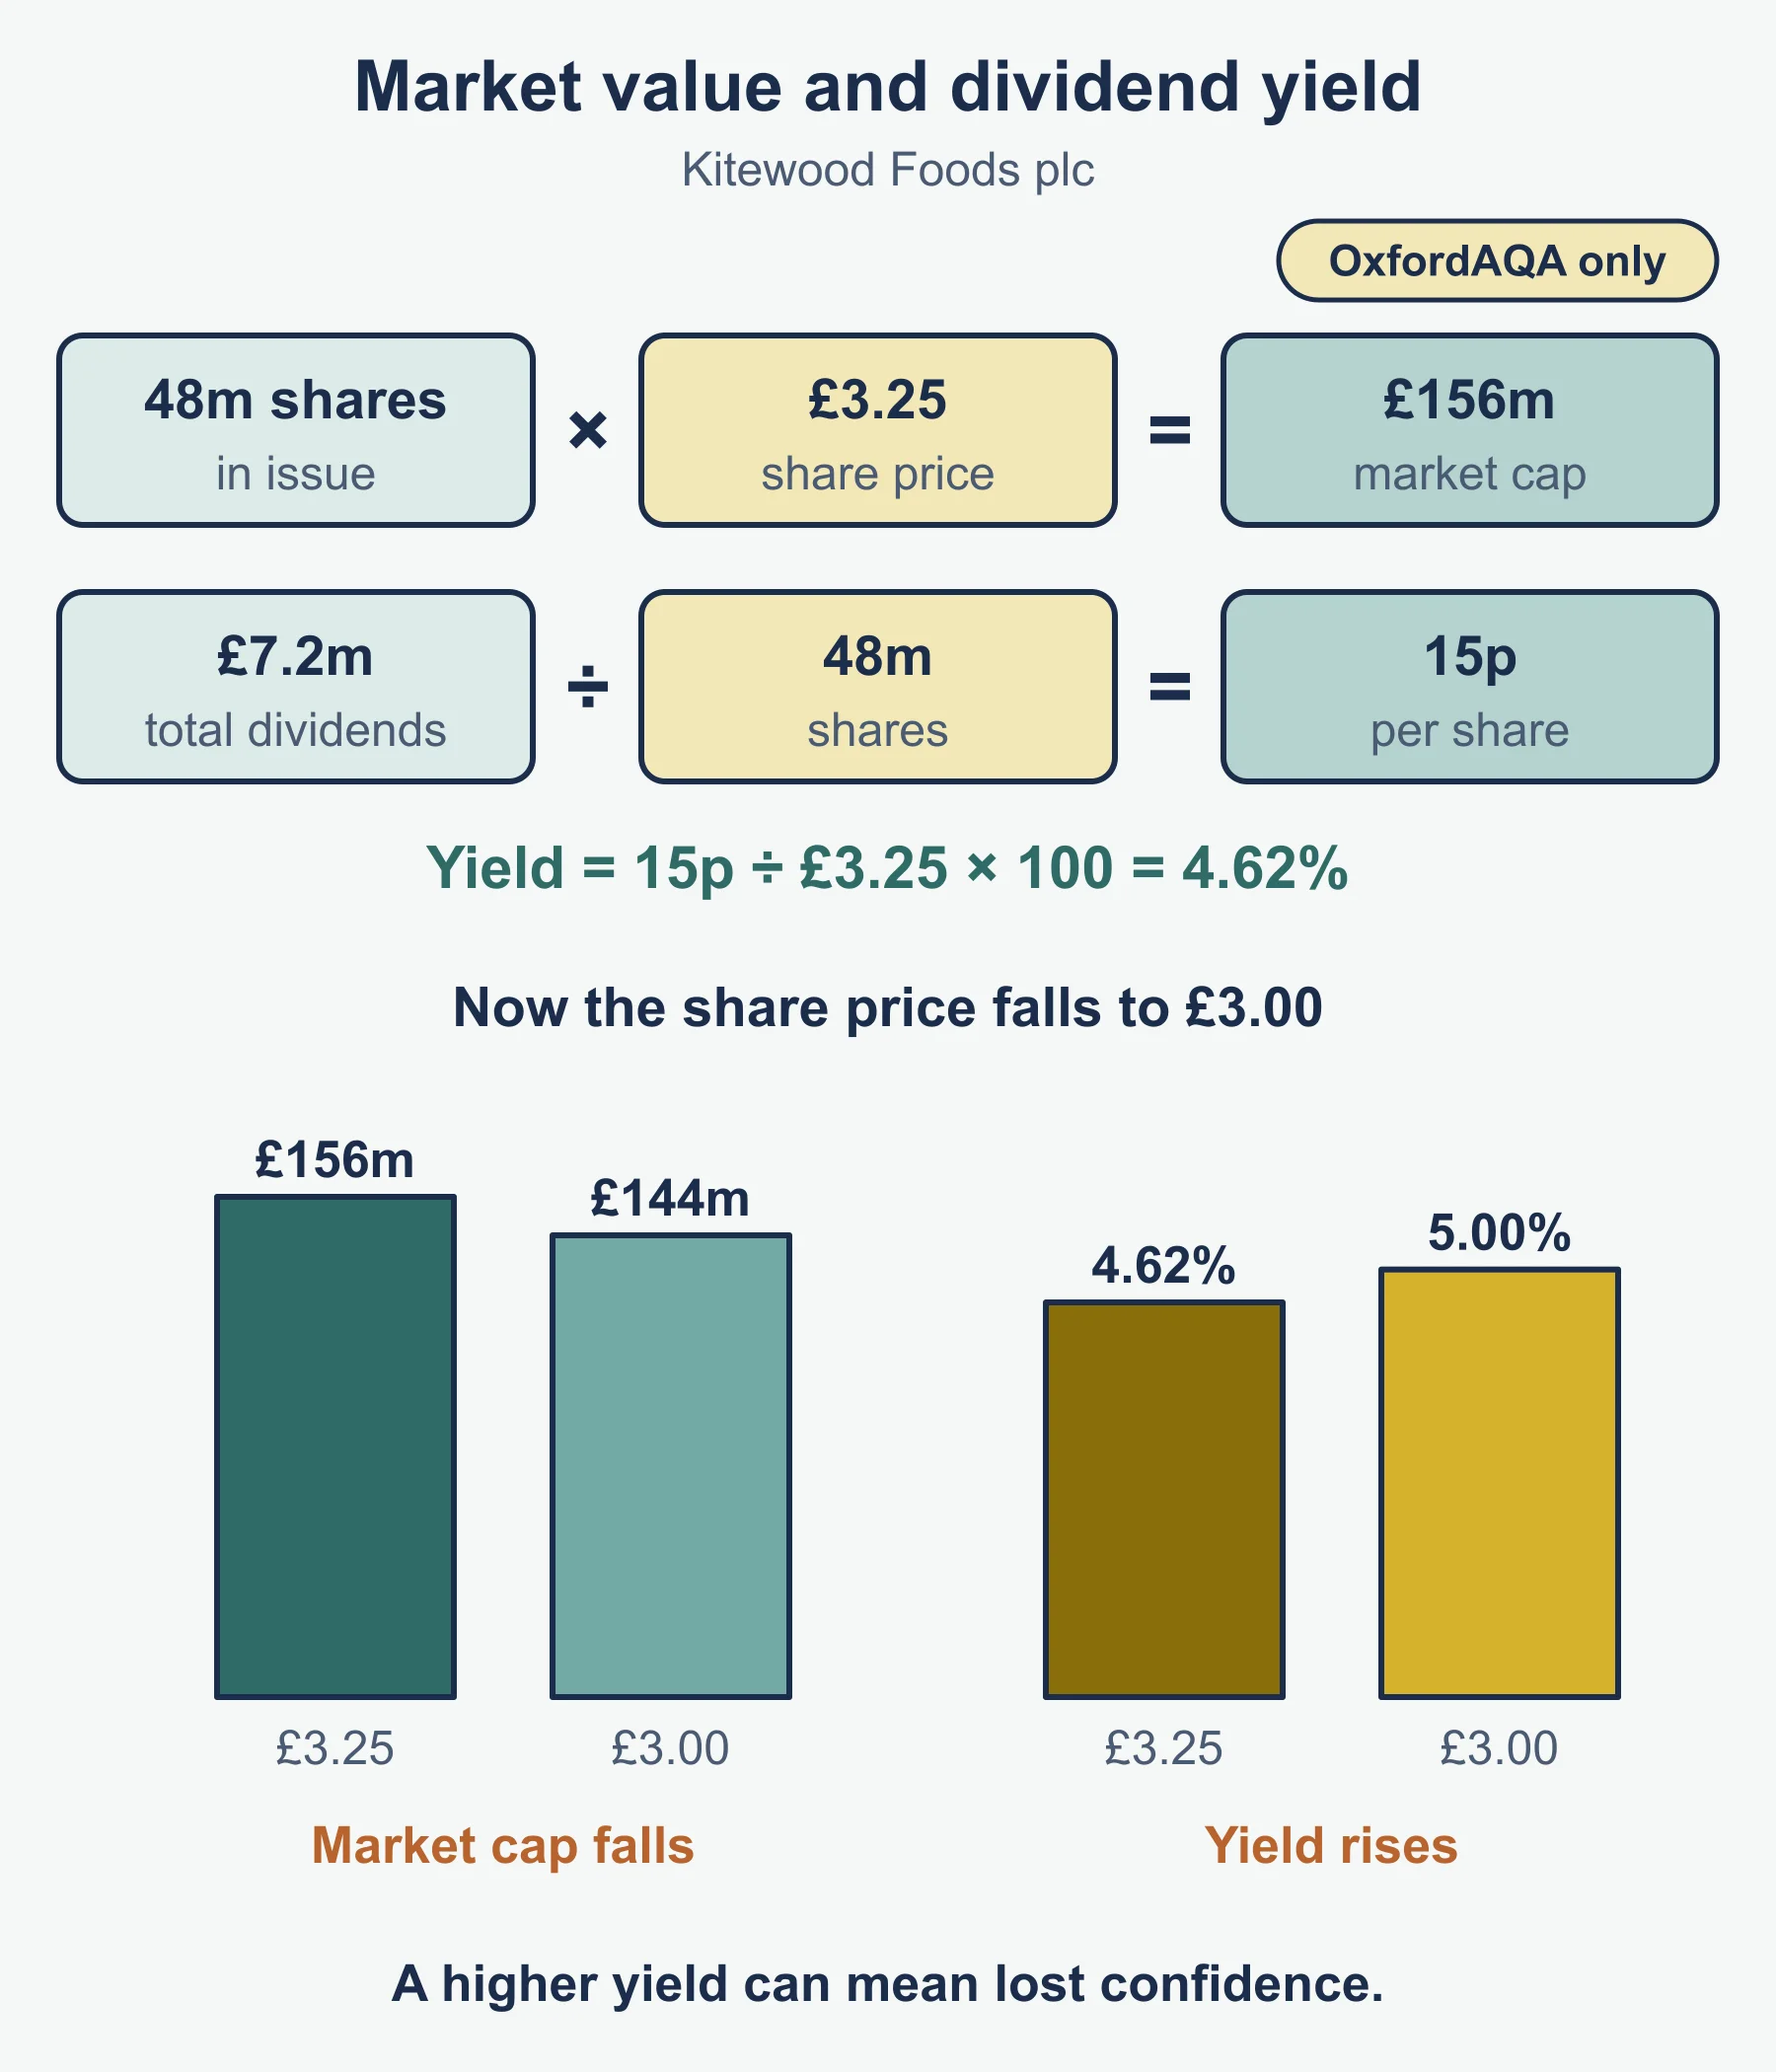
Dividend per share = total dividend / number of shares
Dividend yield (%) = dividend per share / share price x 100
Market capitalisation = share price x number of shares issued
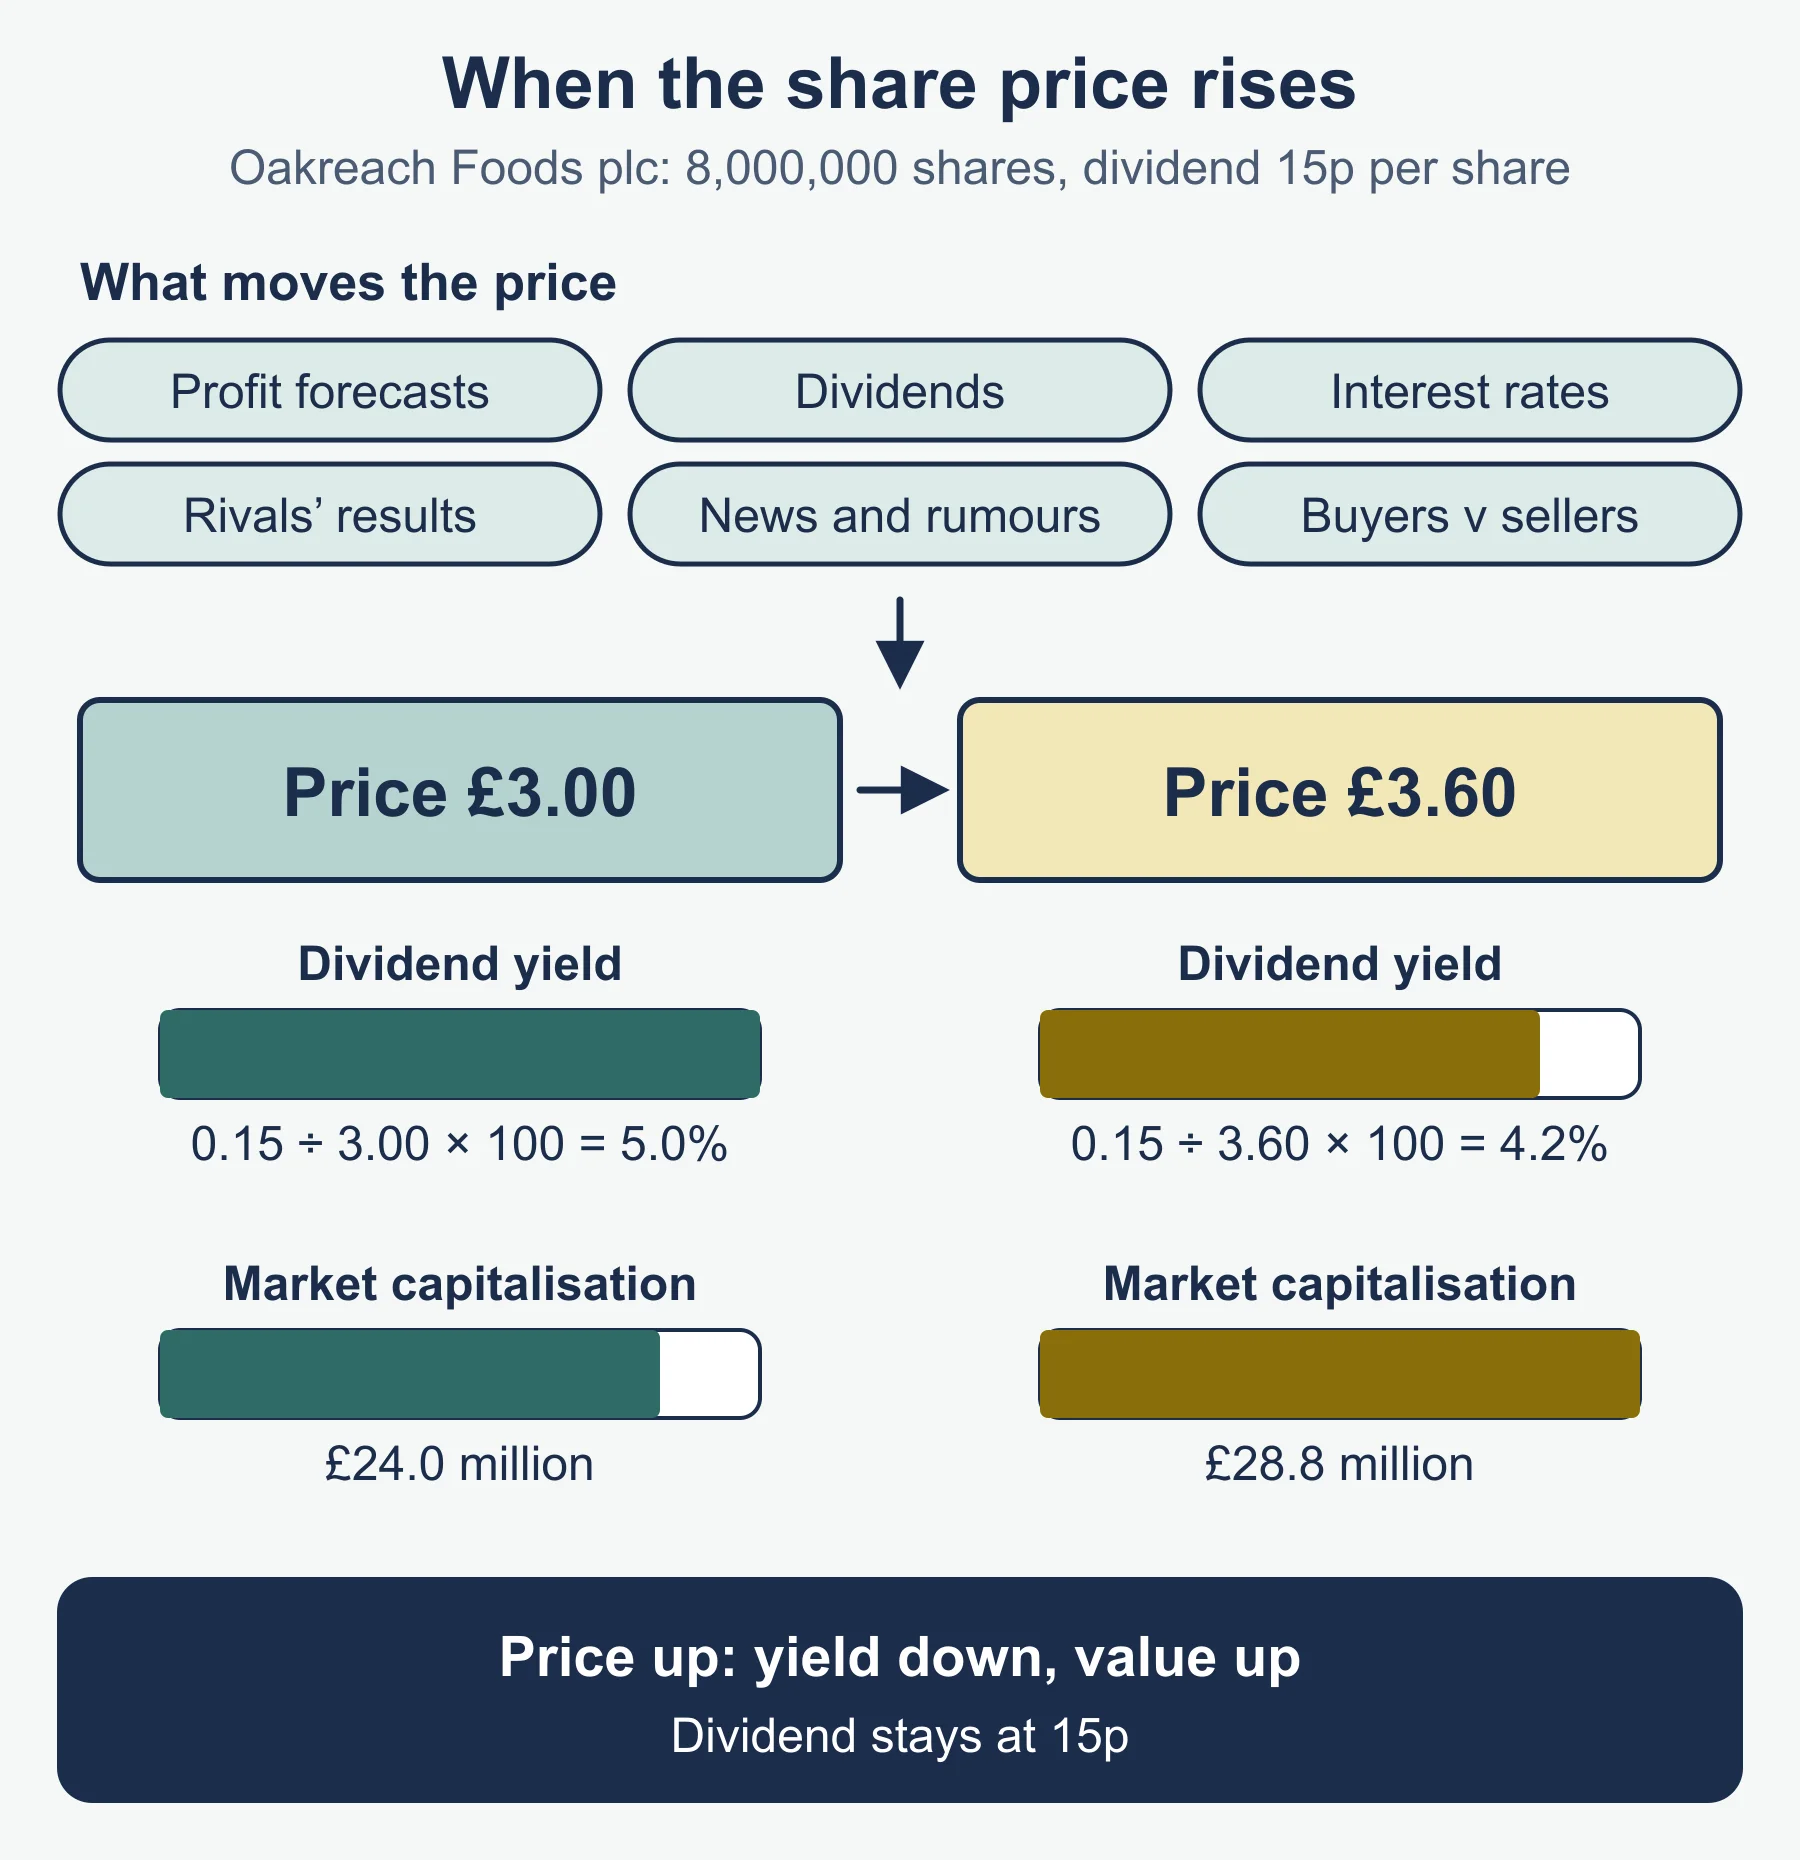
Worked example. Oakreach Foods plc has 8,000,000 ordinary shares, pays a total dividend of £1,200,000, and its share price is £3.00.
Dividend per share = 1,200,000 / 8,000,000 = £0.15 (15p)
Dividend yield = 0.15 / 3.00 x 100 = 5%
Market capitalisation = 3.00 x 8,000,000 = £24,000,000
If the price rises to £3.60 and the dividend stays at 15p, the yield falls to 0.15 / 3.60 x 100 = 4.2% (1 d.p.) and market capitalisation rises to £28,800,000.
Stakeholders (both)
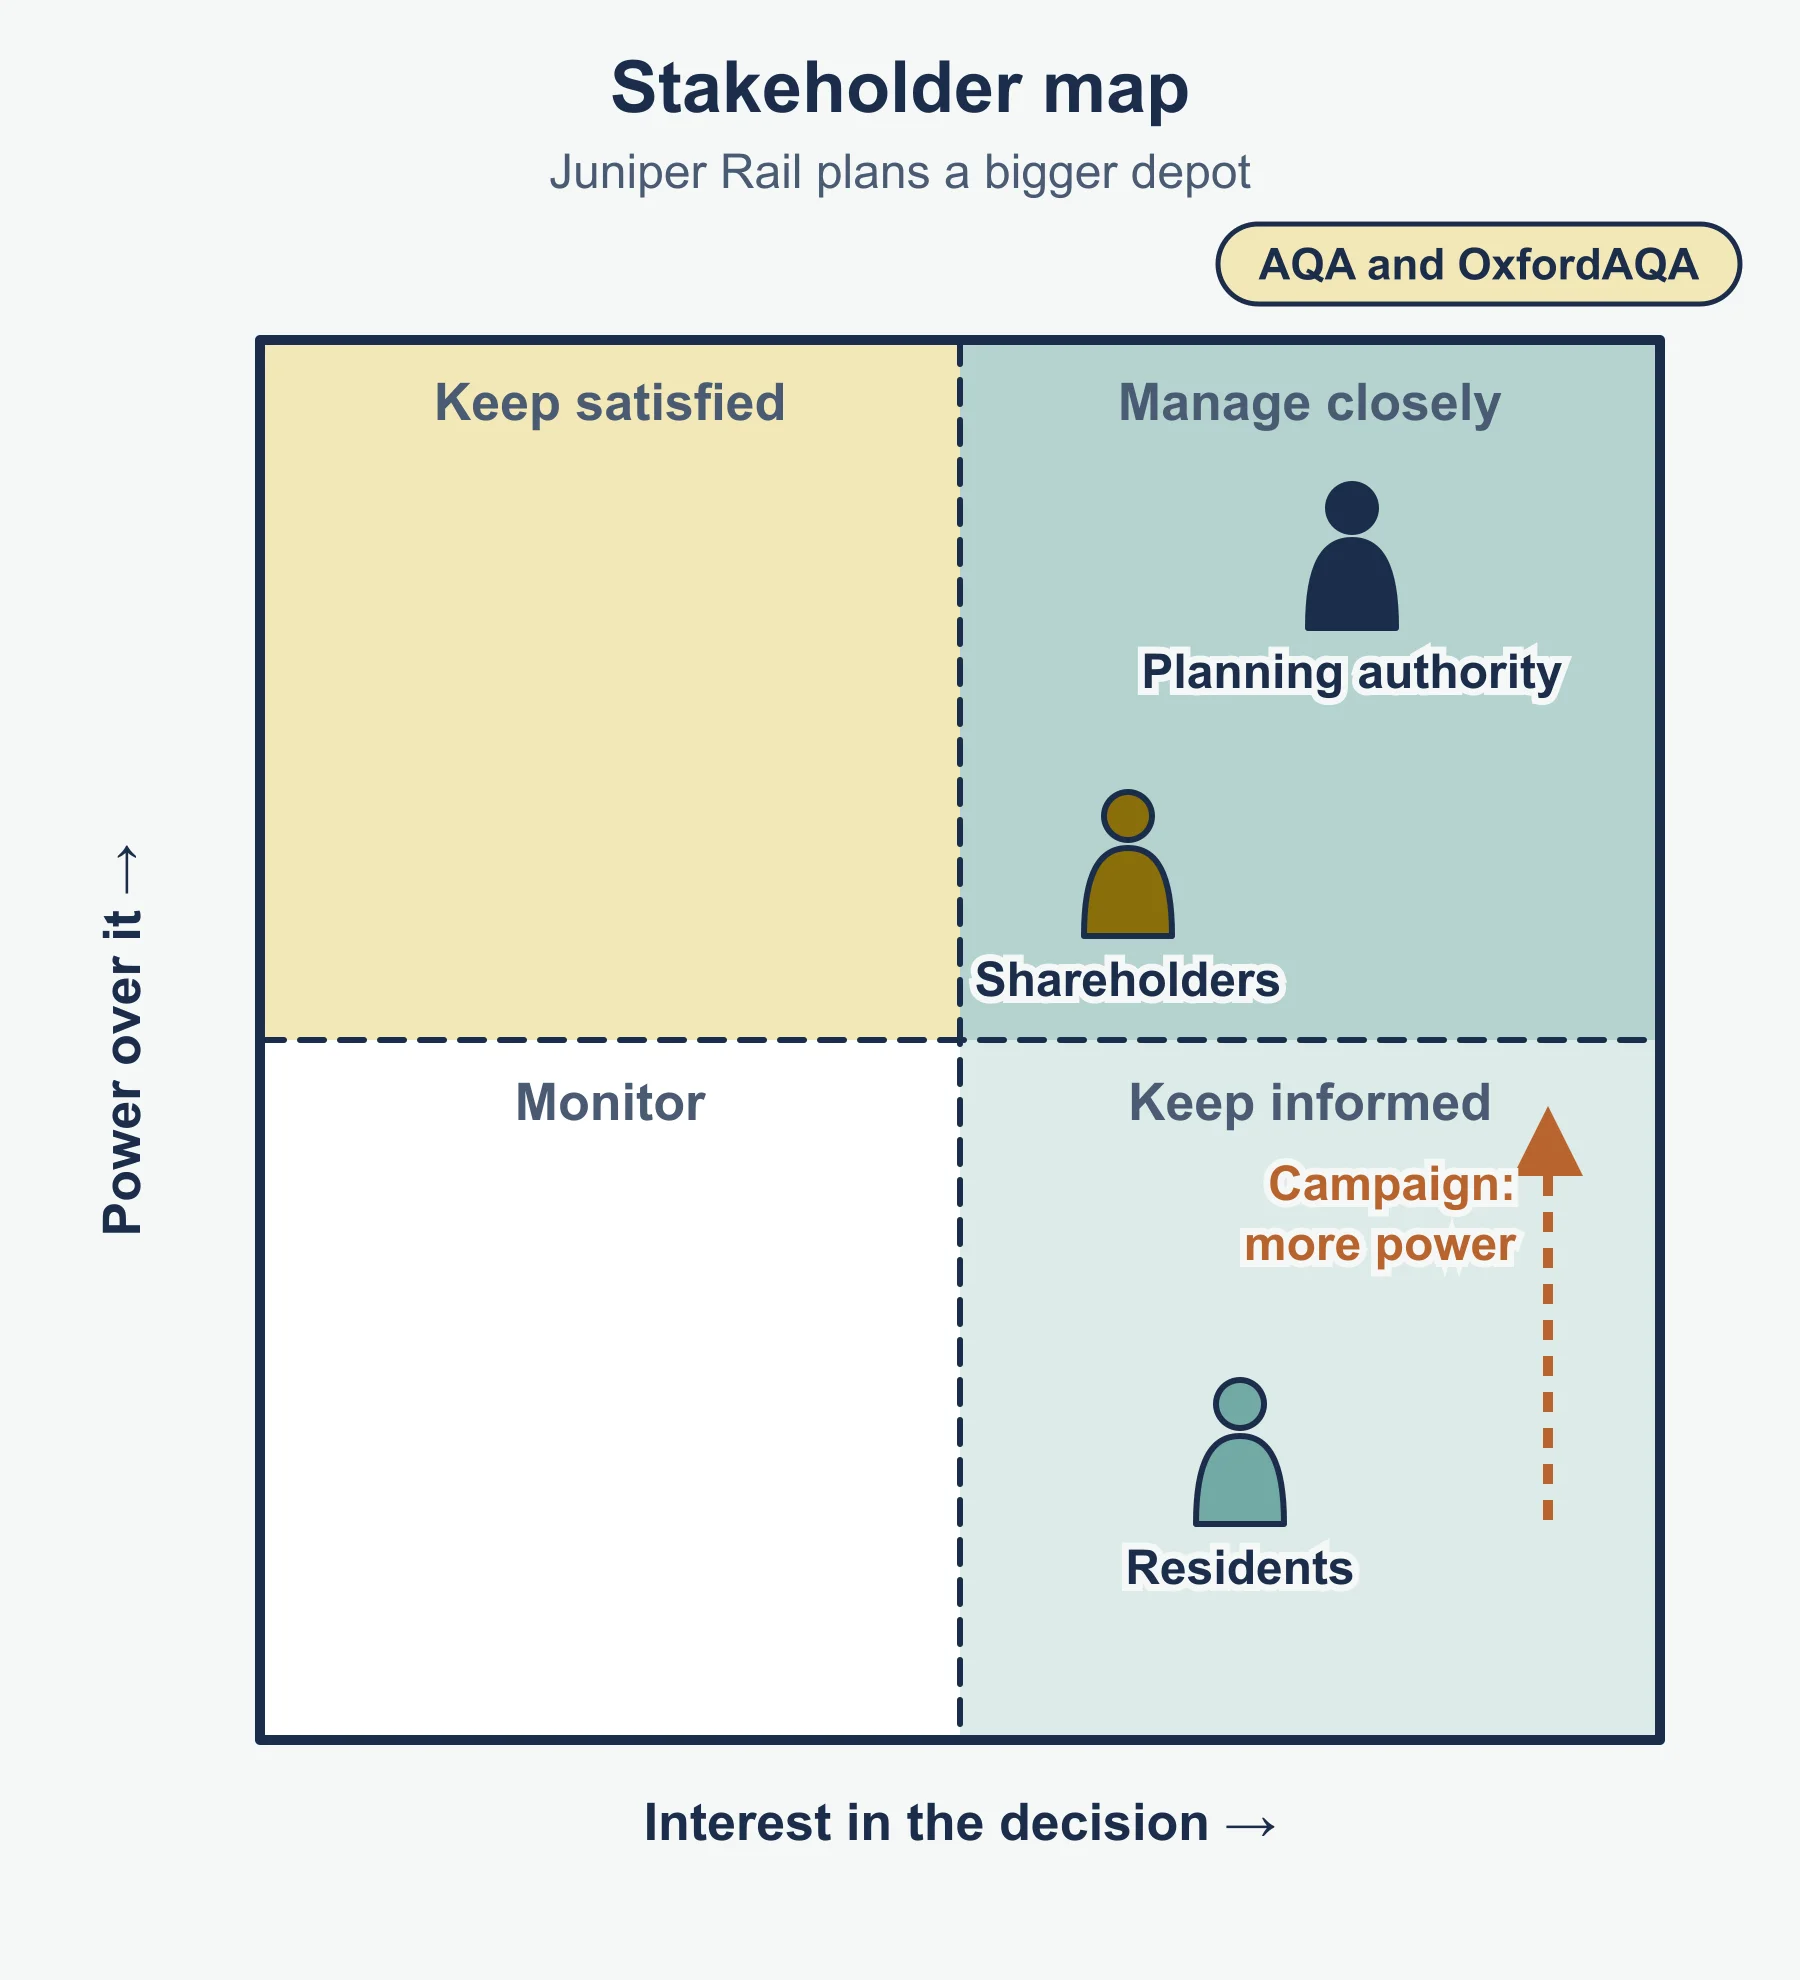
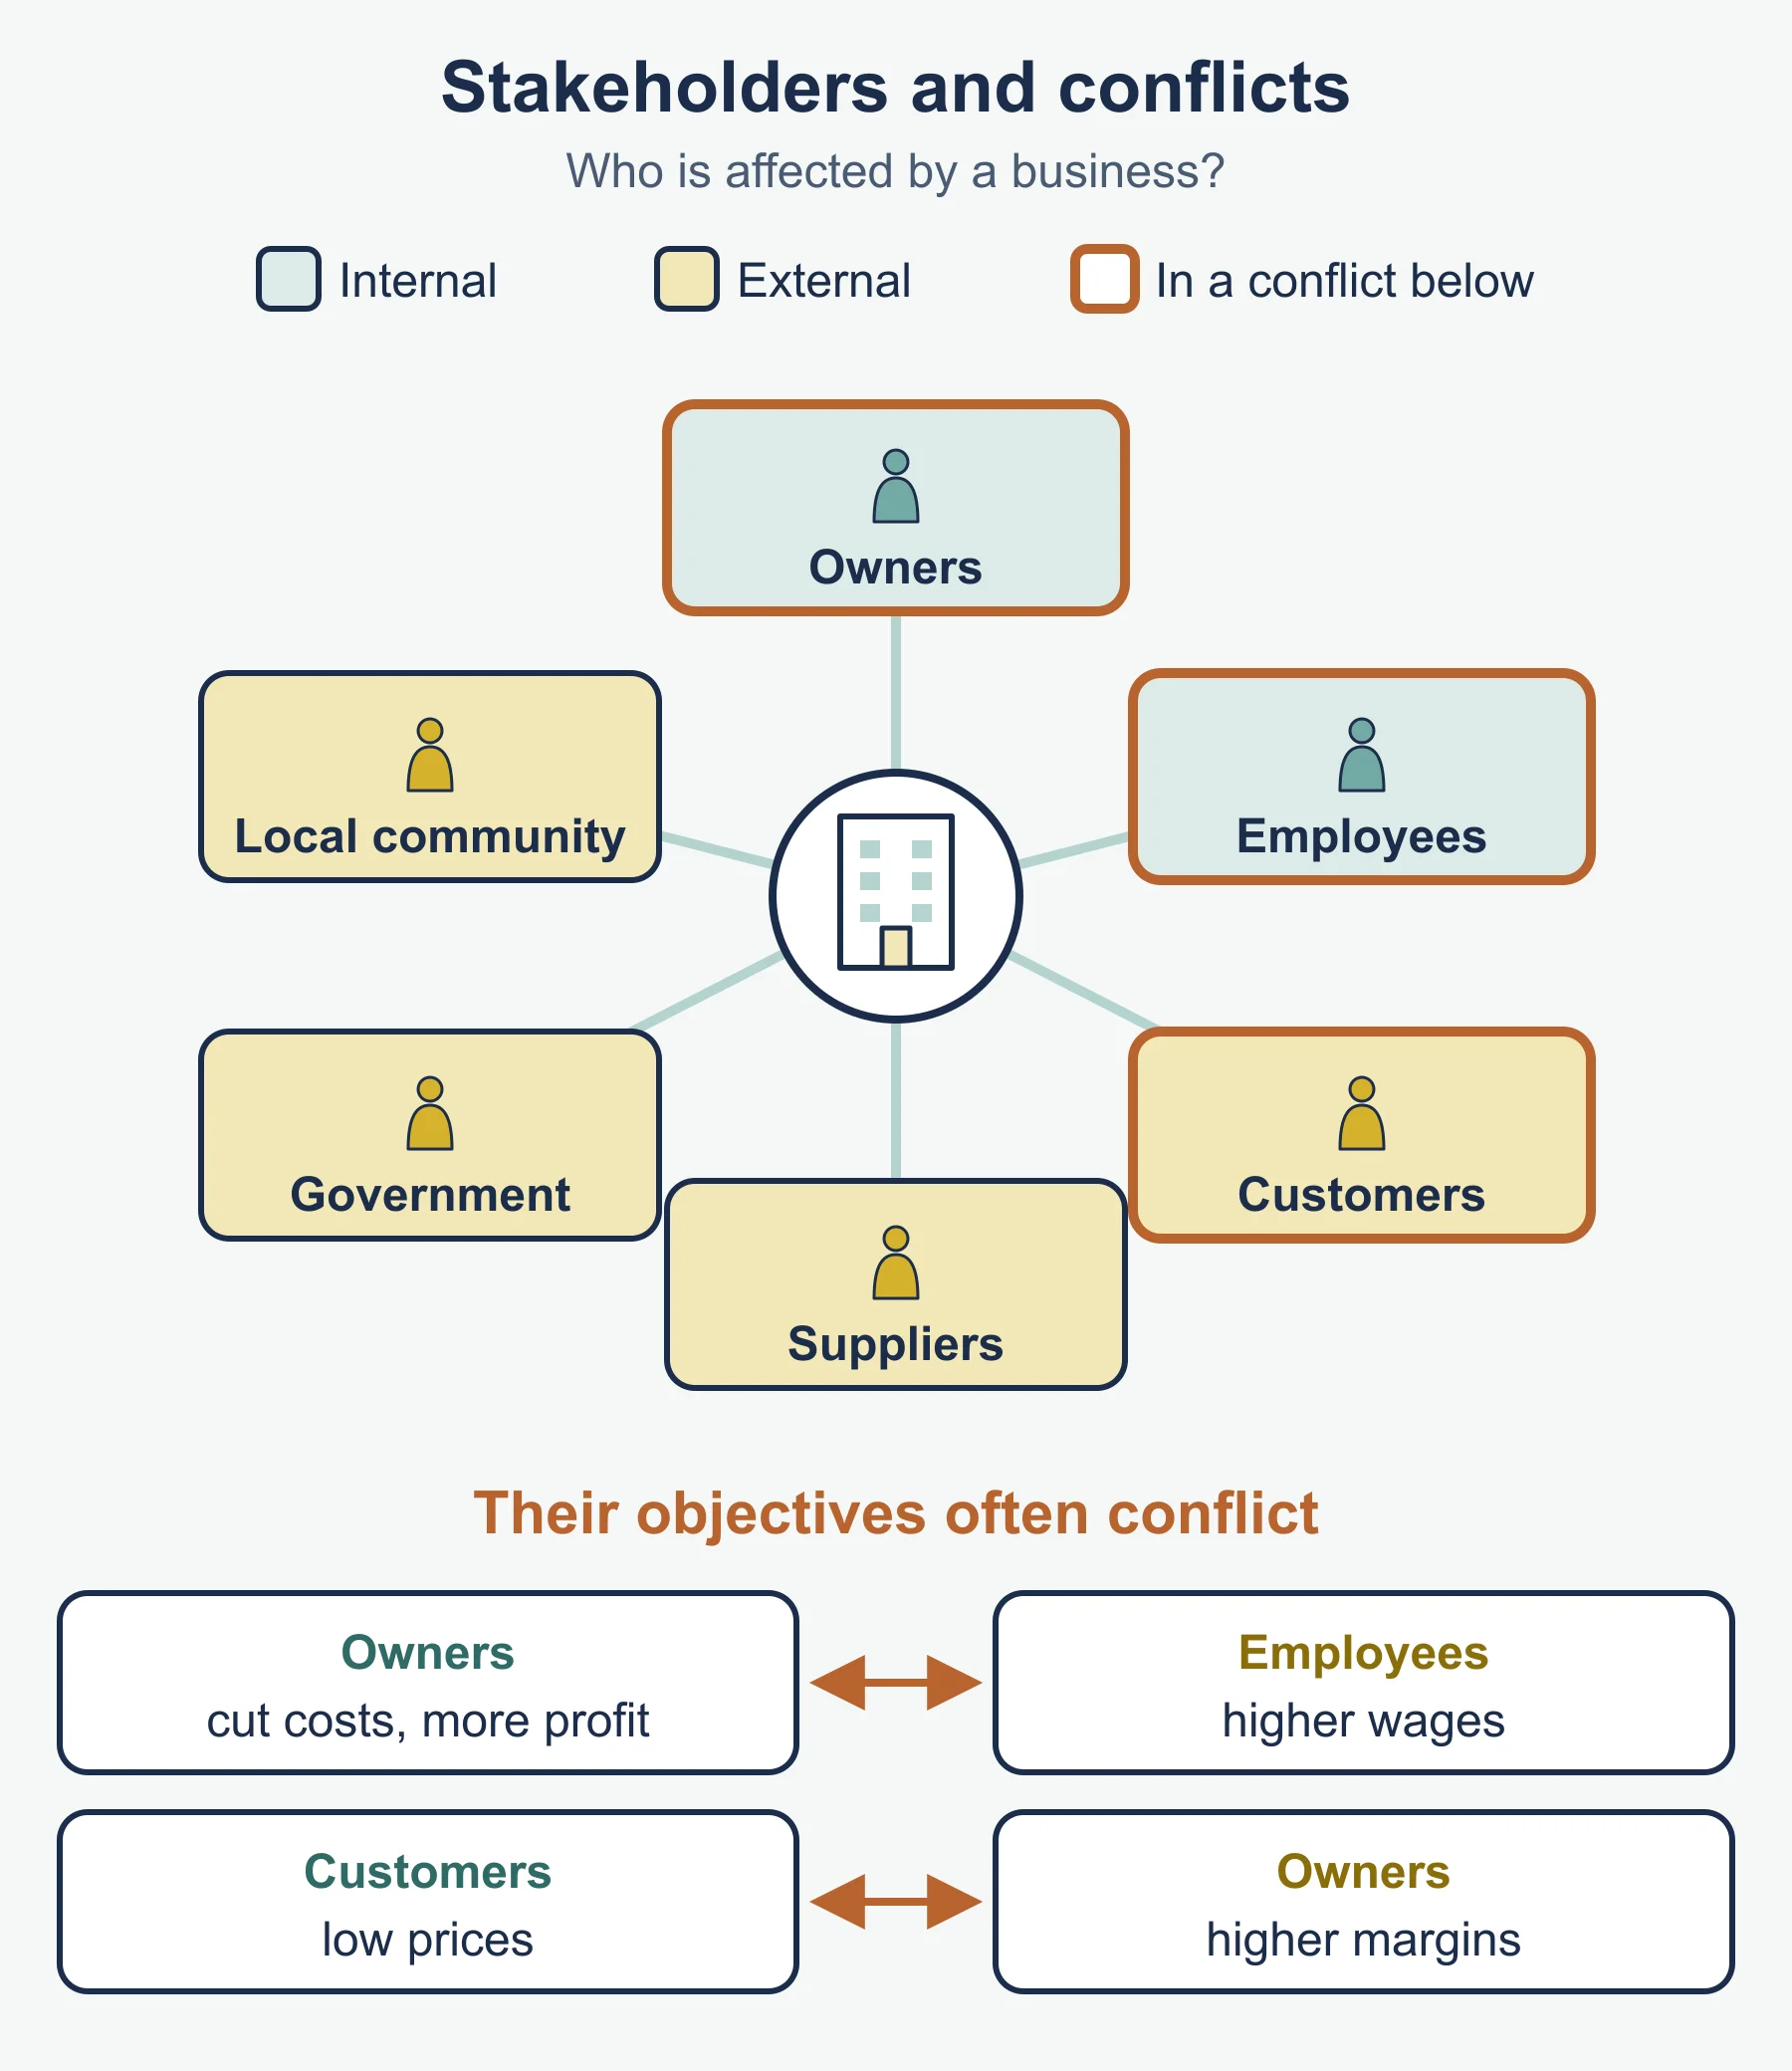
Internal: owners and shareholders, employees. External: customers, suppliers, the community, the government and, in 9725, creditors (those owed money by the firm). Stakeholders have different interests: shareholders want returns, employees want pay and security, suppliers want prompt payment, the community wants jobs without disruption, the government wants tax and legal compliance. To show the impact of business activity, name the stakeholder, the change and the effect.
Common errors
- Writing “limited liability means limited debts”. The firm owes the whole debt, but the shareholder’s loss is limited.
- Confusing a public limited company with the public sector.
- Stopping a decision-tree answer at expected value, without taking off the cost.
- Using partnerships in a 9625 answer, or co-operatives in a 9725 answer, without checking your specification.
Frequently asked questions
What does SMART stand for in OxfordAQA 9725? The 9725 text spells SMART out as Specific, Measurable, Accountable, Realistic and Time specific. An objective such as raising sales by a set percentage by a set date, owned by a named manager, can be checked.
What are the key elements of a business plan in 9725? The 9725 key elements are ownership, objectives, target market and market analysis, competitor analysis, unique selling point (USP) and financial analysis.
What are the primary, secondary and tertiary sectors? The primary sector extracts natural resources, such as farming and mining. The secondary sector makes or builds things, such as manufacturing and construction, and the tertiary sector provides services, such as retail, banking and teaching.
What are the advantages and disadvantages of a family business? A family business can benefit from loyalty, shared values, long-term thinking and quick decisions. Its disadvantages include conflict, limited finance and skills, and difficult succession.
Why do people buy shares? Shareholders invest to receive dividends, which are a share of profit paid out, to gain if the share price rises, and sometimes for a say in decisions or because they back the business’s aims.
Official syllabus
OxfordAQA International AS and A-level Business (9625), Version 3.1, first AS exams May/June 2019 and first A-level exams May/June 2020; and OxfordAQA International AS and A-level Business (9725), Version 1.1, first AS exams May/June 2027 and first A-level exams May/June 2028. Publisher: OxfordAQA. Sections 3.1.1.1 and 3.1.1.2.
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
OxfordAQA A-Level Business: The nature and purpose of business and Types of business ownership (9625/9725) – Practice Questions
Original practice questions with worked answers on OxfordAQA International AS Business 3.1.1.1 and 3.1.1.2: objectives, trees, ownership, shares.
Business · OxfordAQA · AS Level
Try questions -
Revision notes
OxfordAQA A-Level Business: The nature and purpose of business and Types of business ownership (9625/9725) – Revision Notes
Condensed OxfordAQA International AS Business notes on 3.1.1.1 and 3.1.1.2: formulas, ownership table, key distinctions and a checked self-test.
Business · OxfordAQA · AS Level
Revise topic -
Study guides
OxfordAQA A-Level Business: The external environment (9625/9725)
A worked study guide to market conditions, barriers to entry, and the effects of incomes, interest and exchange rates, input costs and competition.
Business · OxfordAQA · AS Level
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business AS LEVEL?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
OxfordAQA Business teachers at Marlbridge
