
Study Guides
IGCSE Business: Analysis of accounts (Cambridge 0264)
Study guide to analysis of accounts for Cambridge IGCSE Business 0264: profitability and liquidity ratios, users of accounts and the limits of ratios.
- Subject
- Business
- Level
- IGCSE
- Topic
- Financial information and decisions
- Author
- Marlbridge Academic Team
- Updated
- Reviewed by
- Salman Ahmad (what this means)
Aligned to Cambridge IGCSE Business (0264), For examination in 2027, 2028 and 2029. Official specification .
Syllabus page (what it covers and how it is assessed): Cambridge IGCSE Business.
Syllabus points this page covers
0264
- 5.5 Analysis of accounts
Found an error? Report a correction.
Need help with this topic? Request a free trial class for IGCSE Business (0450 / 0264).
This guide covers section 5.5 (Analysis of accounts: profitability, liquidity and users of accounts) of the Cambridge IGCSE Business 0264 syllabus for examination in 2027, 2028 and 2029. All candidates take Paper 1 (Short Answer and Data Response) and Paper 2 (Case Study), and both papers are based on all the subject content. So ratios can turn up in stimulus material or in a case study appendix, not only as a stand-alone calculation. Track your progress with the course hub and the printable checklist. Then test yourself with the revision notes and the practice questions. To find weak spots first, try the free diagnostics.
All businesses and people here are invented. Money figures are in dollars.
What this topic covers
| Syllabus point | Skills needed |
|---|---|
| 5.5.1 Profitability | Explain what profitability means. Work out and comment on gross profit margin, profit margin and return on capital employed (ROCE). |
| 5.5.2 Liquidity | Explain what liquidity means. Work out and comment on the current ratio and the acid test ratio. |
| 5.5.3 Users of accounts | Name internal users (owners, managers, employees) and external users (suppliers, government, lenders/banks). Show how they use accounts and ratios to decide, for example whether to lend to or invest in a business. State the limitations of accounts and ratio analysis. |
The syllabus names the ratios but gives no formulas for them. The formulas below are the standard forms. The inputs come from topics 5.3 and 5.4: the statement of profit or loss (revenue, cost of sales, gross profit, expenses, profit) and the statement of financial position (non-current and current assets, current and non-current liabilities, capital employed). The notes to those topics say you will not be assessed on constructing either statement, so in this topic the figures are normally supplied and your job is to calculate, interpret and decide.
Profitability (5.5.1)
Profitability is how well a business turns its sales or its capital into profit. A business can have high profit and poor profitability, because profit alone ignores the size of the business. A shop making 40,000 profit on 100,000 of revenue is doing something very different from one making 40,000 on 2,000,000. Ratios put profit in proportion, so you can compare one year with another, or one business with another.
The three profitability ratios
| Ratio | Standard form | Shows |
|---|---|---|
| Gross profit margin | (gross profit / revenue) × 100 | Profit left from each 100 of revenue after paying for the goods or services sold |
| Profit margin | (profit / revenue) × 100 | Profit kept from each 100 of revenue once every expense is paid |
| ROCE | (profit / capital employed) × 100 | Profit earned for each 100 of long-term money invested in the business |
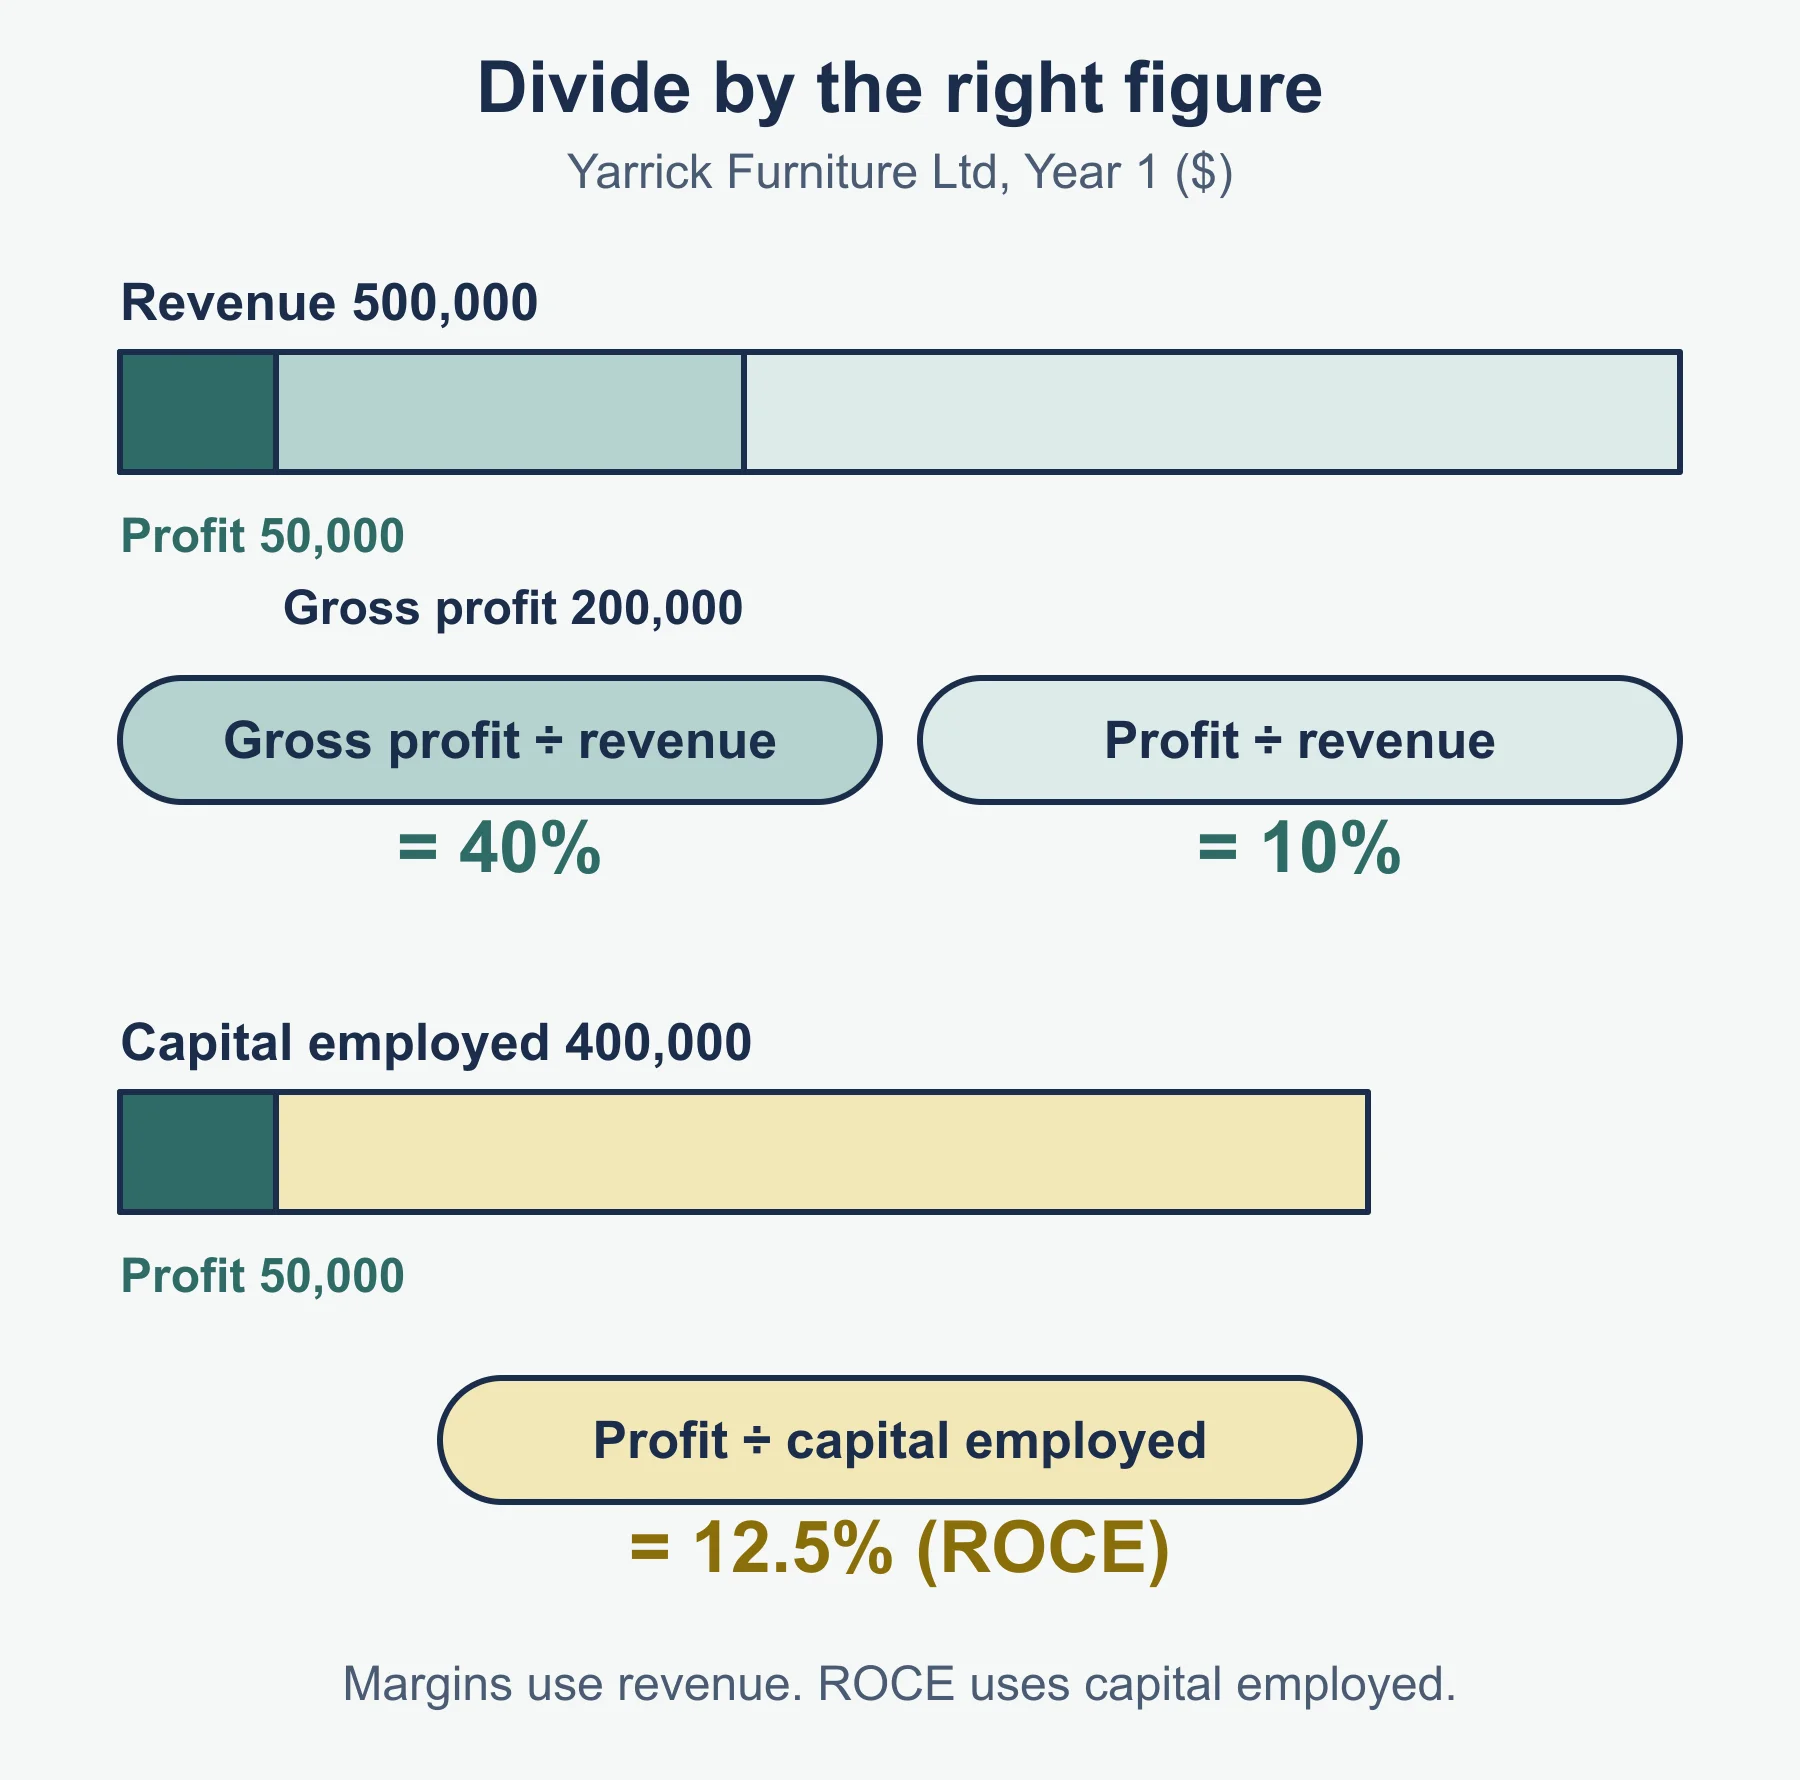
Here profit means the profit line of the statement of profit or loss: gross profit less expenses. Capital employed, in its standard form, is total assets minus current liabilities. It also equals non-current liabilities plus the owners’ capital (including retained profit), which is how the long-term finance of a business adds up. Gross profit margin and profit margin are percentages of revenue. ROCE is a percentage of capital employed. Never divide by the wrong figure.
Worked example 1: three ratios, two years
Yarrick Furniture Ltd makes kitchen tables. Its figures for two years are below.
| Year 1 | Year 2 | |
|---|---|---|
| Revenue | 500,000 | 640,000 |
| Cost of sales | 300,000 | 416,000 |
| Expenses | 150,000 | 176,000 |
| Capital employed | 400,000 | 480,000 |
Step 1: gross profit = revenue − cost of sales. Year 1: 500,000 − 300,000 = 200,000. Year 2: 640,000 − 416,000 = 224,000.
Step 2: profit = gross profit − expenses. Year 1: 200,000 − 150,000 = 50,000. Year 2: 224,000 − 176,000 = 48,000.
Step 3: the ratios.
| Ratio | Year 1 | Year 2 |
|---|---|---|
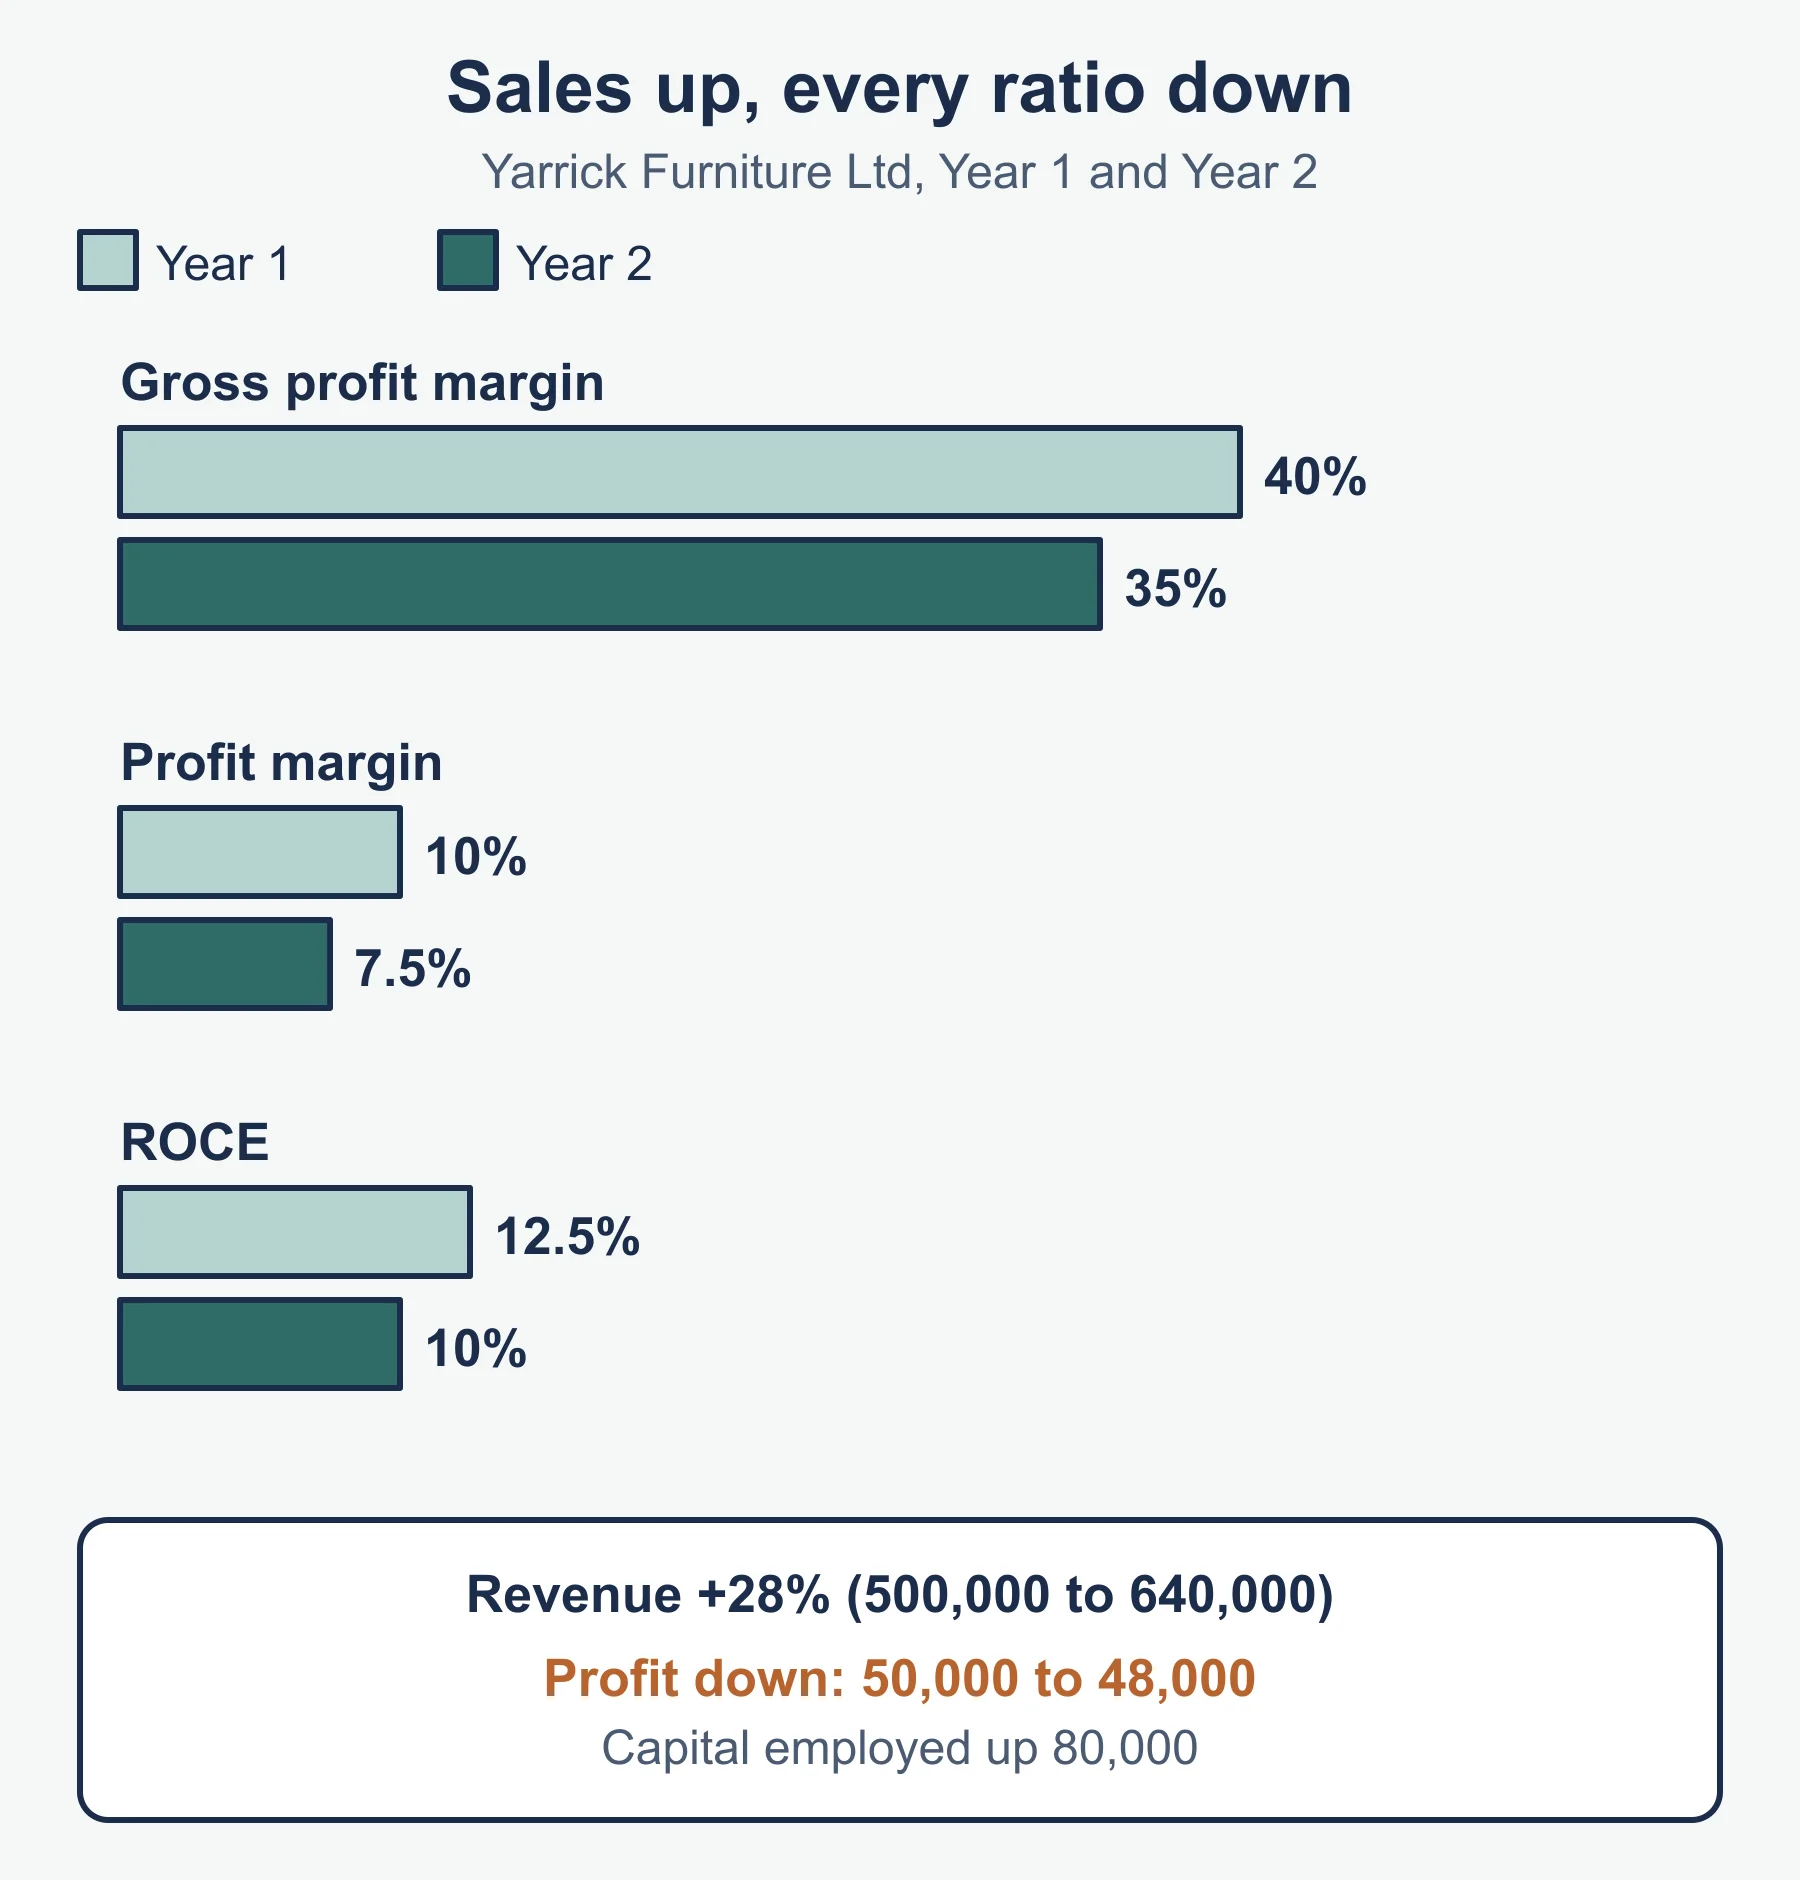
| Gross profit margin | 200,000 / 500,000 × 100 = 40% | 224,000 / 640,000 × 100 = 35% |
| Profit margin | 50,000 / 500,000 × 100 = 10% | 48,000 / 640,000 × 100 = 7.5% |
| ROCE | 50,000 / 400,000 × 100 = 12.5% | 48,000 / 480,000 × 100 = 10% |
Step 4: interpret. Revenue rose by 28%, yet profit fell slightly. Every ratio worsened. The gross profit margin dropped five percentage points, so the business keeps less from each sale after paying for what it sells. Possible reasons are lower selling prices to win sales or higher material costs. The profit margin fell by 2.5 percentage points, less than the gross profit margin, so expenses grew more slowly than revenue and softened the blow. ROCE fell because capital employed grew by 80,000 and profit did not grow with it. The new capital is earning less than the old.
Improving profitability
Margins rise if the business raises prices without losing sales, finds cheaper suppliers, or cuts expenses. ROCE rises if profit rises on the same capital, or if the same profit is earned with less capital. Each route has a cost. Higher prices may lose customers. Cheaper materials may harm quality. Cutting expenses may harm service. Consider these trade-offs when a question asks you to justify a recommendation.
Liquidity (5.5.2)
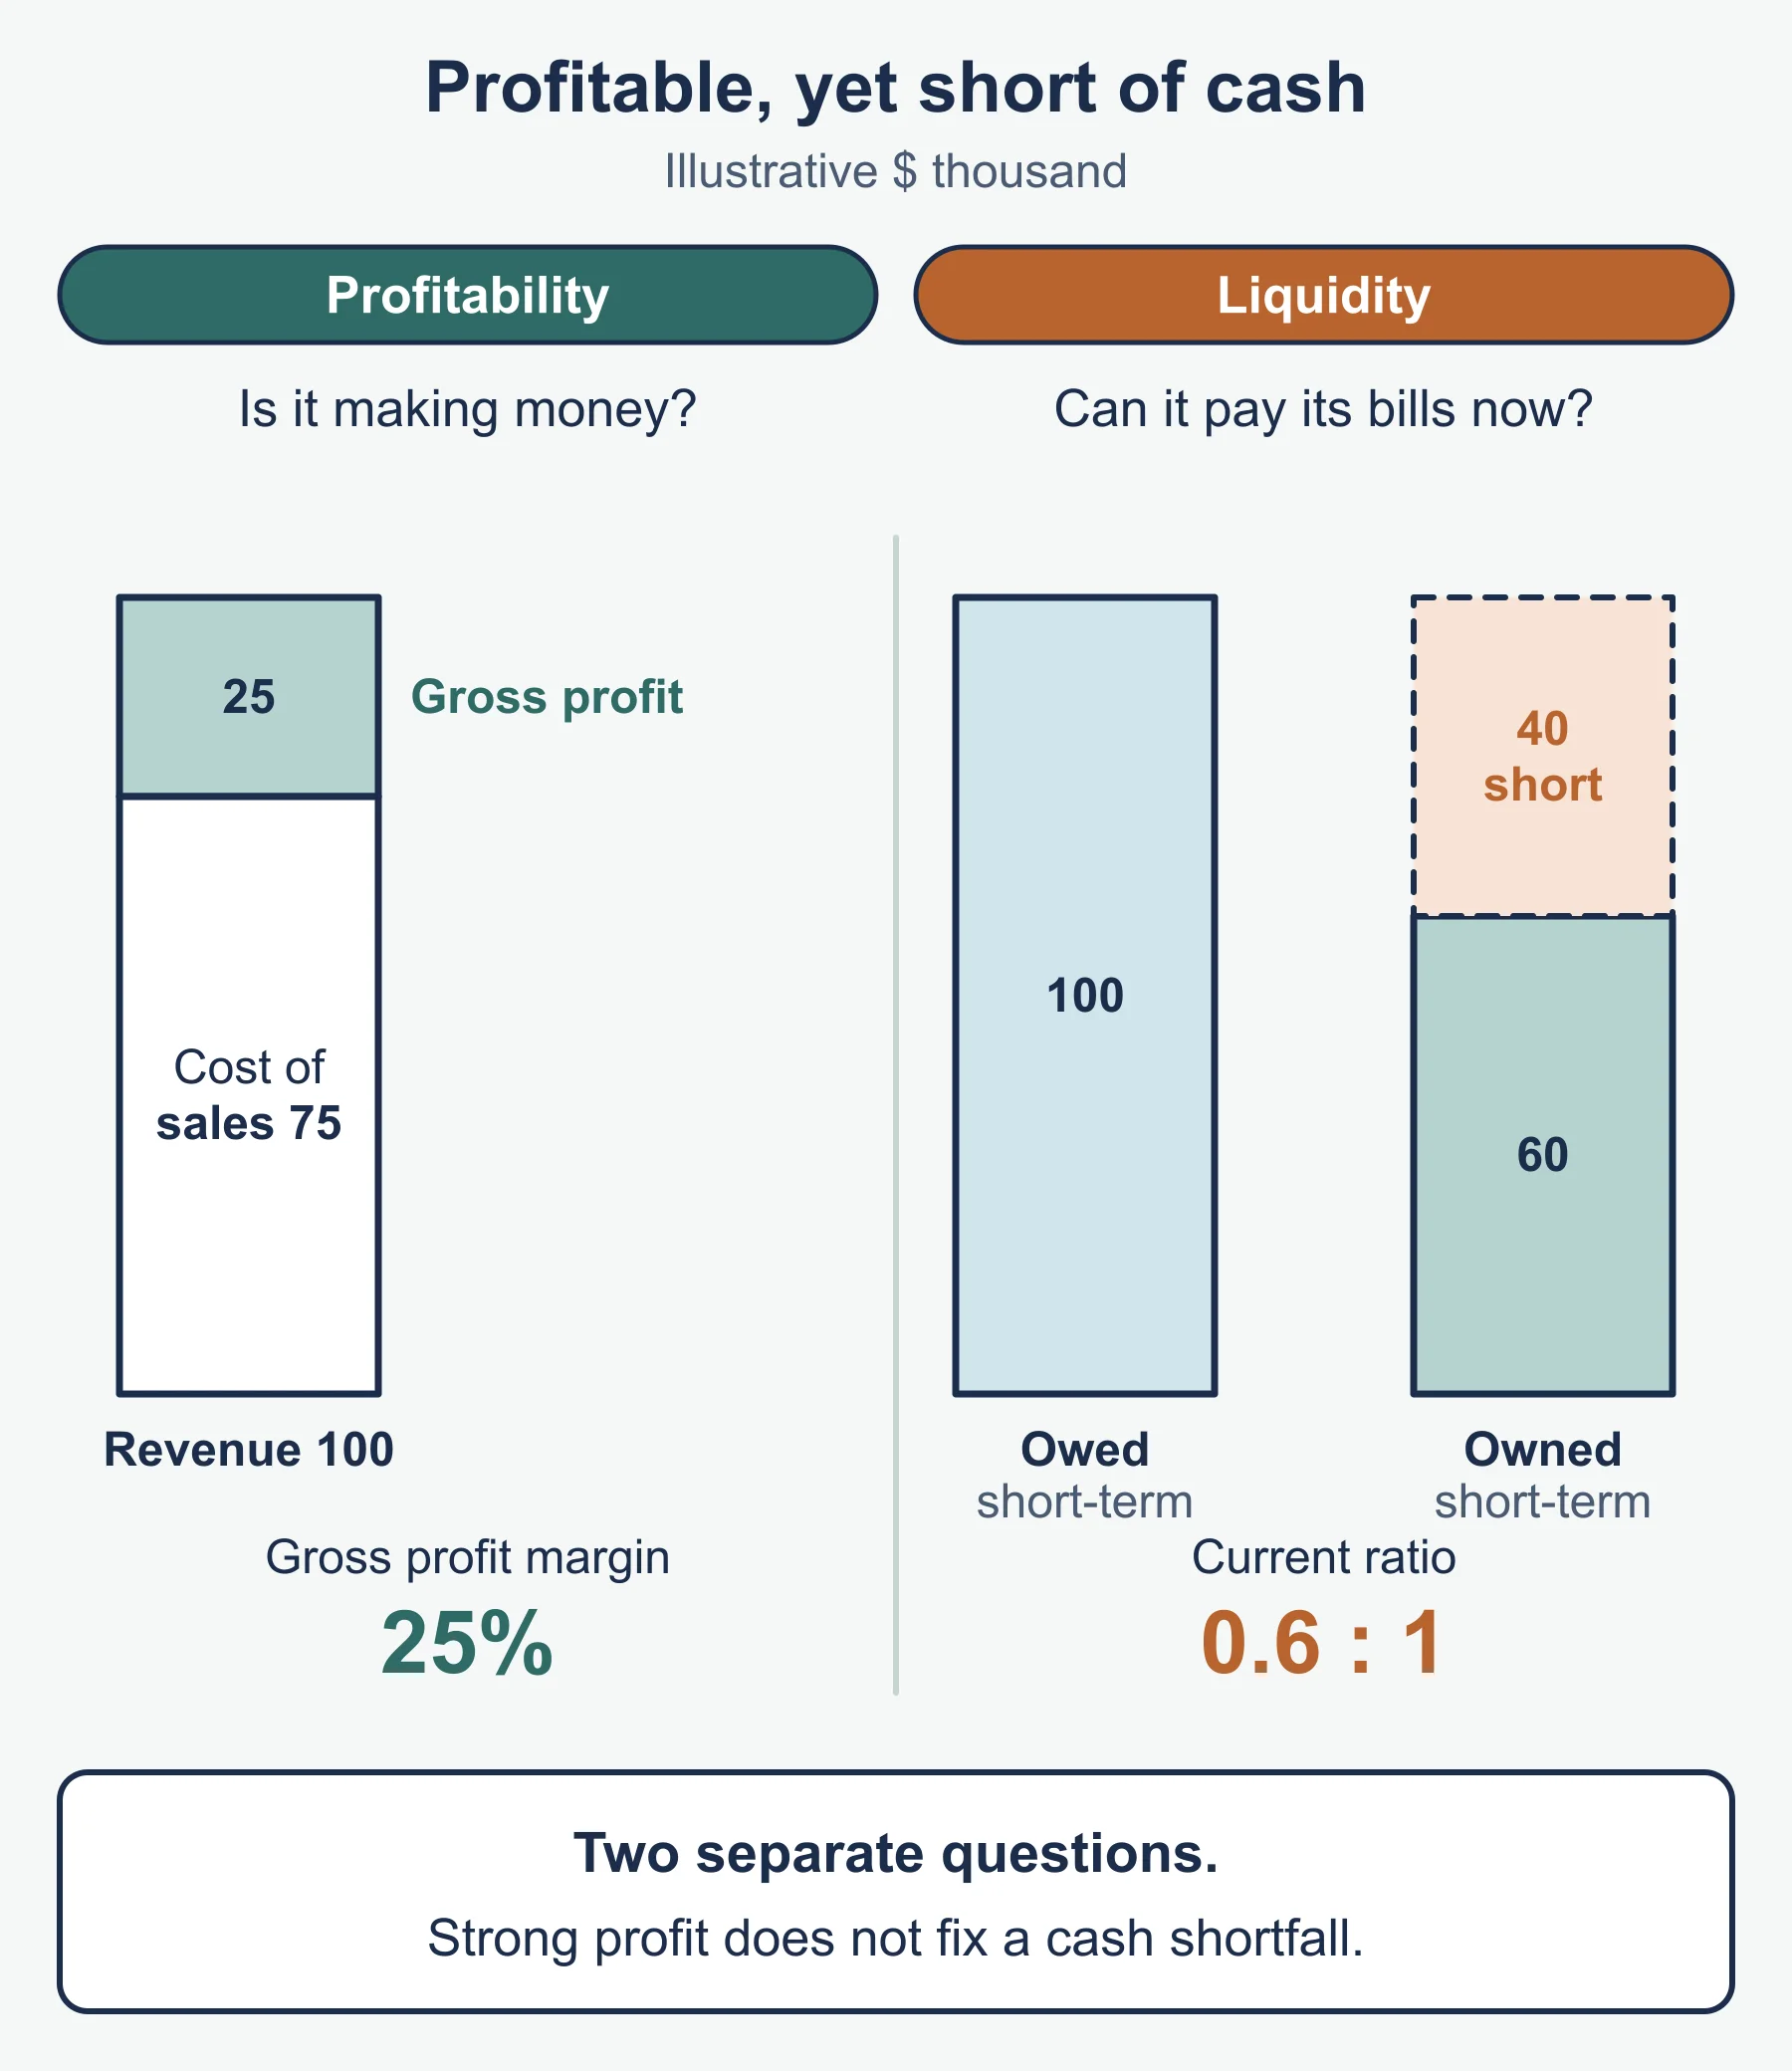
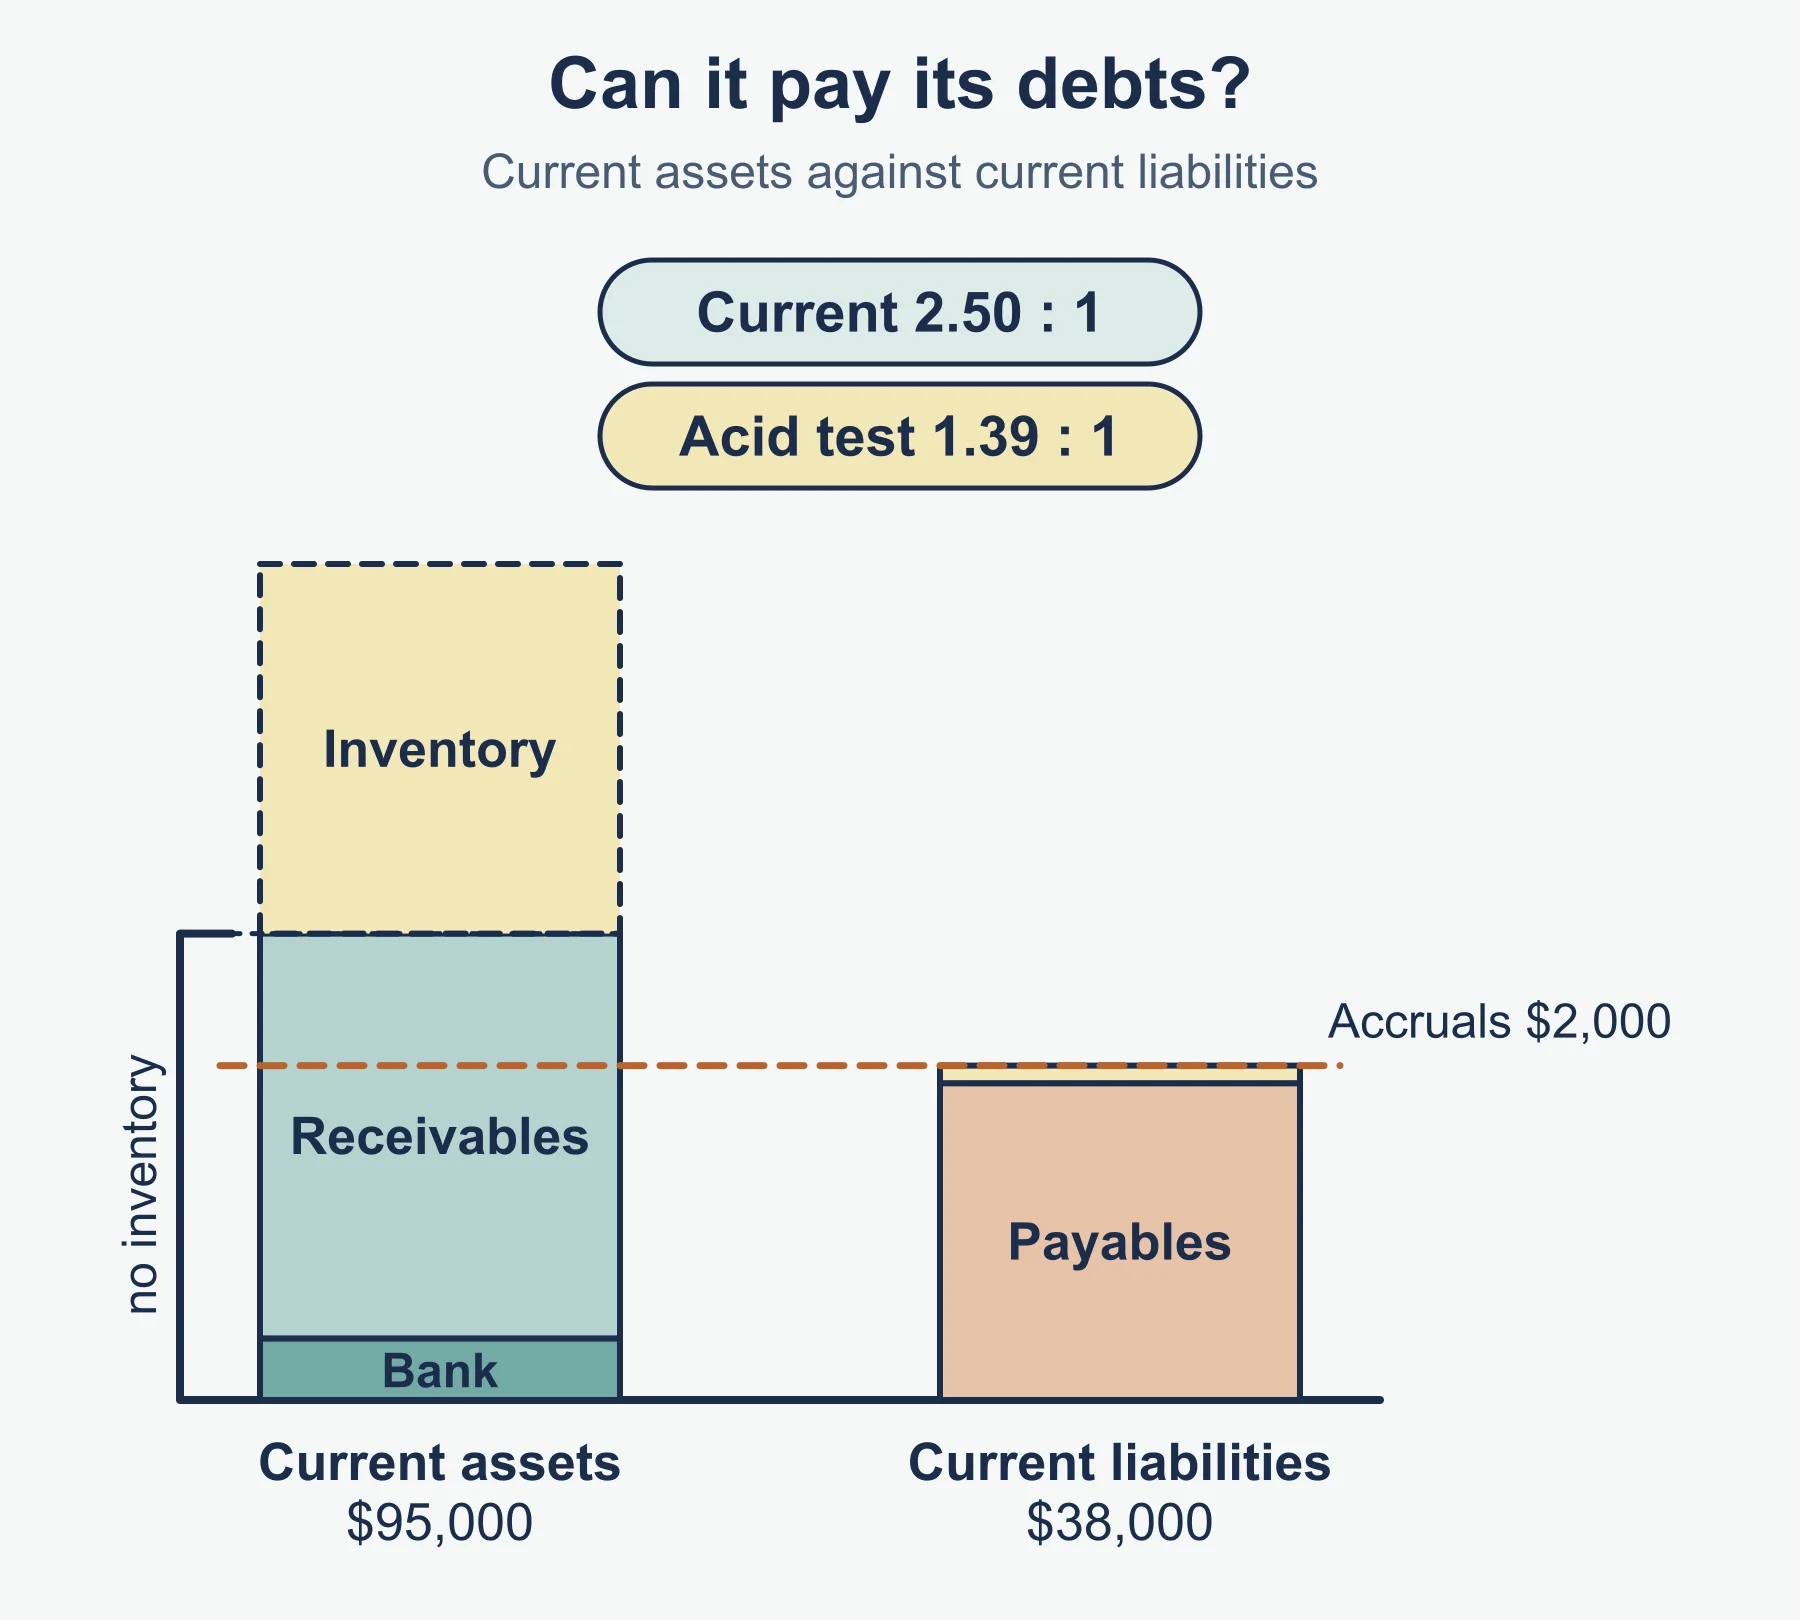
Liquidity is a business’s capacity to meet short-term debts when payment is due, using cash or assets that can be turned into cash quickly. Profit does not guarantee cash: a business can still run short. It may have sold goods on credit and not yet been paid while its own bills are due. Liquidity ratios therefore compare short-term assets with short-term liabilities. They use the current assets and current liabilities from the statement of financial position.
The two liquidity ratios
| Ratio | Standard form | Shows |
|---|---|---|
| Current ratio | current assets : current liabilities | Whether current assets cover current liabilities |
| Acid test ratio | (current assets − inventory) : current liabilities | The same test, but excluding inventory, the least liquid current asset |
You may show the answer as a ratio such as 1.5:1, or as a single number. State which you are using. Inventory is removed in the acid test because stock may take time to sell, and may only sell at a discount. Trade receivables and cash are closer to cash, so they stay in.
Worked example 2: liquidity over two years
Dunmerrow Cycles sells and repairs bicycles.
| Year 1 | Year 2 | |
|---|---|---|
| Inventory | 90,000 | 120,000 |
| Trade receivables | 40,000 | 30,000 |
| Cash | 20,000 | 10,000 |
| Trade payables | 60,000 | 80,000 |
| Overdraft | 40,000 | 50,000 |
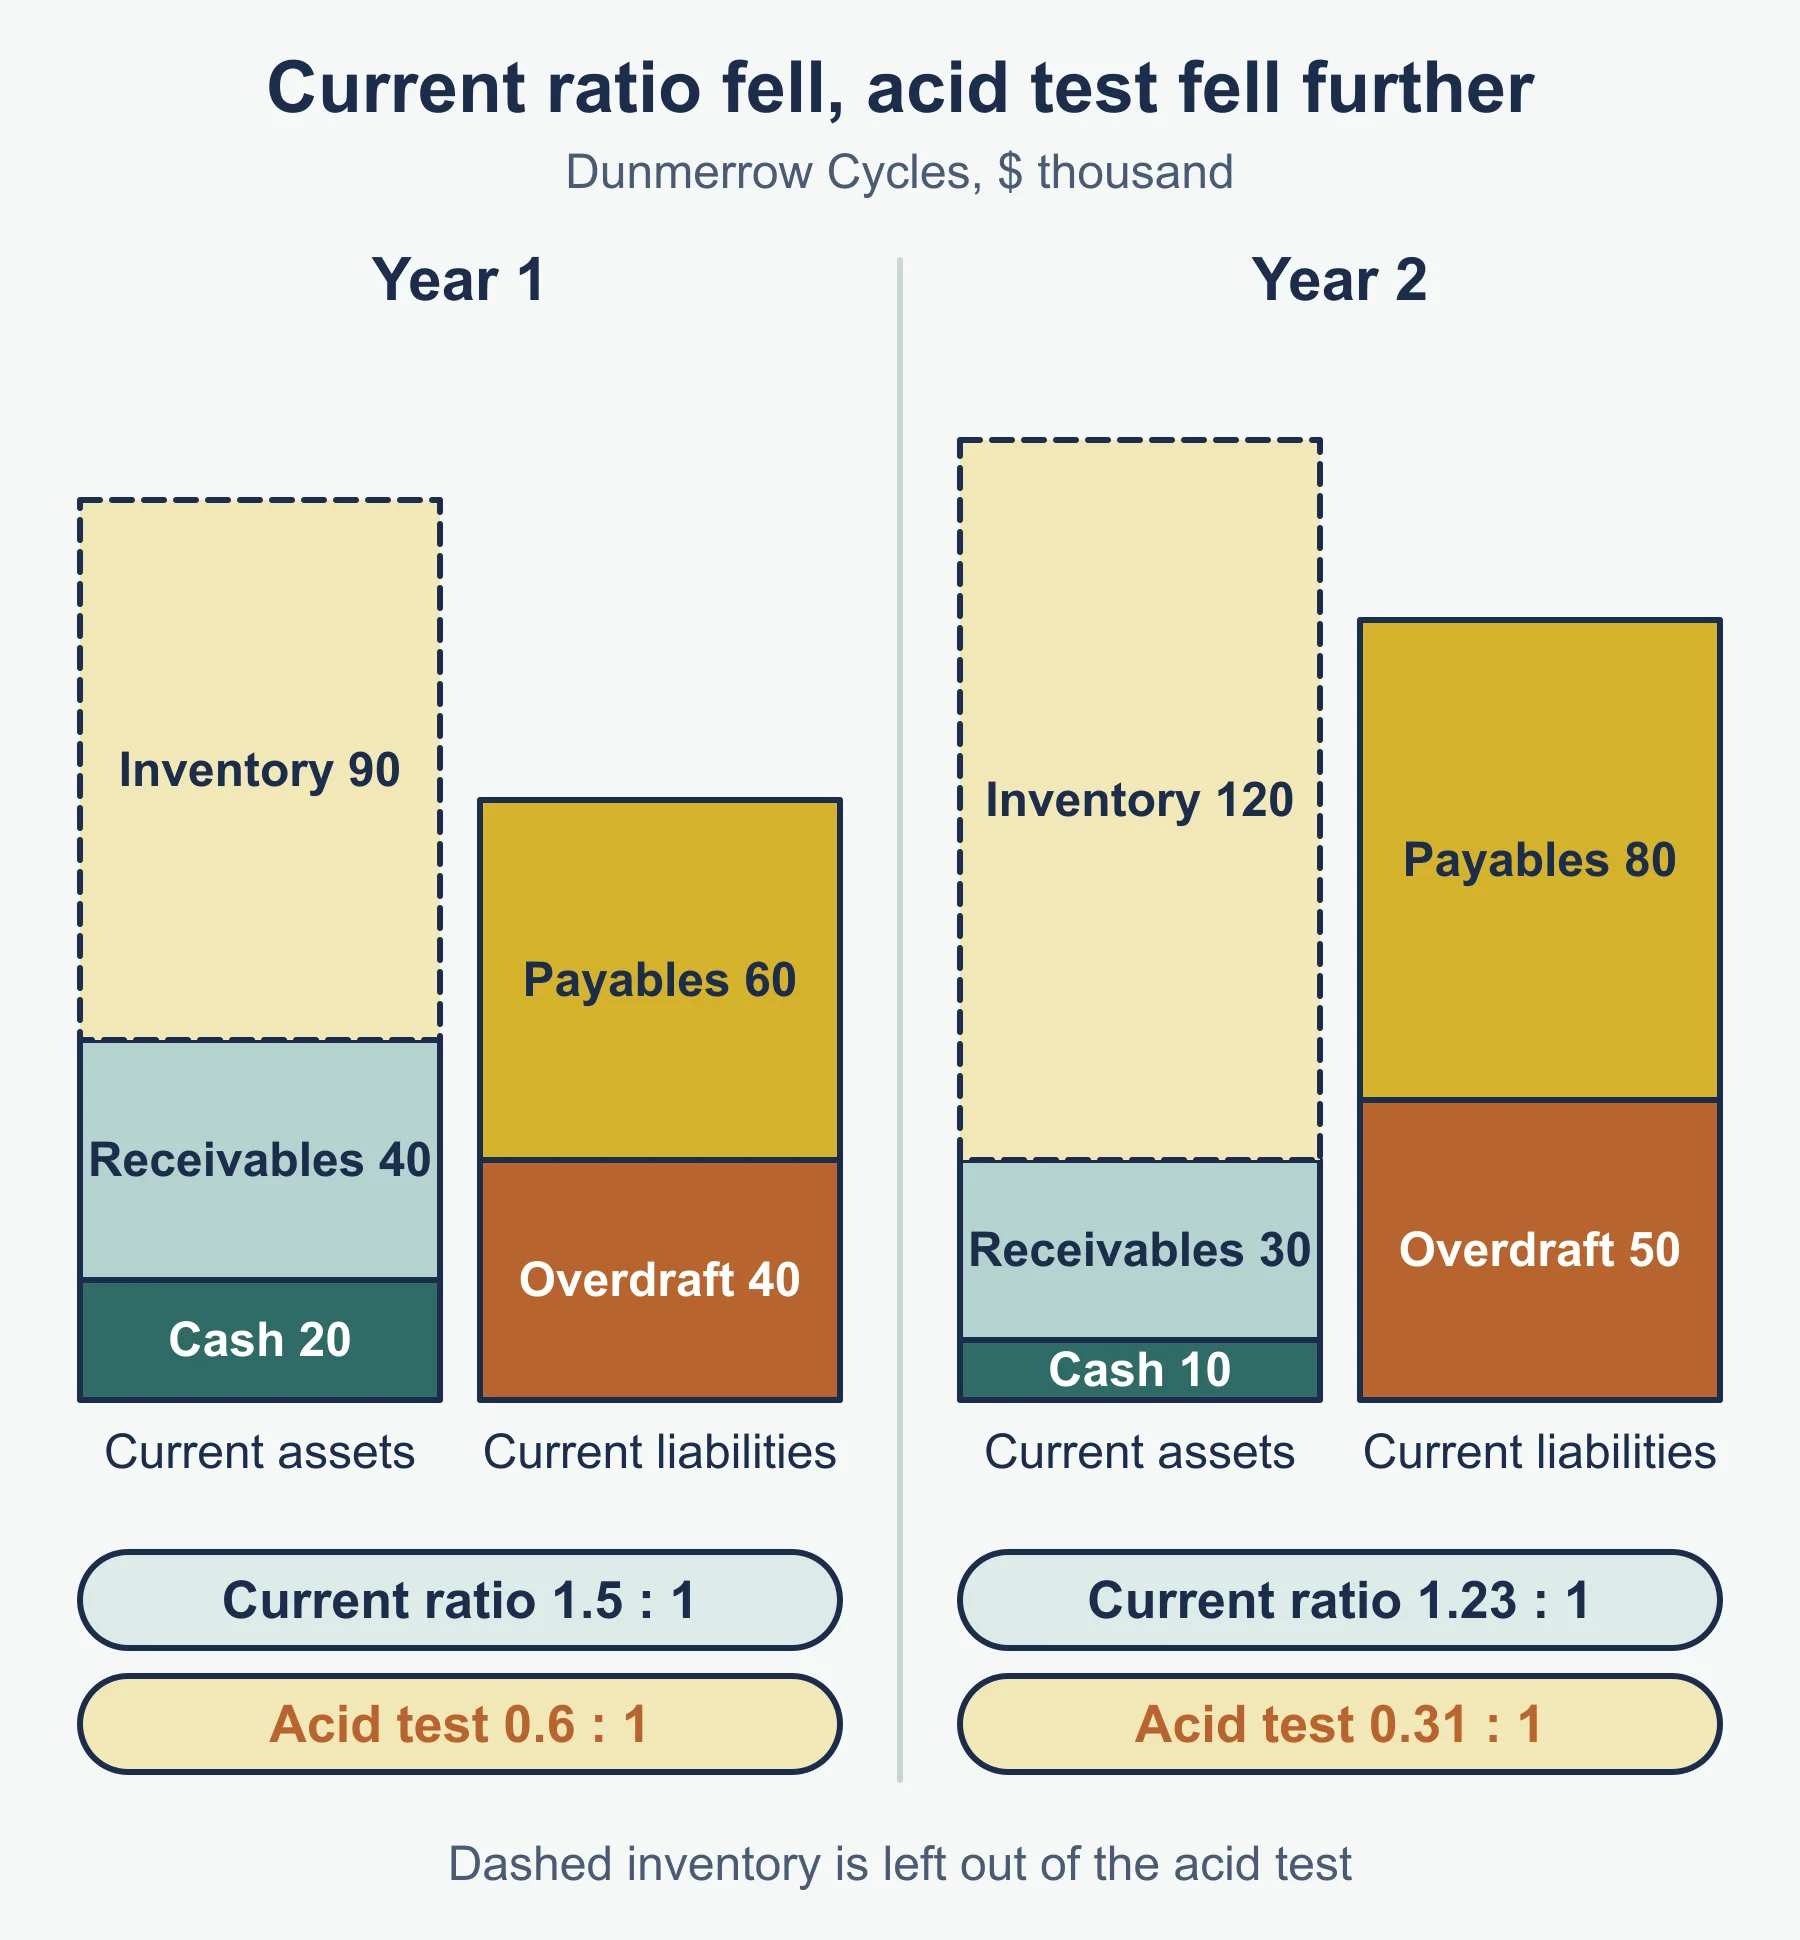
Current assets: Year 1 = 90,000 + 40,000 + 20,000 = 150,000. Year 2 = 120,000 + 30,000 + 10,000 = 160,000.
Current liabilities: Year 1 = 60,000 + 40,000 = 100,000. Year 2 = 80,000 + 50,000 = 130,000.
Current ratio: Year 1 = 150,000 / 100,000 = 1.5:1. Year 2 = 160,000 / 130,000 = 1.23:1 (to two decimal places).
Acid test: Year 1 = (150,000 − 90,000) / 100,000 = 0.6:1. Year 2 = (160,000 − 120,000) / 130,000 = 0.31:1.
Interpretation: the current ratio fell, but the acid test fell much further. Stock grew by 30,000 while cash and receivables fell, so more of the current assets are tied up in bicycles that must still be sold. In Year 2 there are only 0.31 of liquid assets for each 1 owed in the short term, so paying suppliers and the overdraft on time could be difficult. Working capital (current assets minus current liabilities, from topic 5.4) also fell, from 50,000 to 30,000.
Reading the results
There is no single correct figure that suits every business. A ratio of 1:1 or more on the acid test means the liquid assets cover the short-term bills. A low ratio is a warning, not a verdict. A business that sells for cash and holds fast-moving stock, such as a food retailer, can manage on lower figures than a firm that sells on long credit. Compare with the business’s own past years, and with similar businesses, before judging.
If liquidity is weak, the business can collect receivables sooner, hold less stock, delay payments to suppliers where they agree, or arrange longer-term finance in place of the overdraft. Link each fix to its drawback.
Users of accounts (5.5.3)
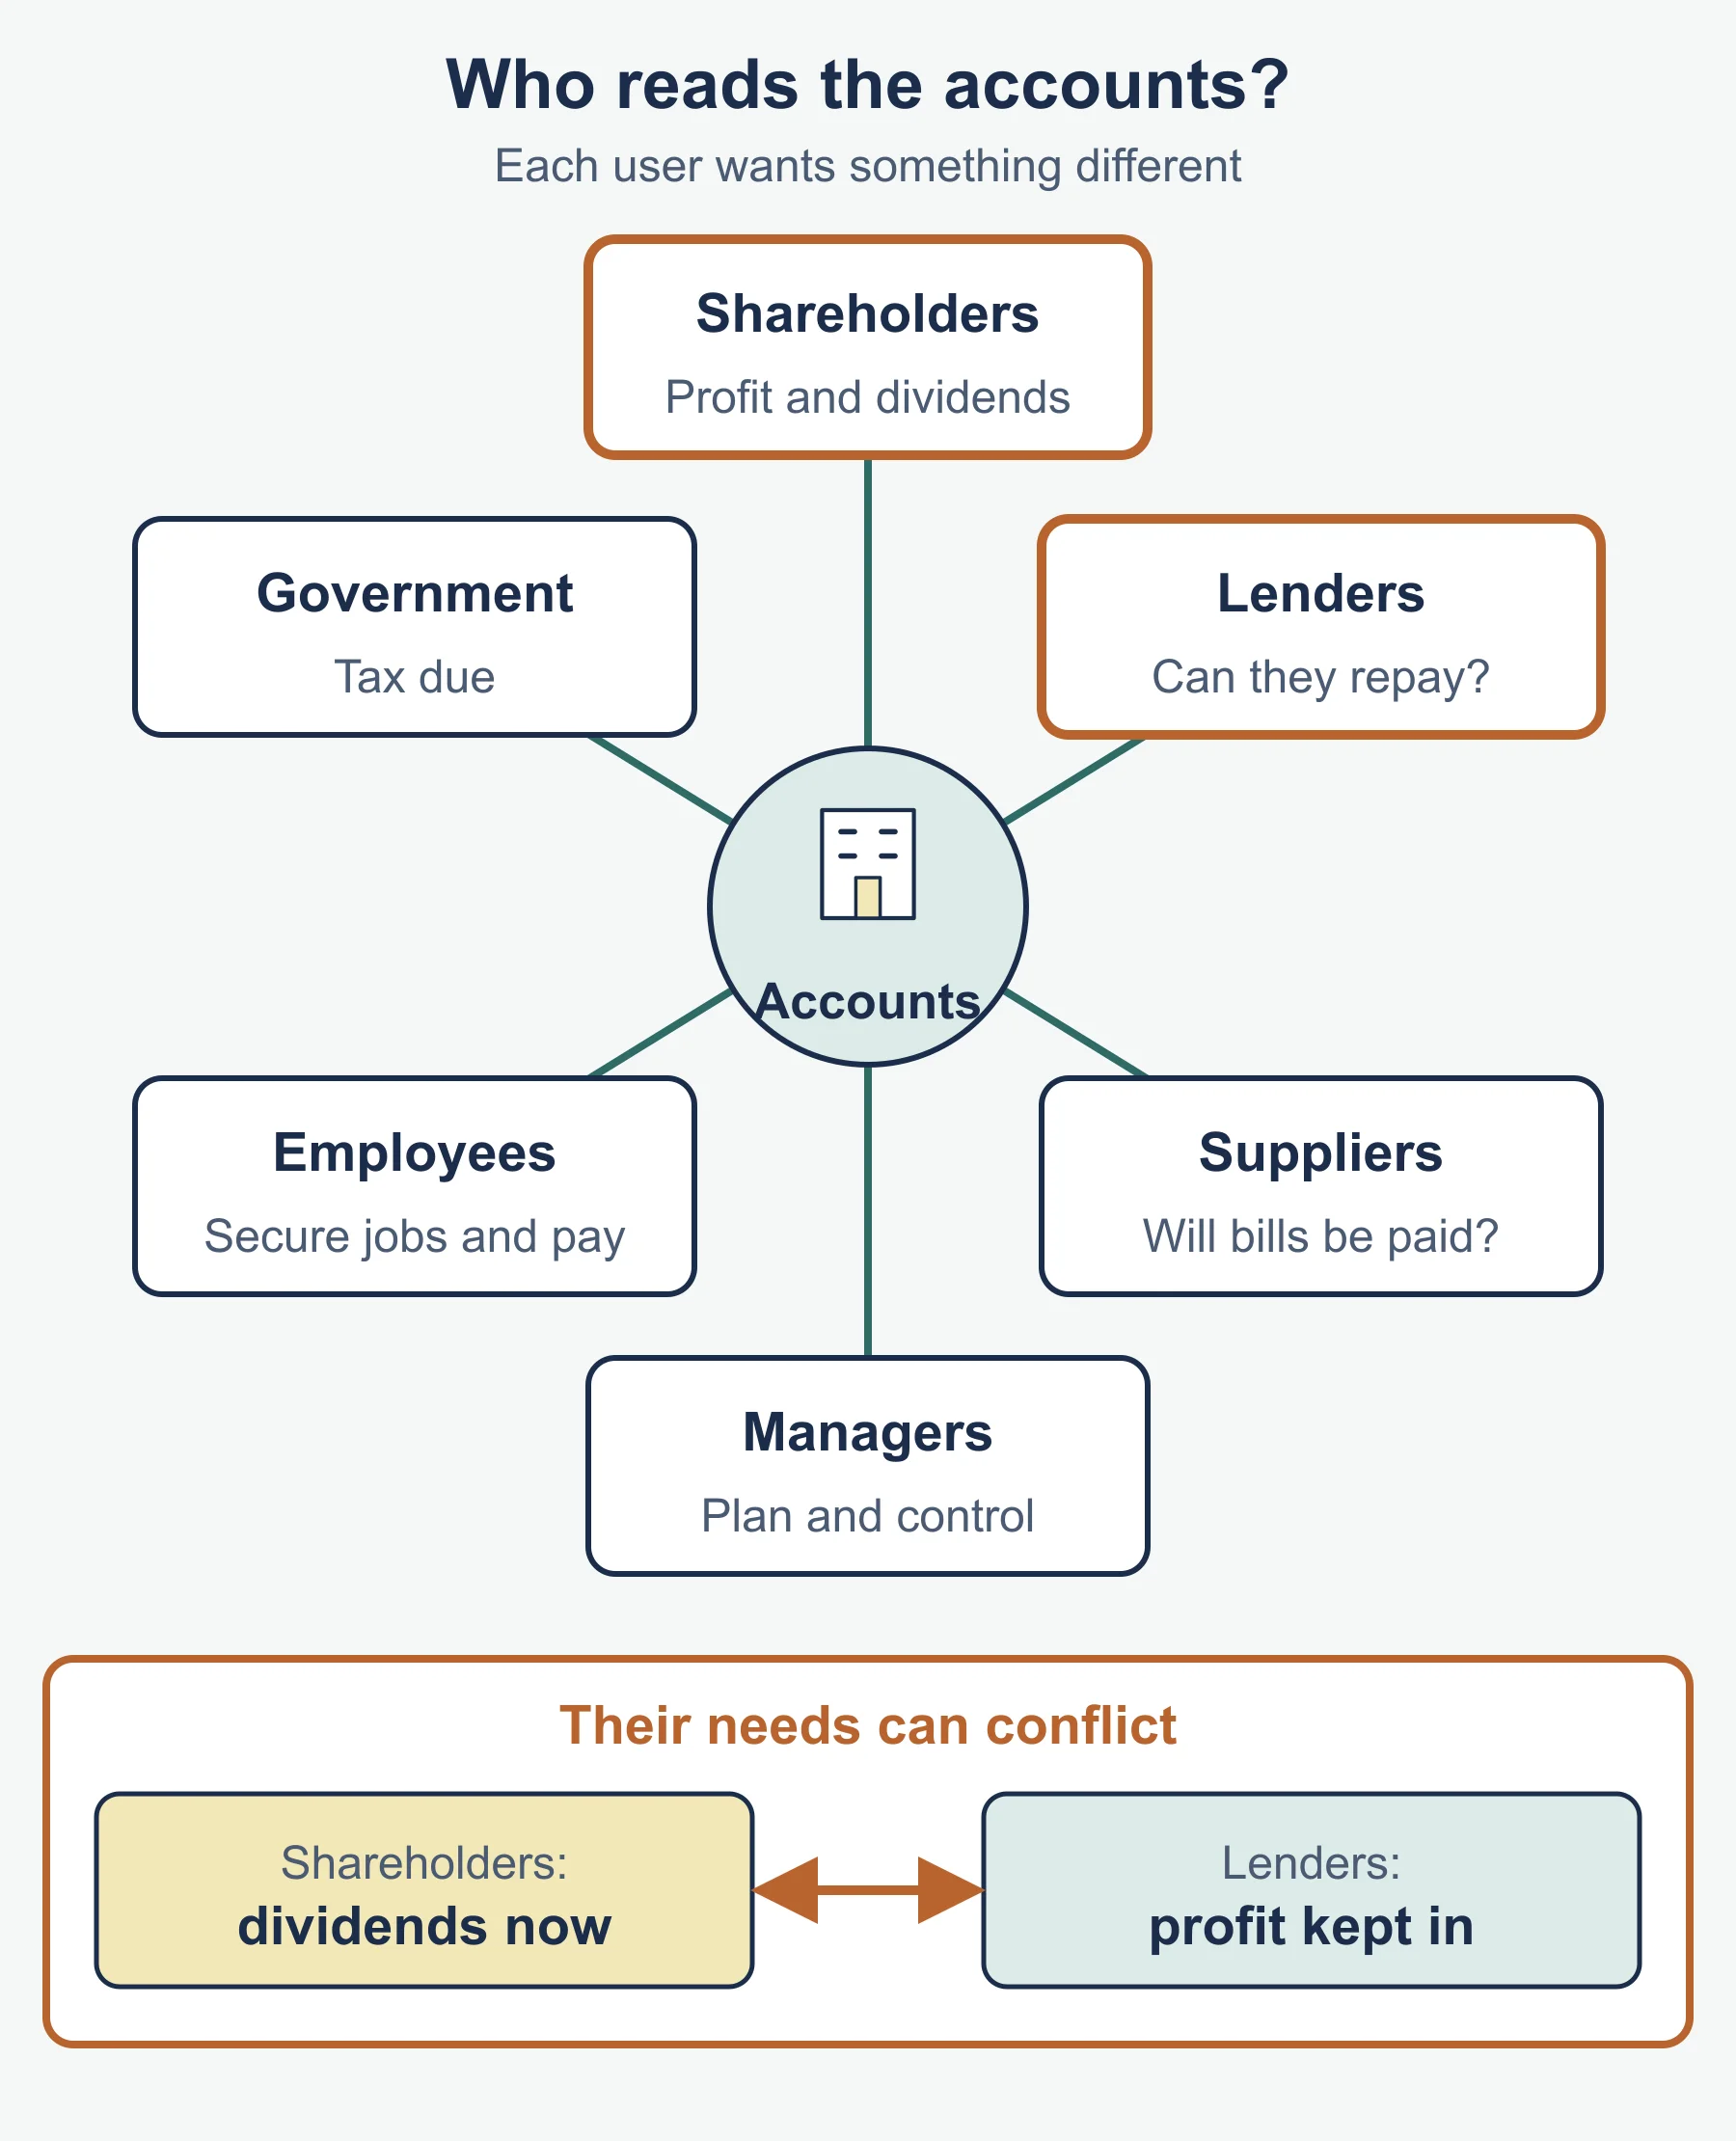
Different people read accounts to answer different questions.
| User | Type | What they look at and why |
|---|---|---|
| Owners: sole traders, partners, shareholders | Internal | Profit and profitability, to judge return on their investment and decide whether to take profit out, reinvest or invest elsewhere |
| Managers | Internal | All ratios, to check performance against targets, find problems and plan |
| Employees | Internal | Profit and liquidity, as signs of job security and whether pay rises or bonuses are affordable |
| Suppliers | External | Liquidity, to decide whether to sell on credit and whether they will be paid |
| Government | External | Profit, to calculate tax owed, and wider health of the business |
| Lenders/banks | External | Liquidity and ROCE, to decide whether to lend and whether interest and repayments can be met |
Worked example 3: a lending decision
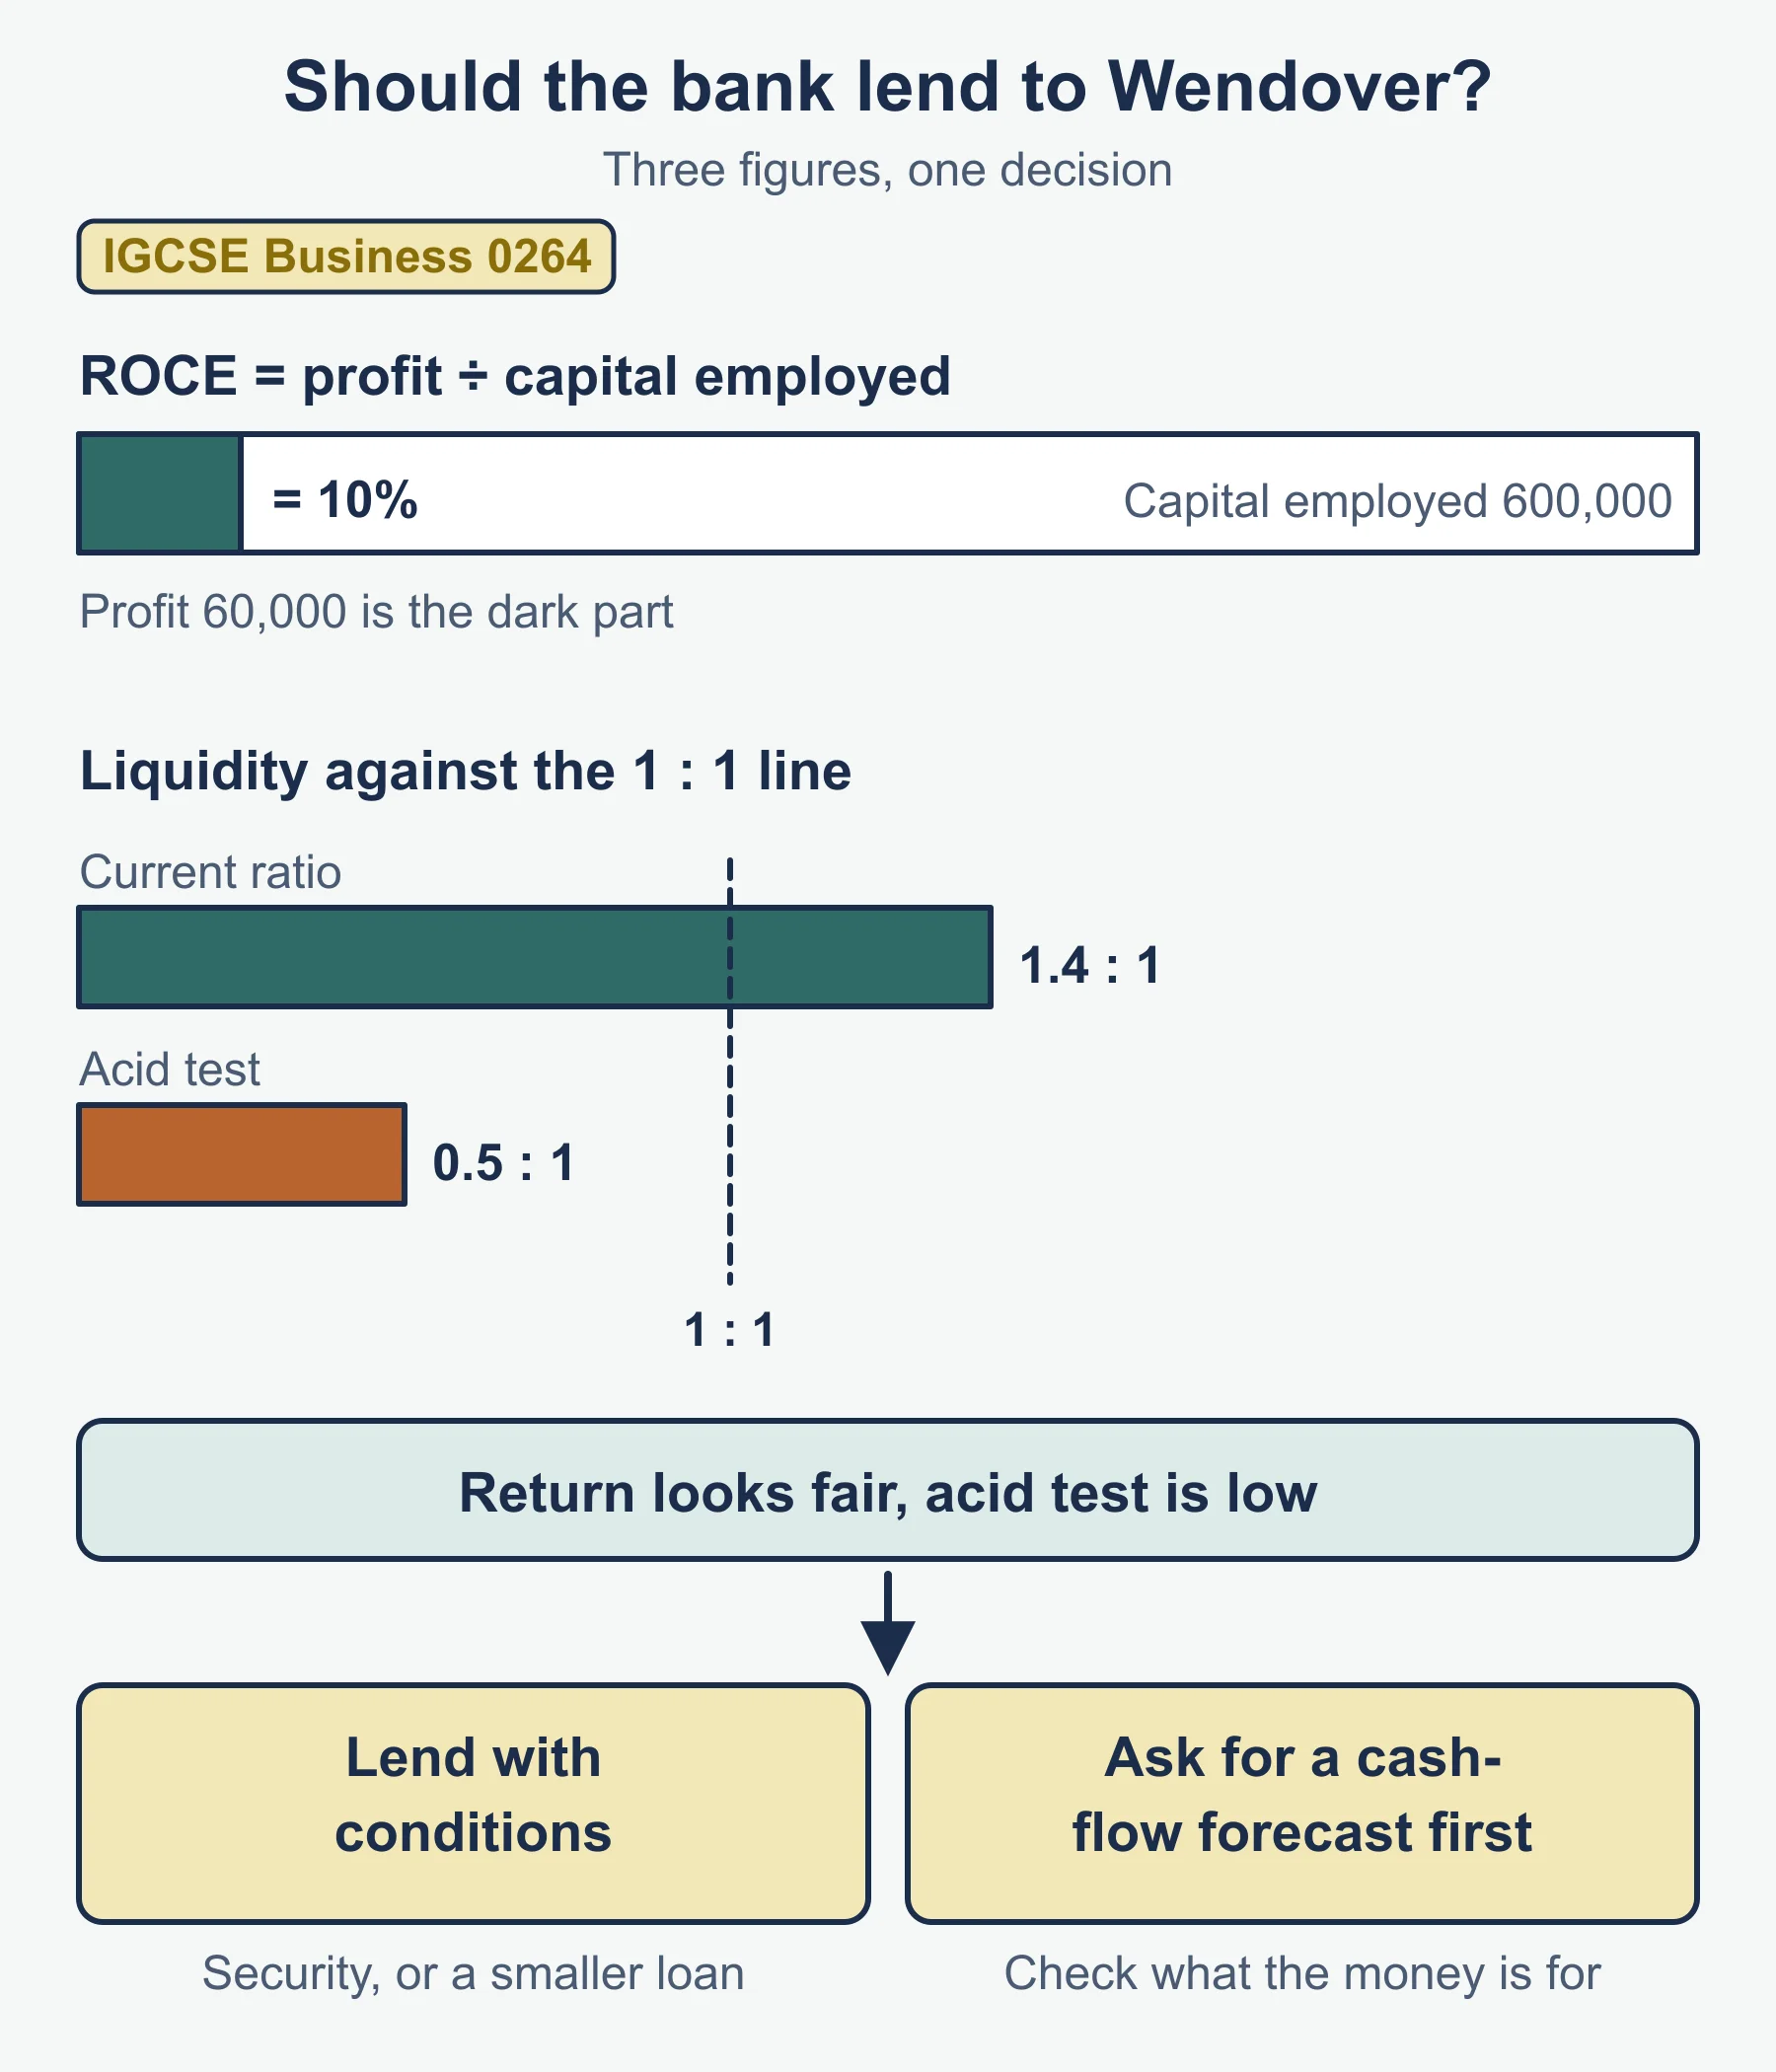
Wendover Tiles Ltd asks its bank for a loan. Its profit is 60,000 and capital employed is 600,000, so ROCE is 60,000 / 600,000 × 100 = 10%. Its current ratio is 1.4:1 and its acid test is 0.5:1.
A banker might reason like this. A ROCE of 10% suggests the business earns a return, and the profit gives some chance of paying interest. The acid test of 0.5:1 is low, so a short-term cash squeeze is possible. The bank could lend with conditions, such as security or a smaller loan, or ask for a cash-flow forecast first. The decision rests on both ratios, and on what the money is for.
A potential investor asks a different question: will the return justify the risk? An investor compares ROCE with what the money could earn elsewhere. A supplier cares less about ROCE and more about being paid on time, so looks at liquidity.
Limitations of accounts and ratio analysis
Ratios help, but they have limits. Quote these with the business in front of you.
- The figures are historical. They show what happened, not what will happen, so changes in the market, costs or competition may make them out of date.
- The statement of financial position is a snapshot on one day. A business may look liquid on that day and not a month later.
- One year’s ratio means little alone. You need earlier years, targets or similar businesses to compare with, and no two businesses are identical in size, products or customers.
- Ratios leave out non-financial factors such as staff morale, customer loyalty, product quality or the reputation of the business.
- Figures can be affected by choices about timing, such as when bills are paid, so two sets of accounts may not be fully comparable.
- Ratios show what has changed but not why. You must still investigate the cause.
Common errors
- Using revenue as the divisor for ROCE, or capital employed for a margin.
- Using gross profit in the profit margin, or profit in the gross profit margin.
- Forgetting to subtract inventory in the acid test, or subtracting it from the liabilities.
- Mixing up a percentage with a ratio: margins and ROCE are percentages, liquidity ratios are not.
- Treating a rise in profit as a rise in profitability. Check the ratio.
- Describing the numbers without saying what they mean for the business or user in the question.
Where to go next
Work through the practice questions and keep the revision notes beside you. For stakeholder groups, see business objectives and stakeholder objectives. For owners of different kinds of firm, see types of business organisation.
Frequently asked questions
Why is inventory left out of the acid test ratio? Inventory is the least liquid current asset, because it must be sold before it becomes cash. Removing it shows whether the business can meet short-term debts without relying on selling stock.
Who uses a business’s accounts? Internal users include owners, managers and employees; external users include suppliers, government and lenders such as banks. Each looks at different figures, such as liquidity for a supplier deciding whether to sell on credit.
What are the limitations of ratio analysis? Ratios use historical figures, the statement of financial position is a snapshot on one day, one year’s ratio means little alone, non-financial factors are left out, timing choices can affect figures, and ratios show that something changed but not why.
How can a business improve its liquidity? It can collect receivables sooner, hold less stock, delay payments to suppliers where they agree, or arrange longer-term finance in place of an overdraft. Each fix has a drawback to weigh.
Official syllabus
Aligned to section 5.5 of the Cambridge IGCSE Business 0264 syllabus for examination in 2027, 2028 and 2029, published by Cambridge University Press & Assessment (Cambridge International Education).
Get free revision emails (optional)
Occasional emails with practice questions, worked explanations and links to free resources for the qualification and subjects you choose. No spam, and you can unsubscribe from any email. The free tools on this site never need an email.
Related resources
-
Practice questions
IGCSE Business: Analysis of accounts (Cambridge 0264) – Practice Questions
Original practice questions with worked answers on analysis of accounts for Cambridge IGCSE Business 0264: ratios, users and limitations.
Business · Cambridge · IGCSE
Try questions -
Revision notes
IGCSE Business: Analysis of accounts (Cambridge 0264) – Revision Notes
Condensed revision notes on analysis of accounts for Cambridge IGCSE Business 0264: ratio formulas, users of accounts, limitations and a self-test.
Business · Cambridge · IGCSE
Revise topic -
Study guides
IGCSE Business: Business finance (Cambridge 0264)
Study guide to Cambridge IGCSE Business 0264 section 5.1: why businesses need finance, working capital, sources of finance and choosing between them.
Business · Cambridge · IGCSE
Read guide
Related articles
-
teaching
A Level tuition in Dubai: Cambridge or Pearson Edexcel International A Level?
Schools in Dubai and Abu Dhabi teach either Cambridge International AS & A Level or Pearson Edexcel International A Level. How the two are structured, why it matters for tuition, and how online classes from Lahore work.
9 October 2026
-
curriculum guides
Choosing subjects at IGCSE and A Level
How subject choices at 14 and 16 affect university options later, and how to keep pathways open without overloading a timetable.
28 July 2026
Studying this with a teacher
Working through Business IGCSE?
This page is free and stays free. If you would rather be taught it, Marlbridge runs Business classes one-to-one and in small groups of up to 15, online in your own time zone. The first trial class is free. WhatsApp replies within an hour (8am–11pm Pakistan time, every day); email the same day.
Cambridge Business teachers at Marlbridge

